メインコンテンツにスキップ
メインコンテンツにスキップ

インフレーション/デフレーション

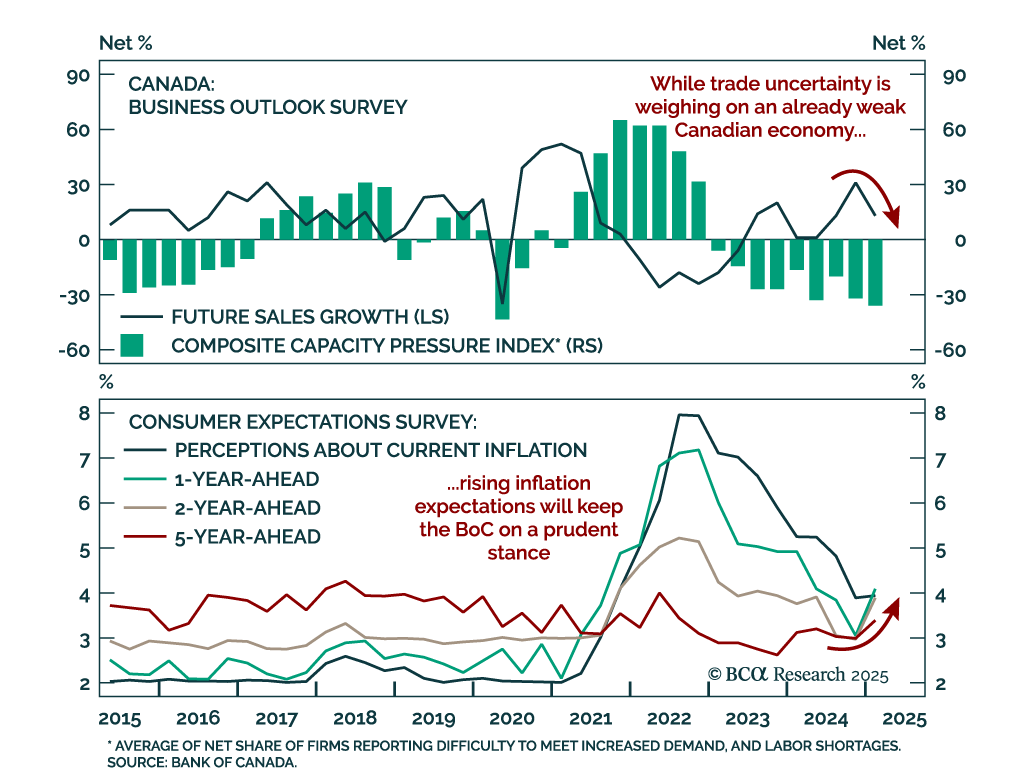
Canada’s difficult macro outlook is already priced, supporting a neutral stance on Canadian government bonds within a global fixed-income portfolio. We continue to recommend a small long CAD/USD position, where bad news is well priced and the reward-to-risk…

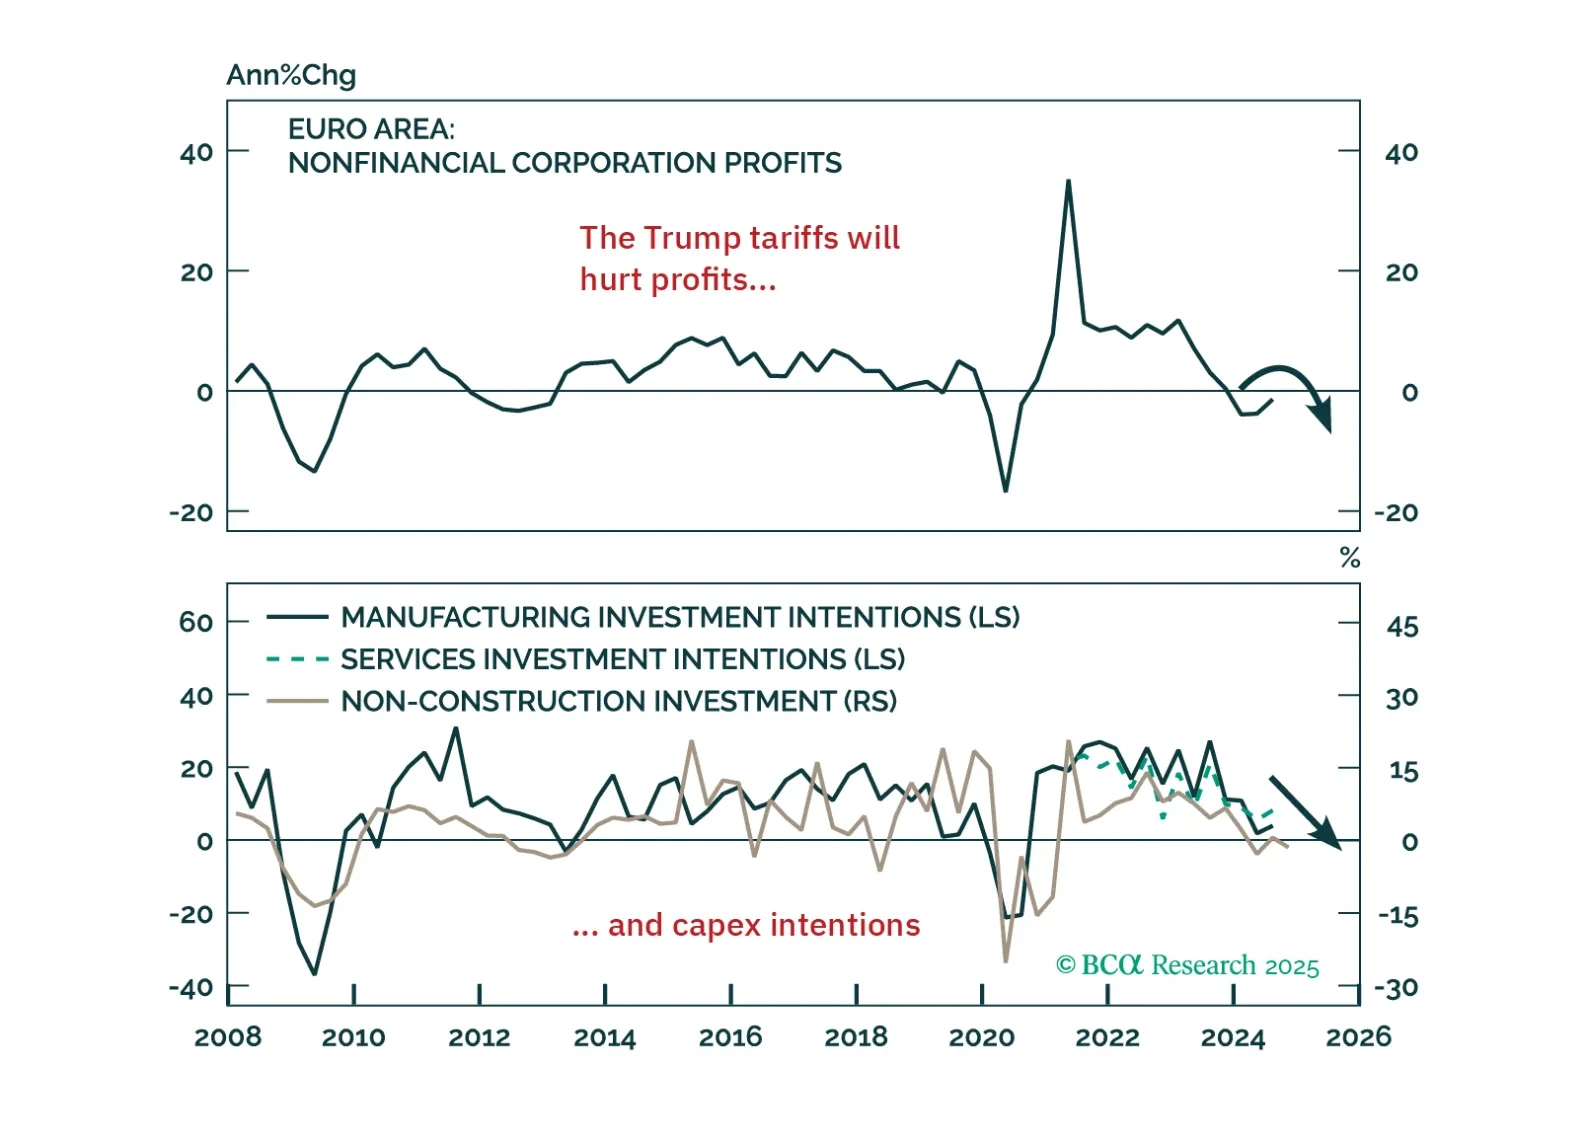
Trump’s tariff shock will push Europe into recession — but it’s also triggering a powerful integration response. In this report, we lay out the tactical case for staying defensive and the structural case for going long European assets when the dust settles.
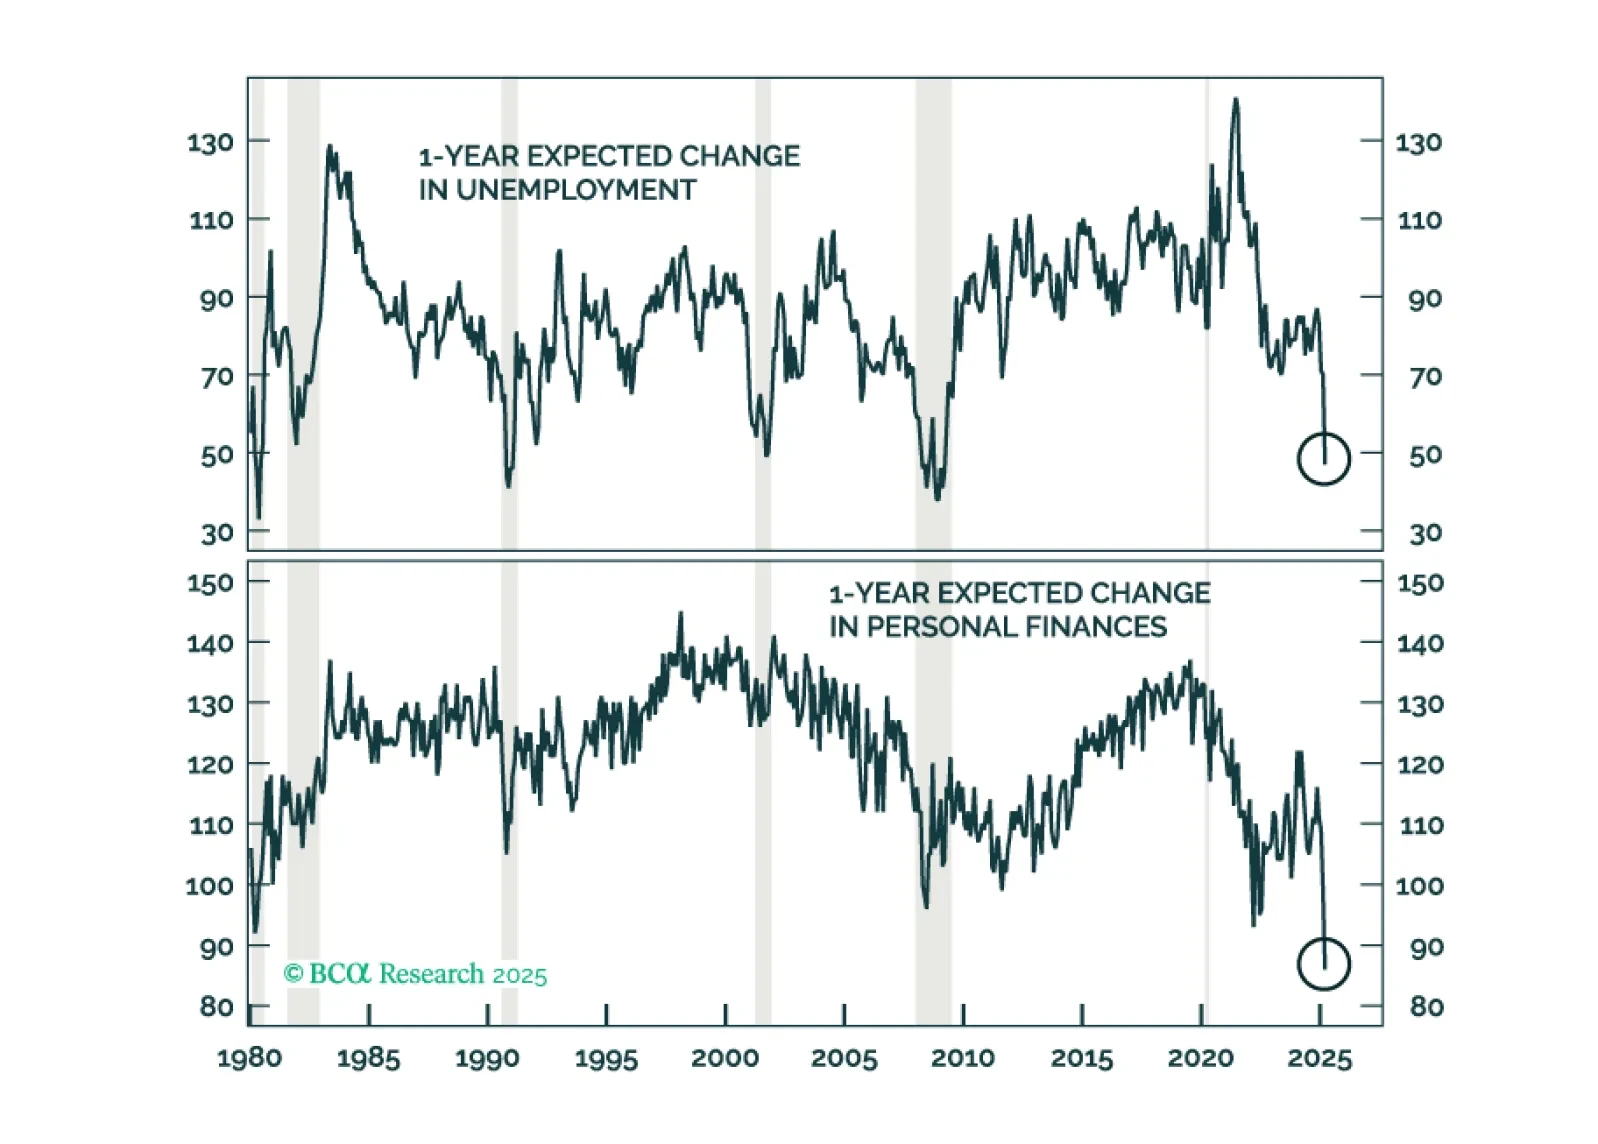
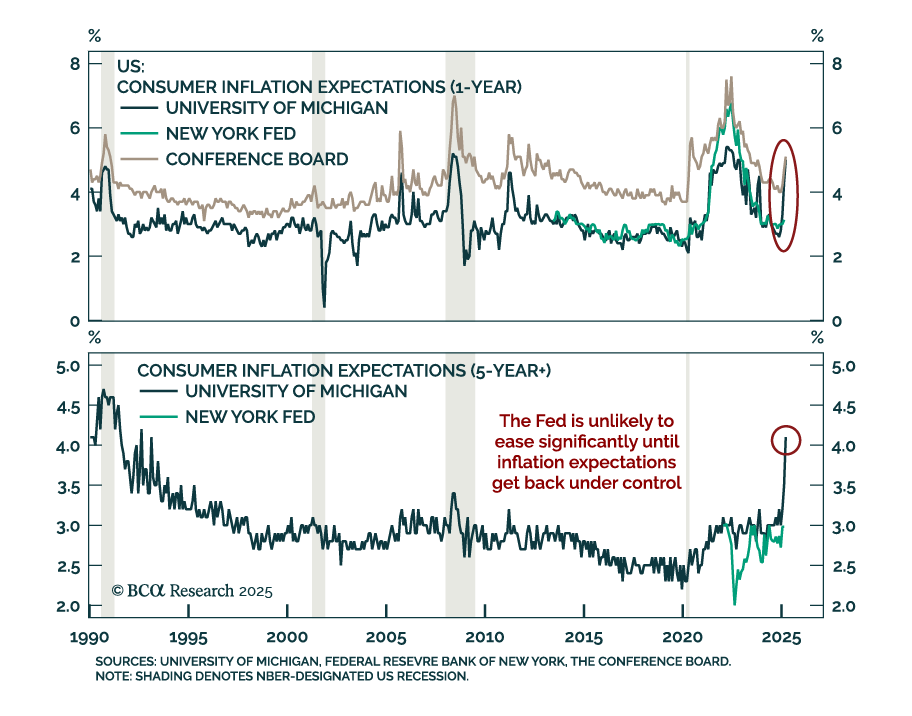
ポストCOVIDの景気拡大を支えた景気刺激策は5年を経て勢いを失い始め、経済は自然に発生する景気後退の方向に向かっていました。DOGEと多方面にわたる貿易戦争がそのタイムテーブルを前倒しした今、我々は改めてリスクオフの推奨を表明します。

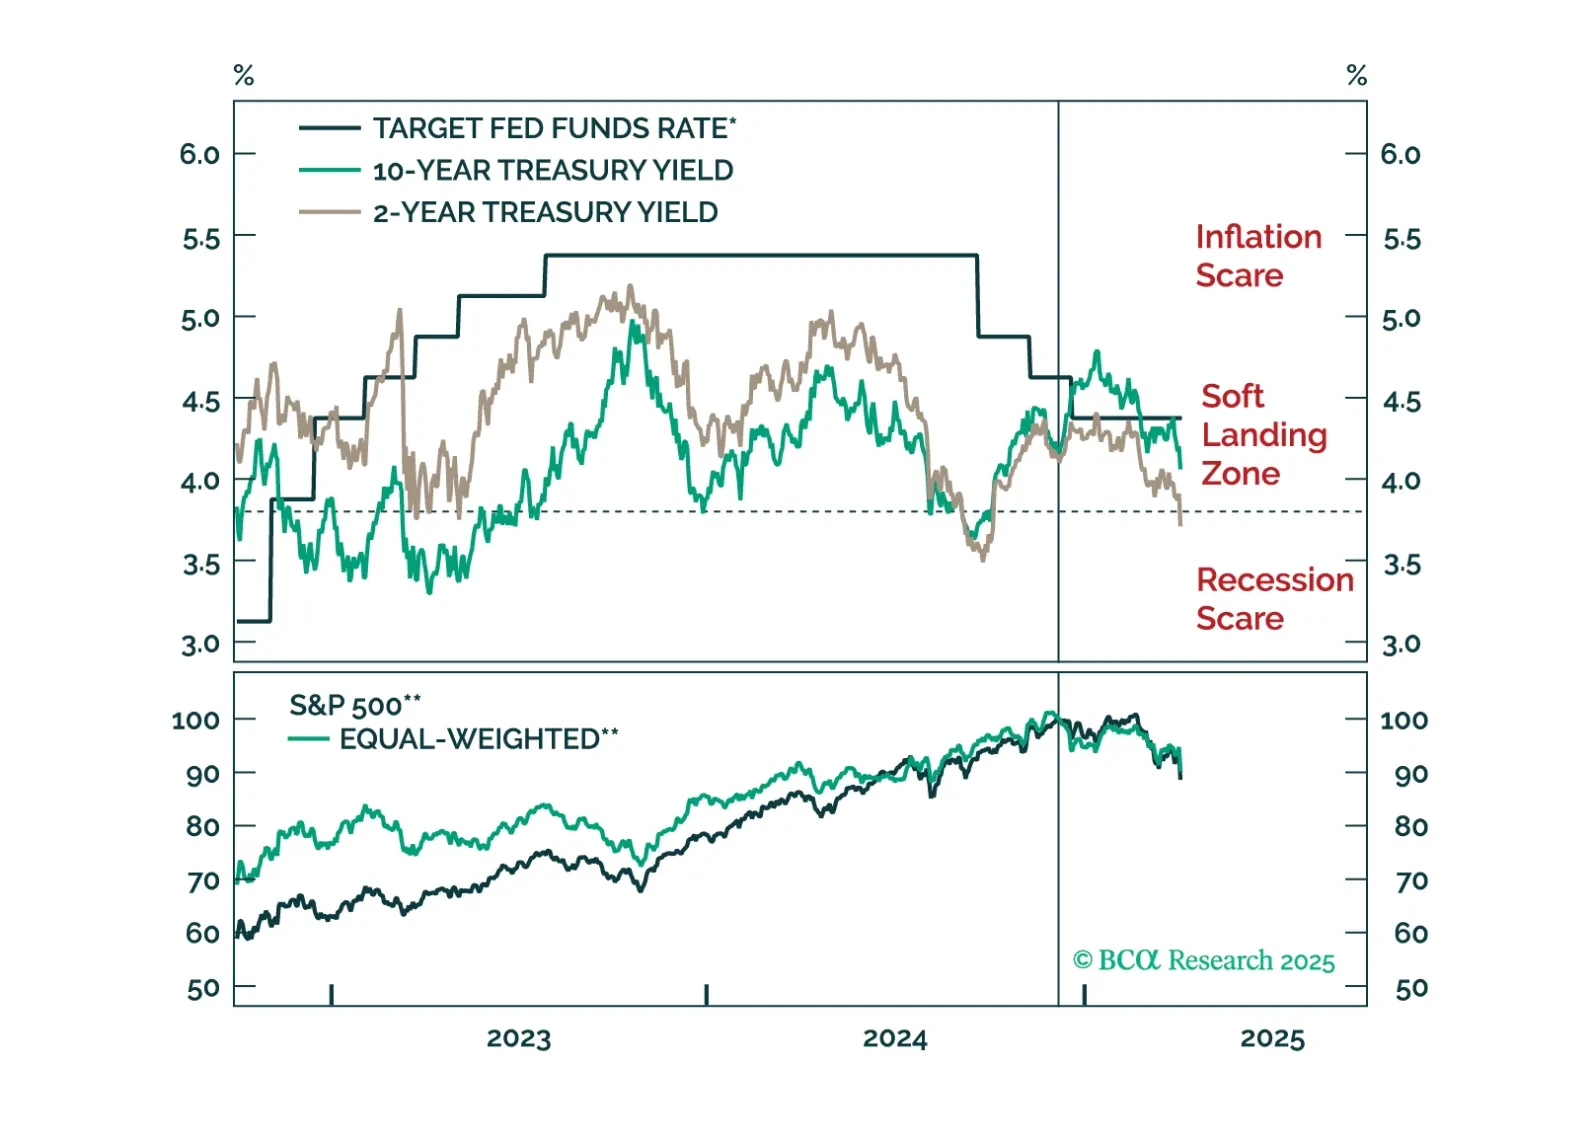
With both the Trump and Fed puts drifting lower, we reiterate our above-benchmark duration stance within a government bond overweight and favor Treasury curve steepeners. If the Trump put’s strike price is declining (See The Numbers), Friday’s remarks by Fed…
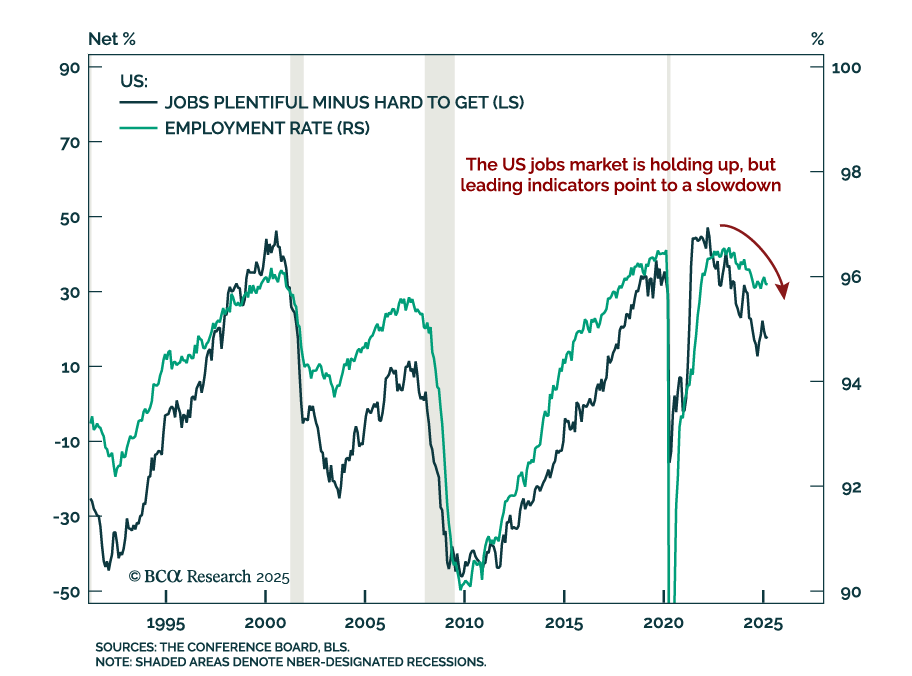
We reiterate our defensive global asset allocation, as risk assets face an asymmetric outlook whether growth slows or re-accelerates. The March US jobs report came in stronger than expected, with payrolls rising by 228k. However, the three-month moving…

The March employment report showed strong job growth, but the labor market remains in a fragile state and the demand shock from tariffs could be the catalyst that tips it over the edge into recession. 
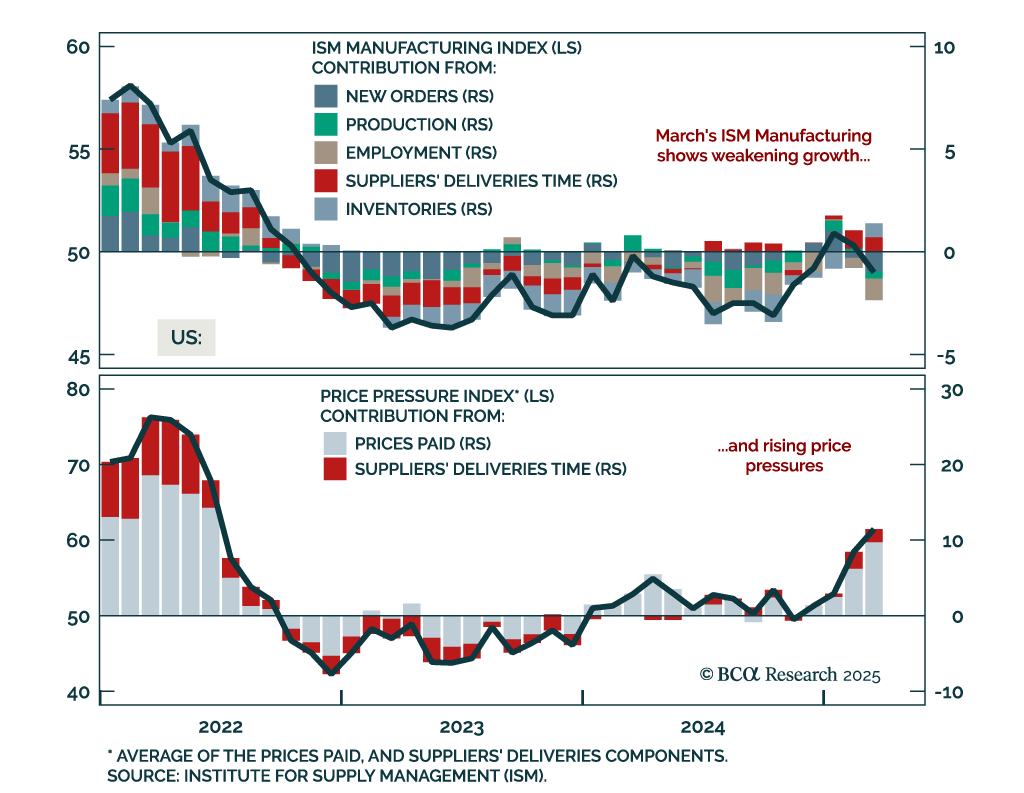
The March ISM Manufacturing adds to the recent stagflationary impulse, but markets remain focused on the growth drag, reinforcing our defensive asset allocation. The headline index fell more than expected to 49.0 from 50.3, with new orders and employment…

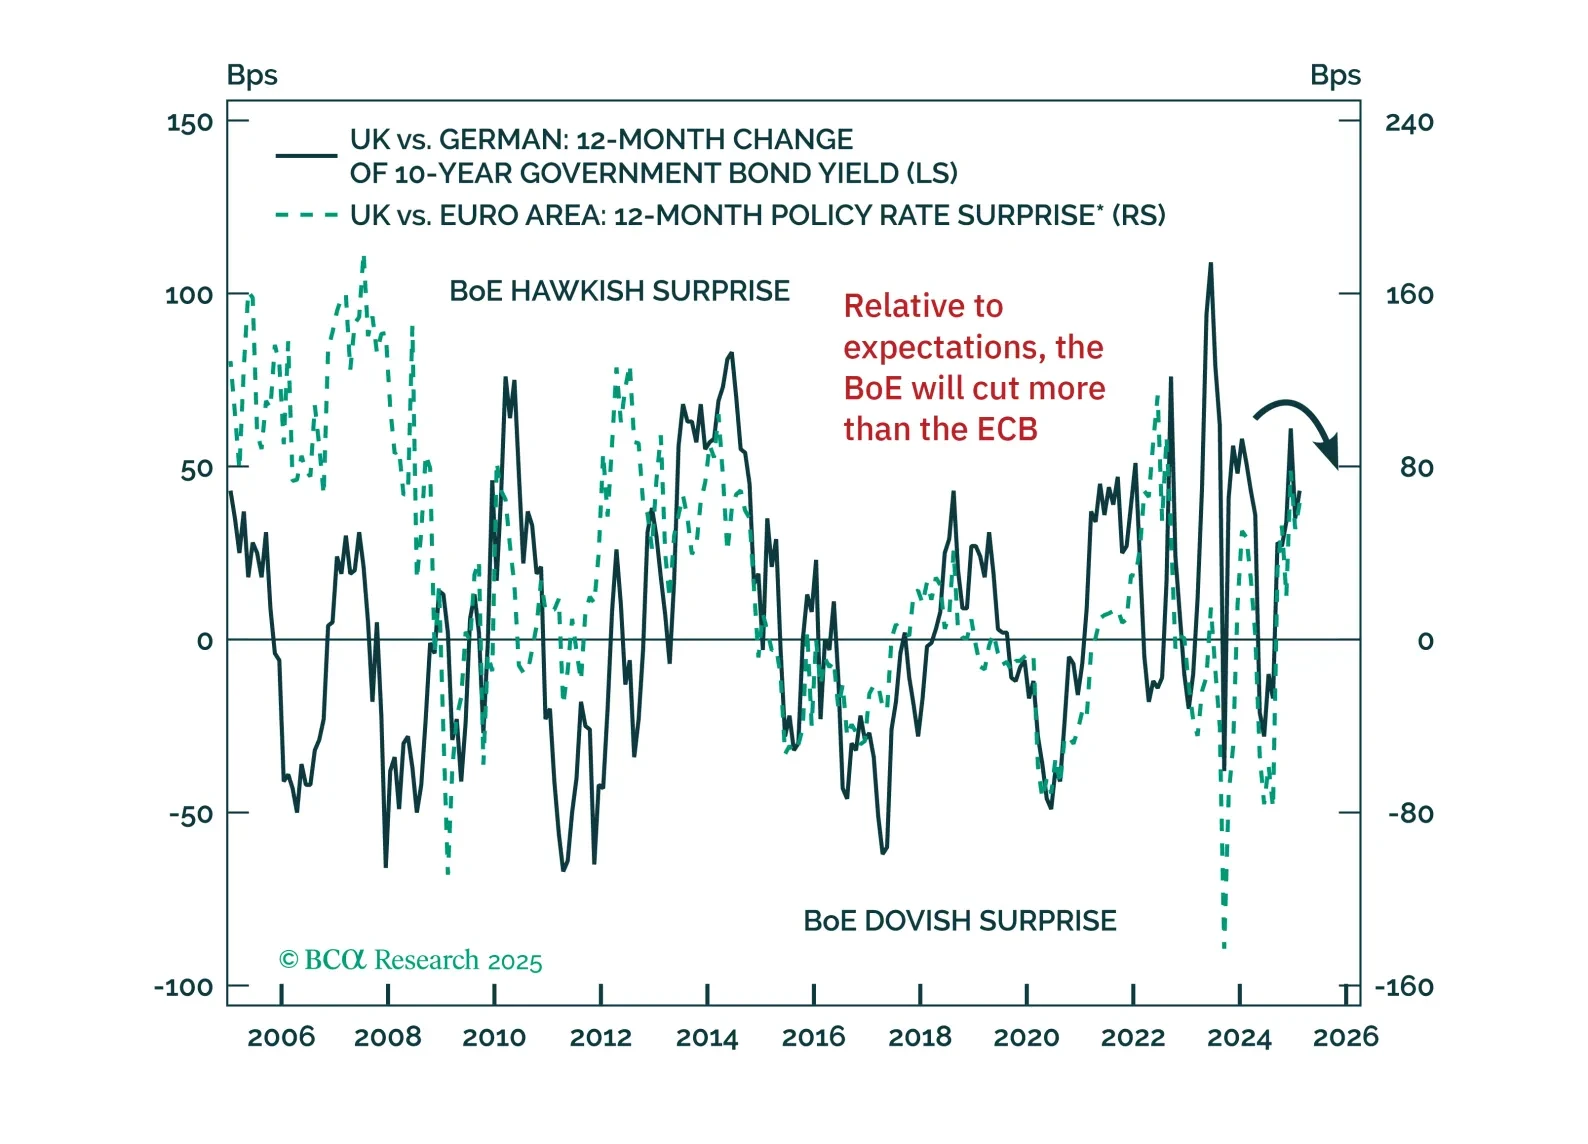
With economic headwinds building and fiscal dynamics shifting, bond markets are at a turning point. Our latest note outlines why German bund yields are set to decline and why UK gilts are poised to outperform — and how to position accordingly.
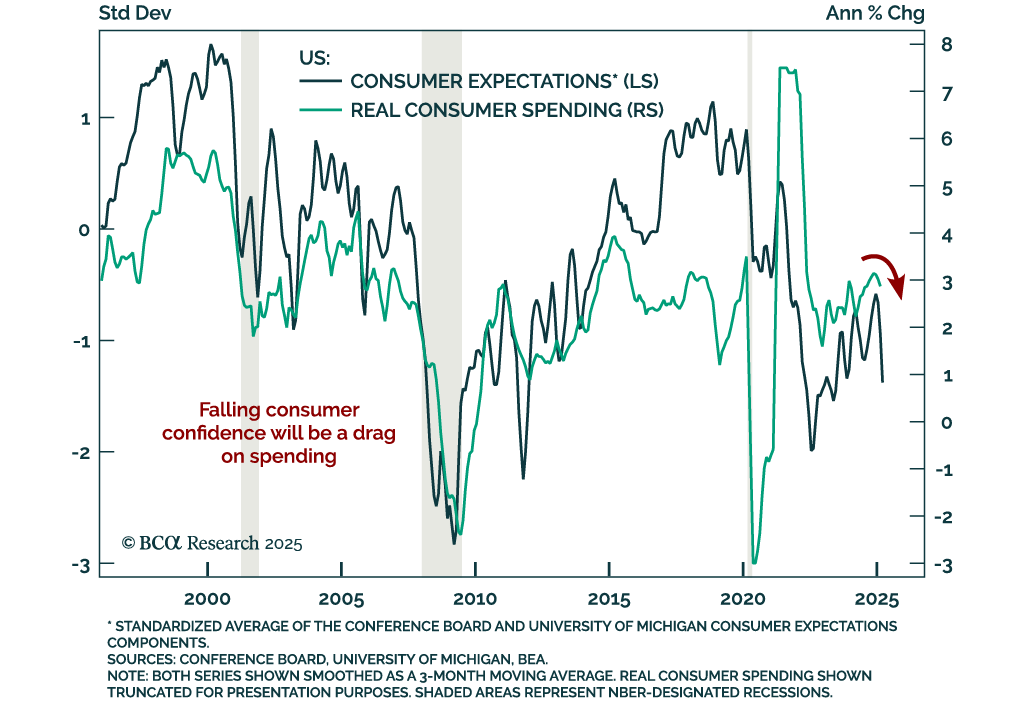
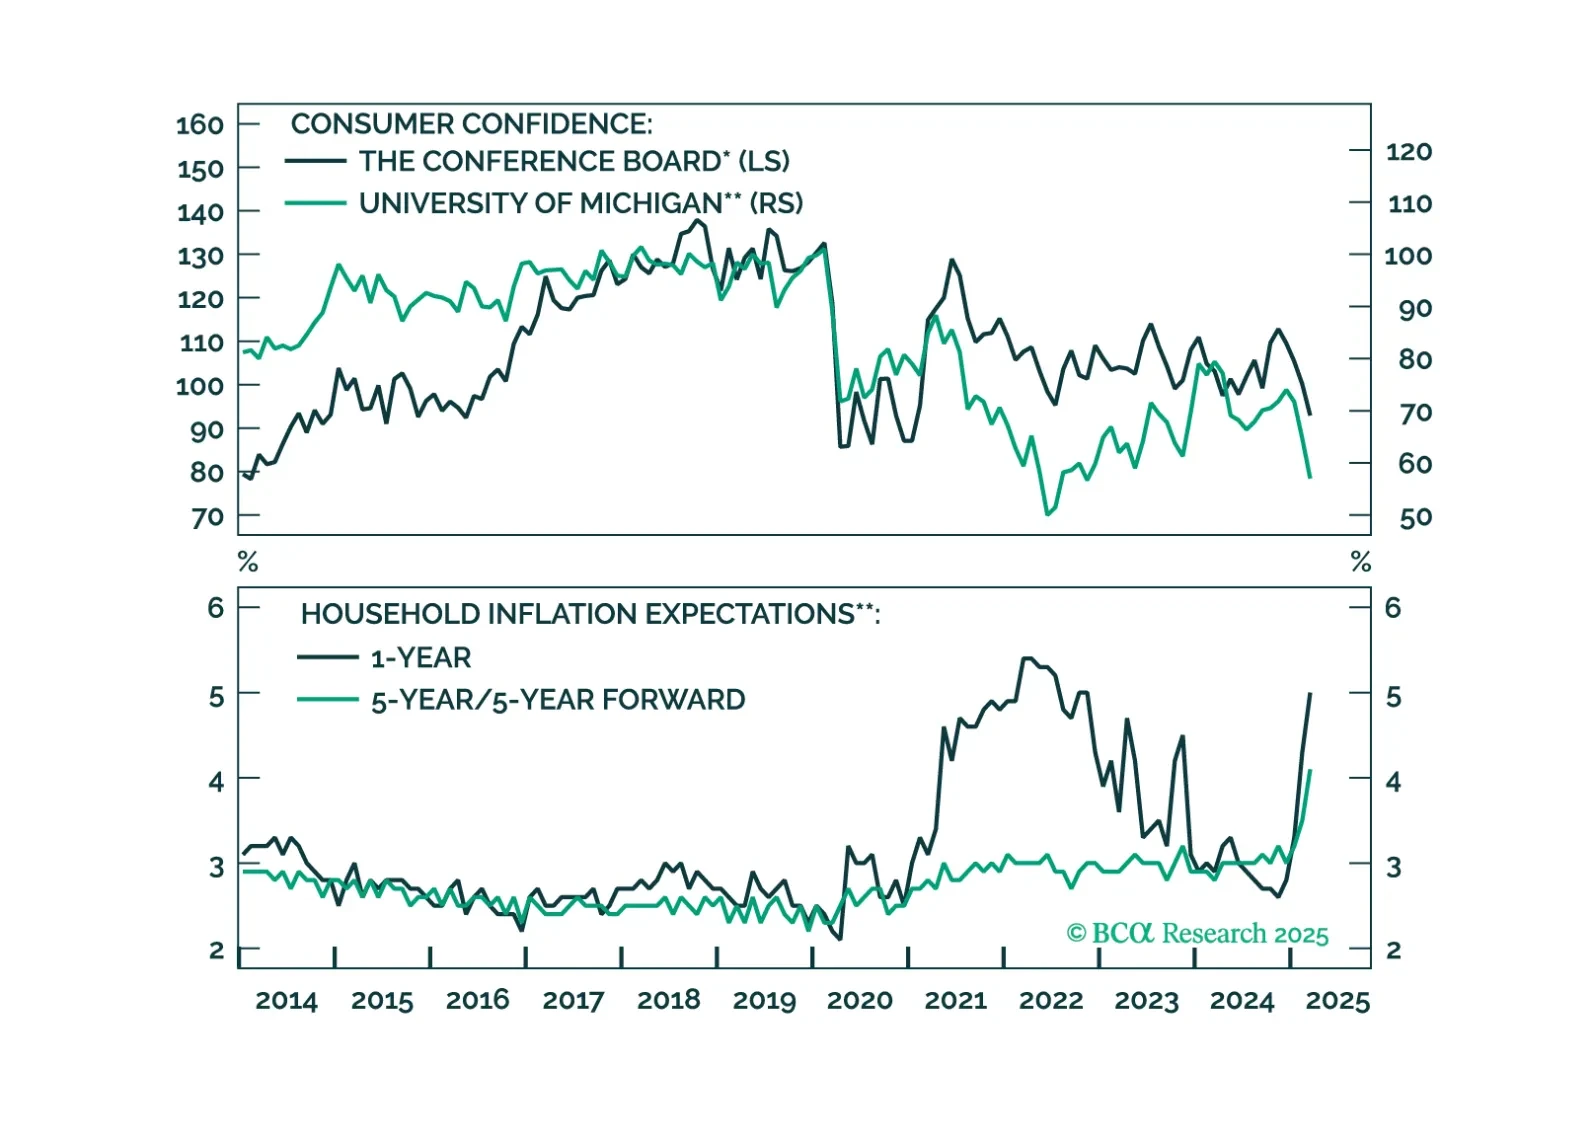
February US PCE data adds to the stagflationary tone, reinforcing our overweight duration stance and tactical short in front-end rates. Core PCE inflation rose 0.4% m/m, lifting the year-on-year rate to 2.8%, matching the Fed’s 2025 projection. Headline held…

This morning’s weak consumer spending and strong inflation data reinforce our sense that the US economy is heading toward recession.