Sector de Productos Básicos y Energía
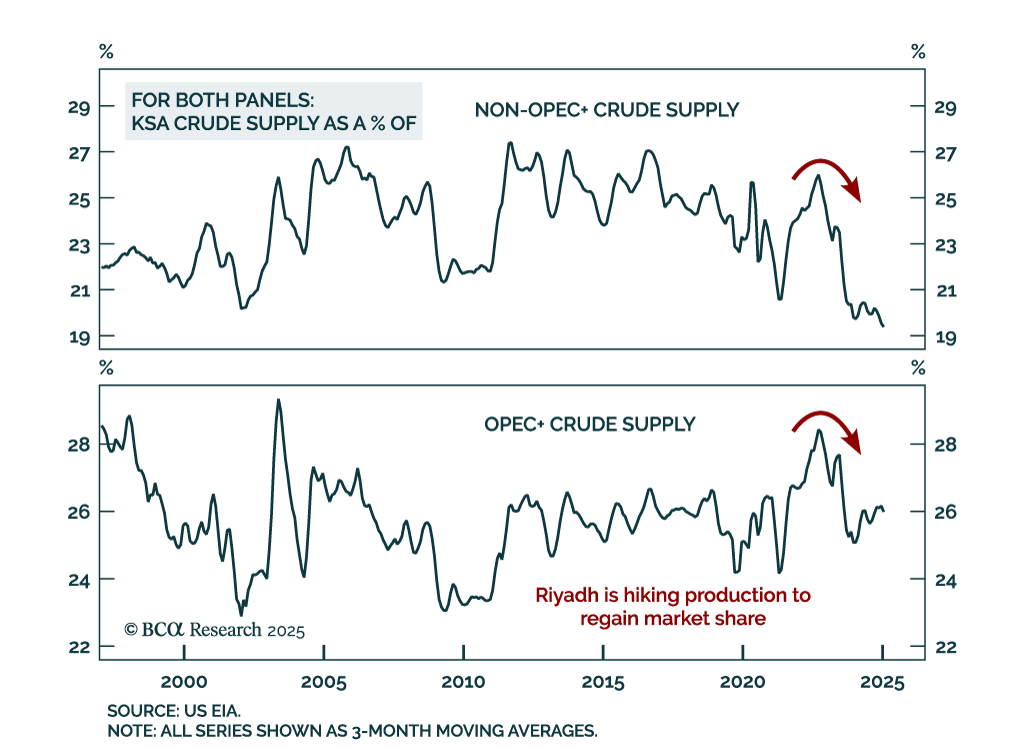
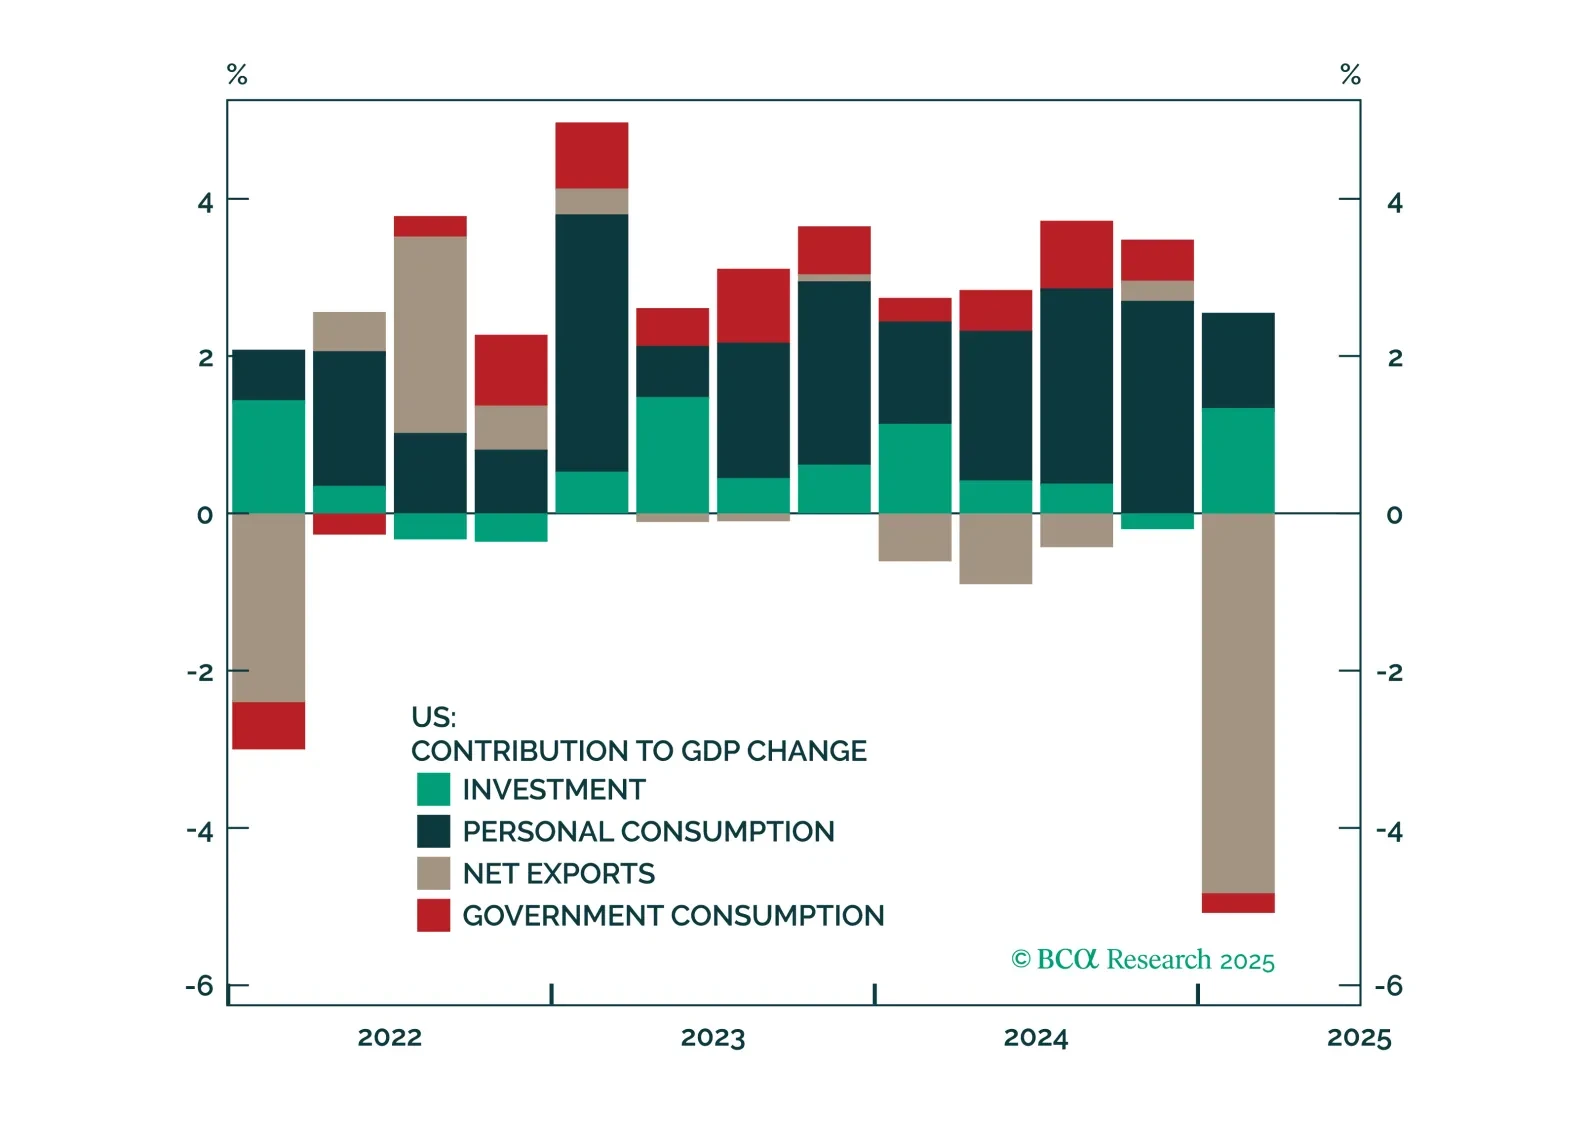
Negotiations on trade, Iran, and Ukraine will prove critical this month. Markets will remain volatile because positive data surprises enable the White House to press its hawkish tariff hikes, while negative surprises force the White House to backpedal.
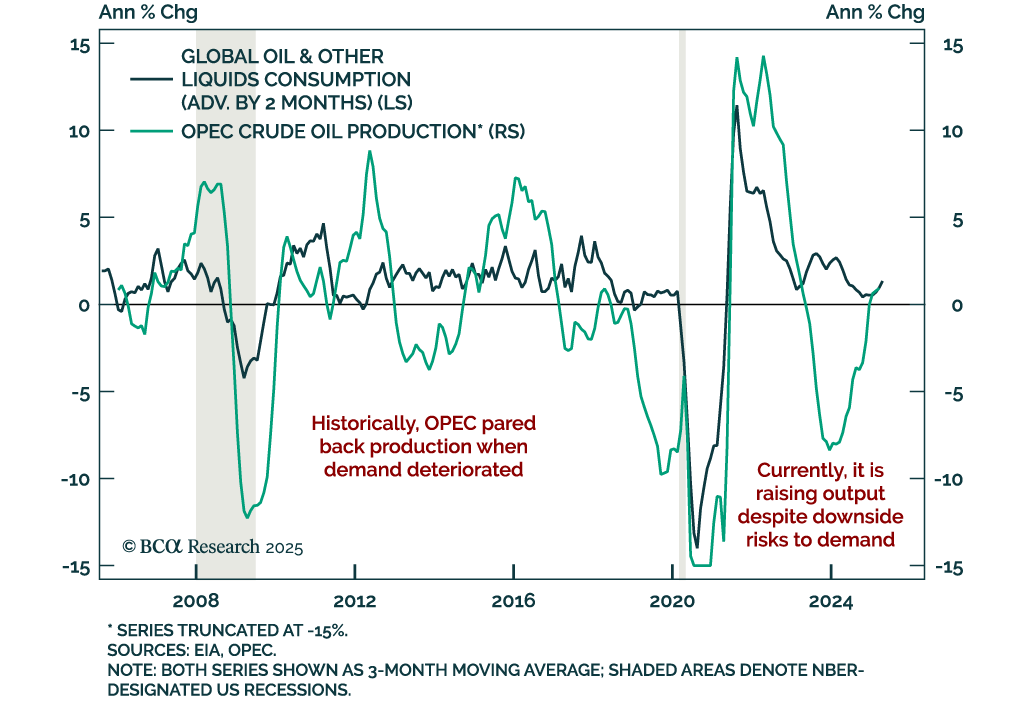
MacroQuant sees the risks to US growth as being to the downside and the risks to inflation as being to the upside. Such a stagflationary brew justifies an underweight on stocks.
MacroQuant considera que los riesgos para el crecimiento de EE. UU. se orientan a la baja y que los riesgos para la inflación se orientan al alza. Una mezcla estanflacionaria de este tipo justifica una infraponderación en acciones.

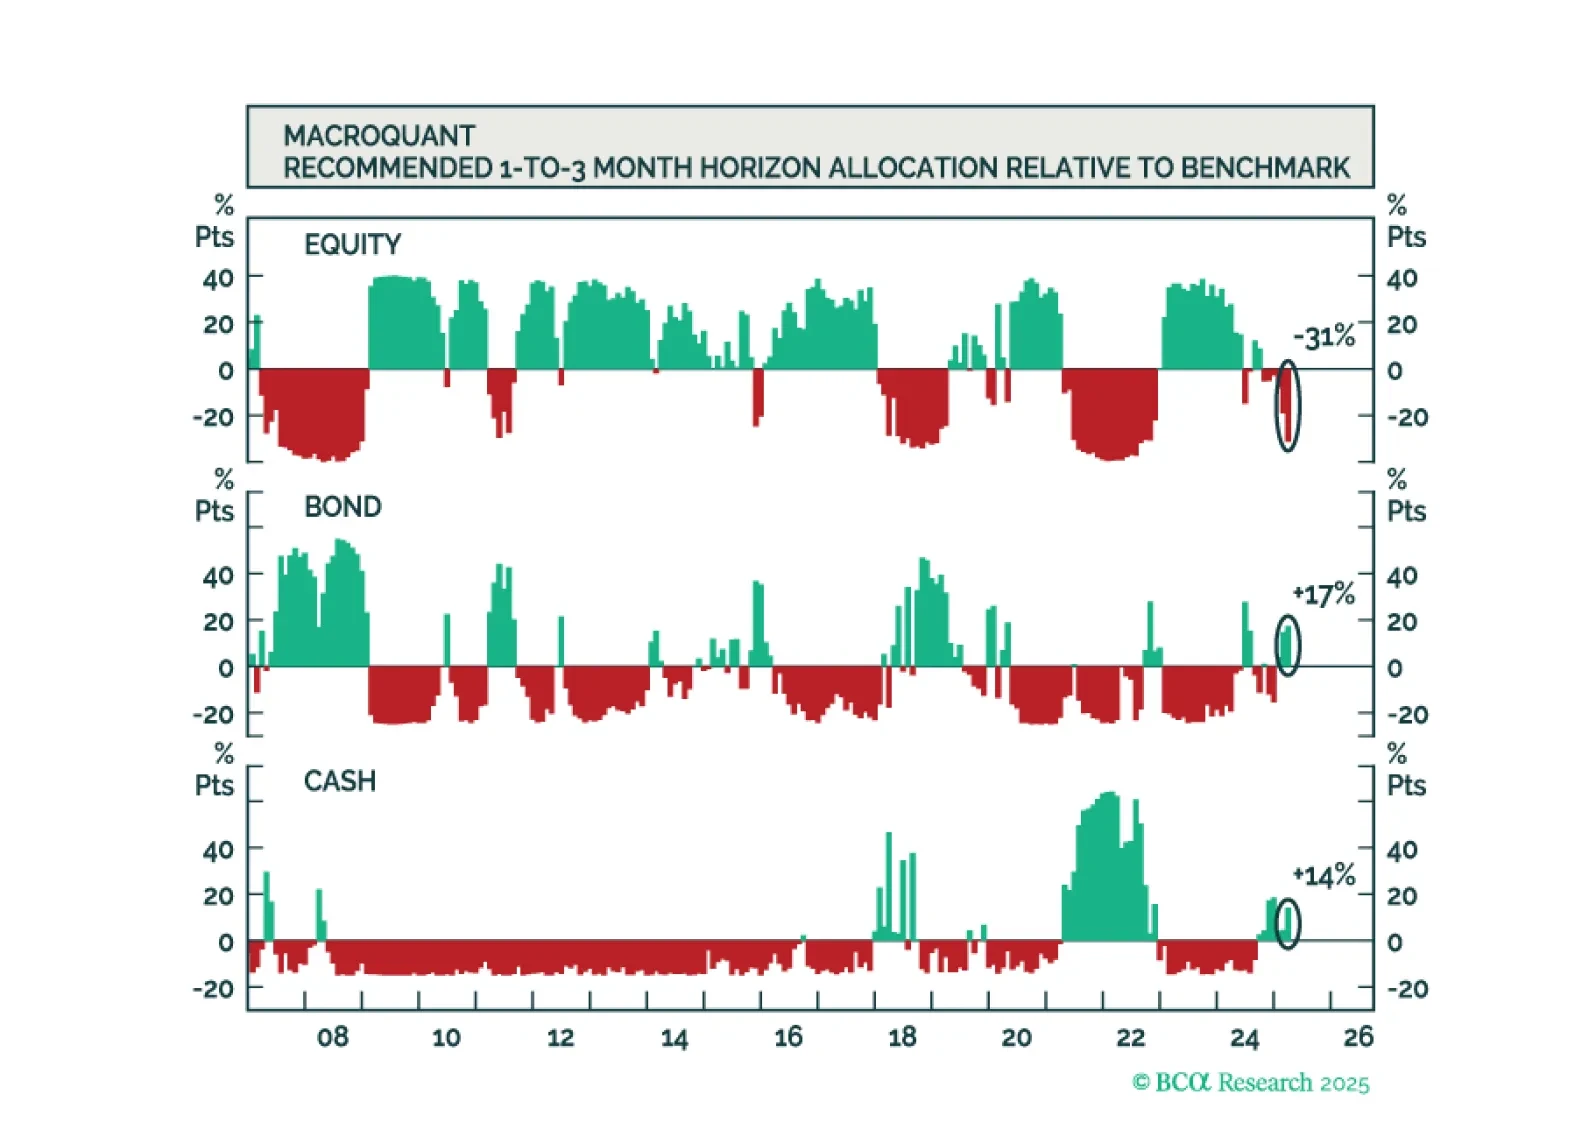
Going into April, MacroQuant recommends a modest underweight on stocks, offset by an overweight on bonds and cash. While MacroQuant is modestly bearish on stocks, we suspect that the downside risks to equities may be greater than what the model assumes.
De cara a abril, MacroQuant recomienda una ligera infraponderación en acciones, compensada por una sobreponderación en bonos y efectivo. Aunque MacroQuant es modestamente bajista en acciones, sospechamos que los riesgos a la baja para las acciones podrían ser mayores de lo que el modelo supone.
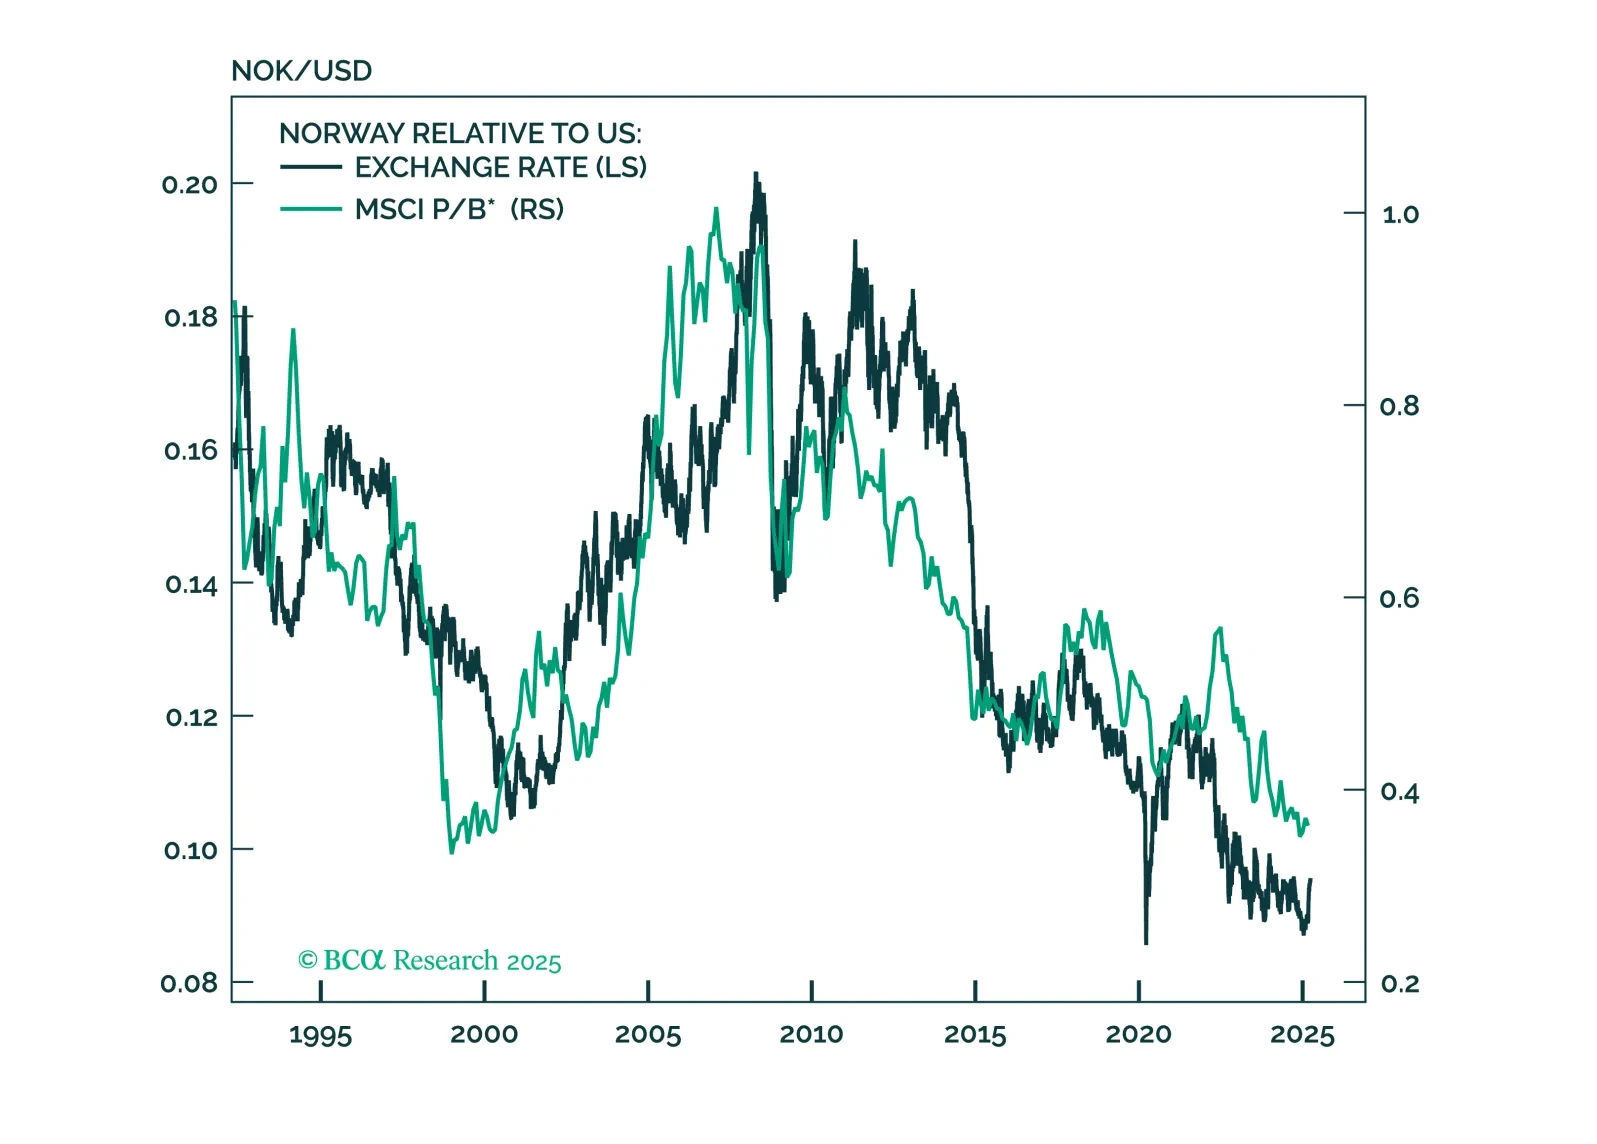
This report looks at investment implications, for Norwegian assets, given the recent meeting, from the Norges Bank.