Sorry, you need to enable JavaScript to visit this website.
Saltar al contenido principal

Mercado laboral

Some thoughts on this morning's employment data and Treasury Secretary Bessent's recent attempts to talk down the 10-year Treasury yield.
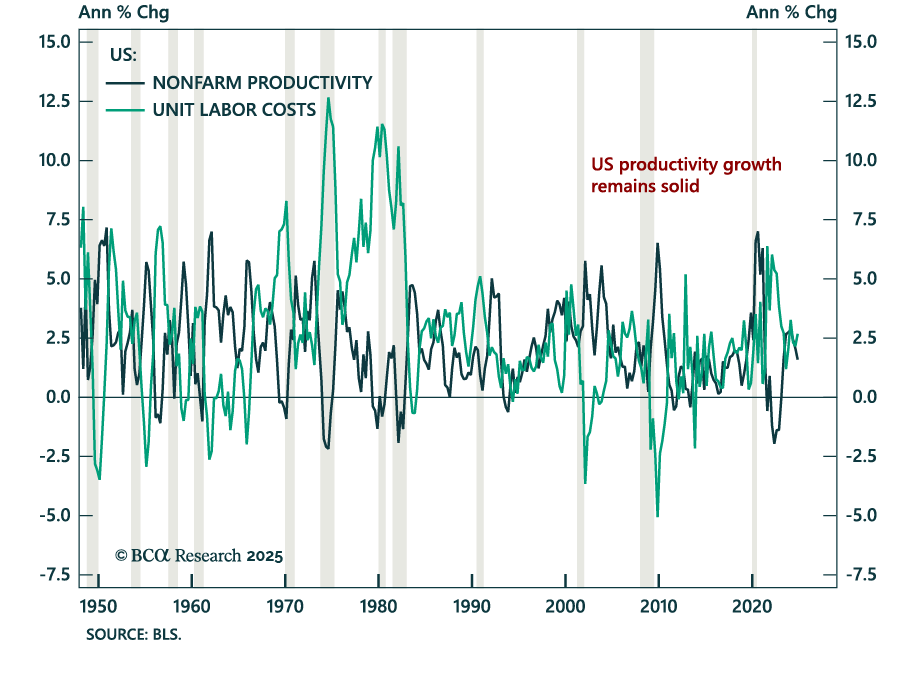
Preliminary nonfarm labor productivity for Q4 came in line with estimates, decreasing to 1.2% annualized growth from an upwardly-revised 2.3%. Unit labor costs growth was lower than expected, but still jumped to 3.0% from a downwardly revised 0.5% in Q3.…

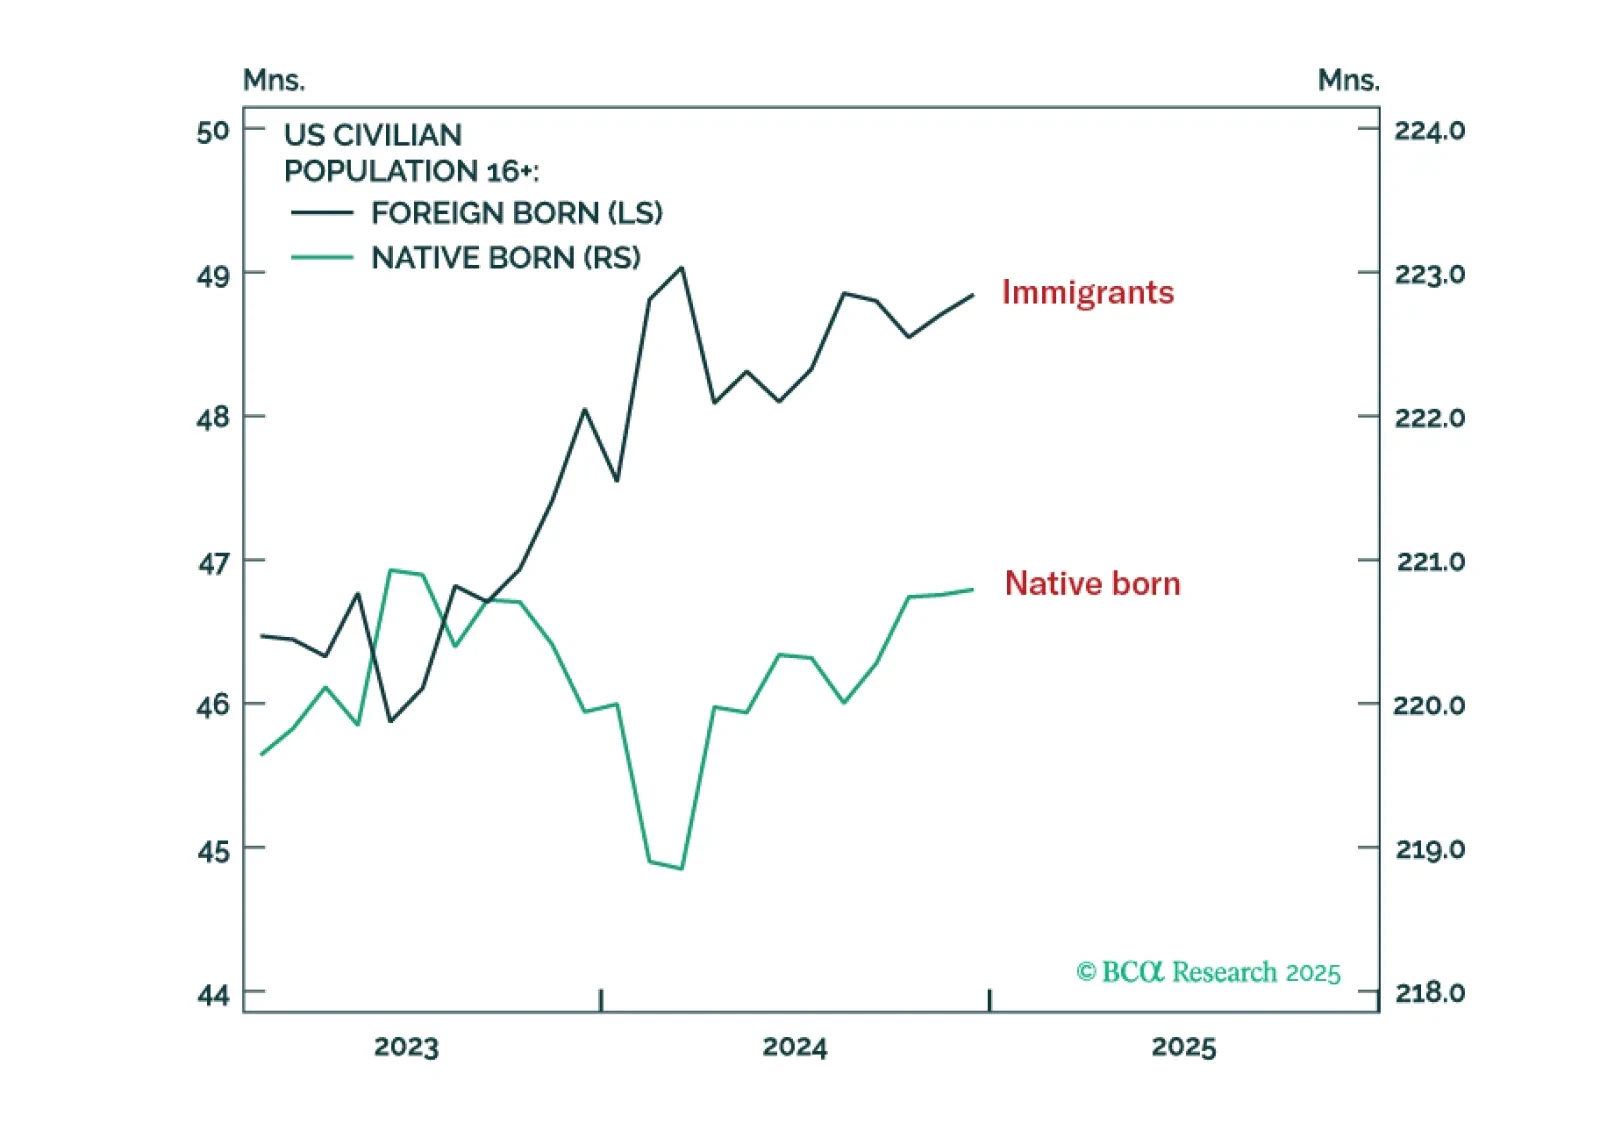
All the growth in the US labour supply since mid-2023 has come from immigration. This means if net immigration comes to a grinding halt, as Trump wants, it will hurt economic growth as well as keep the labour market supply-constrained. An increase in productivity growth could save the day, both to maintain growth and to kill inflation. Yet hopes that AI is about to usher an imminent and sustained boost to productivity growth are misplaced. Hence, expect a slowdown in US growth combined with inflation stuck close to 3 percent, a combination that I call a ‘mini stagflation’. We go through the investment implications. Plus: Tactically overweight Portugal versus Europe.
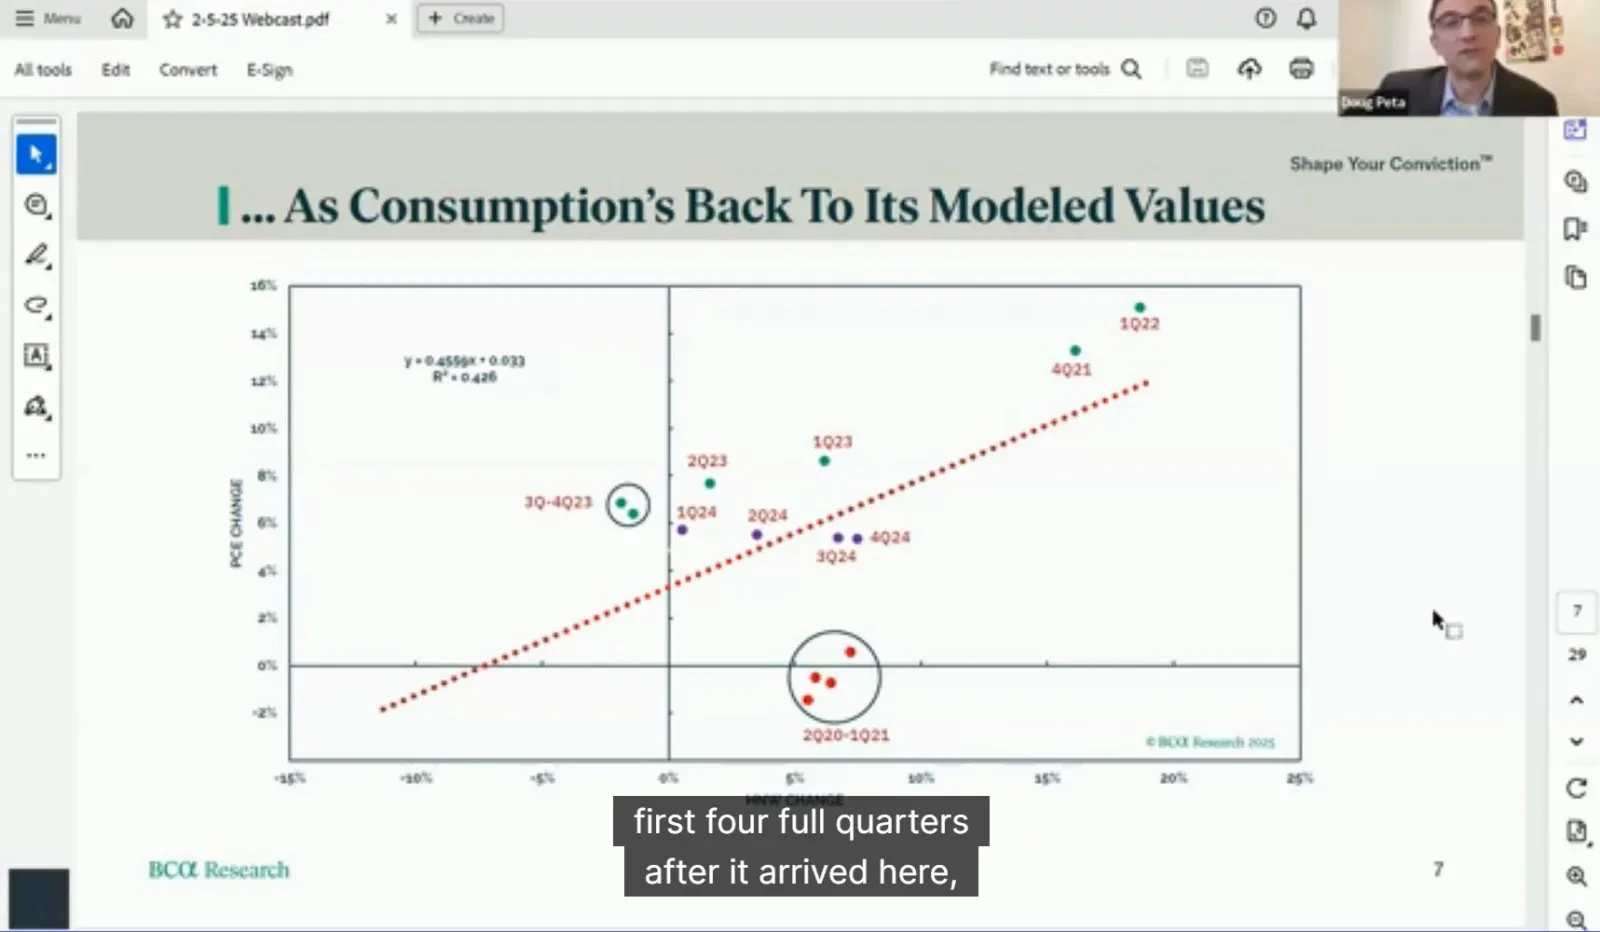
Por favor, únase al estratega jefe de inversiones para EE. UU. de BCA Research, Doug Peta, para un Webcast el miércoles 5 de febrero a las 10:30 AM EST (3:30 PM GMT, 4:30 PM CET).
December job openings missed estimates, decreasing to 7.6m from an upwardly revised 8.2m in November. Quits, hires, but also layoffs all ticked up marginally, leaving the general “slowing-but-not-collapsing” direction of the labor market unchanged. The labor…
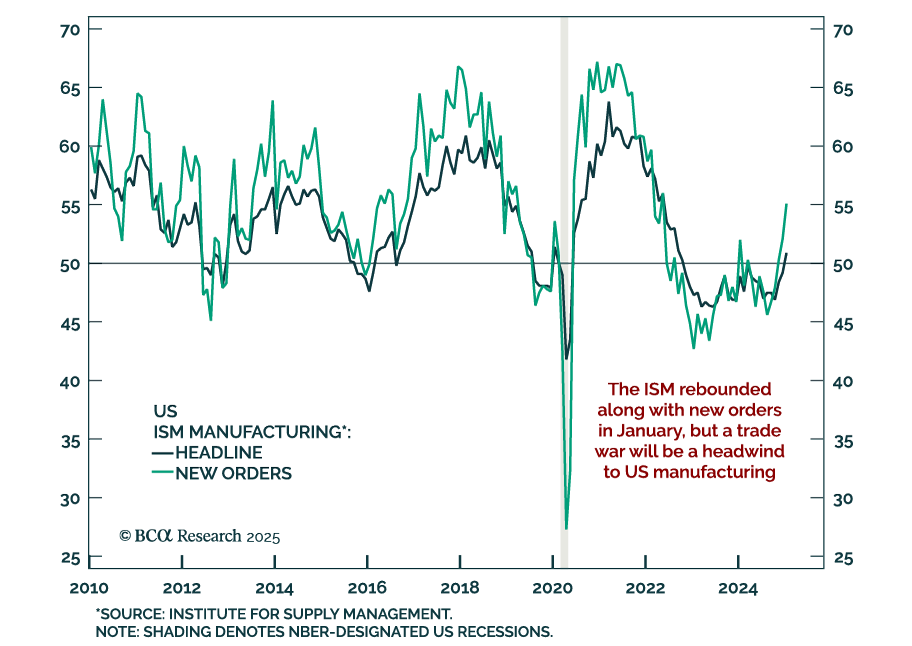
El índice ISM manufacturero de enero superó las estimaciones, aumentando a 50,9 para poner fin a una racha de 26 meses de contracción en la manufactura. Los nuevos pedidos subieron a 55,1 desde 52,1. El empleo también volvió a la expansión. Los precios…
December PCE inflation was in line with expectations, with headline inflation at 0.3% m/m (2.6% y/y) and core at 0.2% m/m (2.8% y/y). The Q4 employment cost index also came in line with expectations at 0.9% q/q. Inflation is currently running below the Fed’s…
The January Tokyo CPI came in stronger than expected, with headline inflation accelerating to 3.4% y/y from 3.0%, and “core core” (ex. fresh food and energy) accelerating to 1.9% from 1.8%. The jobless rate also decreased 0.1% to 2.4% in December. Japan’s…

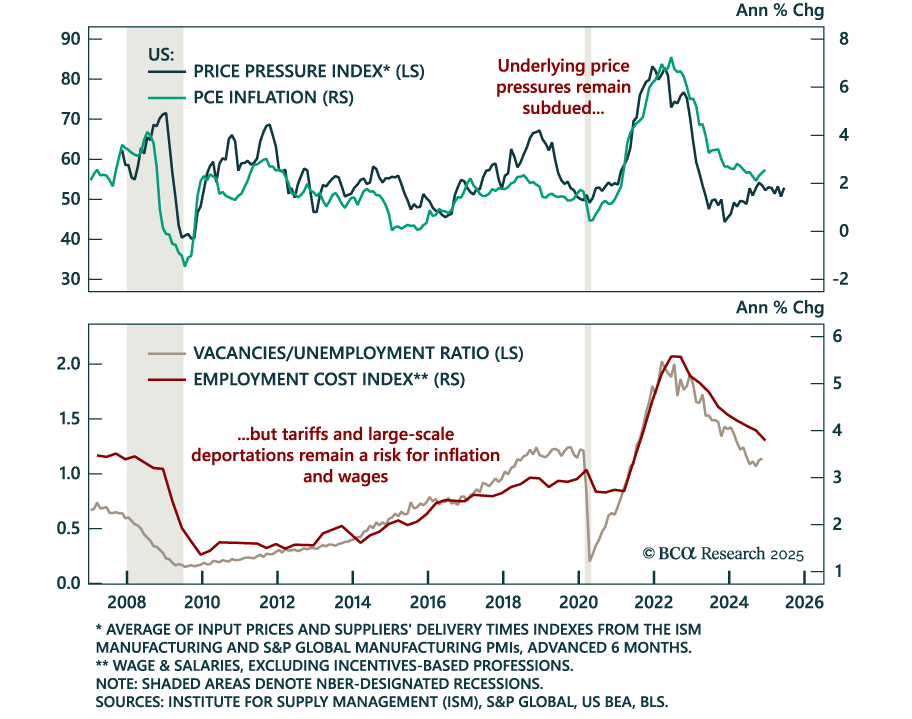
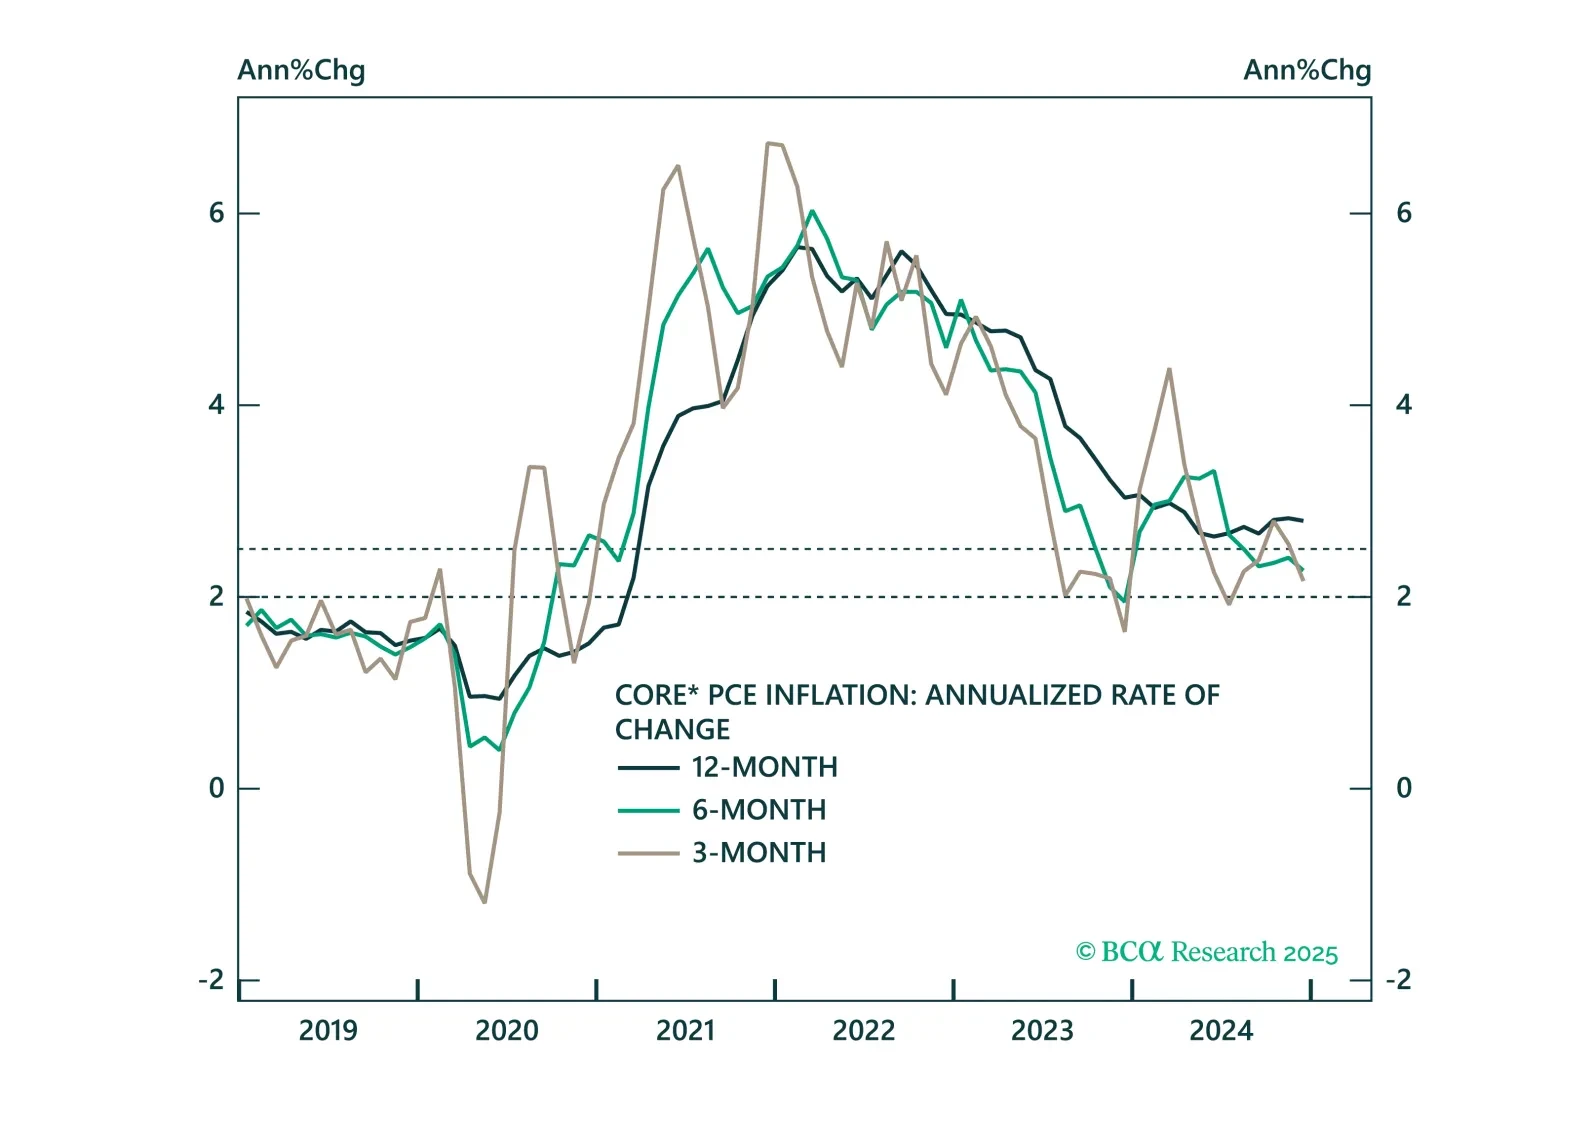
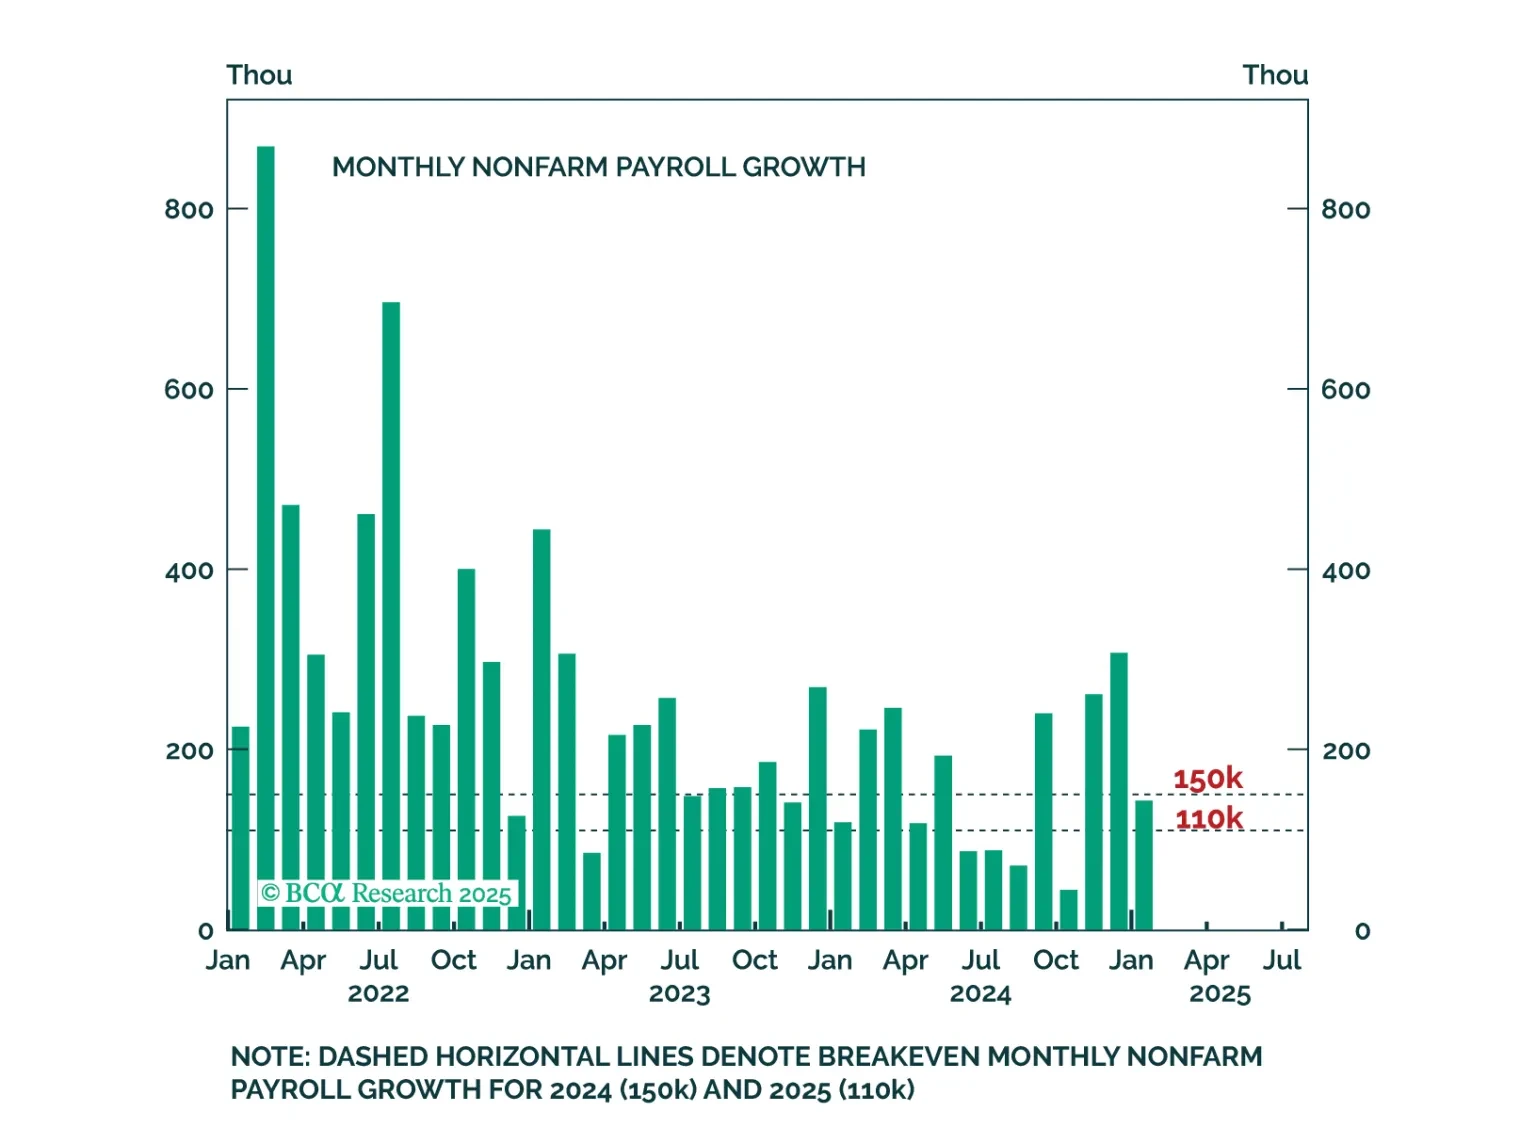
Core PCE inflation came in soft this morning and is tracking well below the Fed’s 2025 forecast. We highlight three upside risks to inflation and preview next week’s employment report.
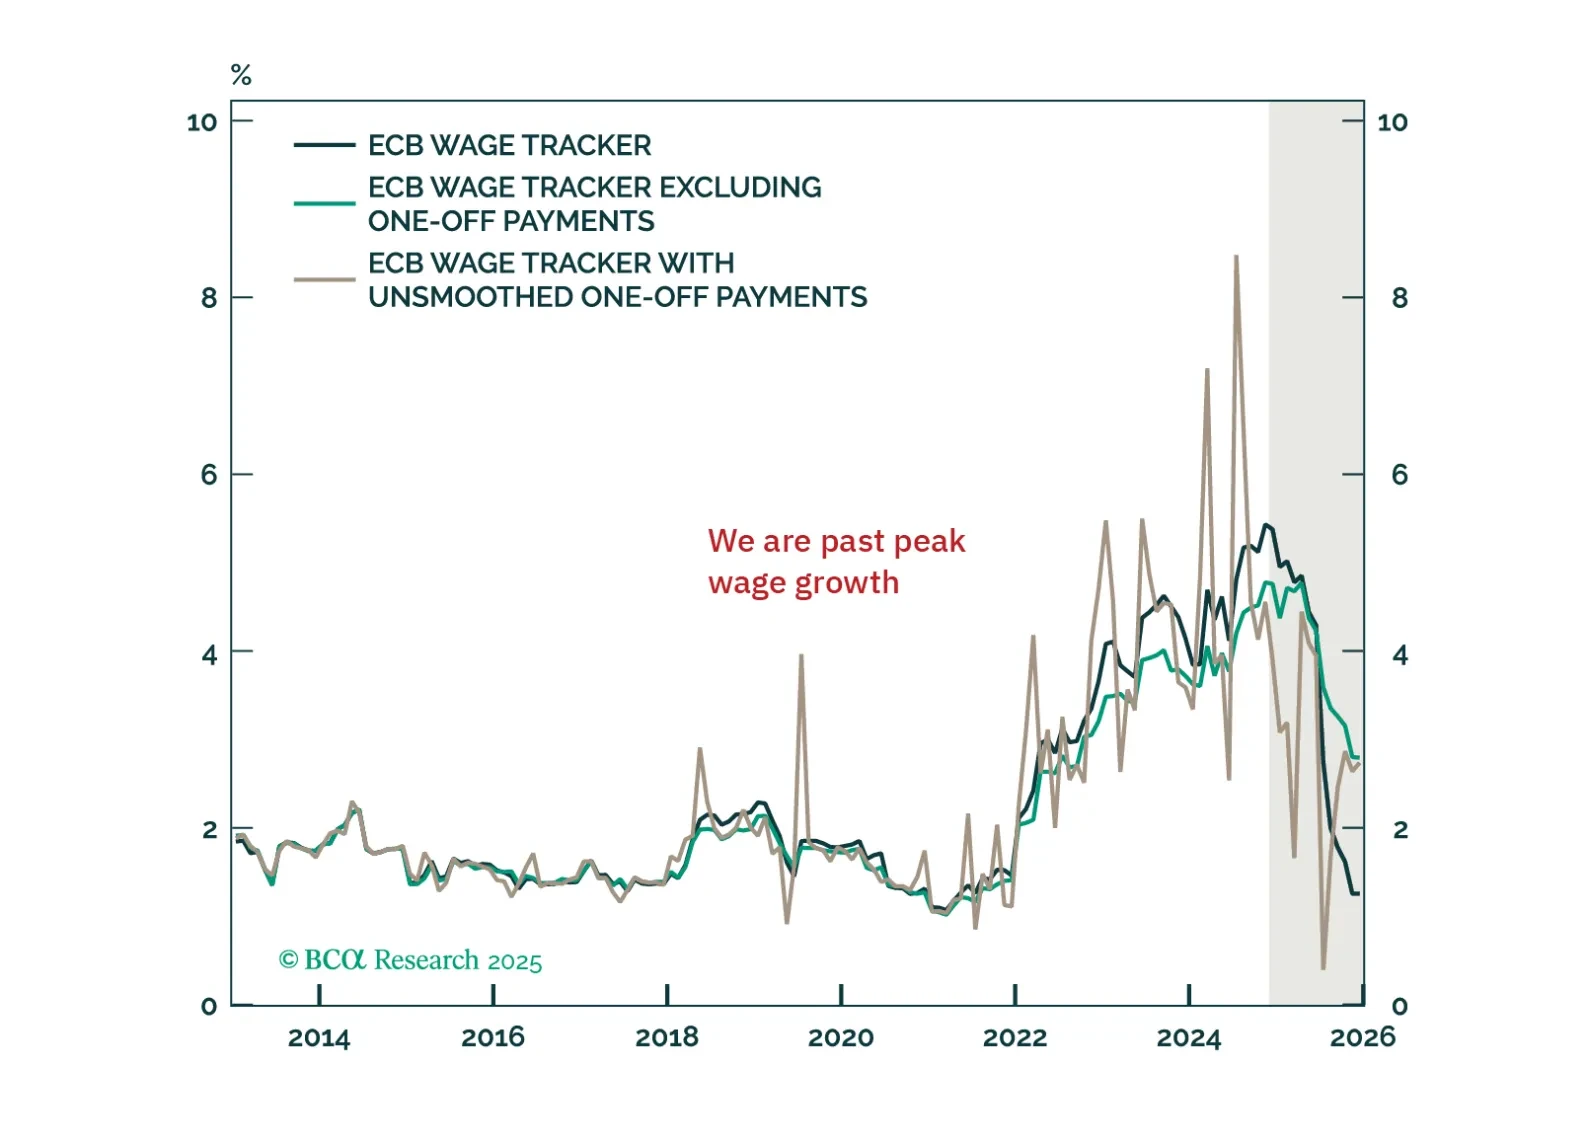
The ECB cut its deposit rate to 2.75%, as was widely anticipated. President Christine Lagarde did not provide any fireworks, but the Governing Council’s message was clear: Policy is restrictive, and inflation will fall further. As a result, if we combine our economic forecasts for the Eurozone with Frankfurt’s data dependency, we continue to expect the ECB’s deposit rate to settle below 2%. Consequently, German bond yields have downside, and the euro has yet to bottomed.