Liquidez
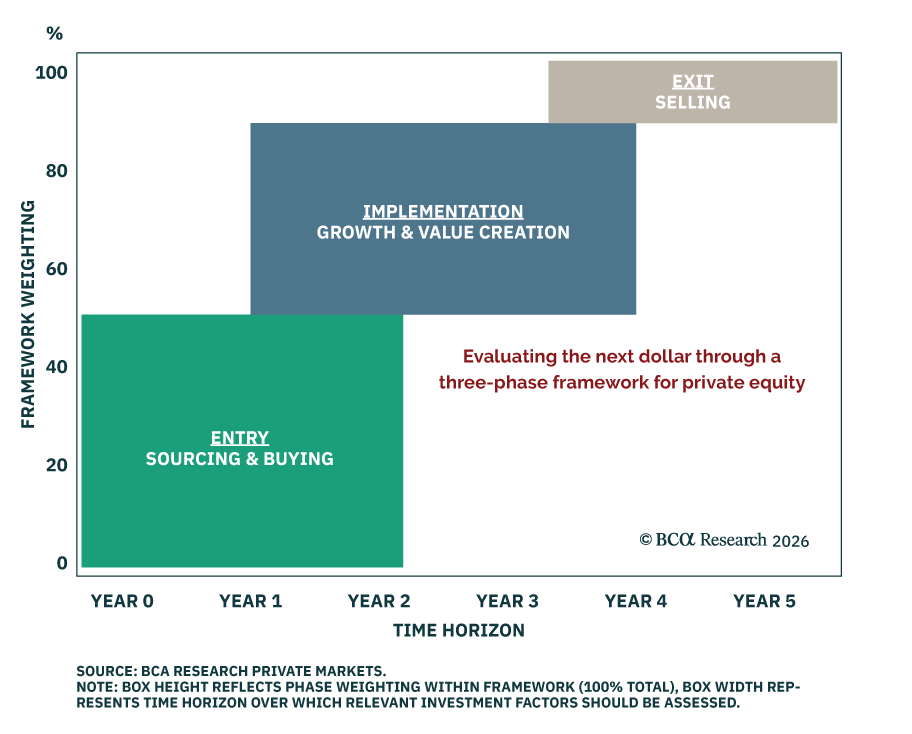

Los vehículos de fondos de Private Equity pueden extenderse más allá de 10 años, pero los activos subyacentes que impulsan el rendimiento normalmente no lo hacen. Proporcionamos el marco para que los inversores capitalicen esta realidad.
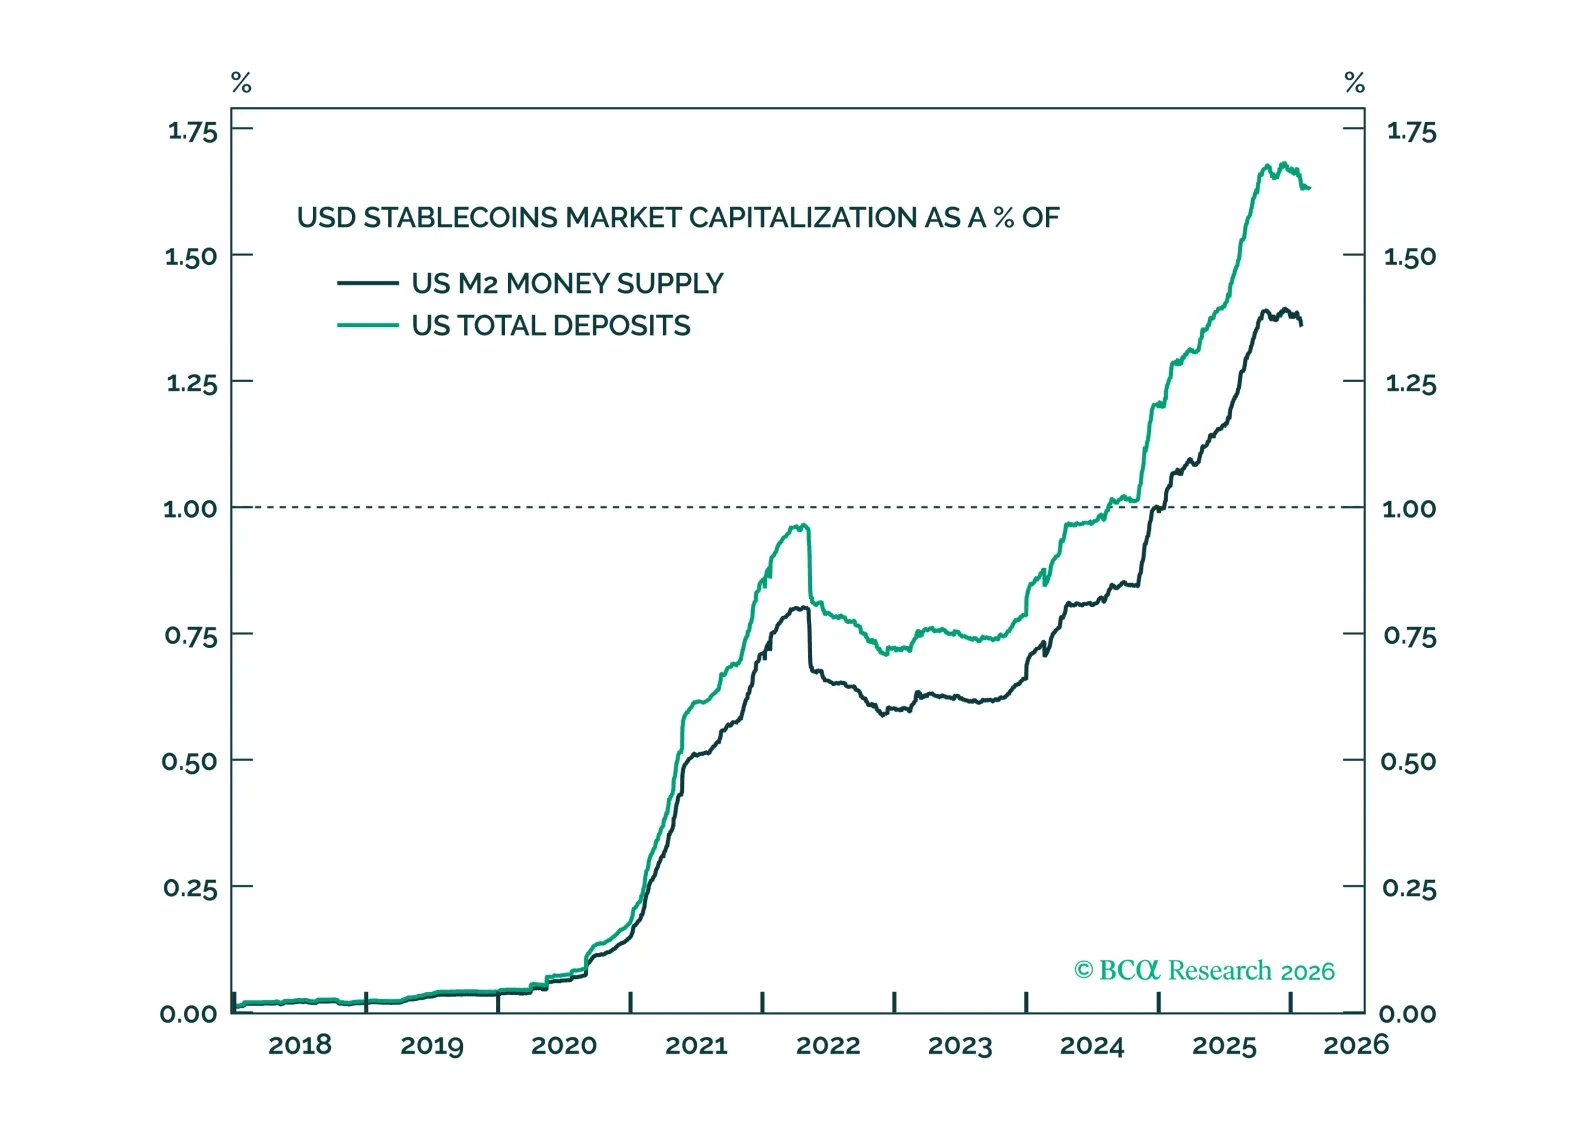
Las stablecoins están evolucionando de un instrumento cripto de nicho hacia una capa financiera de relevancia macro. Este Informe Especial traza los canales de transmisión y las consecuencias para el mercado de Treasury, la dinámica de financiación bancaria y la huella global del dólar.
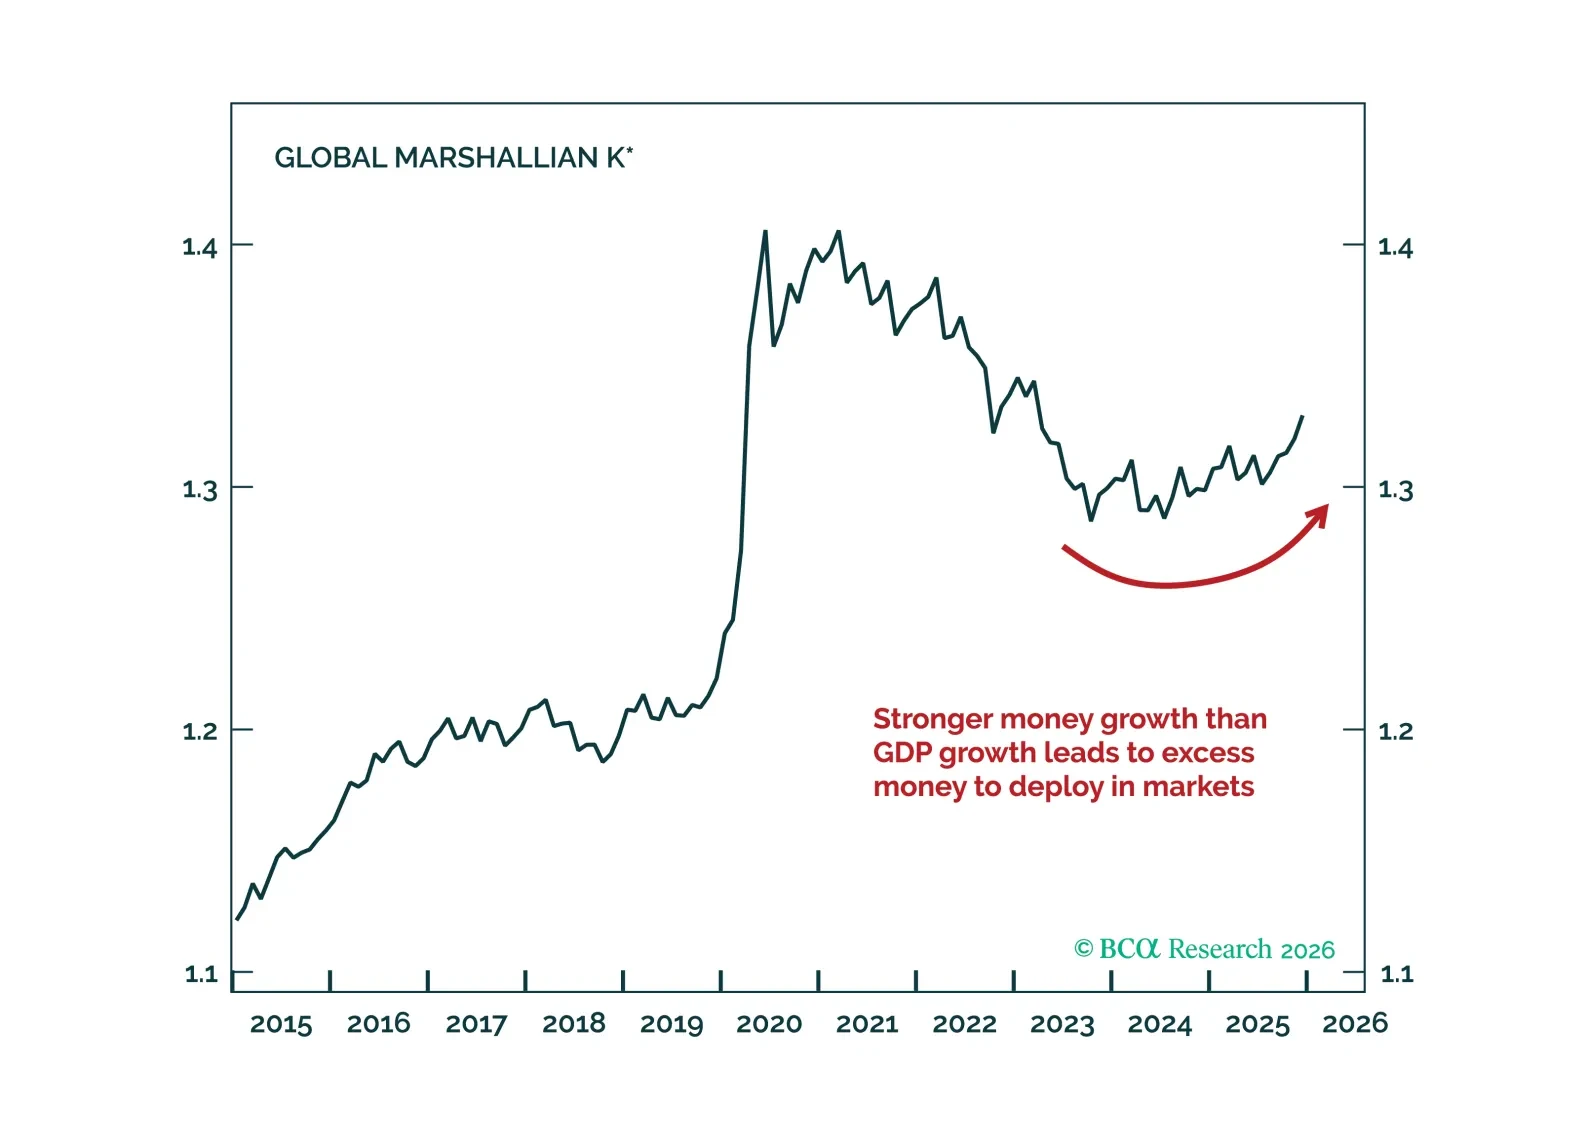
La liquidez global ha sido la variable macro decisiva en 2025 y debería seguir siendo, en términos generales, favorable durante la mayor parte de 2026. Por tanto, nos mantenemos neutrales en renta variable frente a renta fija (las valoraciones están estiradas), mantenemos un sesgo positivo hacia los metales (especialmente el oro) y preferimos las acciones europeas y japonesas frente a las estadounidenses. El riesgo clave es un cambio de régimen de volatilidad a finales de 2026, cuando los temores de sobrecalentamiento obliguen a un reajuste de los tipos de interés.
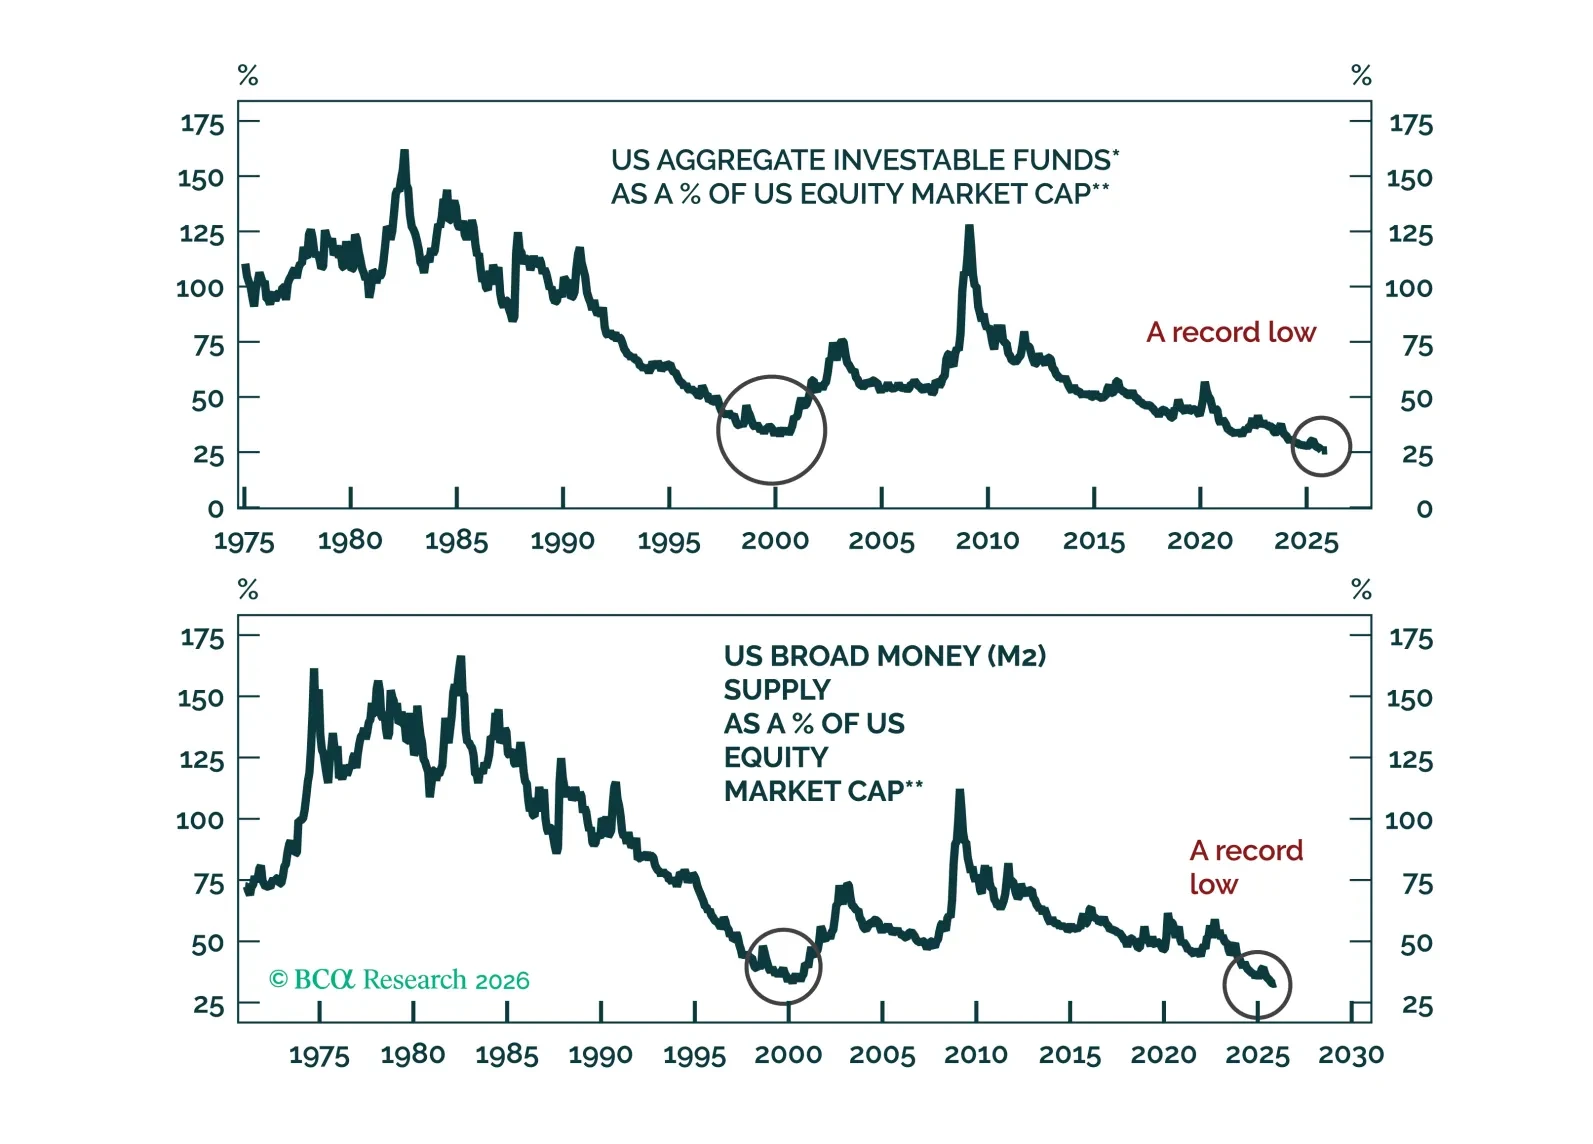
Contrario a la narrativa generalizada, hay poco efectivo en reserva. La relación agregada entre los fondos invertibles y la capitalización bursátil de las acciones está en un mínimo histórico en EE. UU. y en niveles muy bajos en otros mercados desarrollados.

China is trying to export its way out of its economic slowdown while the US has already formed a hawkish consensus on foreign policy and trade. Investors should take cover as global financial markets are underrating the new phase of the trade war, which will escalate from here.
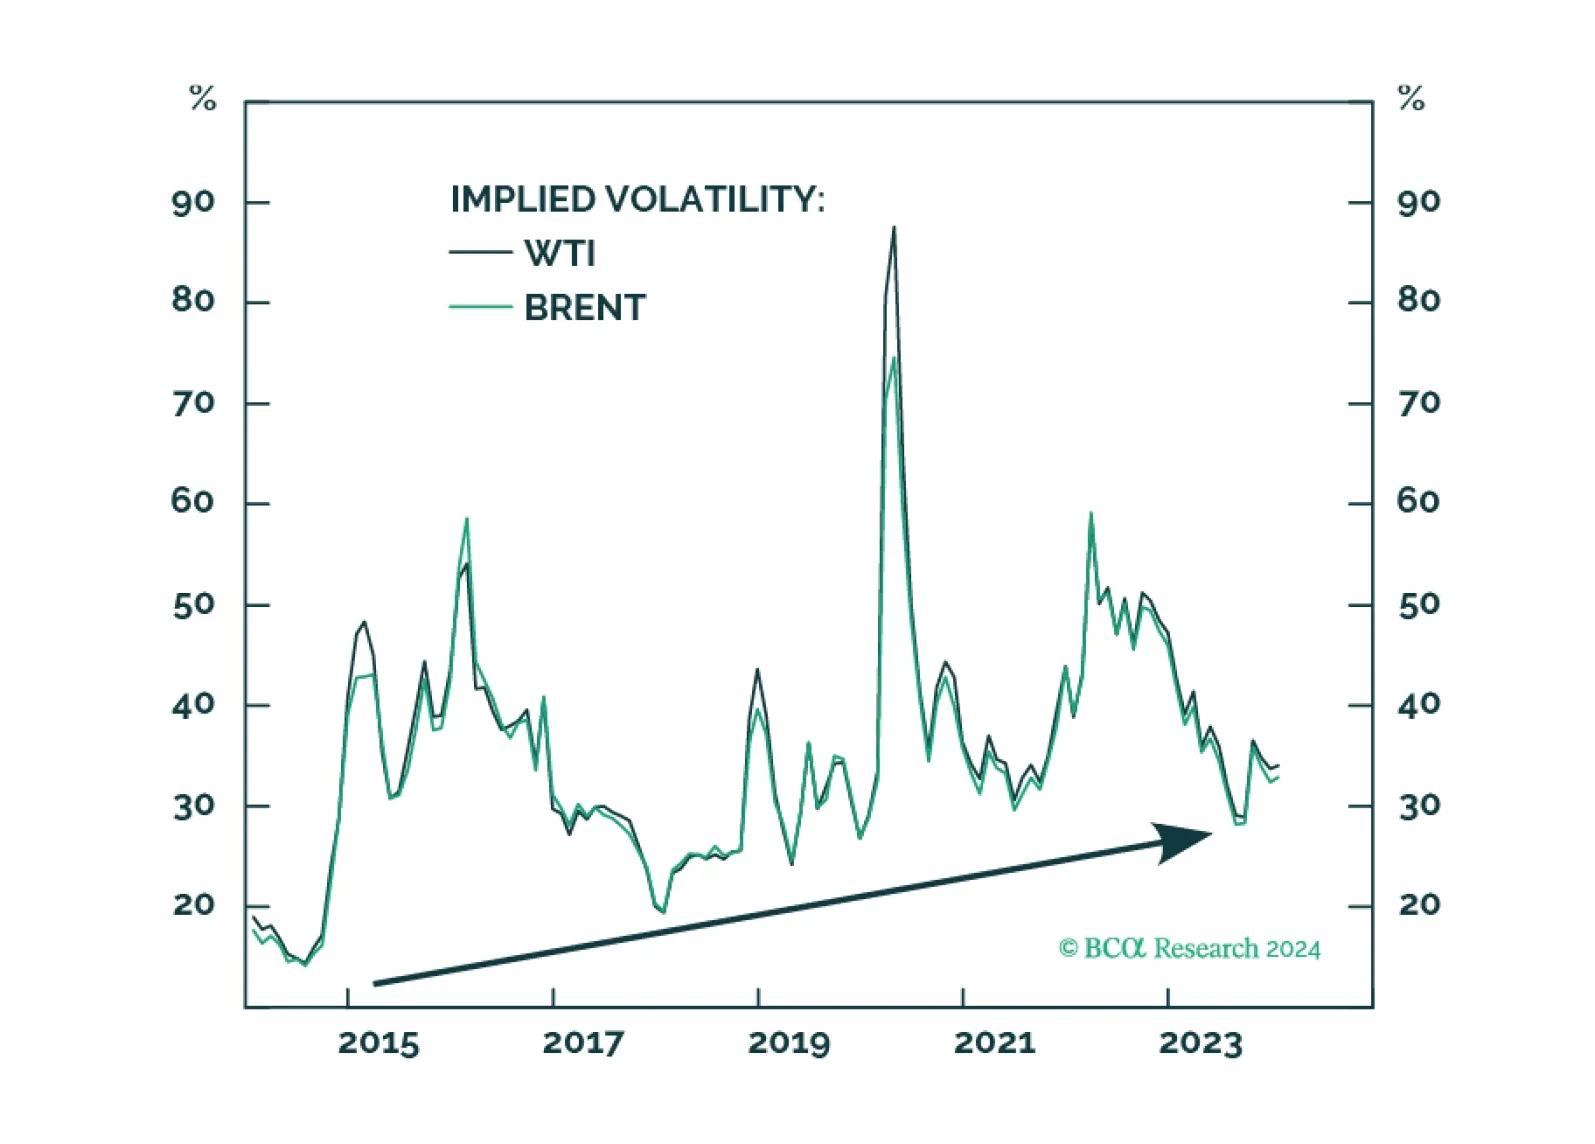
Commodity volatility will continue its rising trend since 2014. The US is on the brink of a major election, the outcome of which could reduce its willingness to engage with the outside world. So, states seeking to carve out their own spheres of influence are incentivized to raise the economic costs to the US and discourage its influence in their regions. These states can do this by interfering in key trading routes in their regions. As a result, geopolitical threats to maritime chokepoints are a structural as well as cyclical problem and will persist due to the revival of superpower competition.
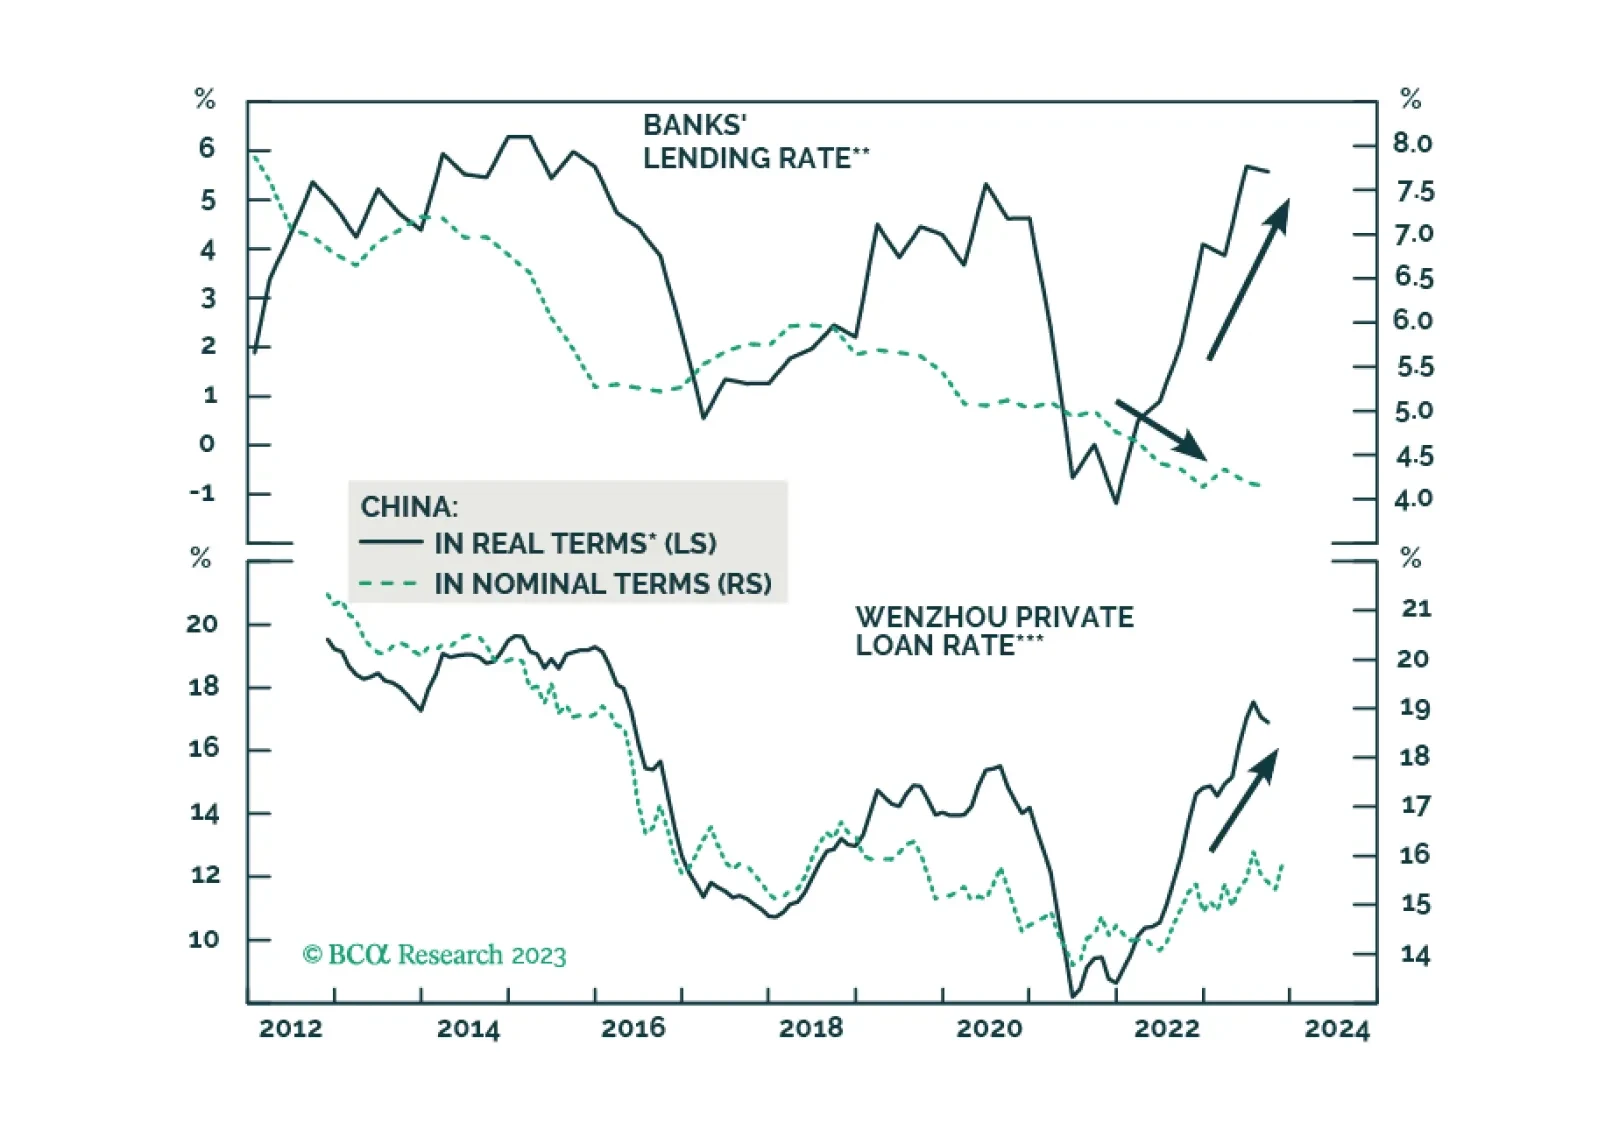
The statement from last week’s Central Economic Work Conference indicates that Chinese authorities are still not considering large-scale stimulus in 2024. Odds are that a full-fledged business cycle recovery in 2024 is unlikely. Chinese share prices remain vulnerable, and strengthening in the RMB will be short-lived.
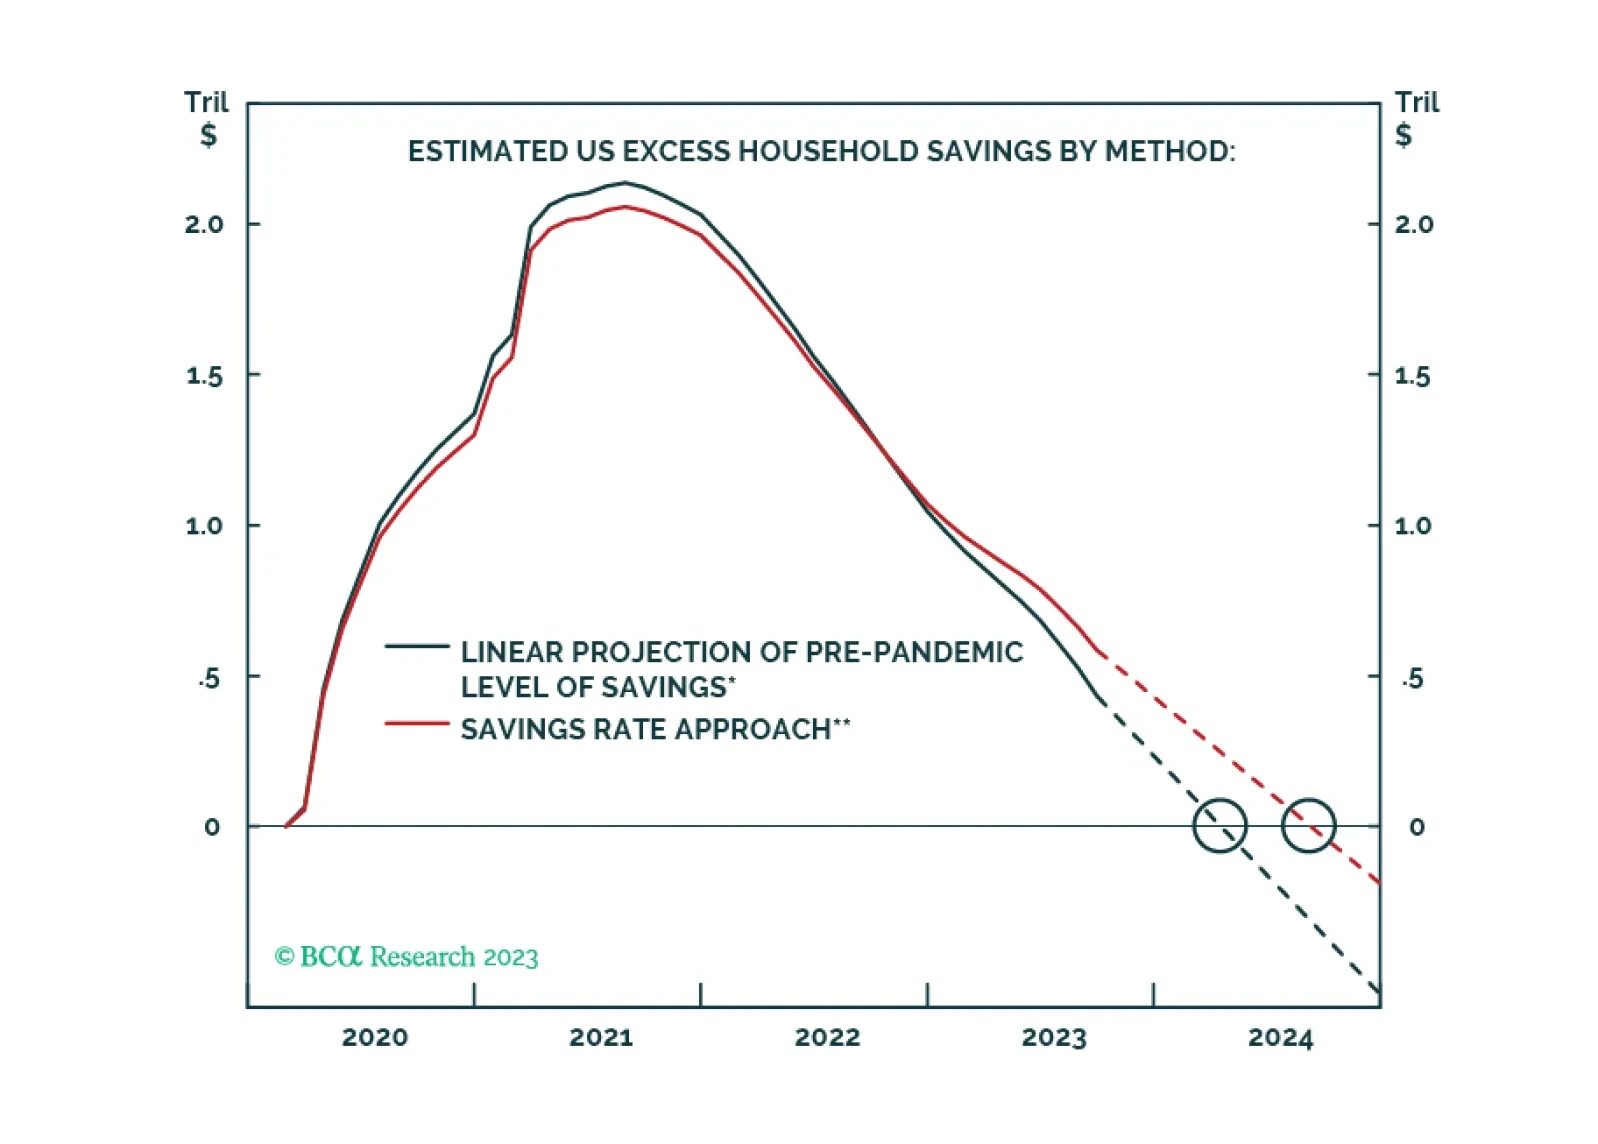
Today, we are sending you the BCA annual outlook for 2024. The report is an edited transcript of our recent conversation with Mr. X and his daughter, Ms. X, who are long-time BCA clients with whom we discuss the economic and financial market outlook for the next twelve months toward the end of each year.
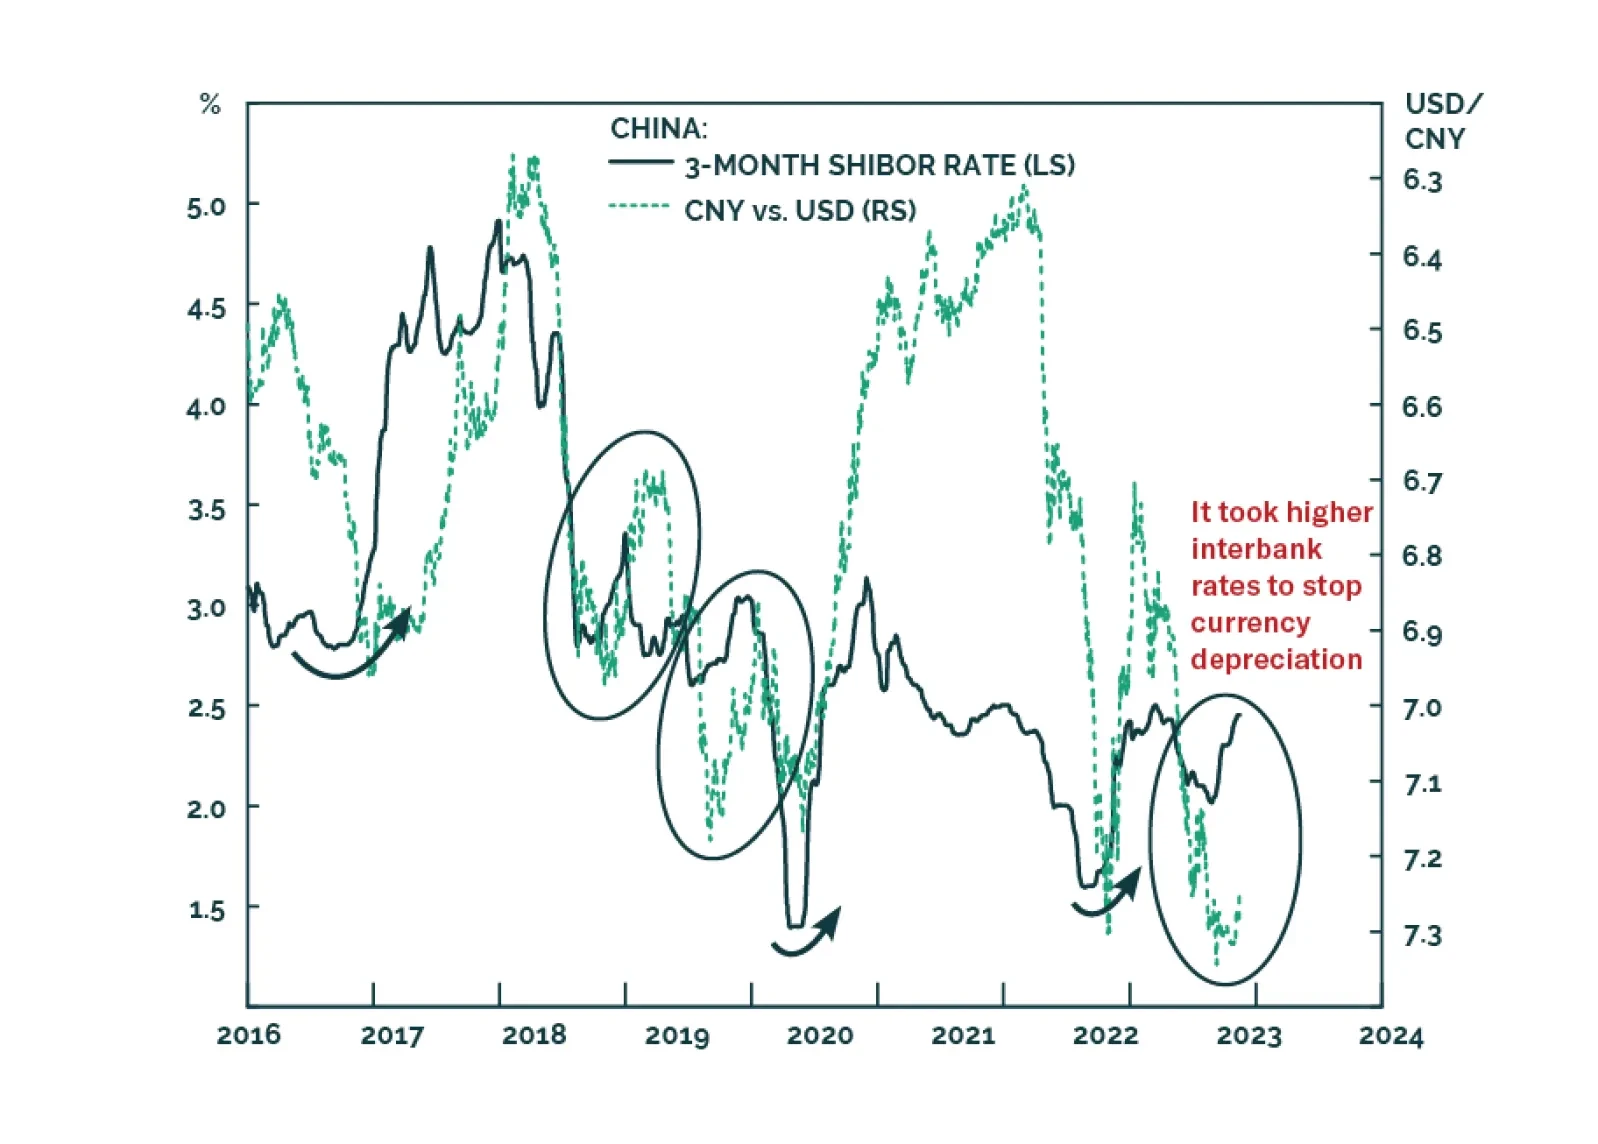
Many commentators have attributed the latest increase in Chinese interest rates to an improving economy, the large issuance of government bonds, the tax payments season, and other technical factors. Yet, these explanations are missing the key point: the PBoC has steered interbank rates higher to defend the currency. Higher borrowing costs are the last thing the mainland economy now needs.