Economía
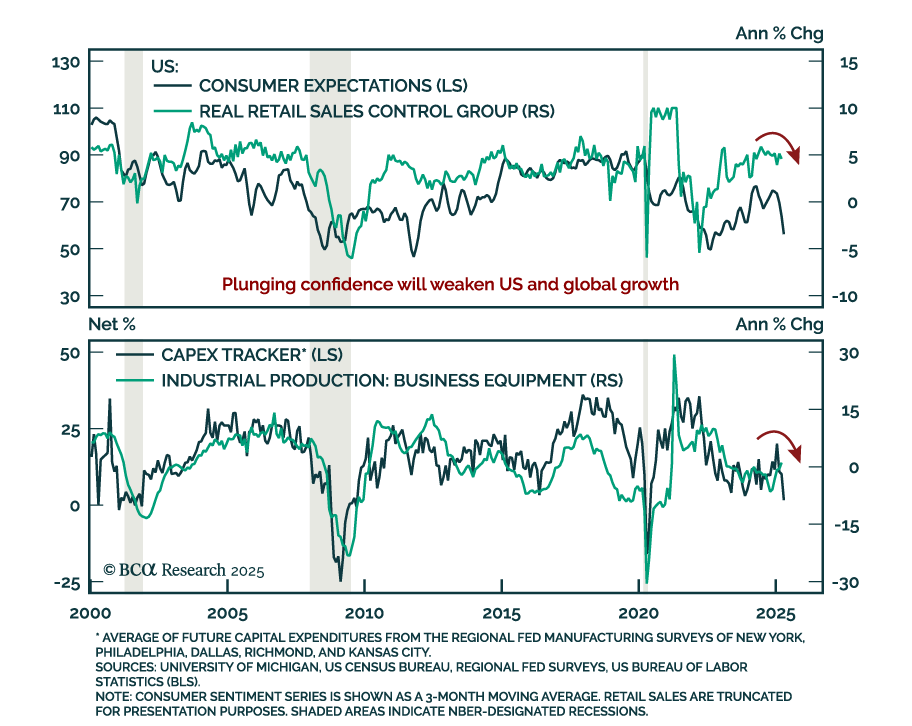
Soft data continues to deteriorate and hard data will soon follow, reinforcing our defensive asset allocation. Consumer and business confidence have plunged as policy uncertainty and inflation expectations rise, with spending, hiring and capex plans…
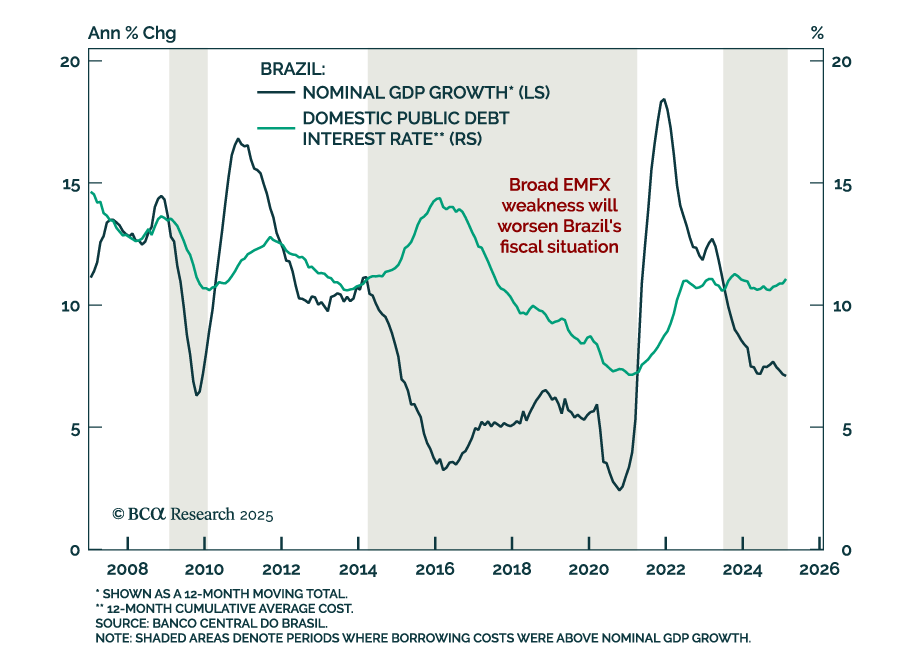
Brazil’s deteriorating fiscal dynamics and rising stagflation risks reinforce our negative stance on Brazilian assets, both outright and relative to EM peers. The latest global financial turmoil, combined with President Trump’s disruptive tariffs and China’s…
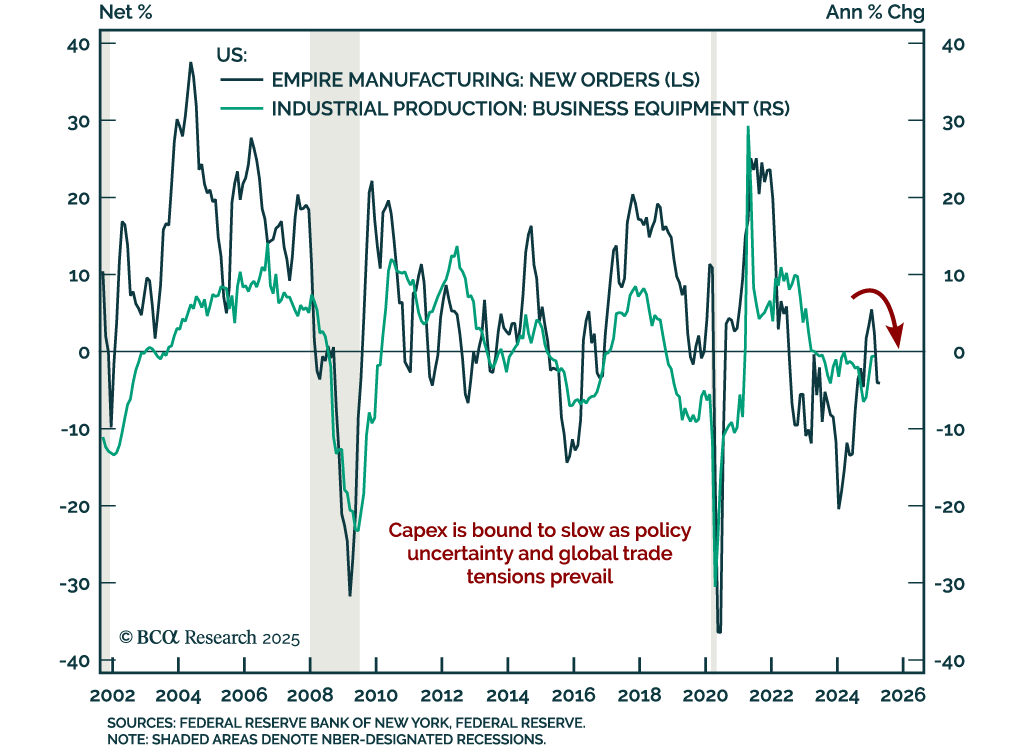
The NY Fed Empire Manufacturing survey adds to recent stagflationary worries, reinforcing our underweight in risk assets and overweight in government bonds. The general business conditions index rose slightly to -8.1 but remains in contraction, while the…
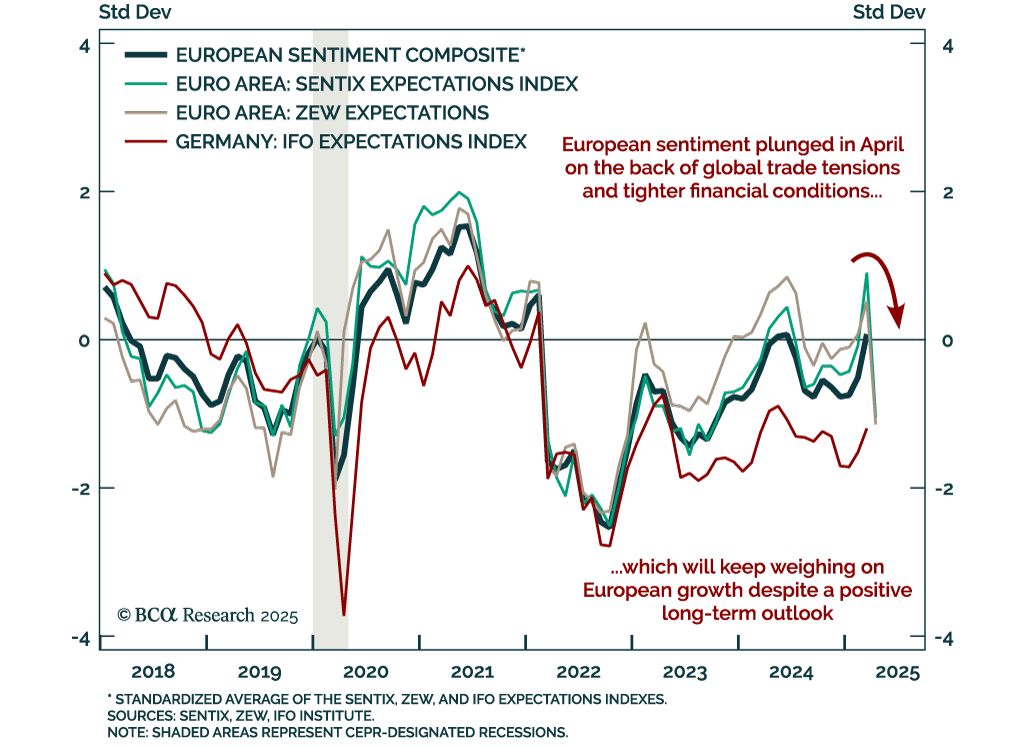
Eurozone sentiment has sharply deteriorated, reinforcing a cautious stance on European assets over the next 6 to 12 months. The April ZEW expectations index for the eurozone collapsed to -18.5 from 39.8, while Germany’s gauge also plunged and missed…
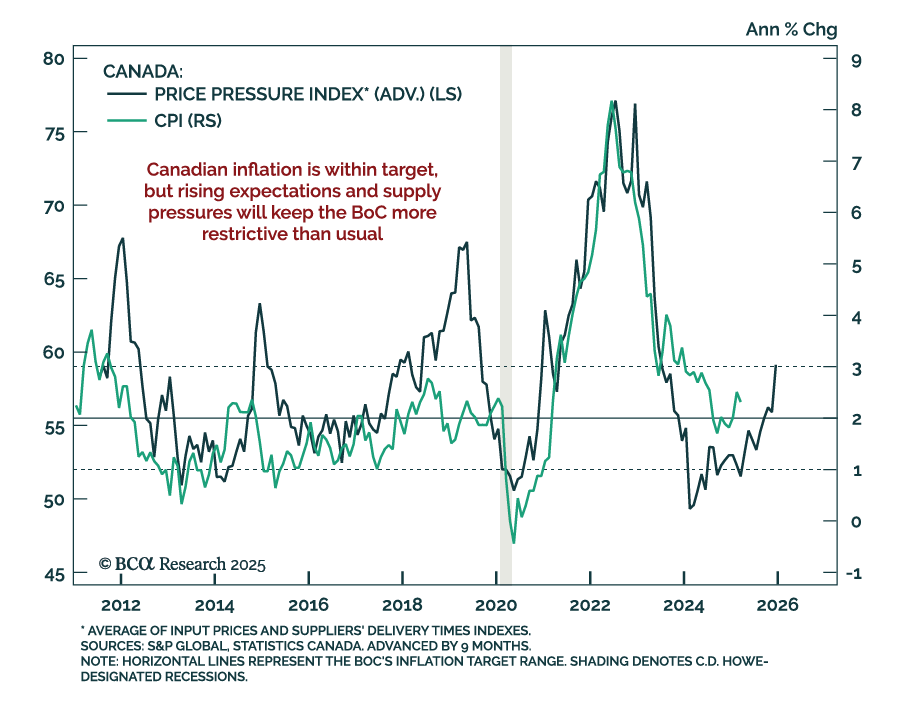
Cooler inflation will not shift the BoC’s stance, as stagflation limits potential easing, keeping us neutral on Canadian bonds. In March, headline CPI slowed more than expected to 2.3% y/y from 2.6%. However, lower energy prices drove much of the downside…
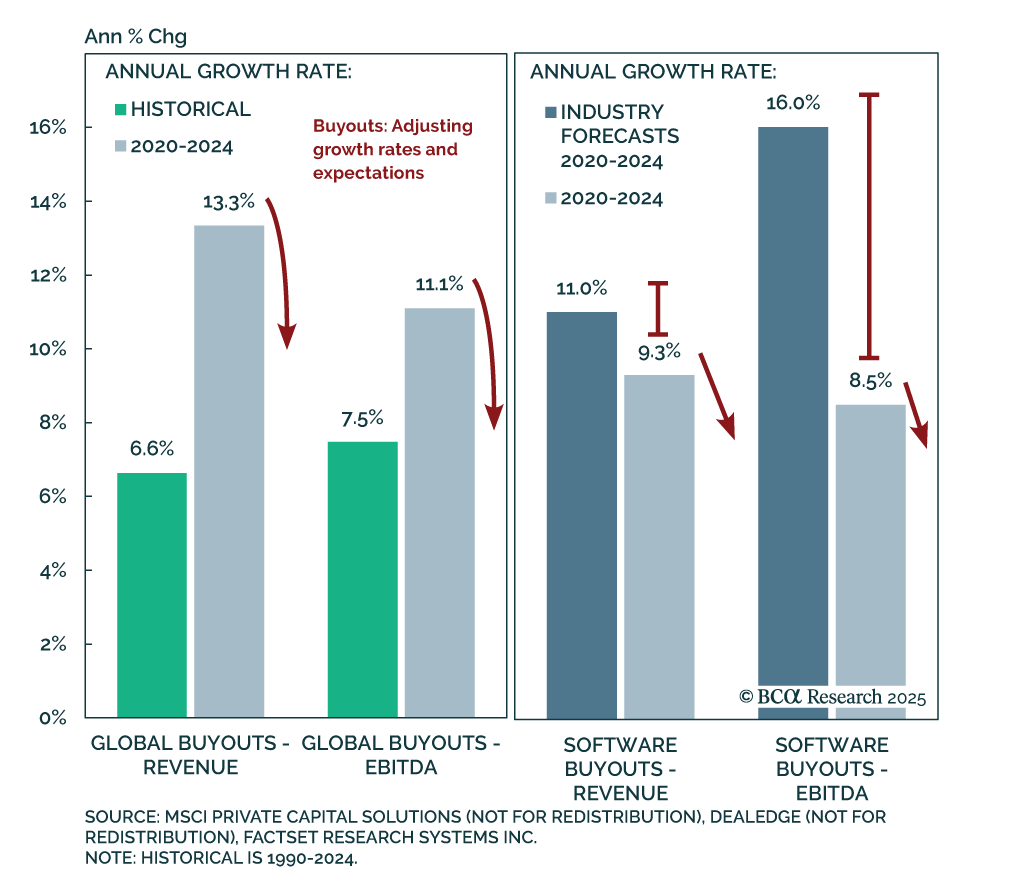
Our Private Markets & Alternatives strategists remain positioned for a downturn. Private Equity is most threatened as tariffs intensify existing recession risks. Buyout strategies face stress from record-low distributions and rising LP-GP friction. Venture…
We are pleased to share the replay of US Equity Market Intelligence Session, hosted by Chief US Equity Strategist Irene Tunkel.
Please join BCA Research's Chief US Equity Strategist, Irene Tunkel, for a US Equity Intelligence session on Wednesday, April 16 at 9:00 AM HKT, 11:00 AM AEST.
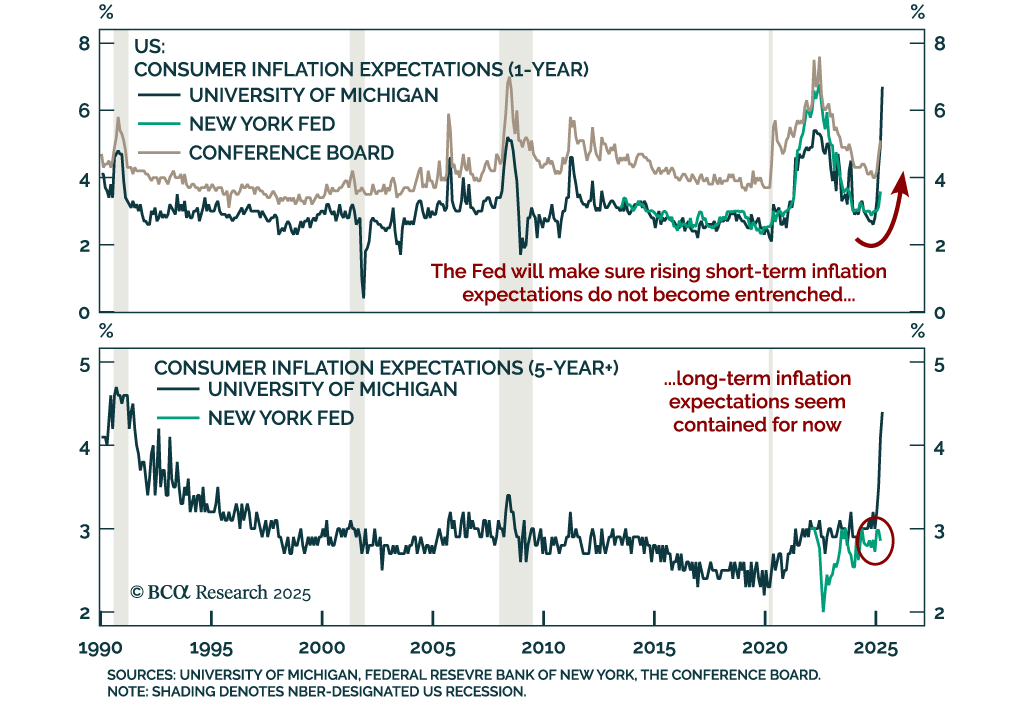
The latest NY Fed Survey of Consumer Expectations reinforces our defensive stance, with growth concerns deepening even as long-term inflation expectations remain anchored. The survey is a useful cross-check against broader sentiment and inflation indicators,…
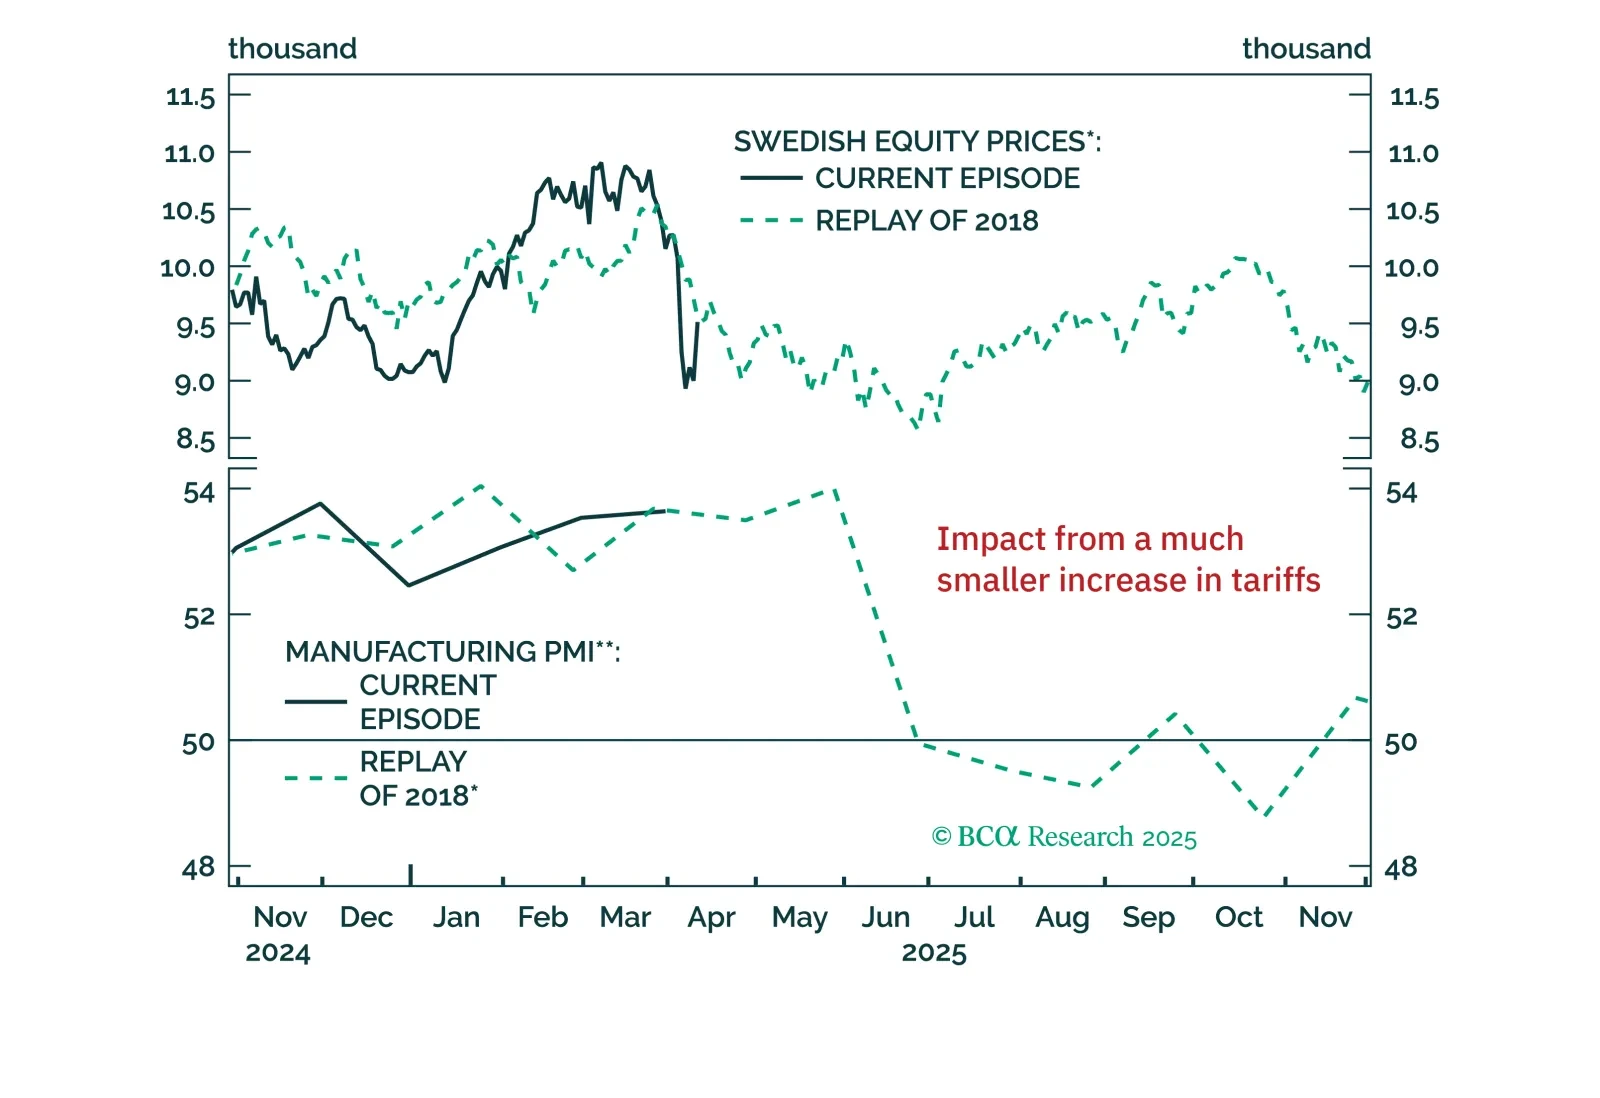
Europe’s near-term outlook remains clouded by uncertainty, even after the tariff reprieve. Our latest update breaks down why the risks to growth, profits, and financial conditions are still skewed to the downside — with Sweden standing out as a key bellwether.