Ciclos Económicos
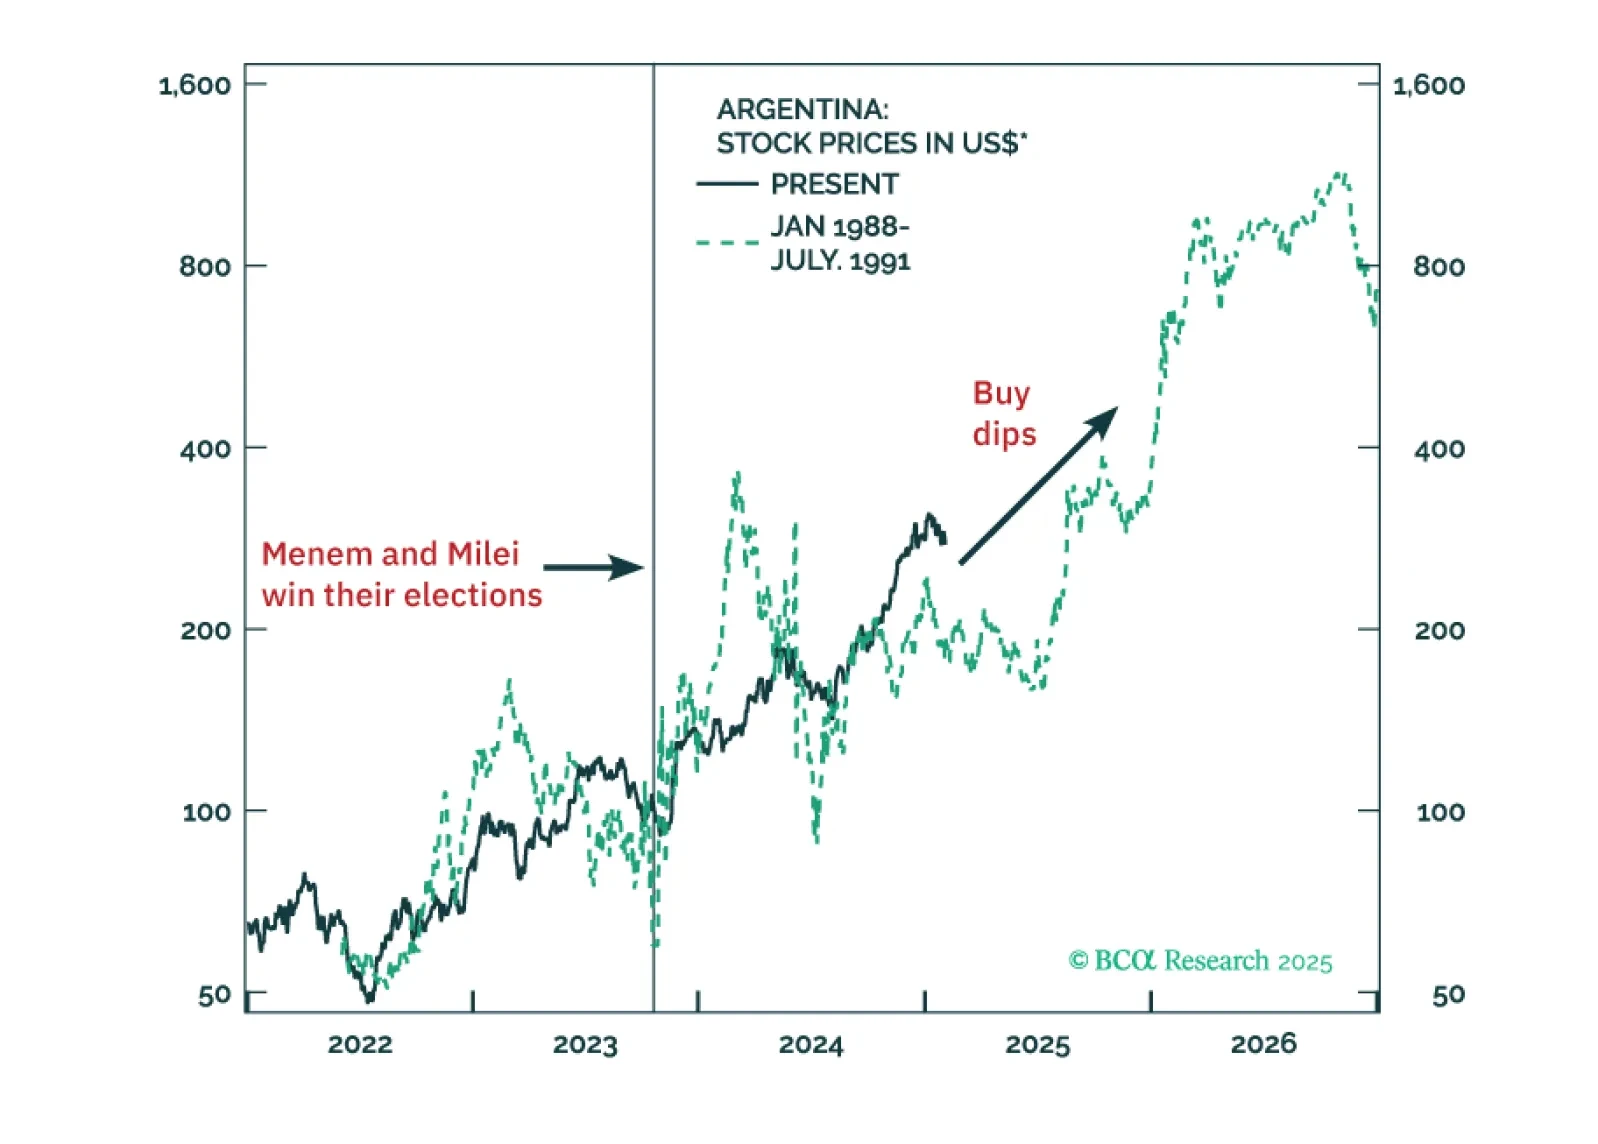
Argentina is entering a regime shift from the traditional short boom-bust cycles of the past 50 years. Profound structural reforms will result in a productivity boom, leading to a more durable economic expansion while keeping with the disinflation trend. Authorities will likely lift capital and currency controls in the second quarter of this year. All in all, odds are that Argentinian assets have entered a multi-year bull market.
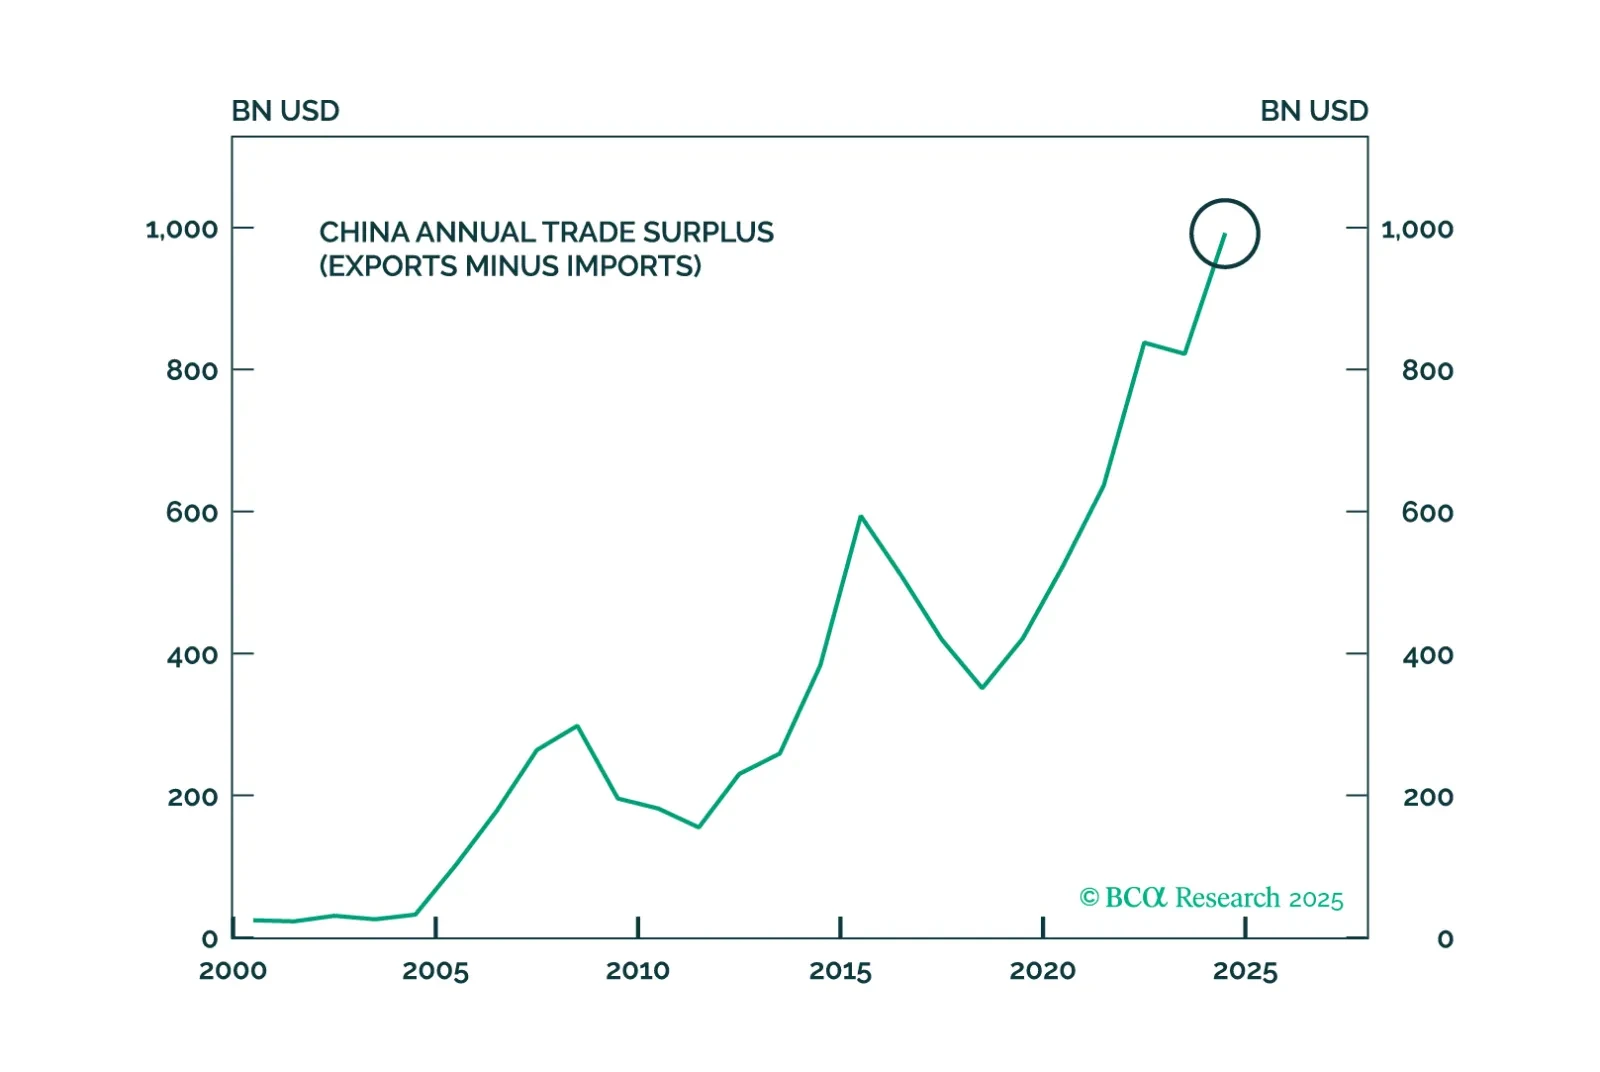
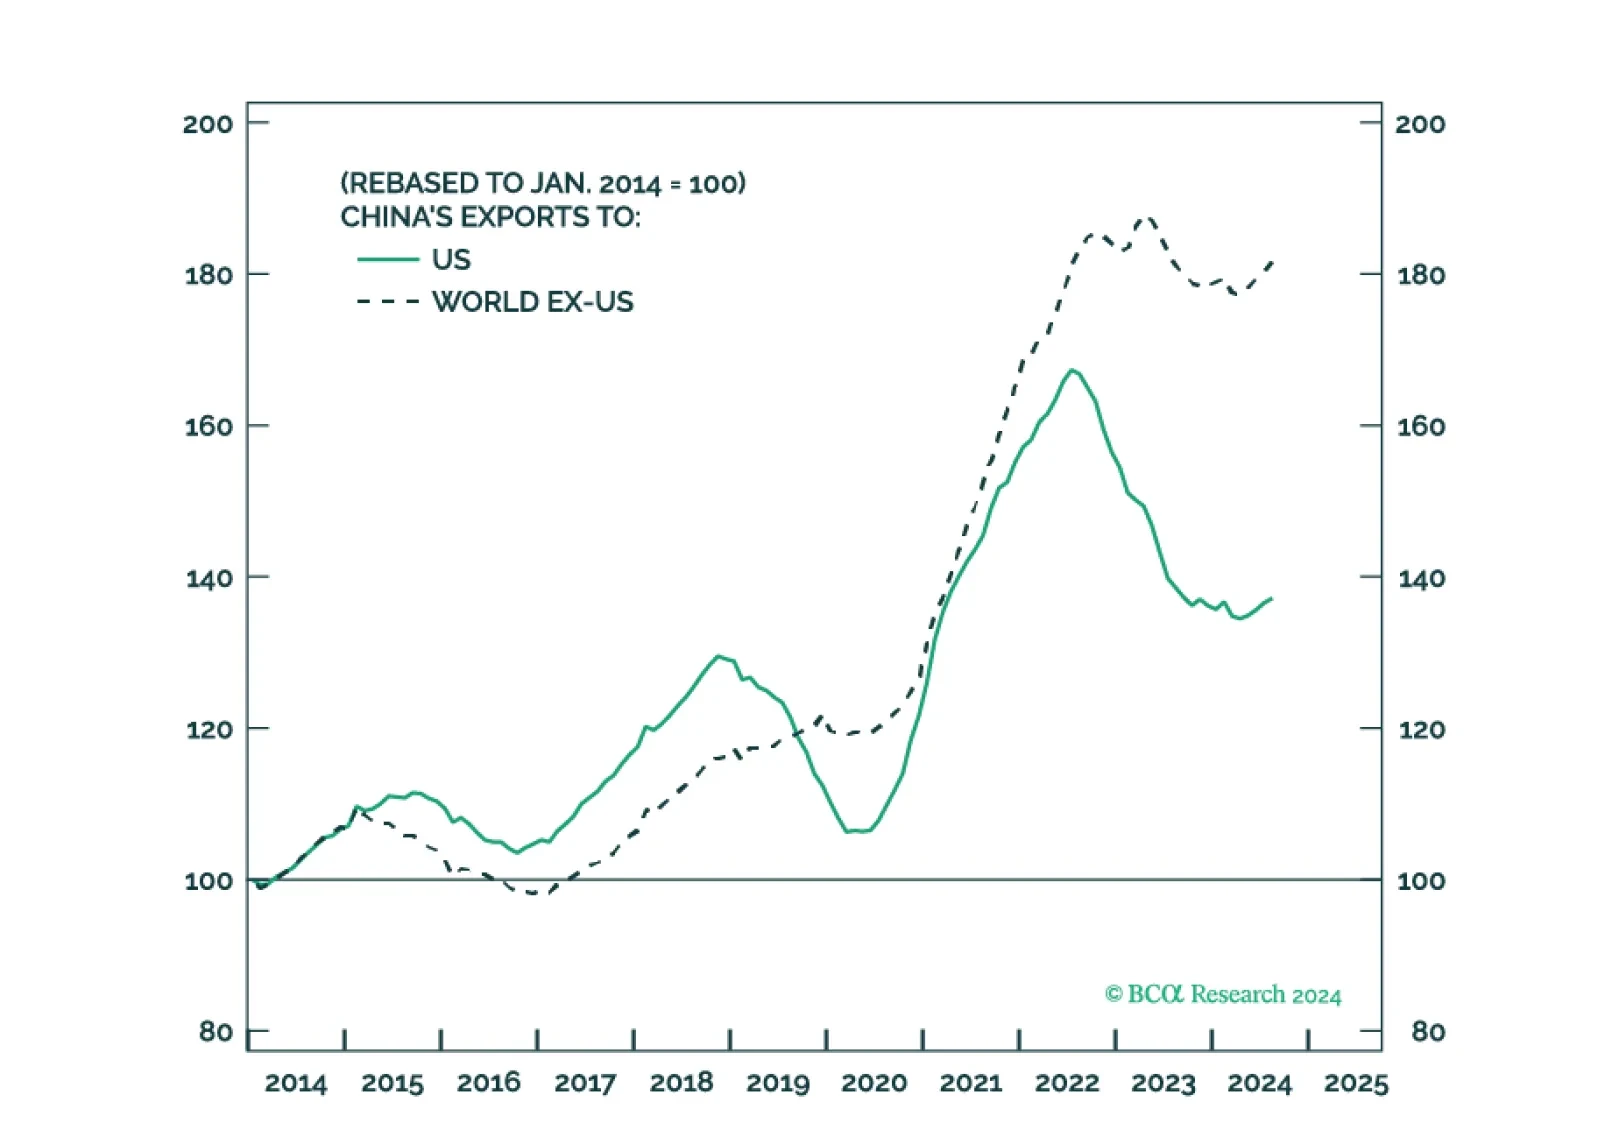
China barely hit its growth target in 2024 by shifting back to its old model of exports, racking up a record trade surplus with the world – right as Donald Trump walks back into the White House. Tariffs will elicit larger fiscal stimulus even as China rolls out innovations such as DeepSeek to meet its 2025 industrial goals, creating a volatile mix this year.
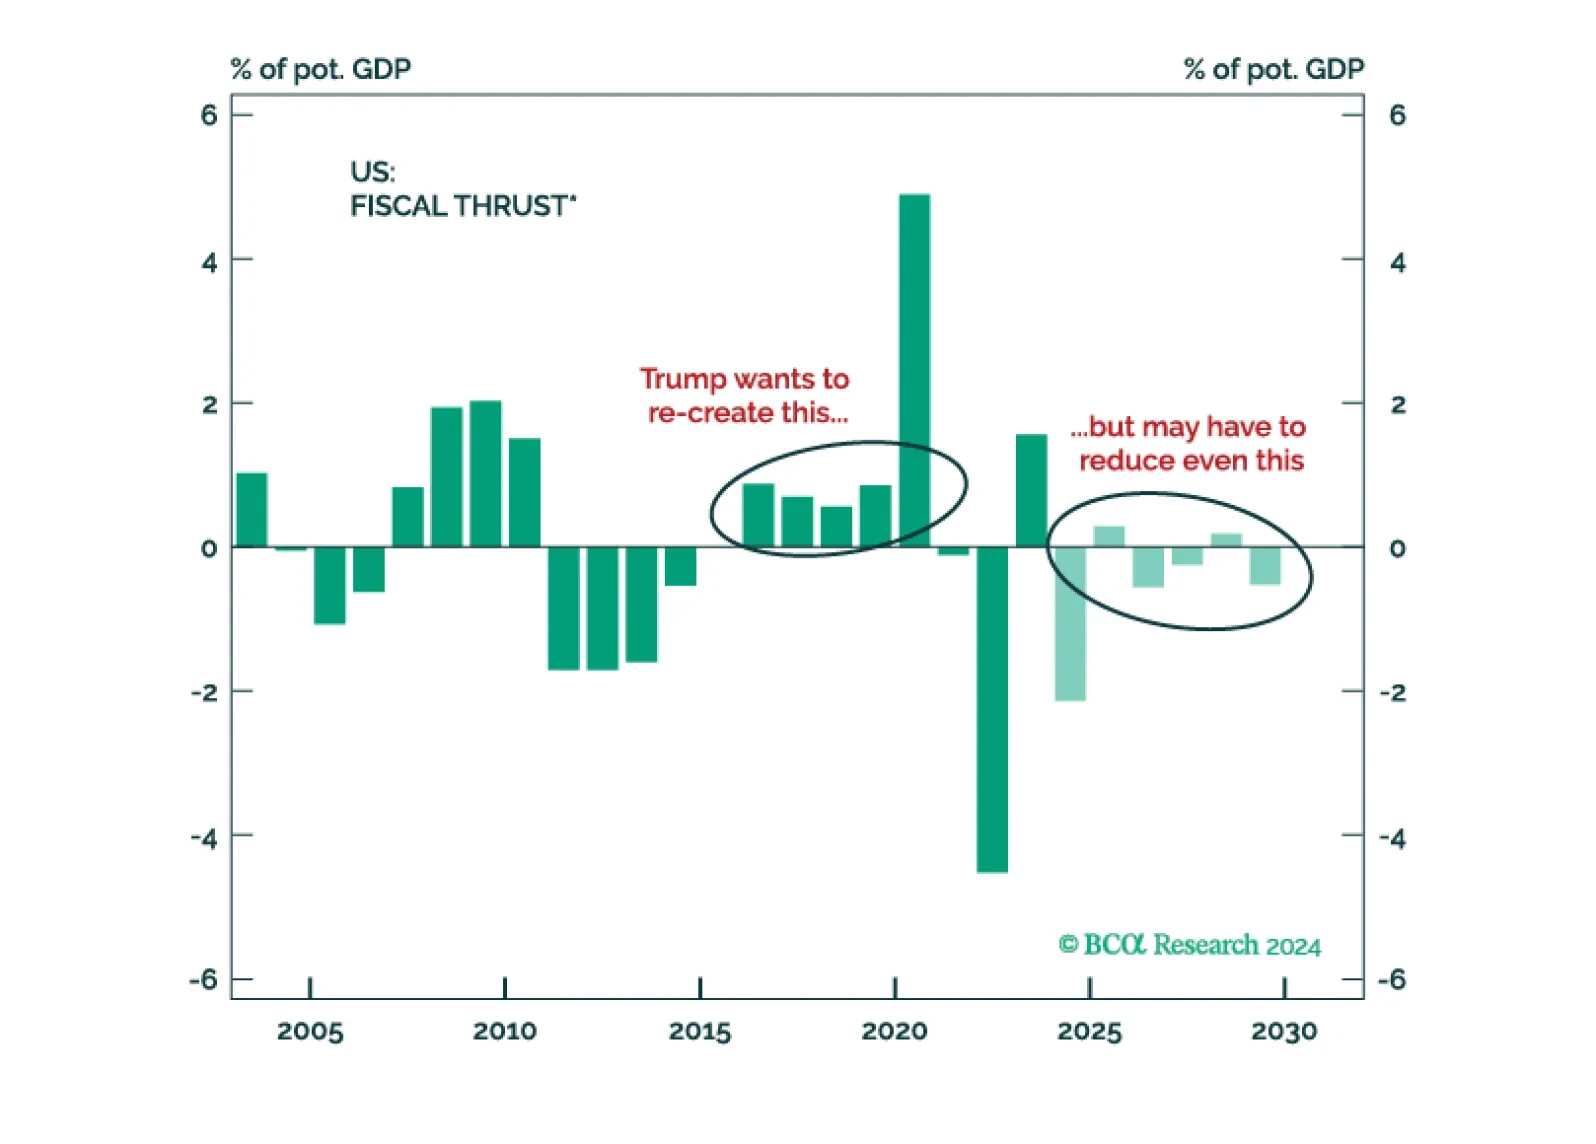
- Congress will pass tax cuts by end of 2025 producing a fiscal thrust of about 0.9% of GDP in 2026.
- Trump will count on that stimulus as a basis for slapping tariffs on leading trade partners.
- China will retaliate against Trump and stimulate its domestic economy, while pursuing stronger trade ties with other countries. Europe will also retaliate.
- Geopolitical risk will shift from Ukraine-Russia to Israel-Iran, where the conflict will continue to escalate until a crisis point is reached within 2025.
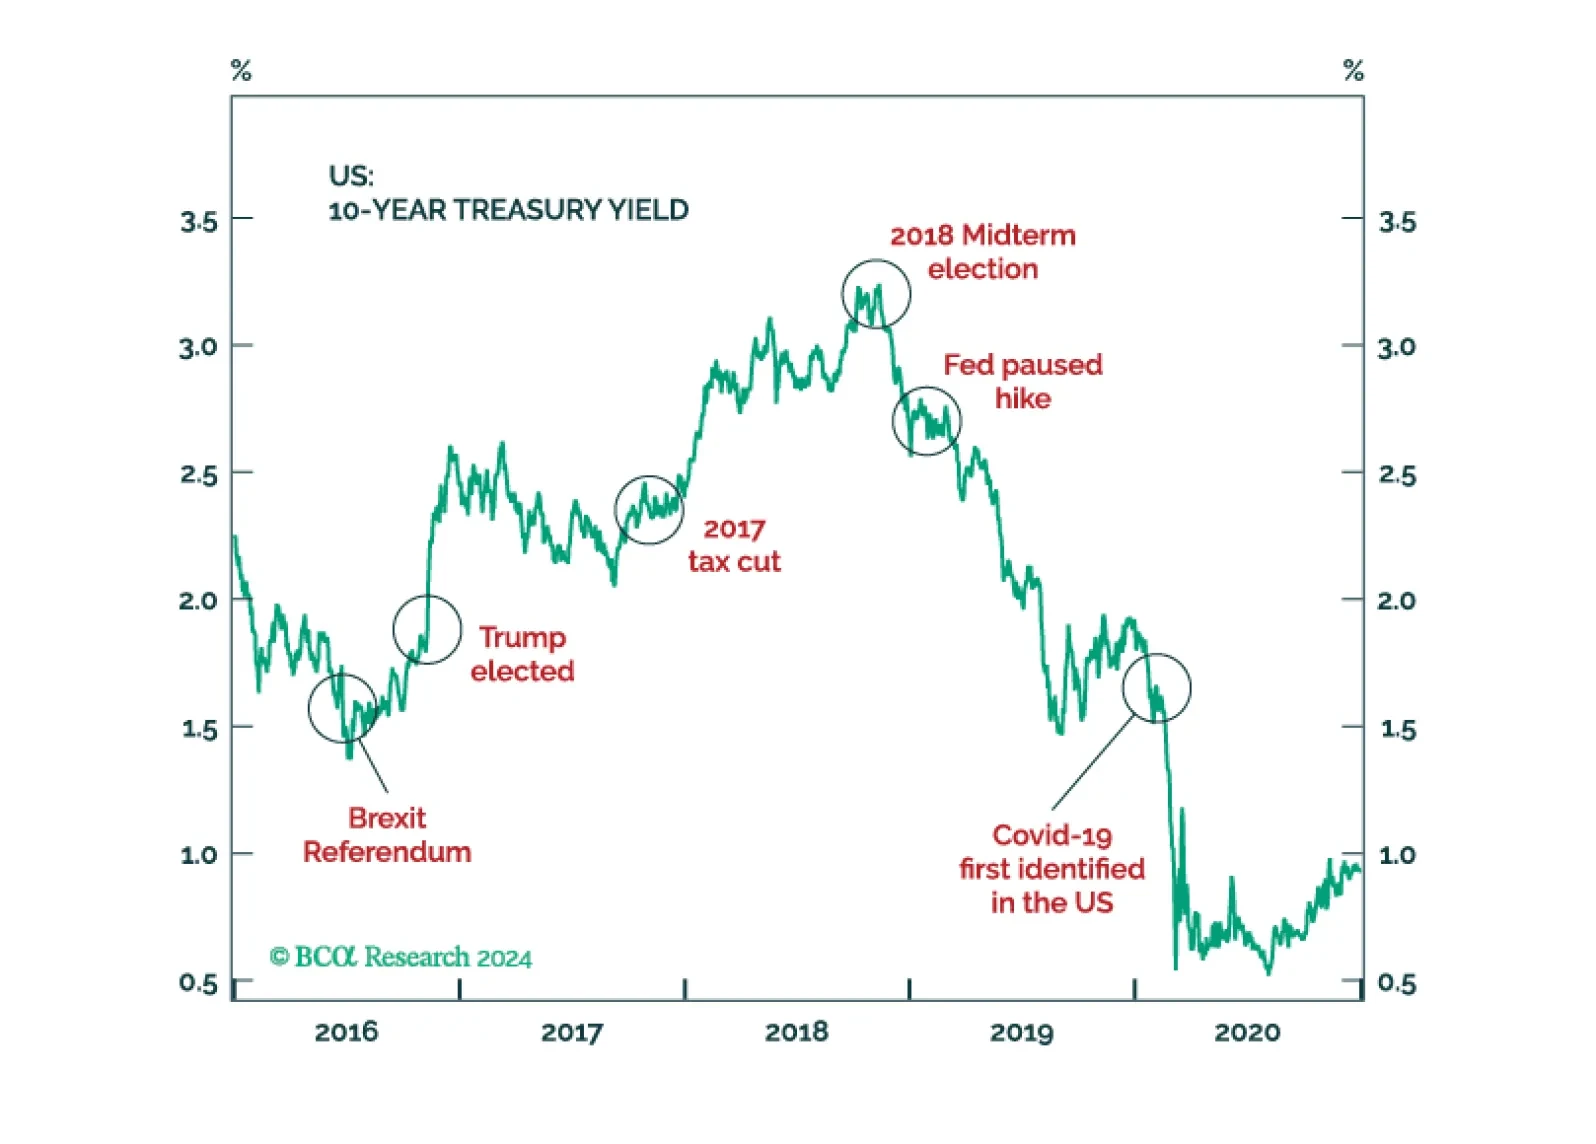
¡El mes de noviembre nos ha traído S&P 6,000! El presidente Trump ha ganado una “Red Sweep” (como esperábamos todo el año) y ha dado paso a un cambio de régimen en Estados Unidos. Por ahora, estamos abiertos a aprovechar el impulso. Sin embargo, el mayor riesgo para el mercado son los rendimientos de los bonos, que deberían subir a medida que los inversores empiecen a valorar las políticas del presidente Trump y su impacto en los déficits.