Australia
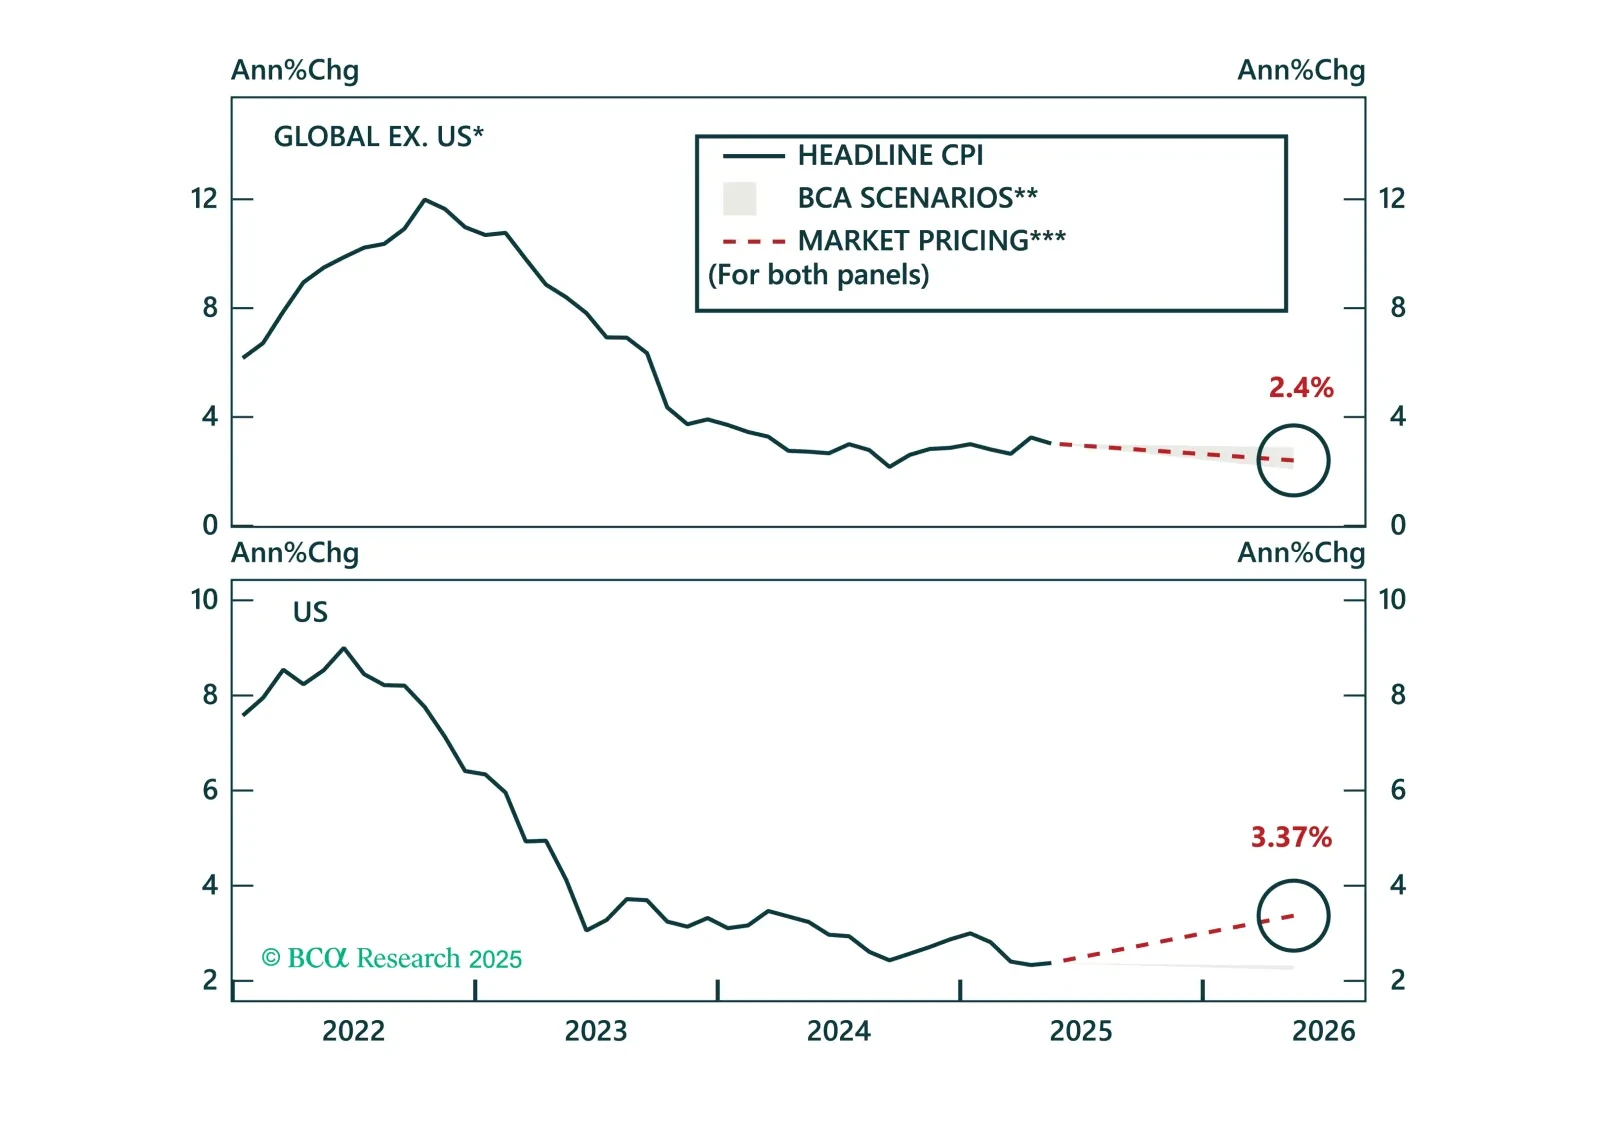
La desinflación sigue desarrollándose a nivel global, y los mercados finalmente están poniéndose al día. Las expectativas de inflación se han realineado ampliamente con los fundamentos, lo que nos lleva a cambiar nuestra asignación global de ILB a neutral. Si bien los riesgos de aranceles están inflando las expectativas en EE. UU., los precios en el Reino Unido, Japón y Australia se han ajustado drásticamente. El Informe de Estrategia de hoy revisa estos desarrollos y actualiza nuestra posición de ILB a nivel de país.
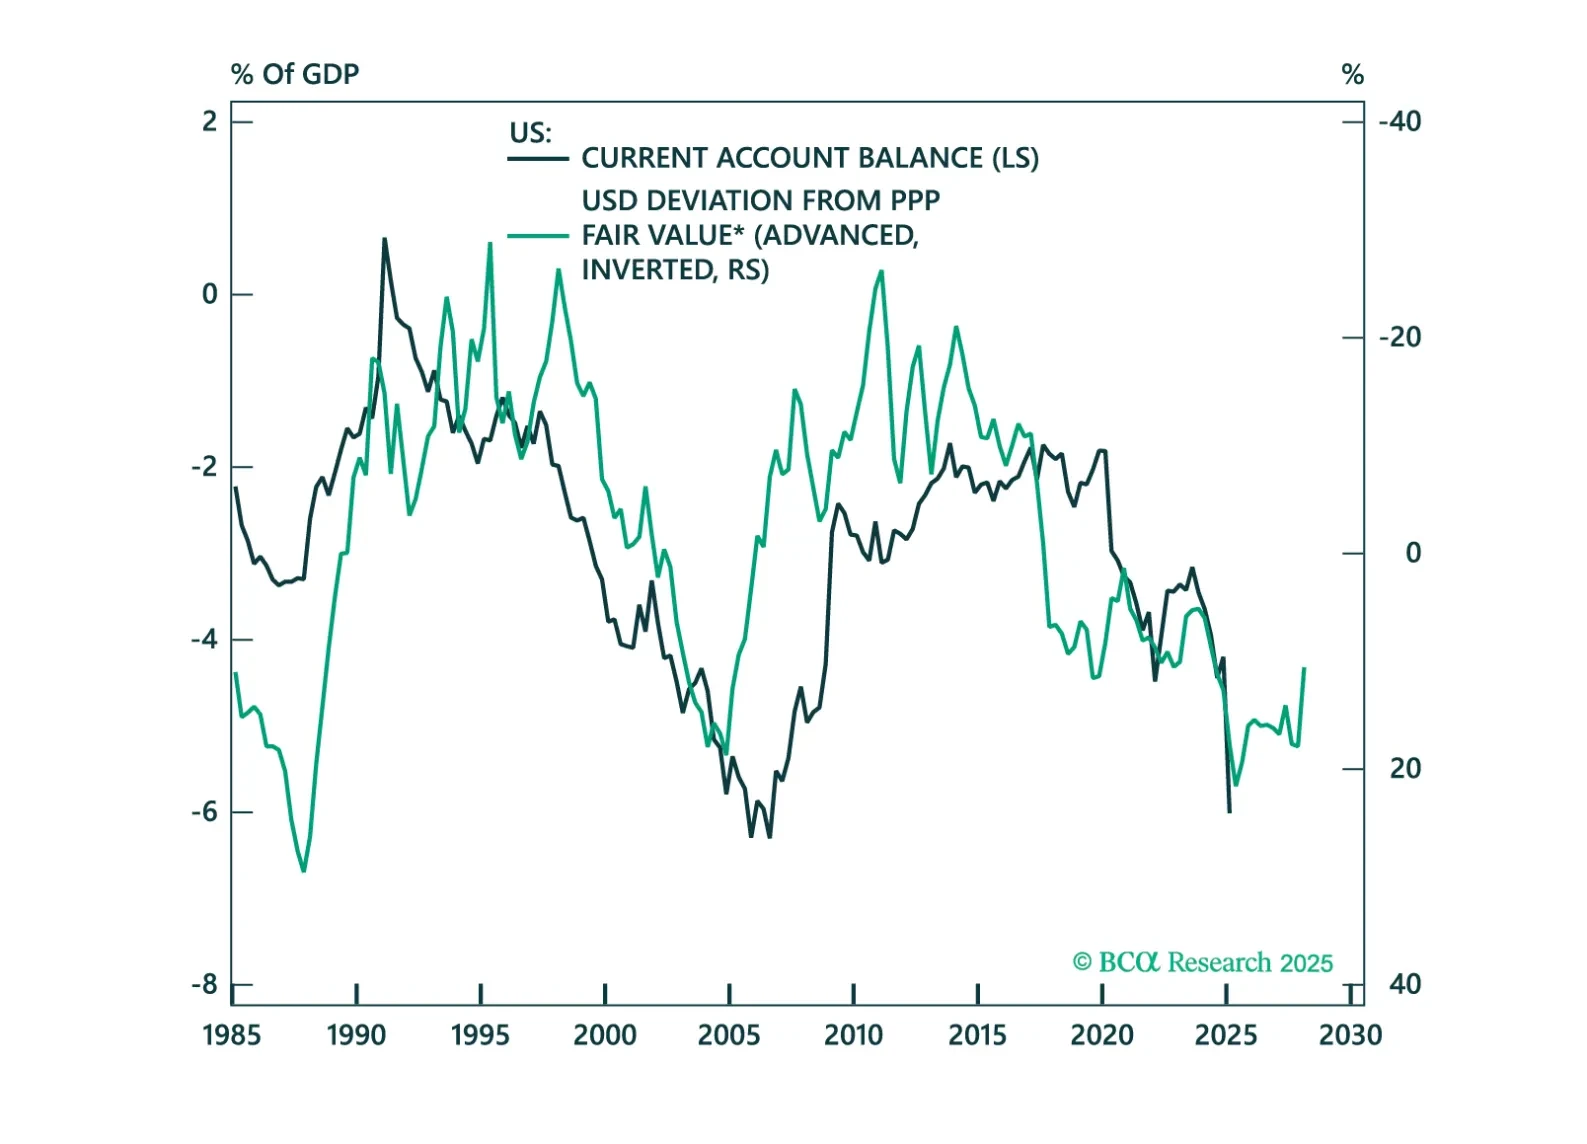
En este libro de gráficos, analizamos la balanza de pagos en países desarrollados (DM) y mercados emergentes (EM). A Estados Unidos no le va bien, pero a algunos otros países tampoco.

In this FX note, we provide a rationale for why it is important to pay attention to technical indicators, while still keeping your eyeball on the structural factors that drive currencies. This report answers the following questions: 1. Should you buy or sell the USD over a three-to-six month period from the pure lens of our proven technical indicators and 2. What are the best tactical cross trades among currencies.

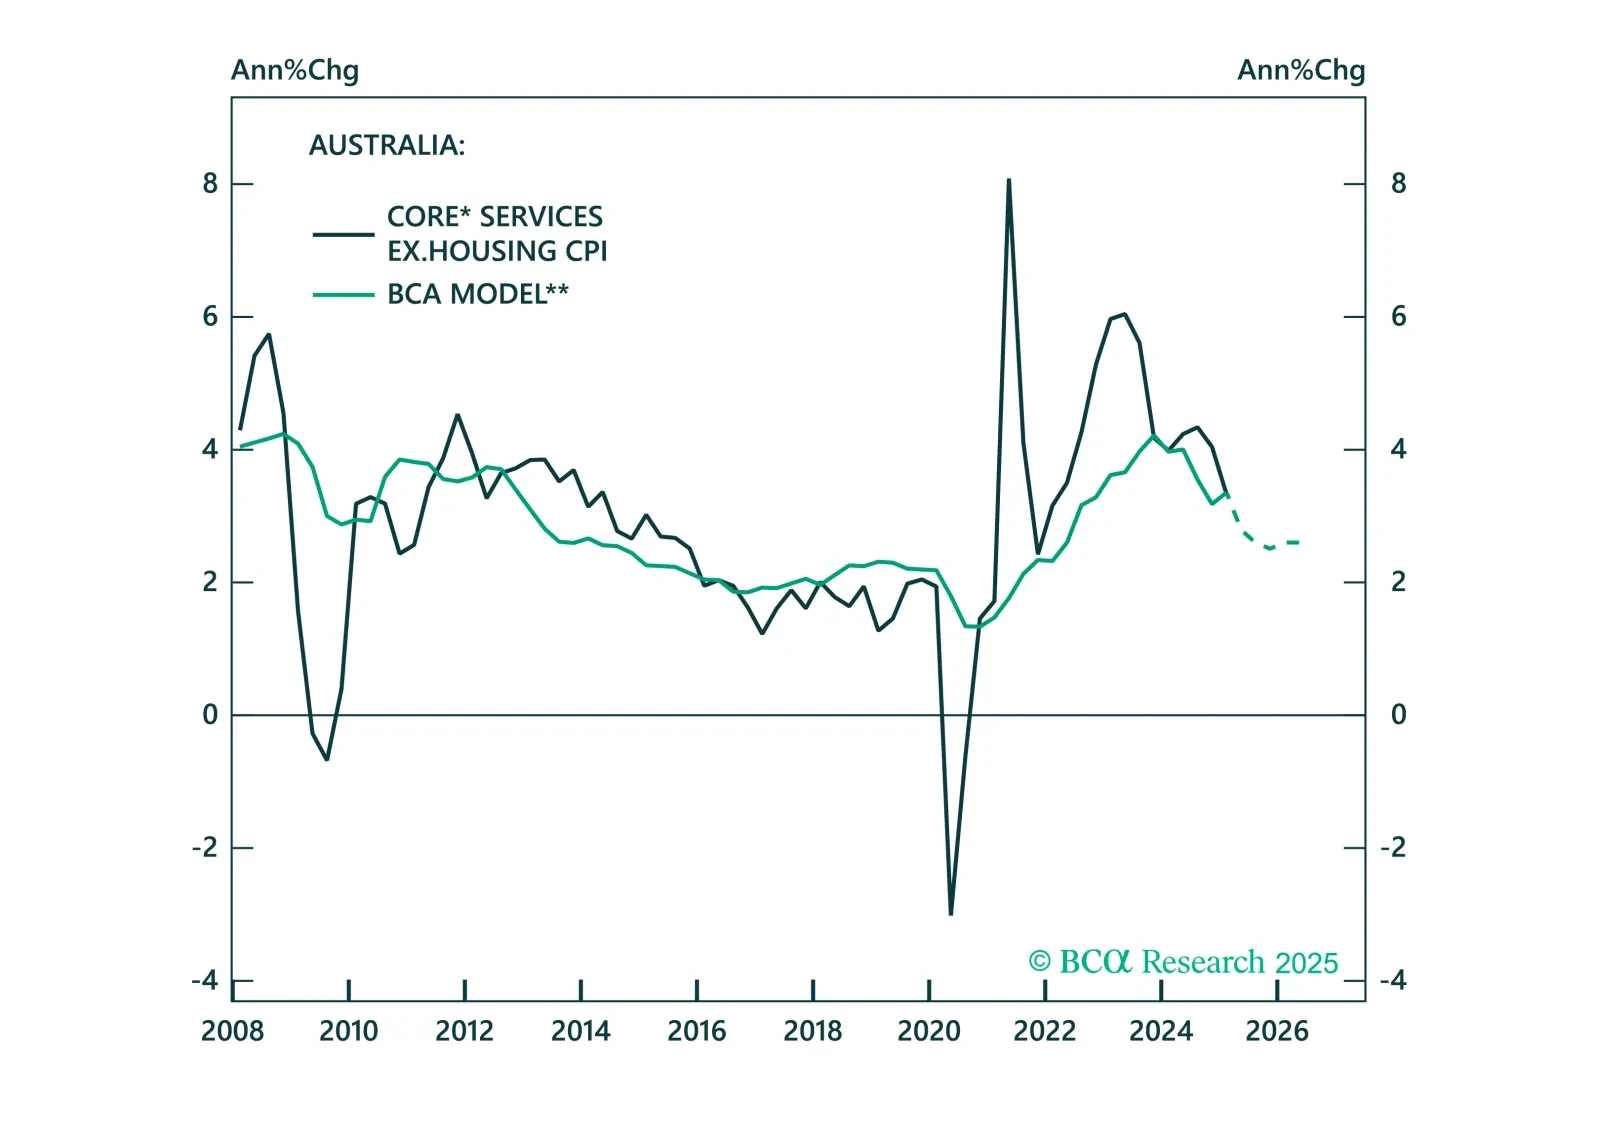
The RBA just turned dovish, but the macro data do not justify many more cuts. We unpack why Australia’s strong labor market and sticky inflation limit the scope for further easing.
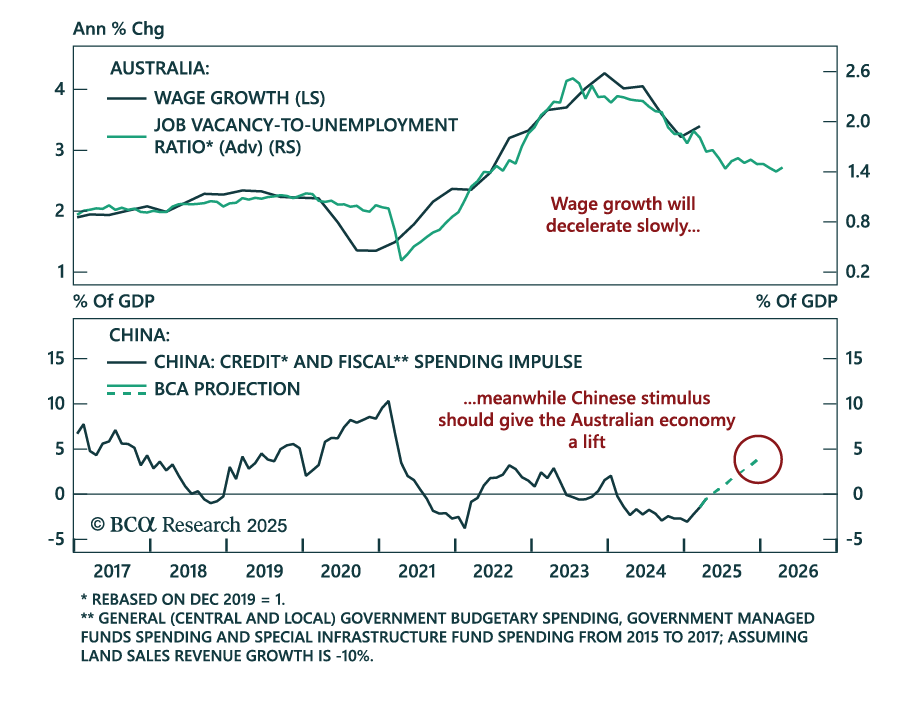
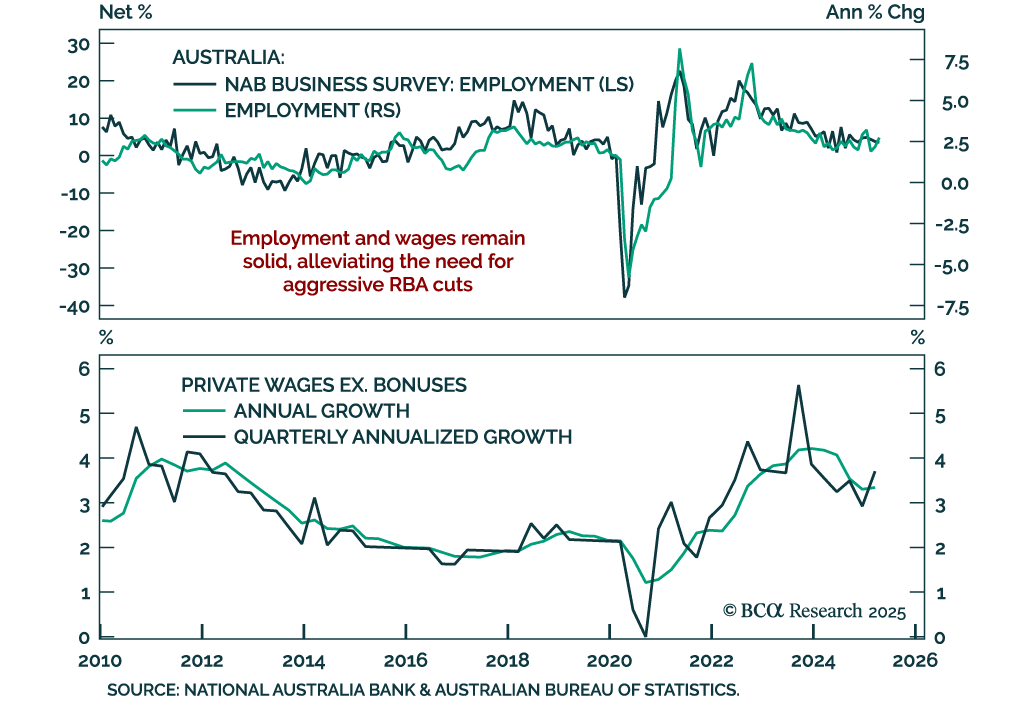

The easing bias remains, but not all central banks are equal. This Central Bank Monitor update reveals who is ready to cut more and who is still pretending not to.
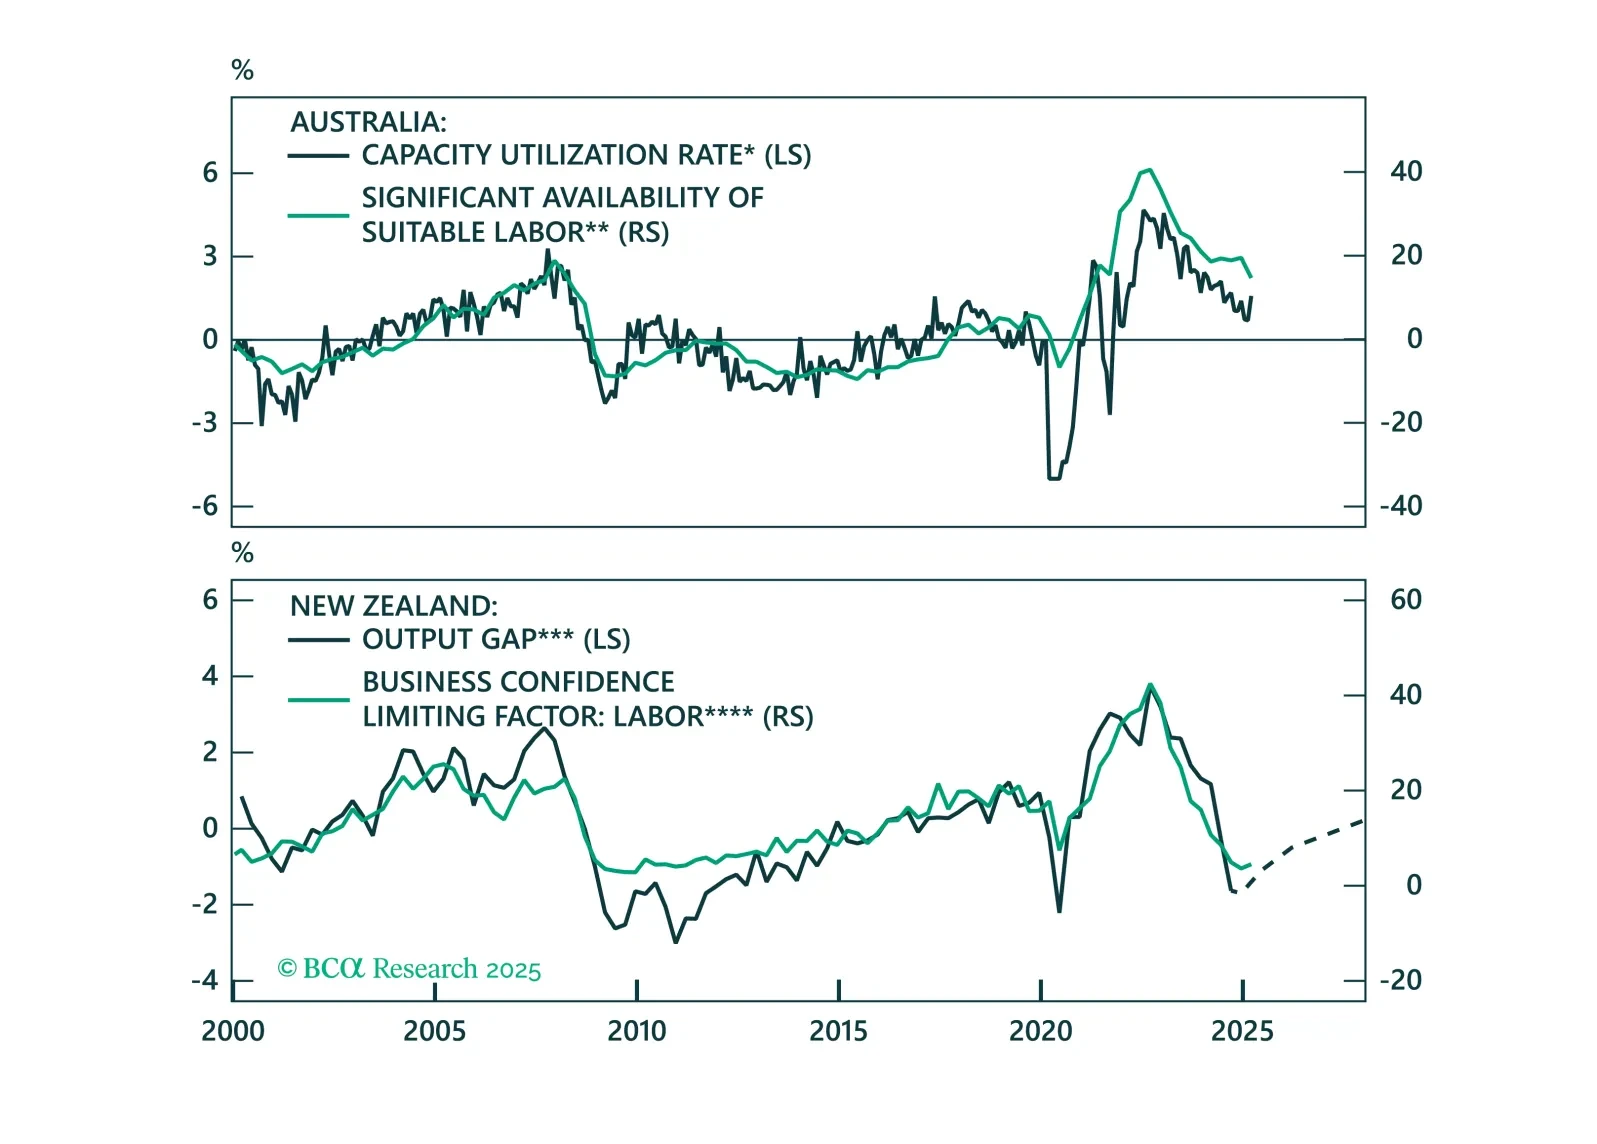
Following the escalation of the US-China trade war, the Reserve Bank of Australia is priced to cut rates most aggressively among its G10 peers. Across the Tasman Sea, the Reserve Bank of New Zealand has already cut rates aggressively, but the economy has yet to respond to this policy easing. This Special Report will examine the prospects of monetary policy for both of these central banks.
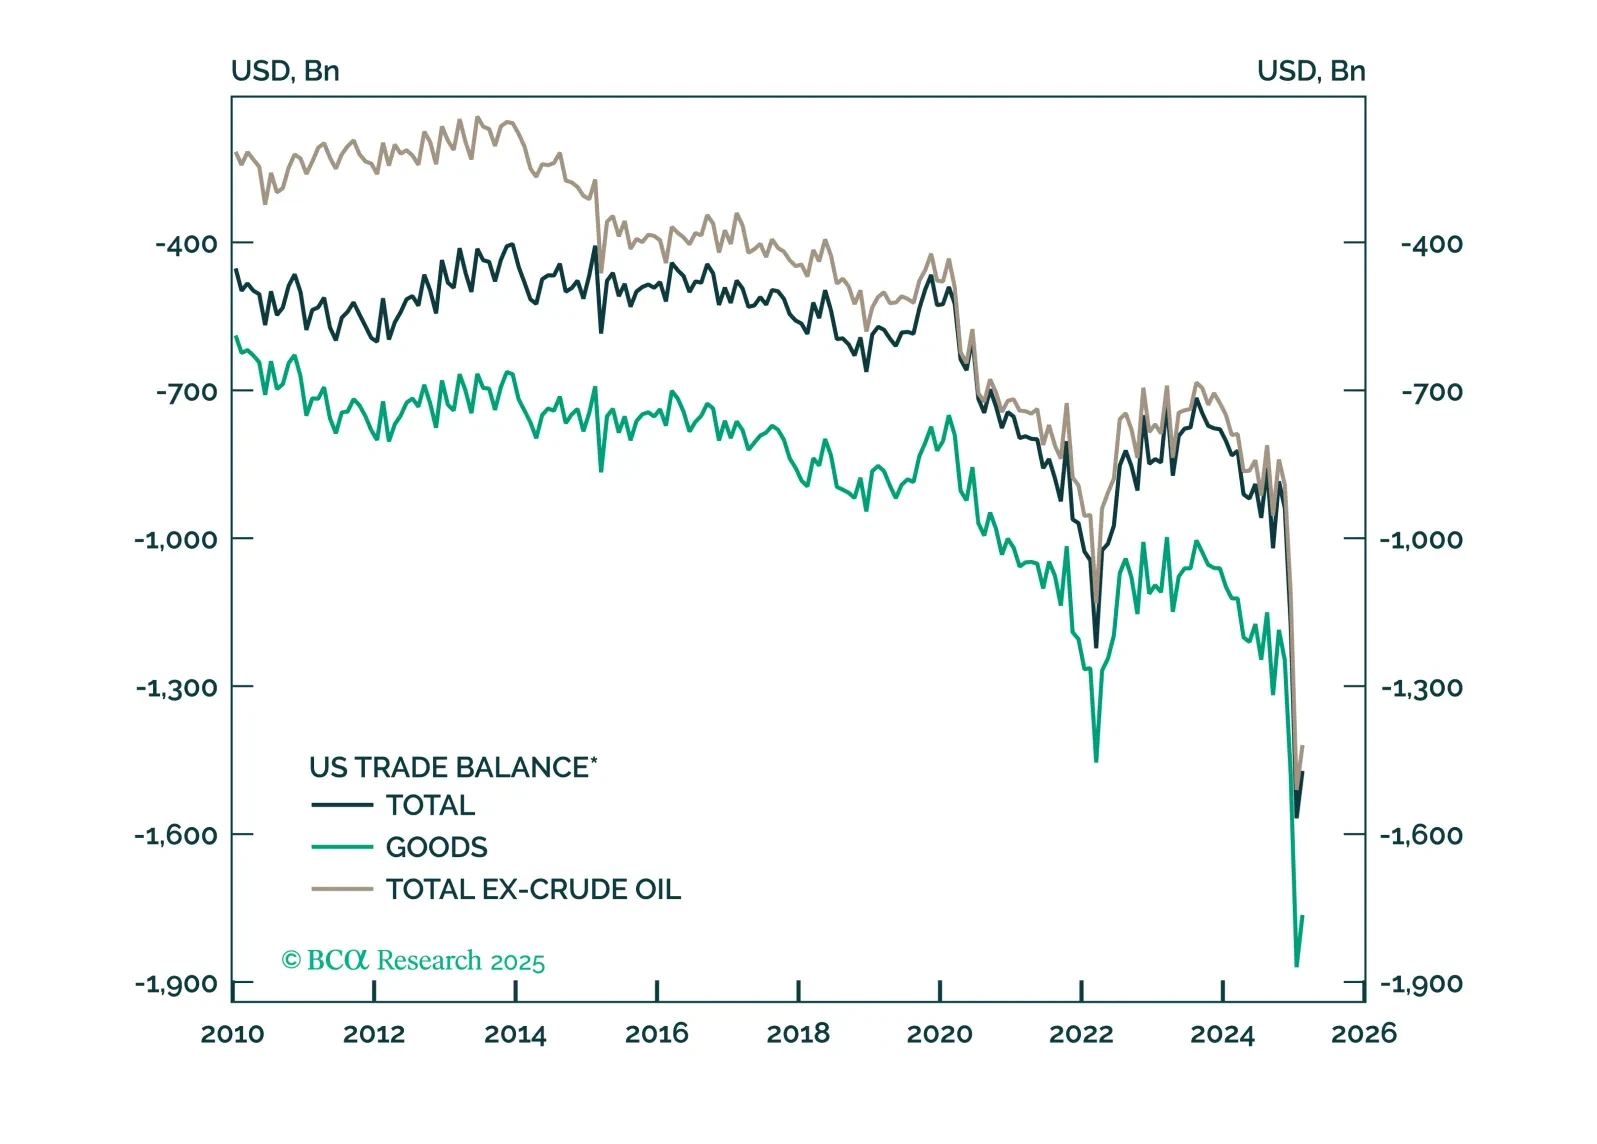
This report looks at the FX implications of the Trump tariffs, and the review of our Q1 trades.