Atención médica
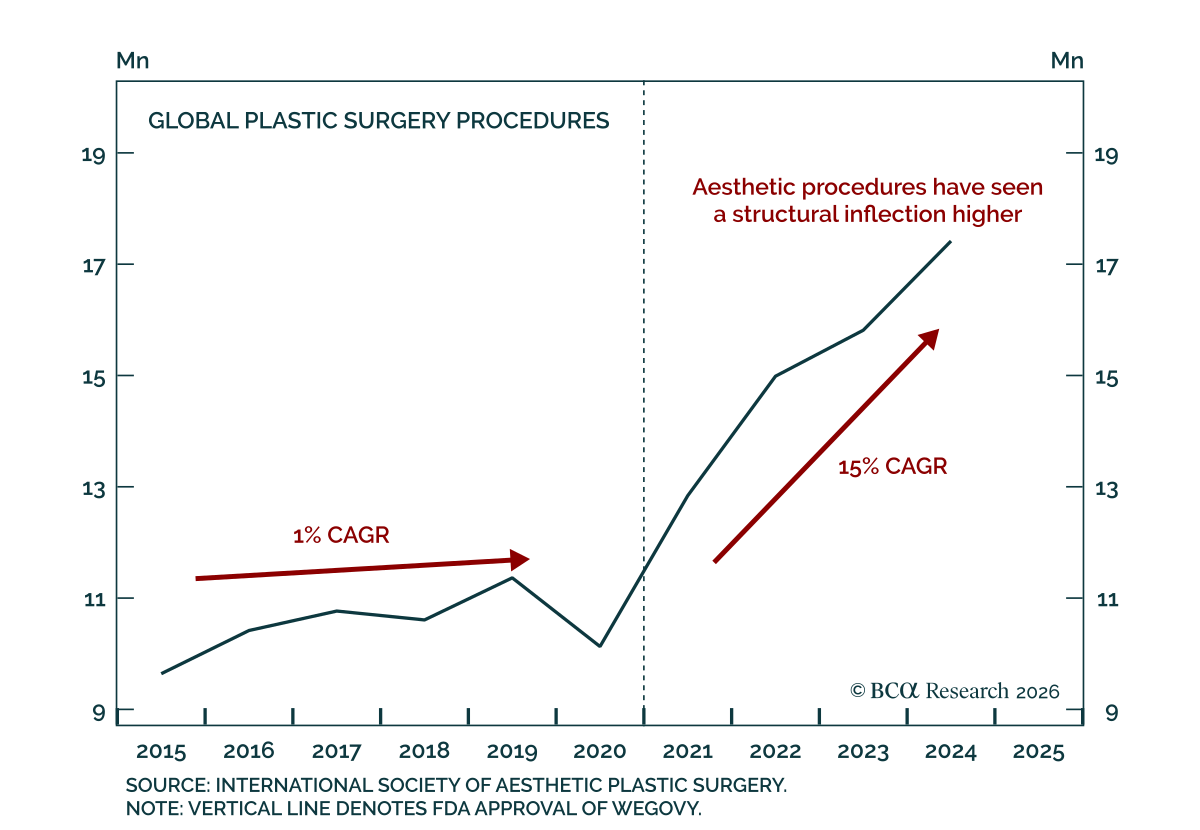
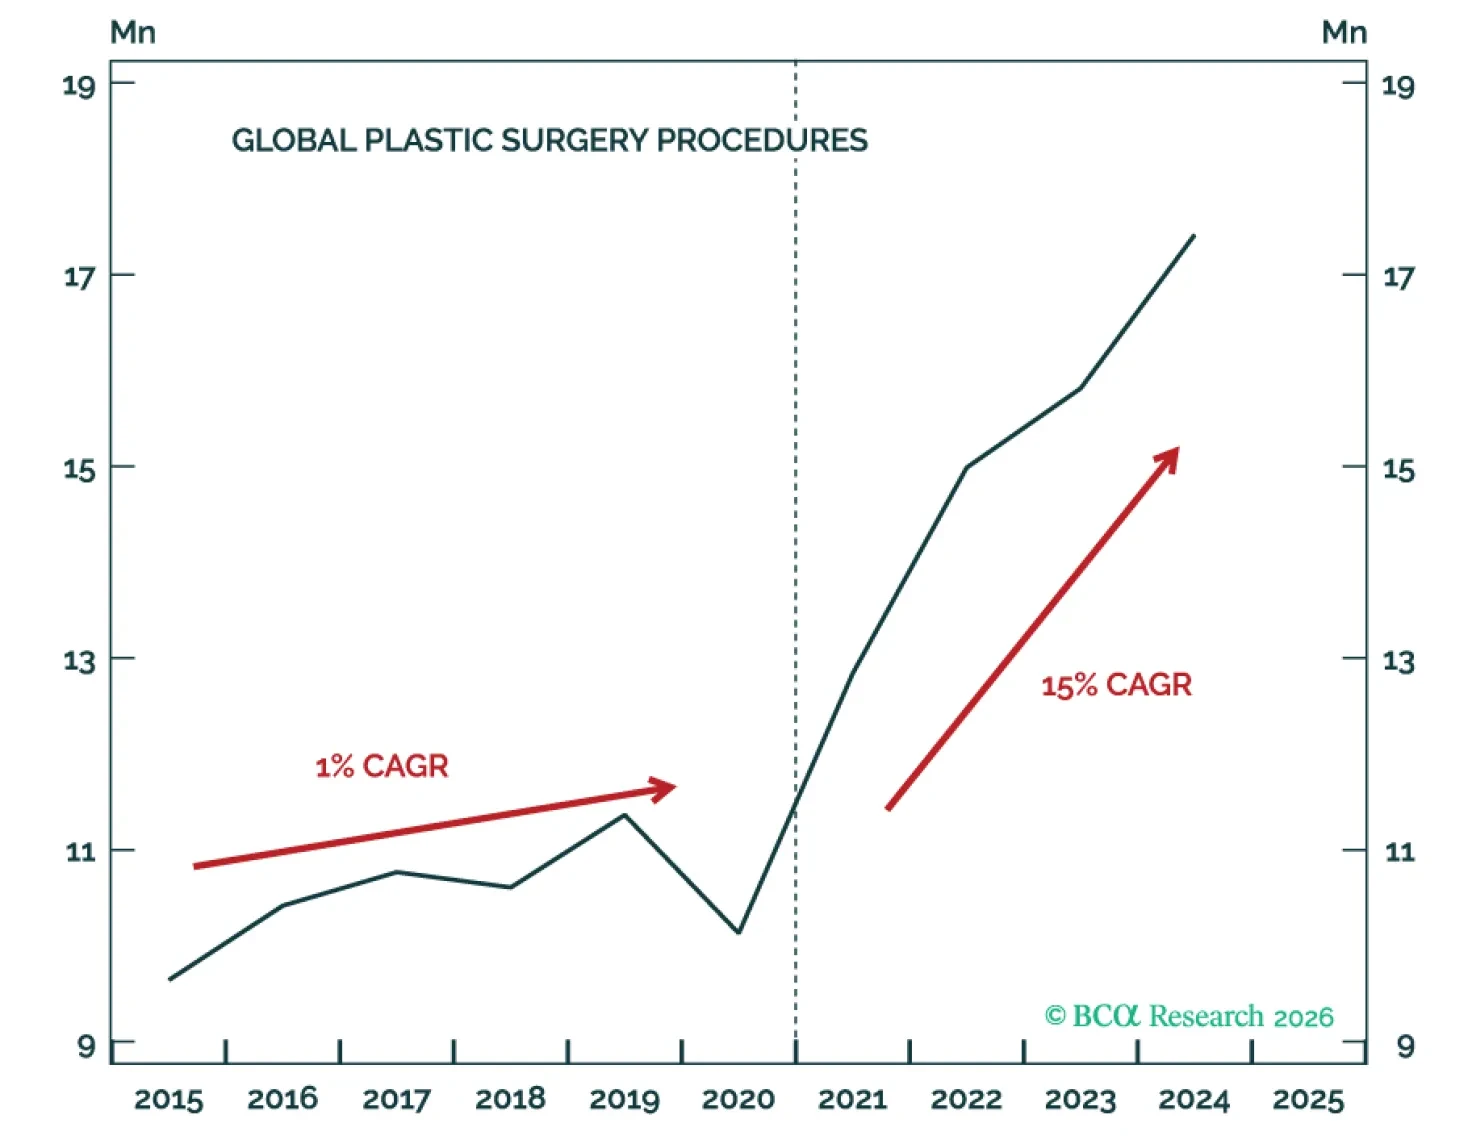
El auge del trabajo remoto, las citas en línea y otros cambios demográficos están aumentando la demanda de estética. Los GLP-1 proporcionan una cura eficaz y económica para la obesidad, y su efecto secundario “Ozempic face” ha alterado estructuralmente la demanda de procedimientos estéticos y productos para el cuidado de la piel. Productores de GLP-1 de larga duración, productores de inyectables biostimuladores y fabricantes por contrato de K-Beauty.
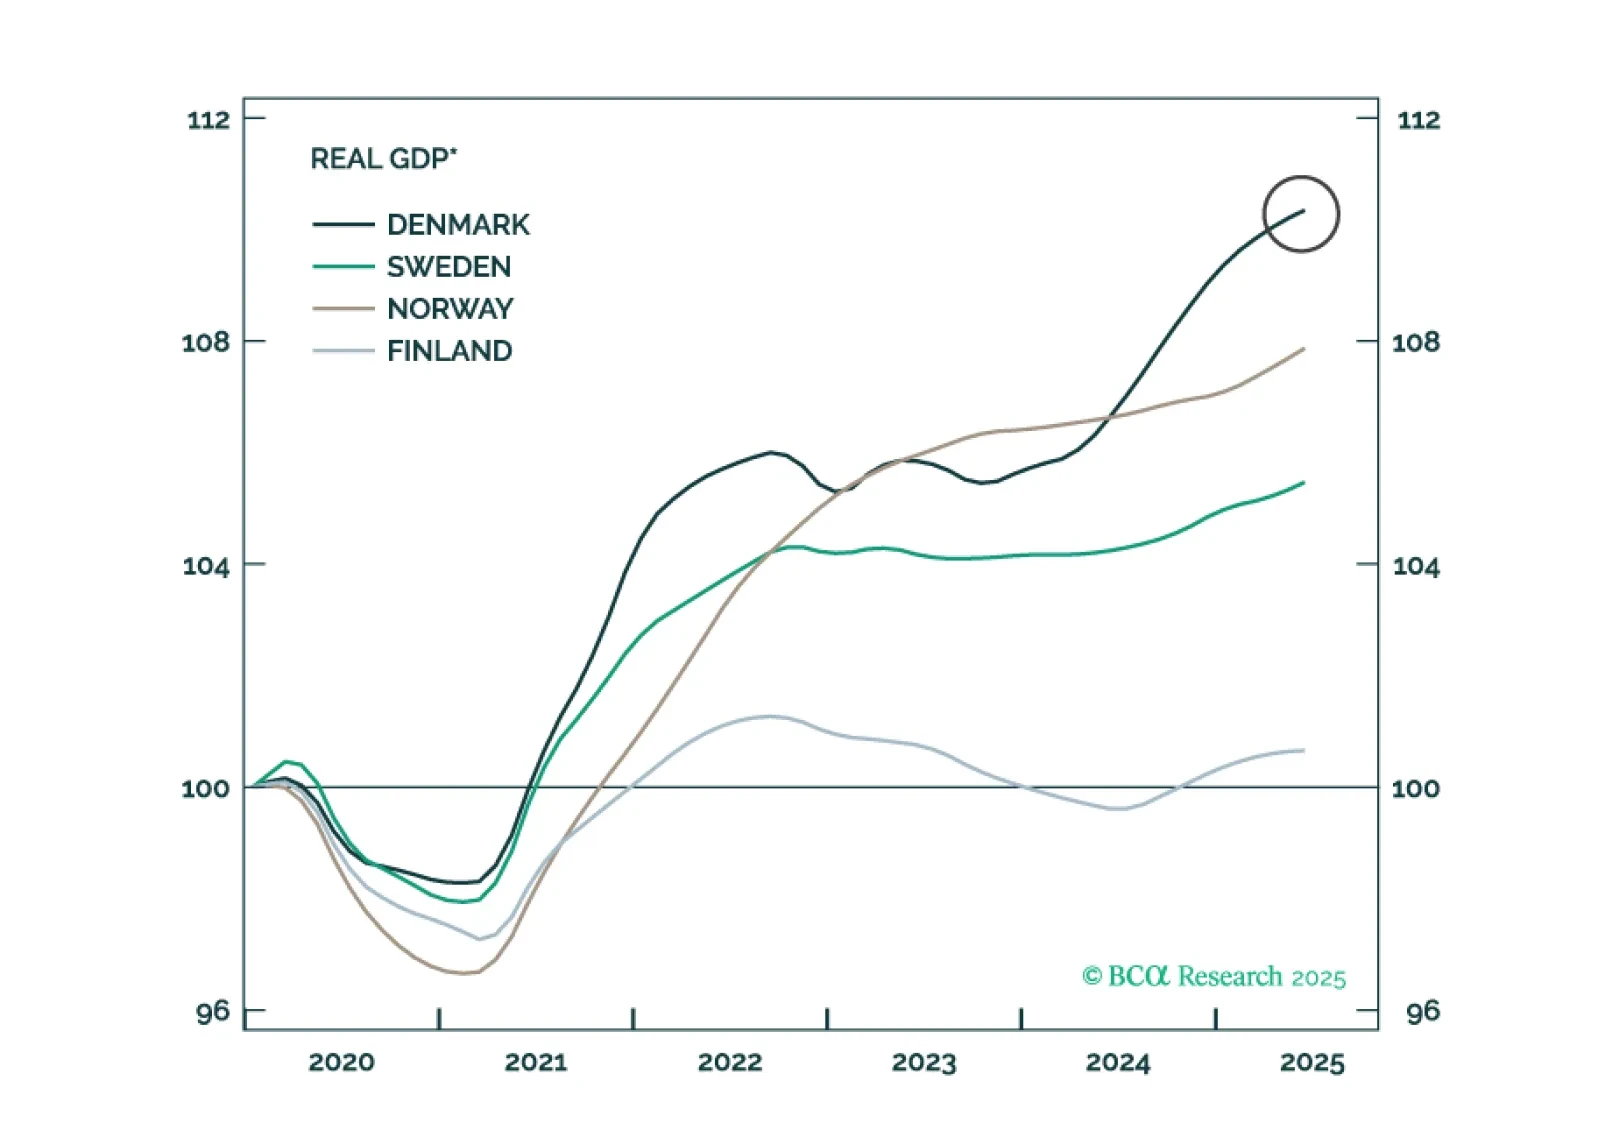
Los bancos centrales nórdicos están ahora alineados en modo de pausa, pero sus economías están divergentes. Con las perspectivas suecas mejorando y los vientos en contra en Noruega aumentando, estamos posicionándonos a favor de las acciones suecas y tomando posiciones cortas en NOK/SEK.
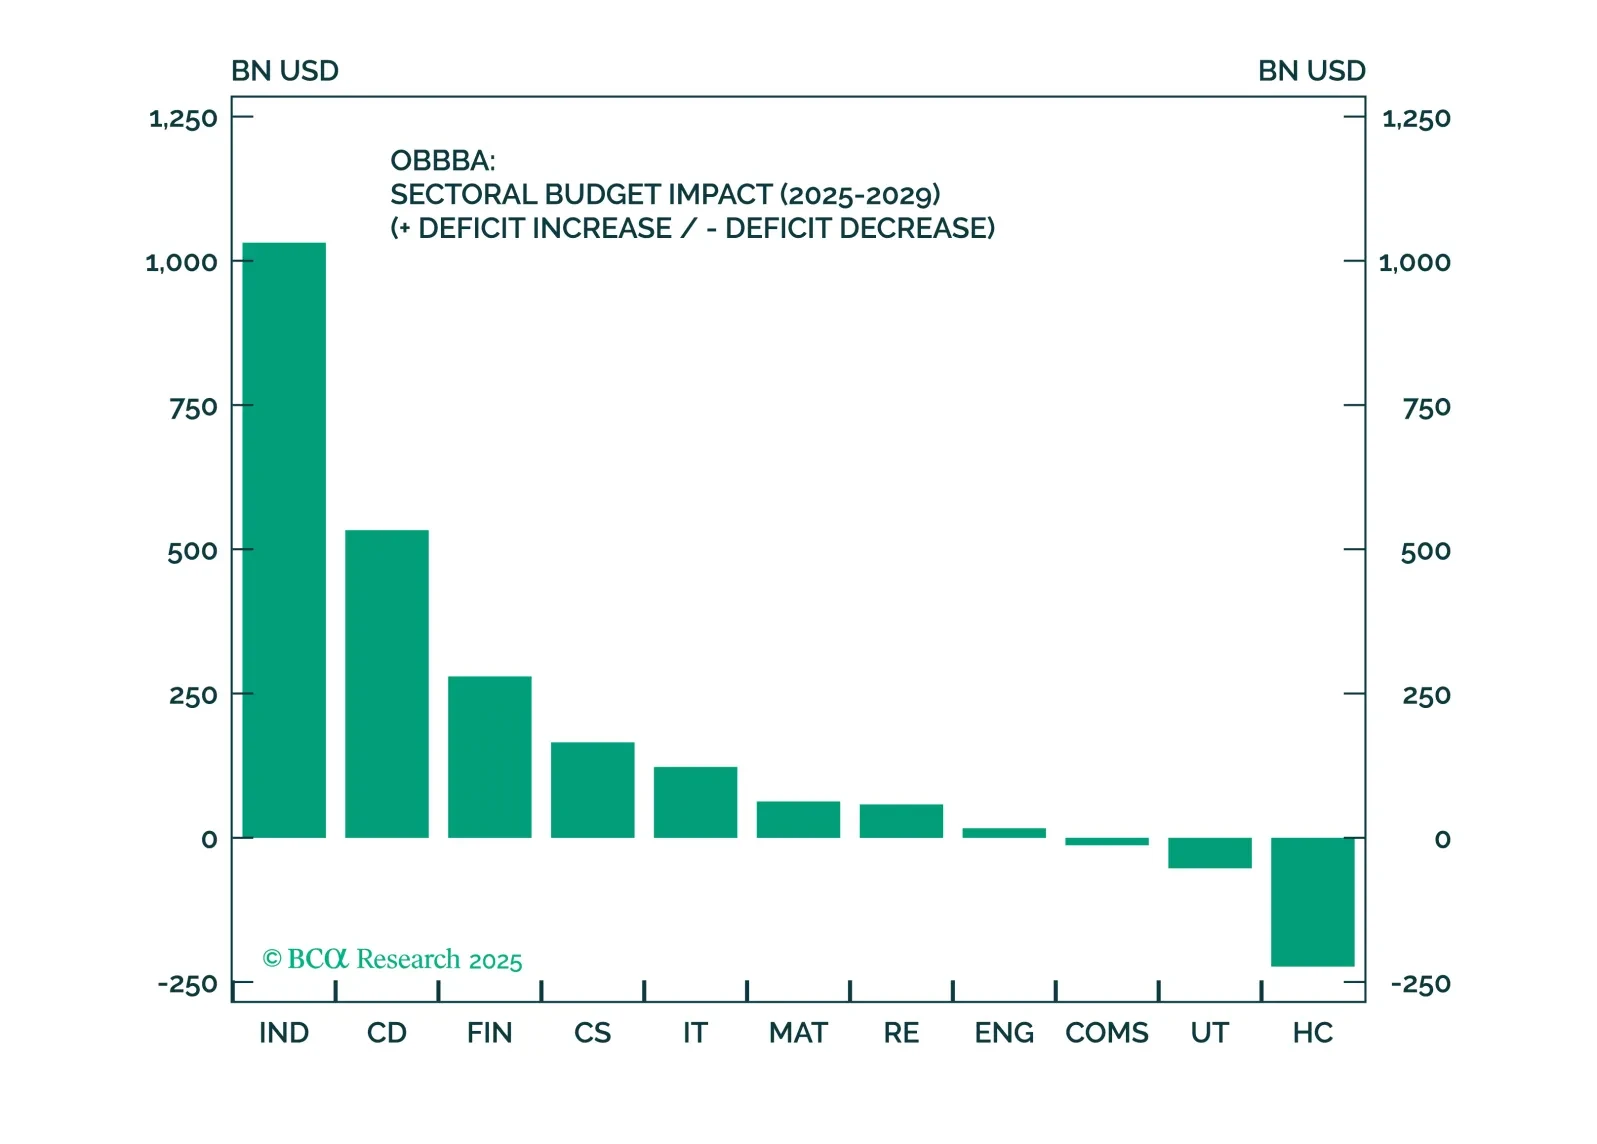
A pesar de los vientos en contra macroeconómicos, el OBBBA claramente favorece los sectores de renta variable de Industriales, Financieros y Consumo Discrecional. Una canasta cuidadosamente construida y consciente de factores en estos sectores está bien posicionada para superar en un entorno incierto impulsado por factores fiscales.
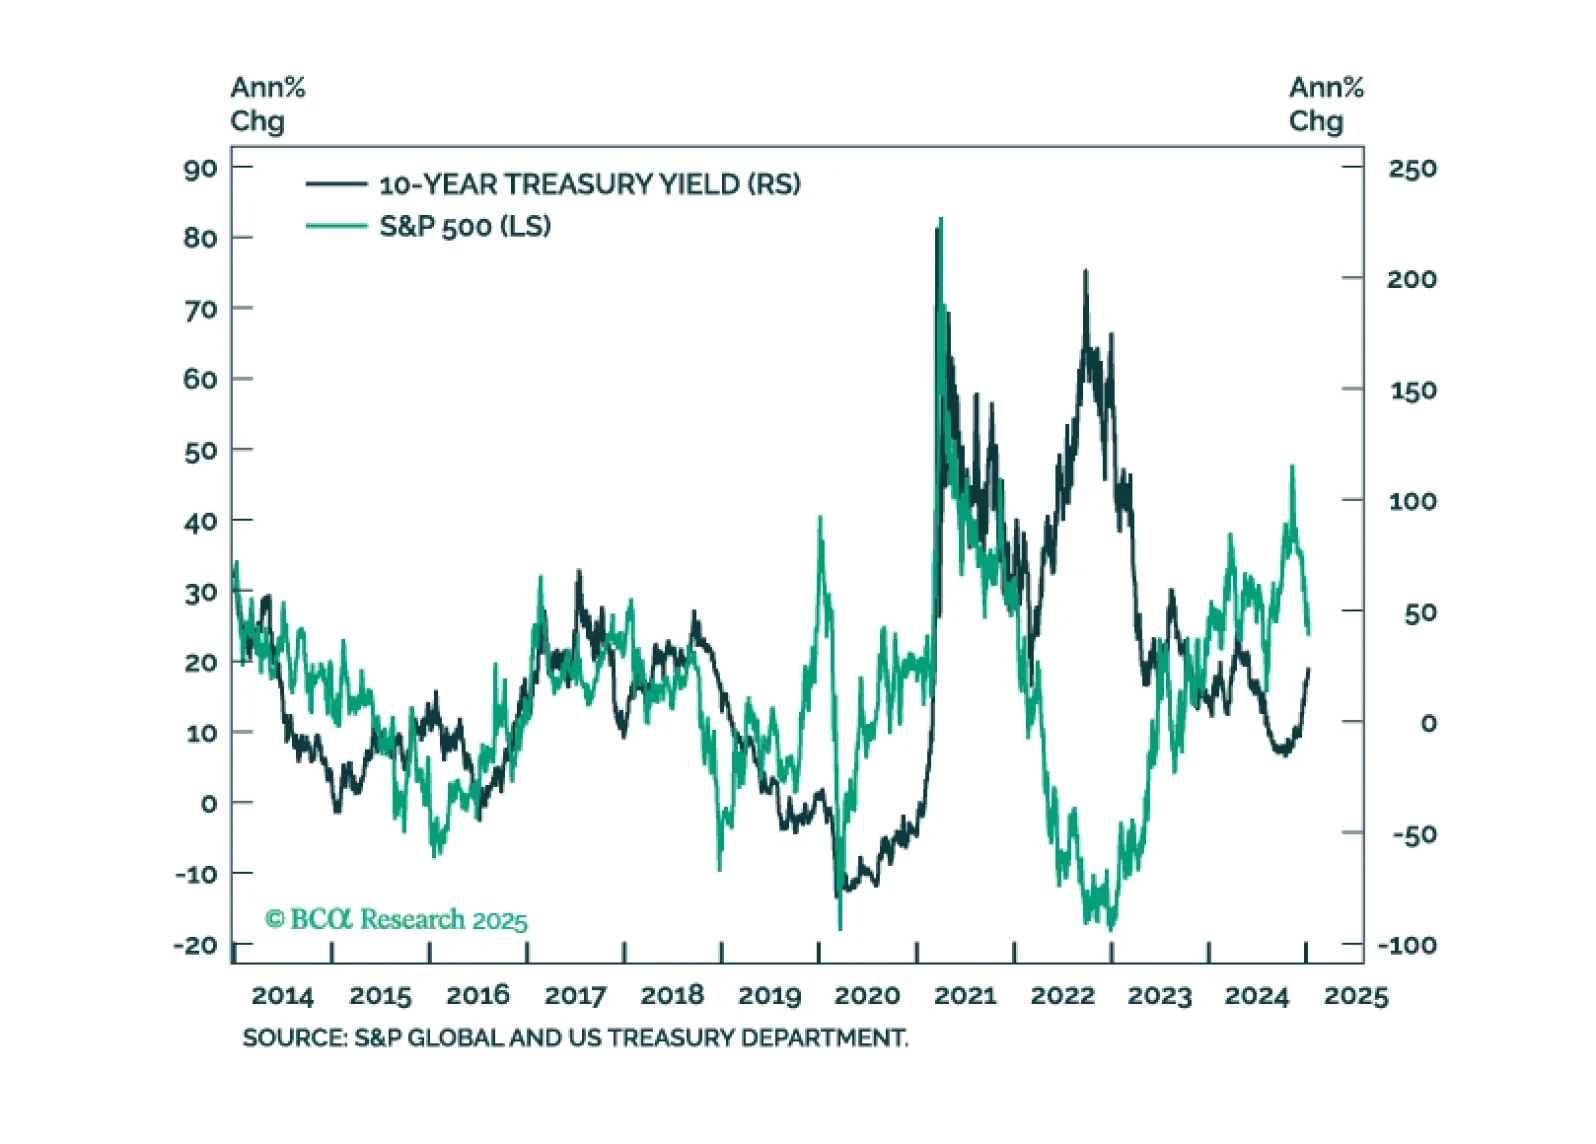
In this first presentation of 2025, we start with an overview of the 2025 outlook webcast polls, and a brief post-mortem of the 2024 market performance. Then, we shift gears and examine what is behind the recent surge in bond yields and its implications for equities. We also review market technicals and positioning and conclude with a list of trades to prepare our portfolio for continued moves in yields.
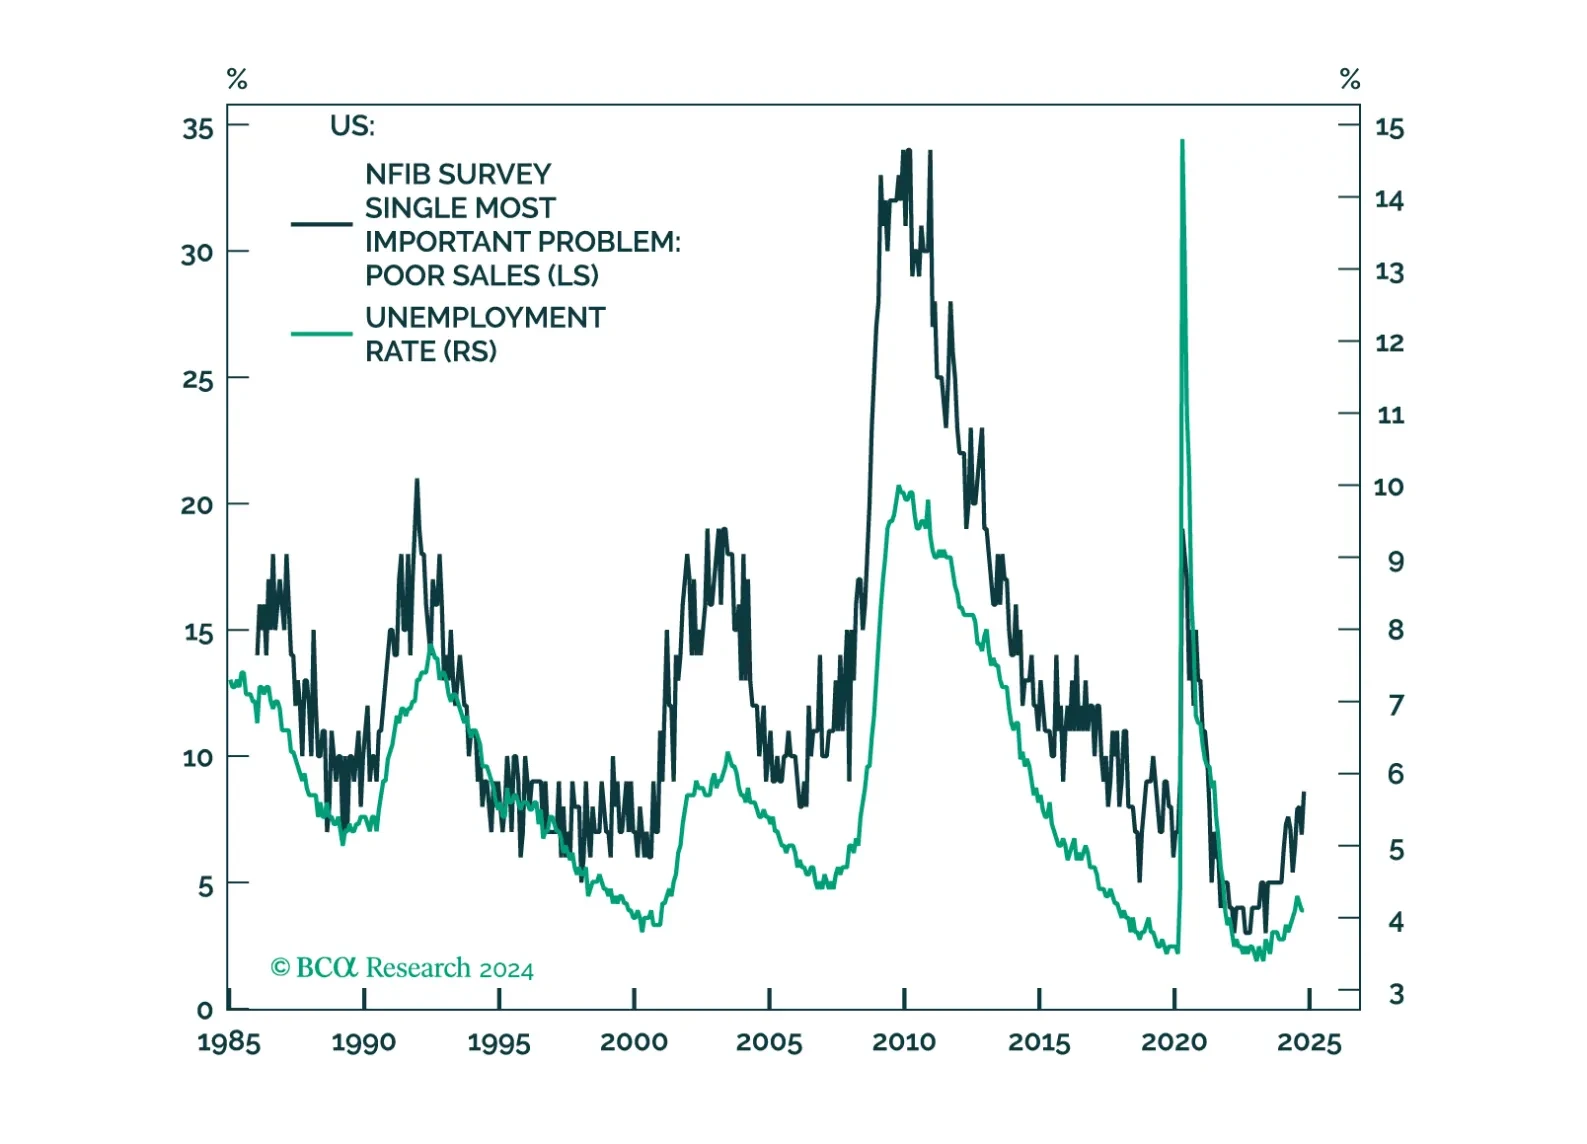
The post-COVID recovery has been one of excesses. Government deficits have ballooned, tight labor markets have led to a windfall of consumer spending, and equity valuations have soared on the back of lofty growth expectations. But these excesses will no longer be sustainable in 2025. Our theme for next year is Thin Is Back In. Government budgets, economic growth, and equity valuations will be leaner than investors expect. We discuss this the reasoning behind this macro view and the asset allocation implications that follow from it.
