Acciones
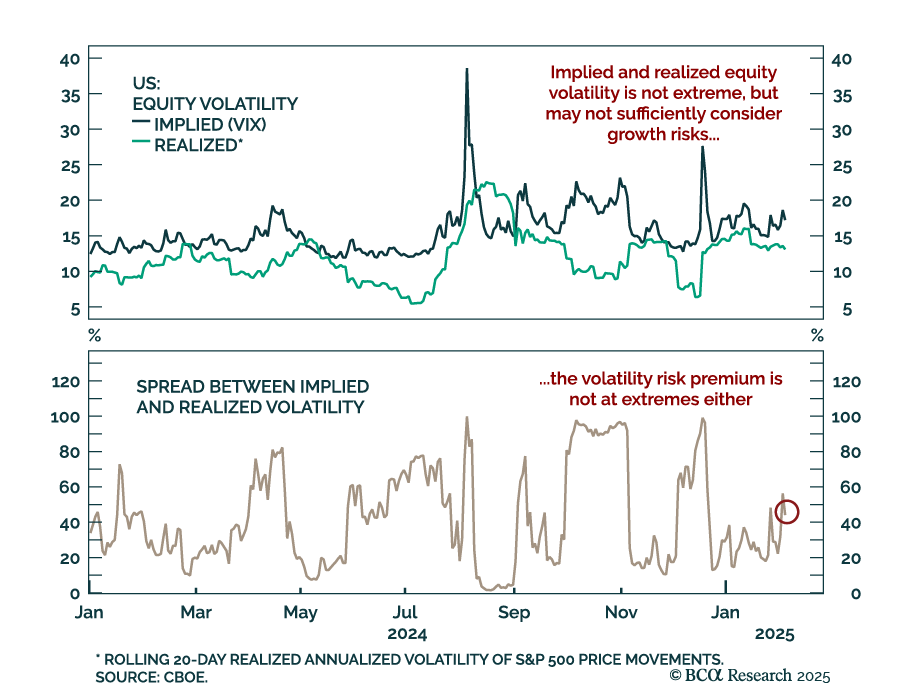
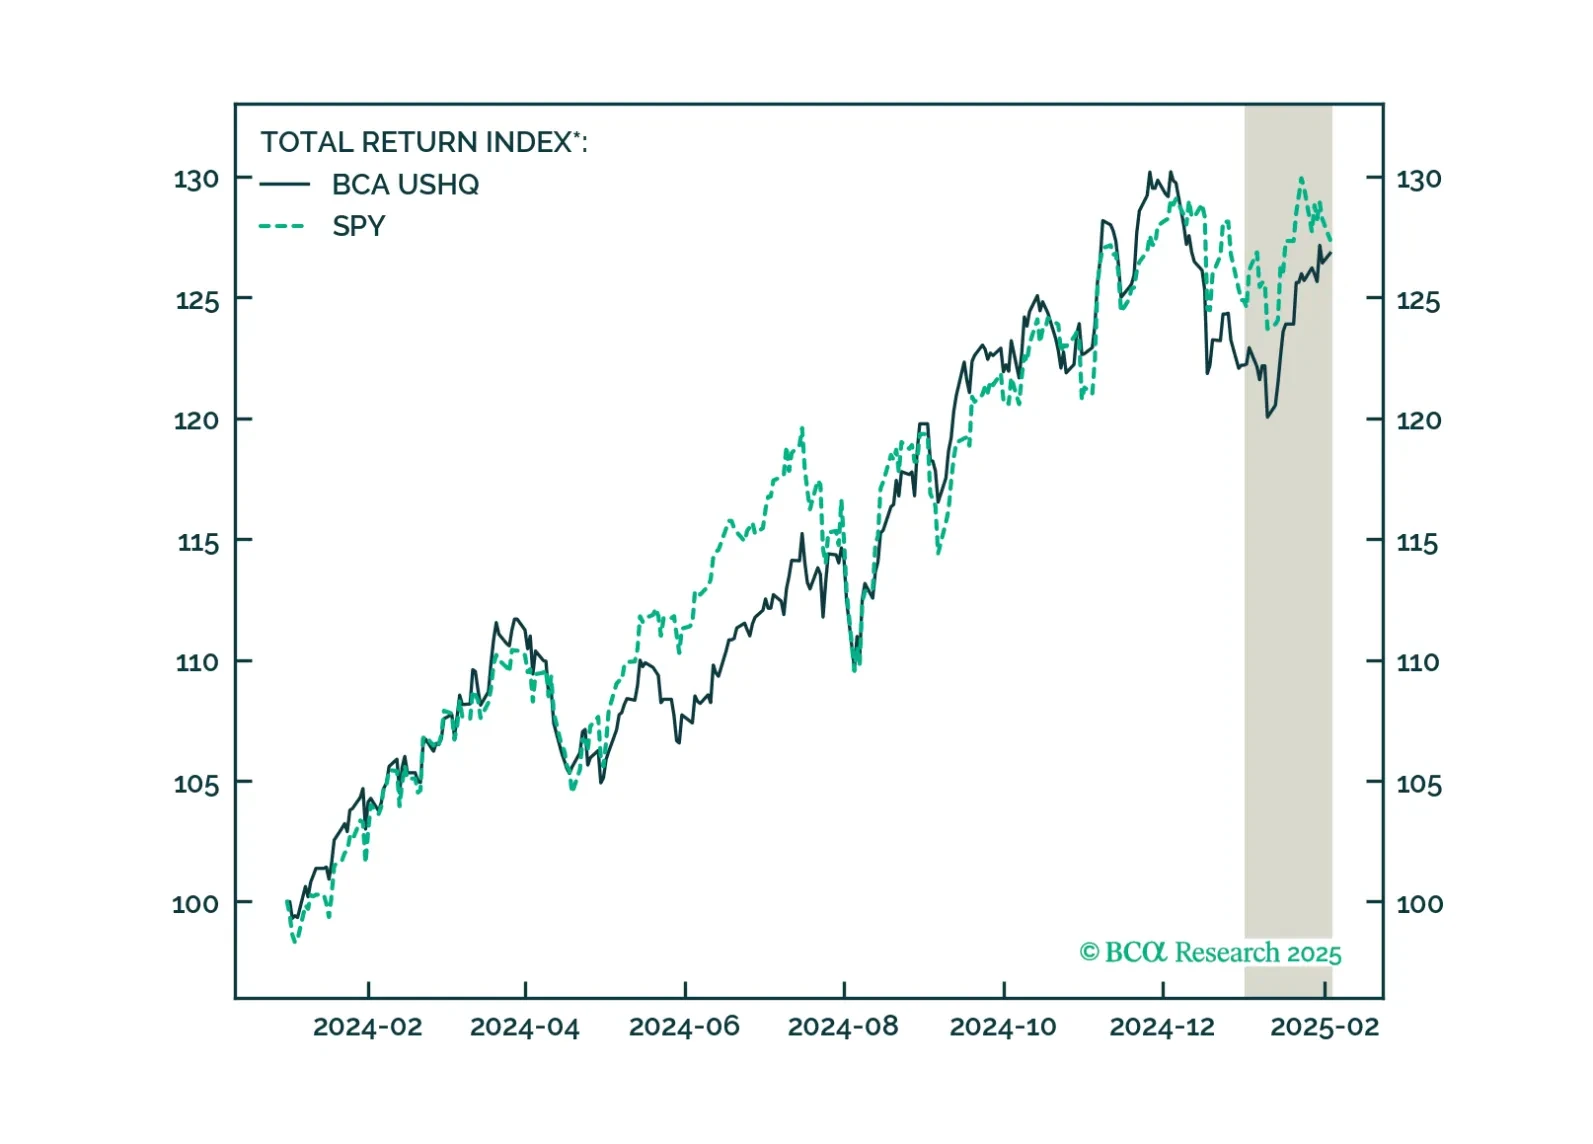
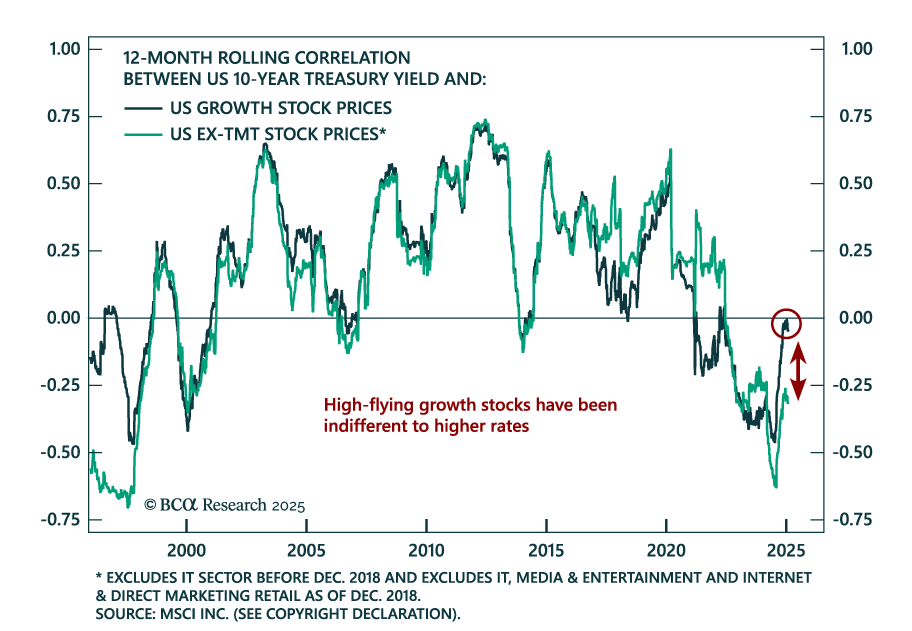
The US High-Quality (USHQ) portfolio slightly outperformed in January, returning 3.4%, whilst its SPY benchmark returned 2.9%. That said, we think the USHQ portfolio will have a solid run through the first half of 2025, benefitting from rising market risk on the back of President Trump’s tariff agenda. USHQ’s underlying Quality and Safety Score factor tilts will be increasingly favored as market uncertainty grows.
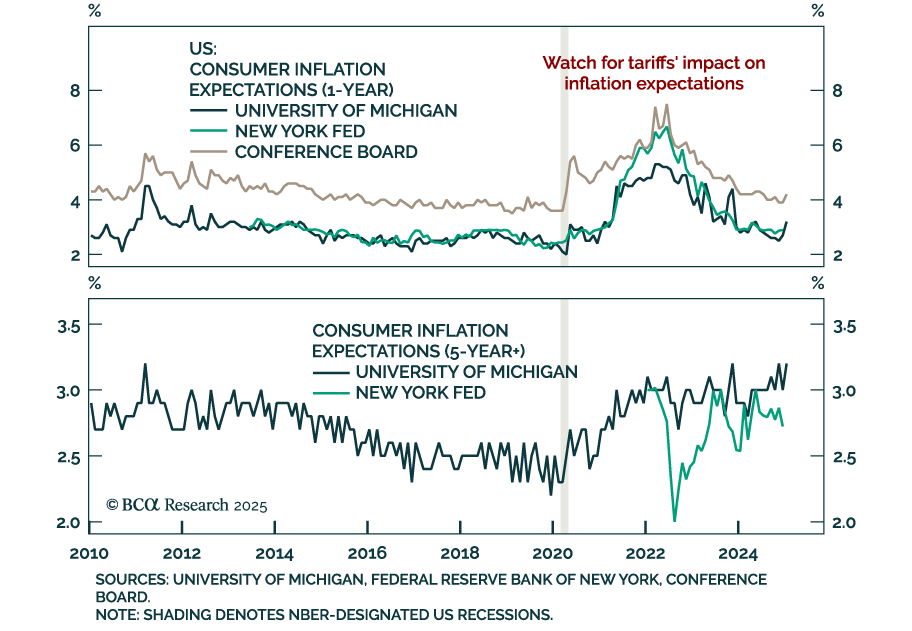
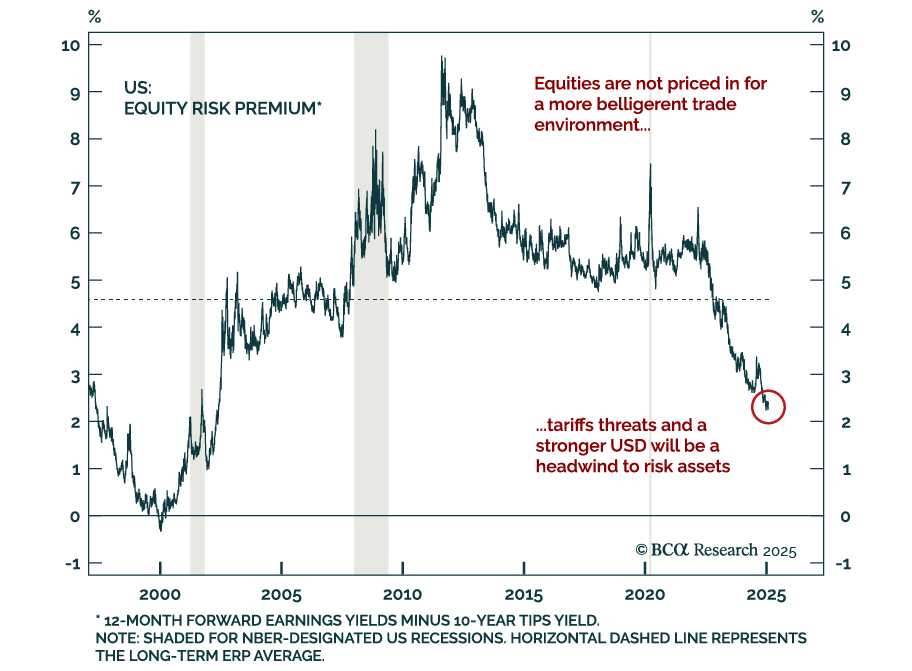
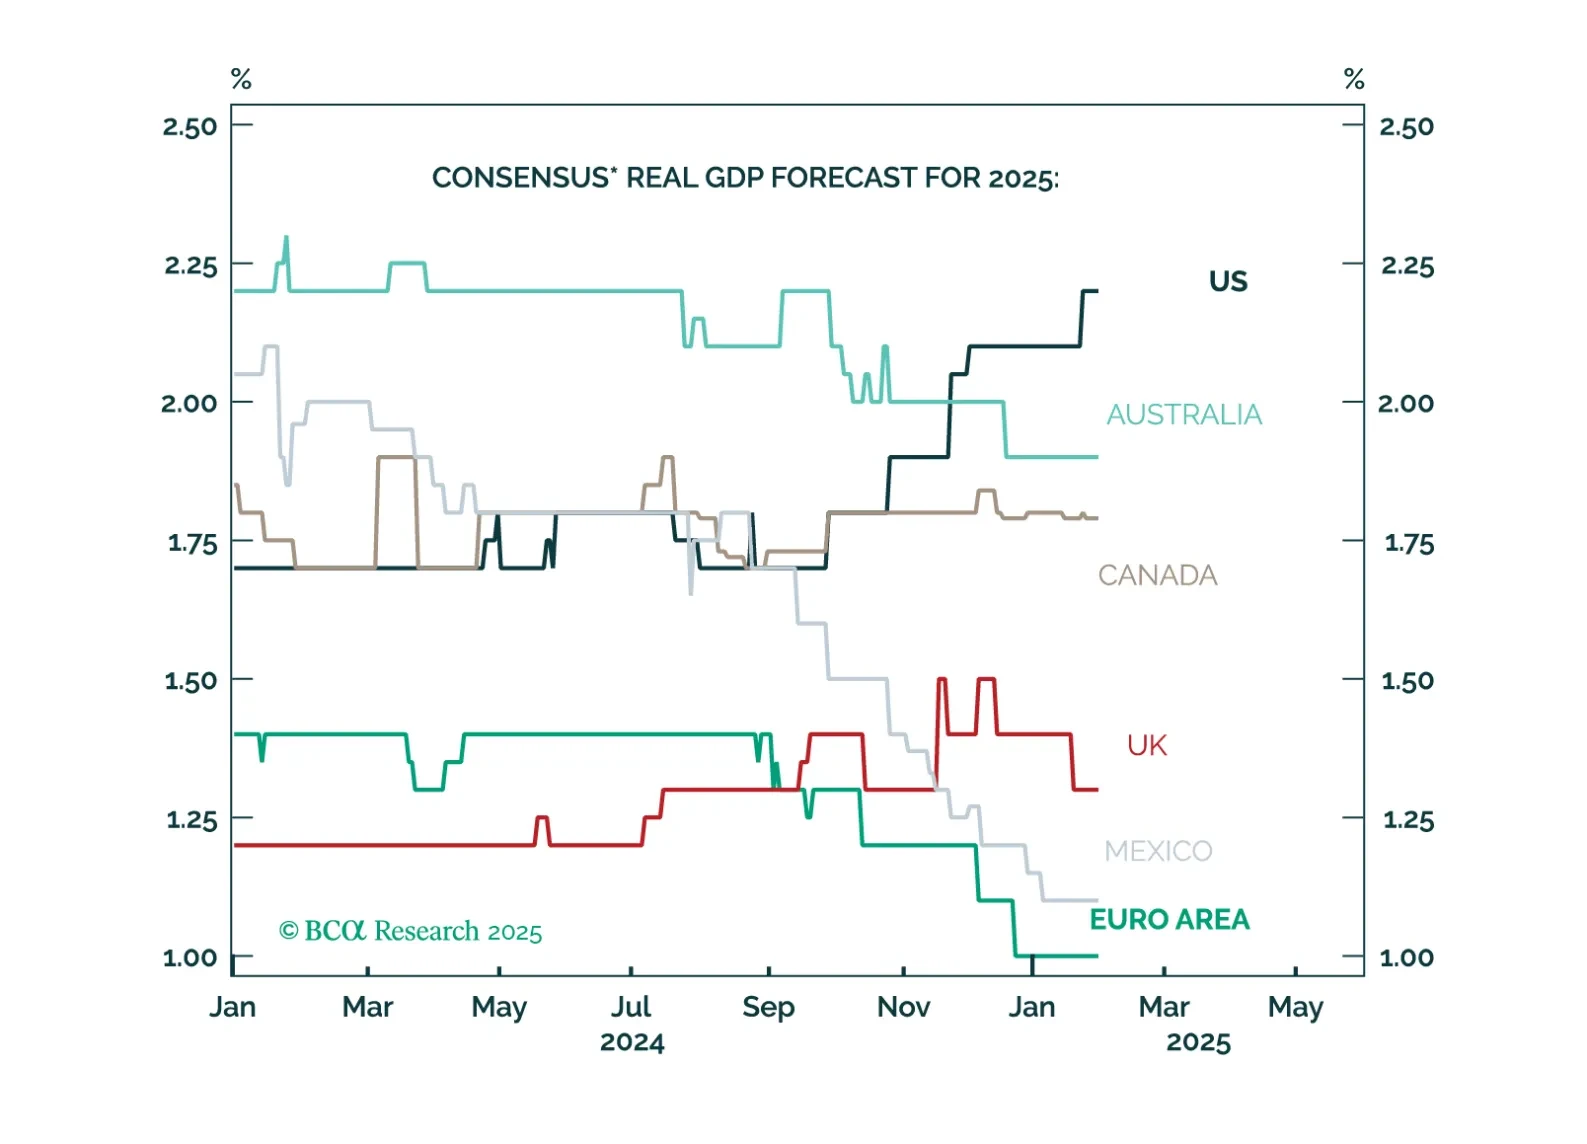
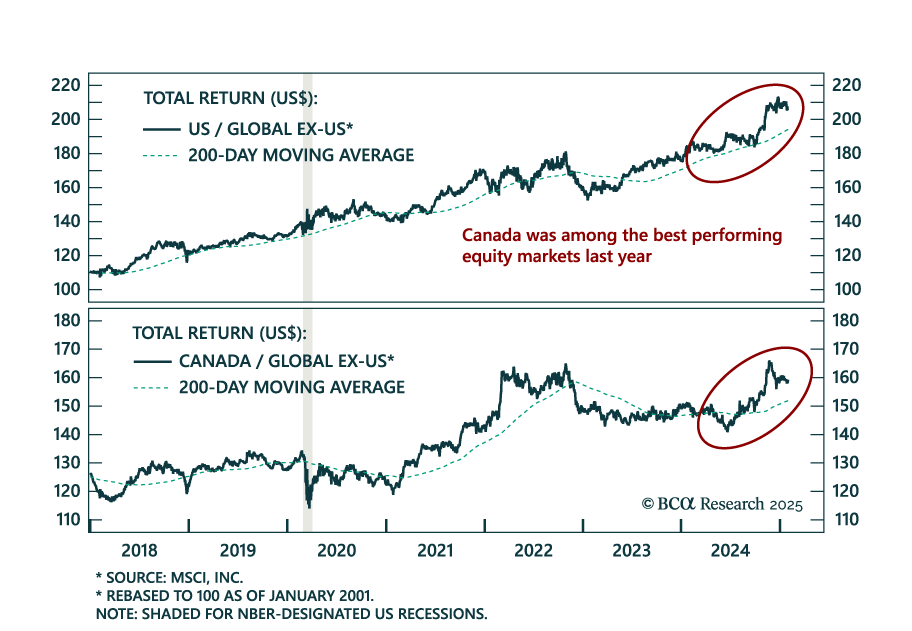
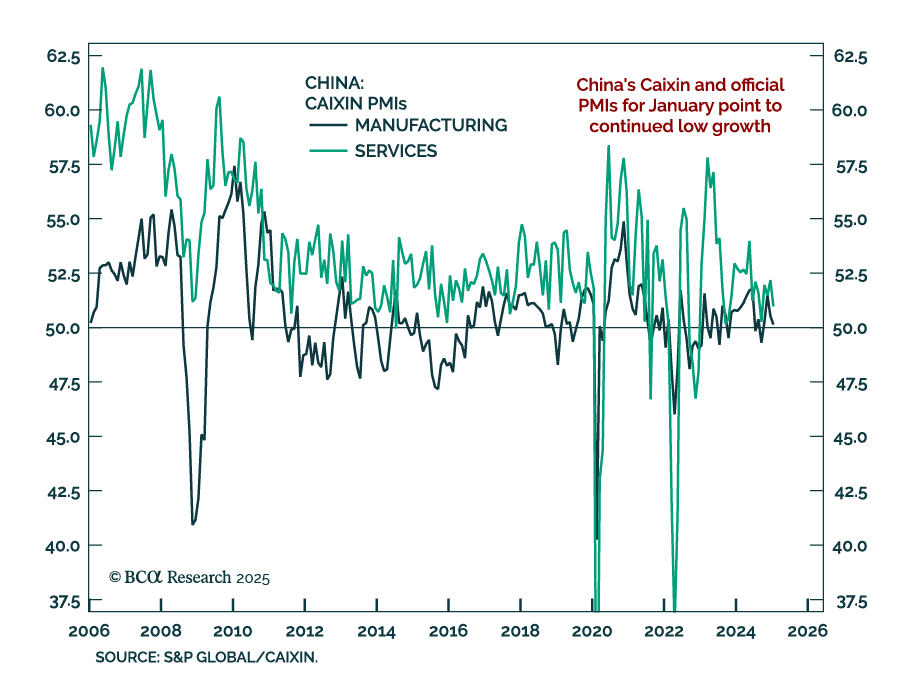
Markets and forecasters anticipate a “Golden Age” for Trump’s America, with US growth expectations soaring while the rest of the world lags. However, this extreme optimism means that there is a lot of room for disappointment. Cooling income growth, weak housing and less deficit spending than expected will result in US growth underperforming expectations. Maintain a modest underweight to equities and modest overweight to fixed income. US markets have become more expensive relative to the rest of the world even as quality differentials have stabilized. Prepare to downgrade US equities to underweight and to upgrade Euro Area and China to overweight. We will wait to pull the trigger until we have more clarity on trade policy and when the dollar's momentum turns negative.
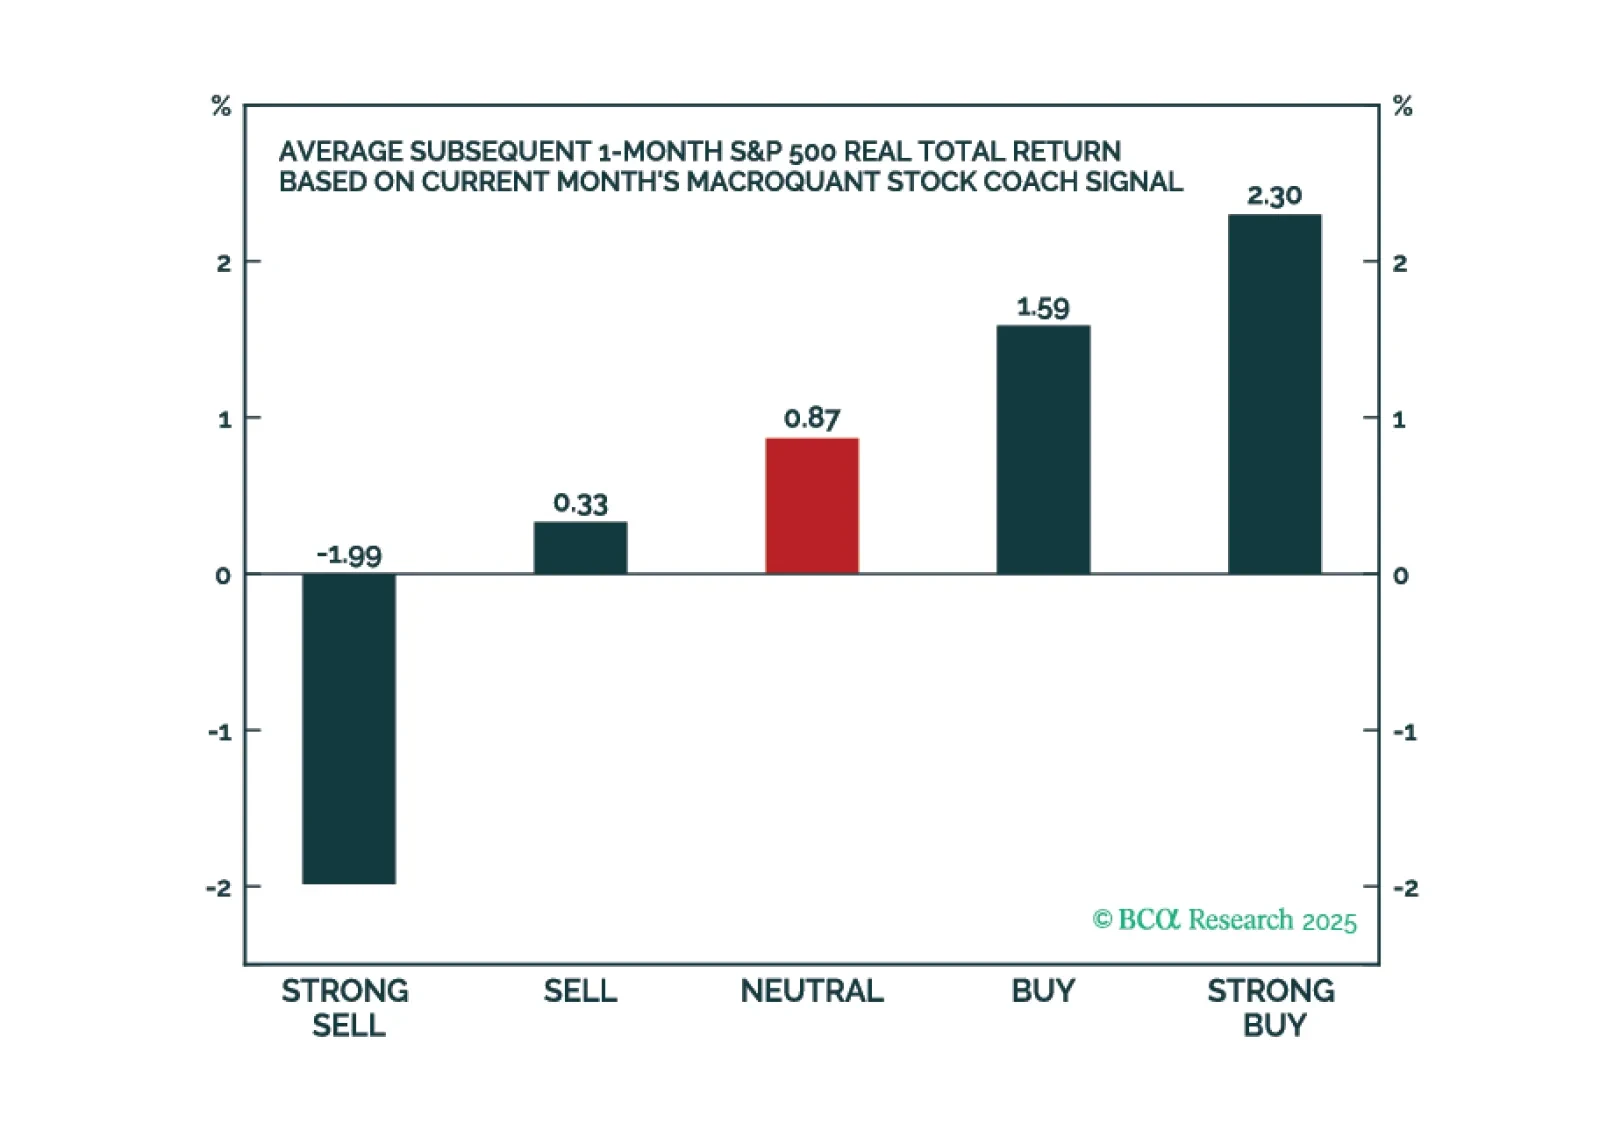
La versión más reciente del modelo MacroQuant sugiere que el mercado alcista de las acciones estadounidenses está llegando a su fin. El modelo espera que los rendimientos del Tesoro bajen más adelante este año, pero aún no está listo para adoptar una posición larga en duración.
La última versión del modelo MacroQuant sugiere que el mercado alcista de las acciones de EE. UU. está llegando a su fin. El modelo espera que los rendimientos del Tesoro caigan más adelante este año, pero aún no está listo para tomar posiciones de larga duración.