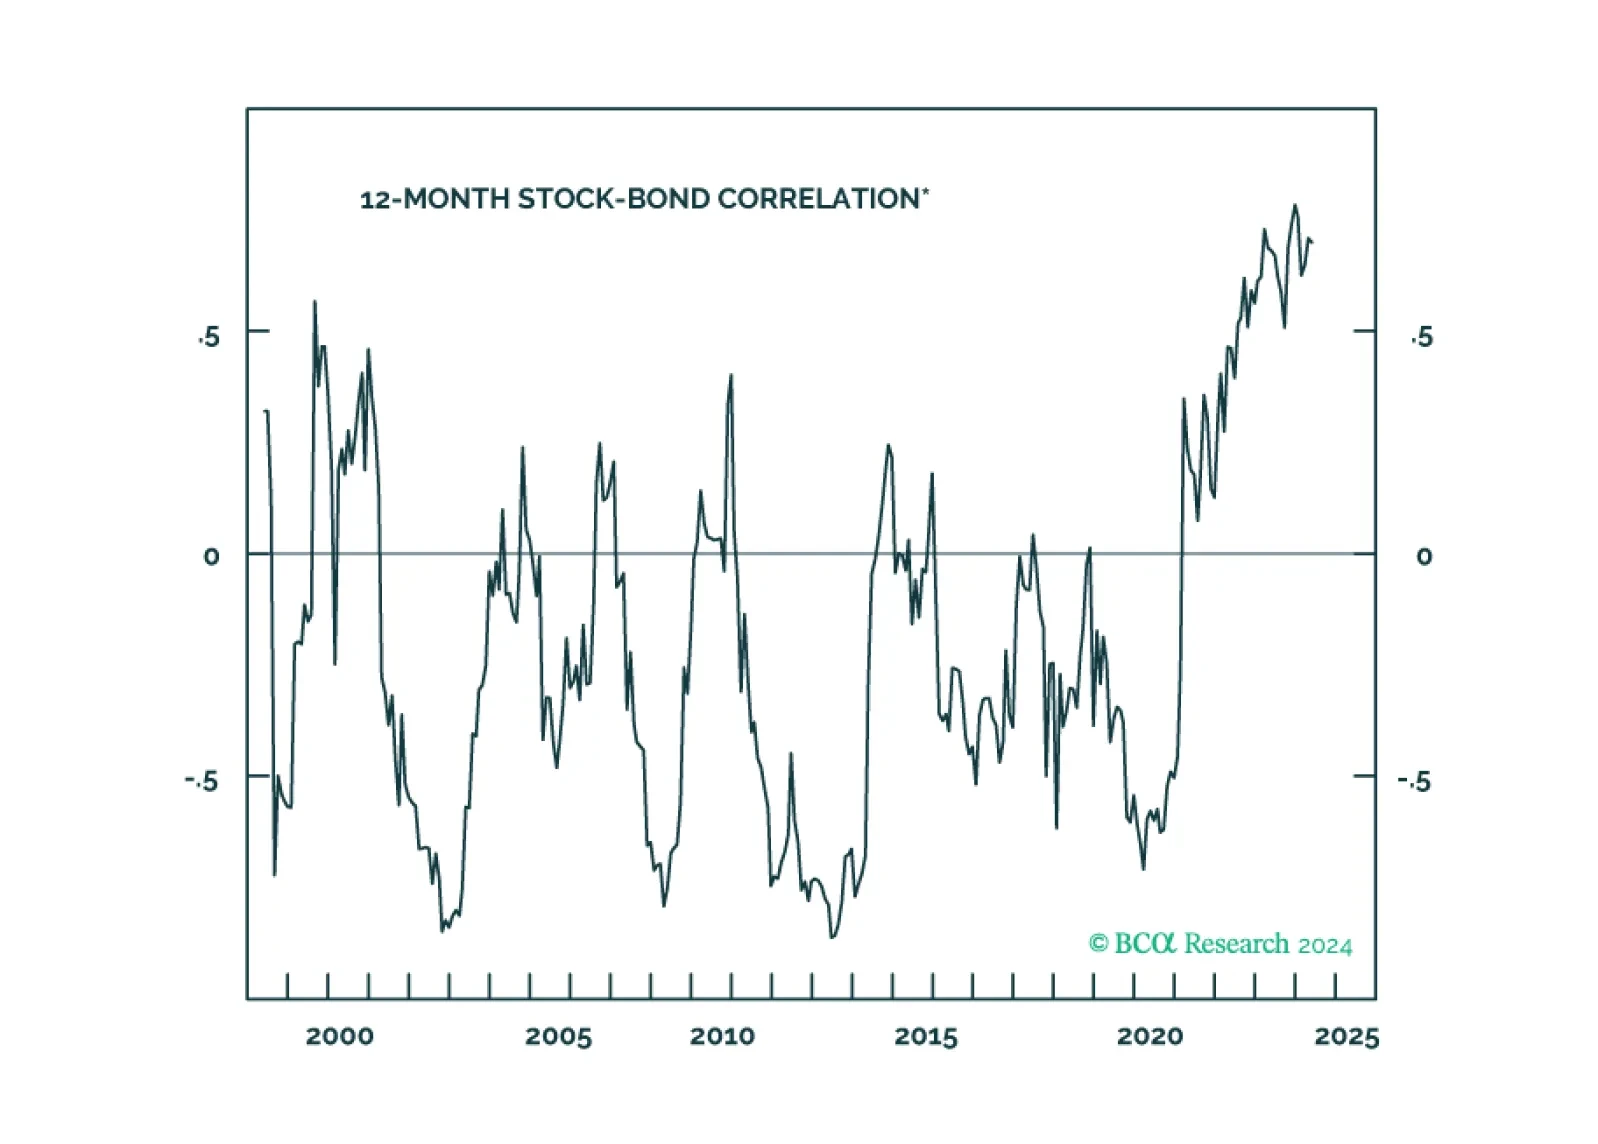
FICC
Find out more
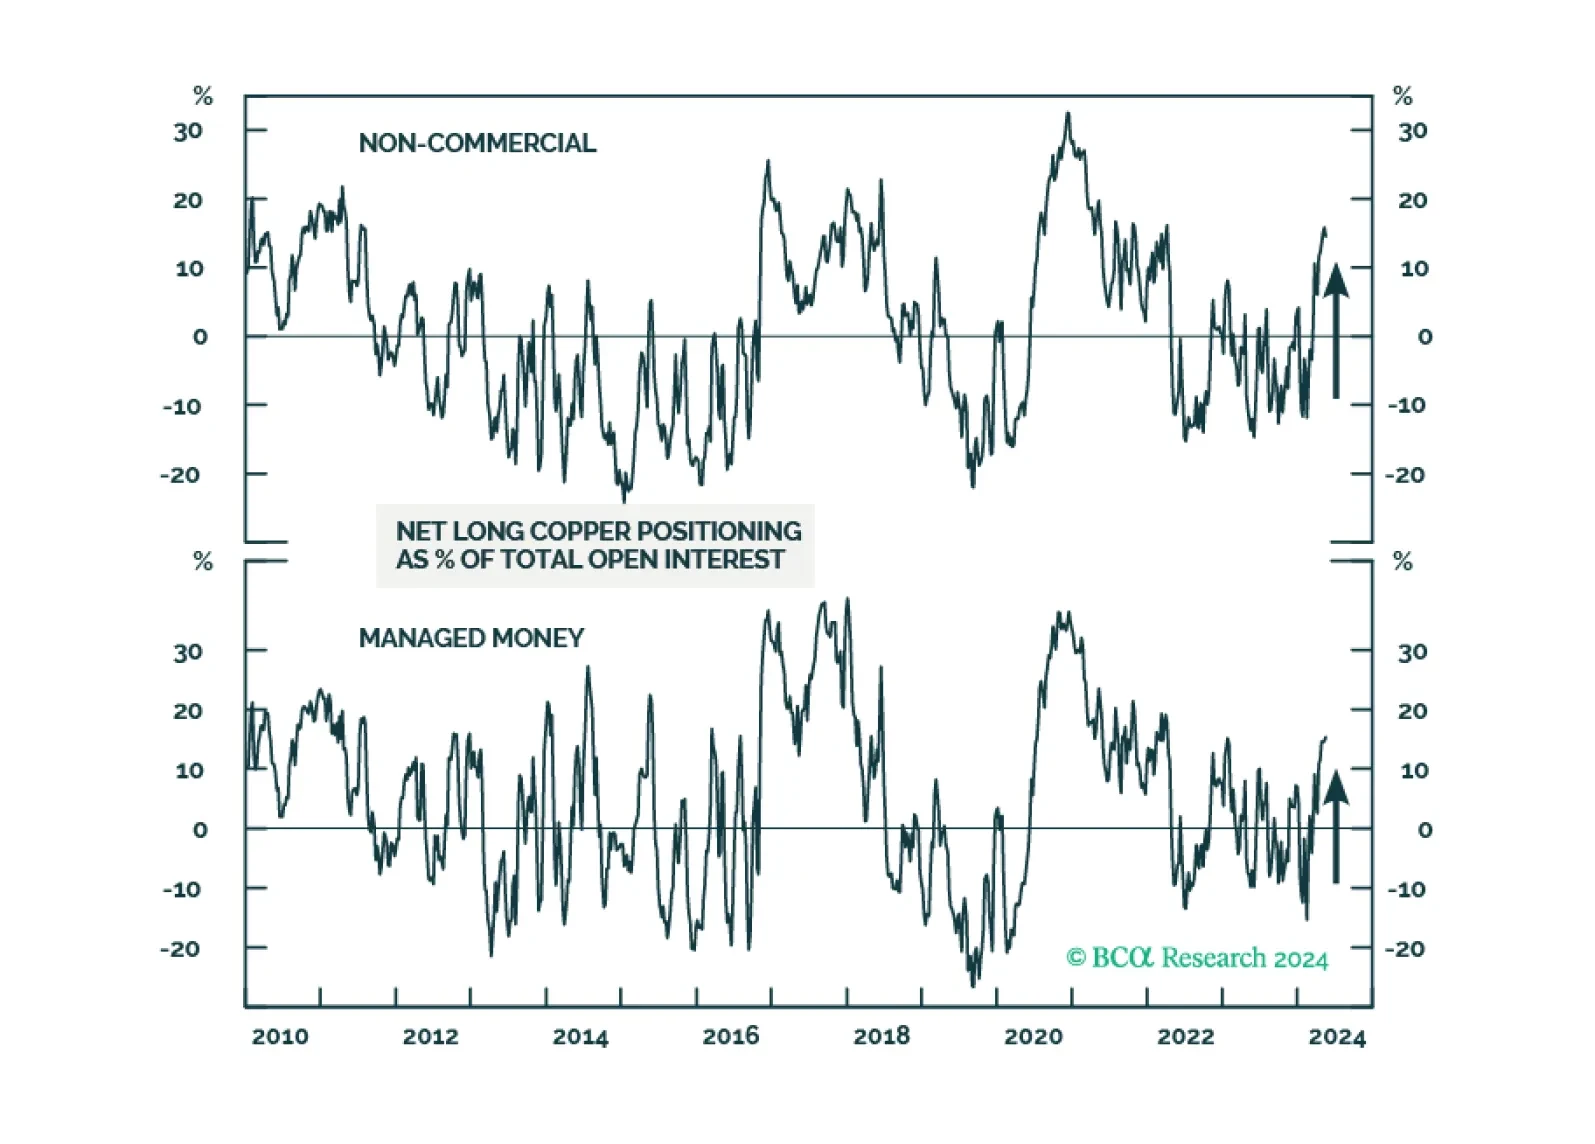
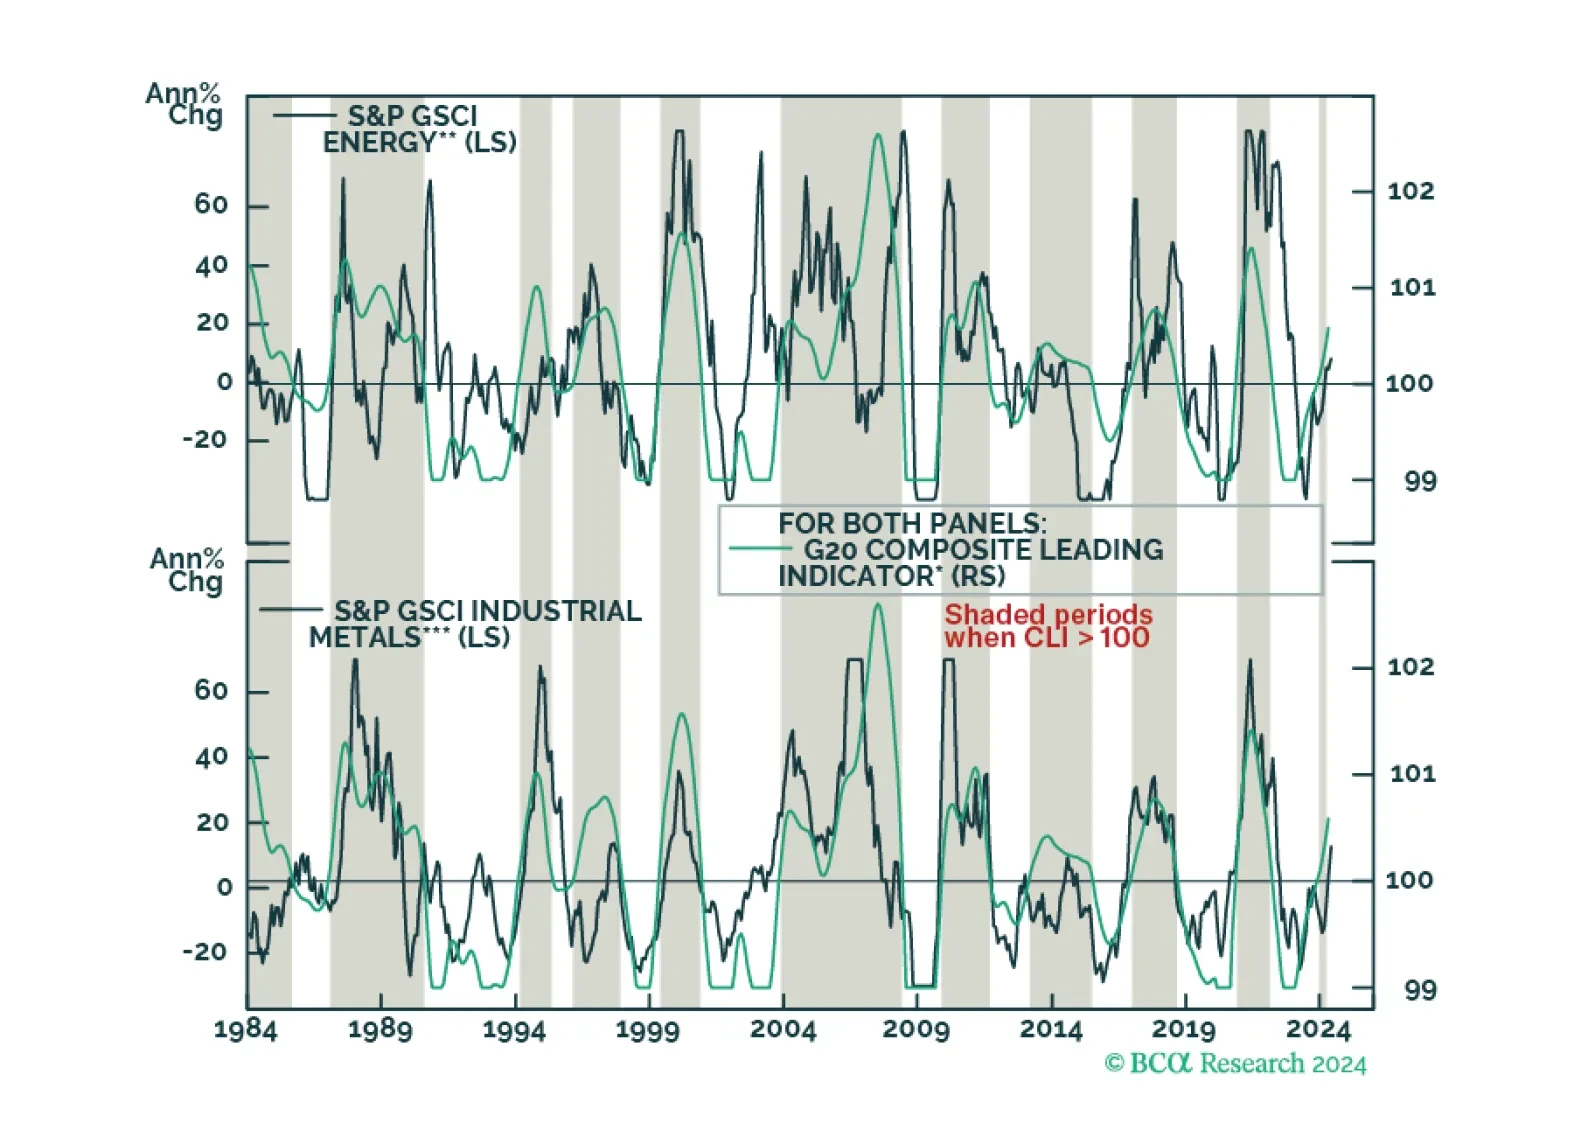
The sharp move higher in copper prices is missing a clear fundamental catalyst. Meanwhile, the cyclical outlook for the global economy in general, and manufacturing activity in particular, is unlikely to provide a tailwind. Given that aggregate copper inventories on global exchanges have been rising briskly, there are high odds that the copper price surge will soon reverse.
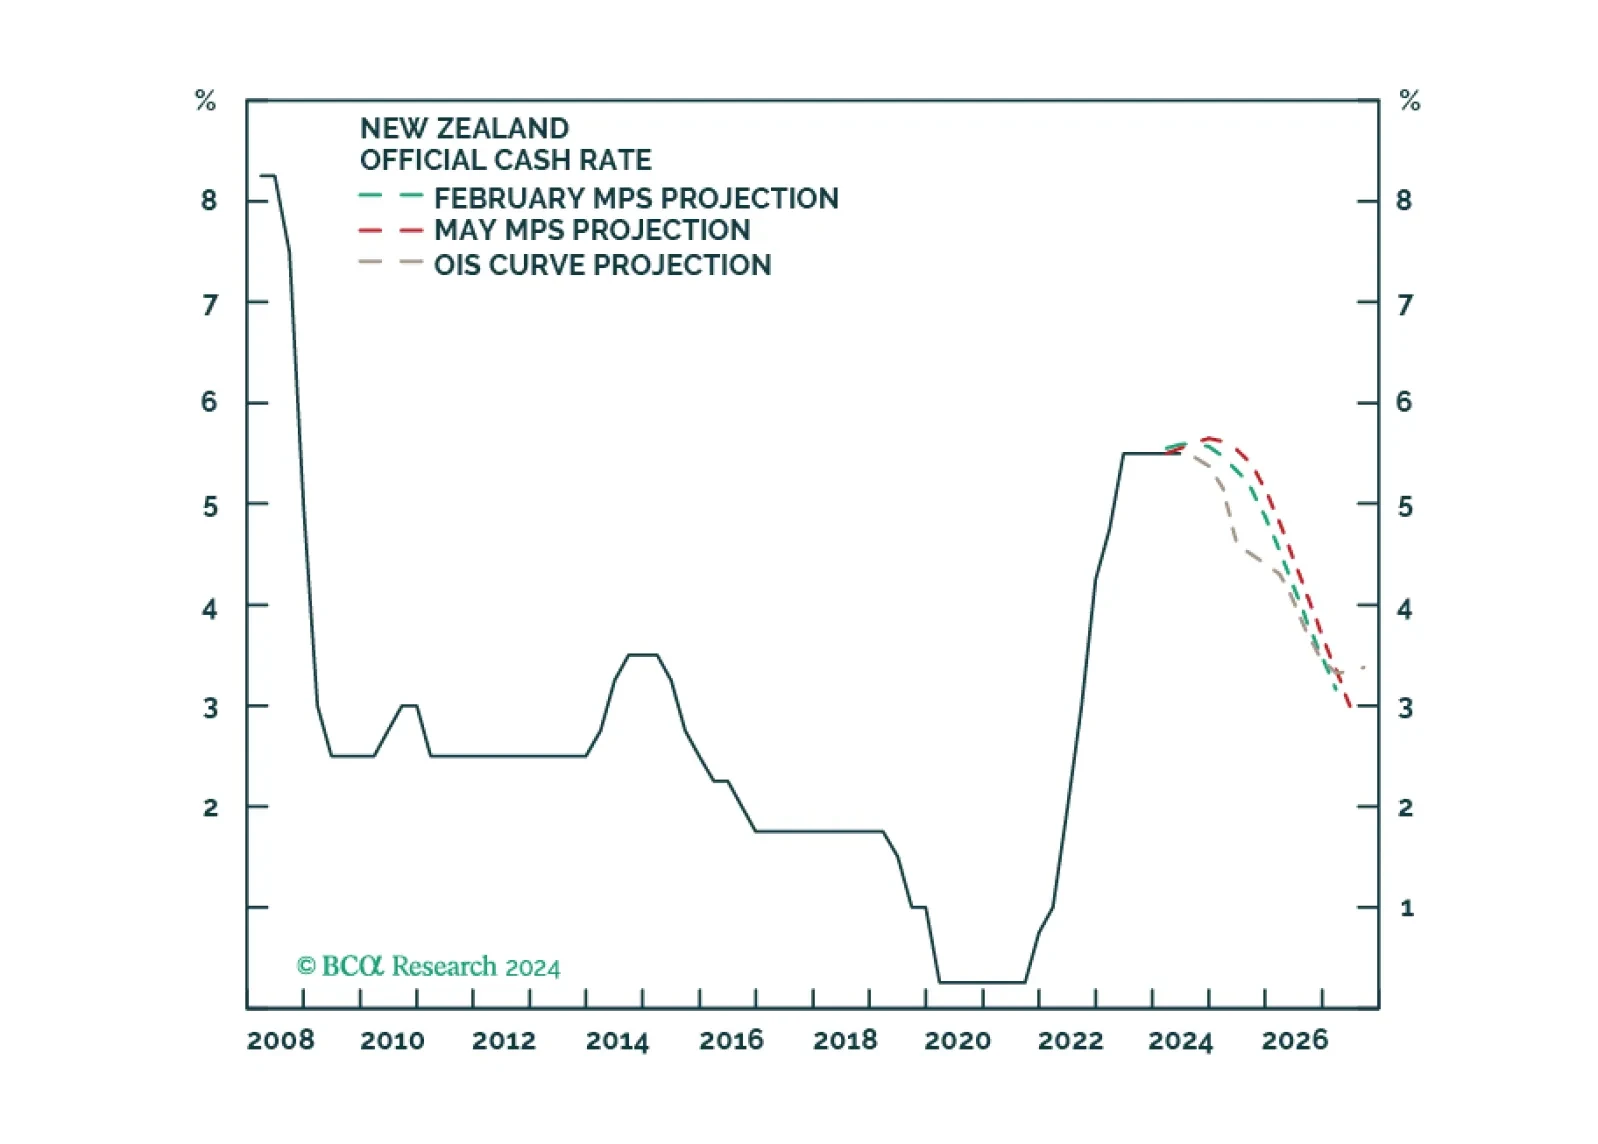
In this Insight, we revisit our "higher for longer" theme for the Reserve Bank of New Zealand, in light of the latest central bank meeting. In conclusion, we are inching towards a more dovish RBNZ ahead. Ergo, we recommend some fixed income and currency trades.
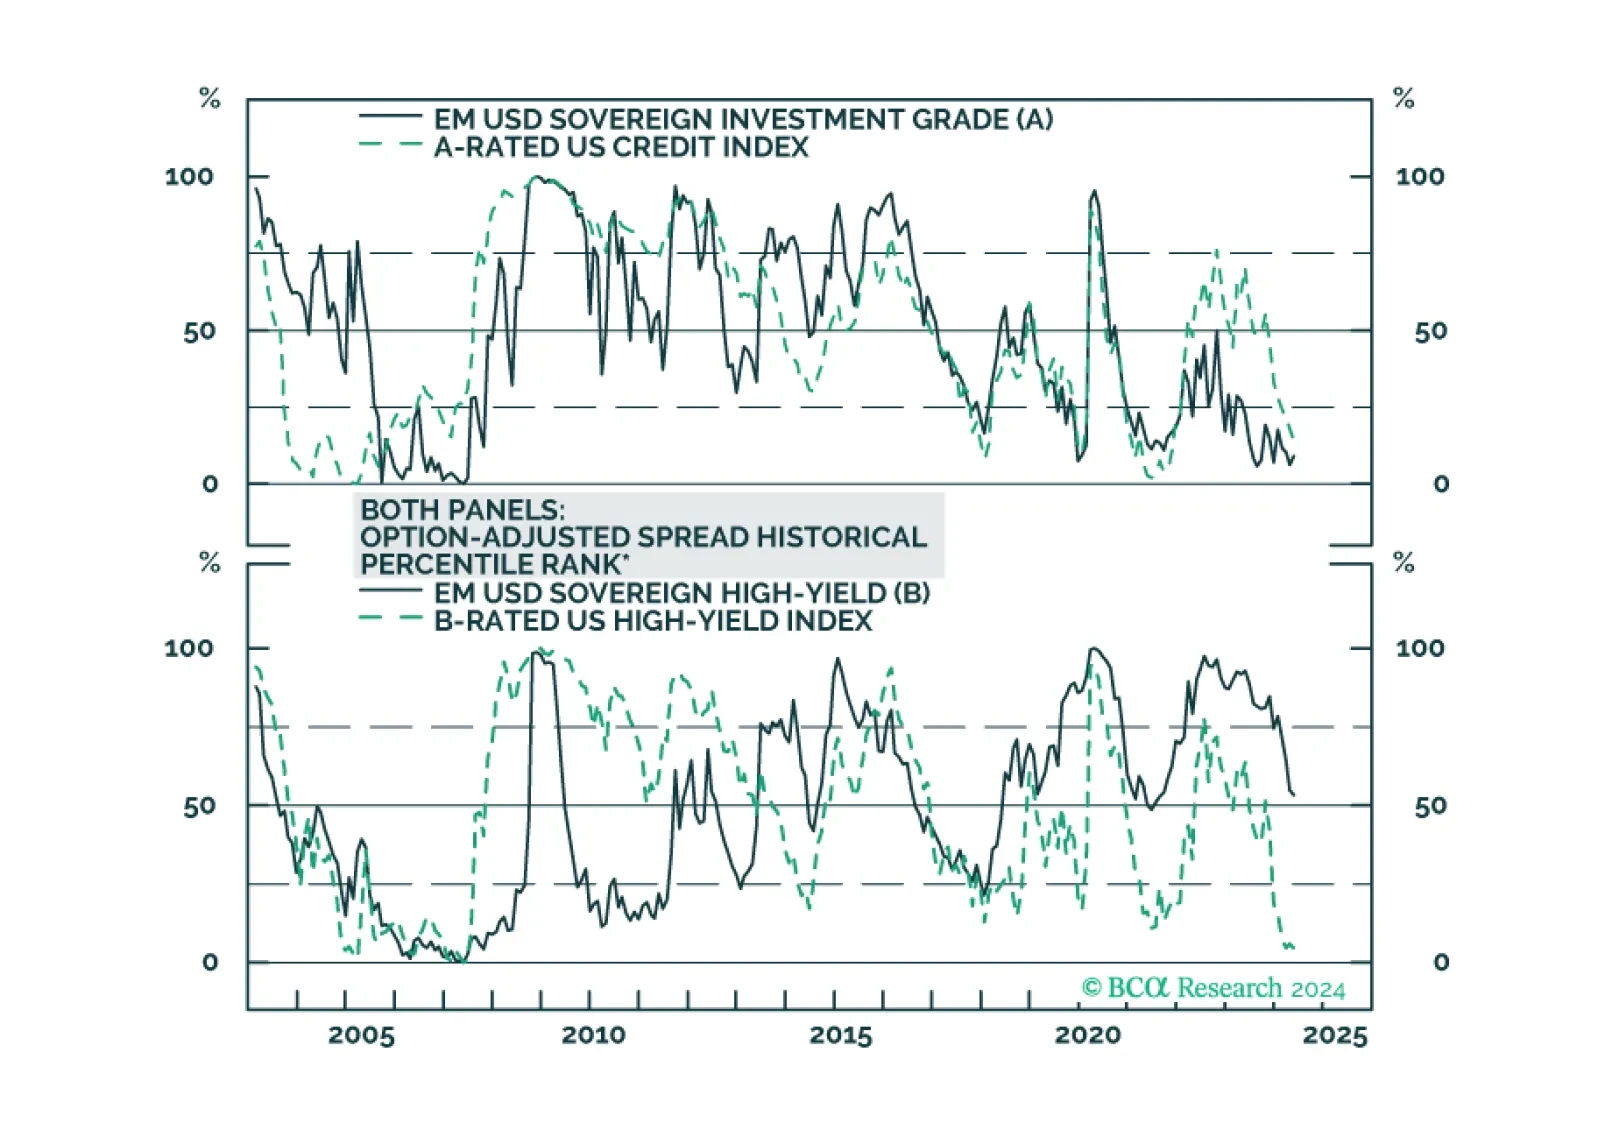
We dig into the USD-denominated Emerging Market Sovereign Index to see which credit tiers and countries offer value relative to US Credit.
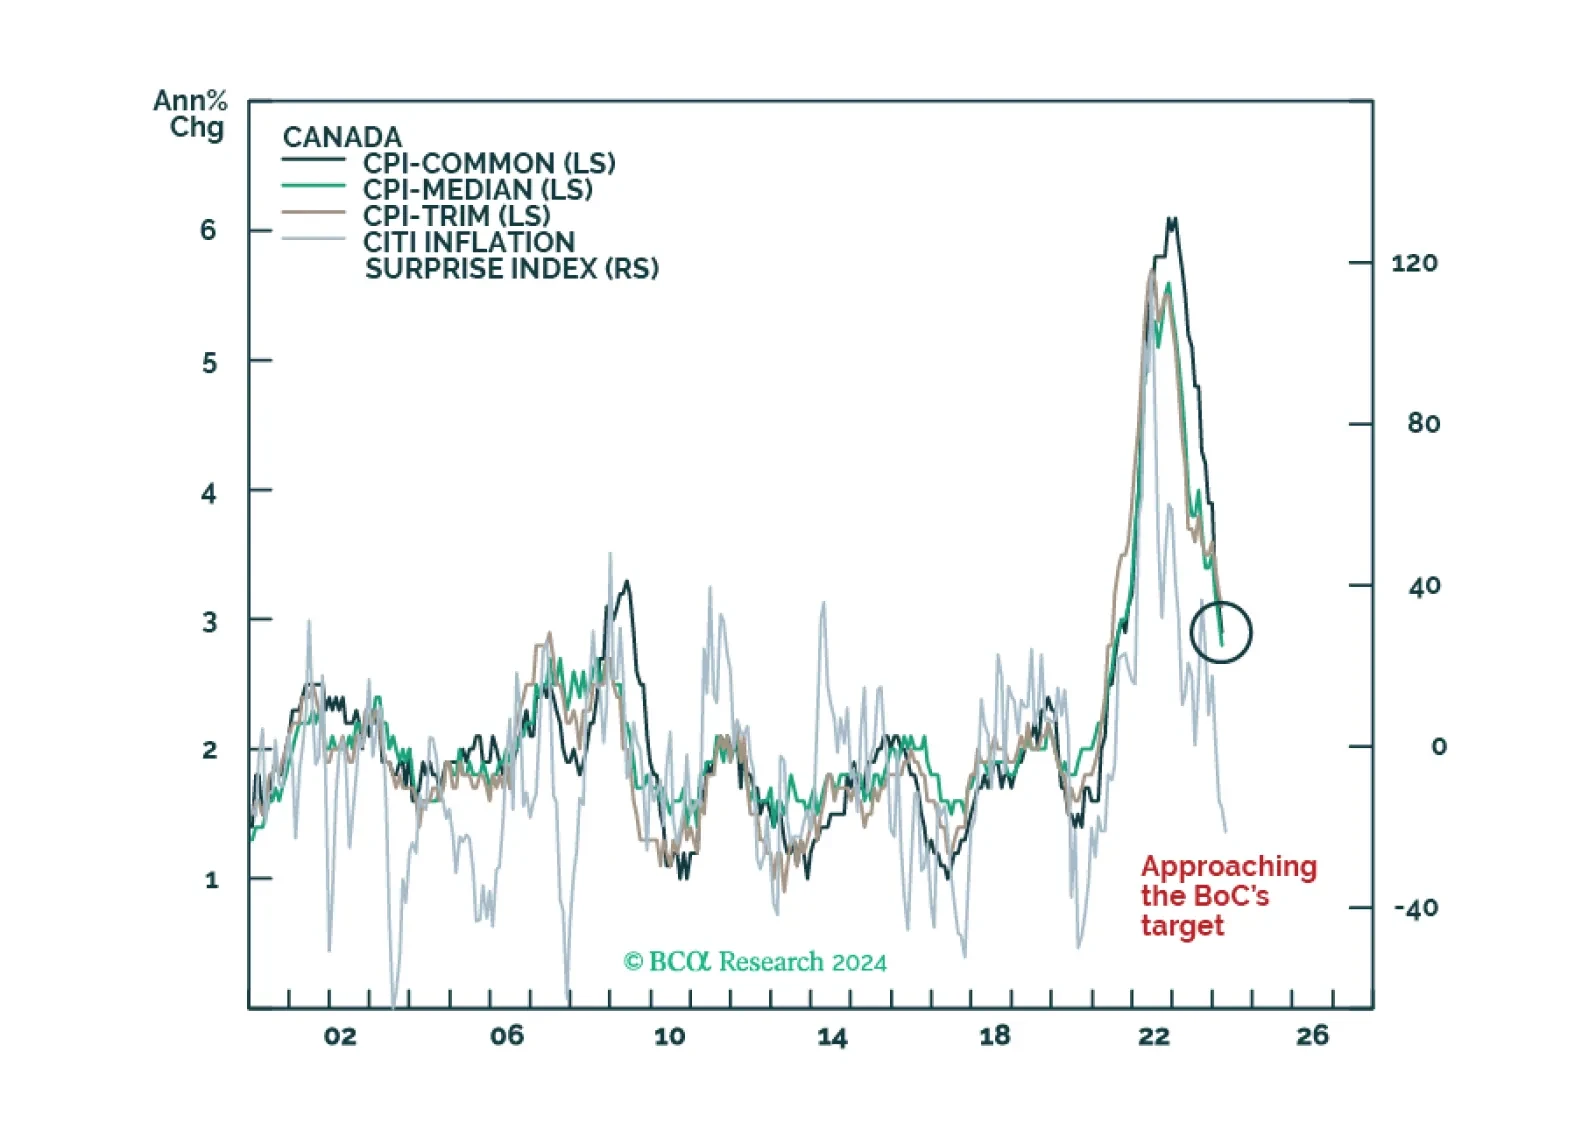
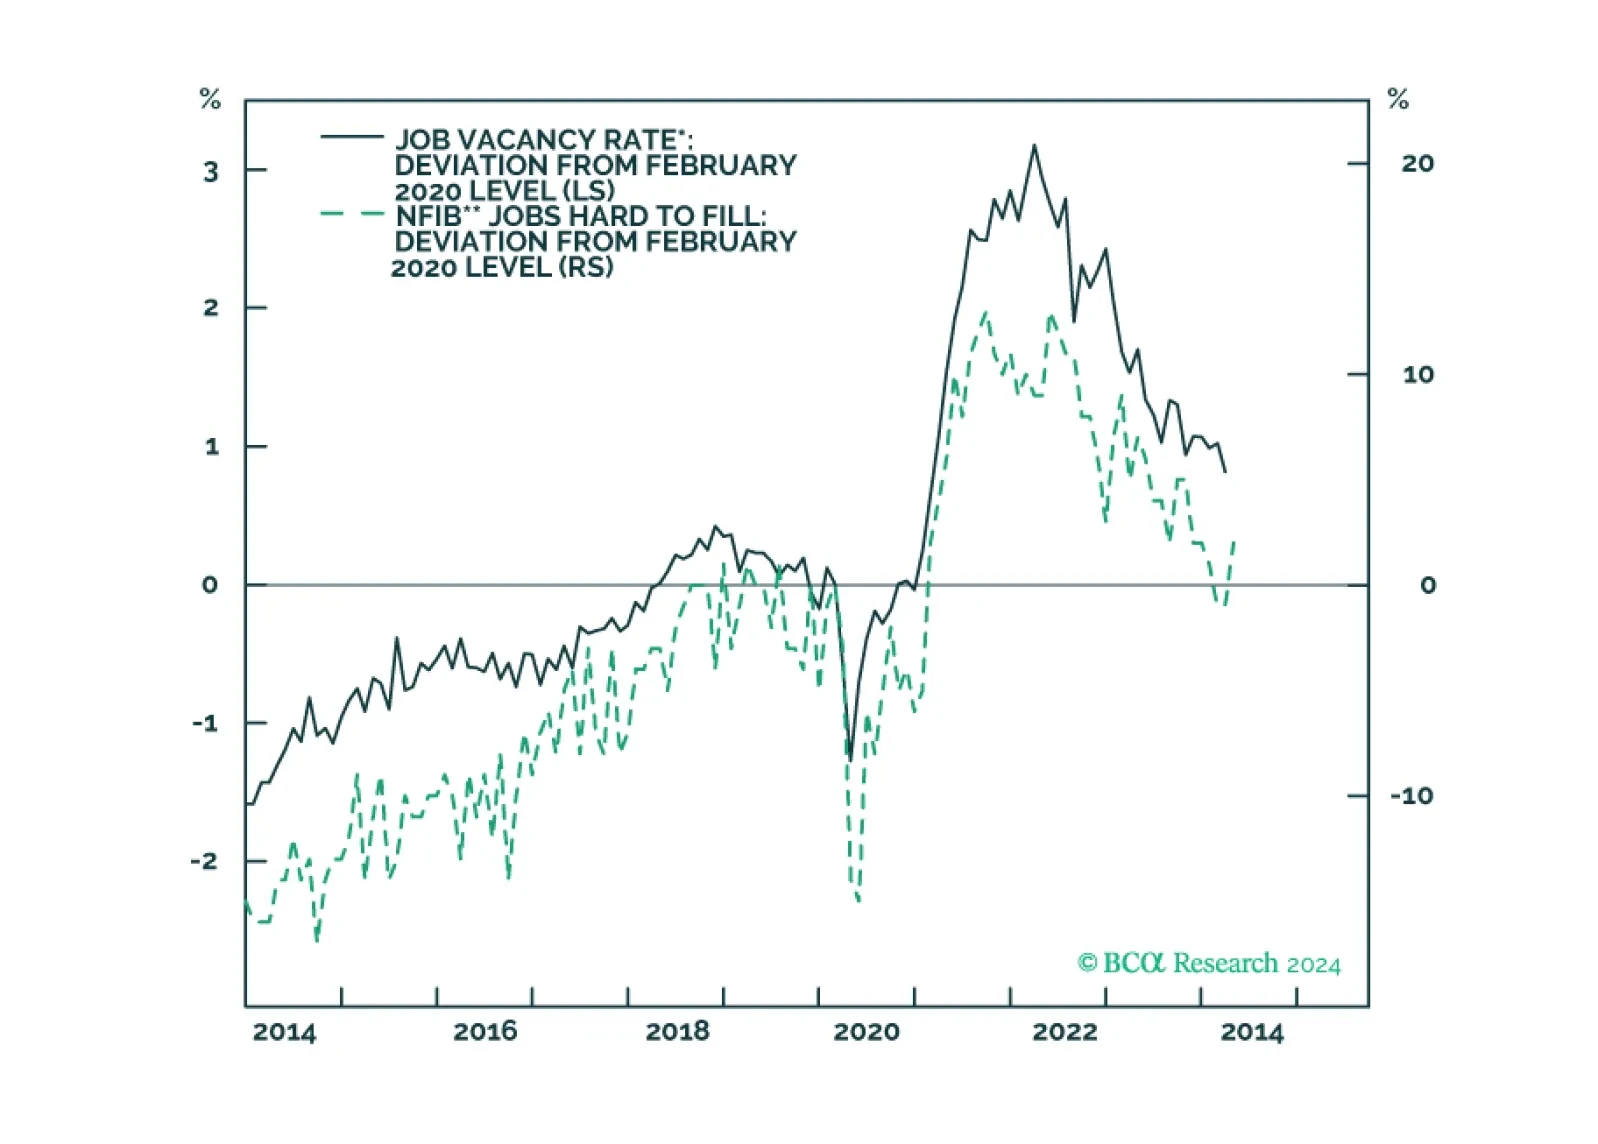
Our updated views on Treasury yields and Fed policy following this morning’s CPI report.
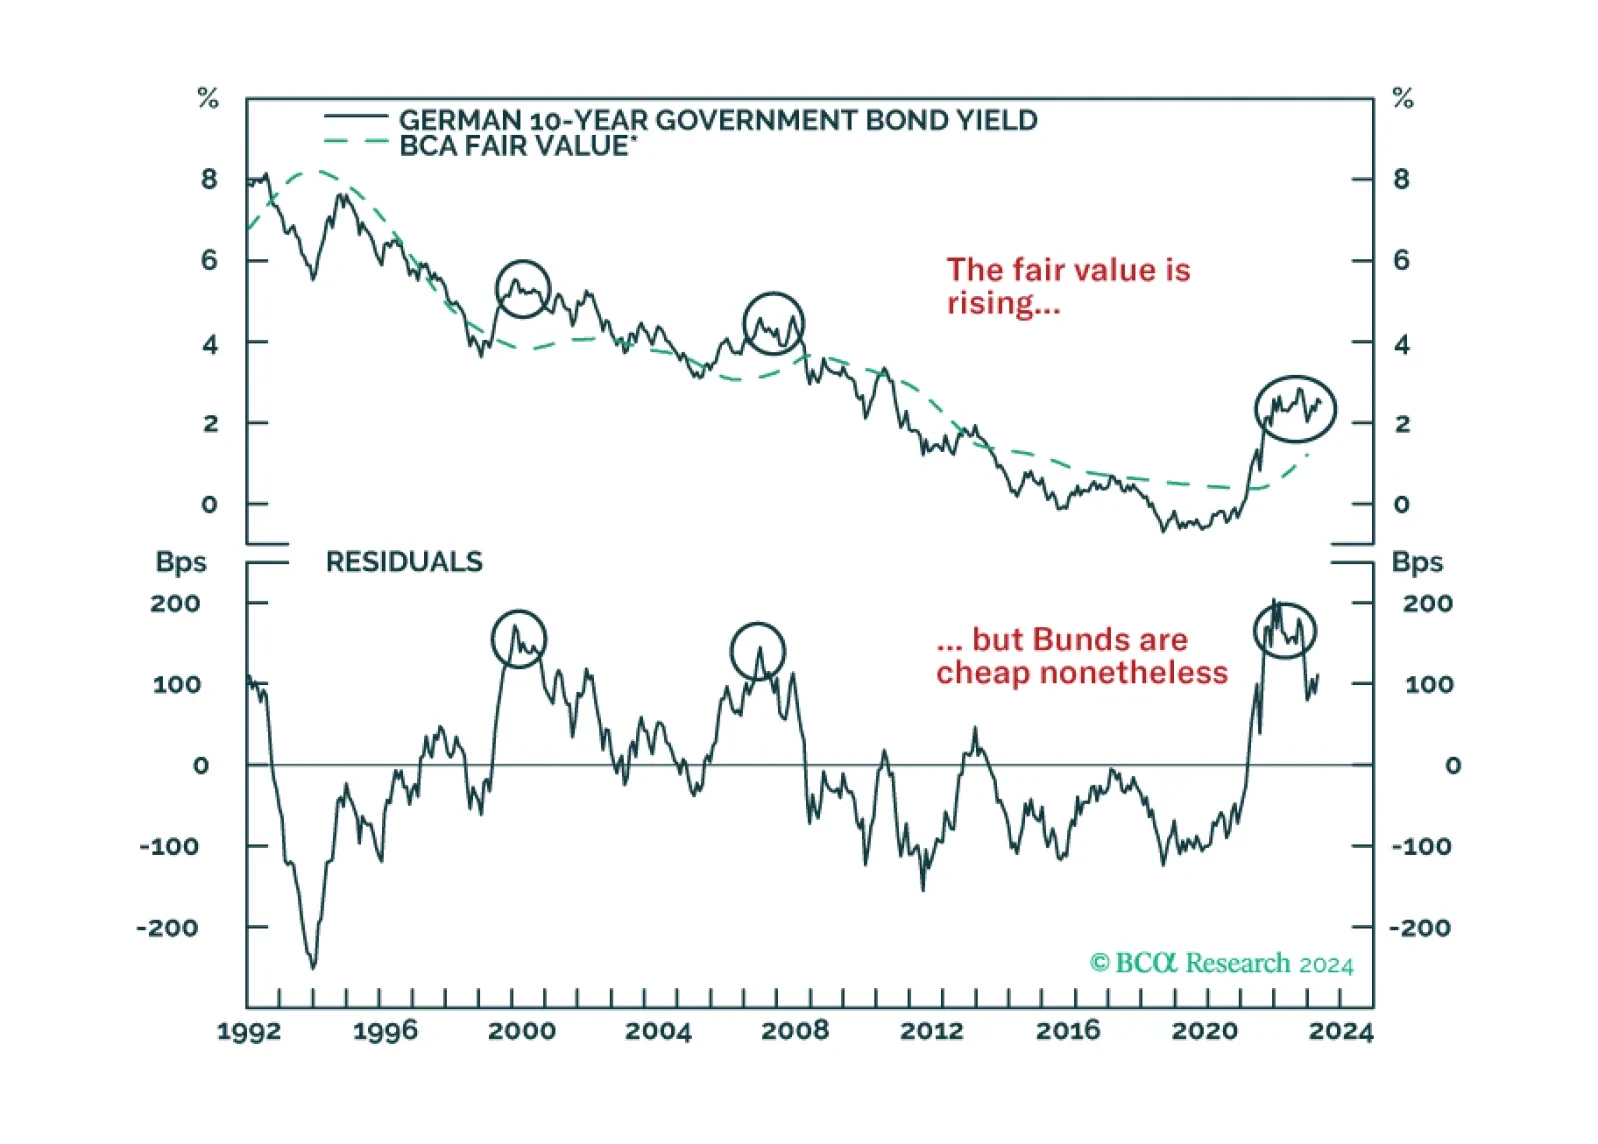
German Bunds have cheapened considerably, and the ECB is about to start cutting rates. Does this combination guarantee immediate profits from buying these bonds?
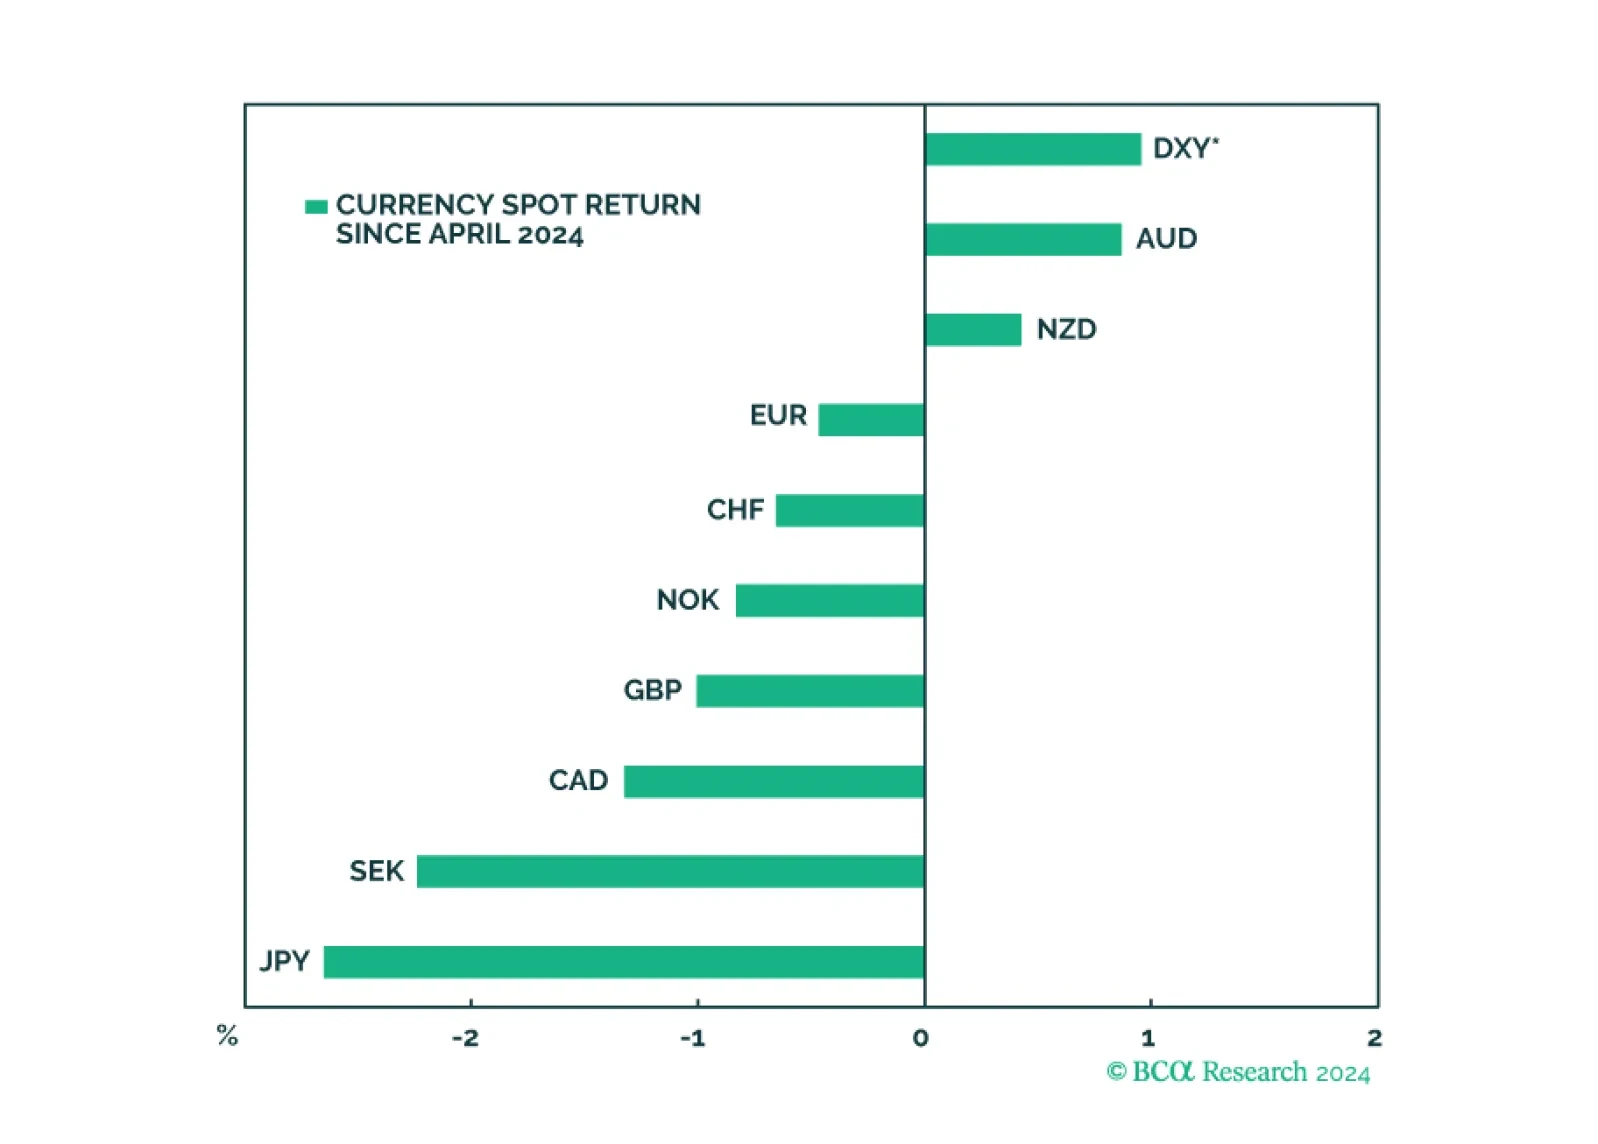
In this report, we review our trade recommendations based on incoming data in the last month.
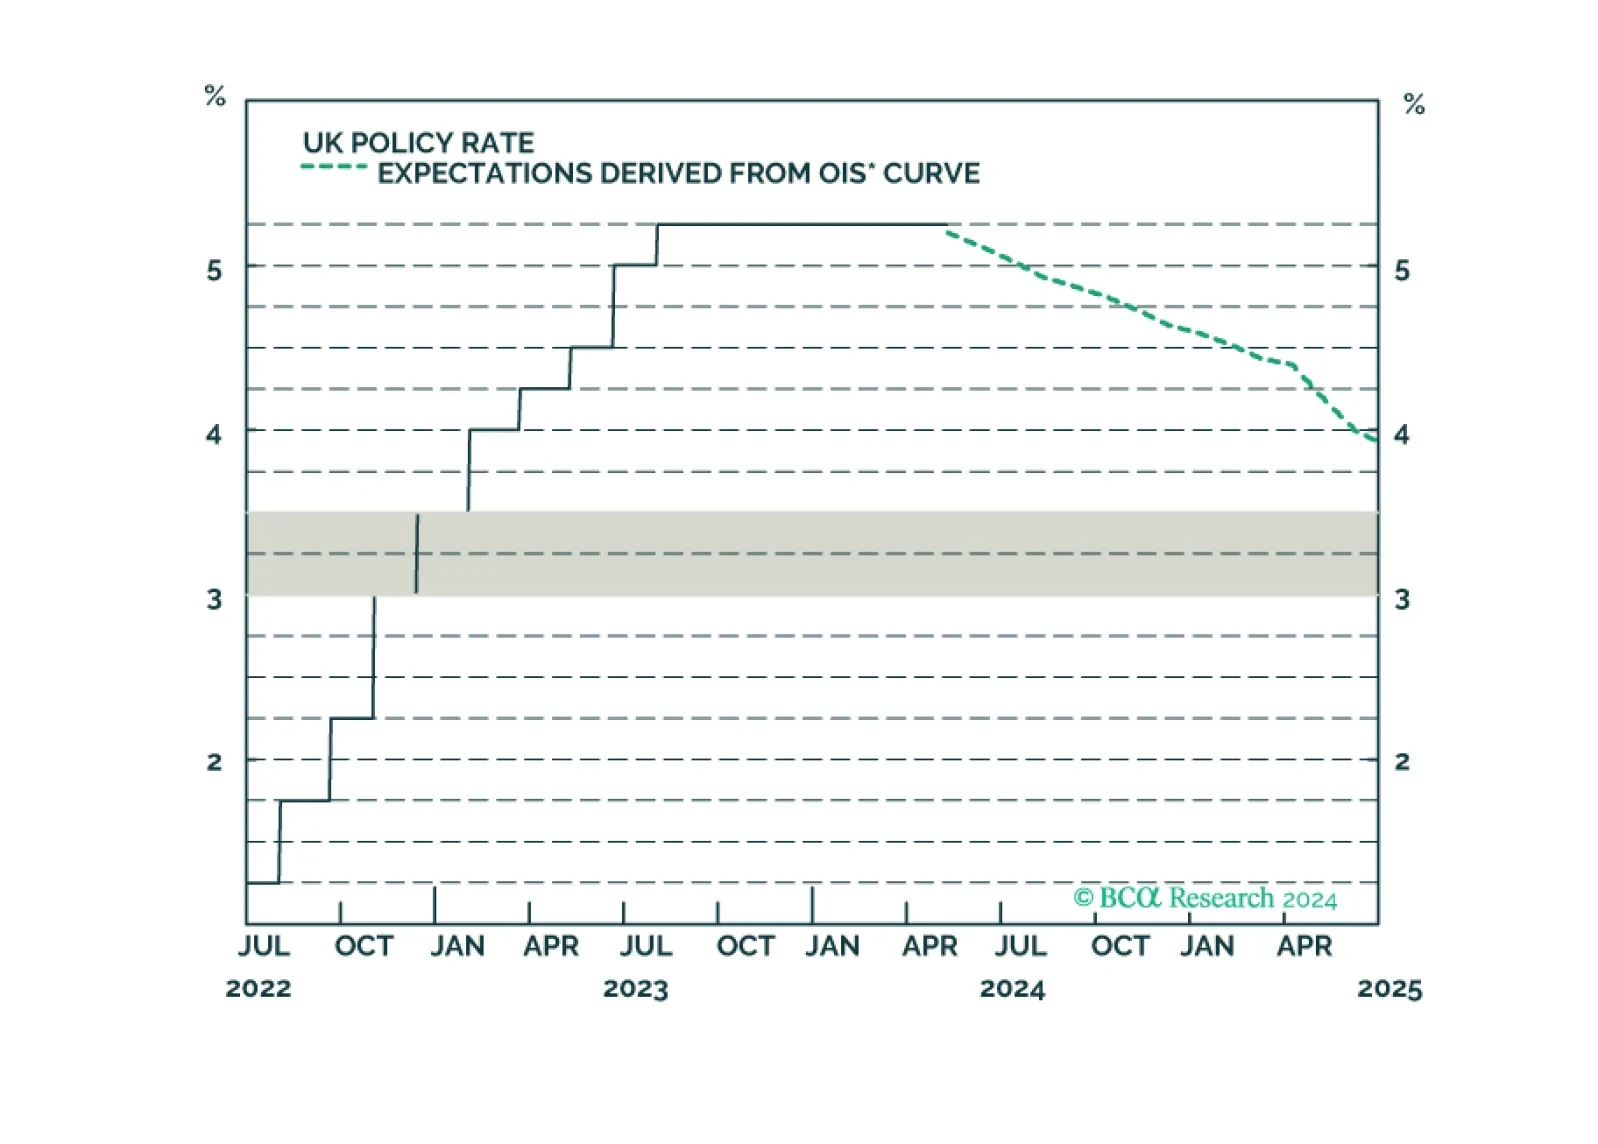
An update to our views on UK rates and currency following today’s Bank of England meeting.