Skip to main content
Some thoughts on this morning’s employment report and recent trends in US economic data.
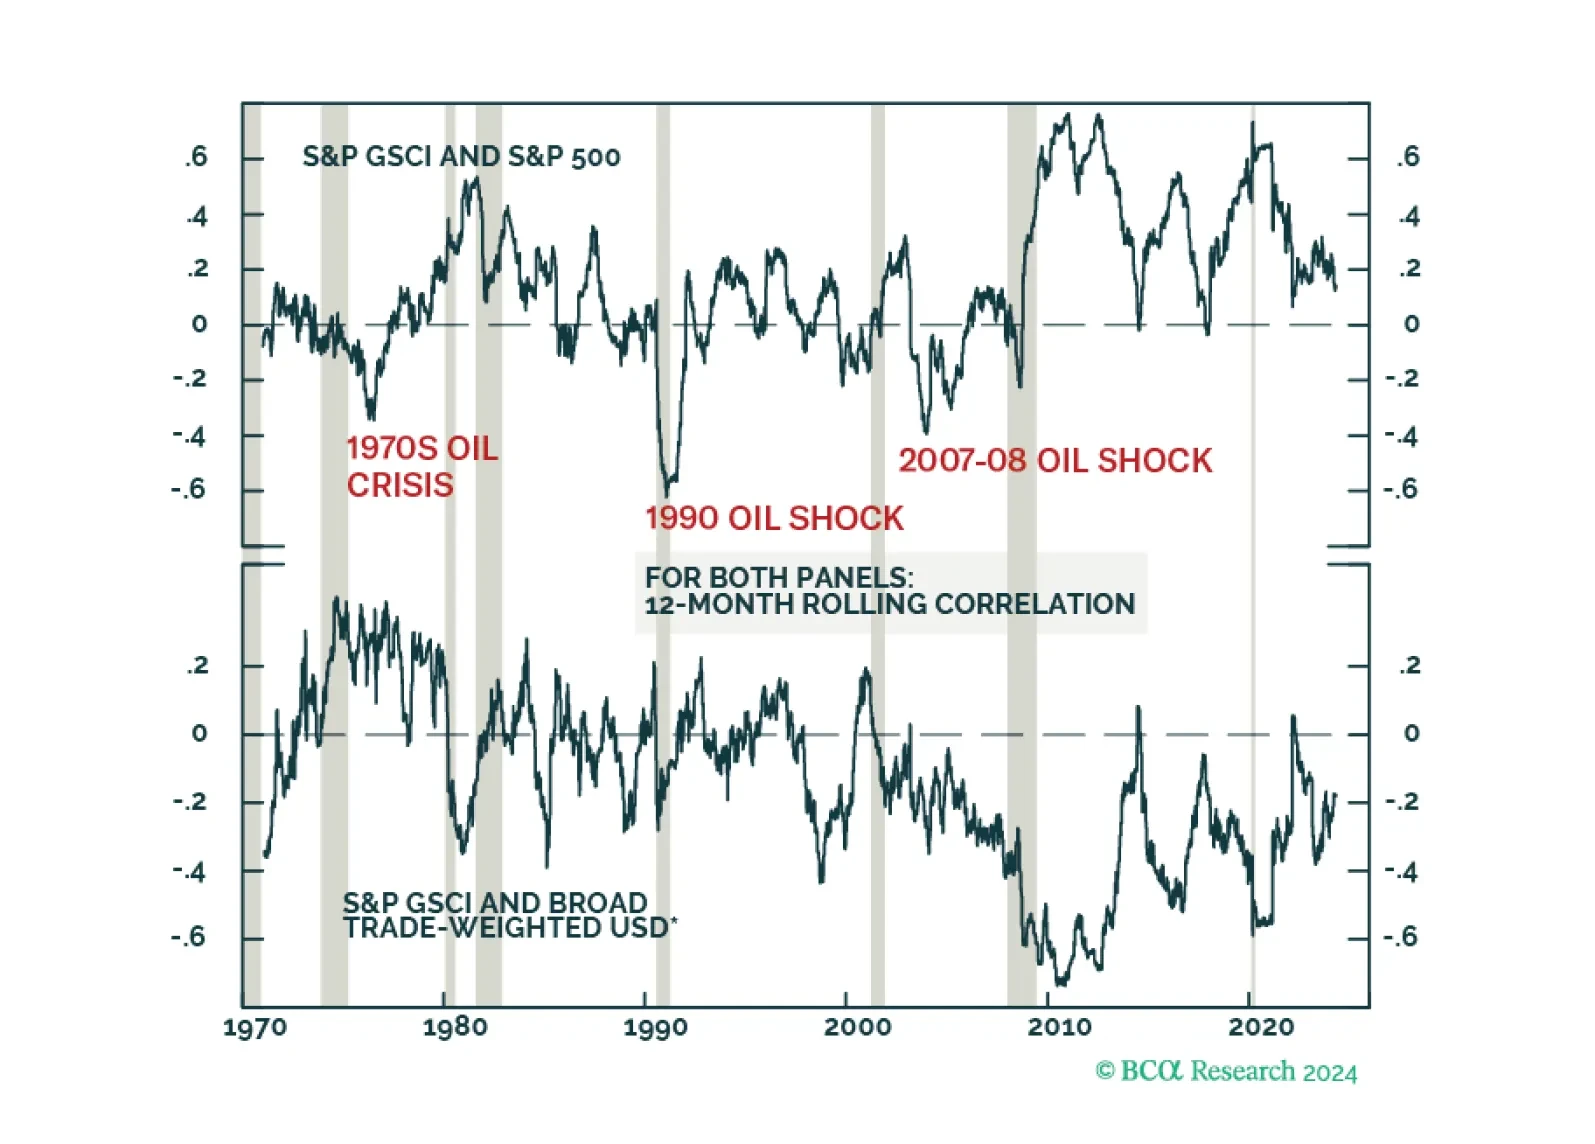
The no landing scenario has been gaining traction as the dominant driver of financial markets, providing a tailwind to commodities via increased demand for inflation hedges. Unless commodity markets experience a major supply shock, a narrative shift in favor of the hard landing scenario would create a headwind for commodities. A decisive top in the equity market would provide an early warning for commodity investors.
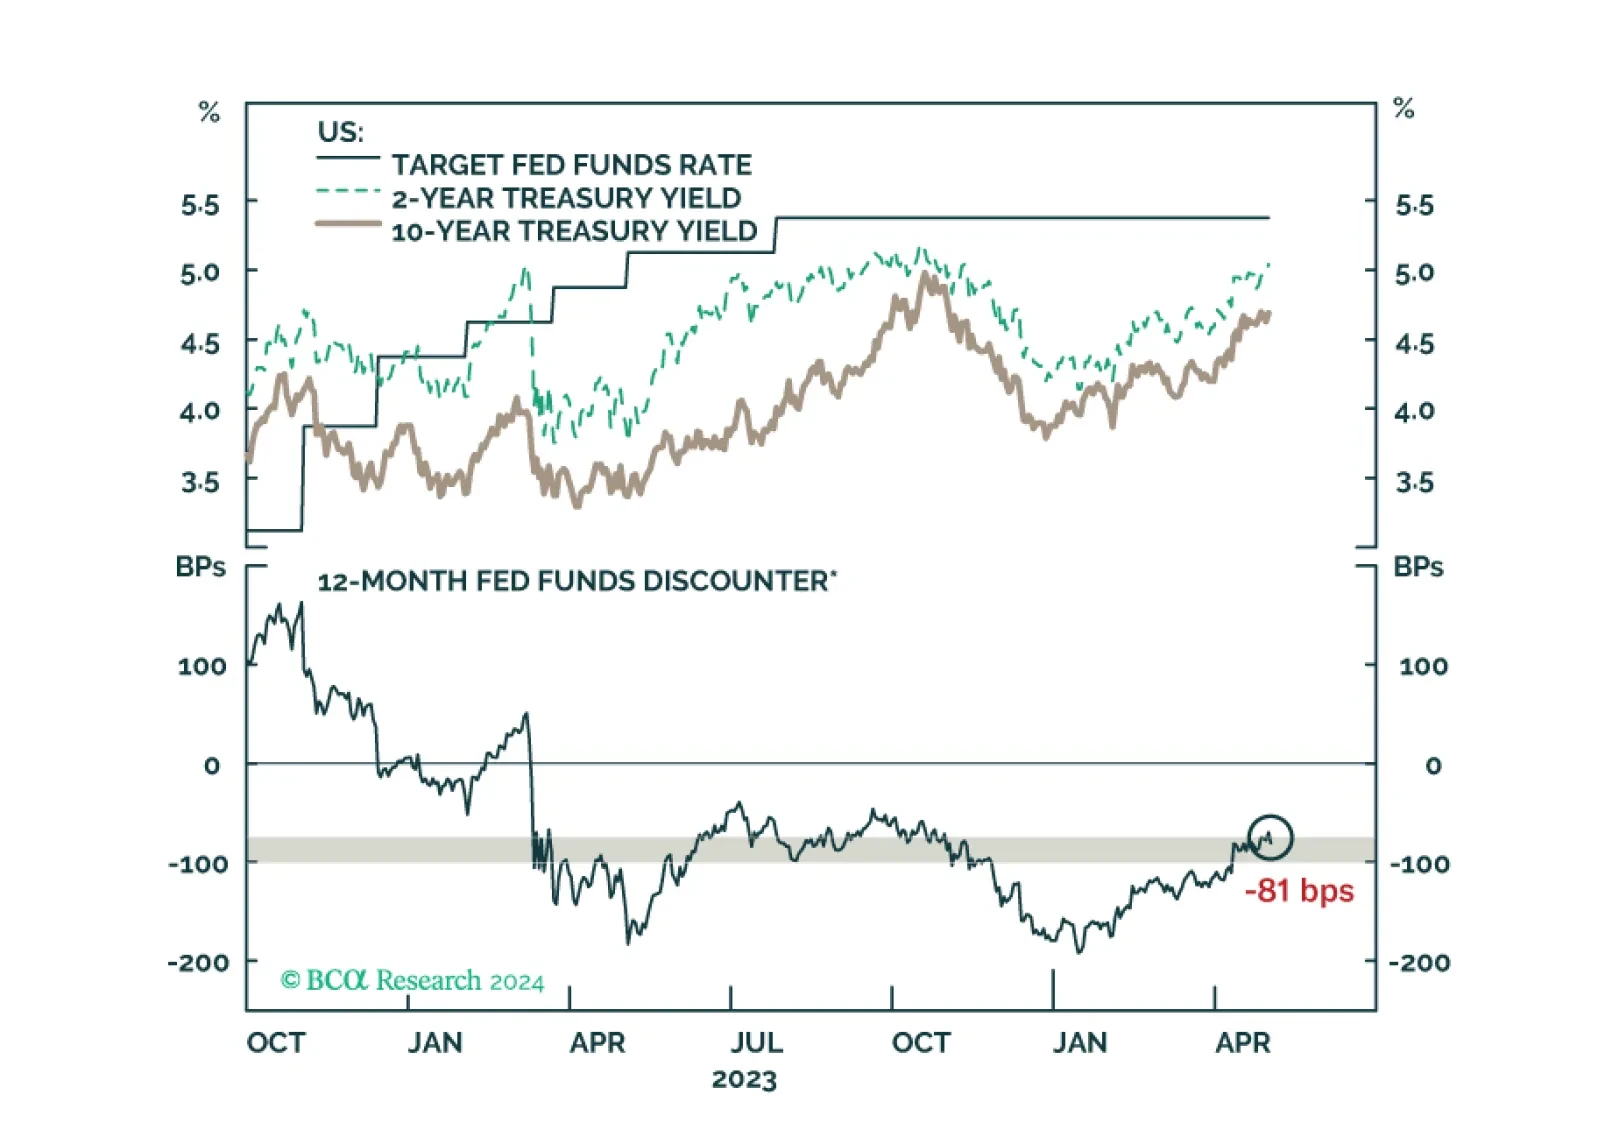
Updated views on US Treasury yields and the dollar following today’s FOMC meeting.
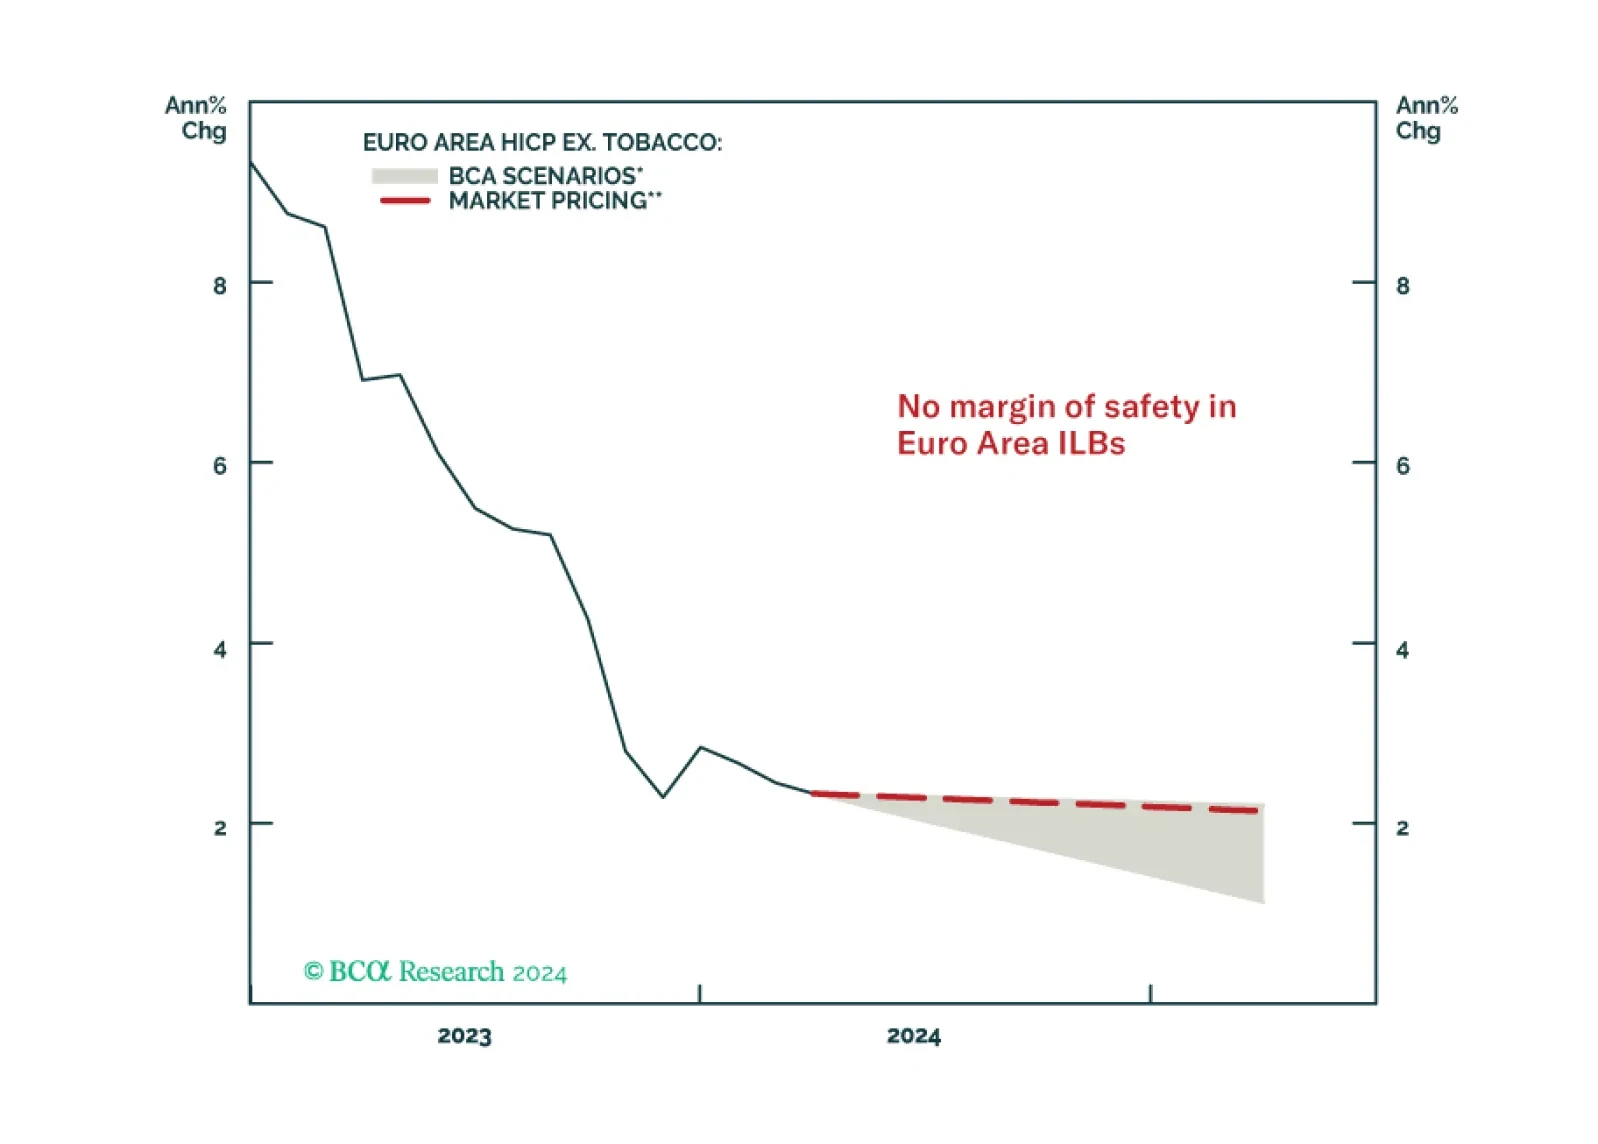
Special Report In this Special Report, we introduce our Euro Inflation-Linked Golden Rule – a framework to profitably trade and invest in Euro Area inflation-linked bonds versus nominals. The Rule is currently signaling that nominal government bonds should outperform inflation-linked bonds over the next year as disinflation in the Euro Area continues.
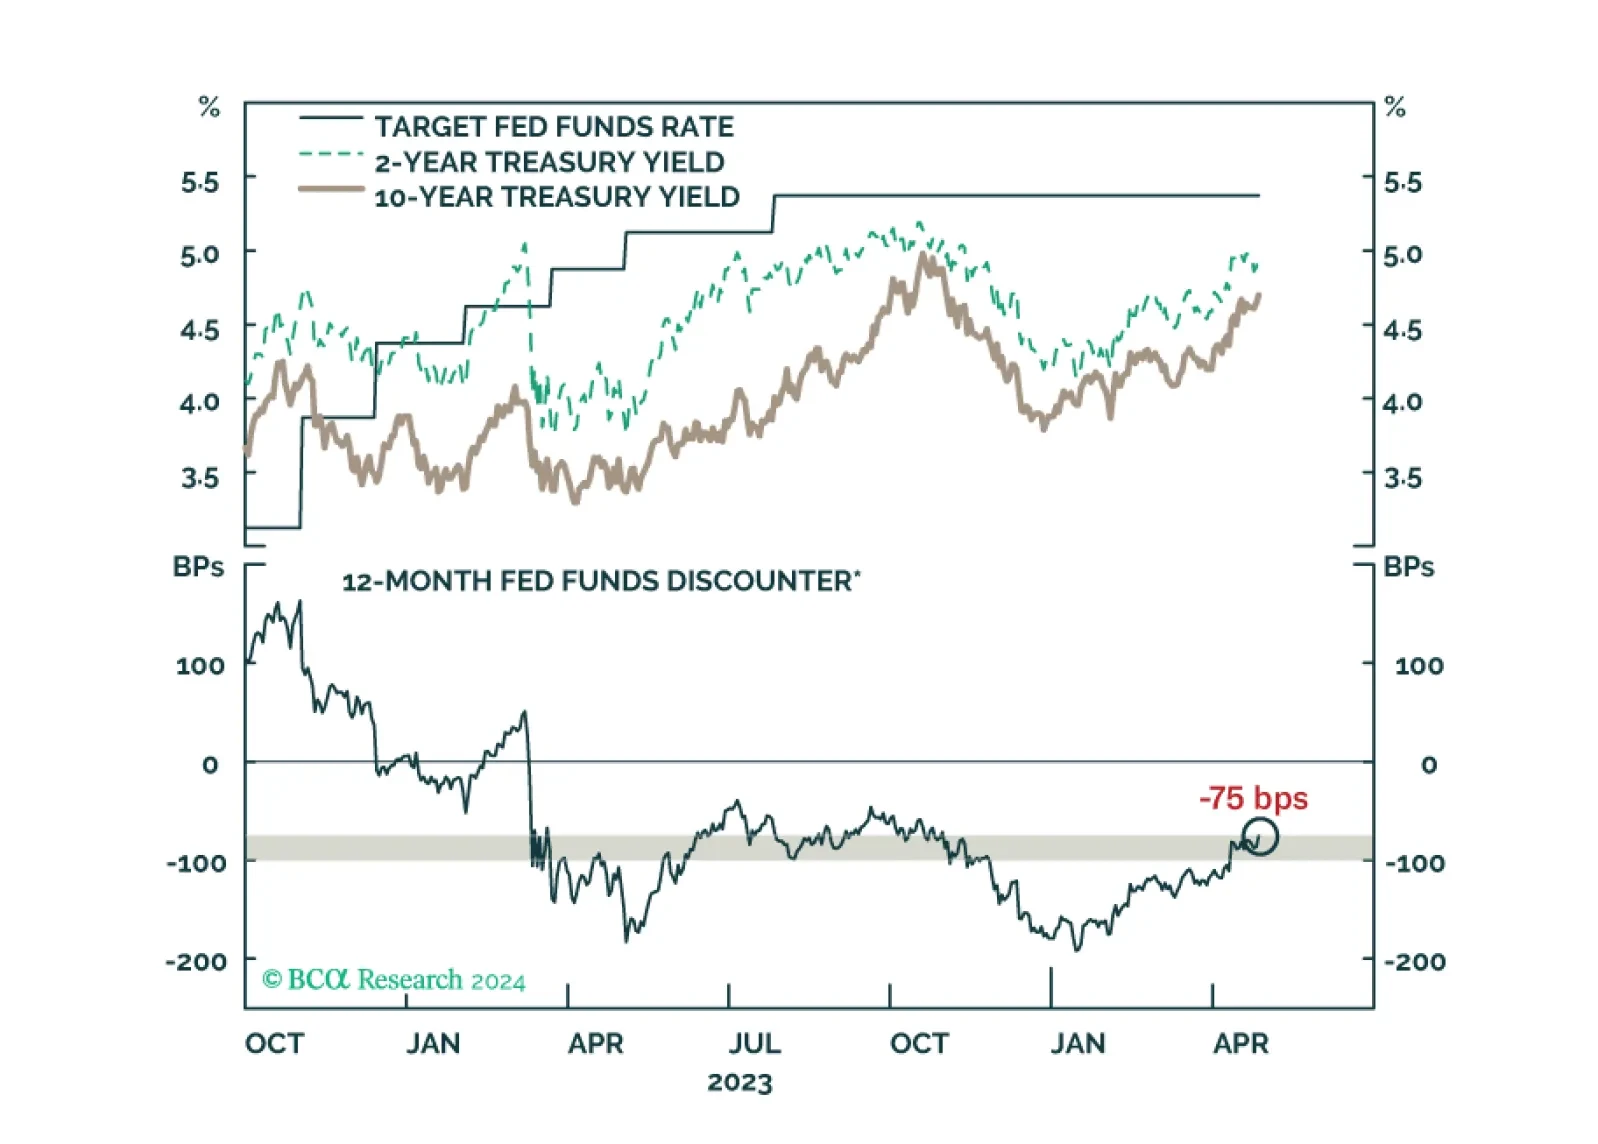
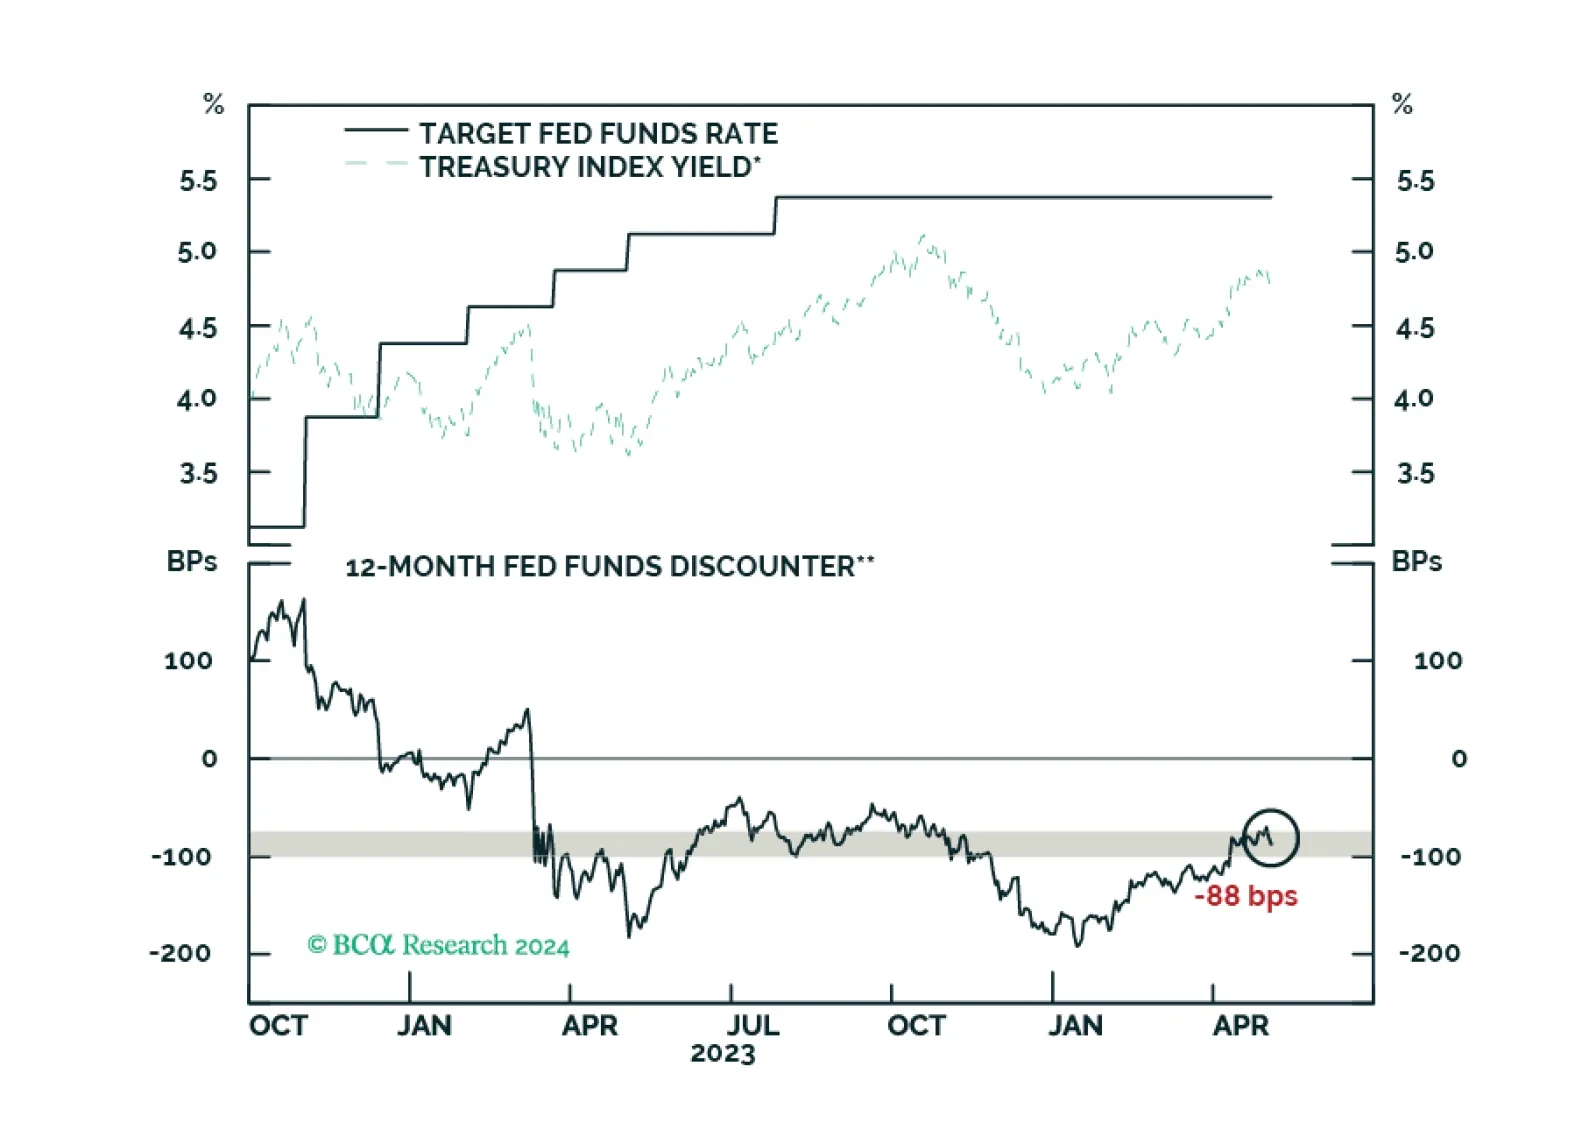
Our latest views on the recent increase in Treasury yields and some key things to watch at next week’s FOMC meeting.
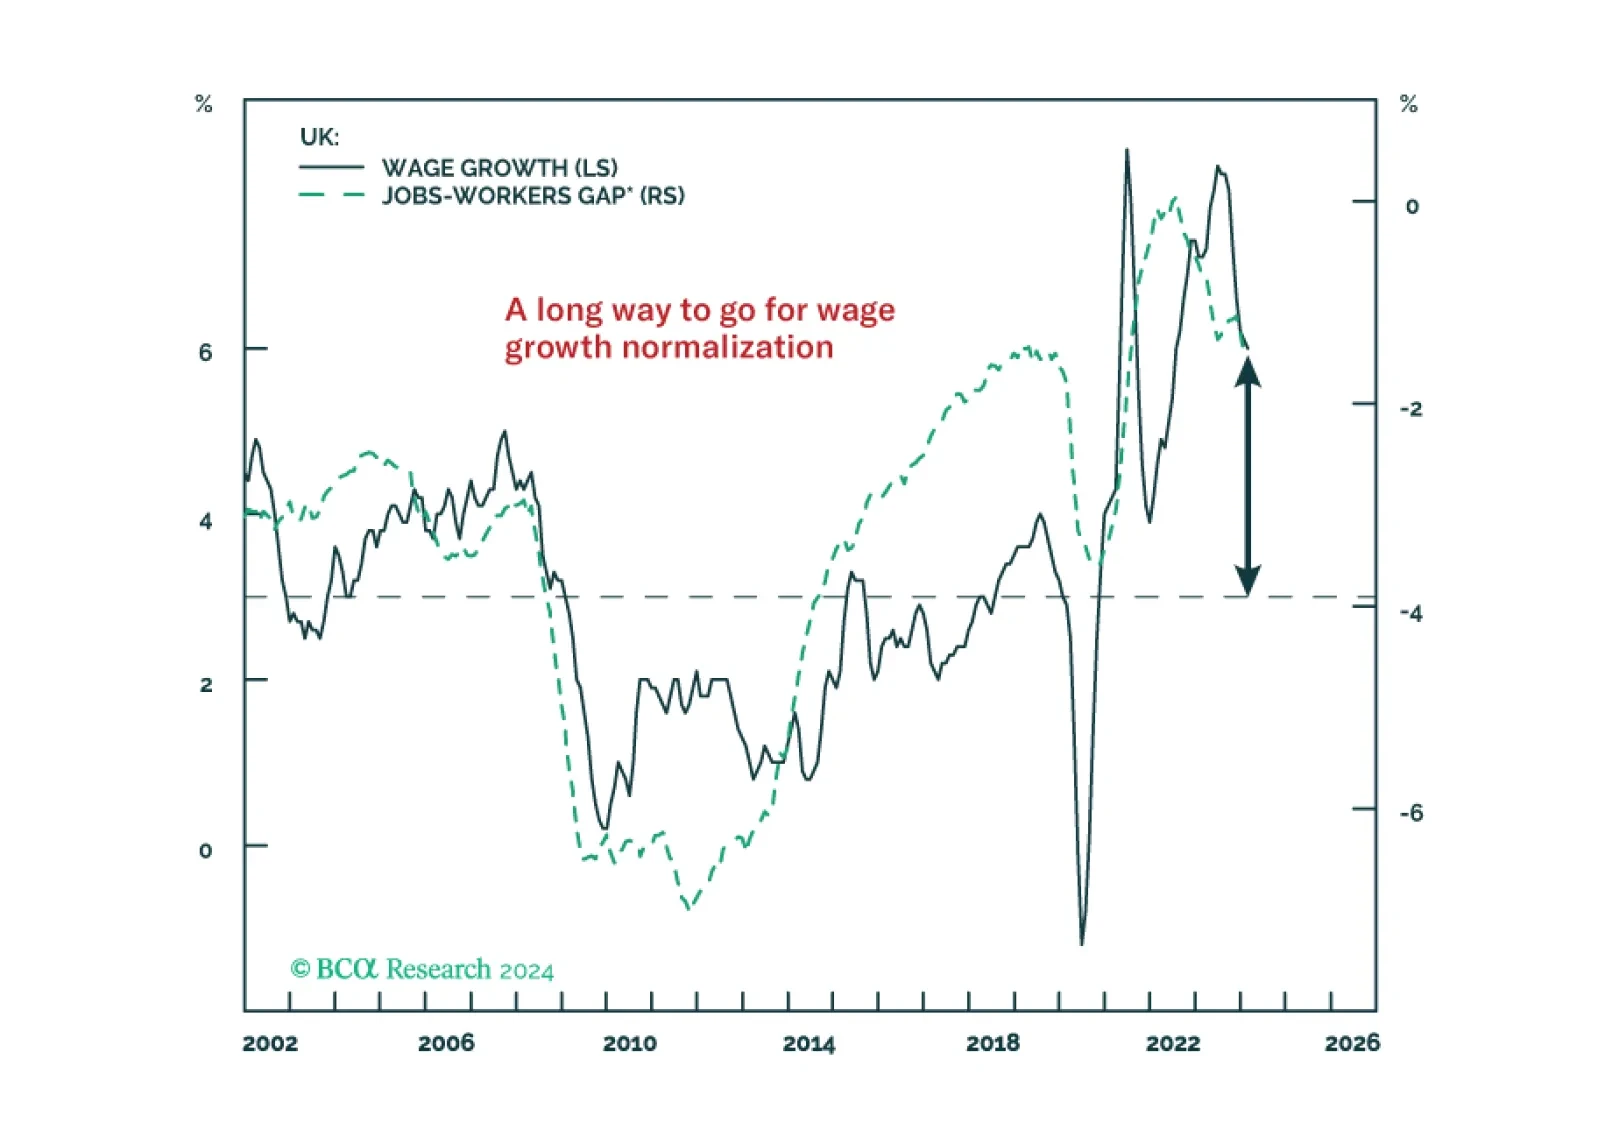
Special Report The UK labor market remains far too tight to expect wage growth to slow to levels consistent with the Bank of England inflation target. A true recession with rising unemployment is needed to finally slay the UK inflation beast. 2024 rate cuts are off the table, with the central bank having to keep monetary policy tighter for longer than markets expect and the UK economy now rebounding. We recommend downgrading UK gilts to underweight in global bond portfolios, while also looking for opportunities to buy the British pound on pullbacks versus the euro, Canadian dollar and Swedish krona.
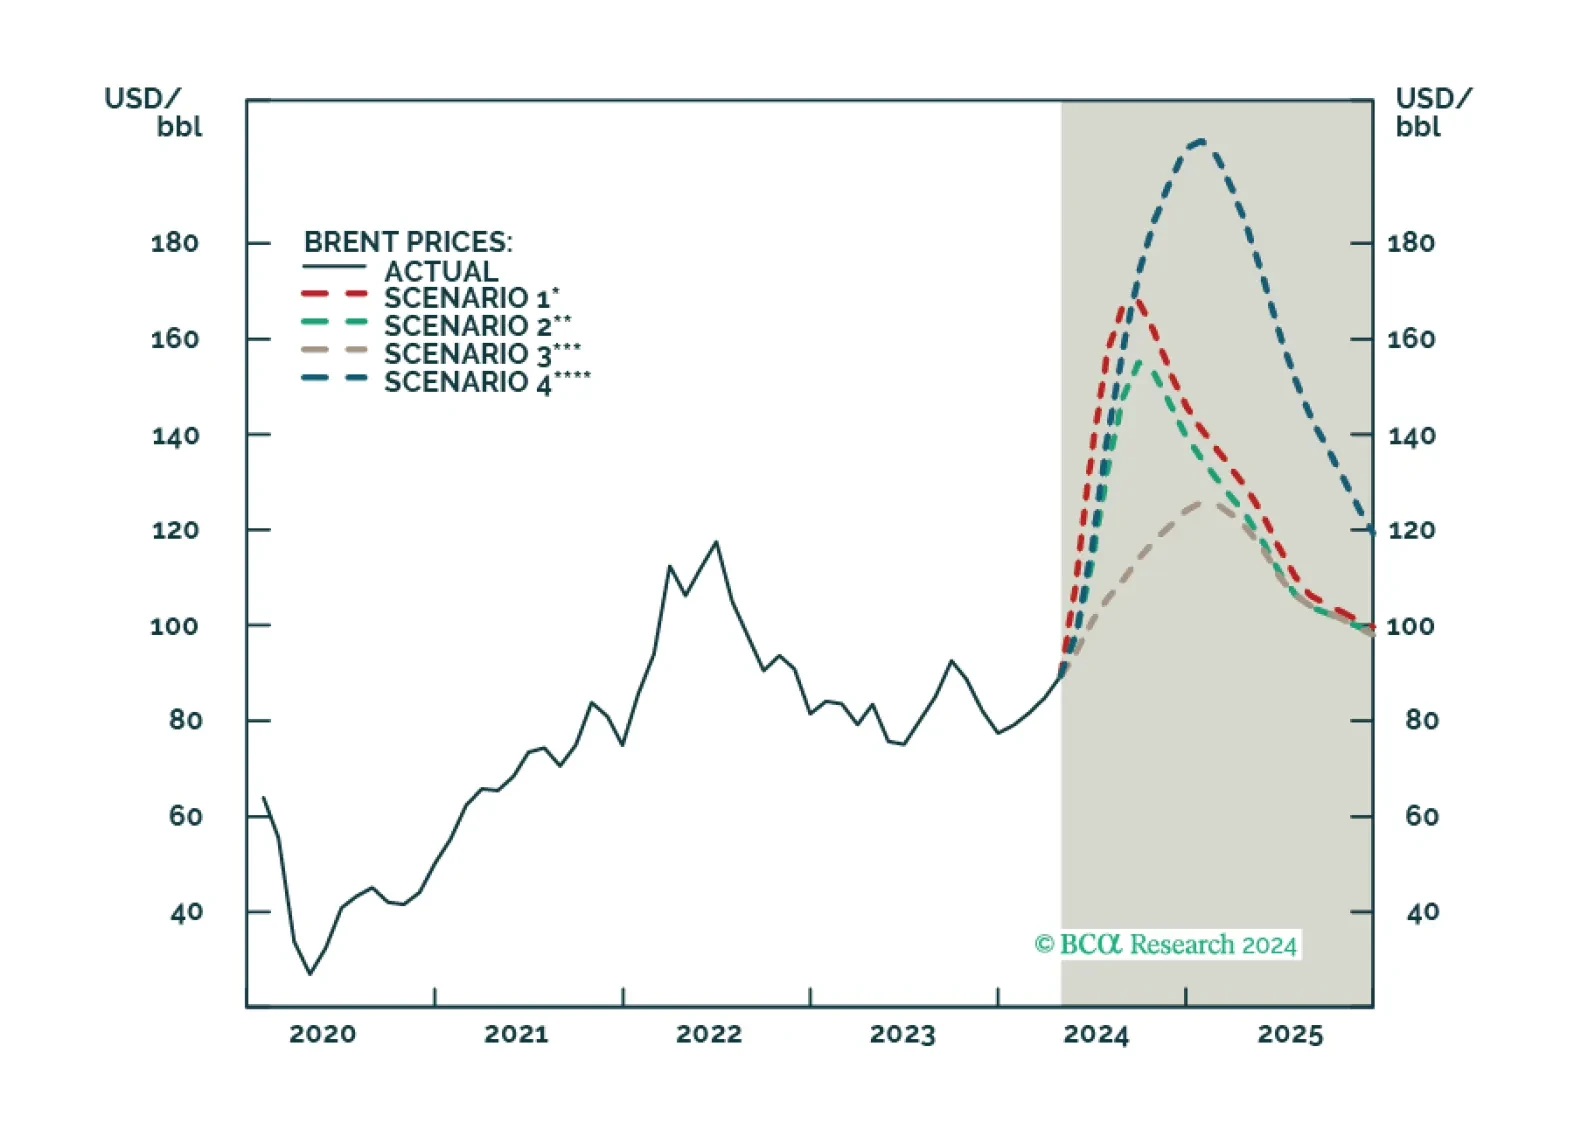
Special Report Investors should not underrate the chance of an oil shock ahead of the US election as Israel needs to push back against Iranian proxies, and Iran needs to demonstrate its regional reach to put a wedge between Israel and the US. We remain strategically long energy commodities and equities, and defense stocks via the COMT, XOP and PPA ETFs, which will continue to outperform cyclicals.
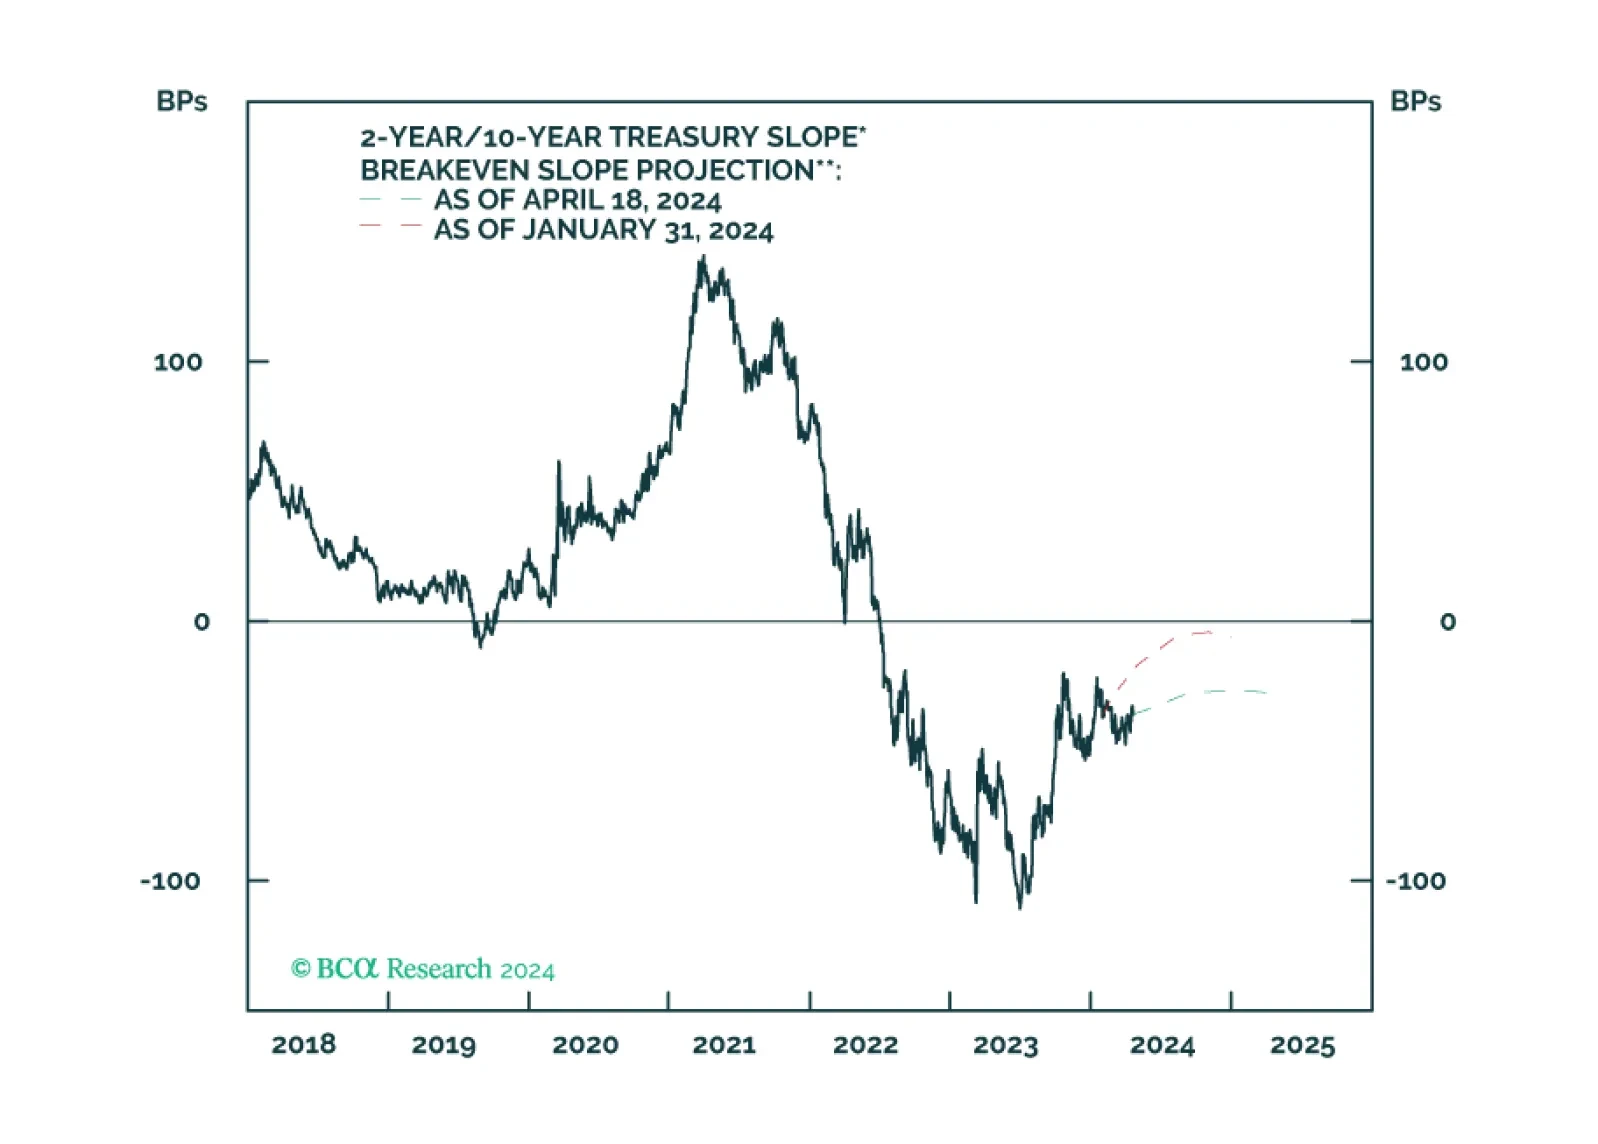
Special Report This Special Report introduces a framework for assessing the relative importance of slope change and initial yield in curve trade performance. The yield penalty for curve steepeners has fallen significantly since the beginning of the year, and we recommend shifting out of Treasury curve flatteners and into Treasury curve steepeners in US bond portfolios.
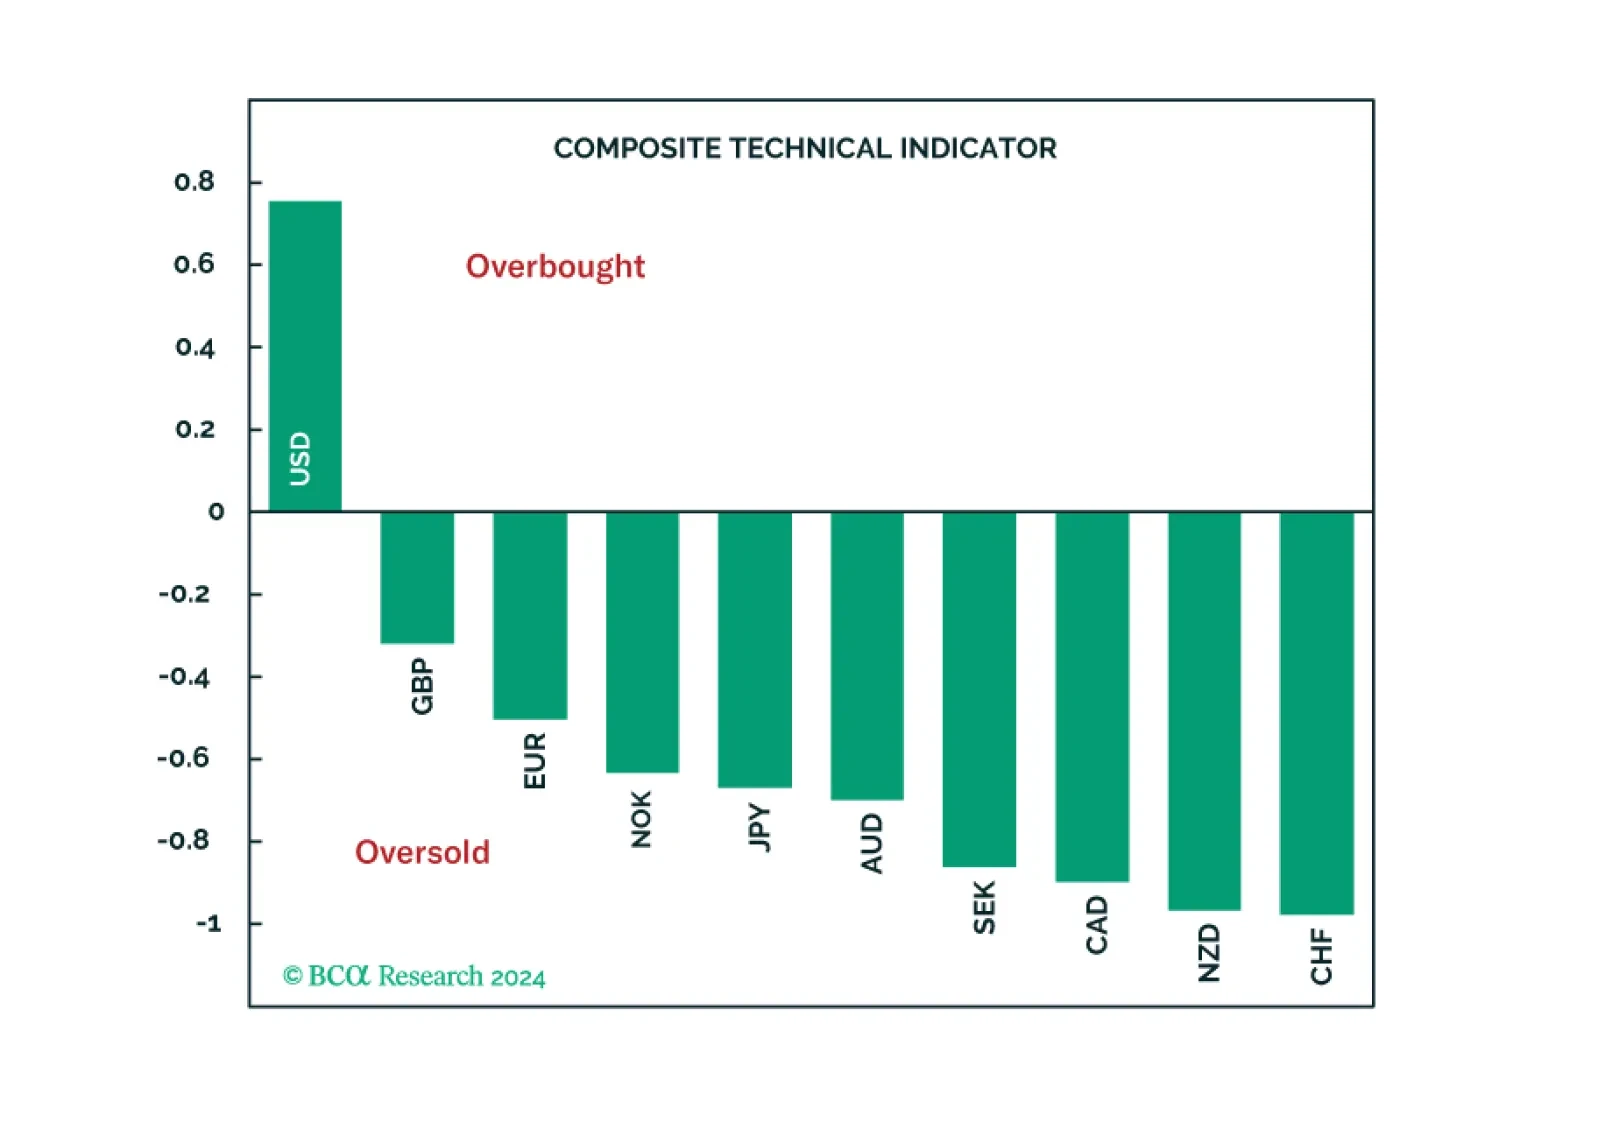
In this report, we review what our technical indicators are telling us about the G10 currencies.
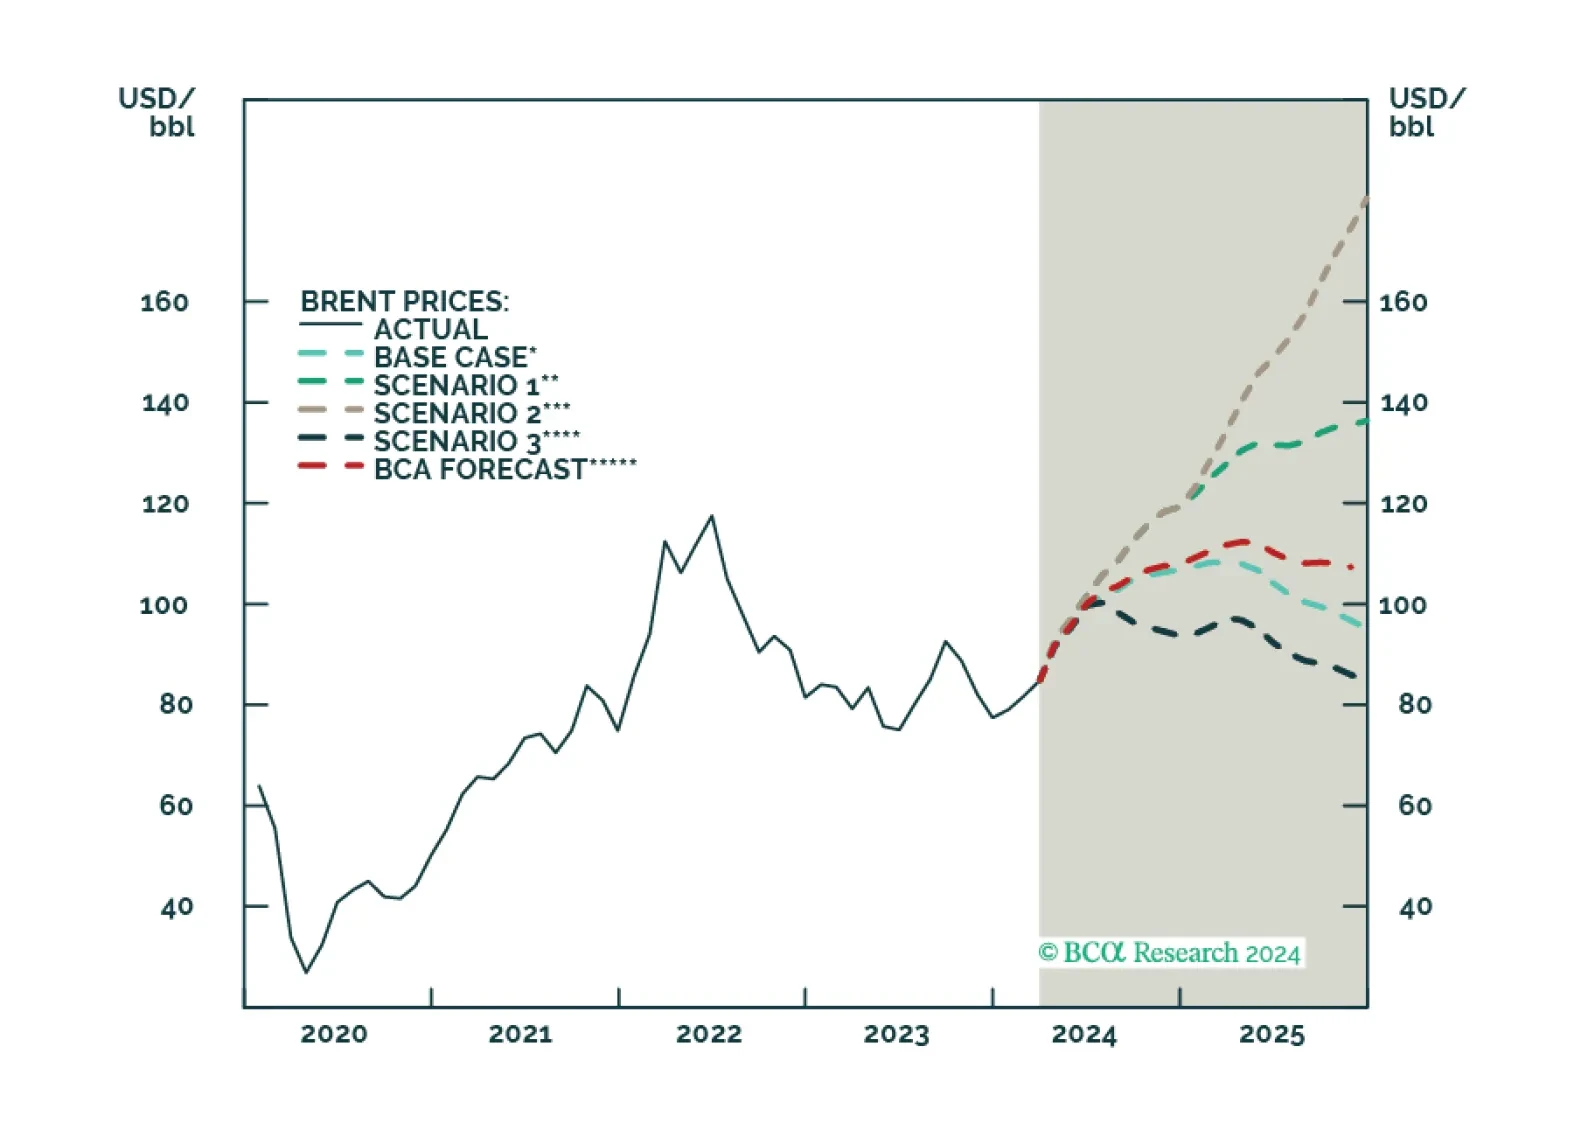
Strong growth in the US and large EMs ex-China will translate into higher oil demand in 2024 – 2025. With mostly unchanged oil supply, tighter markets will ensue. We’ve raised our 2024 average Brent forecast to $98/bbl, and expect $105/bbl in 2H24. In 2025, we expect Brent to average $110/bbl. Prices could easily move higher, if the US moves against one or all of the states enjoying US sanctions forbearance – Russia, Iran, Venezuela. If Brent trades through $110/bbl, Saudi Arabia and the UAE will release spare capacity.