 FICC
Find out more
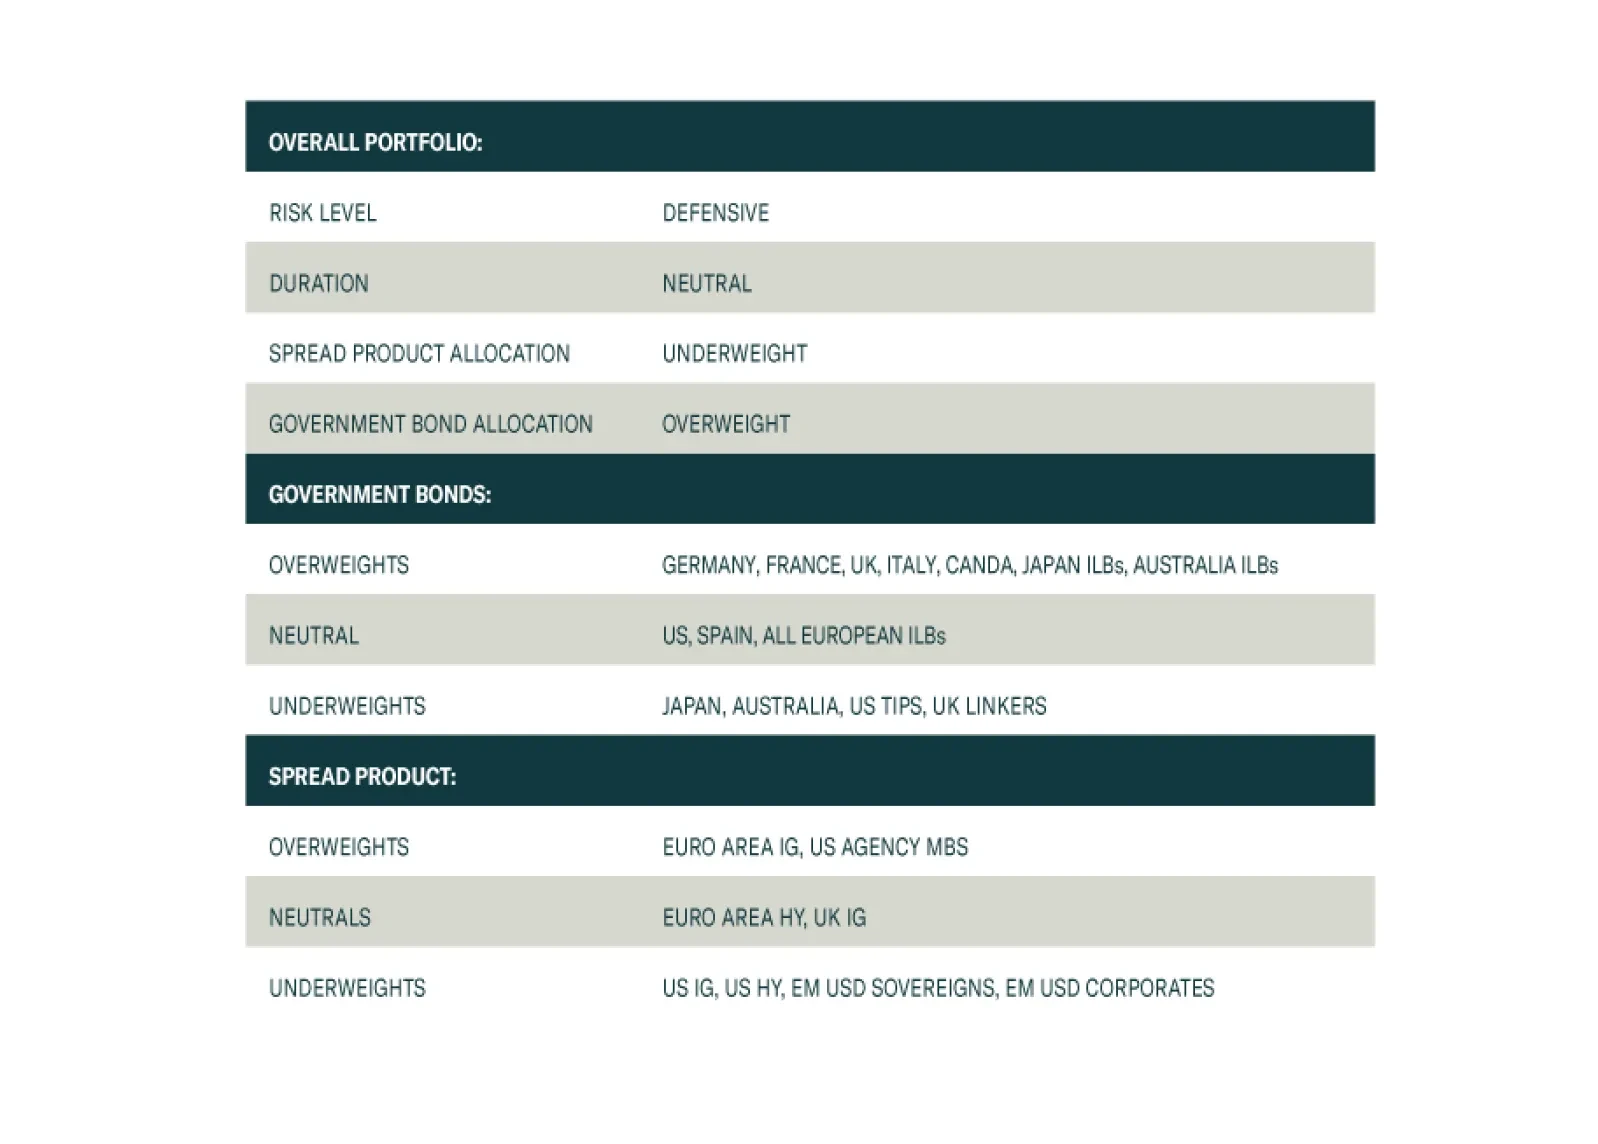
In this report, we present our quarterly review of our Model Bond Portfolio. The anti-growth bias of the portfolio allocations hurt the portfolio performance in Q1/2024 as global growth surprised to the upside. However, we anticipate some recovery of the underperformance in our base case scenario for the next six months.
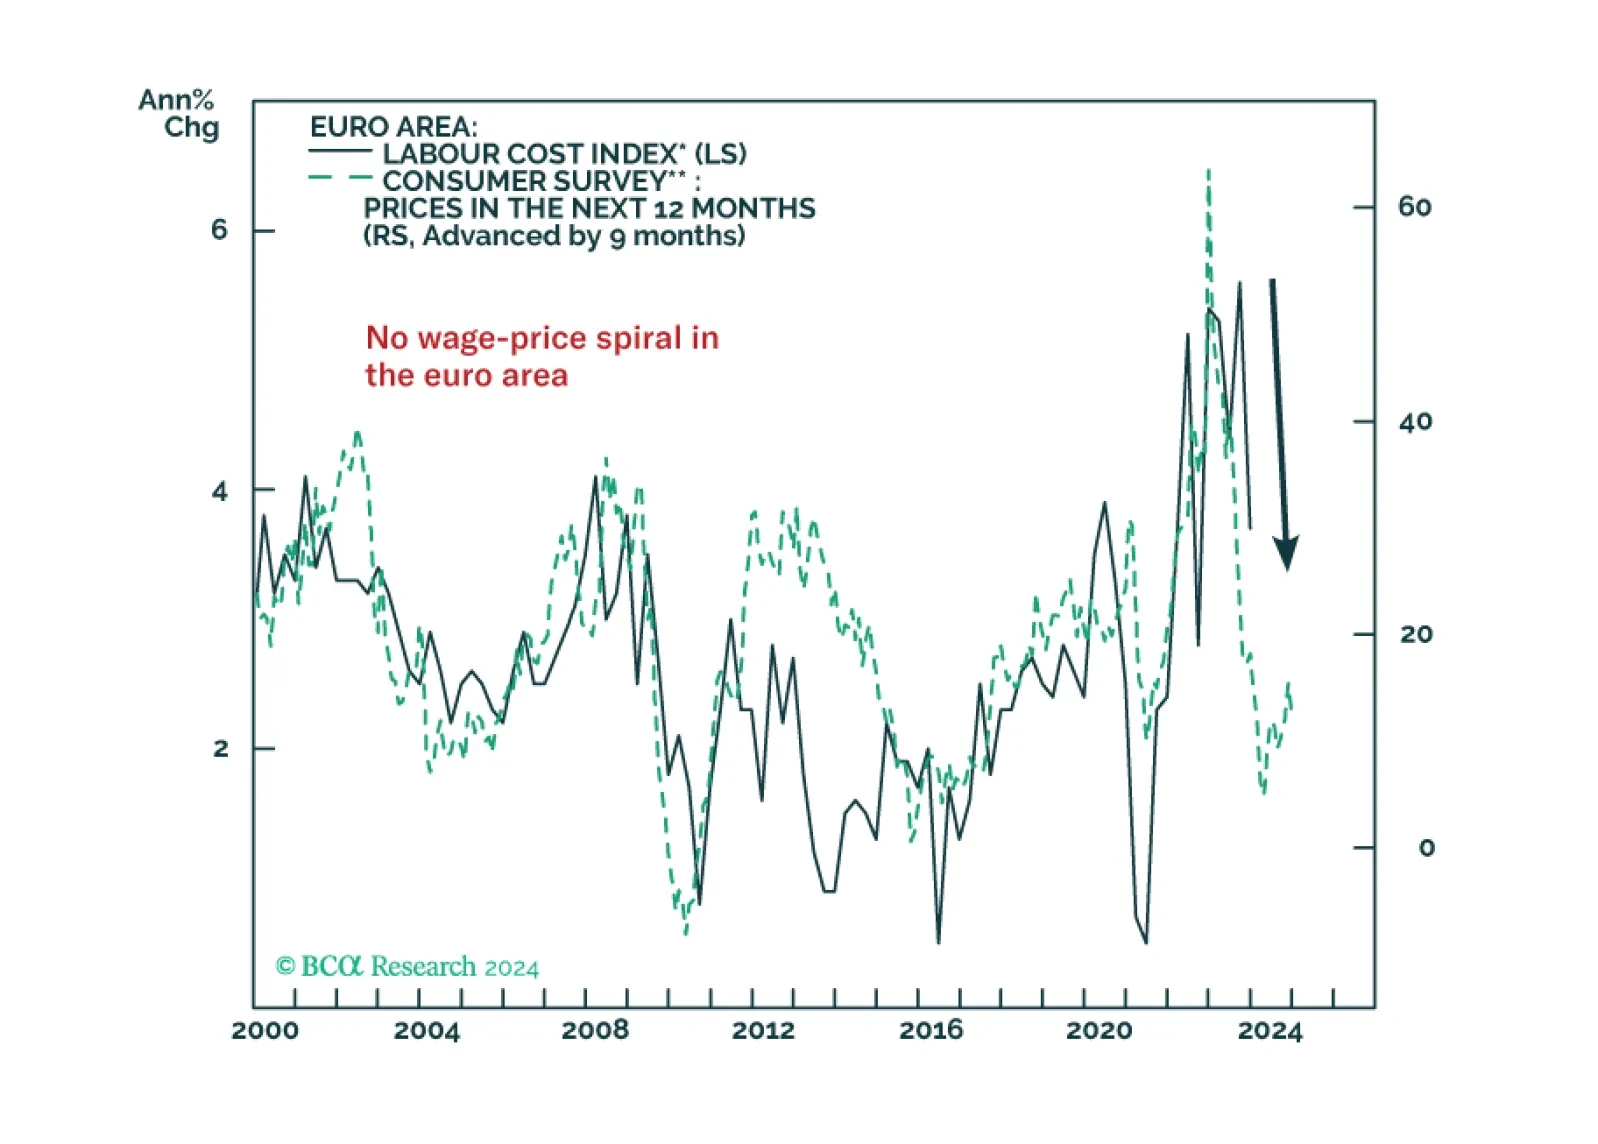
At today’s monetary policy meeting, the ECB gave strong hints that rate cuts will begin as soon as the next meeting in June. In this Insight, we share our thoughts on today’s meeting and discuss the implications for European bond yields and the euro.
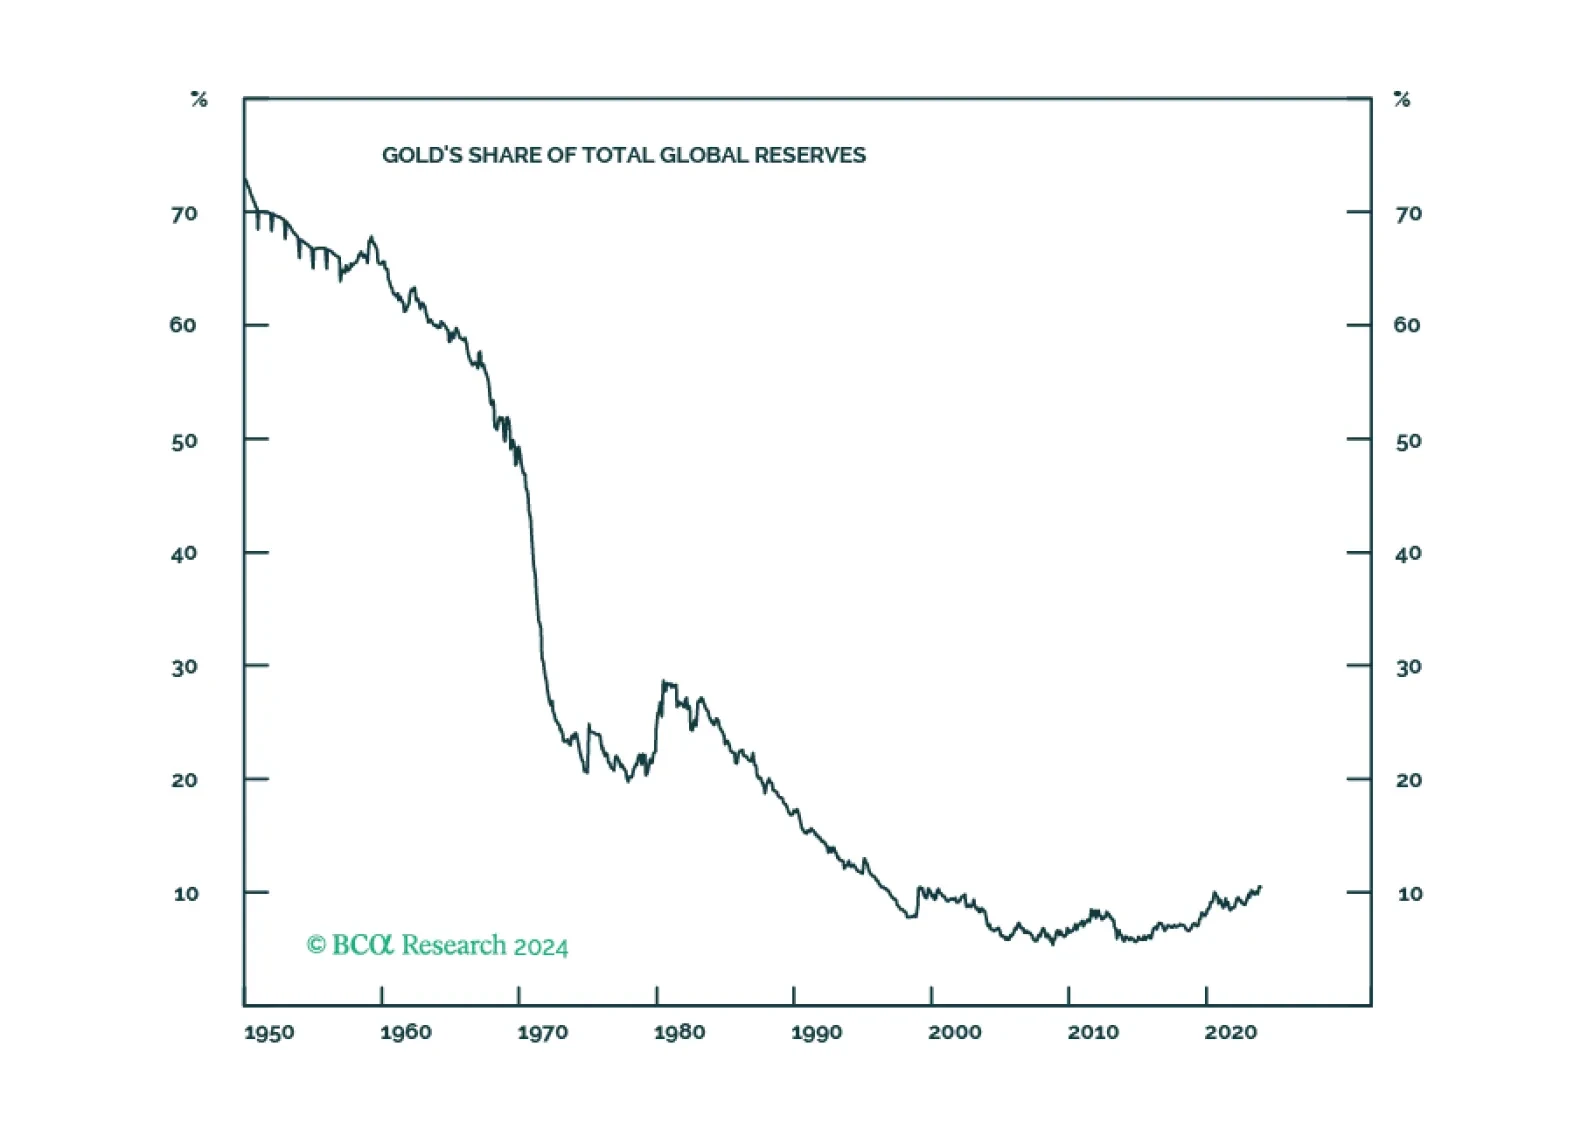
Our bullish gold, copper and oil calls have played out as expected, with gains of 14%, 11% and 16% since the beginning of the year. In this risk assessment of our views, we conclude the bull trends driving these markets higher remain intact. However, the risks of central-bank policy errors, resource nationalism and protectionism are rising. We are raising our gold and copper price targets to $2,500/oz (from $2,300/oz) and $5.00/lb (from $4.50/lb).
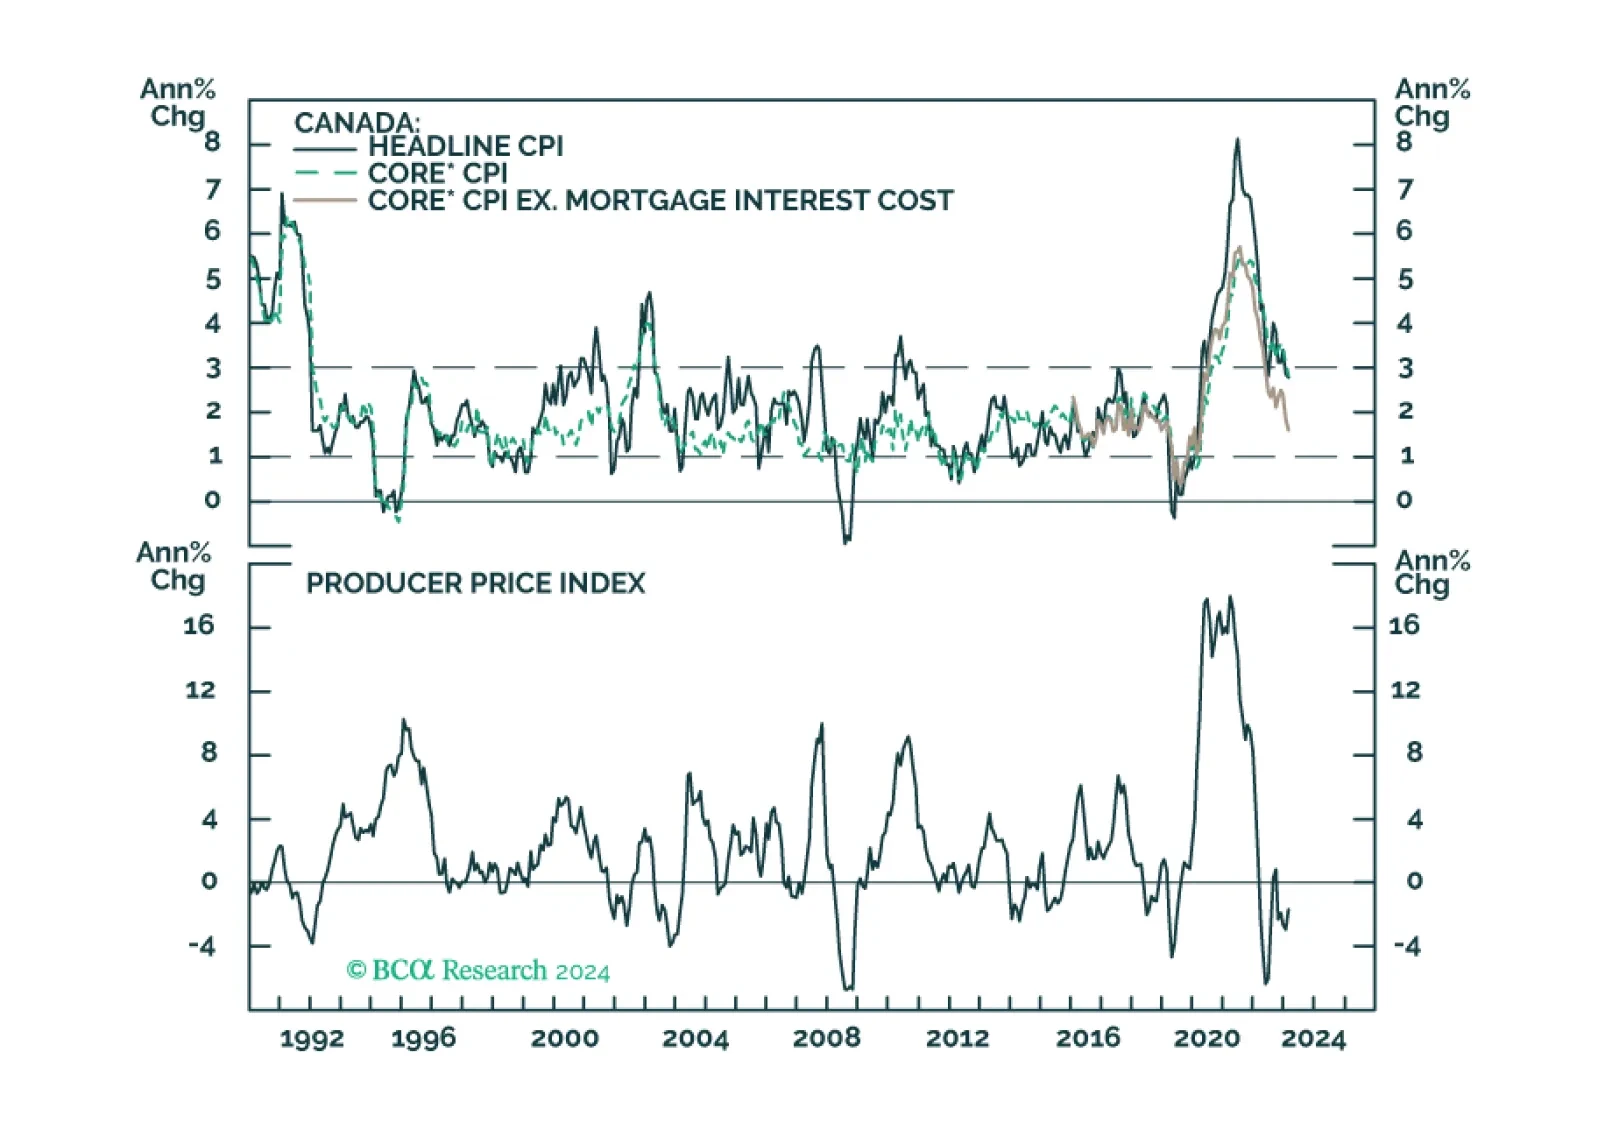
In this insight, we calibrate our investment views based on the latest Bank of Canada decision.
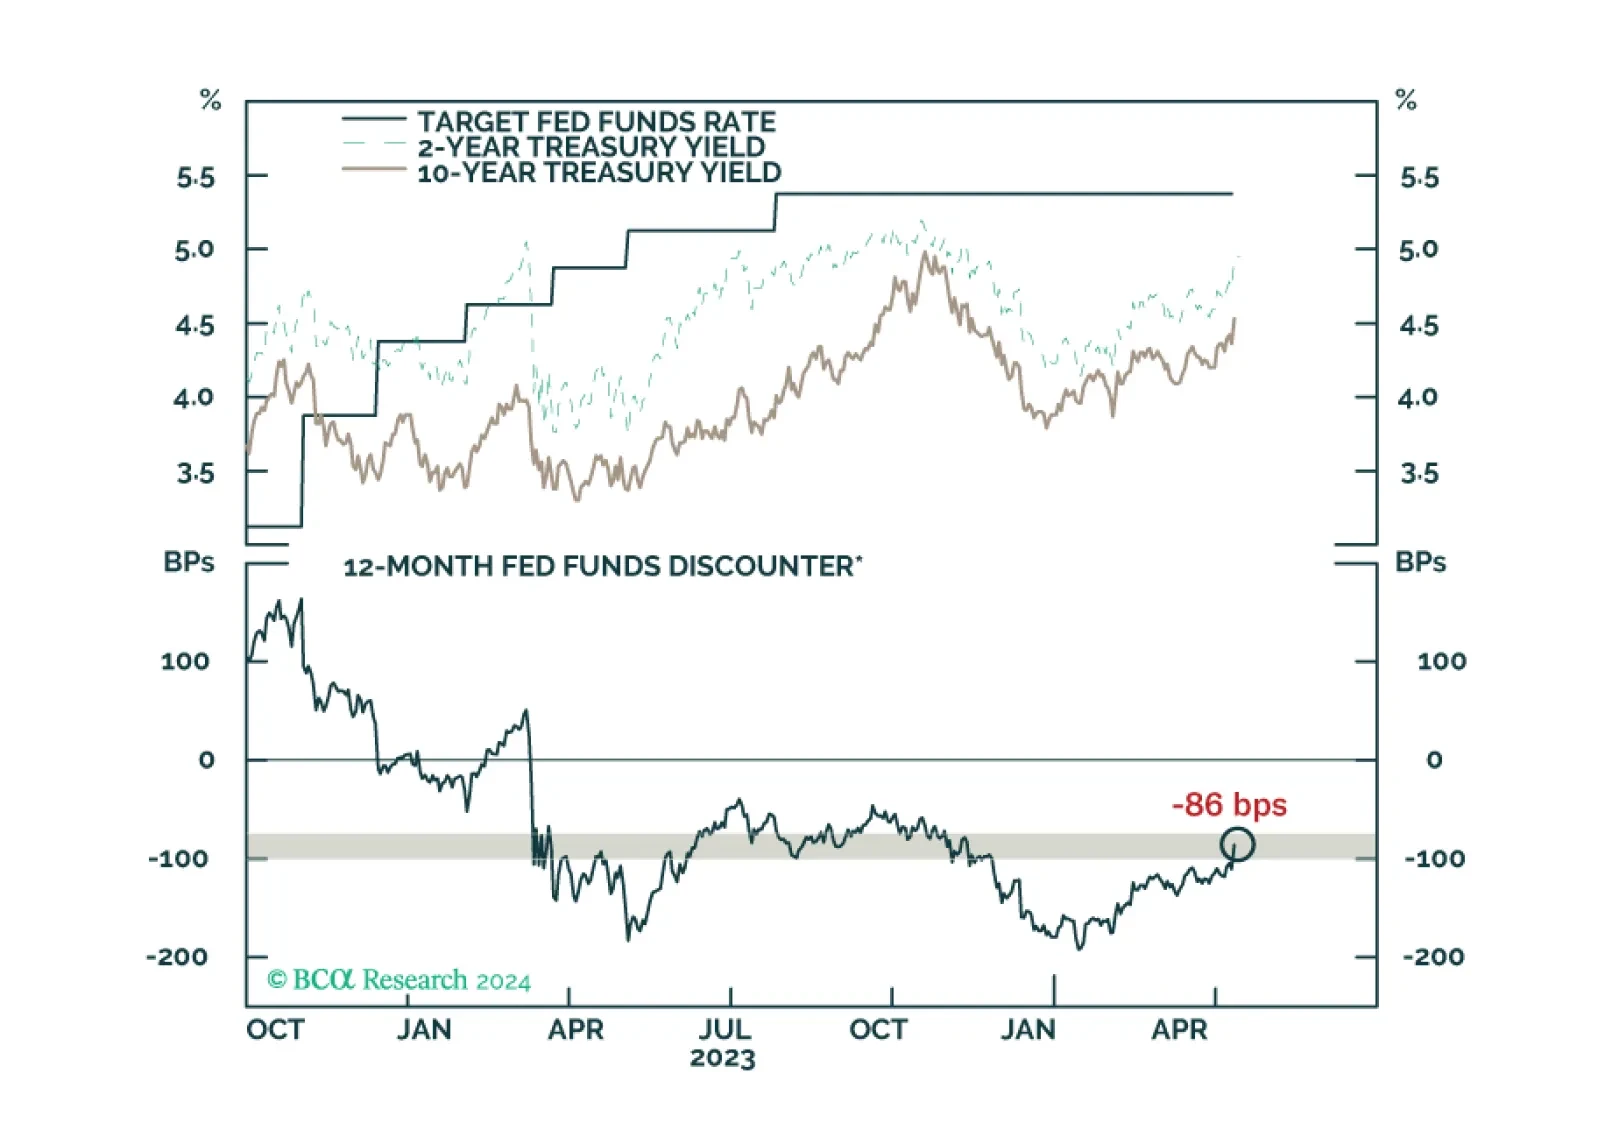
Our reaction to this morning’s CPI report and bond market moves.
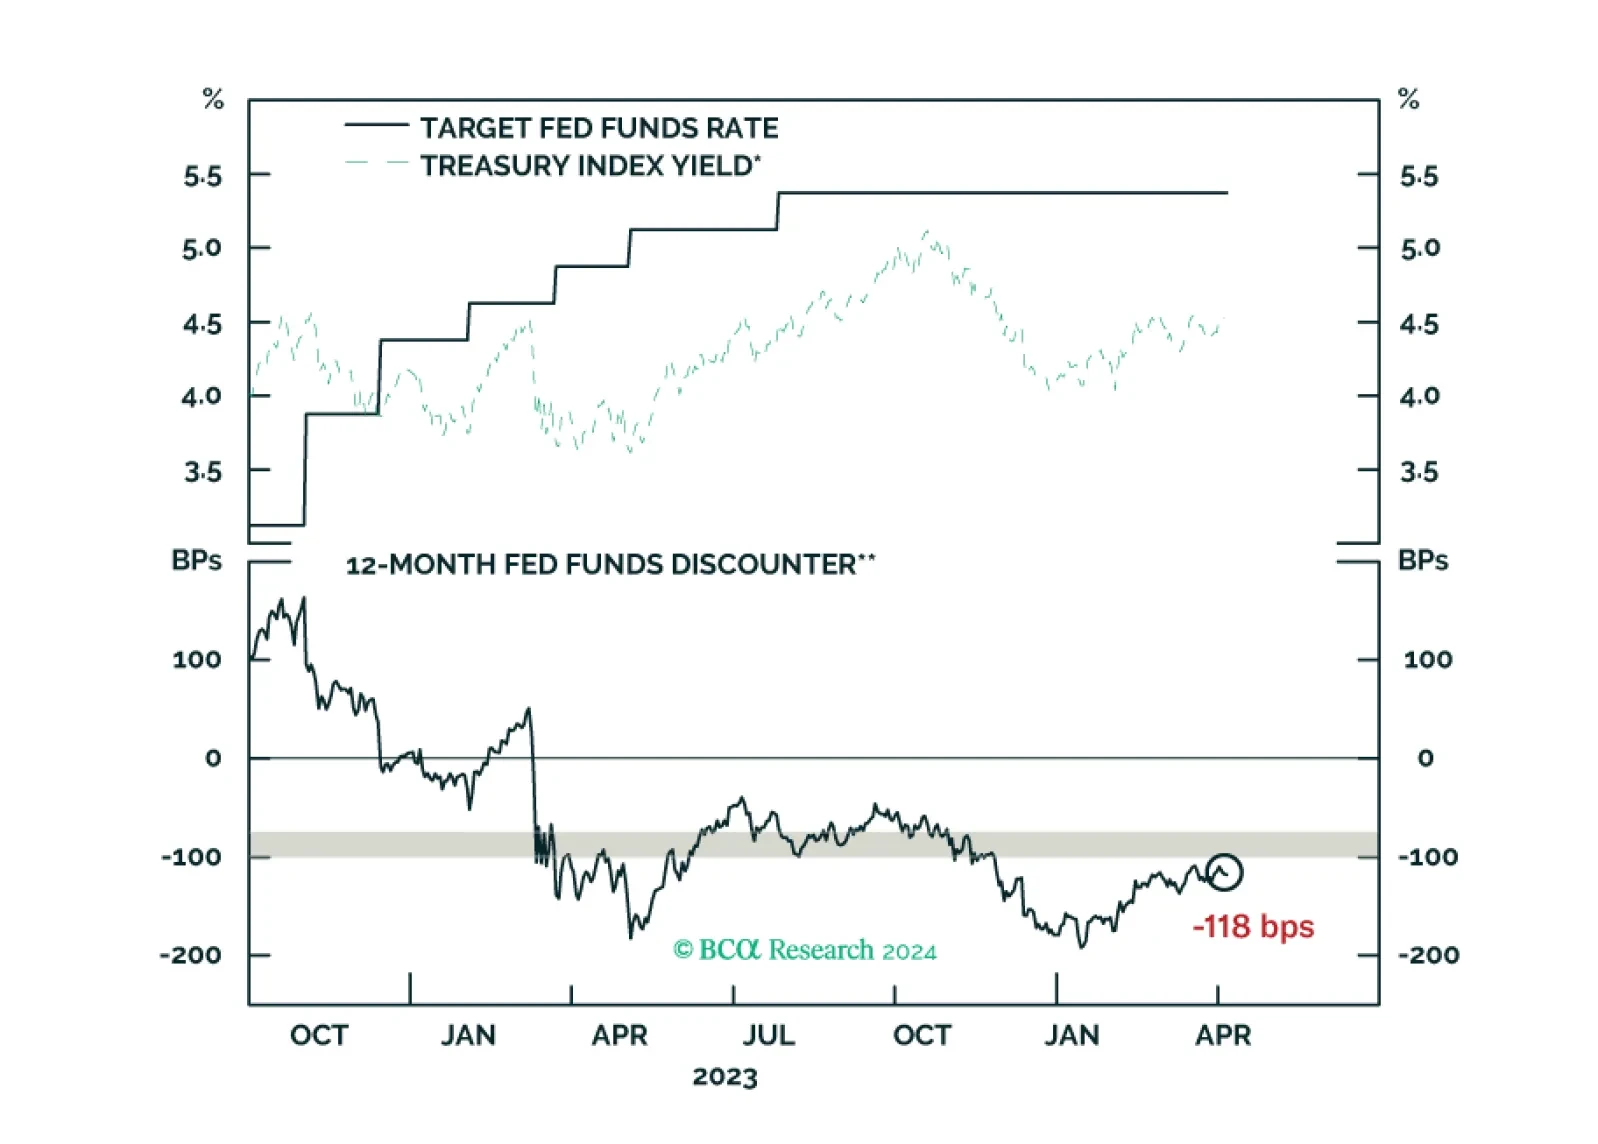
Our reaction to this morning’s employment report and bond market moves.
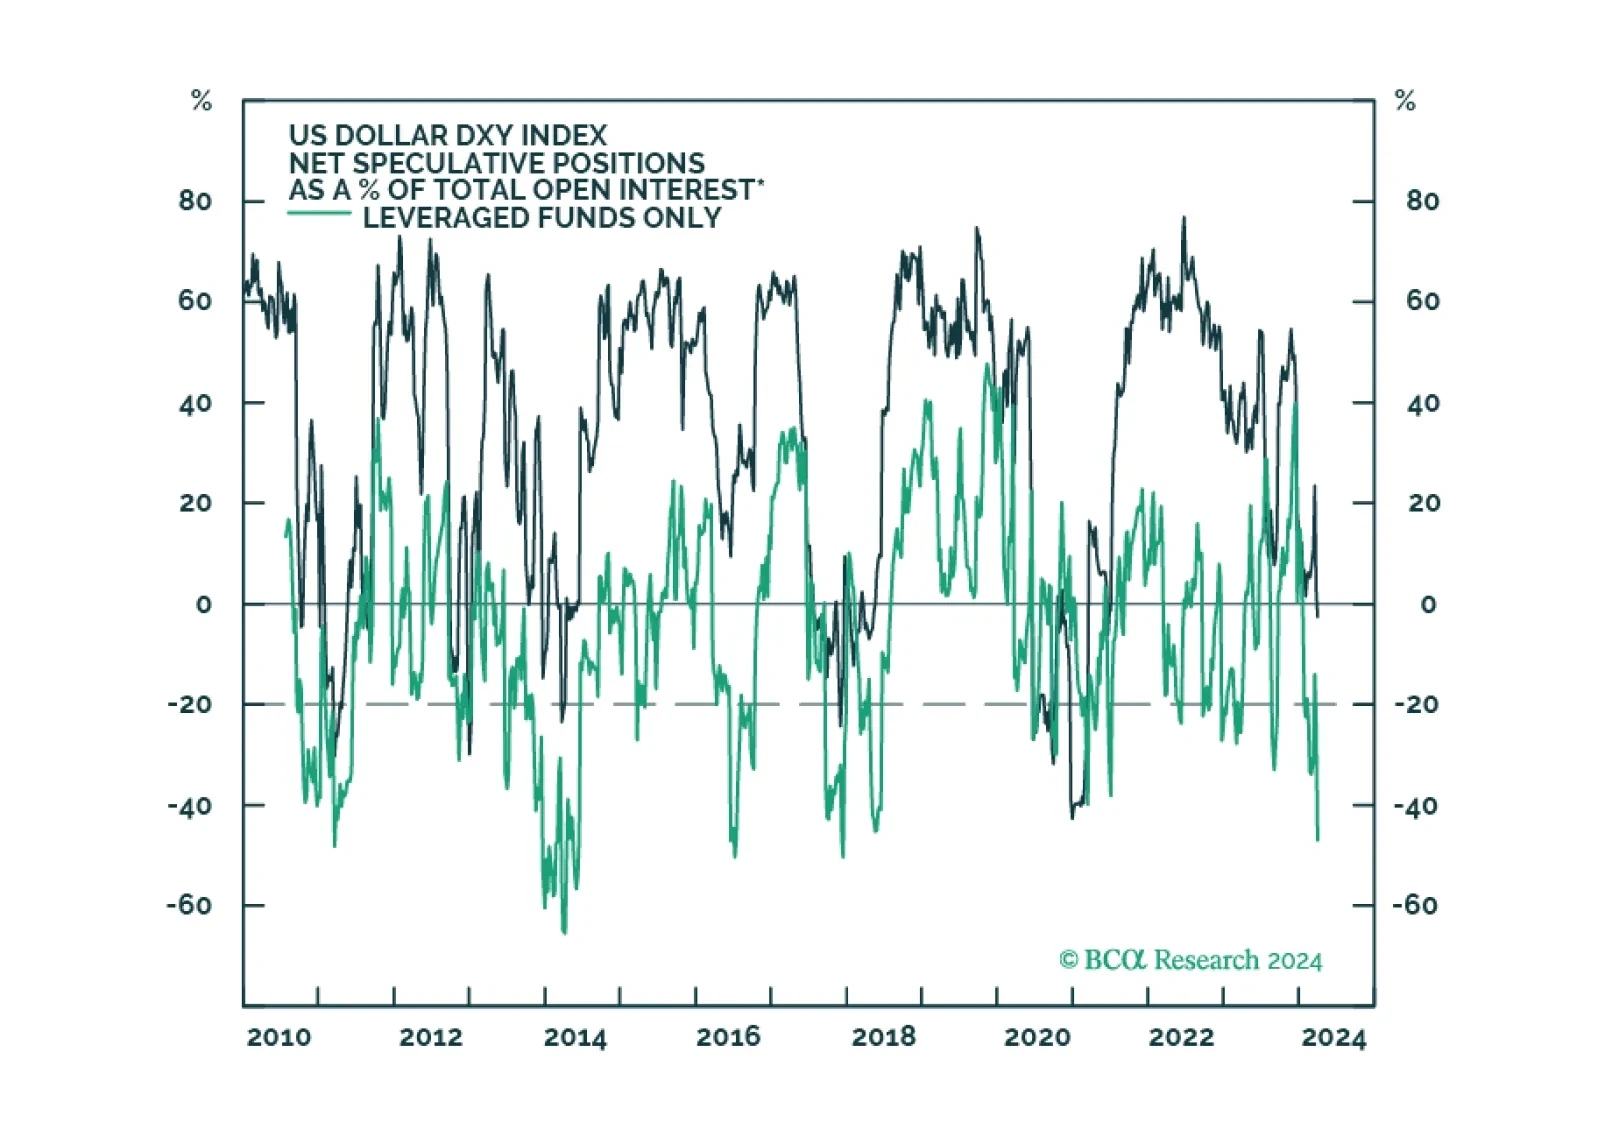
In this report, we review our trade recommendations based on incoming data in the last month.
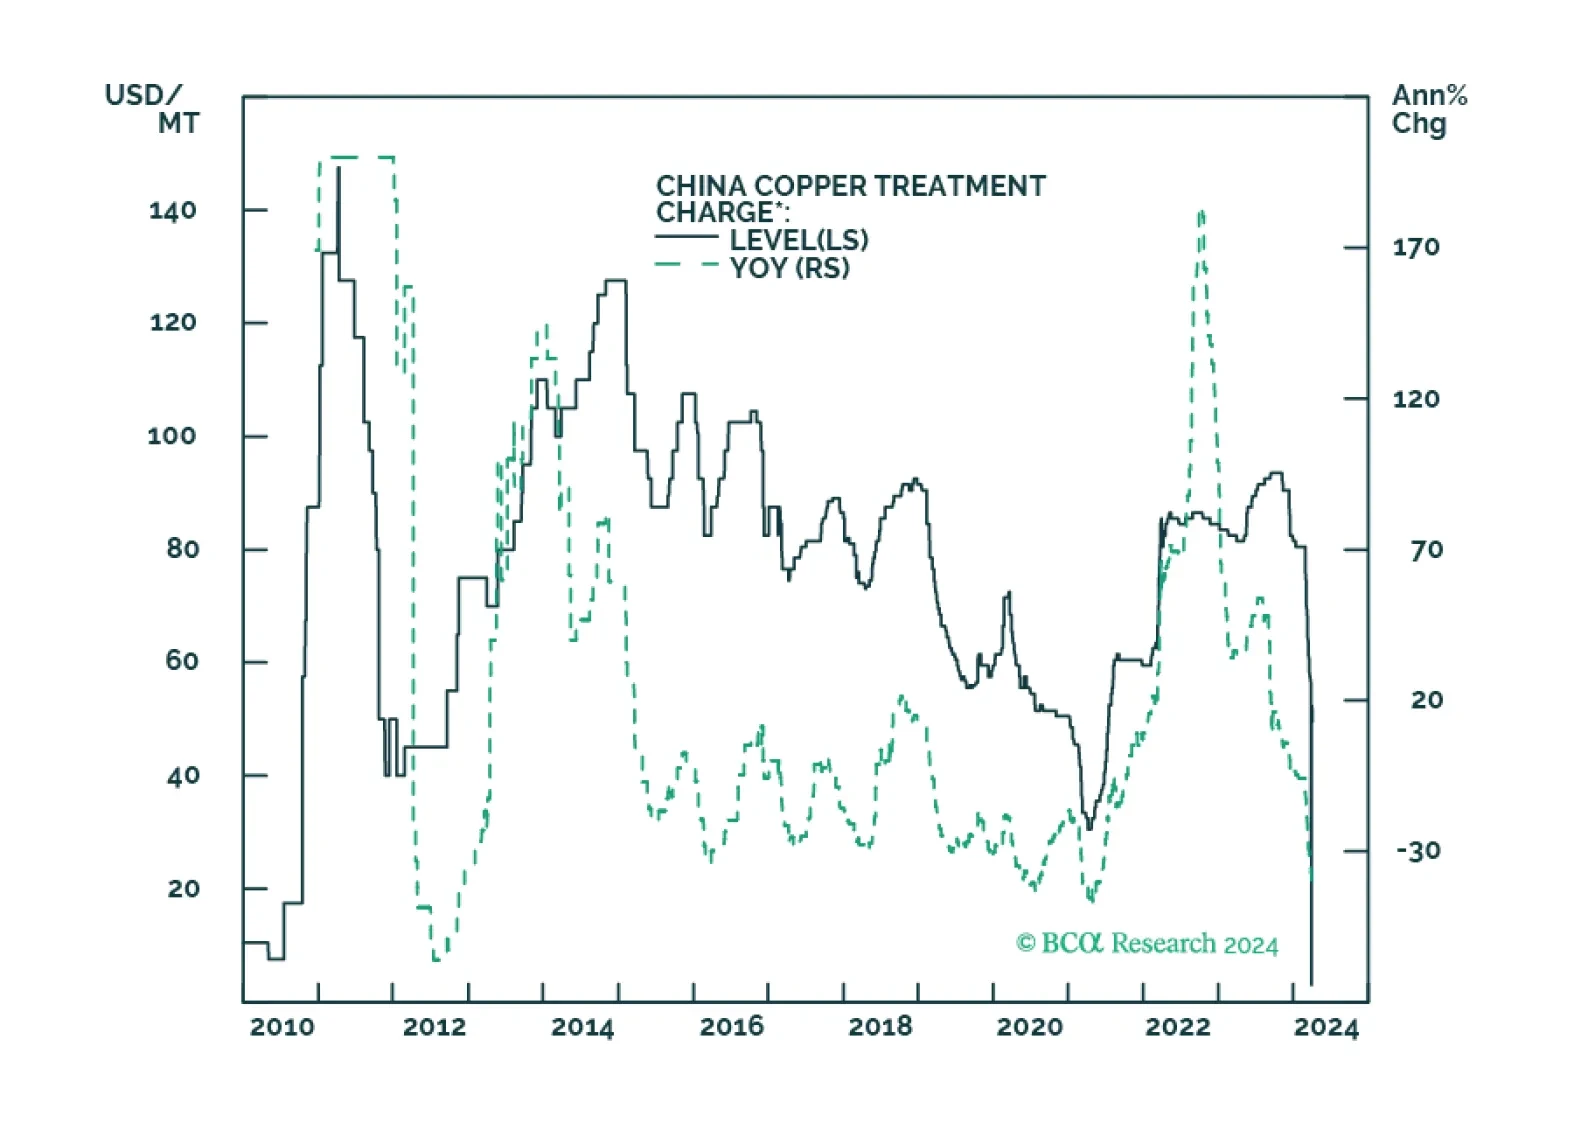
Copper markets are fast approaching a price breakout, as Chinese smelters scramble to find ore to meet increasing refined-copper demand in the wake of a global manufacturing rebound. We are holding fast to our expectation of $4.50/lb (COMEX) this year. We remain long the XME ETF to retain exposure to copper miners and refiners, and the COMT ETF to retain exposure to commodity flat price and the copper backwardation we expect.
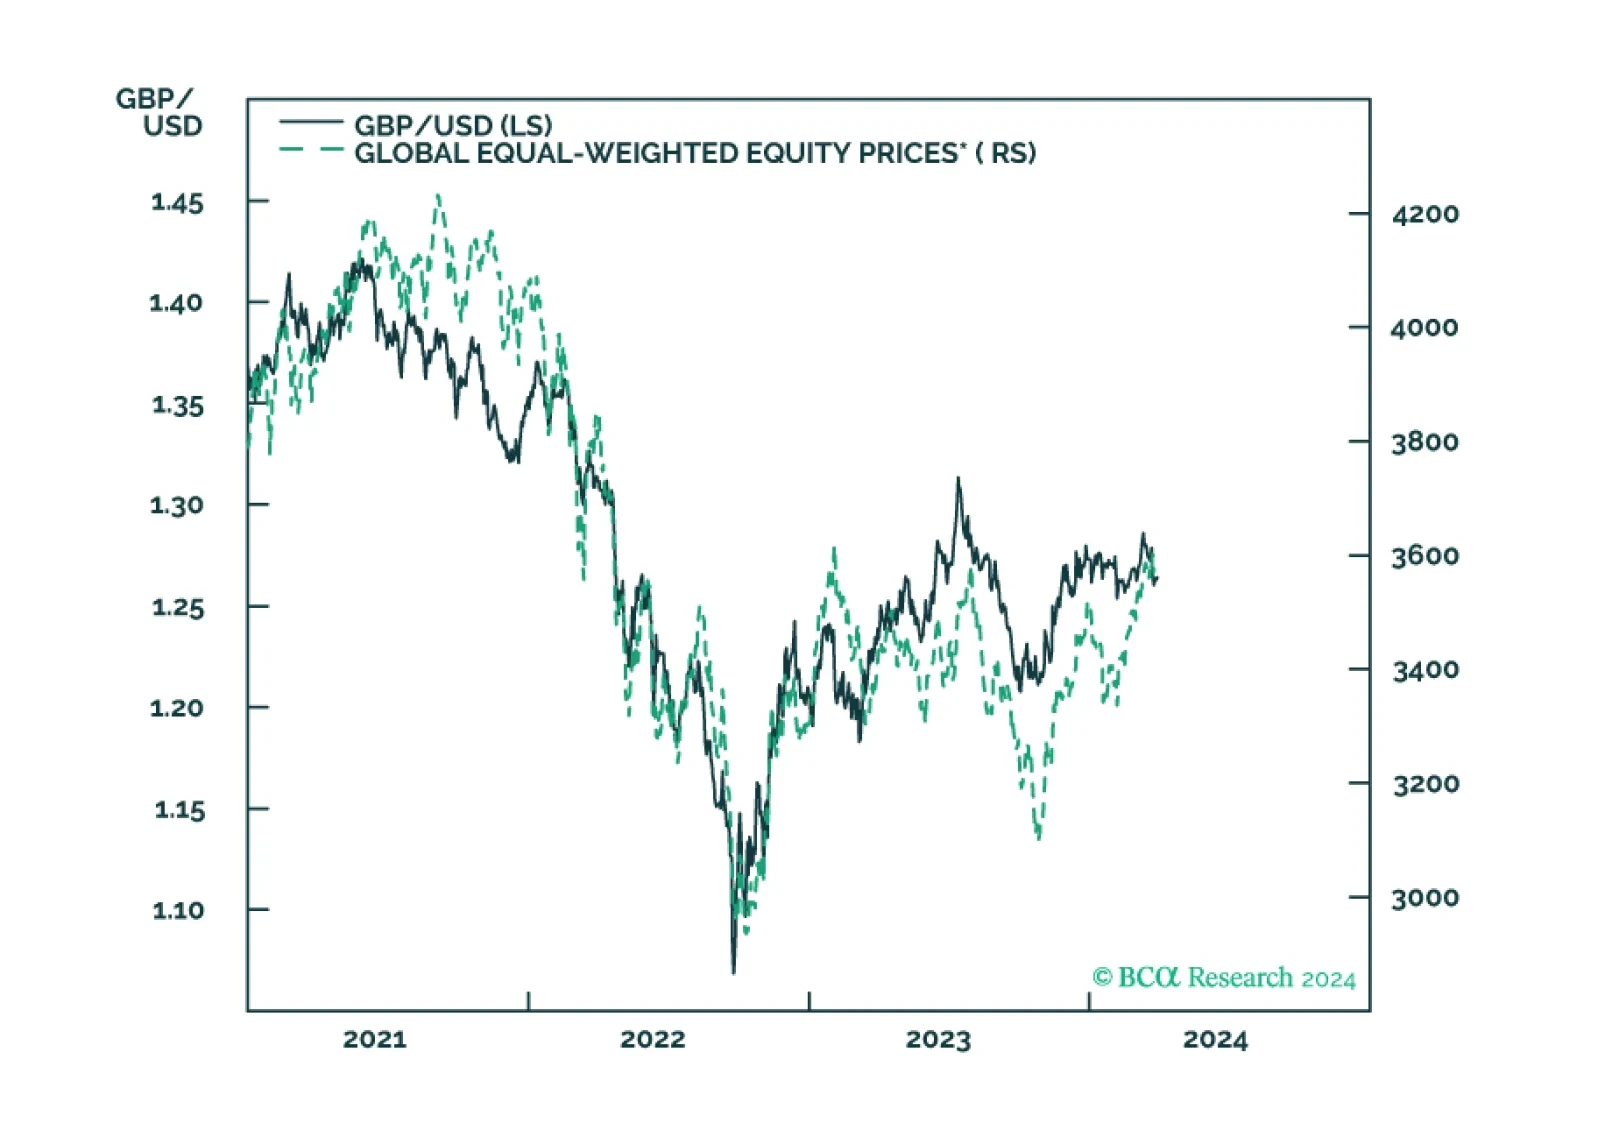
In this Insight, we discuss our rationale for a short sterling position.