 Equities
Macro, fundamental, and quantitative analysis translated into actionable equity views across sectors, factors, themes, and baskets.
In this final note for the year, we take profits and close several long-term investment positions: Overweights in Insurance and Commercial Services, and underweights in Utilities, and Retail and Commercial REITs.
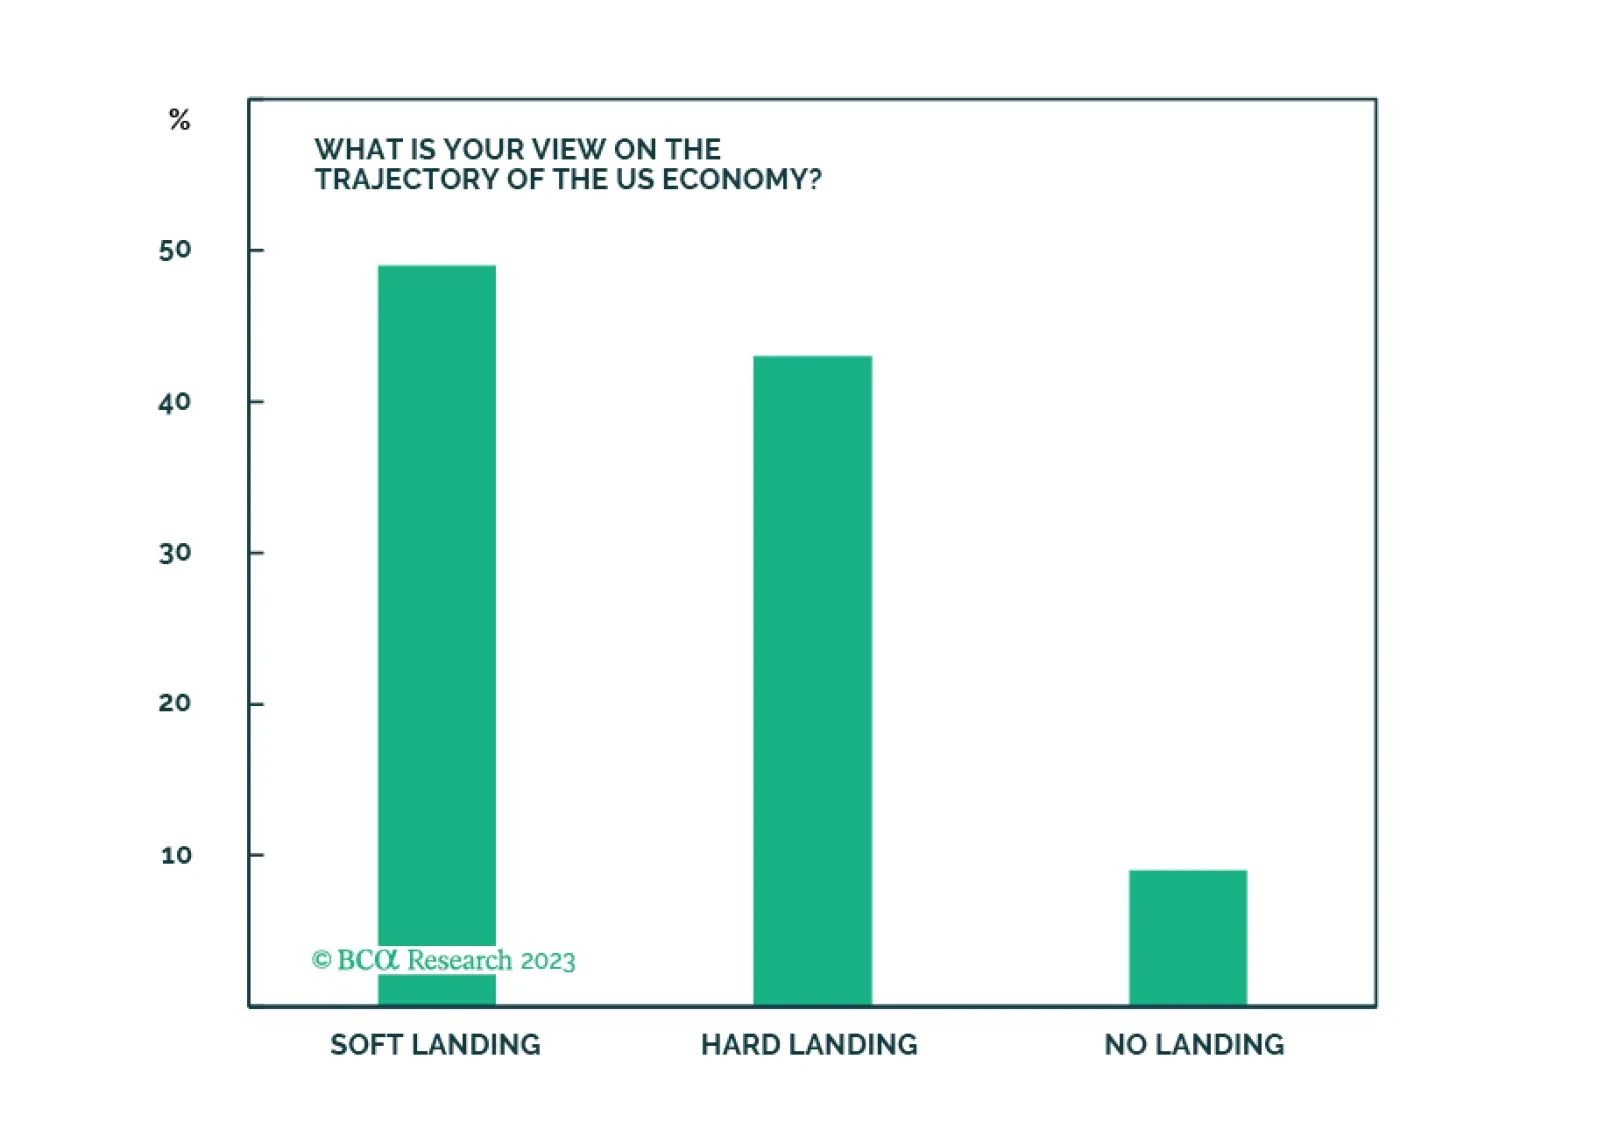
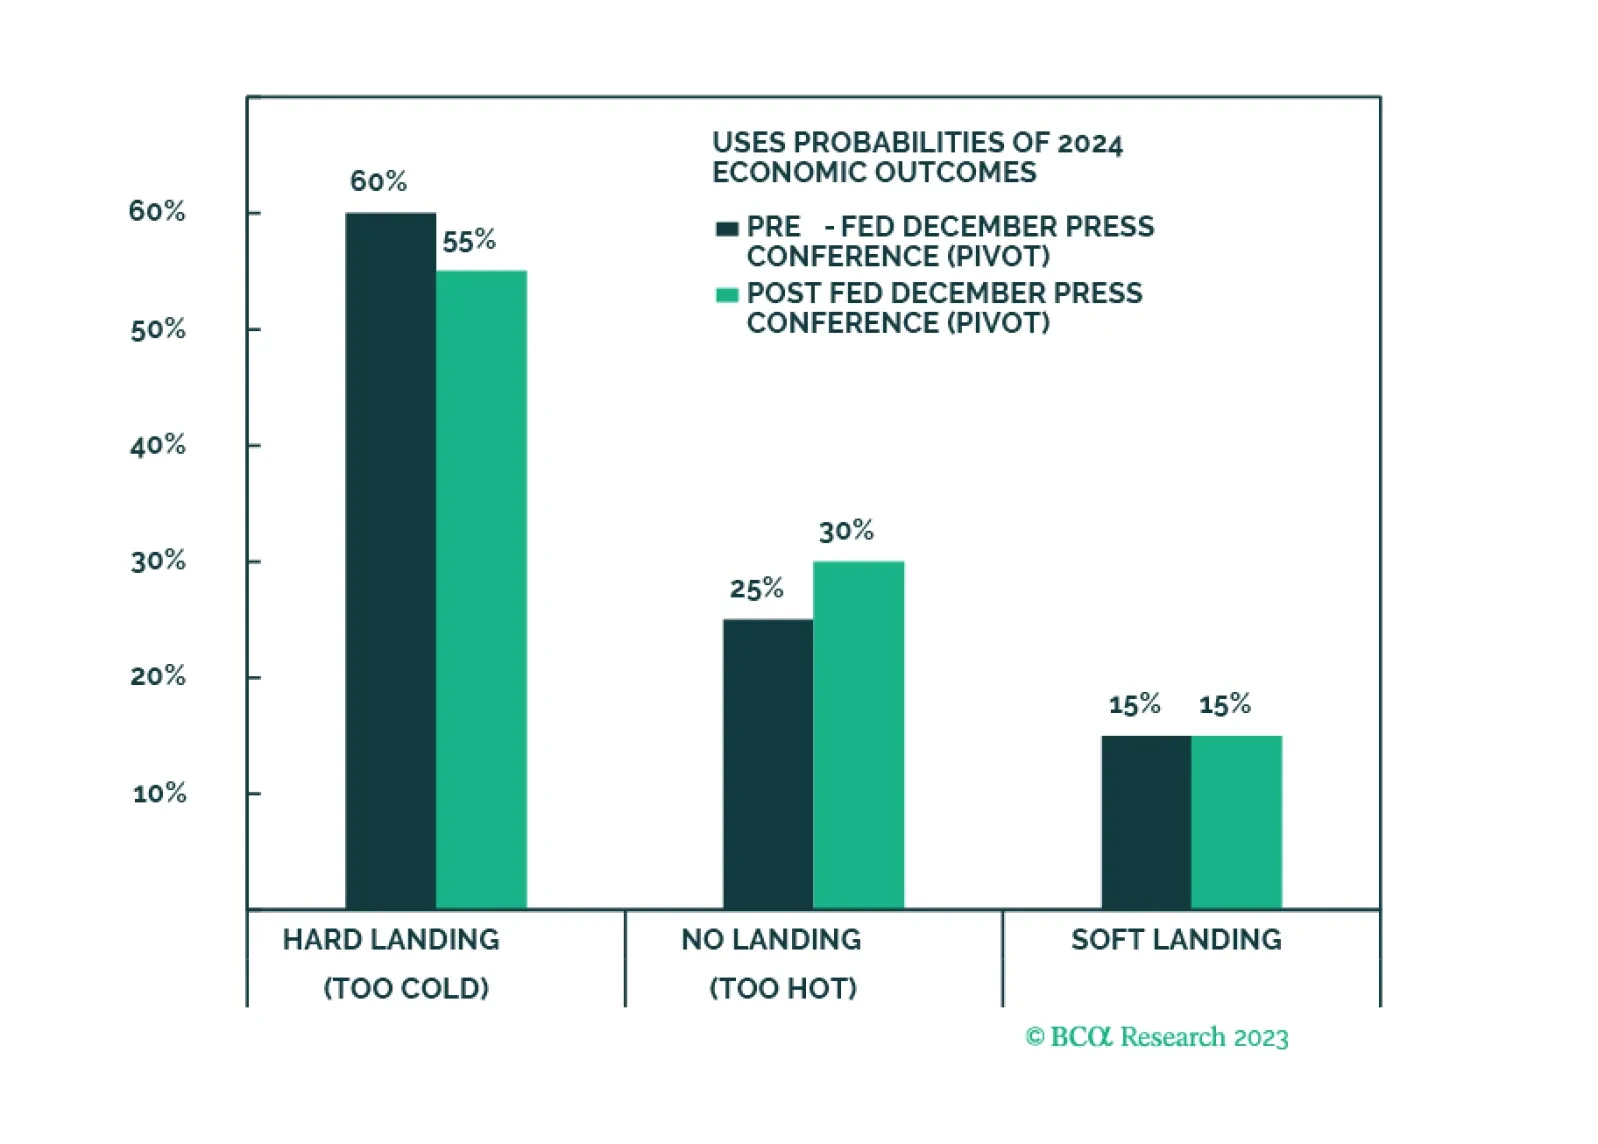
The Santa Claus rally is a repricing of the "soft landing" scenario as a likely economic outcome. Yet, many investors remain cautious, and harbor significant cash balances. Next year, repricing of various scenarios will continue, and volatility will be elevated. We remain in a "hard landing" camp and recommend defensive stance on a strategic investment horizon.
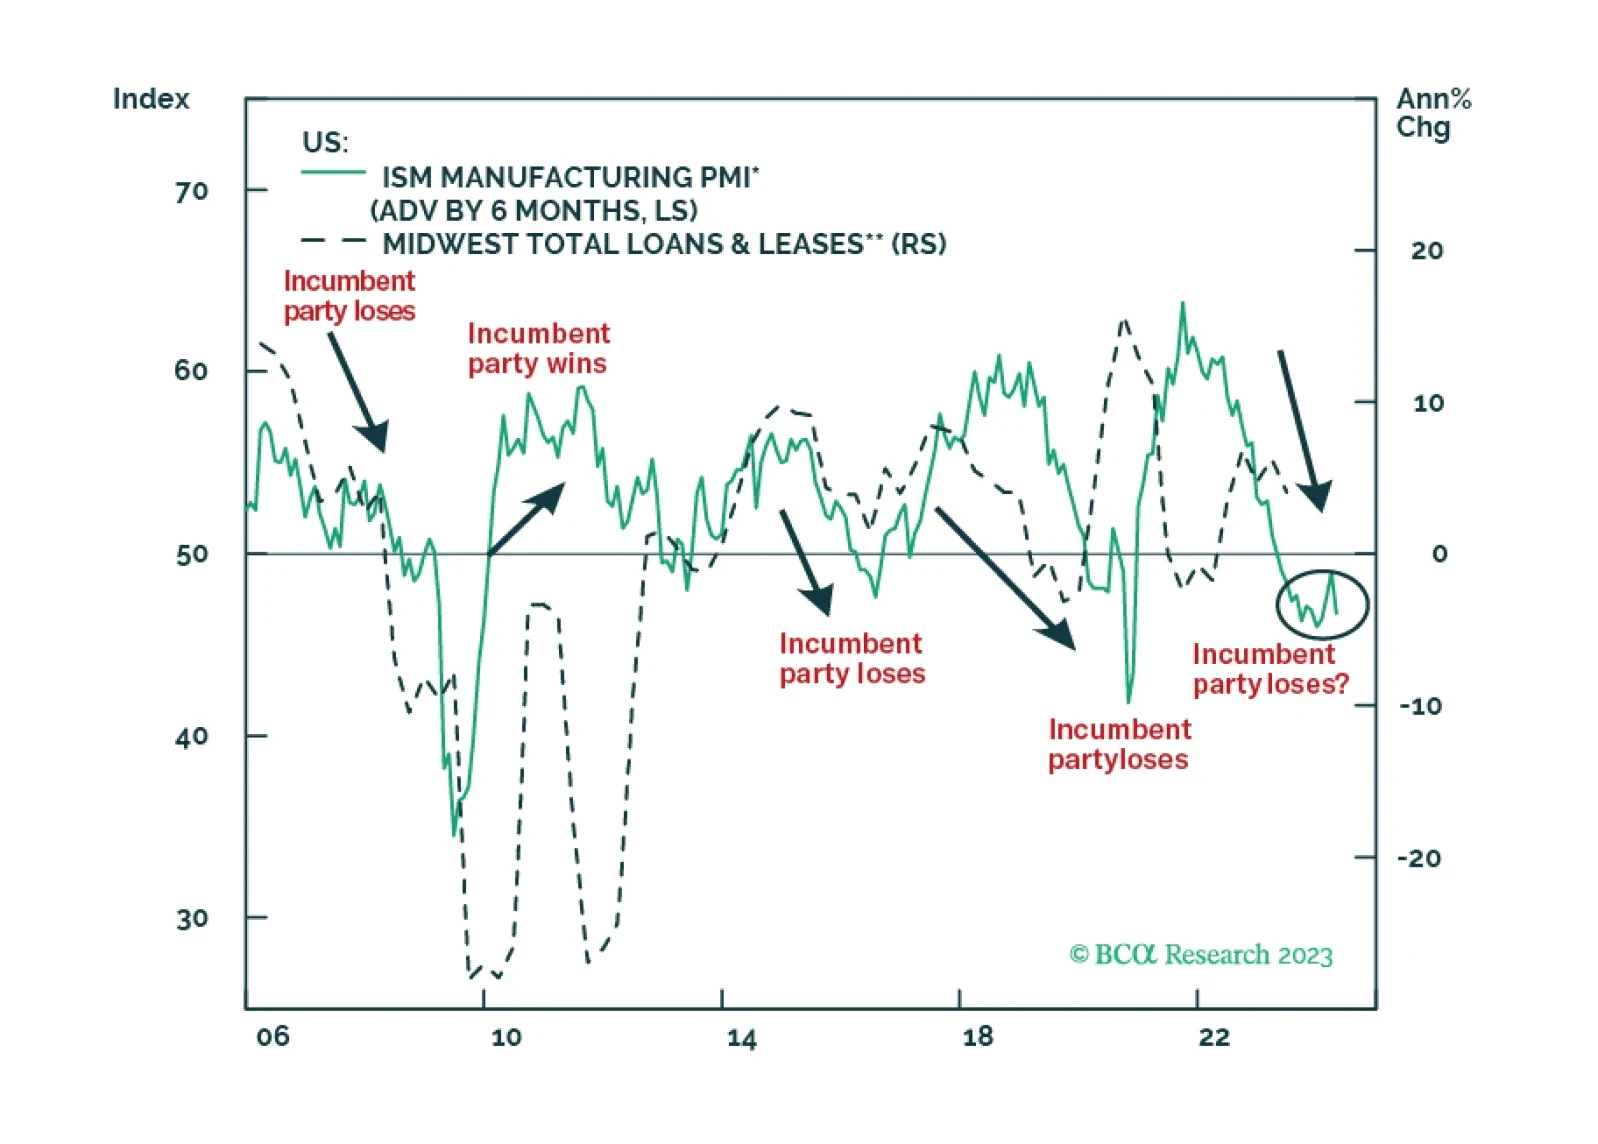
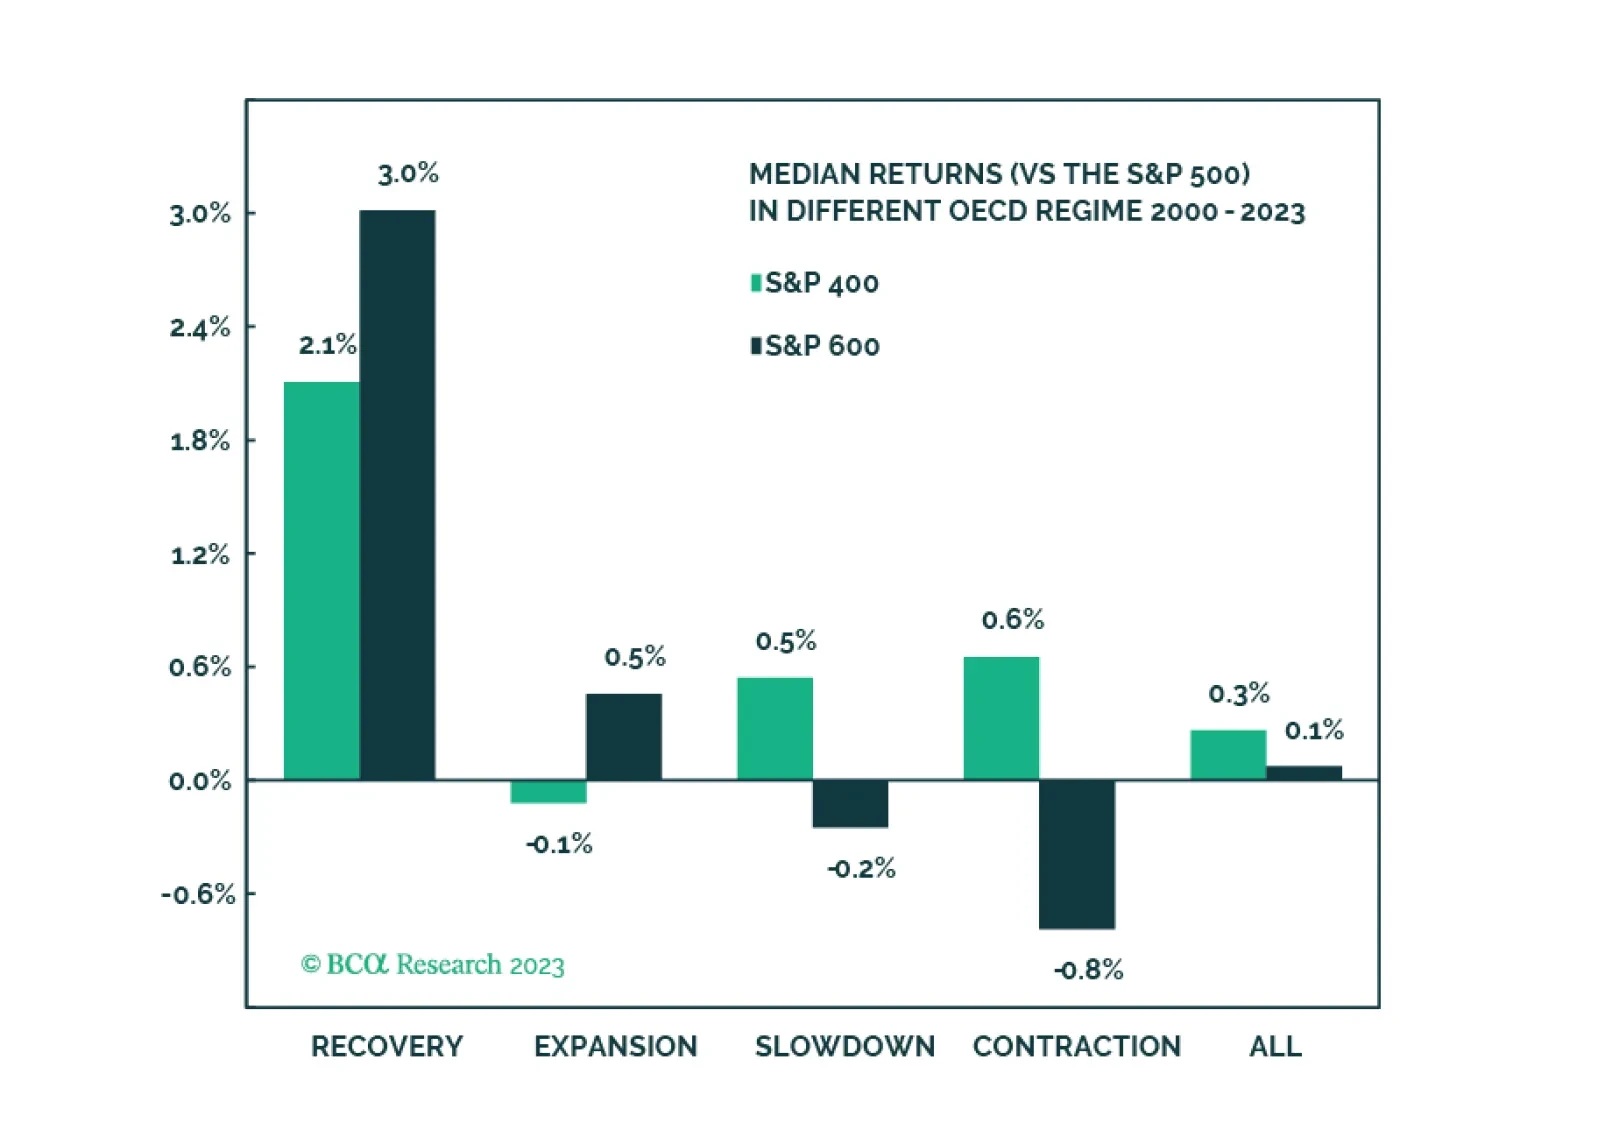
Mid-caps are the best of both worlds and are an excellent strategic overweight thanks to their size premium, but also better financial quality and higher dividend yield than Small. We are bullish on Mid near term and believe that this may be a great trade. We will initiate a position in the S&P 400 as a tactical overweight but will monitor it very closely.
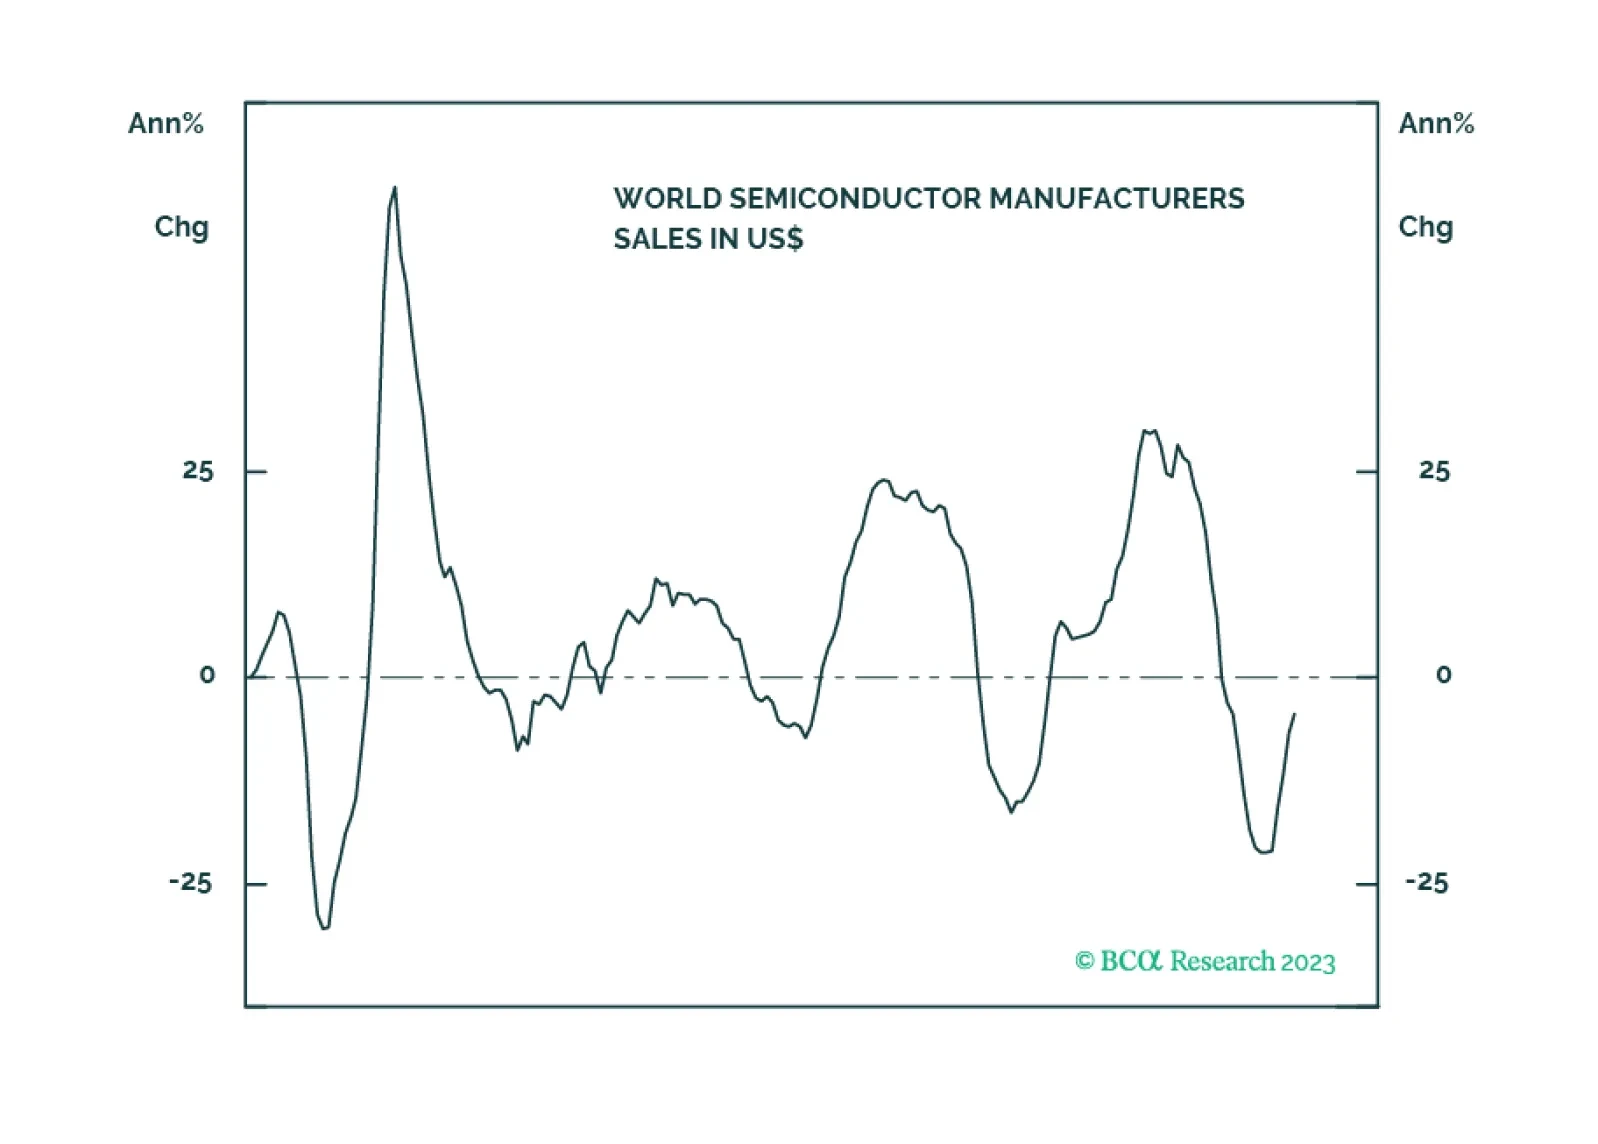
After a prolonged slump, there are early signs that demand for chips has bottomed and is showing signs of life. Meanwhile, corporate demand for future GAI chips is still a significant industry tailwind. In line with our call for an overweight of the Magnificent Seven, upgrade Semis to equal weight from underweight on a tactical basis. Longer-term outlook is neutral to negative as we expect the economy to slow in 2024, while growth expectations may be too high.
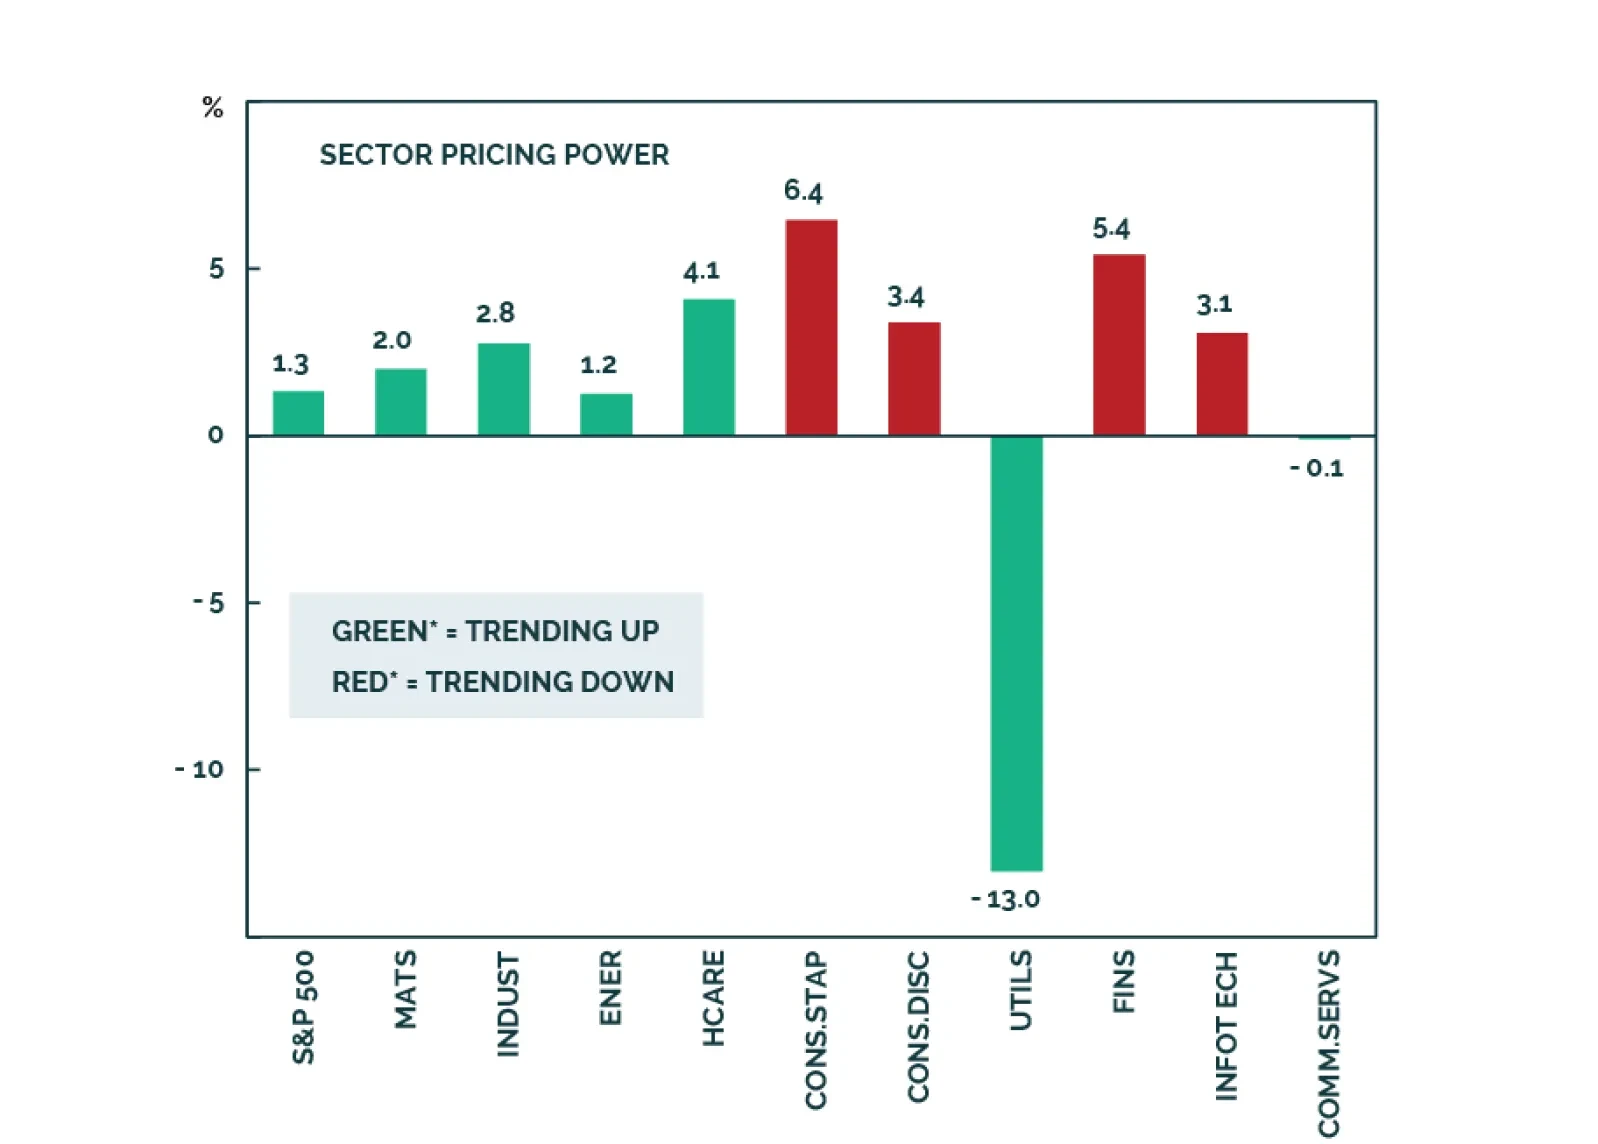
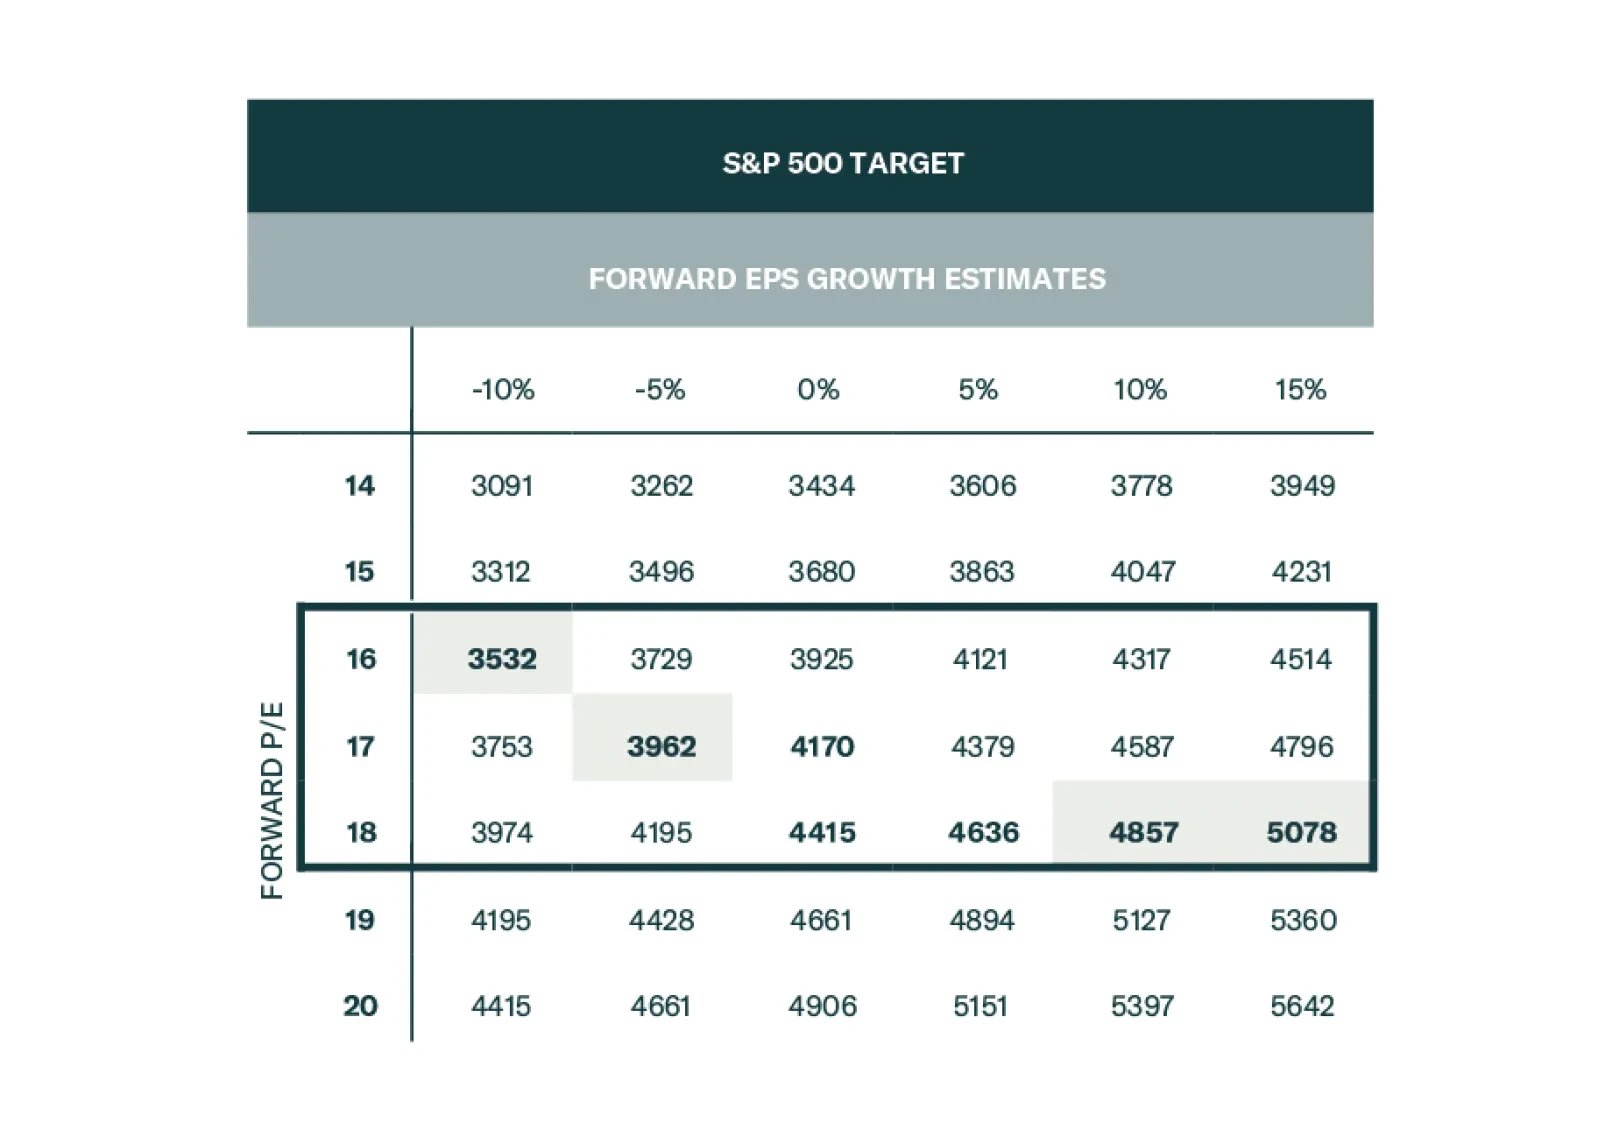
Q3 earnings commentary has been broadly positive, despite intensifying macro headwinds. Going forward, a negative growth outlook and geopolitical risks, are a threat to buoyant earnings expectations. We project that earnings growth for 2024 will move lower than currently projected - a negative for equities. This Santa Claus rally is unlikely to be the start of a new bull market.
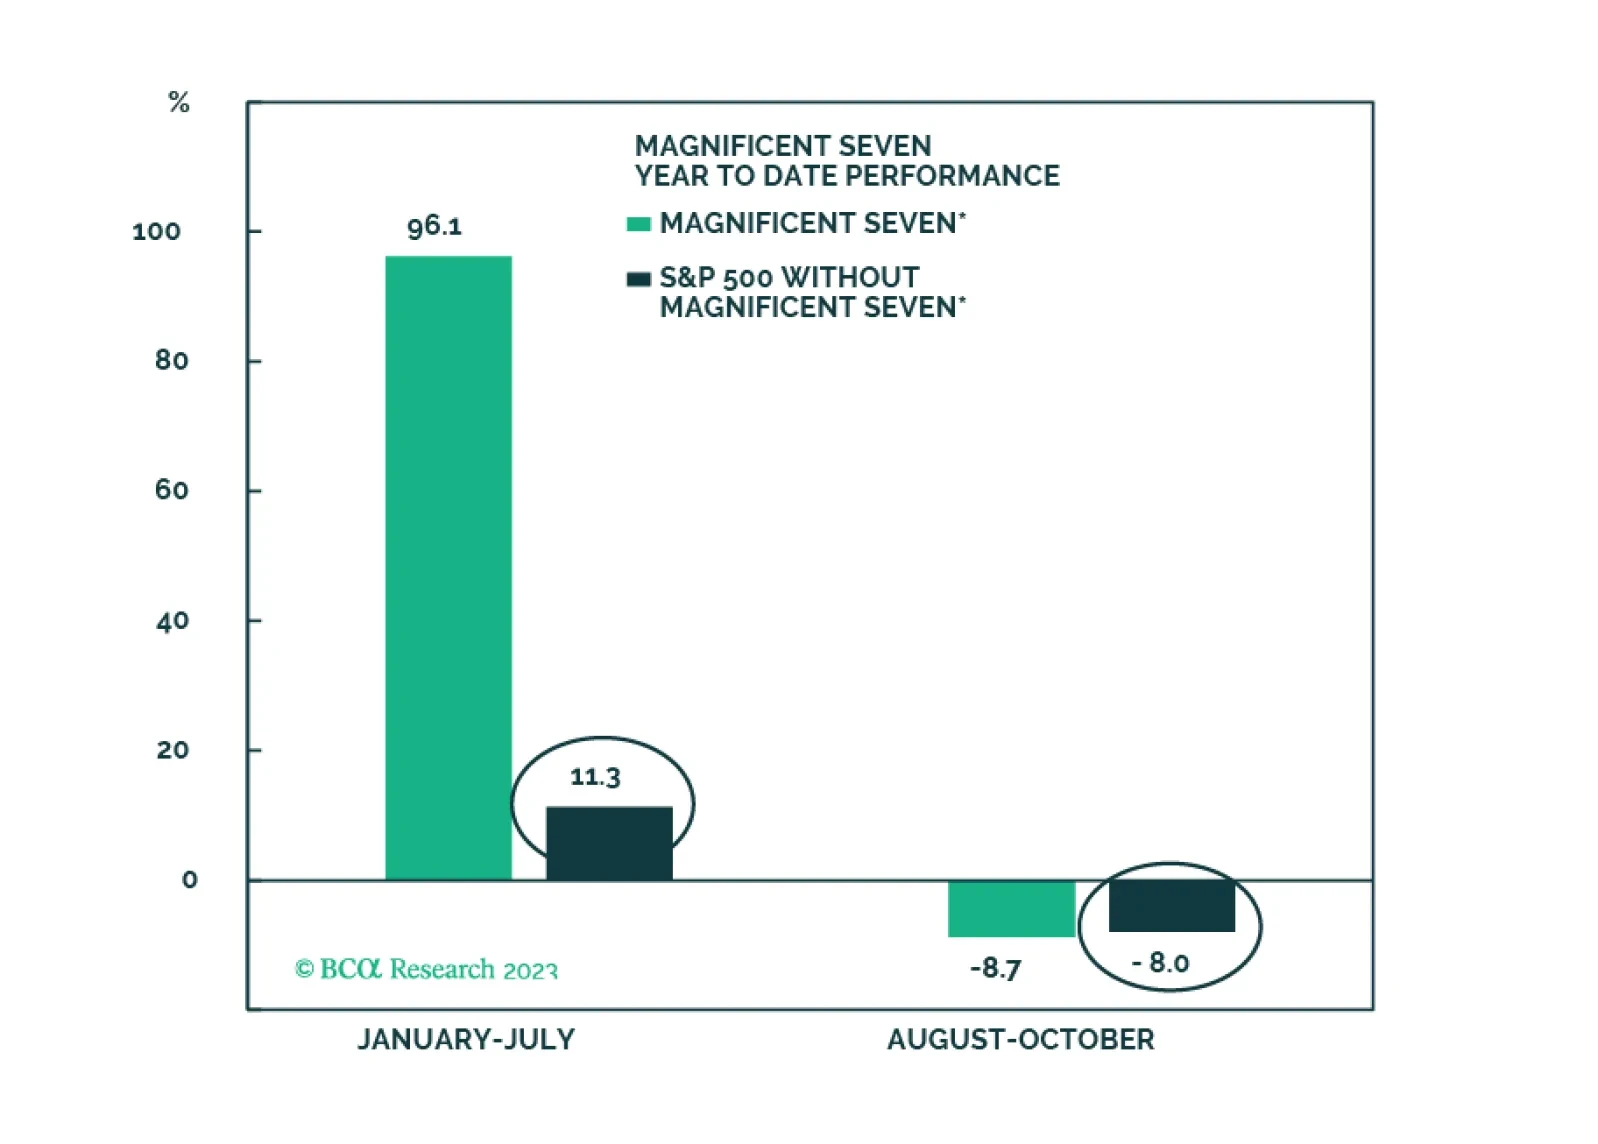
The Vicious Troika remains a long-term threat, but over the short term, rates will likely have another leg down on growth concerns, offering support to equities, which are now fairly valued and are no longer overbought. Longer-term outlook remains negative. The Magnificent Seven will likely lead a tactical rebound. Overweight Growth vs Value and FSemis.
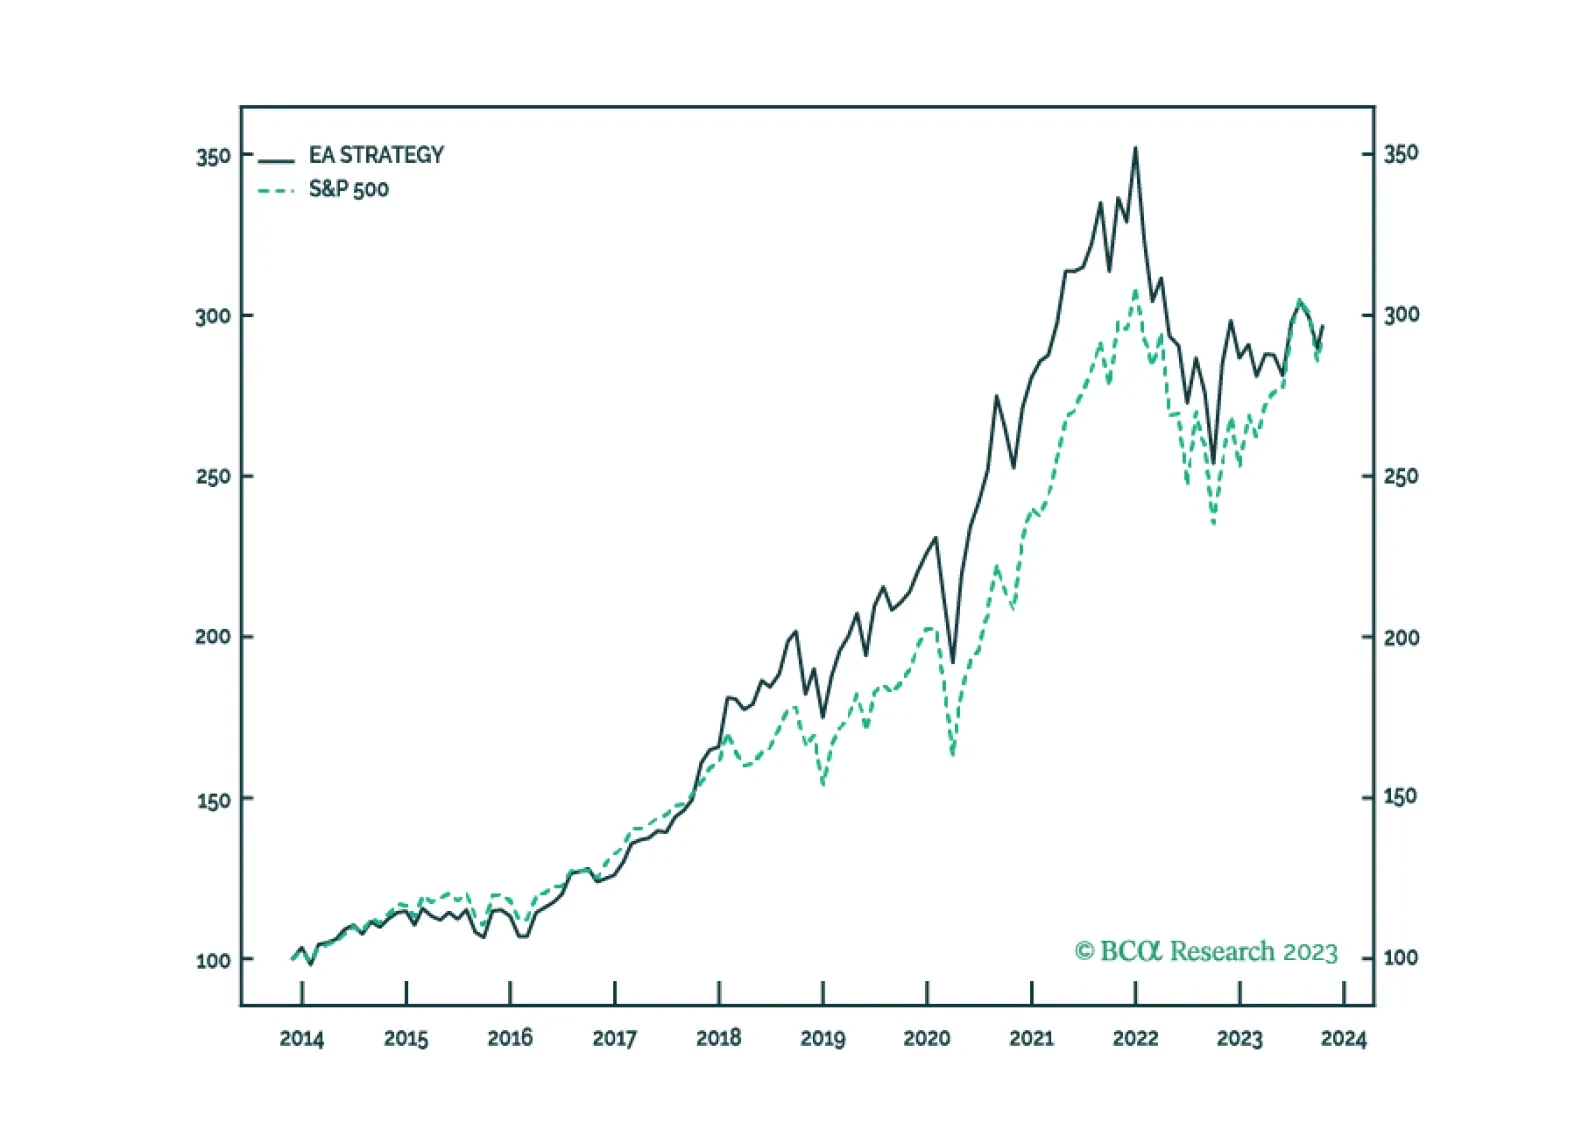
In this insight we suggest two ways clients can use Equity Analyzer to navigate the evolving crisis in the Middle East. The first minimizes commodity exposure and the second uses relies on the BCA Score to add exposure to high quality Energy and Aerospace and Defense stocks.