Monetary Policy
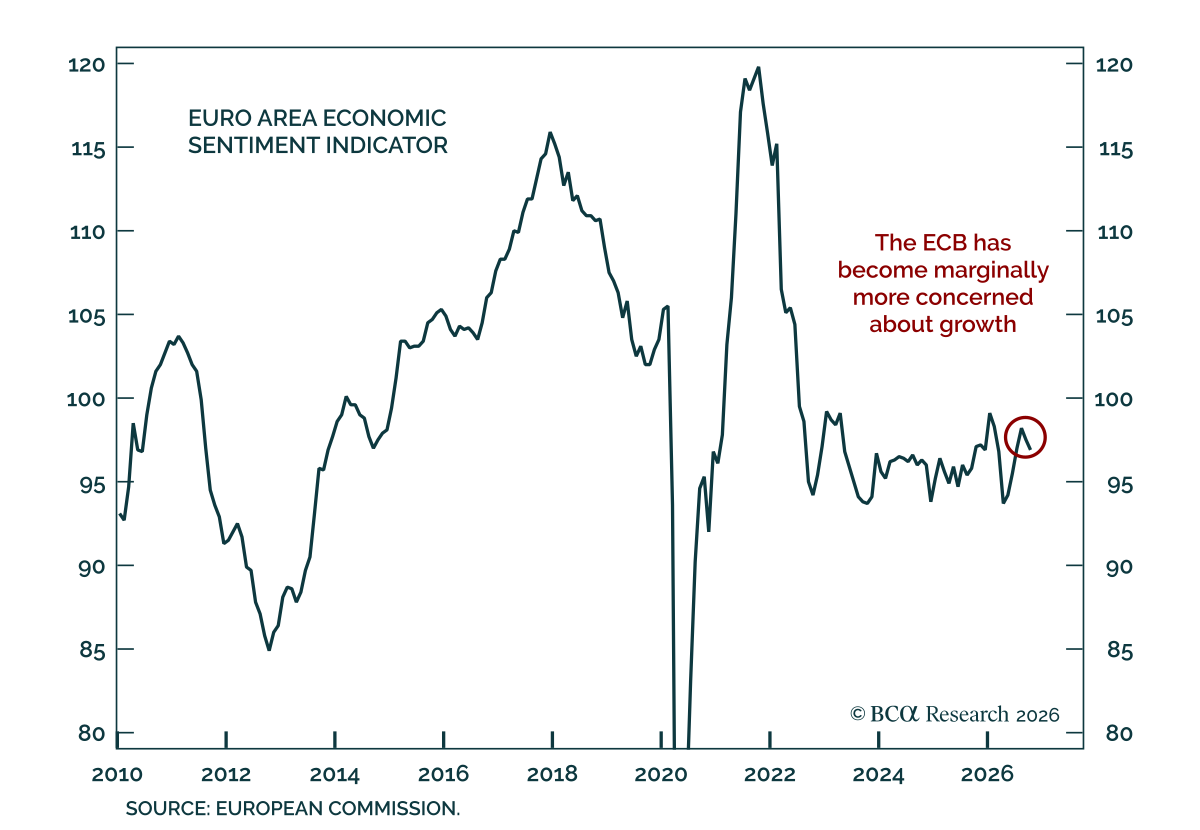
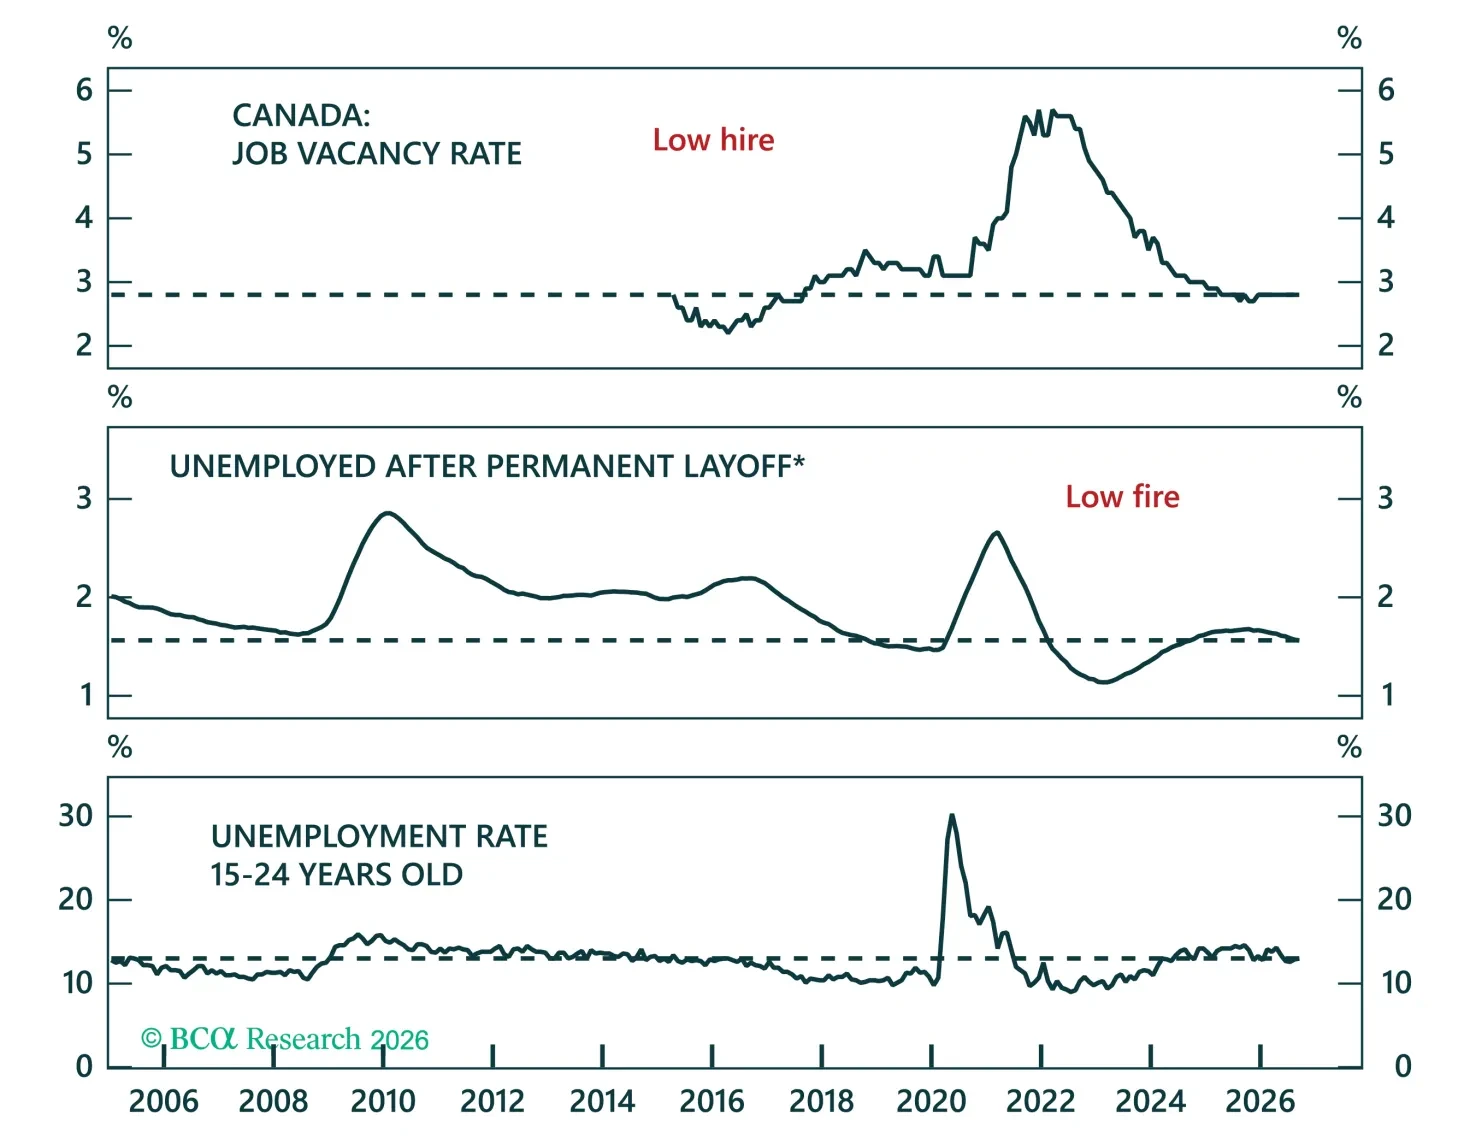
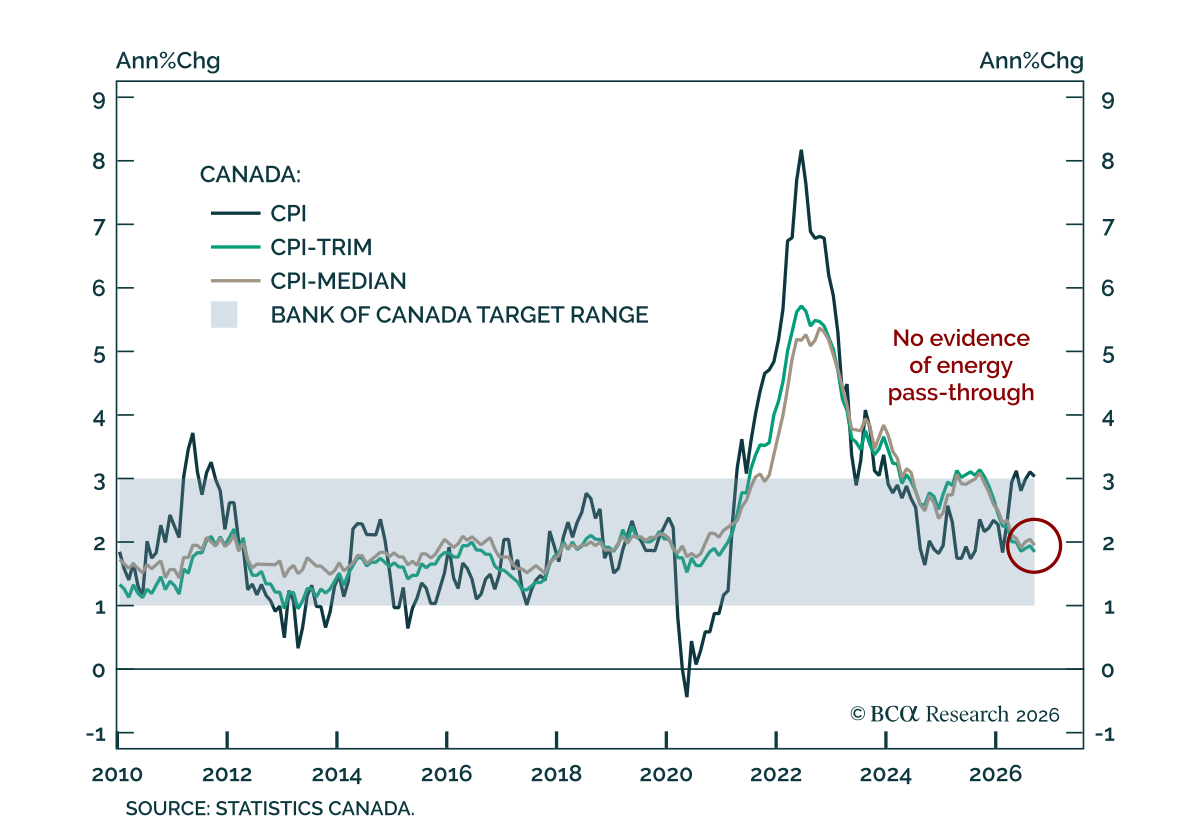
Markets expect further BoC tightening, but Canada’s economic backdrop casts doubt on how far rates can rise. We assess to what extent inflation, the labor market, and housing will limit the hiking cycle, and explore the implications for Canadian bonds and the CAD.
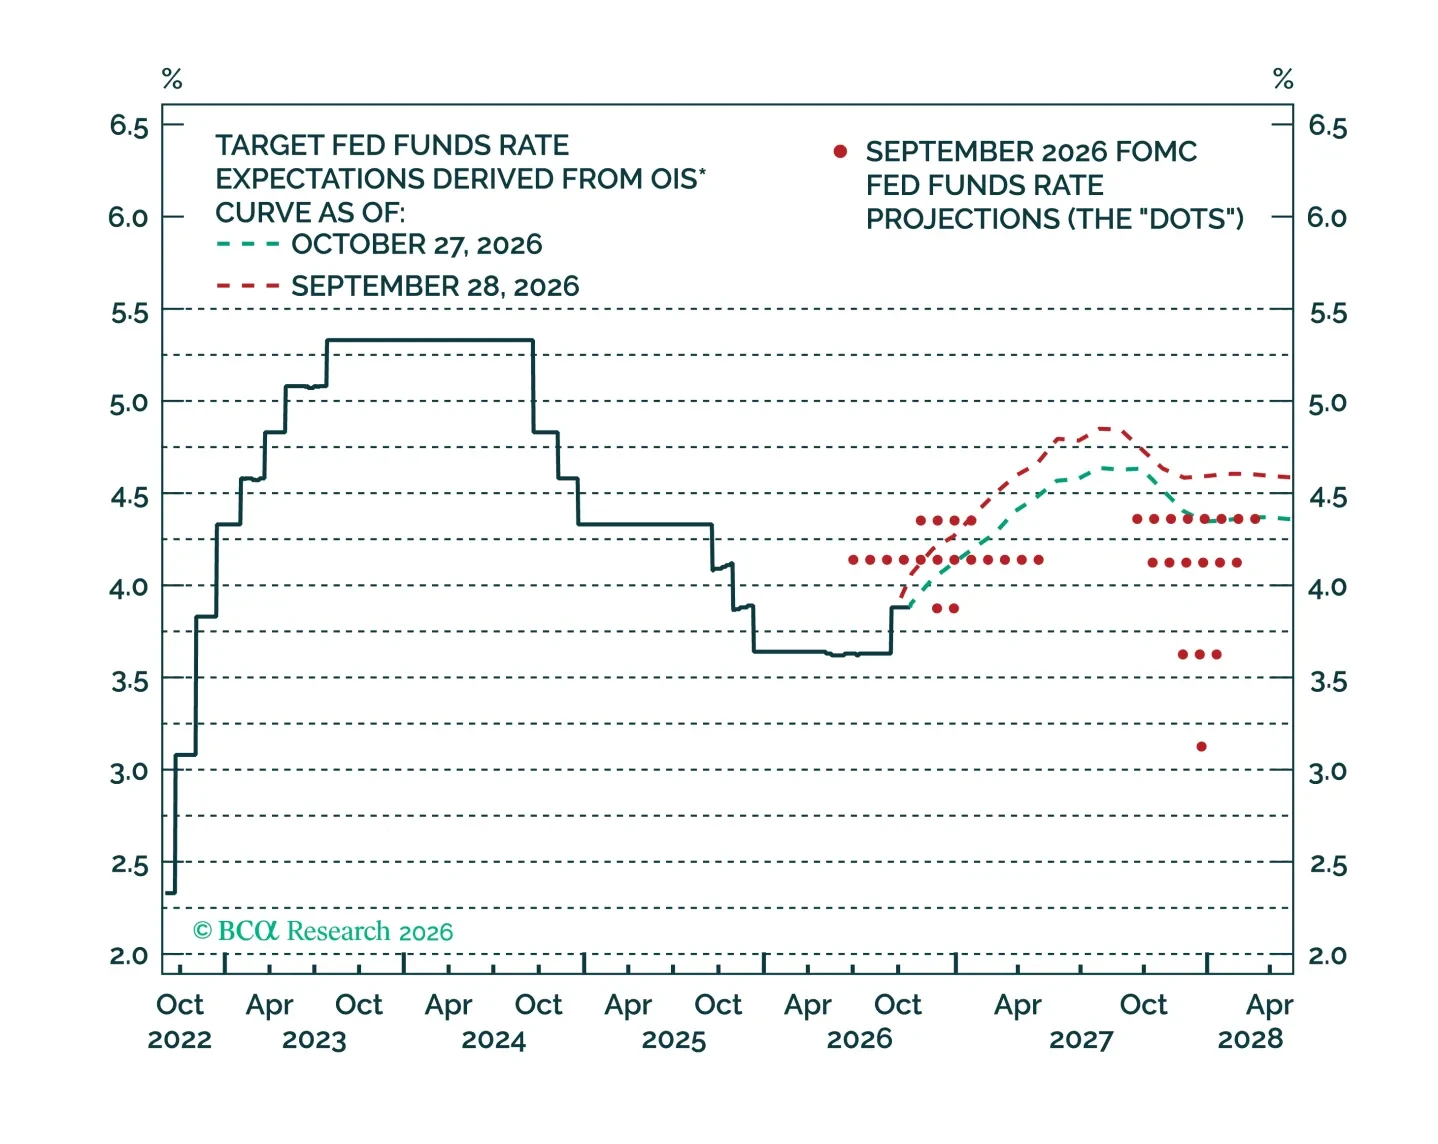
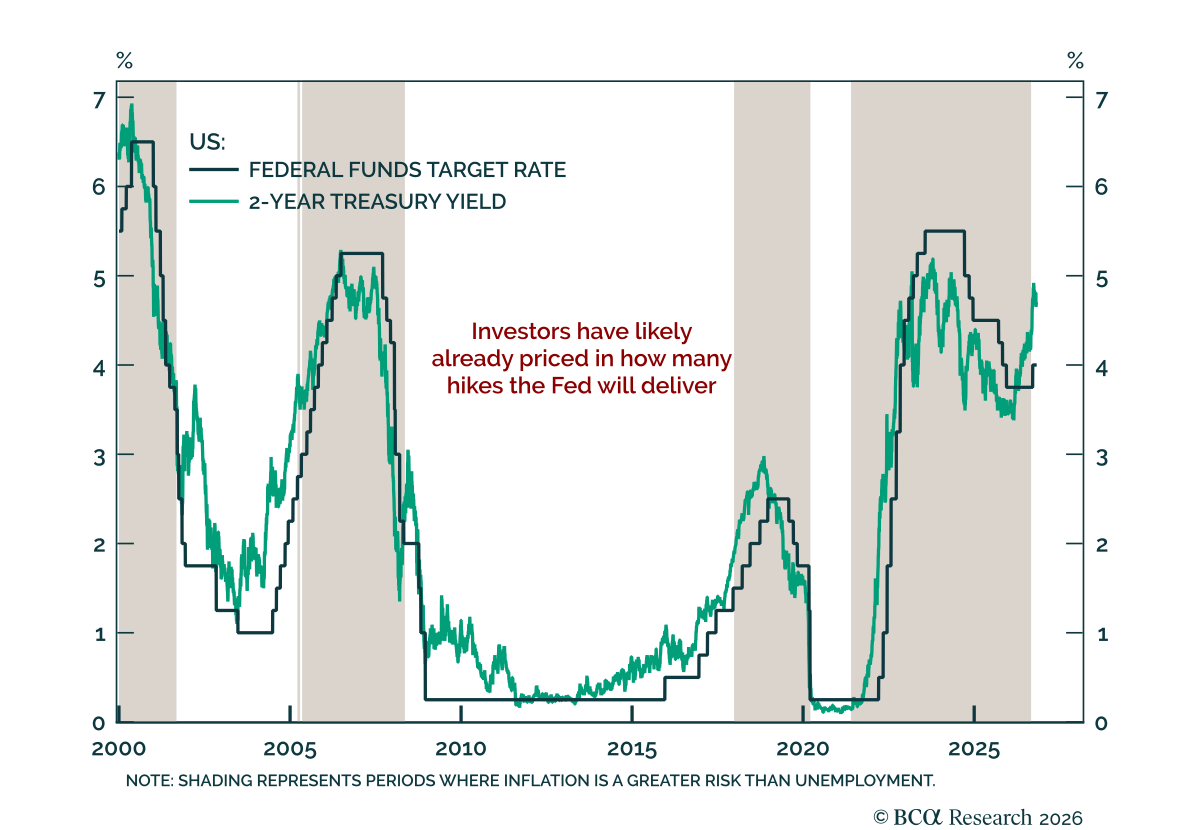
The Fed will hike rates at a pace of 25 bps per quarter until either falling inflation or tighter financial conditions cause it to stop.
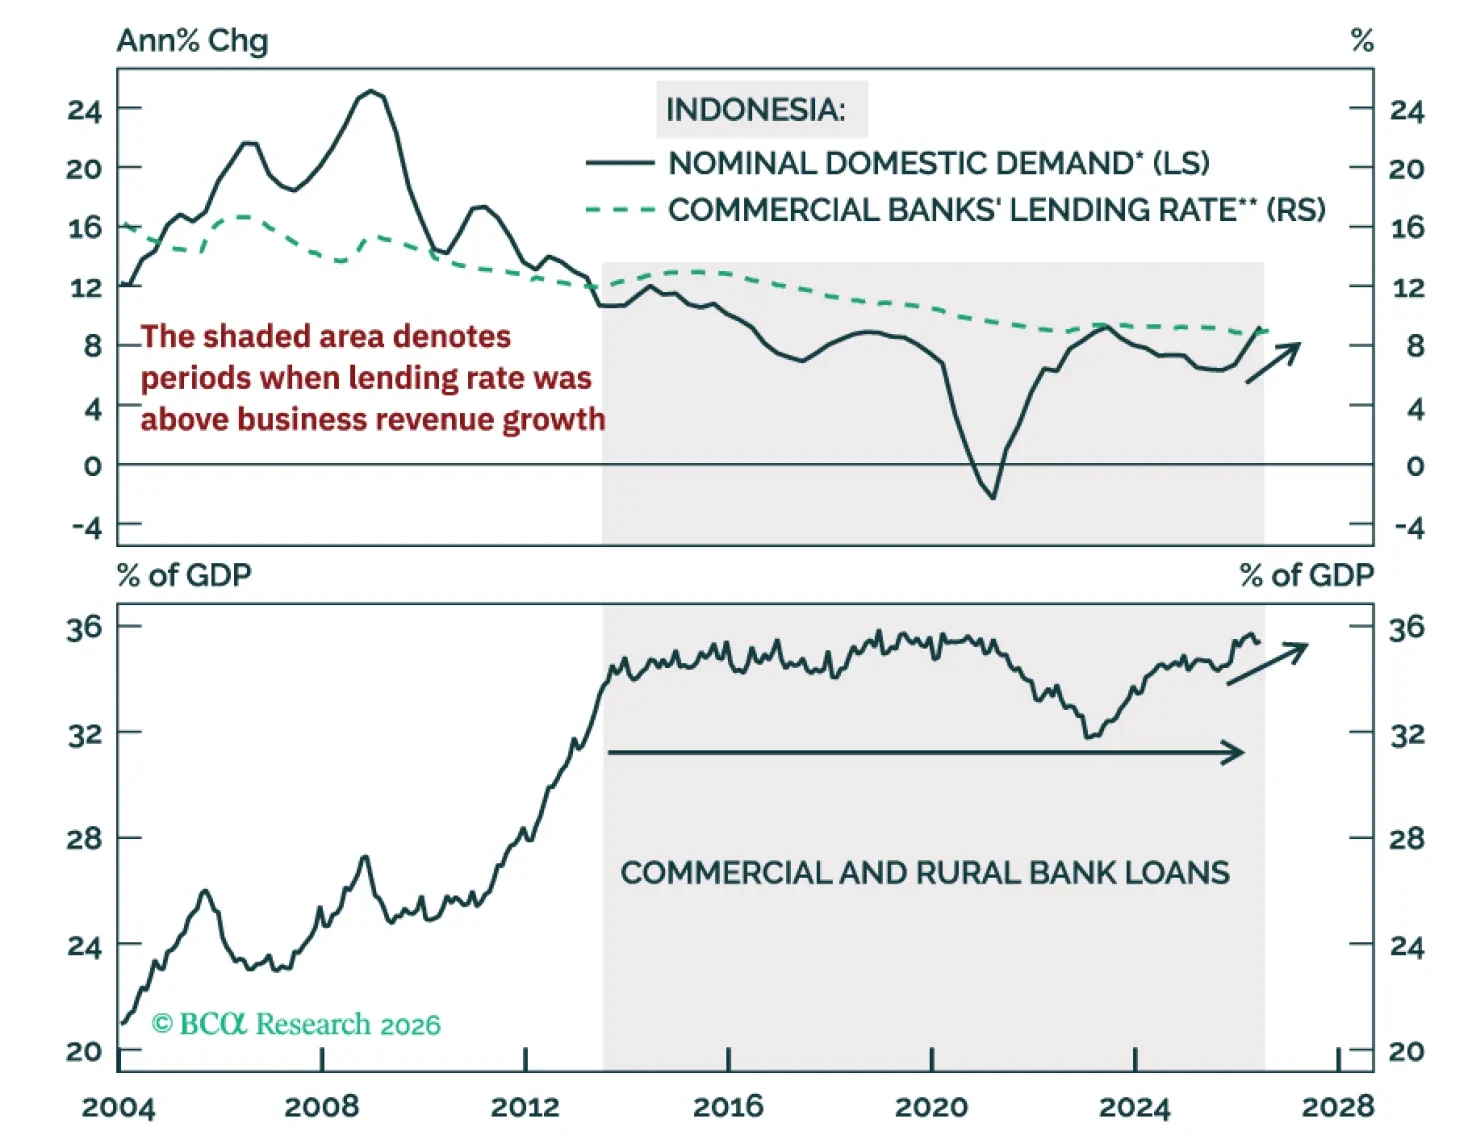
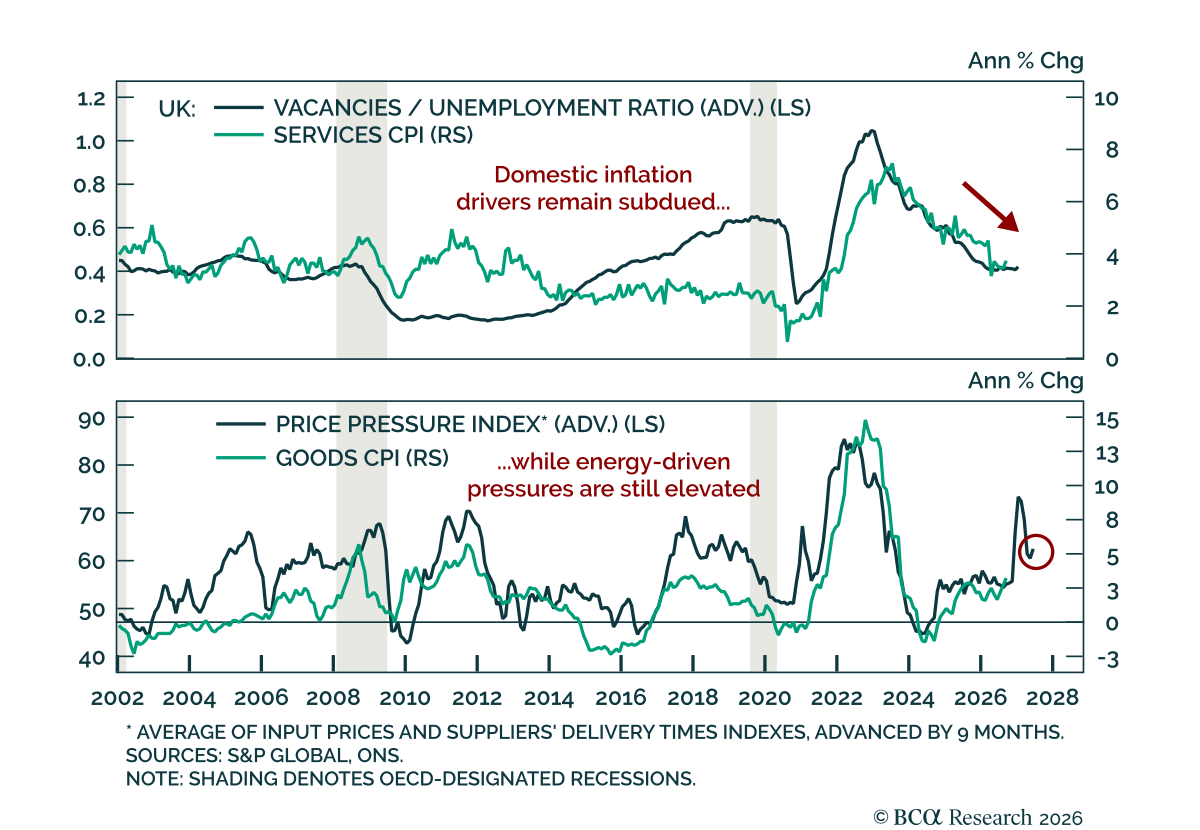
Given that the economy’s productive capacity is limited, government stimulus will lift nominal growth but do little to increase real output growth. The upshot will be rising inflation and wider twin deficits. This is bearish for the currency, bonds, and stocks.
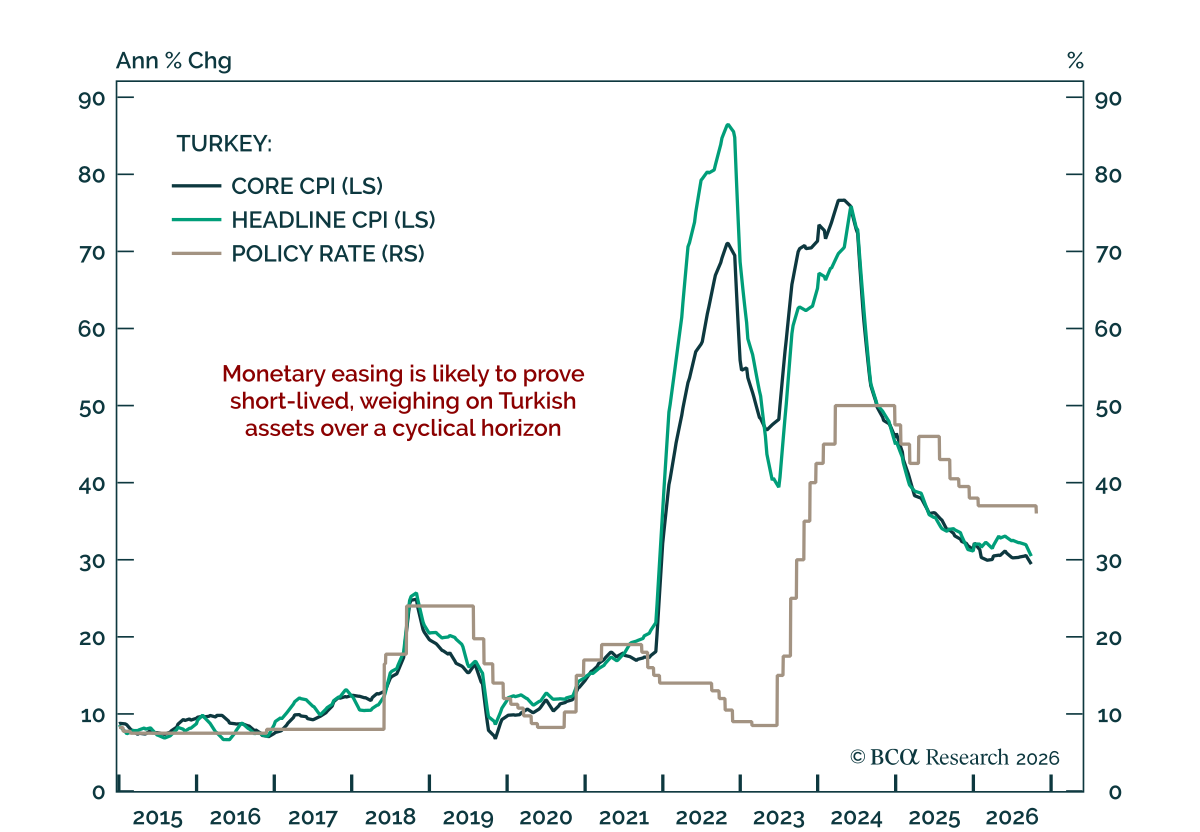
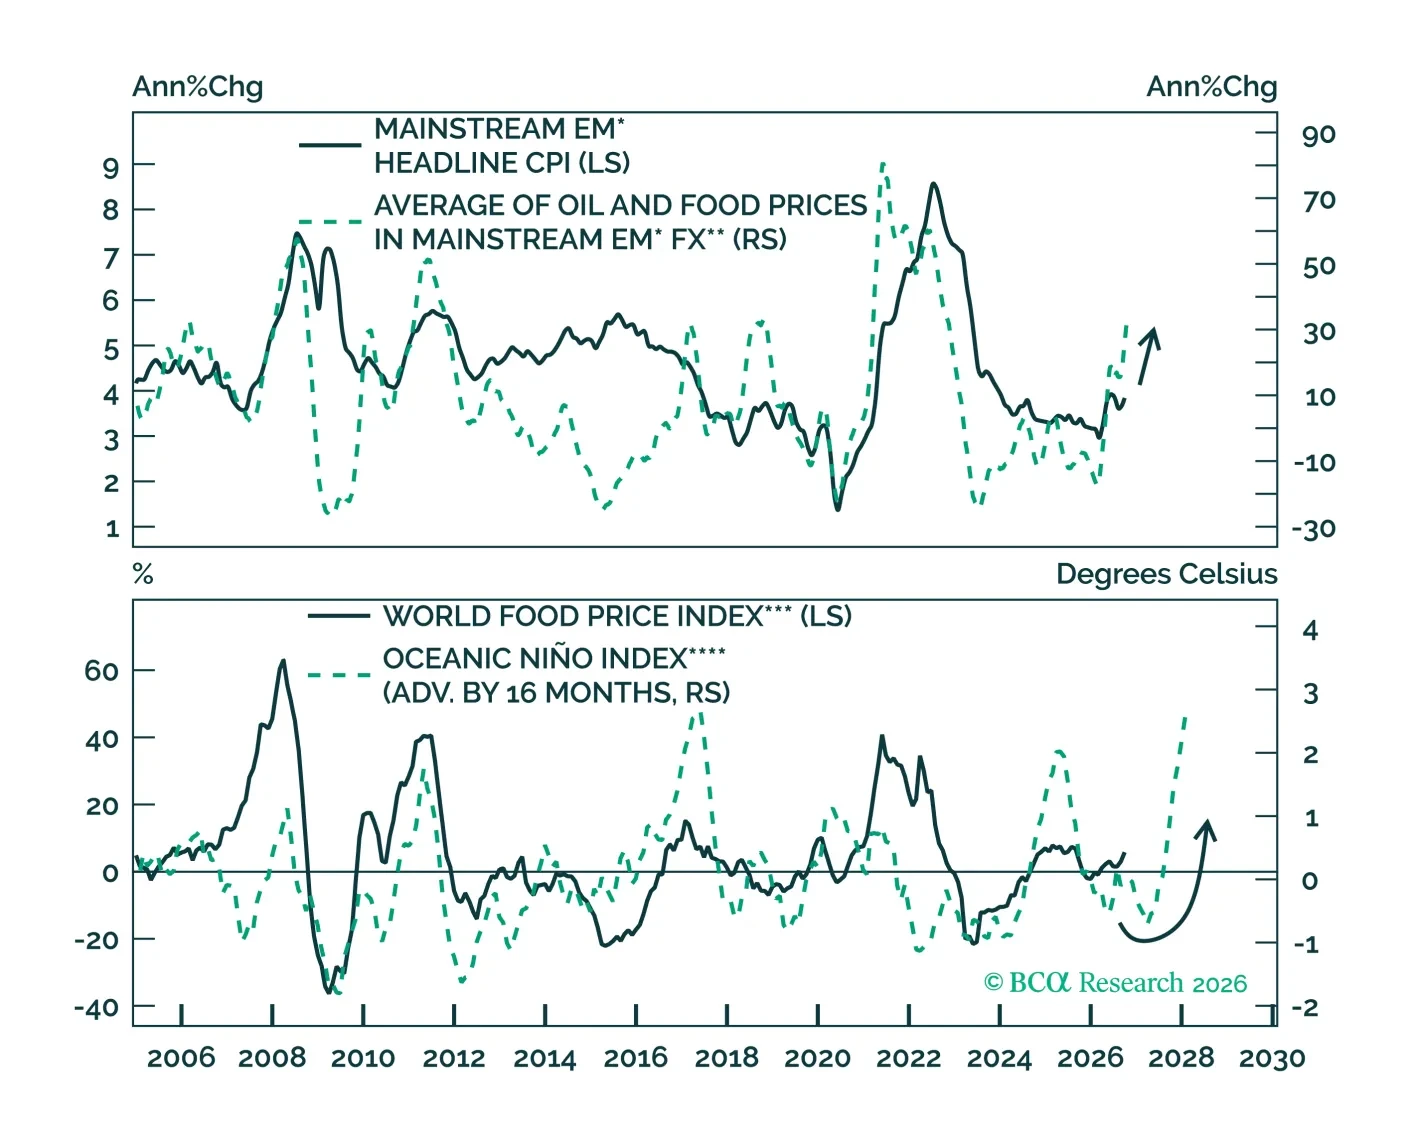
EM local bonds face near-term turbulence from rising inflation, global risk aversion, and currency weakness. Use the sell-off to build exposure: medium- and longer-term fundamentals remain favorable.