Correlations
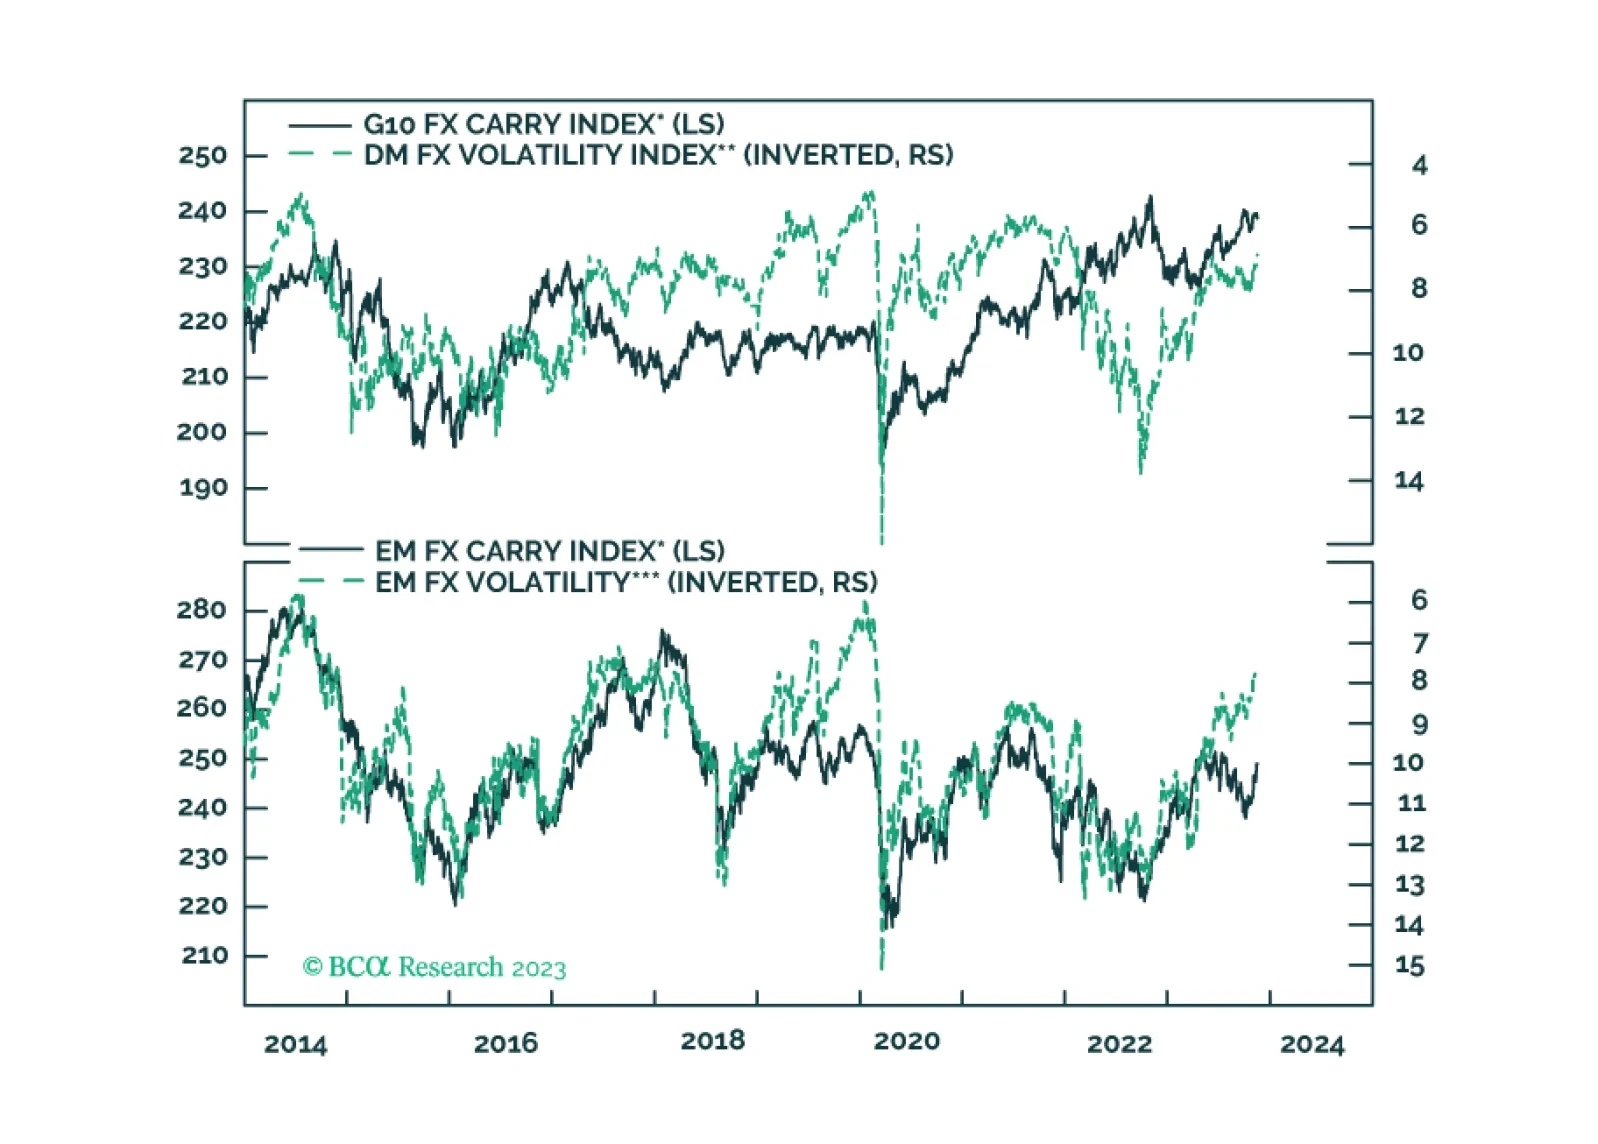
In this report, we evaluate the risk to carry trades in the coming months.

China’s reopening faltered and now it is applying moderate stimulus. OPEC 2.0’s production discipline is getting results, with oil prices climbing. The Fed will not be able to deliver dovish surprises in Q4 2023. Investors should expect stock market and commodity volatility and prefer defensive positioning.
In this report, we highlight why there are upside risks to Brent crude oil and copper prices going into 2024, with the production side expected to drive deficits in these markets. To take advantage of a potential rally, we suggest basket plays for hedging this outcome.
Carbon credits as an asset class are becoming increasingly investable. Given that the structural bull case for this asset class is compelling, strategic investors should long carbon credits. However tactical investors should book profits or consider merits of a short position, since prices are likely to correct over the next 12-24 months.
A global portfolio is likely to return only 5.3% a year over the next decade, compared to 6.7% in the past. Investors either need to lower their return expectations, or take more risk. Our total return methodology remains consistent with previous editions, with changes limited to the Alternatives section.
