Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Fixed Income

Our Portfolio Allocation Summary for September 2026.

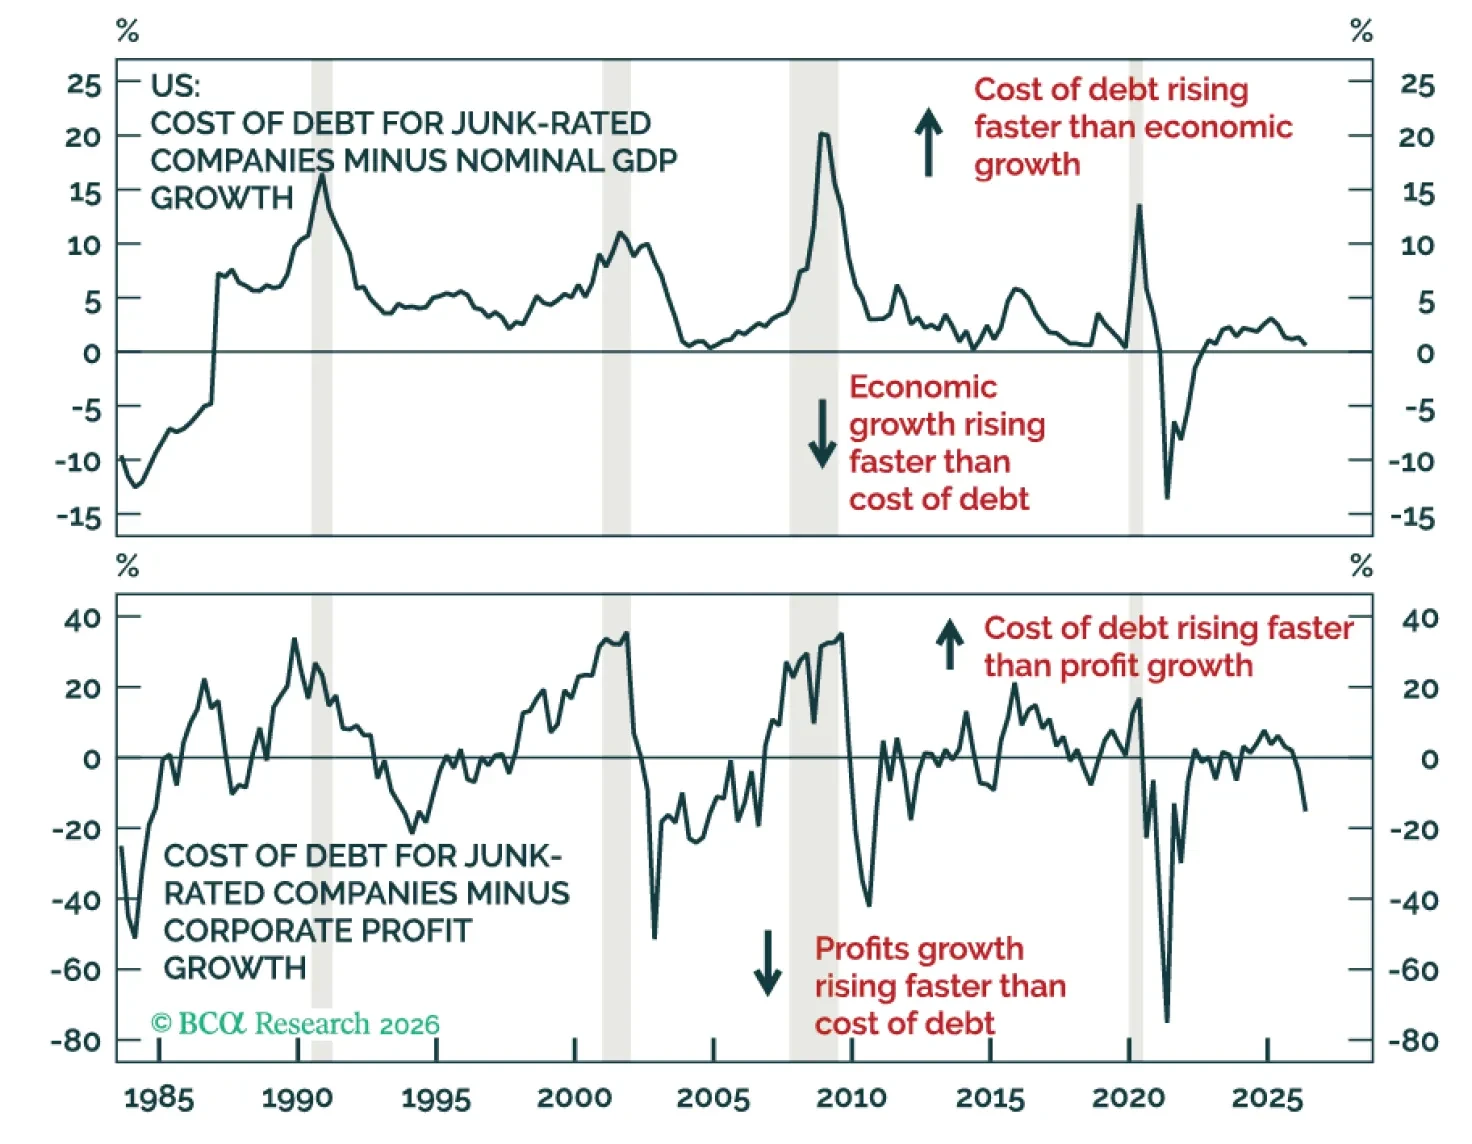
Investors overestimate the threat current interest rate levels pose to both equities and the economy. Despite a rising long end, the gap between high-yield borrowing costs and both nominal growth and corporate profits is at five-year lows and falling. Remain overweight equities. Within Fixed Income, Upgrade High Yield and Downgrade Government Bonds and EM Debt. Downgrade Chinese Equities to Neutral.
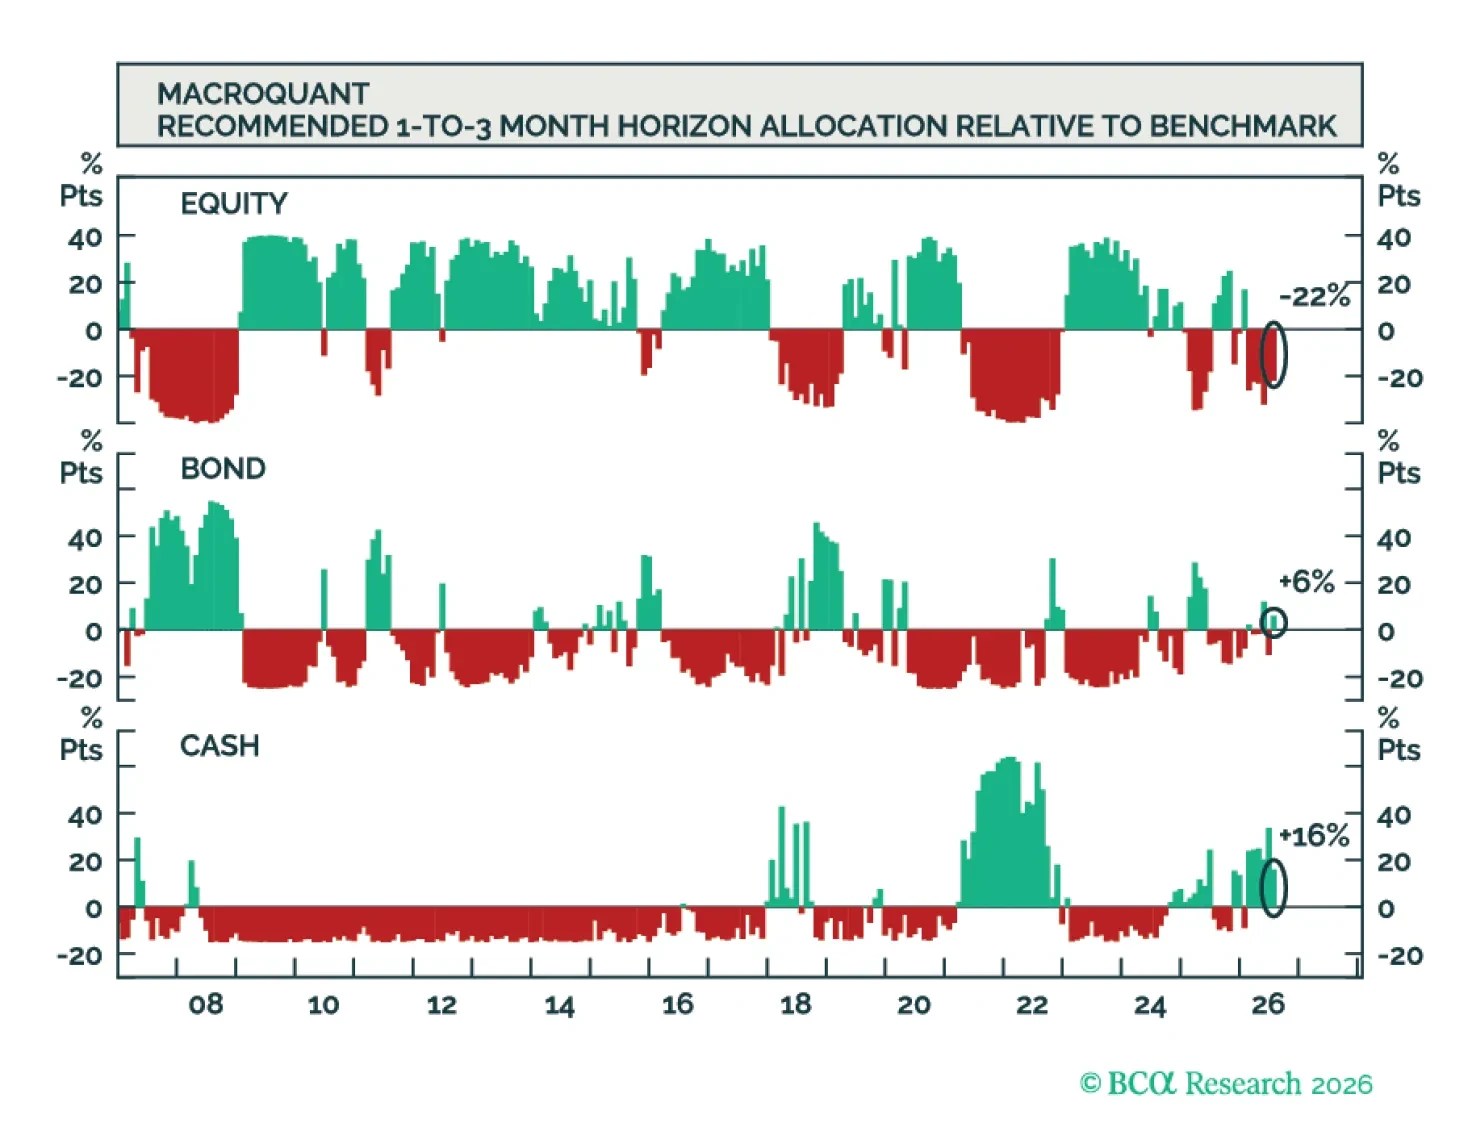
MacroQuant recommends a slight underweight position in equities, counterbalanced by a slight overweight to bonds, and a significant overweight to cash. The model is positive on the US dollar, modestly negative on gold, and bullish on copper and oil.
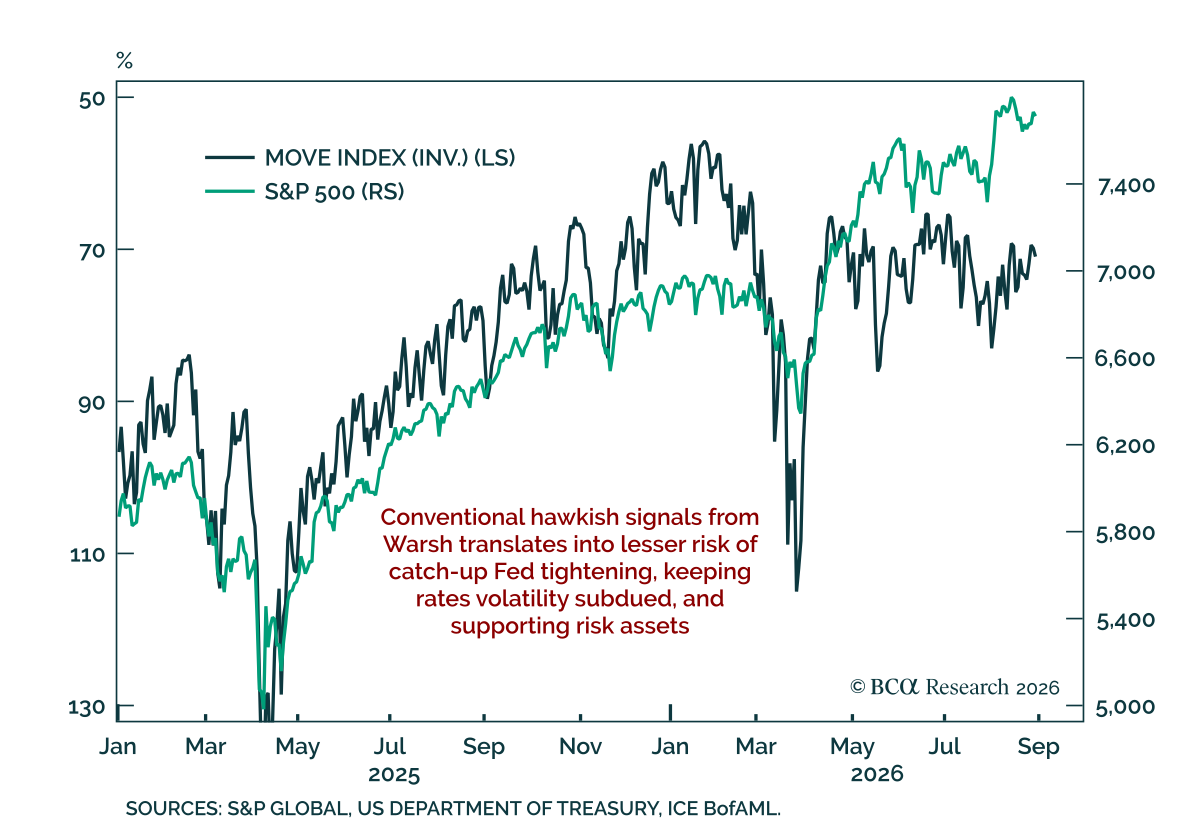
The level of yields matters less for equities than how quickly rates move, making implied rates volatility the more useful gauge of equity risk. Stocks have delivered positive returns across different rate regimes, with both rising and falling yields. The key…

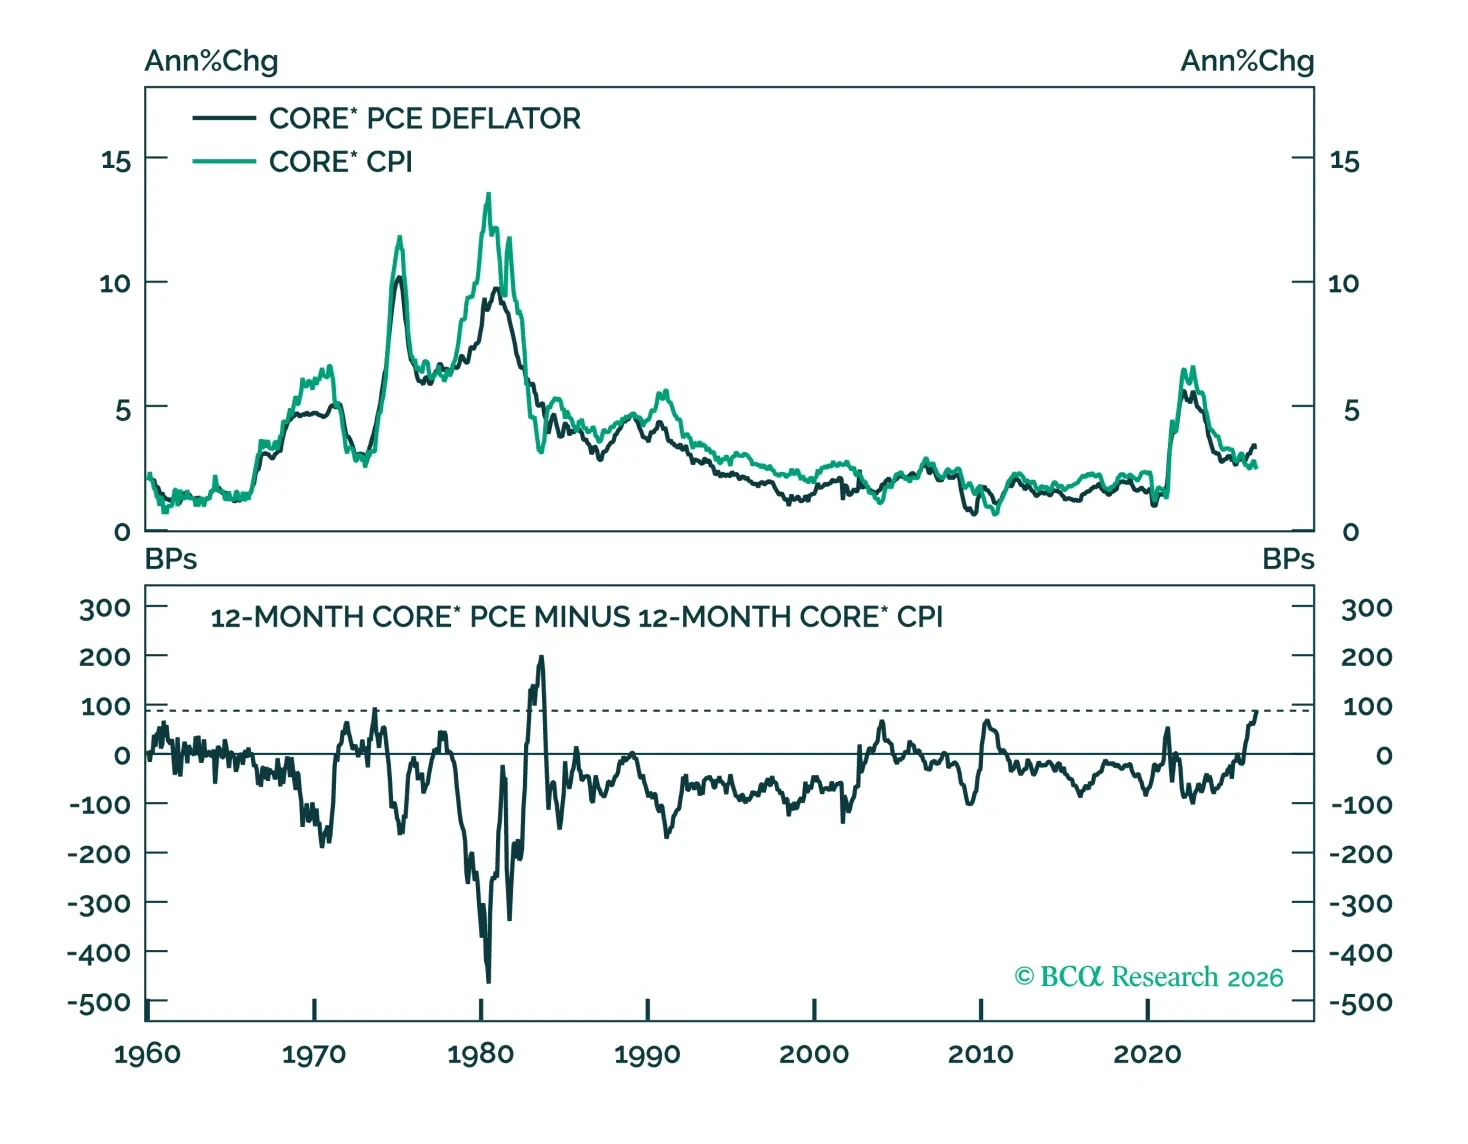
The PCE/CPI gap is an increasingly important factor driving the near-term outlook for Fed policy. We discuss the drivers of that gap and conclude that it’s likely to narrow in the coming months.
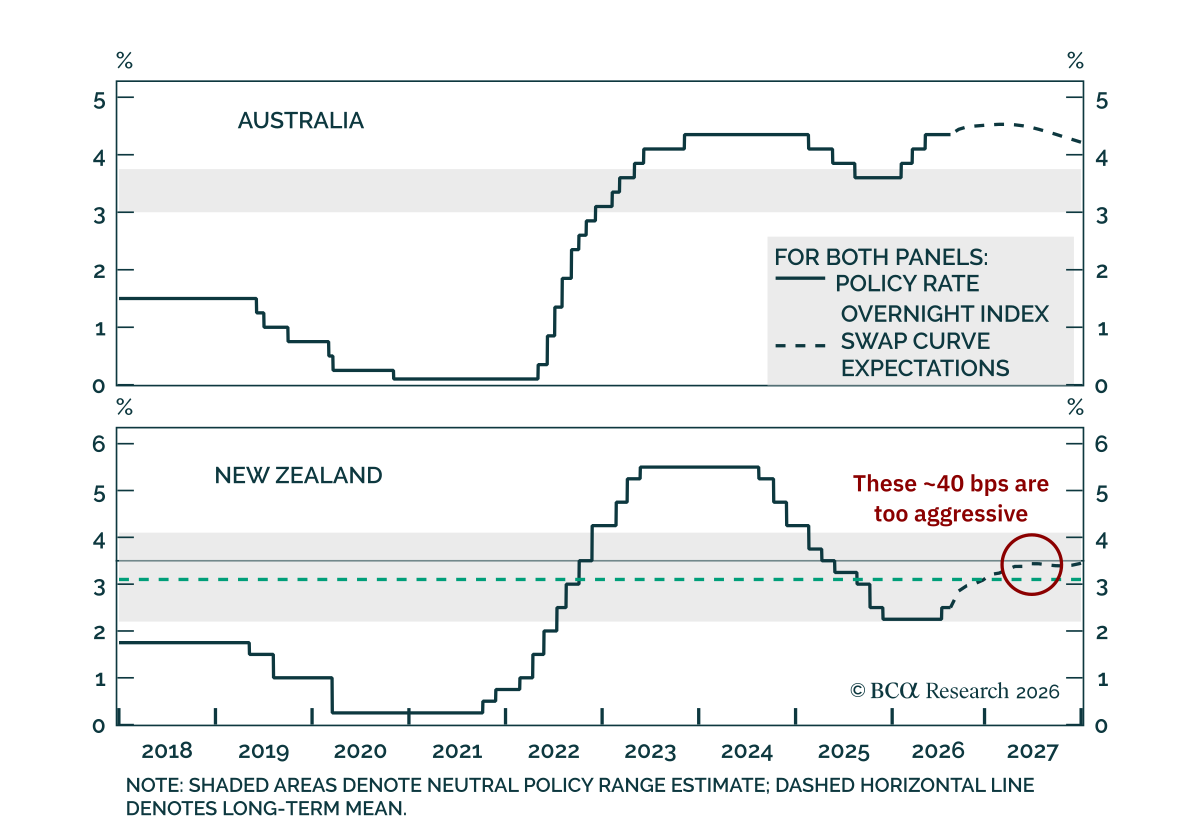
 

Our FICC strategists remain neutral on Australian government bonds, upgrade New Zealand government bonds to overweight, and recommend long AUD/NZD. Housing is becoming a disinflationary force in both economies, though for different reasons. Australian house…
The global bond selloff strengthens the case for underweighting French OATs, as France’s fiscal vulnerability is increasingly showing up in sovereign spreads. French 10-year yields rose to 4.13% on Friday, the highest since 2008, with the OAT-Bund spread…

The US Treasury department’s attempts at yield suppression are doomed to fail unless the Federal Reserve gets involved.
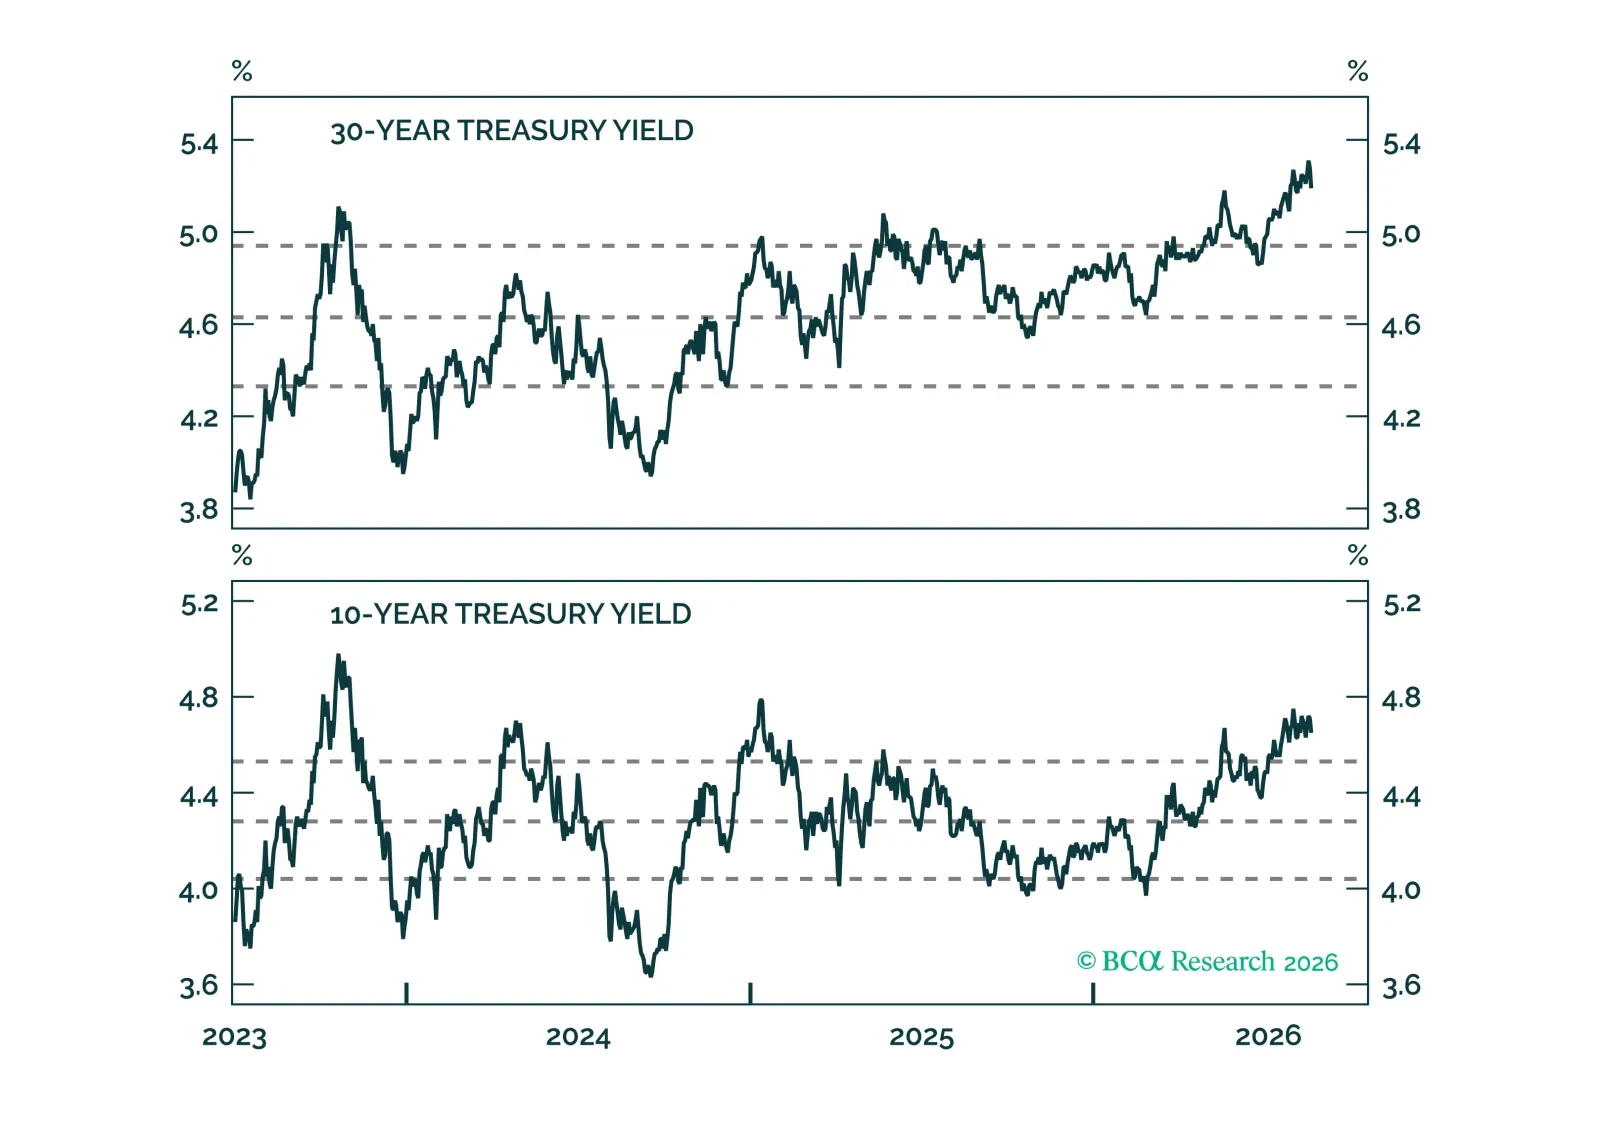
Despite recent increases, long-maturity Treasury yields are roughly consistent with fundamental fair value. We see limited value in long duration plays.
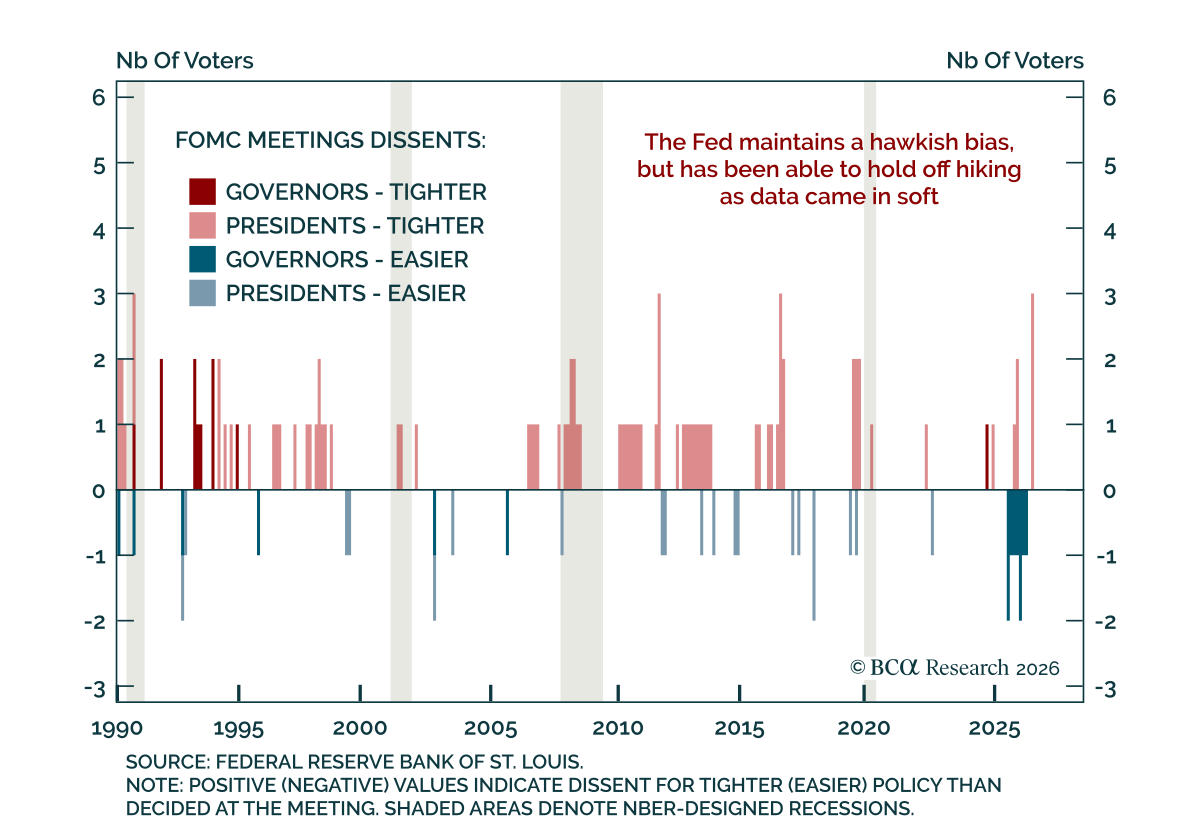
The July Fed minutes showed a broader hawkish bias than the vote suggested, but softer data since the meeting have reduced the urgency to hike. The FOMC held rates at 3.5%-3.75% despite three dissents in favor of a 25 bps hike. The minutes revealed support…