Business Cycles

Chinese exports in USD terms missed expectations in July, growing by 7.0% y/y, down from 8.6% in June. Conversely, imports rebounded smartly from a 2.3% contraction, rising by 7.2% in July and upending expectations of 3.2%. Slower export growth is symptomatic…
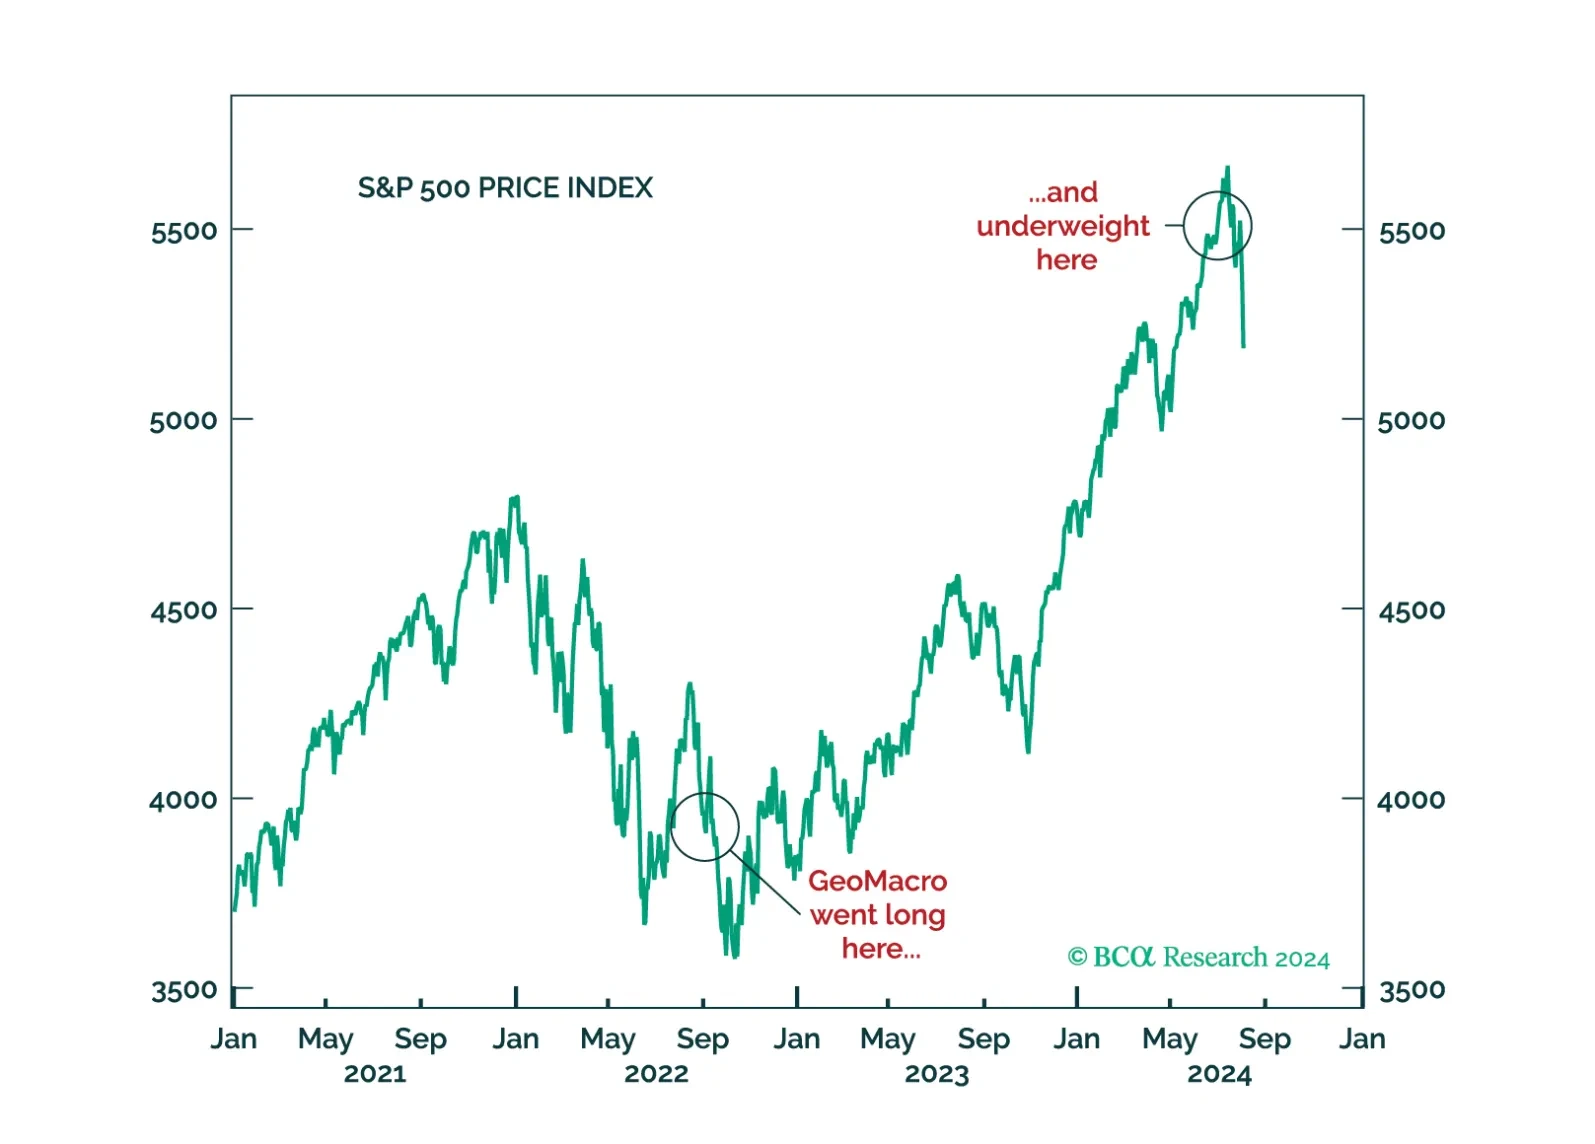
The decision by GeoMacro team on July 2 to short USDJPY and underweight equities has proven to be prescient. We still do not like the market setup from here on out. A recession would, obviously, be negative for risk assets. But even if investors avoid that scenario, the transition from cash- to leverage-driven growth is unlikely without a significant Fed rate-cutting cycle.
The ISM services PMI surprised positively in July. The headline index expanded 2.6 ppts to 51.4, reversing May’s fastest pace of contraction in four years. Notably, the business activity subcomponent increased 4.9 ppts to 54.5, new orders and new export…
July nonfarm payrolls expanded by 114 thousand workers, a sharp slowdown from June’s downwardly revised 179 thousand, and significantly disappointing expectations of 175 thousand. The unemployment rate unexpectedly edged 0.2ppt higher to 4.3% in July, rising…
A decisive risk-off mood dominated markets at the end of last week, amid disappointing payrolls, tech earnings and manufacturing PMIs. The Nasdaq and other tech-heavy stock markets such as Japan, Korea and Taiwan led the equity declines. Other pro-cyclical…
According to BCA Research’s Commodity & Energy Strategy service, robust iron ore imports are sending a false signal about steel demand. Instead, these supplies are being used to restock inventories. By the end of last year, iron ore stocks at Chinese ports…
Sweden’s manufacturing PMI started contracting in July, plummeting from 53 to 49.2, falling far short of expectations that growth would broaden. Weakness was broad-based. Notably, new orders and new export orders plunged a whopping 15.1 and 8.7 points in…
No clear risk-on/risk-off pattern emerged from July’s market performance data. On the one hand, consistent with a risk-off environment, US bonds ranked highest in the monthly return distribution, while pro-cyclical industrial metals and oil lagged. However,…
According to BCA Research’s Global Asset Allocation service, there are clear signs that growth is weakening. BCA’s Global Nowcast has been slowing for three months. Behind this slowdown is the fact that the US consumer – the biggest factor keeping growth…
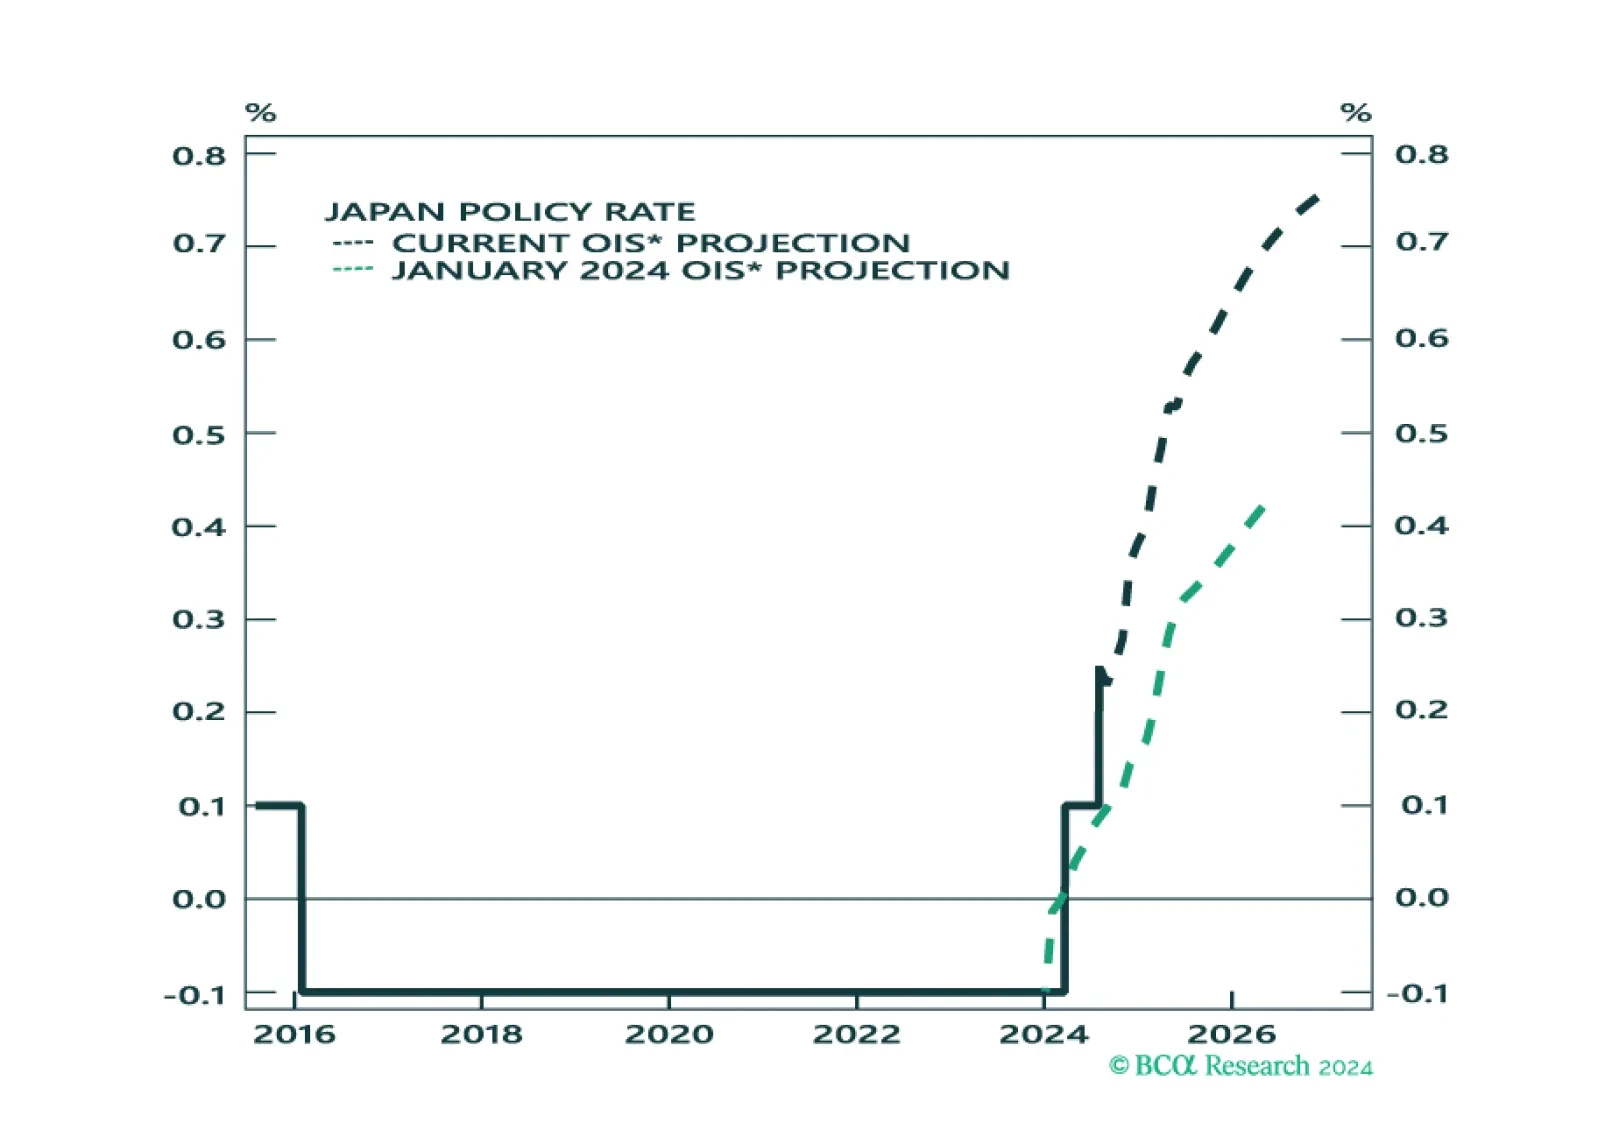
We assess the investment implications of the BoJ and Fed meetings, and give our take on the next policy moves. We also assess the impact on asset markets.