Latest from BCA Research
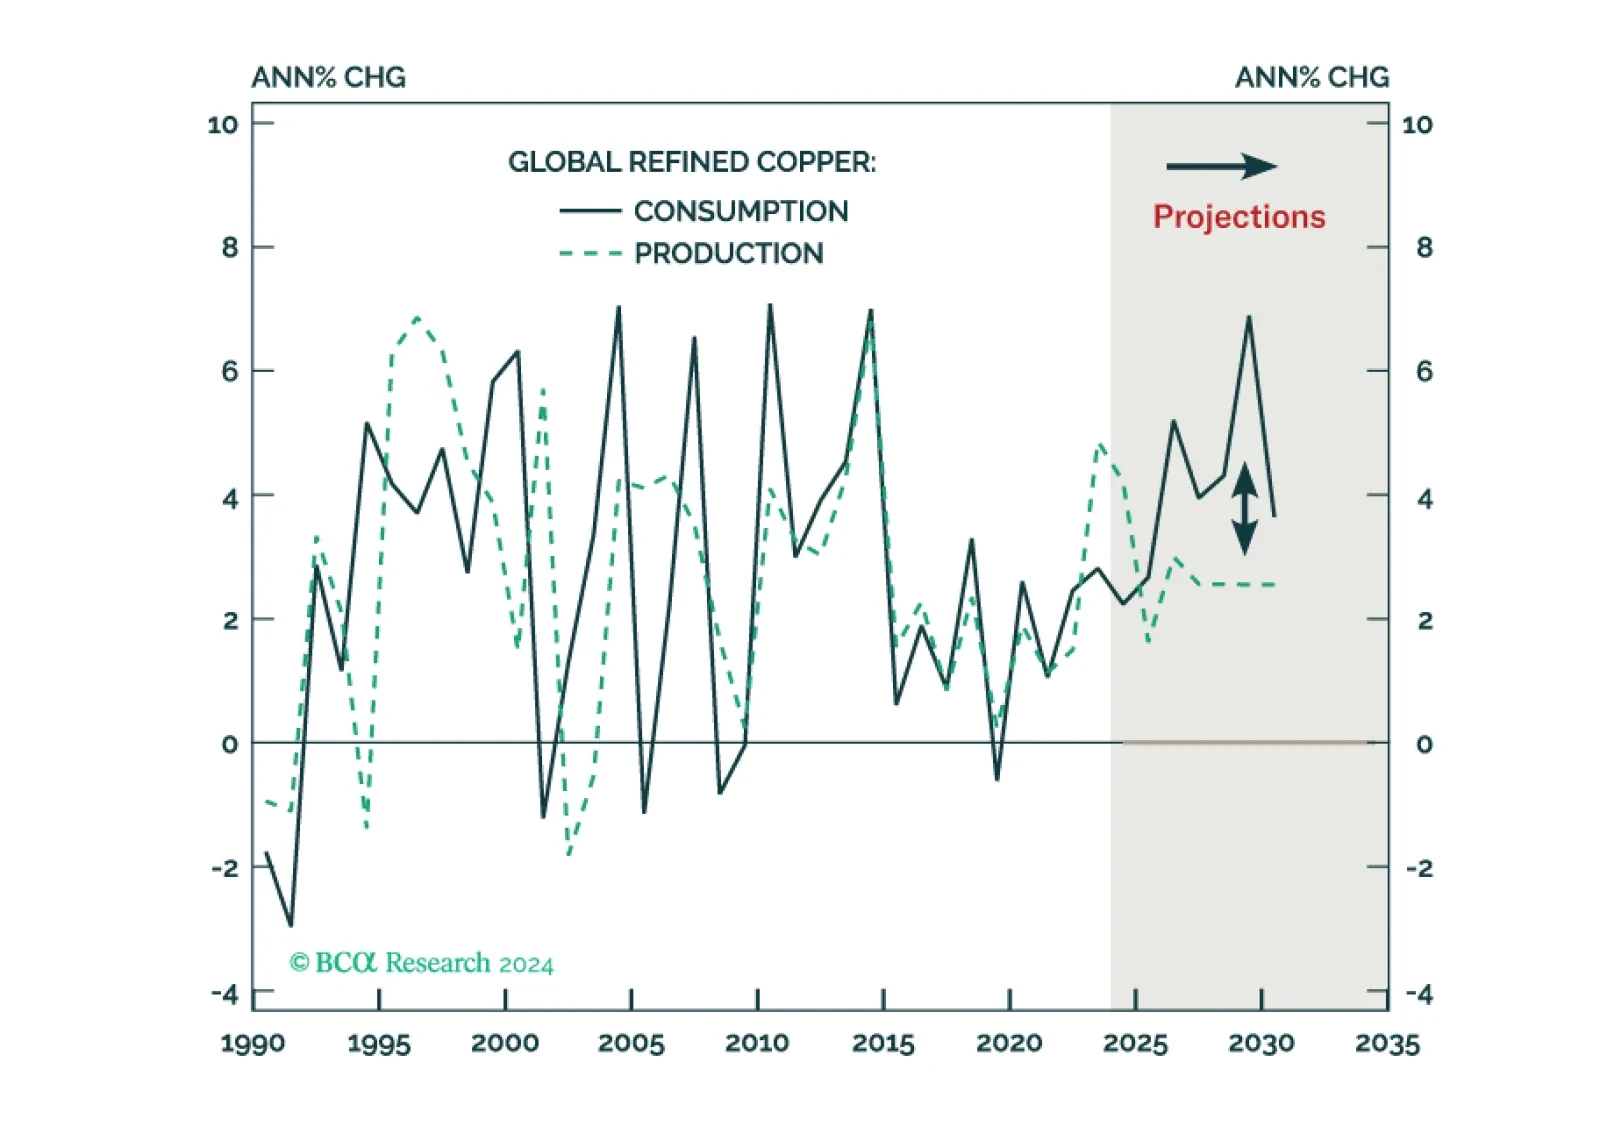
The force of the post-election momentum leads us to believe we could be stopped out of our defensive positioning before the week is out, but we still believe in our recession call. If we are eventually stopped out, we will seek a more opportune entry point to bet against risk assets once the election fever runs its course.
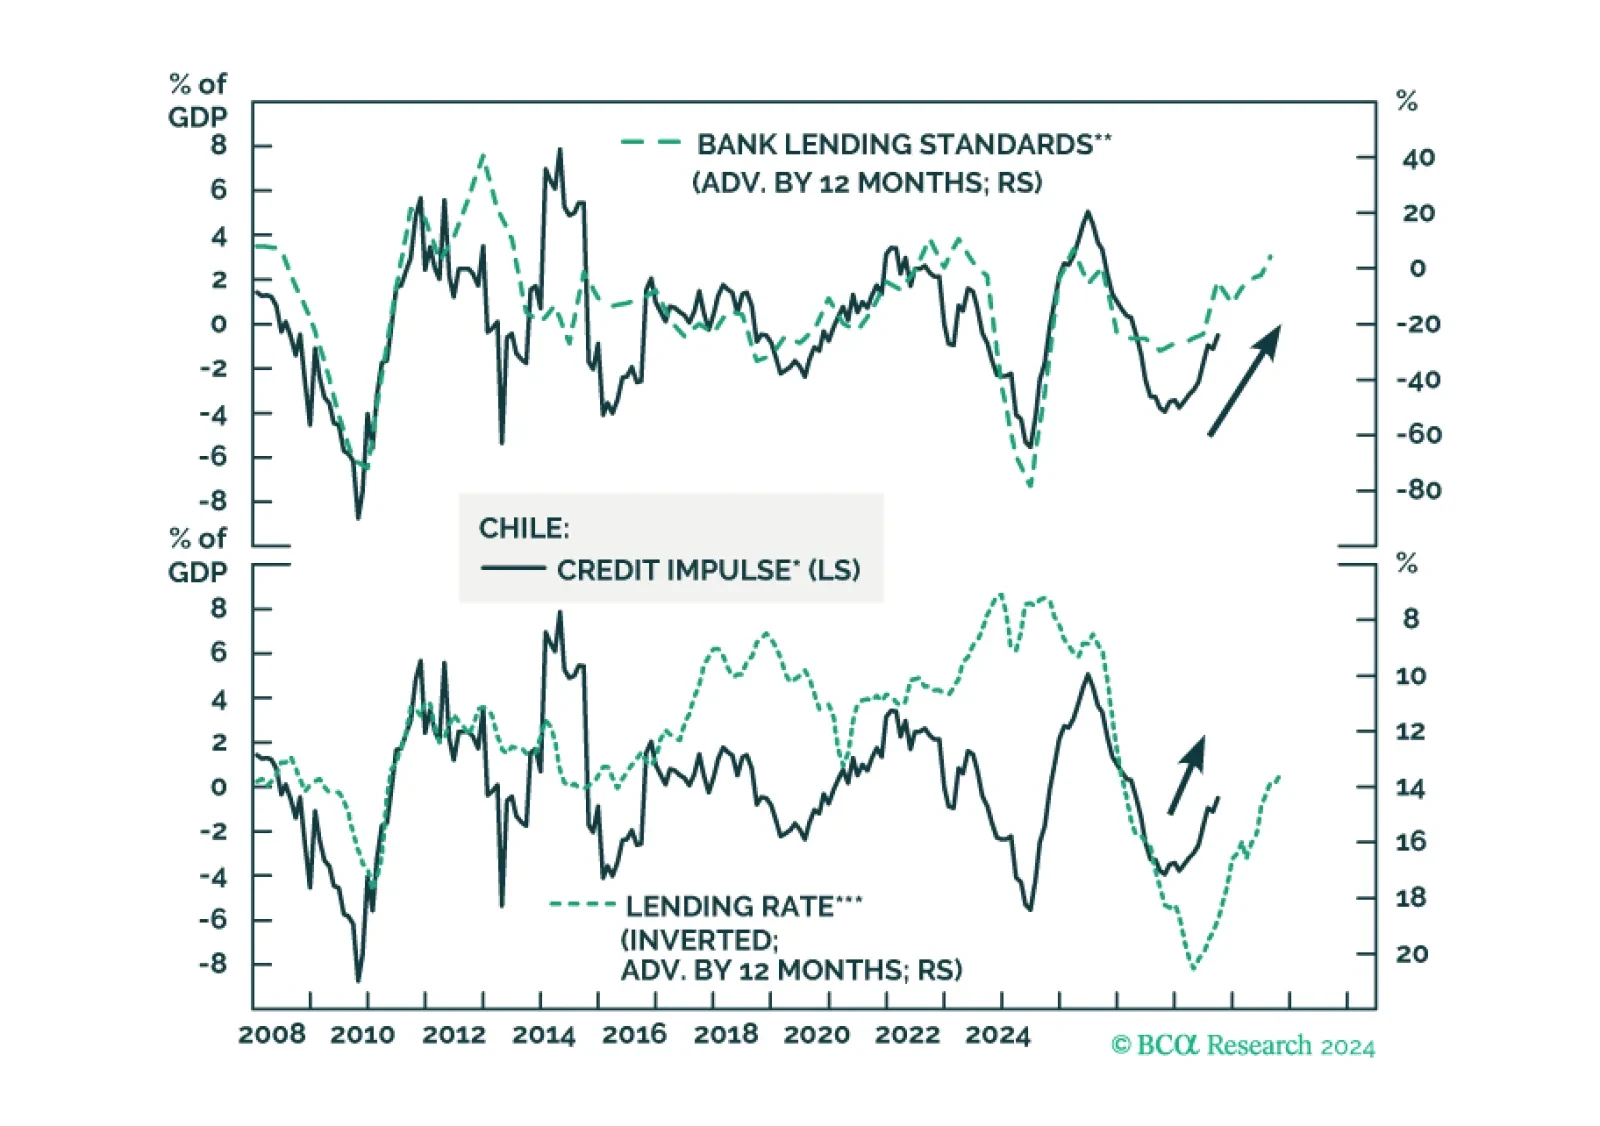
In absolute terms, Chilean markets and the currency will fall given a strengthening trend in the US dollar and weak global trade. However, Chile’s economy can withstand the global trade slump relatively well due to substantial monetary easing at home, which will help Chilean markets outperform EM peers. Moreover, a favorable and improving political backdrop and attractive valuations will benefit Chilean equities and the peso versus their EM counterparts.
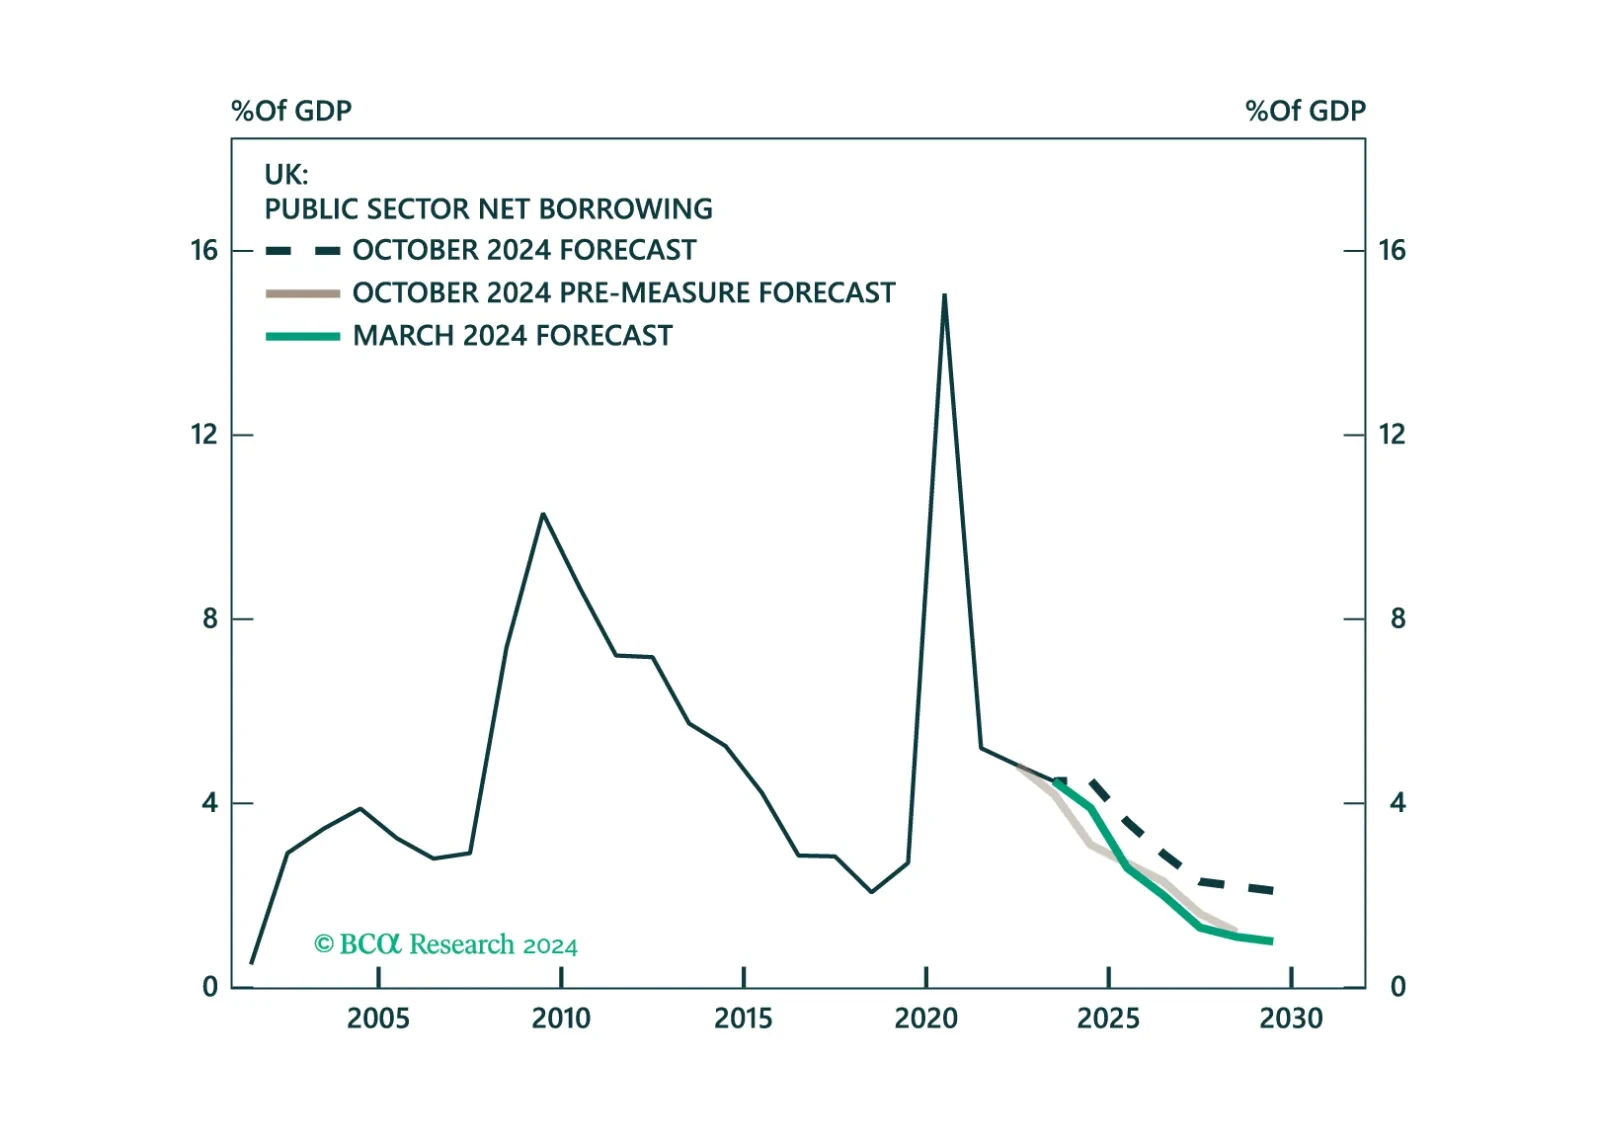
This Strategy Insight presents our view on today’s rate cut by the Bank of England as well as the budget announced by the UK government last week.
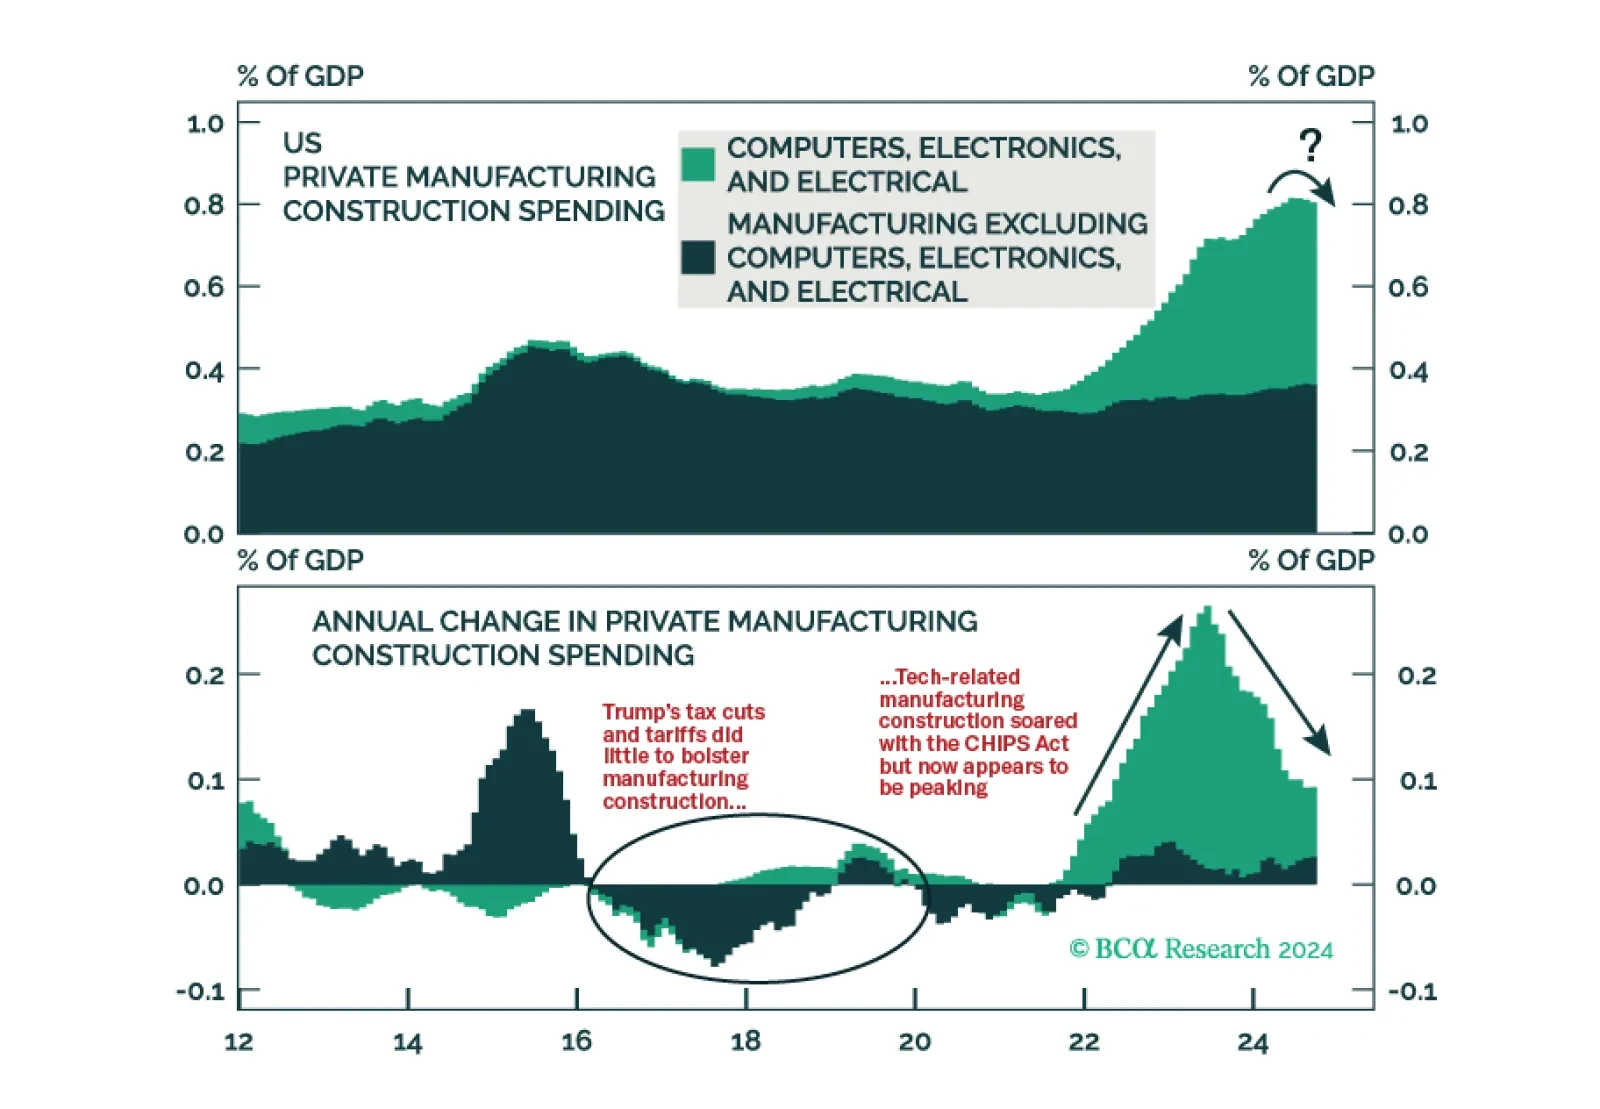
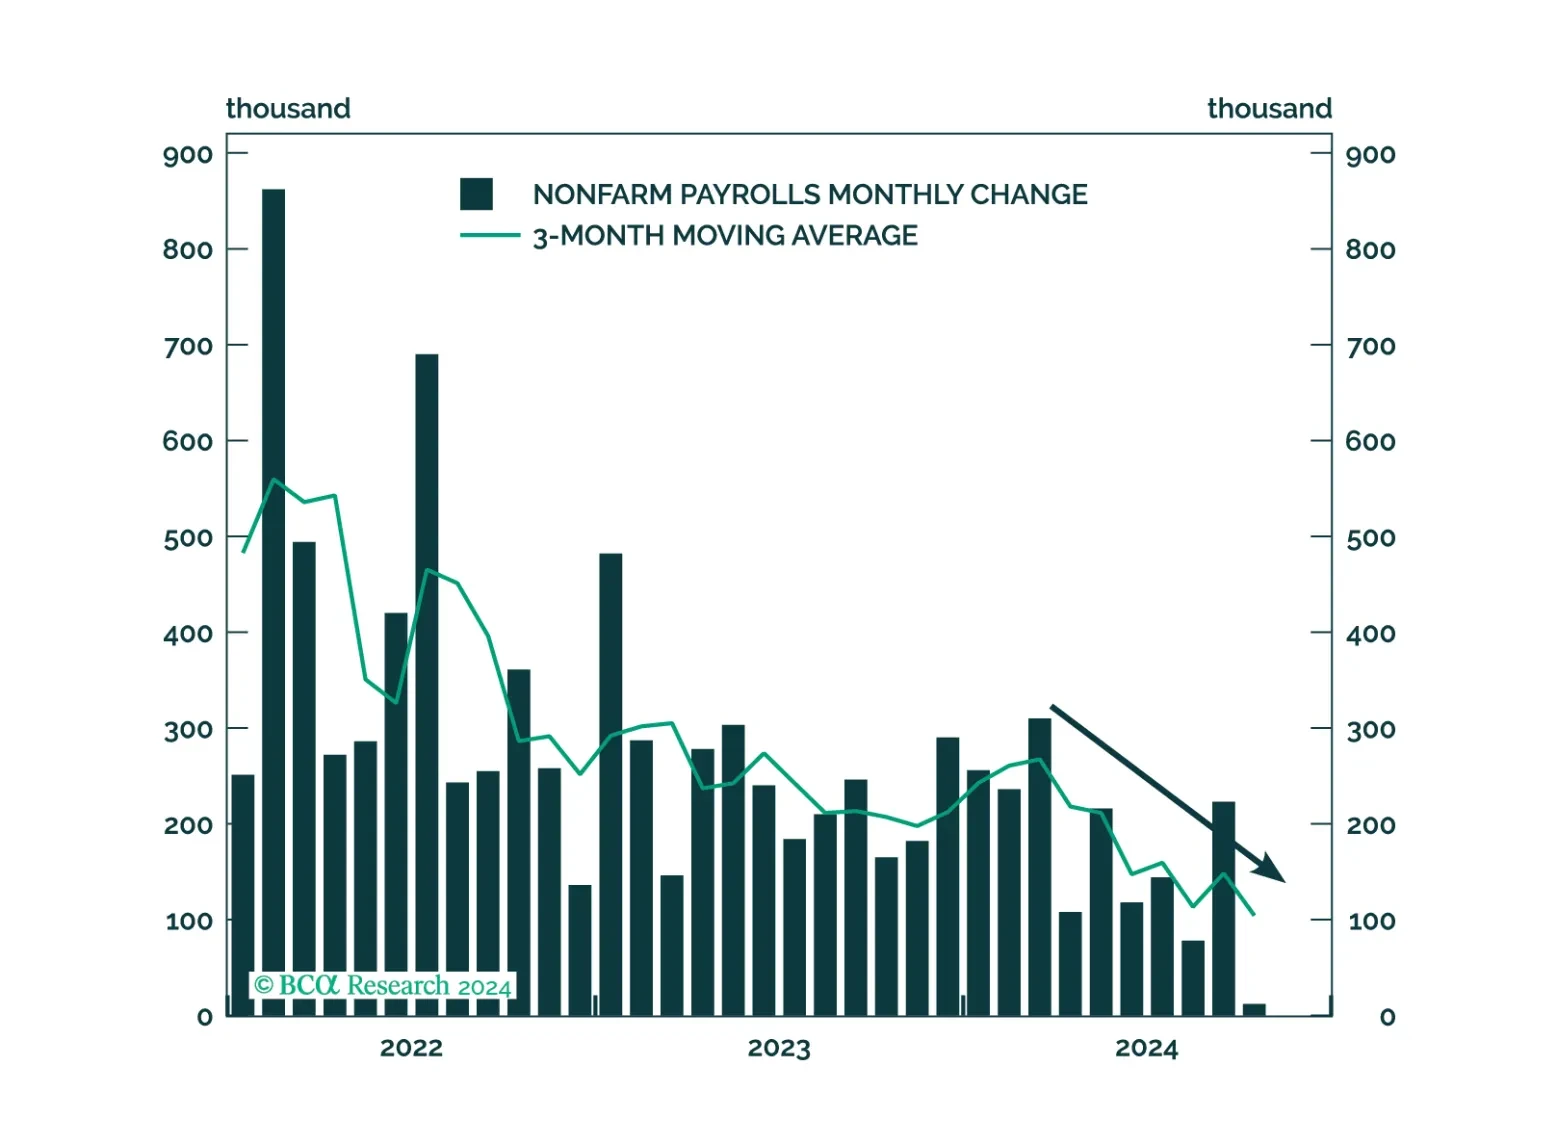
The prospect of a new trade war more than offsets the other pro-business parts of Trump’s agenda. With the labor market already weakening going into the election, we are raising our 12-month US recession probability from 65% to 75%.

Our thoughts on the bond market’s reaction to the election and this afternoon’s FOMC meeting.
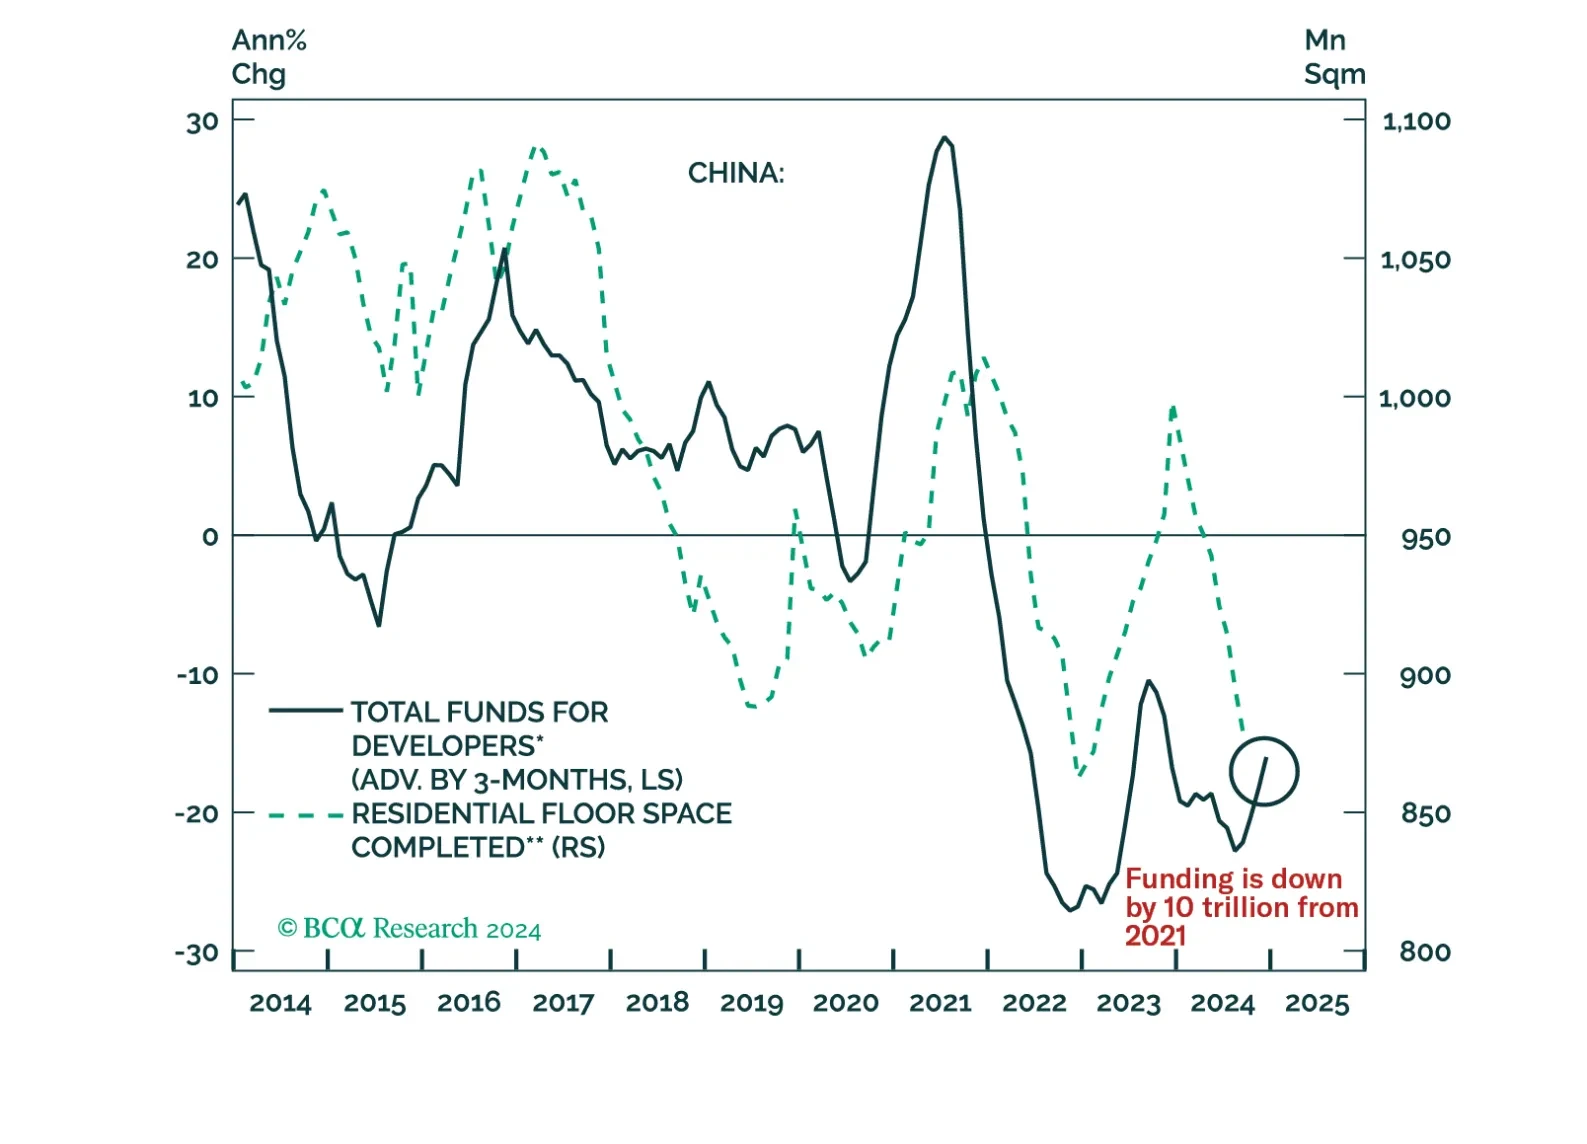
We spent last week visiting our clients in China. In this report, we share some of the key questions from the client meetings as well as our responses.
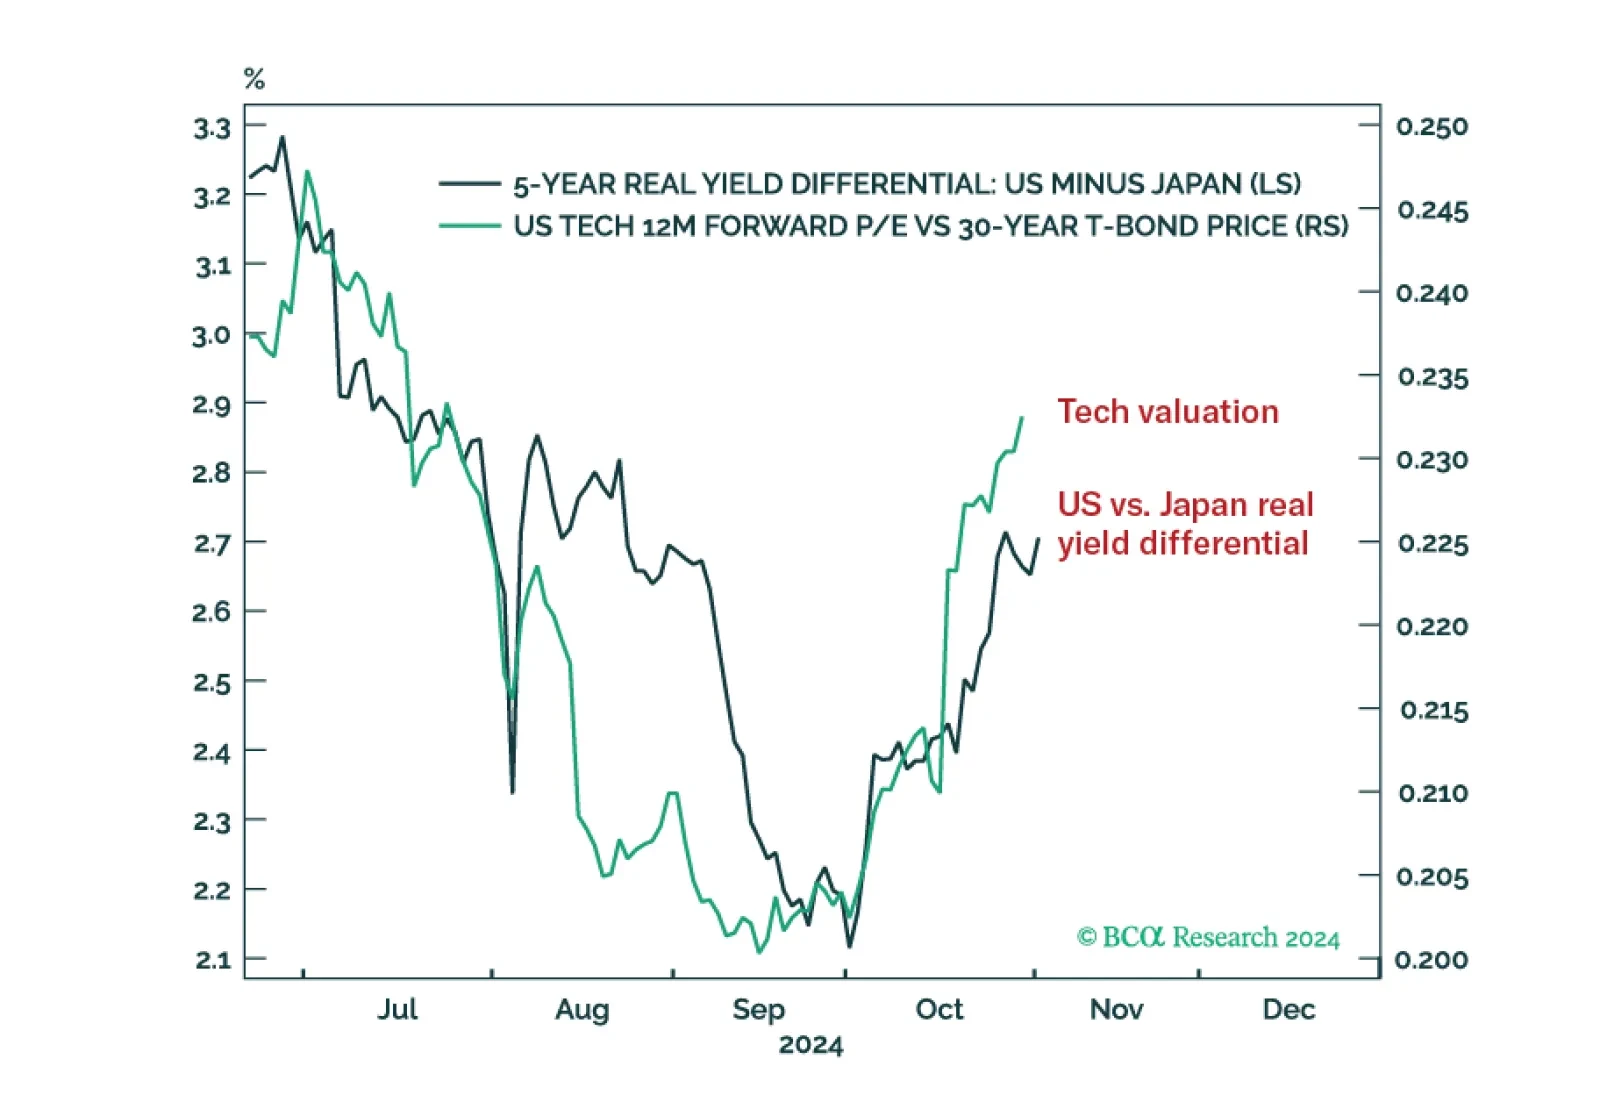
The most important transmission mechanism of a Trump presidency on the stock market will be via its impact on the US-Japan real yield differential. This is because Japan’s extreme negative real yield versus the US is the dominant source of global liquidity right now, and thereby the main driver of stock market valuation. In the short term therefore, higher US bond yields mean higher stock prices. The longer-term implications are more concerning though.
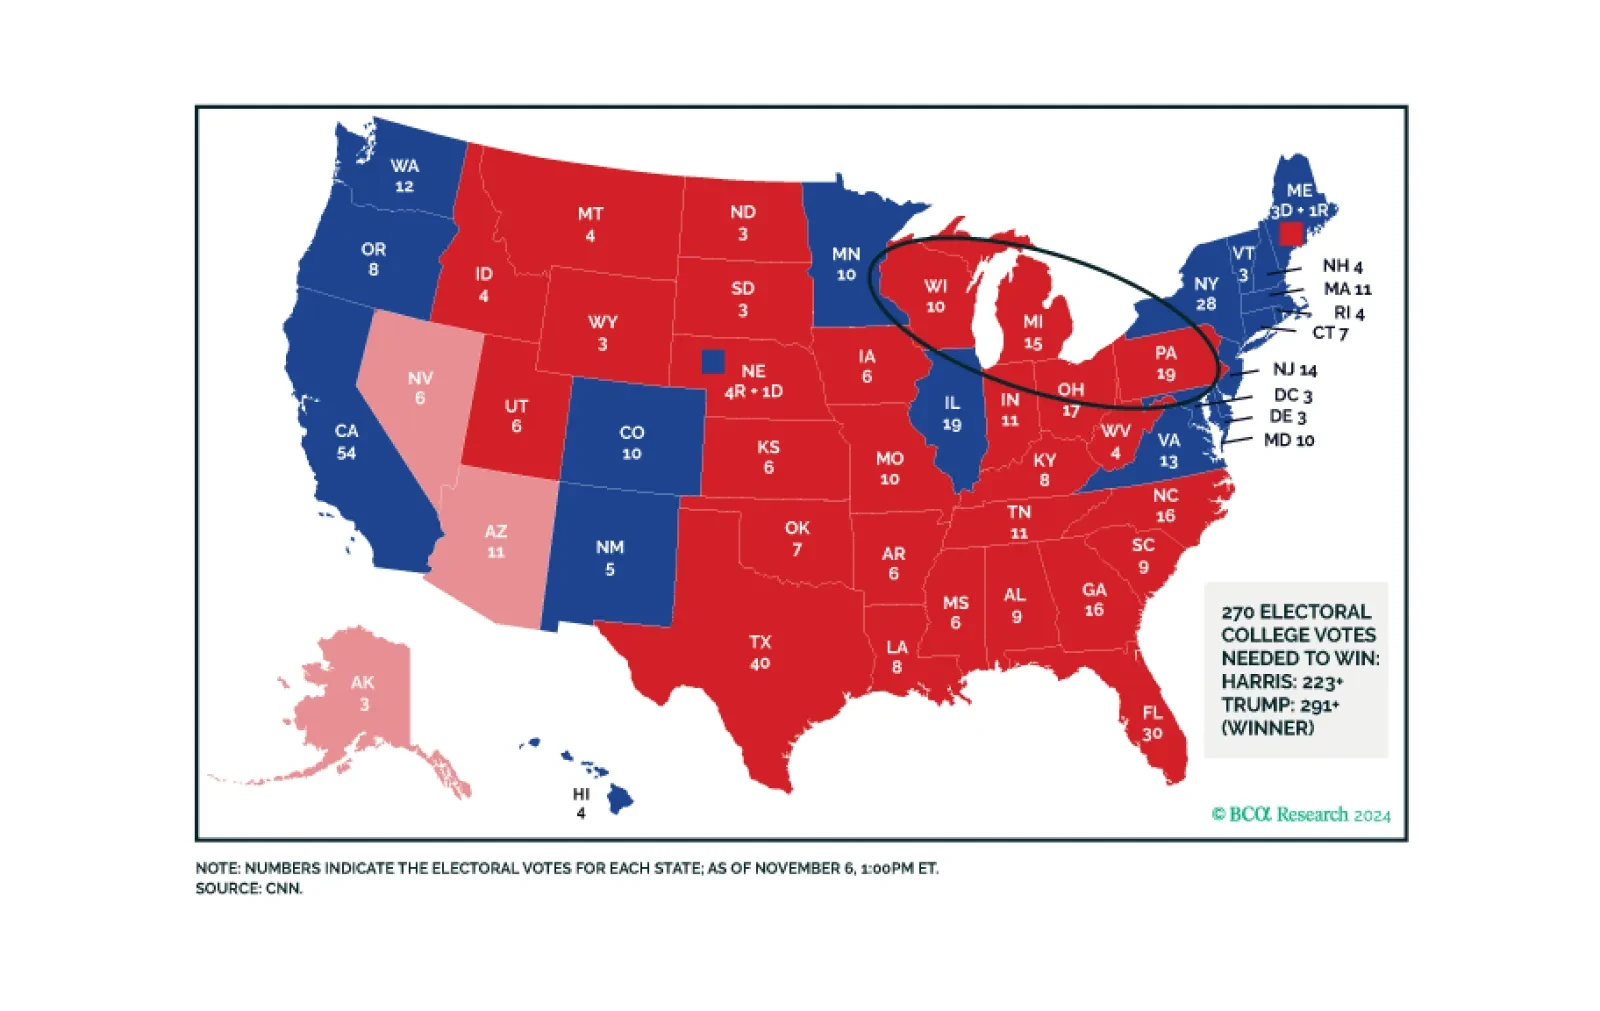
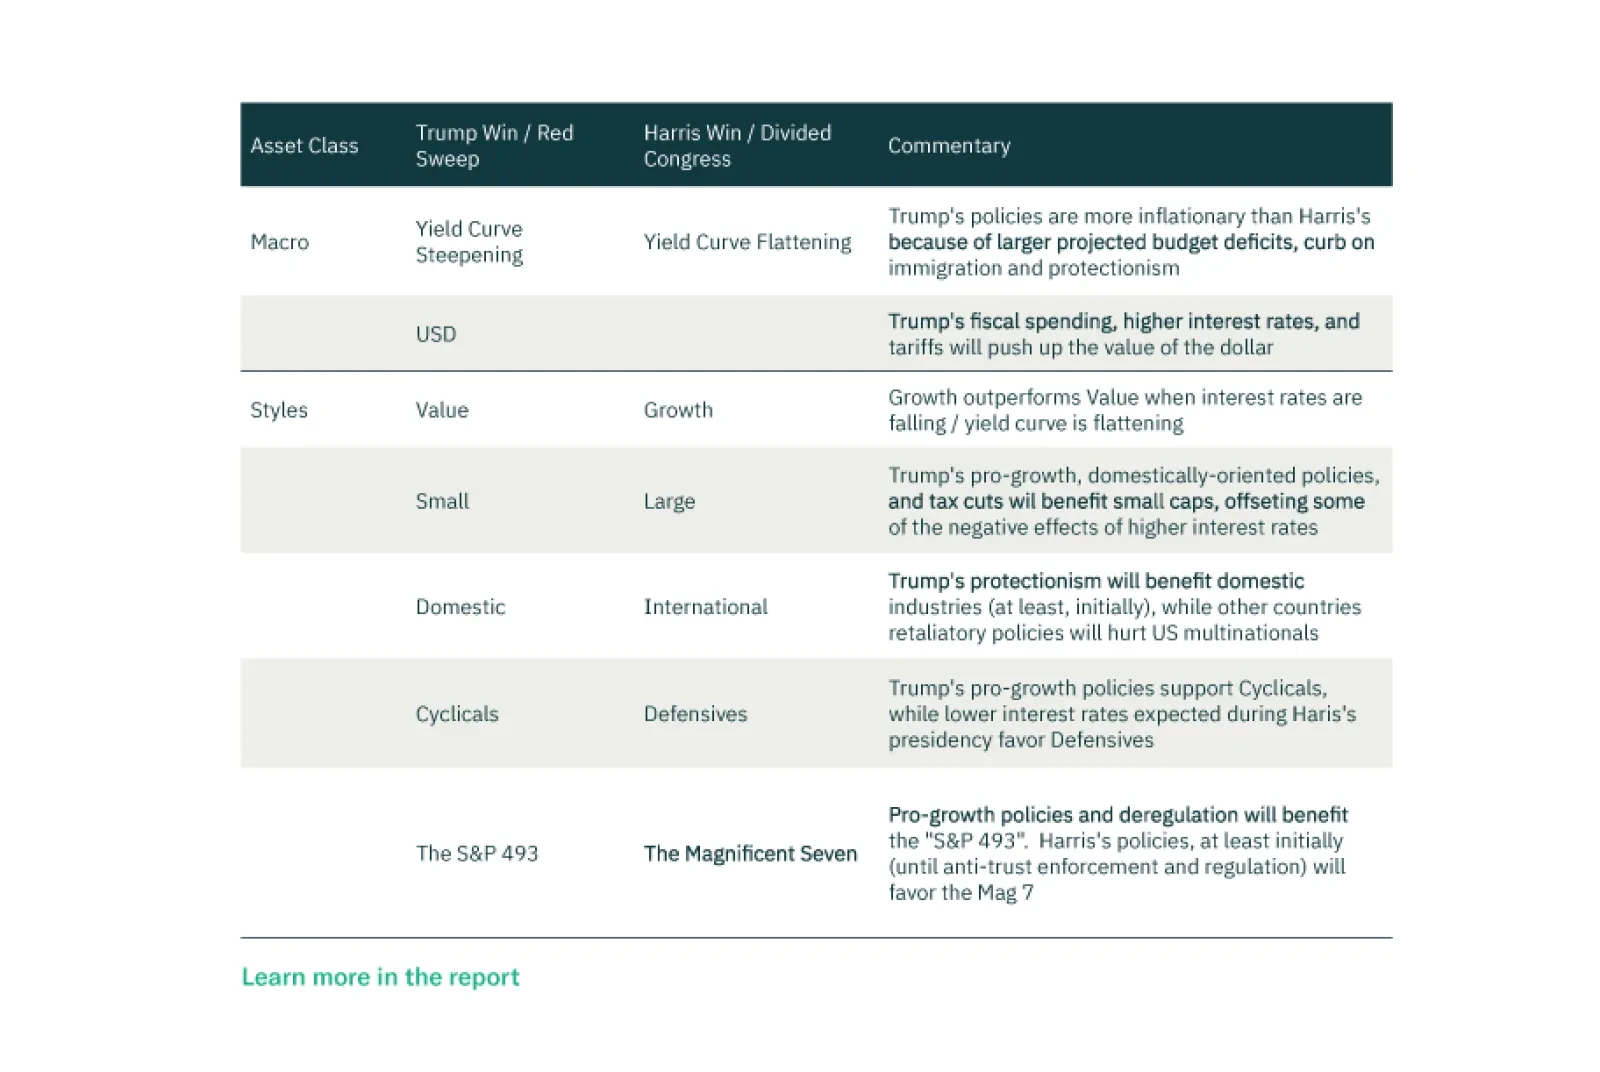
The most likely outcomes for the US elections are a “Red Sweep” and a “Blue Gridlock.” The following is a brief discussion of likely policies associated with each election outcome. We also present a post-election US Equities Cheat Sheet, in which we summarize winning trades for each scenario over the tactical investment horizon.