 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
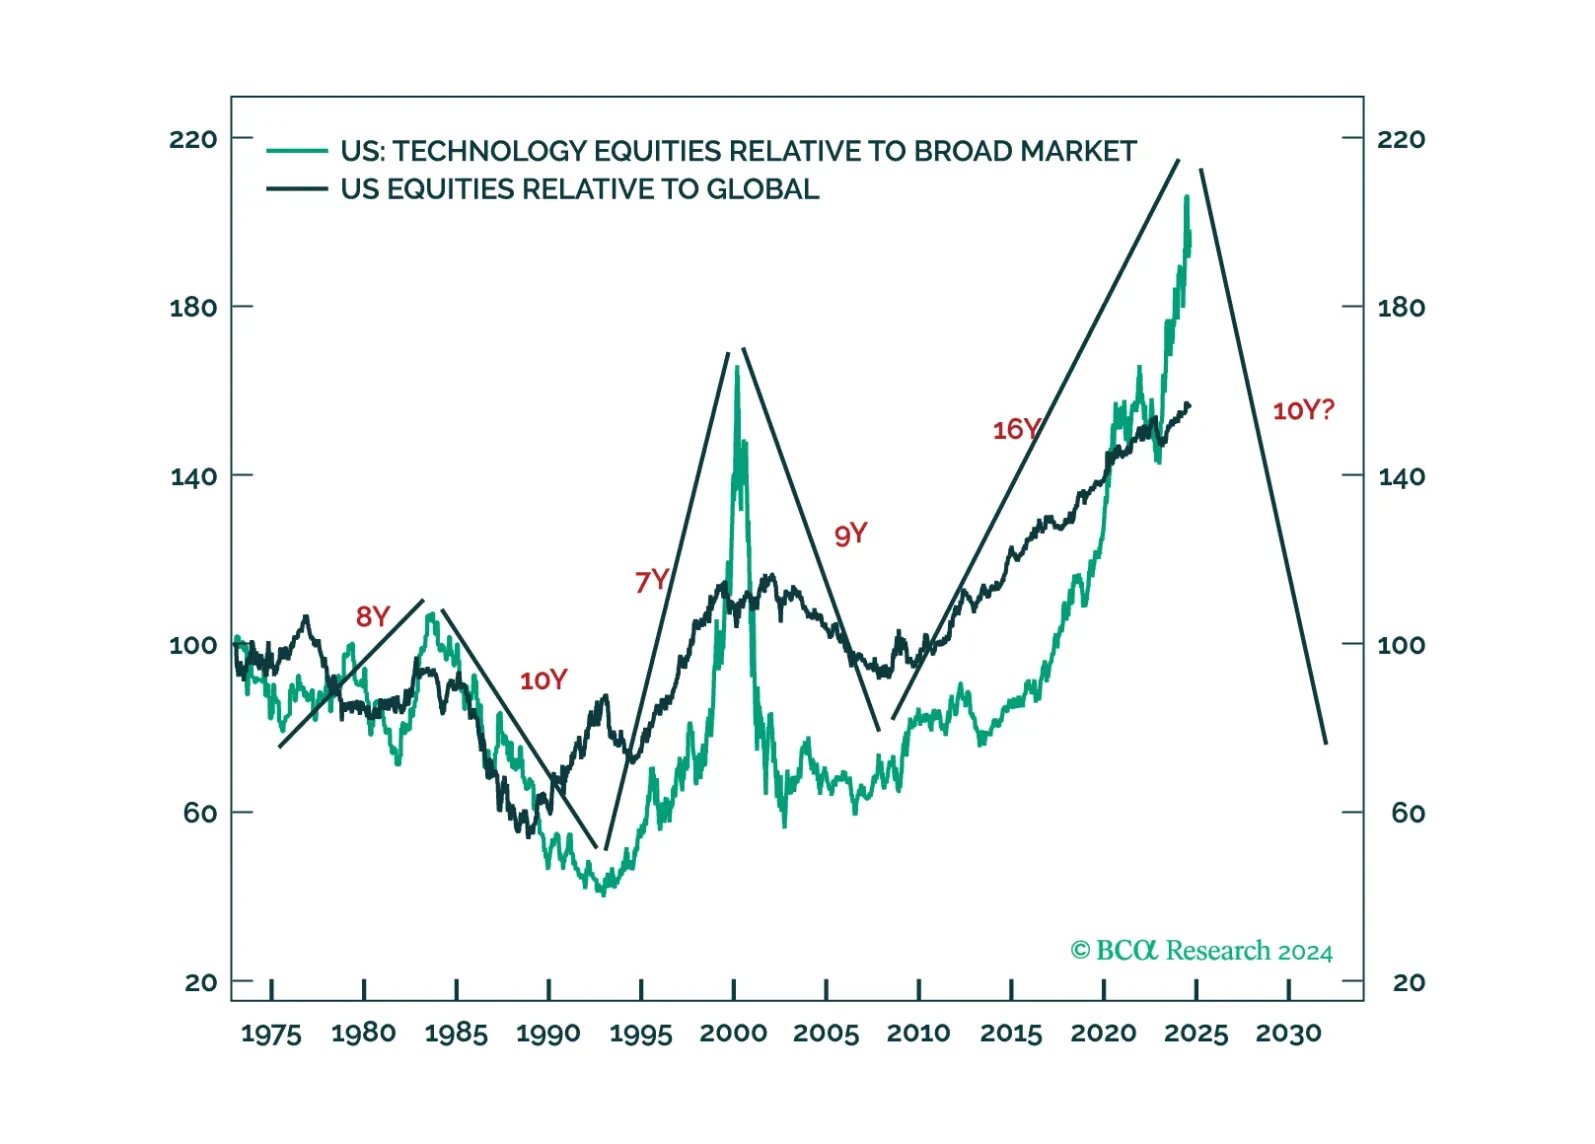
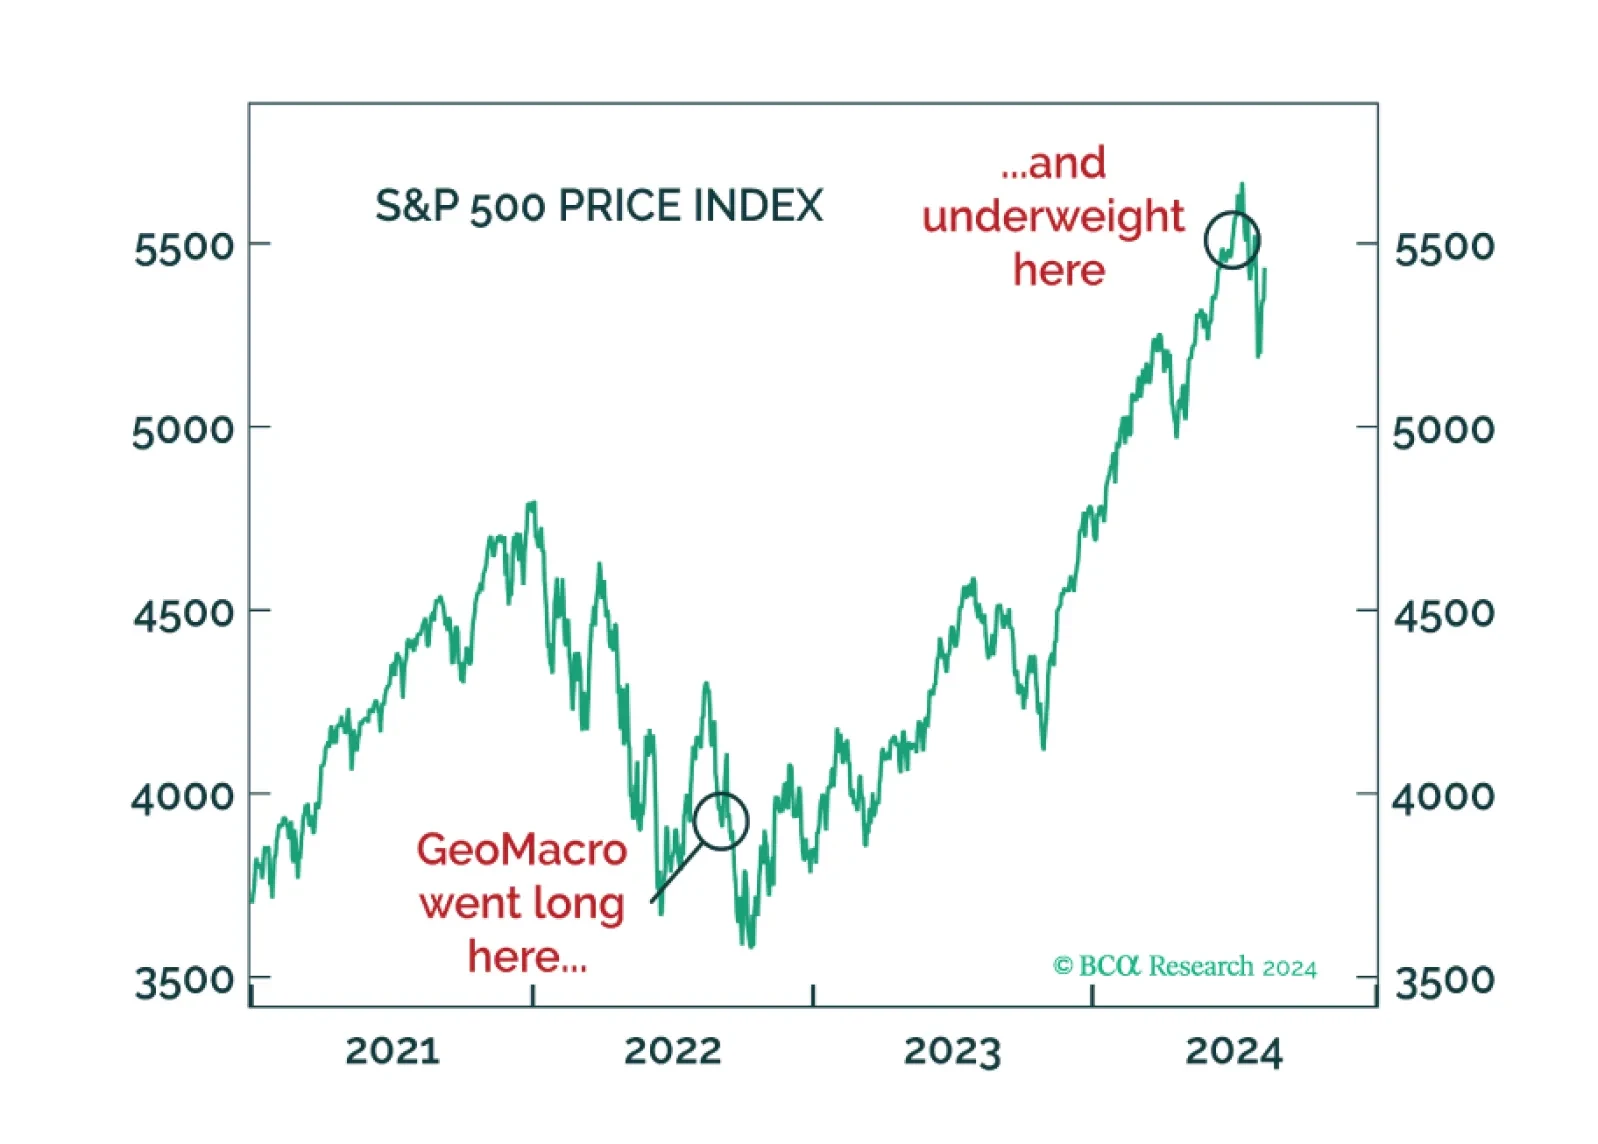
We remain concerned that the risk-reward for equities is limited above our end-of-the-year target of 5,500 for the S&P 500. There is seasonality to consider, as well as positioning and sentiment. As such, we are not necessarily bearish because a recession is certain. But, rather, that the upside to the AI mania is uncertain. Long term? The real bubble may be in America, broadly speaking. As such, more downside to USD could be ahead.
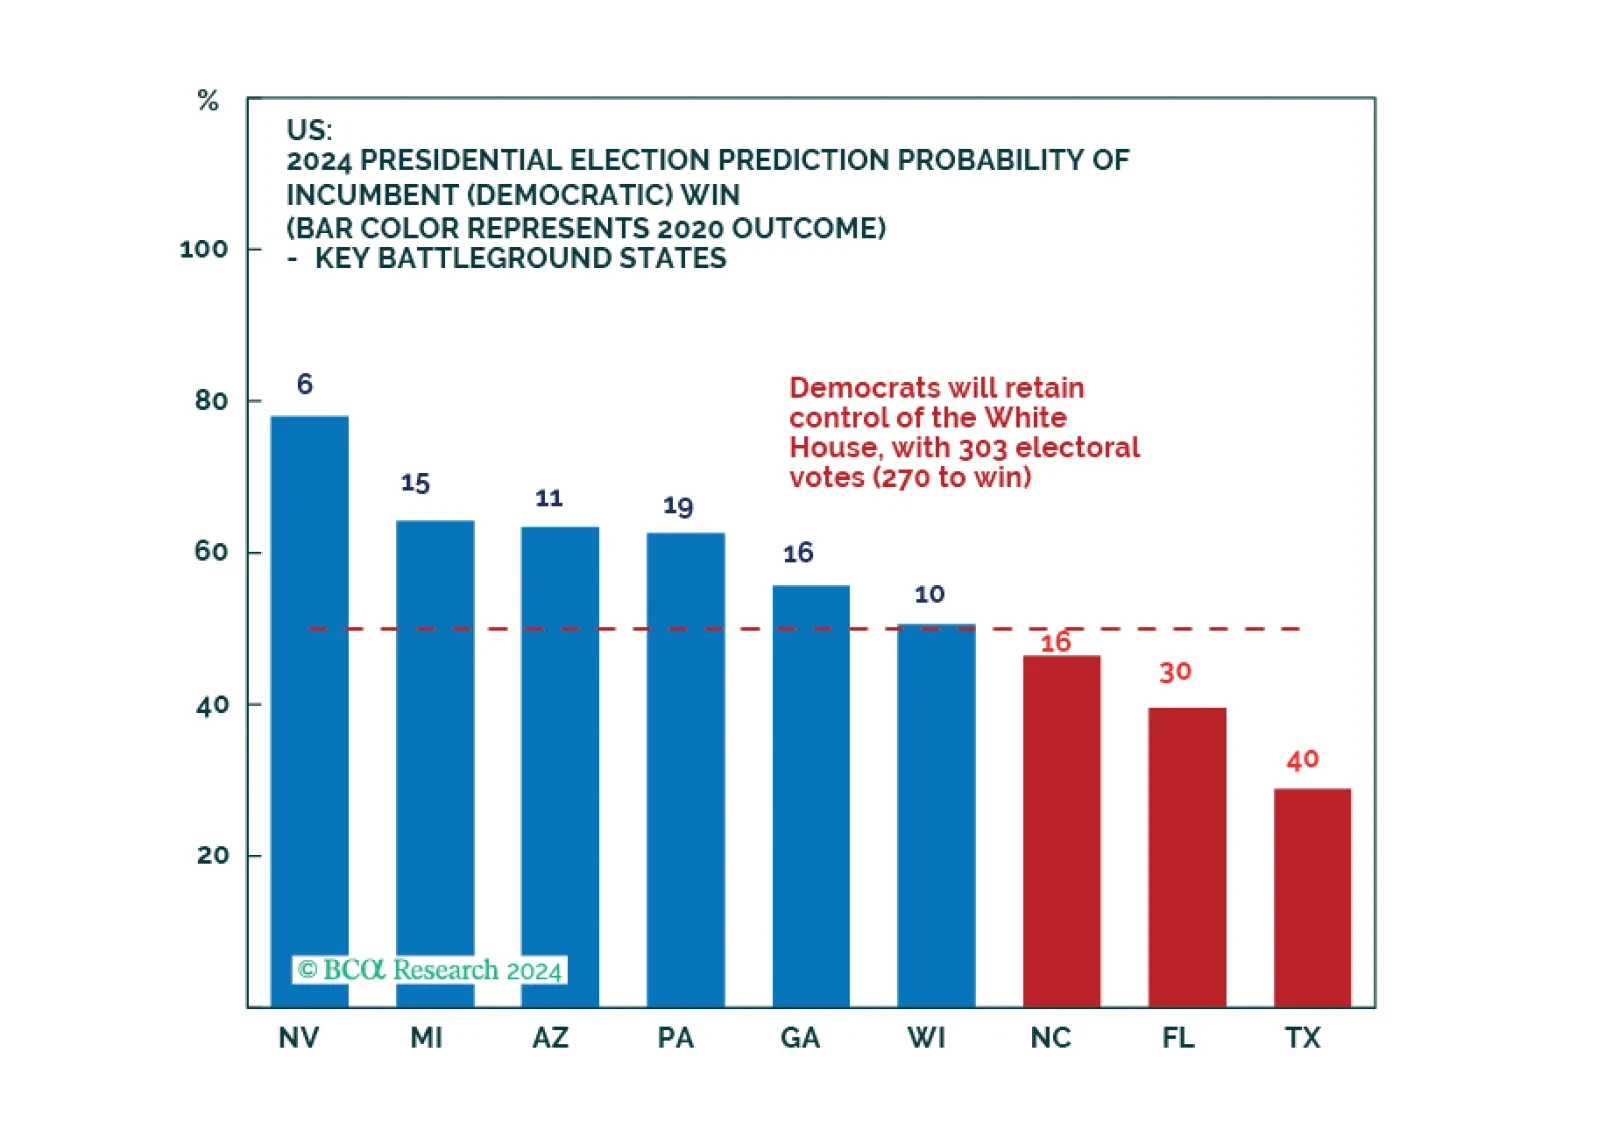
Democrats will not win a full sweep and implement drastic new tax hikes. However, our quant model still favors them to win the White House and just upgraded their odds. While we expect equity volatility around the election, investors do not need to worry about corporate tax hikes.
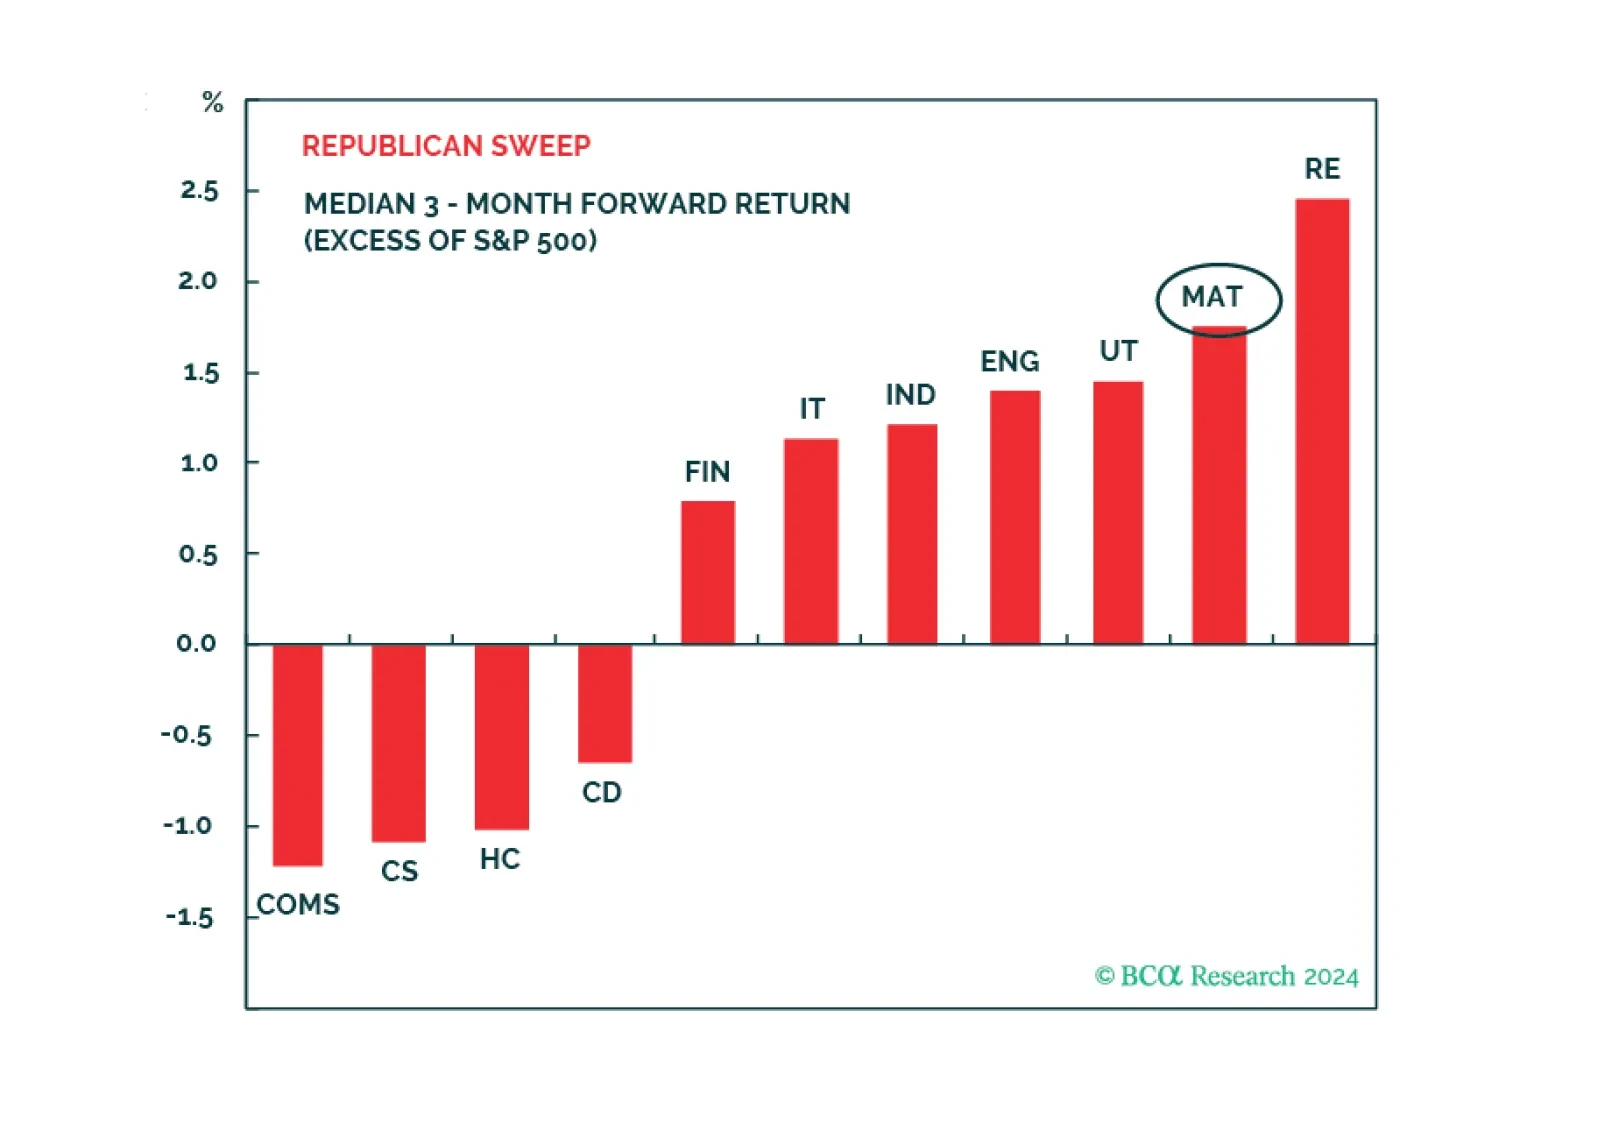
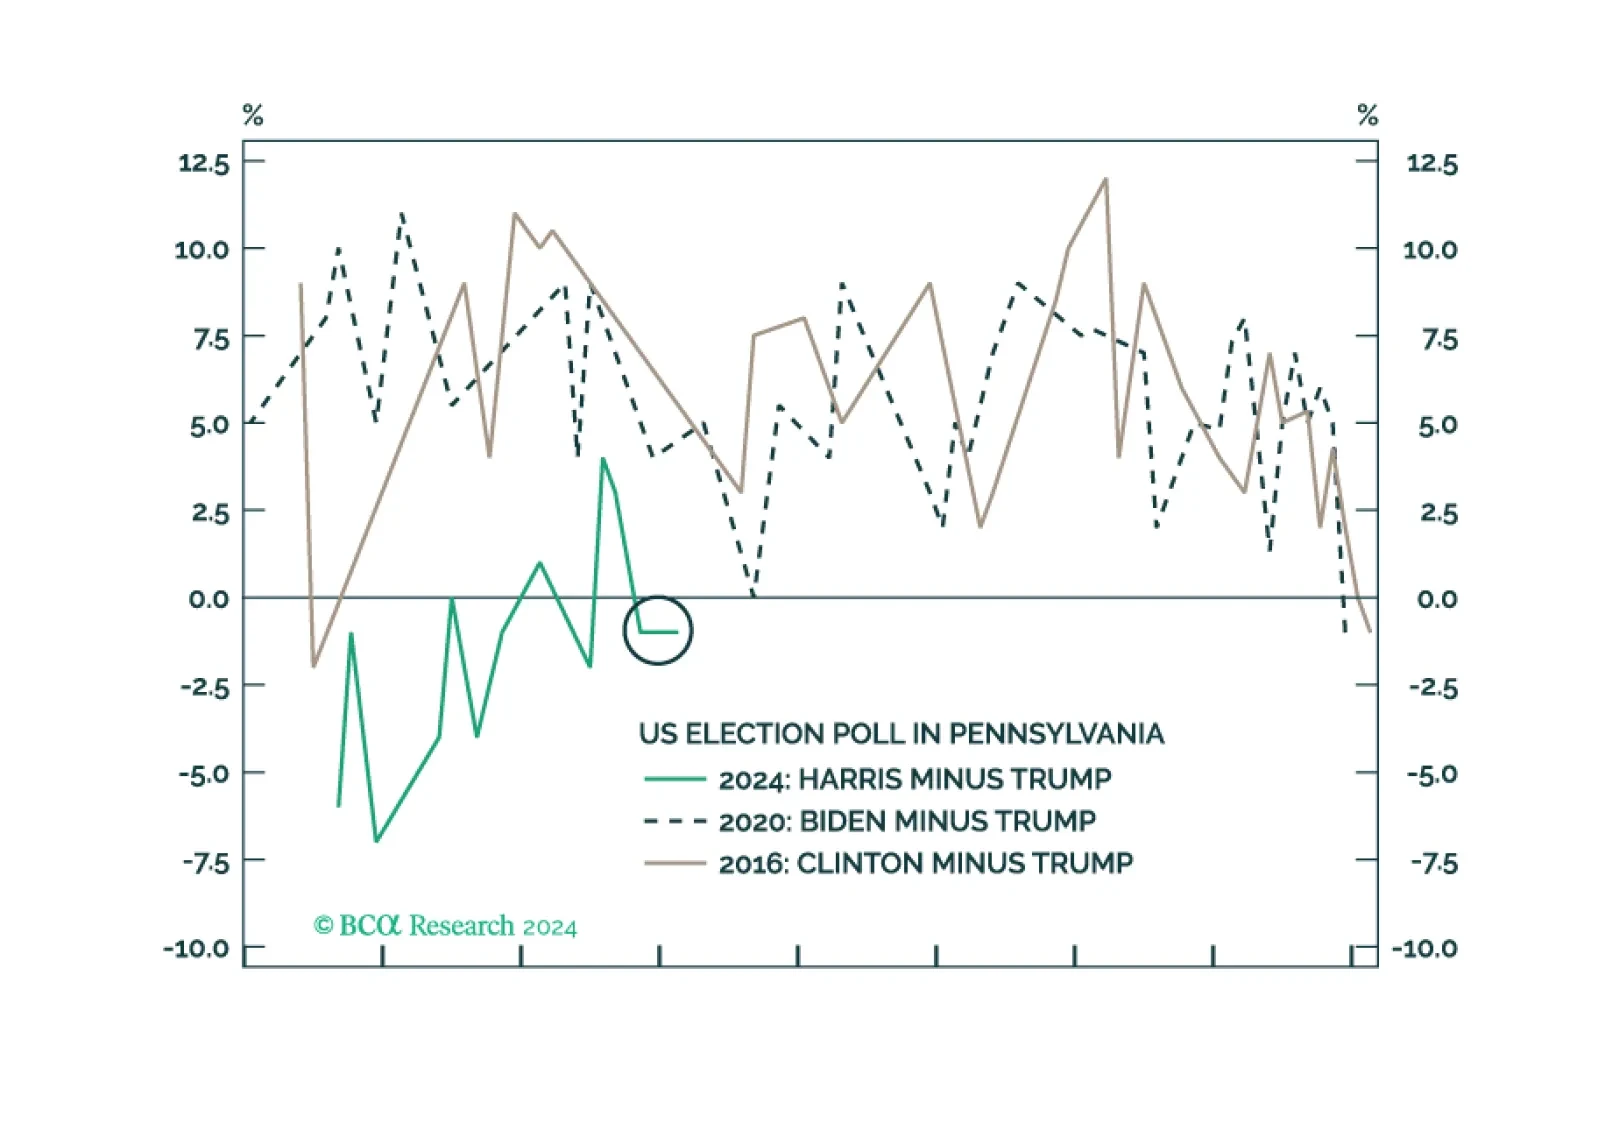
Investors should buy protection against further volatility. The shakeup in early August was a taste of things to come. The US election is a pivotal moment in modern history that will drive up uncertainty, while other countries take advantage of US division and distraction.
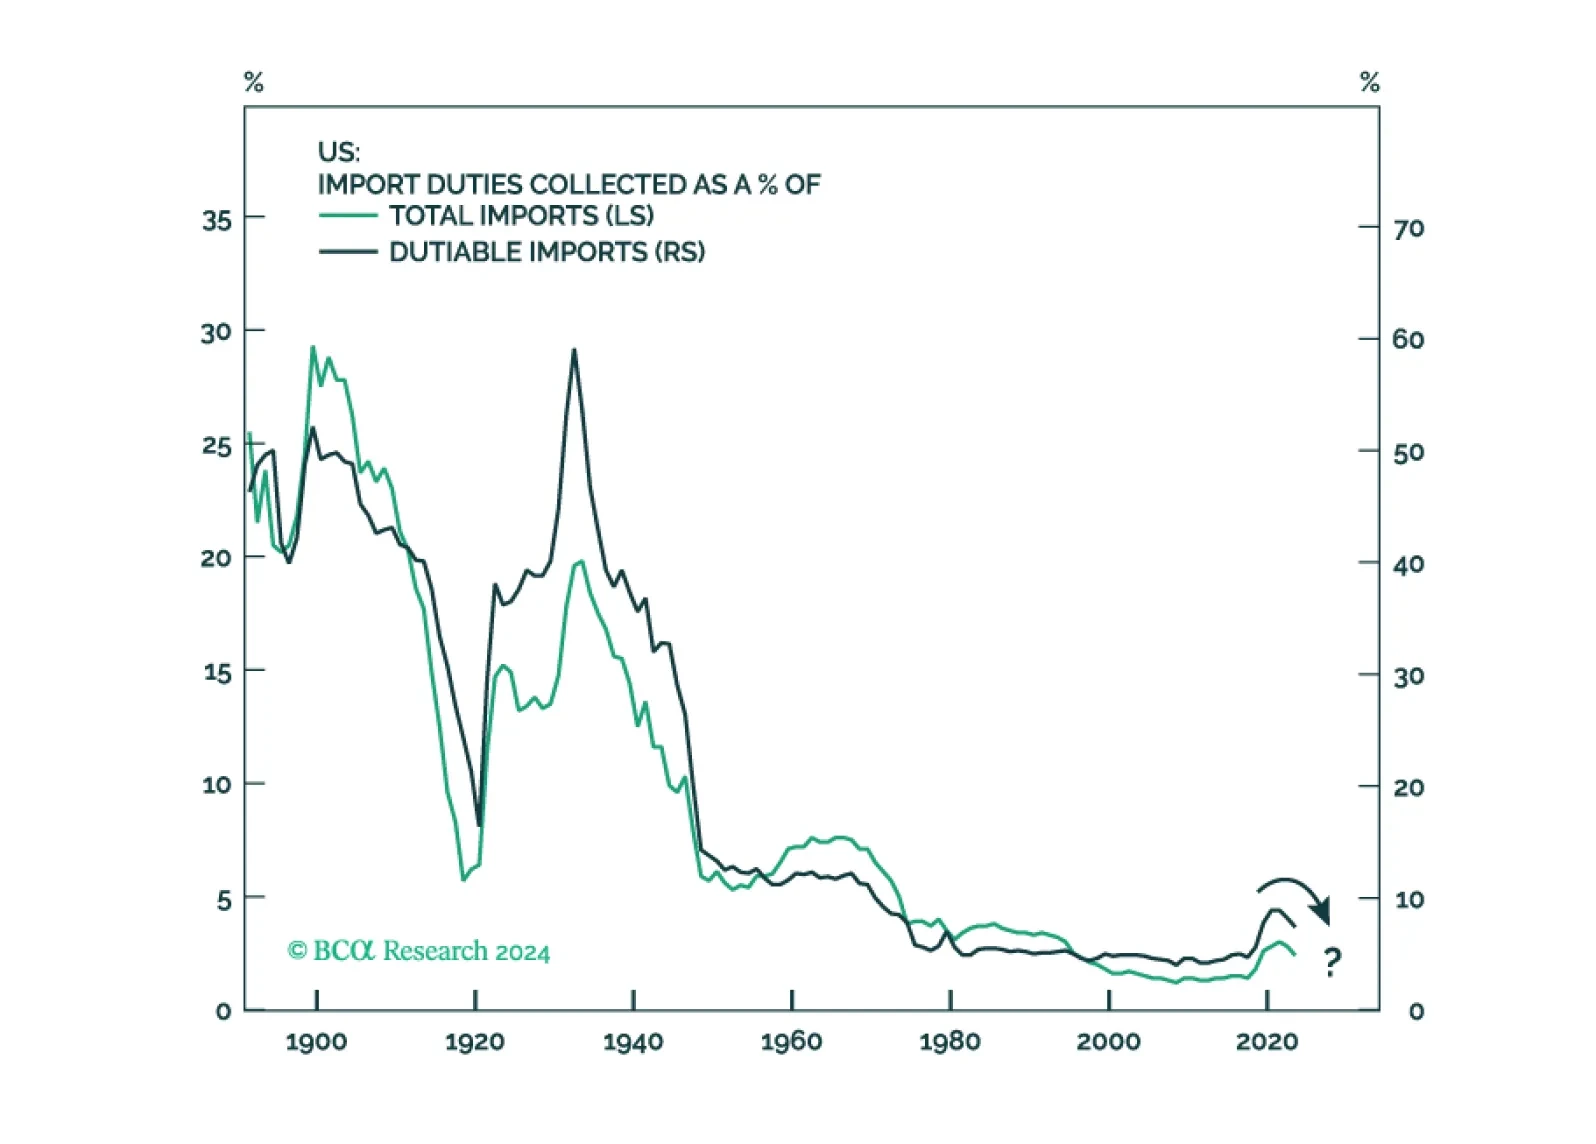
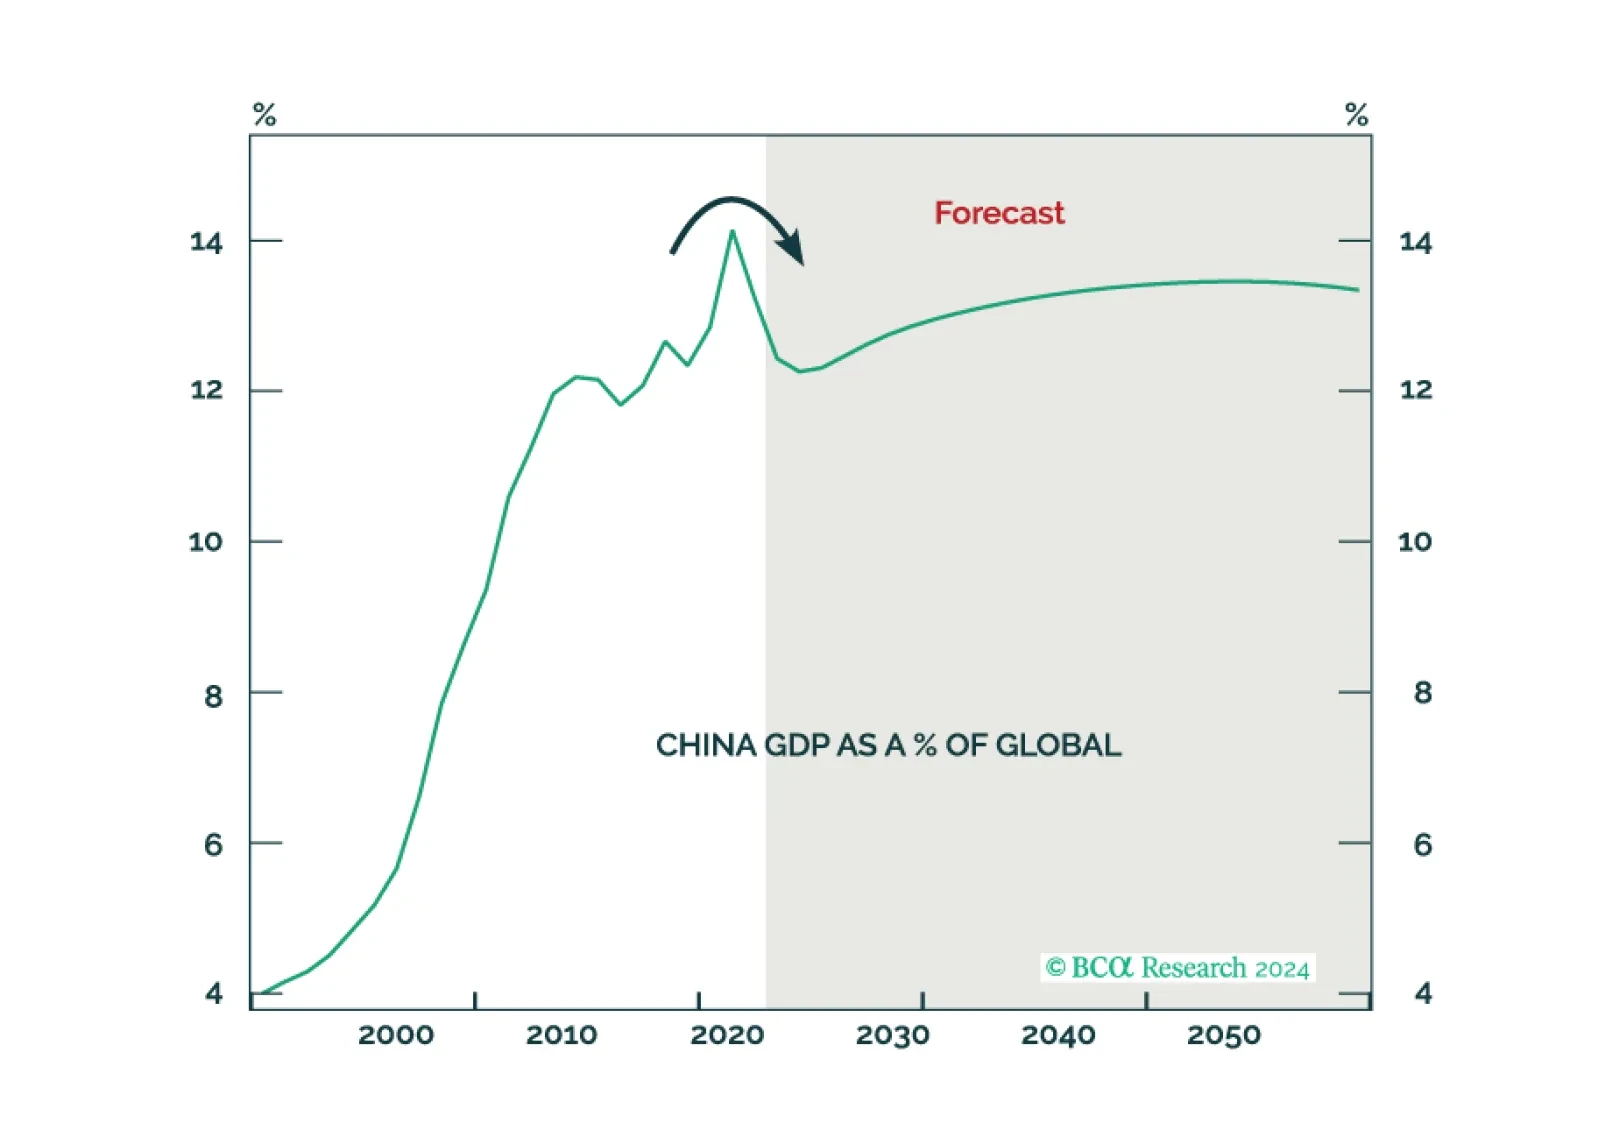
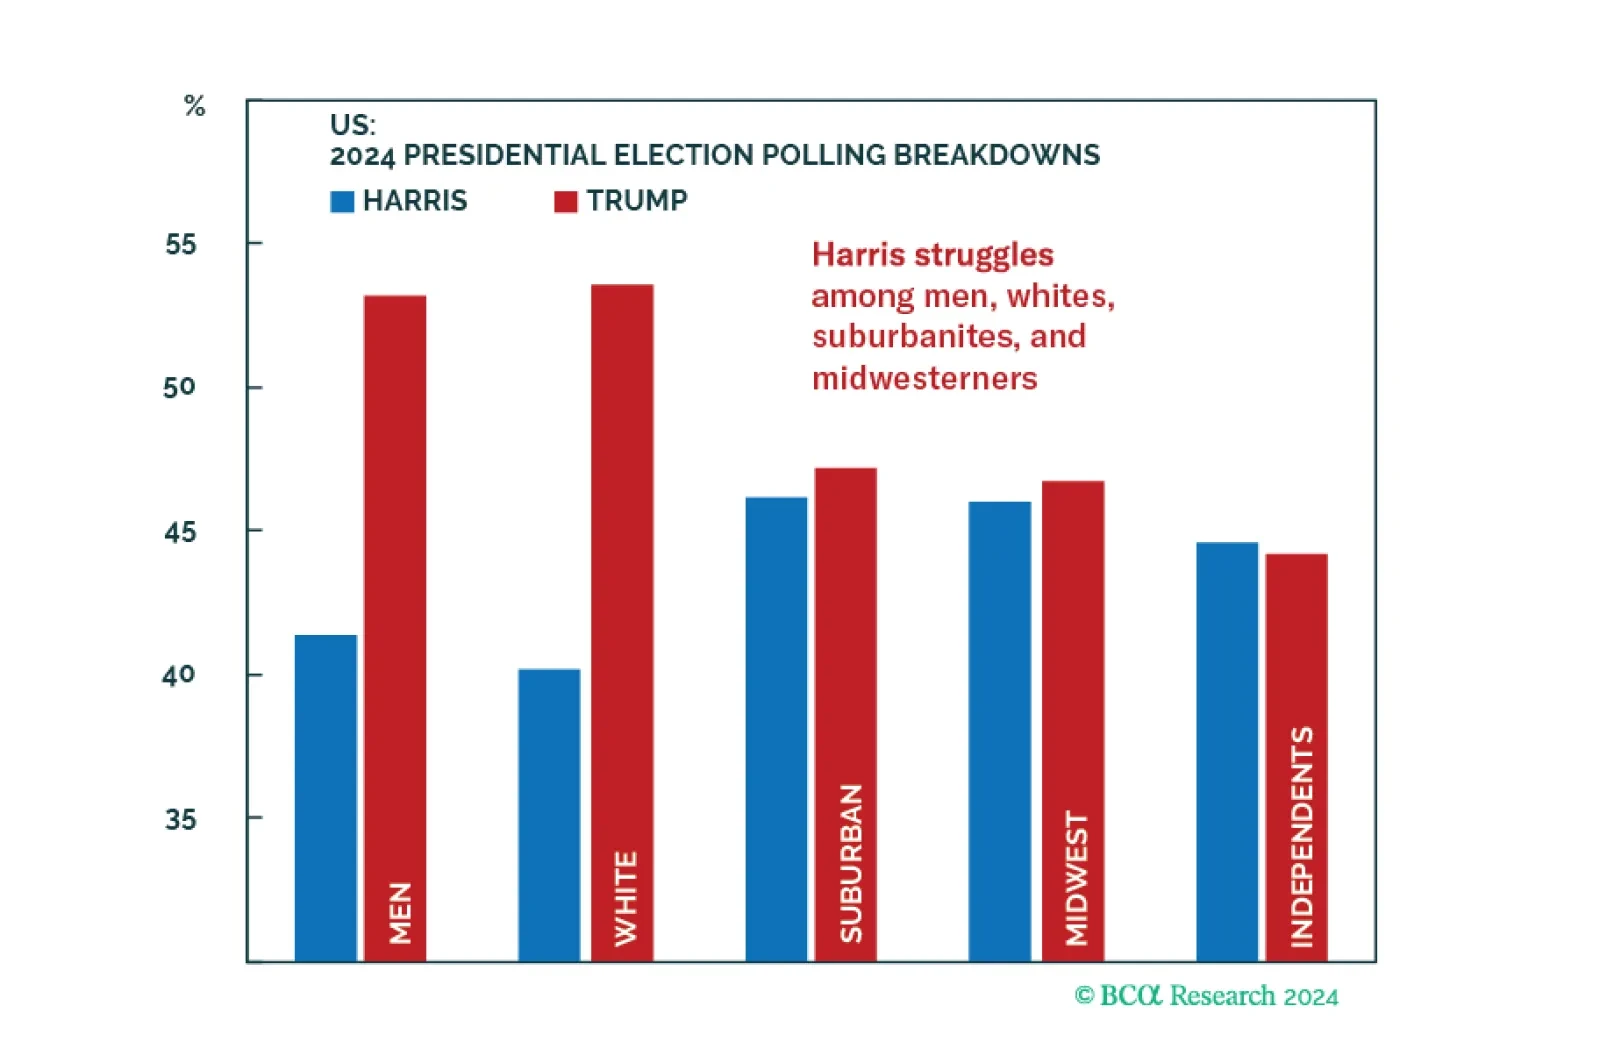
Harris picked Walz to patch up her weak side in the electorally vital Midwest. But the US election will continue to weigh on risk appetite, stocks, and high-beta assets because the odds of a single-party sweep are at least 50%, probably higher. Policy uncertainty and risk premiums will rise, not fall, in the coming months.
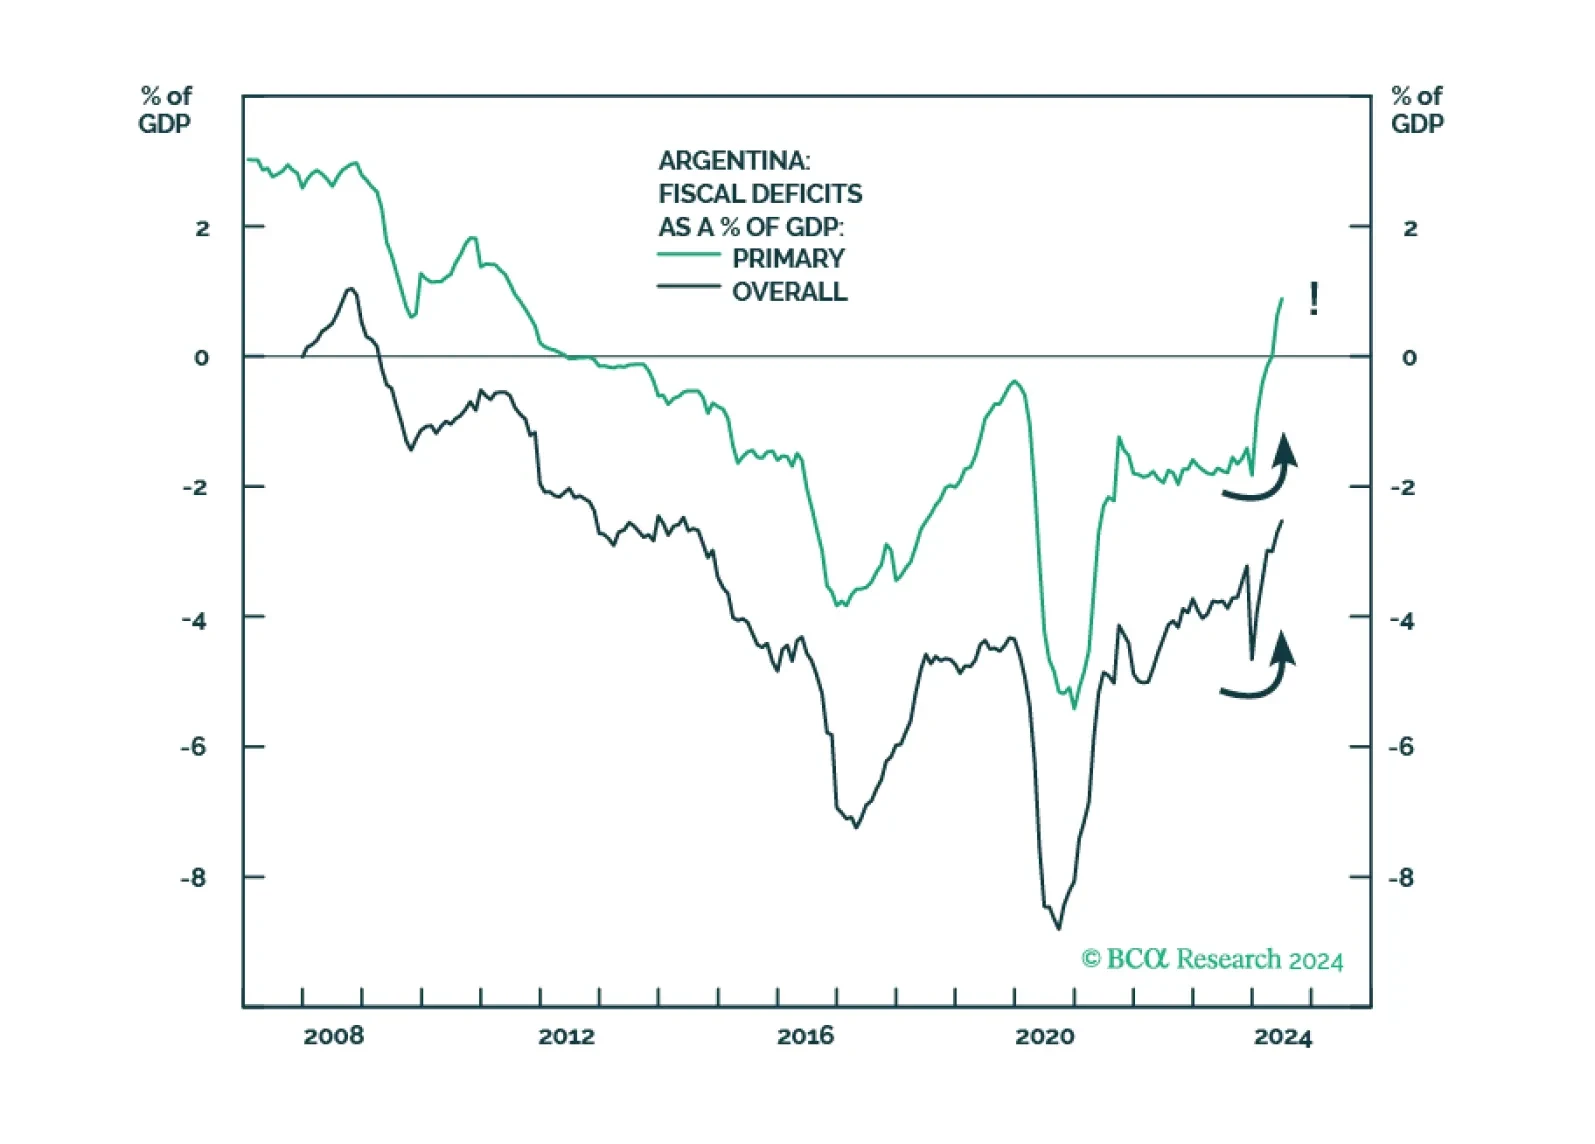
GeoMacro team partners with BCA’s Emerging Markets Strategy to examine political reforms in Argentina. Our colleague Juan Egaña argues that the time is not right to go long Argentinian assets and that Buenos Aires must avoid the mistakes of the Macri era: opening to foreign capital flows too soon without addressing structural macro imbalances. However, the Milei administration is on the right path with potentially global implications.