 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
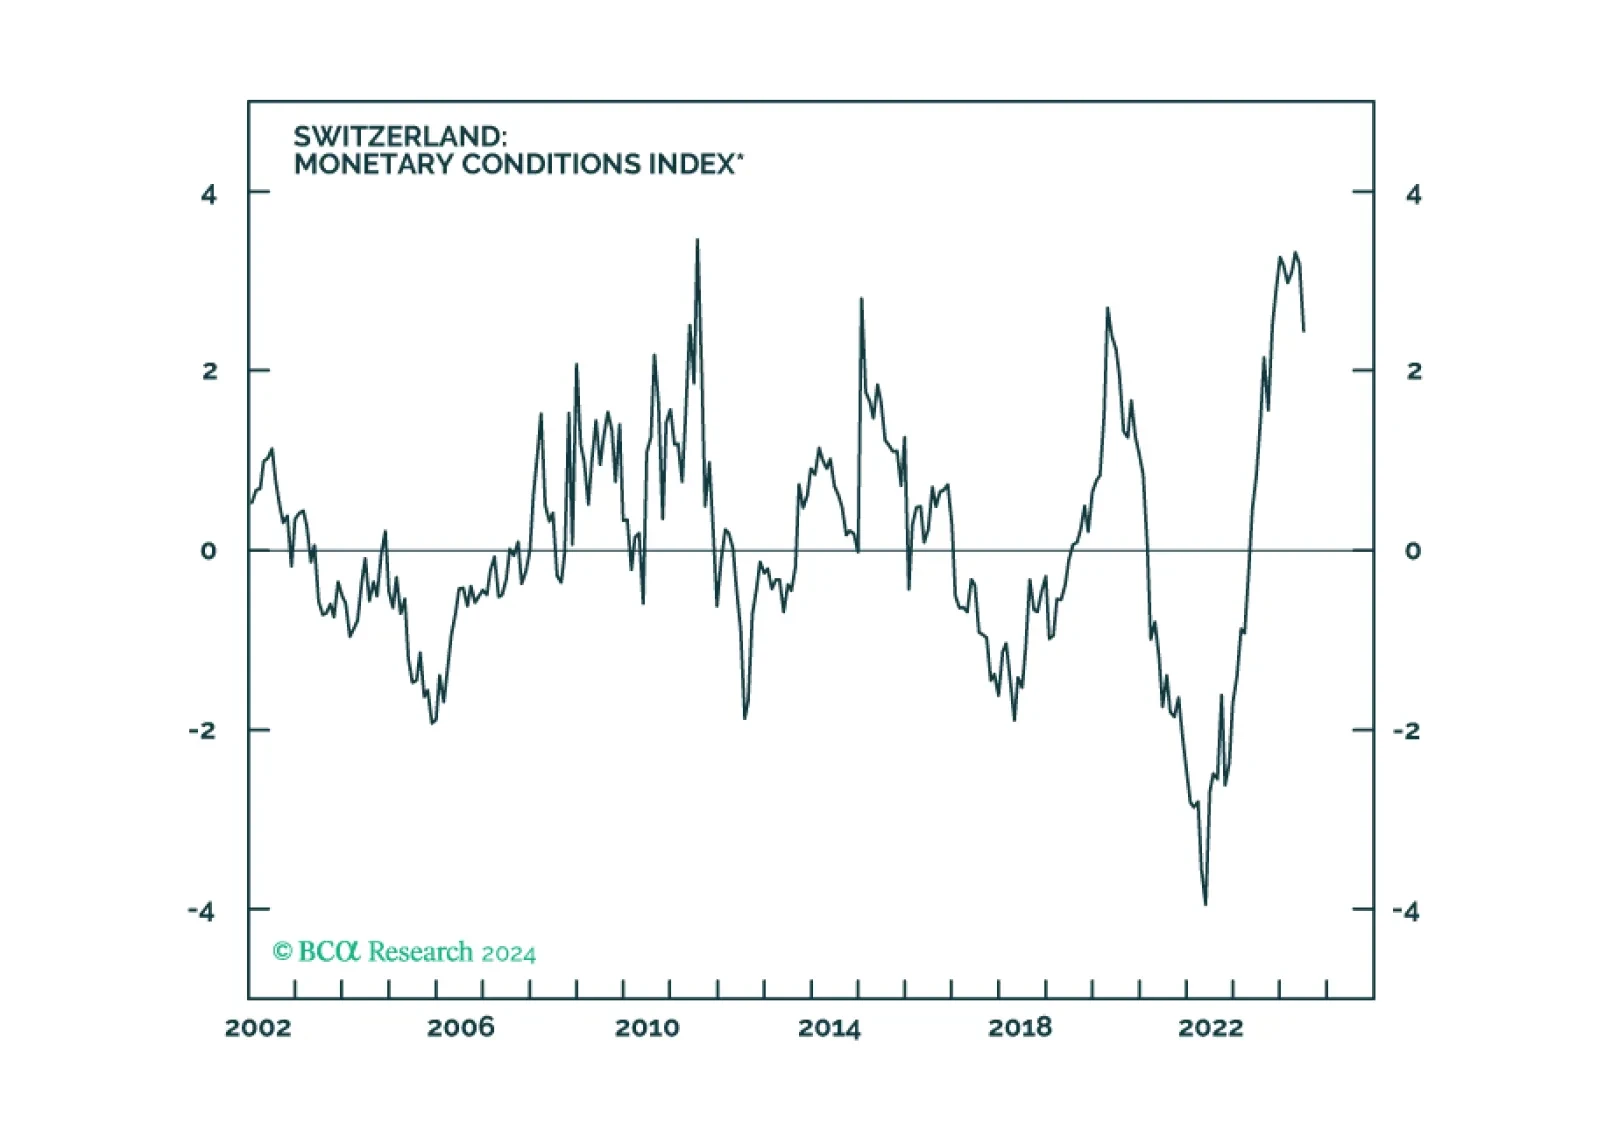
We look at the implications a various European central bank meetings this week, for currency strategy.
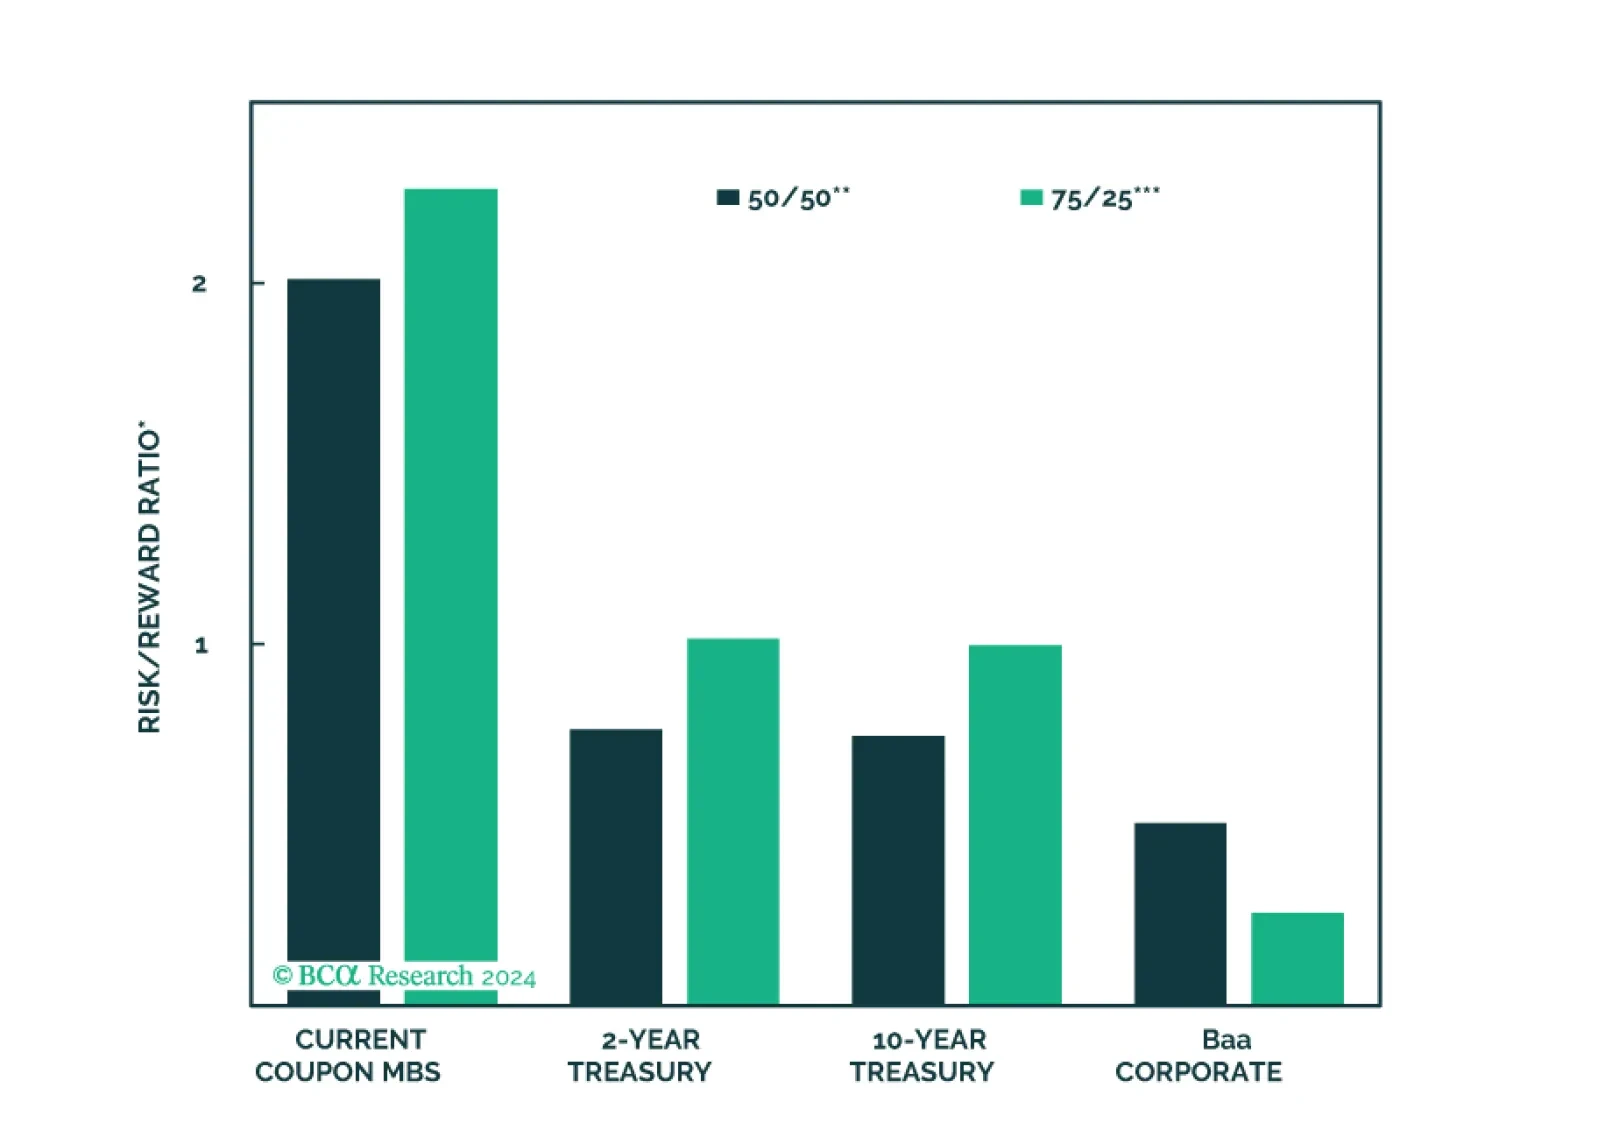
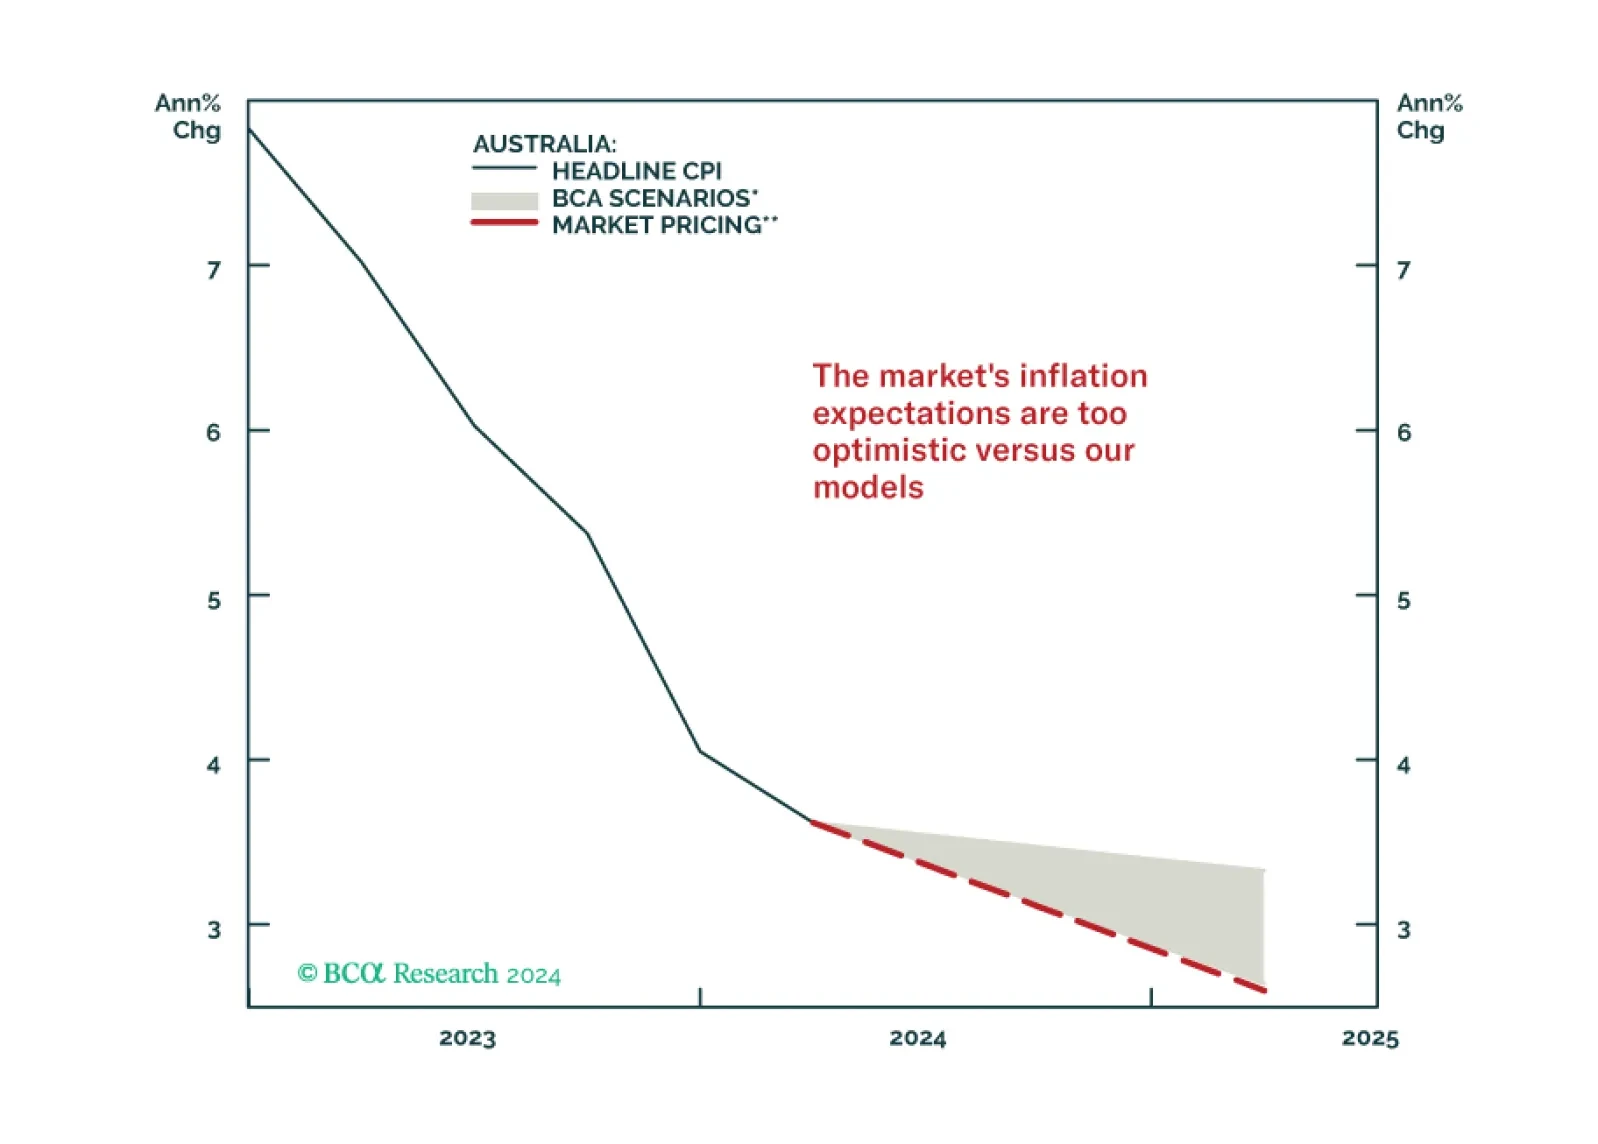
In light of this week’s RBA decision to keep policy on hold, we look at the best possible trades in fixed income markets. In our view, inflation-linked bonds, relative to nominals remain a good bet.

Gold prices might experience a correction or consolidation over the near term. However, cyclical and structural forces will ultimately cause the yellow metal to trend upwards.
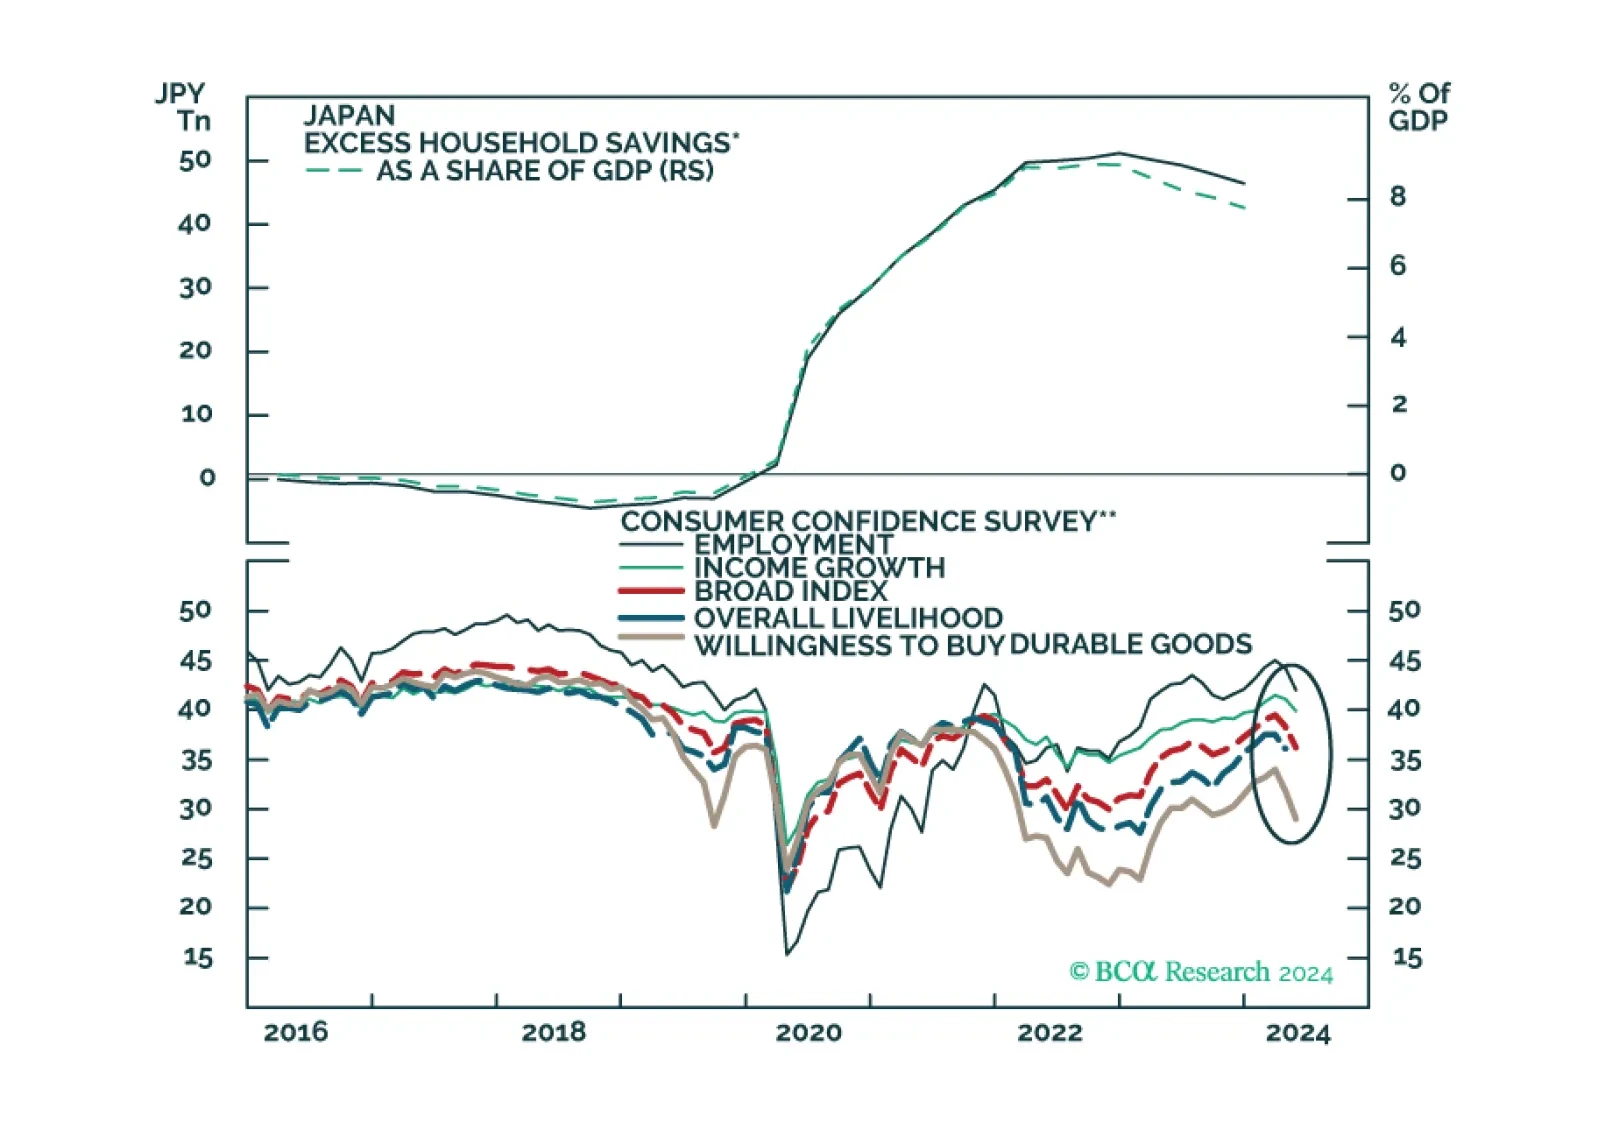
In this insight, we update our thinking on the recent BoJ move in terms of positioning for the yen and JGB yields.
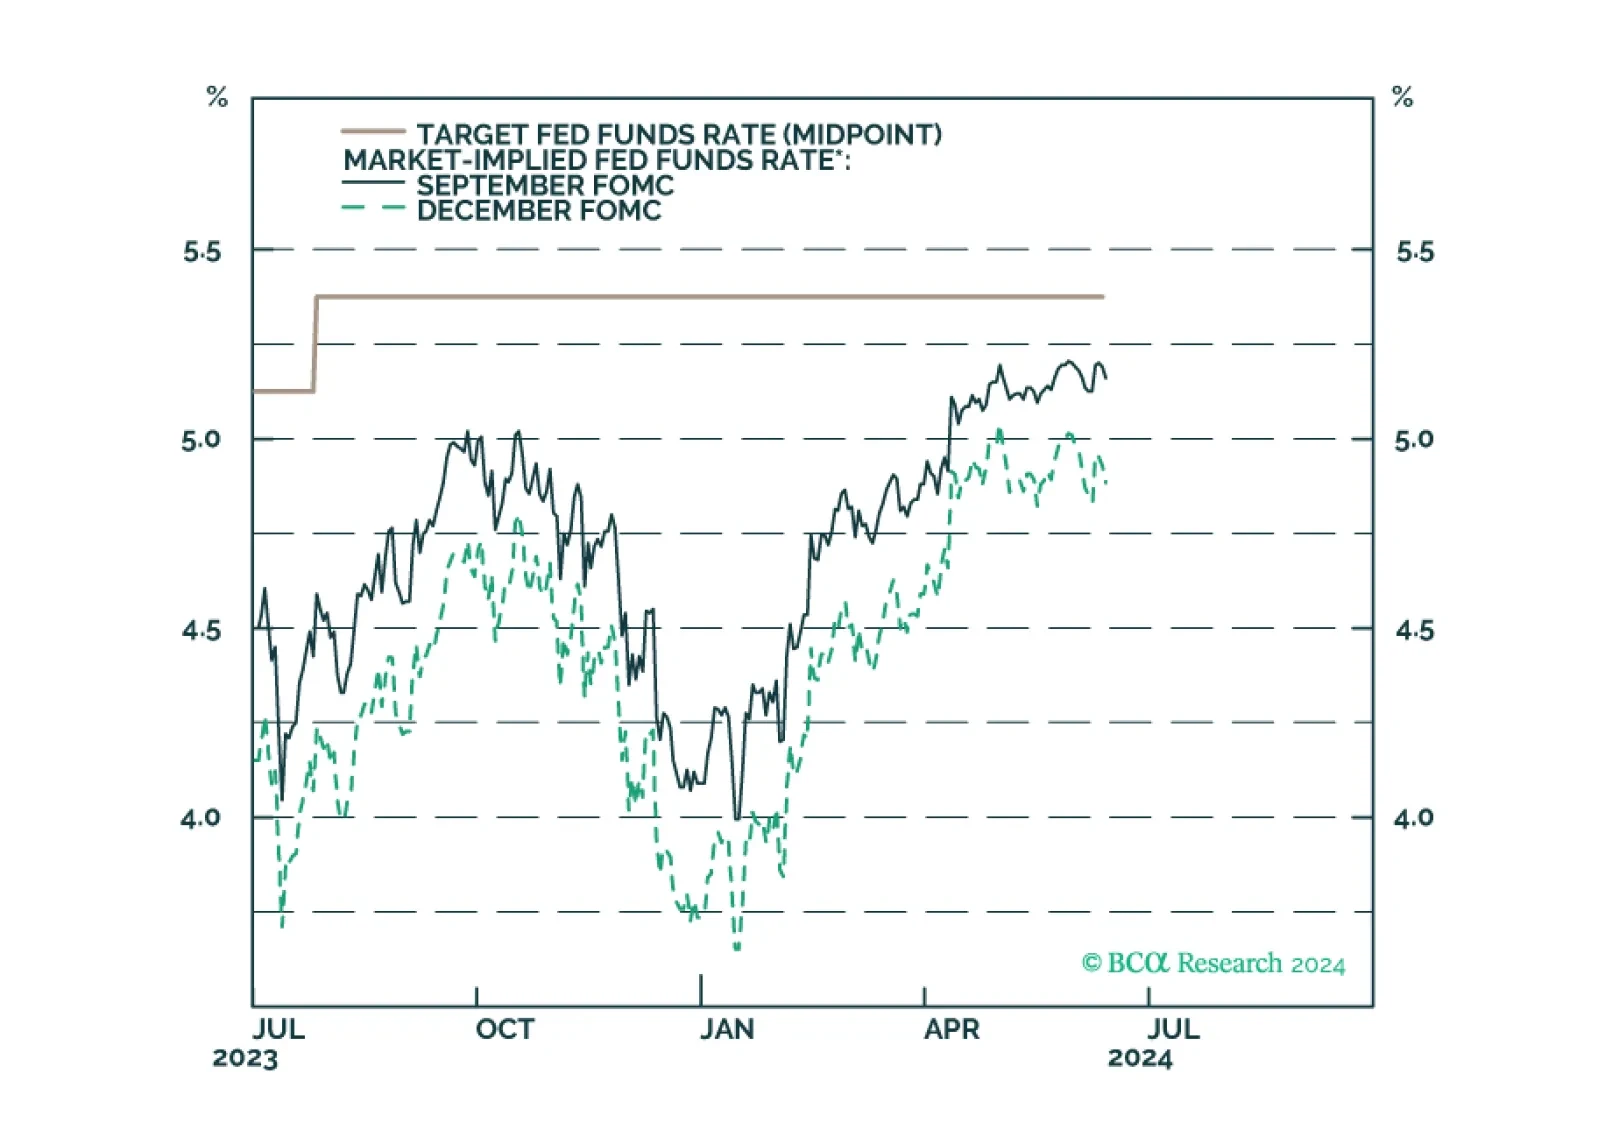
Our reaction to this morning’s CPI report and this afternoon’s FOMC meeting.
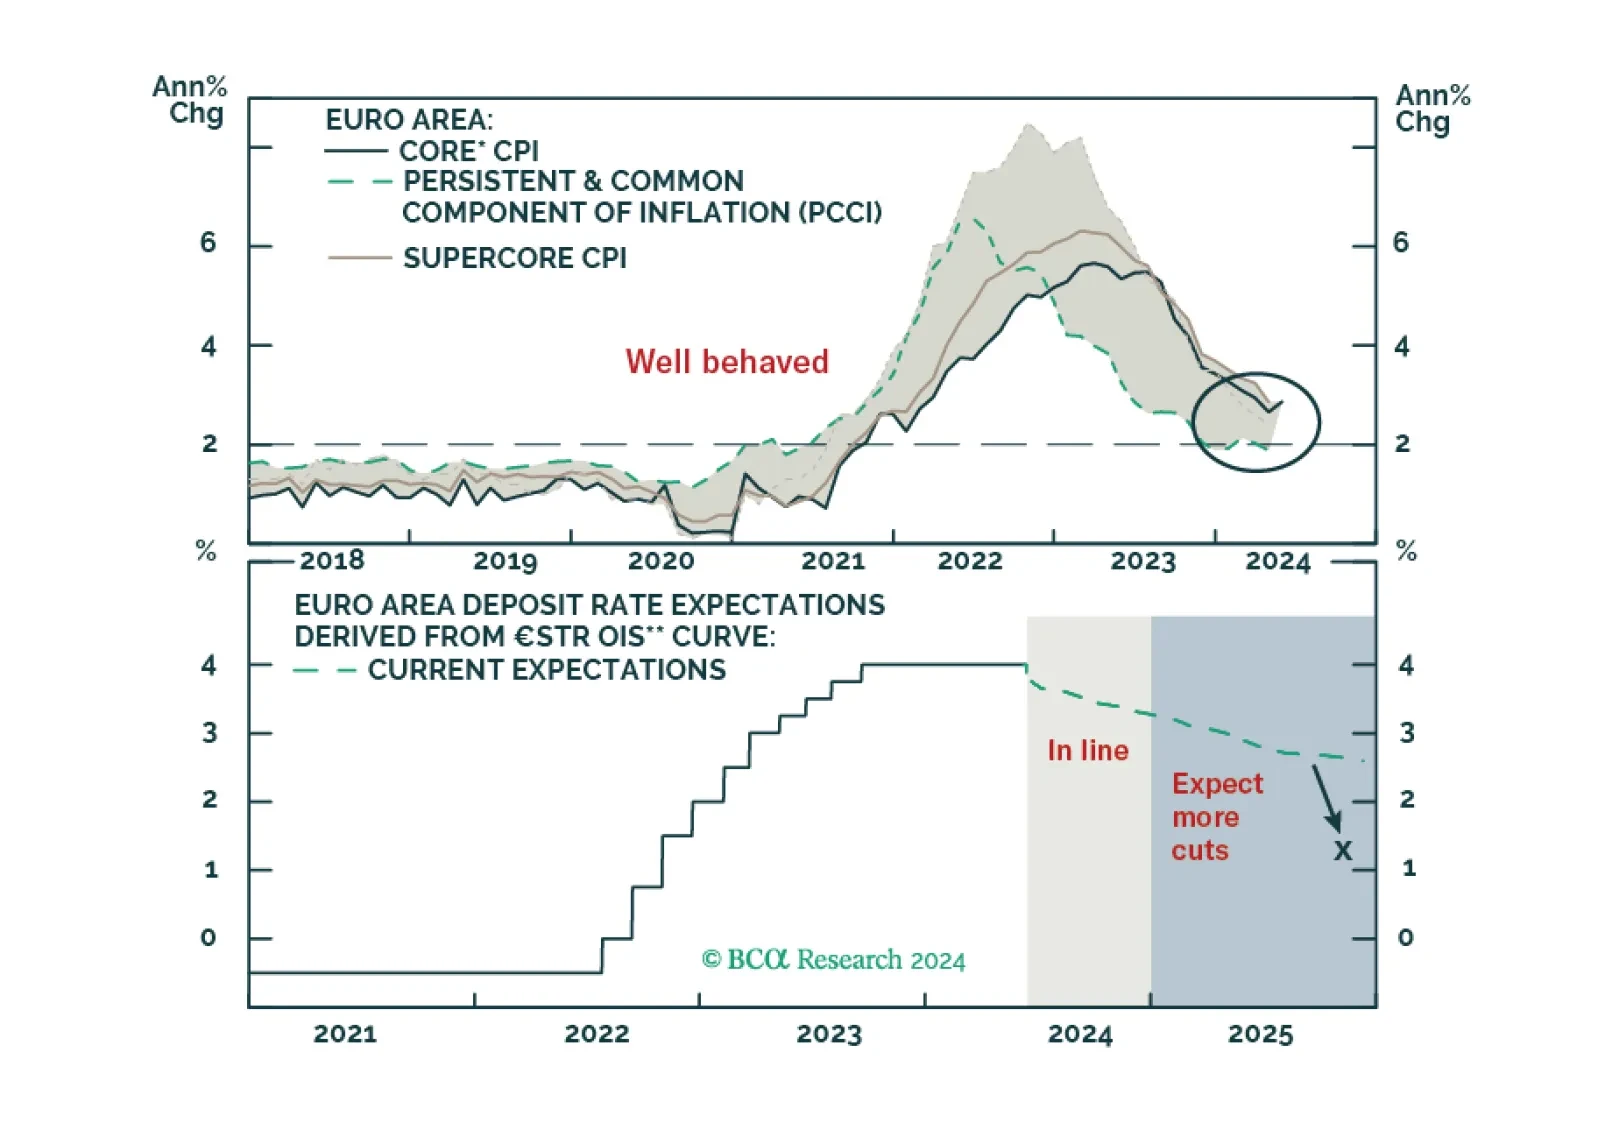
The ECB is now firmly in easing mode, even if it refuses to pre-commit to a specific rate path. What does this data dependency mean for the euro and European yields?
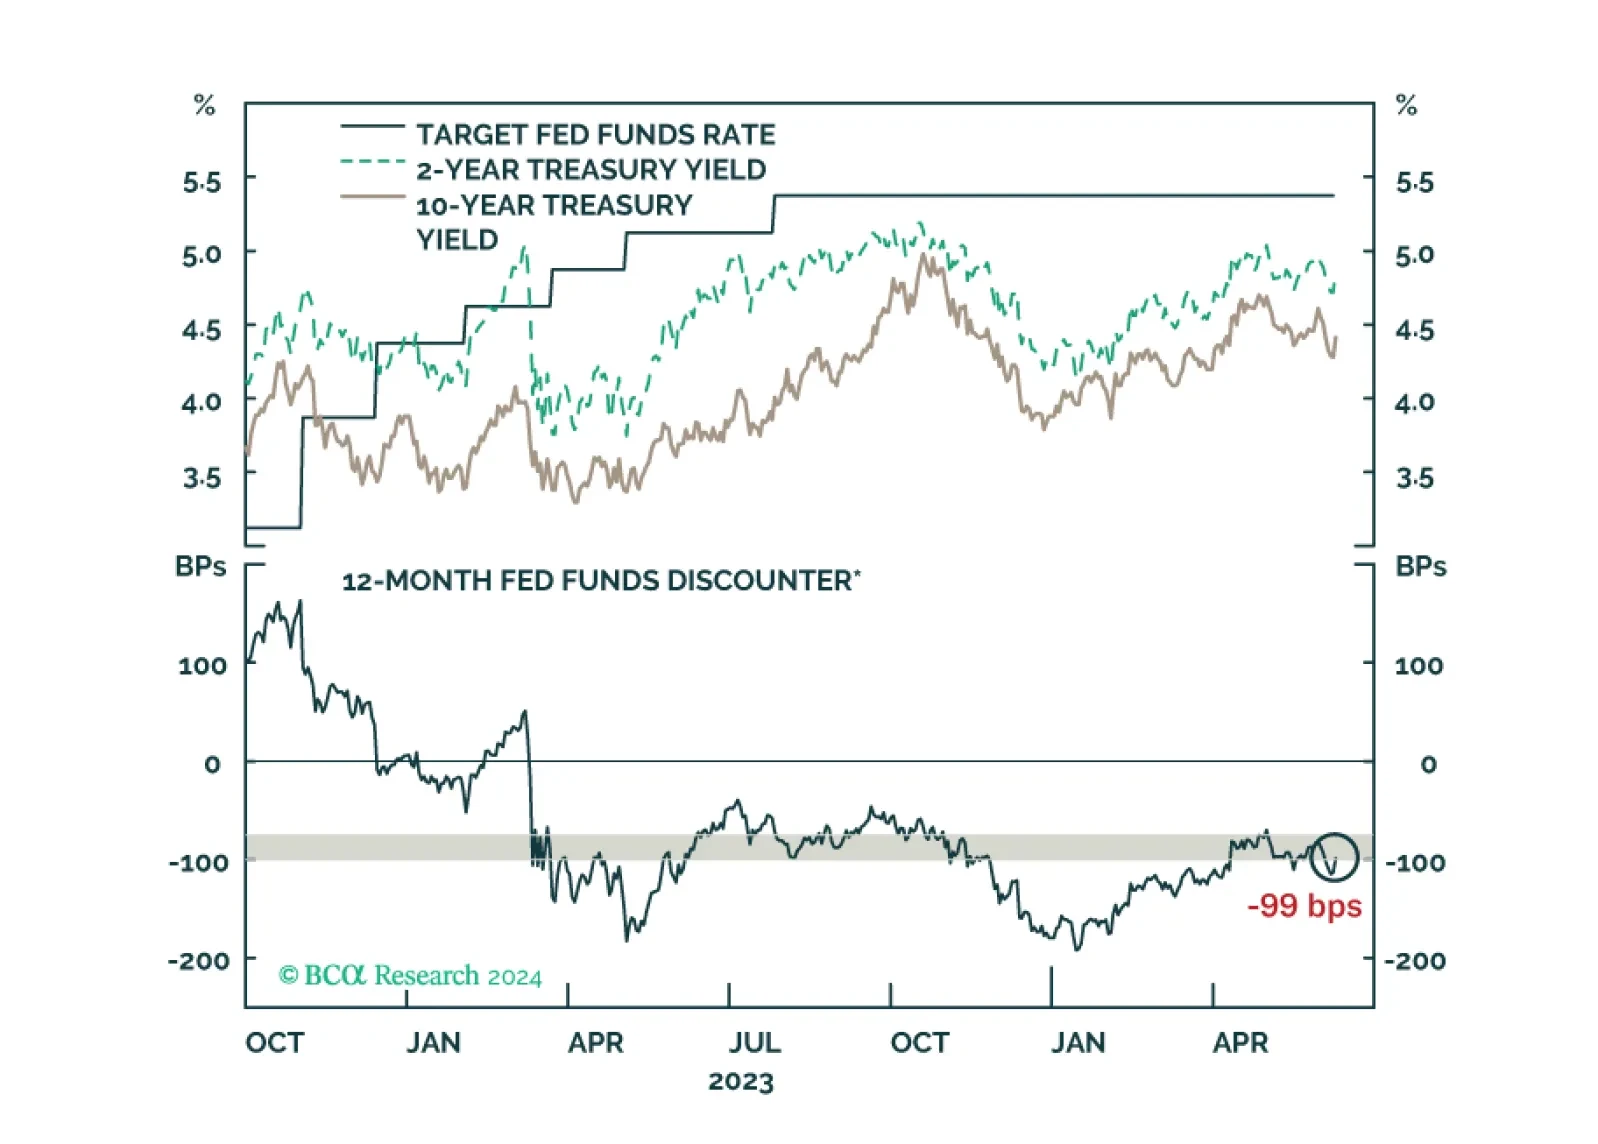
US Treasury yields bounced after this morning’s employment report. We offer our updated views about how long the recent trading range will hold.
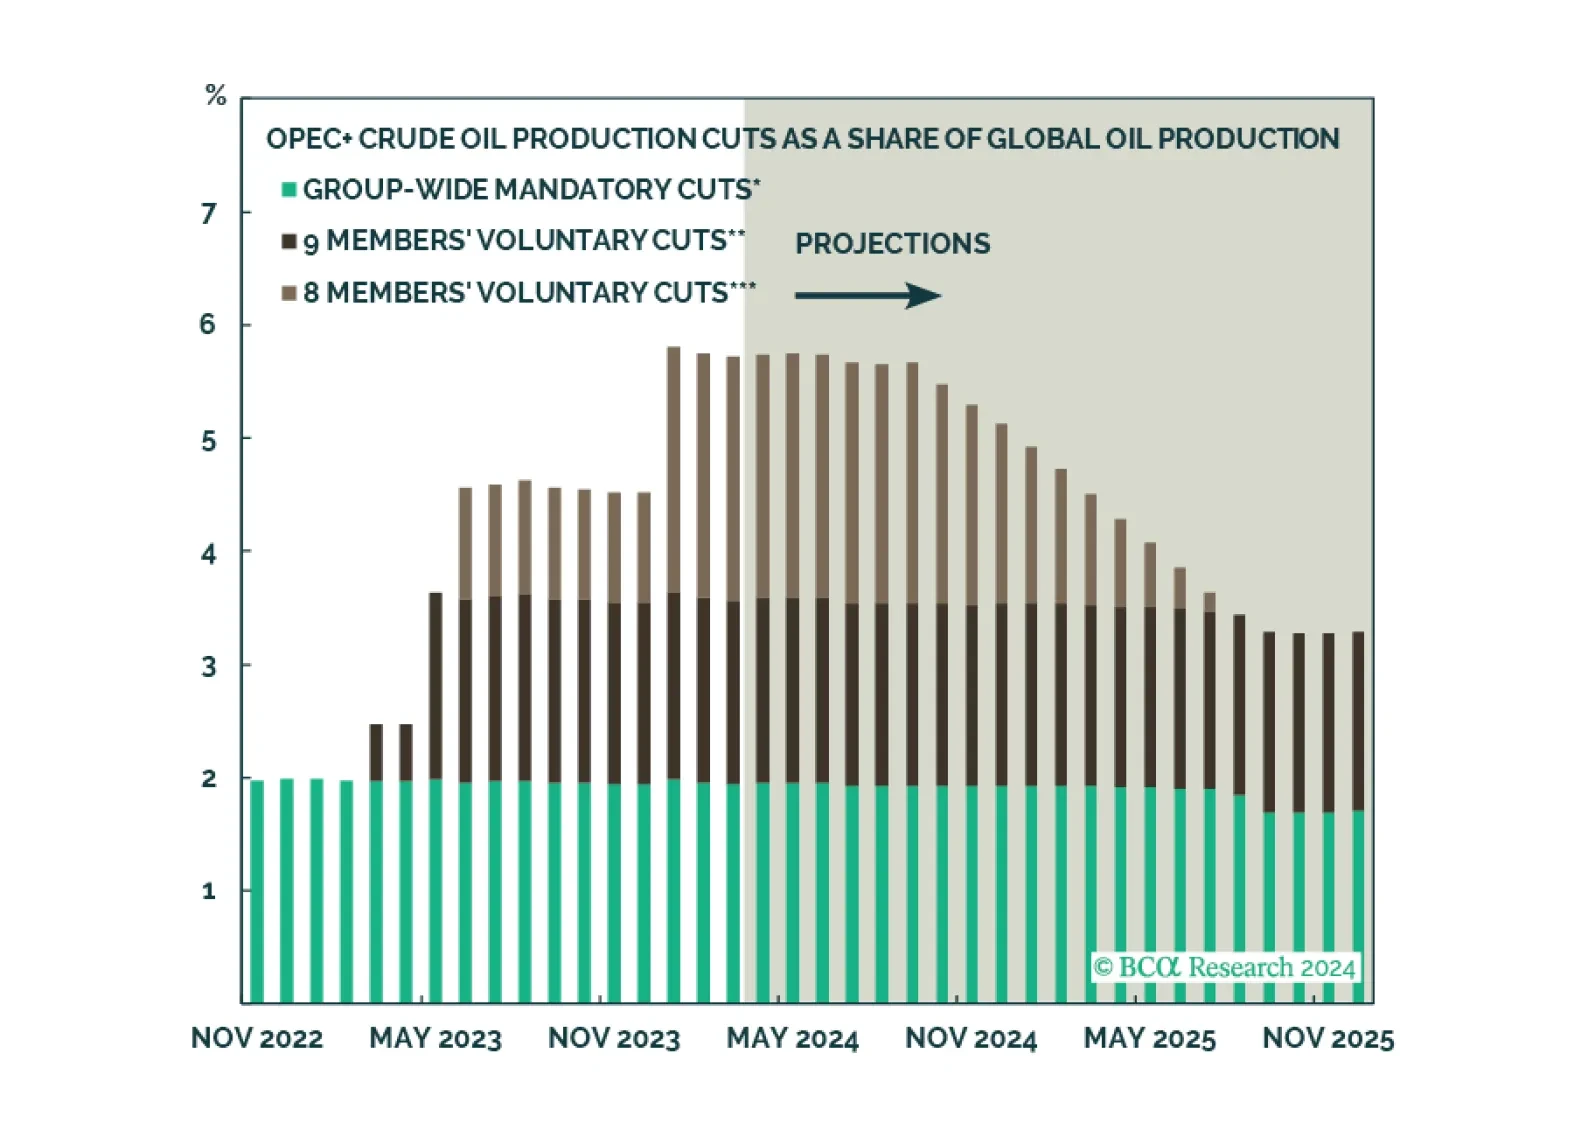
According to OPEC+’s revised production path, the group will begin unwinding some of its production curbs in Q4. This announcement suggests that the coalition might be shifting its strategy towards defending a price floor. Such a shift in OPEC+ strategy does not imply that the ‘OPEC put’ is completely dead. Rather, its strike price has been lowered.
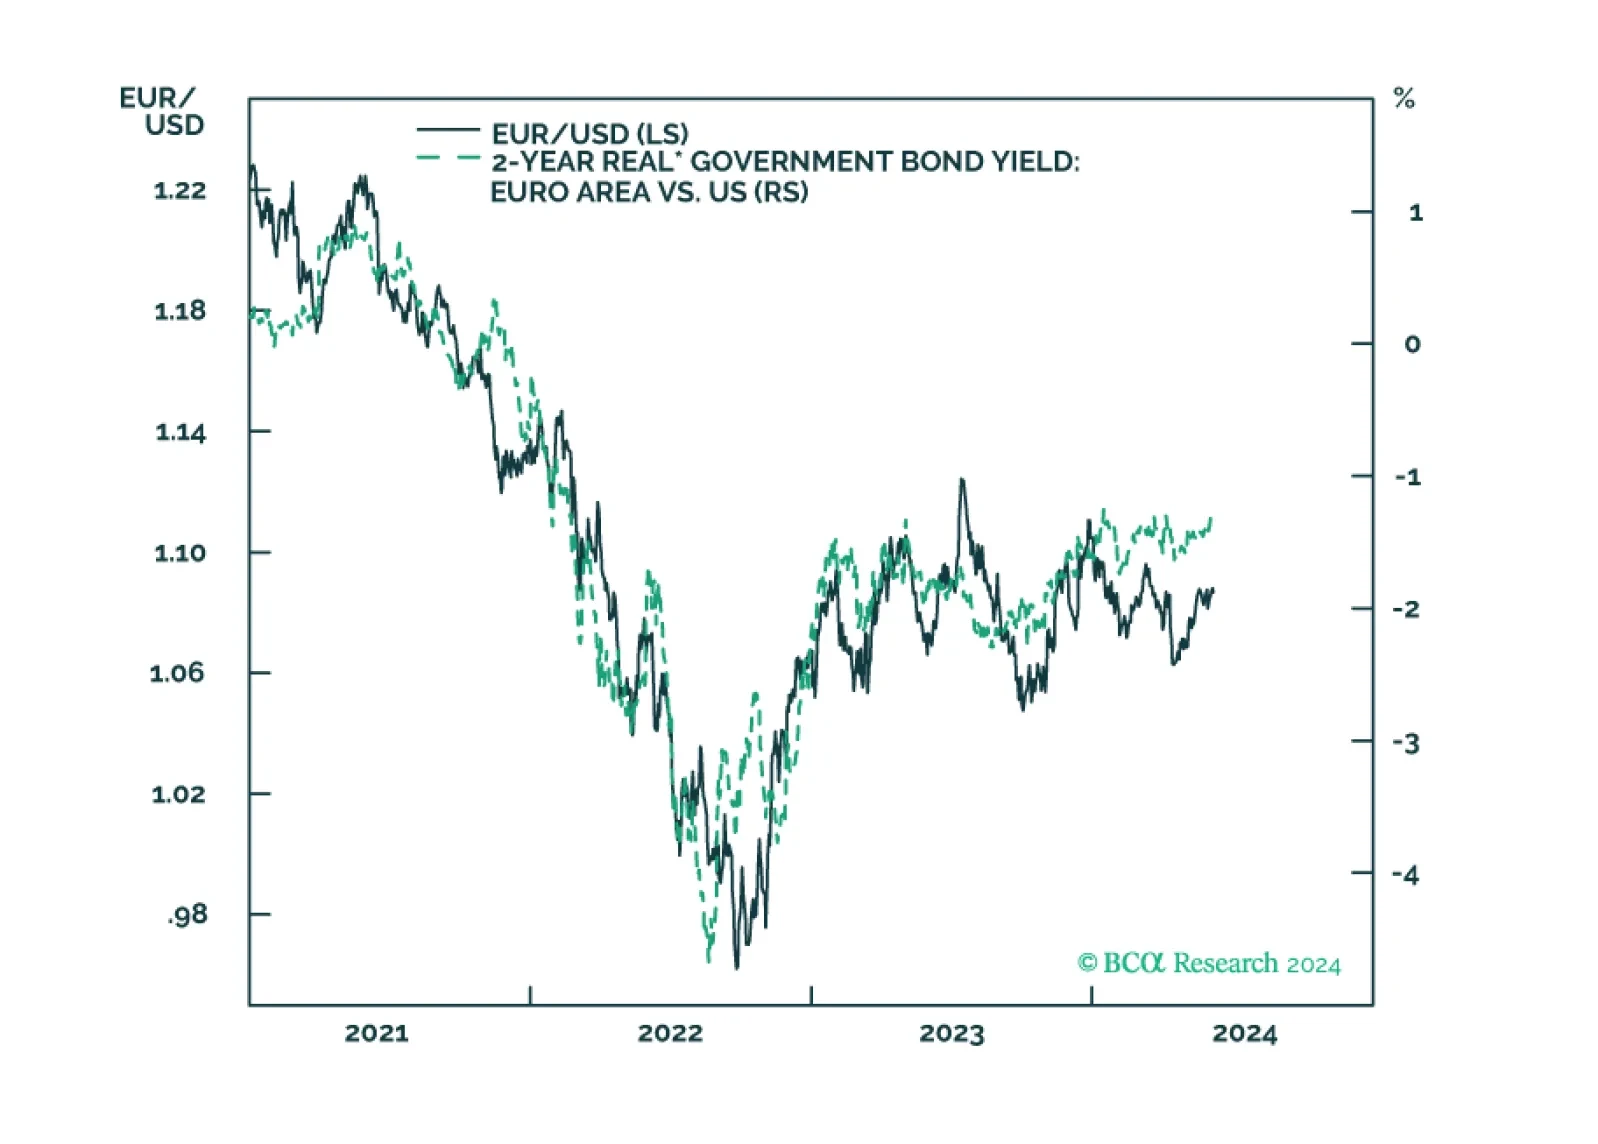
A short insight on the ECB and near-term implications for European asset markets.