 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
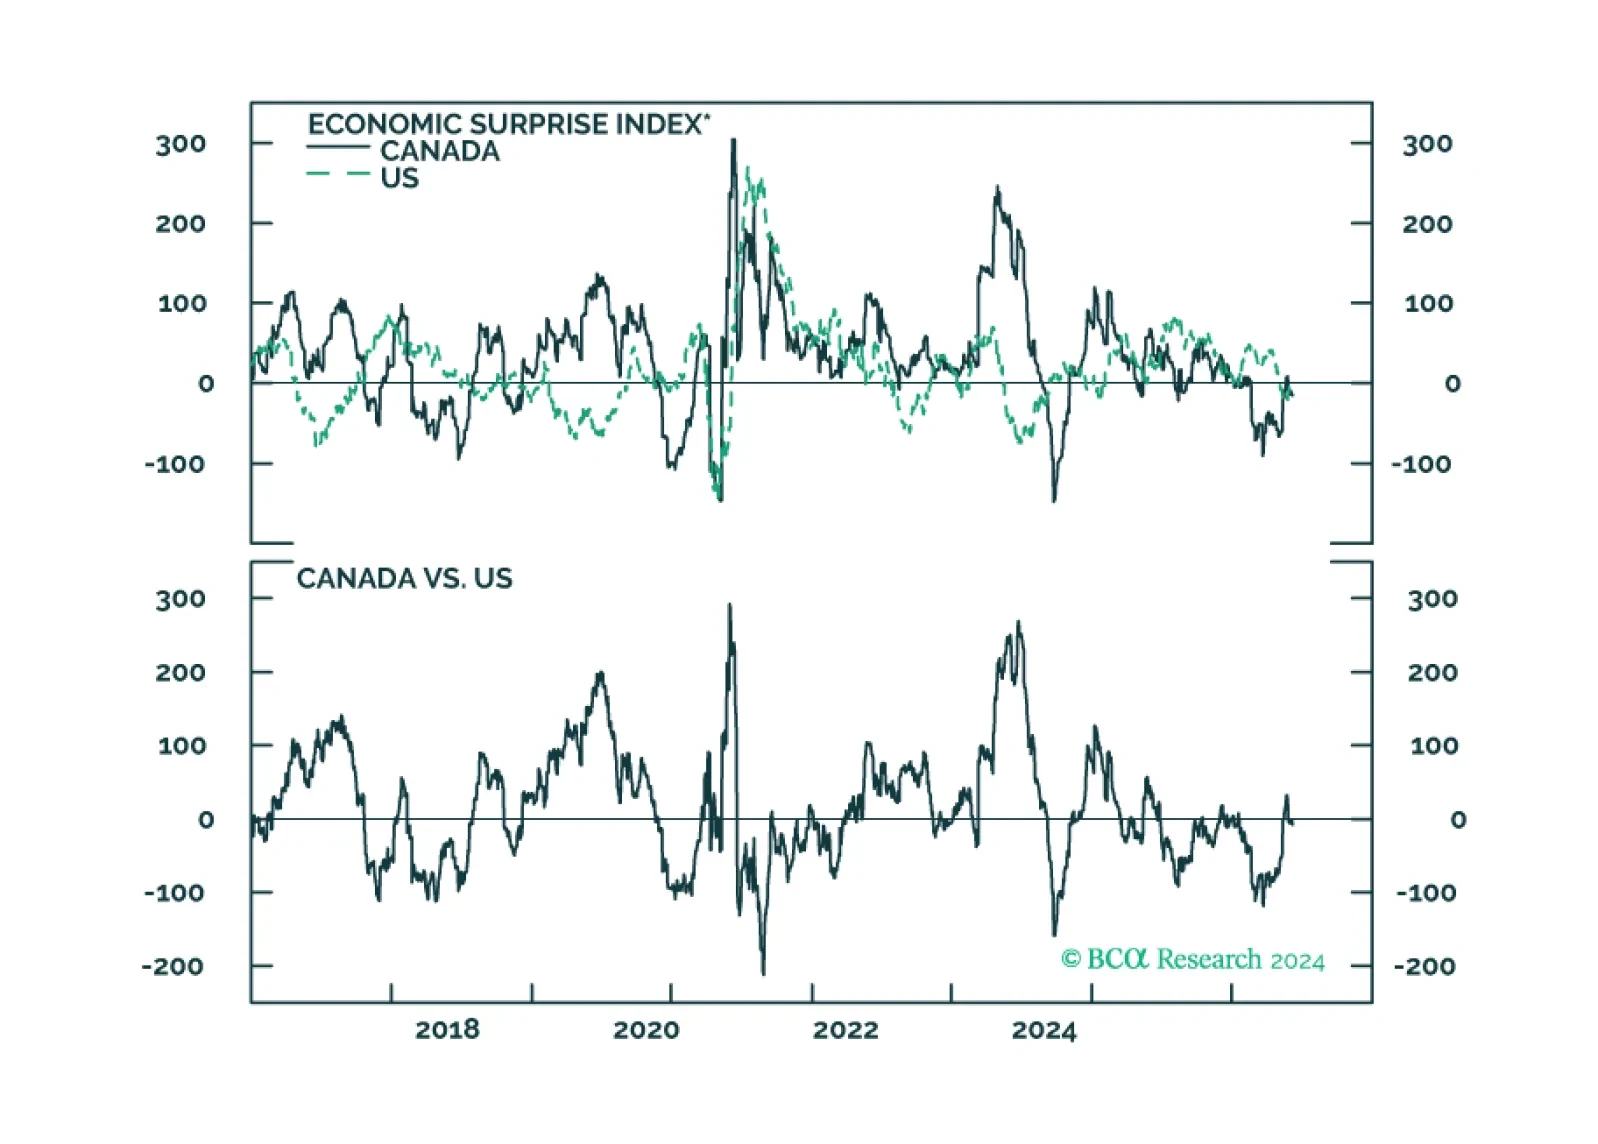
In this insight, we provide an update on the Canadian economy, given yesterday’s rate cut, and implications for Canadian assets.
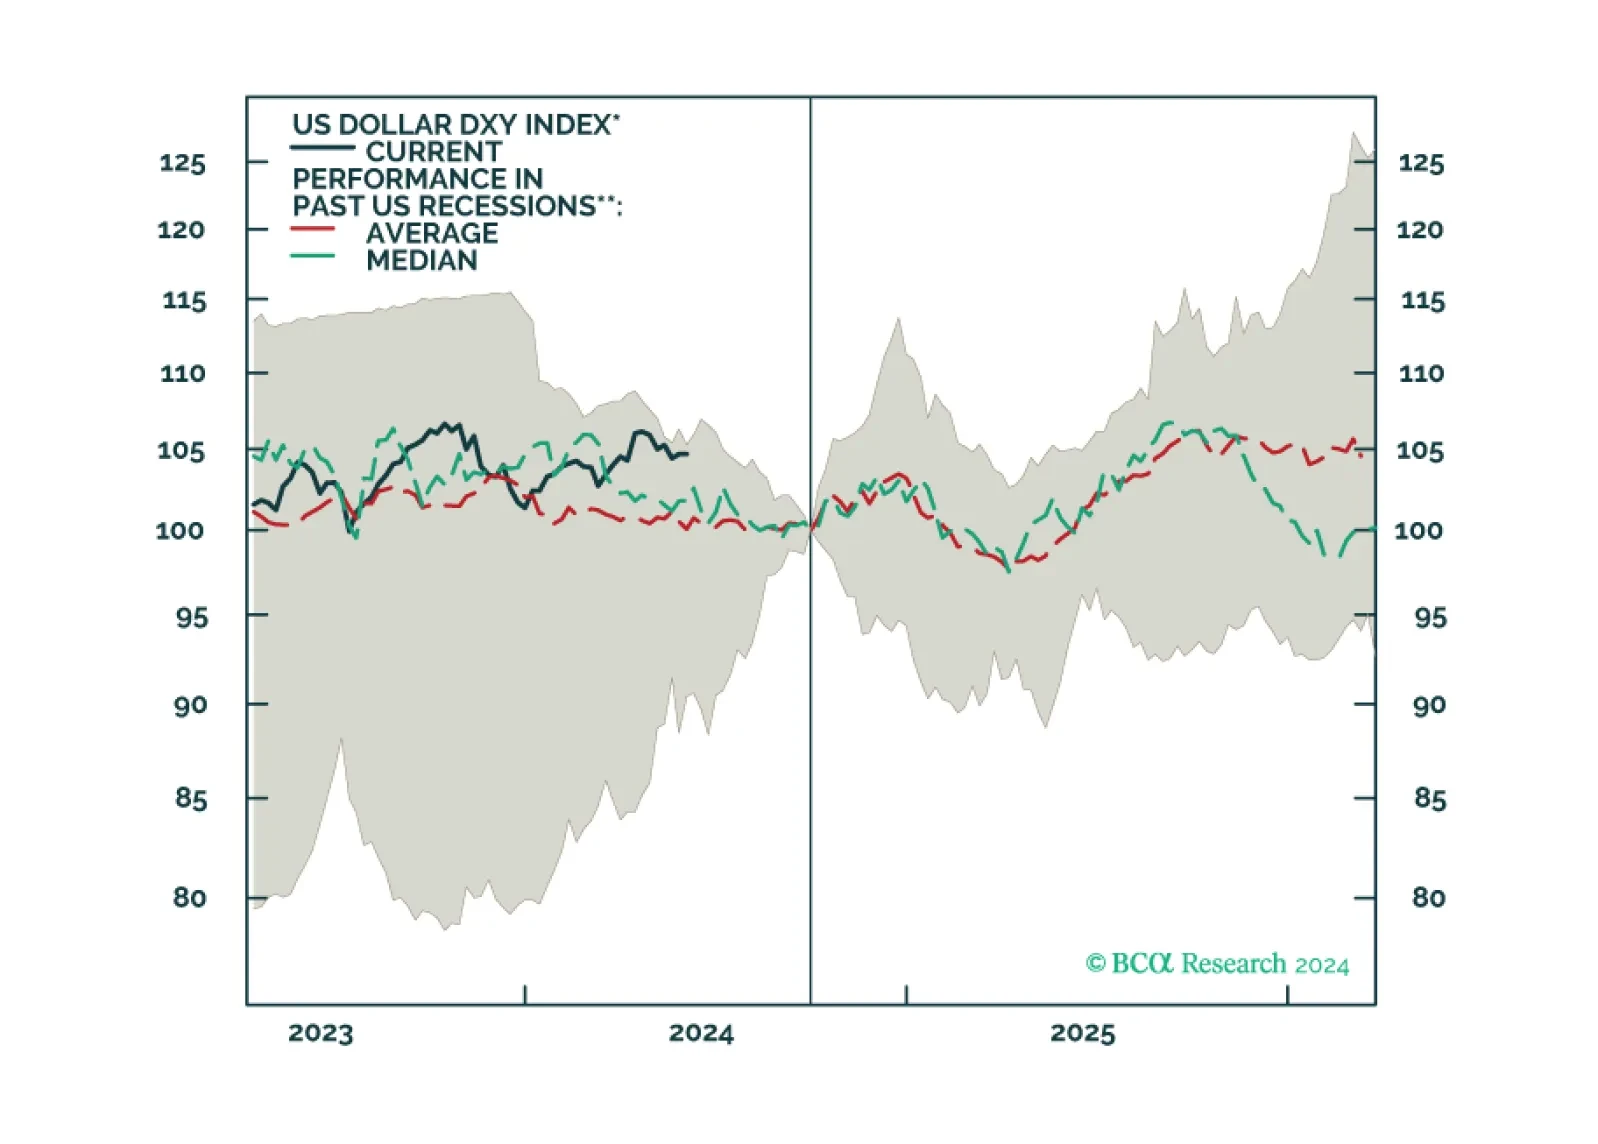
In this report, we gauge the outlook for the dollar given client visits in Africa.
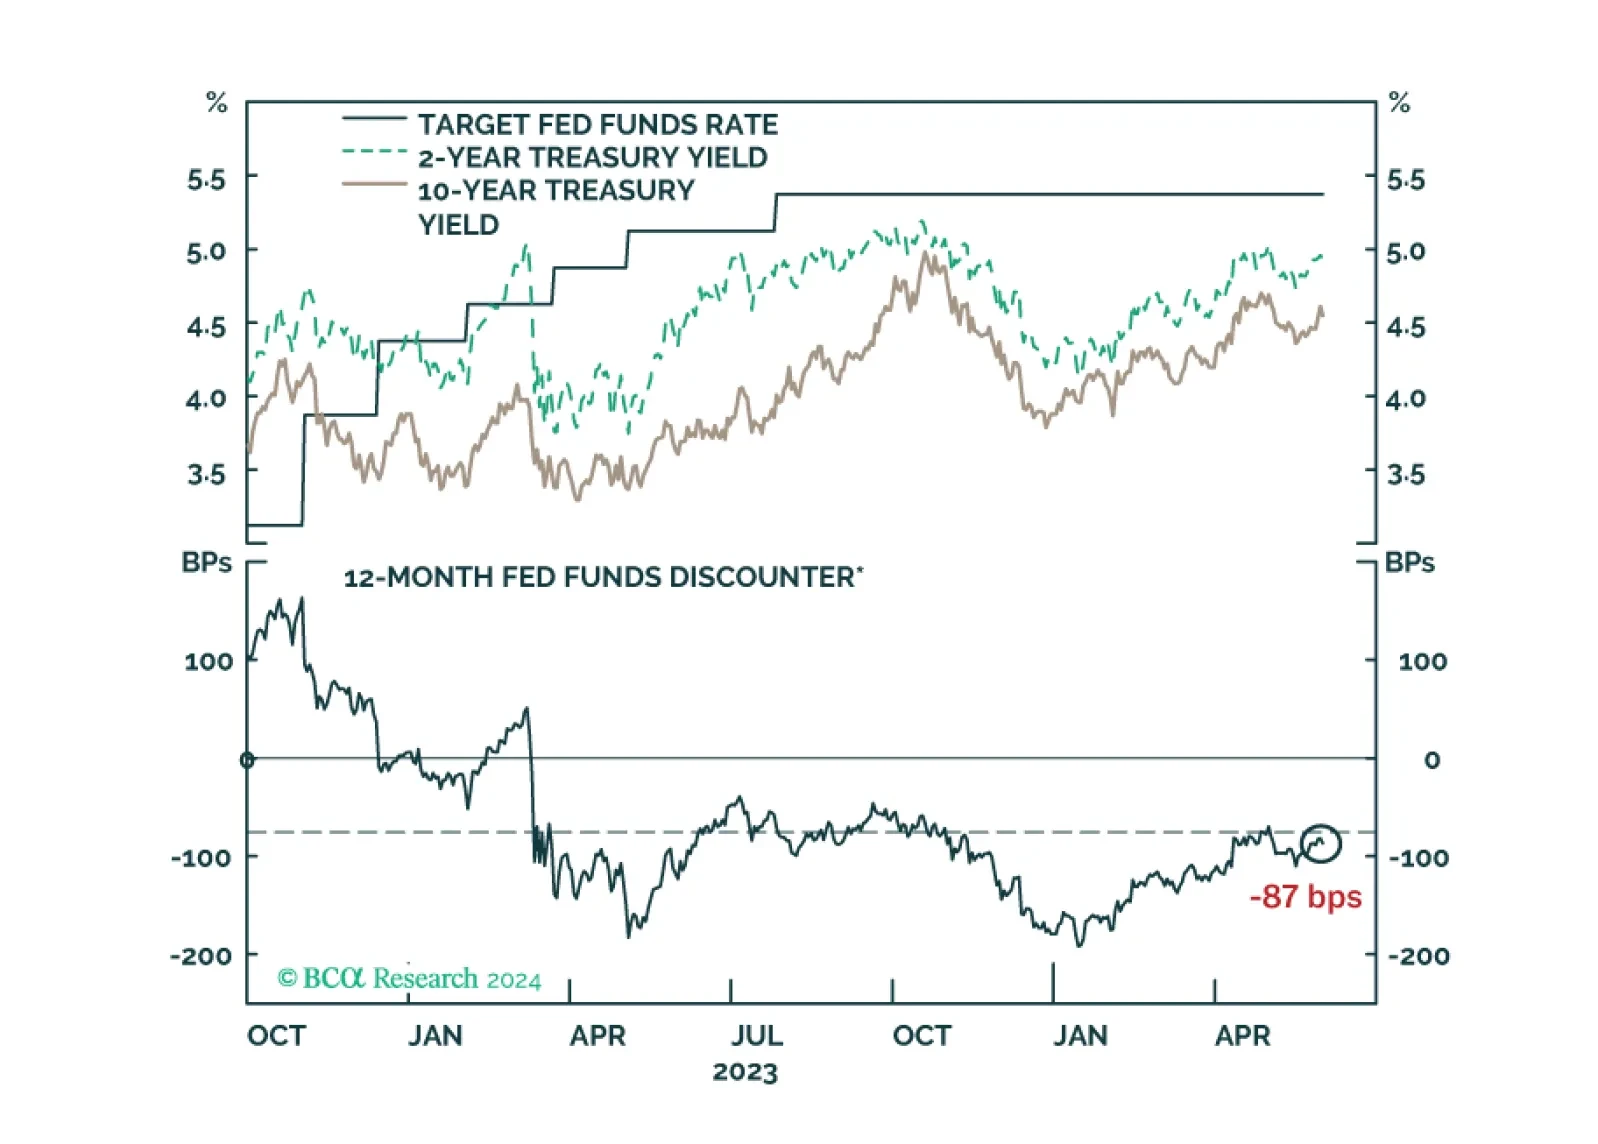
We comment on whether Treasury market valuation is sufficiently attractive to get long bonds and consider some of the common arguments for why yields may yet make new highs.
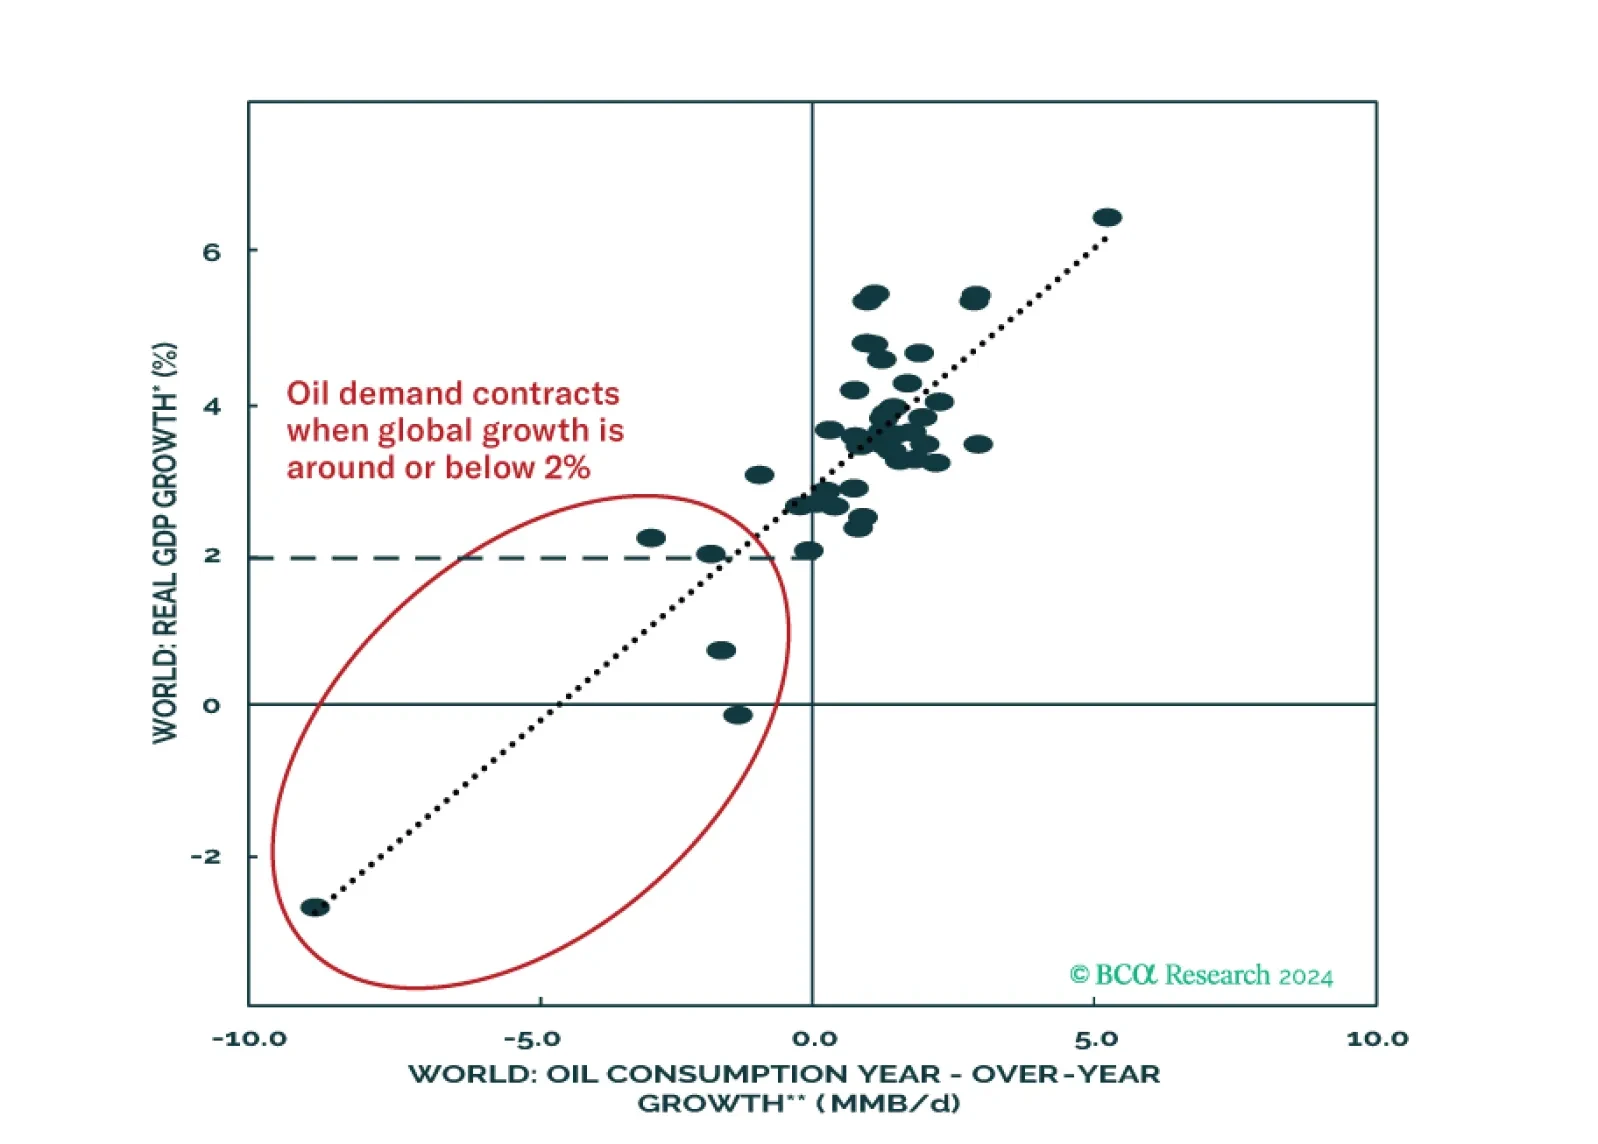
The three major oil forecasters – IEA, EIA, and OPEC – are forecasting oil demand growth until 2025 to be broadly in line with its range over the past four decades. On a cyclical horizon, we give high odds that a recession will begin within the coming 6-12 months, disappointing these oil demand forecasts. On a strategic horizon, the IEA projects EVs will displace 9% of global oil demand by 2035, serving as a long-term demand headwind.
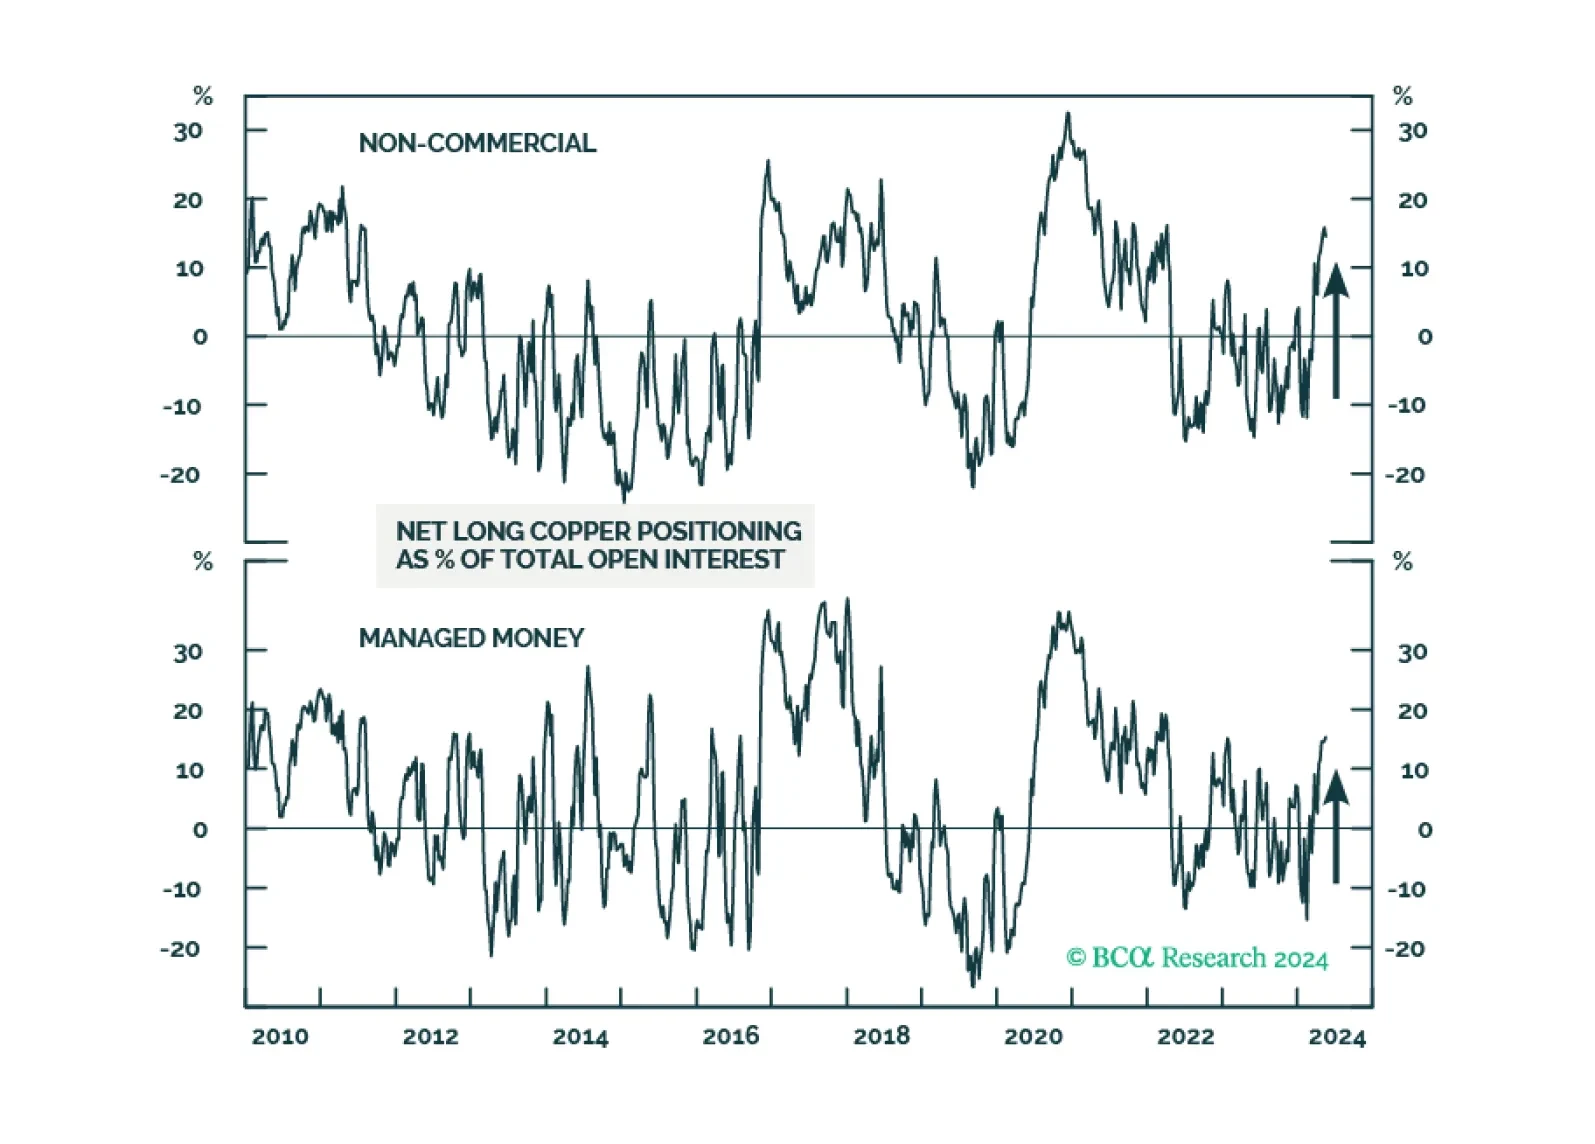
The sharp move higher in copper prices is missing a clear fundamental catalyst. Meanwhile, the cyclical outlook for the global economy in general, and manufacturing activity in particular, is unlikely to provide a tailwind. Given that aggregate copper inventories on global exchanges have been rising briskly, there are high odds that the copper price surge will soon reverse.
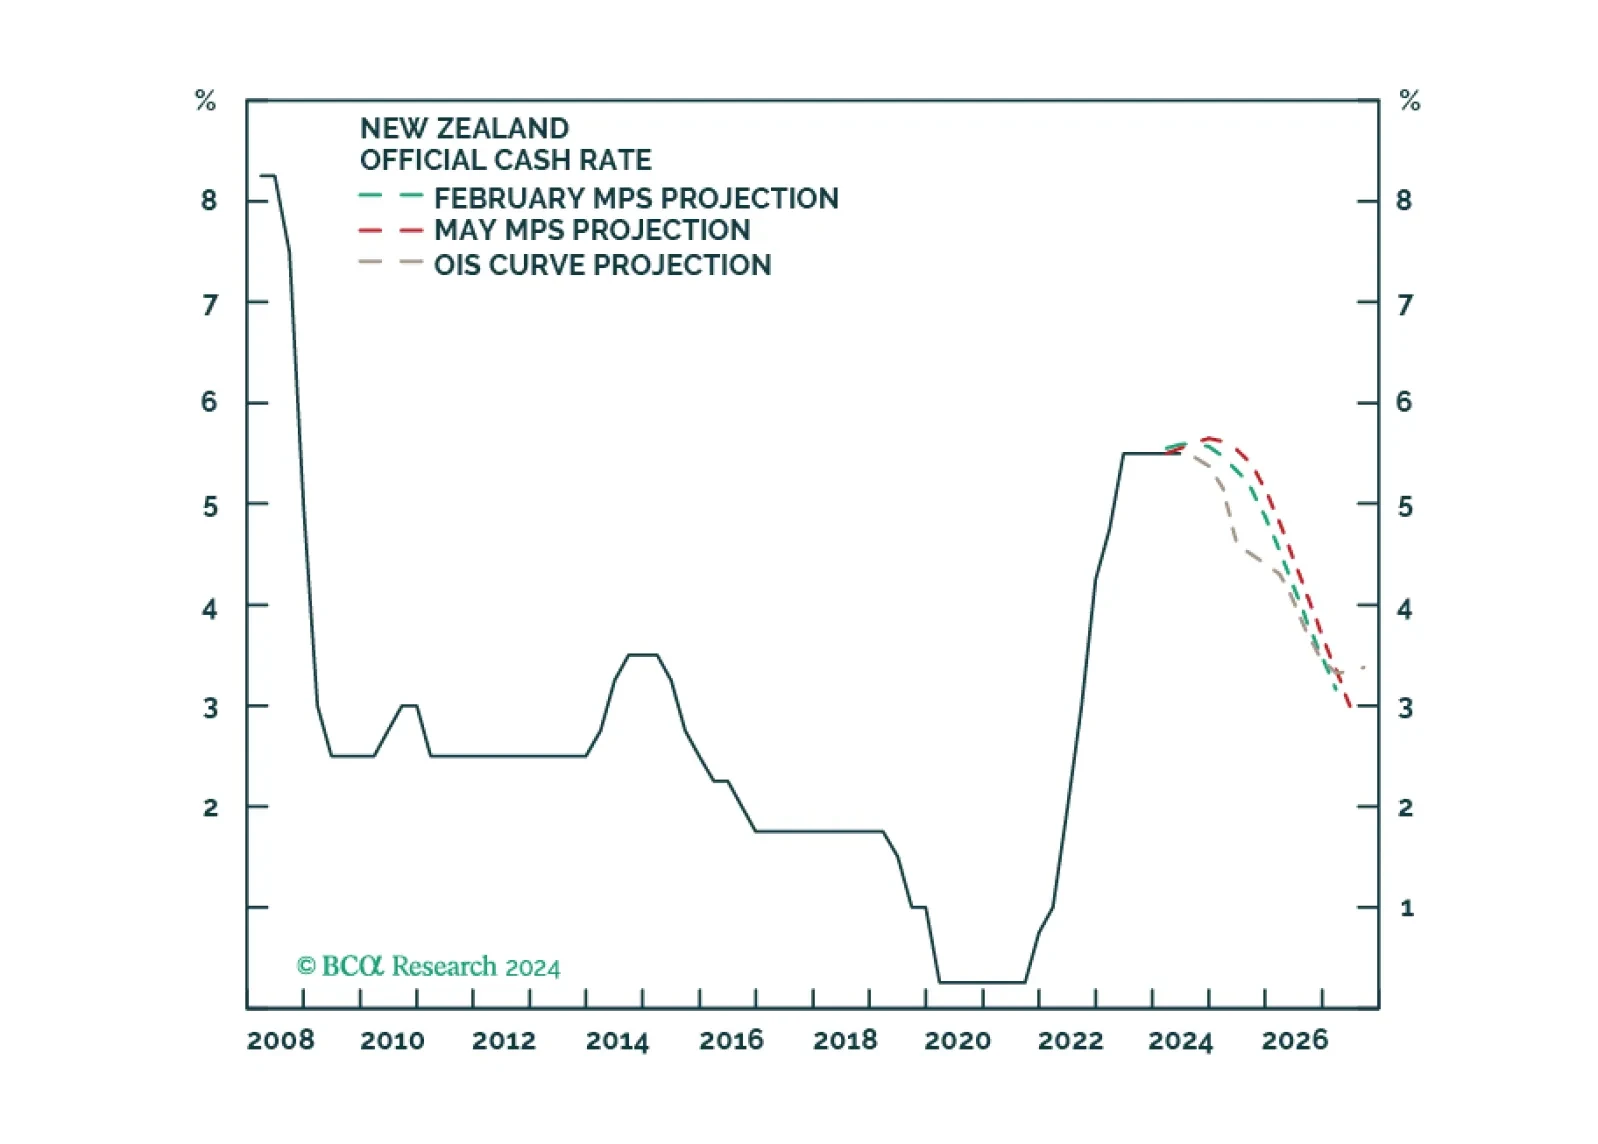
In this Insight, we revisit our "higher for longer" theme for the Reserve Bank of New Zealand, in light of the latest central bank meeting. In conclusion, we are inching towards a more dovish RBNZ ahead. Ergo, we recommend some fixed income and currency trades.
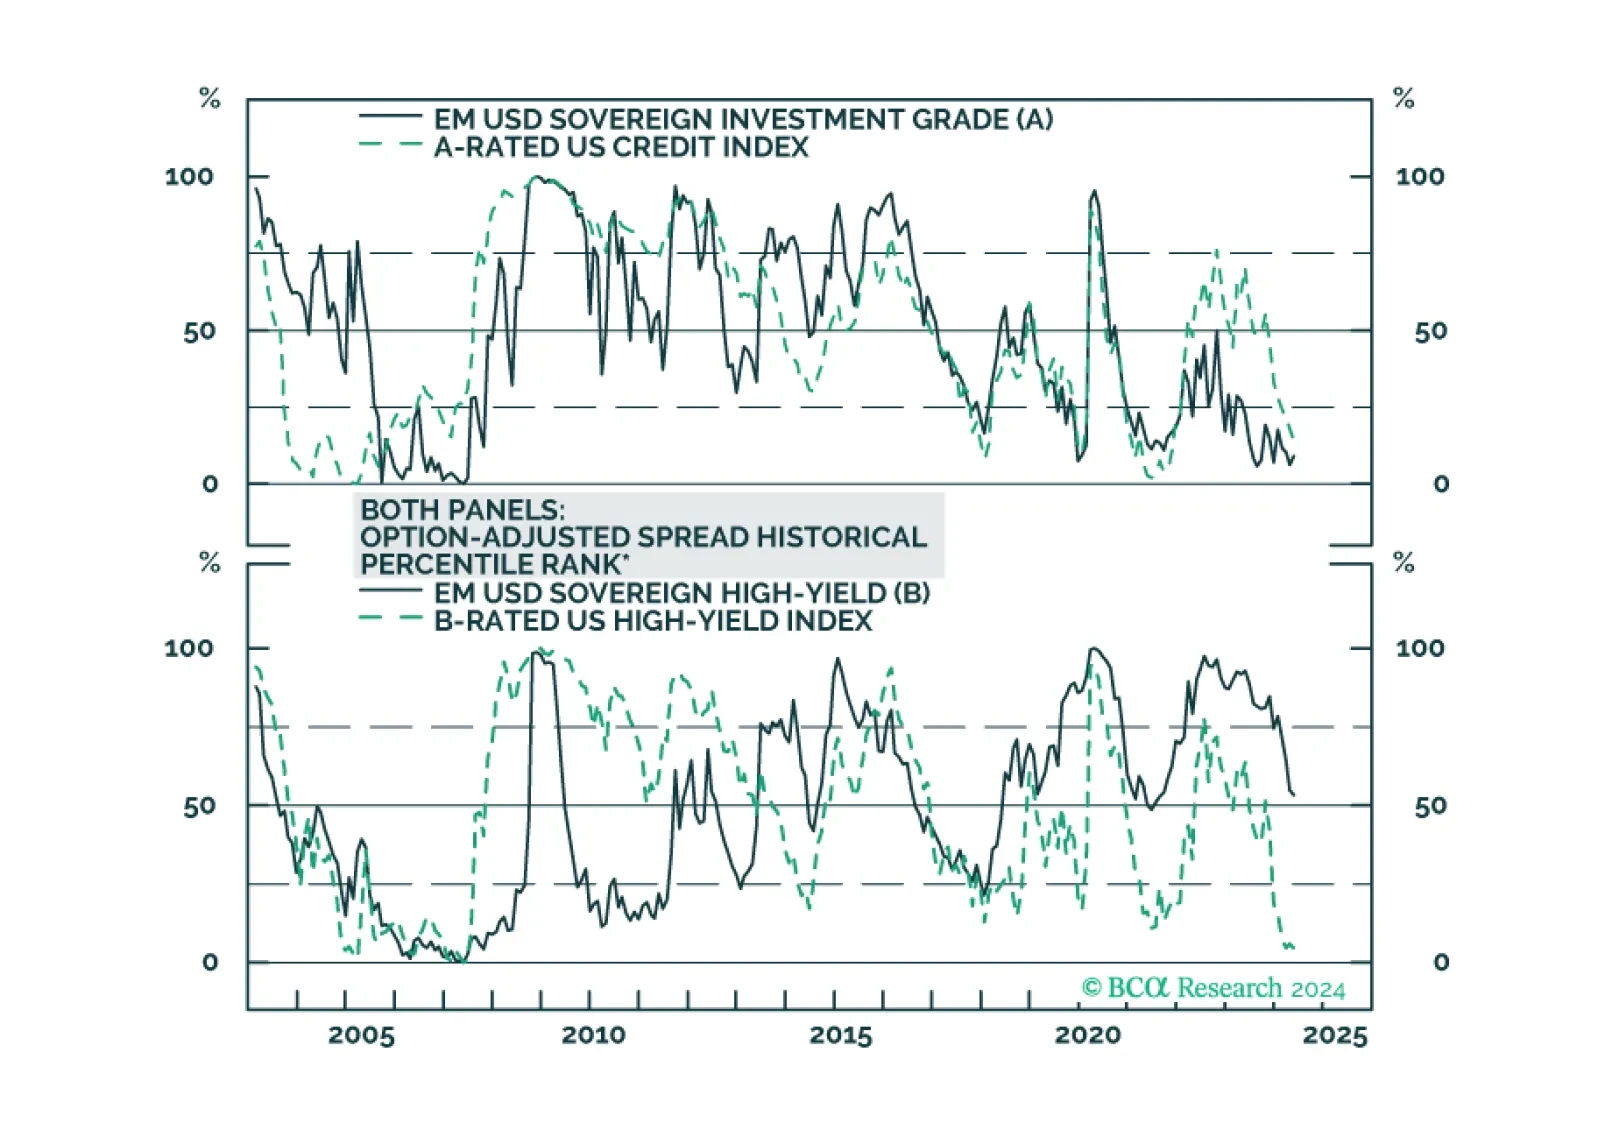
We dig into the USD-denominated Emerging Market Sovereign Index to see which credit tiers and countries offer value relative to US Credit.