 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
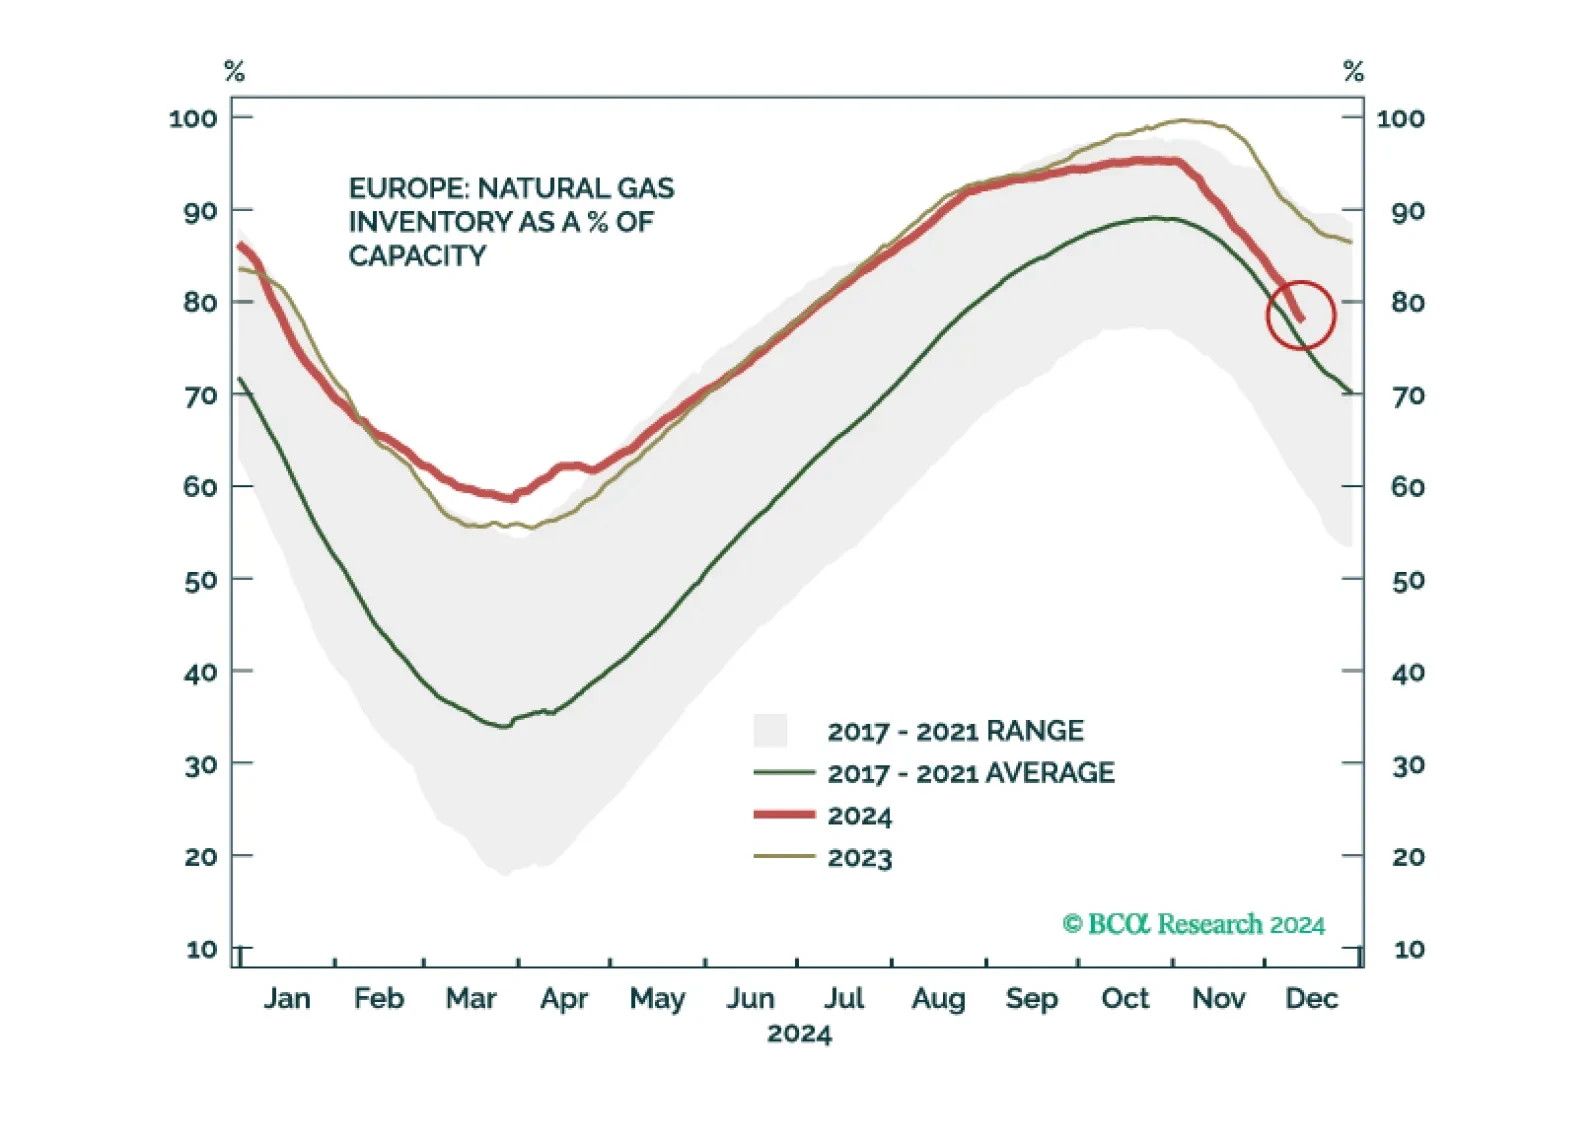
A confluence of both supply and demand factors contributed to the natural gas rally over the past few months. This trend could continue for a while longer. However, cyclical and structural factors ultimately argue against a sustained increase in prices.
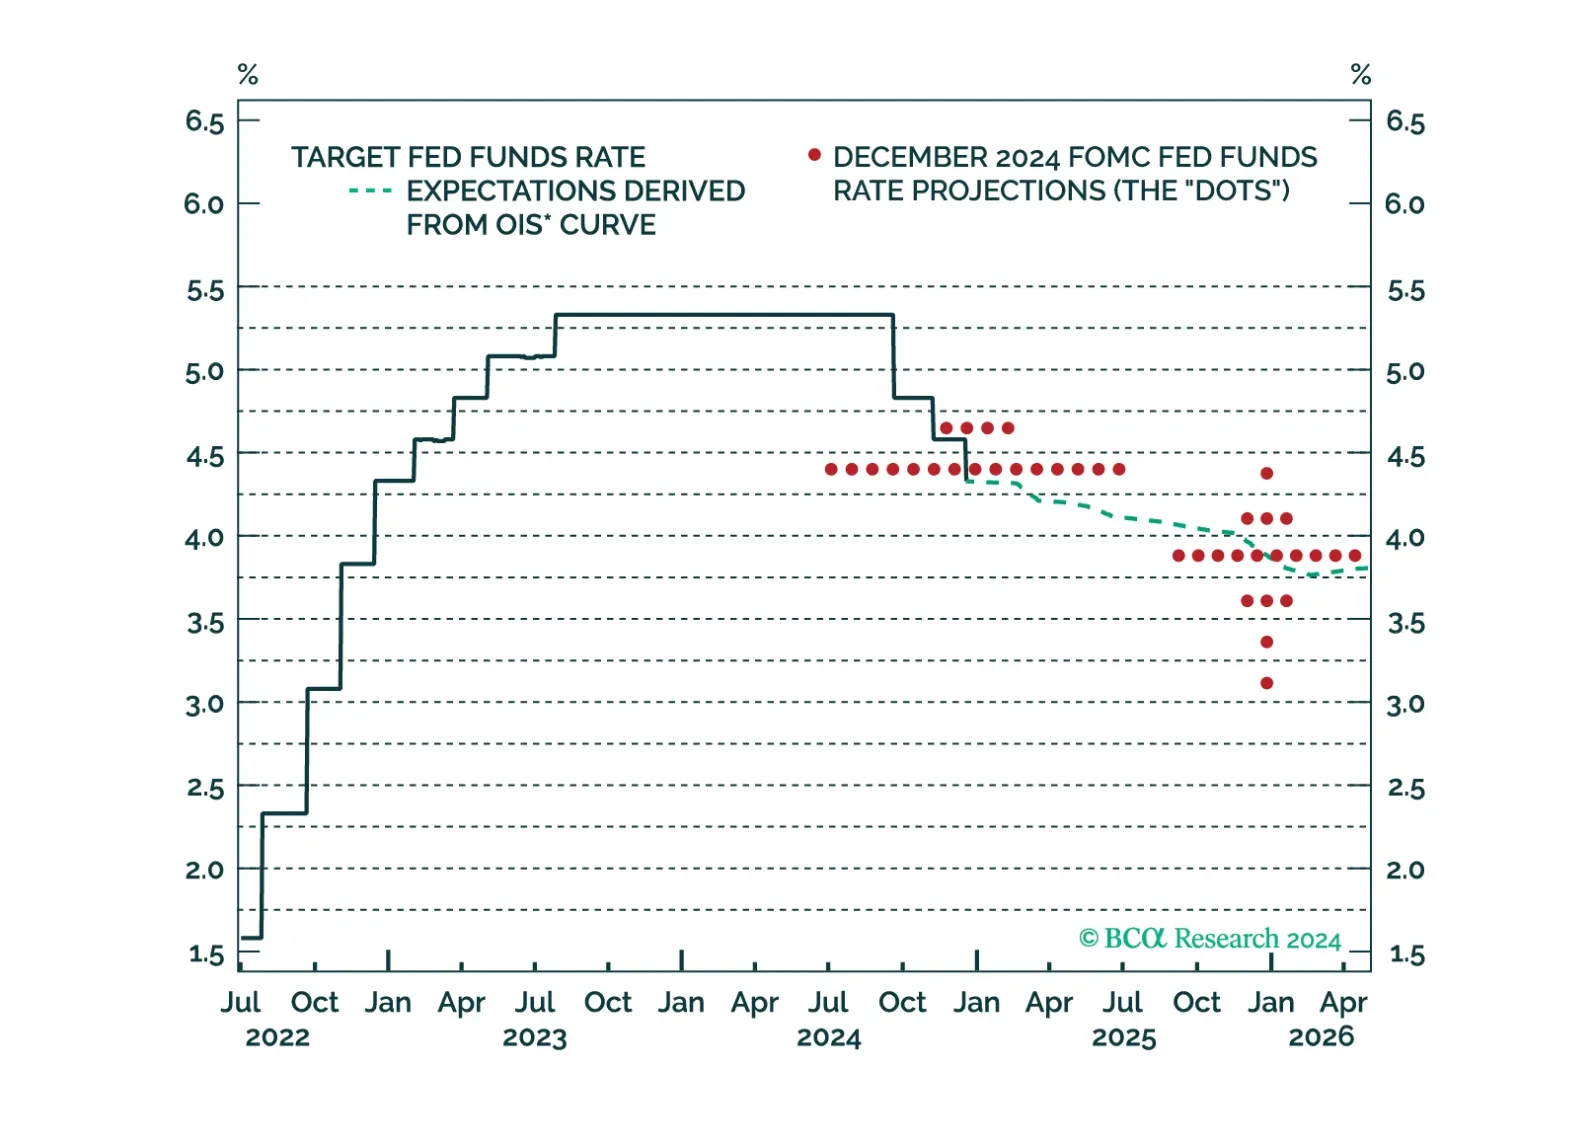
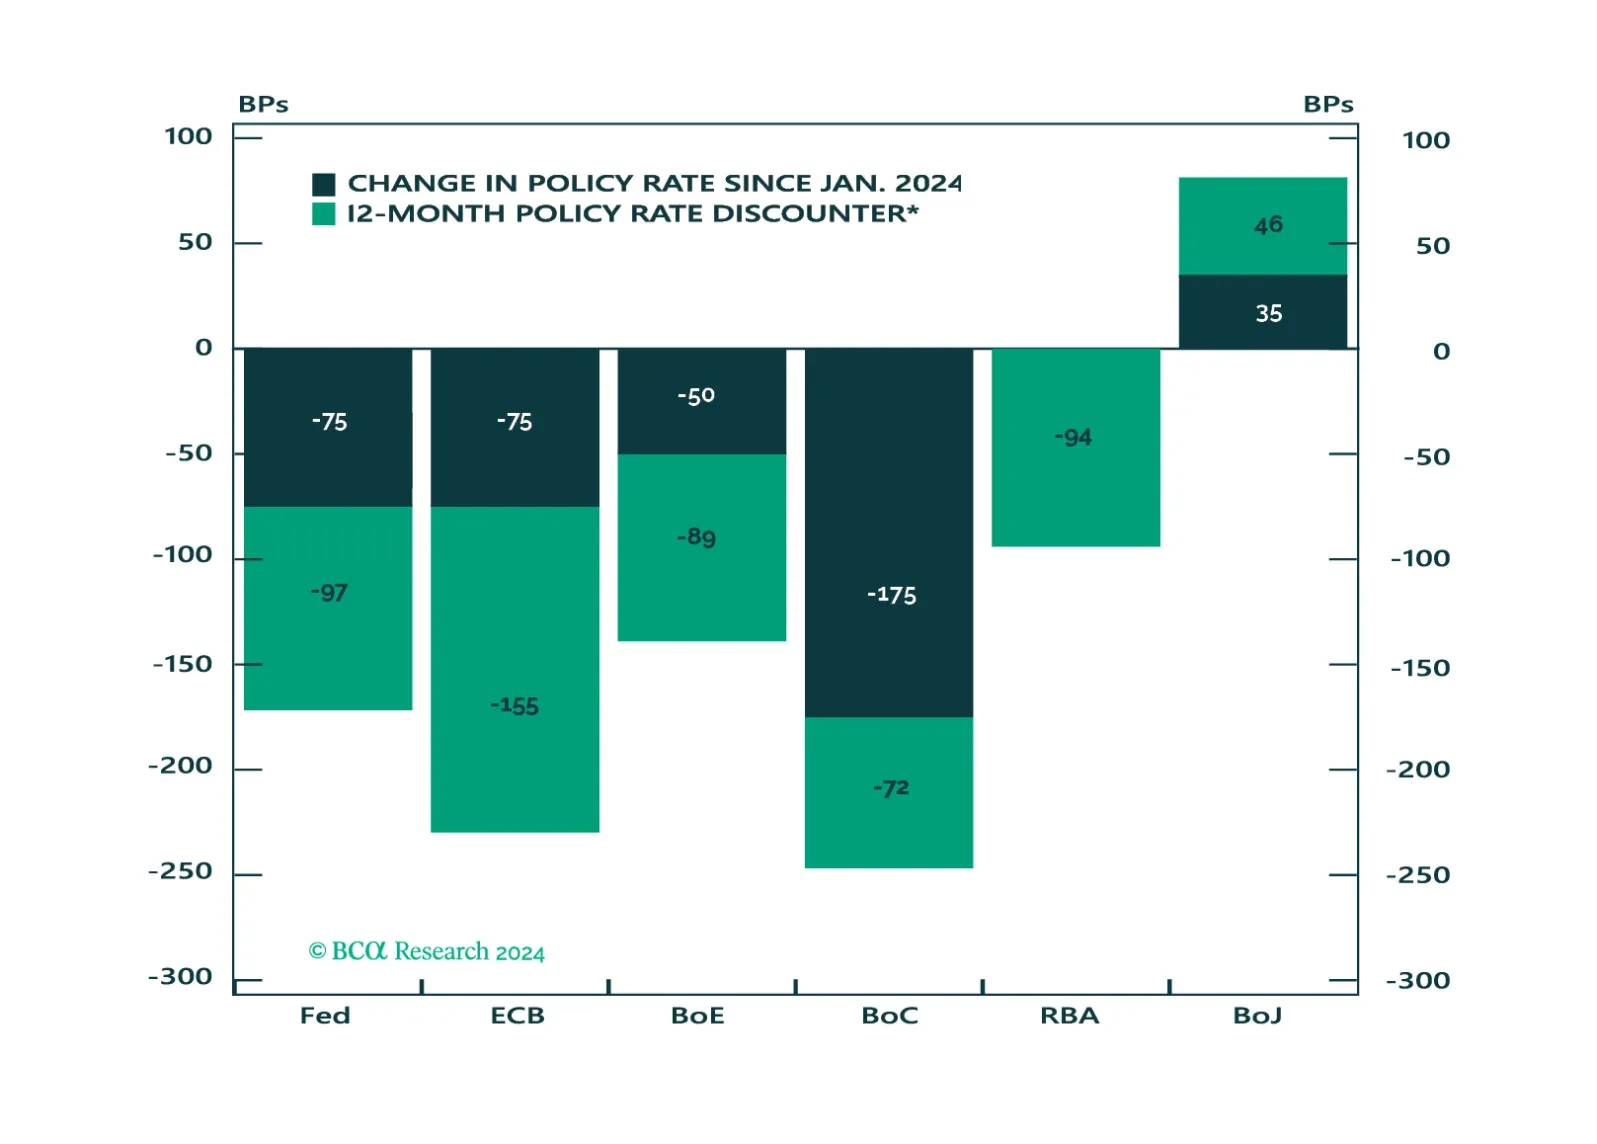
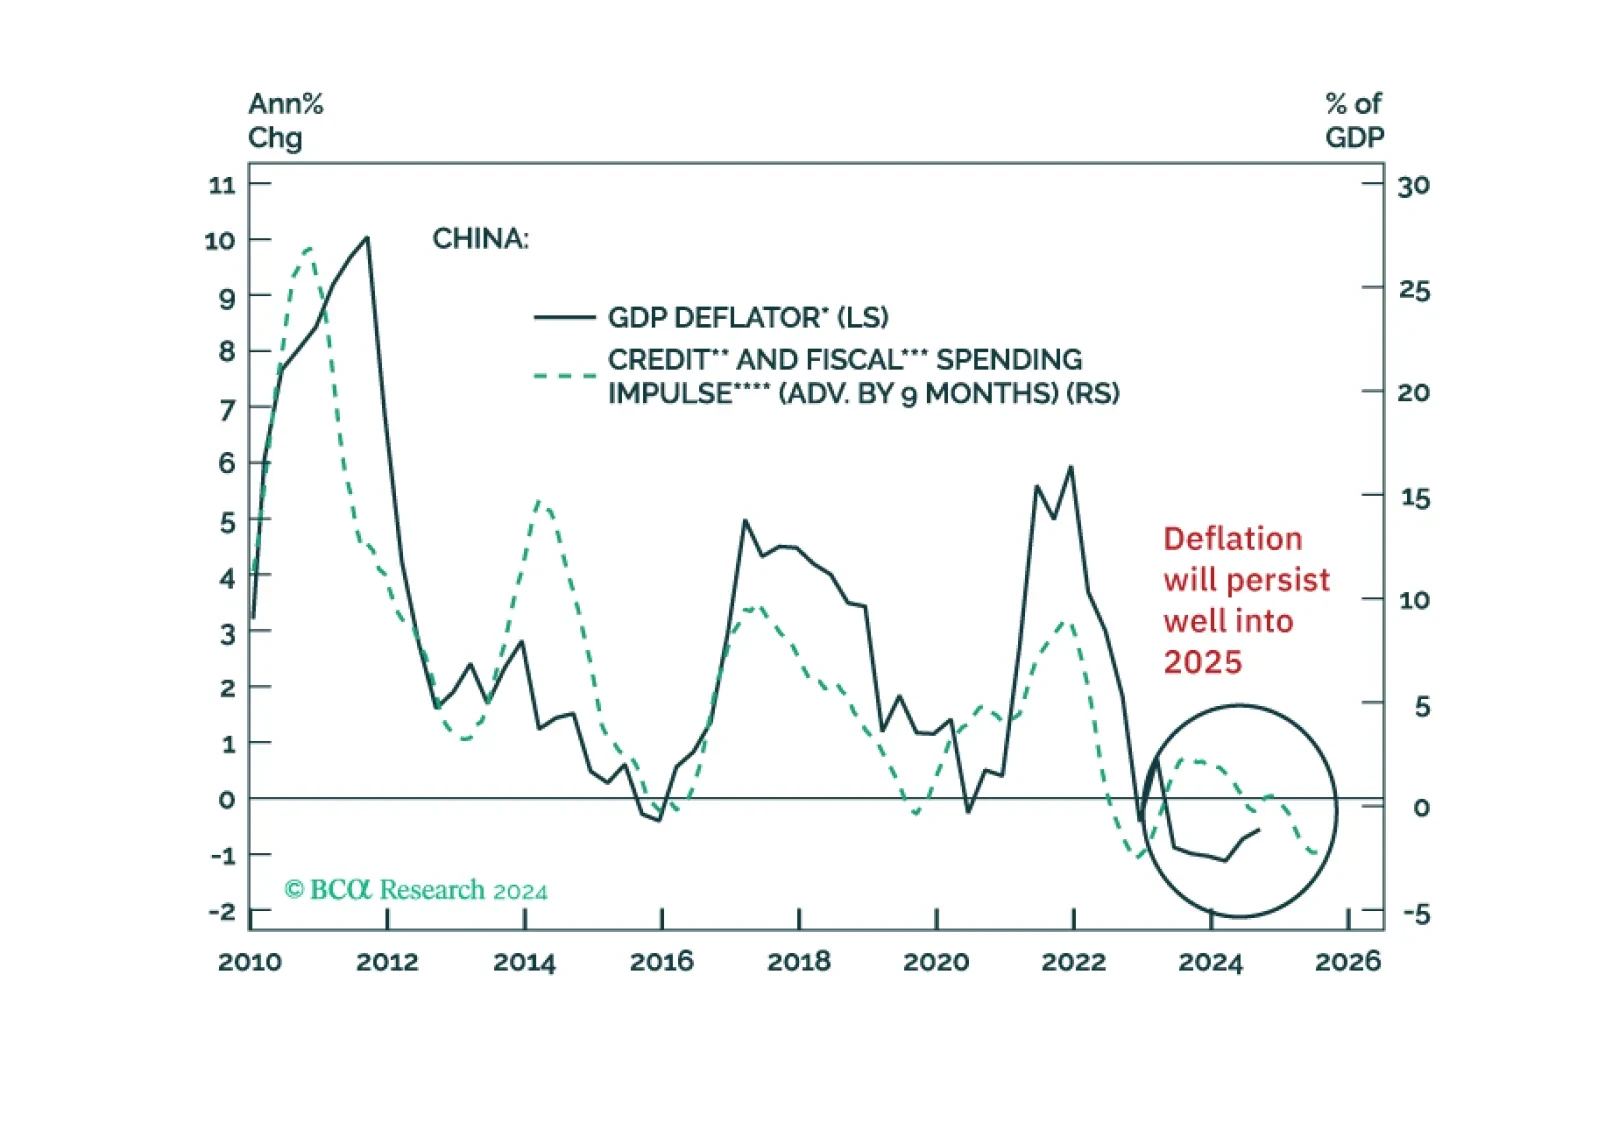
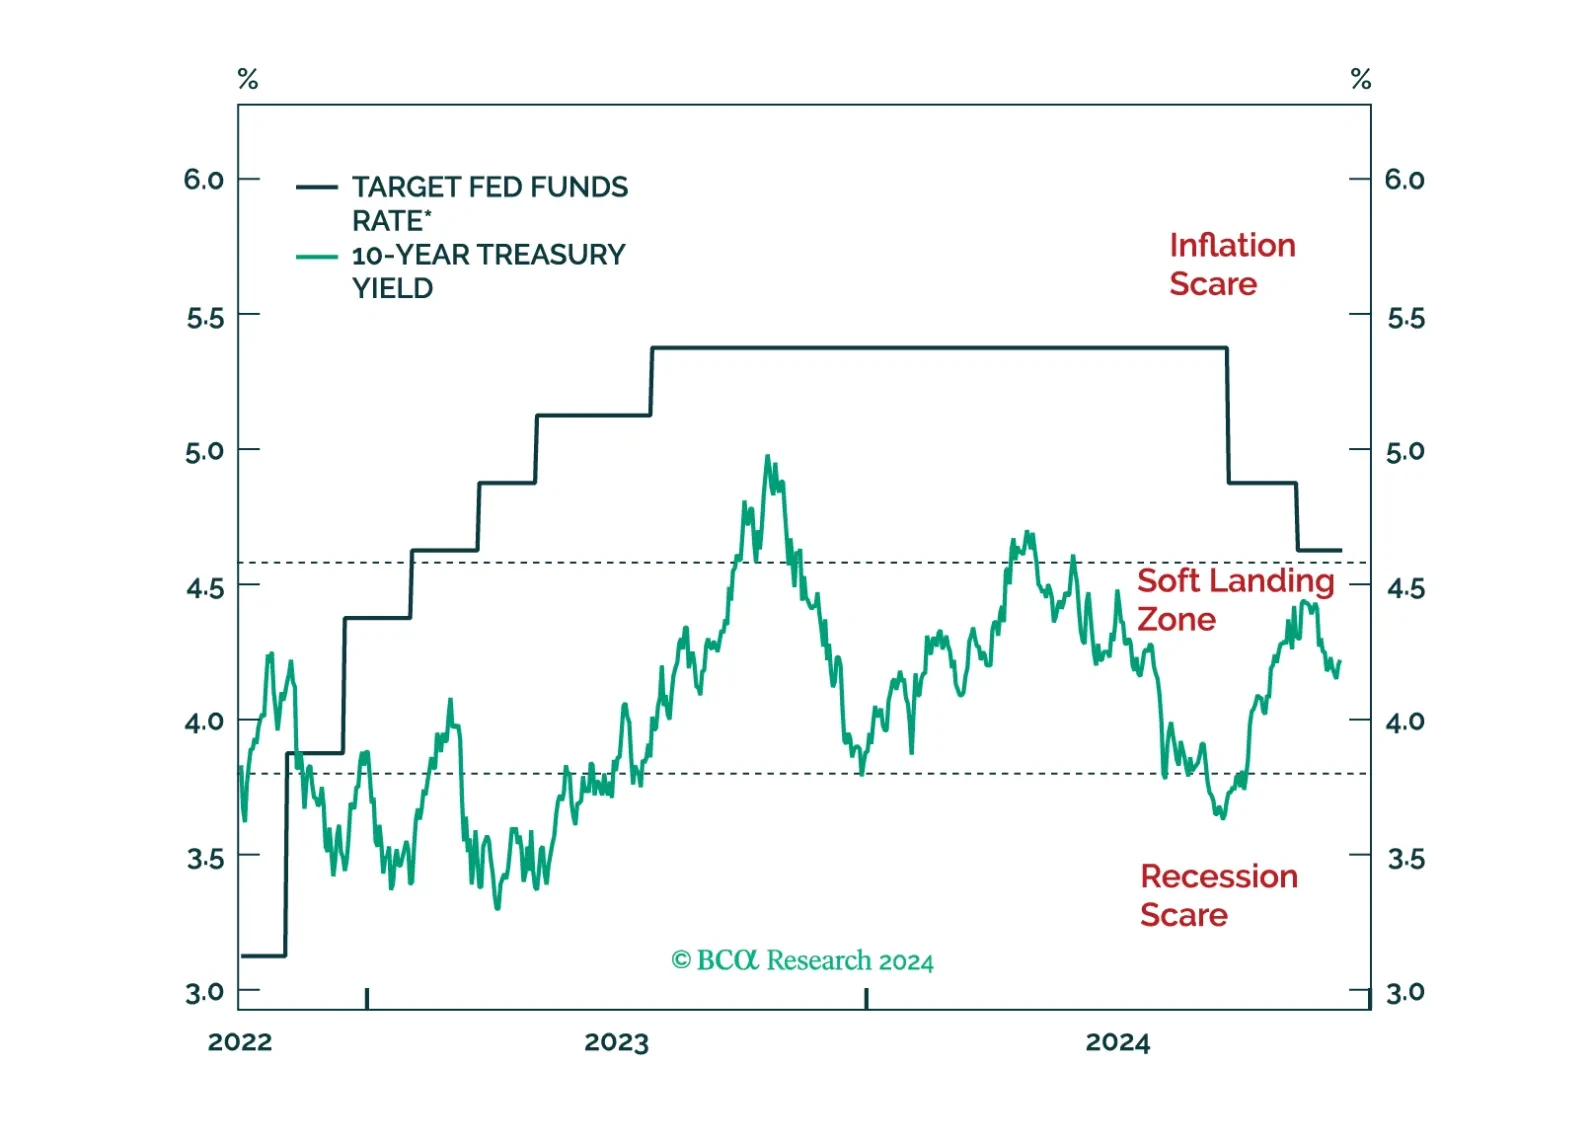
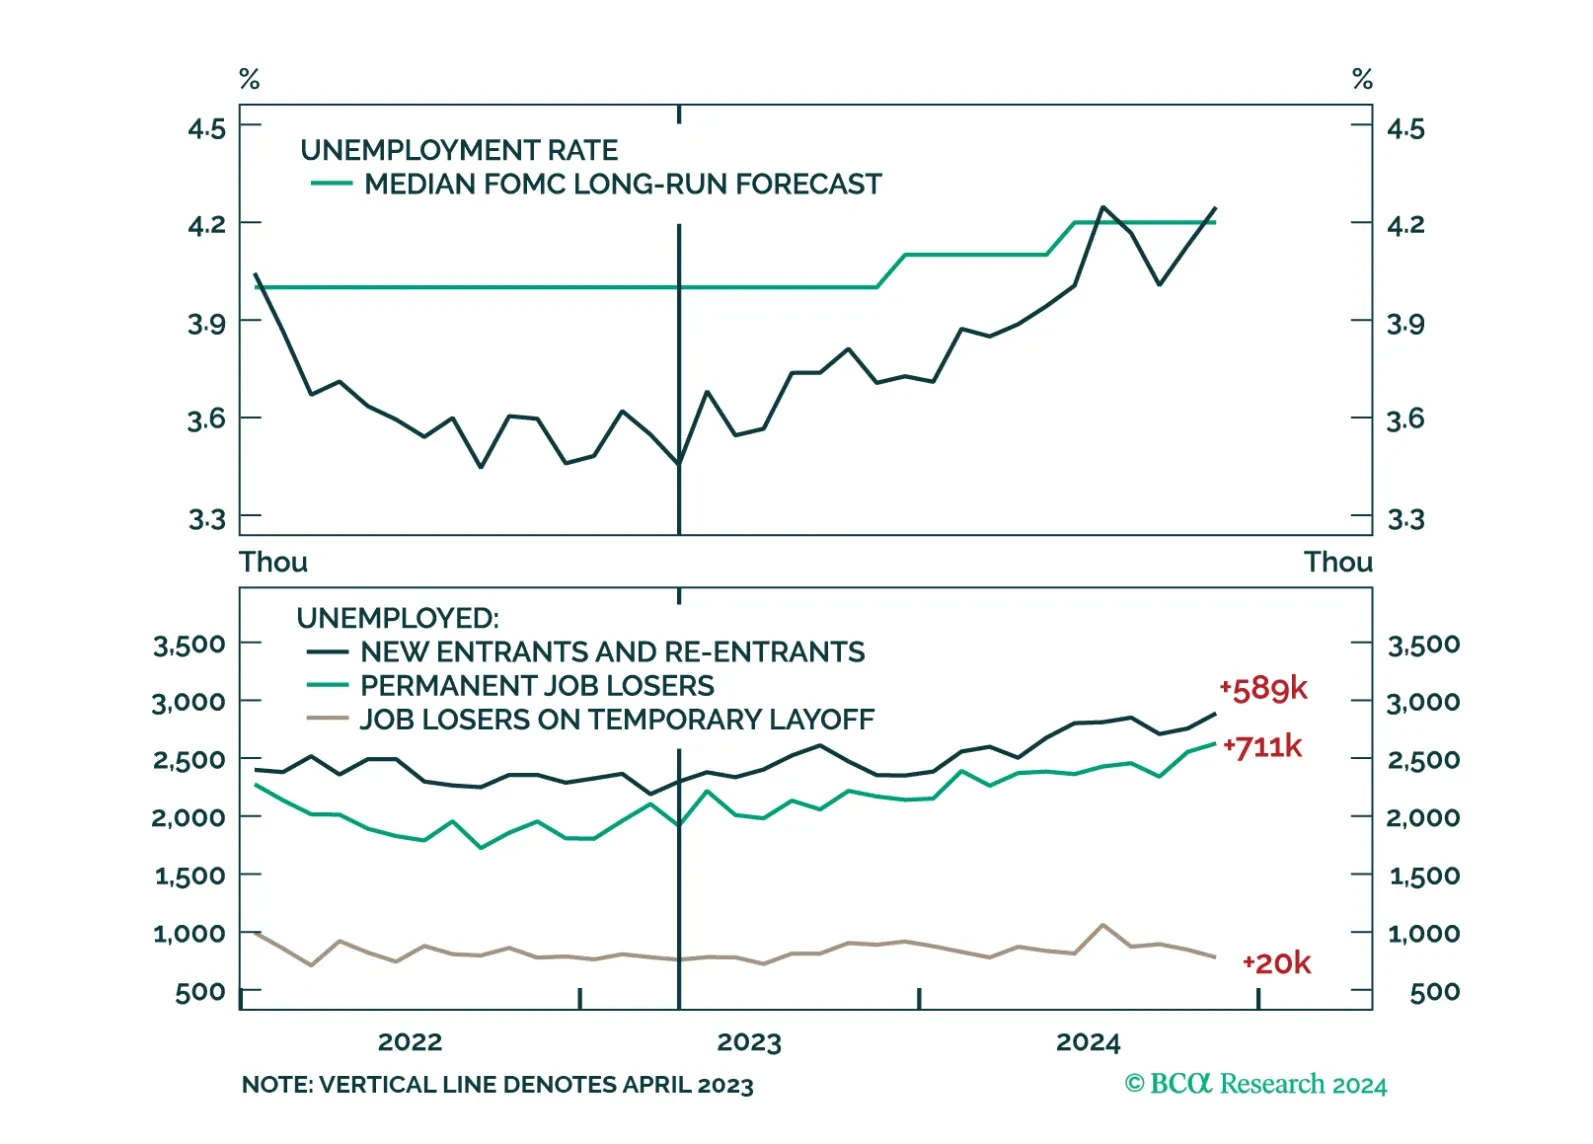
Updated views on trends in labor supply and demand in light of this morning’s employment report.
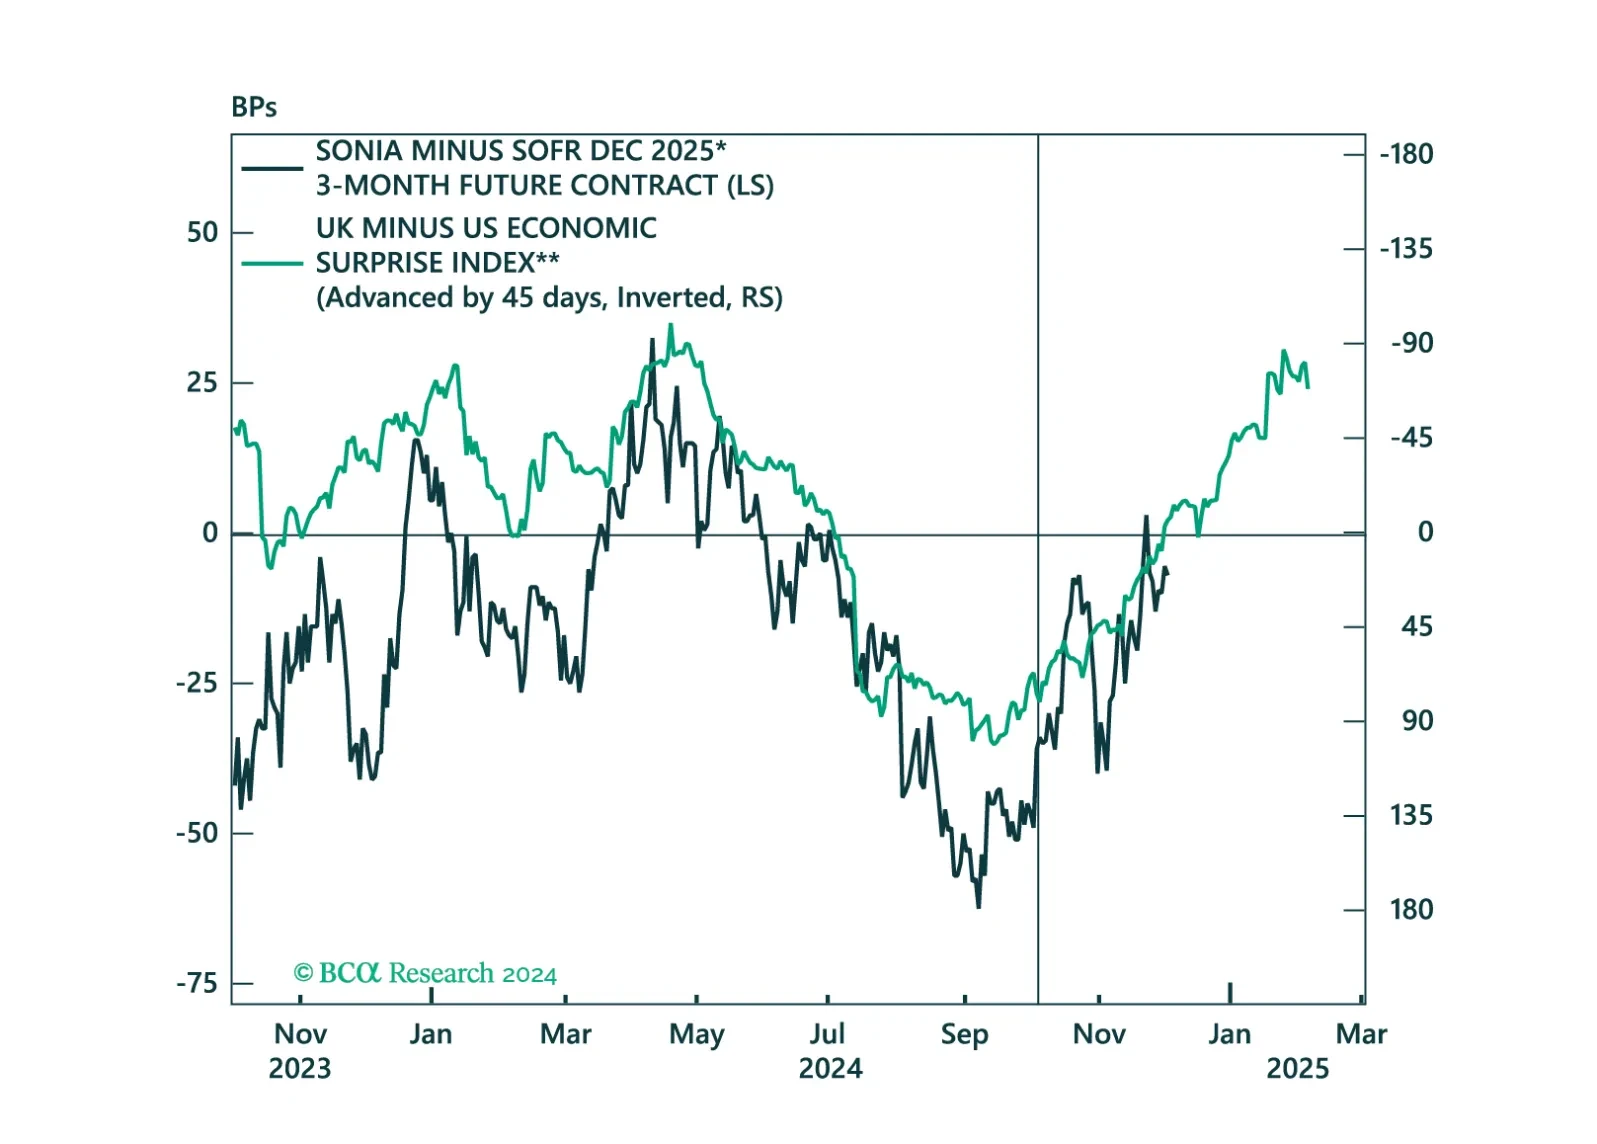
This report reviews our FX and Fixed Income trades over the last year. We look forward to sharing our thoughts for 2025 next week.
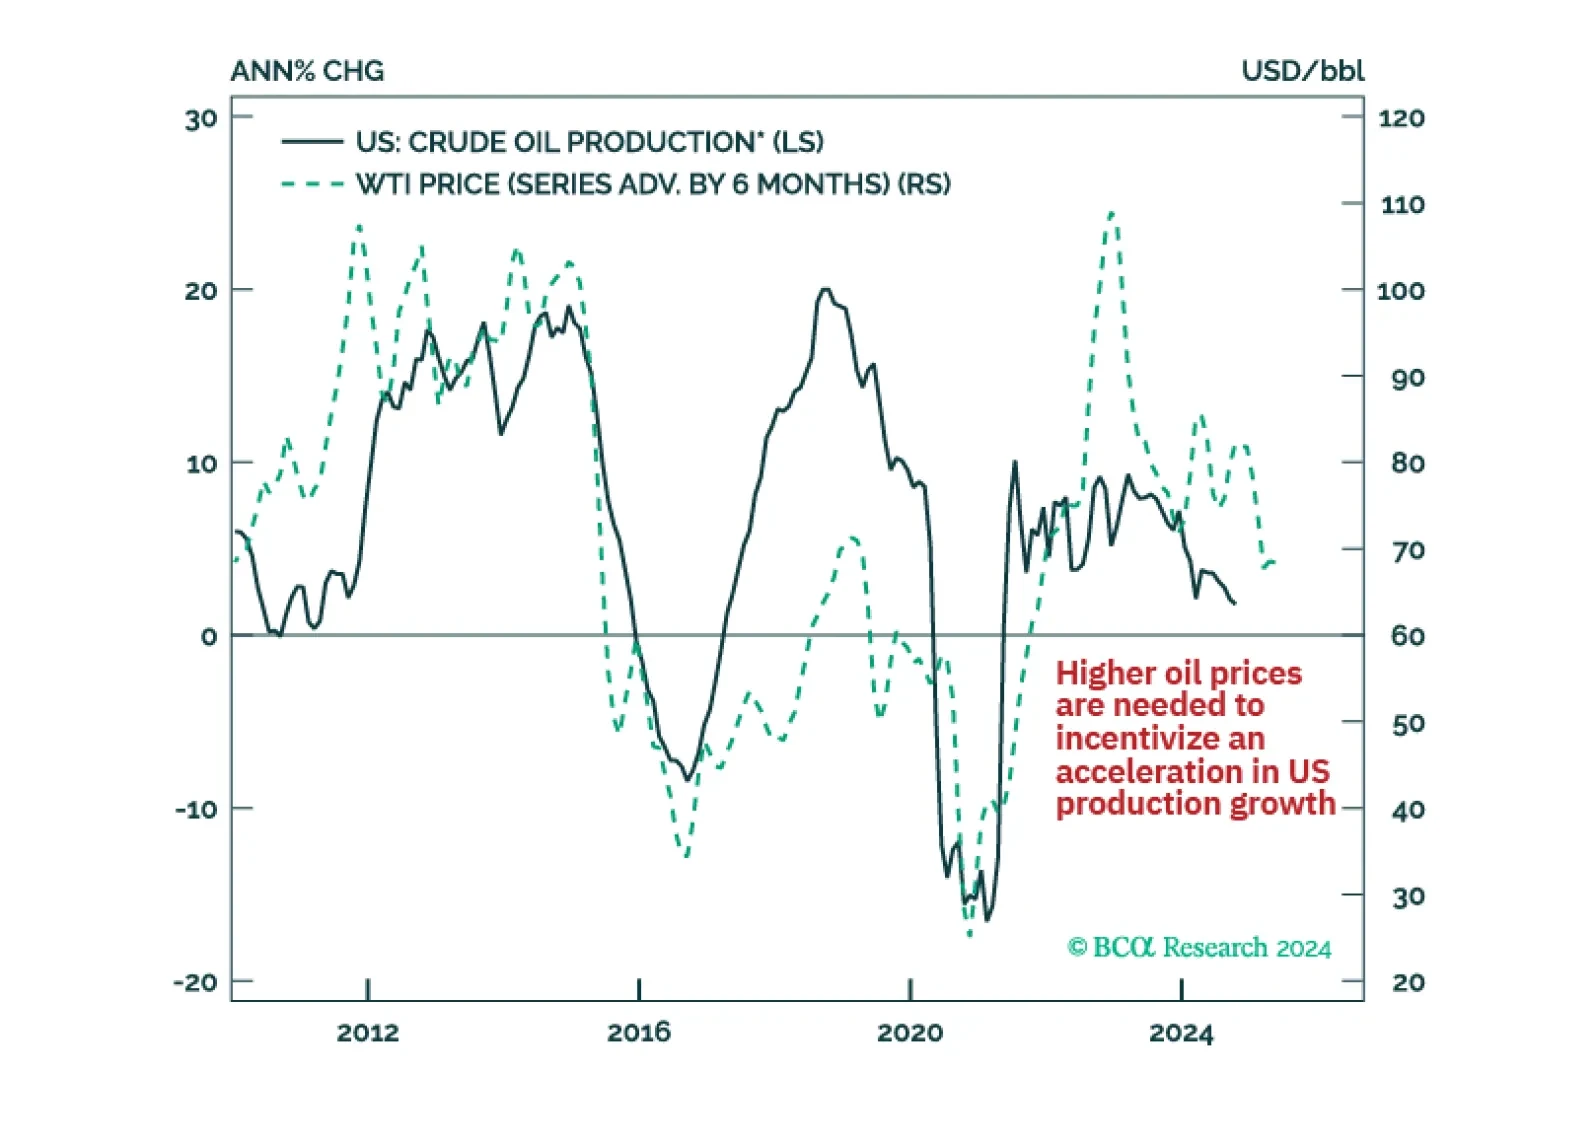
President Trump’s victory has injected a dose of uncertainty into the outlook for commodity markets. Most notably, the new administration’s energy policies are likely to be part of the early agenda. Changes in US domestic and foreign policies will also impact the outlooks for gold and industrial metals. In this Strategy Report we highlight the likely consequence of Trump’s election on the major commodities.
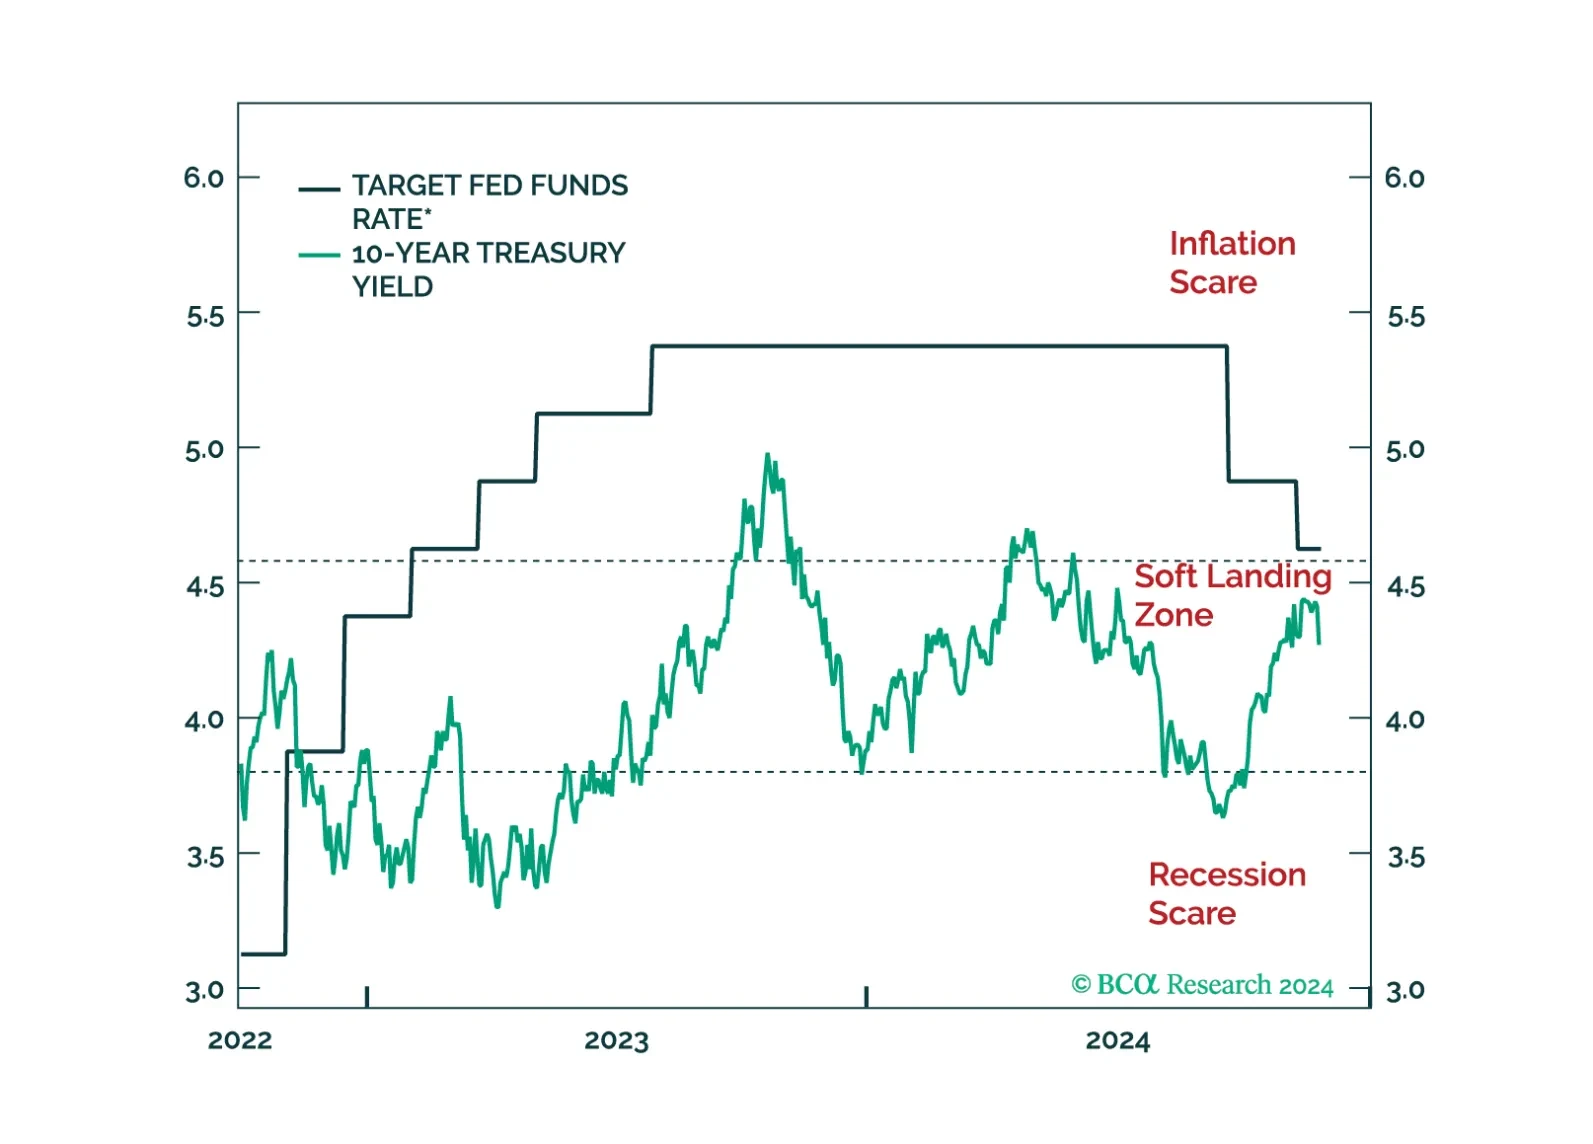
Corporate bond spreads have tightened significantly during the past month, even as the range of economic outcomes consistent with stable credit spreads narrows.