 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
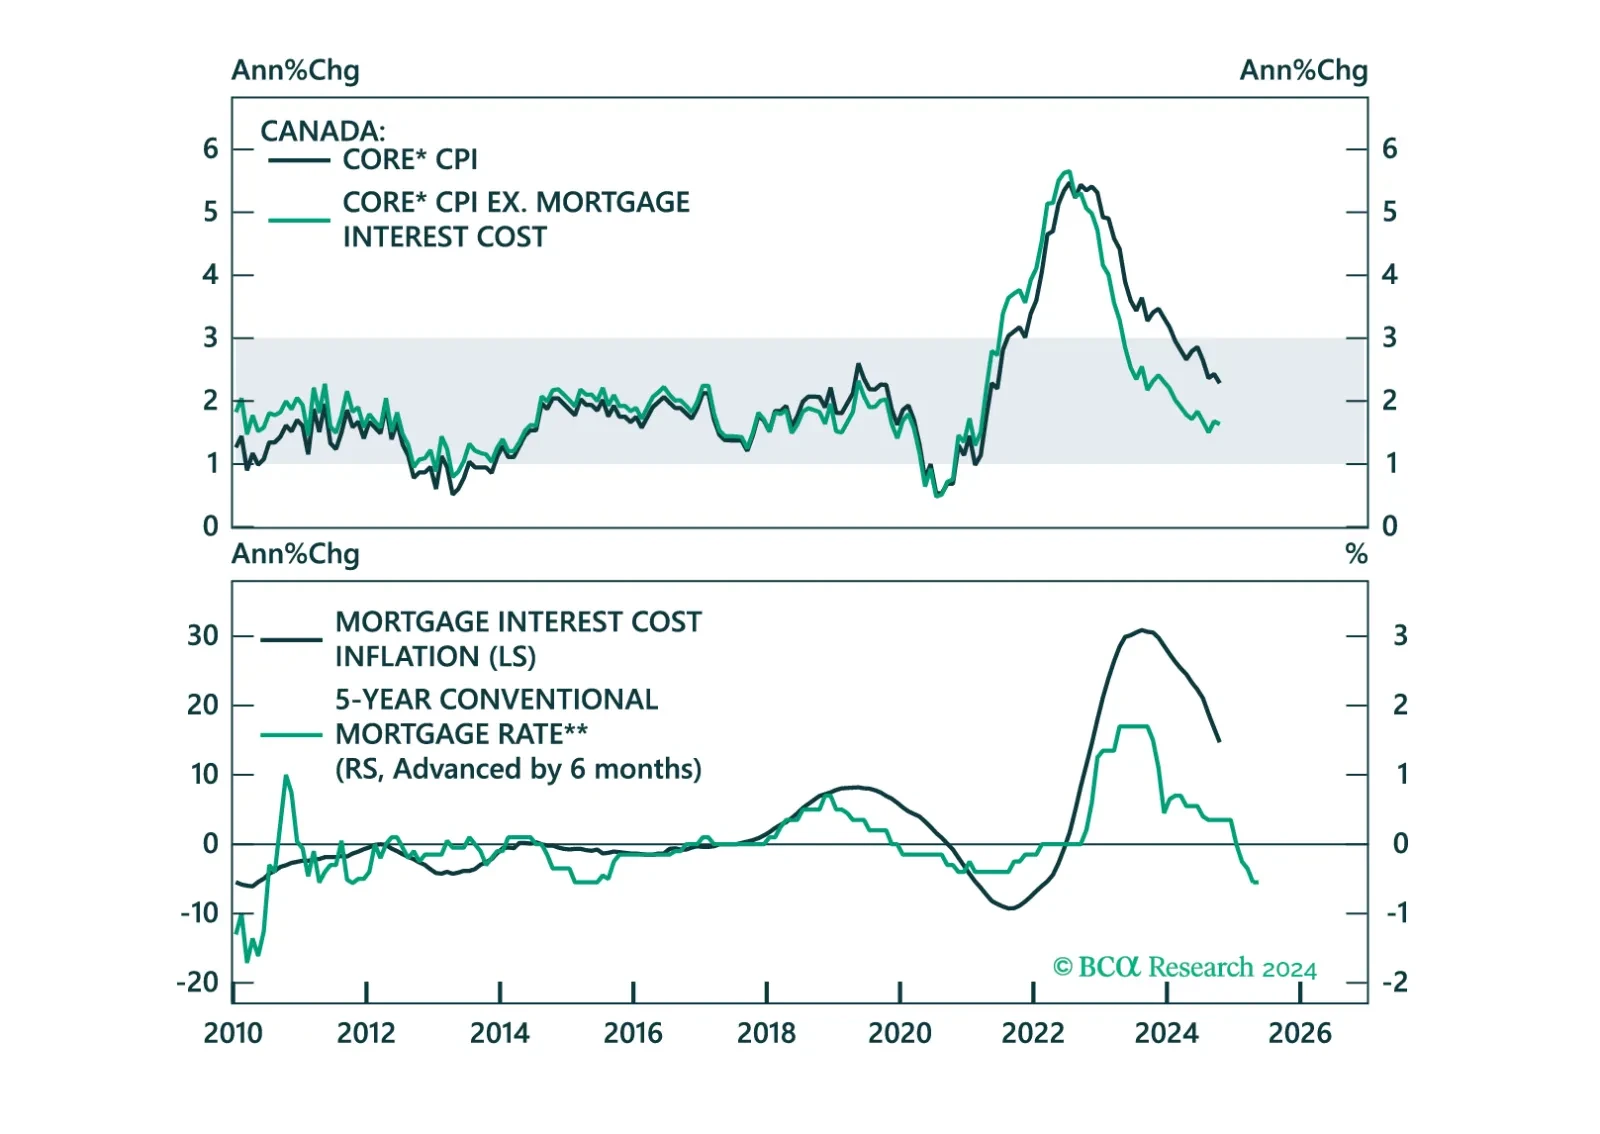
October CPI numbers for Canada, the UK and Japan were released last week. This Strategy Insight examines the respective underlying drivers of inflation in those three economies and discusses the implications for monetary policy.
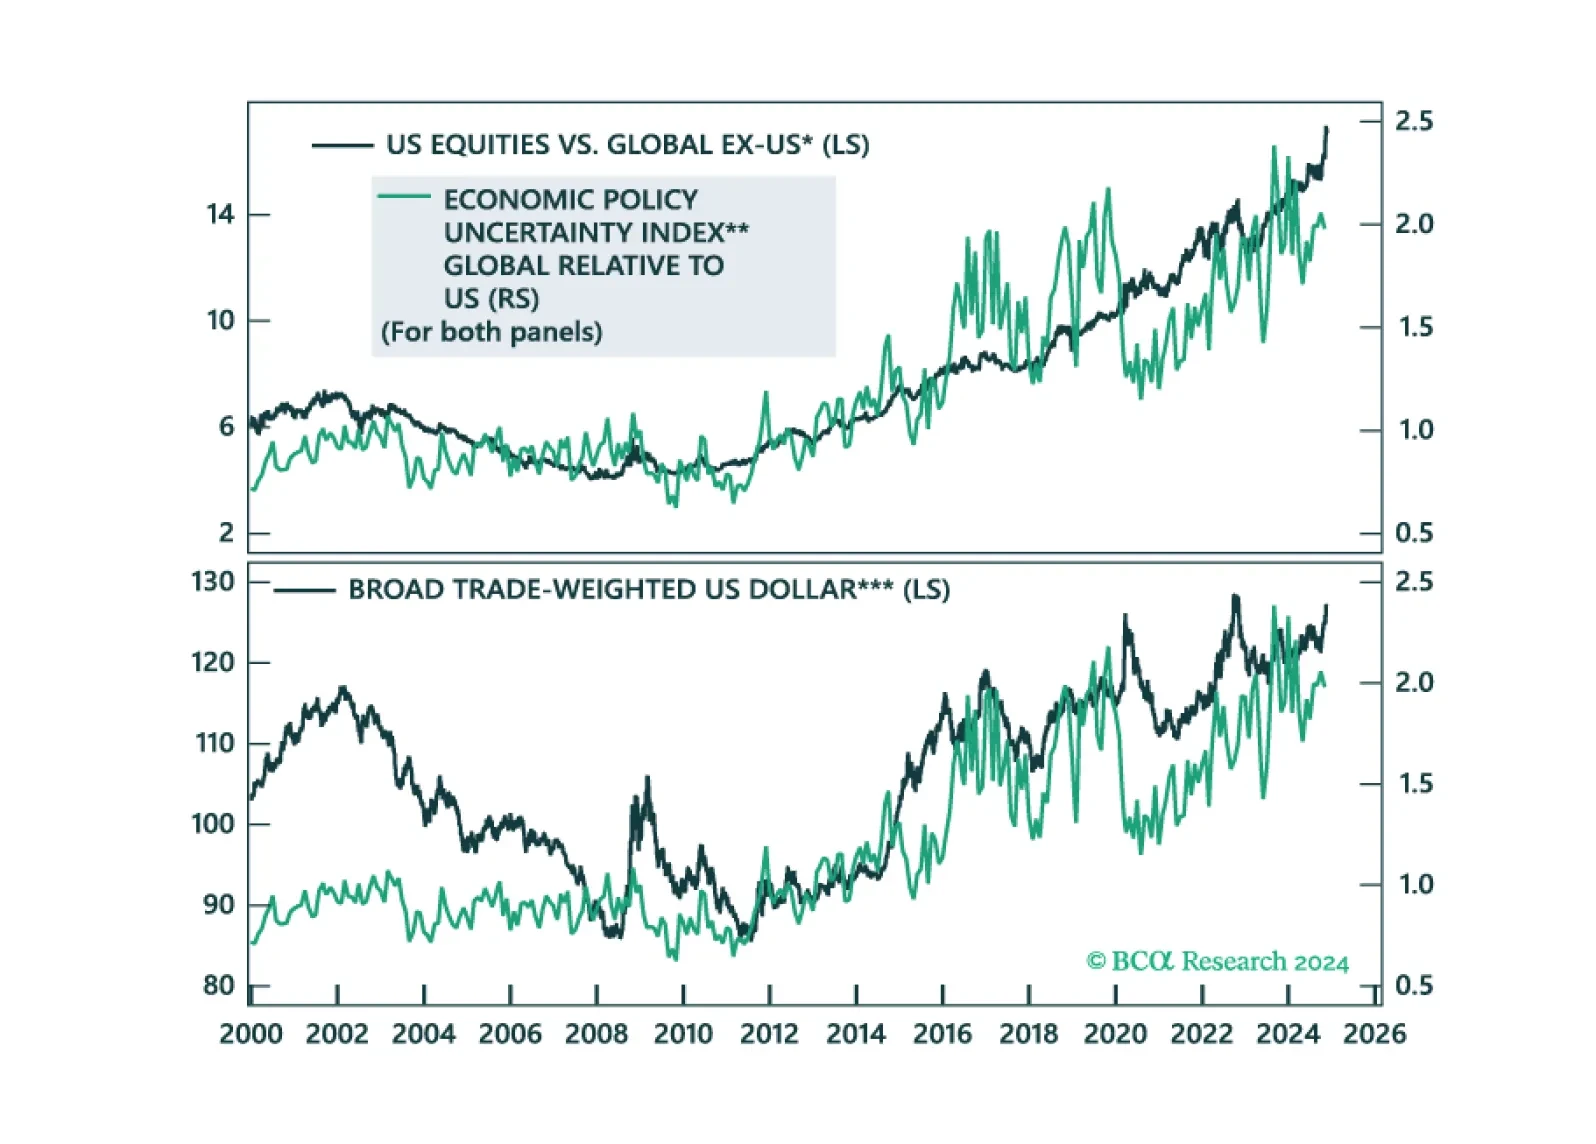

We update our inflation forecast following this morning’s CPI release, concluding that TIPS breakeven inflation rates have room to fall.

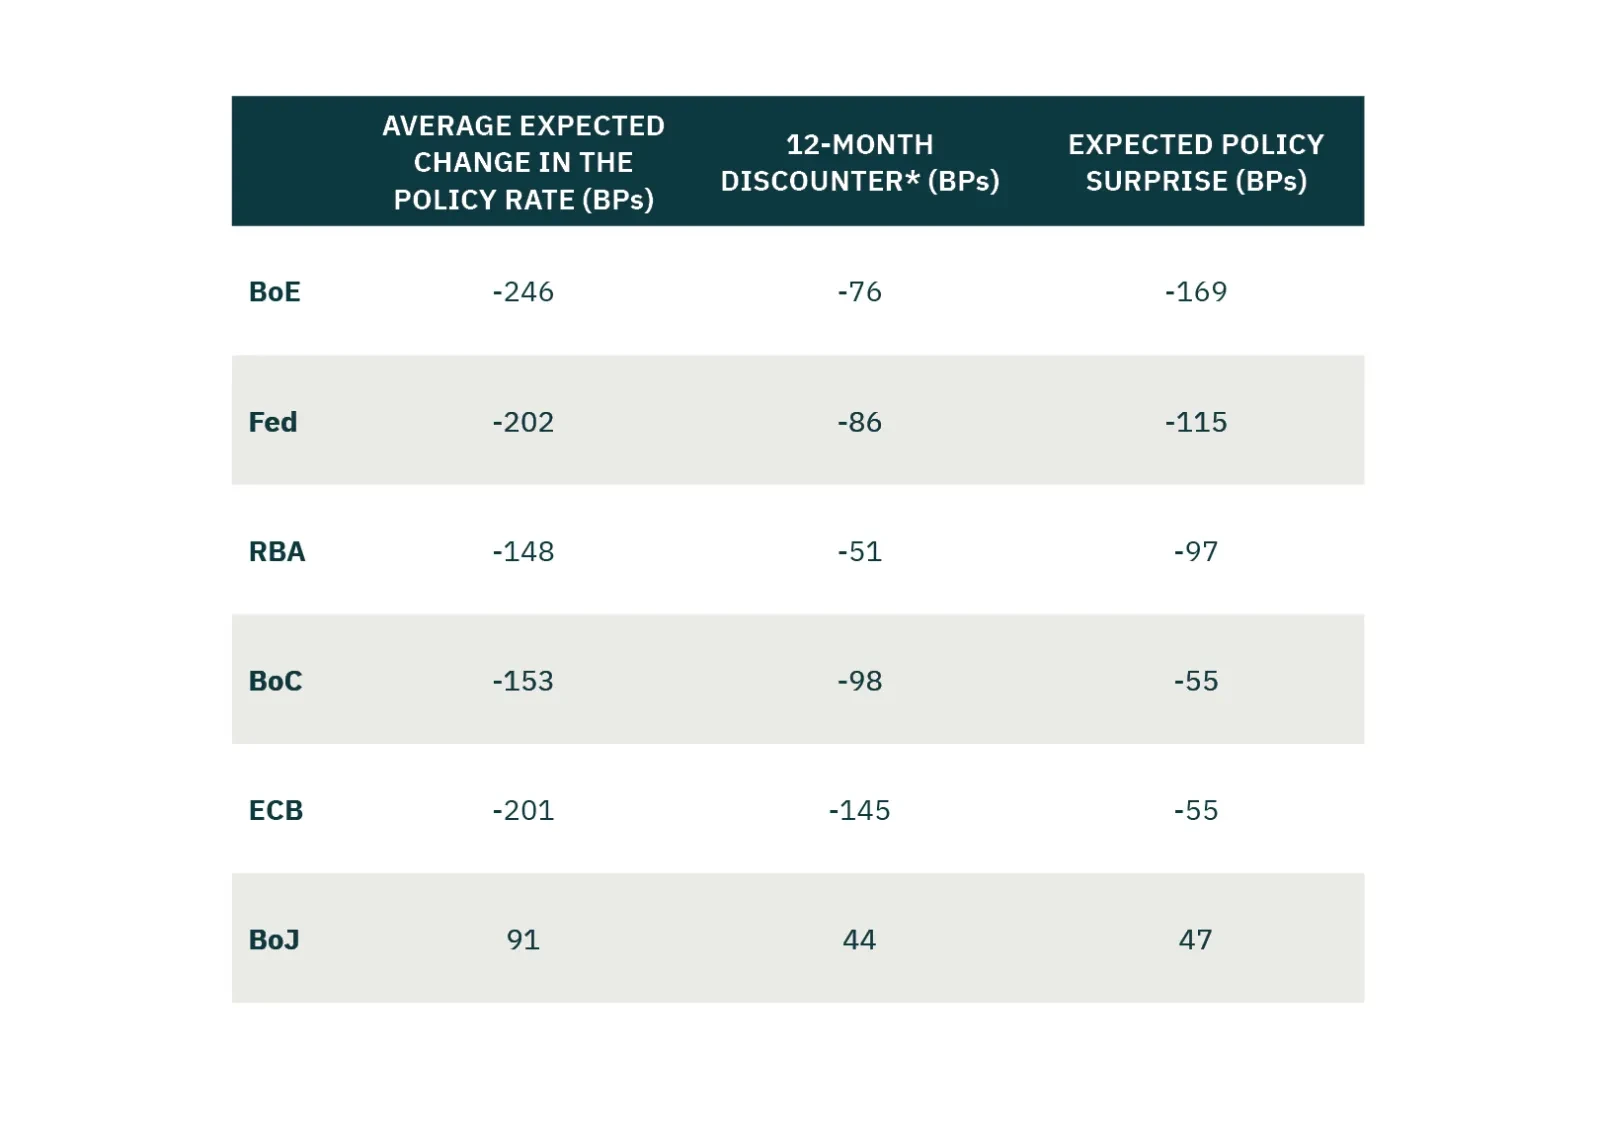
This week, we update our Central Bank Monitors (CBMs), that help us calibrate how monetary policy should be adjusted in developed-market economies. Our conclusion is that while overall, easier monetary settings are required, there a few trade ideas that arise from the divergences in signals amongst G10 countries.
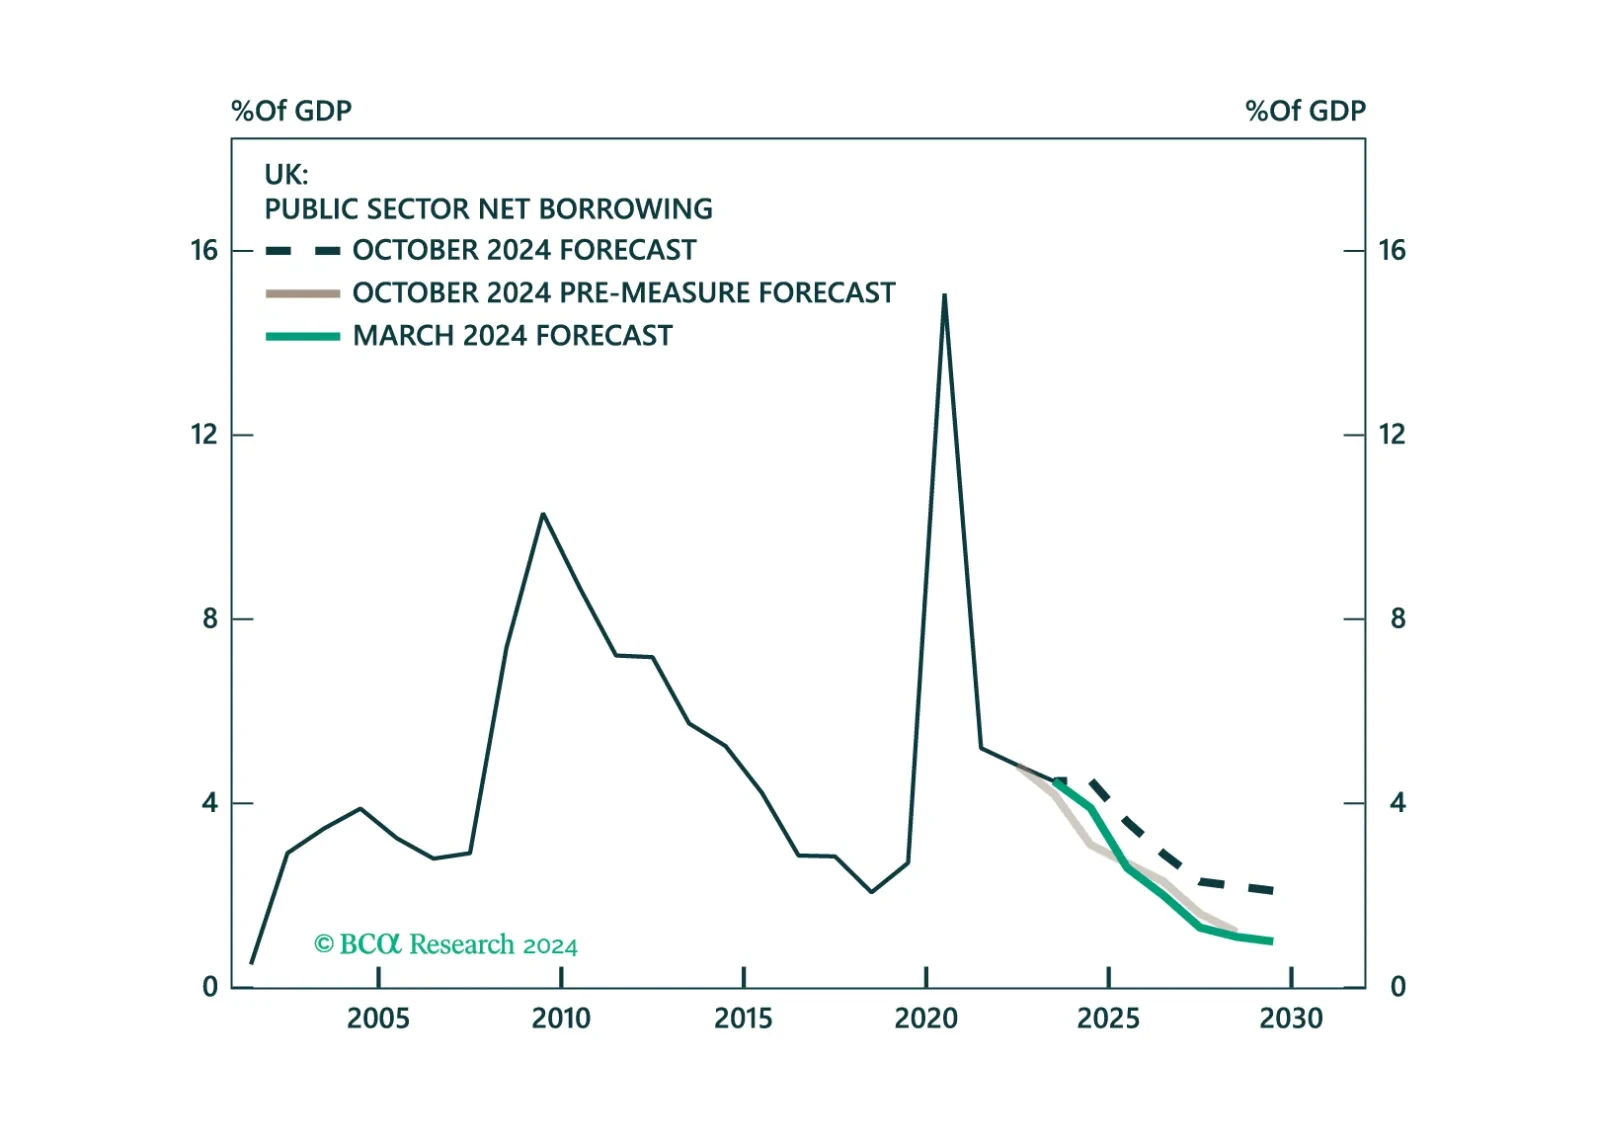
This Strategy Insight presents our view on today’s rate cut by the Bank of England as well as the budget announced by the UK government last week.

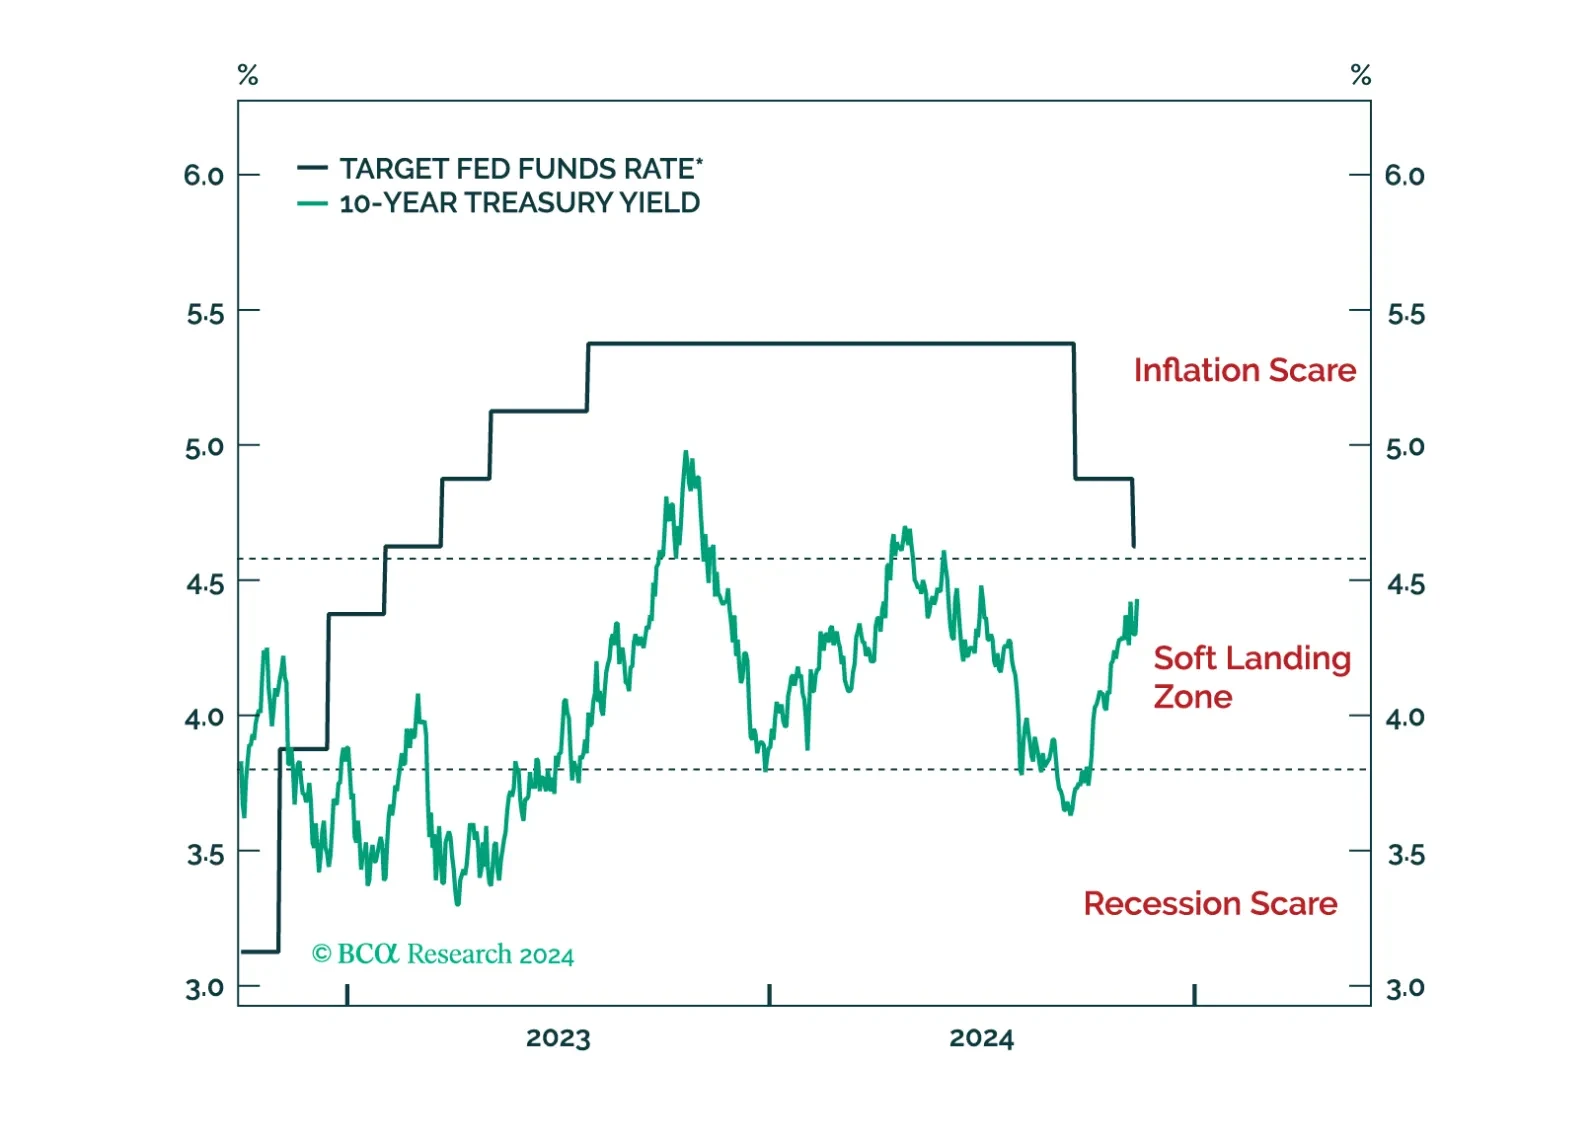
Our thoughts on the bond market’s reaction to the election and this afternoon’s FOMC meeting.
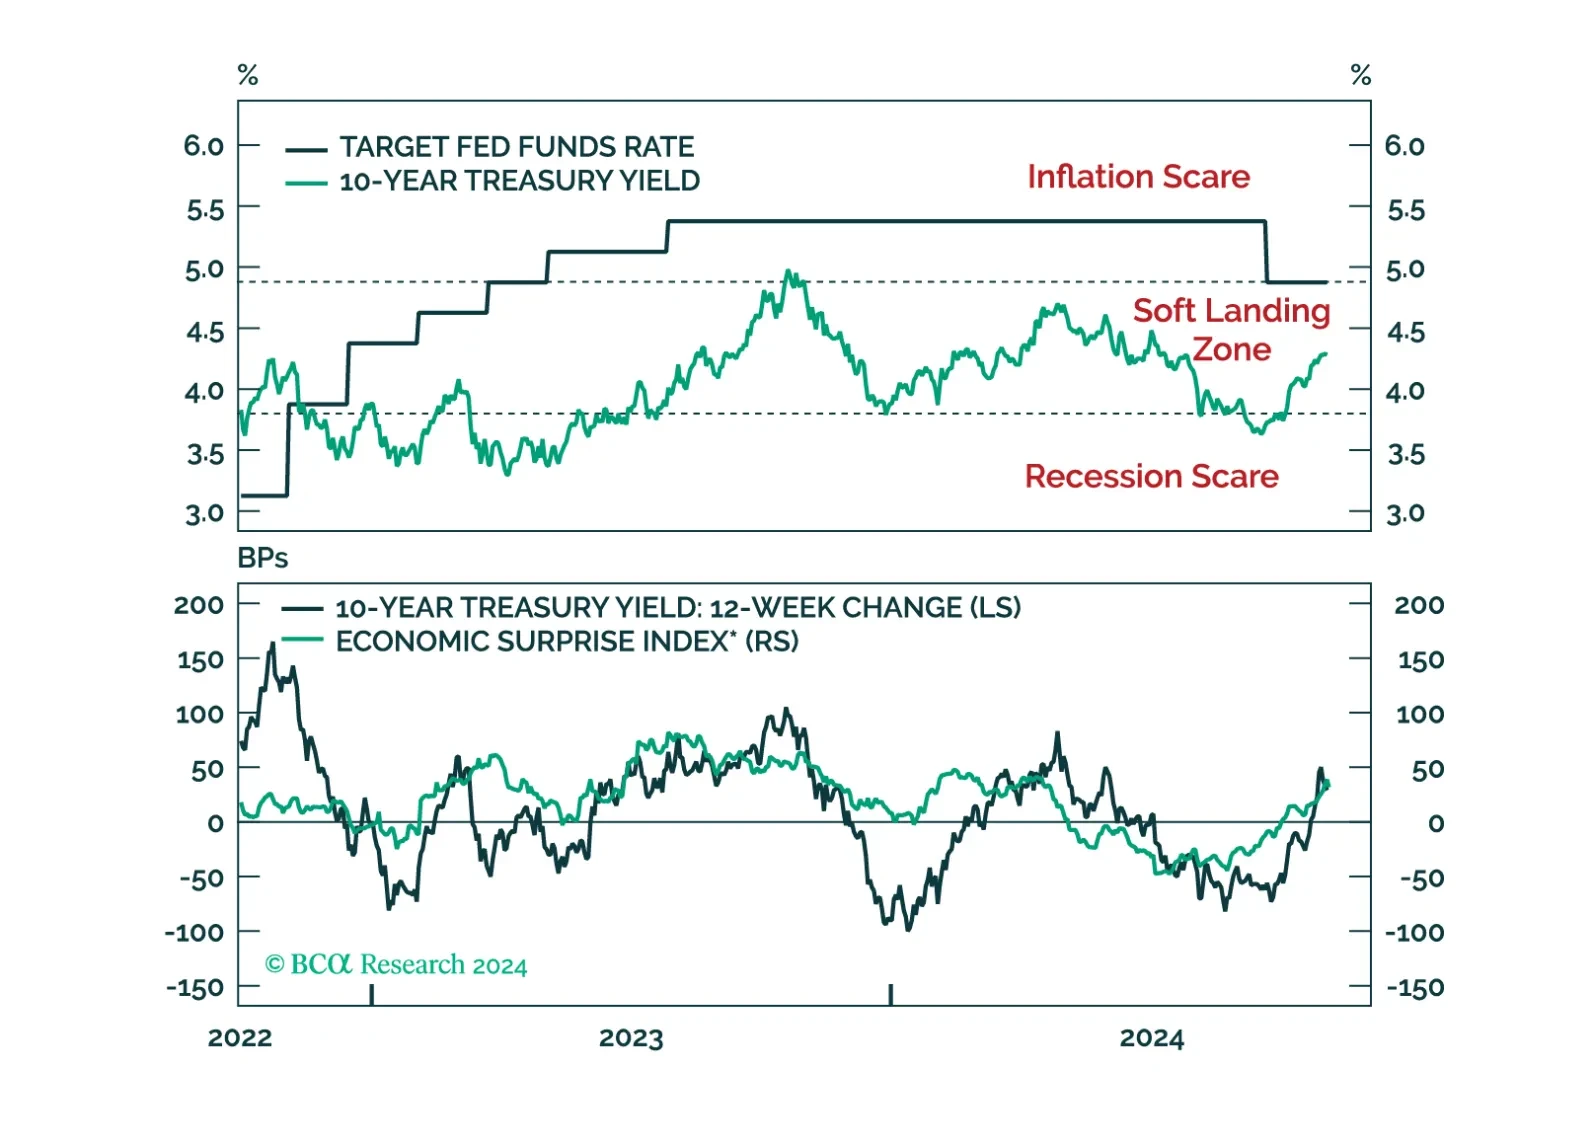
A reaction to this morning’s employment report and a preview of the potential bond market implications of next week’s US election and FOMC meeting.