FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
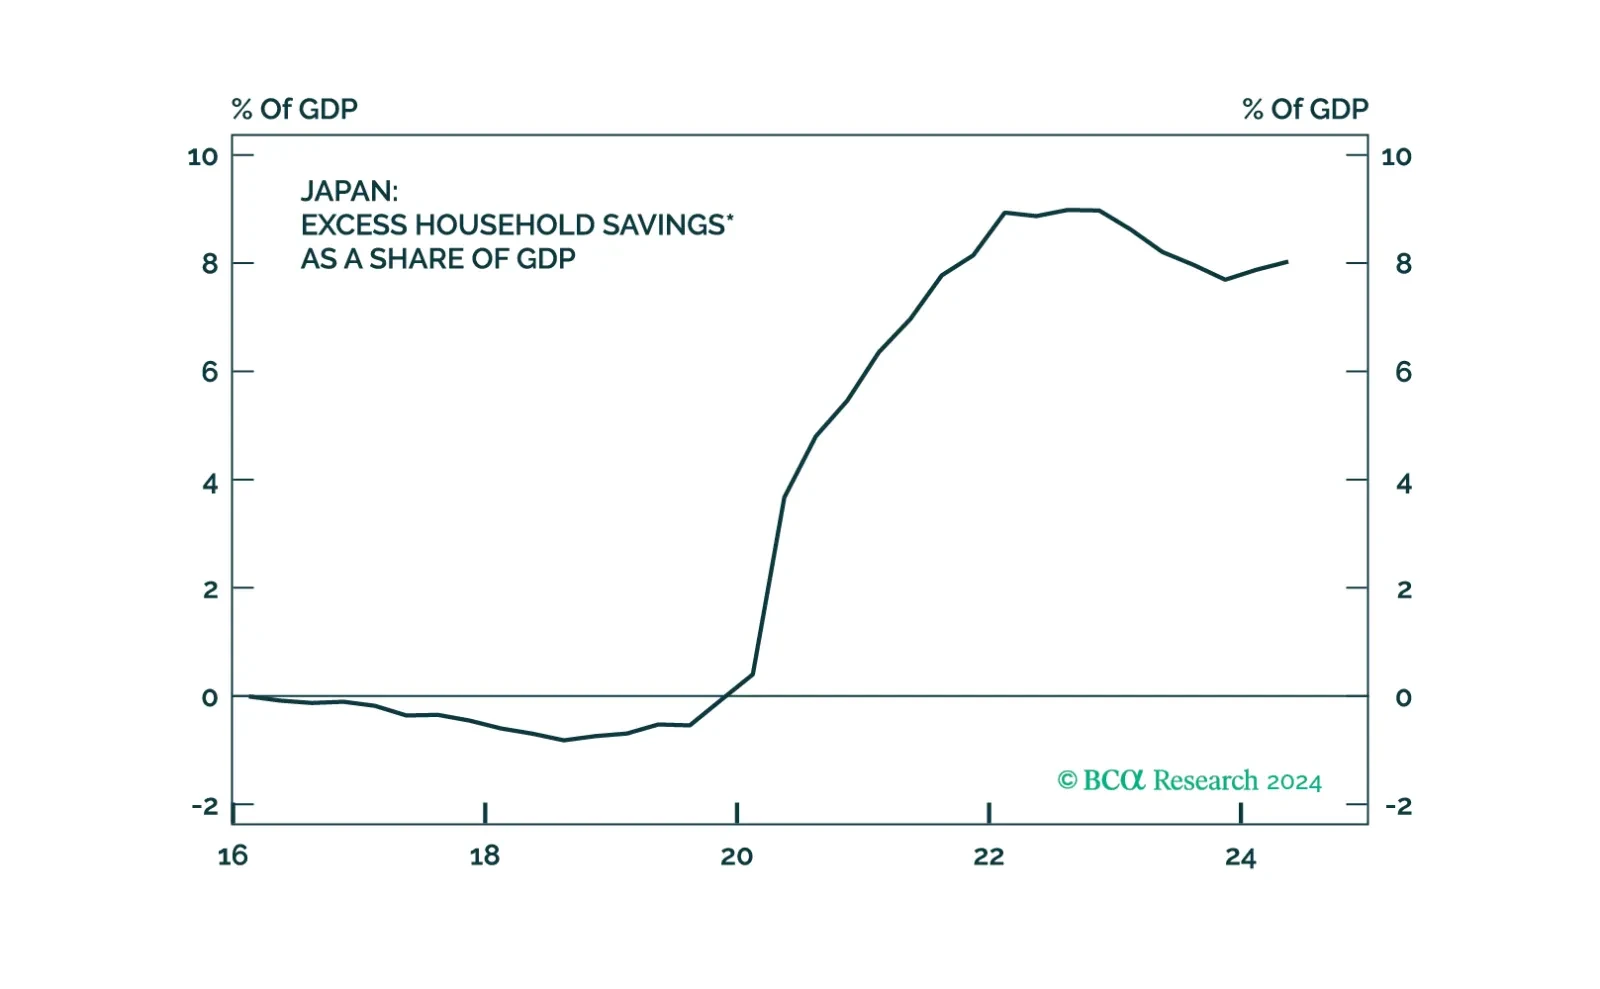
The latest Bank of Japan meeting did not alter our high-conviction views of being long the yen and underweight JGBs.

We update our 12-month return projections for different US fixed income sectors in soft-landing and recession scenarios.
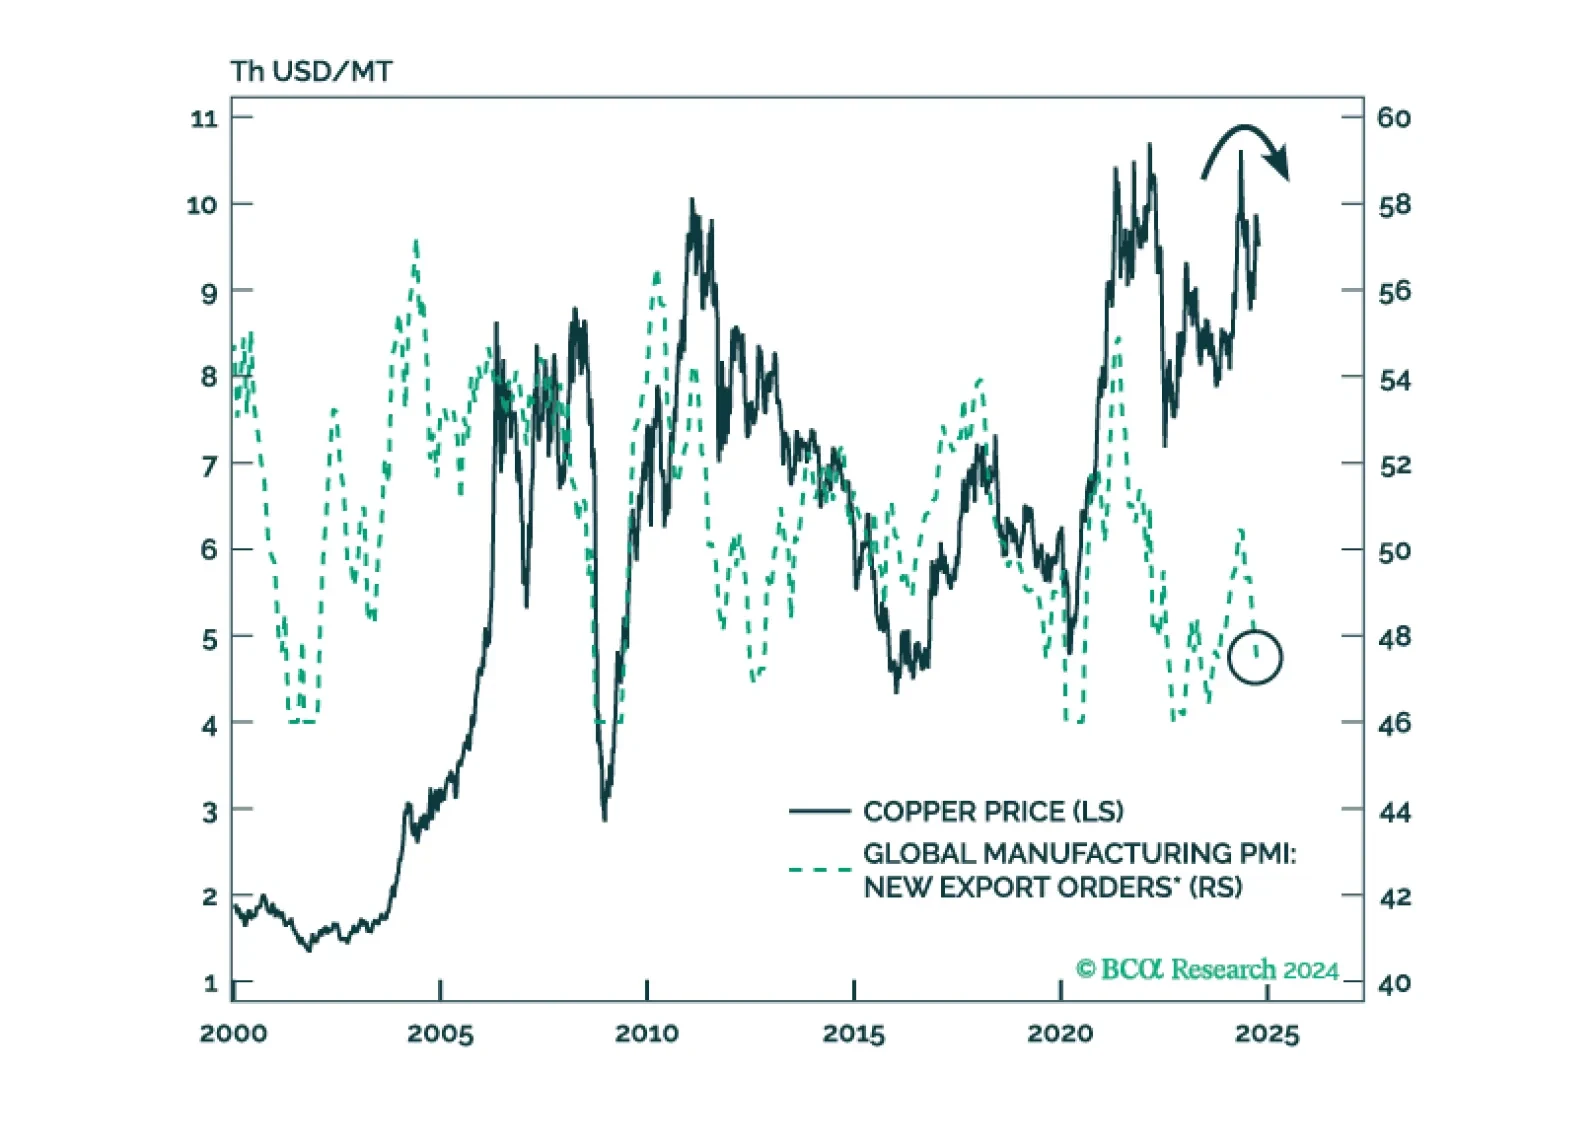
It is premature to bet on a copper demand acceleration over the coming months. Rather, copper prices are vulnerable to the downside. We believe that a better opportunity to turn bullish on copper prices and copper mining stocks will emerge in the coming six-to-nine months.
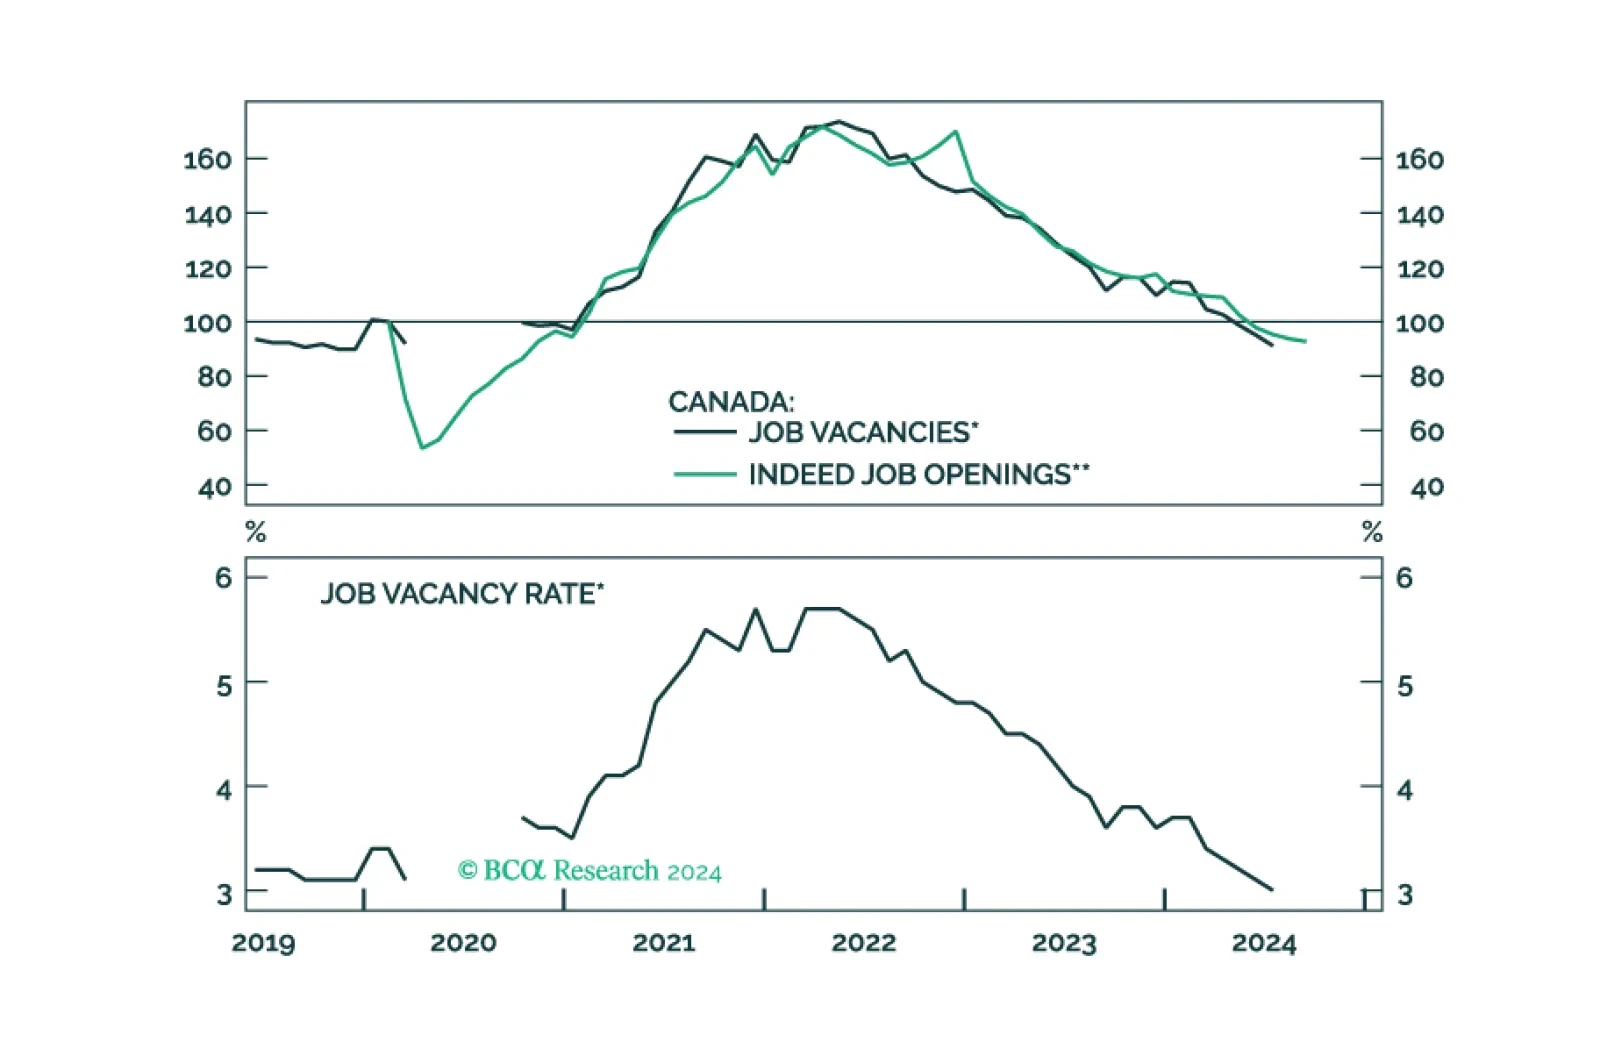
In this Insight, we evaluate if there is more juice in our macro bet of being long June 2025 CORRA versus SOFR futures, and correspondingly, being short the CAD, for investors with a 1-3 month horizon.
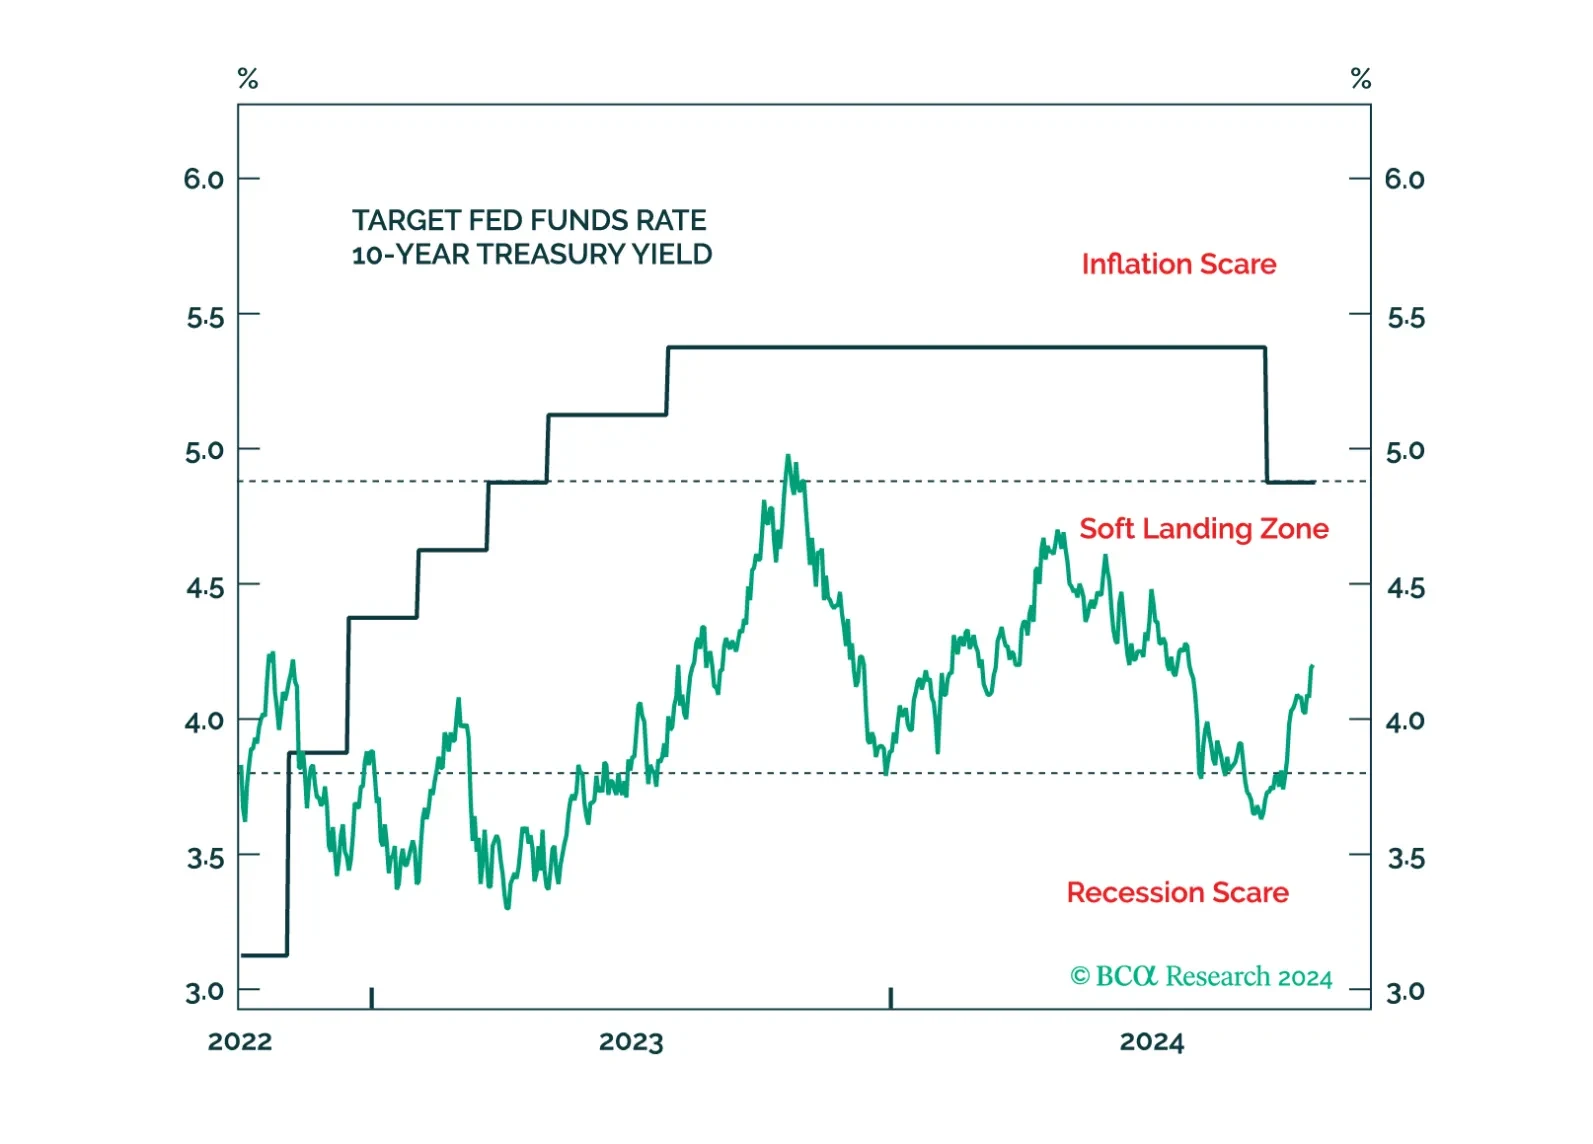
A Donald Trump victory would send bond yields higher during the next few weeks, but yields will fall in 2025 no matter the election outcome.
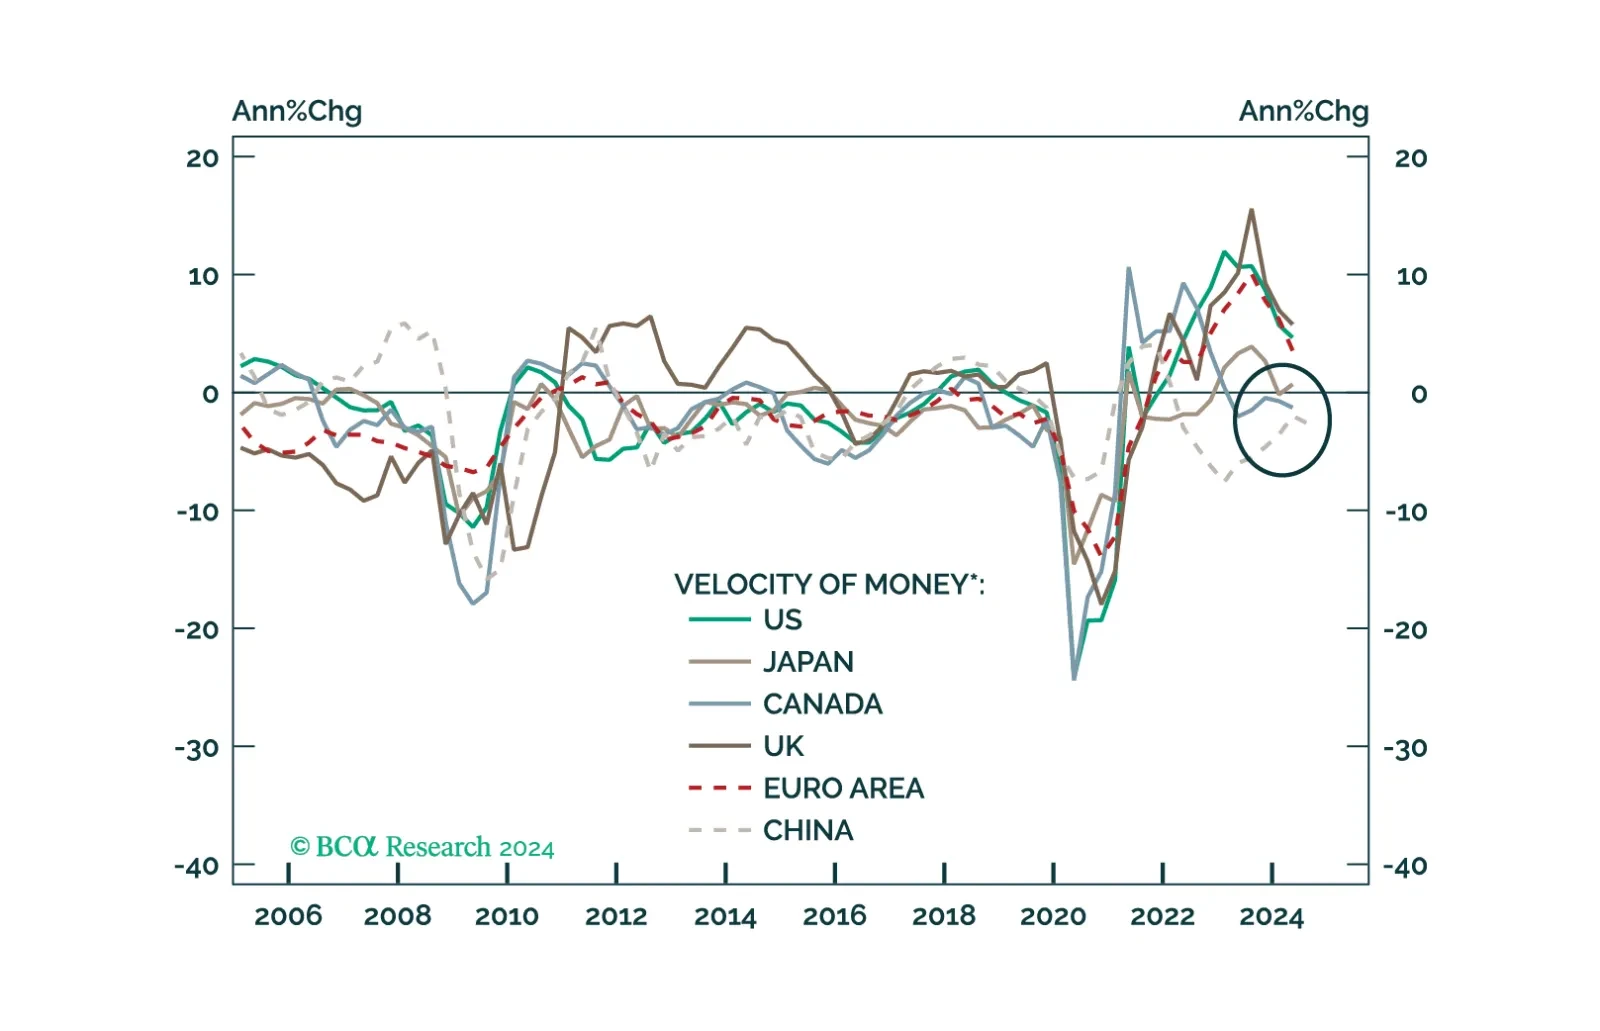
This Insight looks at the likely direction of bond yields and the dollar, from the lens of money velocity.
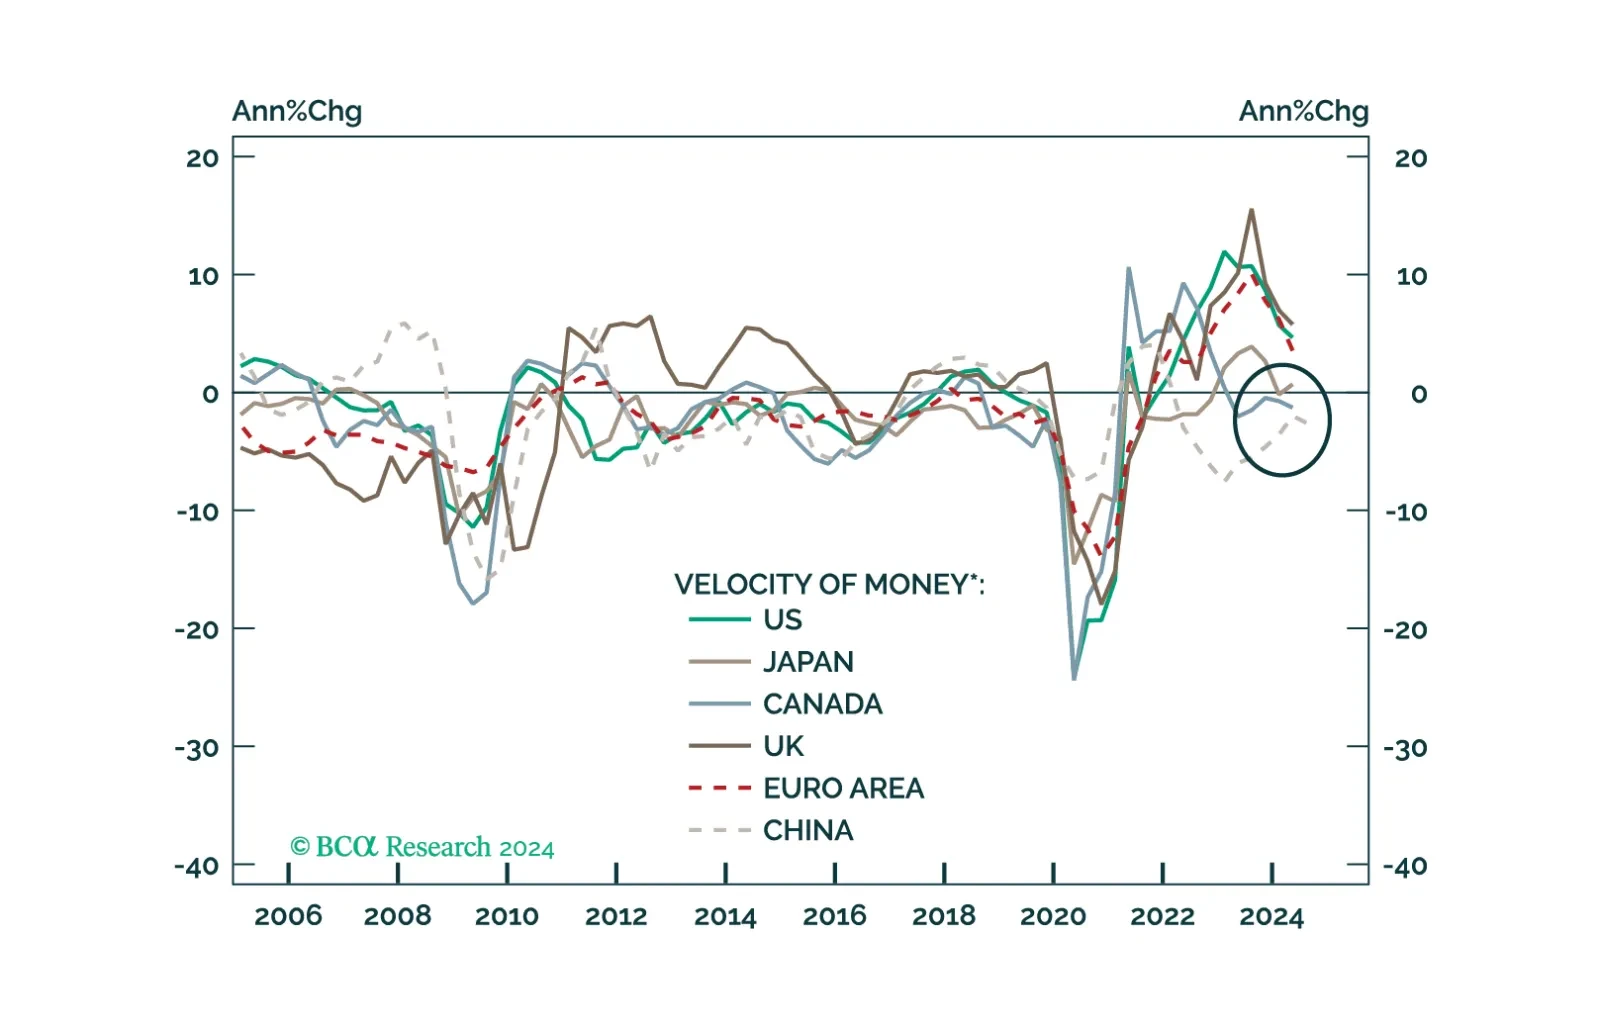
This Insight looks at the likely direction of bond yields and the dollar, from the lens of money velocity.
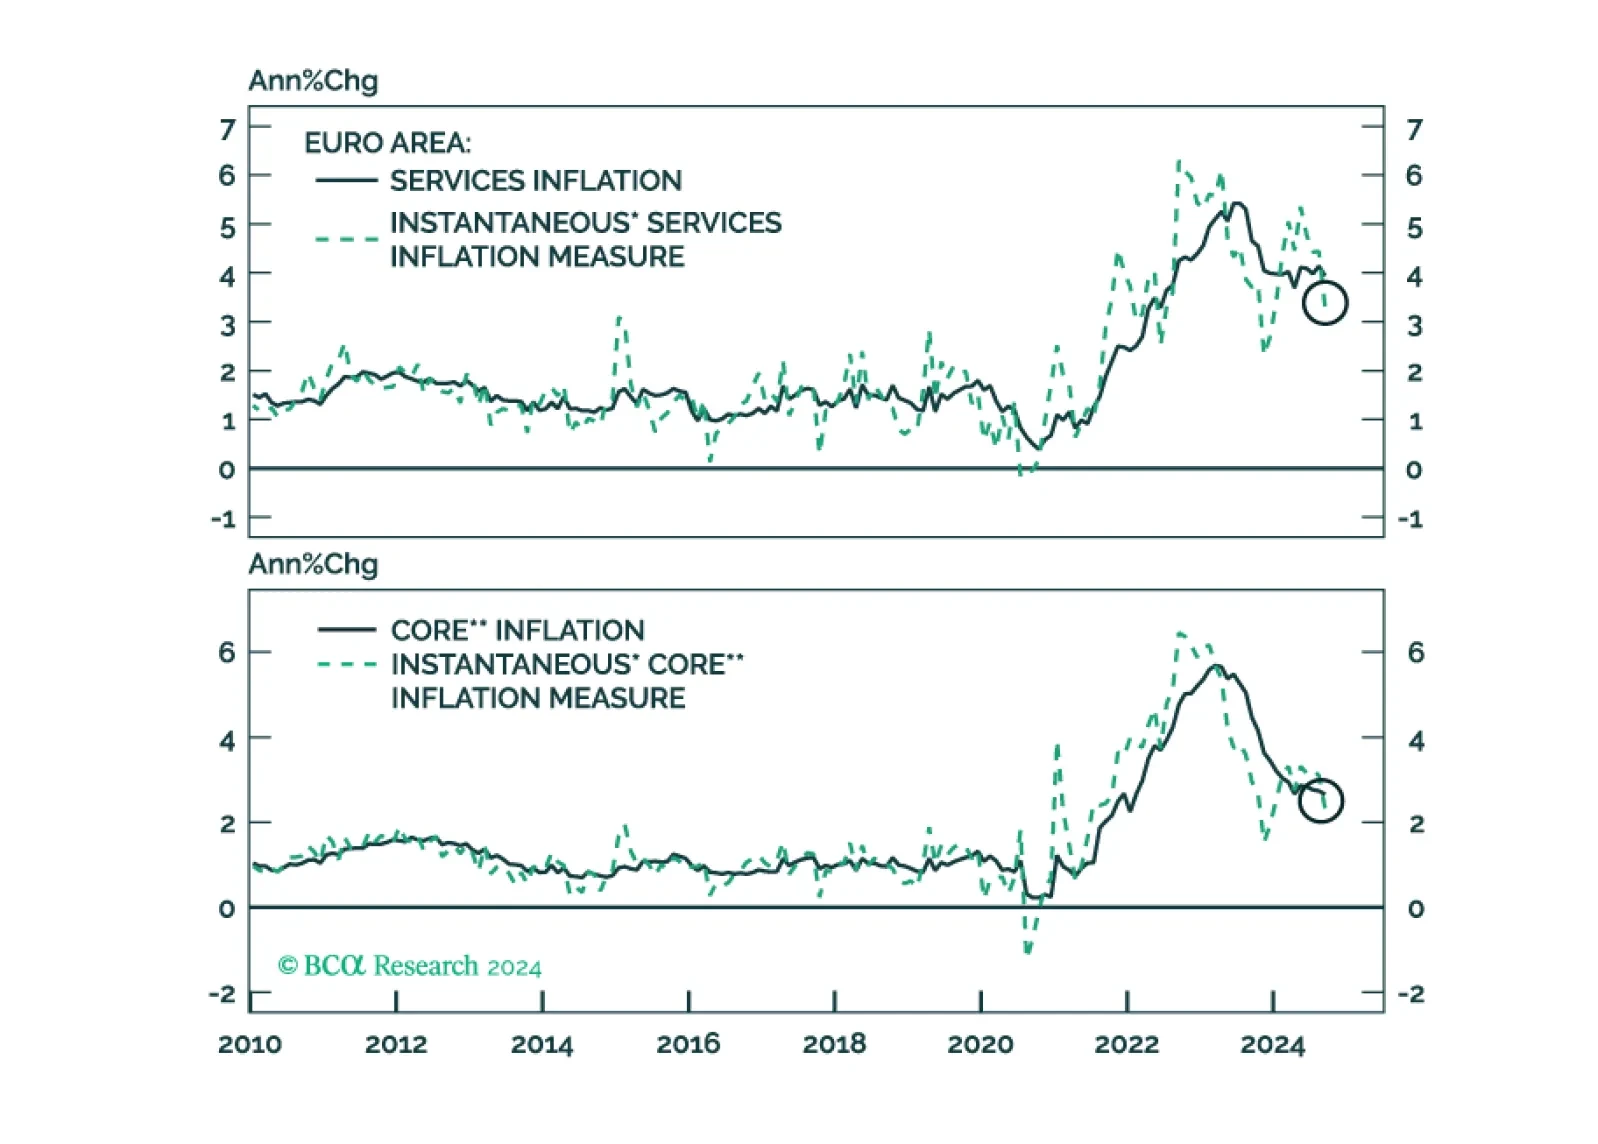
Yesterday, the ECB solidified its recent dovish tilt in response to weaker growth and decreasing inflationary pressures. It is now set to cut rates 25bps each meeting. How low will the ECB deposit rate ultimately go and what does this imply for yields and the euro?
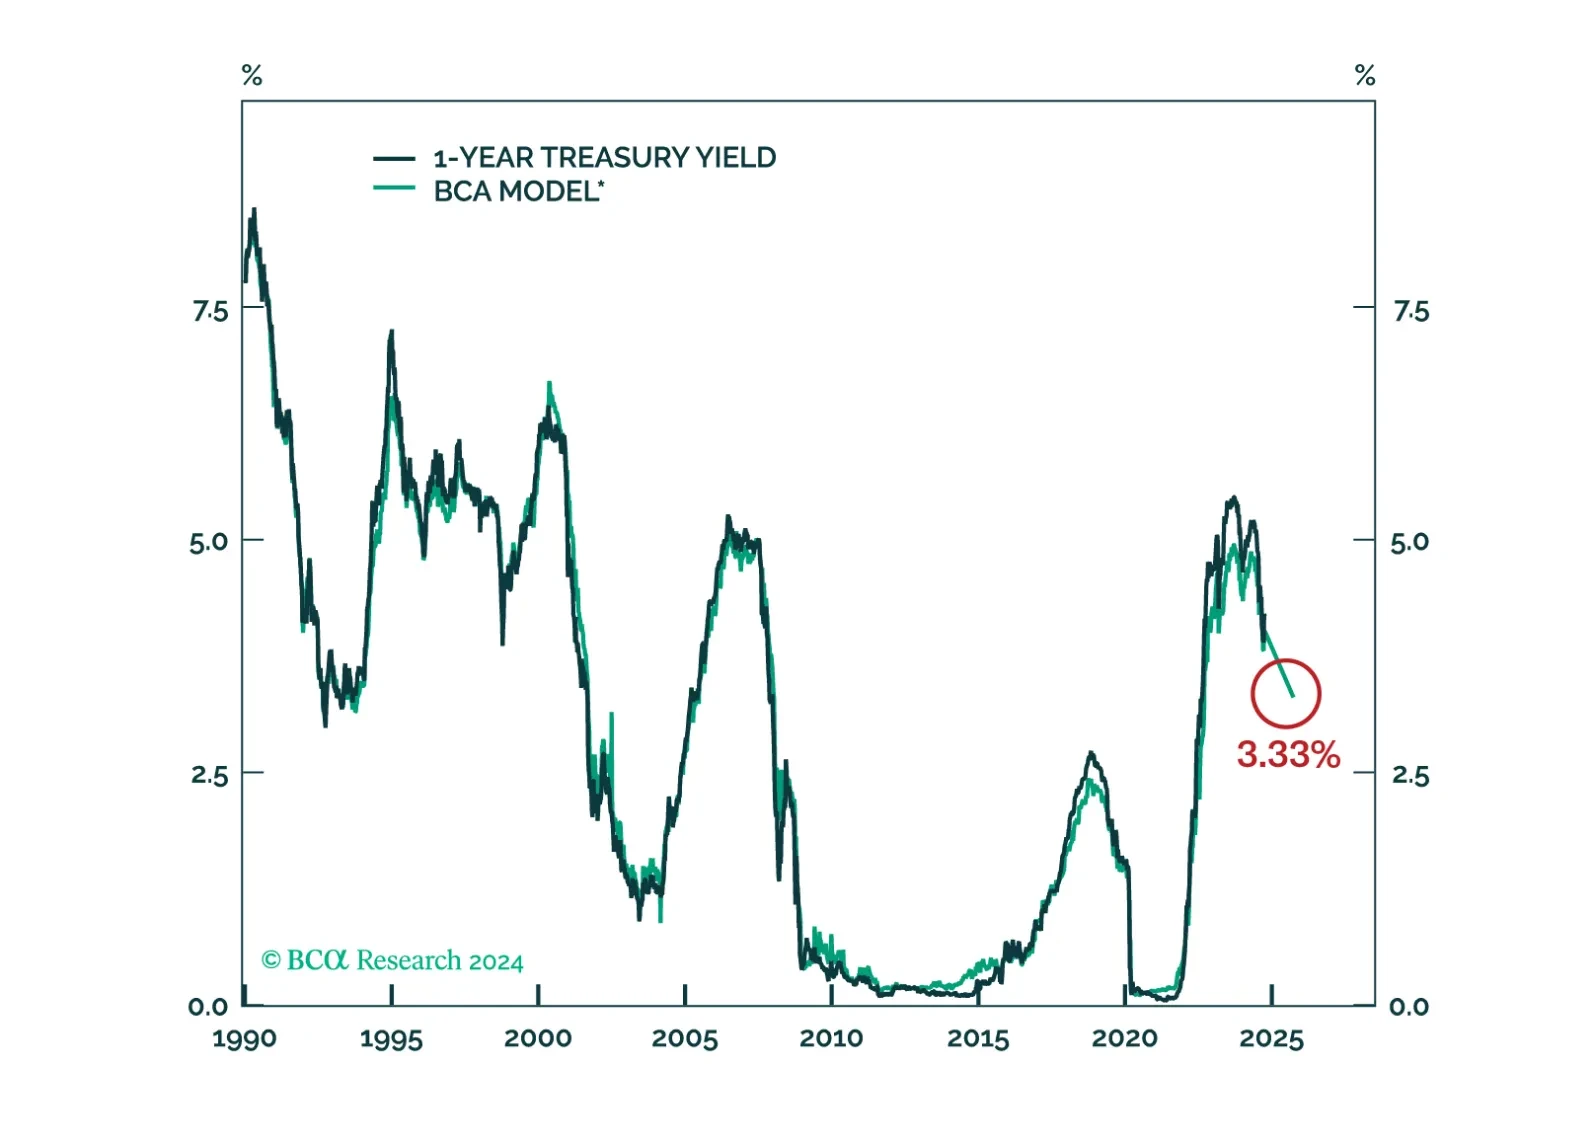
We estimate where Treasury yields might go in a soft landing economic scenario.