Productivity
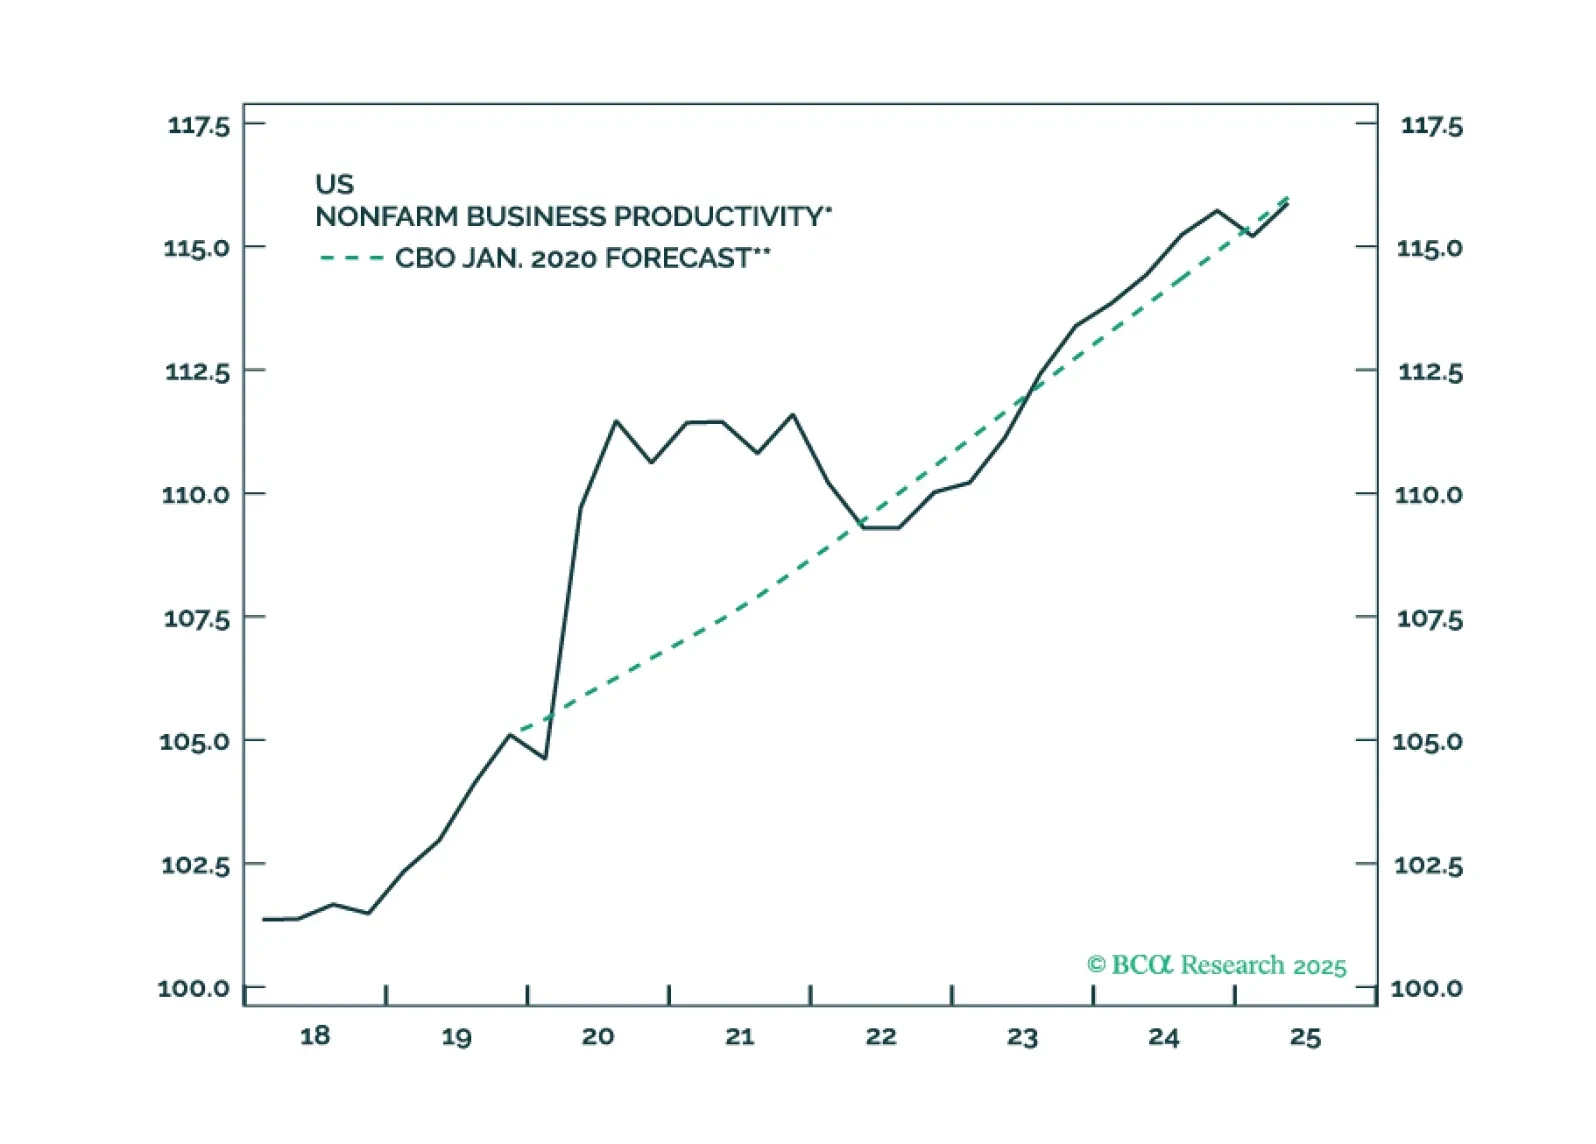
AIブームは広く信じられているほど経済に大きな影響を与えていません。これがいずれ変化する可能性はありますが、その前に投資家が忍耐を失うリスクがあります。
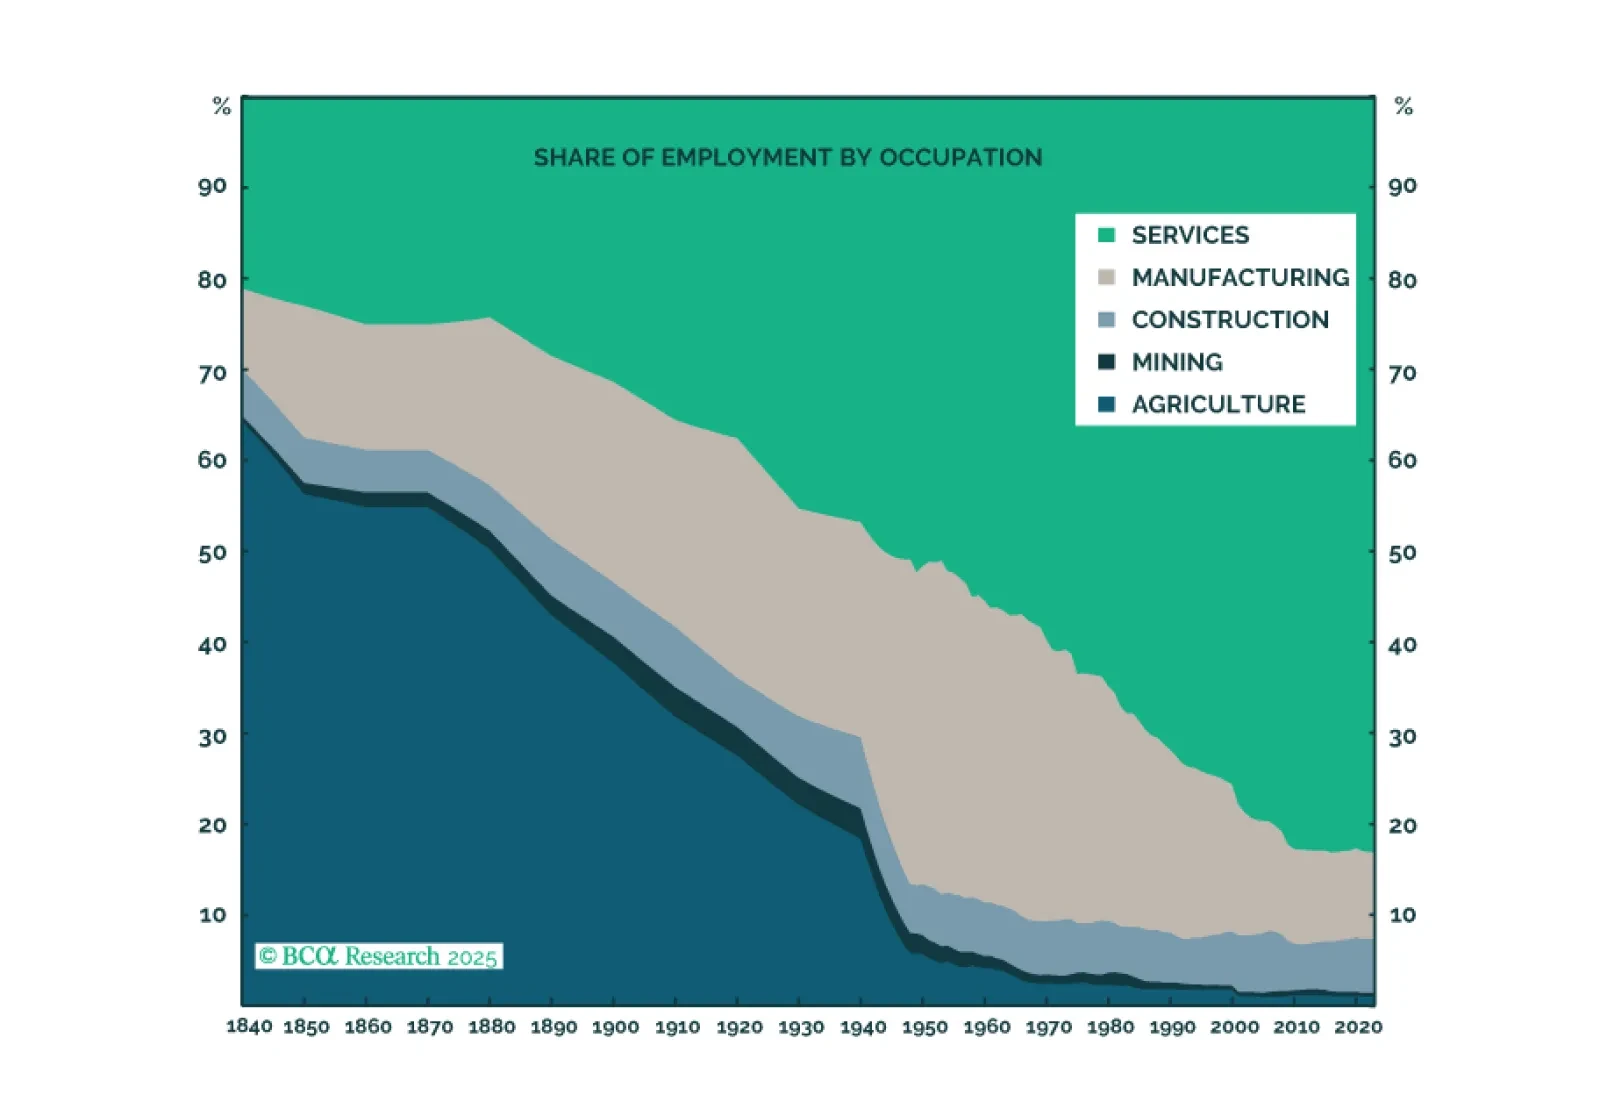
Provided that humanity can overcome the existential risks posed by AI, real incomes will rise. Although most workers will ultimately gain from the transition to an AI-dominated economy, the biggest winners will be those who control the land and the natural resources beneath it.
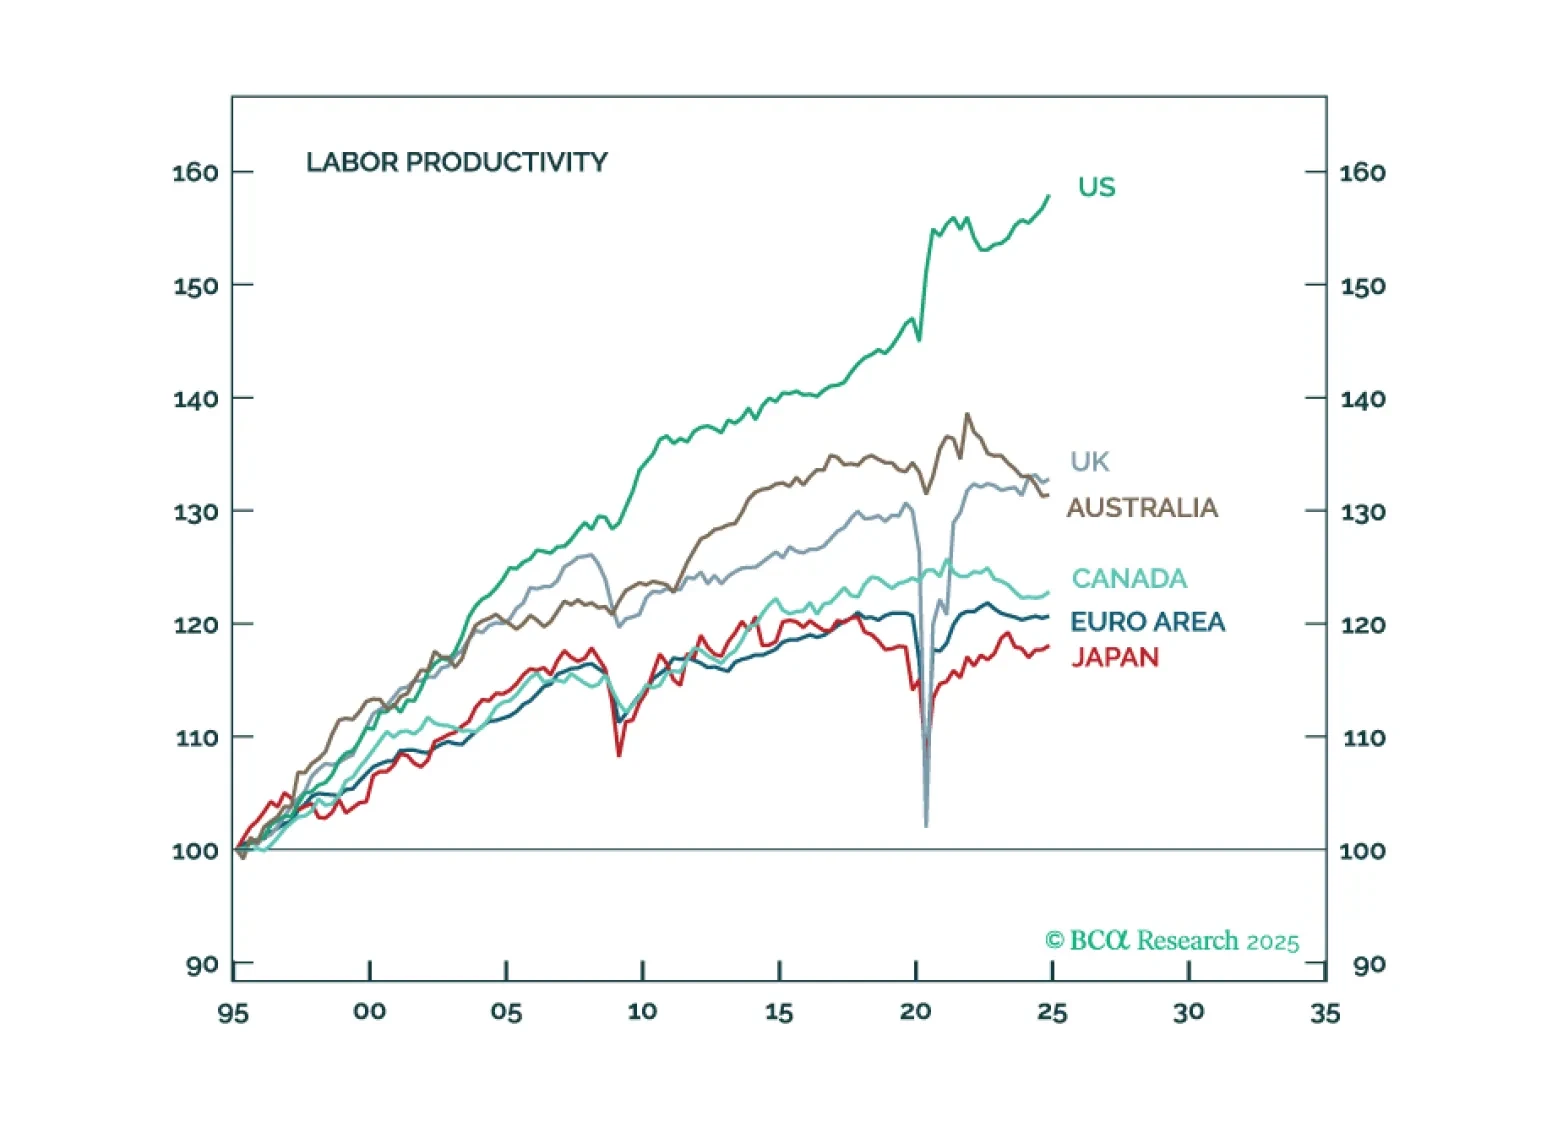
Although the sell-off in the US dollar and relative outperformance of non-US stocks will pause over the coming months as a global recession begins, the fading of US exceptionalism will still cause the dollar to weaken and US stocks to underperform over a multi-year horizon.
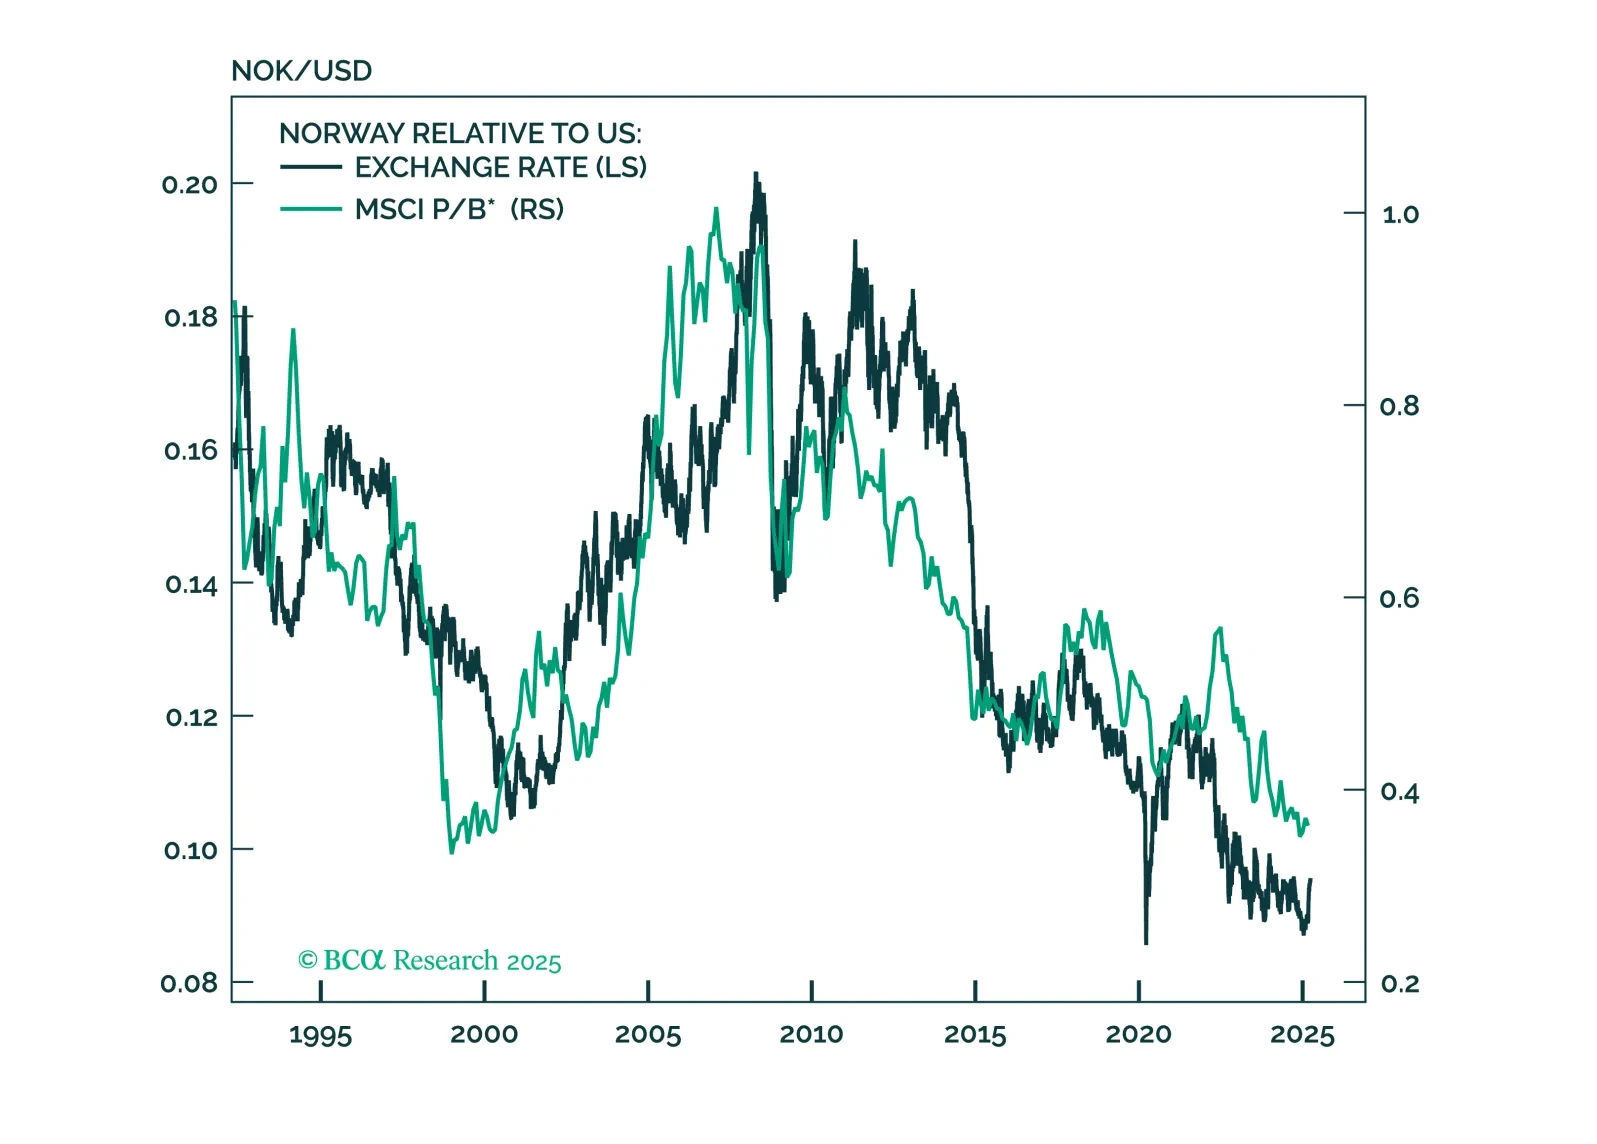
This report looks at investment implications, for Norwegian assets, given the recent meeting, from the Norges Bank.
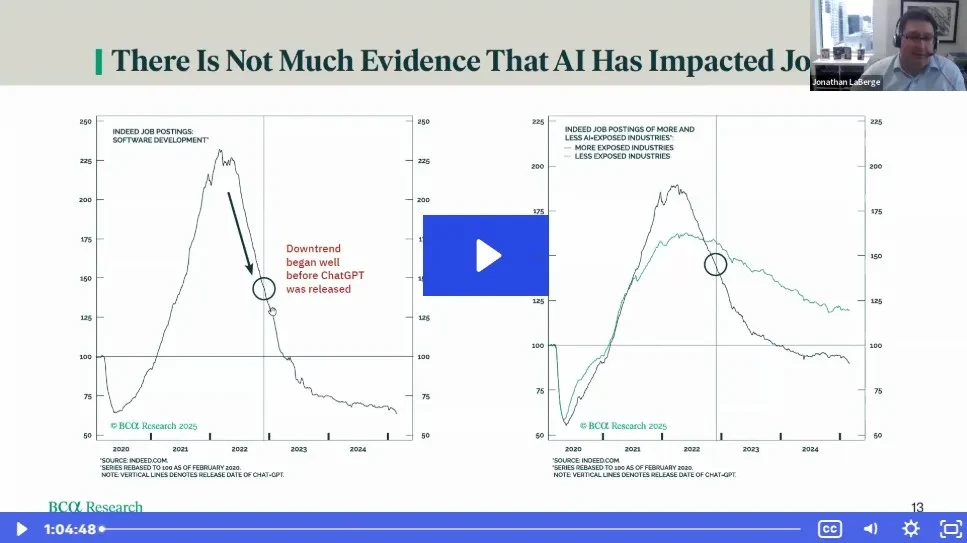
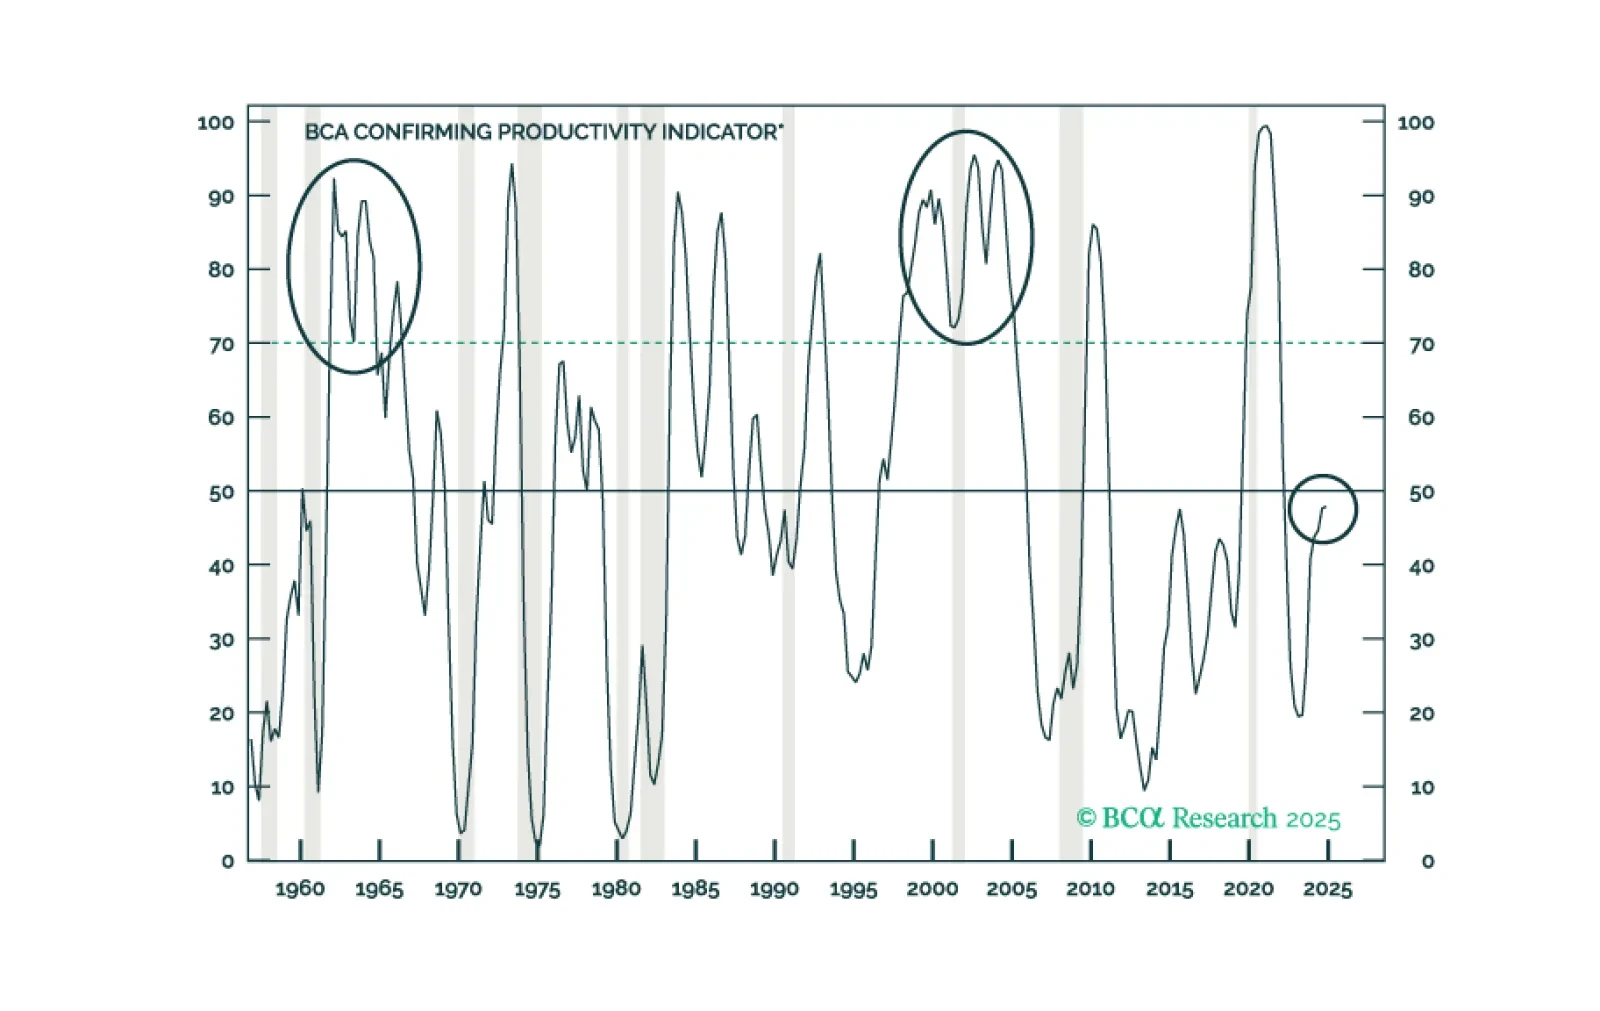
In Section II, Jonathan presents a checklist that investors can use to confirm whether AI’s purported productivity gains are real. The checklist does not currently suggest that artificial intelligence is meaningfully boosting productivity growth. US equity valuation reflects very significant optimism about AI, underscoring the profound risk facing equity investors if the narrative about AI shifts in a pessimistic direction.
In Section I, Doug notes that the chaos of the new administration, including bellicose tariff threats and DOGE’s abrasive and indiscriminate approach, are sowing uncertainty and fortifying economic headwinds. Lowered guidance of prominent retailers, alongside weakening services PMIs, bode poorly for economic activity considering that improving manufacturing PMIs likely reflect tariff frontrunning. A recession remains our base case, suggesting that investors should be underweight stocks within multi-asset portfolios. In Section II, Jonathan presents a checklist that investors can use to confirm whether AI’s purported productivity gains are real. The checklist does not currently suggest that artificial intelligence is meaningfully boosting productivity growth. US equity valuation reflects very significant optimism about AI, underscoring the profound risk facing equity investors if the narrative about AI shifts in a pessimistic direction.
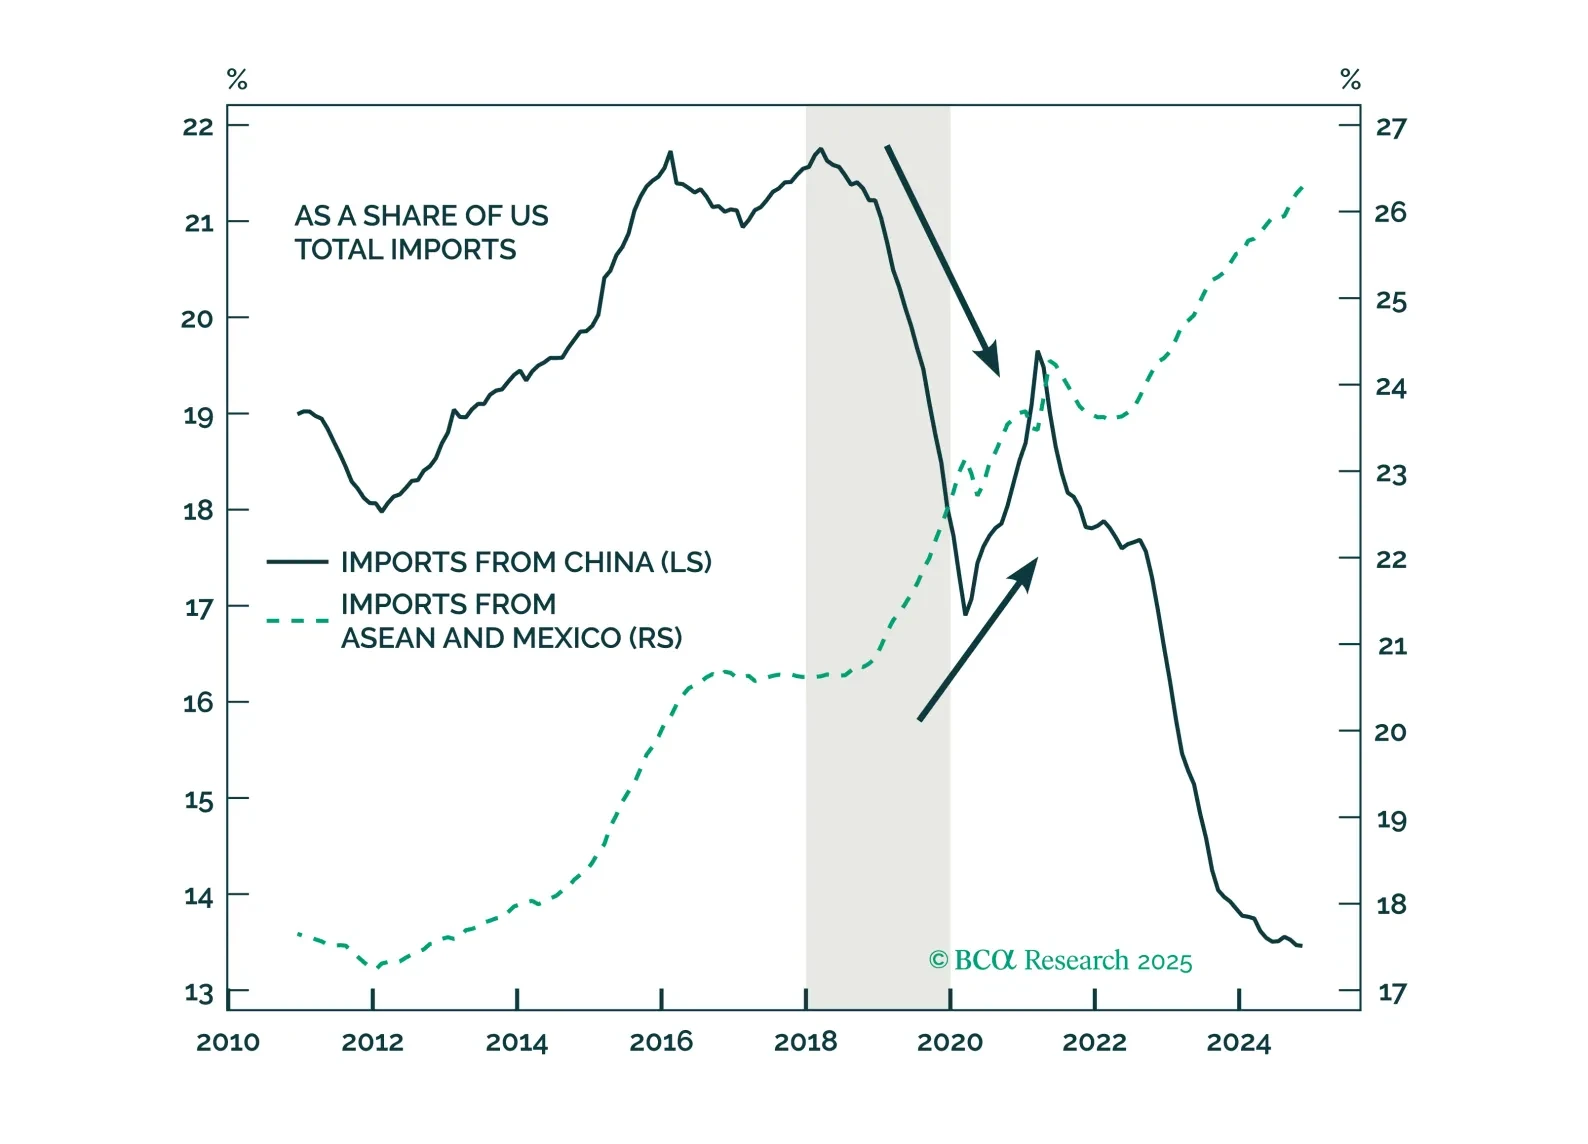
We anticipate decisive tariff measures early in Trump’s second term. In this Special Report, we explore how the costs of higher tariffs might be distributed among foreign suppliers, U.S. importers, and consumers.
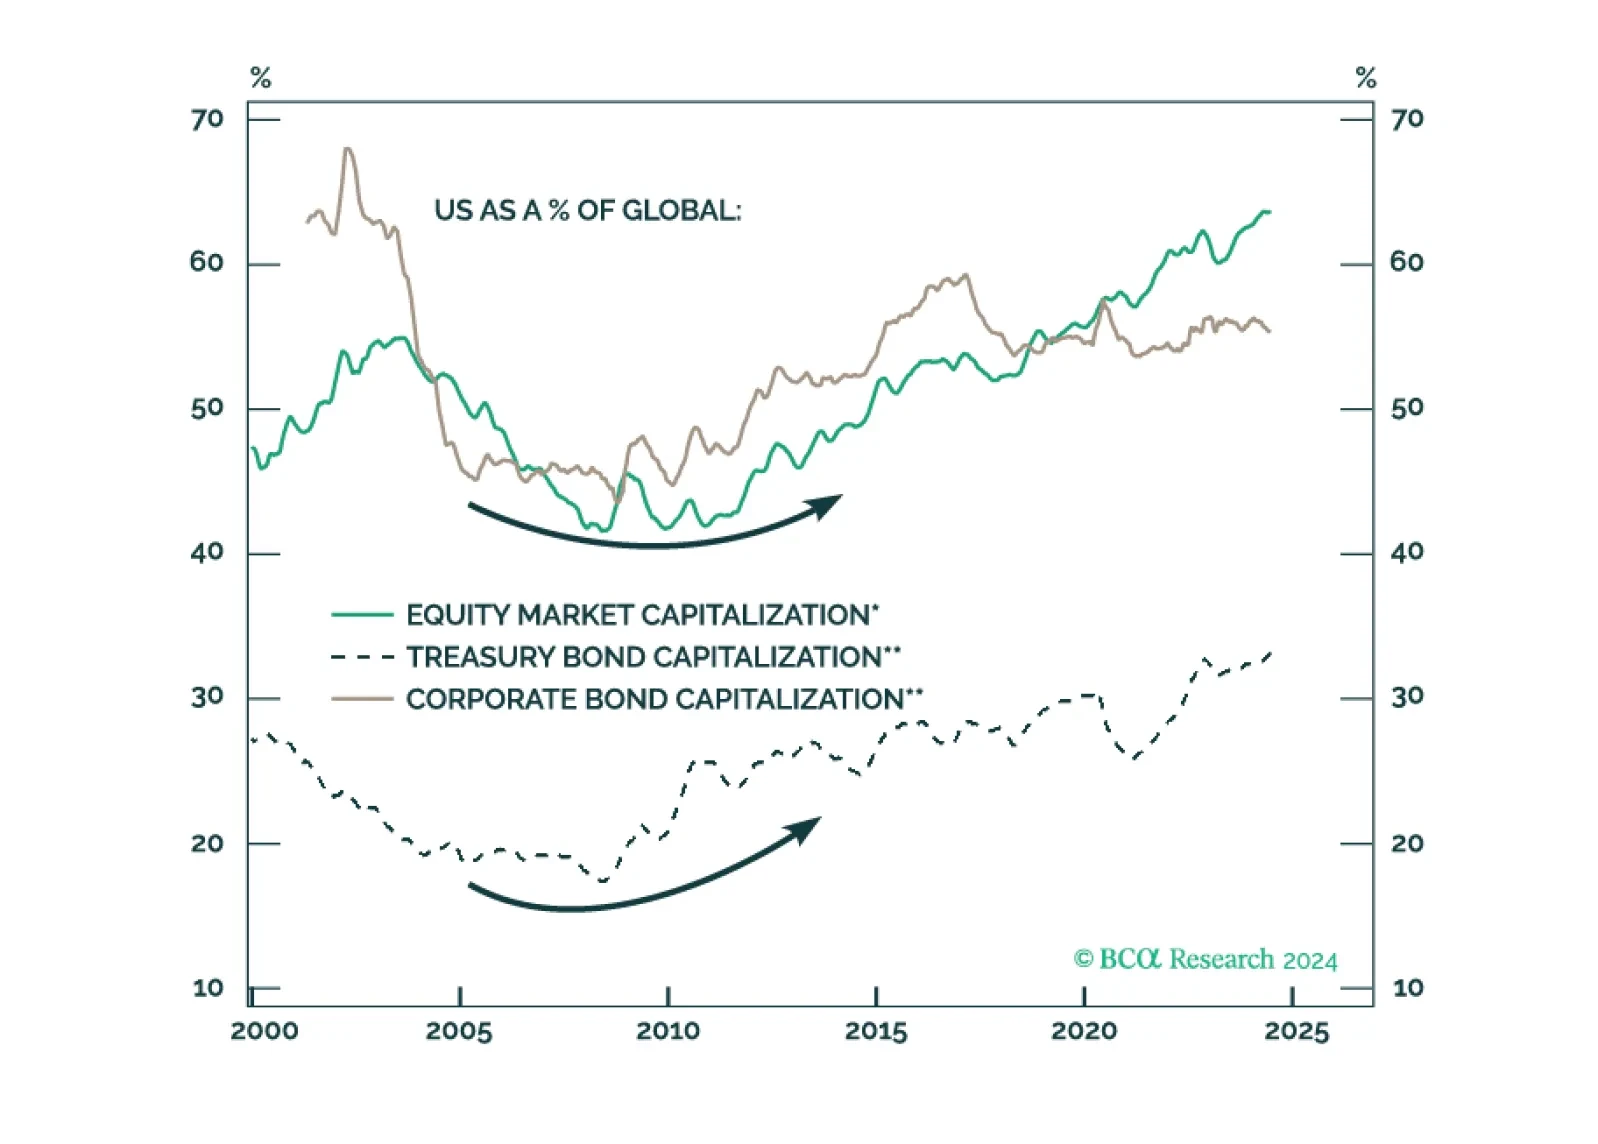
US assets and the US dollar should remain resilient relative to global peers over the next 12 months as policy uncertainty, election risk, and geopolitical risk reach a climax. After that, investors should reassess their regional allocation.
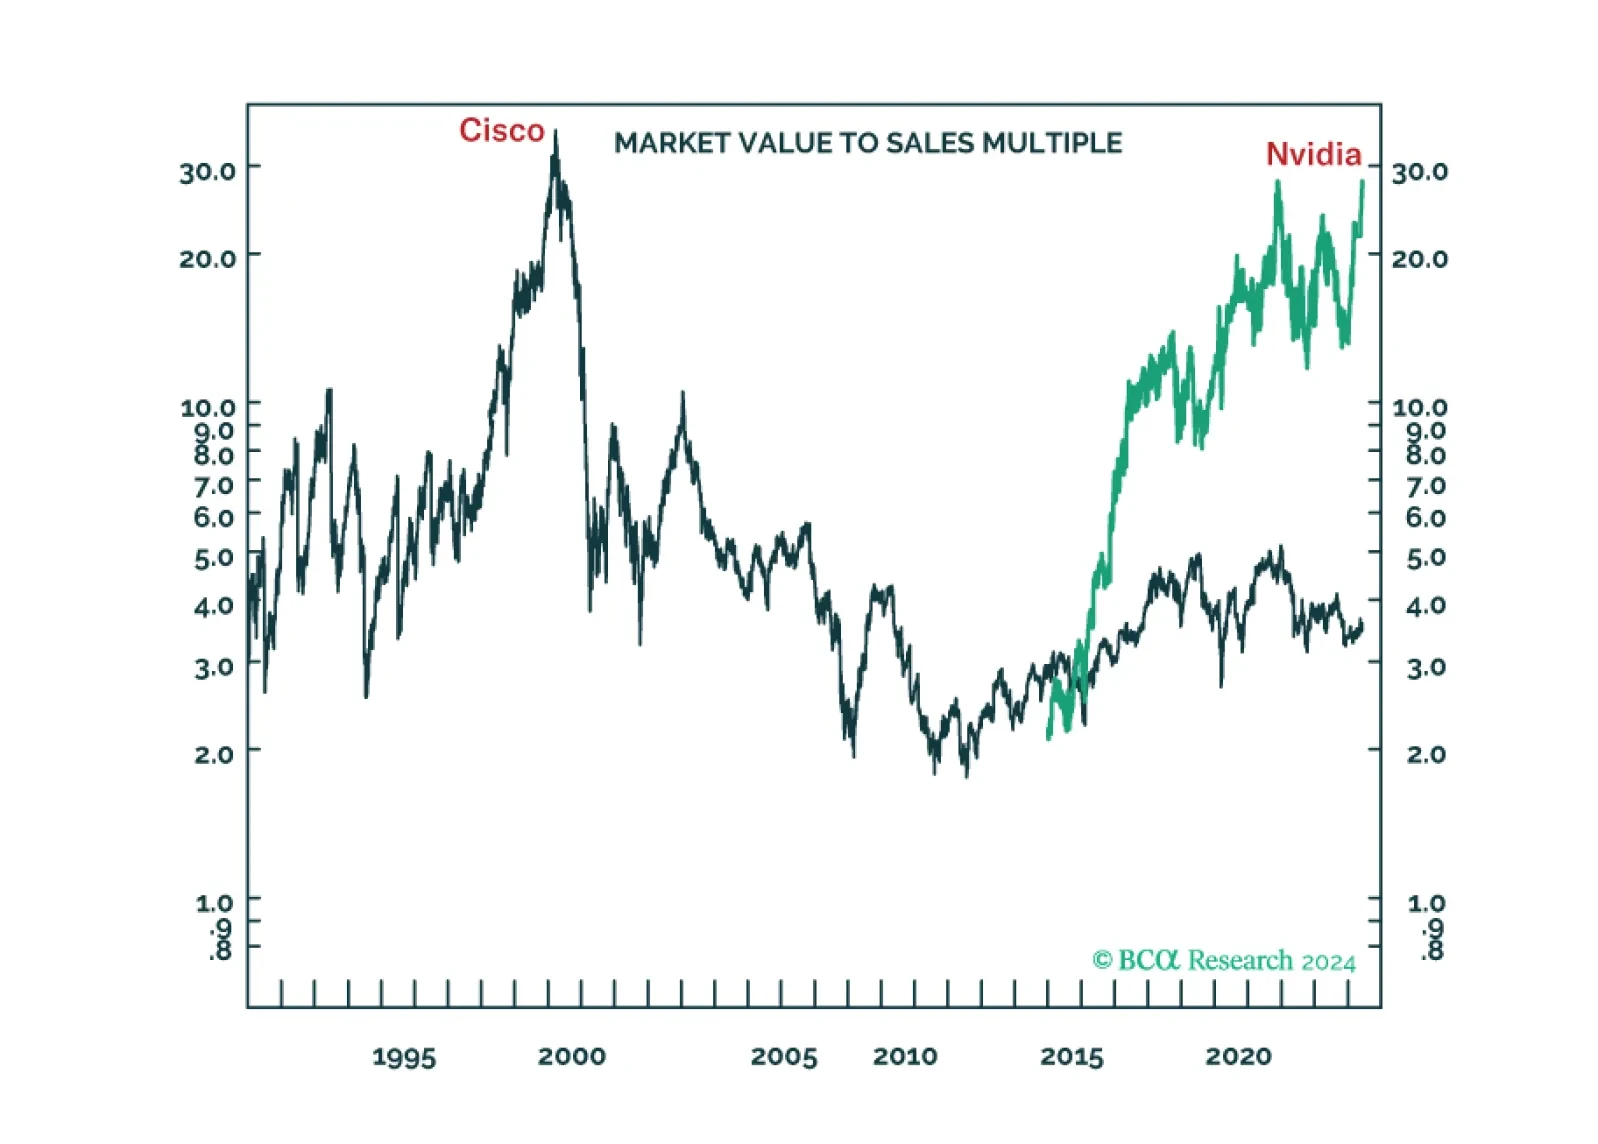
The long-term winners from the generative-AI gold rush are unlikely to be the ‘picks and shovels’ stock Nvidia or the overvalued US superstars of Web 2.0. We discuss the structural investment implications. Plus: time to go tactically overweight global consumer discretionary (RXI).