Inflación
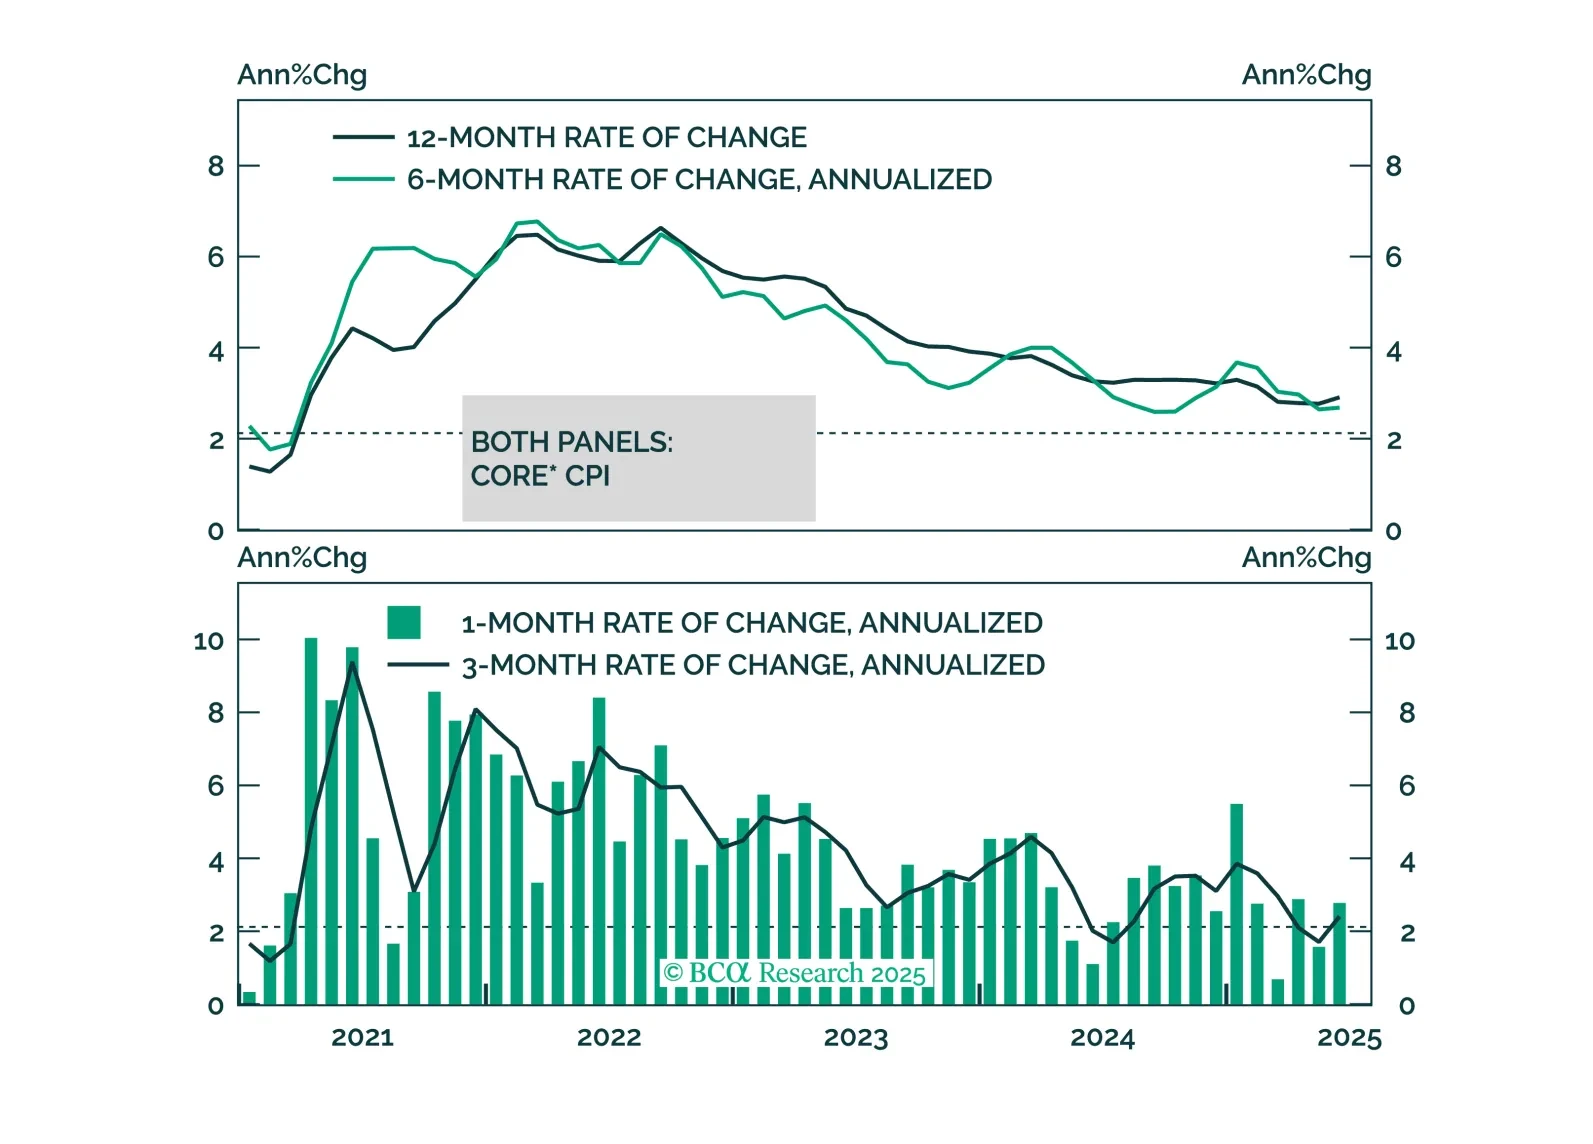
Hablamos sobre las implicaciones del informe del IPC de esta mañana y la relativa atractividad de los empinadores de curva del Tesoro a 2/5 años.
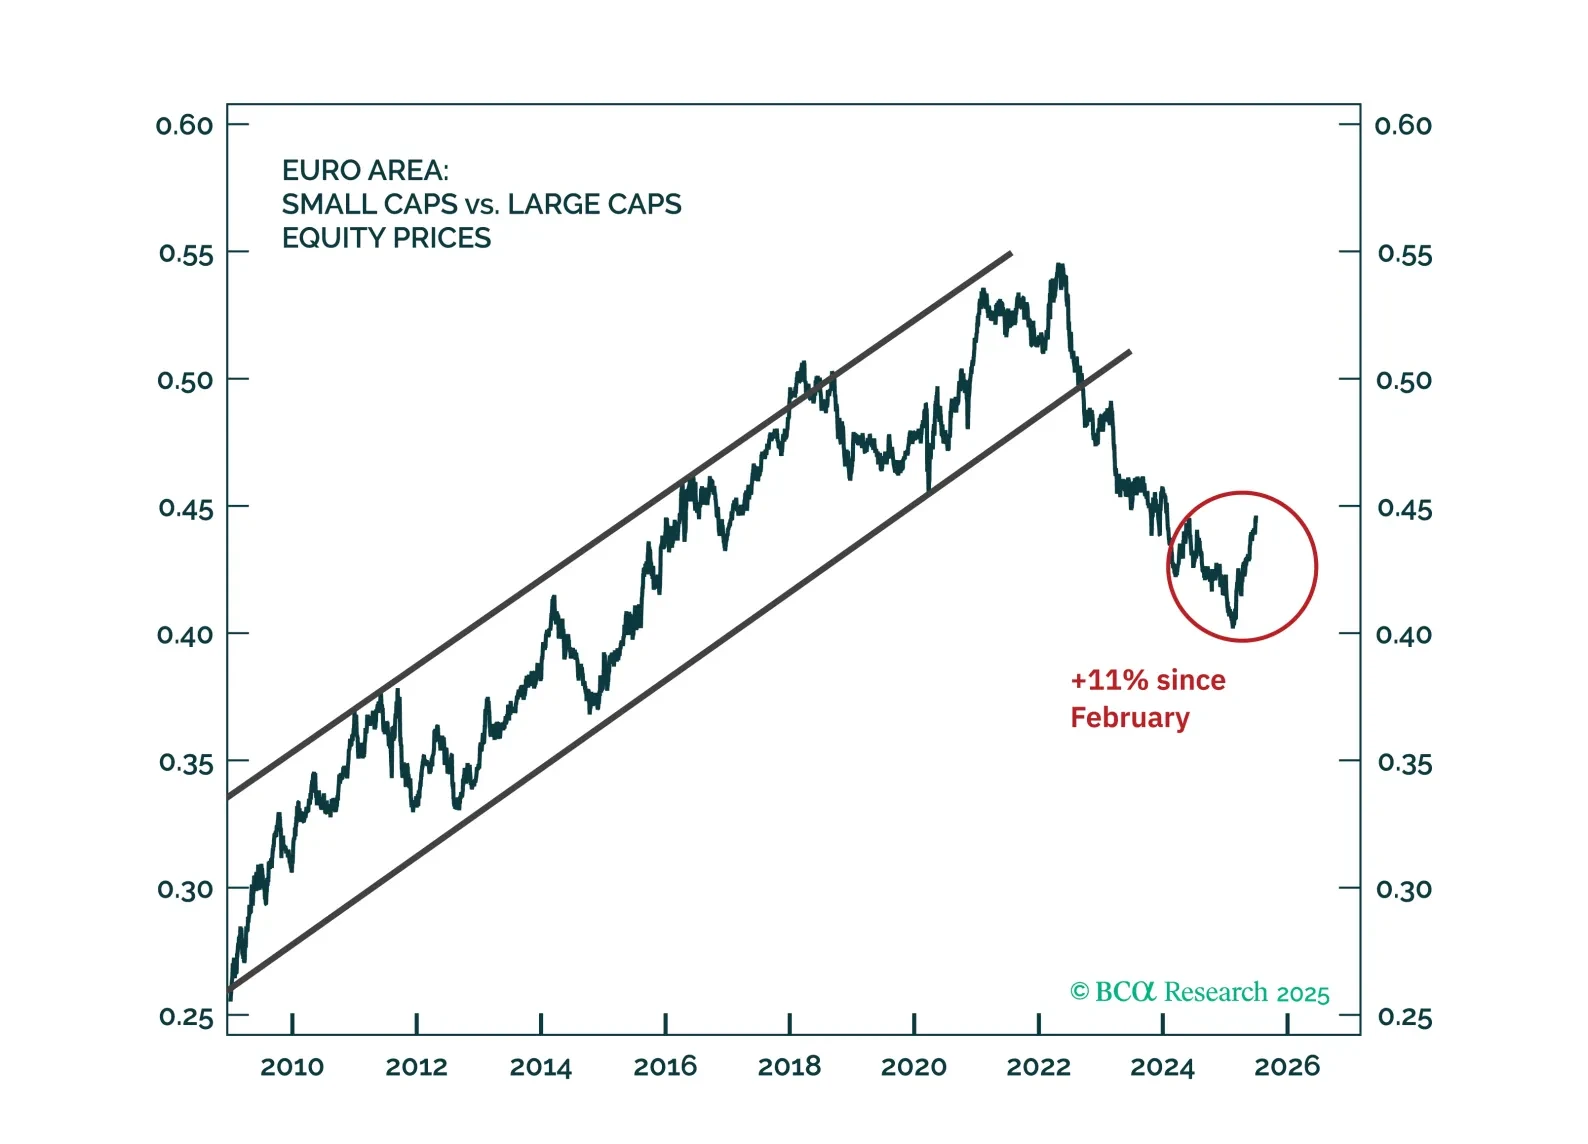
Recomendamos incrementar al máximo la sobreponderación de las small caps europeas y reafirmamos nuestra recomendación de posicionarse largo en small caps europeas en comparación con las estadounidenses.
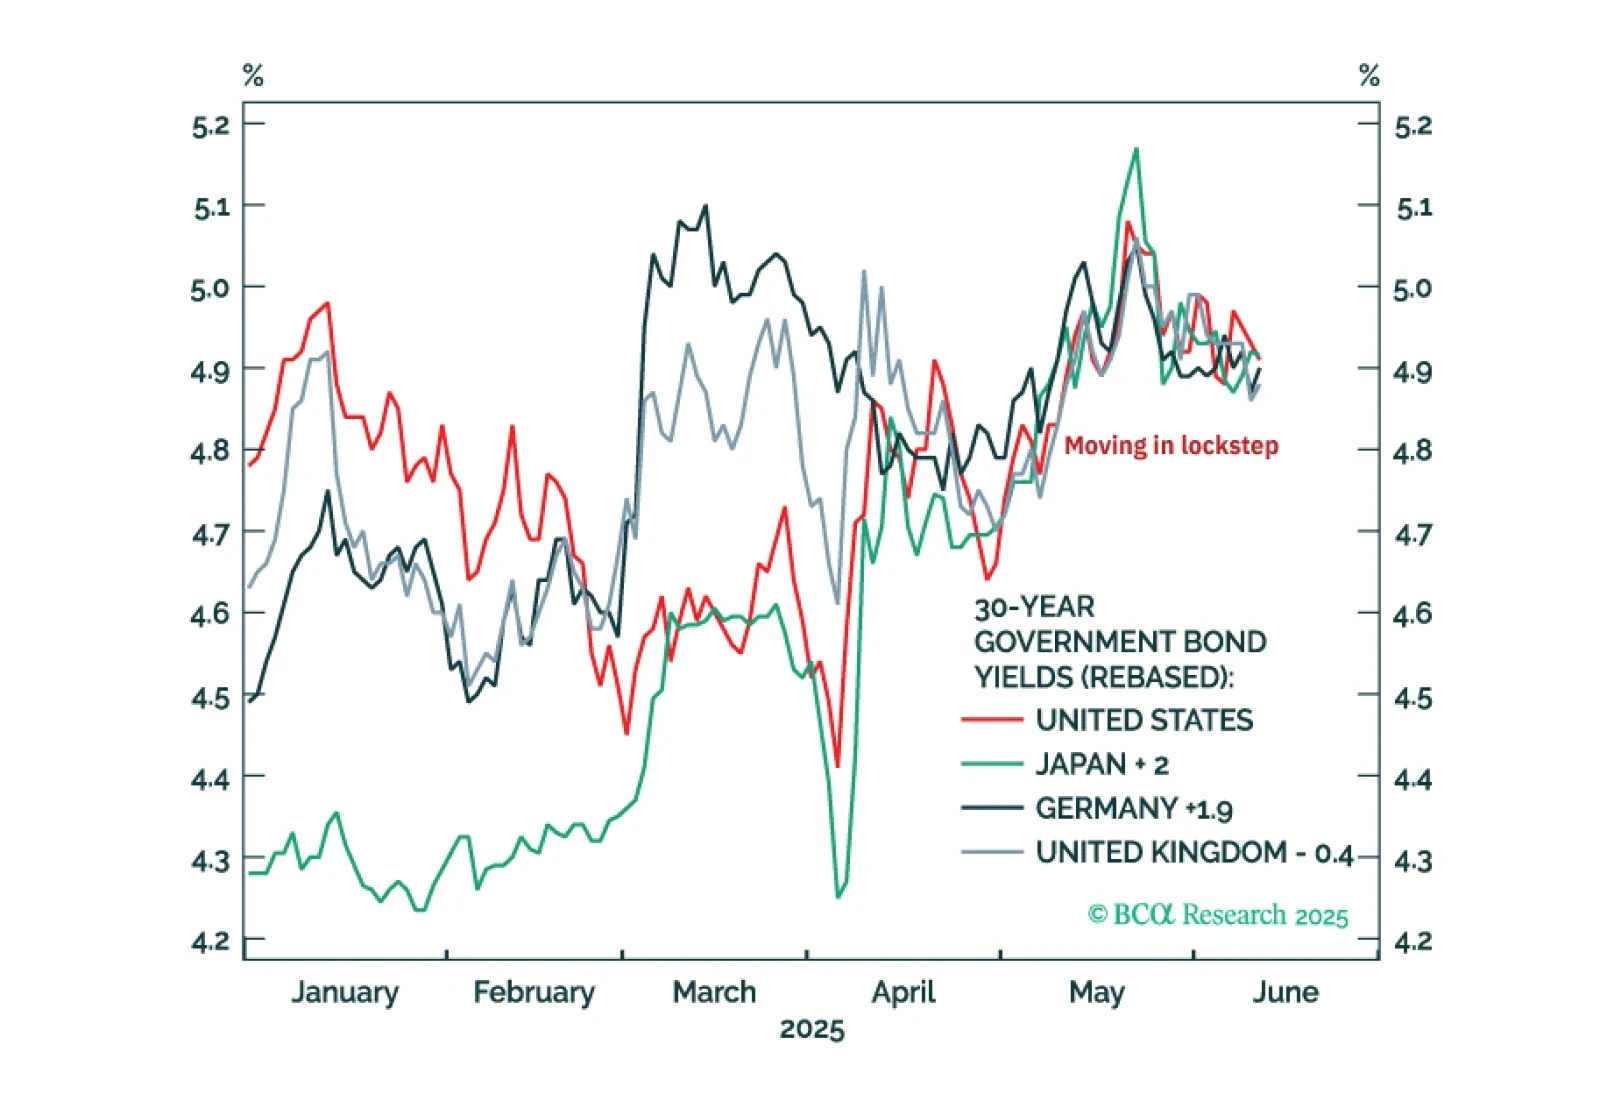
The perfectly synchronised moves in US, Japanese, German, and UK 30-year bond yields through the past two months are odd… and irrational. These irrational moves present compelling investment opportunities.
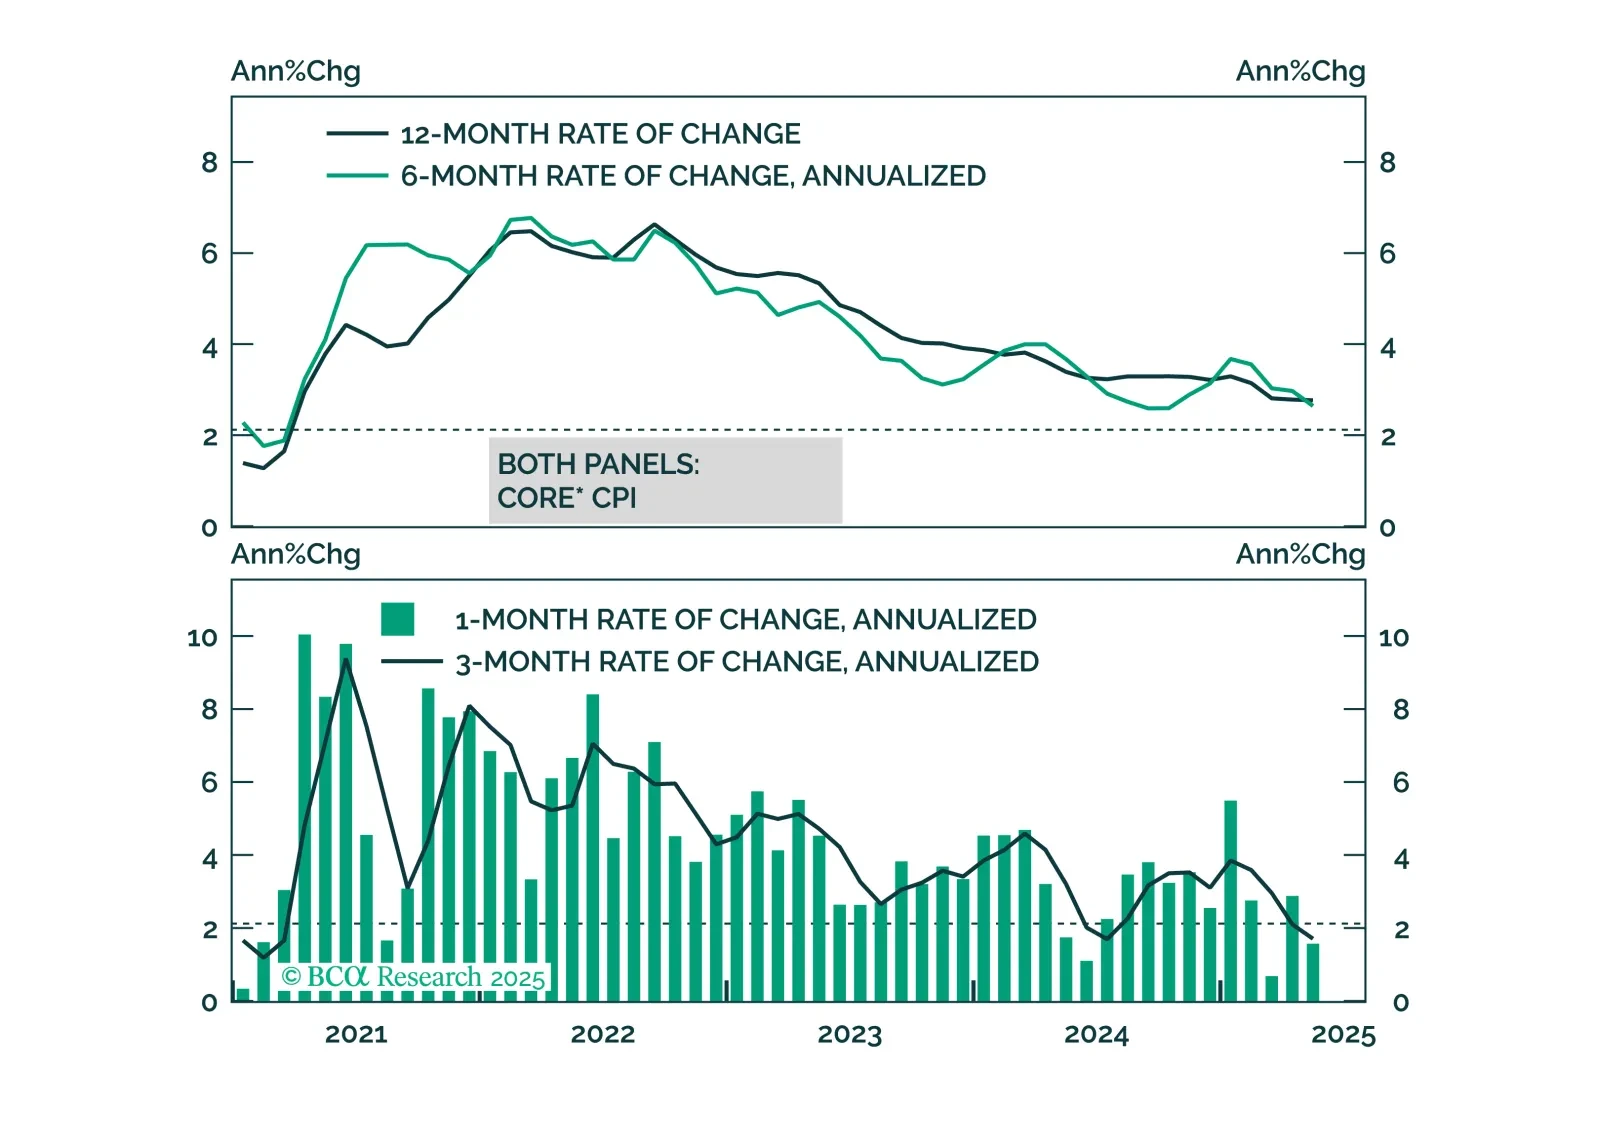
While we anticipate higher inflation in June, it looks increasingly likely that the price impact from tariffs will be less aggressive and long-lasting than many feared.
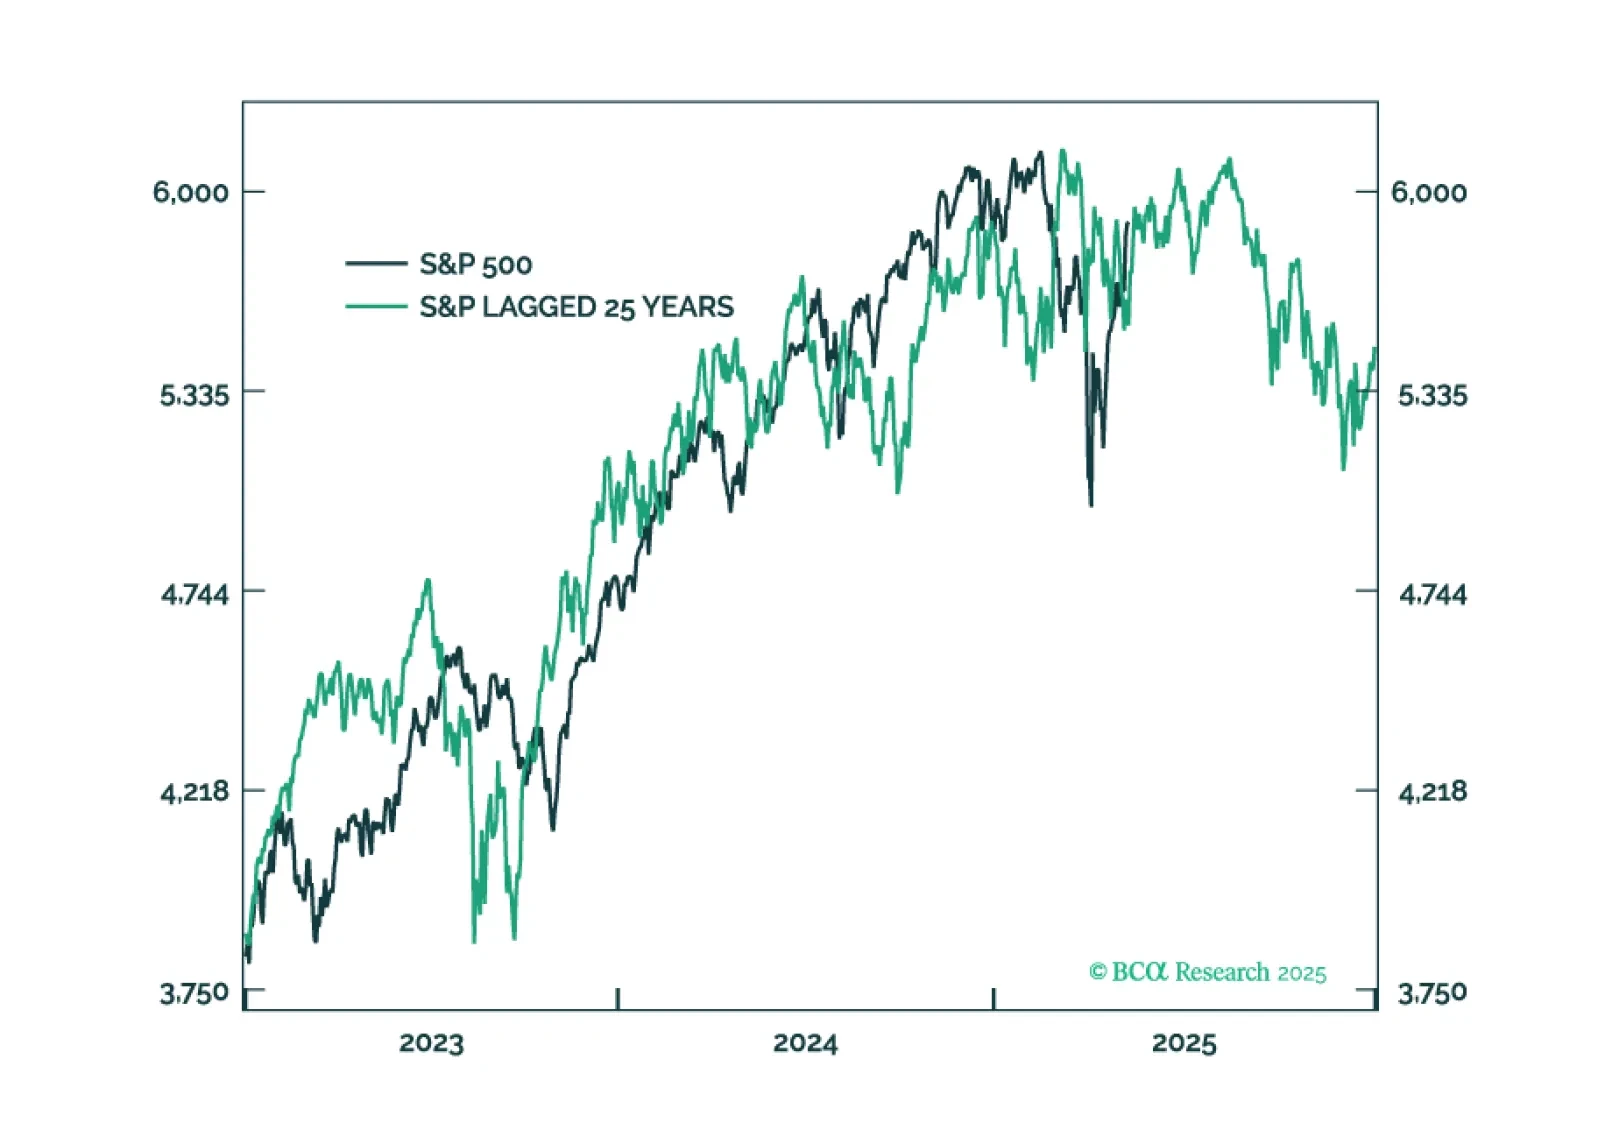
This year’s plunge in tech stocks followed by the recent strong countertrend rally is eerily reminiscent of 2000. But the market and economic parallels between 2025 and in 2000 run much deeper. This report lists 10 striking parallels between 2025 and 2020, then highlights some important differences, and ends by describing how the rest of 2025 might unfold based on a playbook that is: 2025 = ‘2000 with some tweaks.’

A weakening economy will apply downward pressure to Treasury yields, but the Trump term premium will keep long-dated yields higher than they would otherwise be. This makes Treasury curve steepeners the most attractive trade in US fixed income.
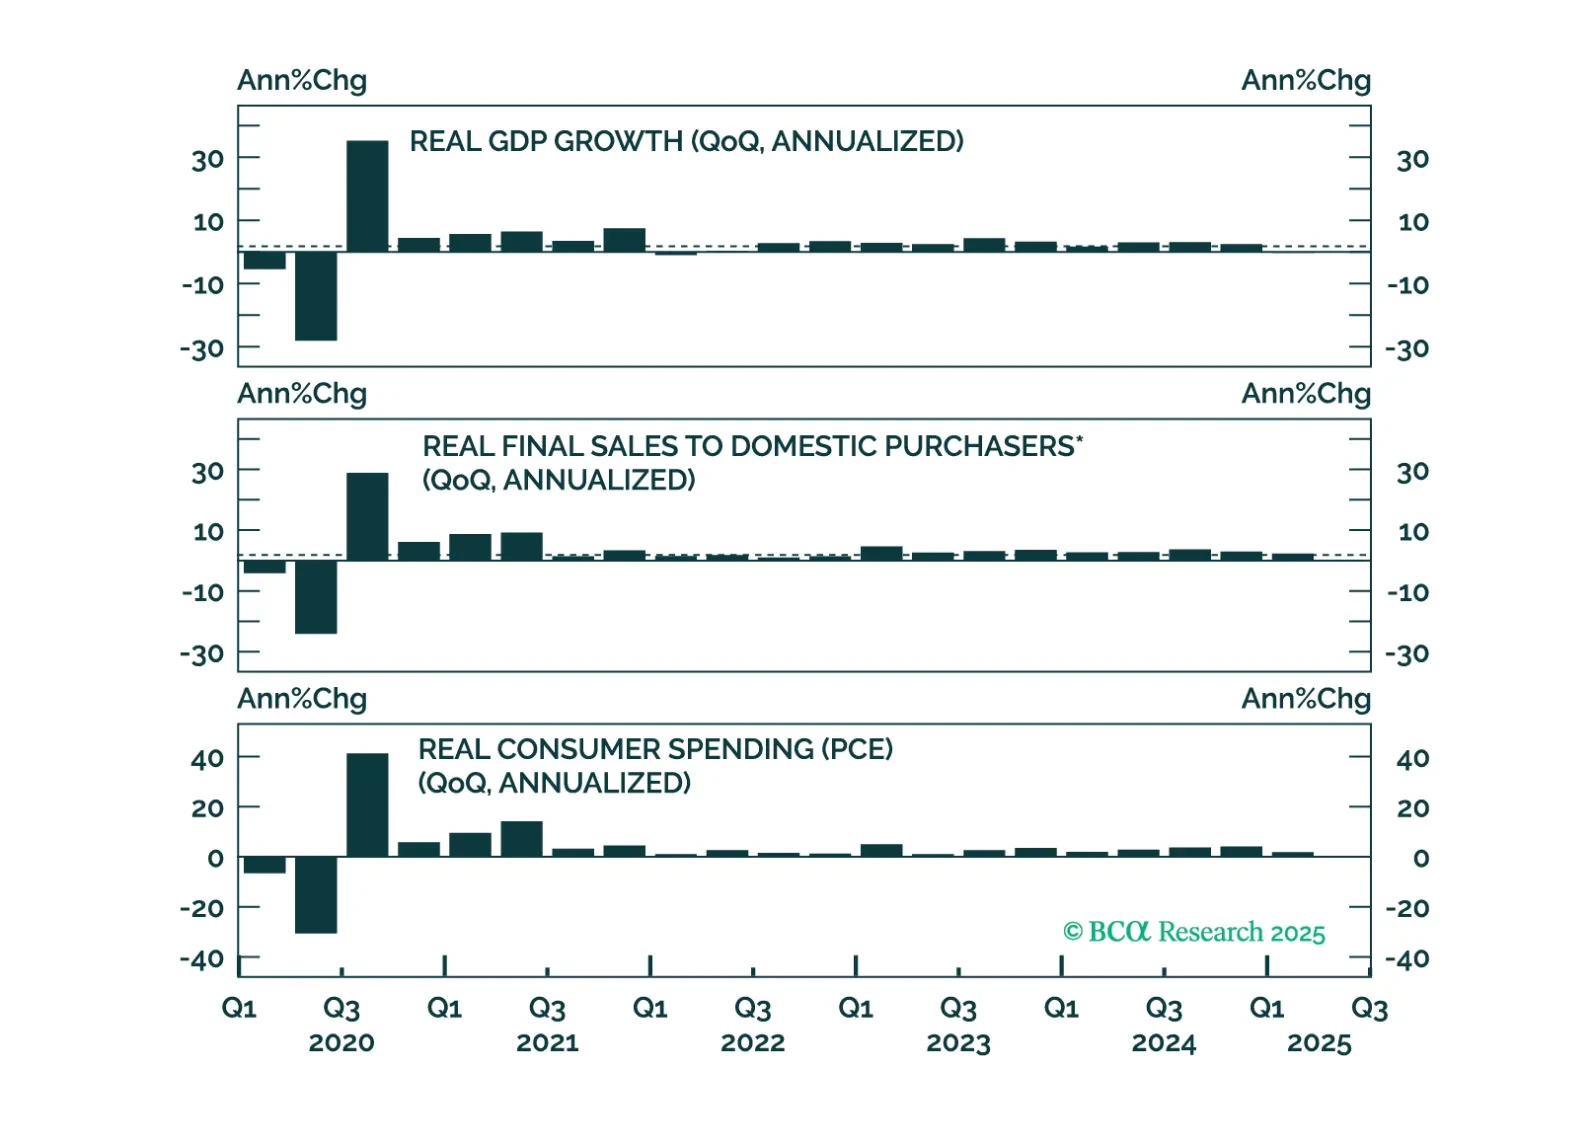
The Fed held rates steady this afternoon, and the timing of its next move will be dictated by whether the tariff shock to inflation is transitory or more long lasting.
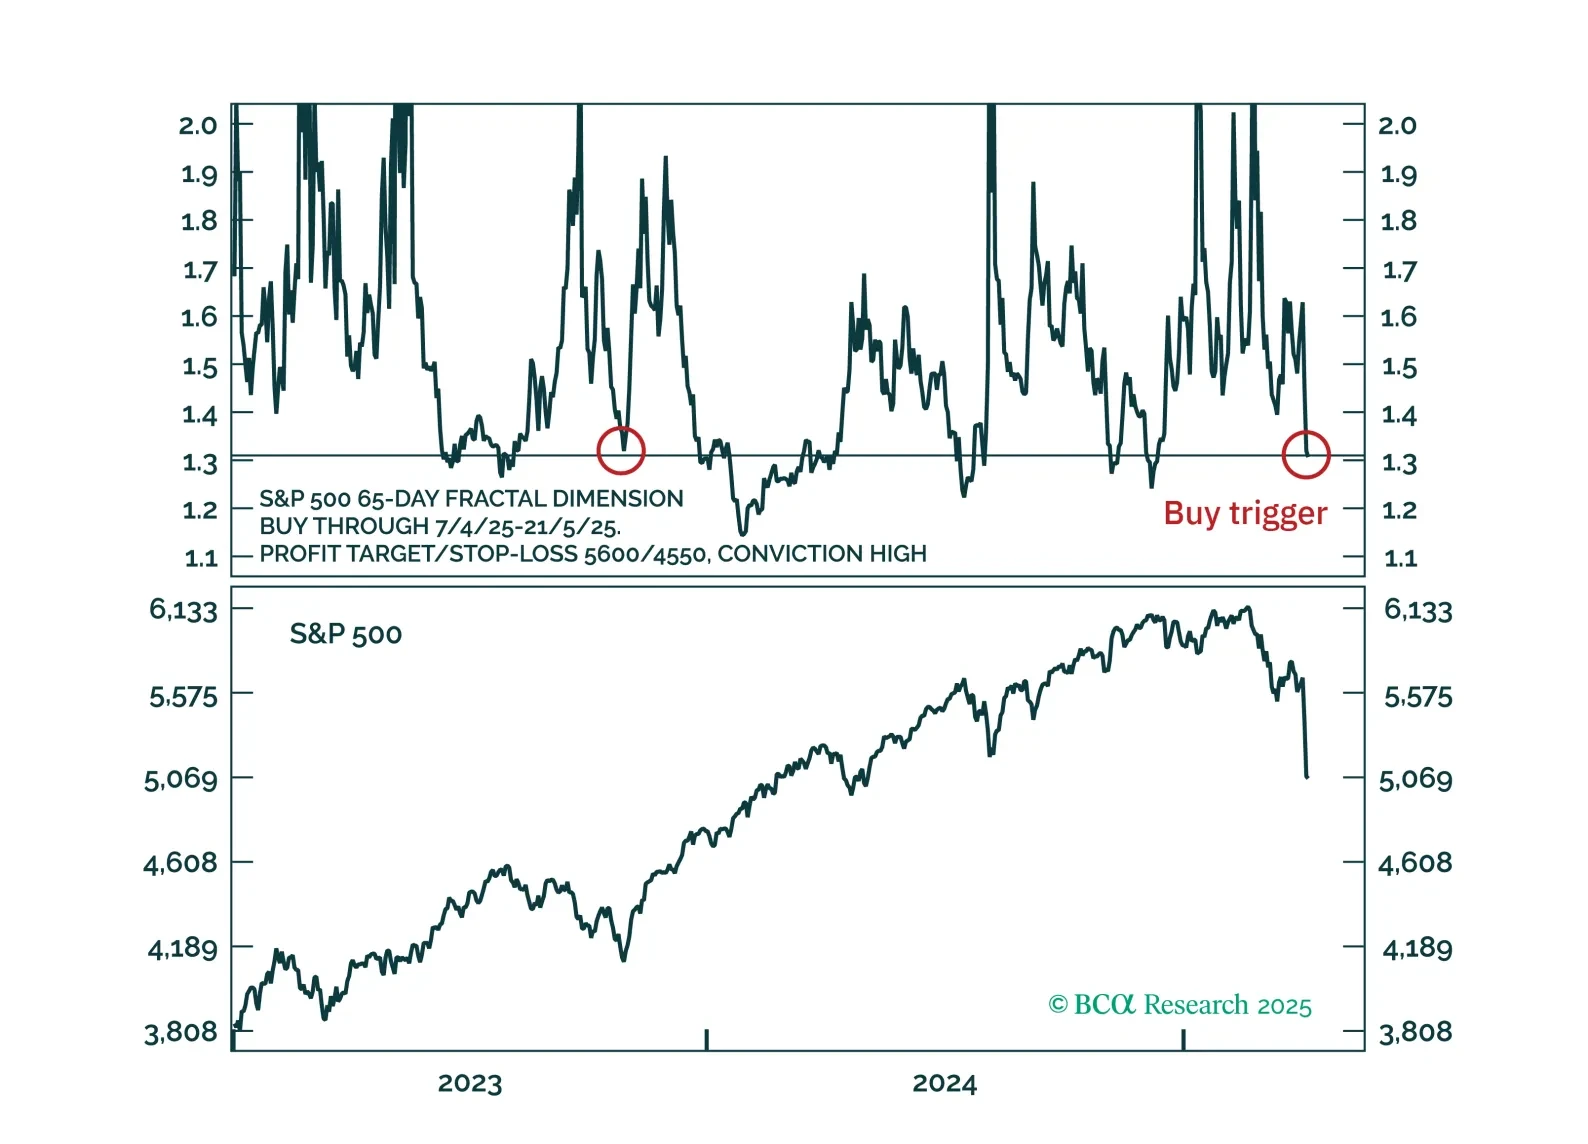
Countertrend buy triggers have been activated for the S&P 500, Nasdaq and Nasdaq versus 30-year T-bond.
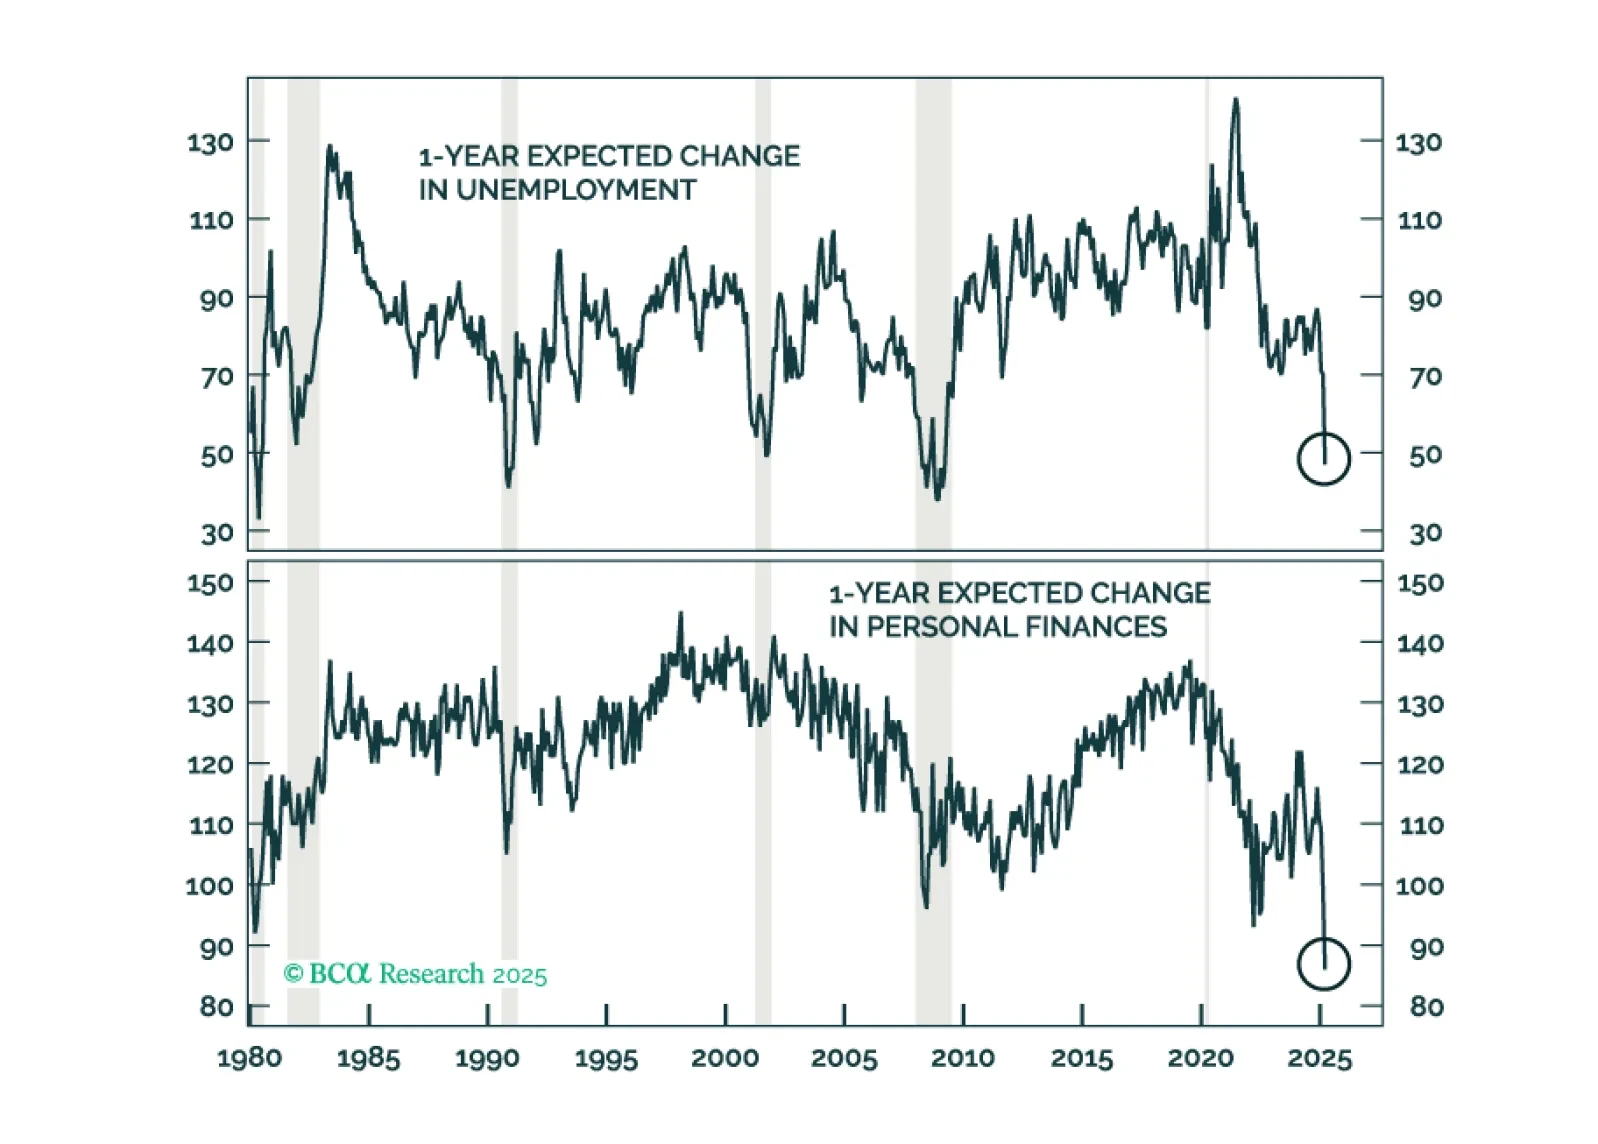
Las medidas de estímulo que impulsaban la expansión pos-COVID empezaban a disminuir después de cinco años y encaminaban a la economía hacia una recesión que se produciría de forma orgánica. Ahora que DOGE y la guerra comercial en múltiples frentes han acelerado el calendario, reiteramos nuestras recomendaciones de aversión al riesgo.
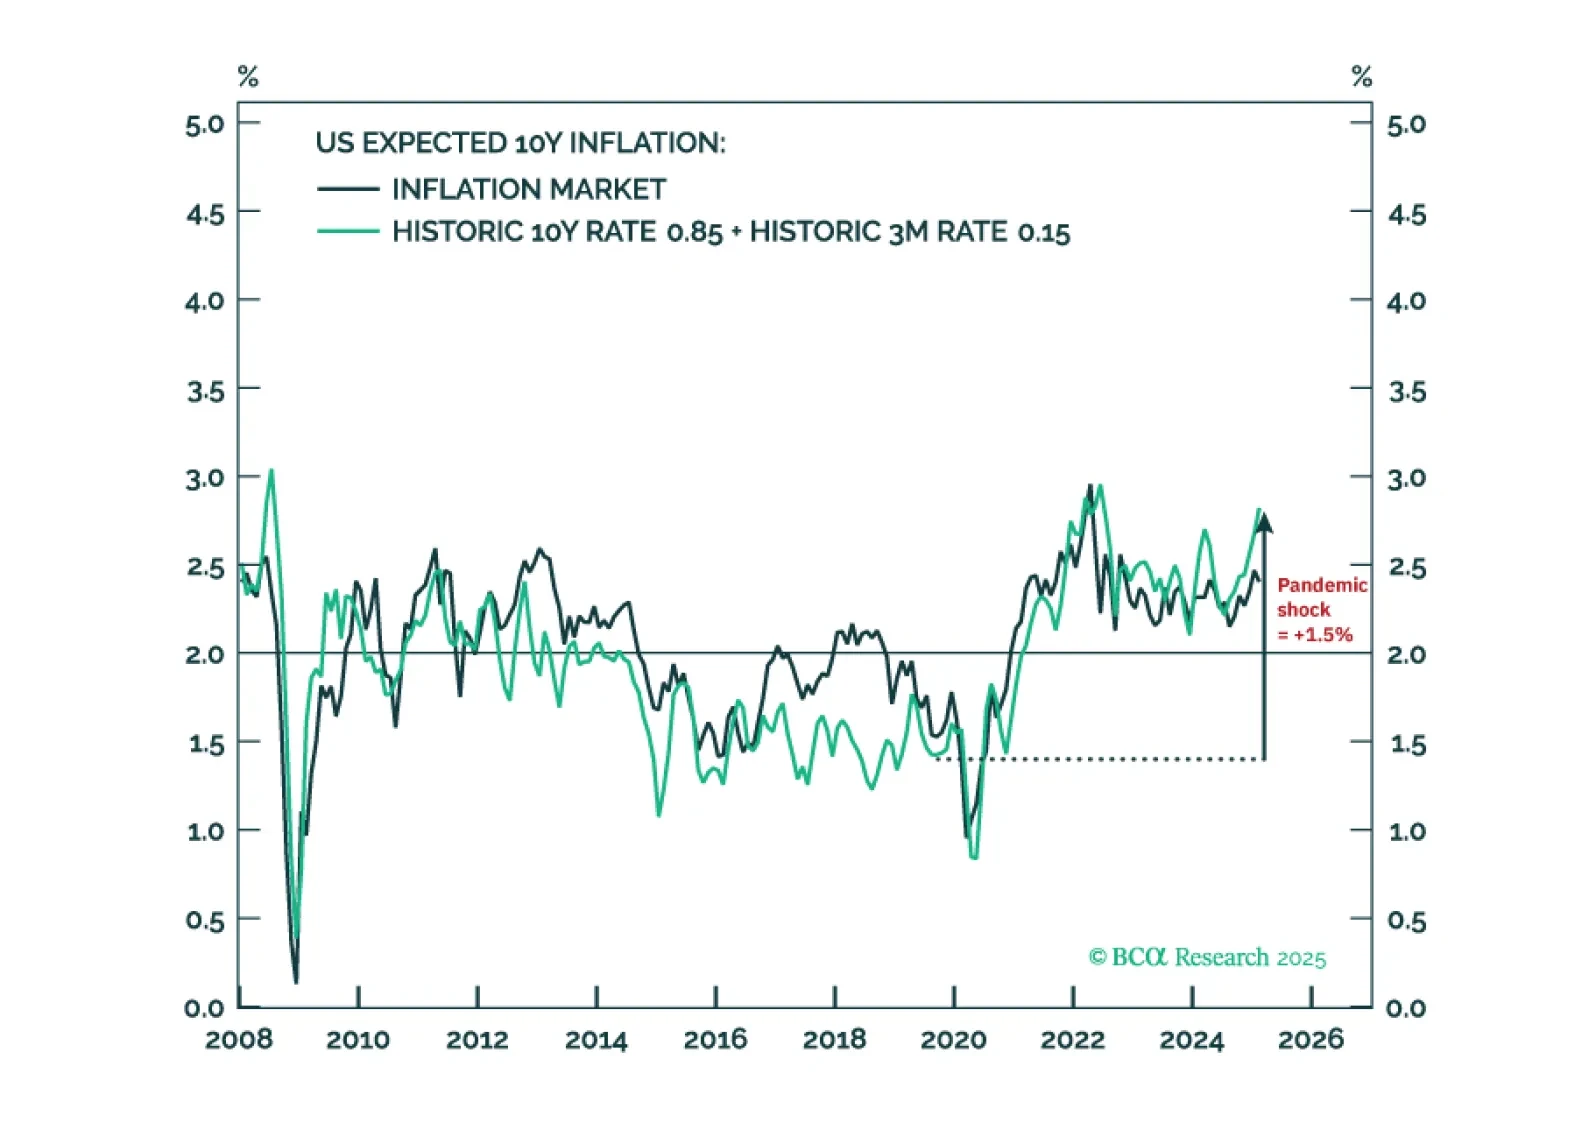
Tariffs will make a difficult job almost impossible. Hitting and sustaining a precise 2 percent inflation target is more about luck than judgement. It requires both the starting point for inflation expectations and any inflation/deflation shock to combine perfectly to 2 percent. While structural inflation expectations in the euro area and Japan could be close to 2 percent, those in the US and the UK will be stuck uncomfortably above 2 percent. We discuss the investment implications for rates and FX. Plus: gold is vulnerable to a tactical reversal.