Estados Unidos
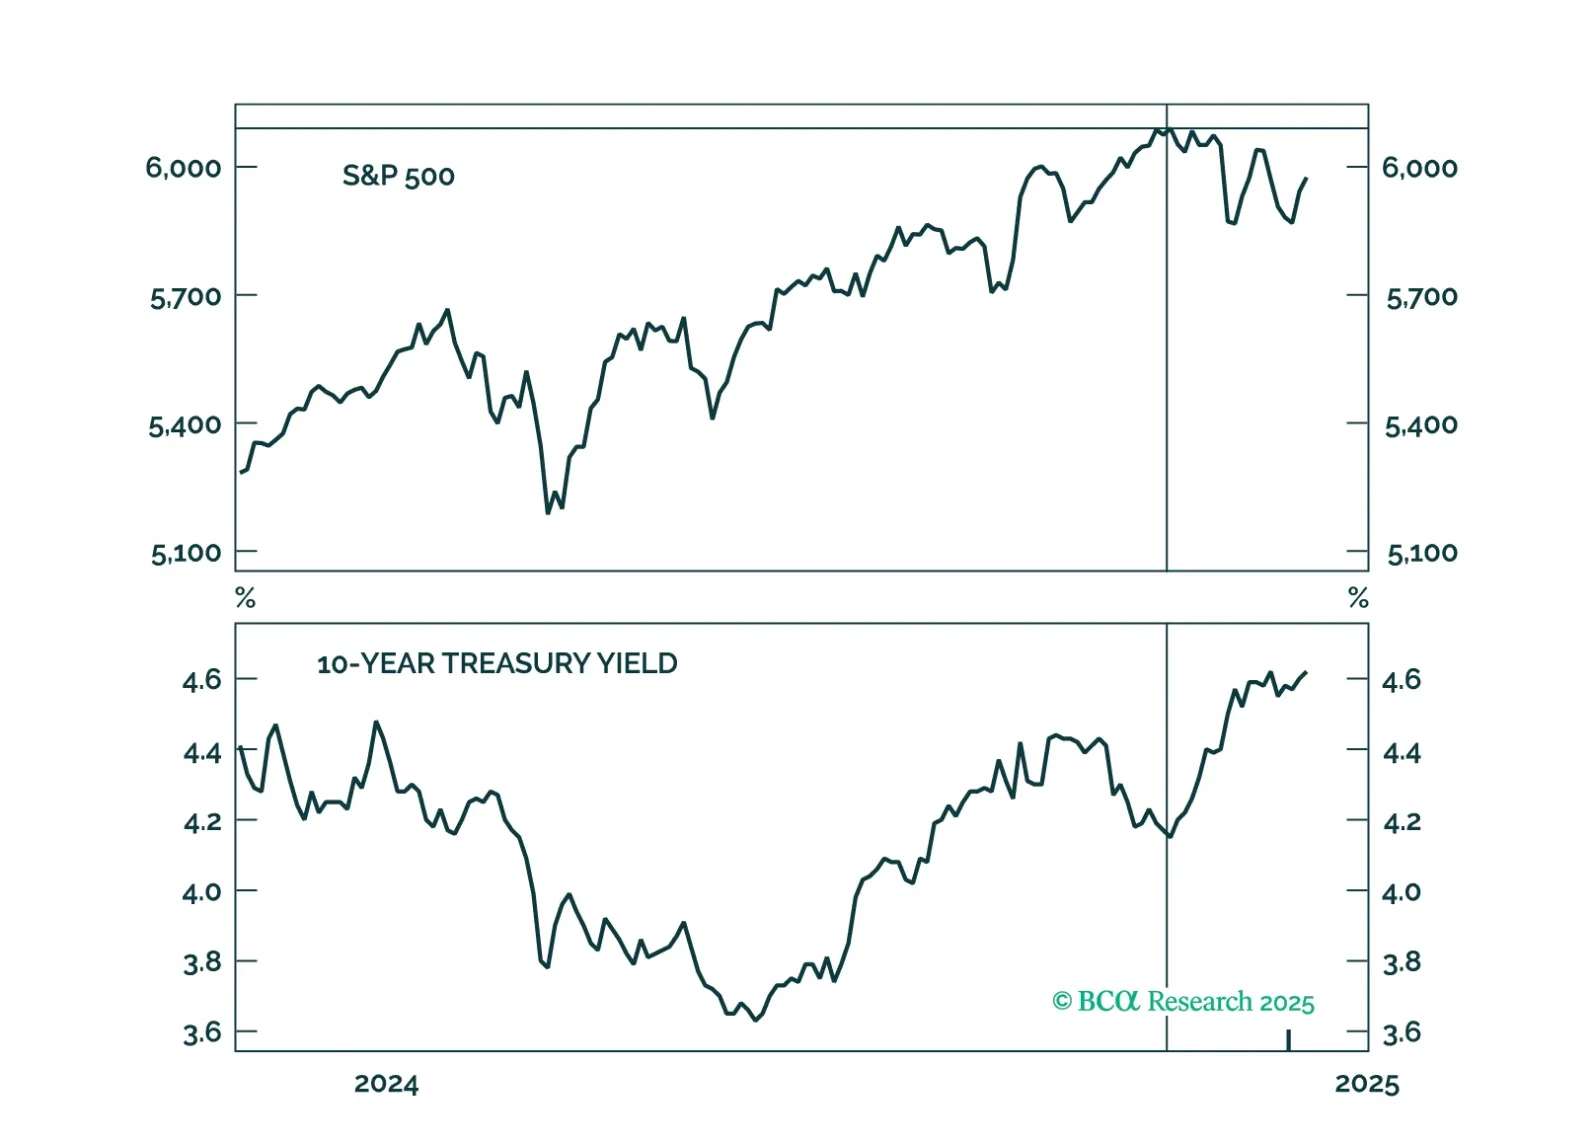
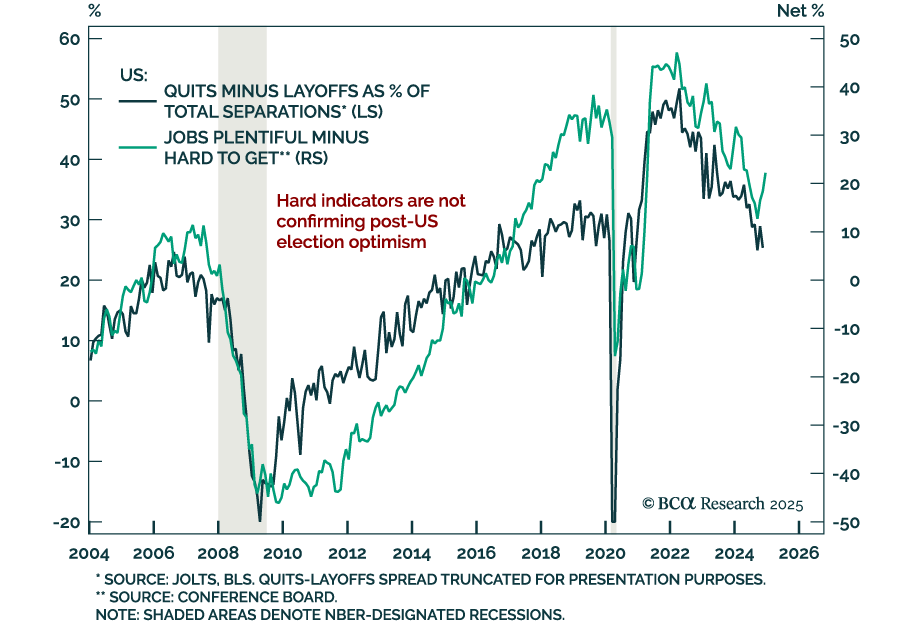
Las ofertas de empleo volvieron a superar las expectativas en noviembre, aumentando a 8,1 millones desde 7,8 millones en octubre. Sin embargo, las contrataciones y las renuncias disminuyeron y los despidos aumentaron. La brecha entre renuncias y despidos, un…
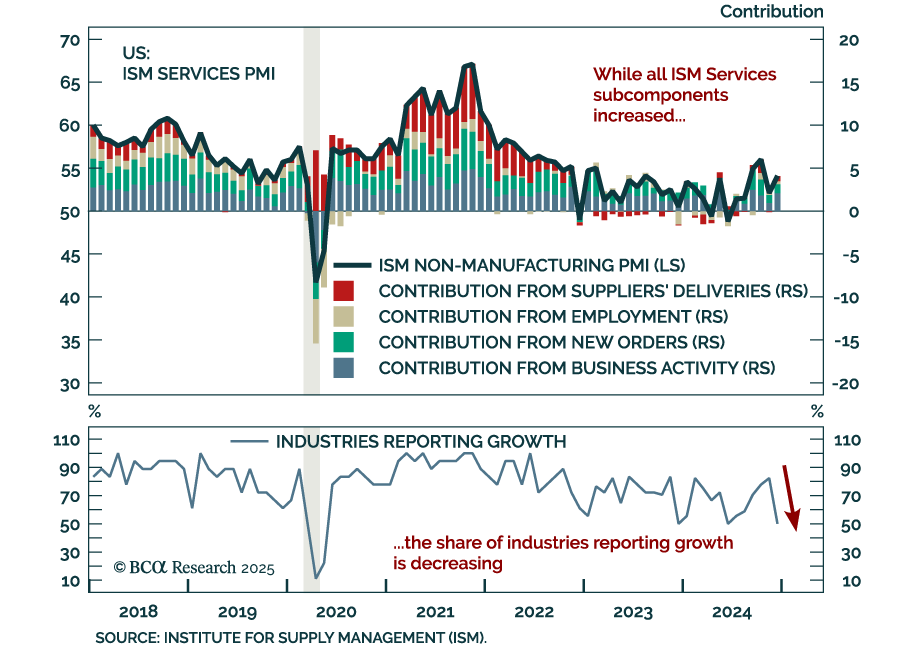
The December ISM Services PMI beat estimates, increasing to 54.1 from 52.1 in November. All subcomponents increased except for employment, which nonetheless remains in expansion. The prices paid component was especially strong, increasing to 64.4 from 58.2.…
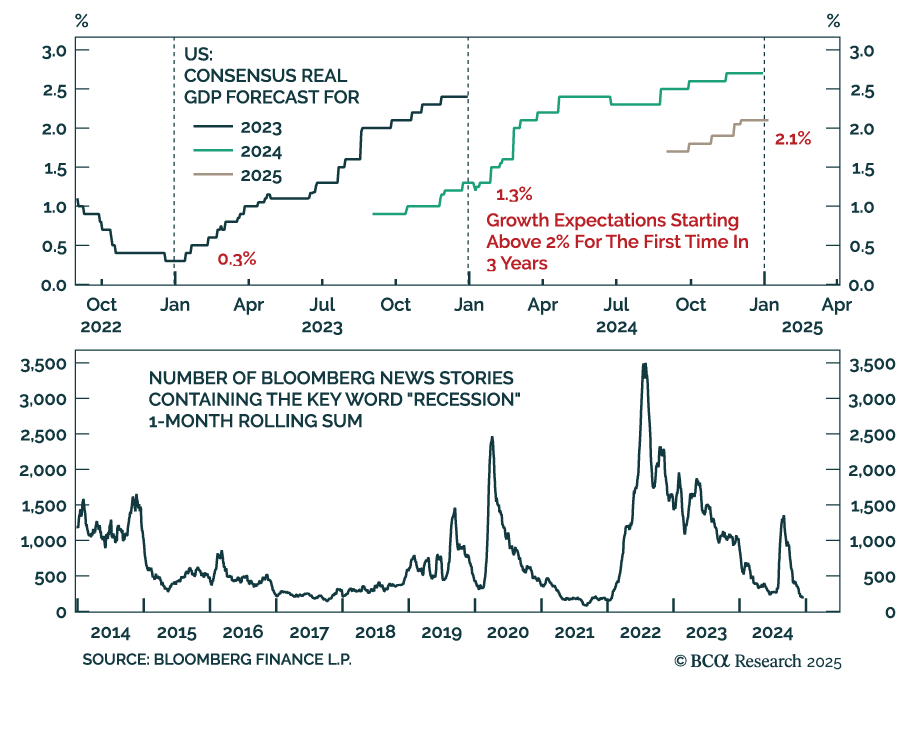
Our Global Asset Allocation strategists published their monthly tactical asset allocation report, where they illustrate booming expectations in the US will be self-limiting. For the first time since 2022, US GDP growth is expected to start the year above 2%,…
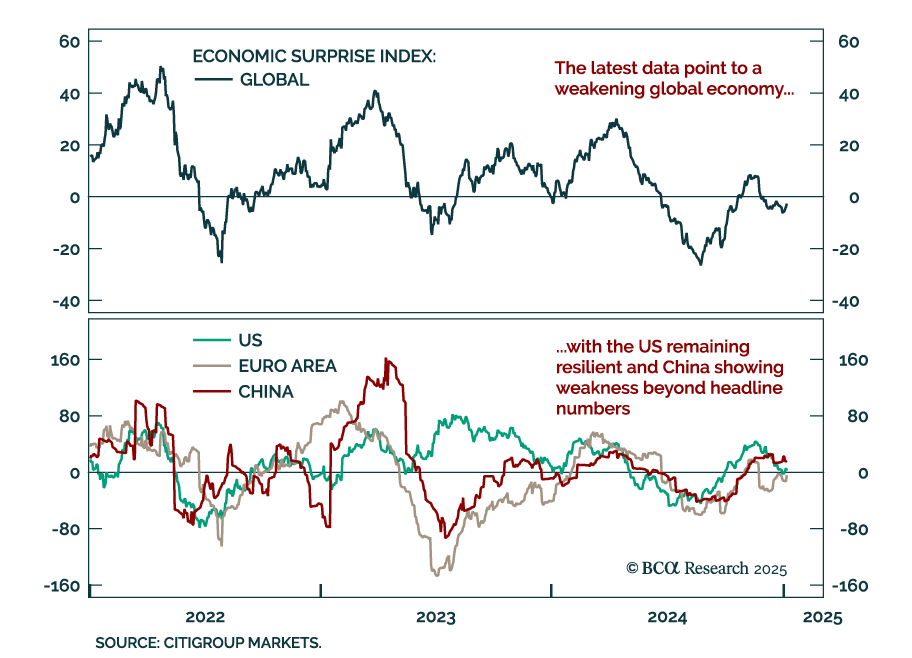
Economic data released over the holiday period extended recent trends, reflecting a softening global economy with resilient US growth, and an ailing manufacturing sector. The December global manufacturing PMI declined to 49.6 after reaching the 50 level in…
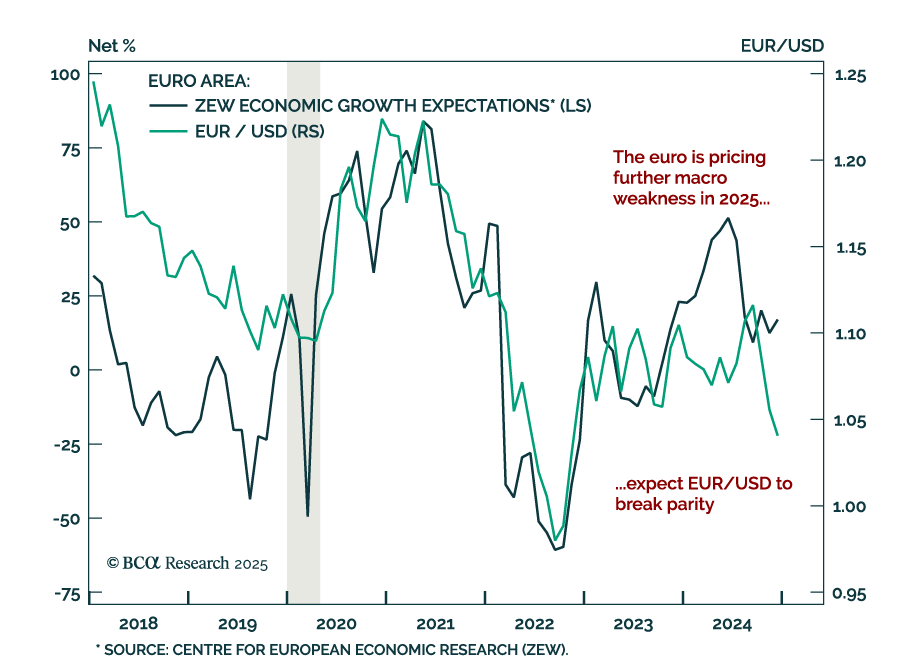
The euro broke the support level of its 2-year trading range against the USD, extending the strong dollar trend witnessed since September of last year. This trend will continue in Q1 2025. Despite global yields rallying in late 2024, the Bund-Treasury spread…
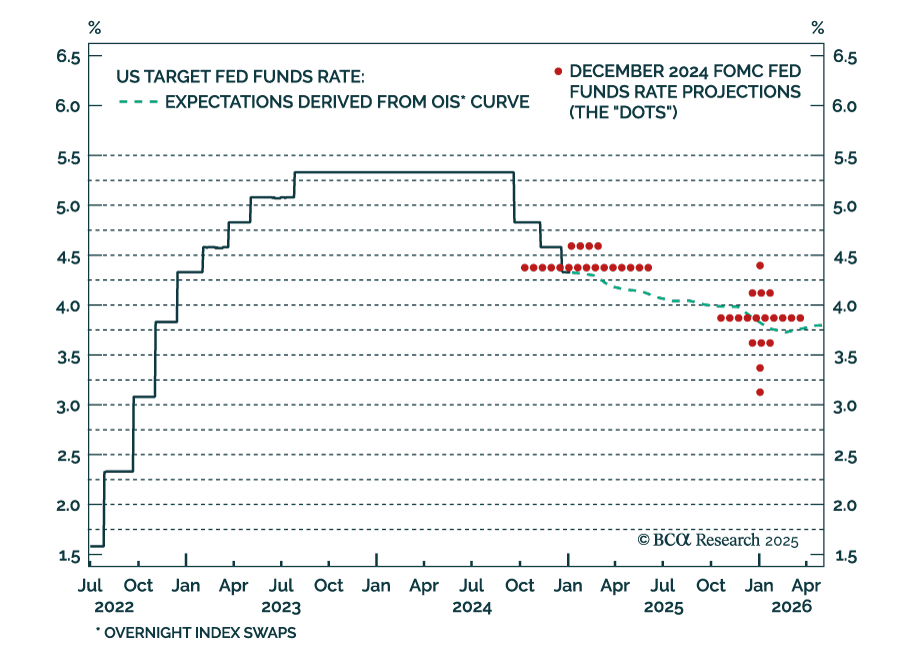
Our US Bond Strategy team published their outlook for the Fed in 2025. They expect more cuts than the 50 bps signaled by the Fed at its December meeting. Core PCE inflation is tracking well below the Fed’s 2.5% forecast, while unemployment could exceed the…
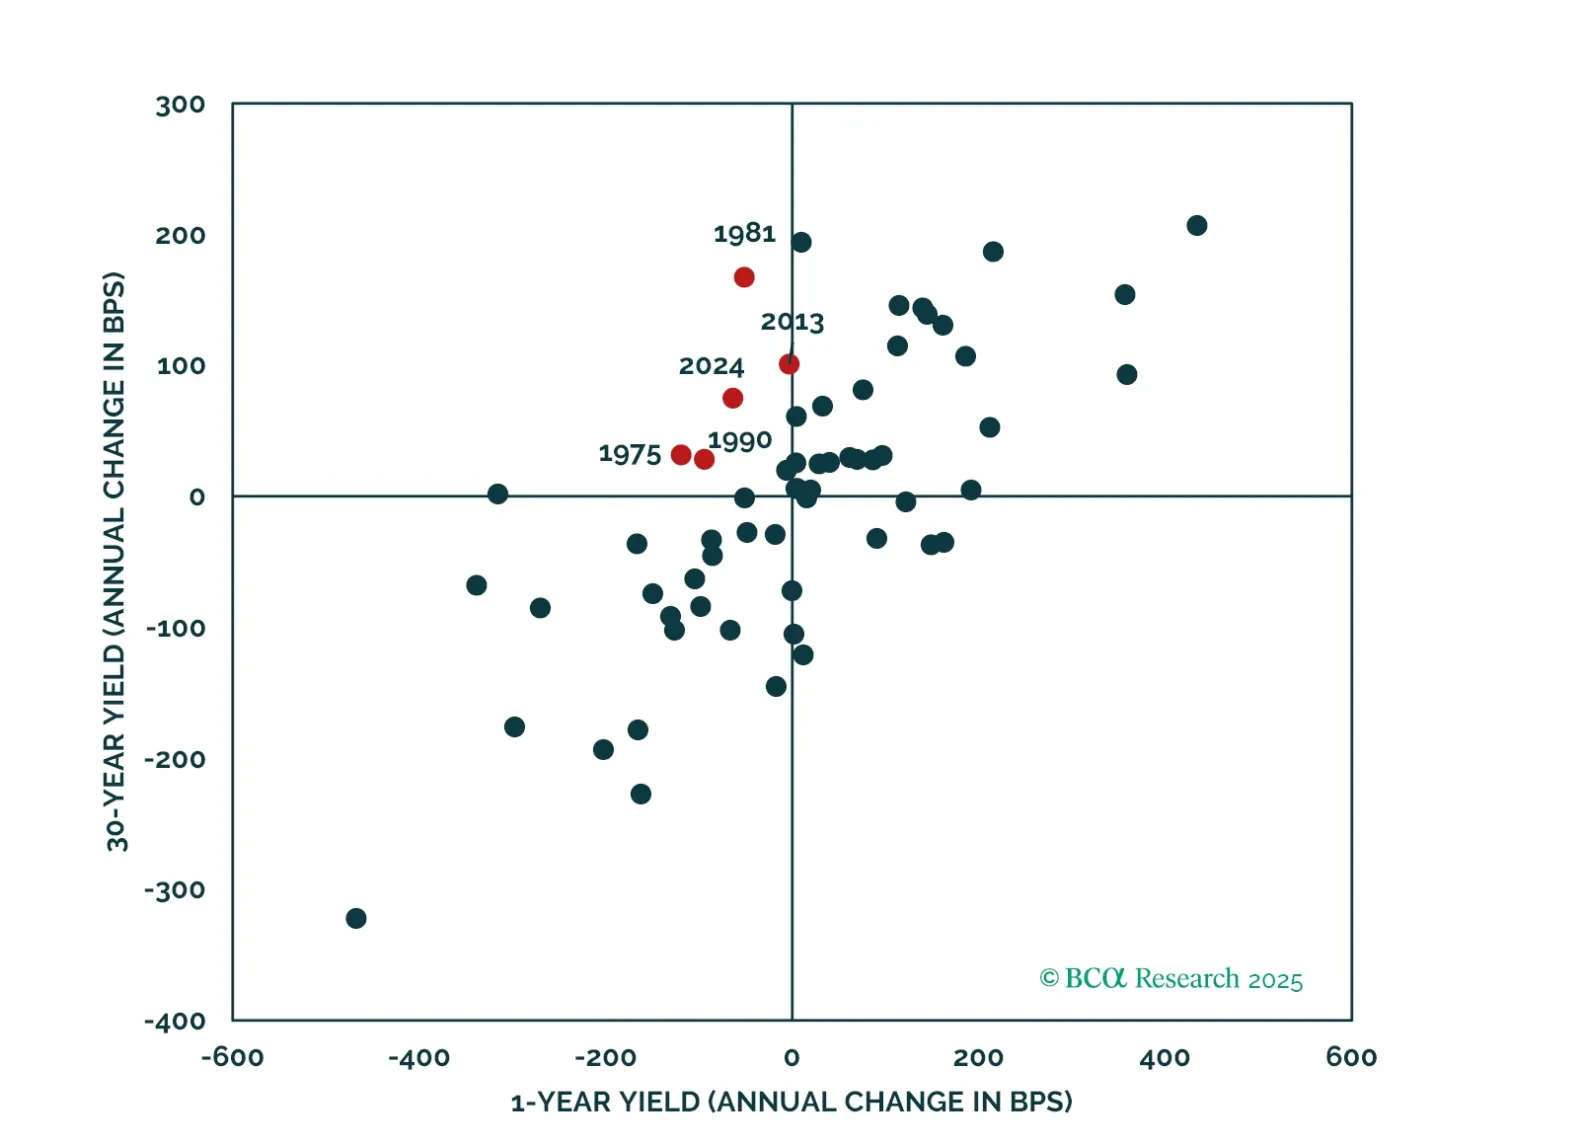
Paradoxically, raging optimism on the US economy is making a reacceleration in growth less likely in 2025. The reaction of the bond market has made the Fed rethink its cutting campaign. Markets are also constraining Trump’s agenda. US manufacturing will not recover with a surging dollar. Fears of inflation and debt sustainability have made moderate House Republicans push back against the President Elect’s wishes. Given the sky-high optimism embedded in asset prices, we believe a defensive portfolio stance is warranted on a 12-month horizon. Overweight gold to hedge the risk of a fiscal crisis.
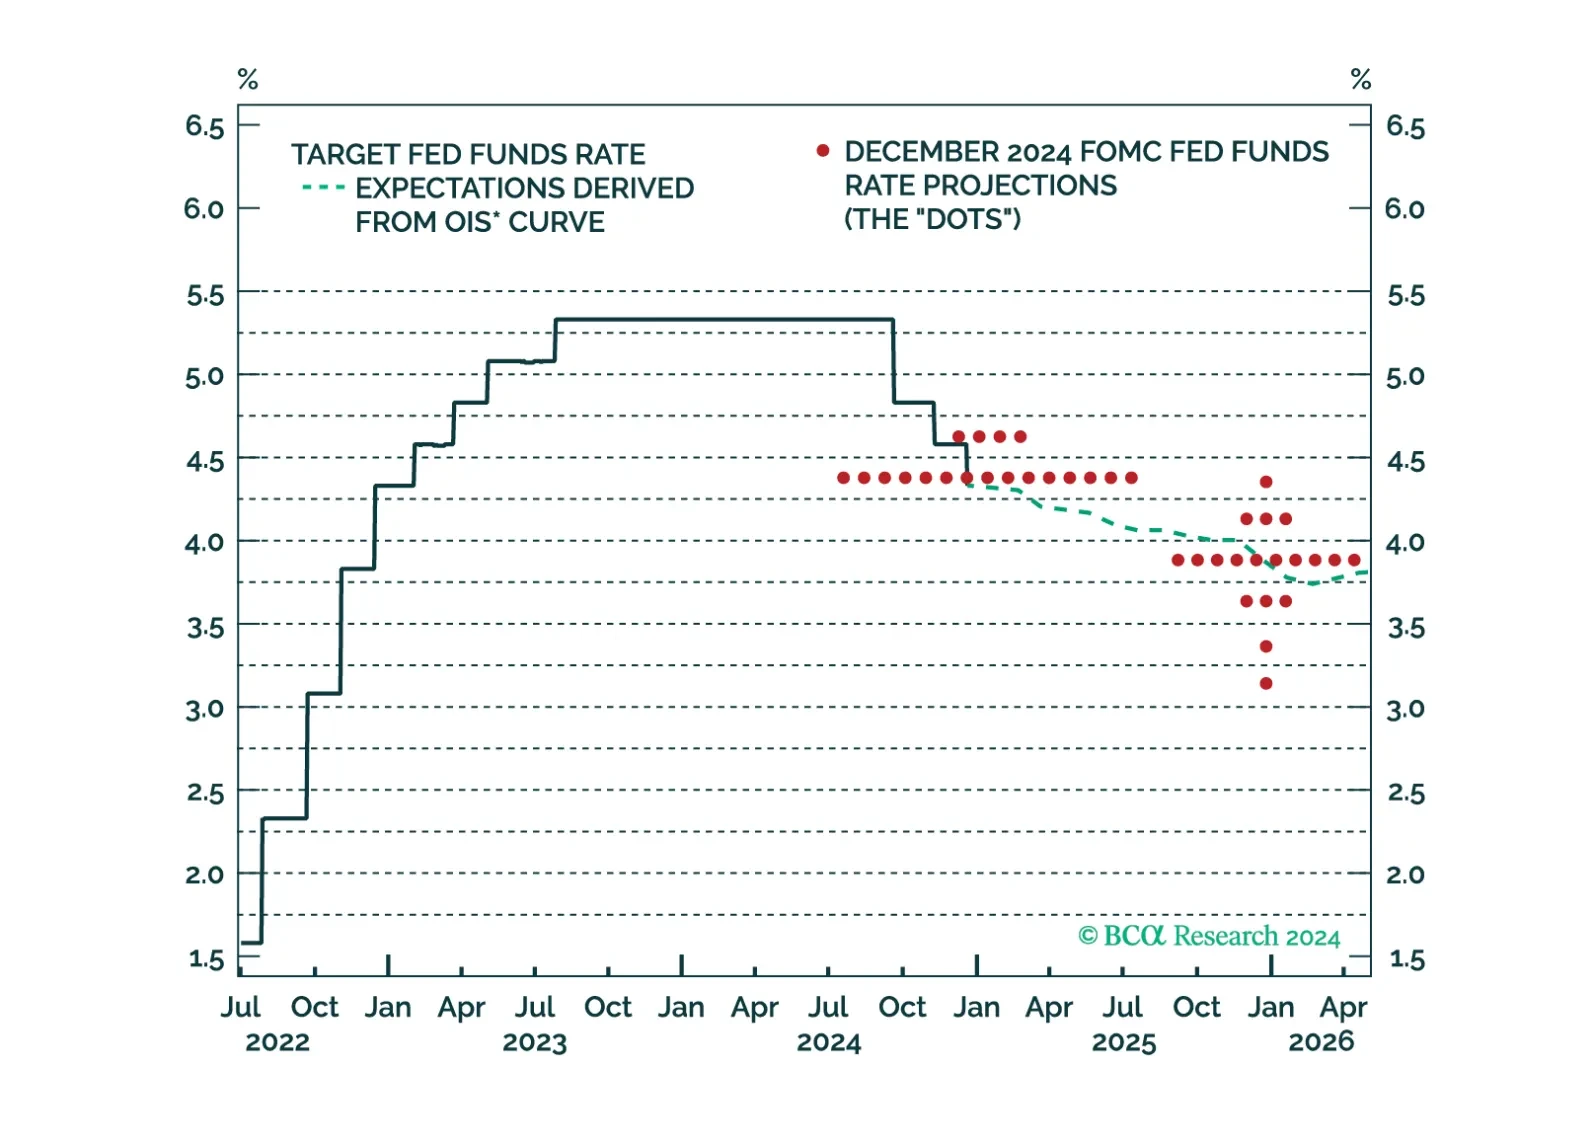
Our outlook for Fed policy in 2025 discusses our expectations for interest rates, the Fed’s balance sheet and the 2025 strategic review.
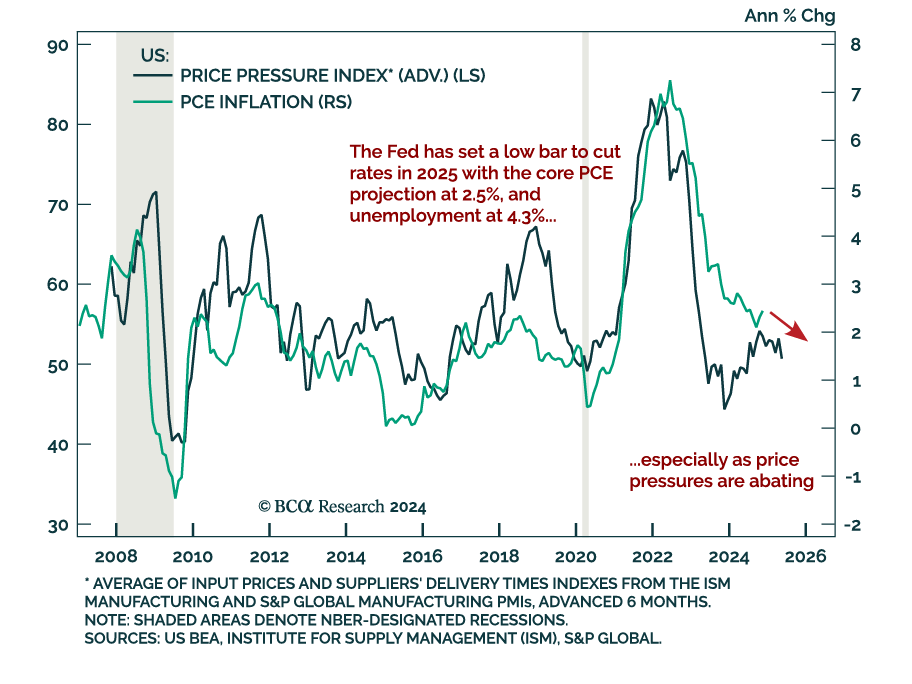
The Fed’s preferred measure of inflation, core PCE, came in below expectations at 0.1% m/m in November, remaining steady at 2.8% y/y. The monthly advance was the lowest since May. The inflation deceleration was broad-based. Core services inflation increased…