Economía
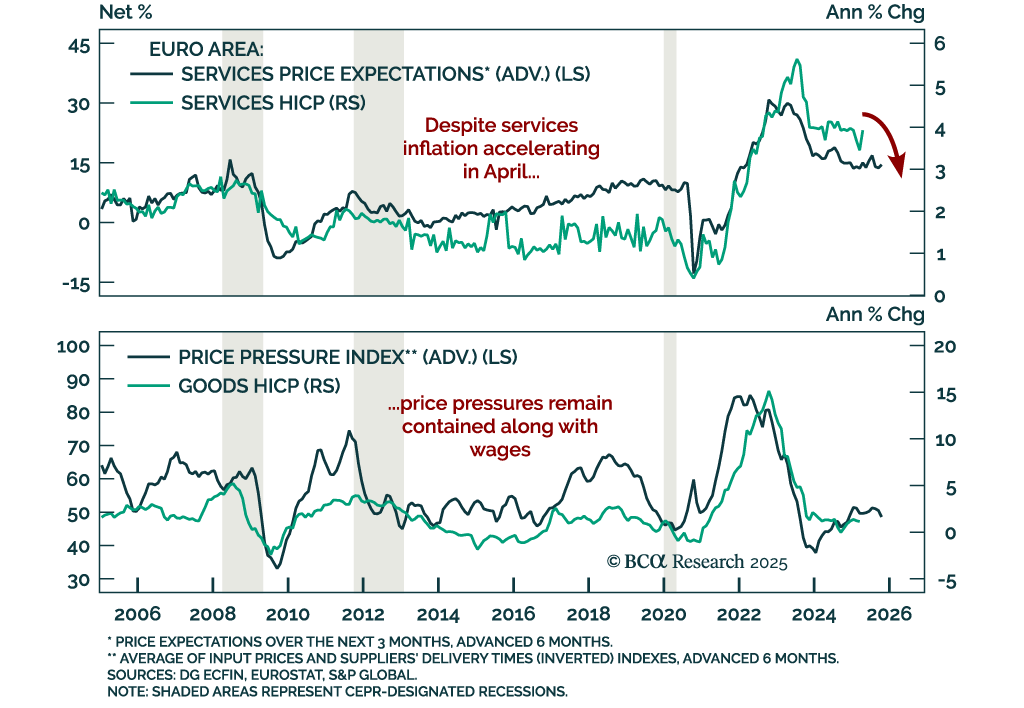
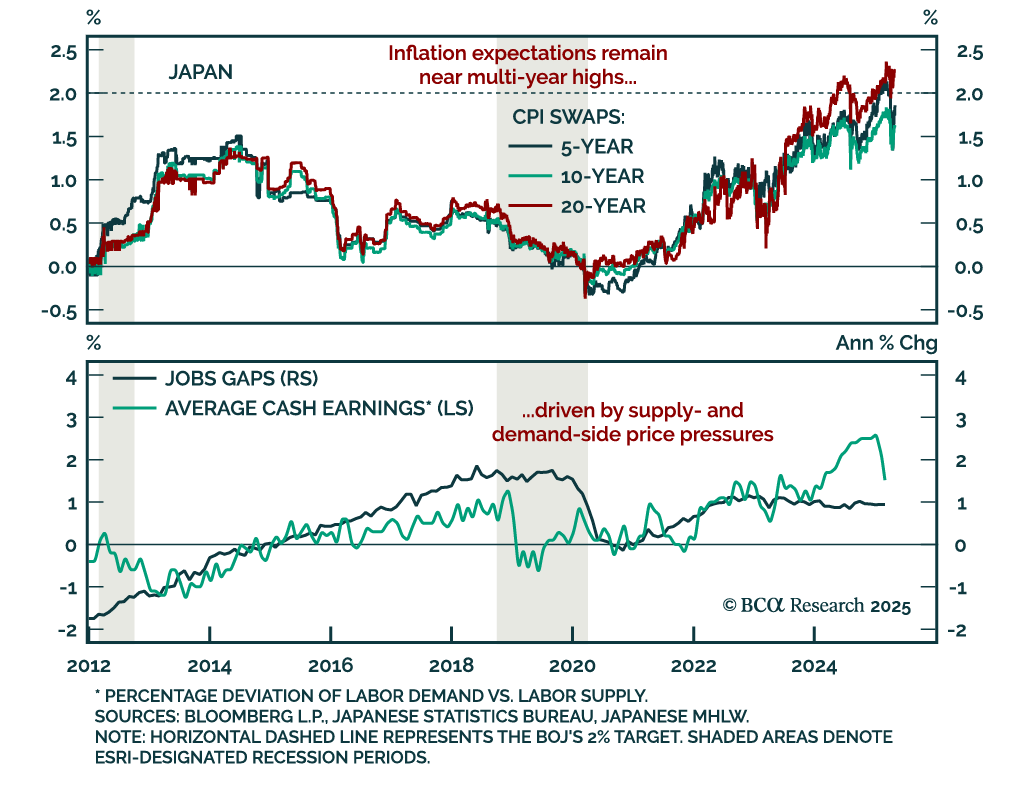
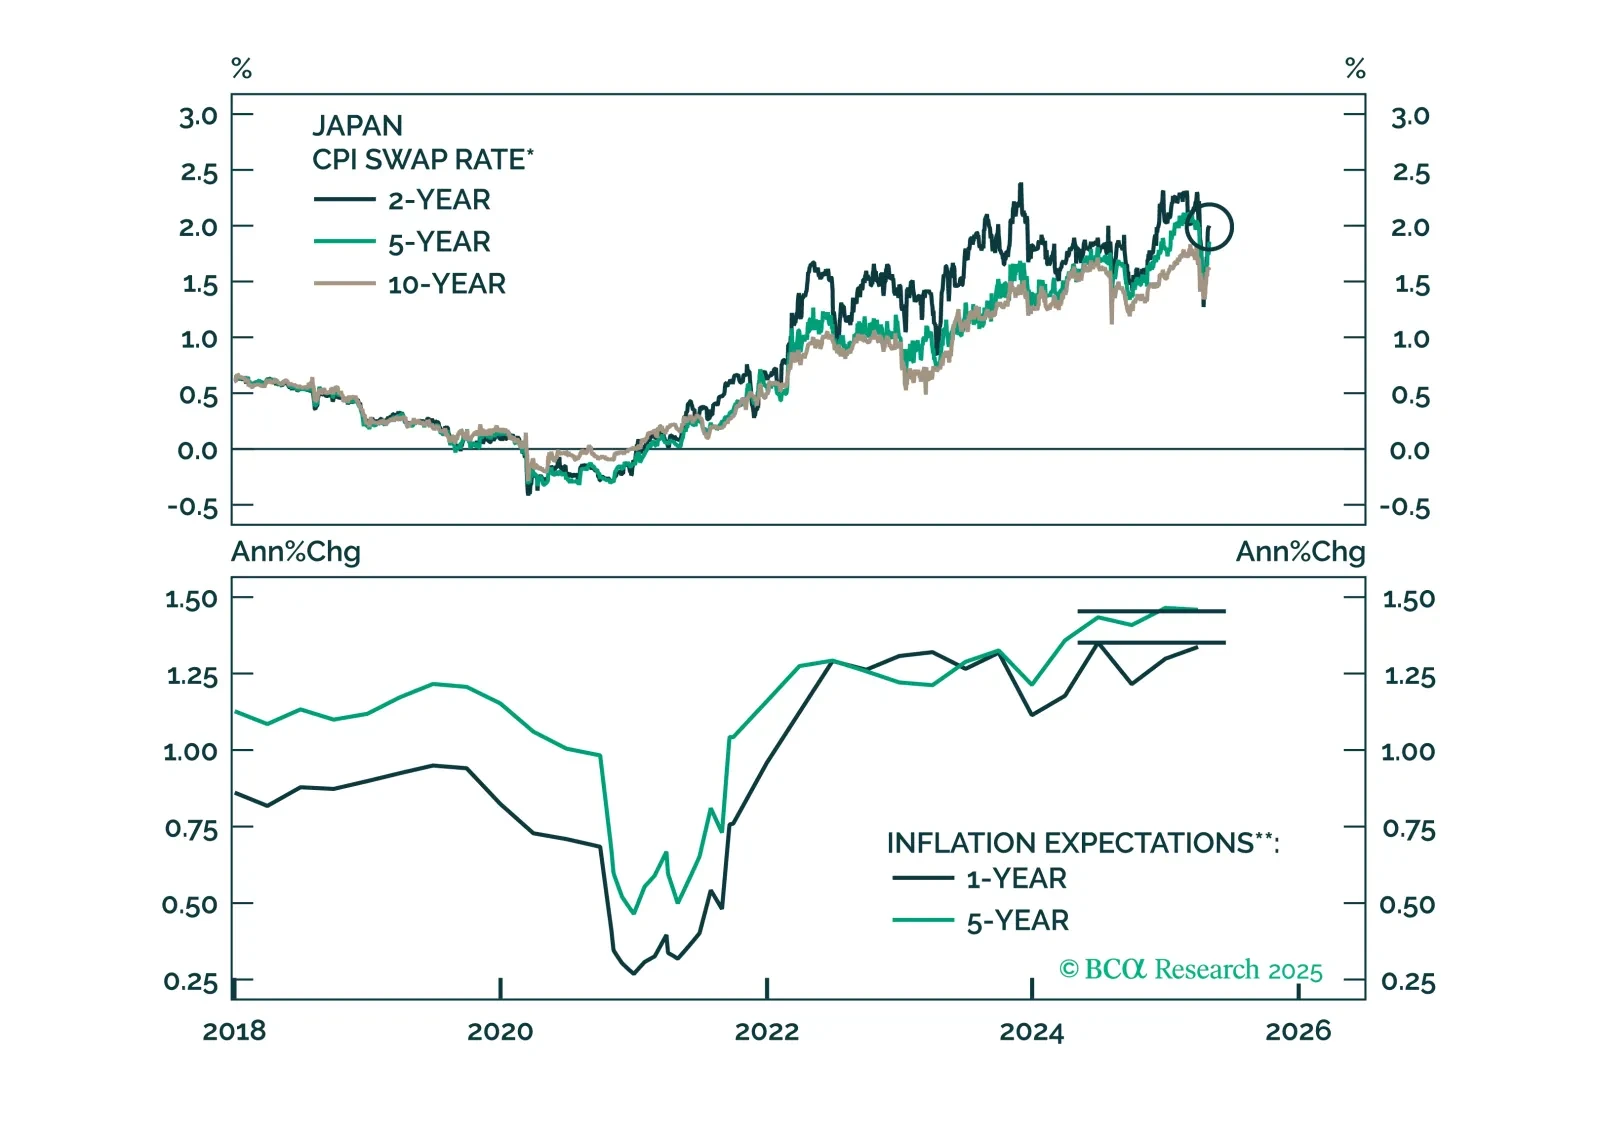
This week’s report looks at Japan, with the recent BoJ meeting. While a trade war has injected uncertainty into the Japanese economy, our conviction remains high that JGBs will underperform other government bond markets, and the yen will ultimately rally. That said, JPY is due for a tactical pullback.
This year’s corporate bond sell off has hit high-yield more than investment grade, and high-yield spreads have turned relatively more attractive as a result.
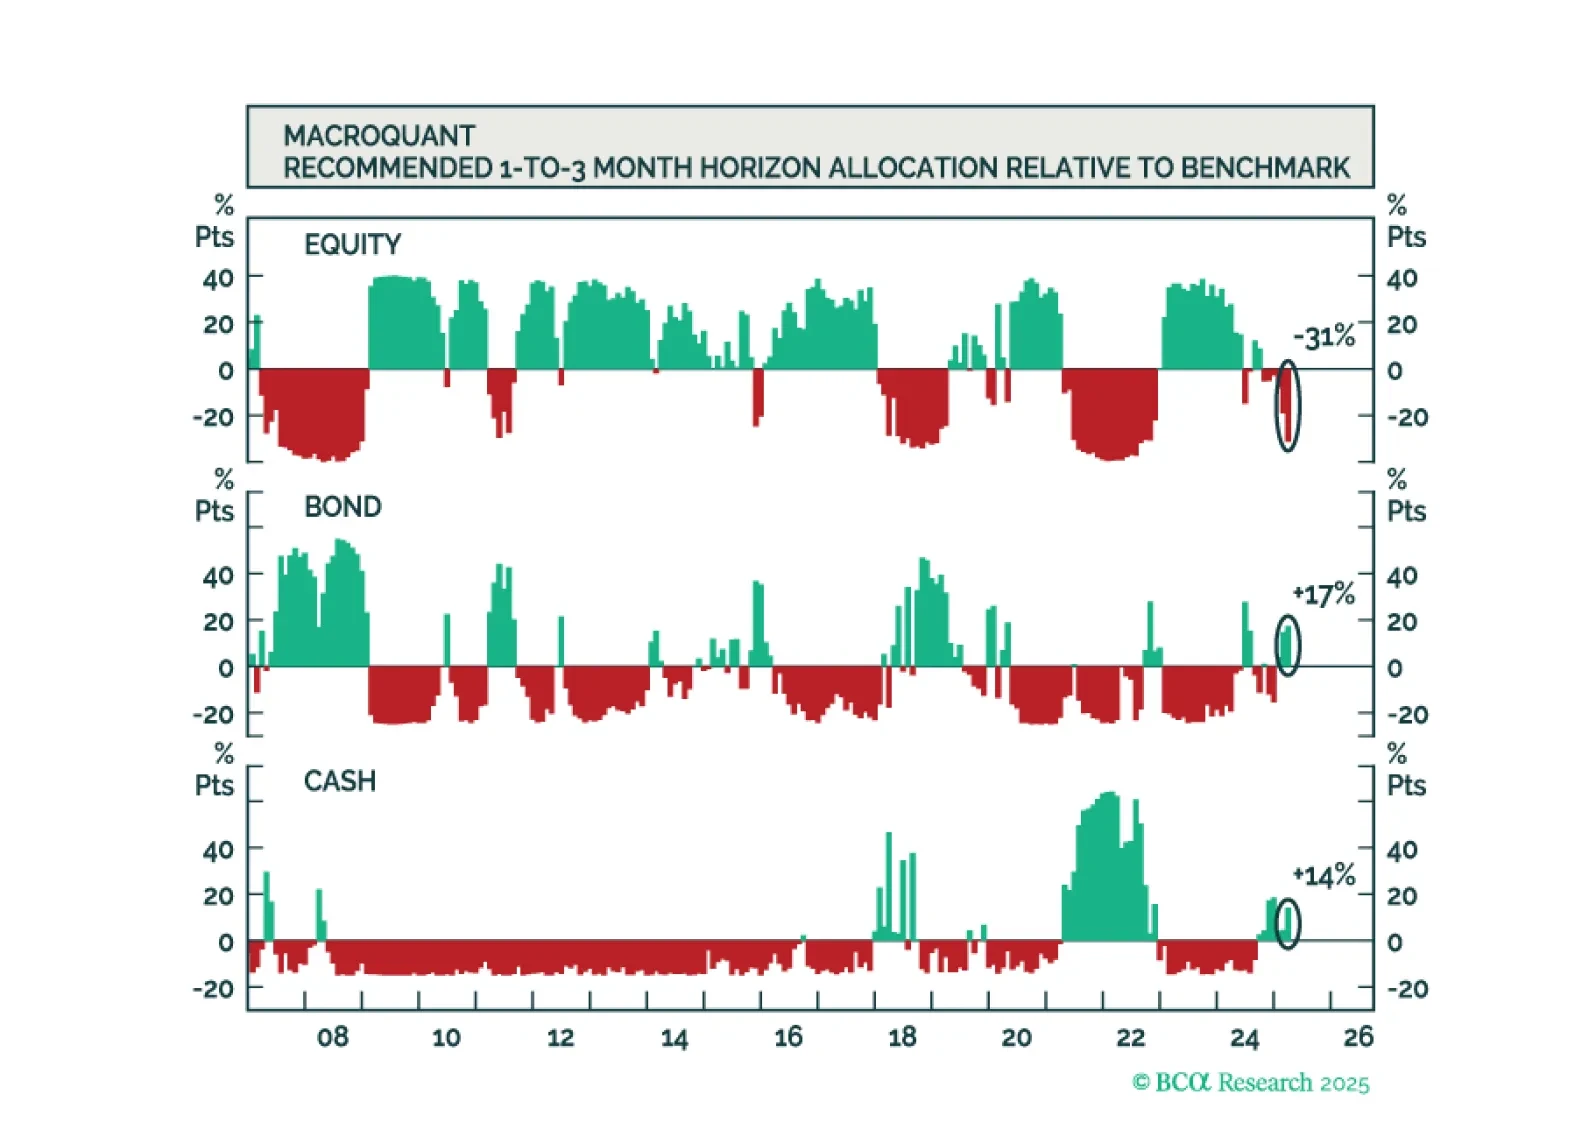
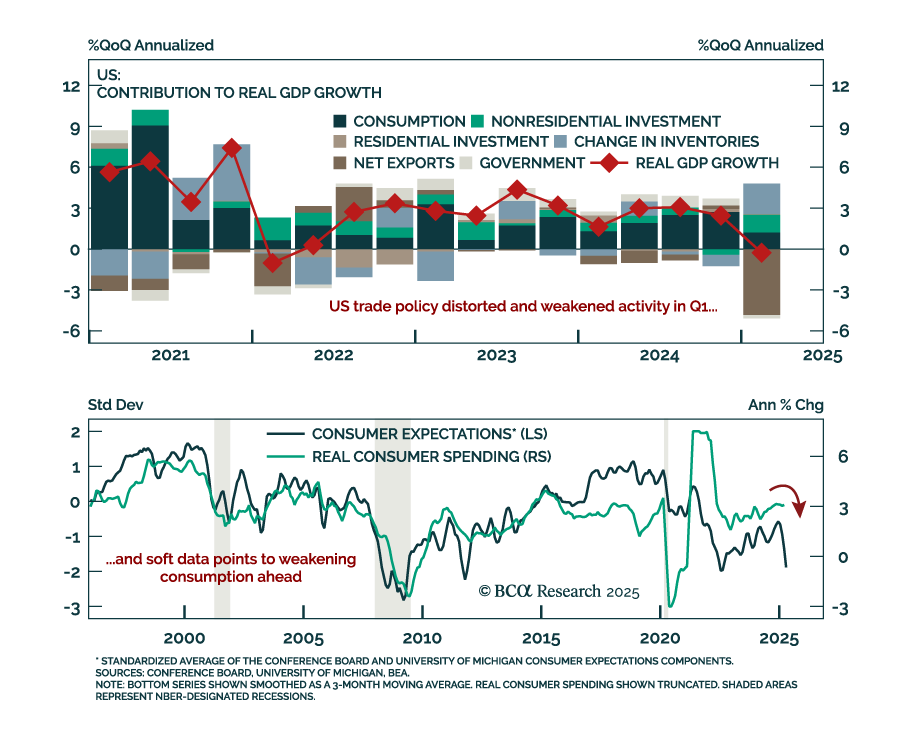
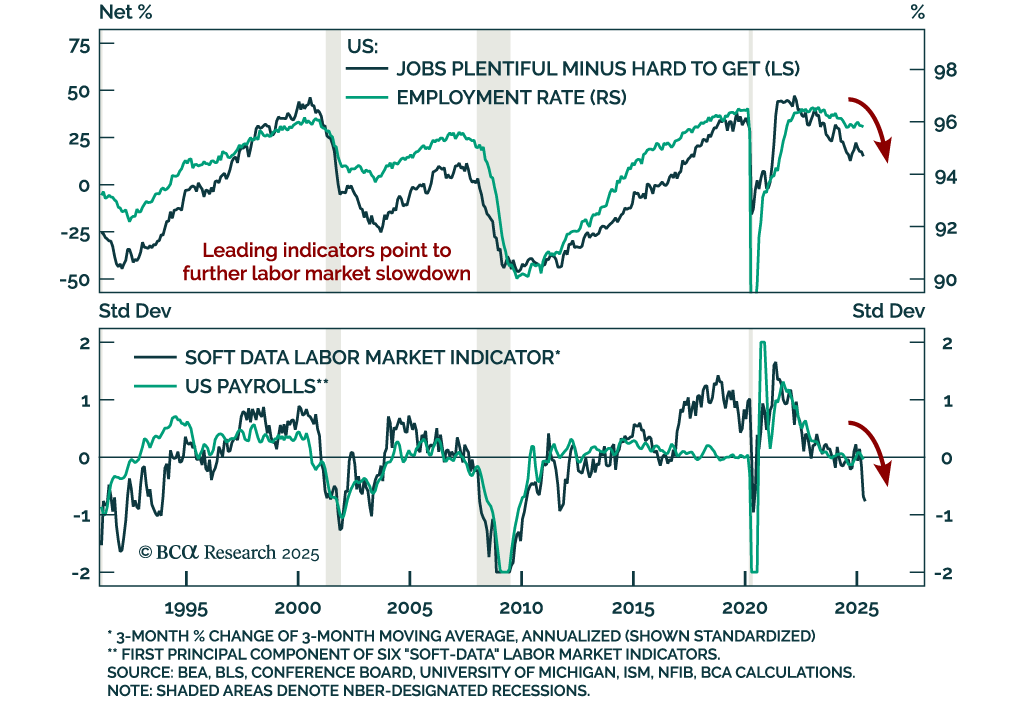
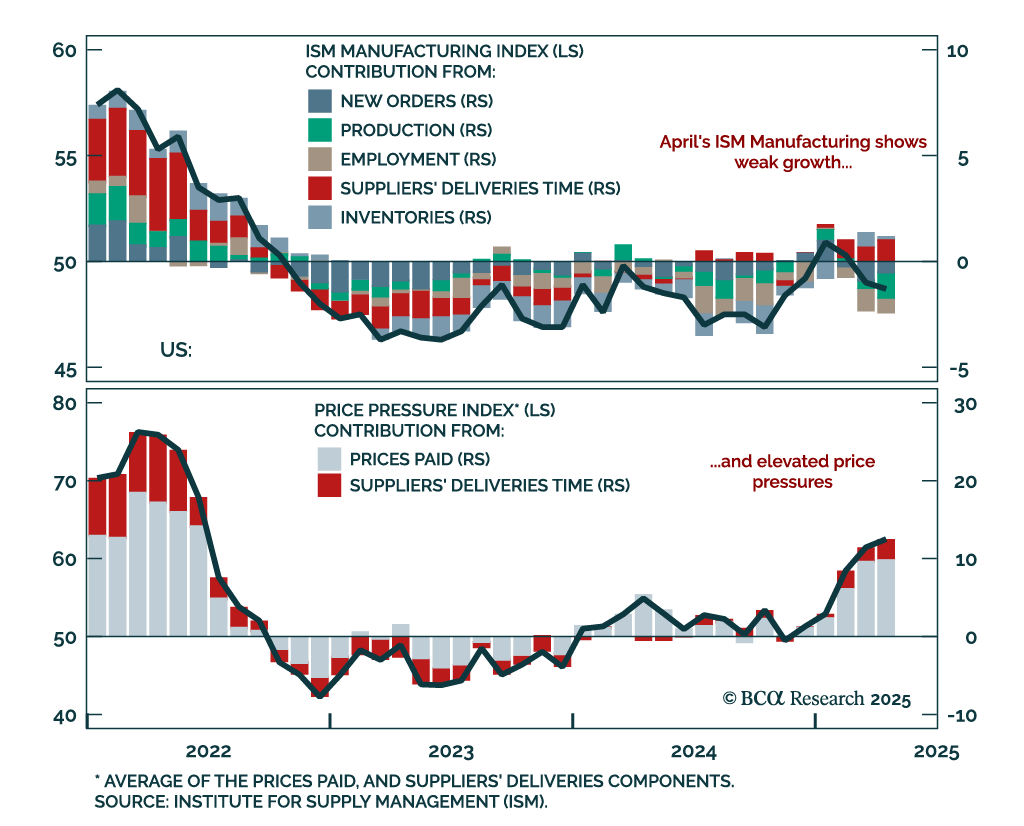
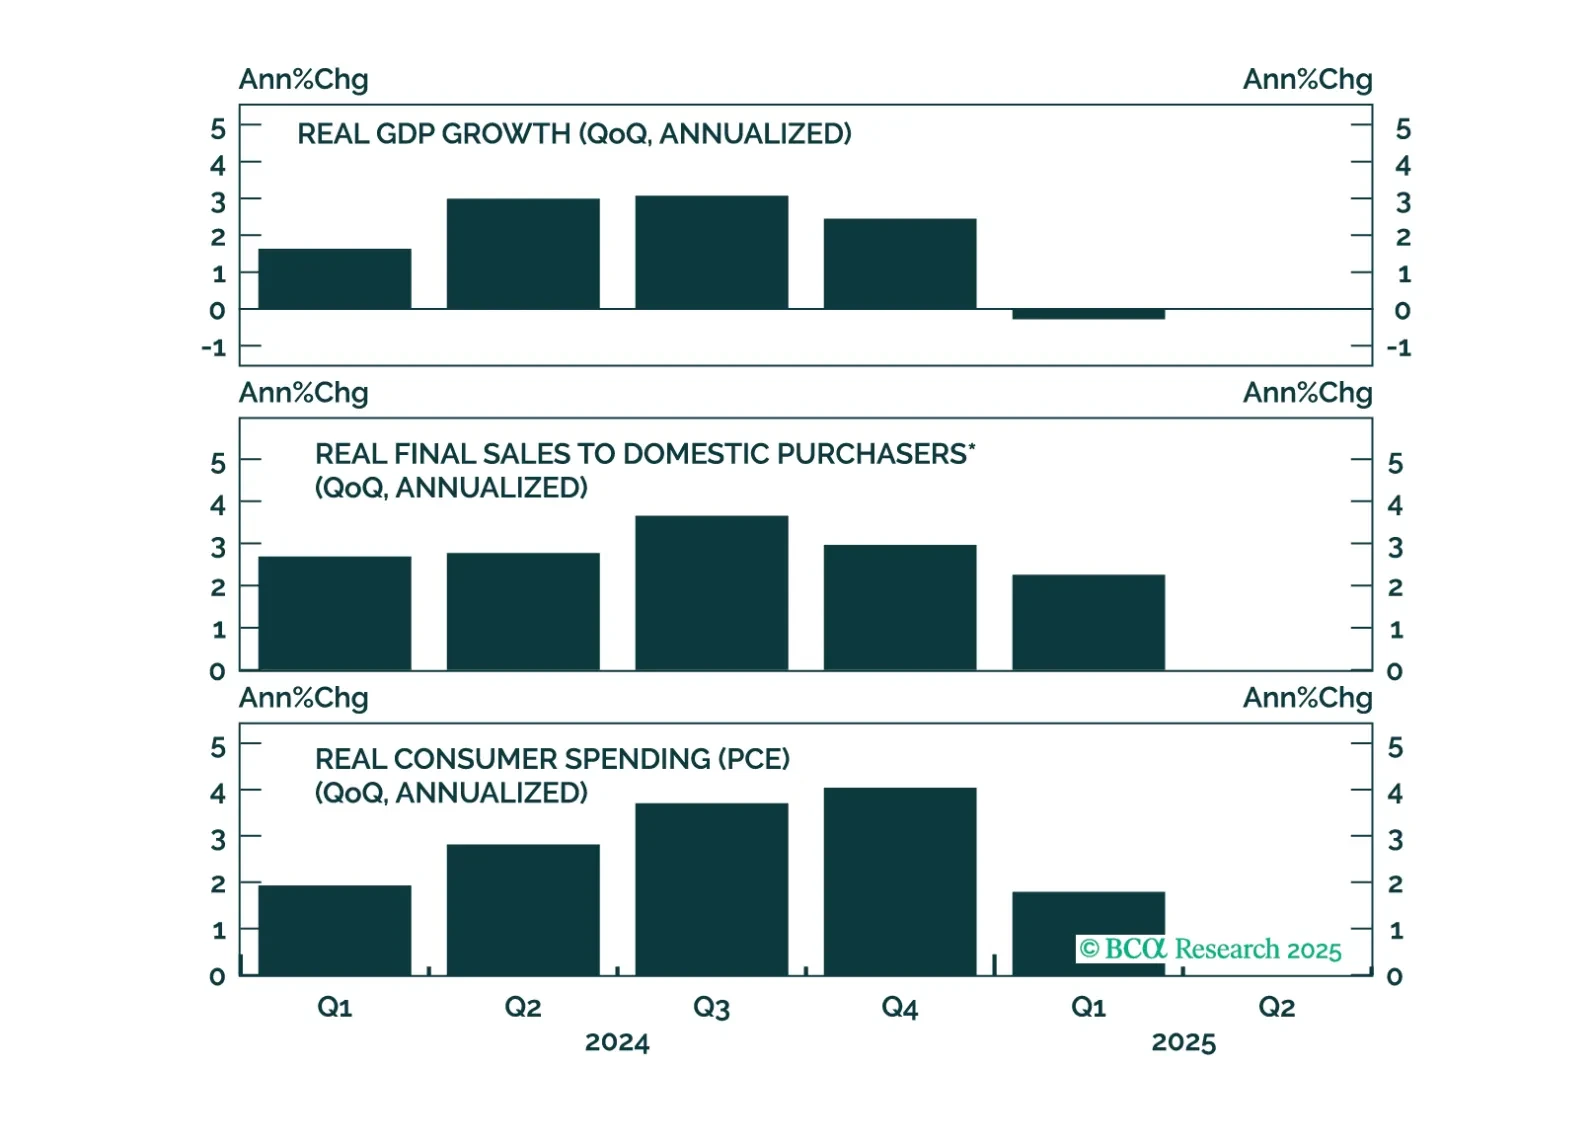
MacroQuant sees the risks to US growth as being to the downside and the risks to inflation as being to the upside. Such a stagflationary brew justifies an underweight on stocks.
MacroQuant considera que los riesgos para el crecimiento de EE. UU. se orientan a la baja y que los riesgos para la inflación se orientan al alza. Una mezcla estanflacionaria de este tipo justifica una infraponderación en acciones.