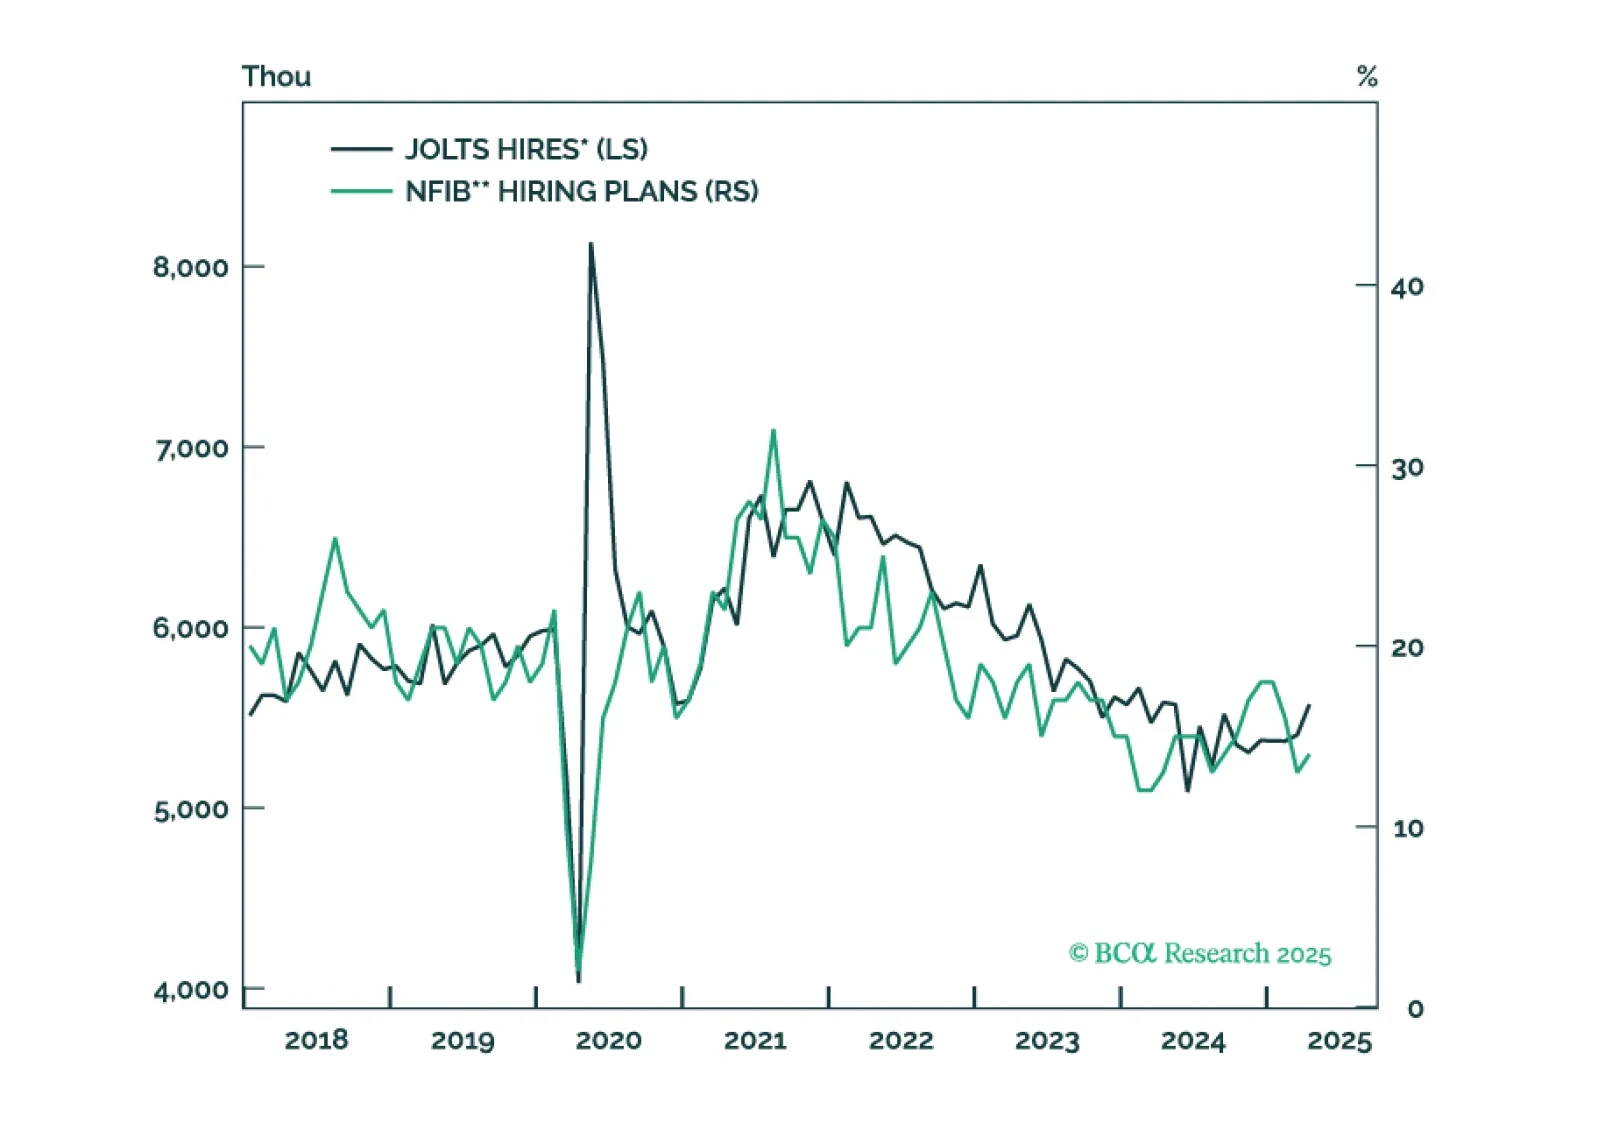
Comercio
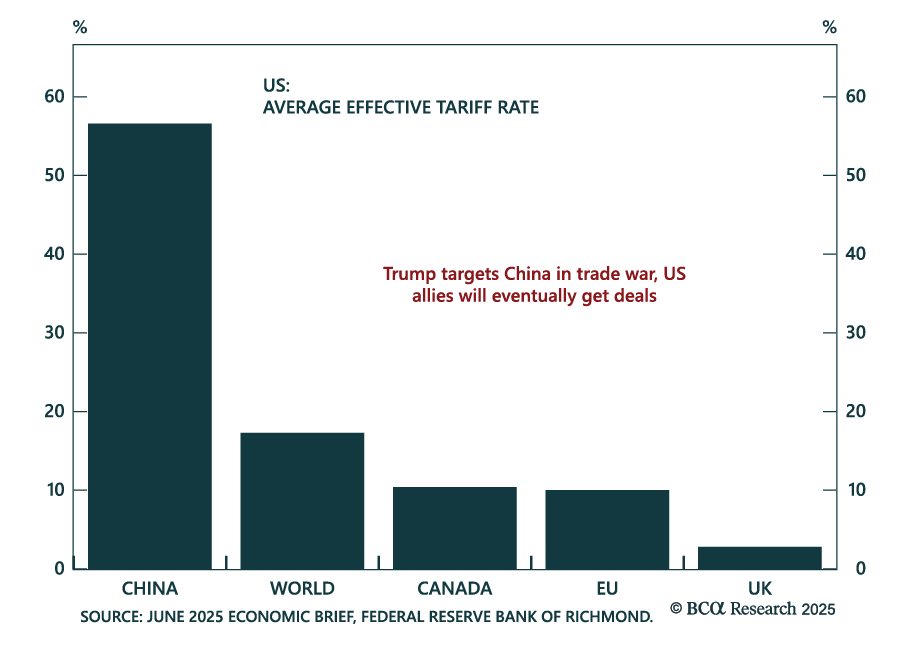
Los riesgos geopolíticos agudos, como un impacto masivo en el petróleo, pueden estar disminuyendo. Pero el riesgo geopolítico estructural sigue siendo alto y podría alterar un mercado despreocupado. Los riesgos económicos cíclicos están subestimados mientras EE. UU. se desacelera y China continúa tambaleándose. Los inversores deberían asegurar algunas ganancias en previsión de la implementación de aranceles y un descenso en los datos económicos sólidos.
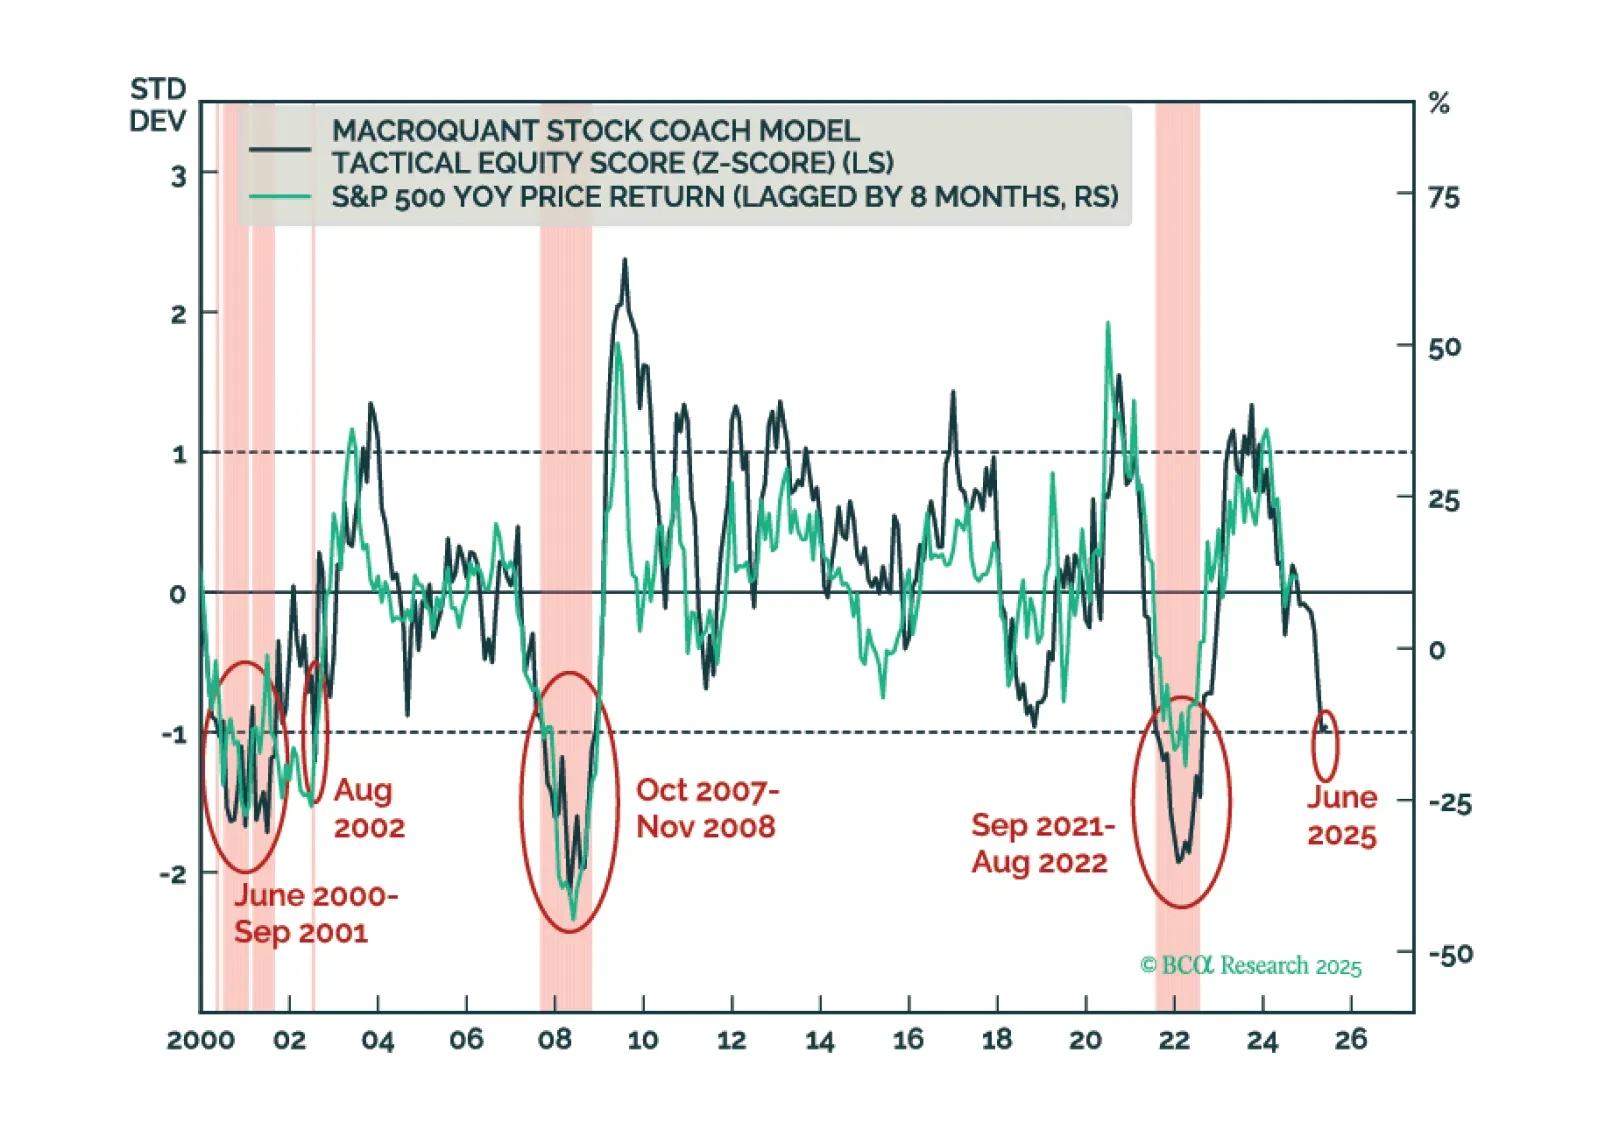
Los inversores deberían reducir modestamente la ponderación de las acciones en sus carteras y buscar adoptar una posición más agresivamente defensiva una vez que los signos claros de la recesión sean visibles. Creemos que eso sucederá en los próximos meses.
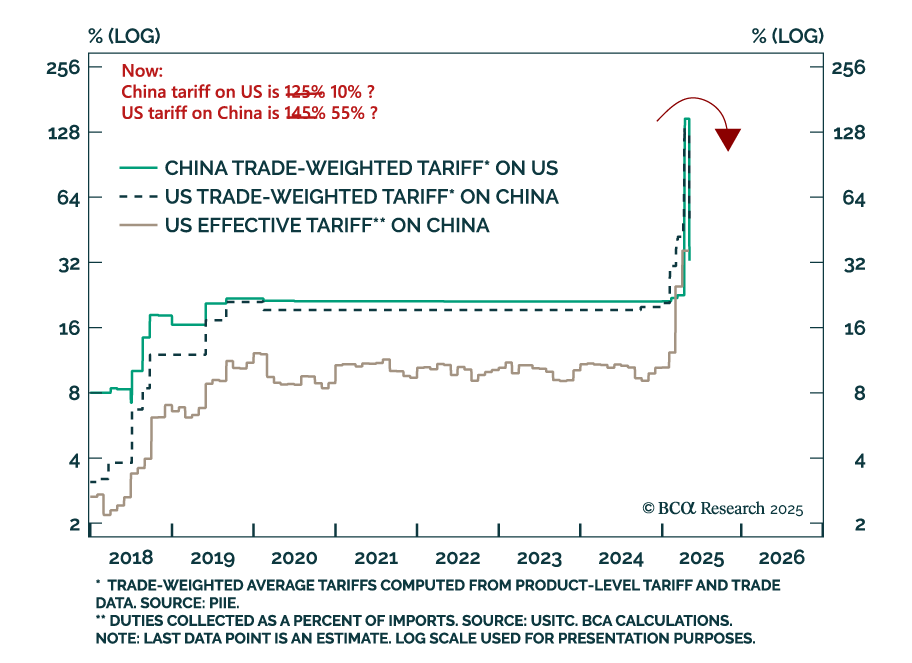
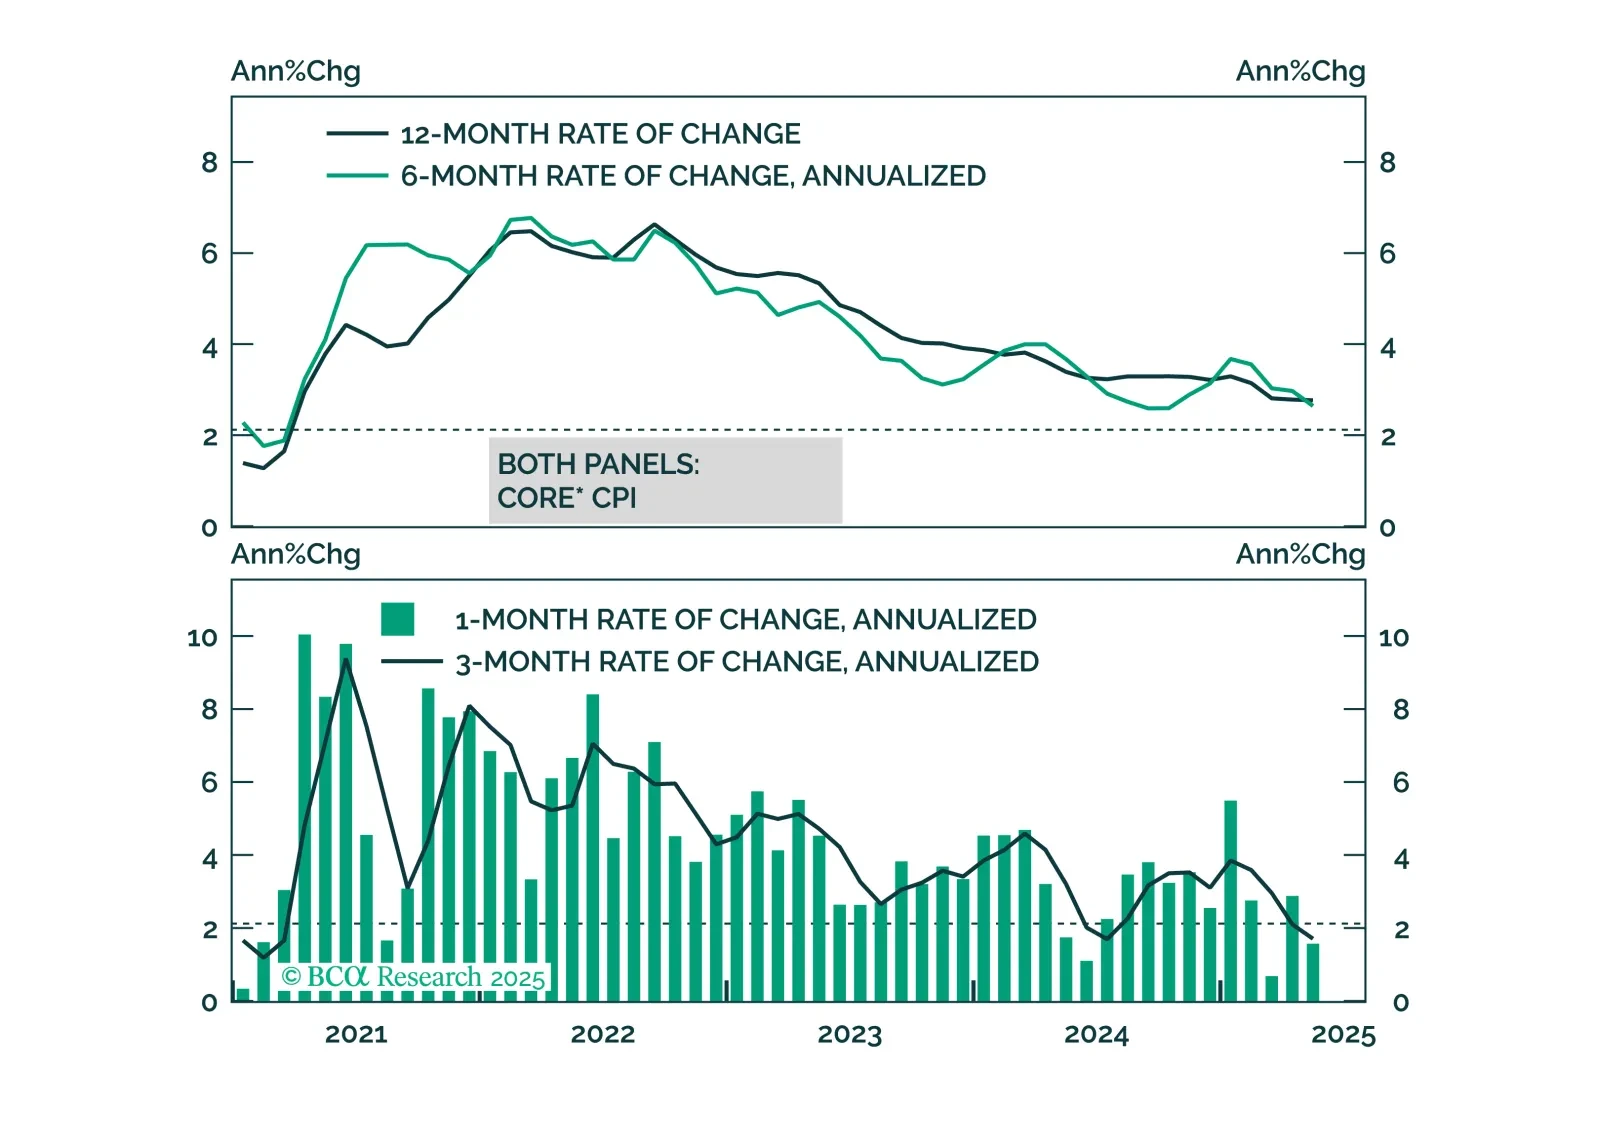
While we anticipate higher inflation in June, it looks increasingly likely that the price impact from tariffs will be less aggressive and long-lasting than many feared.
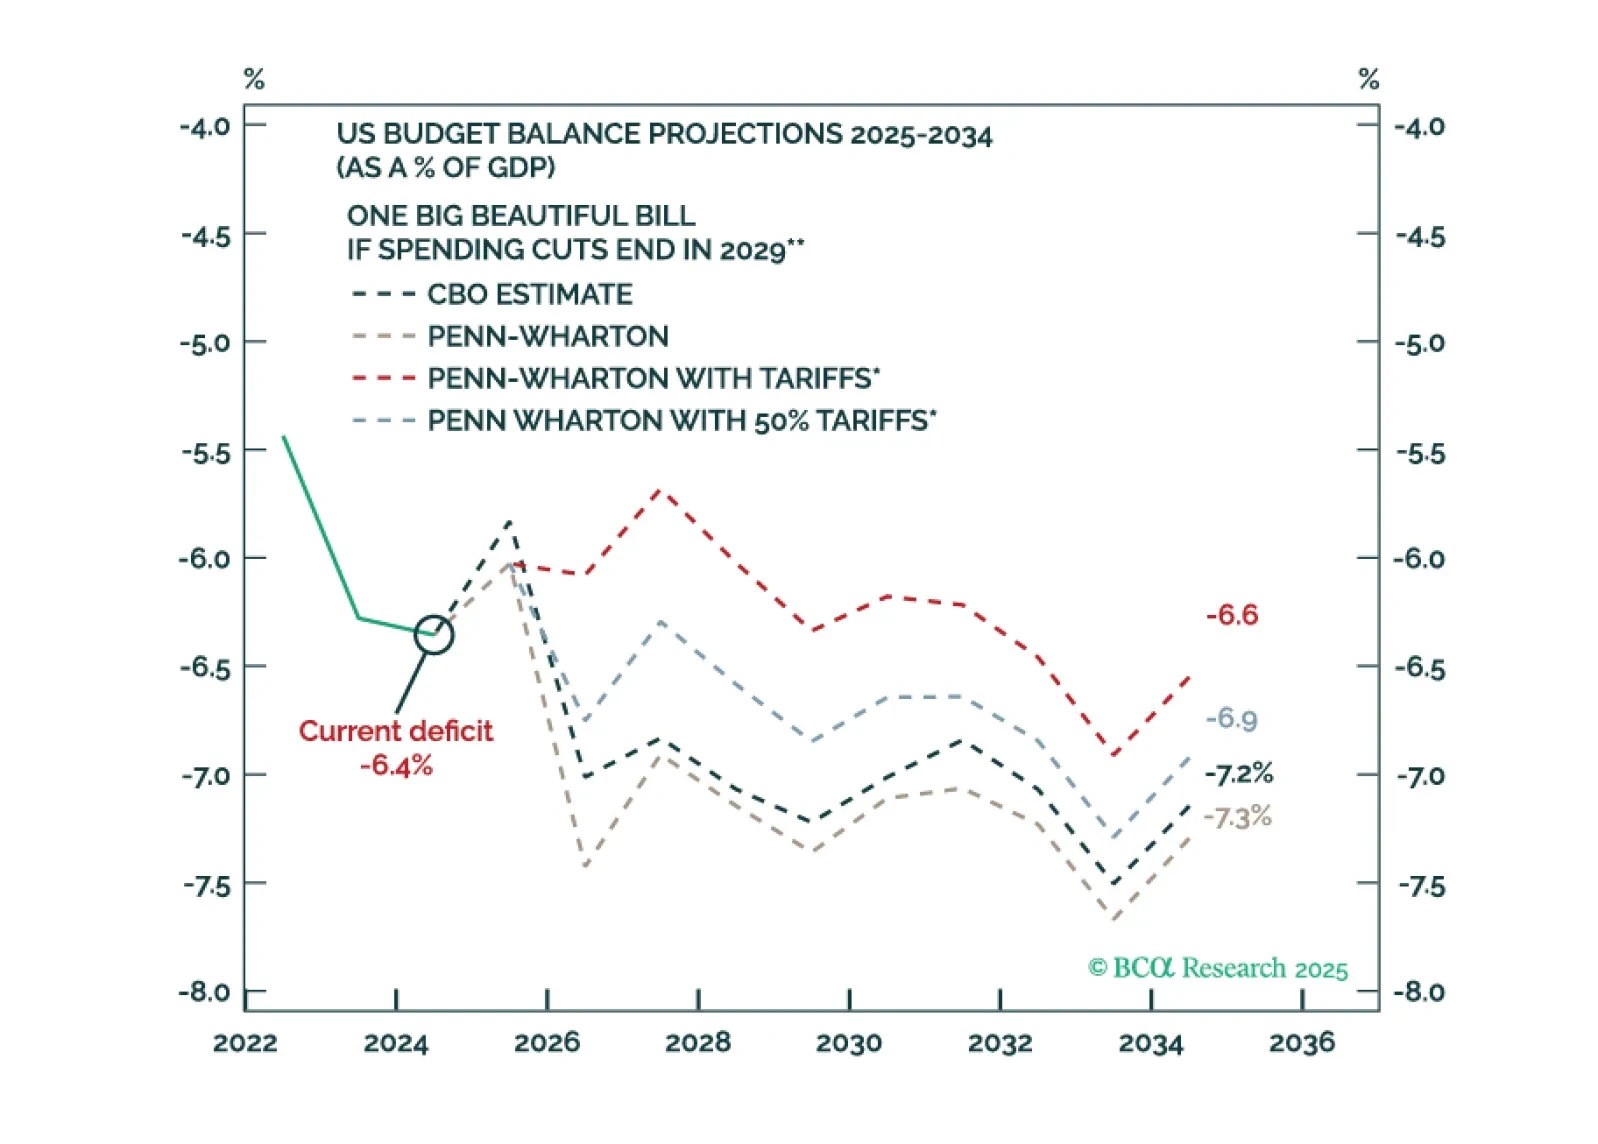
Bond market volatility will spike again in the near term. The Fed is committed to an easing cycle yet the Trump administration’s signature fiscal policy action will stimulate the economy. Tariffs are supposed to keep the budget deficit contained but they are inflationary.

The US economy has held up better so far this year than we had expected. For the time being, investors should remain modestly underweight equities. A more aggressive underweight would be justified only once the “whites of the recession’s eyes” are visible.
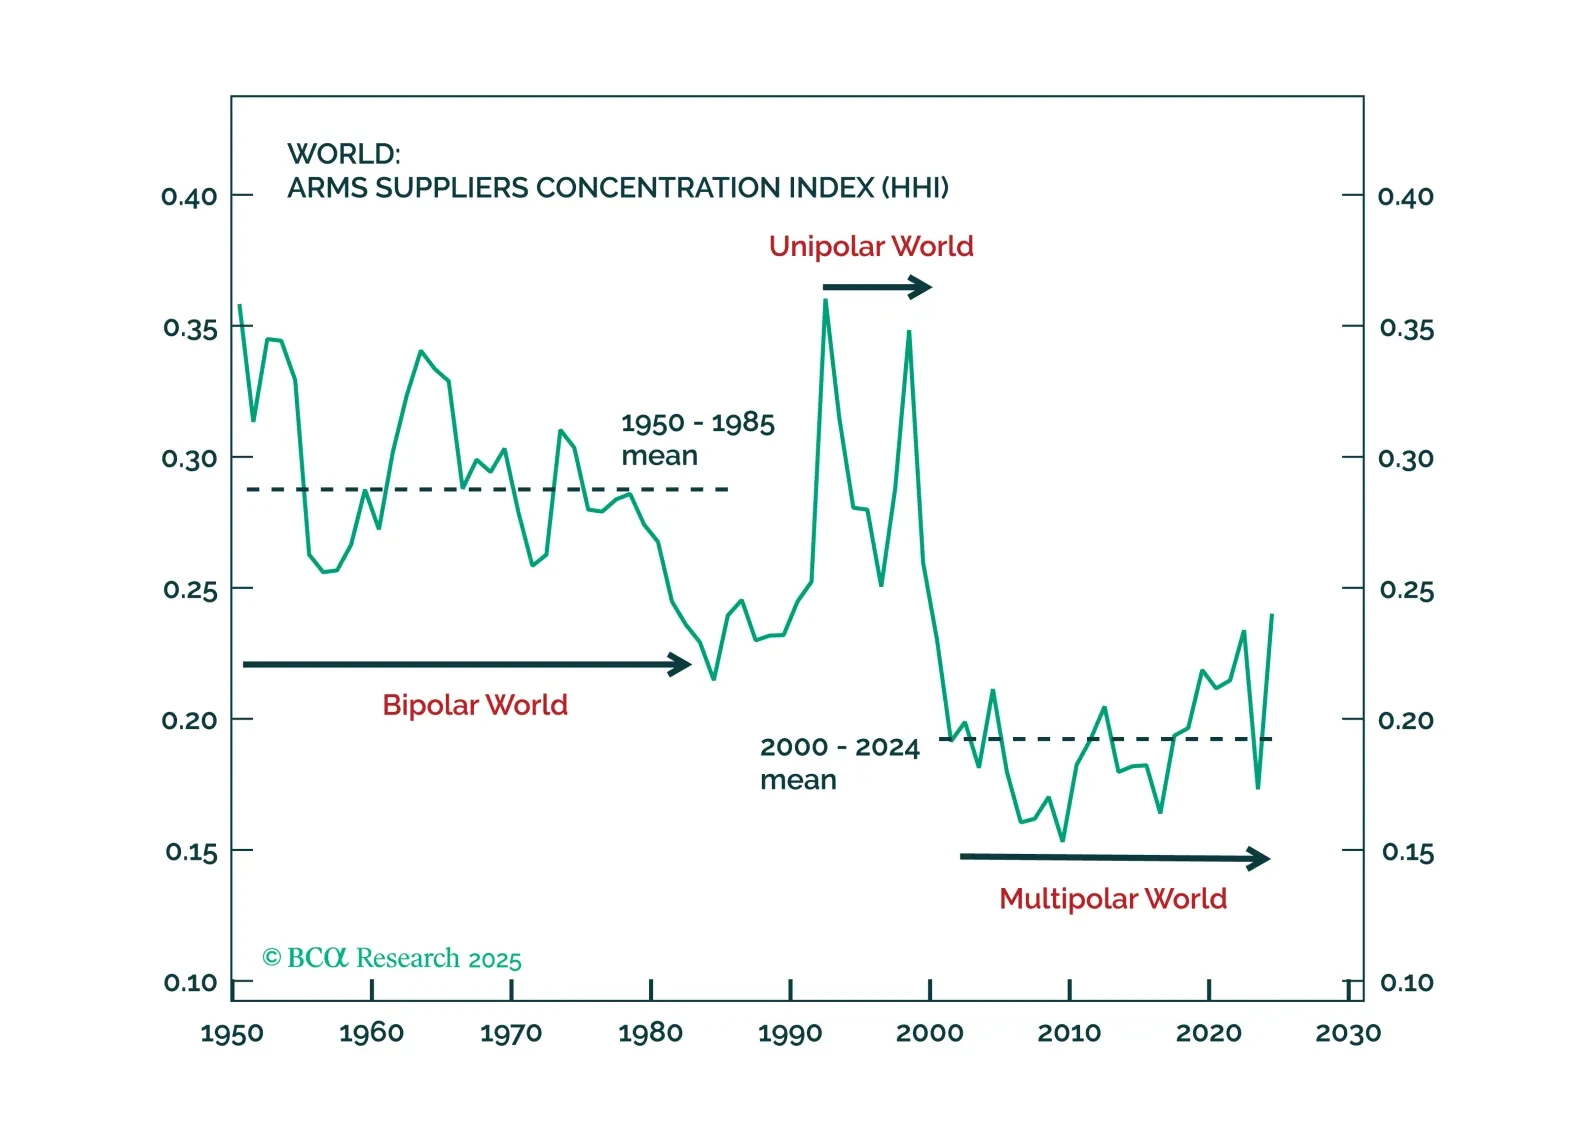
In our Beta report, we focus on our decade view. Many of our global allocator clients are scrambling to incorporate geopolitics into their strategic asset allocation. For most, this means thinking about war… or about future end-states. This is a mistake. We consider the next five years (maybe a decade) as the transition to the new era, a transition away from American unipolarity. And the transition itself is investment relevant. A transition to a multipolar world – which we think is occurring – will crush the USD and favor non-US assets. A transition to a bipolar world – not our base case, but still possible – would do the opposite.