Bear/Bull Market
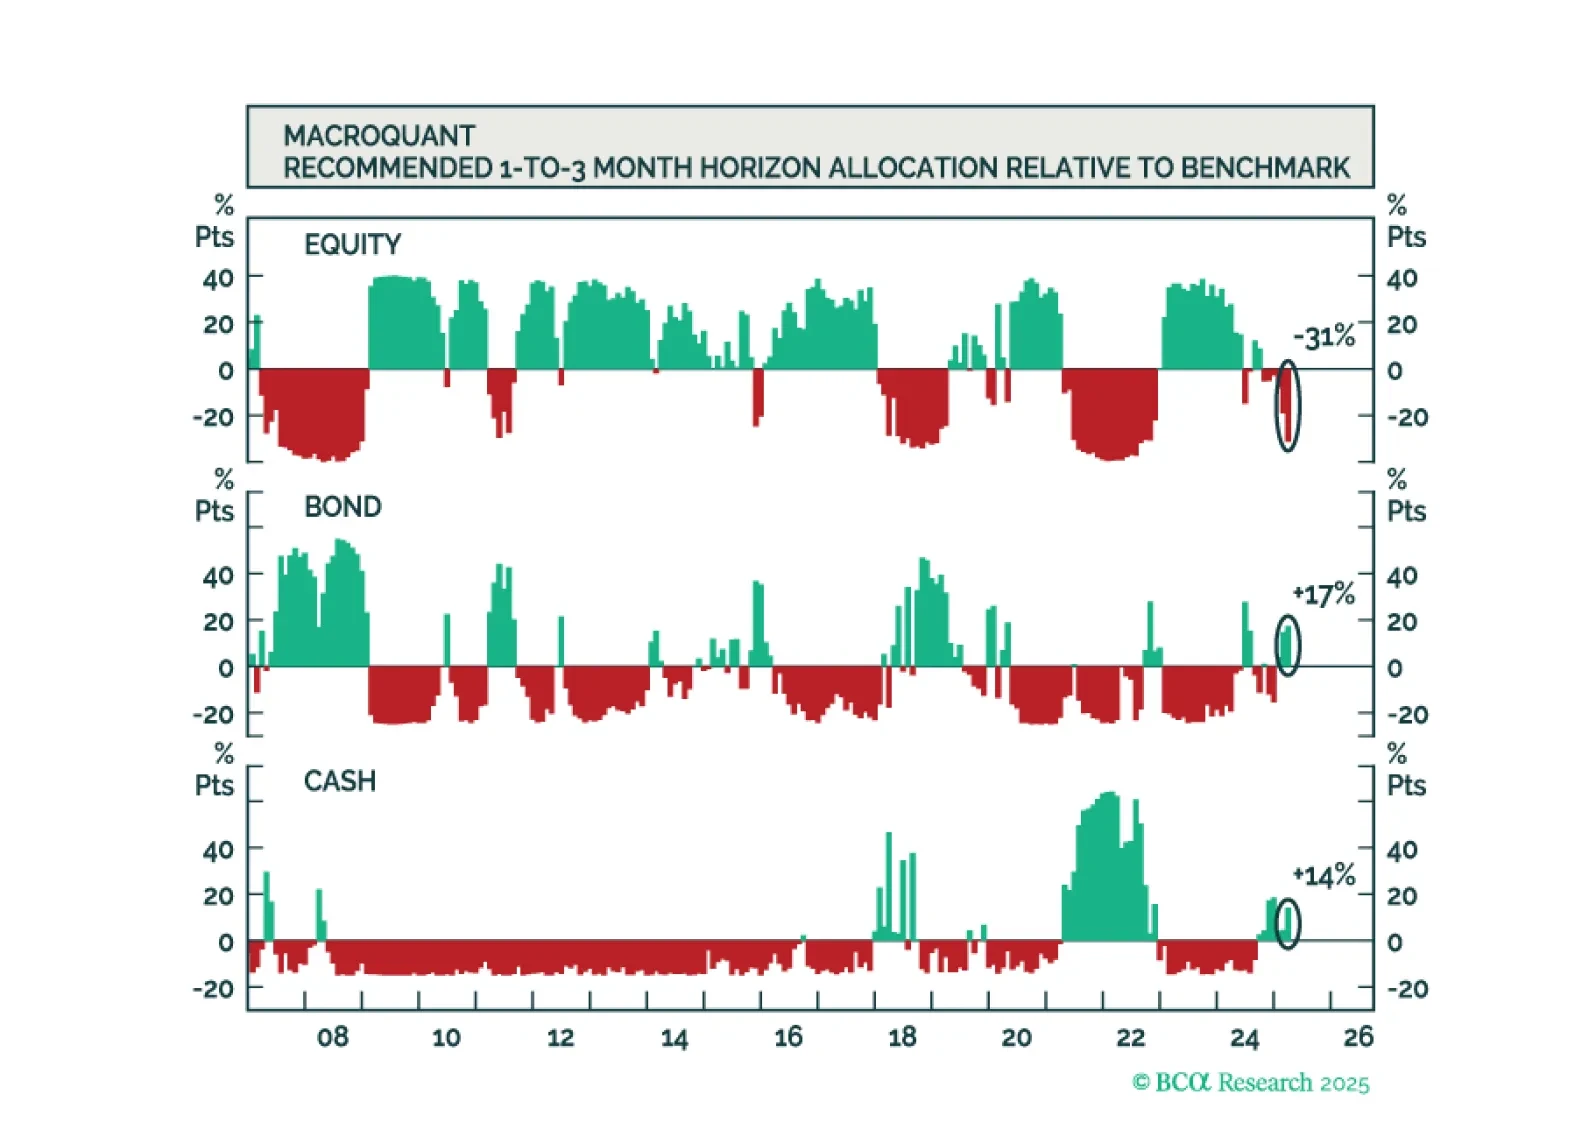
MacroQuant sees the risks to US growth as being to the downside and the risks to inflation as being to the upside. Such a stagflationary brew justifies an underweight on stocks.
MacroQuant considera que los riesgos para el crecimiento de EE. UU. se orientan a la baja y que los riesgos para la inflación se orientan al alza. Una mezcla estanflacionaria de este tipo justifica una infraponderación en acciones.

Amid the storm of global financial uncertainty, Argentina stands out as a free-market safe haven. The lifting of currency controls was the last step taken by this country to embrace market mechanisms. We recommend that investors buy Argentine equities, sovereign credit, and domestic bonds, and overweight Argentina within EM equity and fixed-income portfolios.
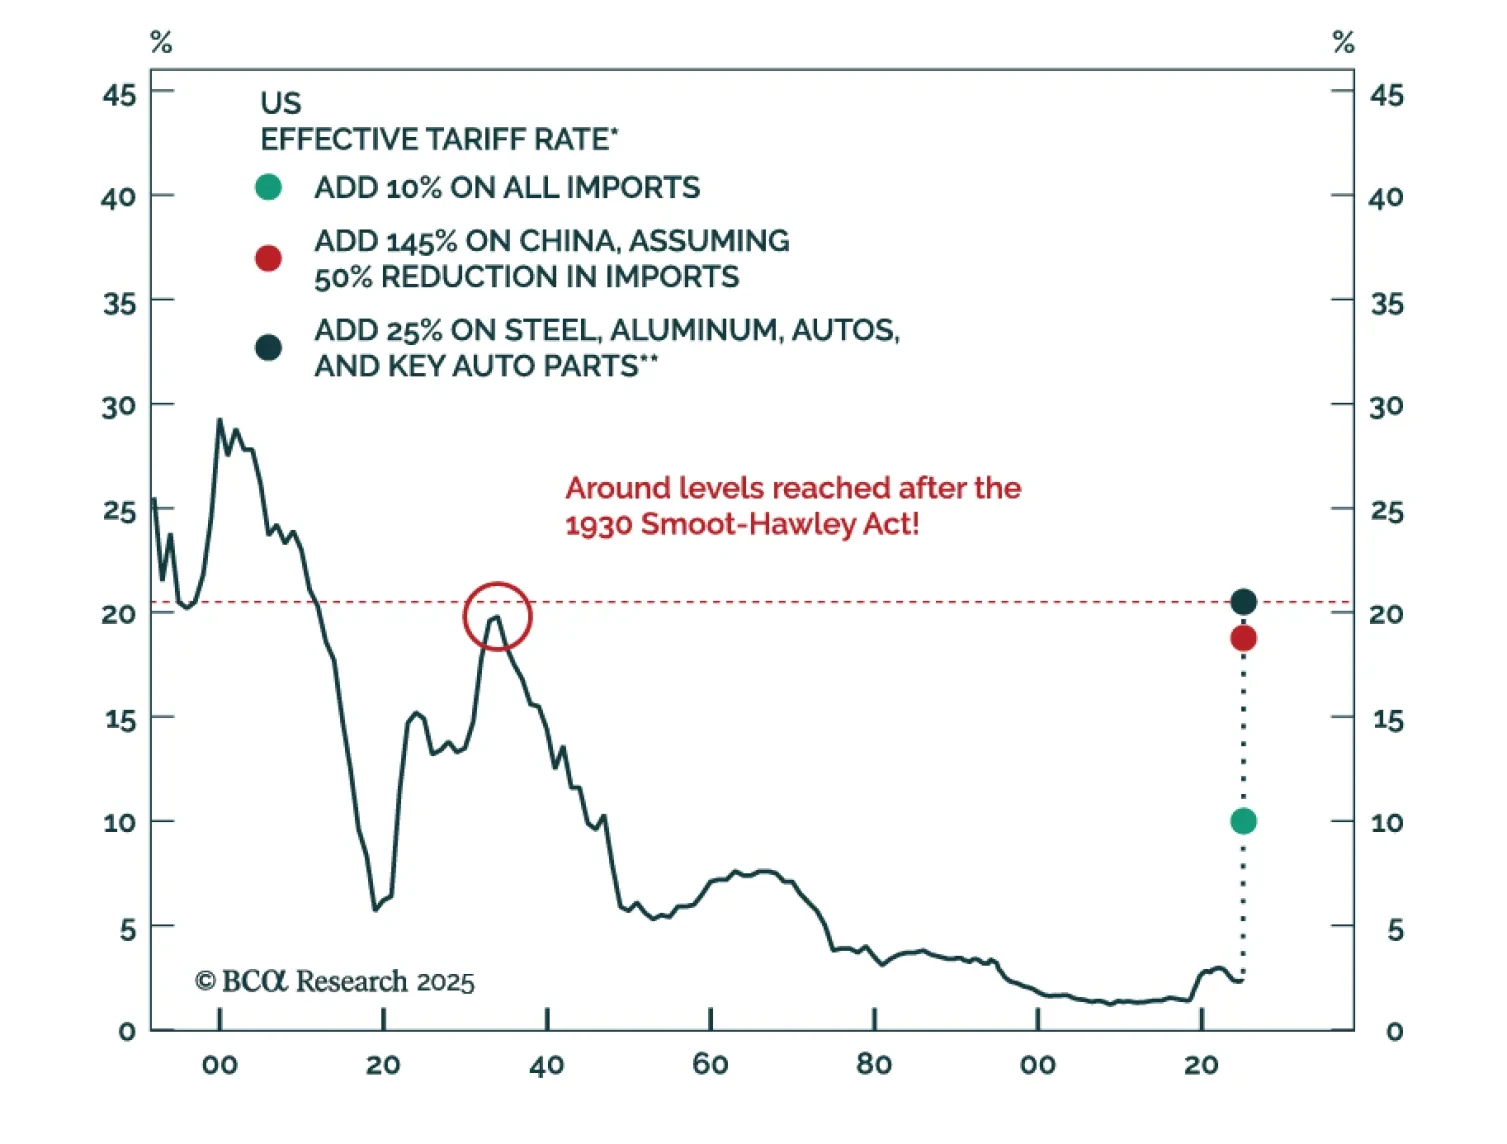
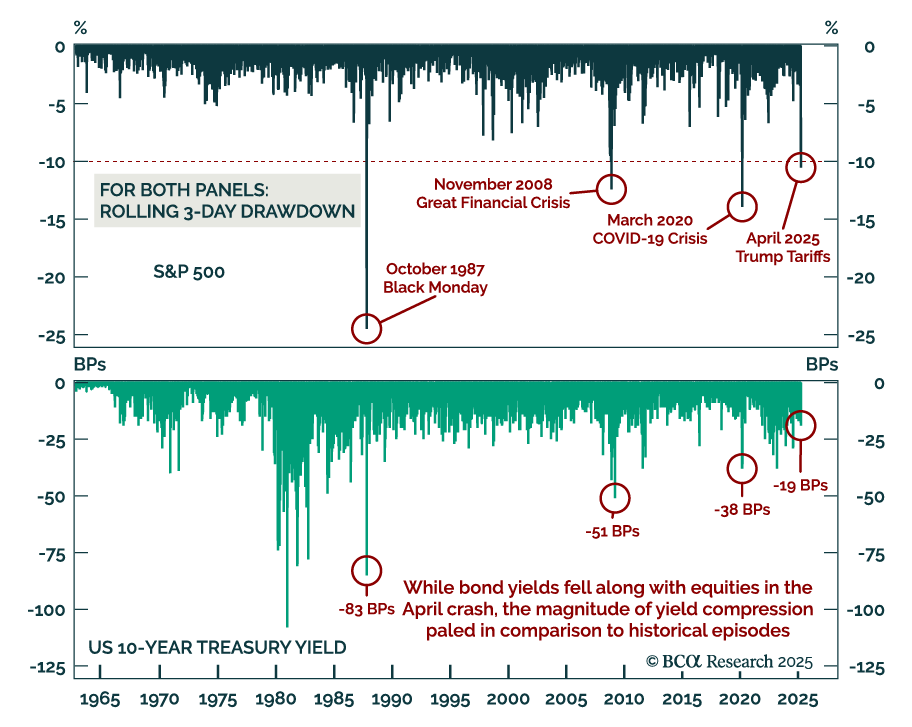
Barring a dramatic further de-escalation of the trade war, the US and much of the rest of the world will enter a recession over the next few months. Investors should remain defensively positioned for now.
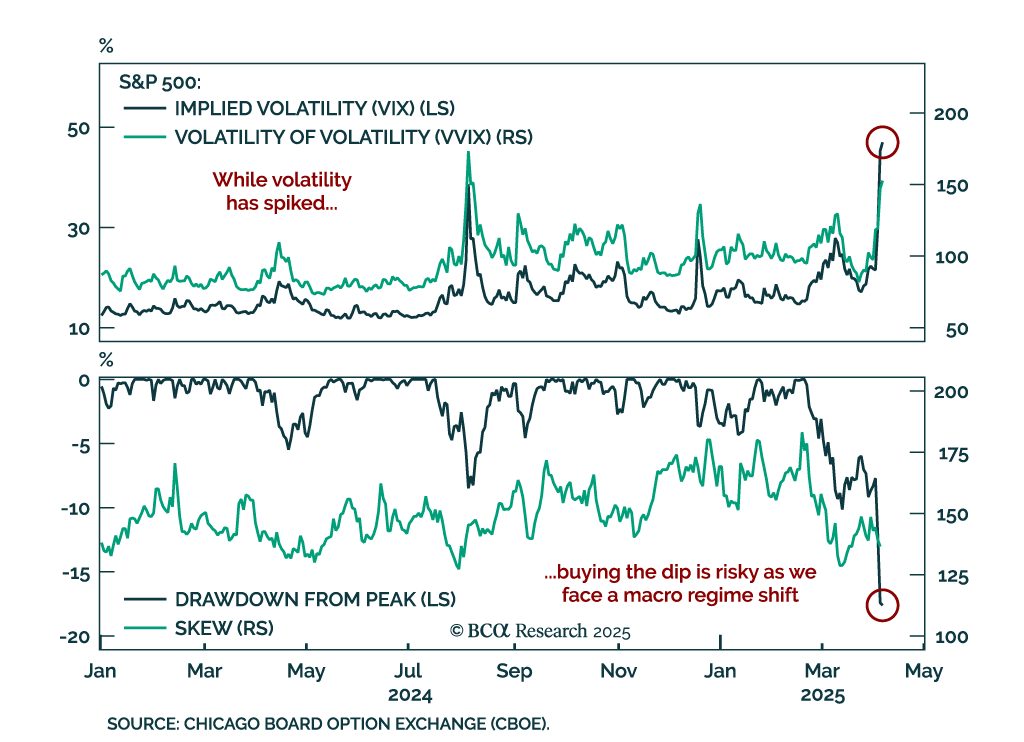

Going into April, MacroQuant recommends a modest underweight on stocks, offset by an overweight on bonds and cash. While MacroQuant is modestly bearish on stocks, we suspect that the downside risks to equities may be greater than what the model assumes.
De cara a abril, MacroQuant recomienda una ligera infraponderación en acciones, compensada por una sobreponderación en bonos y efectivo. Aunque MacroQuant es modestamente bajista en acciones, sospechamos que los riesgos a la baja para las acciones podrían ser mayores de lo que el modelo supone.
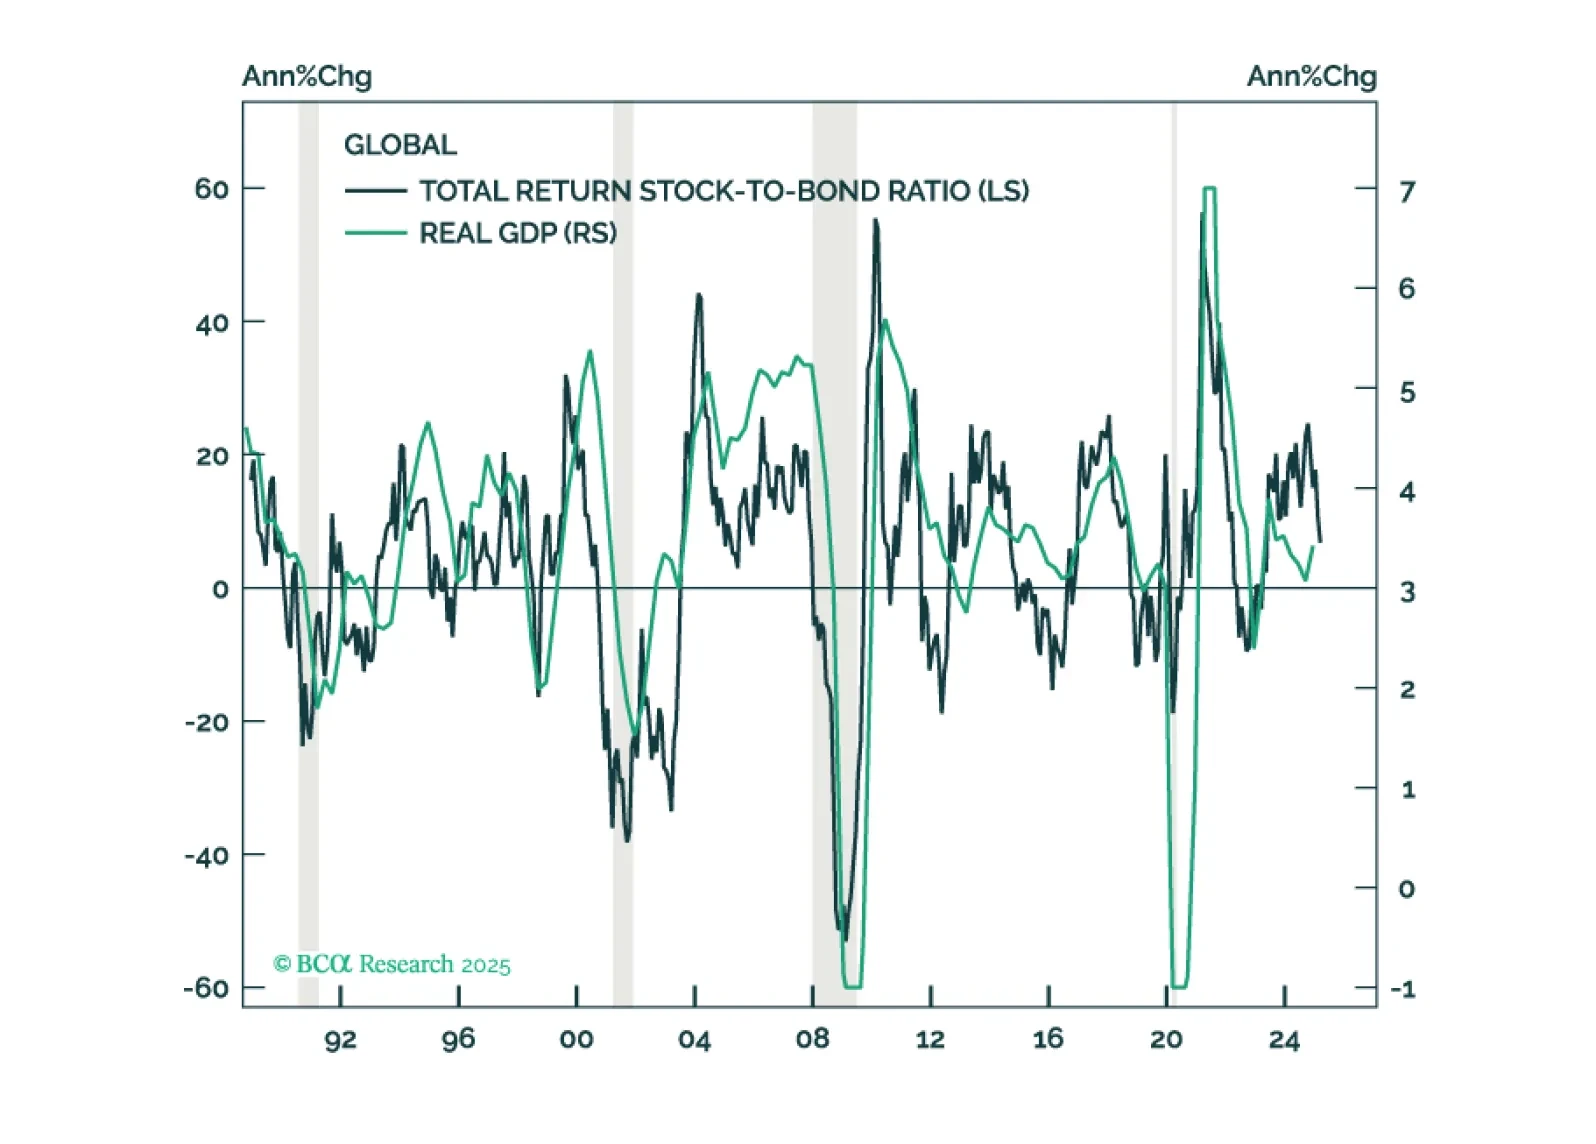
In this Second Quarter Strategy Outlook, we explore the major trends that are set to drive financial markets for the rest of 2025 and beyond.