GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
Bullish equity sentiment may persist in the second quarter on the Fed’s pause, but tight monetary policy, financial instability, elevated recession odds, extreme US polarization and policy uncertainty, and still-high geopolitical risk should encourage investors to maintain a defensive position for the coming 12 months.
Stay defensive in the second quarter. We can see a narrow window for risky assets to outperform but we recommend investors stay wary amid high rates, supply risks, extreme uncertainty, peak polarization, and structurally rising geopolitical risk.
US financial instability reinforces our bearish investment outlook by weighing on economic growth and corporate earnings while also increasing US policy uncertainty and geopolitical risk.
Investors in Europe and the American West are already starting to think about the implications of the 2024 election, given that sticky inflation and tighter monetary policy keep the risk of recession elevated.
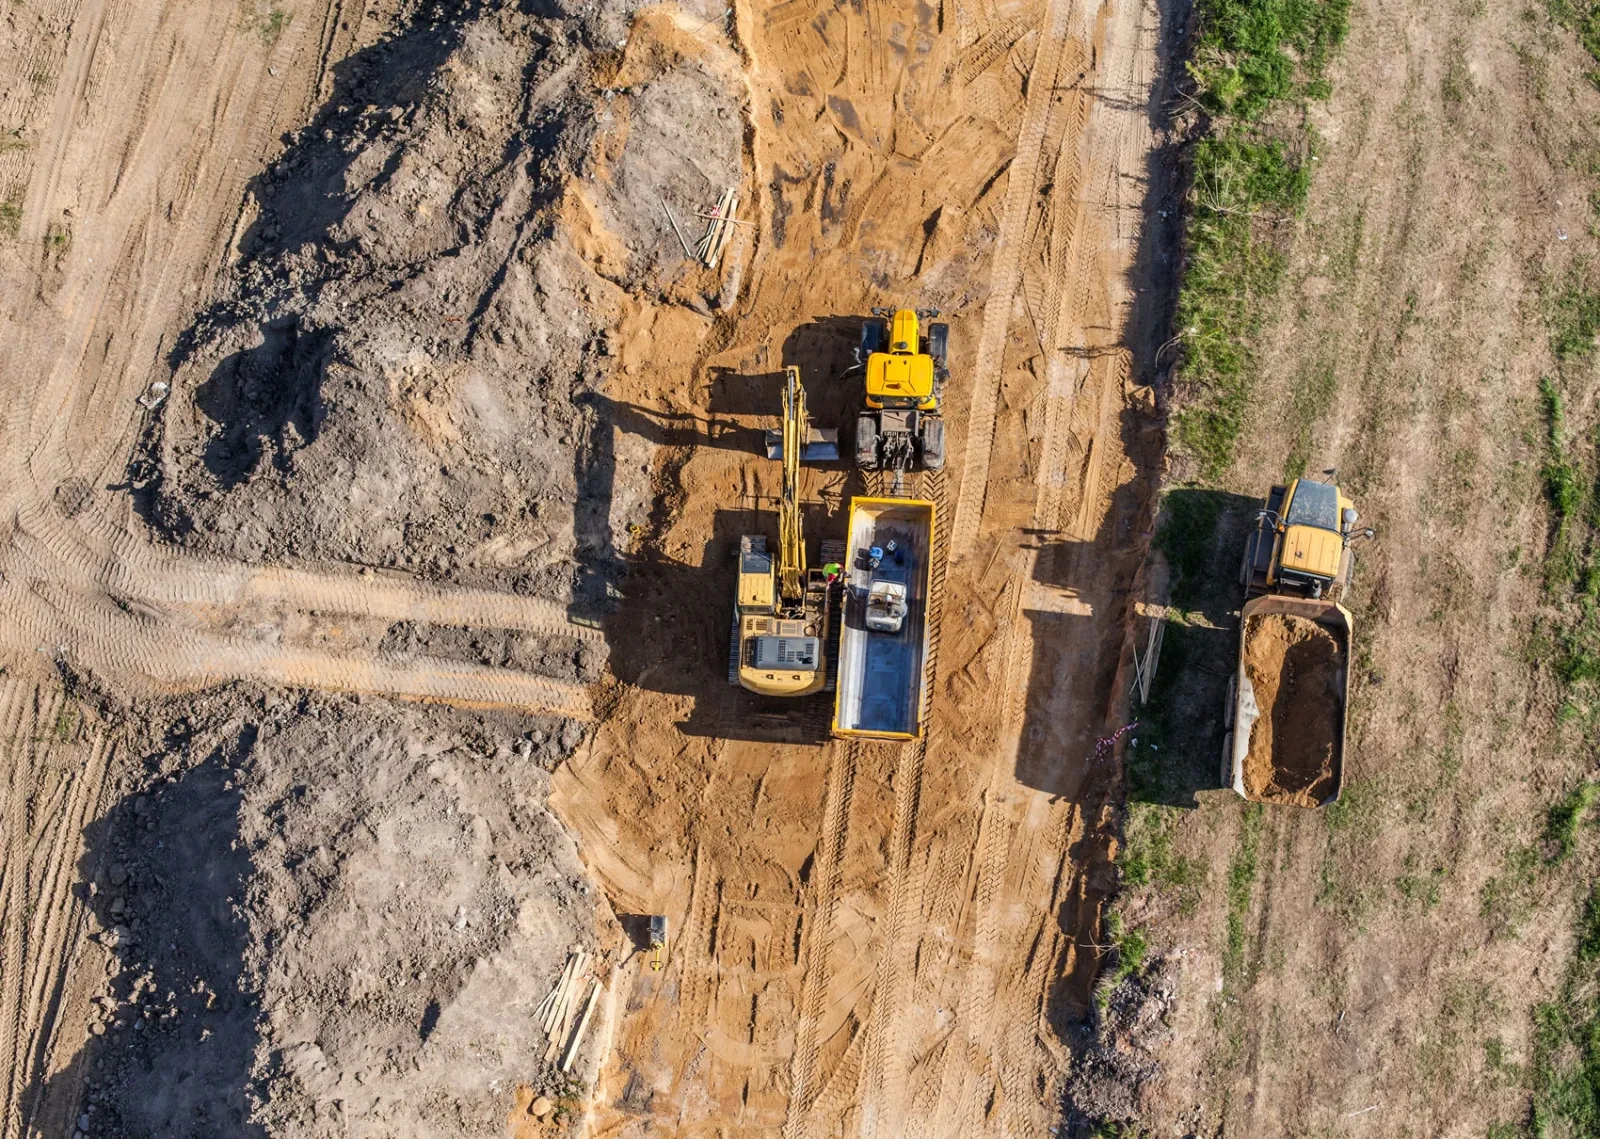
US domestic politics, hypo-globalization, and Great Power Competition favor a revival of US manufacturing capacity. The industrial sector will benefit from the attempt to rebuild US manufacturing. Go long physical infrastructure and defense stocks. Find opportunities to take a long position on the universe versus the metaverse.