 FICC
Find out more
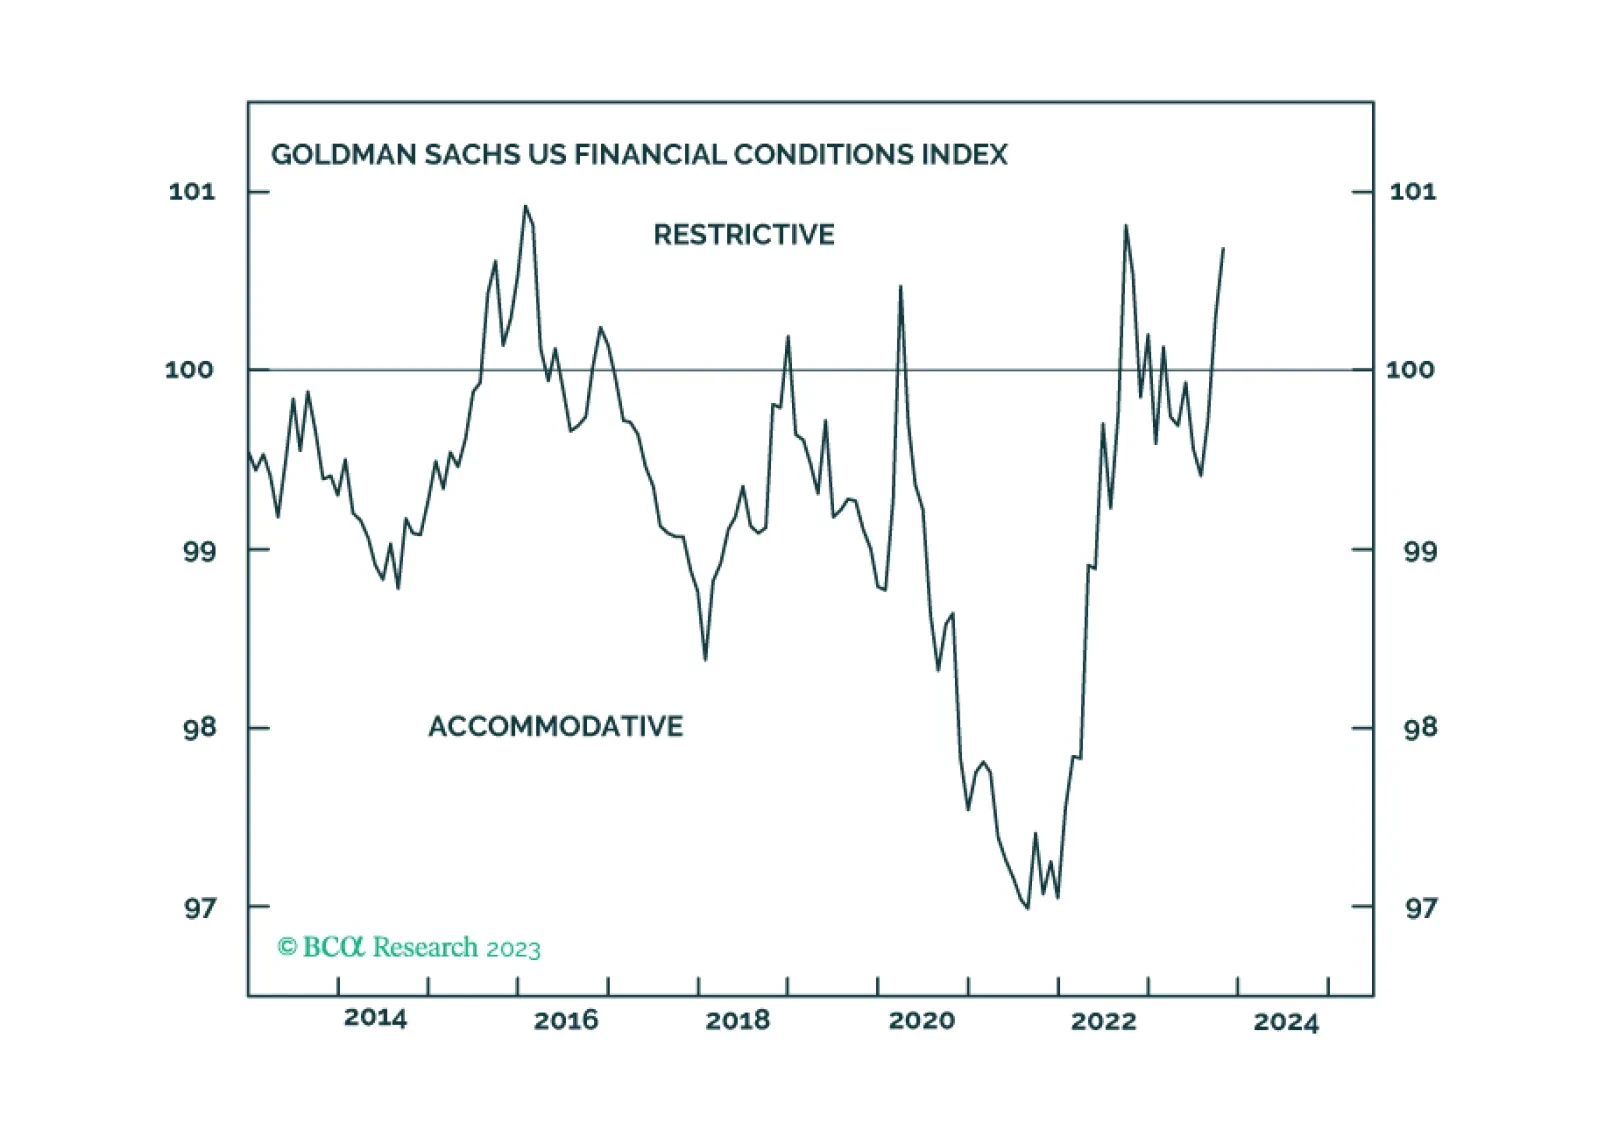
Our reaction to today’s FOMC meeting and the Treasury’s Quarterly Refunding Announcement.
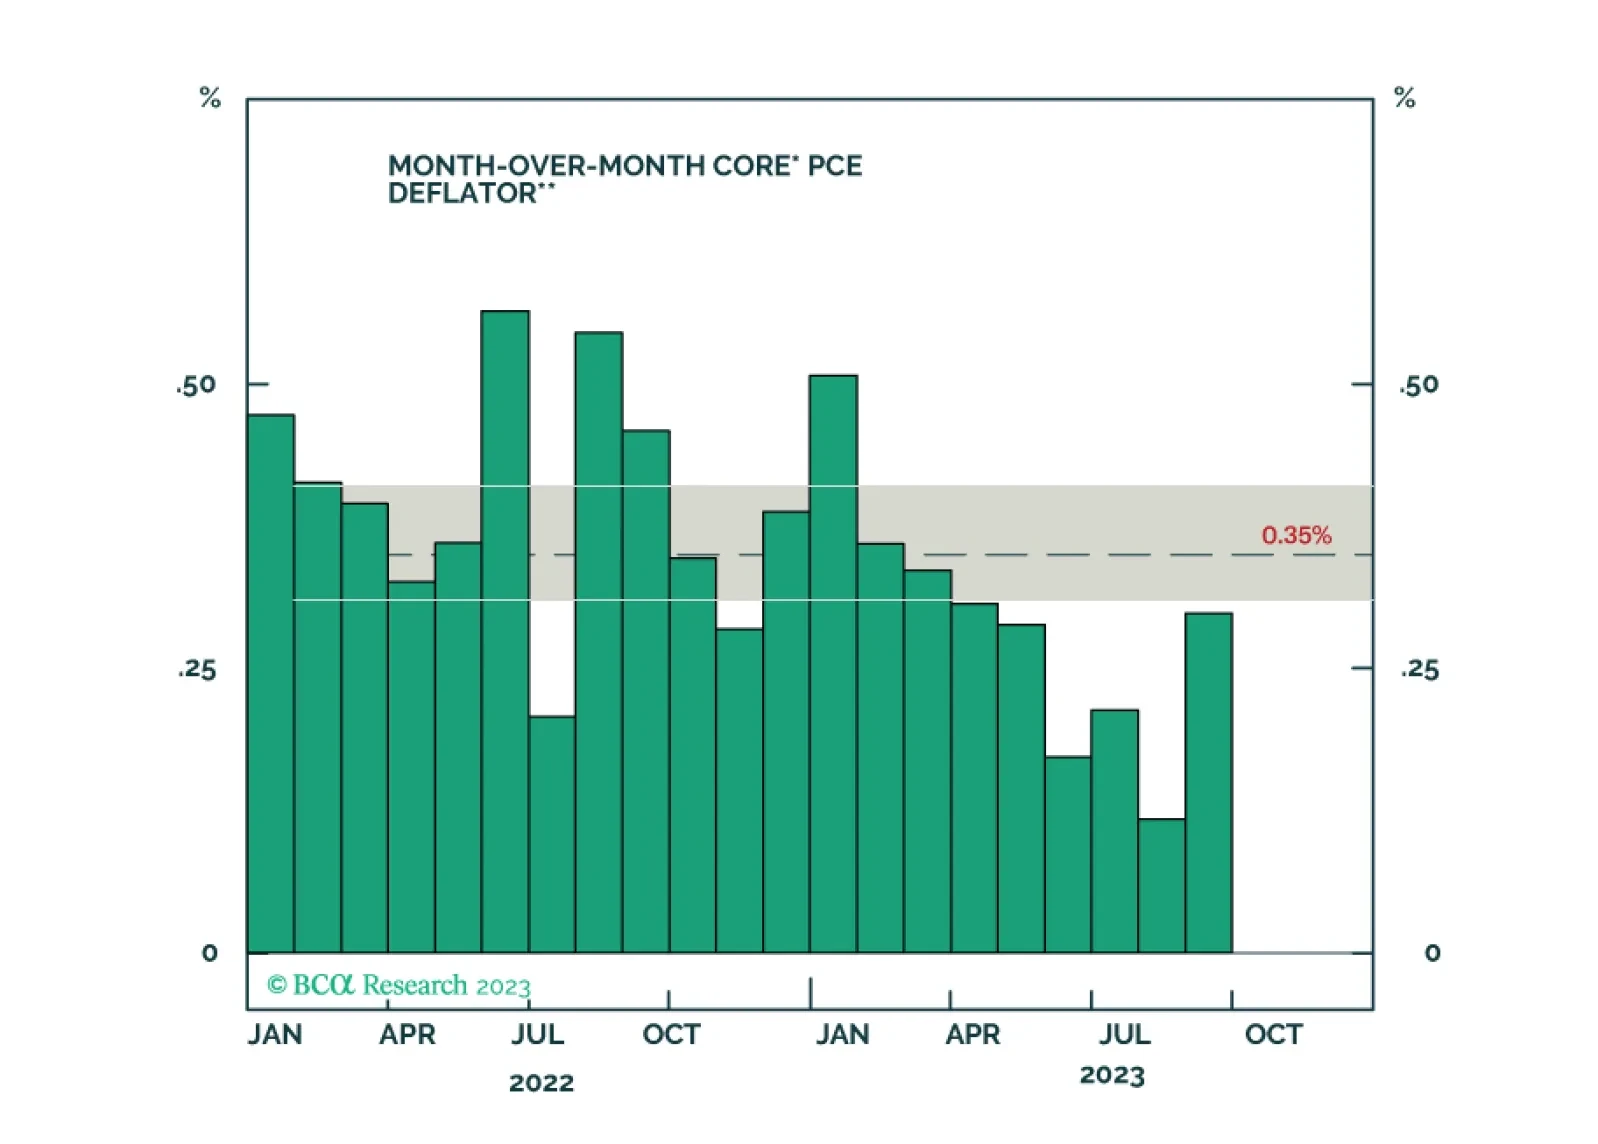
A look at recent data on economic growth, inflation and the labor market, and a discussion of the implications for Fed policy and bond strategy.
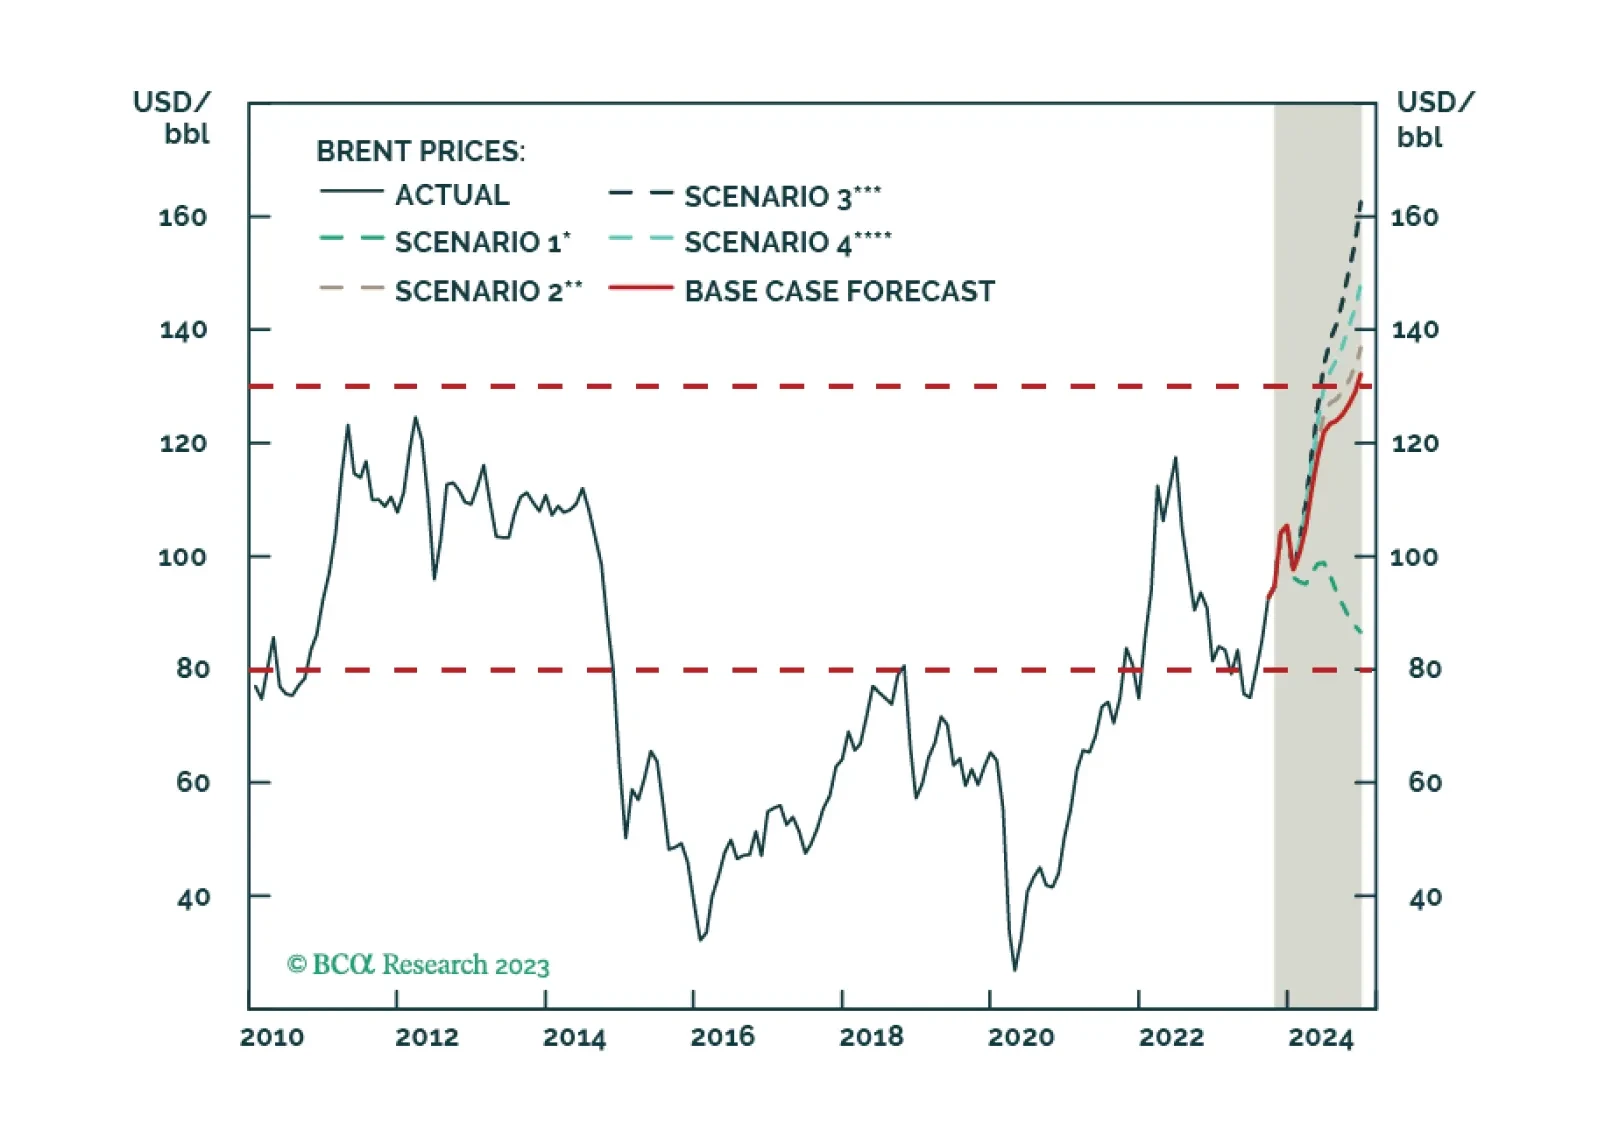
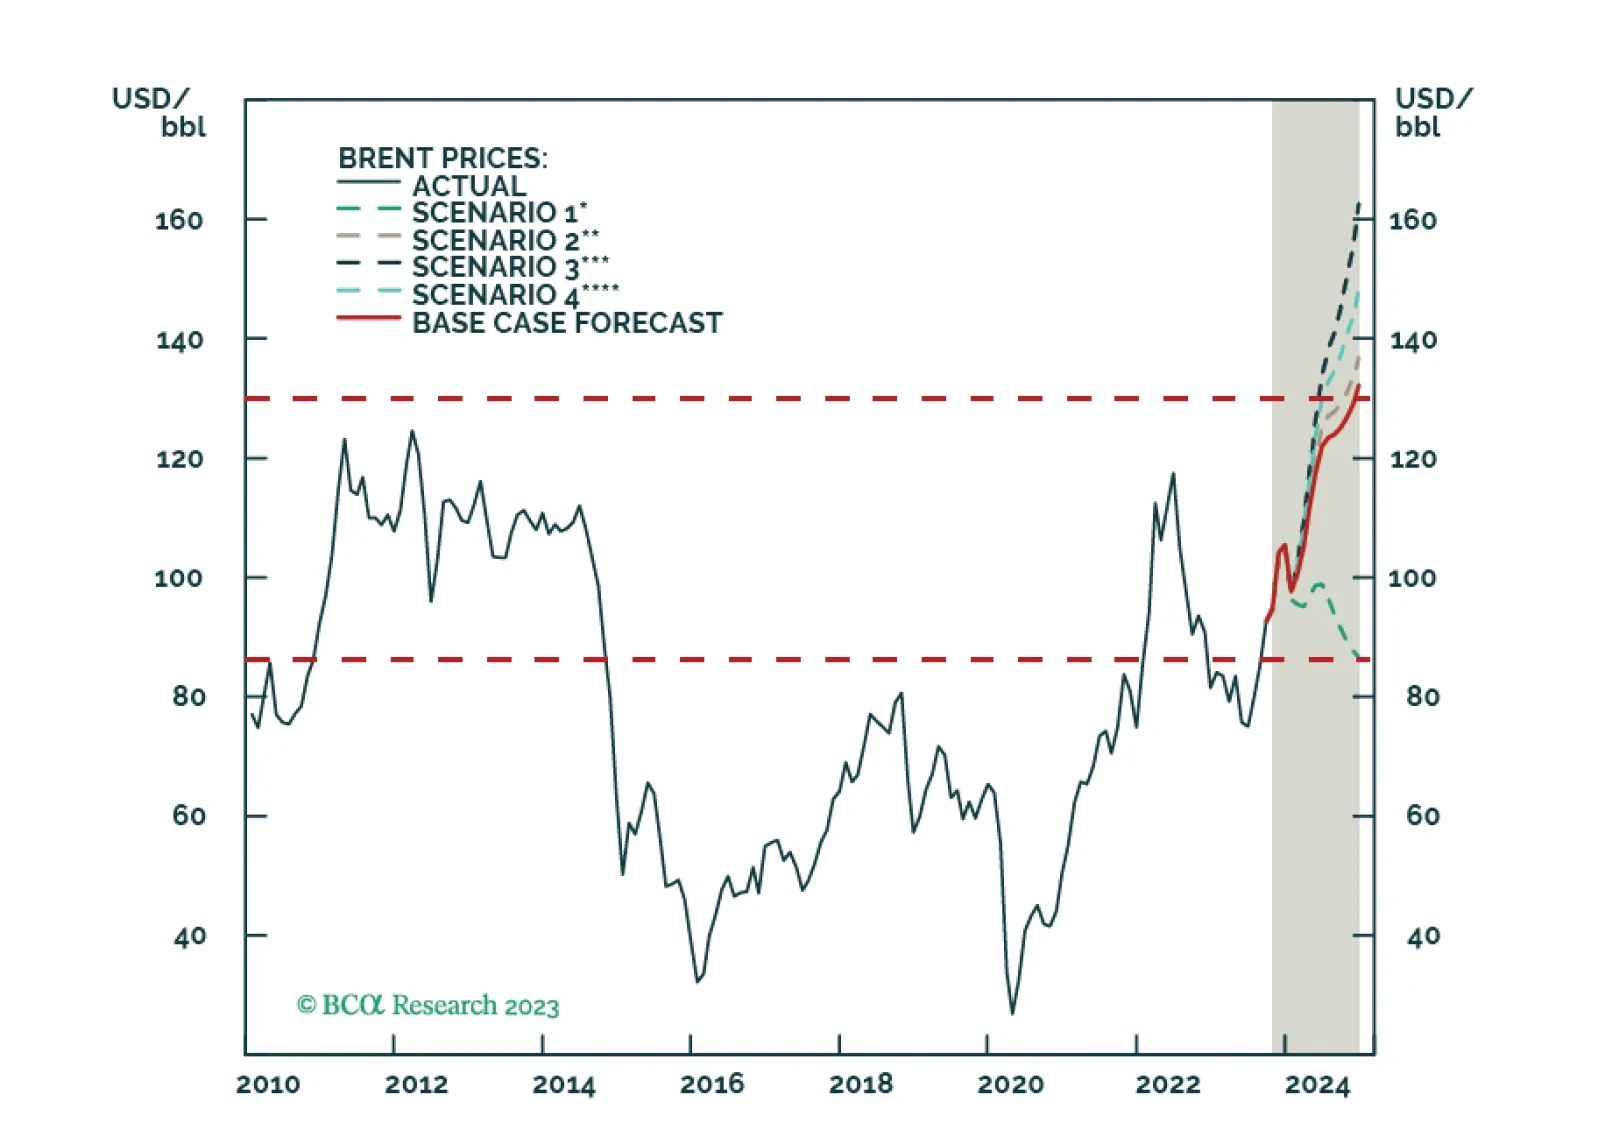
The US and core OPEC 2.0 are – wittingly or not – laying the groundwork for a price band with a floor and cap on oil prices – at $79/bbl and $130/bbl, respectively – “at least” to May 2024. This accommodates multiple goals for both. To meaningfully support policy, the US would need to scale up purchases to refill its SPR. We remain long the XOP and COMT ETFs for direct exposure to energy E+P equities and commodities.
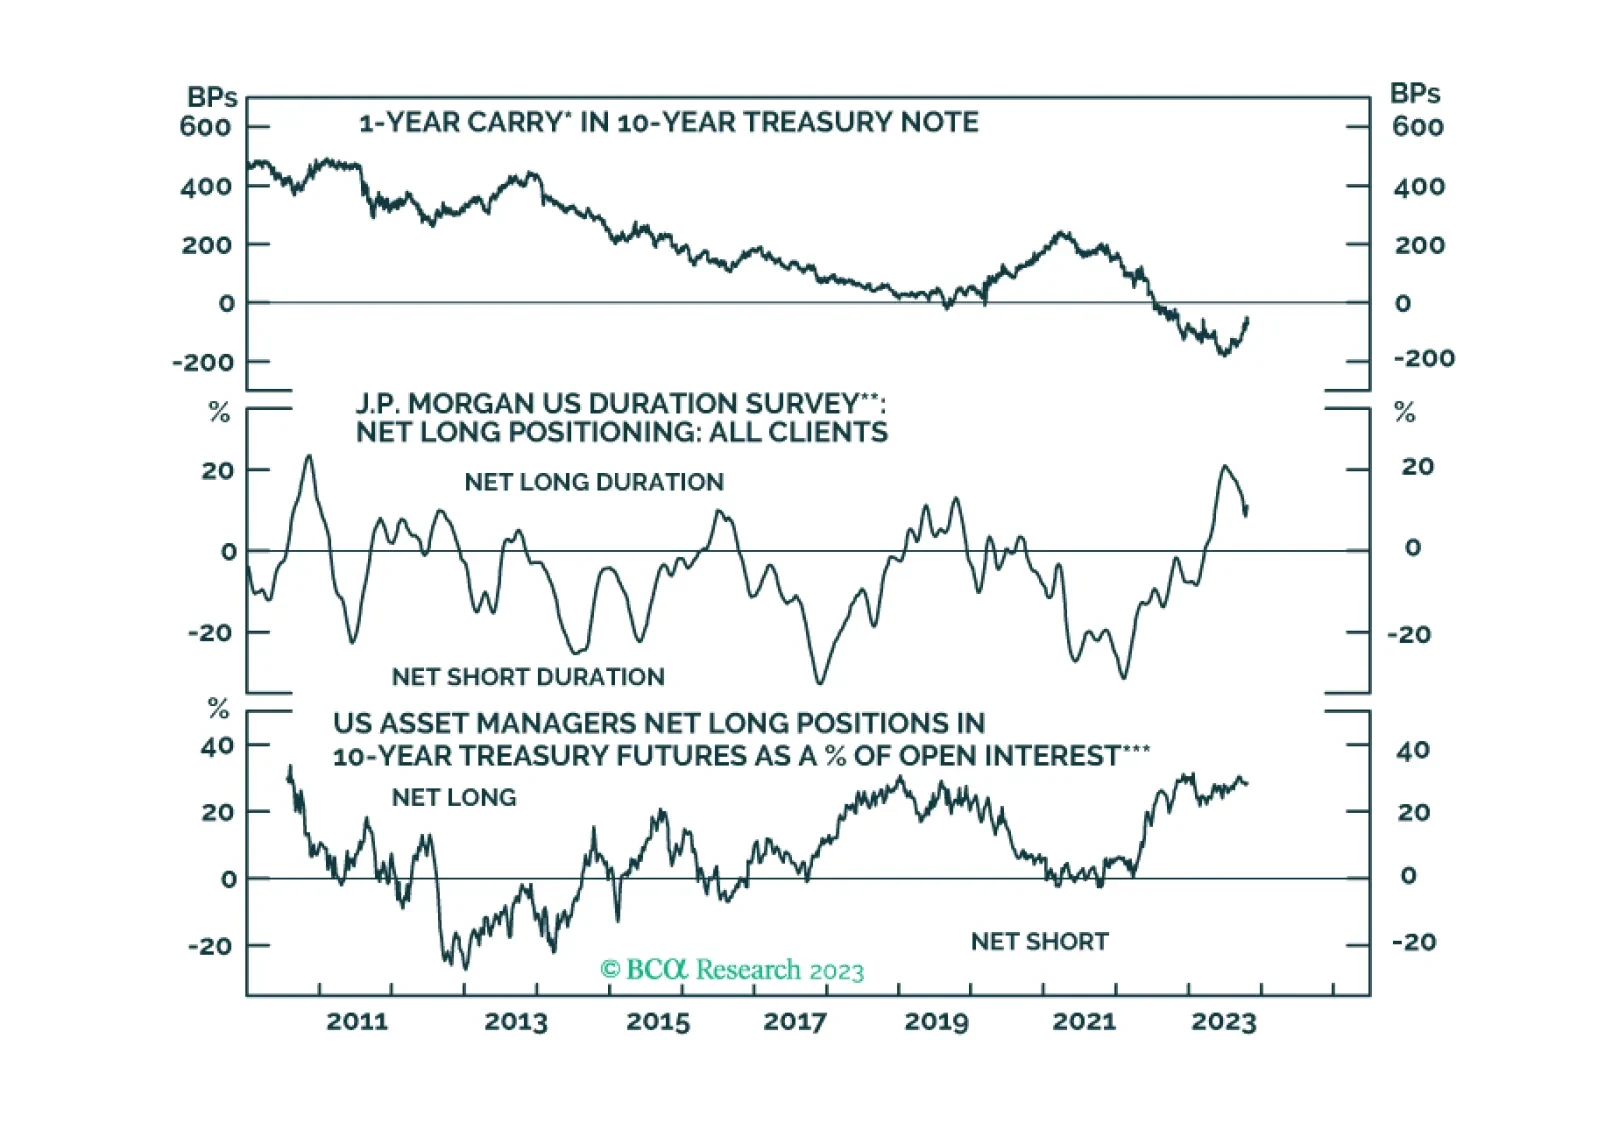
This week’s report contains an update on the Treasury curve’s recent bear-steepening trend and a look at different measures of long-maturity Treasury valuation.
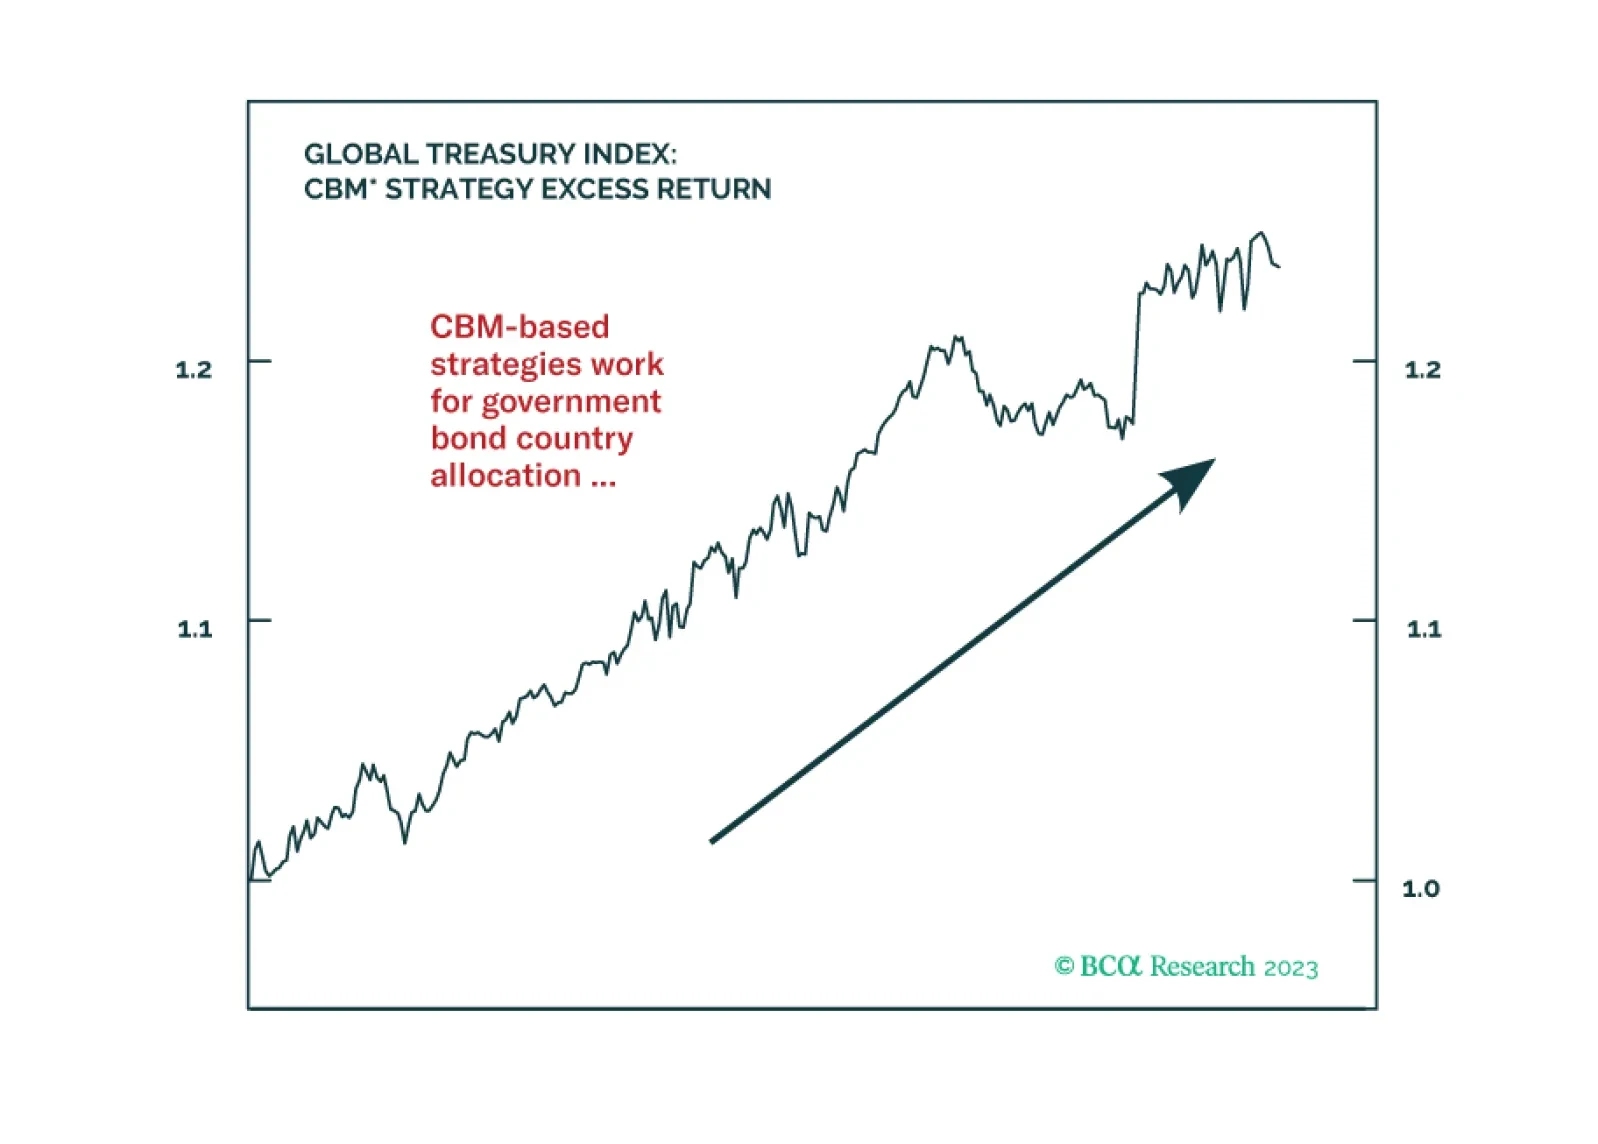
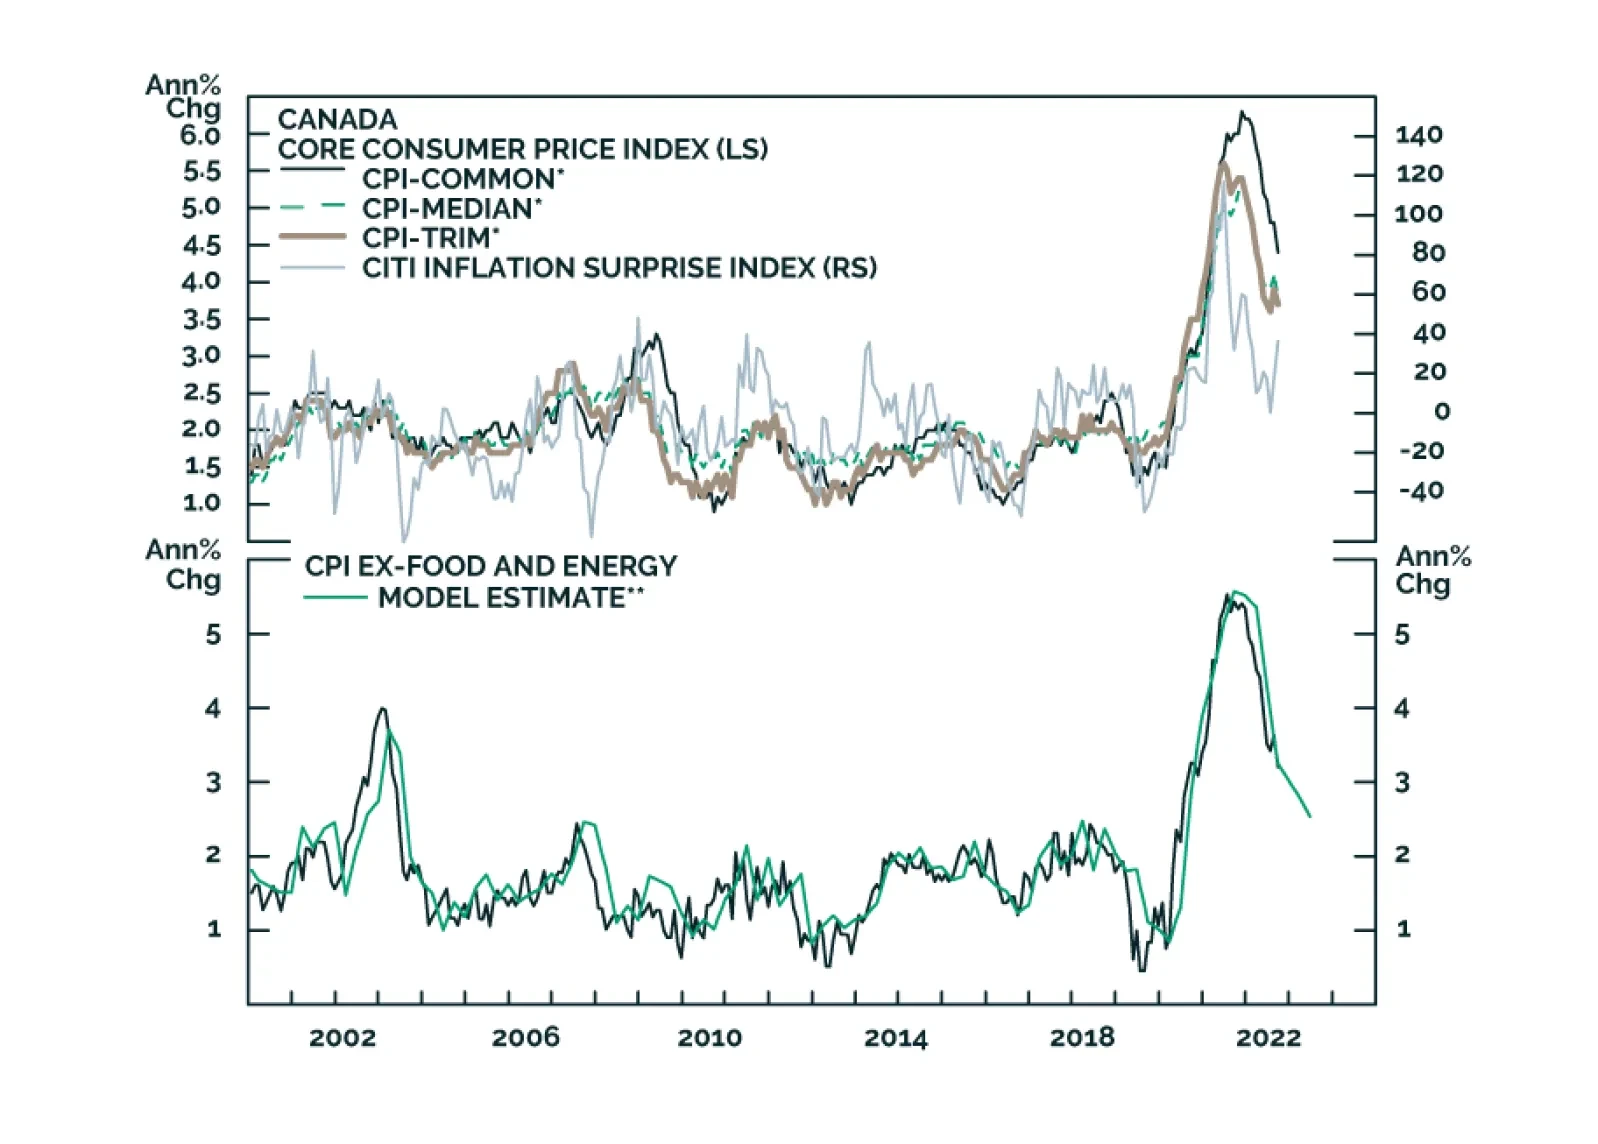
In this insight, we look at whether the recent data justifies a shift by the BoC, and some potential trades.
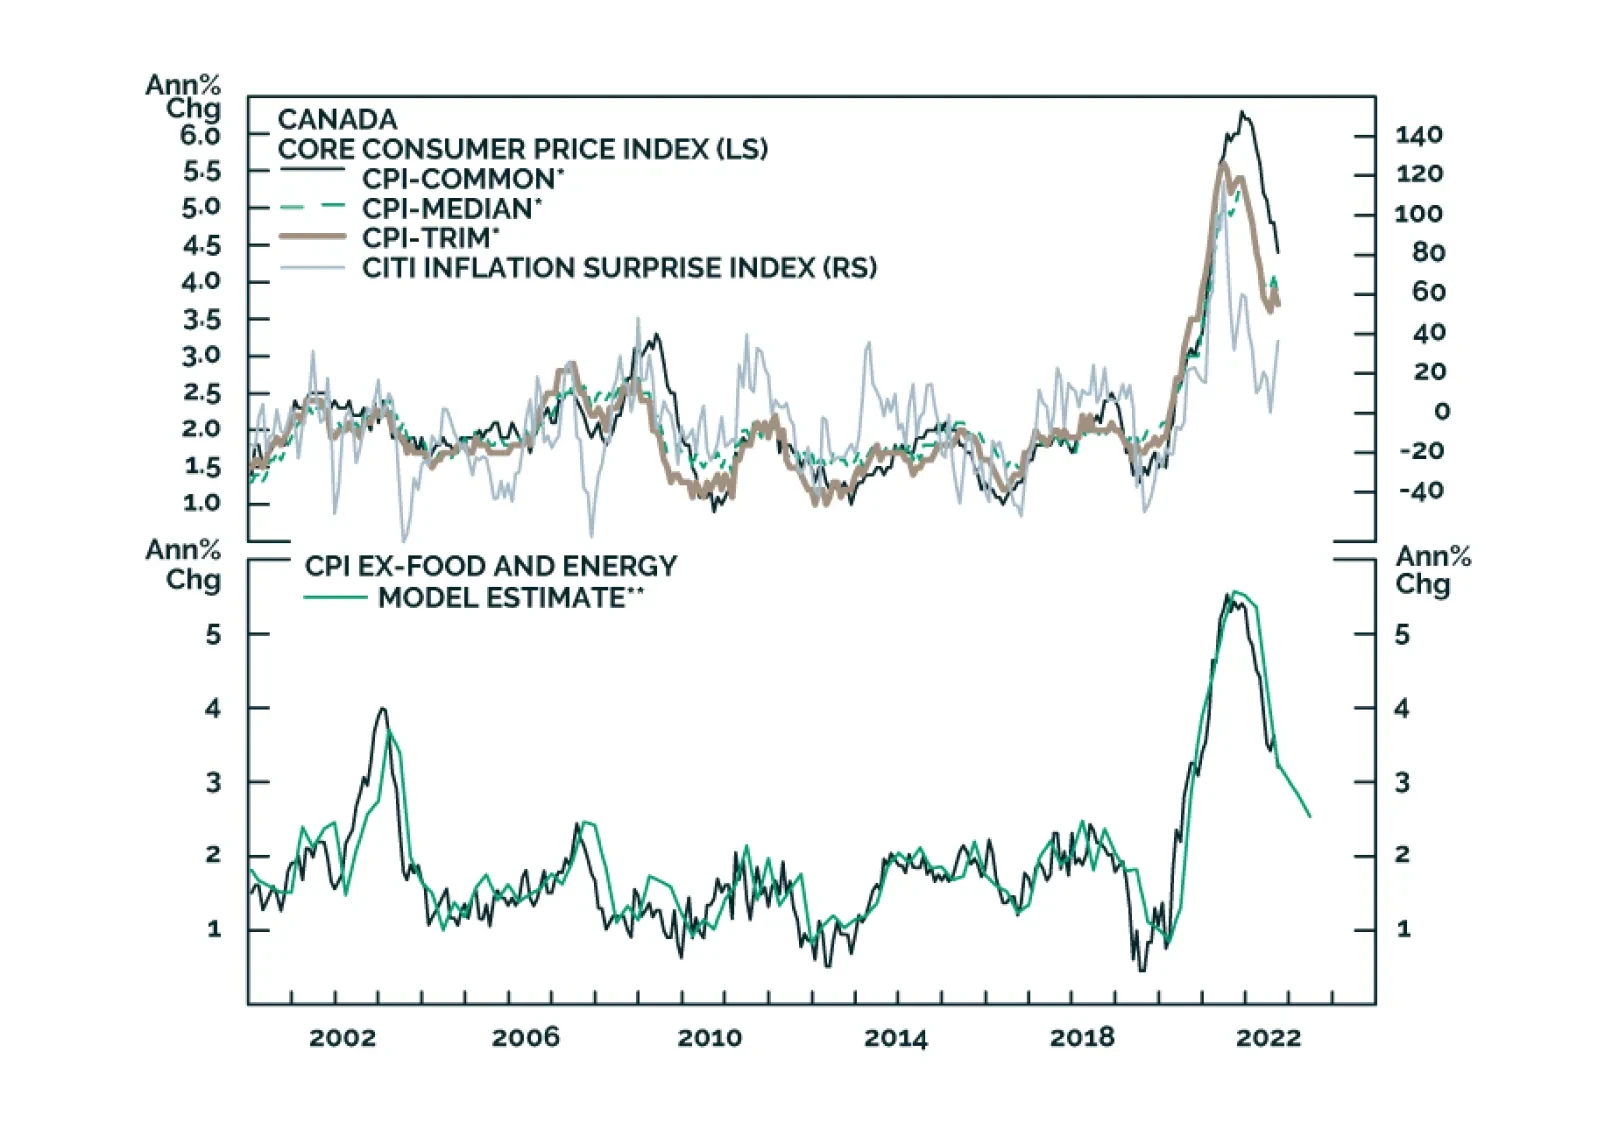
In this insight, we look at whether the recent data justifies a shift by the BoC, and some potential trades.
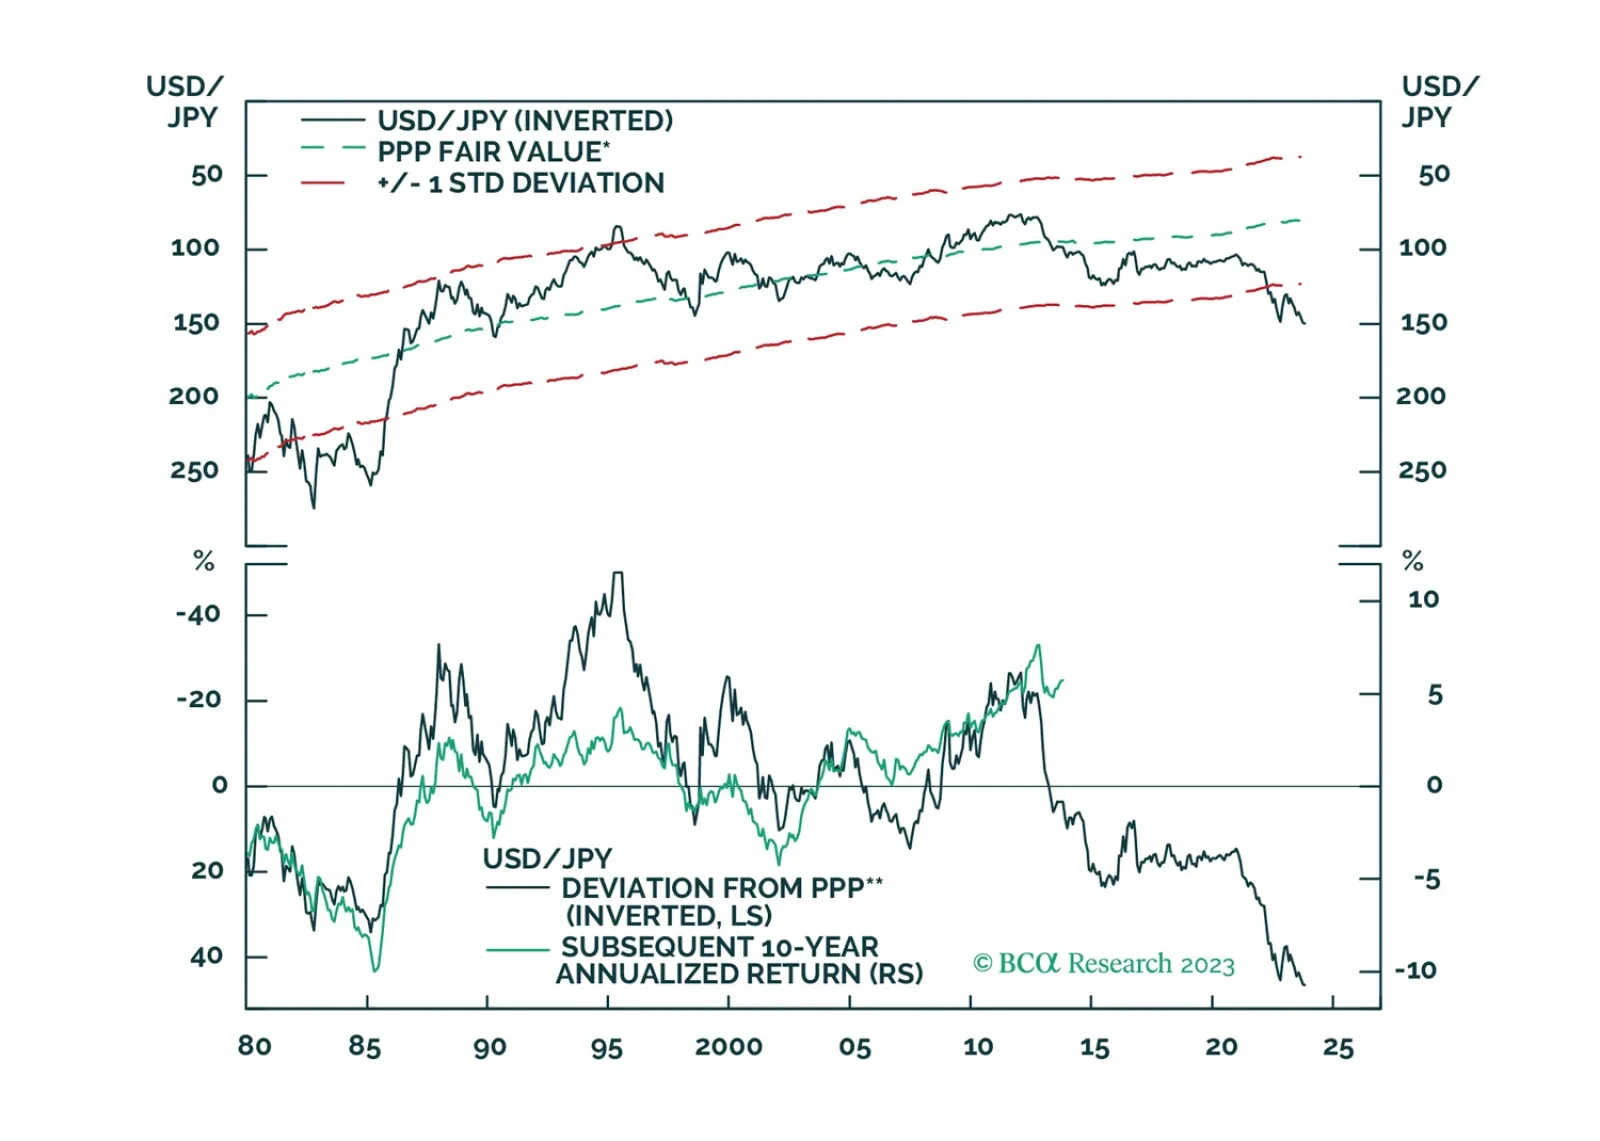
There is a high probability that the global economy will tip into recession in the second half of 2024. A long yen position is an excellent hedge against that risk.
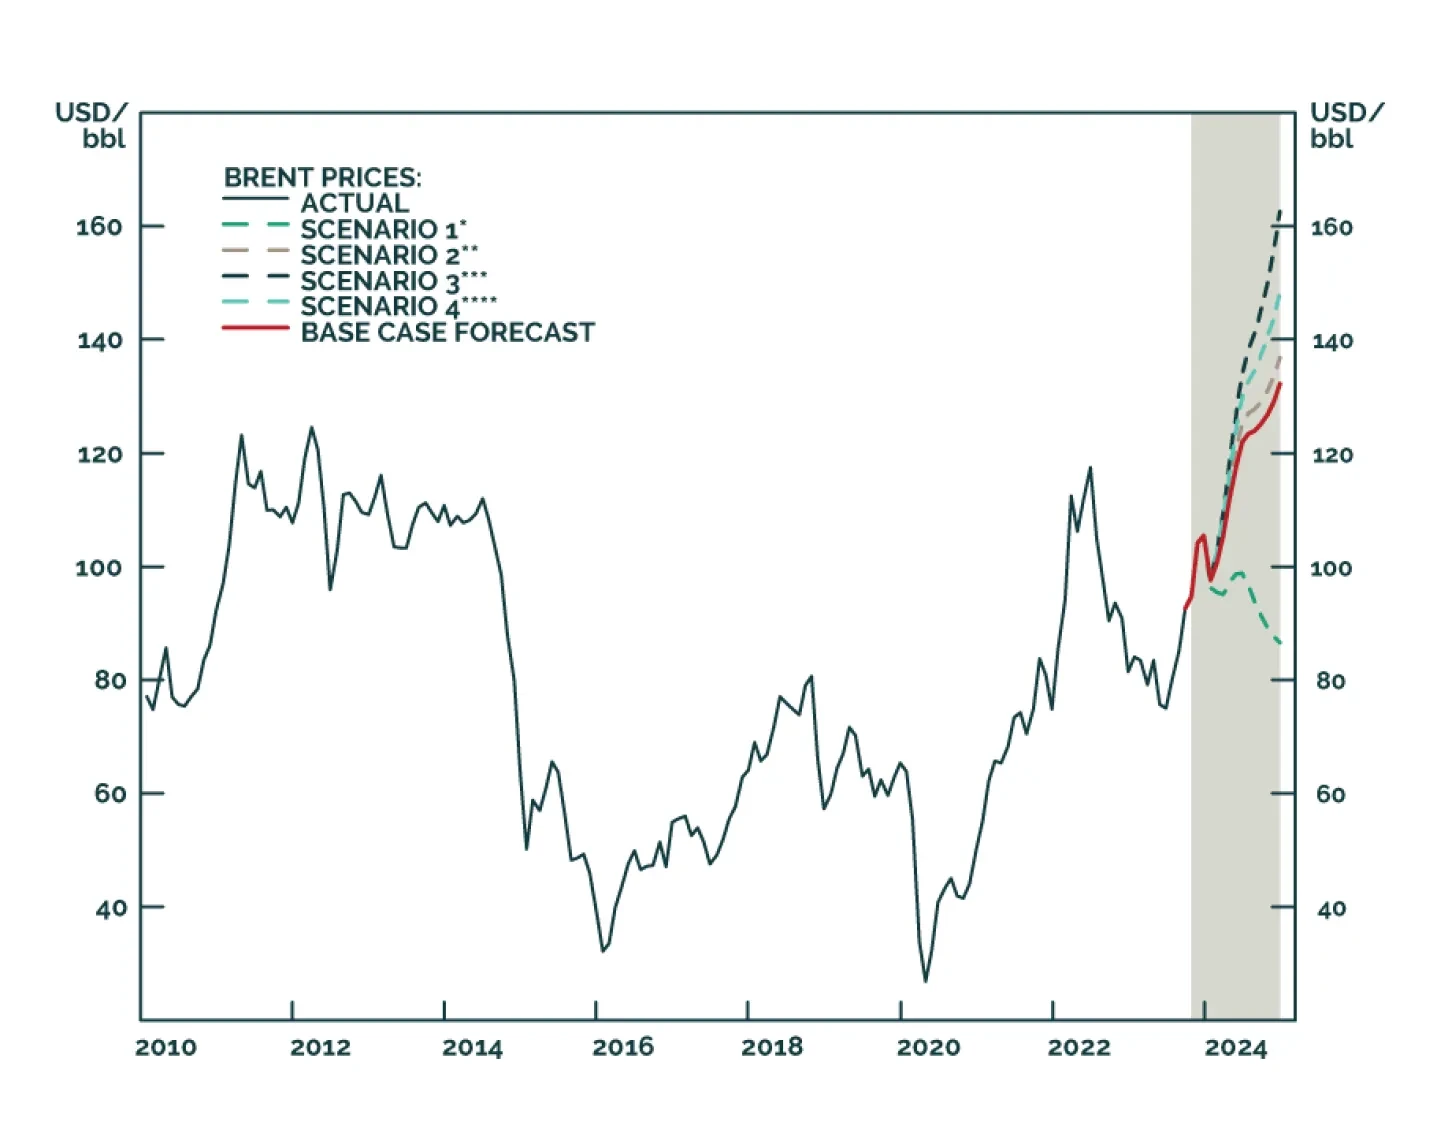
Despite higher uncertainty, our Brent price forecasts remain unchanged at just over $101/bbl for 4Q23 and $118/bbl for next year. We remain long equity exposure to oil and gas producers via the XOP ETF, and commodity exposure via the COMT ETF. We also remain long $100 Dec24 Brent calls and long 1Q24 Brent futures vs. short 1Q25 Brent futures in anticipation of stronger backwardation.