 Explore FICC
FICC | Bonds
Actionable asset allocation recommendations for your bond portfolio, drawing on macro analysis of interest rates and global debt market dynamics. Typically published weekly.
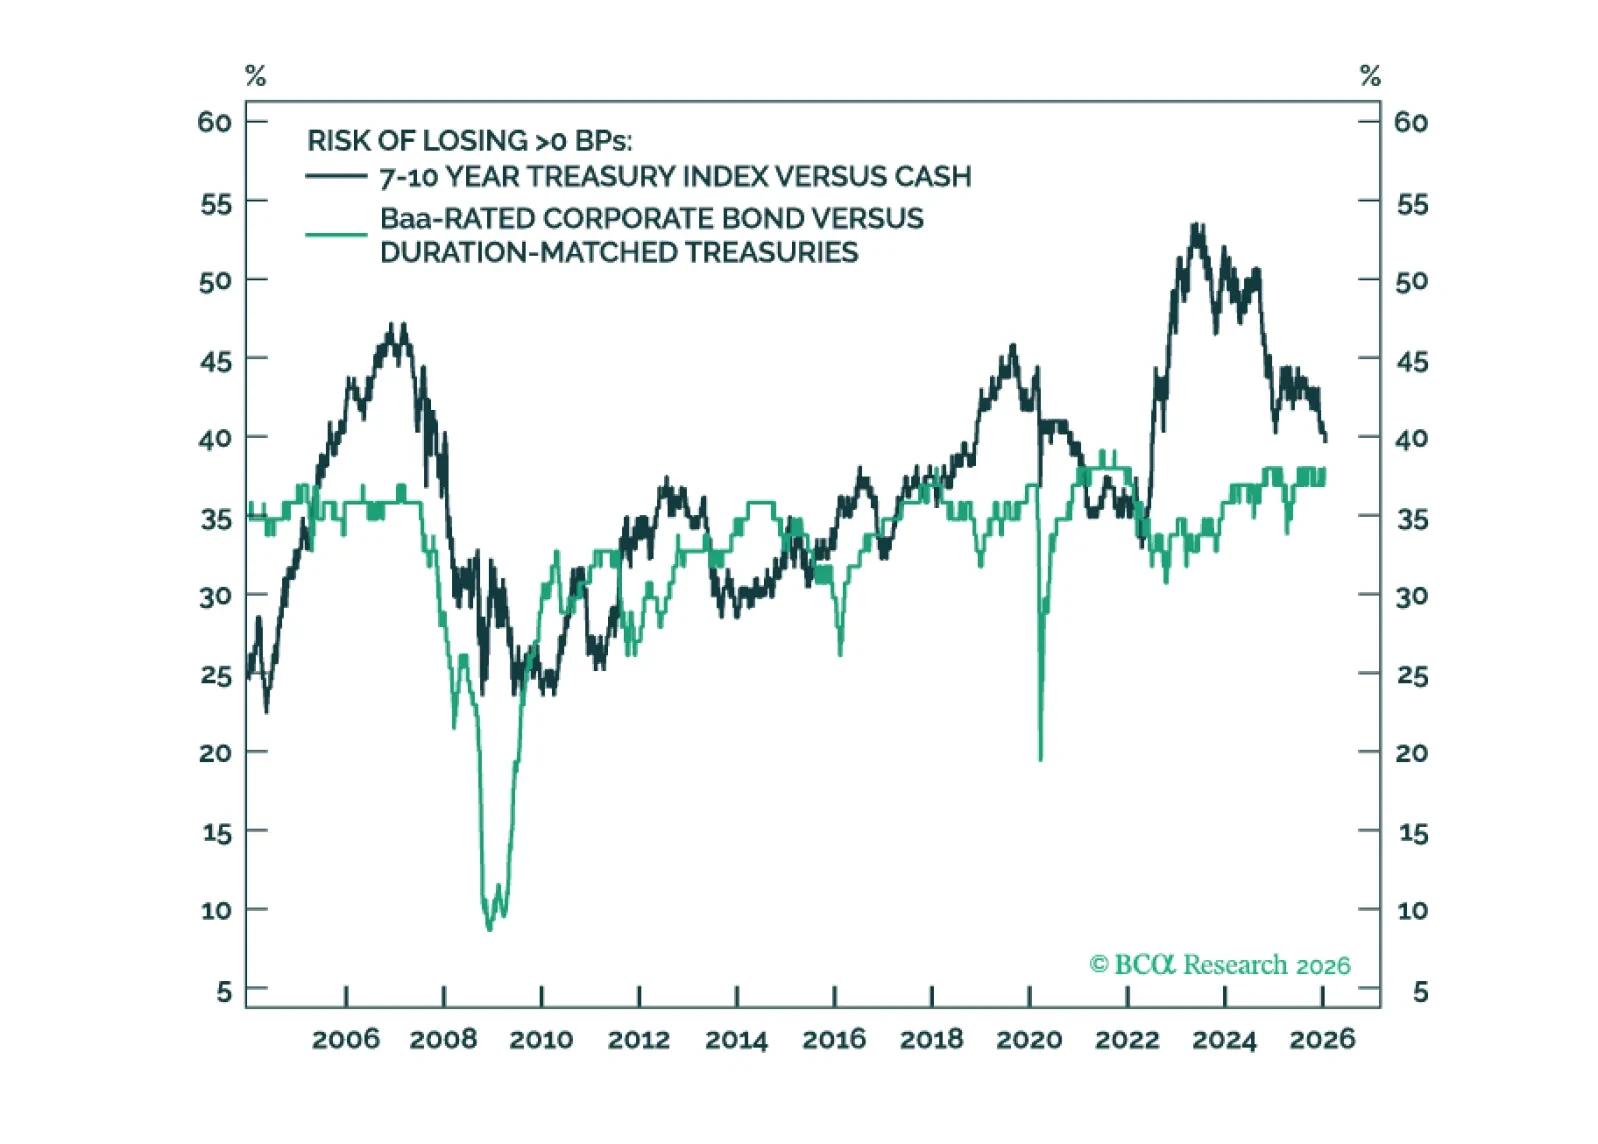
The 10-year Treasury term premium is now competitive with Baa- and Ba-rated credit spreads. Even without term premium compression, duration carry trades could outperform credit carry trades in a low rate vol environment.
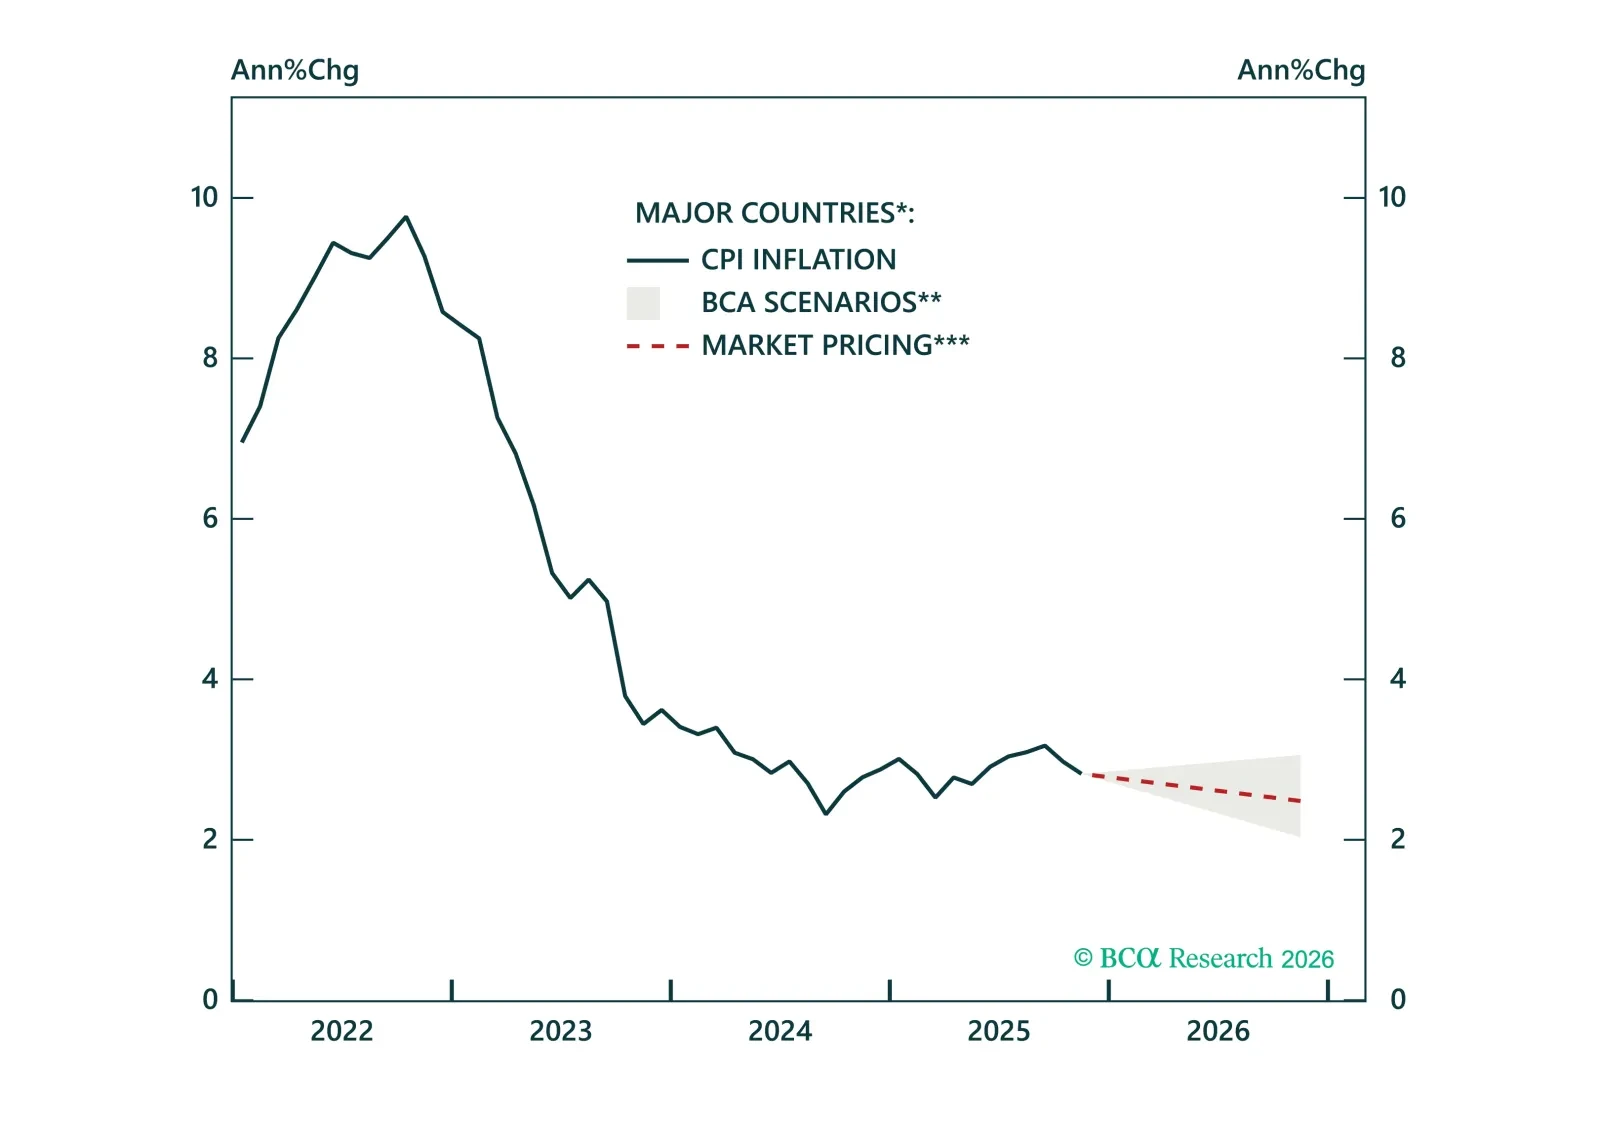
In our 2026 inflation outlook, we explain why 2026 will bring more disinflation, upside risks remain contained, and how to position in ILBs across major markets.
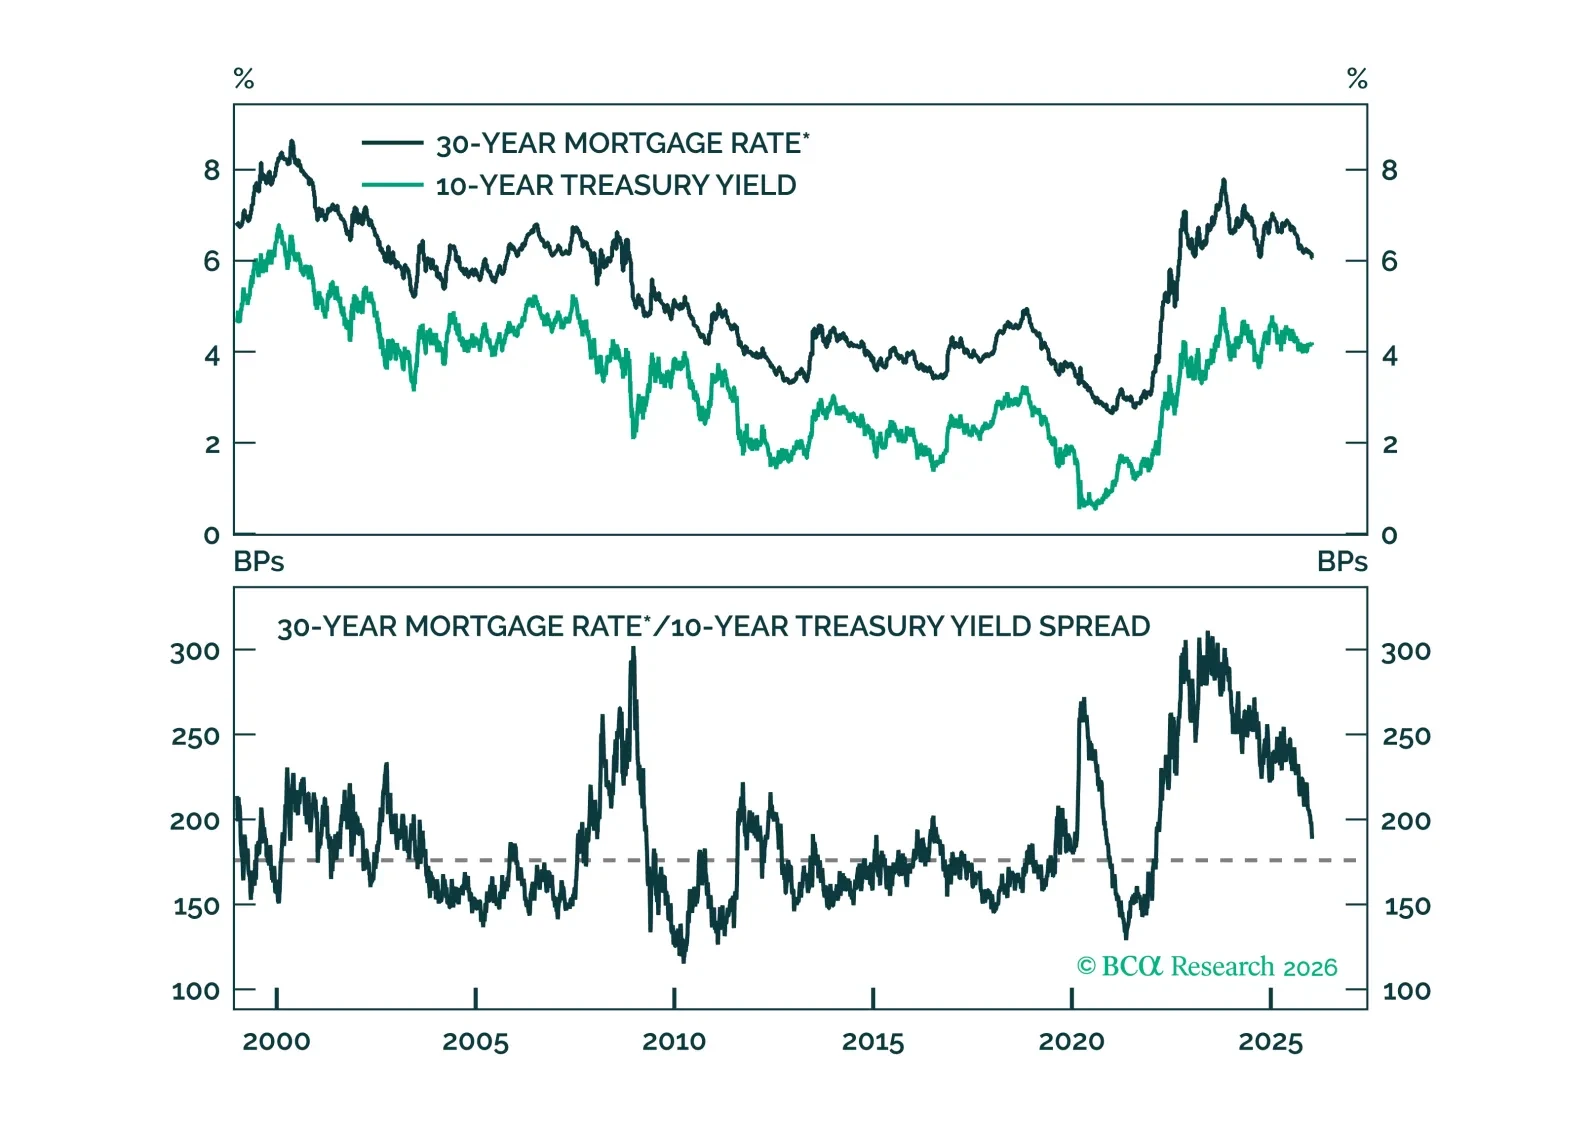
Mortgage spread tightening has run its course. Any further drop in mortgage rates will necessitate lower Treasury yields.

This morning’s CPI report signals that the worst of the tariff impact on inflation may already be in the rearview mirror.

Our Q1 outlook maps global growth, curve dynamics, and policy surprises, which we then translate to our recommended global fixed income portfolio allocations and trades.

Measures of labor market utilization improved in December, ruling out a January cut and significantly reducing the odds of a March cut.
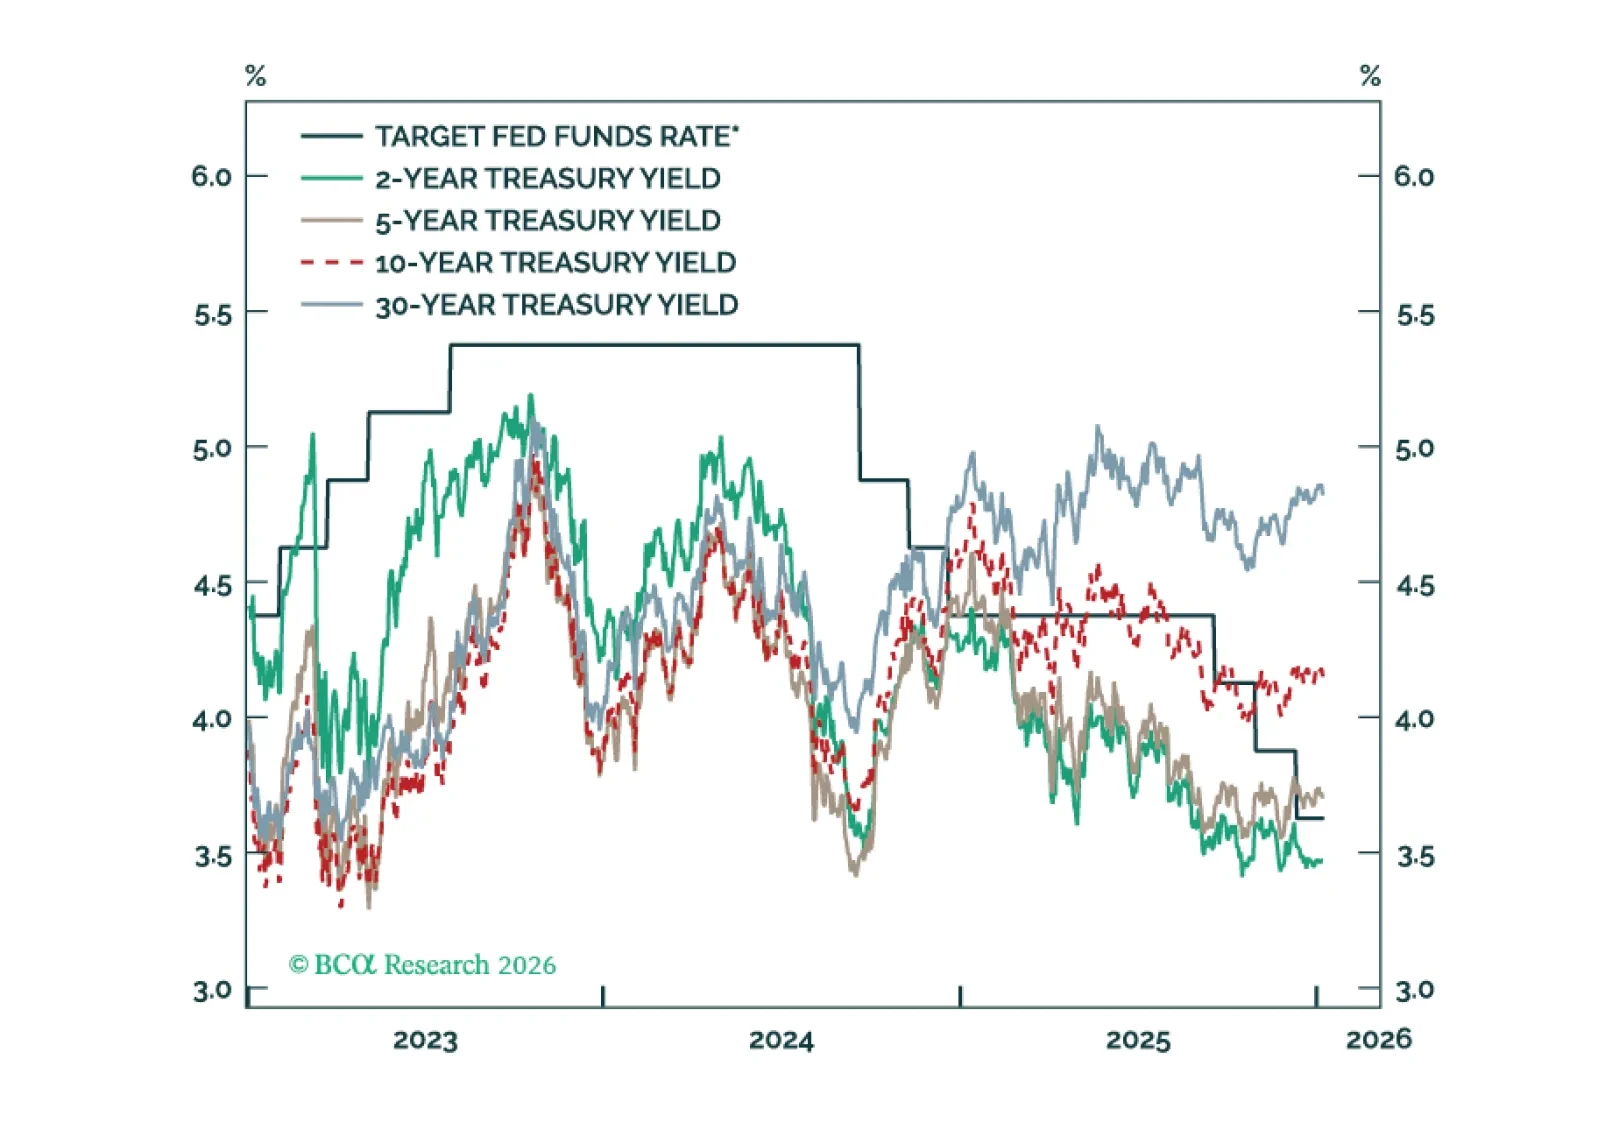
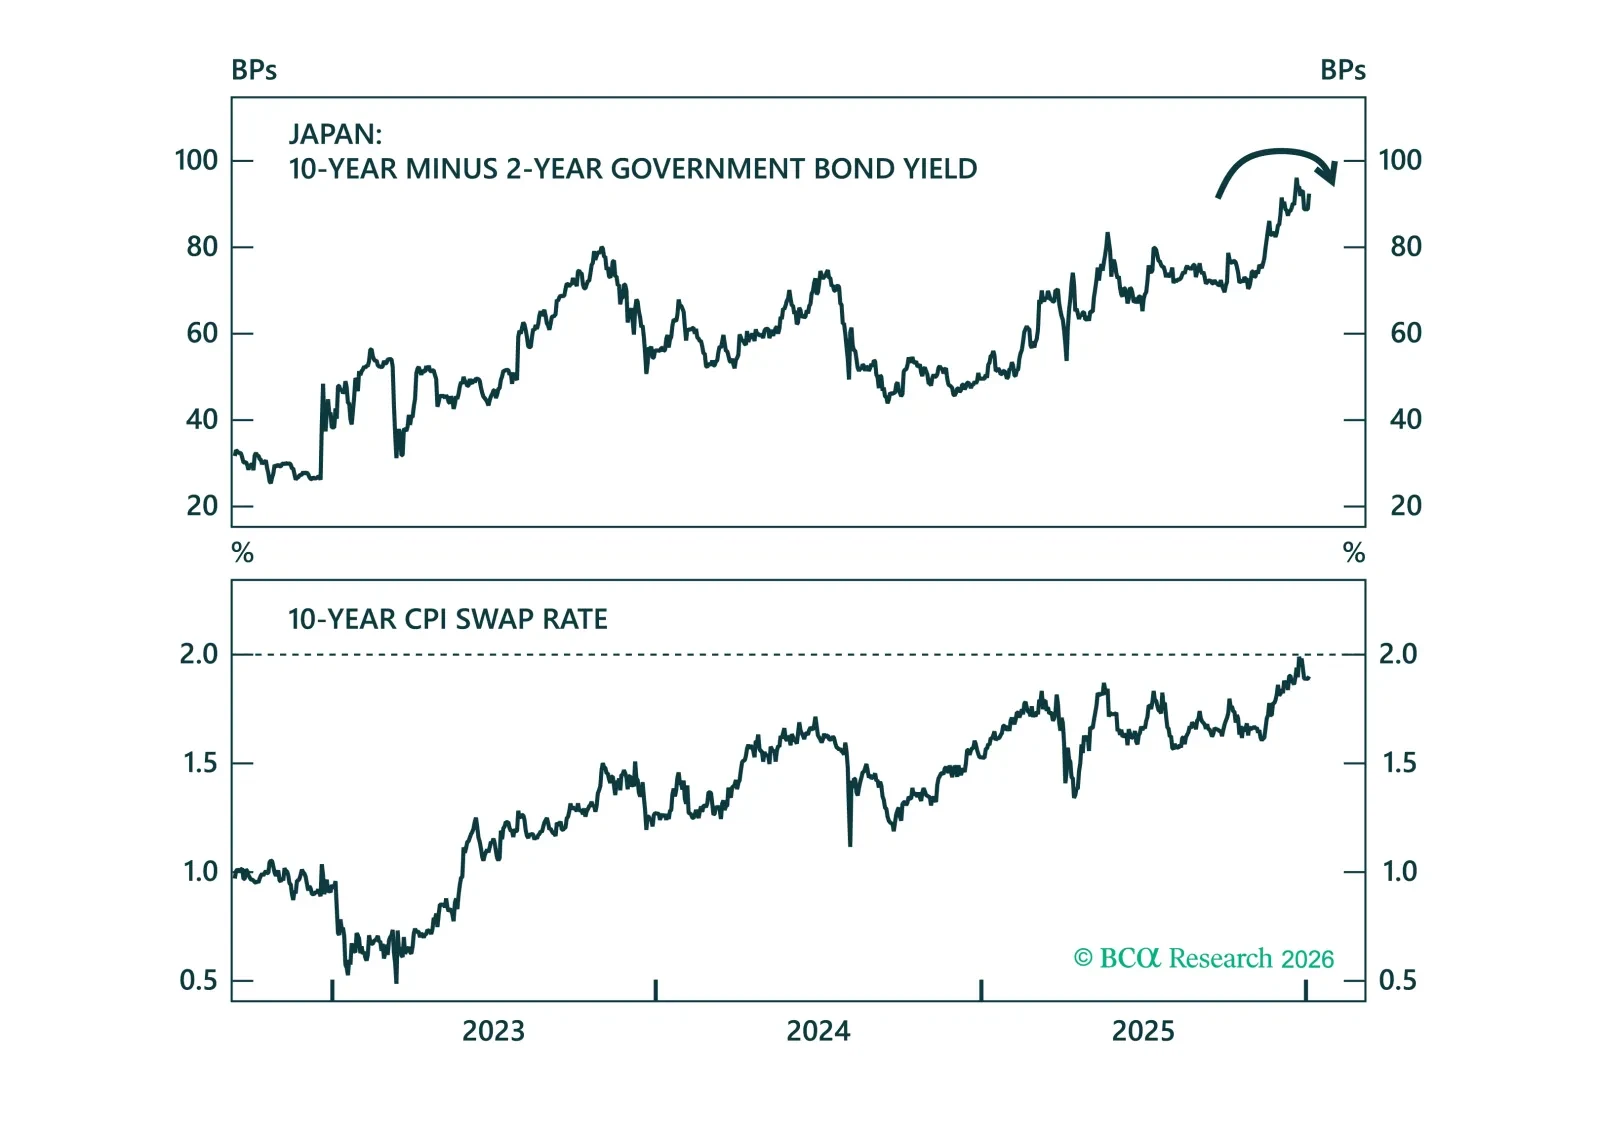
From steepening to flattening. As the BoJ continues to tighten in 2026, we show why curve flatteners are finally the right trade.

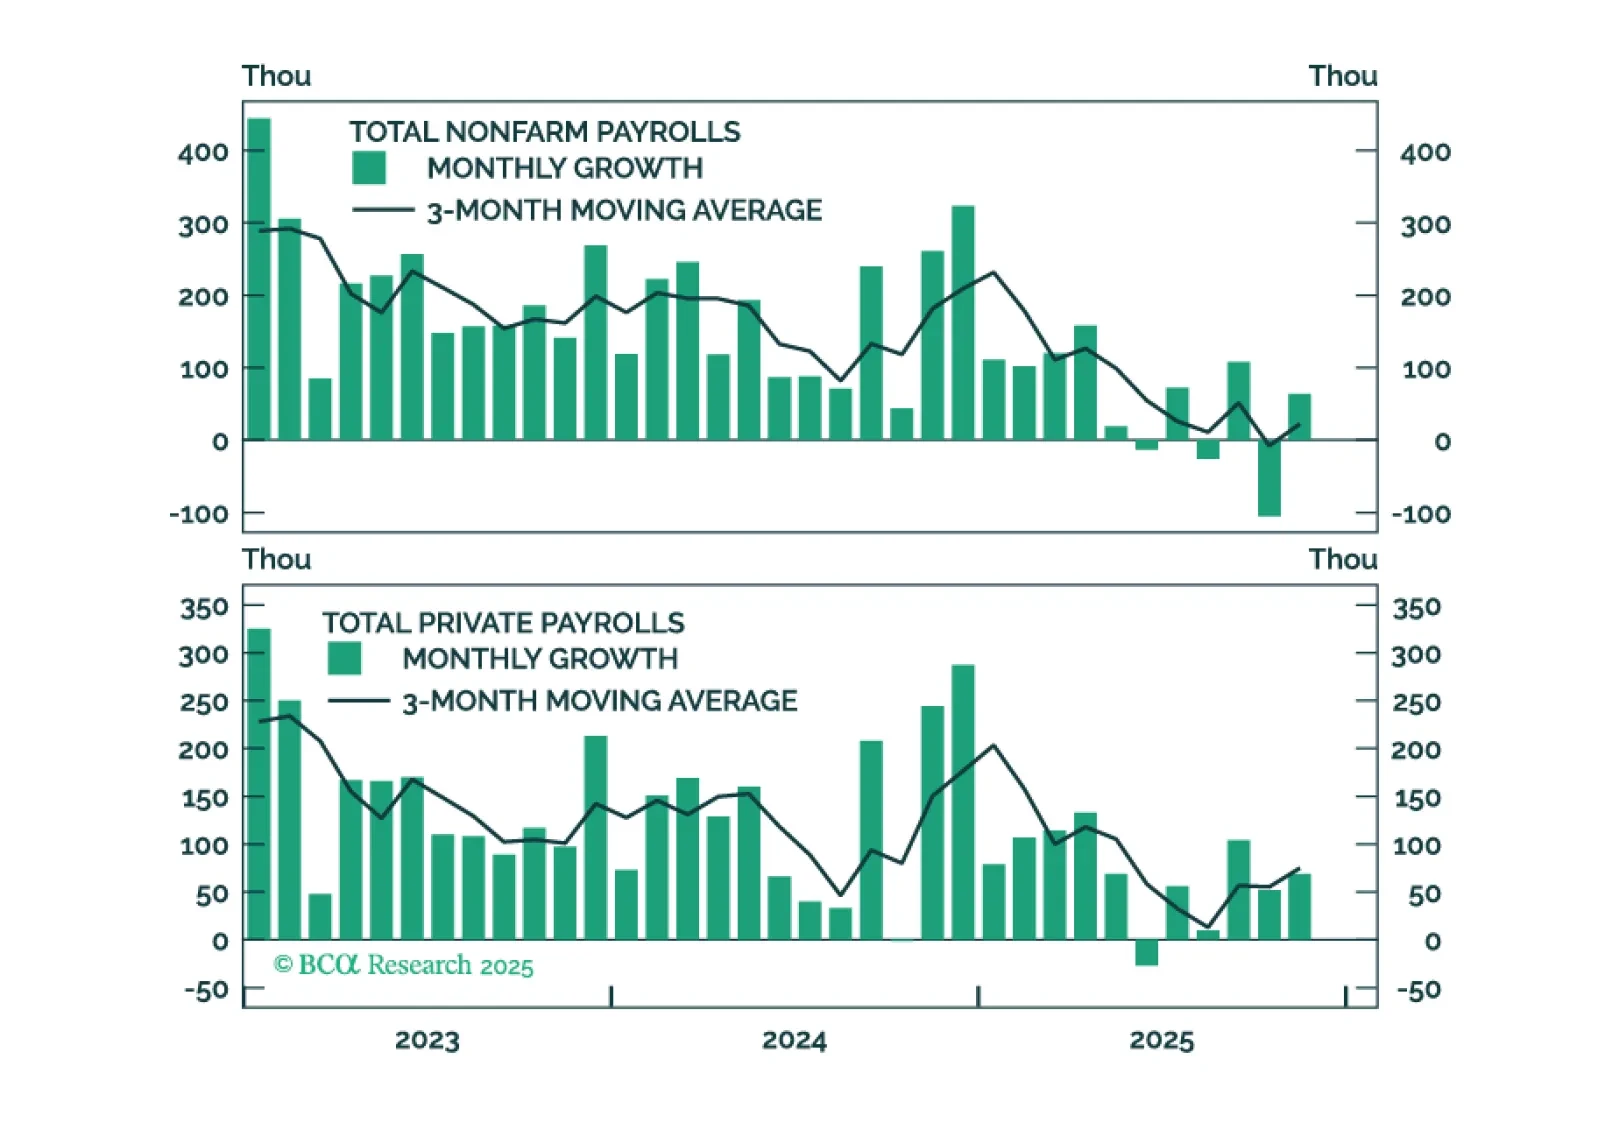
Employment Data Point To Dovish Policy Surprises In 2026