
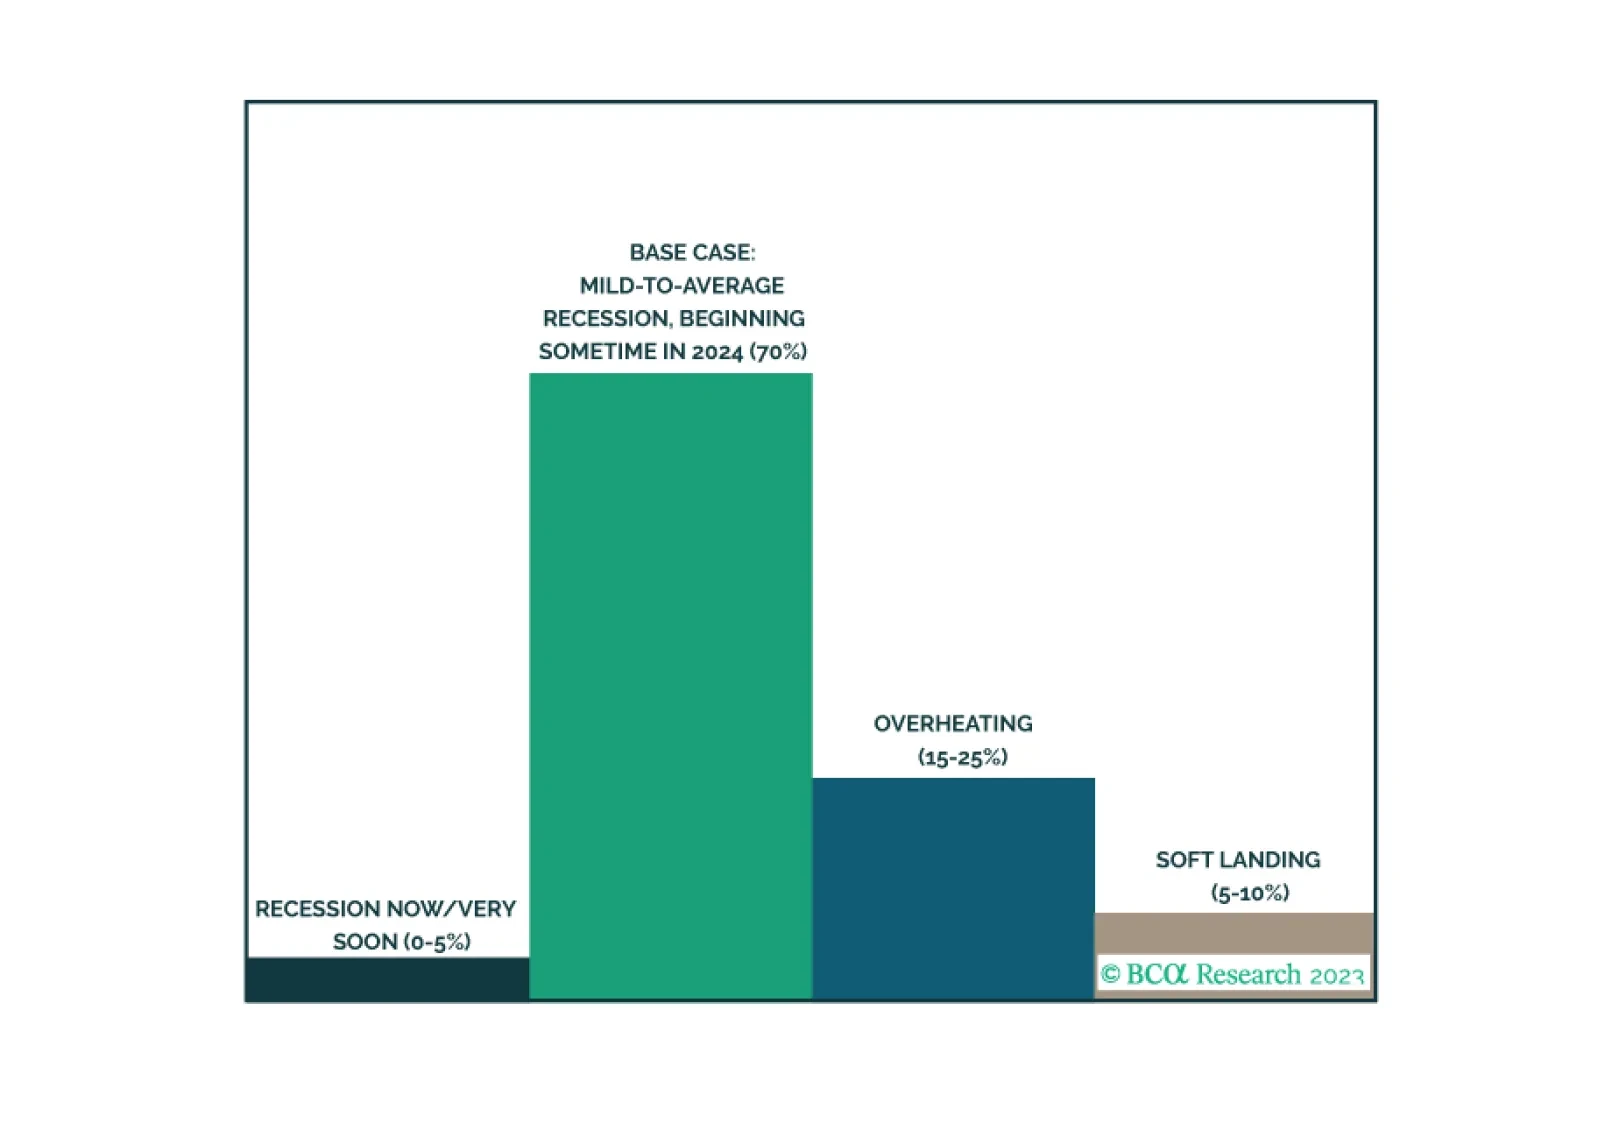
Our last publication of 2023 is an illustrated guide to our view that the economy will enter a recession around midyear. We expect equities will underperform Treasuries and cash over much of 2024, but we are waiting to turn tactically defensive until more investors are drawn into the soft-landing camp, capping the equity rally.
The soft-landing narrative has gotten nowhere at BCA but appears to be making some headway with broker-dealers and investors. We are preparing to lean against it once it pushes equity prices a little higher.
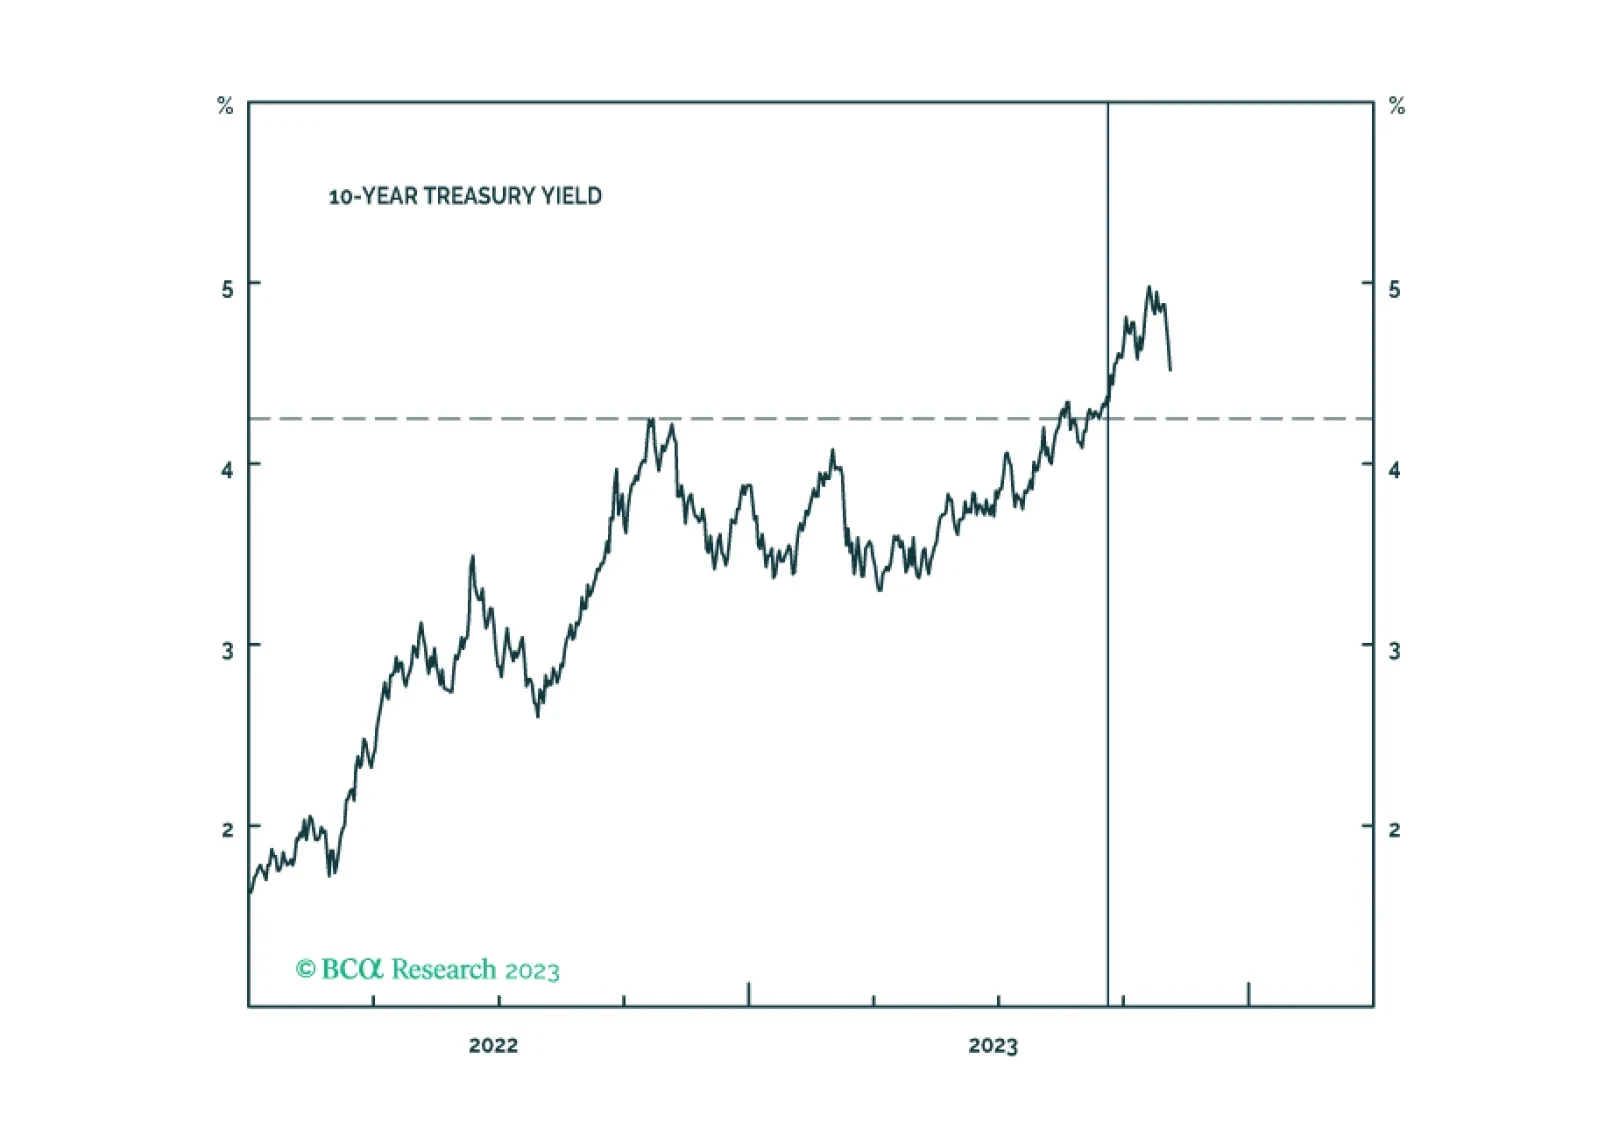
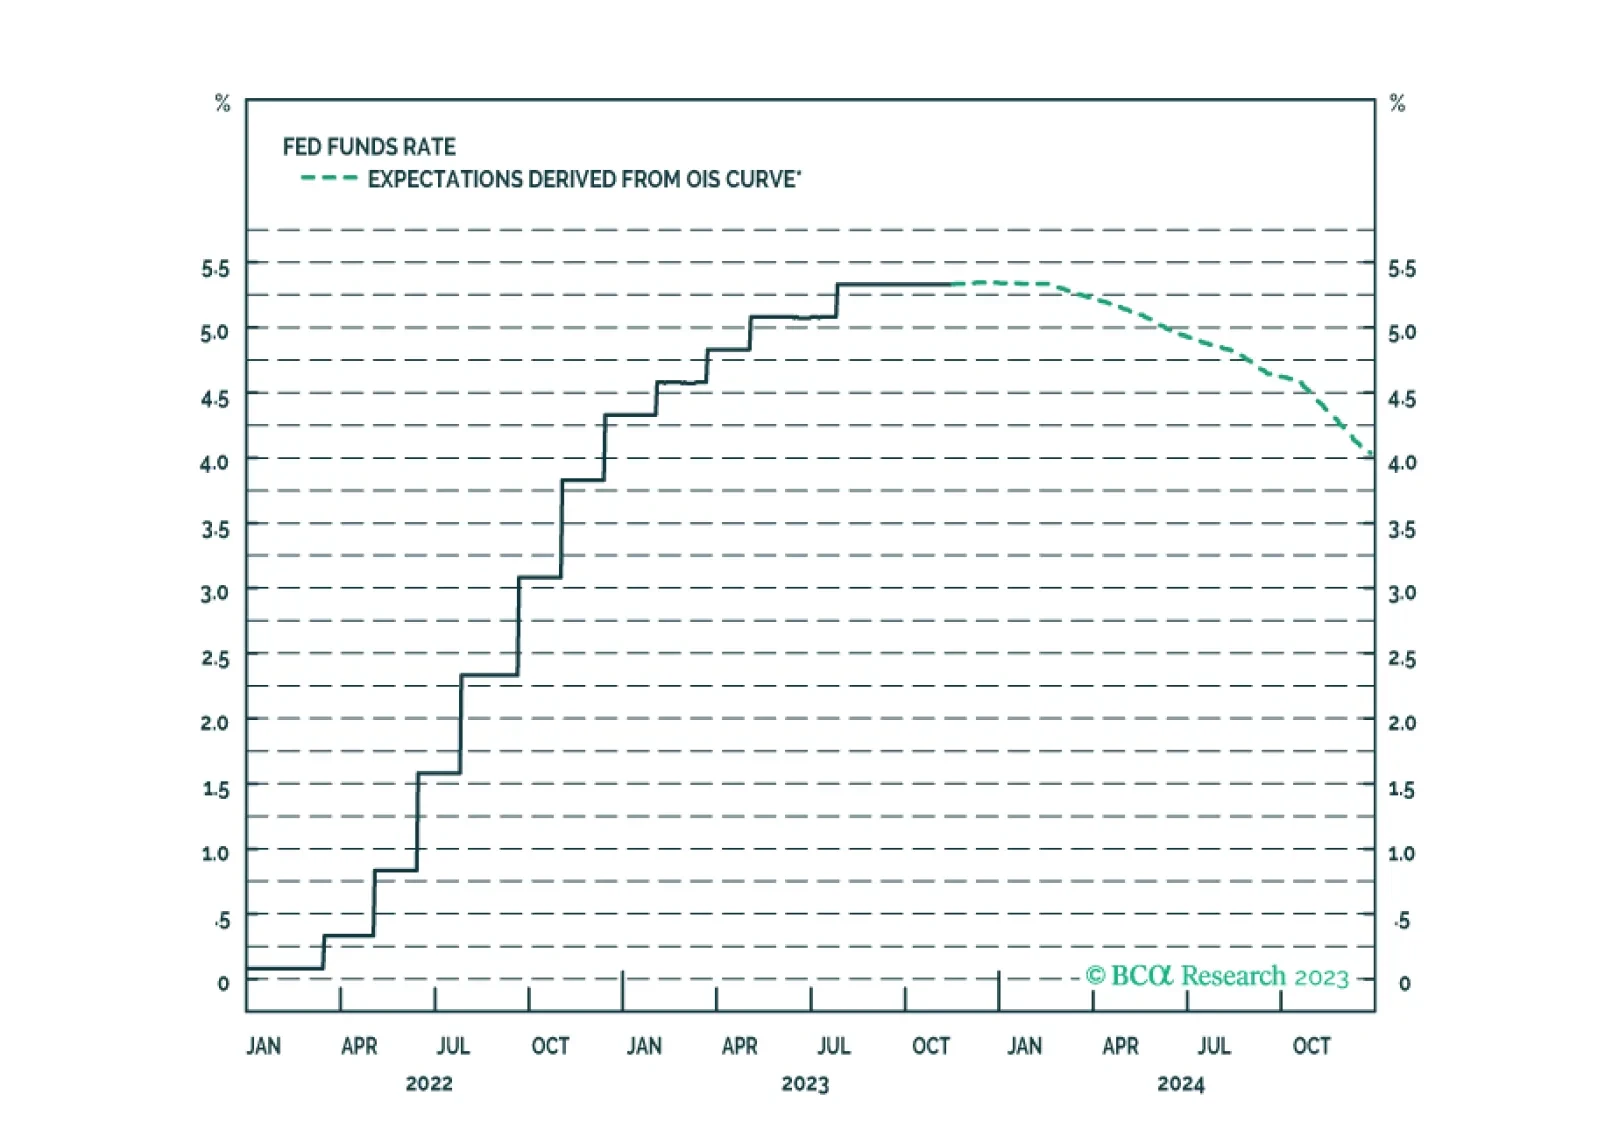
We consider several uncertainties in this week’s report, from the interest rate outlook to the source of the mountain of cash households have amassed since the pandemic began. We have not adjusted our tactical asset-allocation recommendations but will do so soon to align with the defensive cast of our cyclical recommendations.
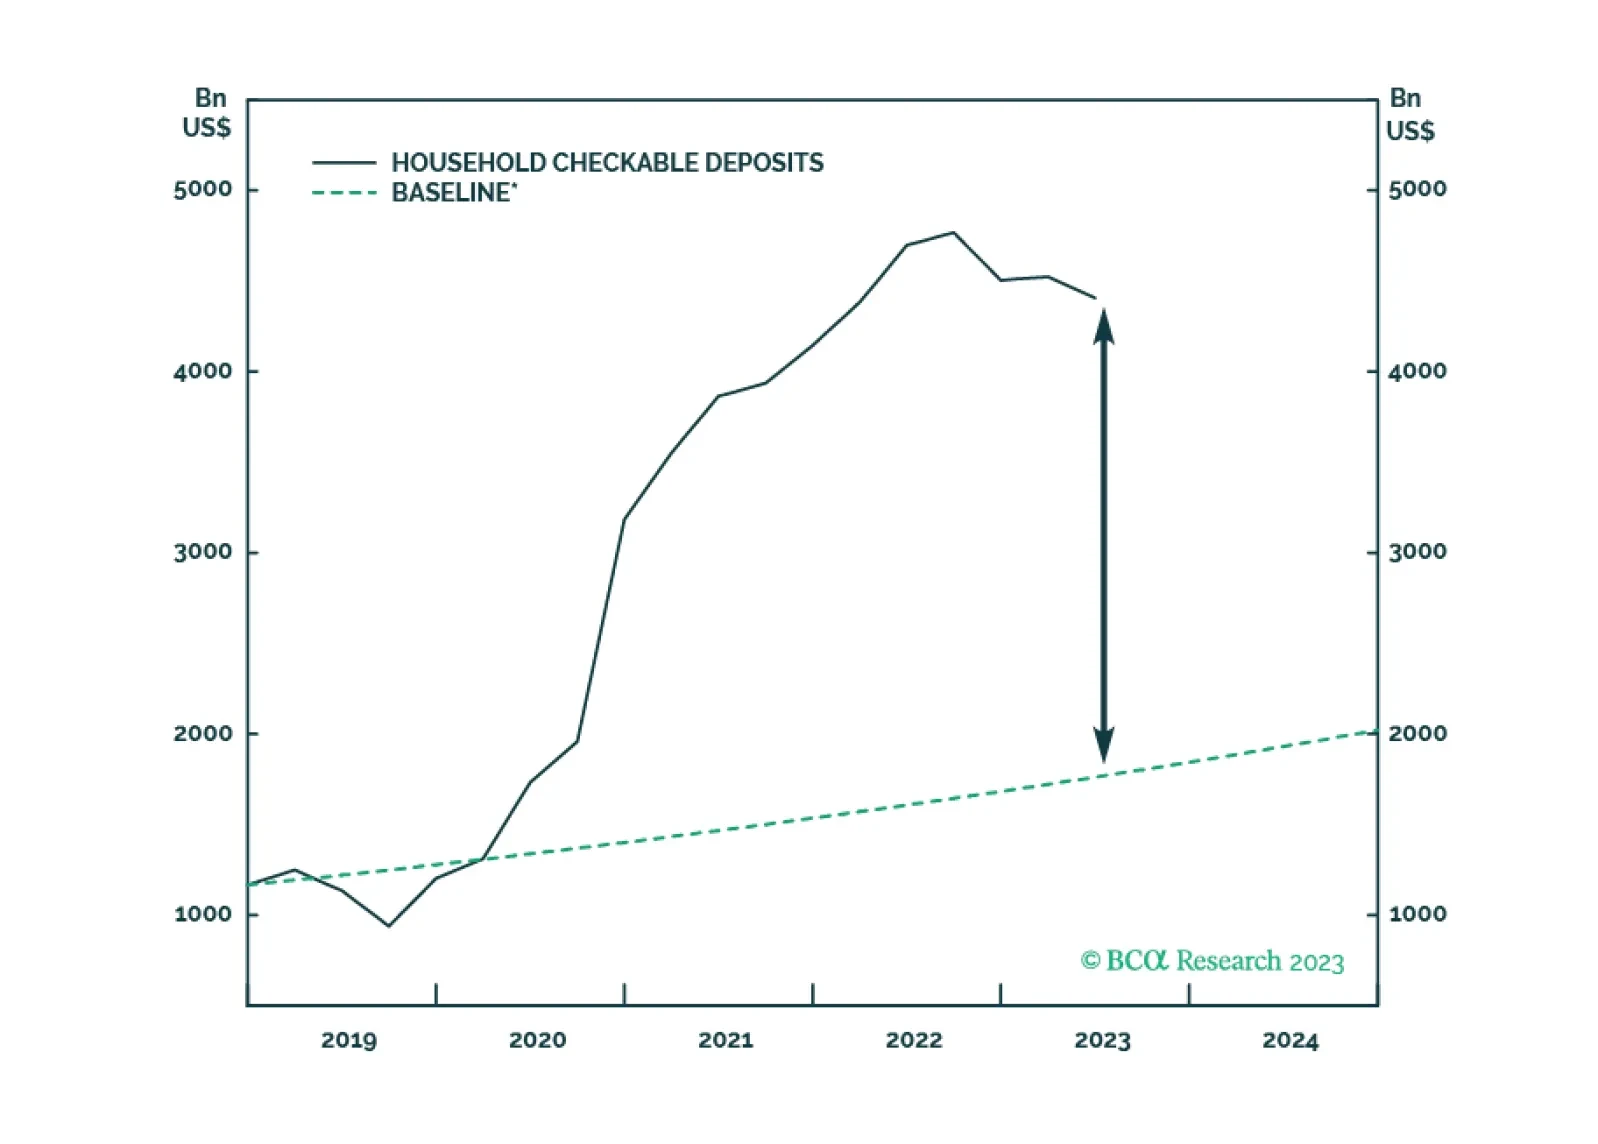
The biggest banks report that consumer credit card delinquencies still have yet to get back to pre-COVID levels and other credit performance indicators, leading and lagging, remain solid. There is still a great deal of cash sloshing around the banking system, though consumption has clearly slowed. We reiterate our view that a recession is coming, but not before the year is out.
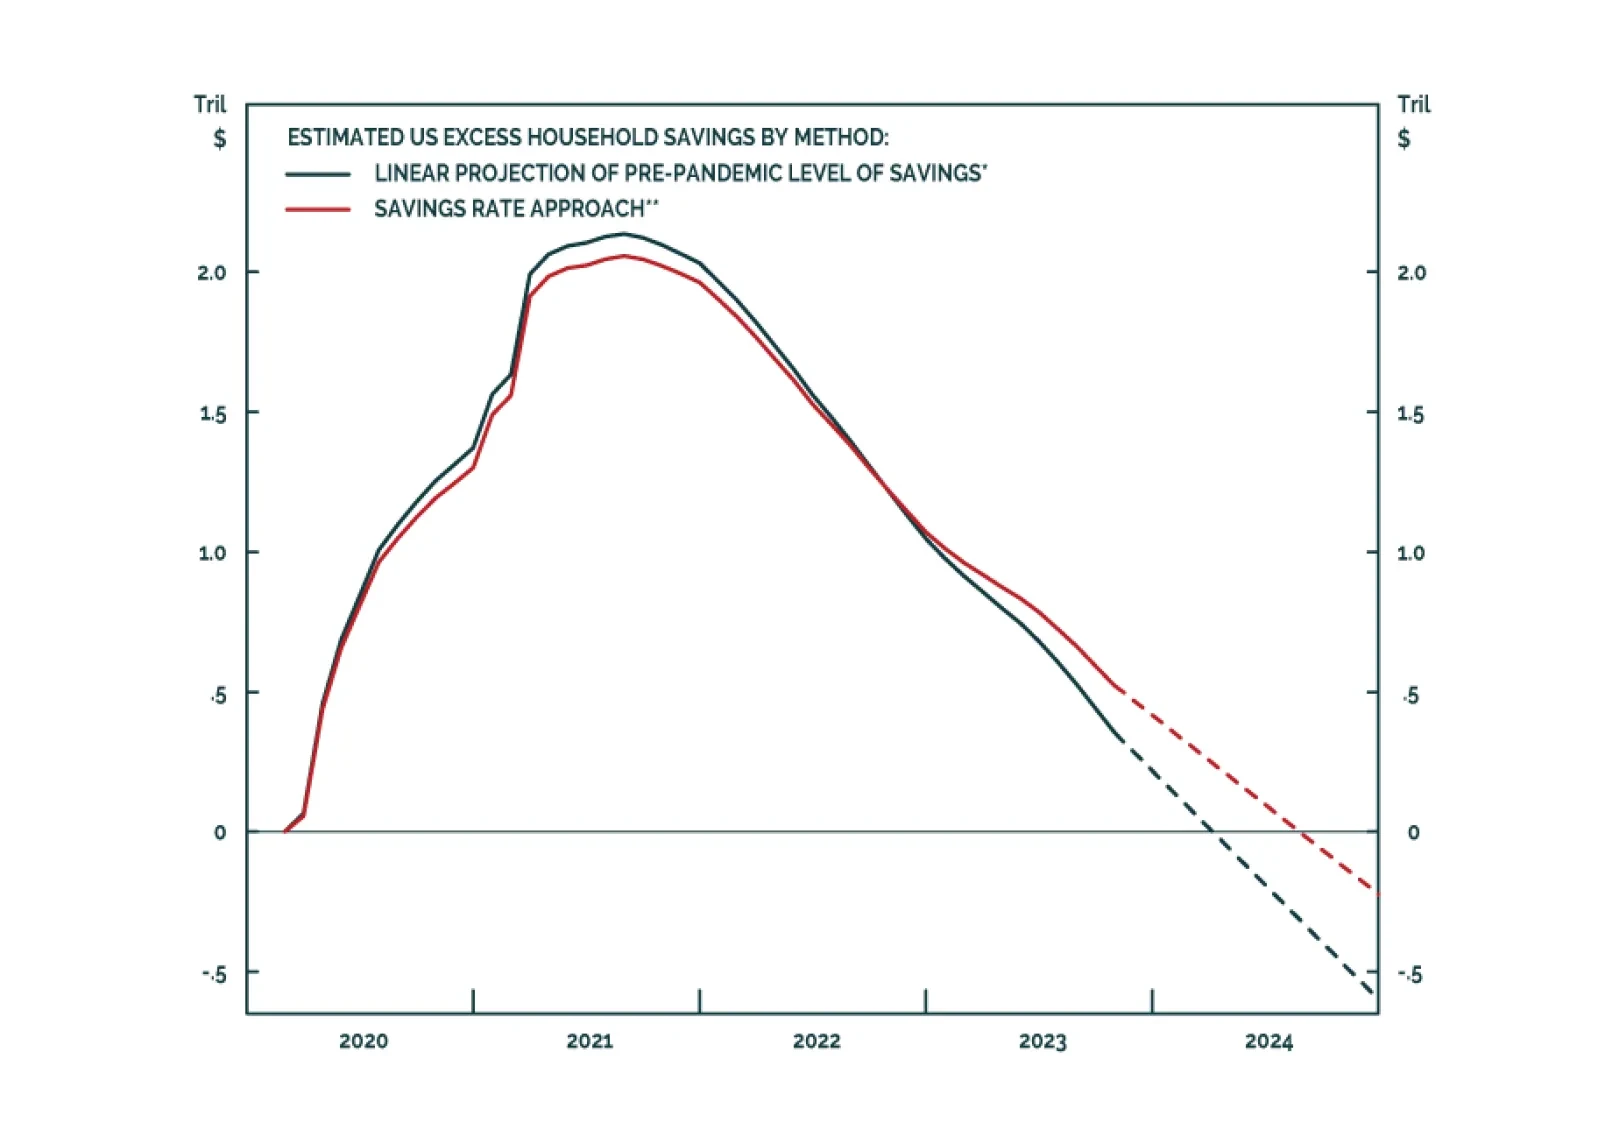
Households’ excess pandemic savings will eventually run out, but we continue to disagree with the widespread view that they’re already gone or entirely in the hands of the wealthy. Consumers’ demise continues to be greatly exaggerated.
Emergency pandemic fiscal and monetary policy measures buffered households and nonfinancial corporate businesses in ways that have acted to lengthen the lags between monetary policy changes and their effect on the economy. We believe, however, the extended lags are merely delaying the recession, not cancelling it. We expect to downgrade equities on a tactical basis from equal weight to underweight soon.
Magnificent Seven leadership is neither a new nor an unnatural phenomenon. There is no shortage of reasons why equities might have already made a top, but investors should not be tricked into thinking that the rally was somehow specious.
Today’s Strategy Report chartbook presents the data underpinning our view that both inflation and growth are slowing, likely pointing to a recession beginning sometime in the first half of next year. We are tactically equal weight across asset classes after being stopped out of our equity overweight on August 17th and expect our next move will be to underweight equities and overweight fixed income, in line with our twelve-month view.
Inspired by a client’s questions, we examine the rationale behind the implementation of the trailing stop governing our near-term asset allocation recommendations.