Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Labor Market

The Conference Board’s measure of consumer confidence surprised to the upside on Tuesday. The headline index improved to 102 from 97.5, upending expectations of a continued moderation to 96. The rebound follows 3 consecutive months of decline. The improvement…
At BCA Research, fundamentals drive our analysis and we use indicators and quantitative metrics as guides to inform our views further. It is our fundamental assessment of the US labor market that underpins our view that softer labor demand and decelerating…
According to BCA Research’s Global Investment Strategy service, there is only a narrow path to a soft landing. Our colleagues estimate a mere 20% chance that the US will avoid a recession before the end of 2025. The US unemployment rate is a highly…

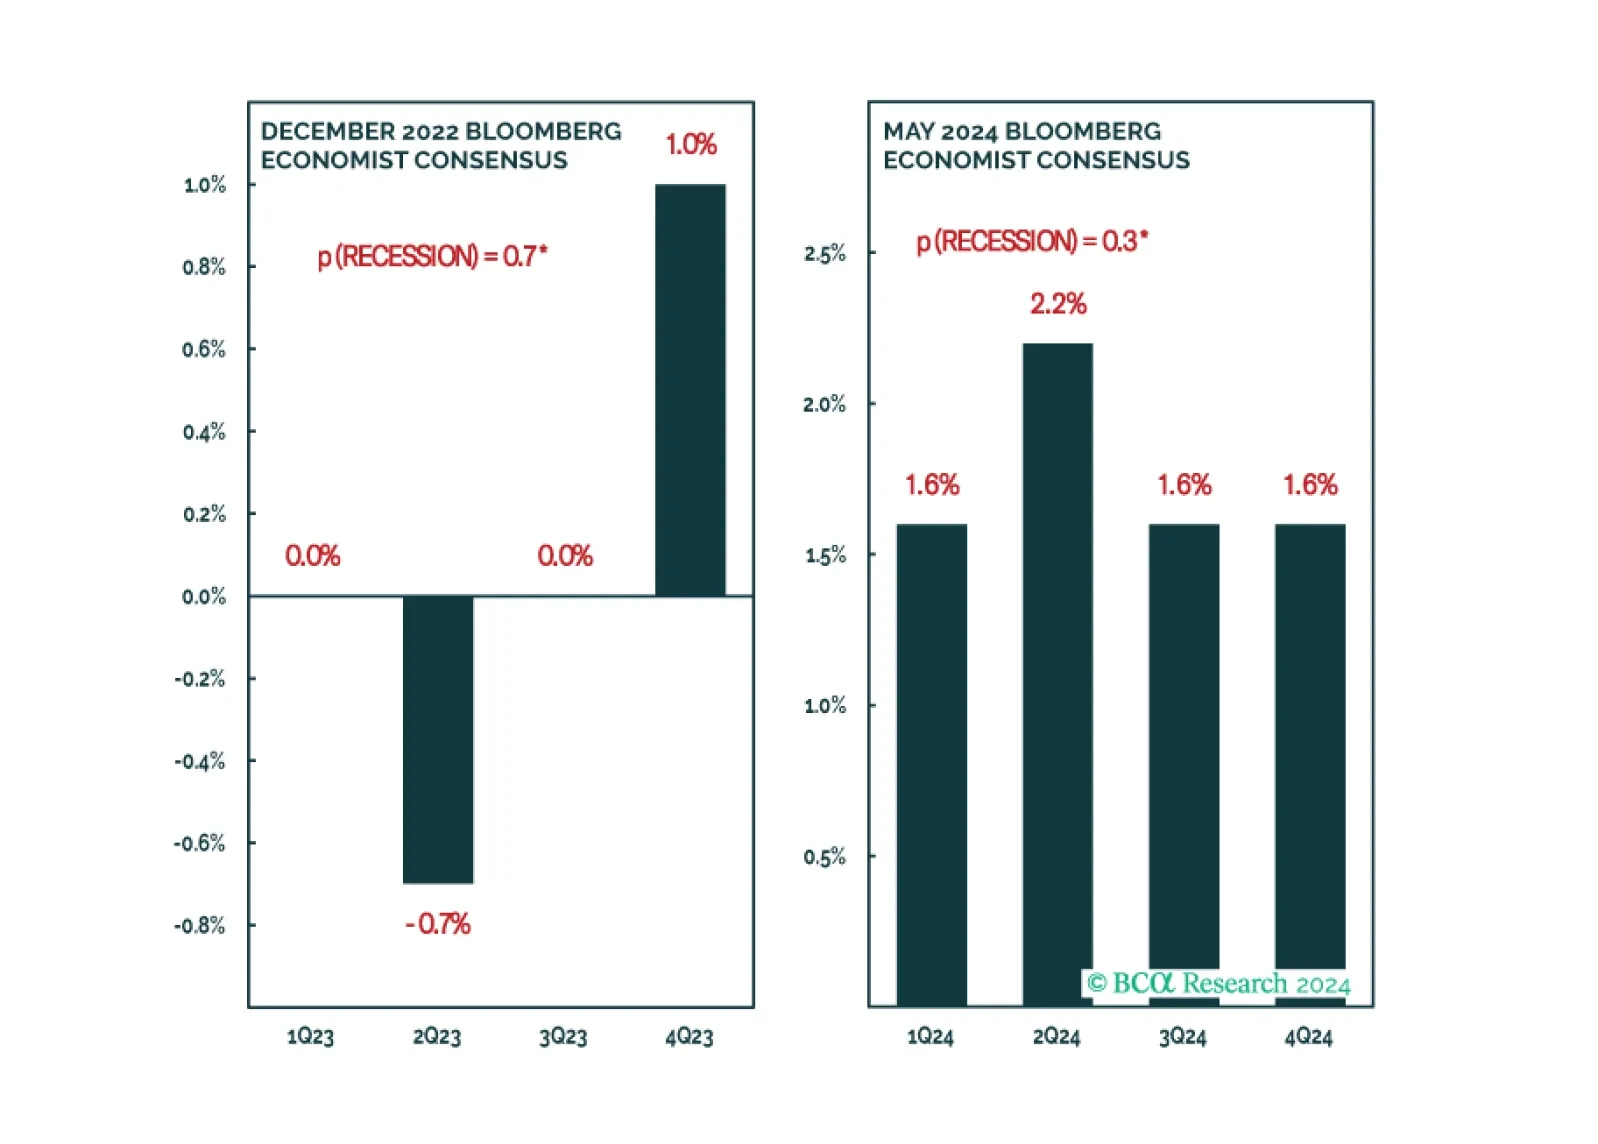
The signs of an approaching recession are starting to emerge. We will turn tactically defensive once they all fall into place.
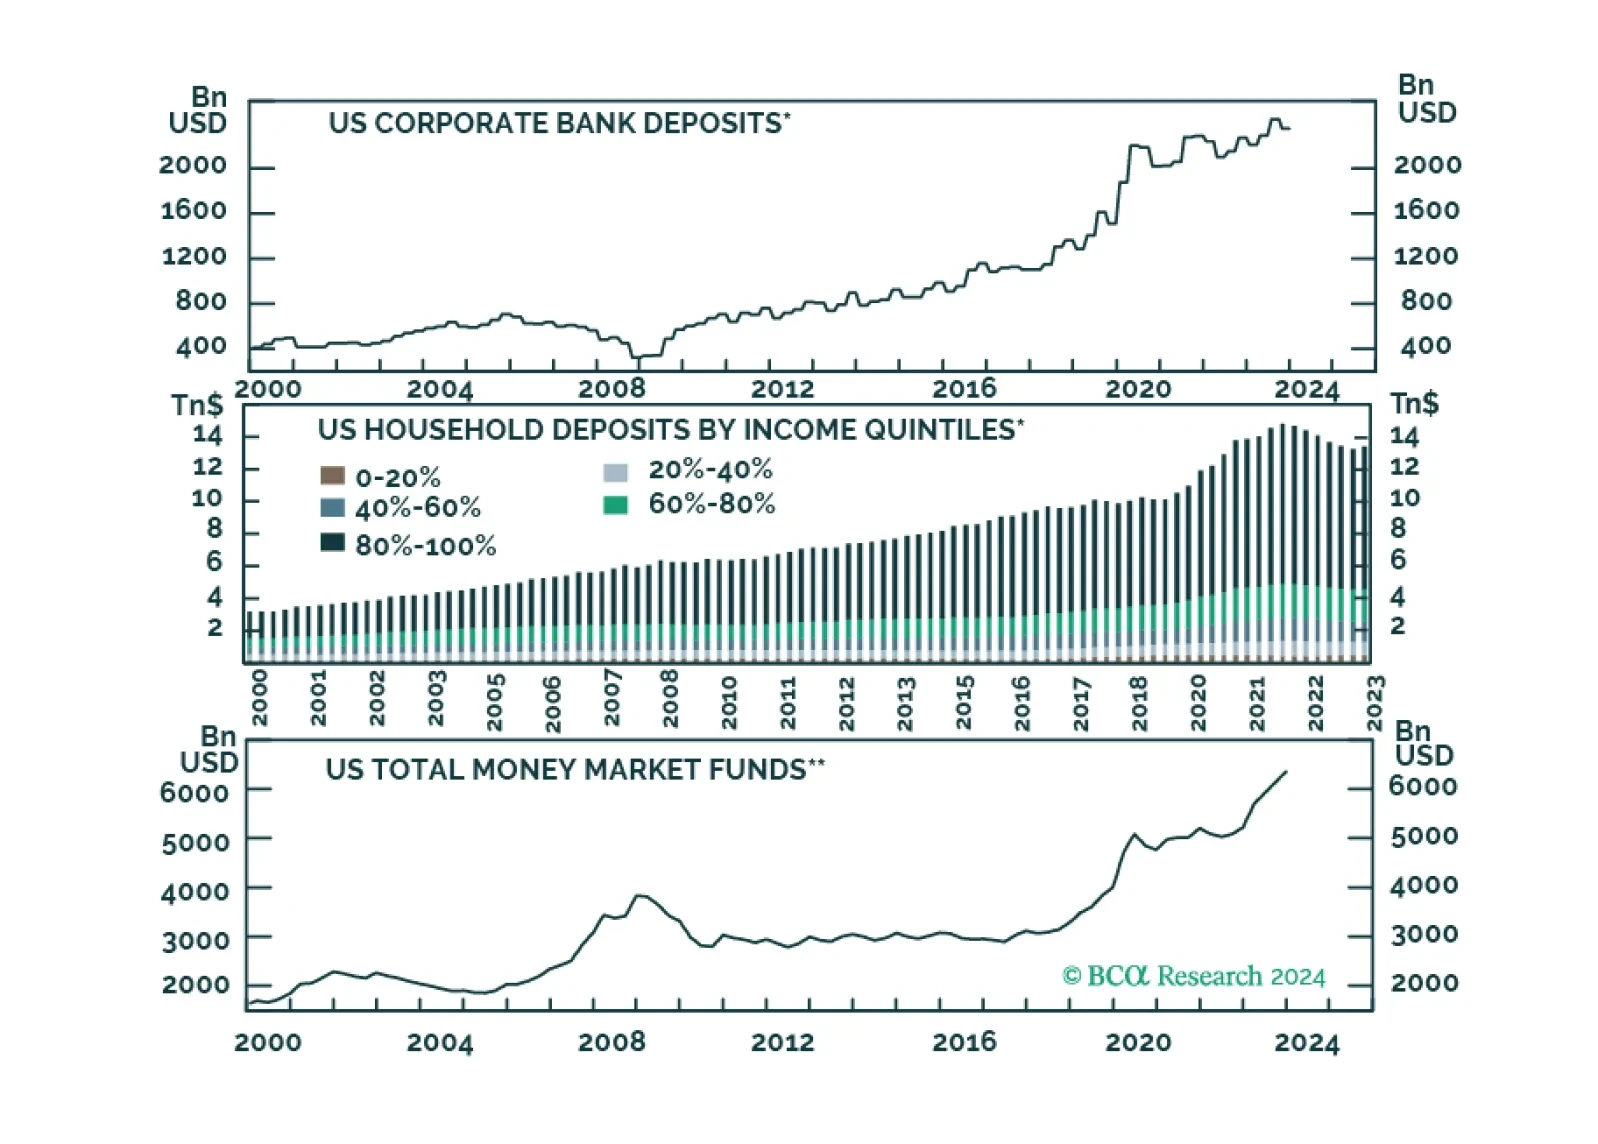
Looking at economic activity, global monetary policy seems restrictive, however, the behavior of financial markets tells a different story. What gives?
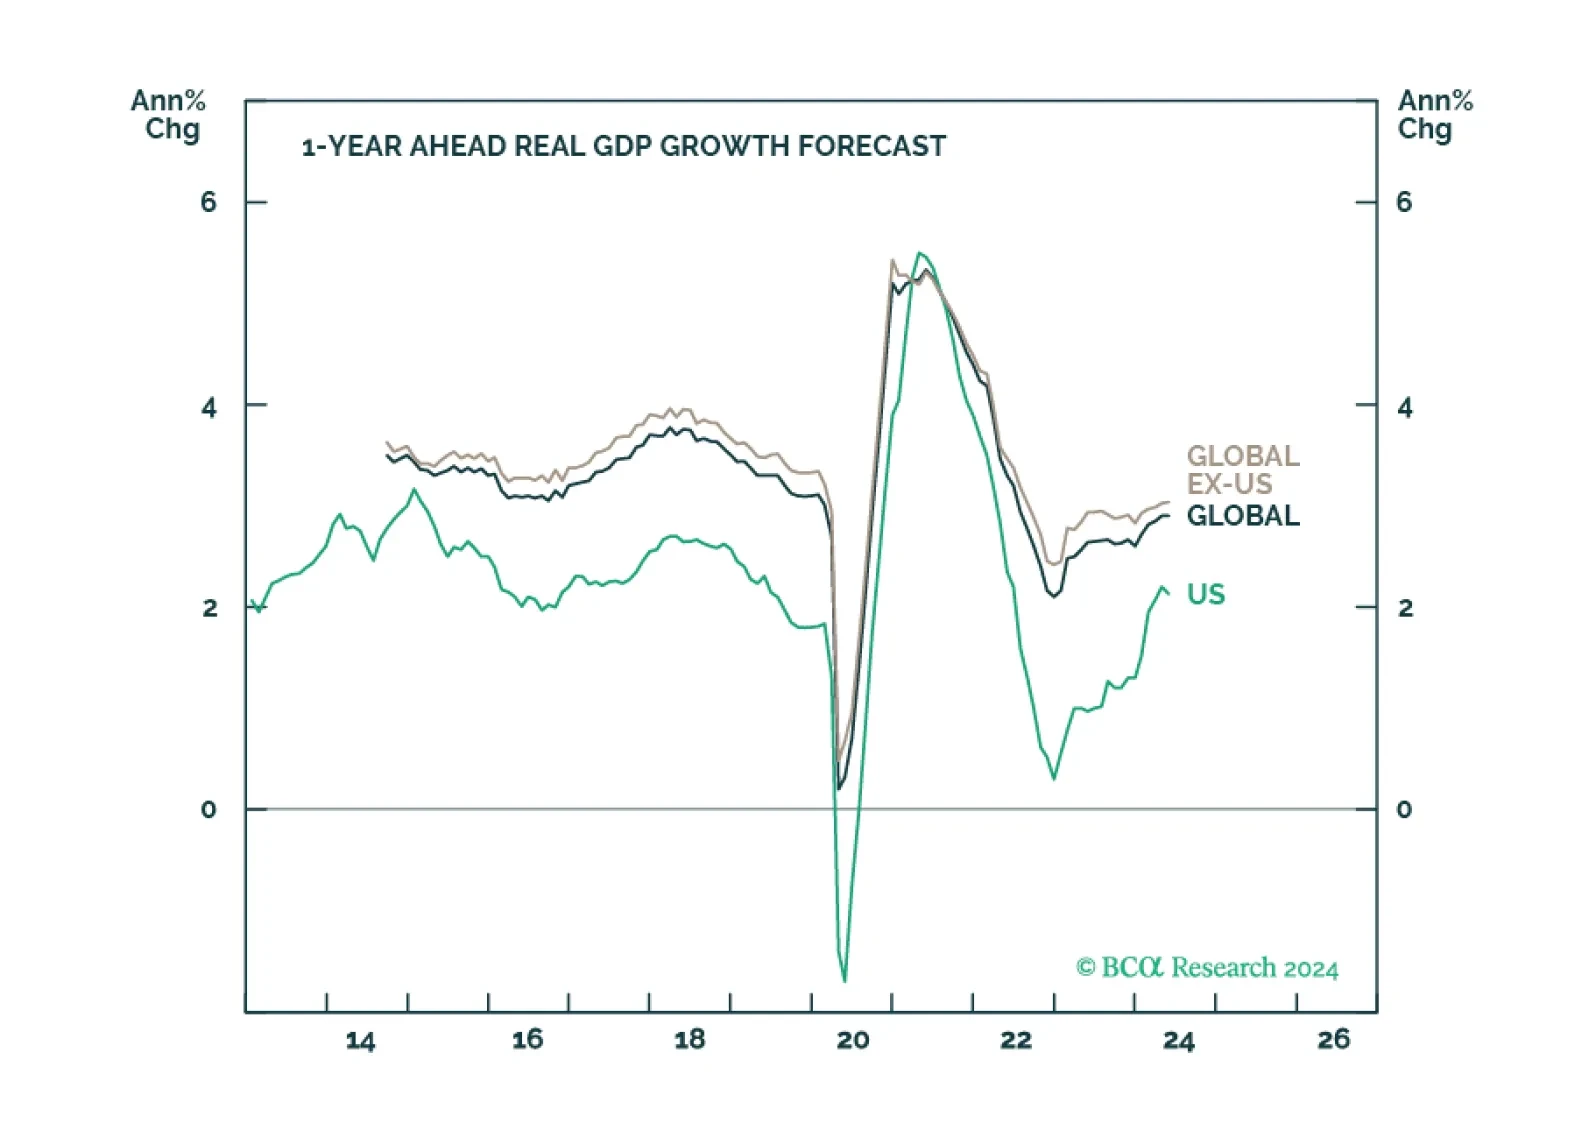
There is a path to a soft landing, but it is a narrow one. We estimate that there is only a 20% chance that the US will avoid a recession before the end of 2025. We are currently neutral on global equities, but expect to downgrade stocks to underweight during the summer.
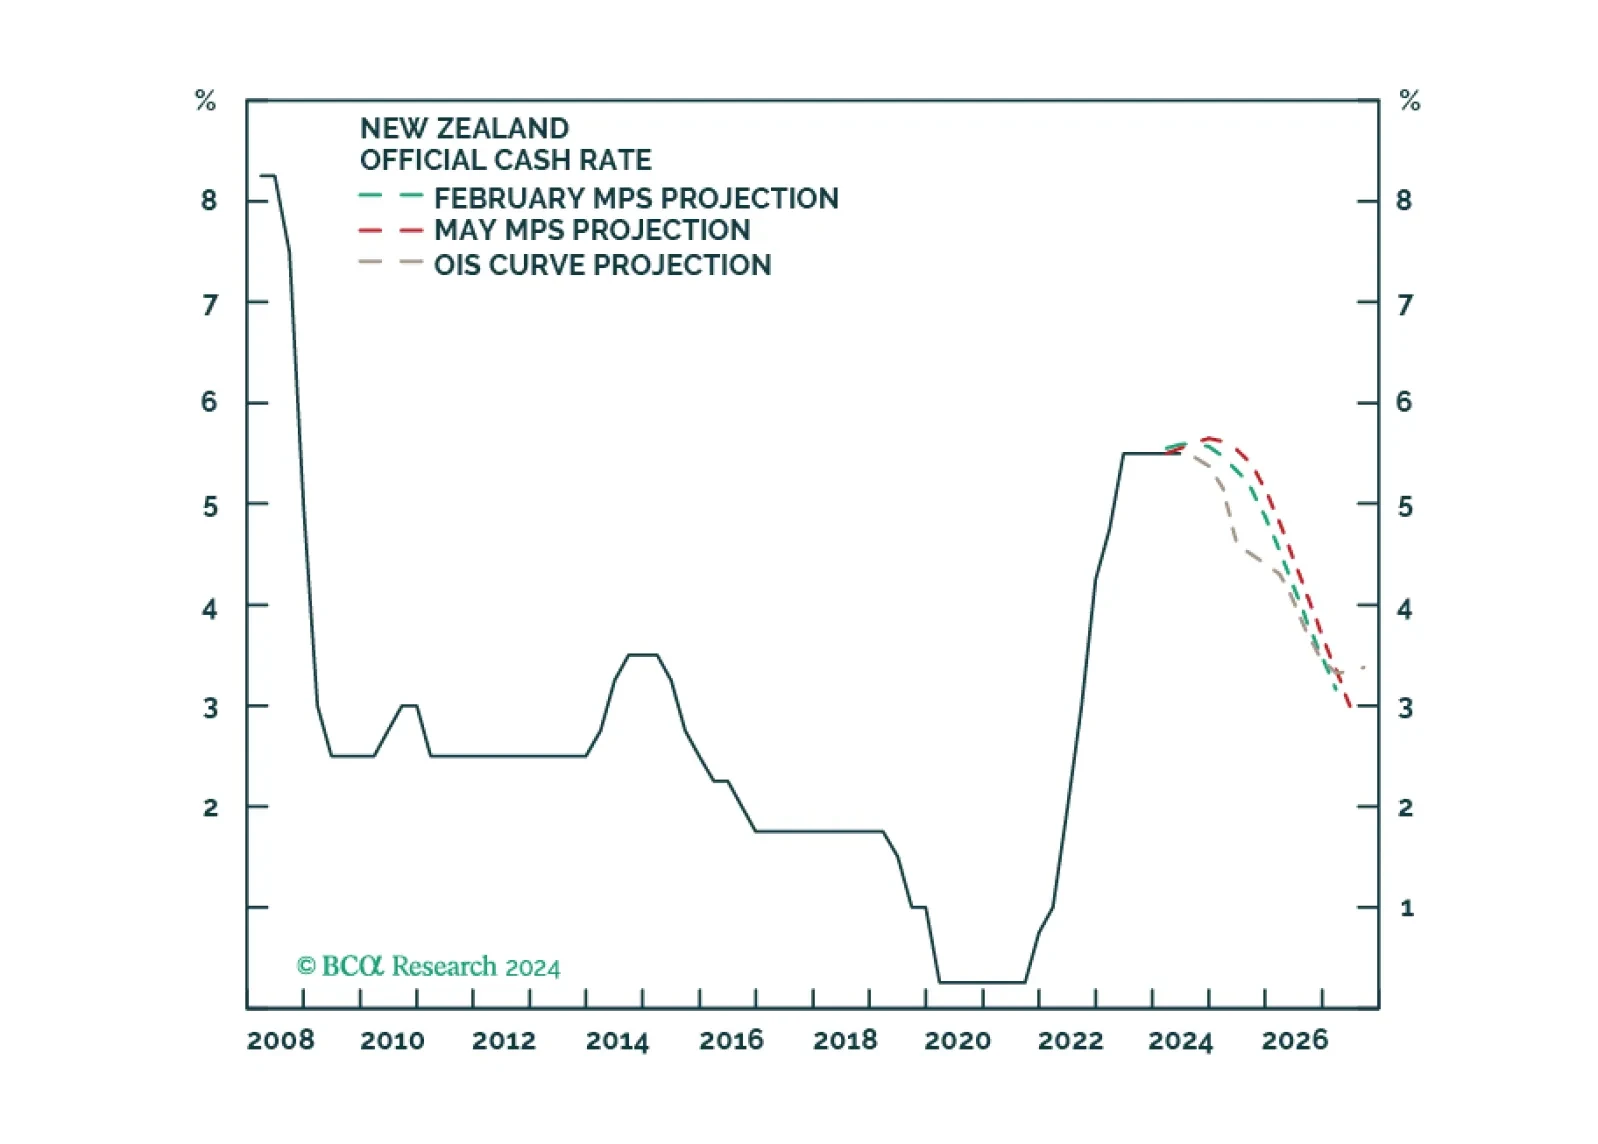
The Reserve Bank of New Zealand (RBNZ) kept interest rates on hold at this week’s monetary policy meeting, in line with expectations. However, there were three new notes from its monetary policy statement that will likely affect how it approaches future…
Negotiated wages rose 4.7% y/y in Q1, from 4.5% y/y in Q4 in the Eurozone. Meanwhile, preliminary estimates for the Eurozone Composite PMI surprised to the upside in May. Although wage growth is the main driver of services inflation and Euro Area economic…
Preliminary estimates suggest that manufacturing activity generally improved across DM economies in May. Manufacturing PMIs for the US, the Eurozone, Japan and the UK all improved from their April levels. Notably, manufacturing activity started growing again…

In this Insight, we revisit our "higher for longer" theme for the Reserve Bank of New Zealand, in light of the latest central bank meeting. In conclusion, we are inching towards a more dovish RBNZ ahead. Ergo, we recommend some fixed income and currency trades.