High-Yield

Our Portfolio Allocation Summary for October 2024.
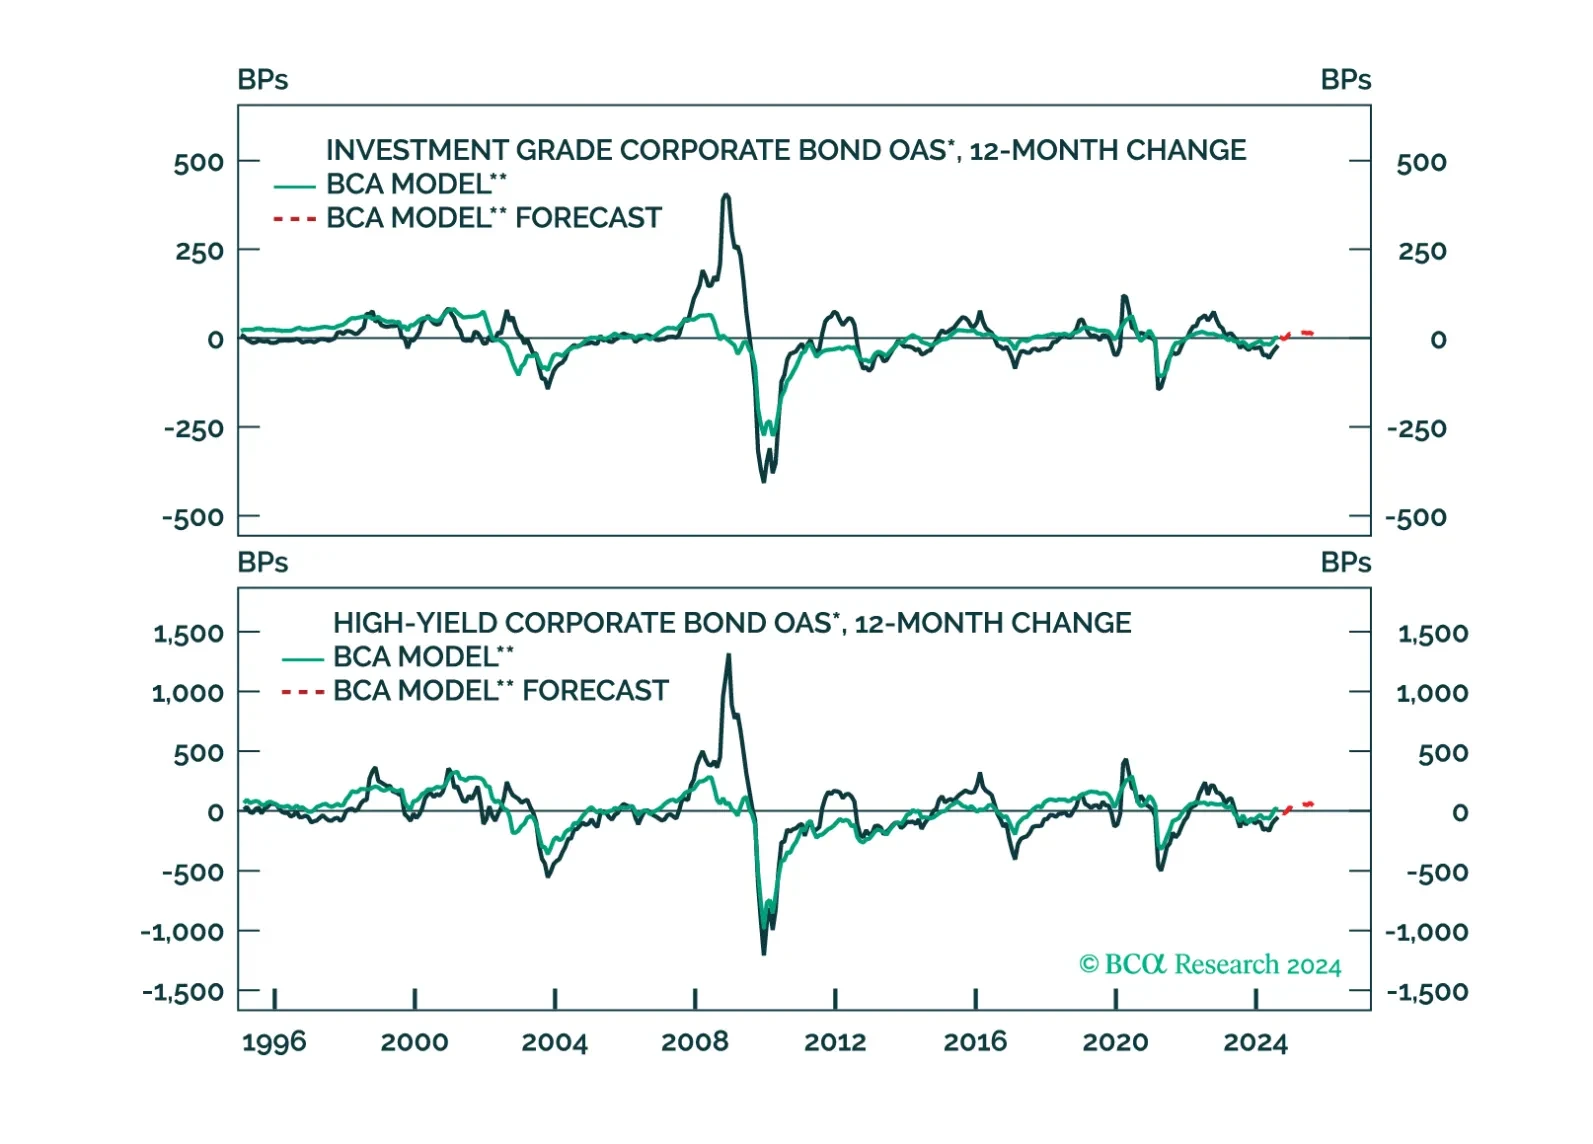
We update our corporate default rate model and consider the implications for corporate bond spreads.

The pro-cyclical Eurozone economy is highly exposed to a global downturn, which we expect will materialize by early 2025. The ECB is behind the curve and we thus expect it to ease more aggressively than markets expect next year. A dovish surprise in 2025 is…


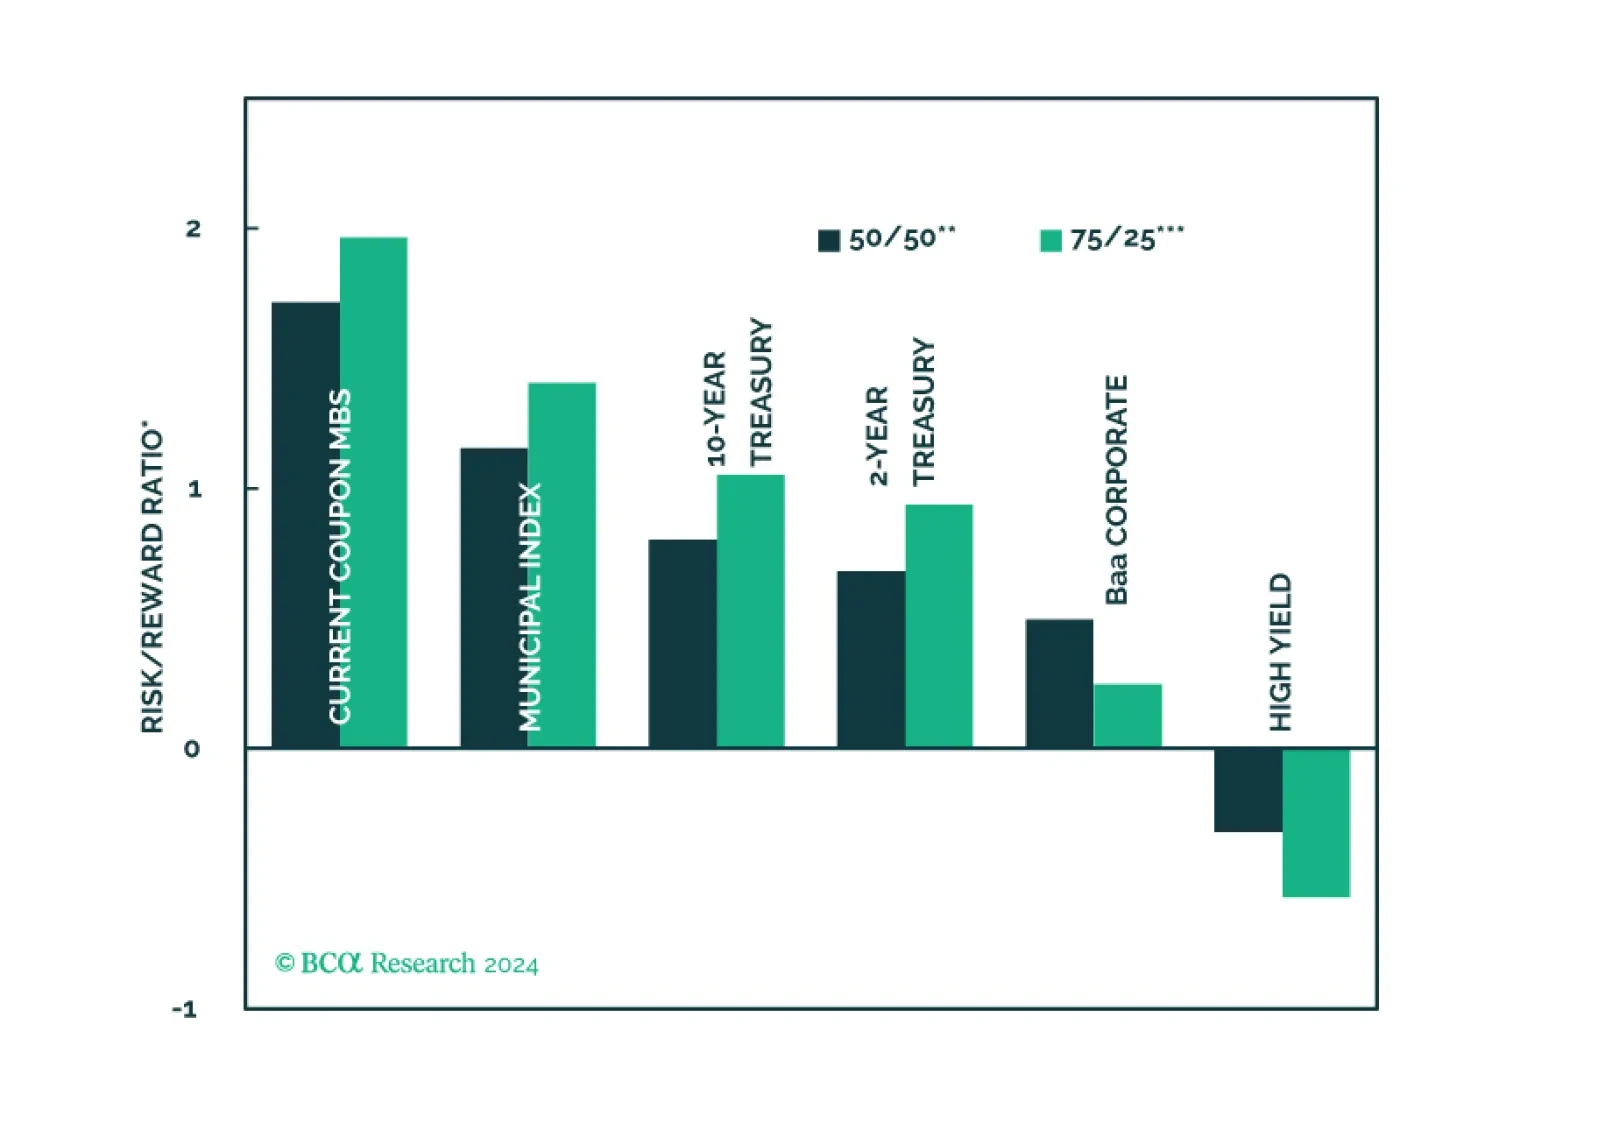
We calculate expected returns for several different US fixed income sectors with a focus on how municipal bonds stack up against the investment alternatives.
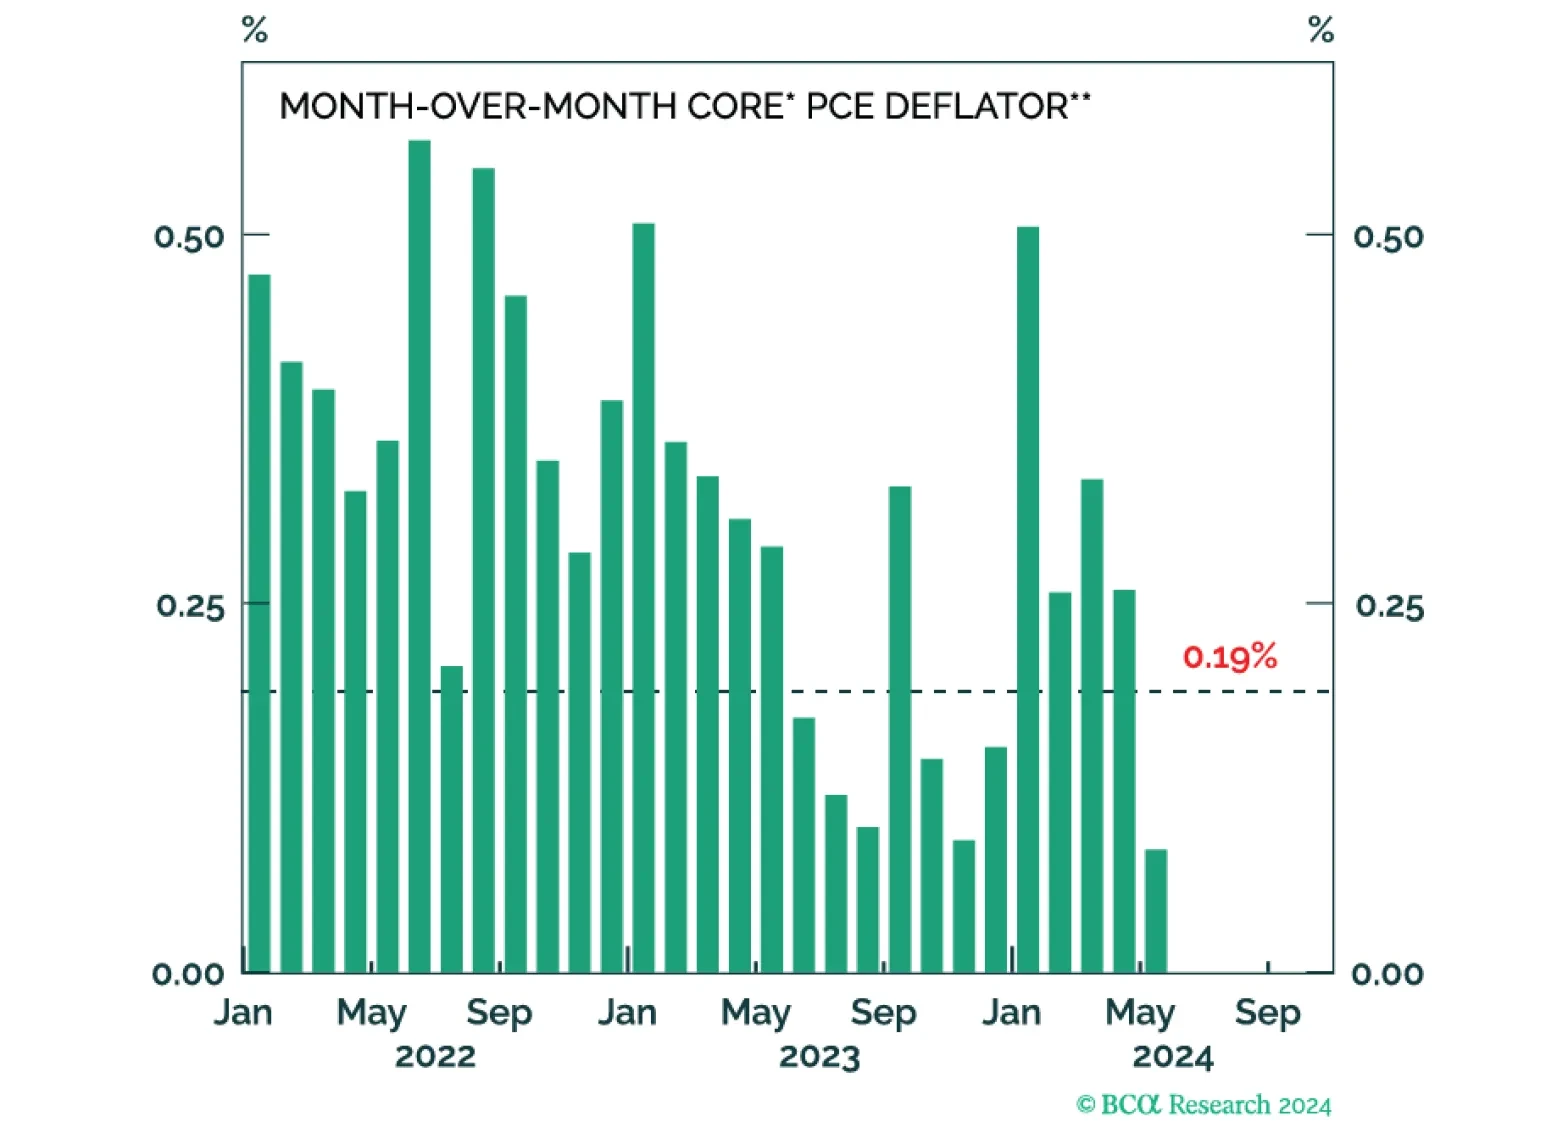
Corporate and junk bonds are the fixed-income sectors that are most exposed to an economic downturn. We’ve highlighted that markets continue to price in a Goldilocks scenario, with spreads narrowing despite ongoing deterioration in the labor market. Spreads…
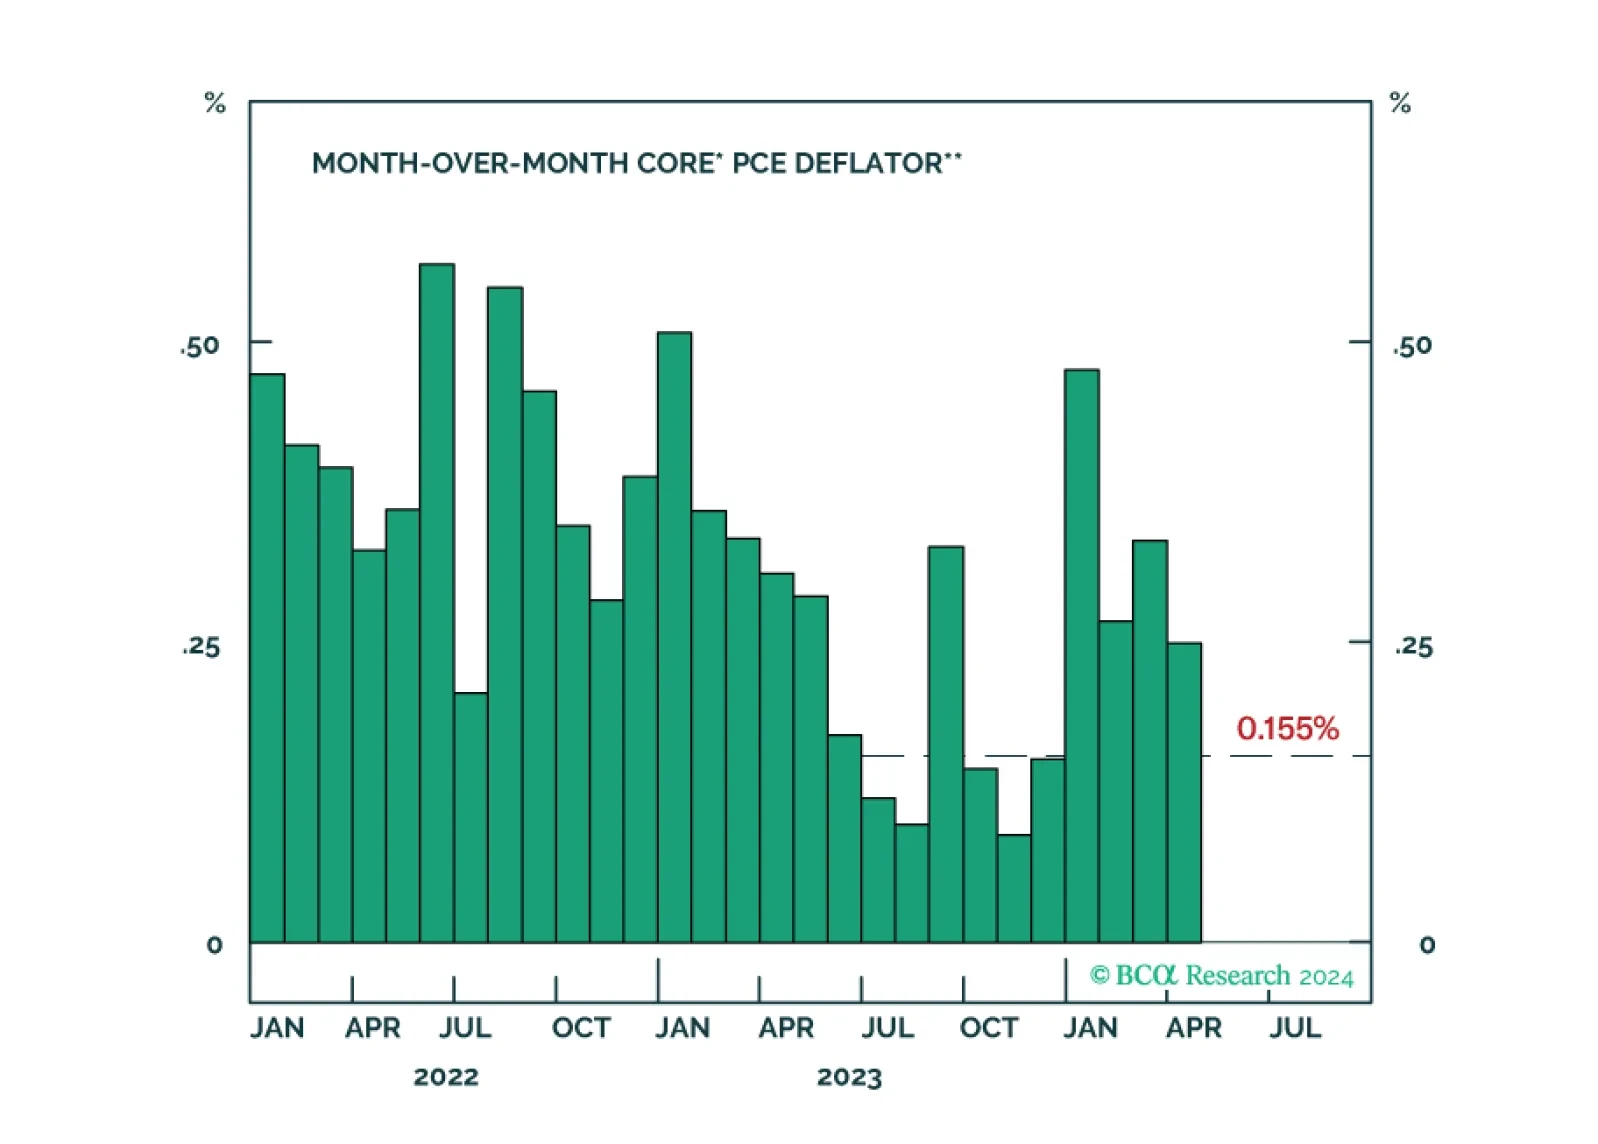
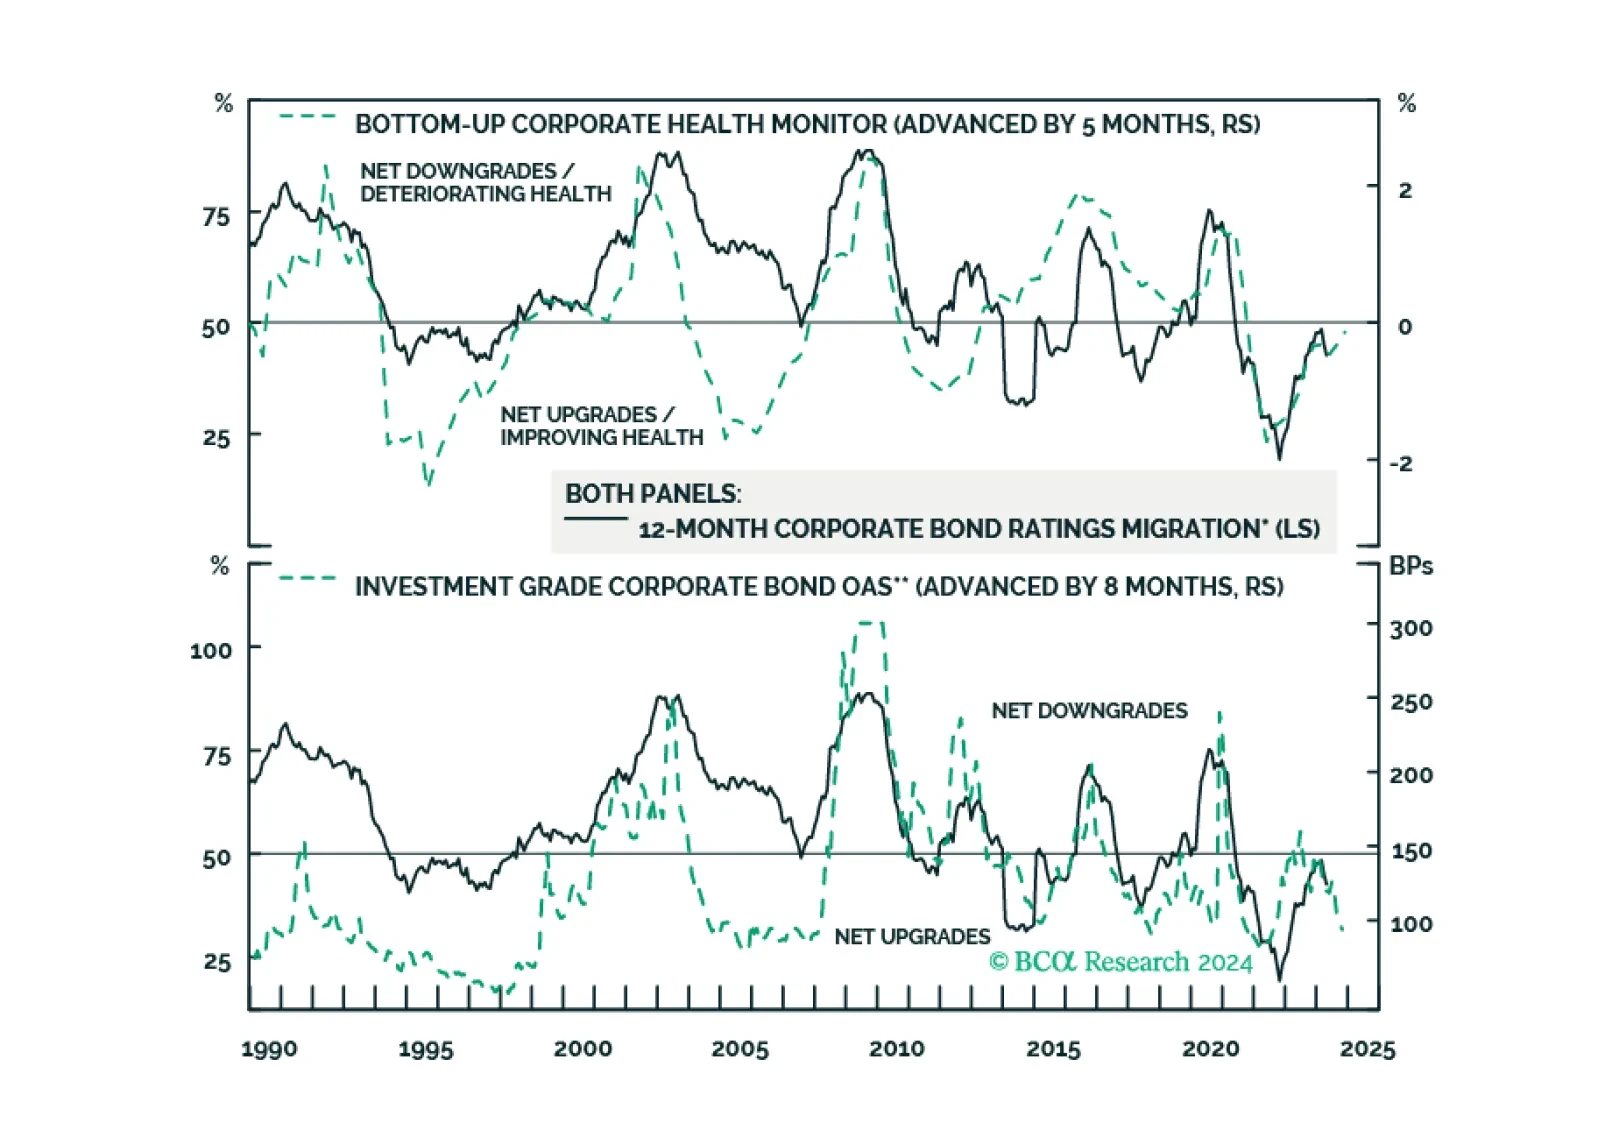
Nonfinancial corporate balance sheets are generally in good shape, but there are signs of deterioration at the bottom-end of the credit spectrum. We present evidence showing that credit deterioration at the bottom-end of the credit spectrum has a habit of migrating upwards.