Latest from BCA Research
The recent rebound is not a harbinger of a prolonged recovery in risk assets. The many potential negatives will keep volatility high and trigger further occasional selloffs.
The Treasury market is now discounting too slow a pace of Fed tightening, while junk spreads are discounting too rapid an increase in the default rate. This week we examine the risk/reward proposition of temporarily leaning against some prevailing long-run macro trends.
Inflation expectations in the Developed Markets have been adjusting down to the lower trend of actual inflation, although the bulk of this adjustment now appears complete.
China will neither propose nor support any coordinated initiatives among central banks on the RMB issue in G20 meetings this year. RMB bonds will prove attractive to foreign investors, given their higher yields and lower exchange rate volatility.
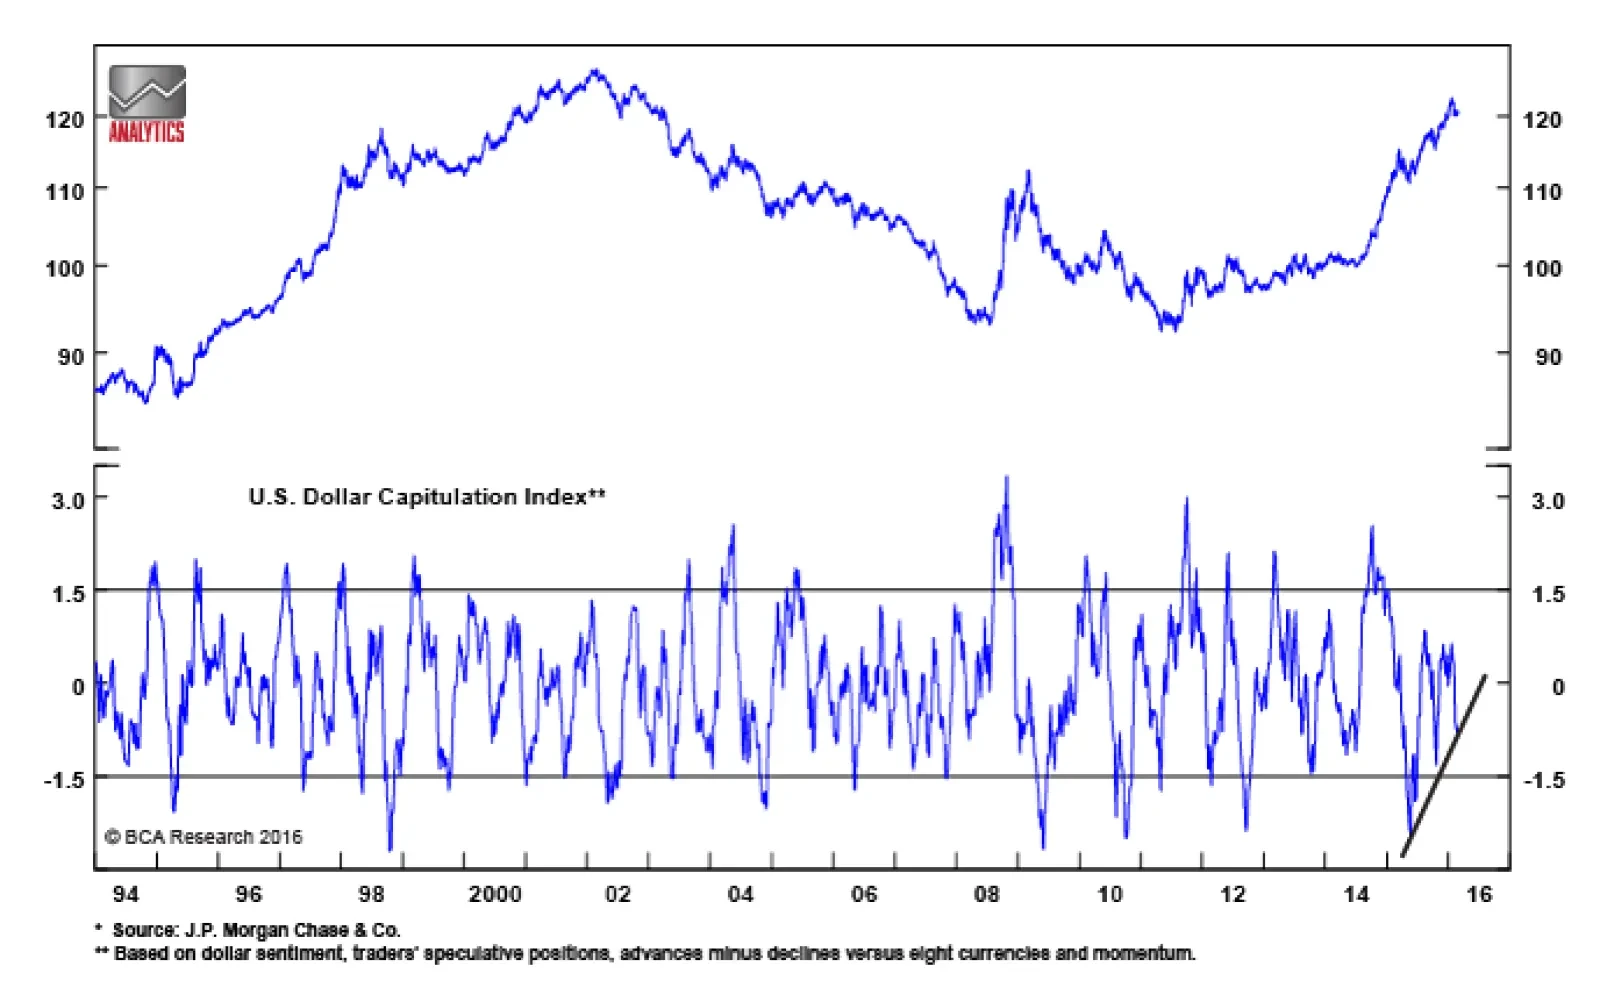
For the month of February, the model underperformed both global and U.S. equities. For March, the model has modestly pared back its equity risk exposure, shifting the allocation into bonds. While Europe remains the largest equity overweight, EM and Canada also received some allocation. The U.S. and New Zealand were slightly downgraded. In the fixed-income space, the model is sticking with Italy and Spain.