Latest from BCA Research
In this report, we review our trade recommendations based on incoming data in the last month.
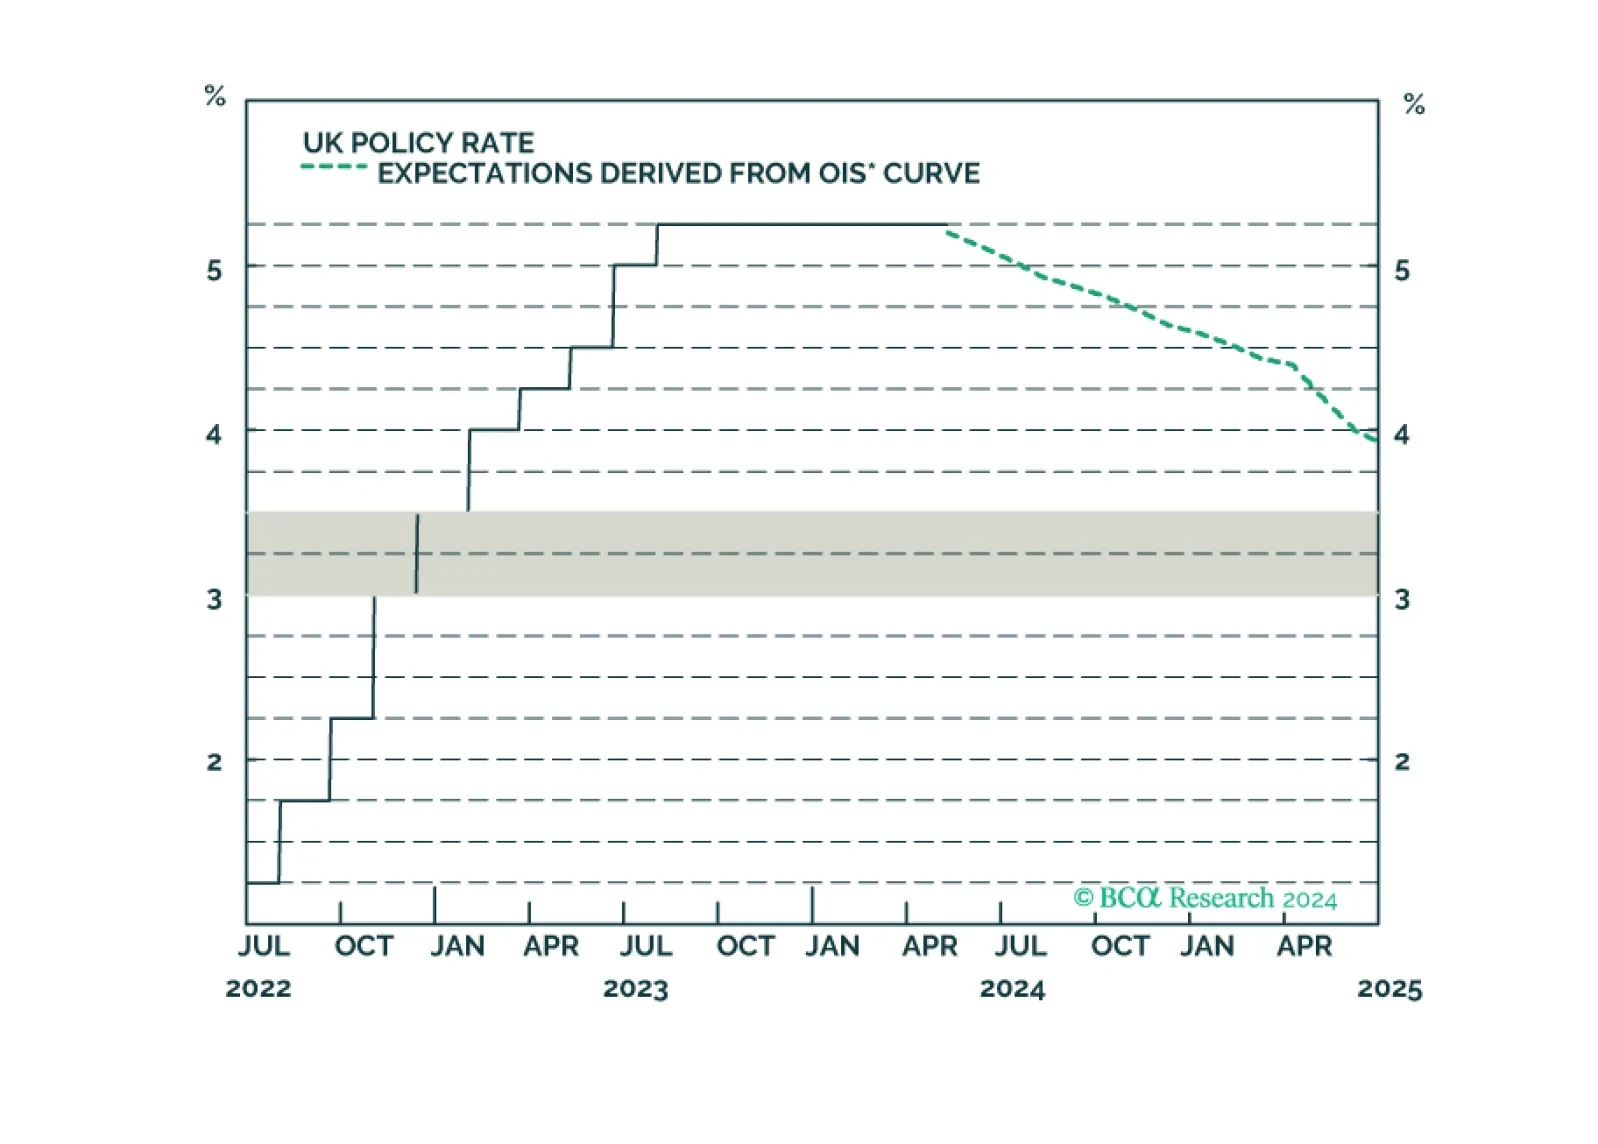
An update to our views on UK rates and currency following today’s Bank of England meeting.
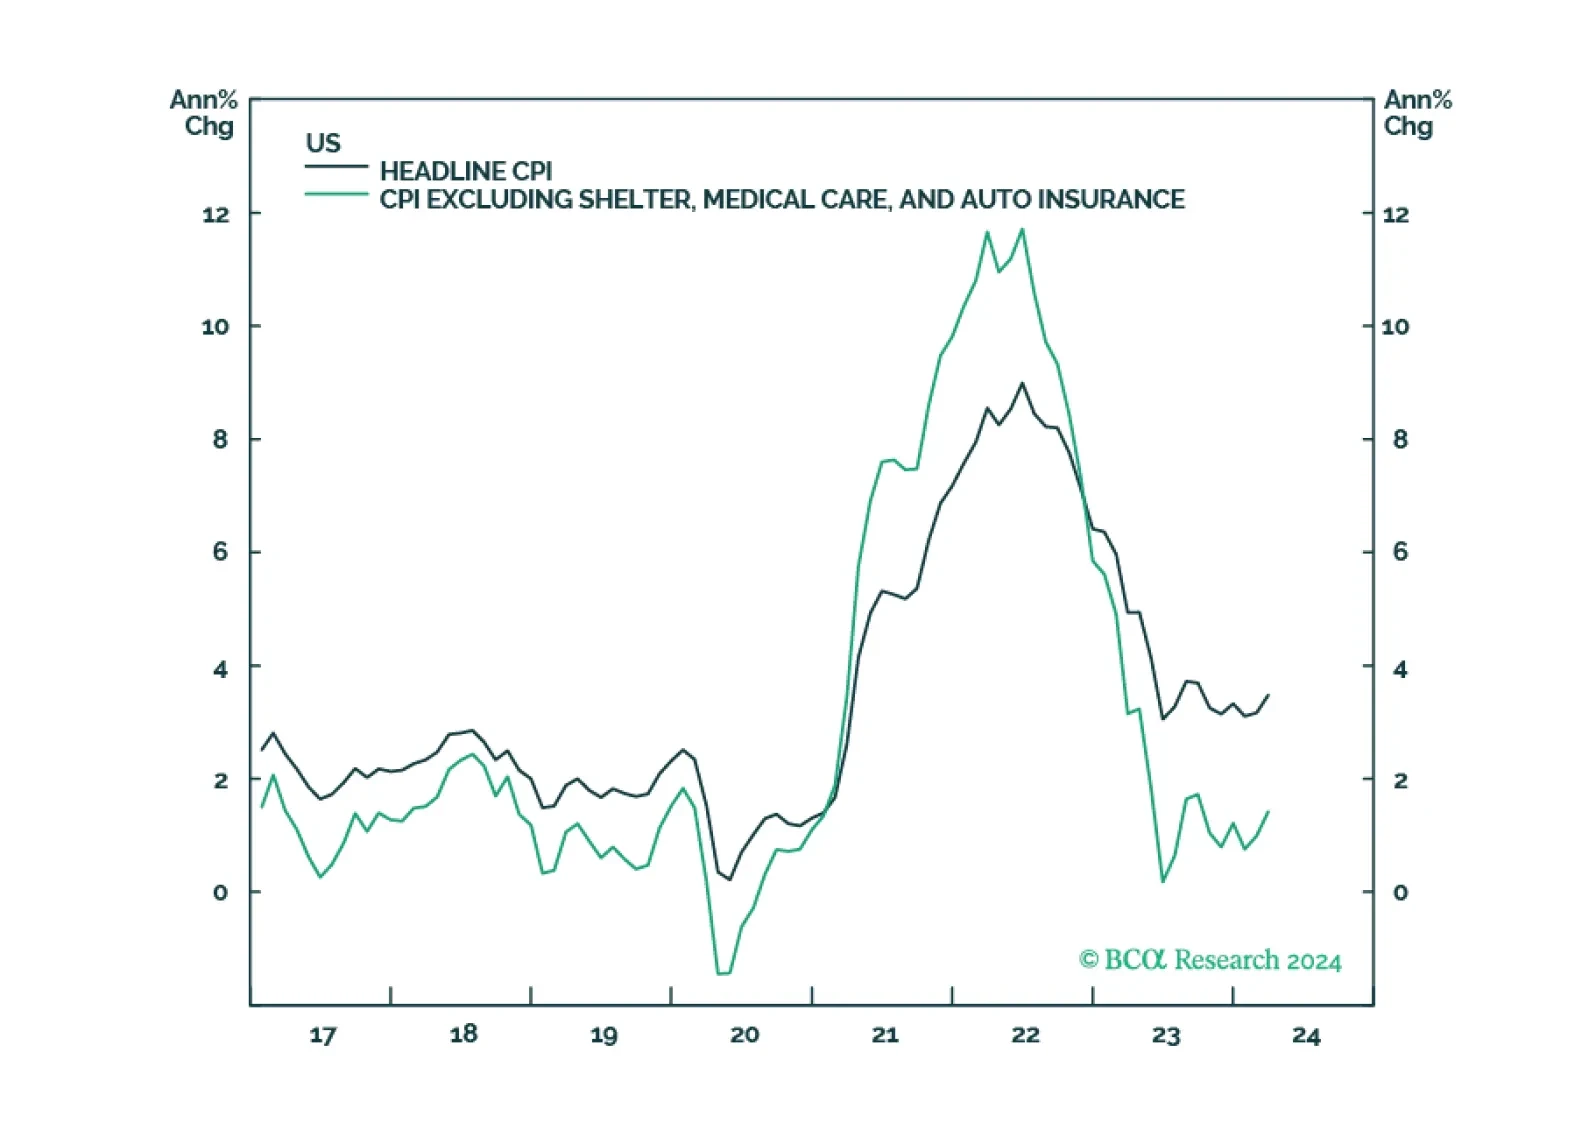
In this week’s report, we defend four out-of-consensus claims. Claim #1: Underlying inflation in the US is not reaccelerating. Claim #2: The US labor market is set to weaken abruptly. Claim #3: The S&P 500 will drop to 3700 in 2025. Claim #4: Japan is not in danger of a currency crisis.
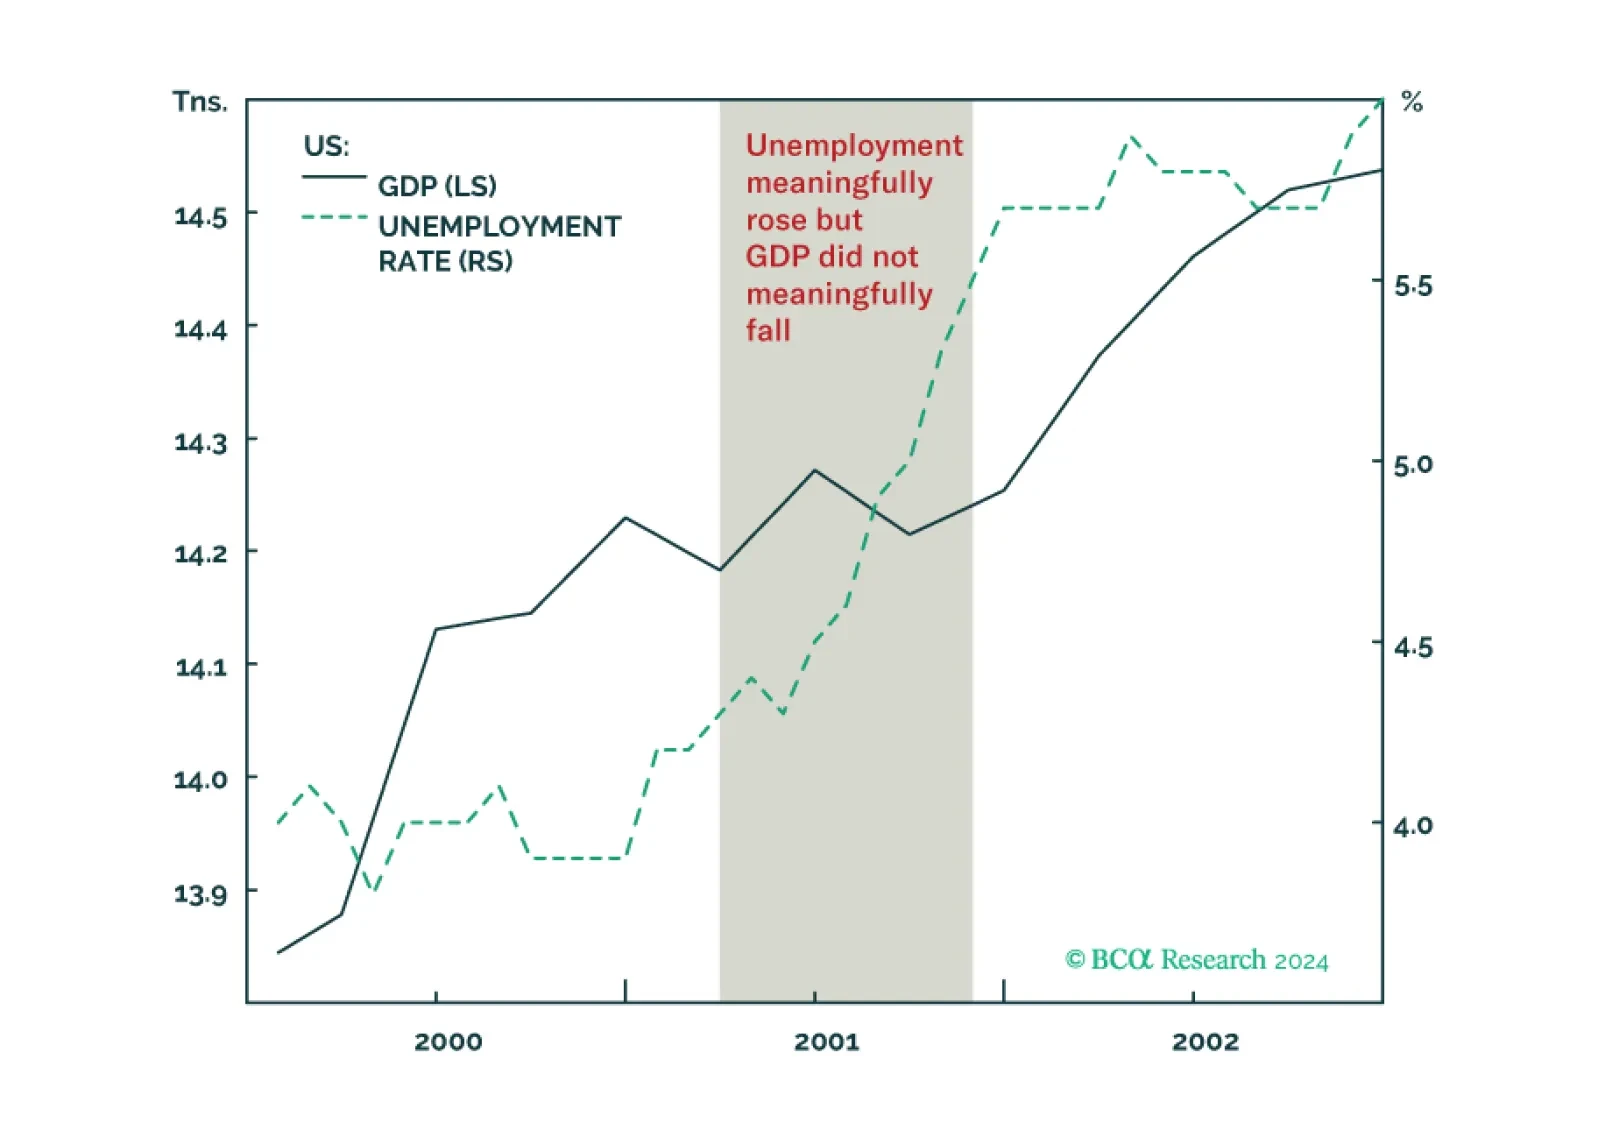
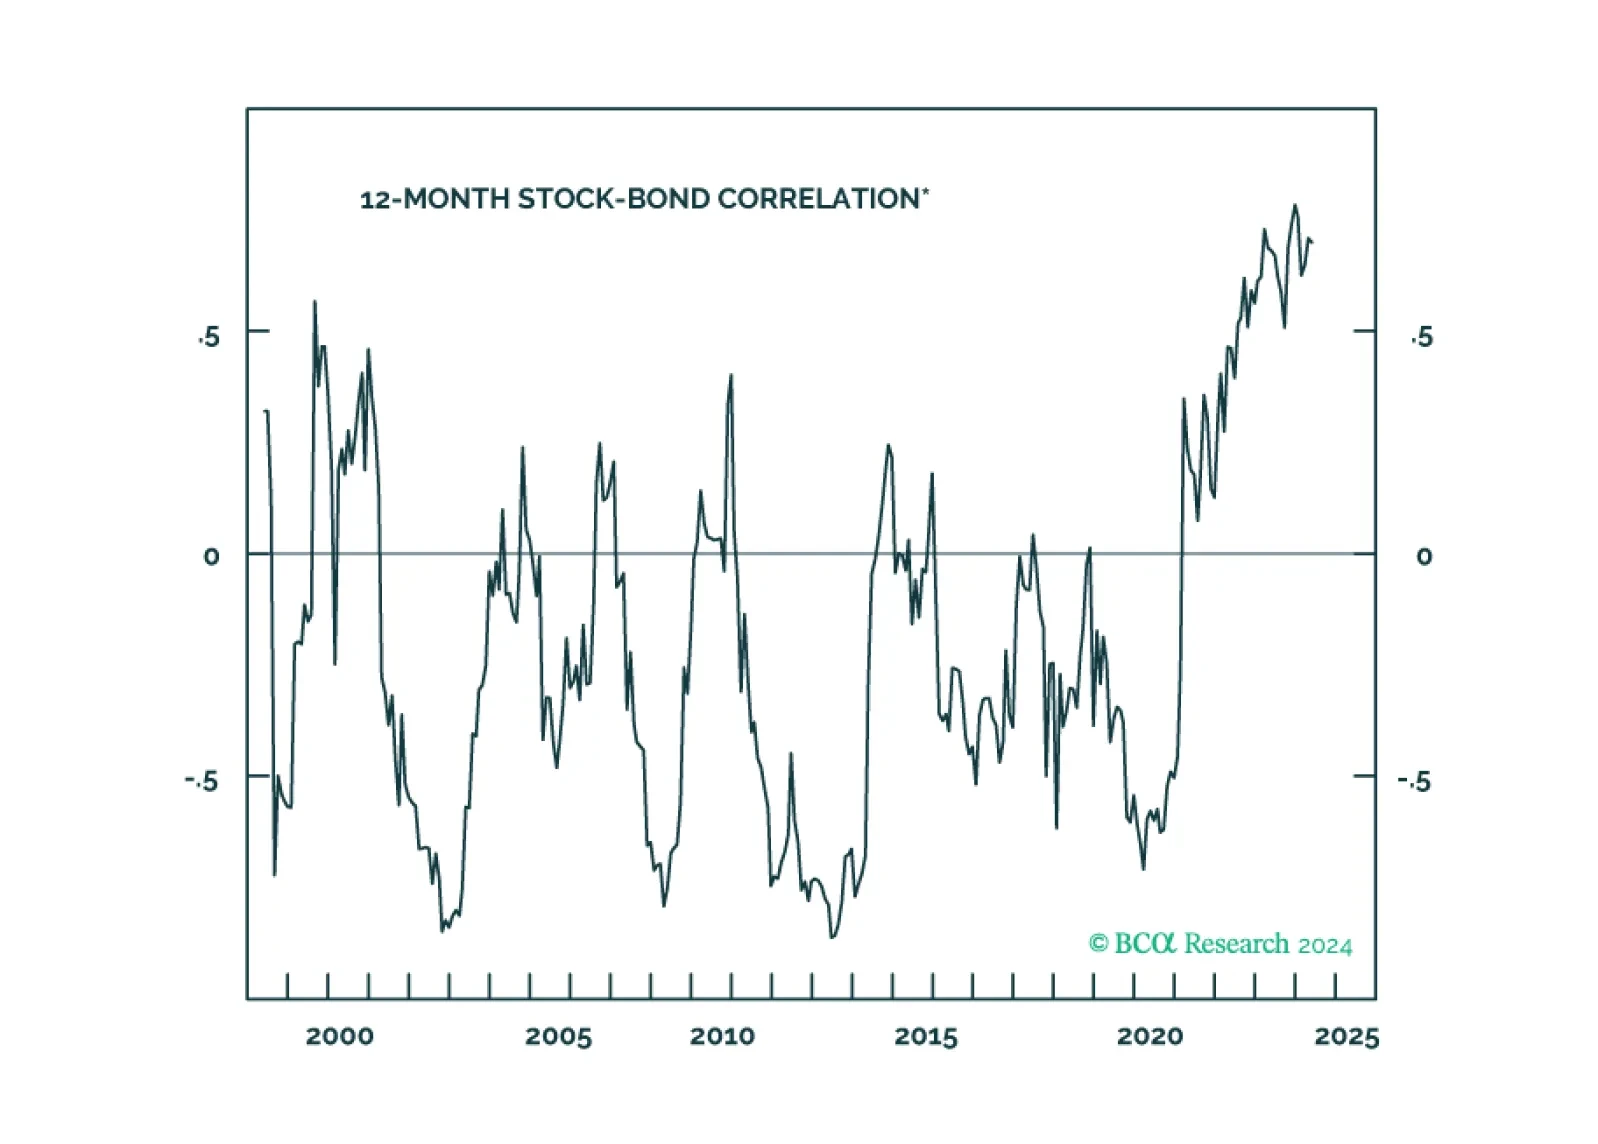
Why the US could get a jobs recession without a GDP recession, as happened in 2001, and what it means for stocks and bonds. Plus, an update on the Joshi rule.
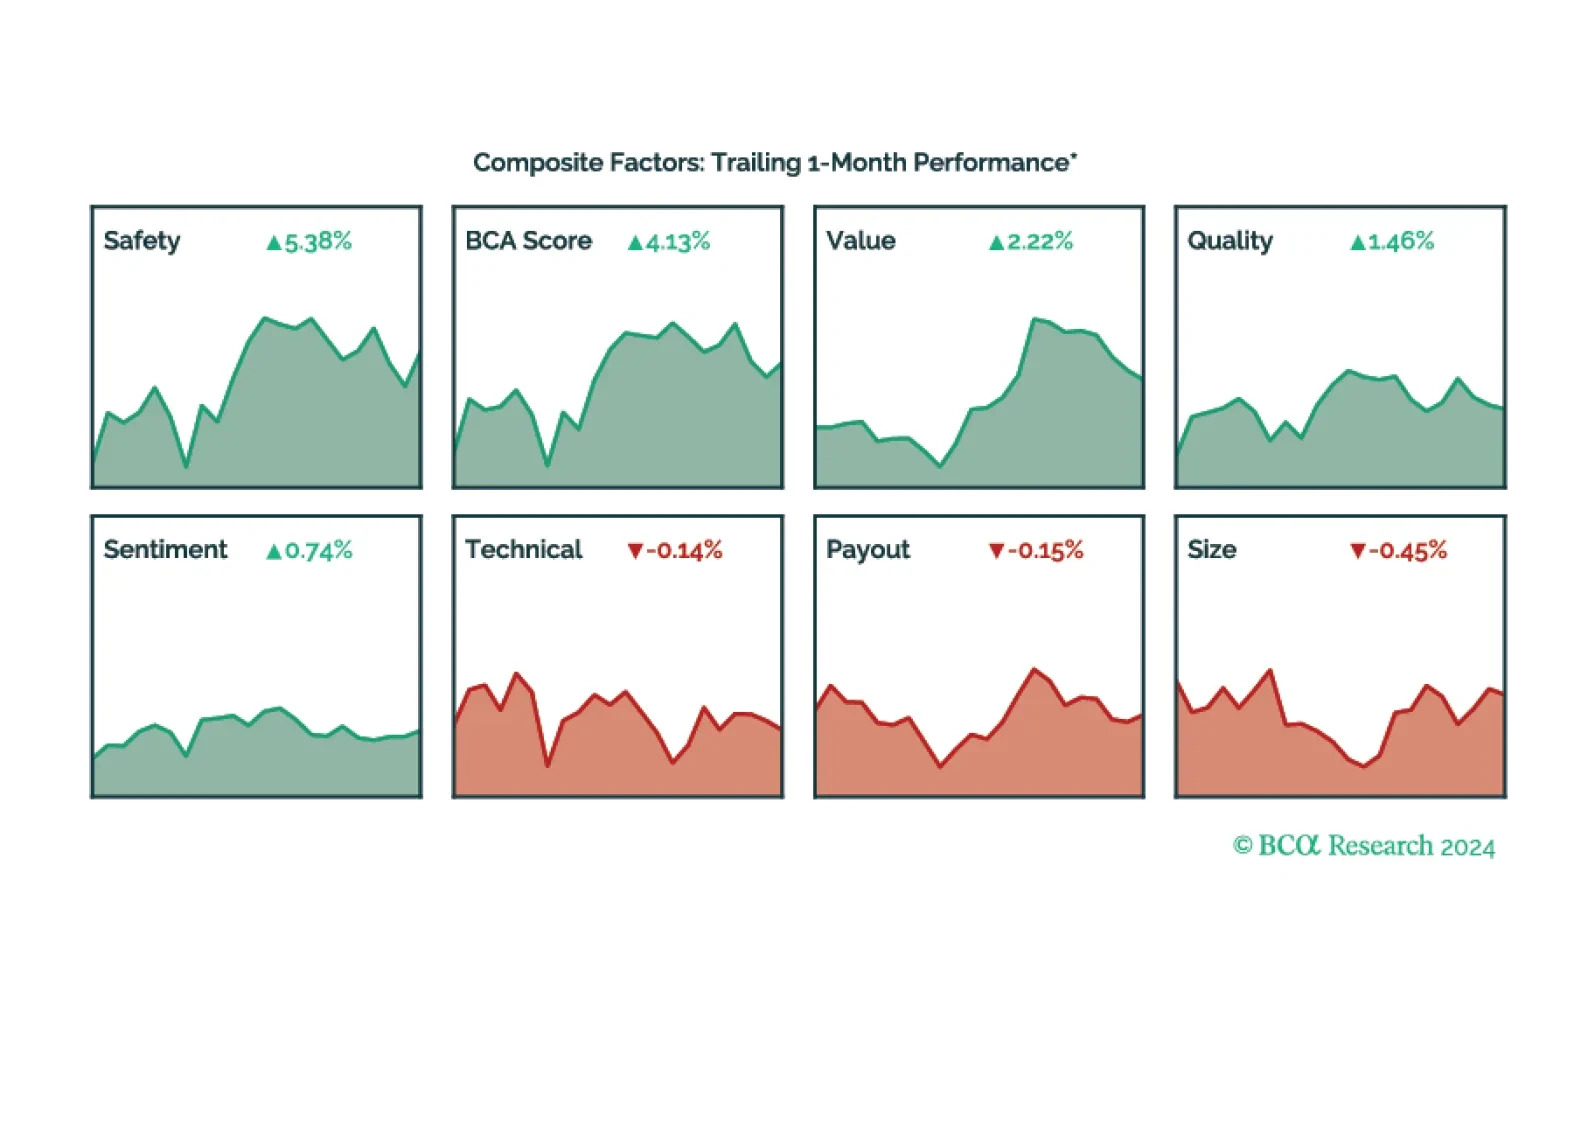
This month both the USHQ and SMID portfolios saw a downturn due to the idiosyncratic risk from the Powell's dovish stance in the May FOMC meeting. However, the Safety, Value, and Quality outperformed, resulting in a 4.13% return in BCA Score L/S.
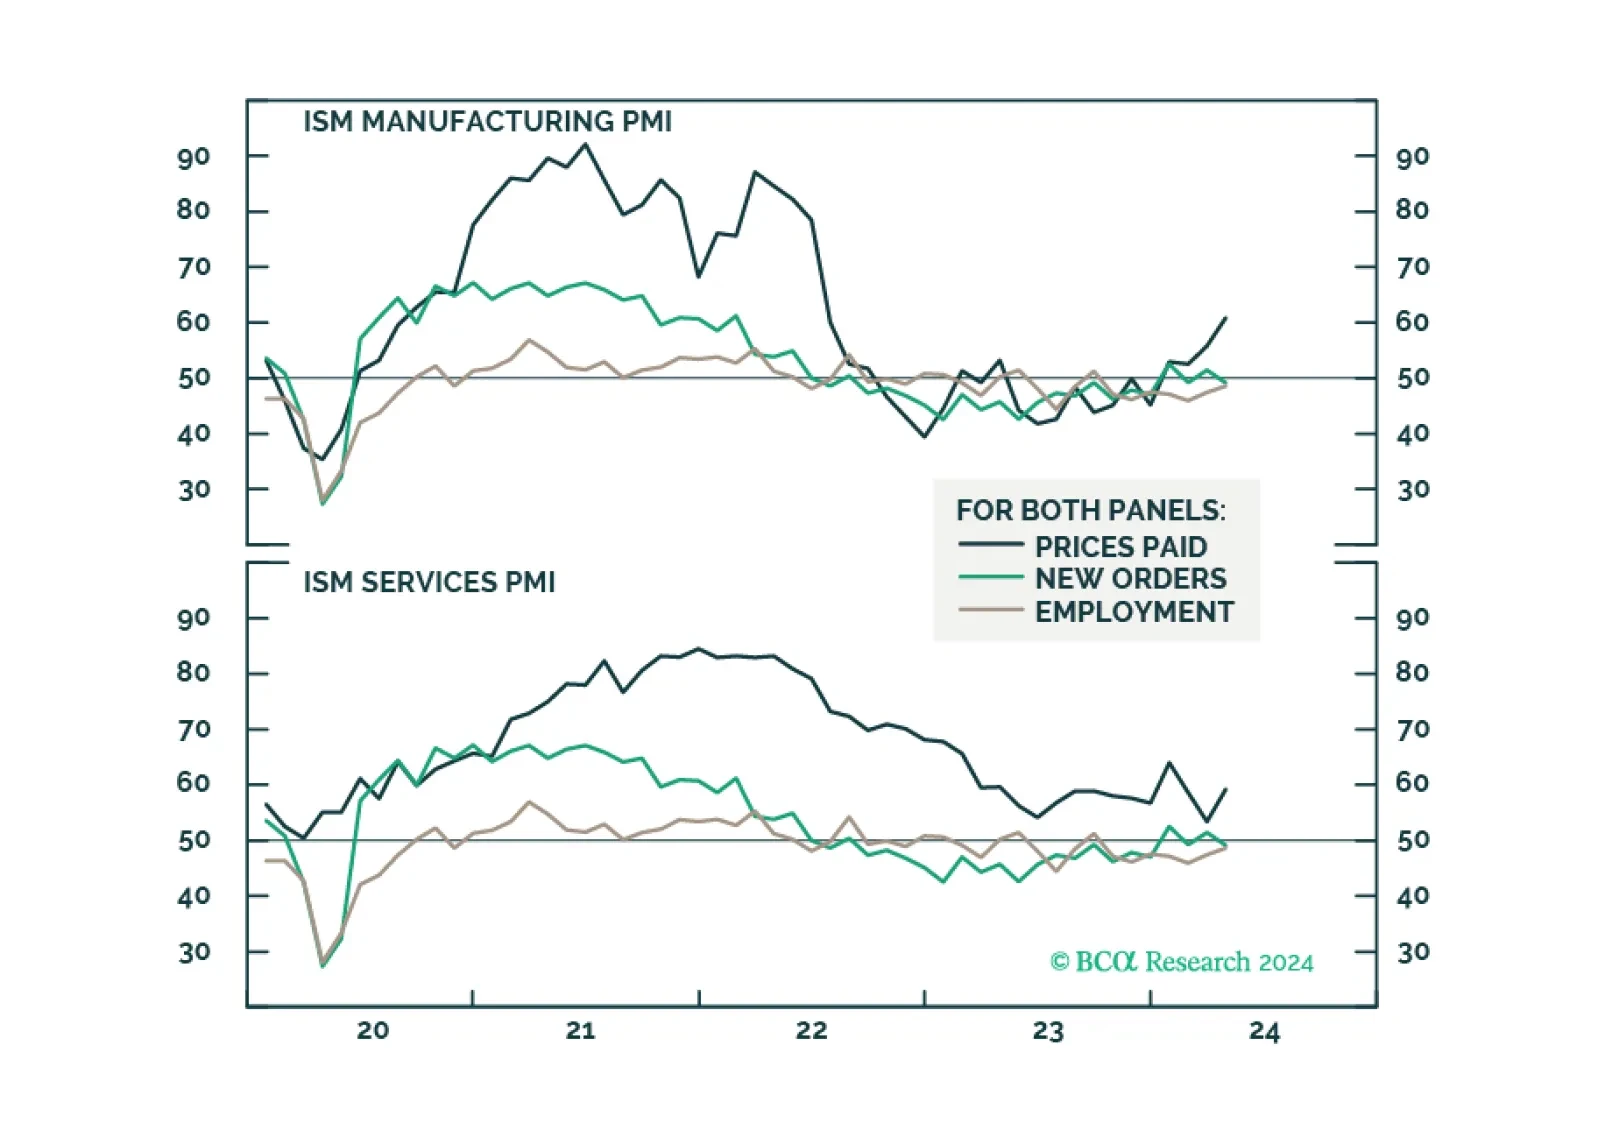
The broad market took a significant step backward in April, as market jitters gripped investors, stoking fears of higher for longer monetary policy. However, our roundtable investor poll has demonstrated that the majority remain constructive on equities, and have plenty of cash ready to be invested, which could prolong the rally. Economic data is deteriorating while inflation is stubborn. However, so far, bad news is good news as many believe that a “Fed put” is still on.