Latest from BCA Research
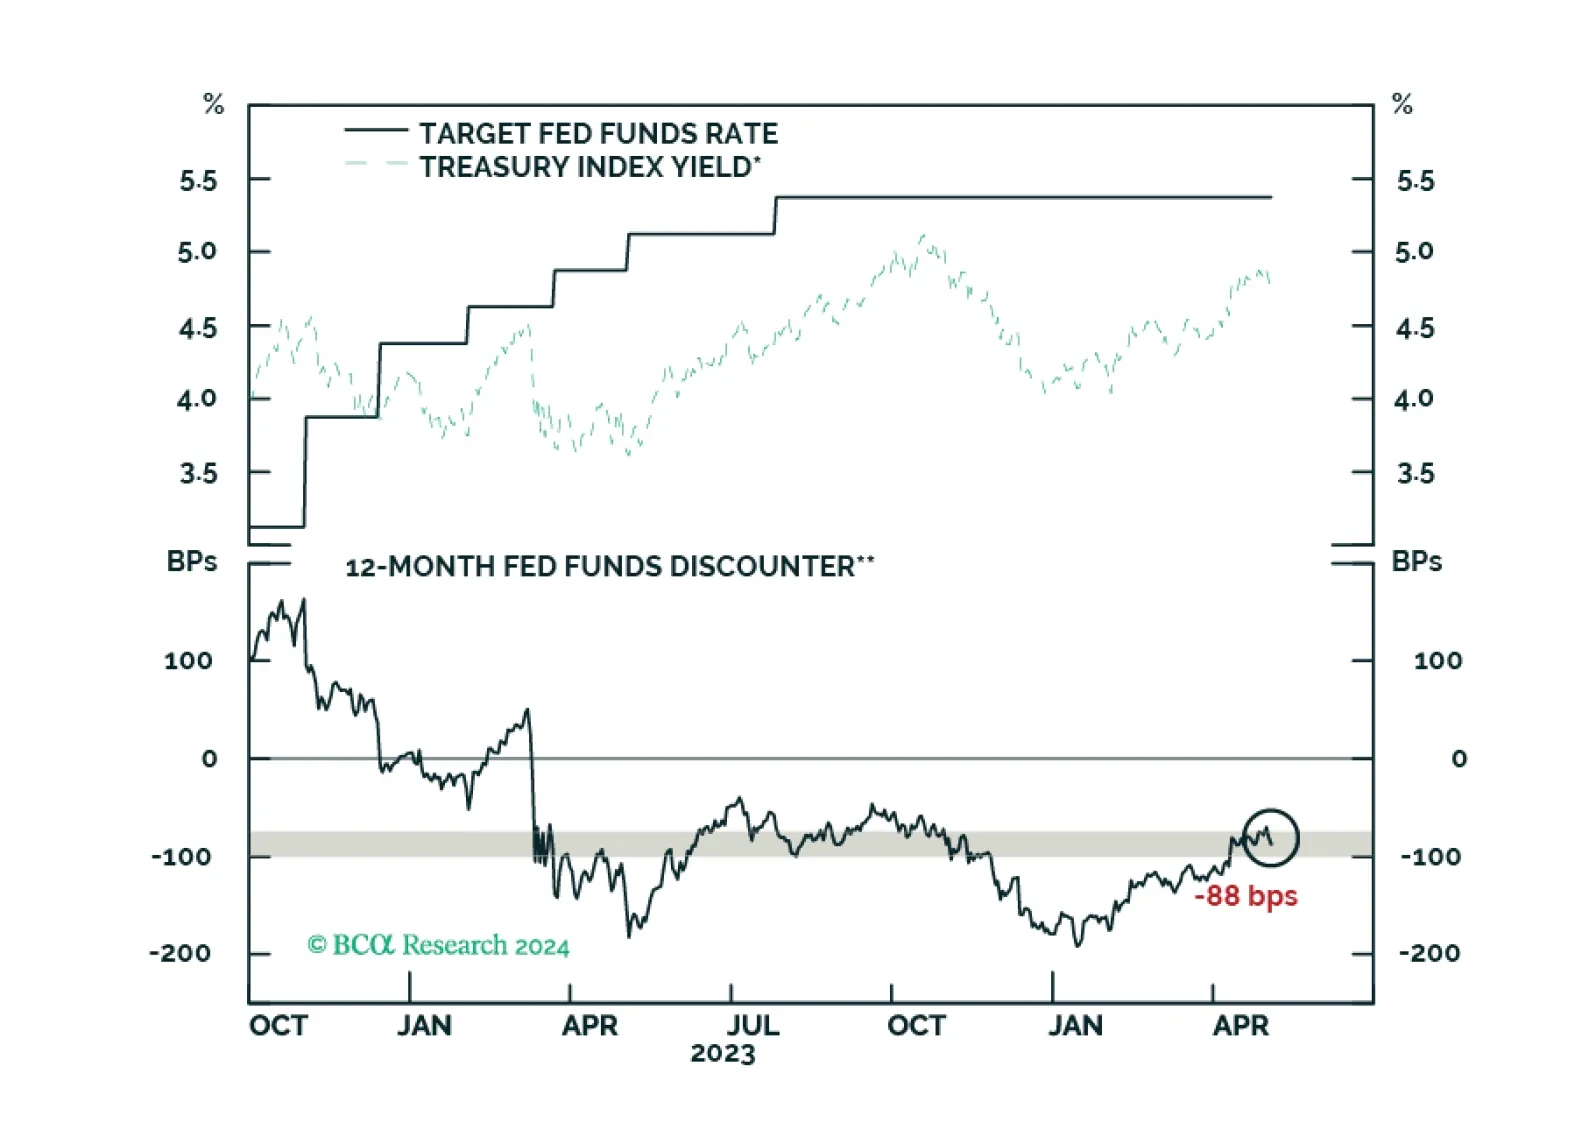
Some thoughts on this morning’s employment report and recent trends in US economic data.
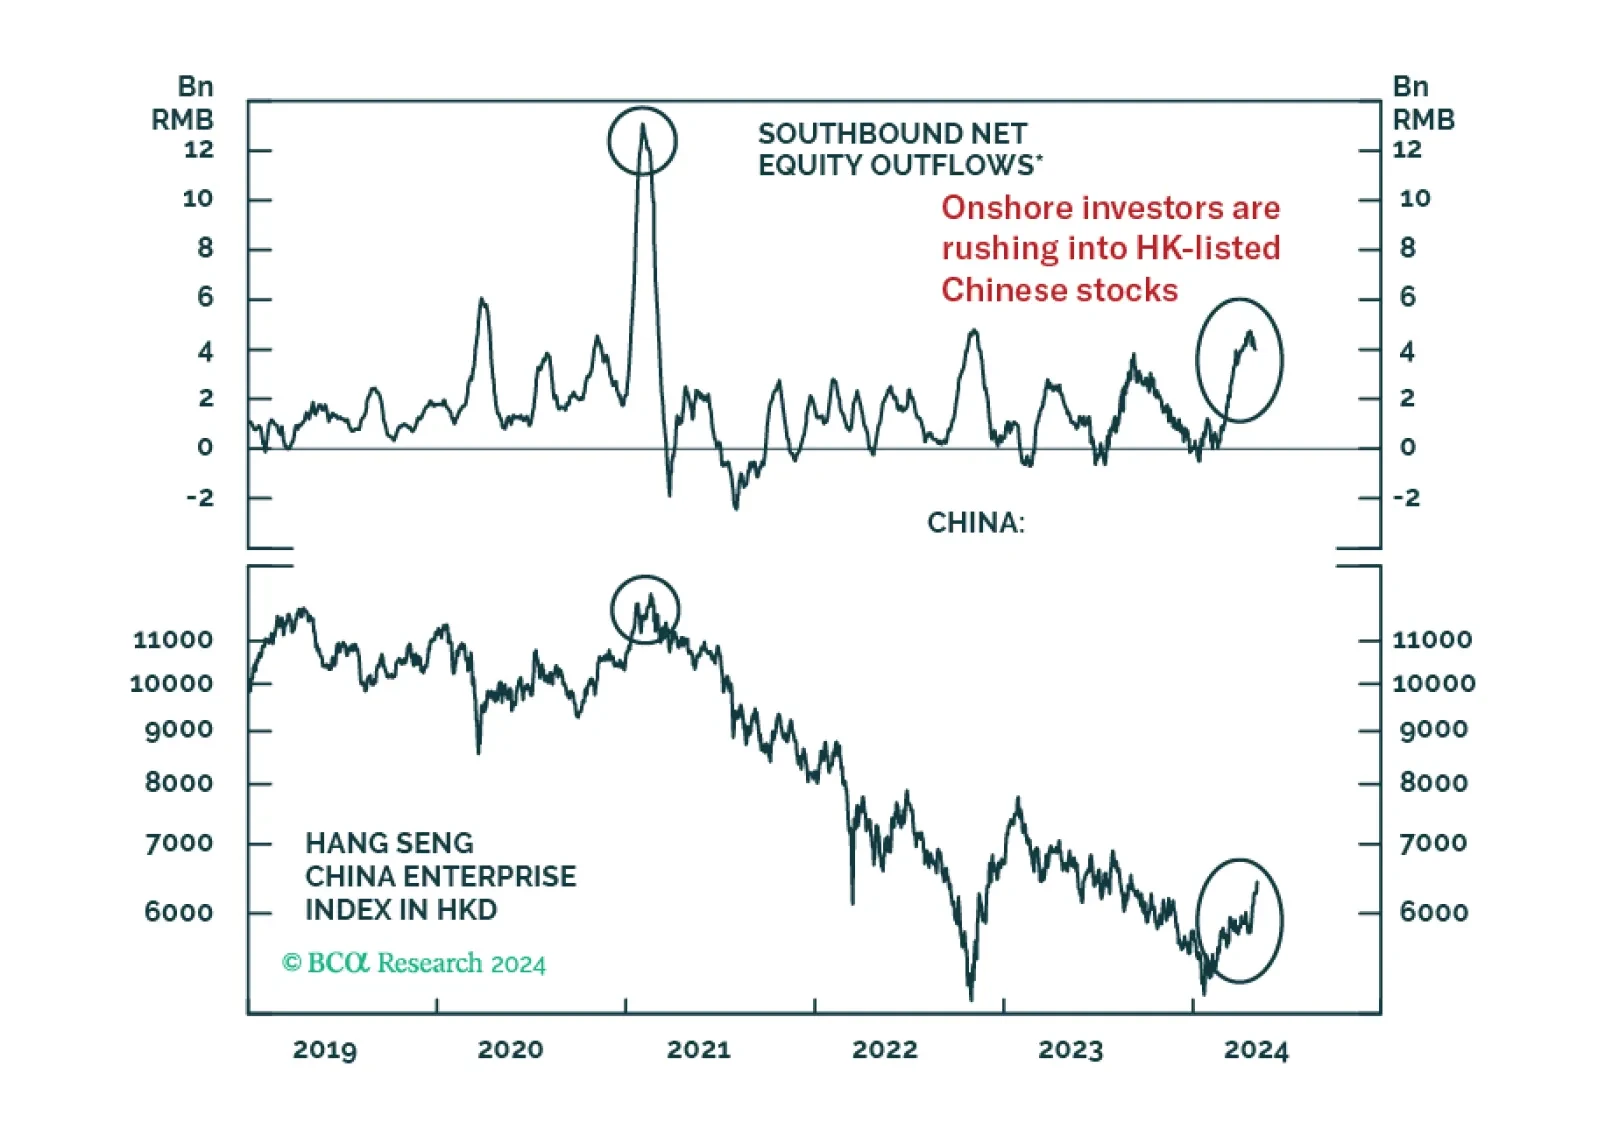
Mainland residents’ investments in gold, other metals, and Hong Kong-traded stocks are a form of capital outflow. Chinese authorities will counter any excessive capital flight with stricter administrative controls. Thus, markets benefiting from these flows will likely be hurt.
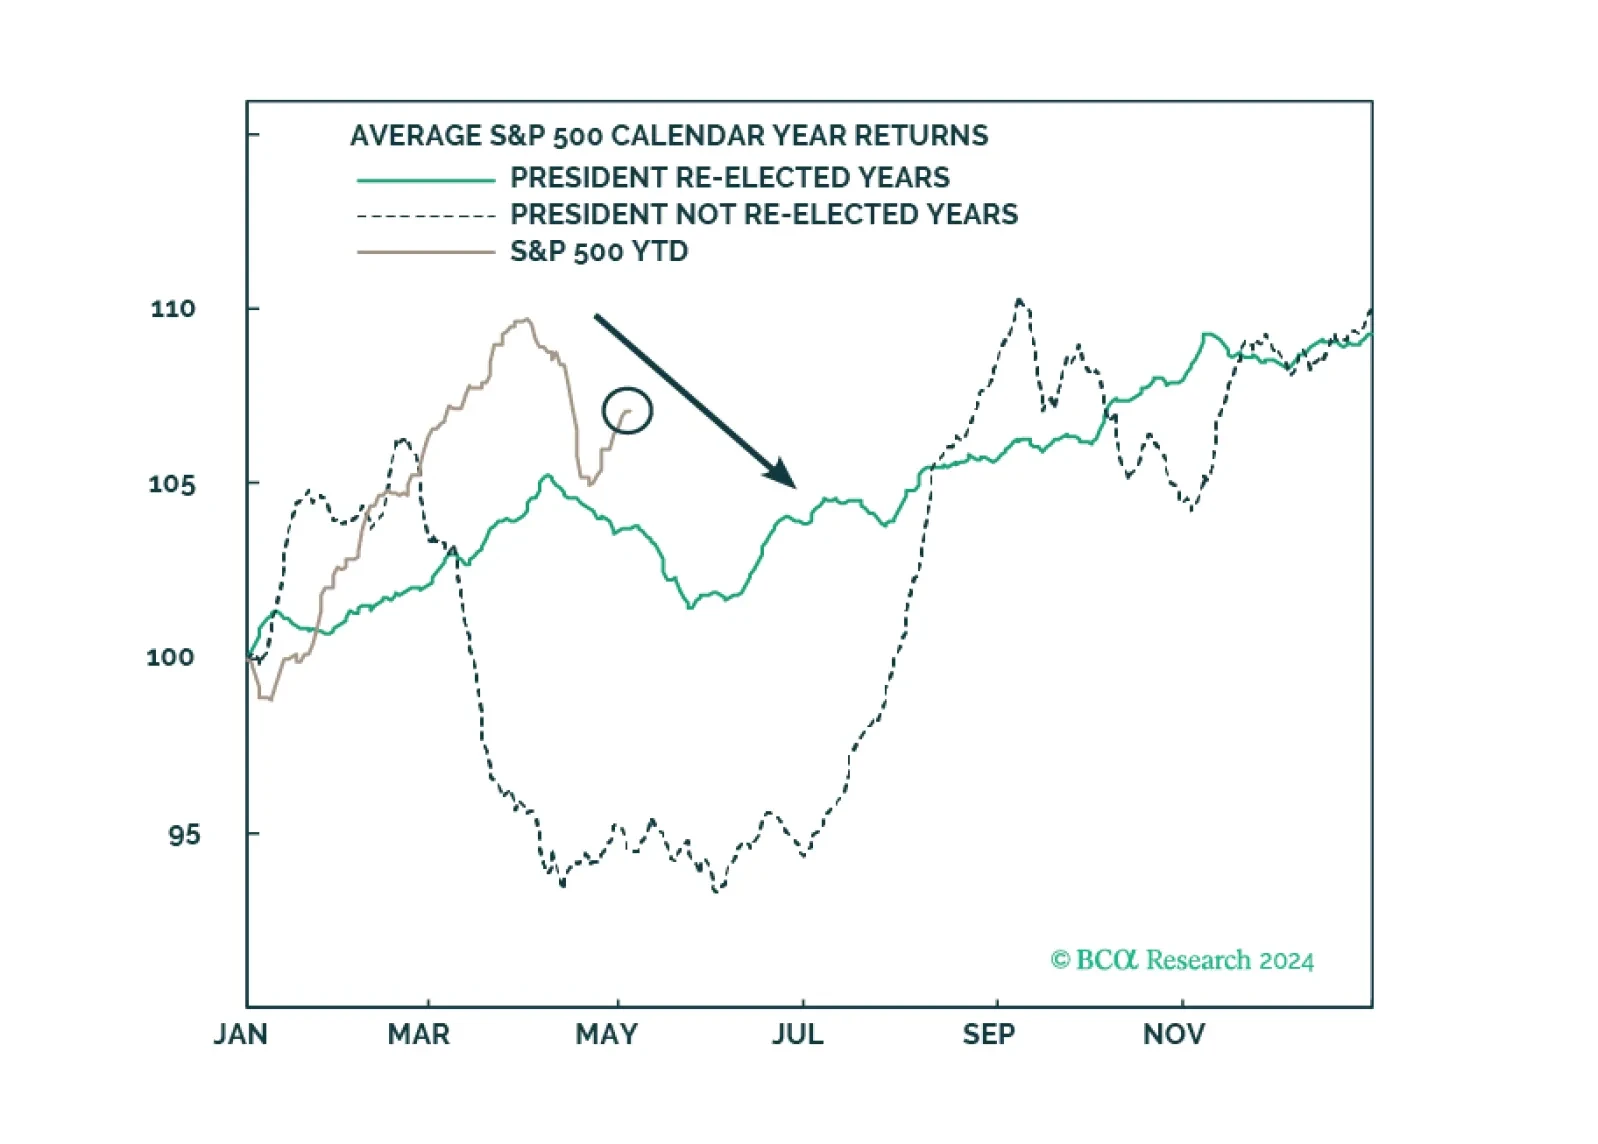
Investors should prepare for economic data to weaken even as policy uncertainty and geopolitical risk skyrocket ahead of the US election.
The Sector model continues to favor Energy and IT but upgraded Financials and Materials at the expense of Health Care and Consumer Discretionary. The Style indicator remains inclined towards Value-Large cap.
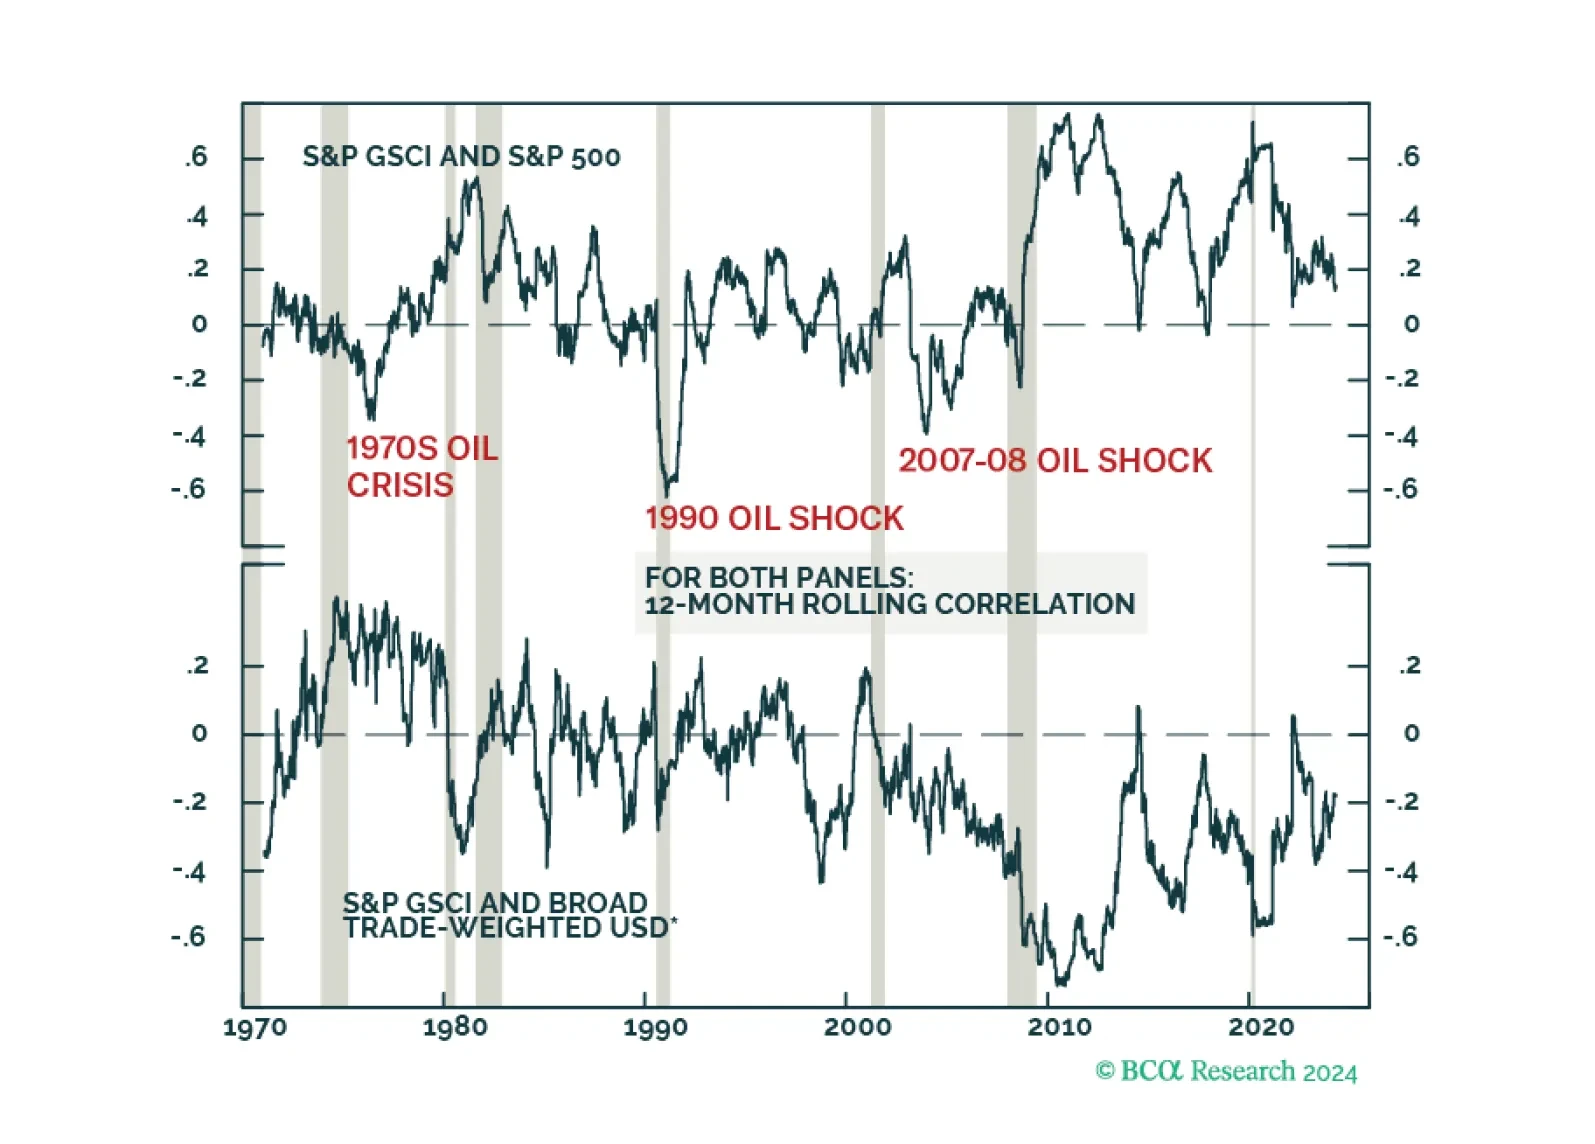
The no landing scenario has been gaining traction as the dominant driver of financial markets, providing a tailwind to commodities via increased demand for inflation hedges. Unless commodity markets experience a major supply shock, a narrative shift in favor of the hard landing scenario would create a headwind for commodities. A decisive top in the equity market would provide an early warning for commodity investors.
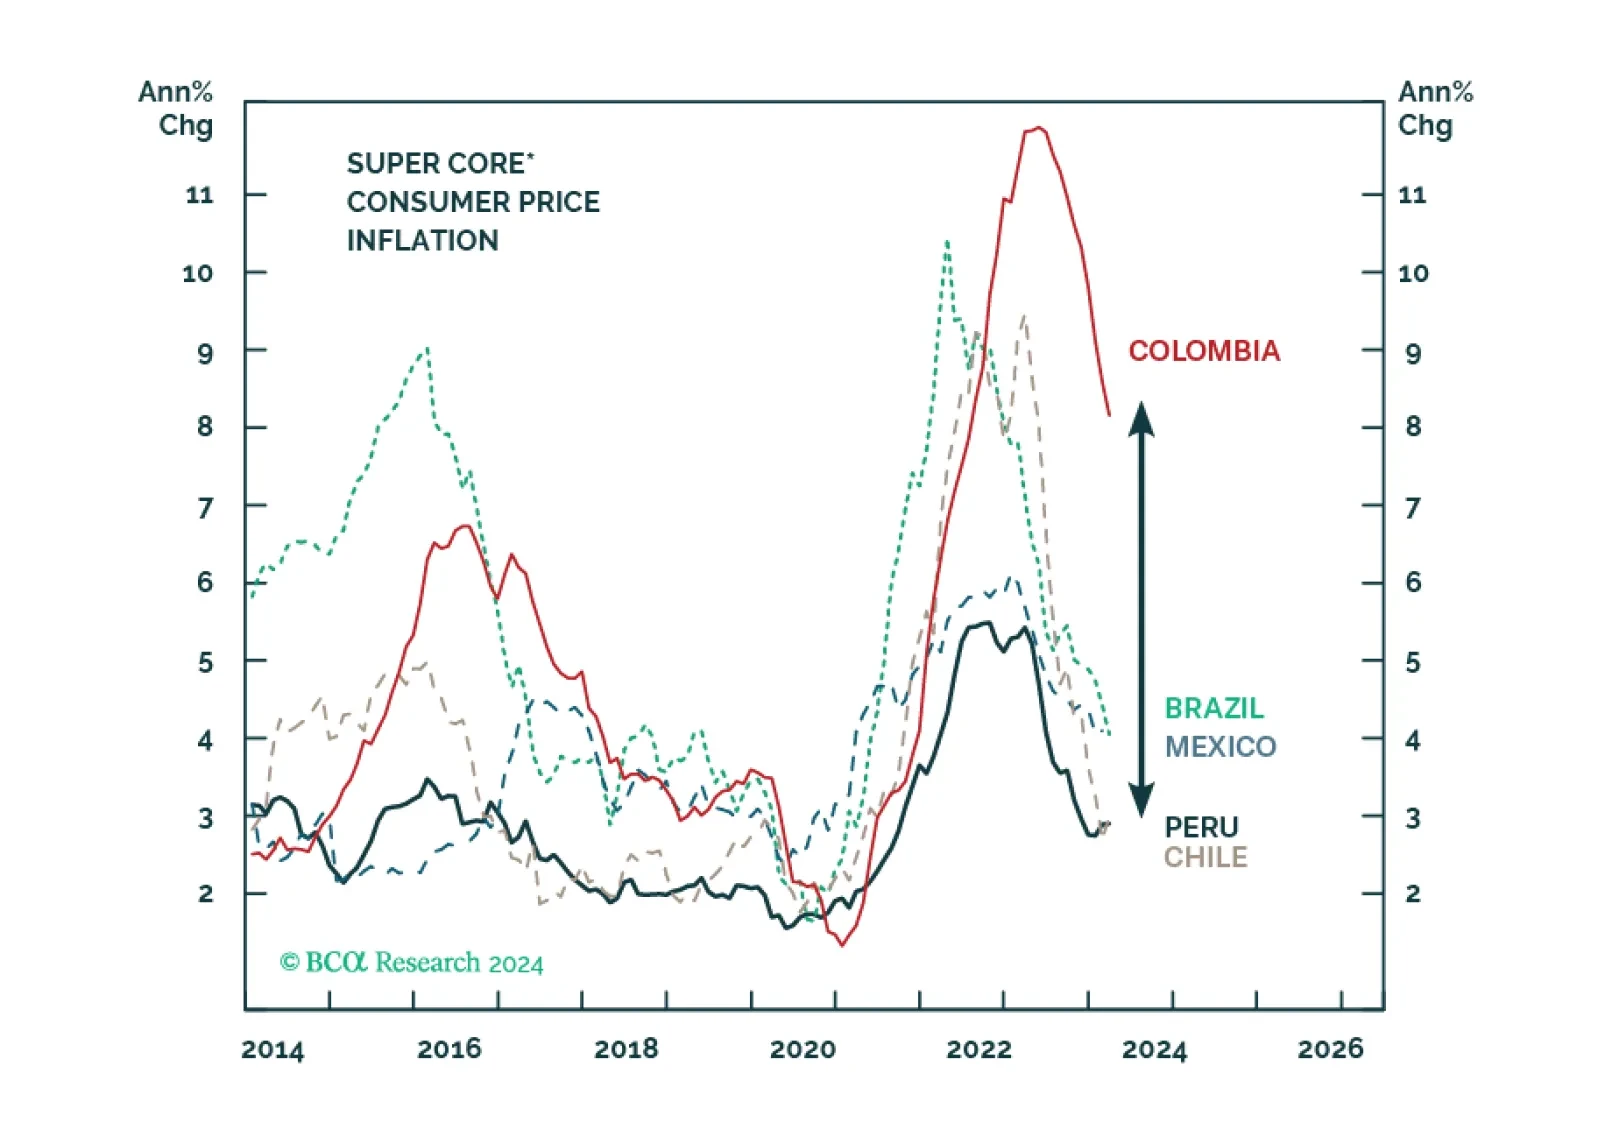
Peru is entering a benign macro environment: low and falling inflation amid a solid economic recovery. The country’s balance of payments position is robust, which will help the PEN depreciate by less than other EM currencies. The political situation is on shaky ground, but a regime shift will have to wait until 2026. We remain overweight on Peruvian equities, domestic bonds, and sovereign credit relative to the EM benchmarks.
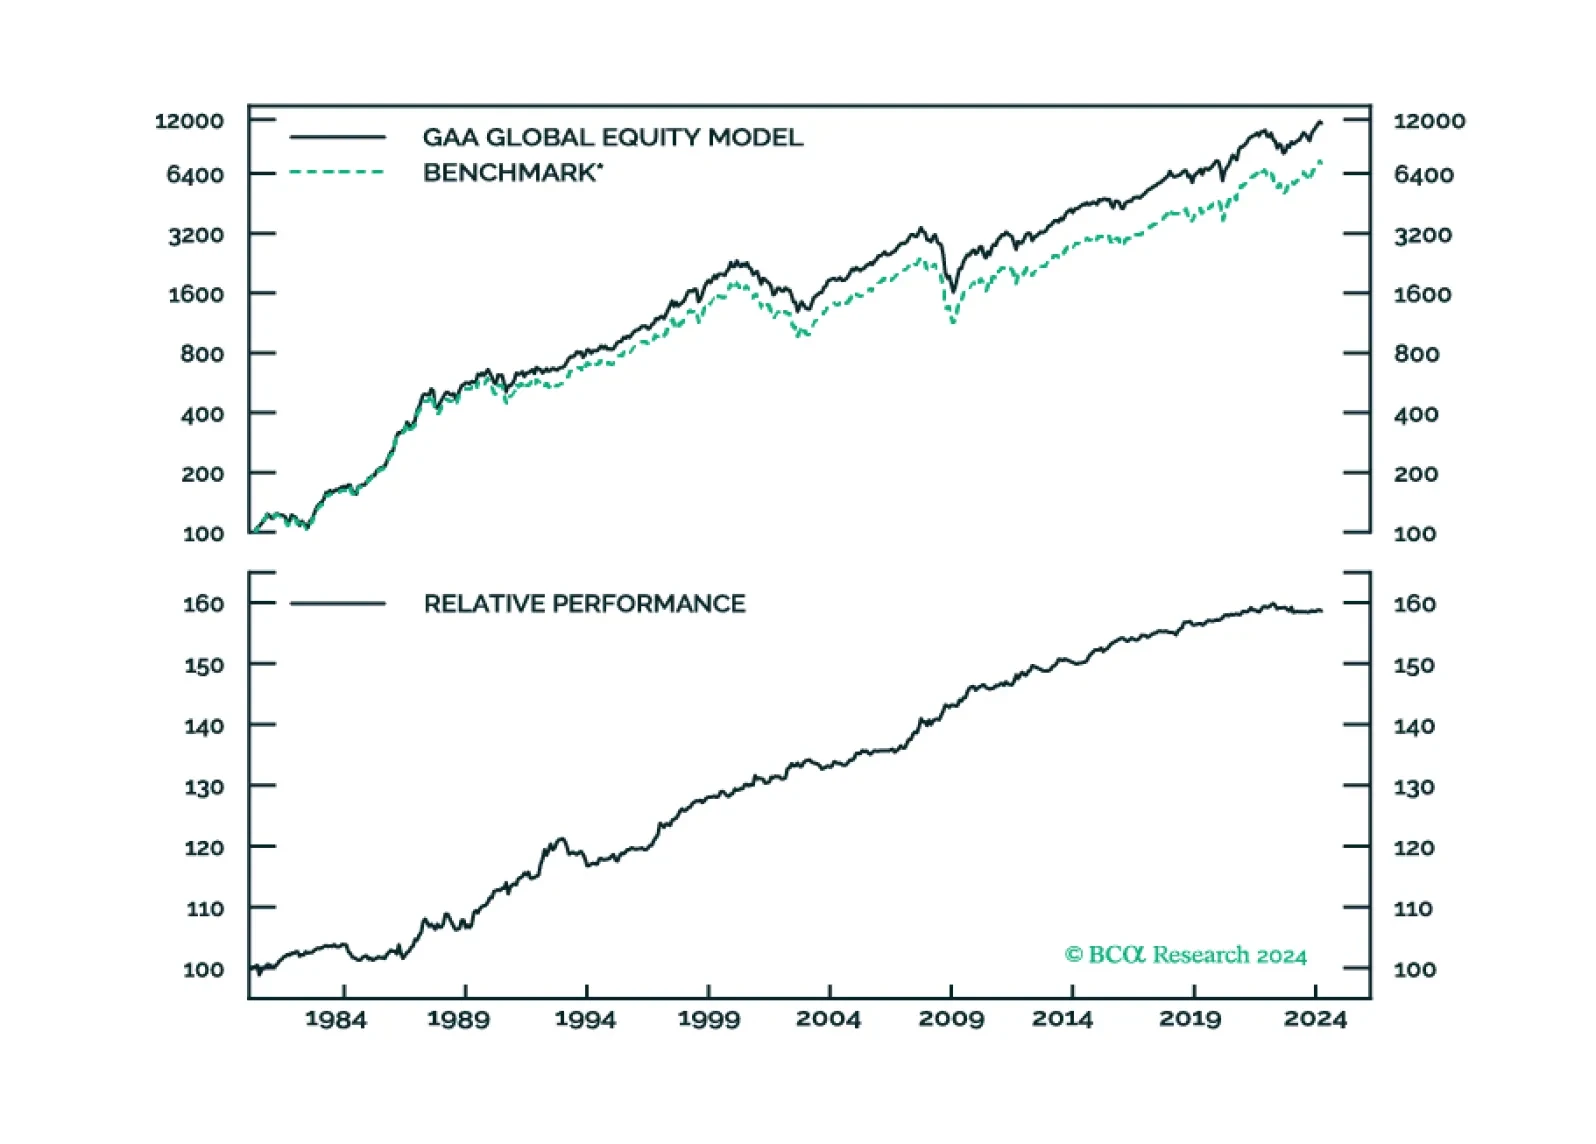
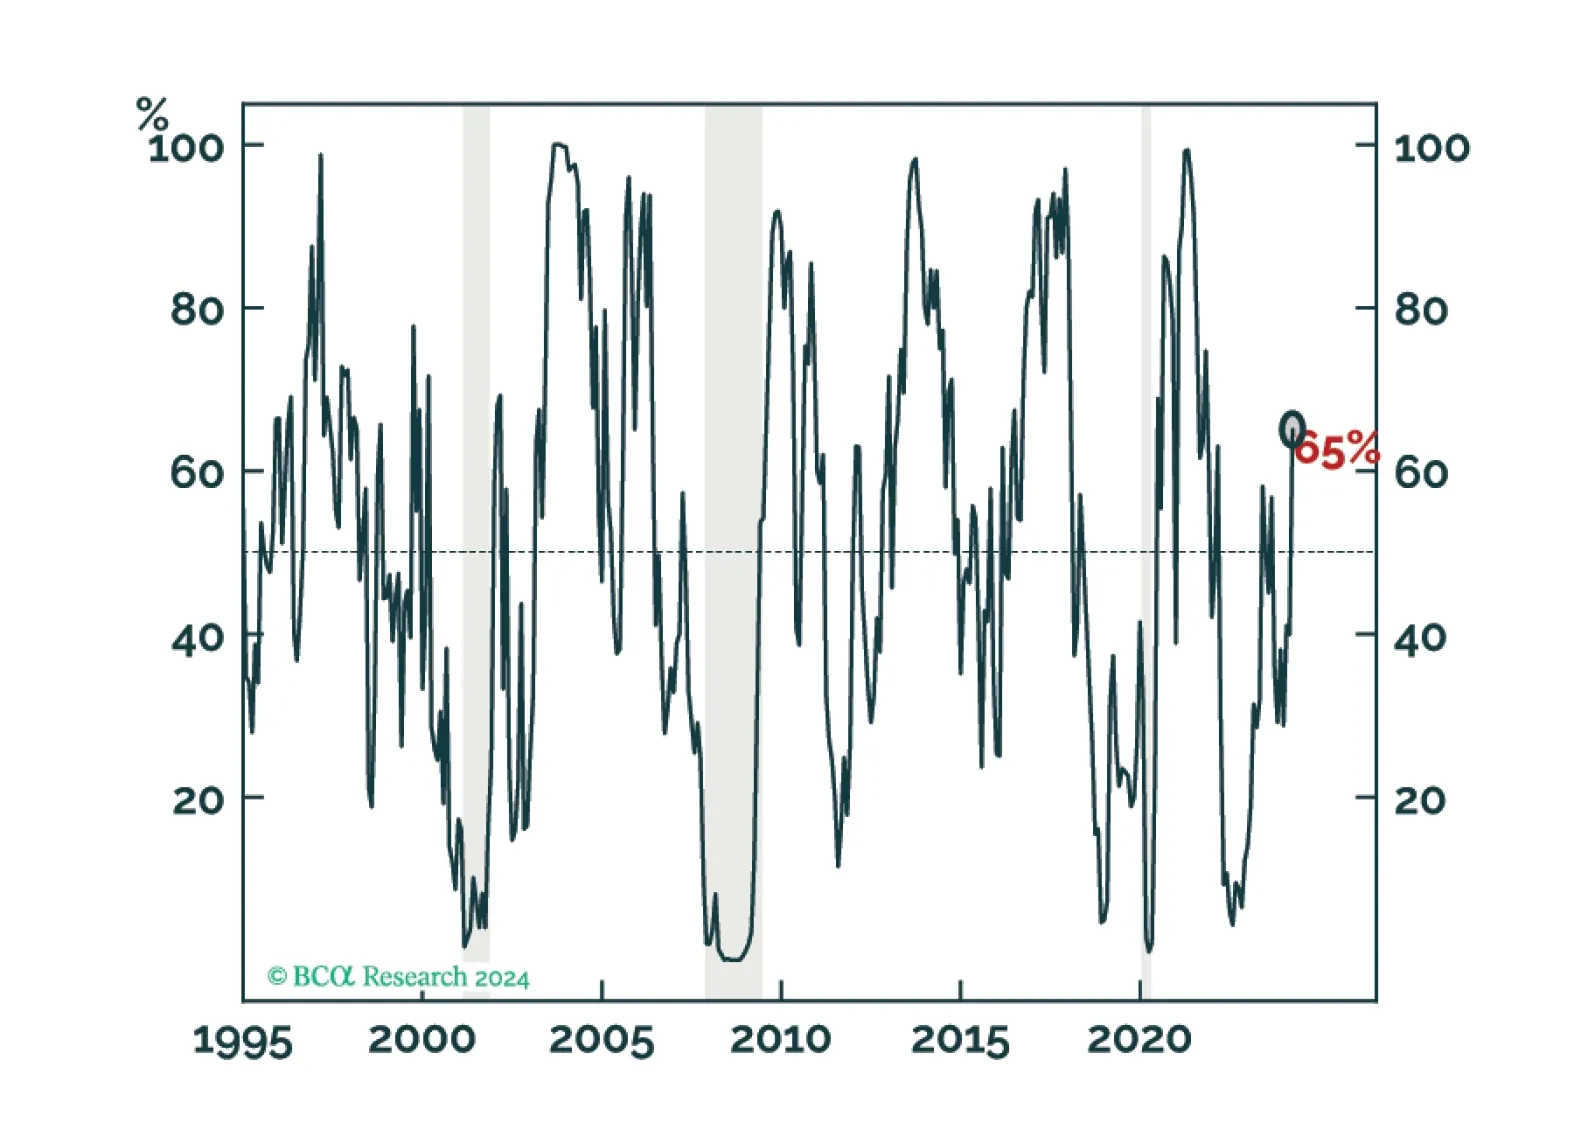
At the asset class level, the GAA Quant model is overweight equities, underweight bonds, and neutral cash.
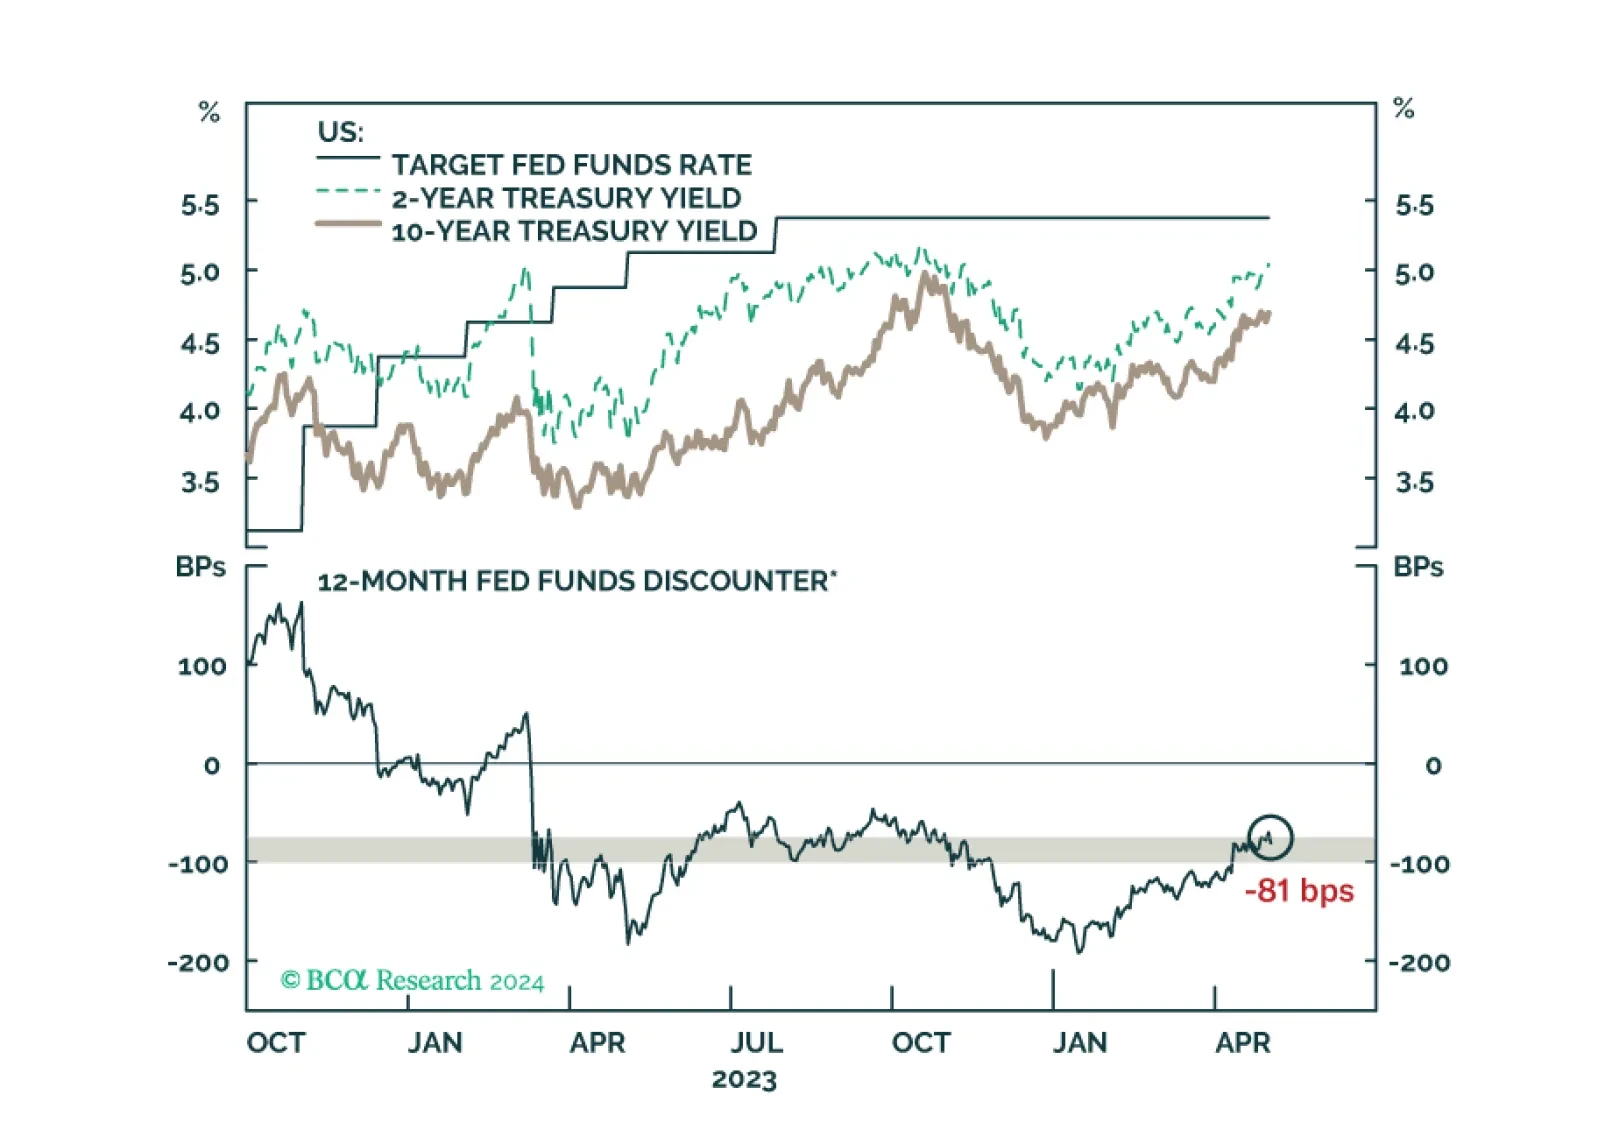
Updated views on US Treasury yields and the dollar following today’s FOMC meeting.
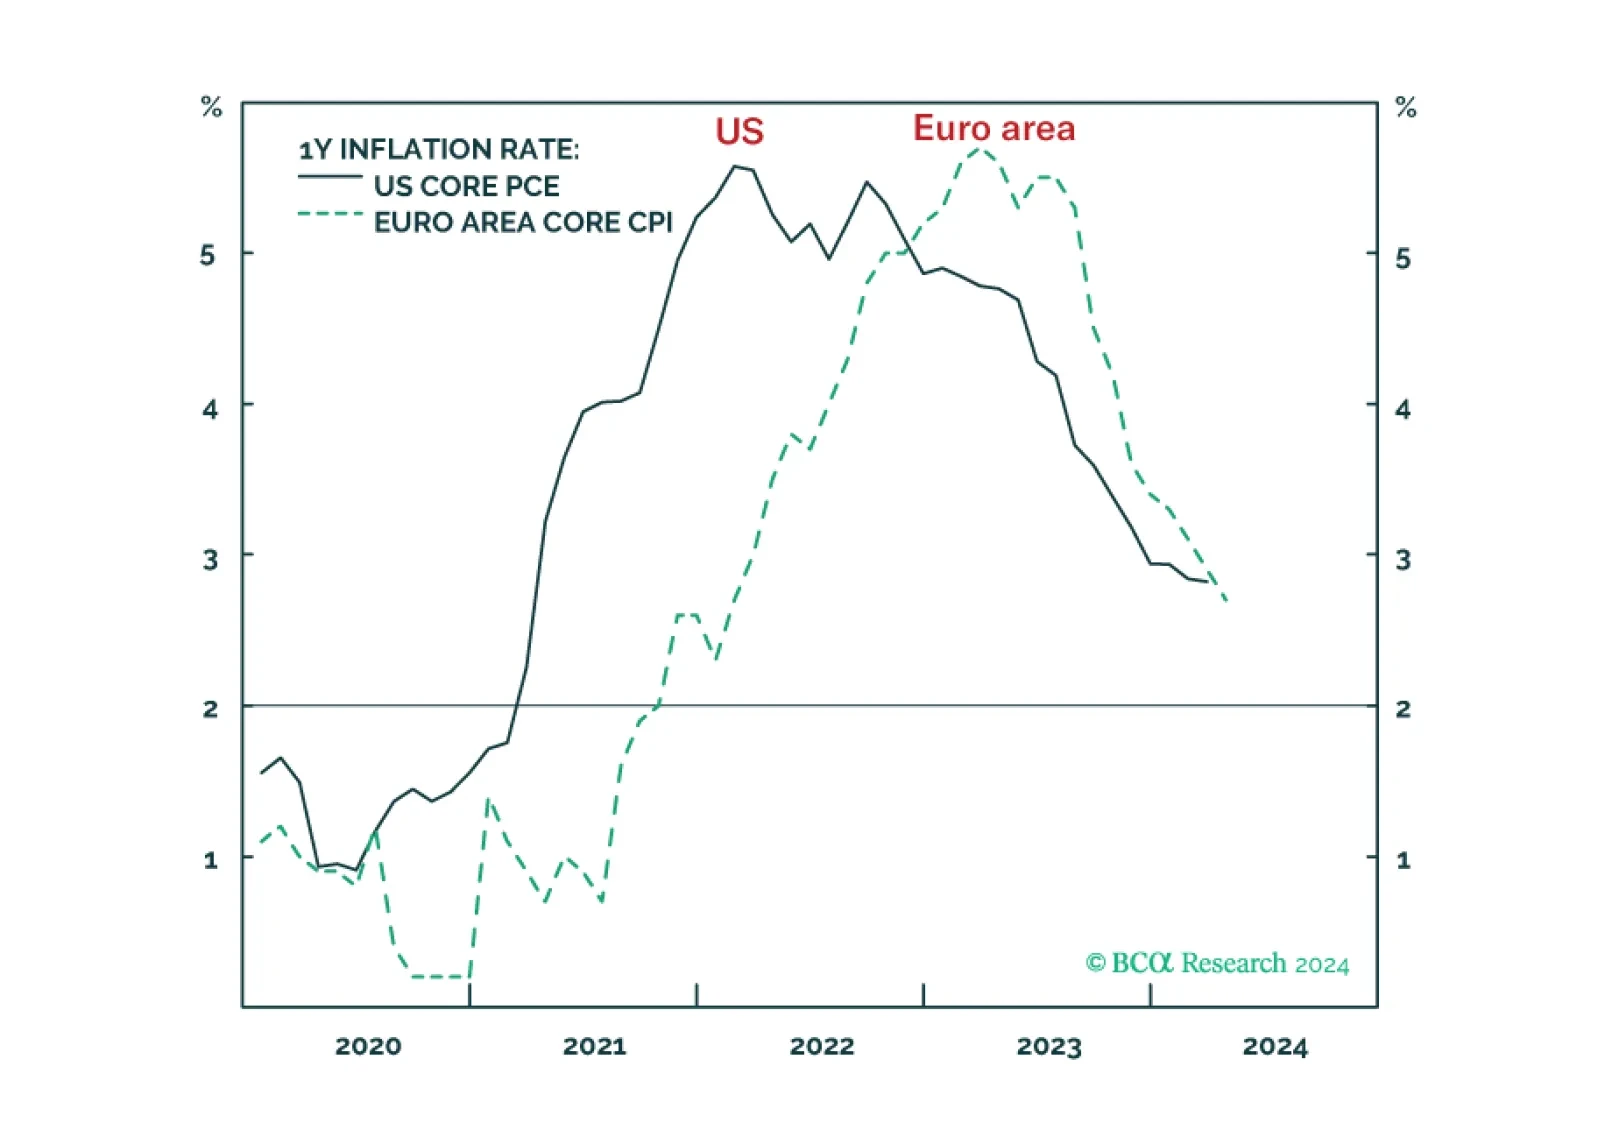
Wild hopes for US rate cuts got shattered, exactly as we predicted. But given the different incentives that the Fed and ECB now face, the relative pricing between the Fed and the ECB could widen further in the coming months. We discuss the implications for rates, the dollar, and the relative positioning in US versus European equities.
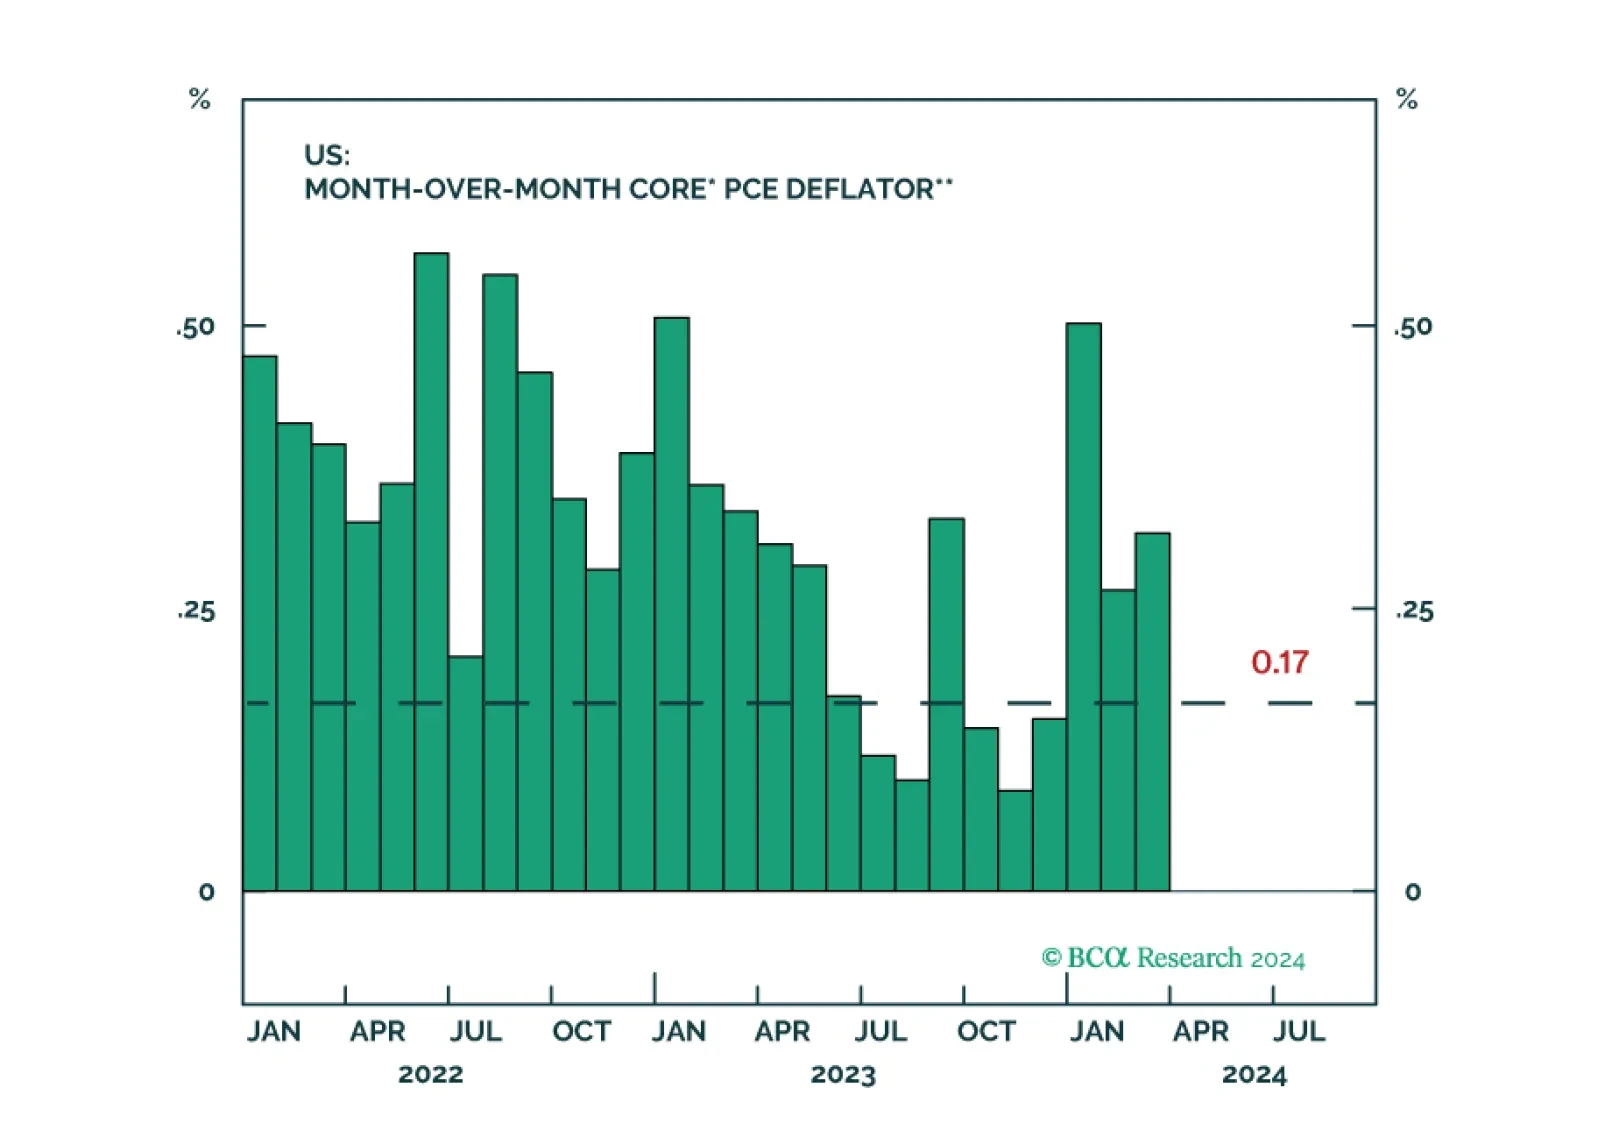
Central banks are in a dilemma whether to prioritize supporting growth or bringing inflation back to target. This is unlikely to end well. Investors should be defensively positioned.