Latest from BCA Research
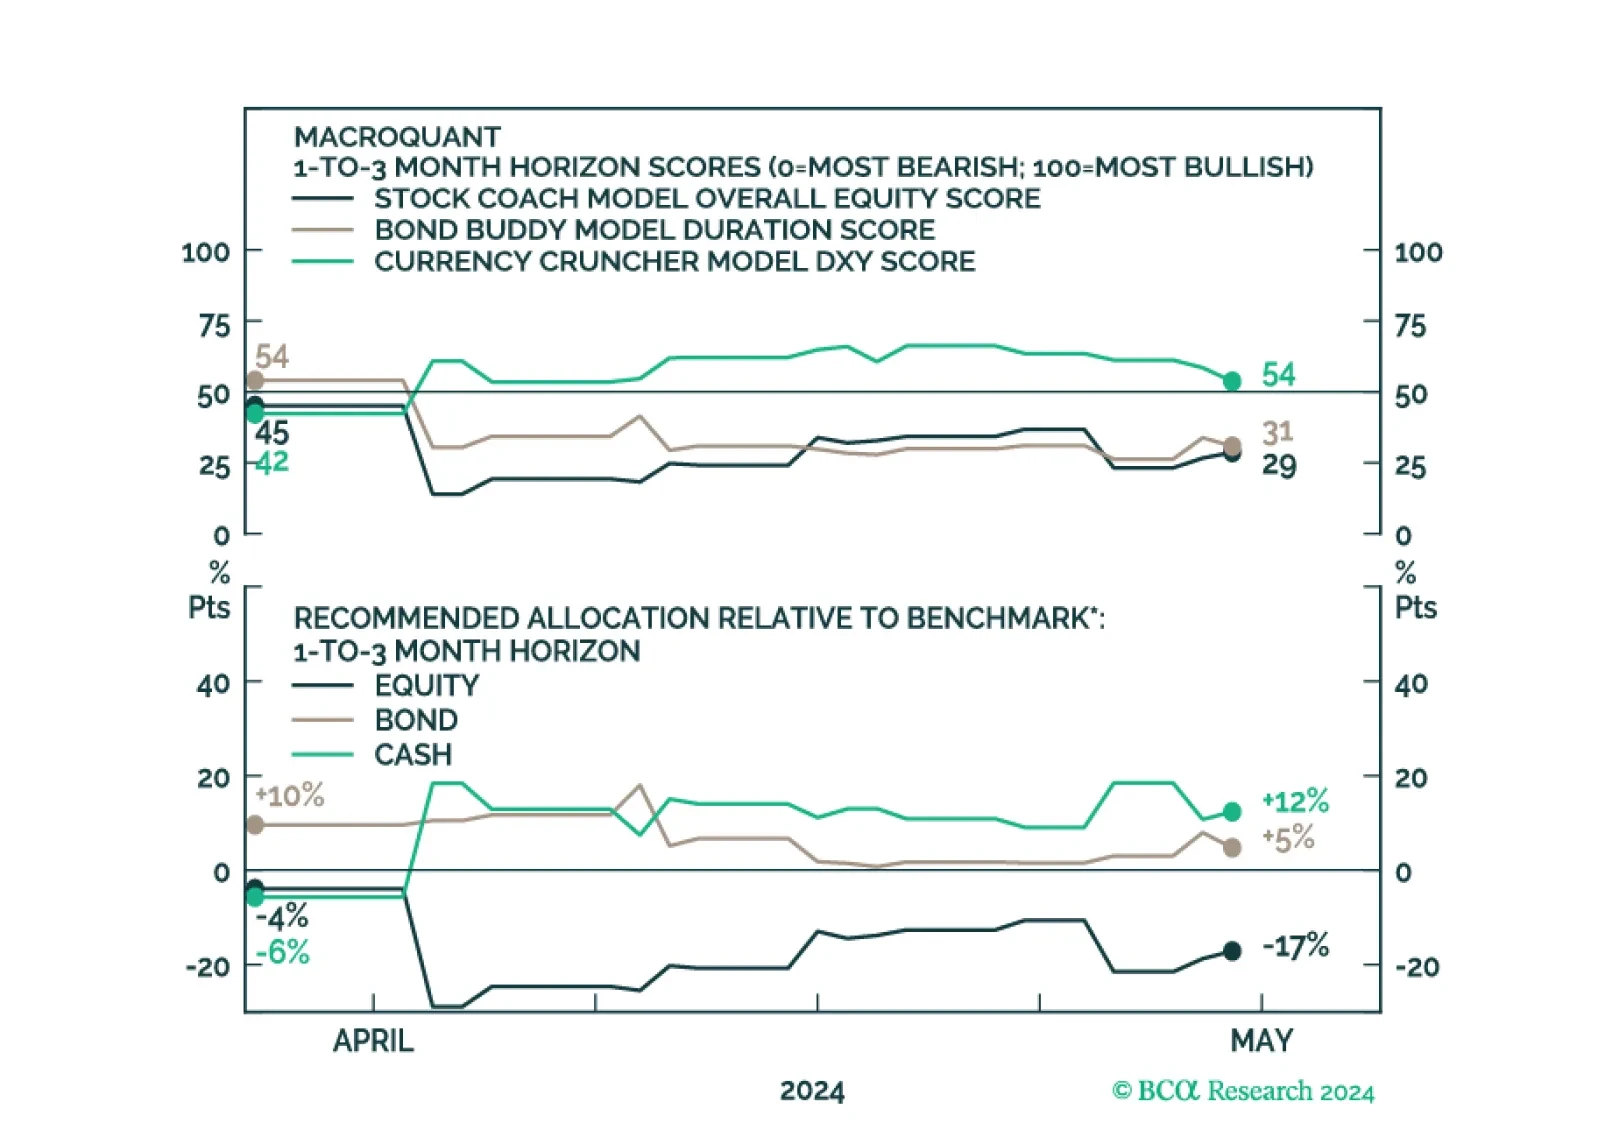
MacroQuant downgraded equities from neutral to underweight on a 1-to-3 month horizon. The model suggests increasing exposure to cash.
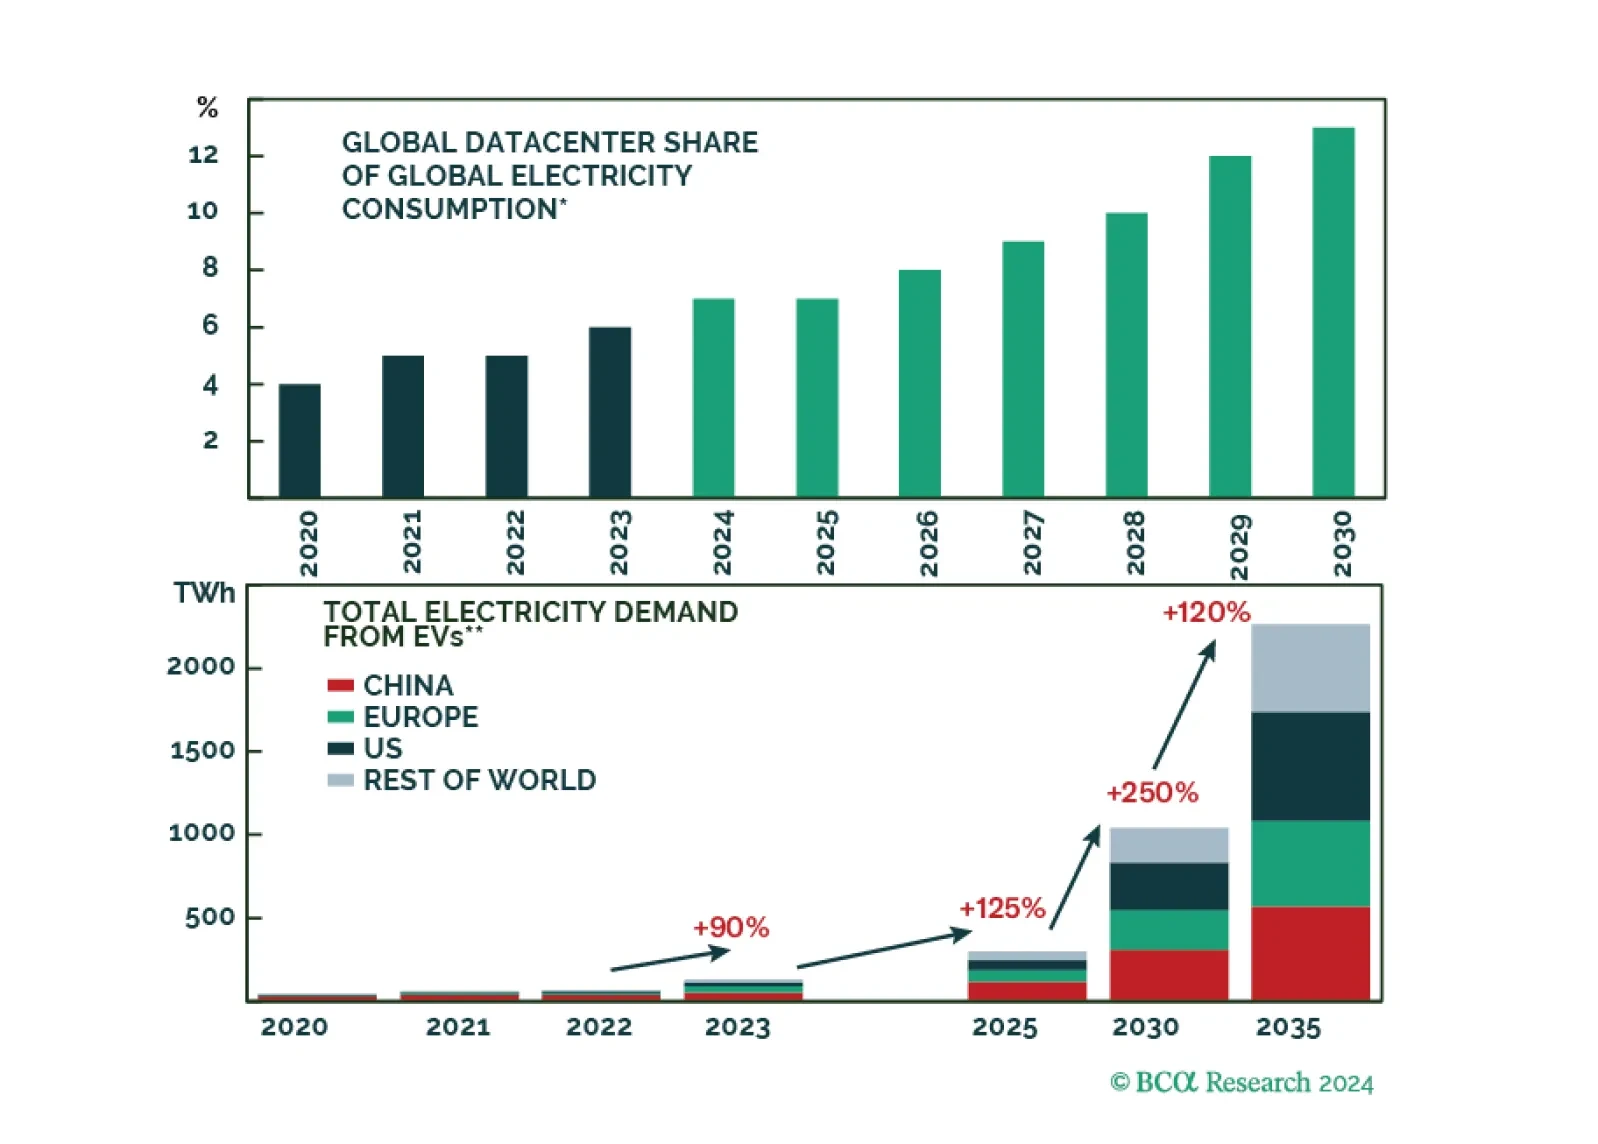
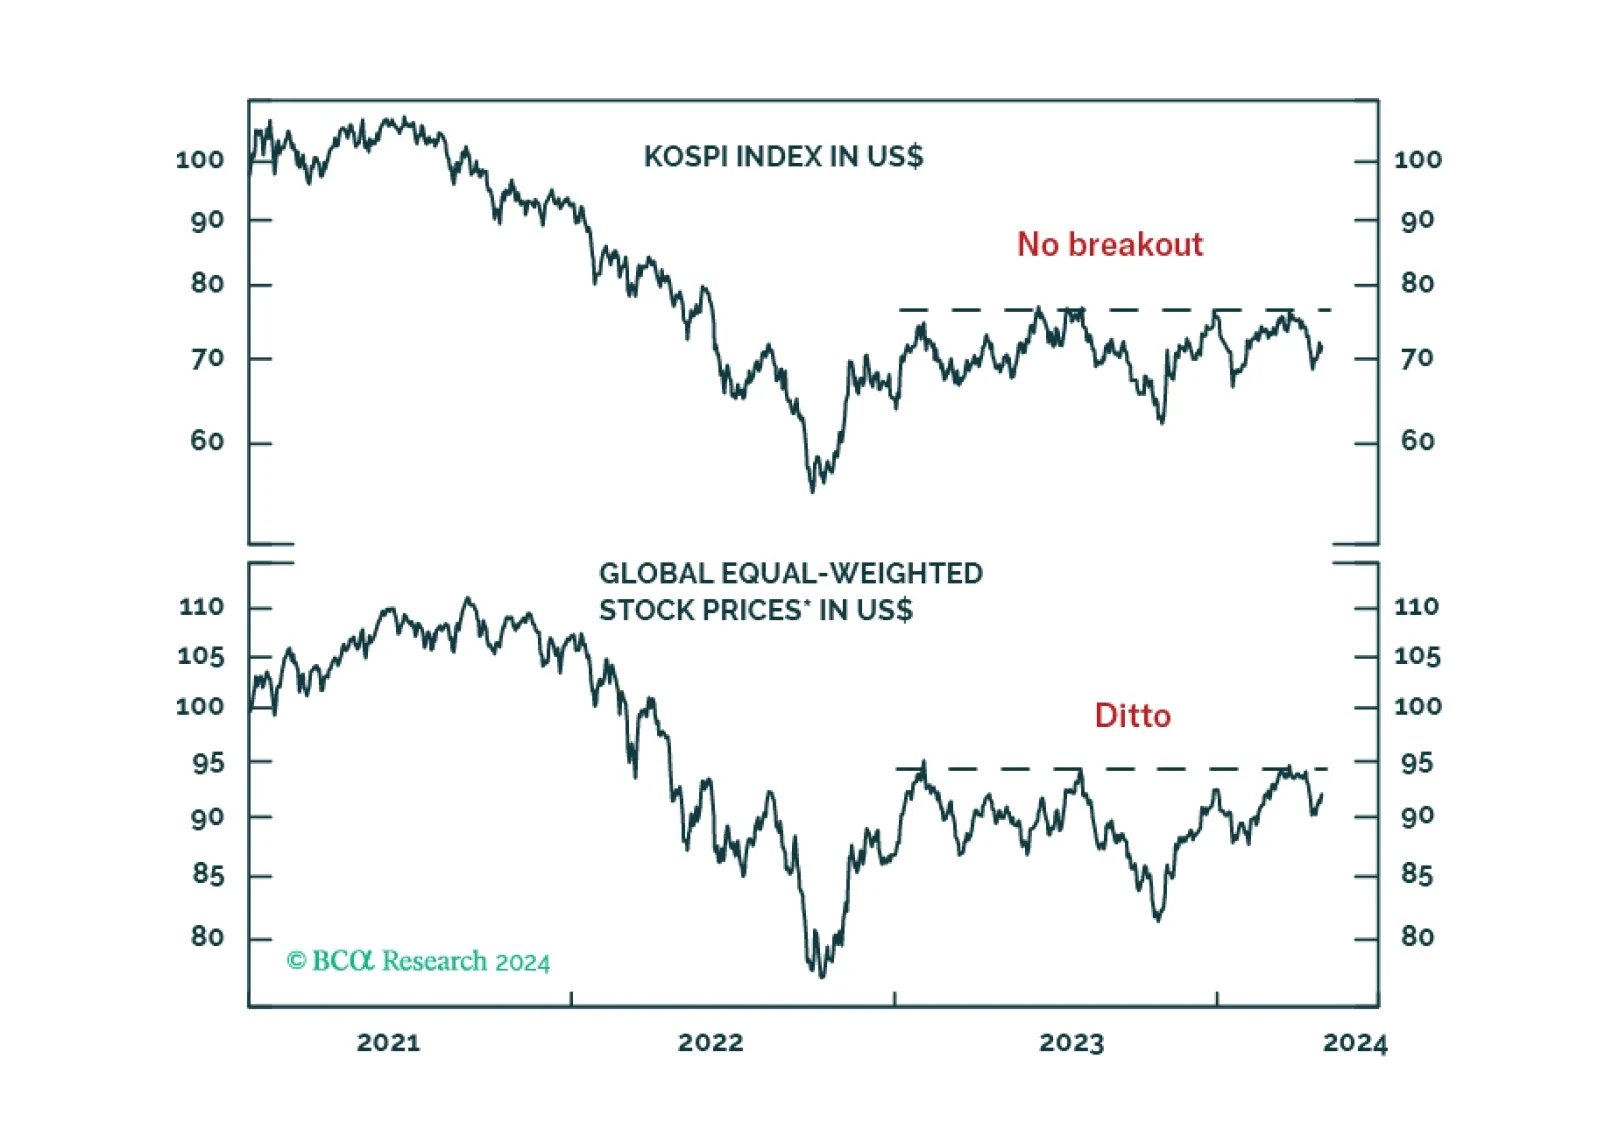
We are publishing the chart pack I used during my meetings with clients and prospects in Europe last week. It contains charts on China, global macro, and EM asset classes, all of which are mostly self-explanatory and convey my views and analysis.
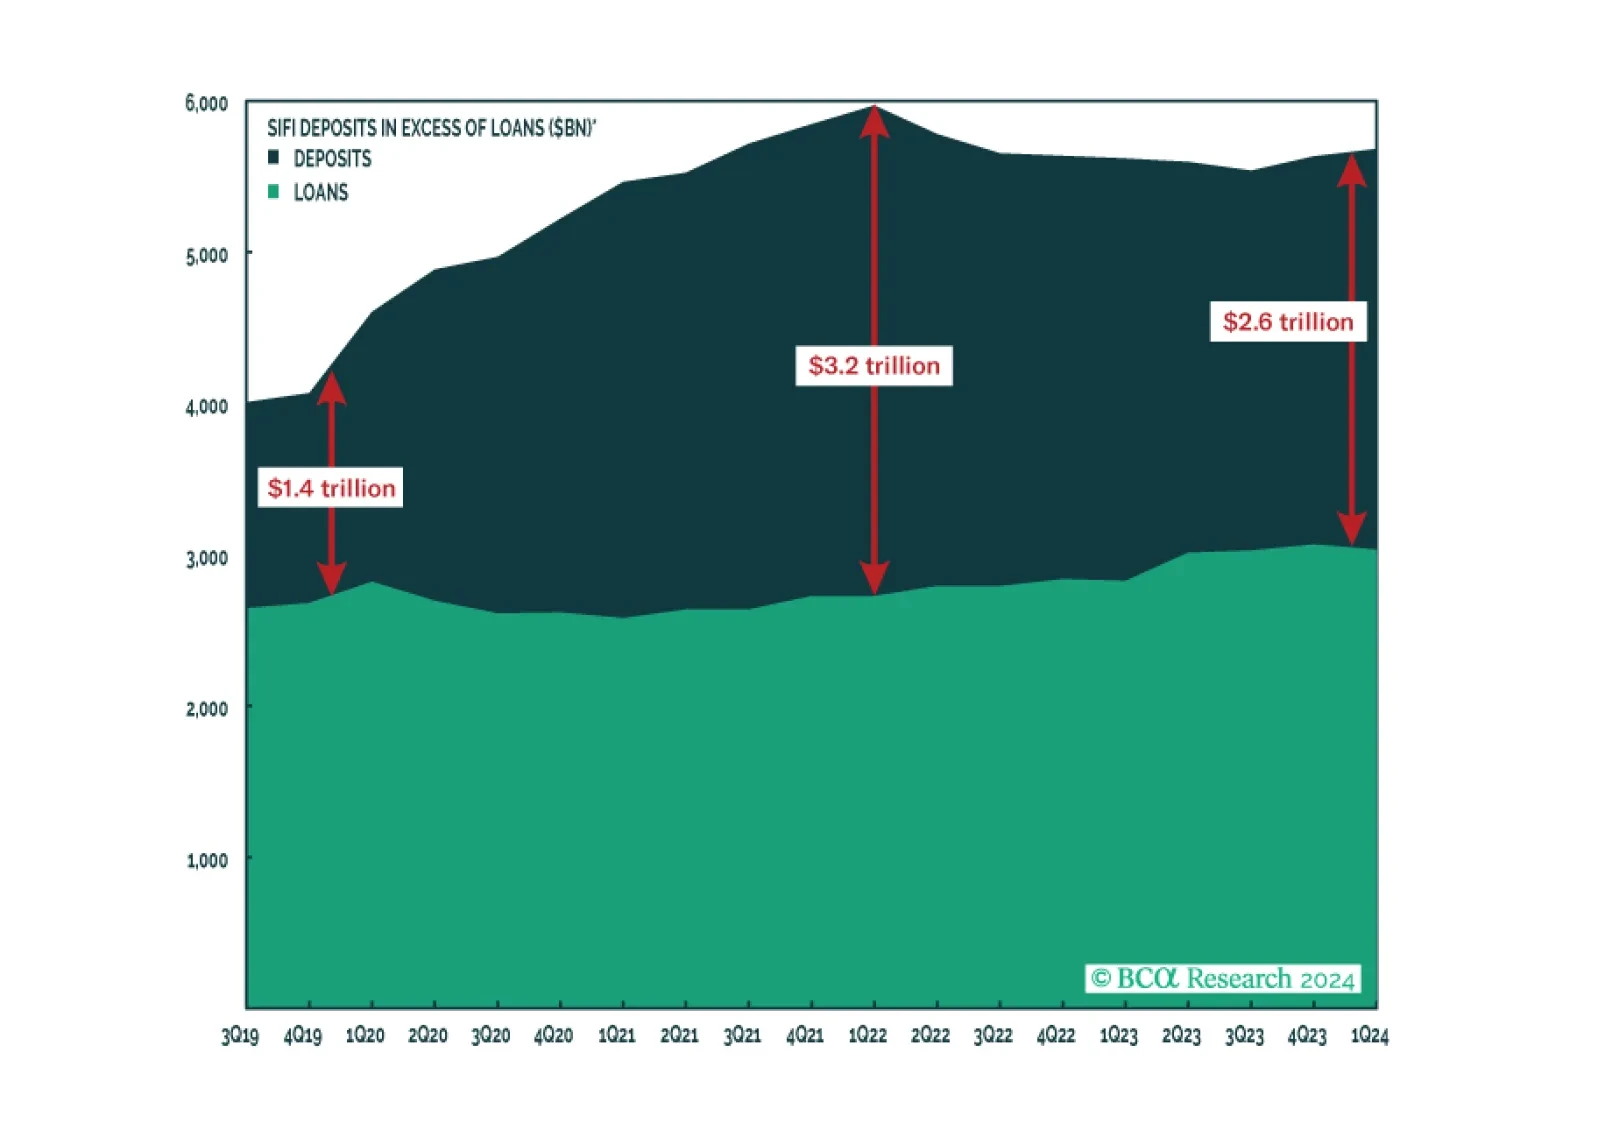
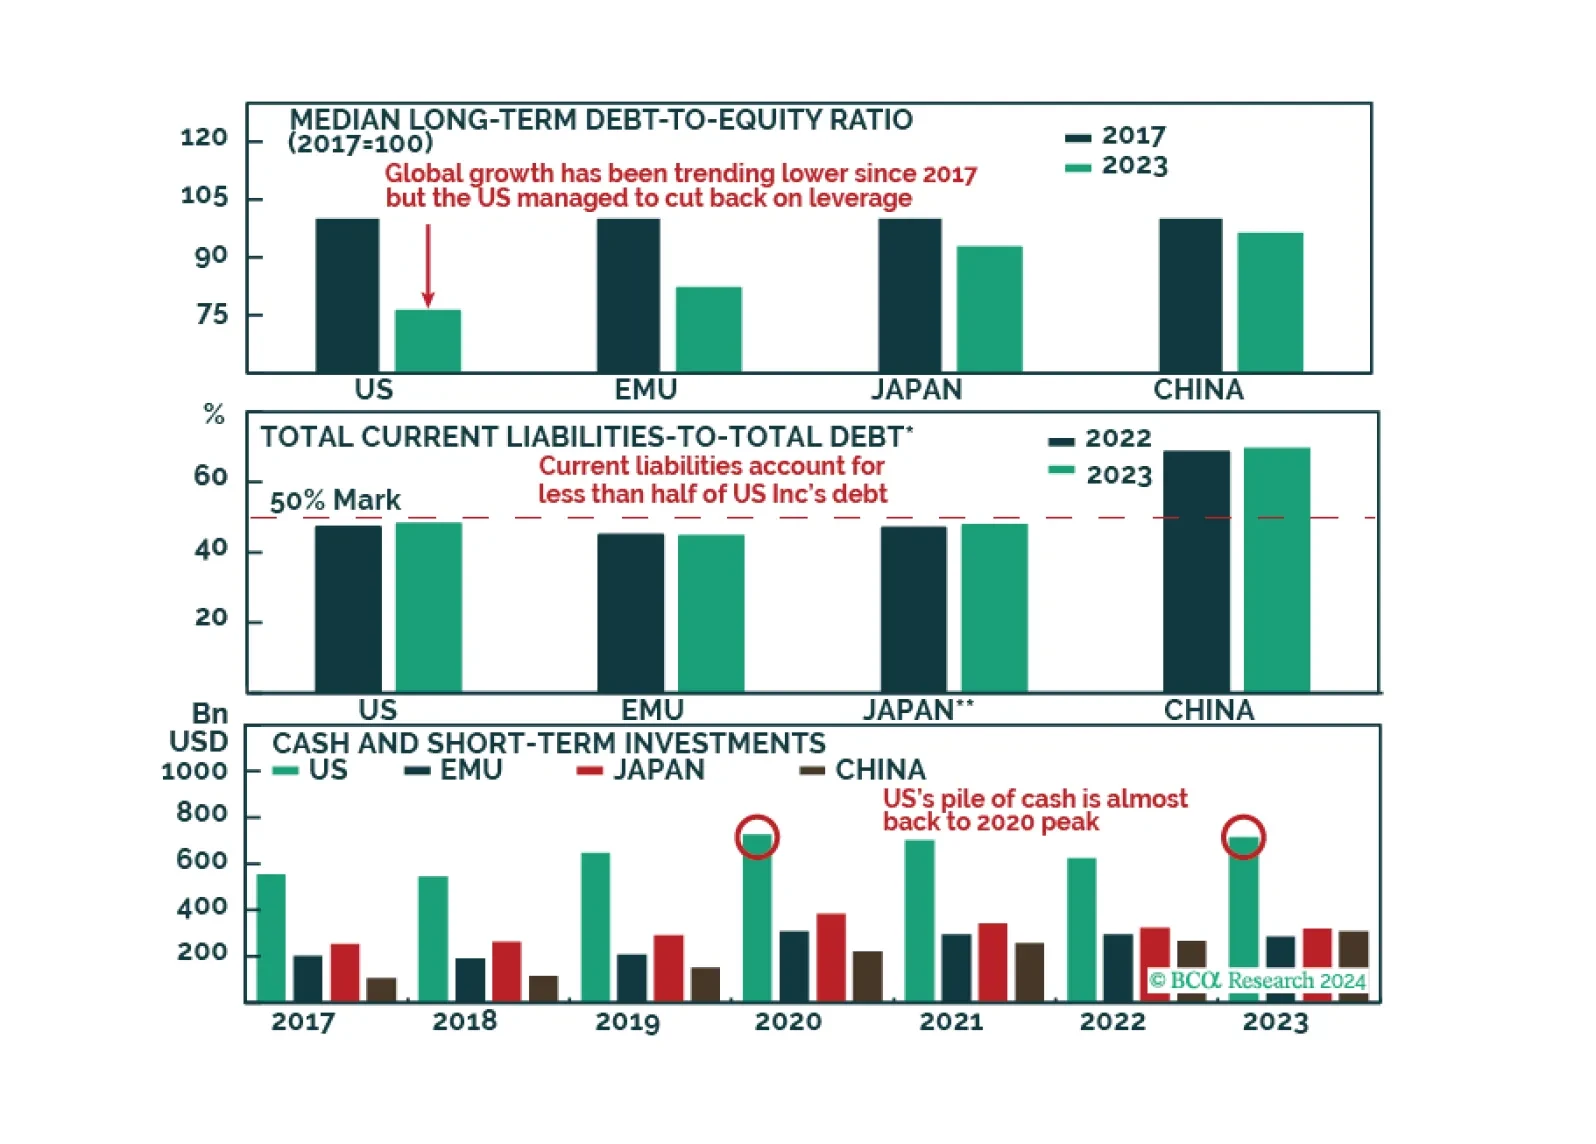
The latest edition of our Big Bank Beige Book suggests the expansion remains intact, though weakness in C’s private-label credit card portfolio could be a harbinger of distress among lower-income consumers. We remain tactically neutral with a bias to turn defensive once clearer signs of a recession emerge.
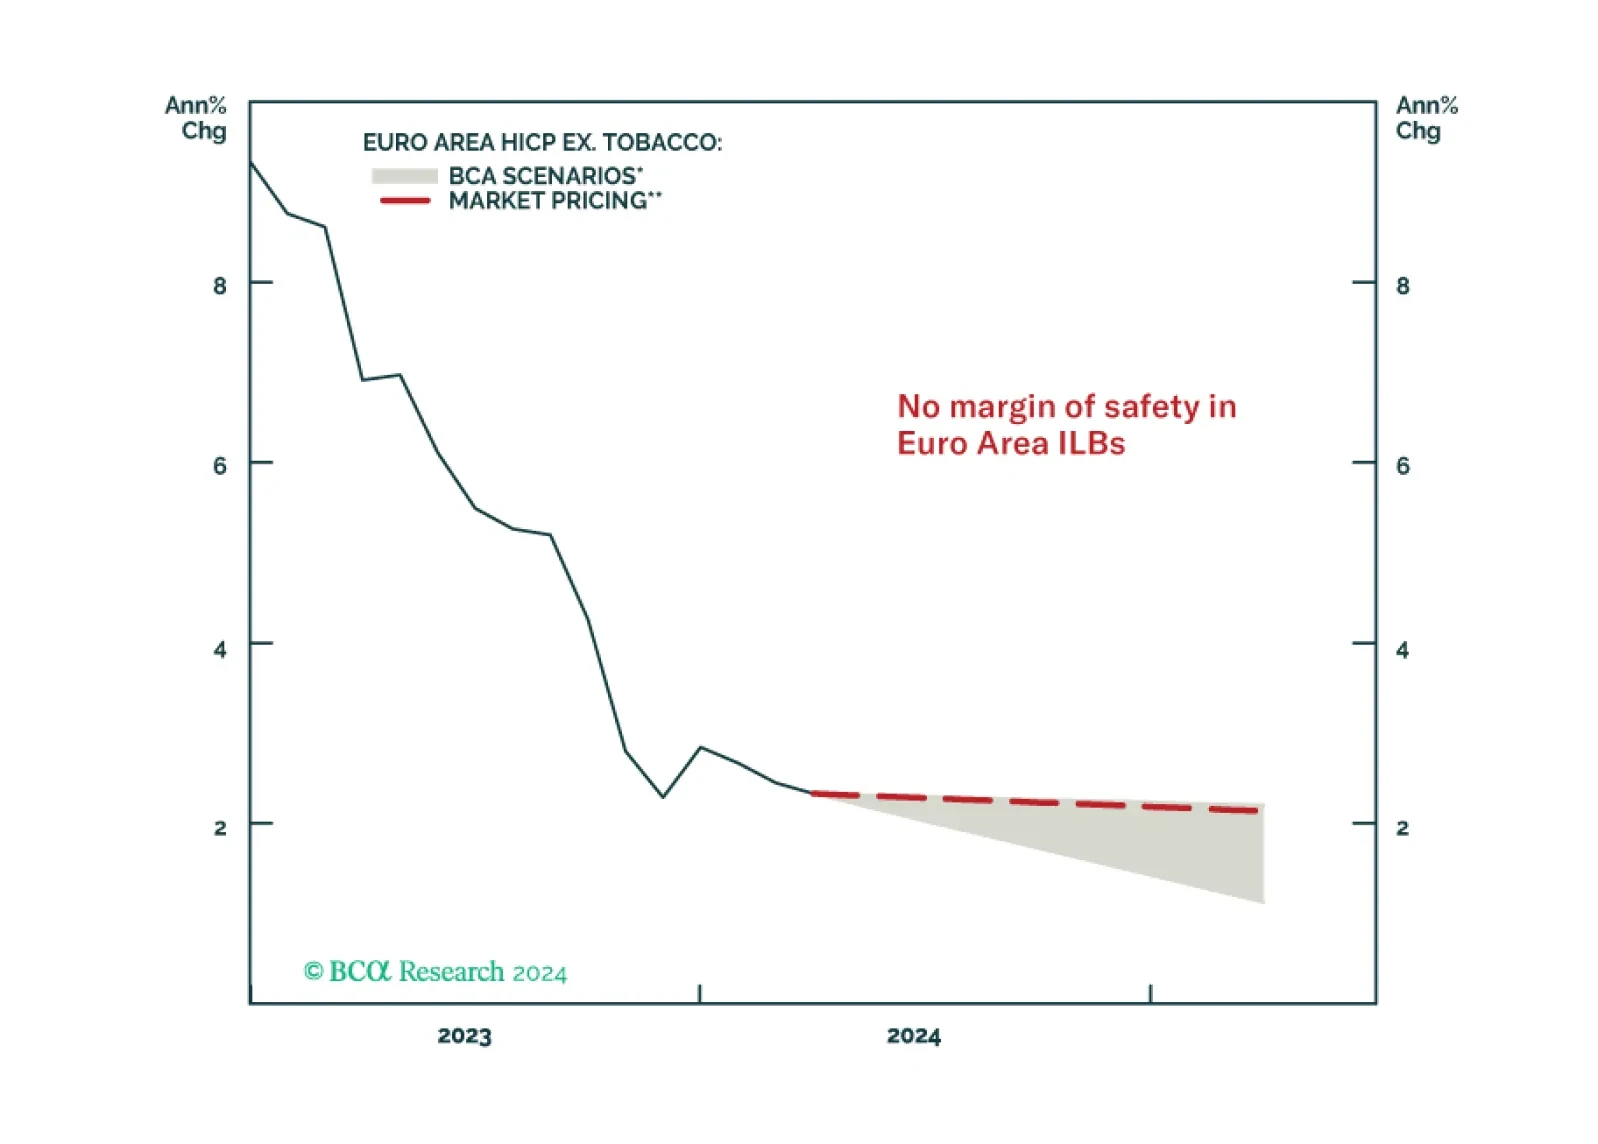
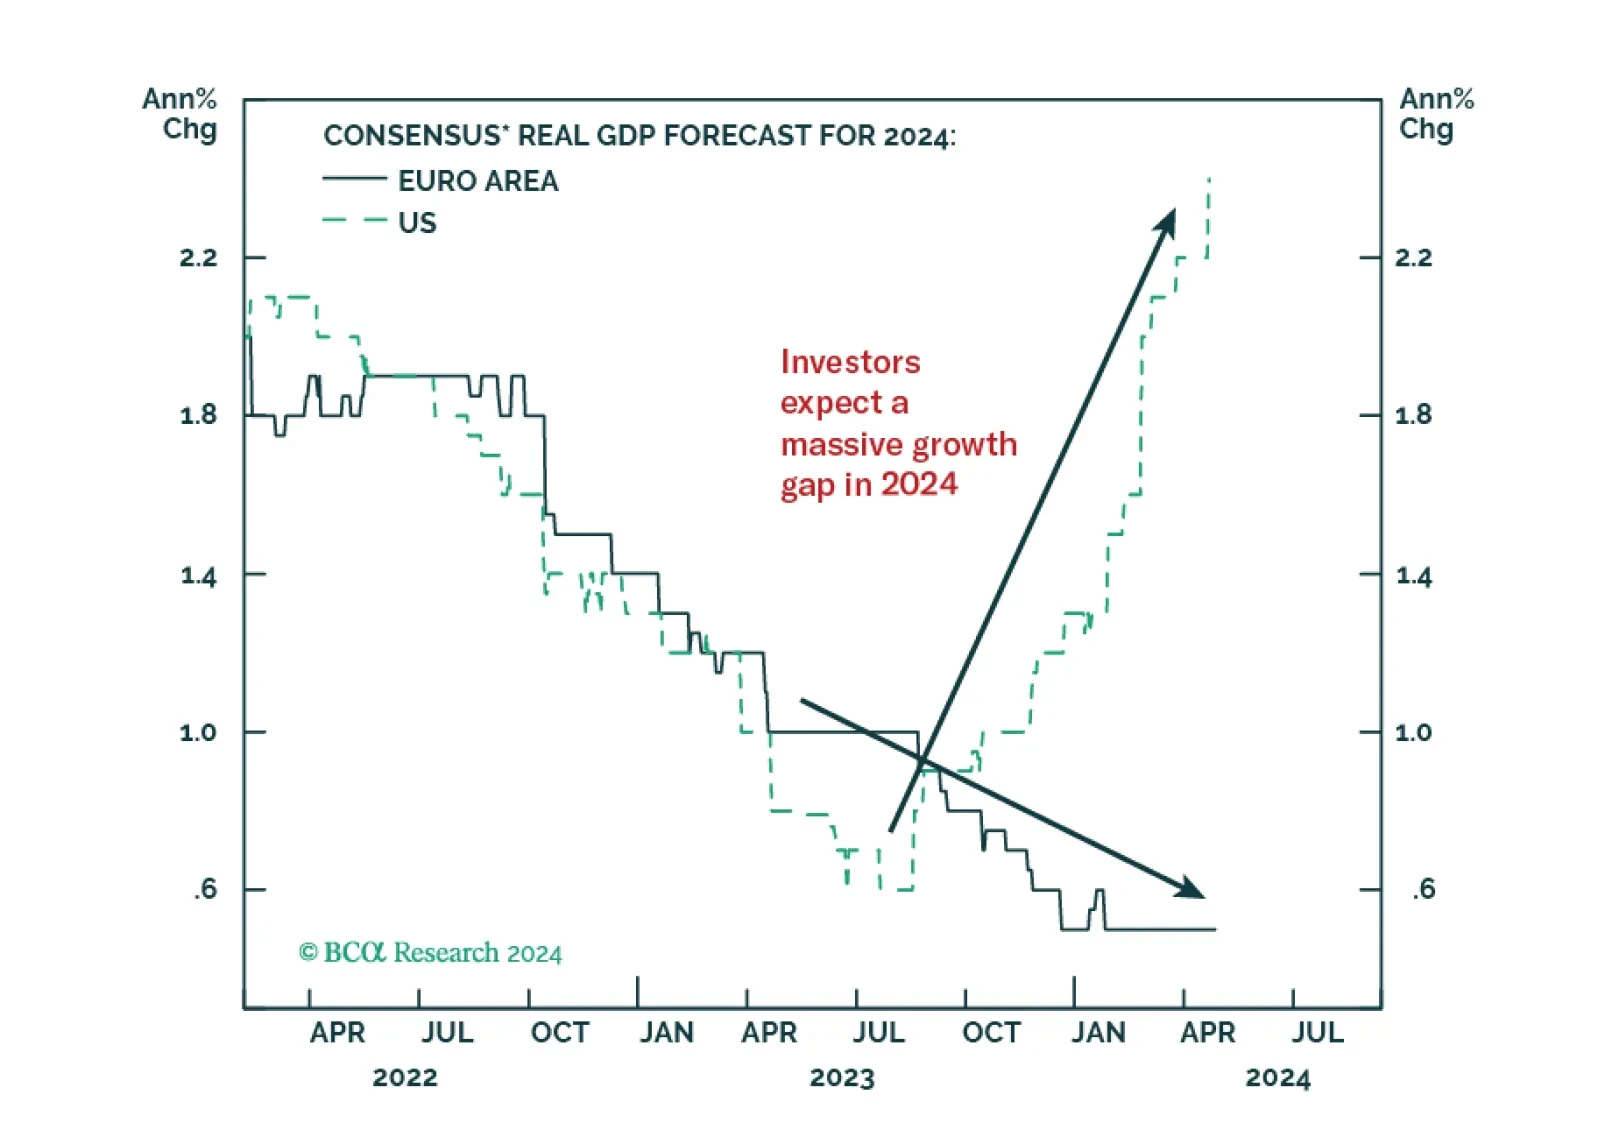
Investors anticipate a record growth gap between the US and the Eurozone in 2024. Does this skewed expectation create market opportunities?
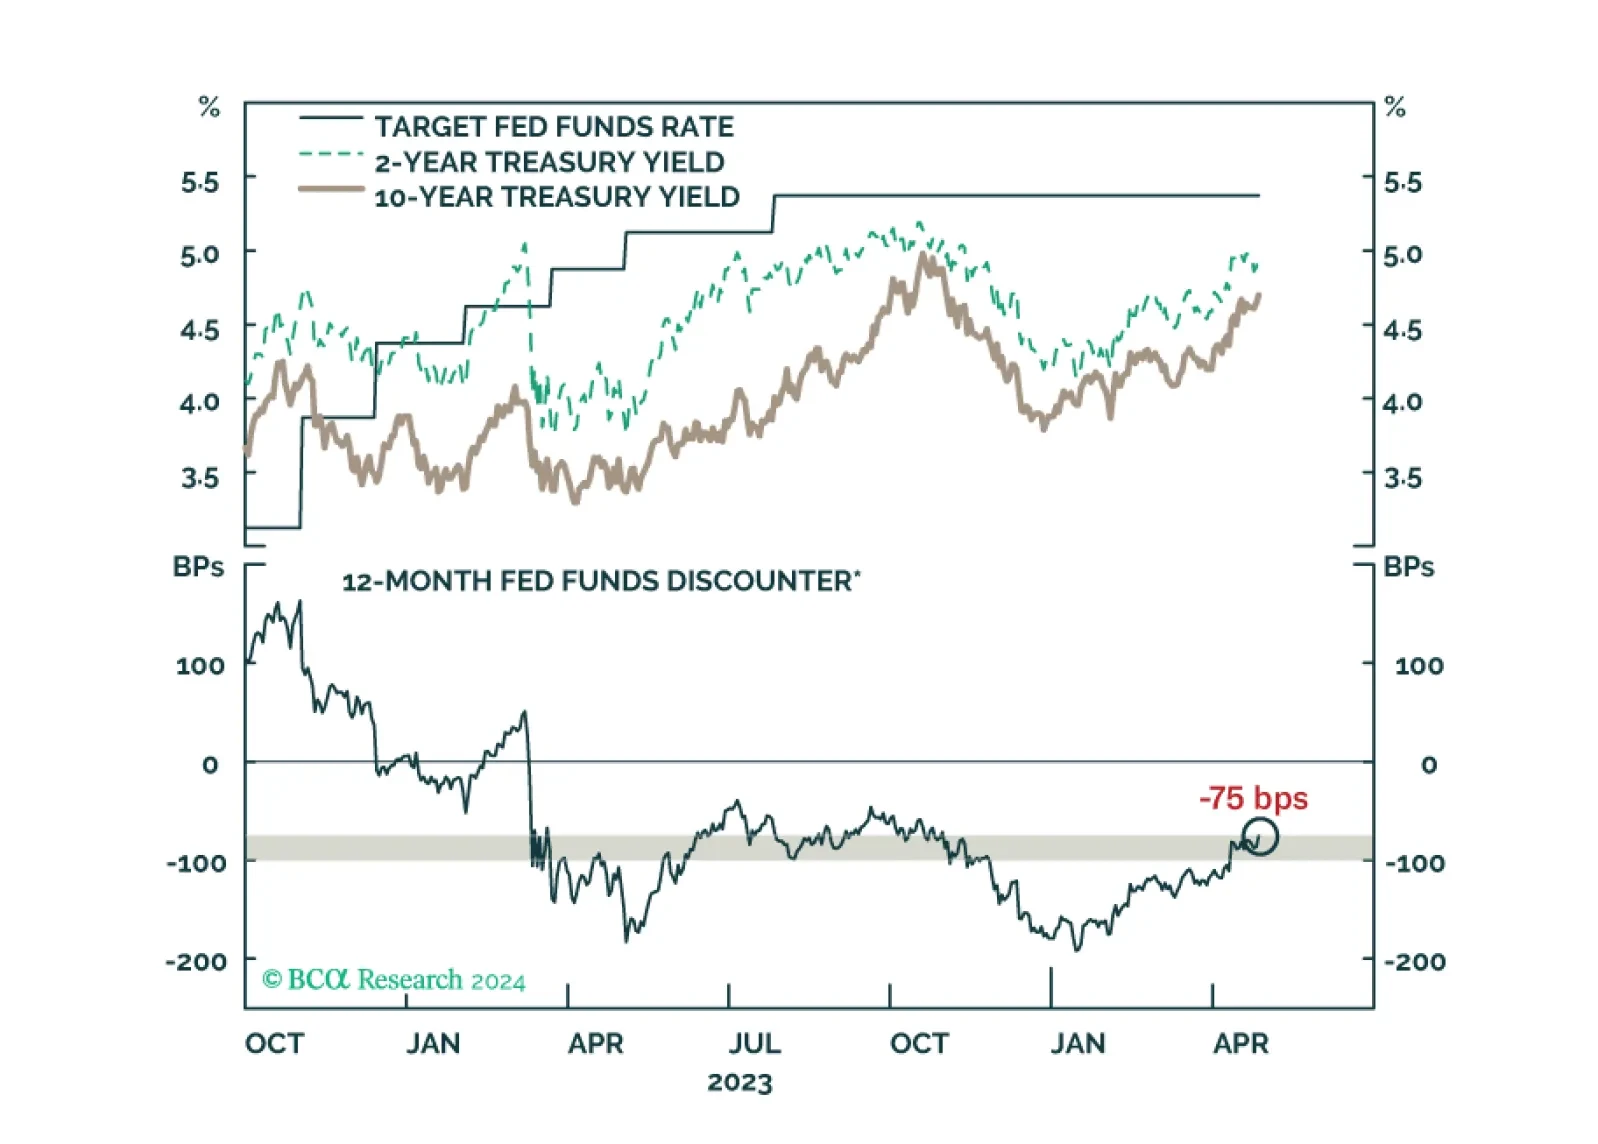
Our latest views on the recent increase in Treasury yields and some key things to watch at next week’s FOMC meeting.
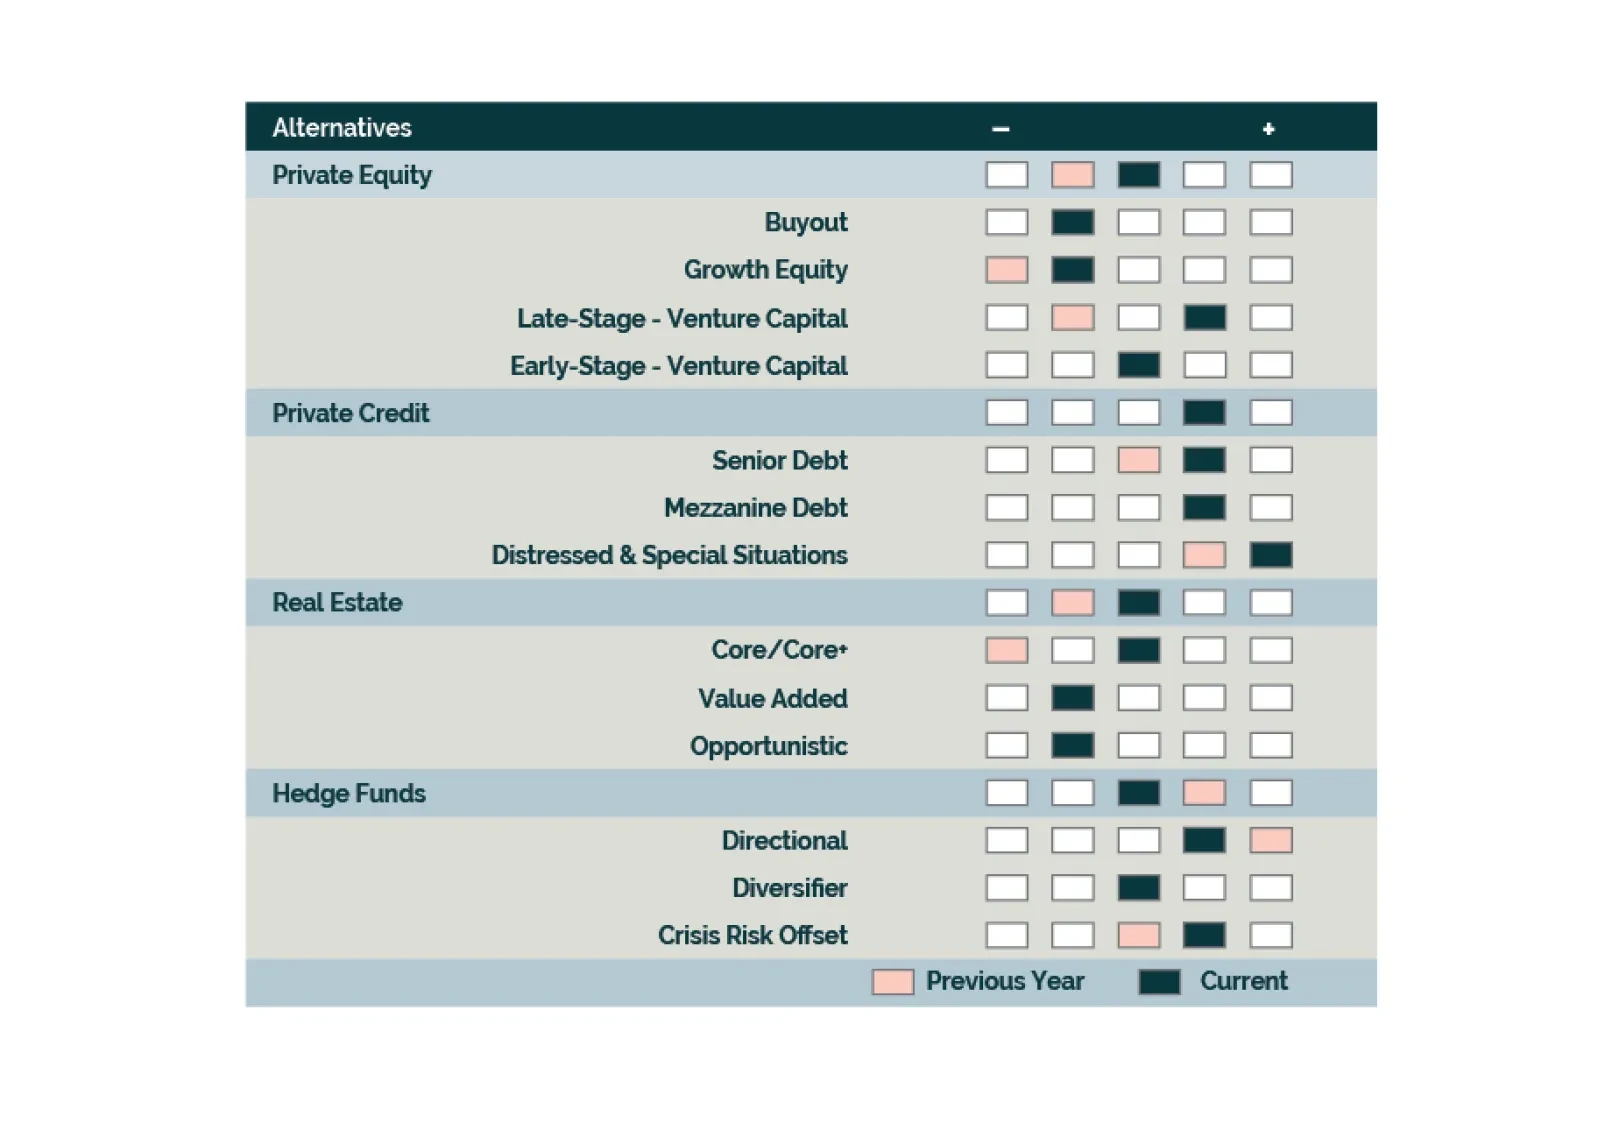
We go overweight Late-Stage Venture Capital and APAC Private Equity but remain underweight North America Buyouts. We maintain our neutral outlook towards Hedge Funds and are positive on Long-Short Equity, Event Driven, and CRO strategies. We are cooling towards Direct Lending strategies as competition and relative opportunities increase. CRE’s downturn continues to unfold; we are starting to be buyers.