Skip to main content

Latest from BCA Research
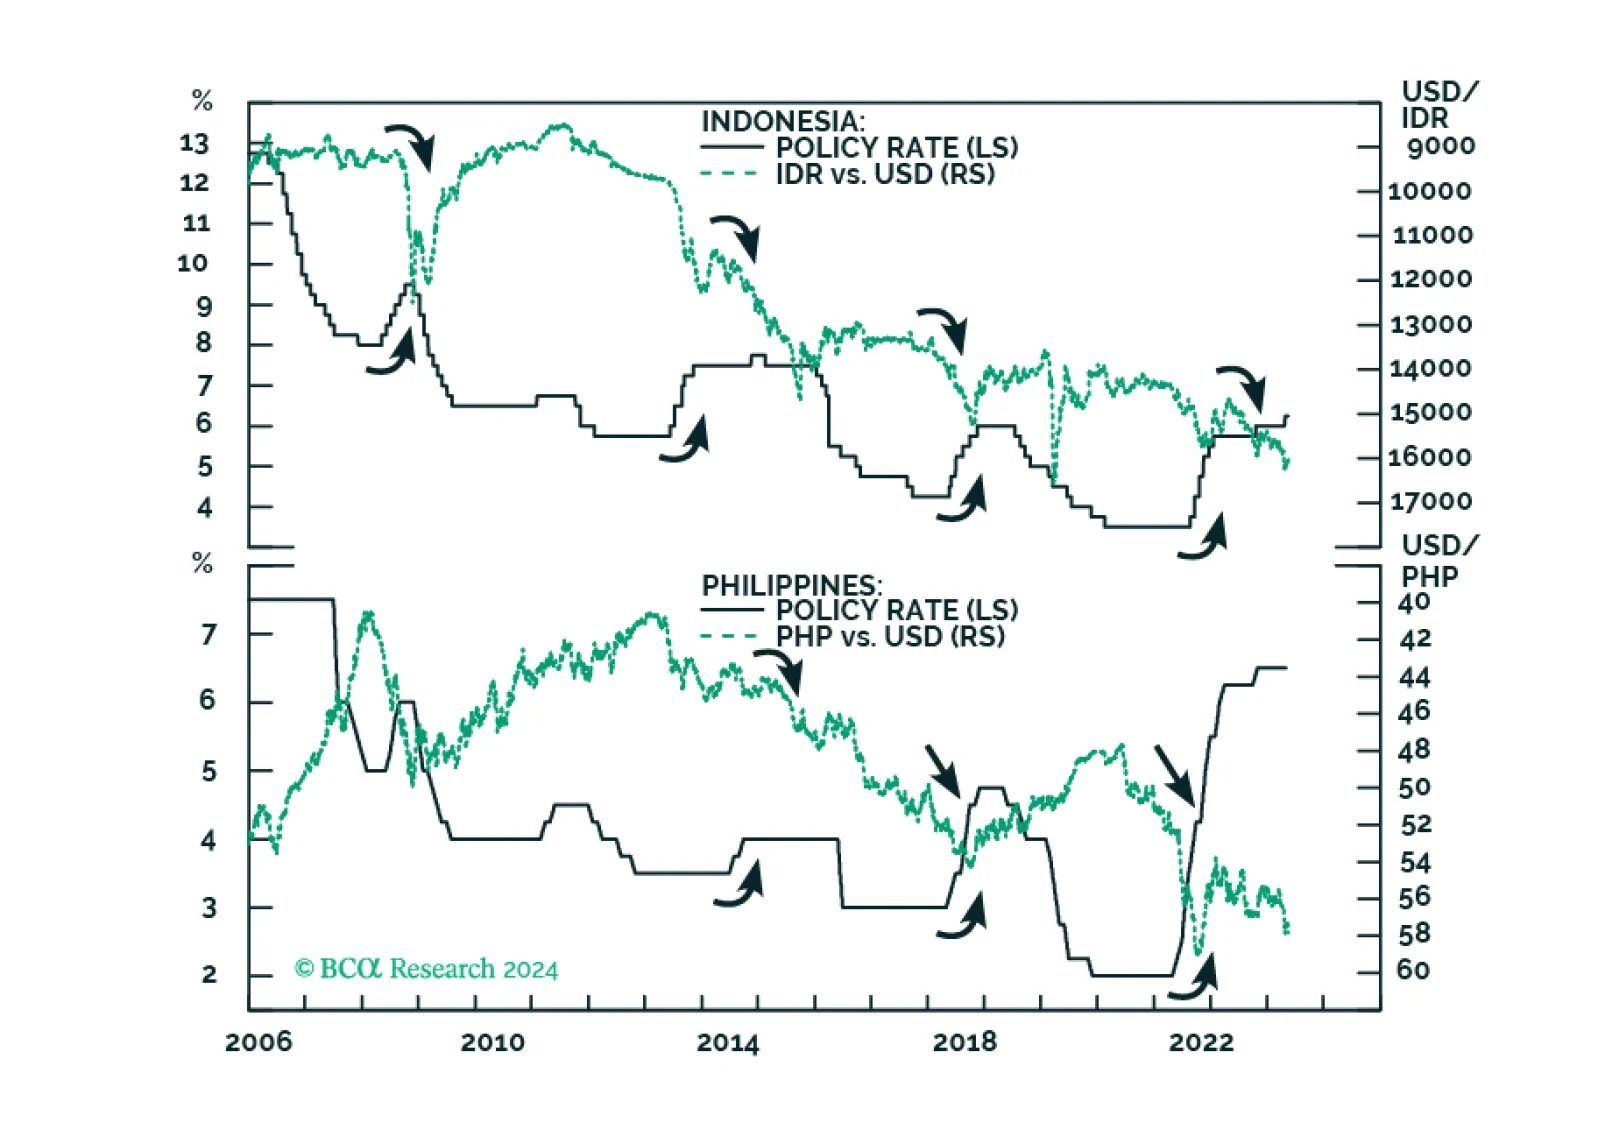
ASEAN stocks and currencies will weaken further as these economies face multiple headwinds. Raising policy rates did not stop a sliding currency in the past, it is unlikely to do so now.
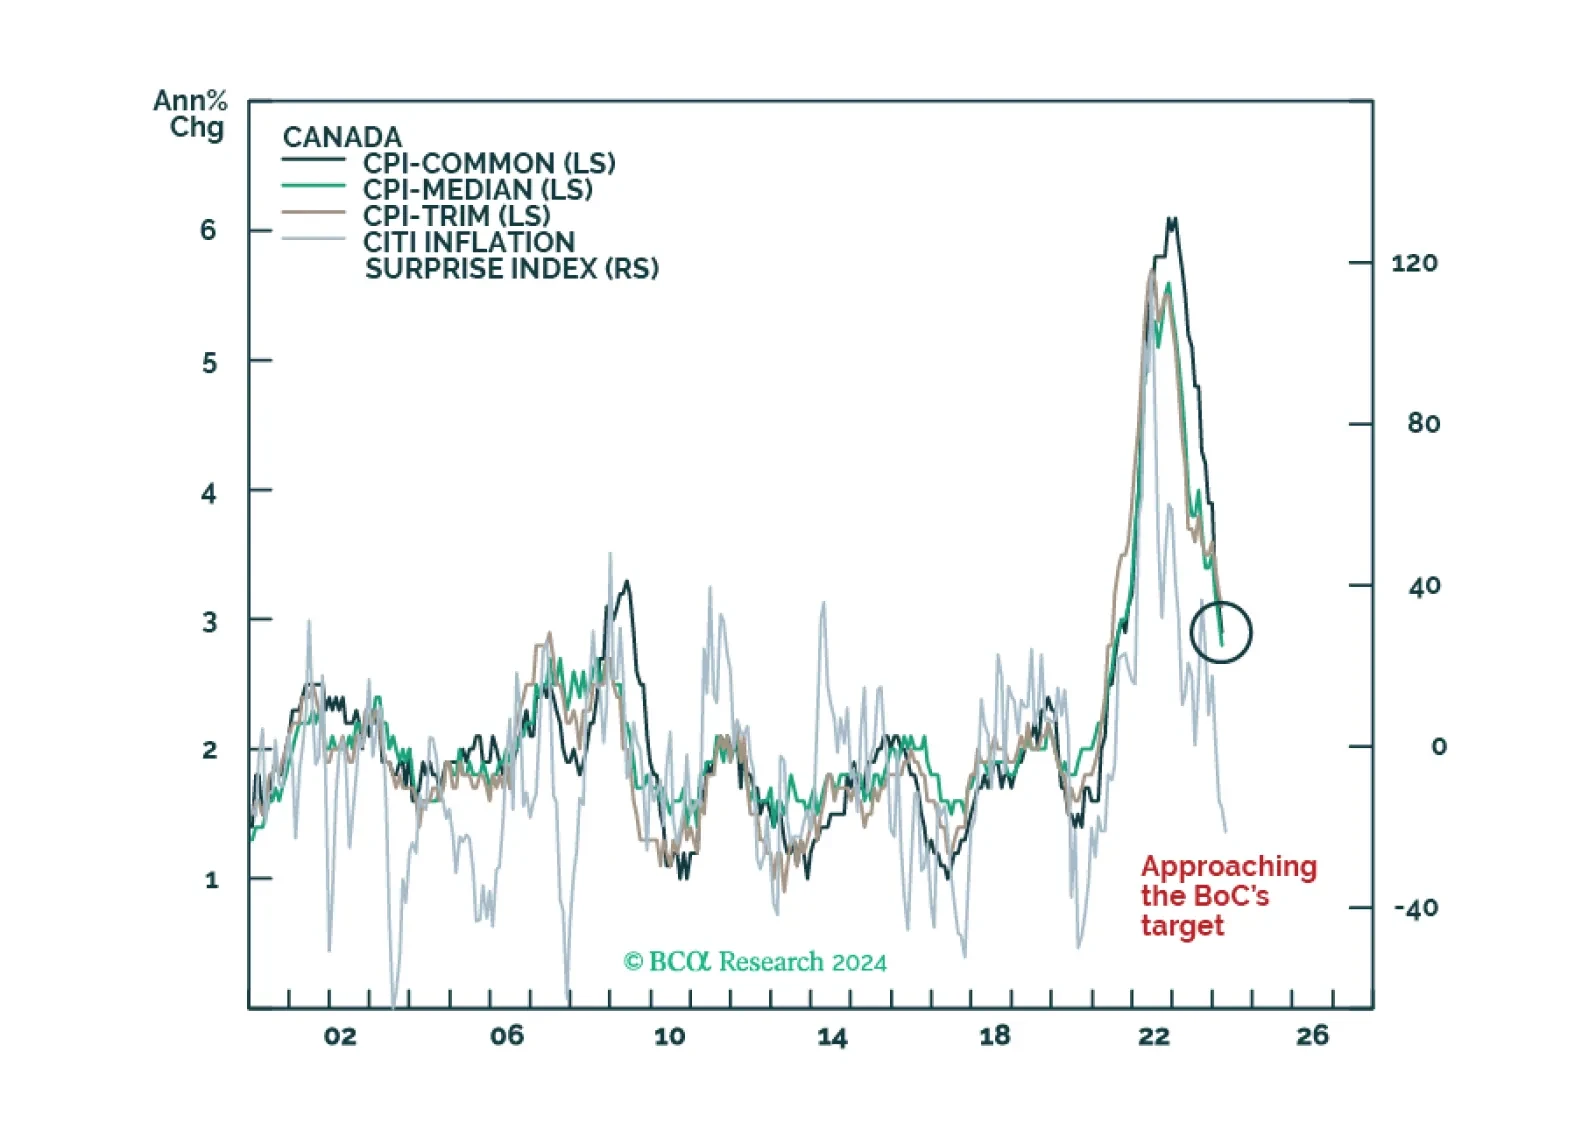
Special Report This Special Report argues that rate cuts will come sooner in Canada than the US and offers how investors can profit from this.
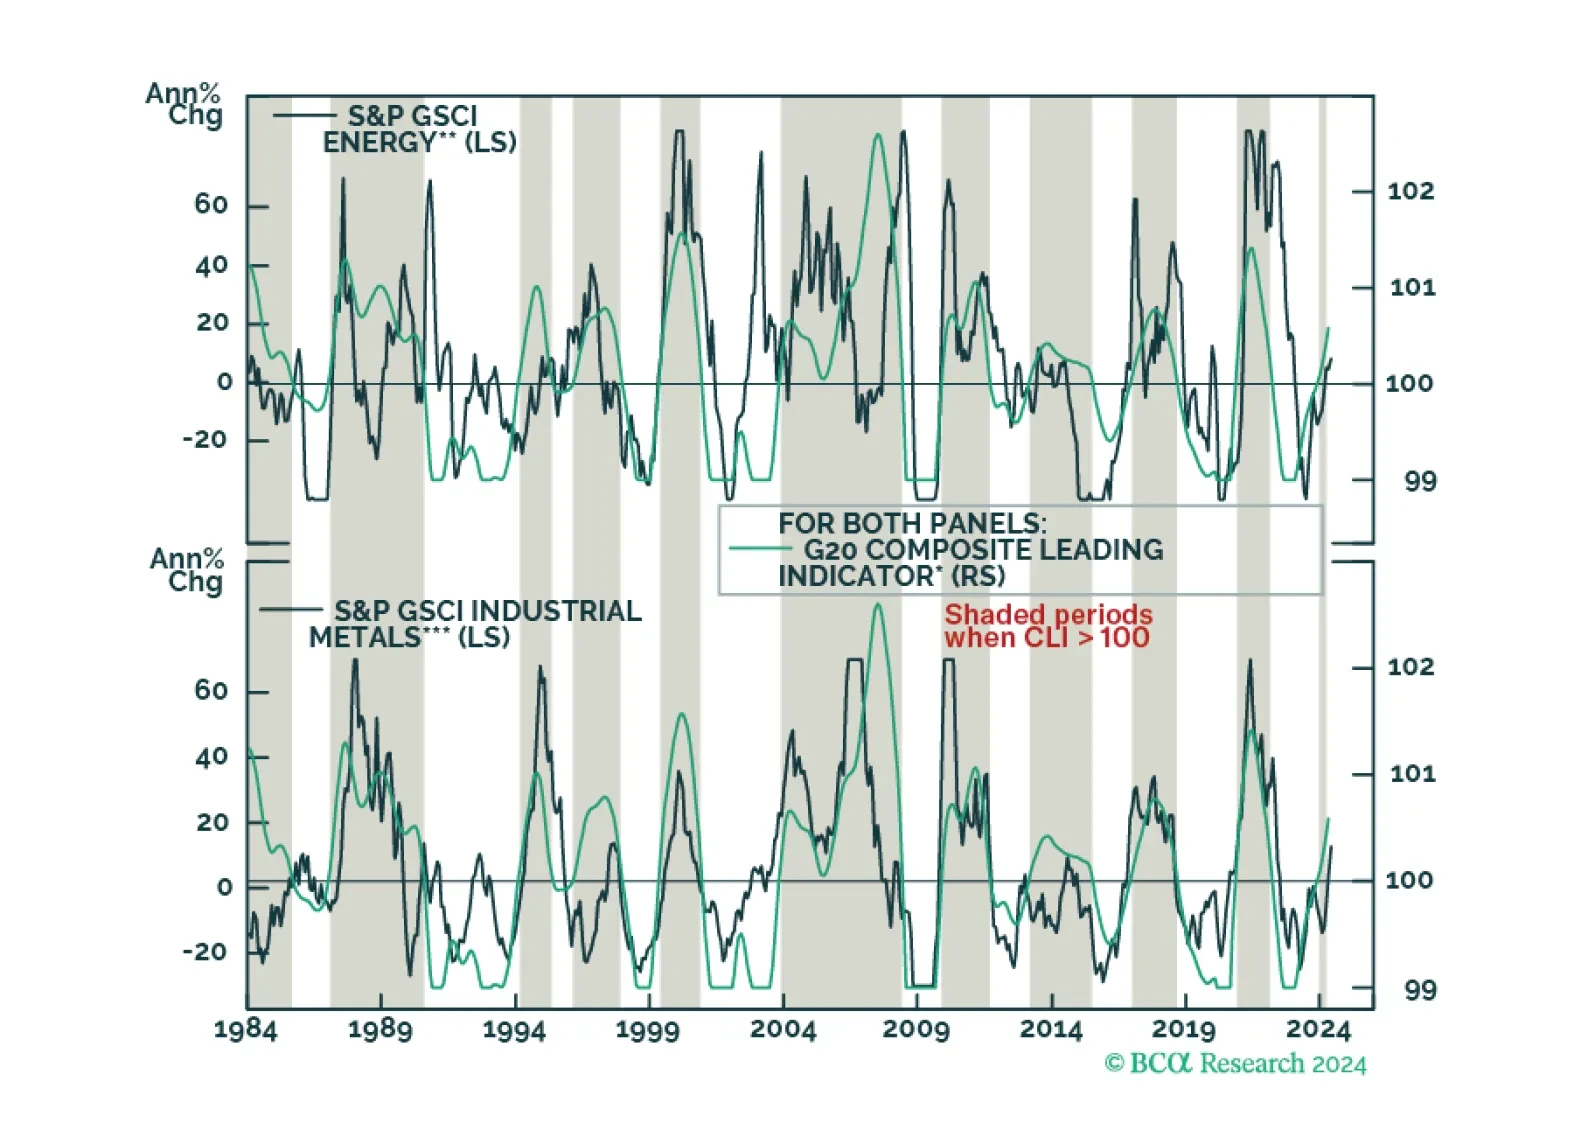
Special Report Varying degrees of exposure to certain economic sectors and regions can help explain differences in performance across commodities. This report uncovers some of these differences. In doing so, it presents our framework for analyzing commodities from a business cycle perspective.
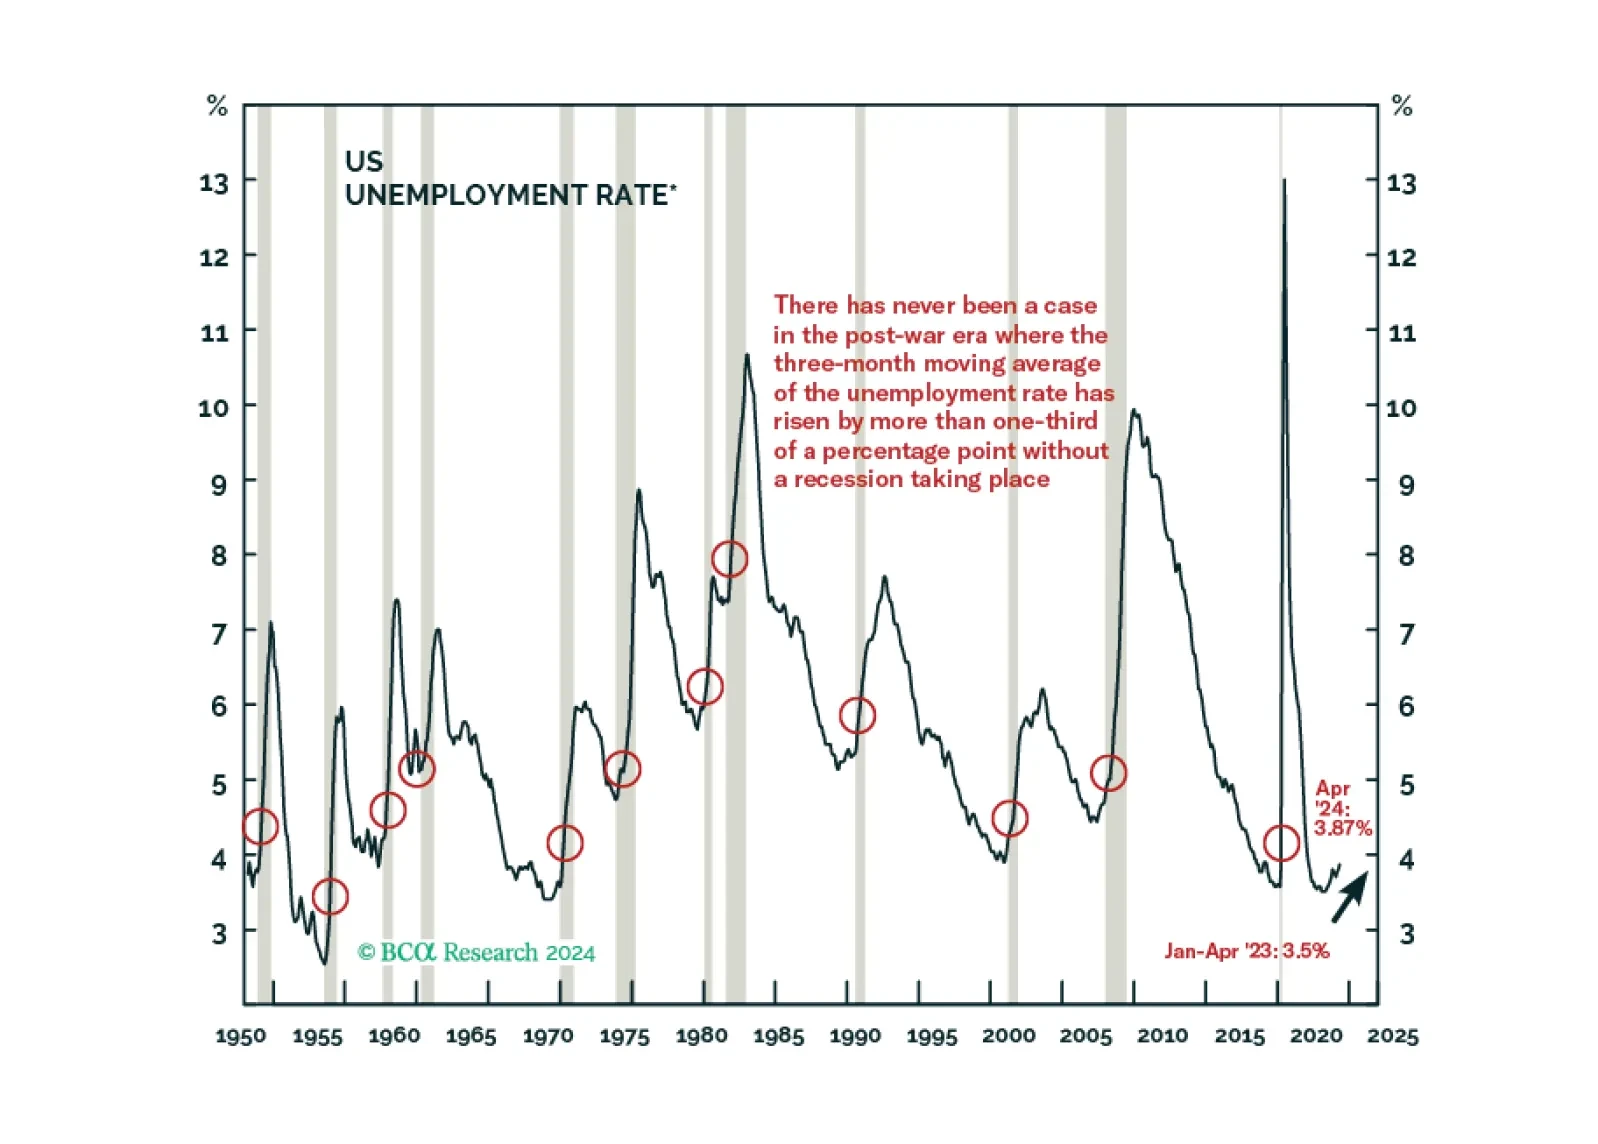
The stock market will suffer a setback from the weakening labor market and a rebound in US and global policy uncertainty.
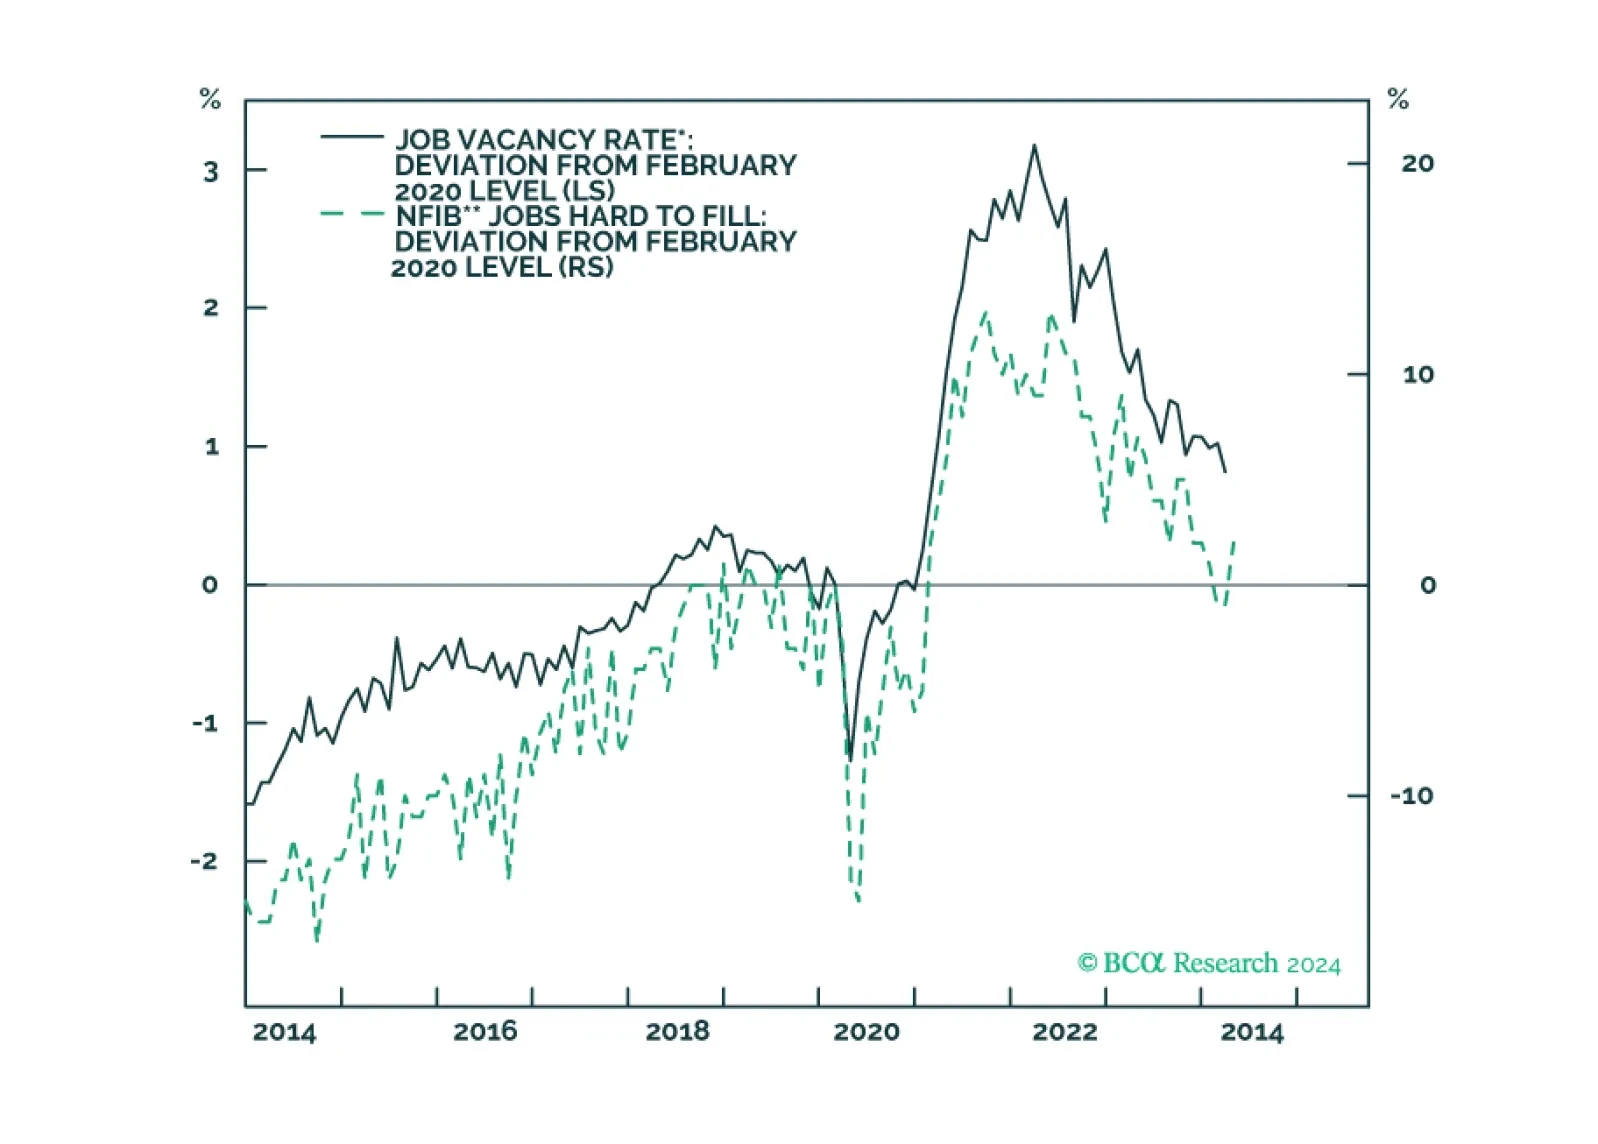
Our updated views on Treasury yields and Fed policy following this morning’s CPI report.
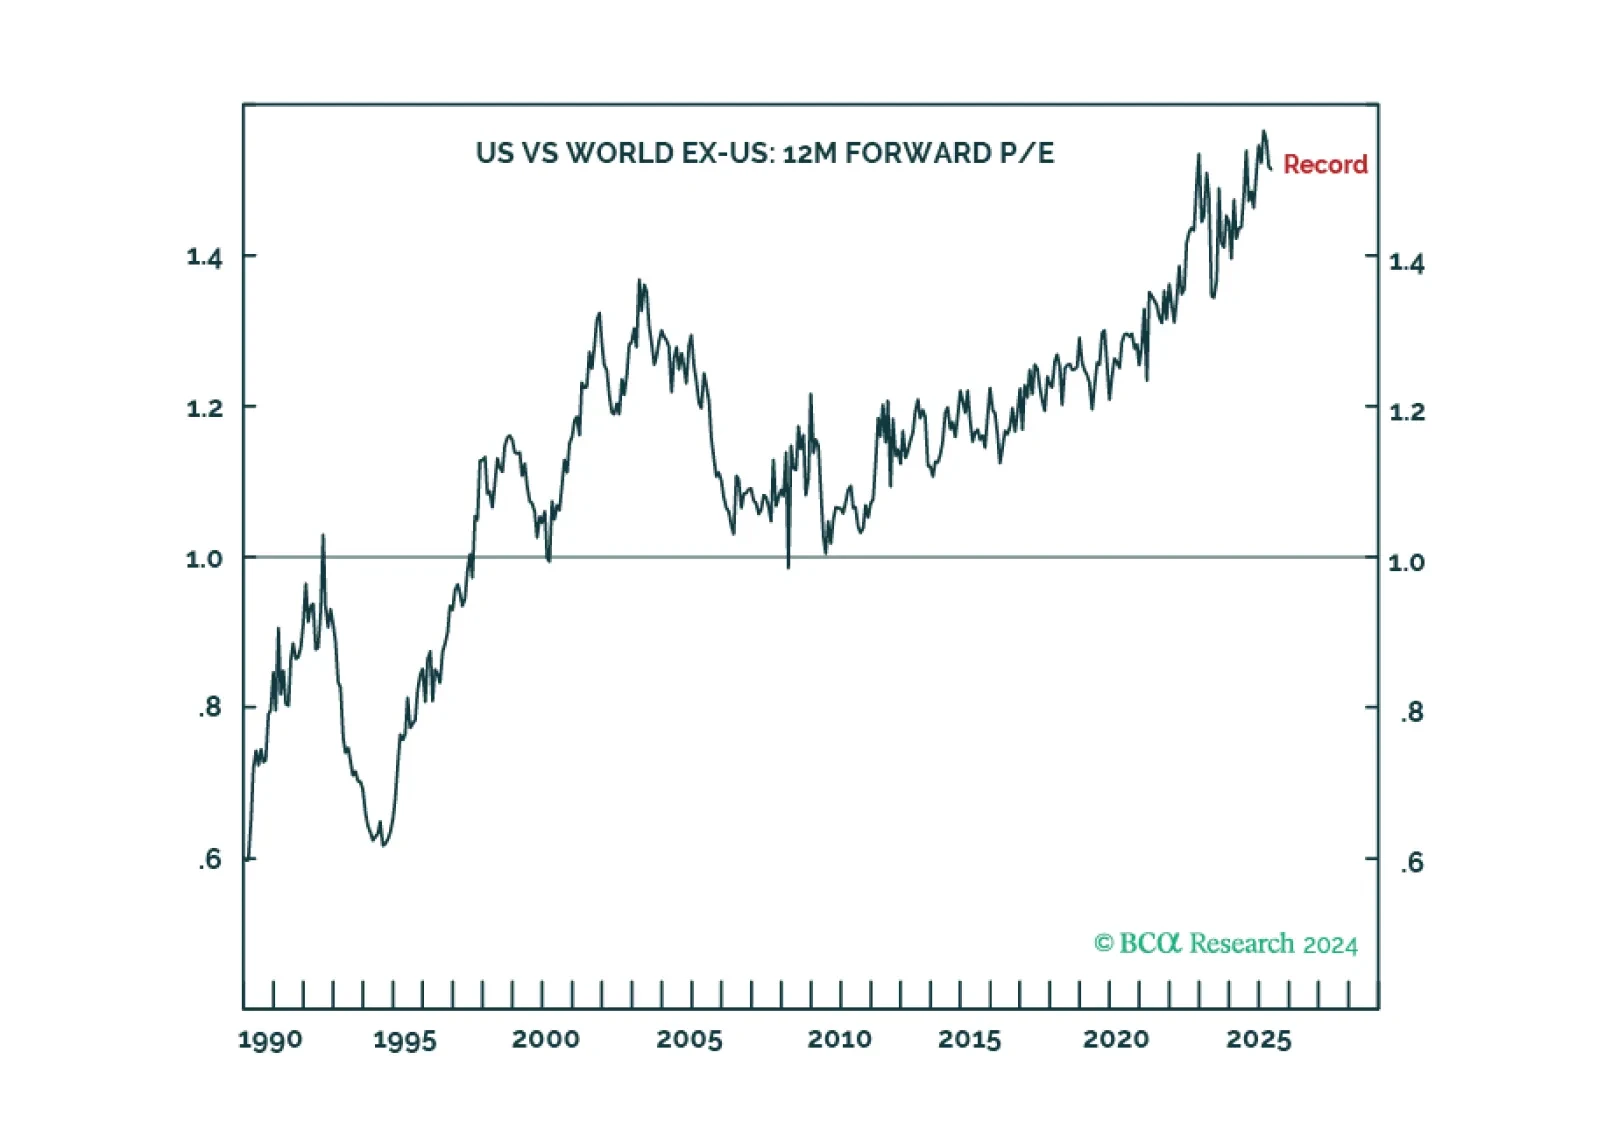
Special Report The US stock market’s record 50 percent valuation premium versus the non-US stock market is pricing generative AI to do through the next decade what the Web 2.0 network effect did through the last decade. But this is a huge ask, as it will be very difficult for the Web 2.0 superstar companies to become generative AI superstar companies, assuming there are indeed any lasting generative AI superstar companies. We go through the main long-term investment implications.
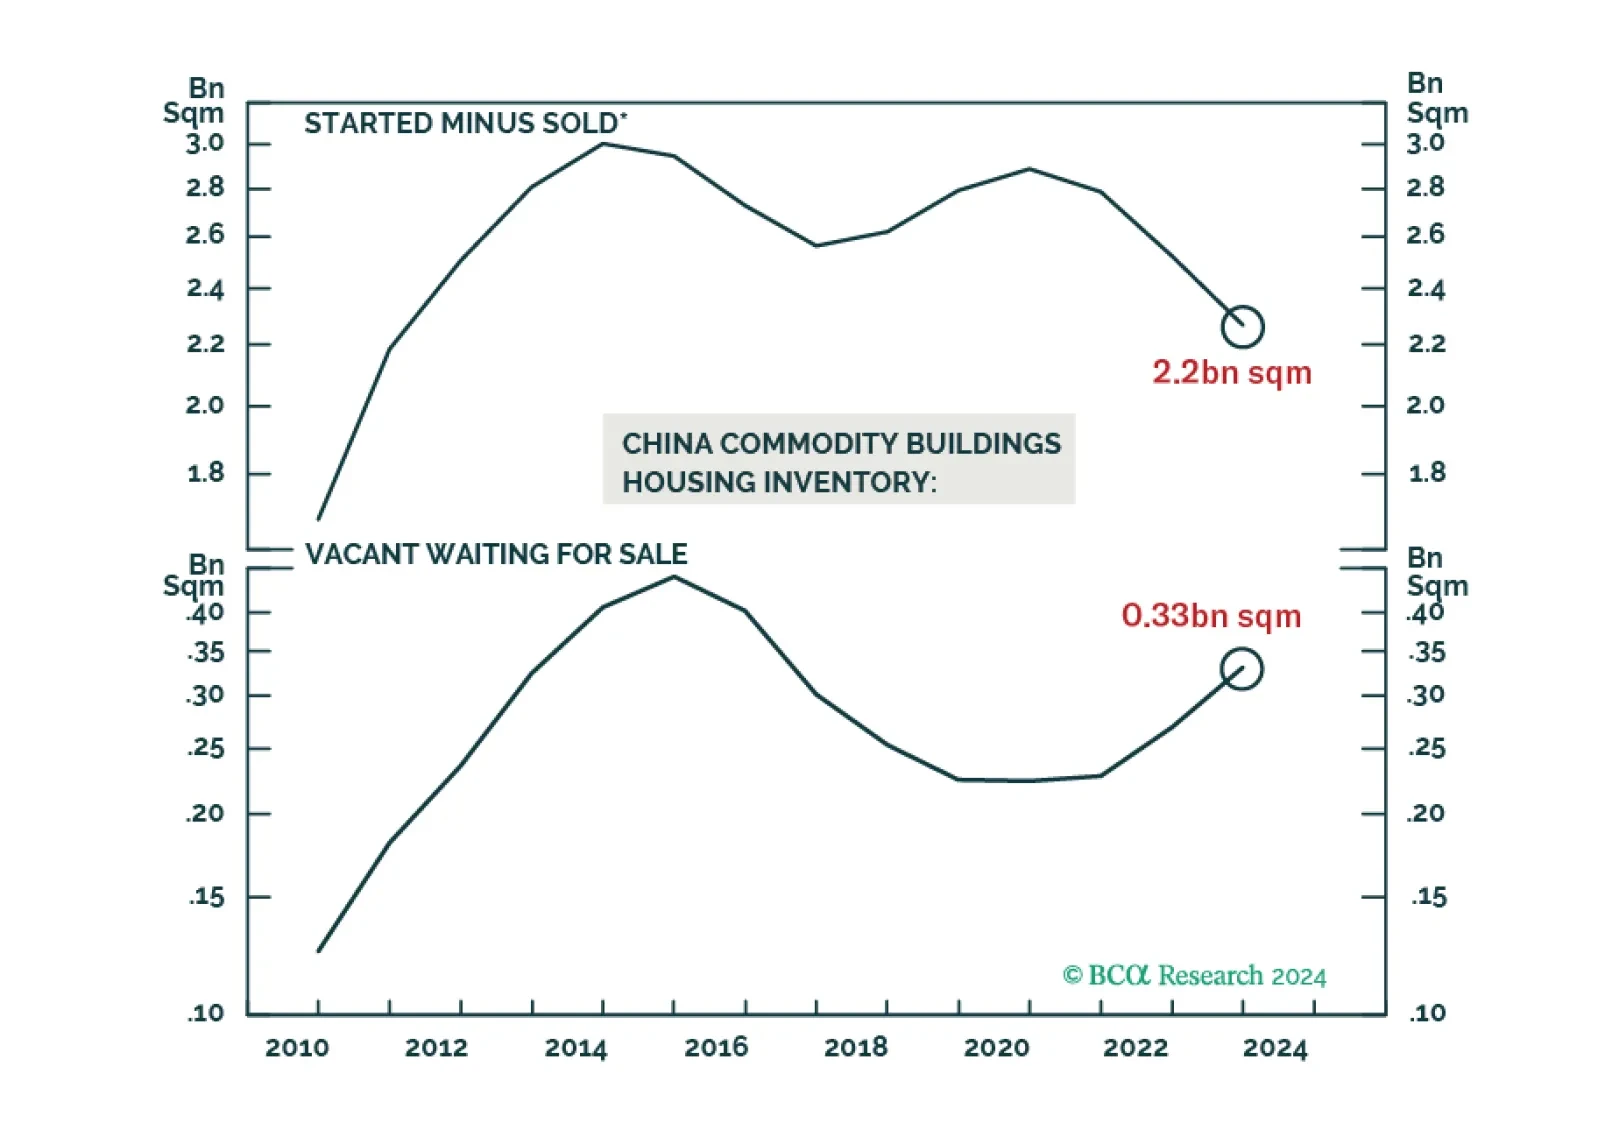
A reality check on credit data and announced property sector support measures indicates that the recent surge in Chinese share prices is unjustified based on the country's economic fundamentals.
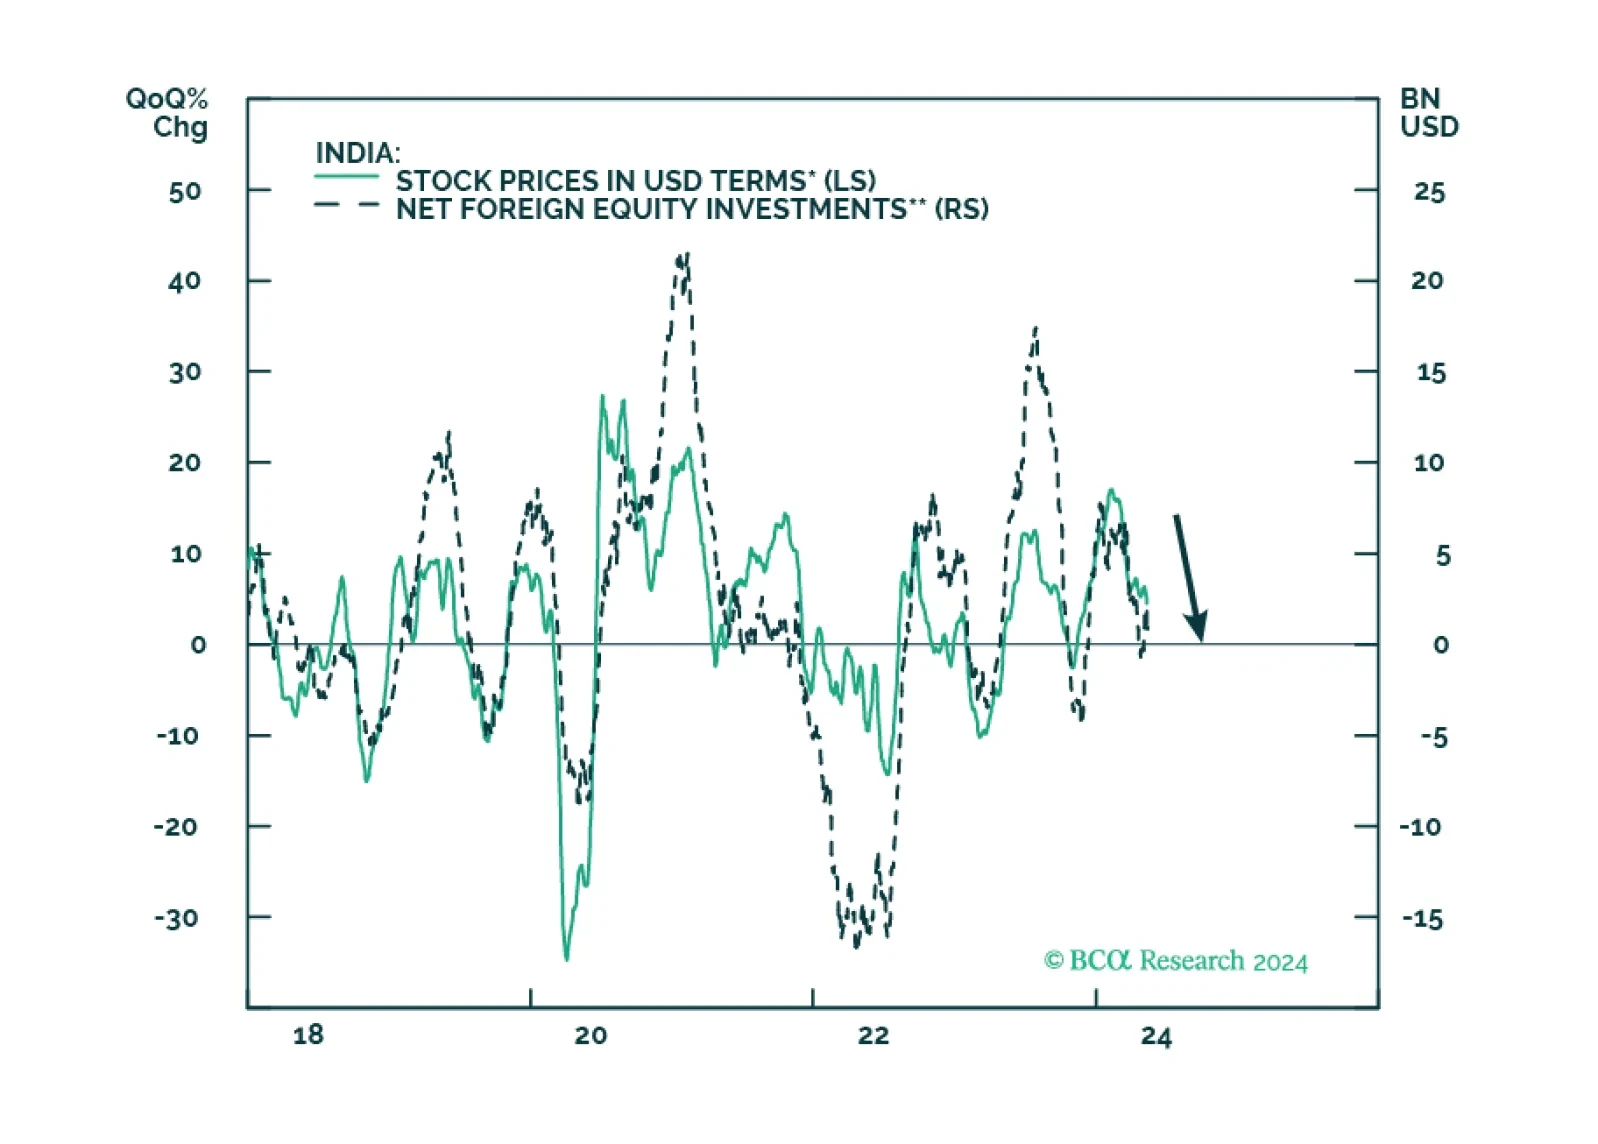
Special Report Modi and the BJP are at or near the peak of their political dominance, and their third term will be challenging as they must deal with harder reforms amidst a slowing domestic and global economic environment. In the long run, however, we remain constructive on India’s prospects, as its geopolitical and economic positioning are favorable and improving.
We marked the first X on our Equity Downgrade Checklist and the latest JOLTS, Employment Situation and SLOOS releases brought us closer to ticking some others. We remain tactically neutral on equities but expect that we will underweight them as excess savings are further depleted, leading labor market indicators continue to soften and consumer credit performance continues to fray.
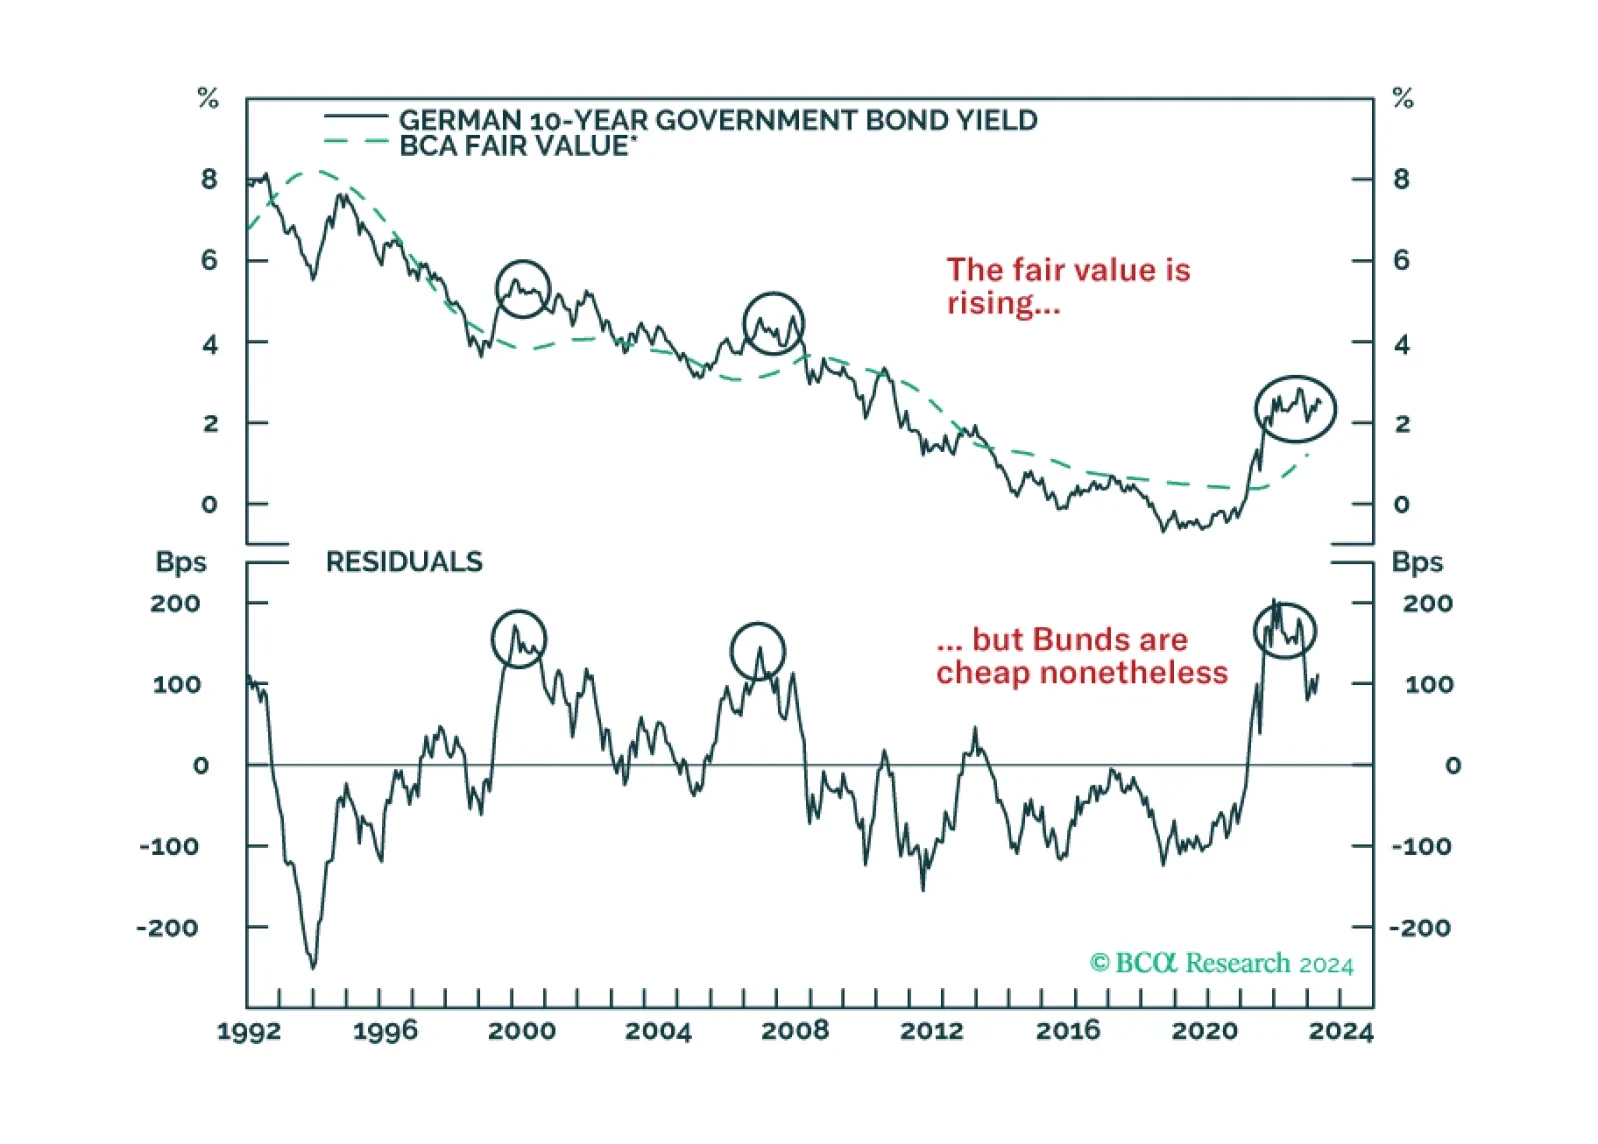
German Bunds have cheapened considerably, and the ECB is about to start cutting rates. Does this combination guarantee immediate profits from buying these bonds?