Latest from BCA Research
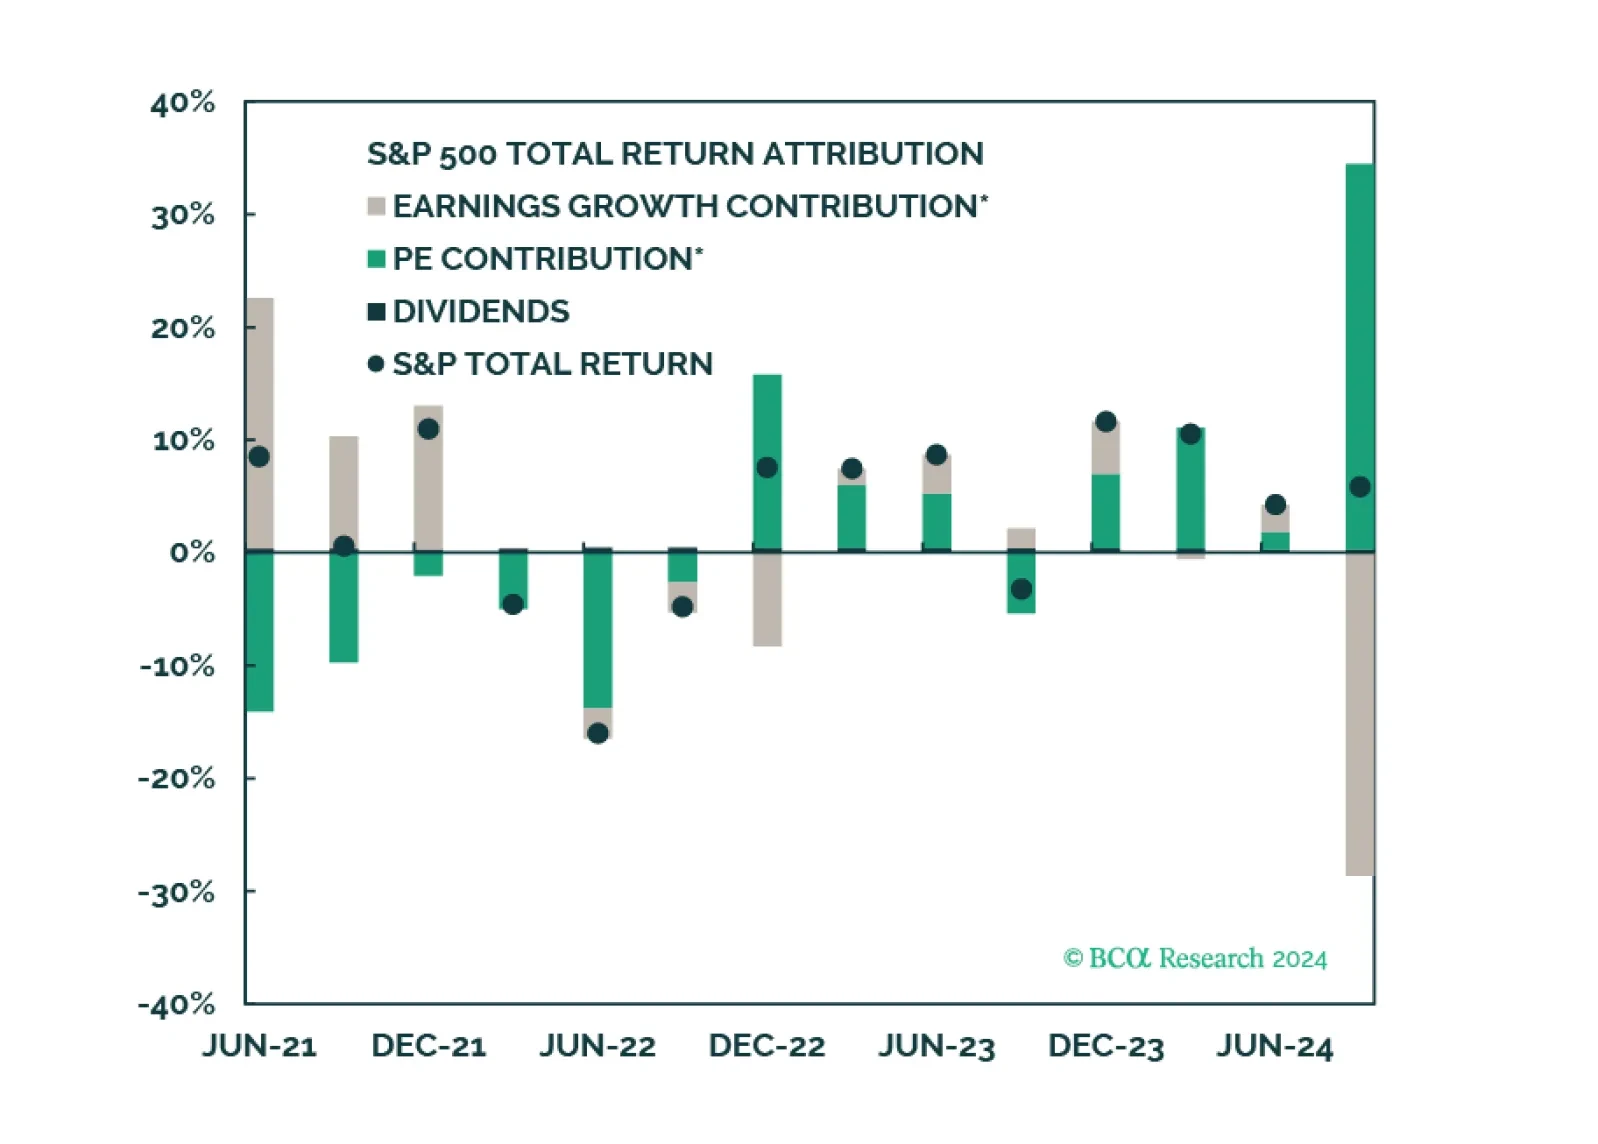
Earnings growth is expected to be strong enough to assuage investors' fears that recession is not yet imminent. Q3 earnings expectations have been revised downward over the past three months, and the bar for the beats has been lowered. Operating margins are also expected to expand.
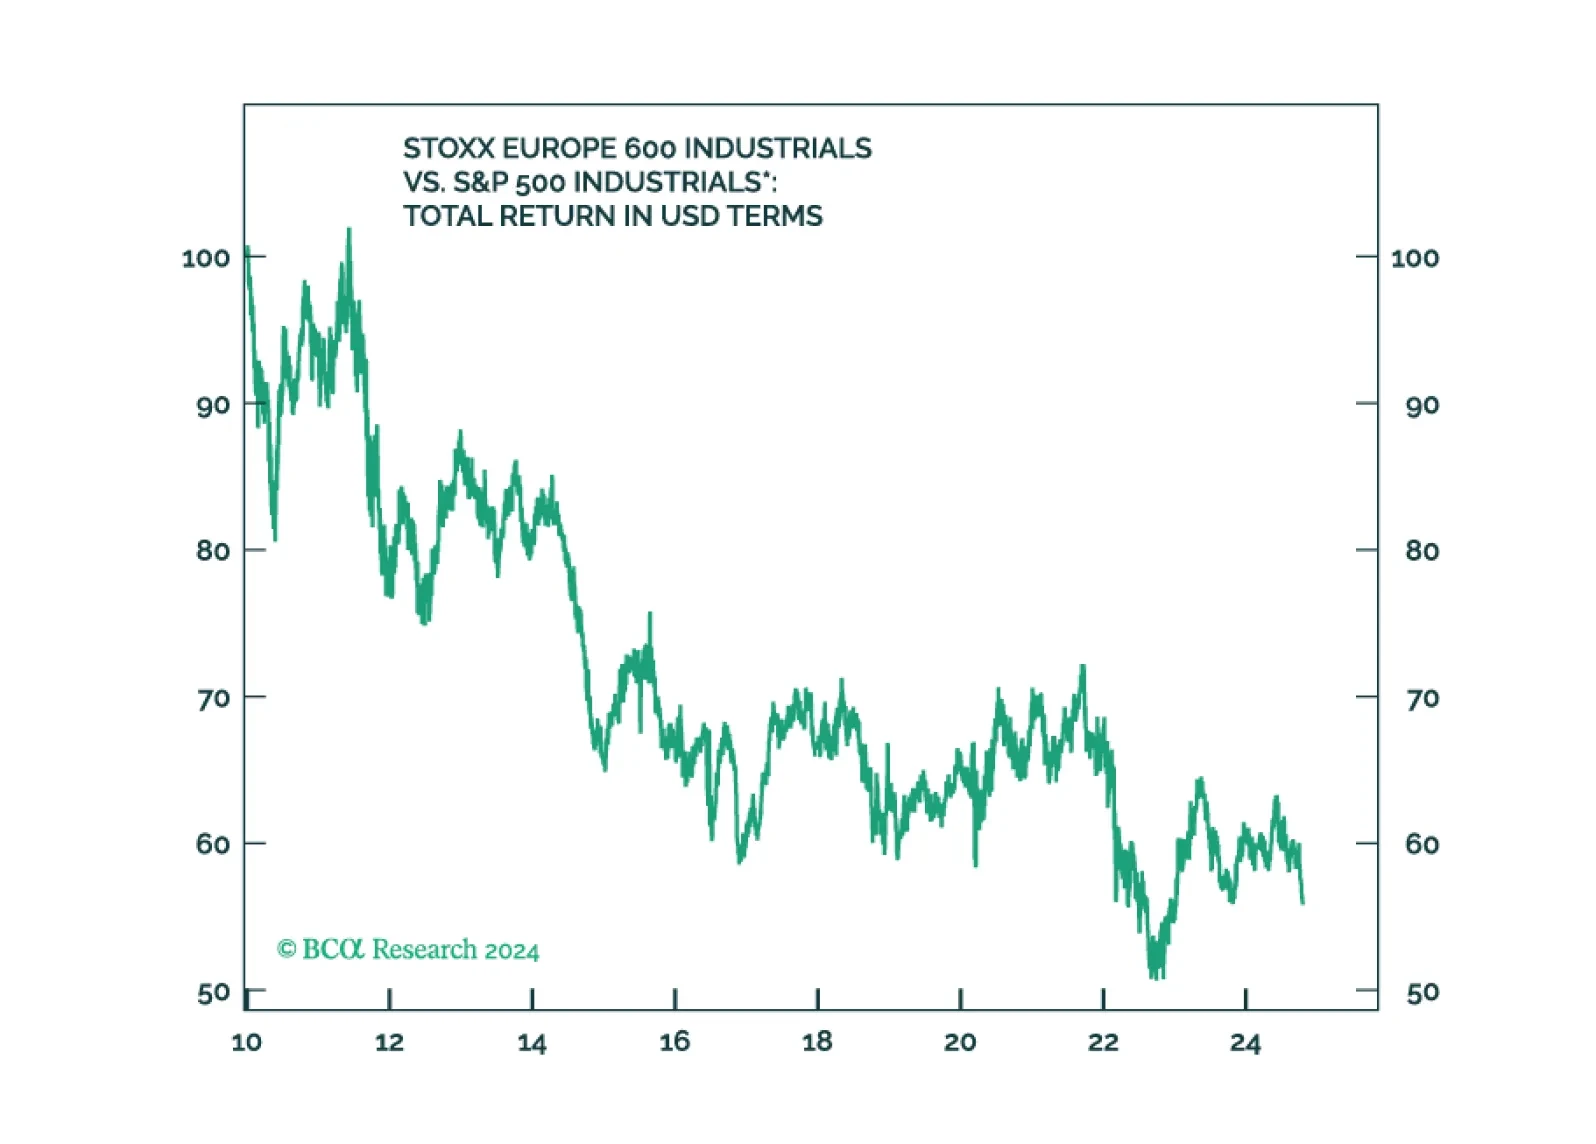
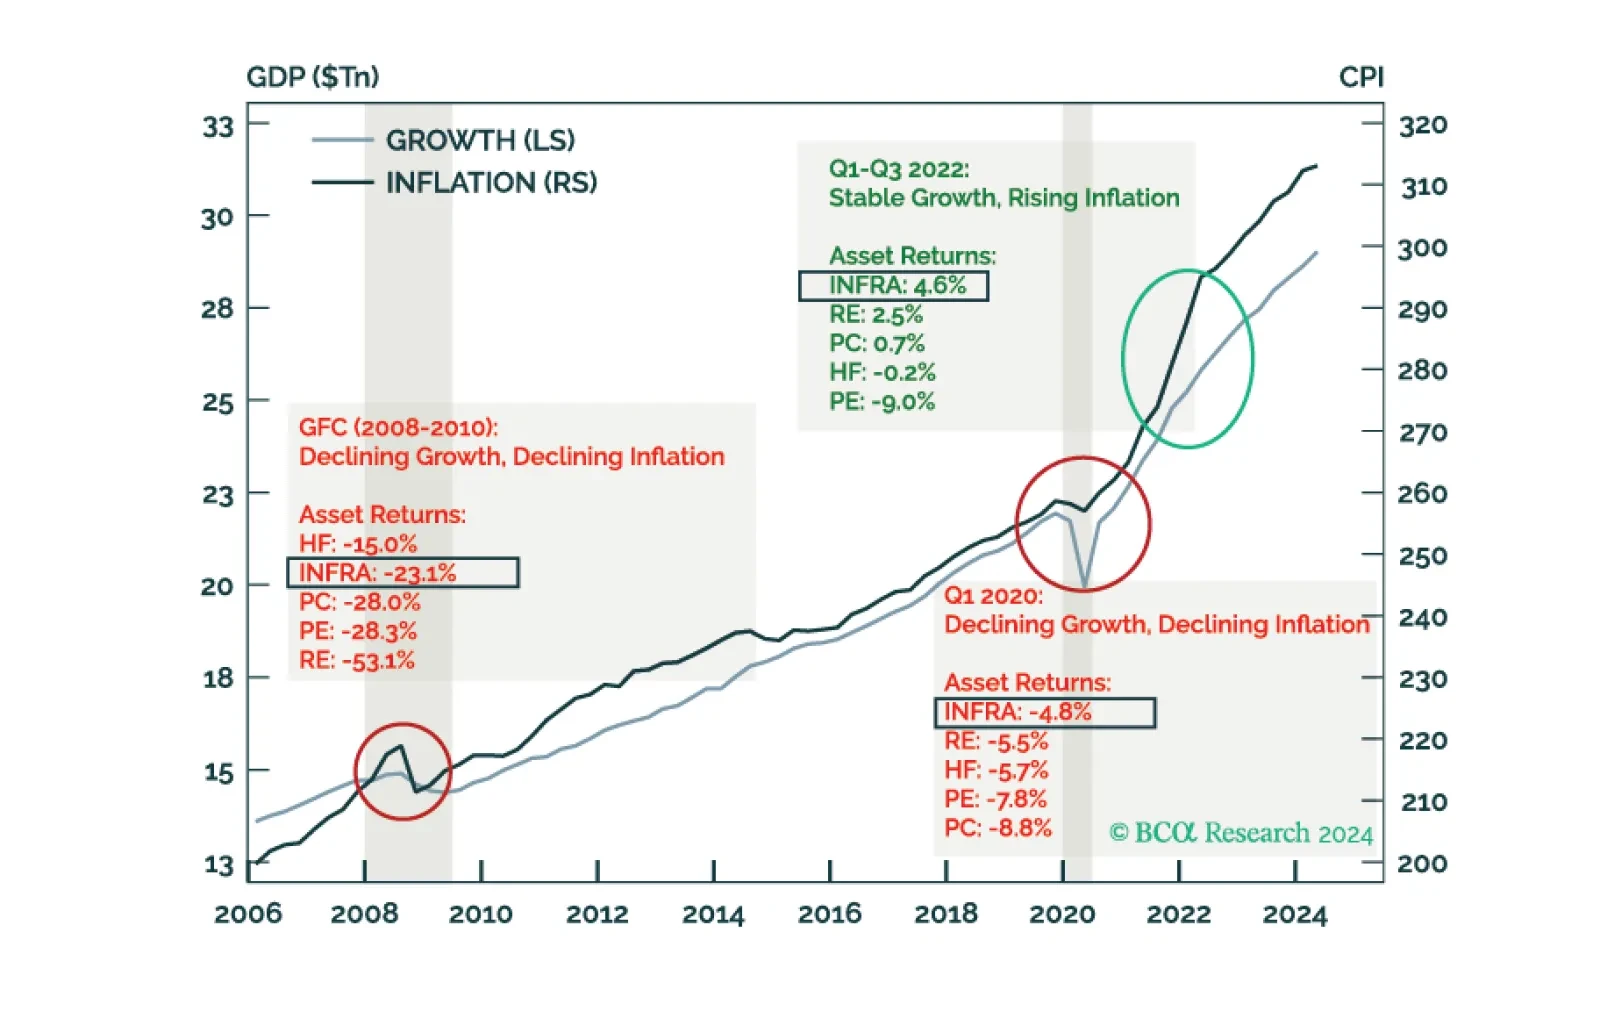
Institutional investing is not as straightforward as picking the fastest horse. Infrastructure’s attraction as an investment stems from its diversification, specifically its feature as an inflation-hedge, cash flow stability, and scalability. This Primer lays the groundwork for integrating Infrastructure into the PMA framework.
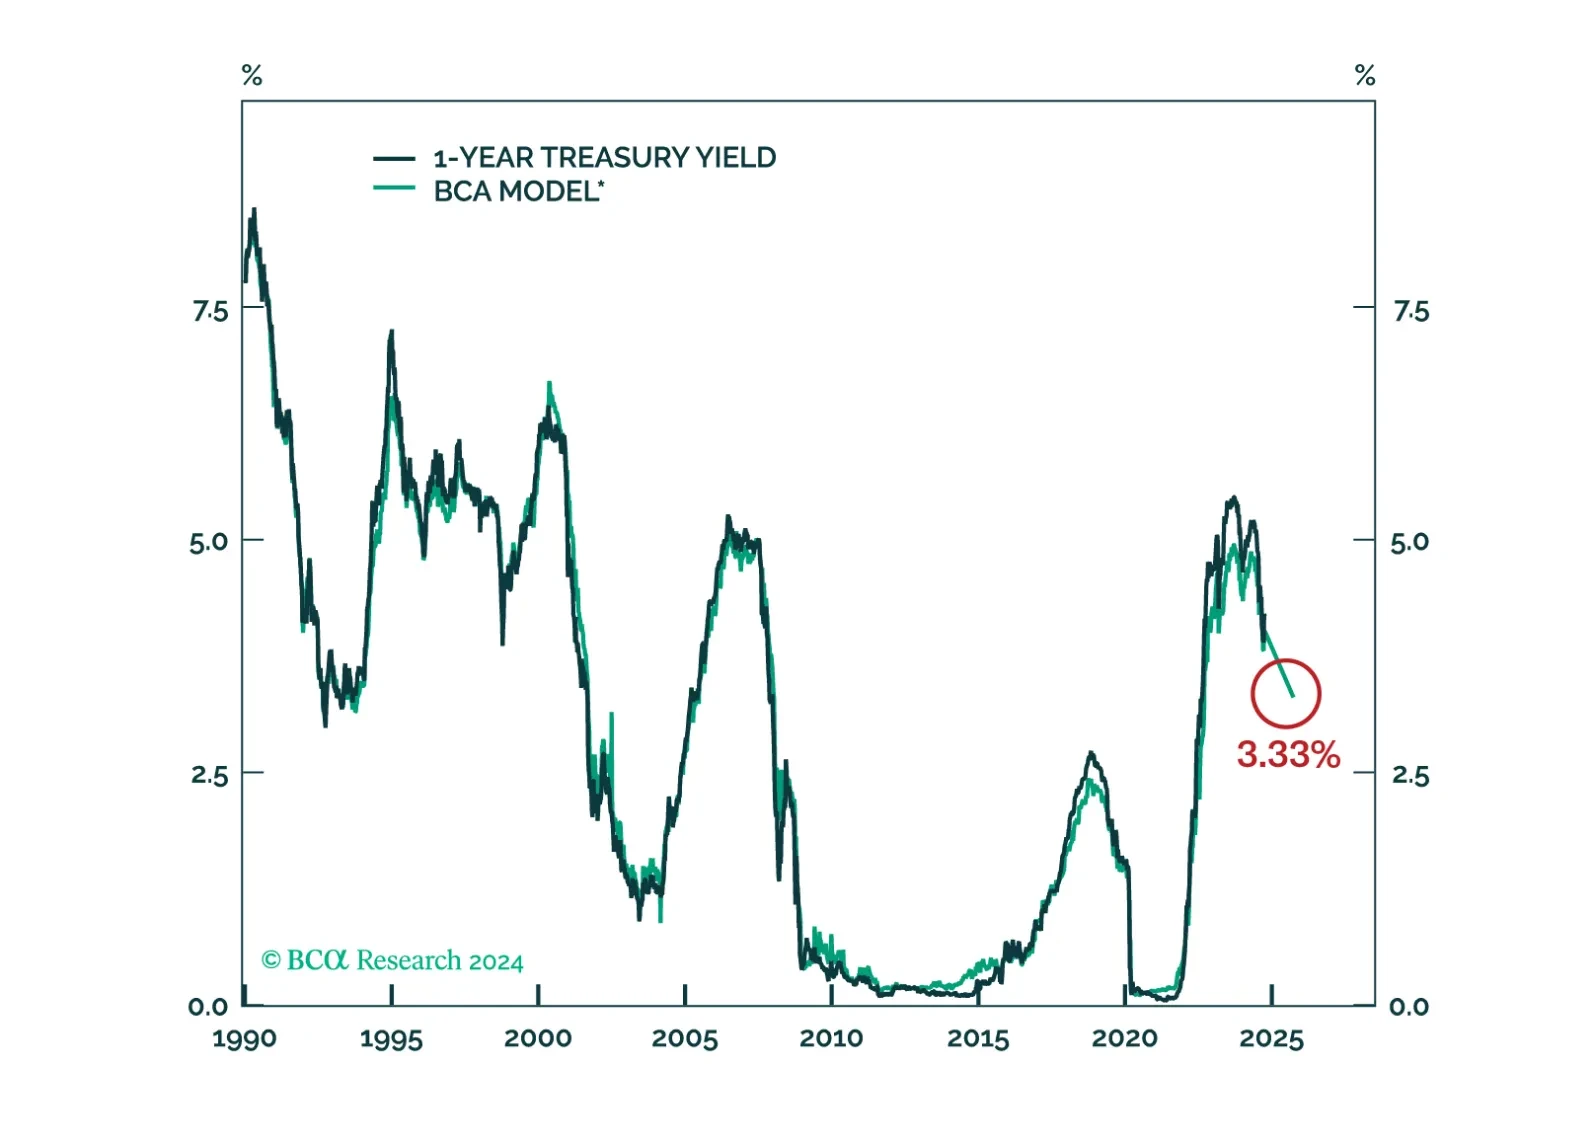
We estimate where Treasury yields might go in a soft landing economic scenario.
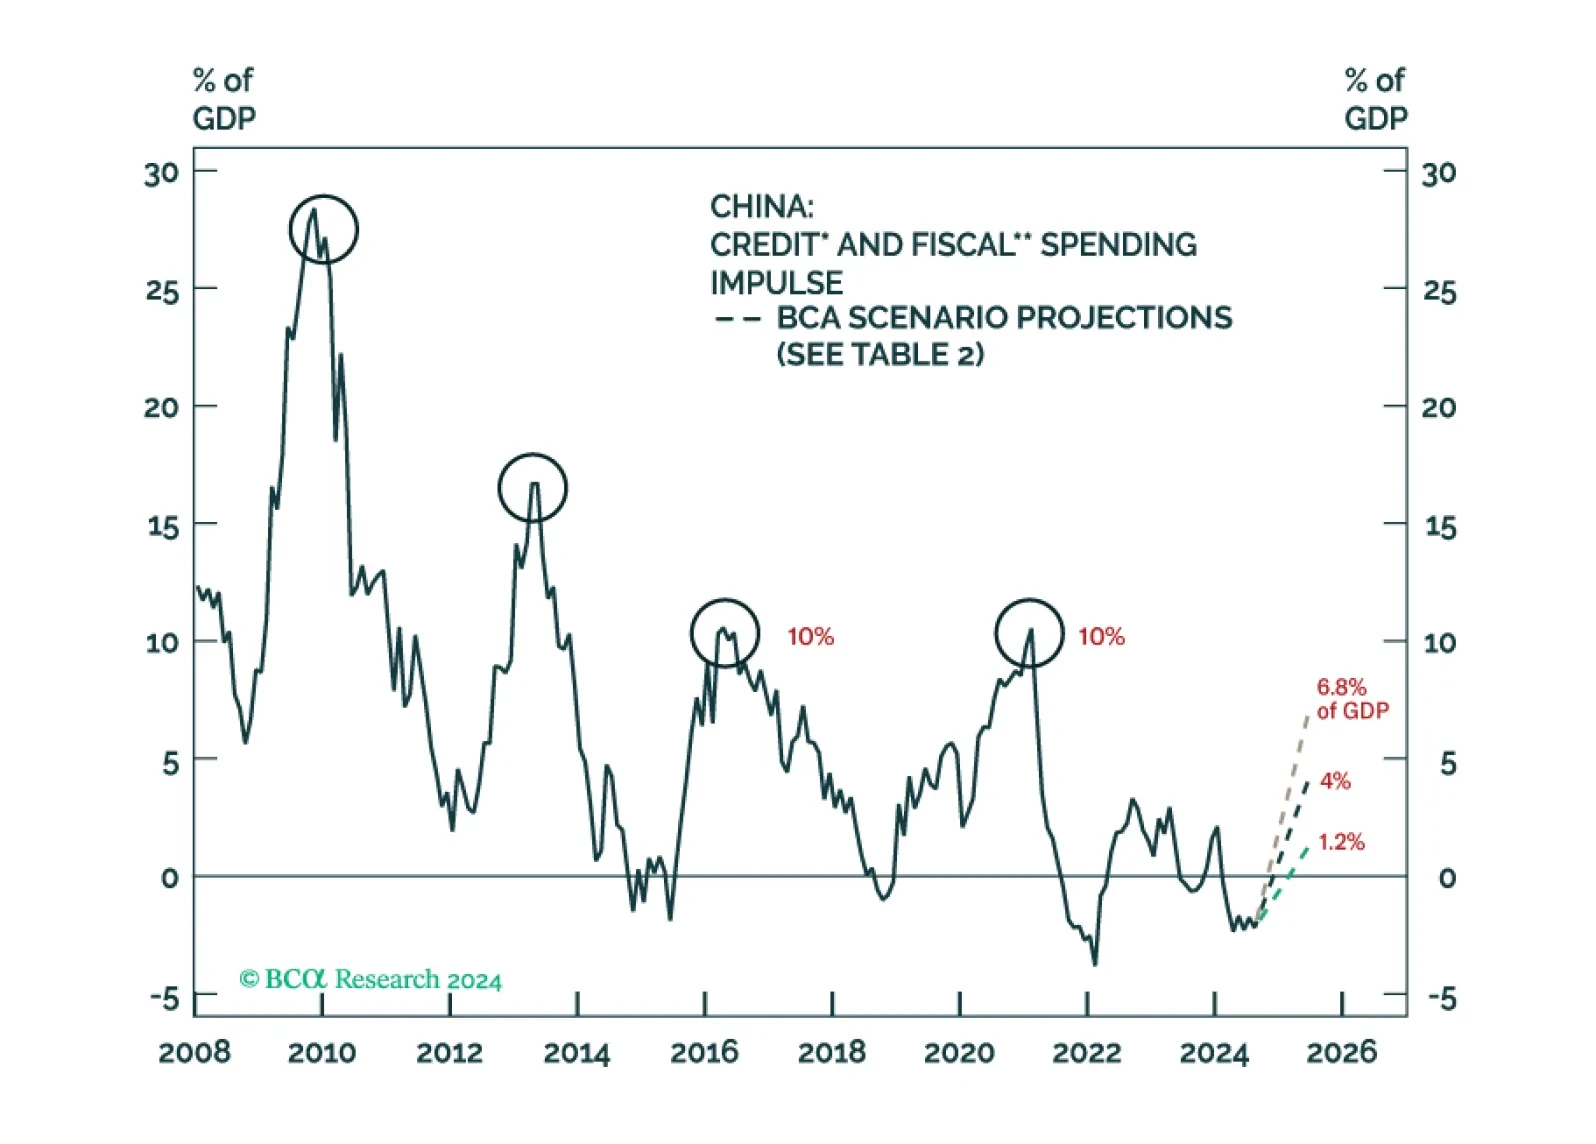
To produce a moderate economic recovery, at least RMB 3 trillion in additional government expenditures is needed in H1 2025. Our bias is that Beijing is not yet ready to launch such a massive fiscal support measure. Hence, volatility-adjusted equity returns in China will be poor.
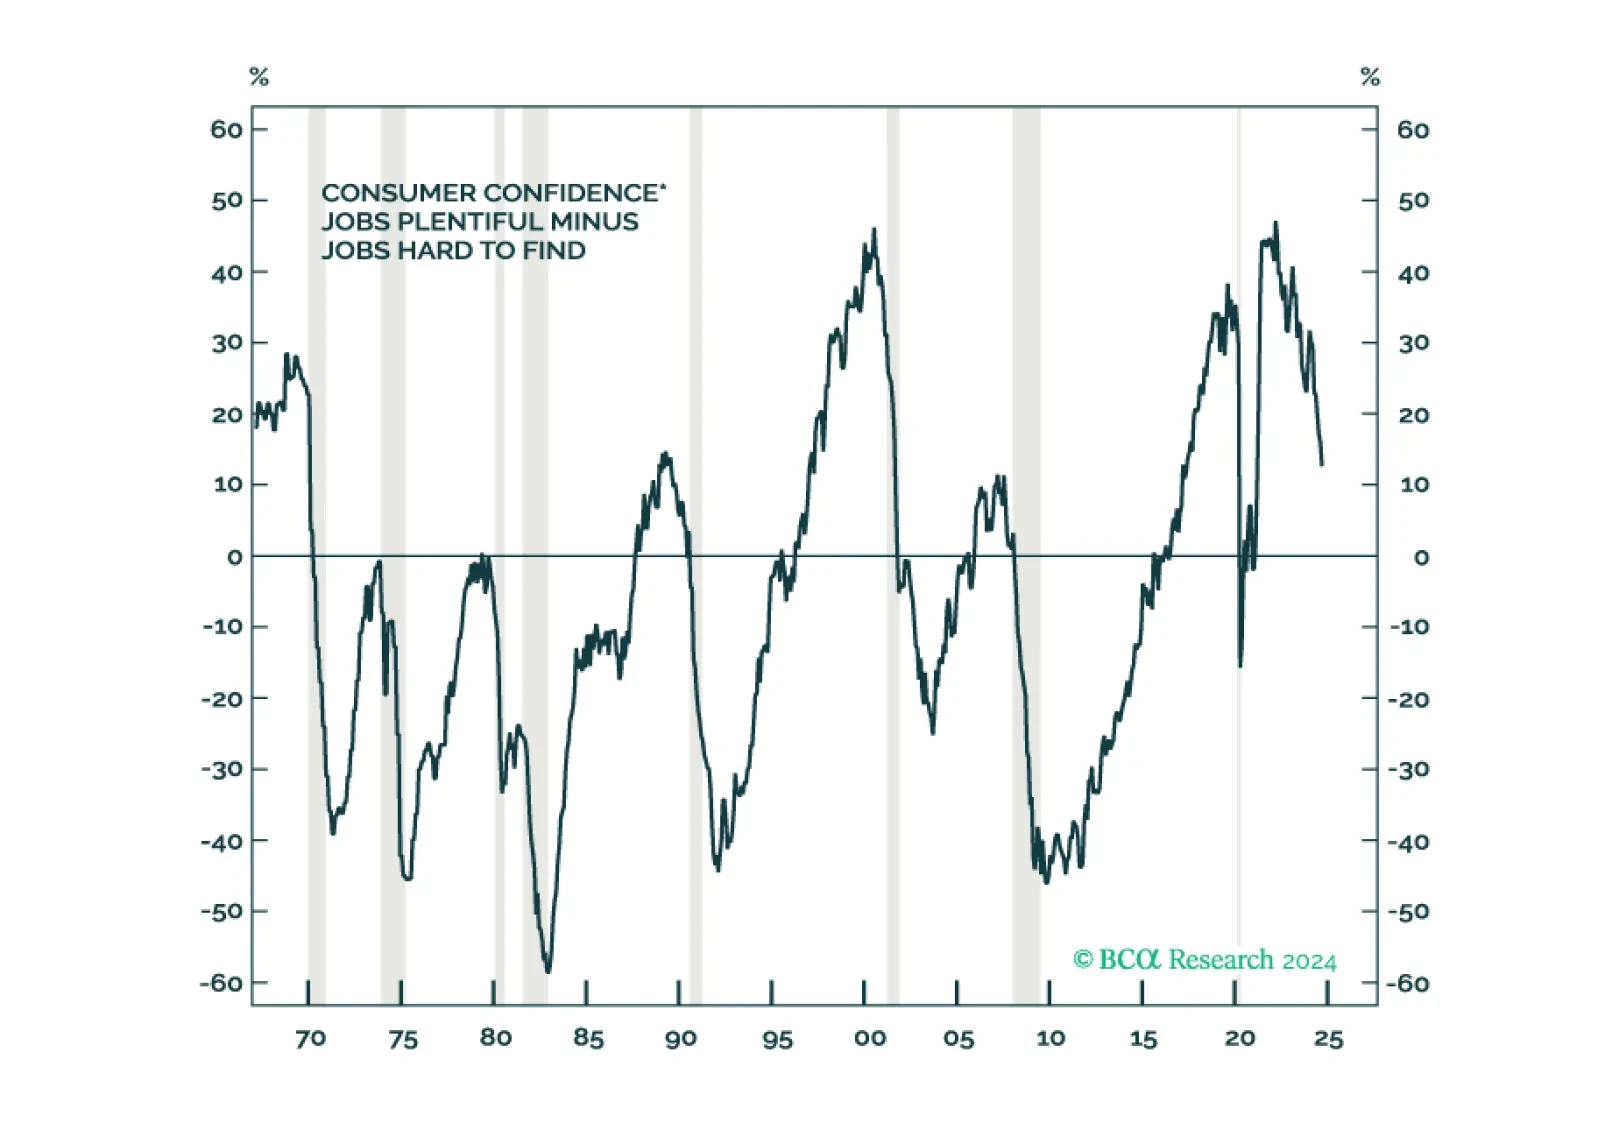
Rising stock prices and improving economic data have us re-examining our bearish thesis, but we still see deterioration in leading labor market indicators and expect it will eventually culminate in a recession. We reiterate our defensive investment recommendations.
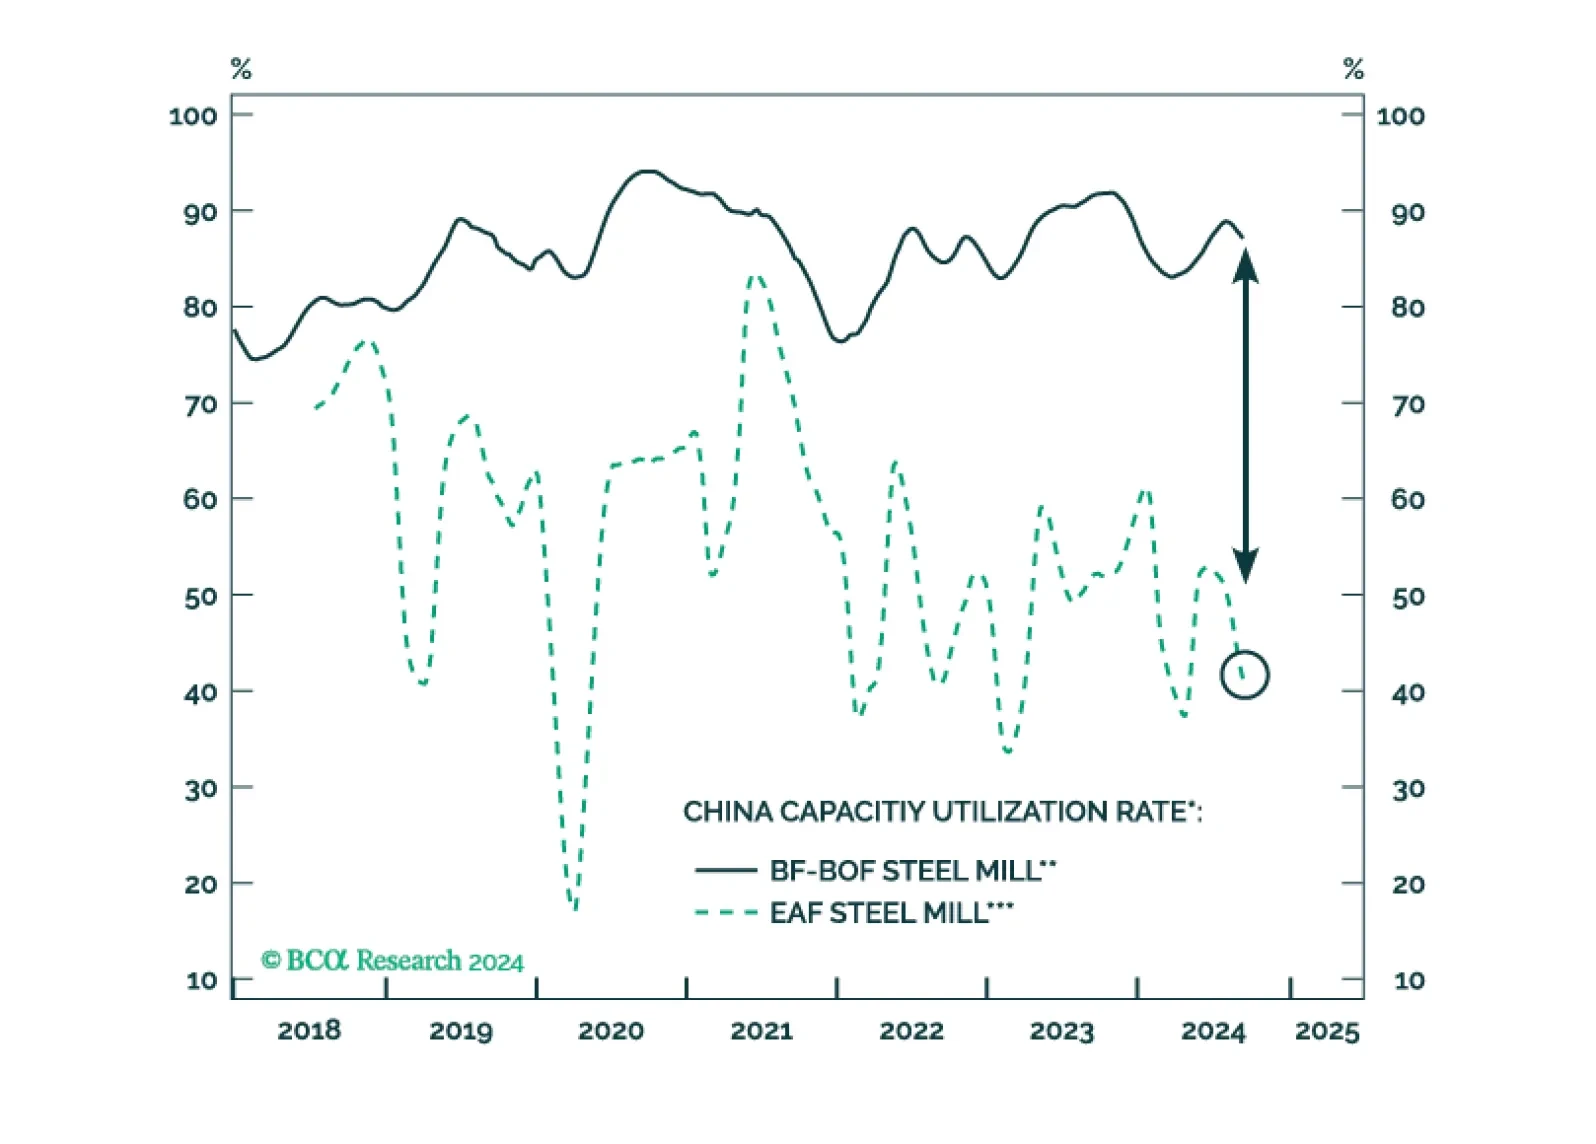

This week, we cover the main questions we fielded during our latest client trip in Europe. Among the many topics broached are Europe’s recession odds, the impact of China’s stimulus, and the outlook for European markets.
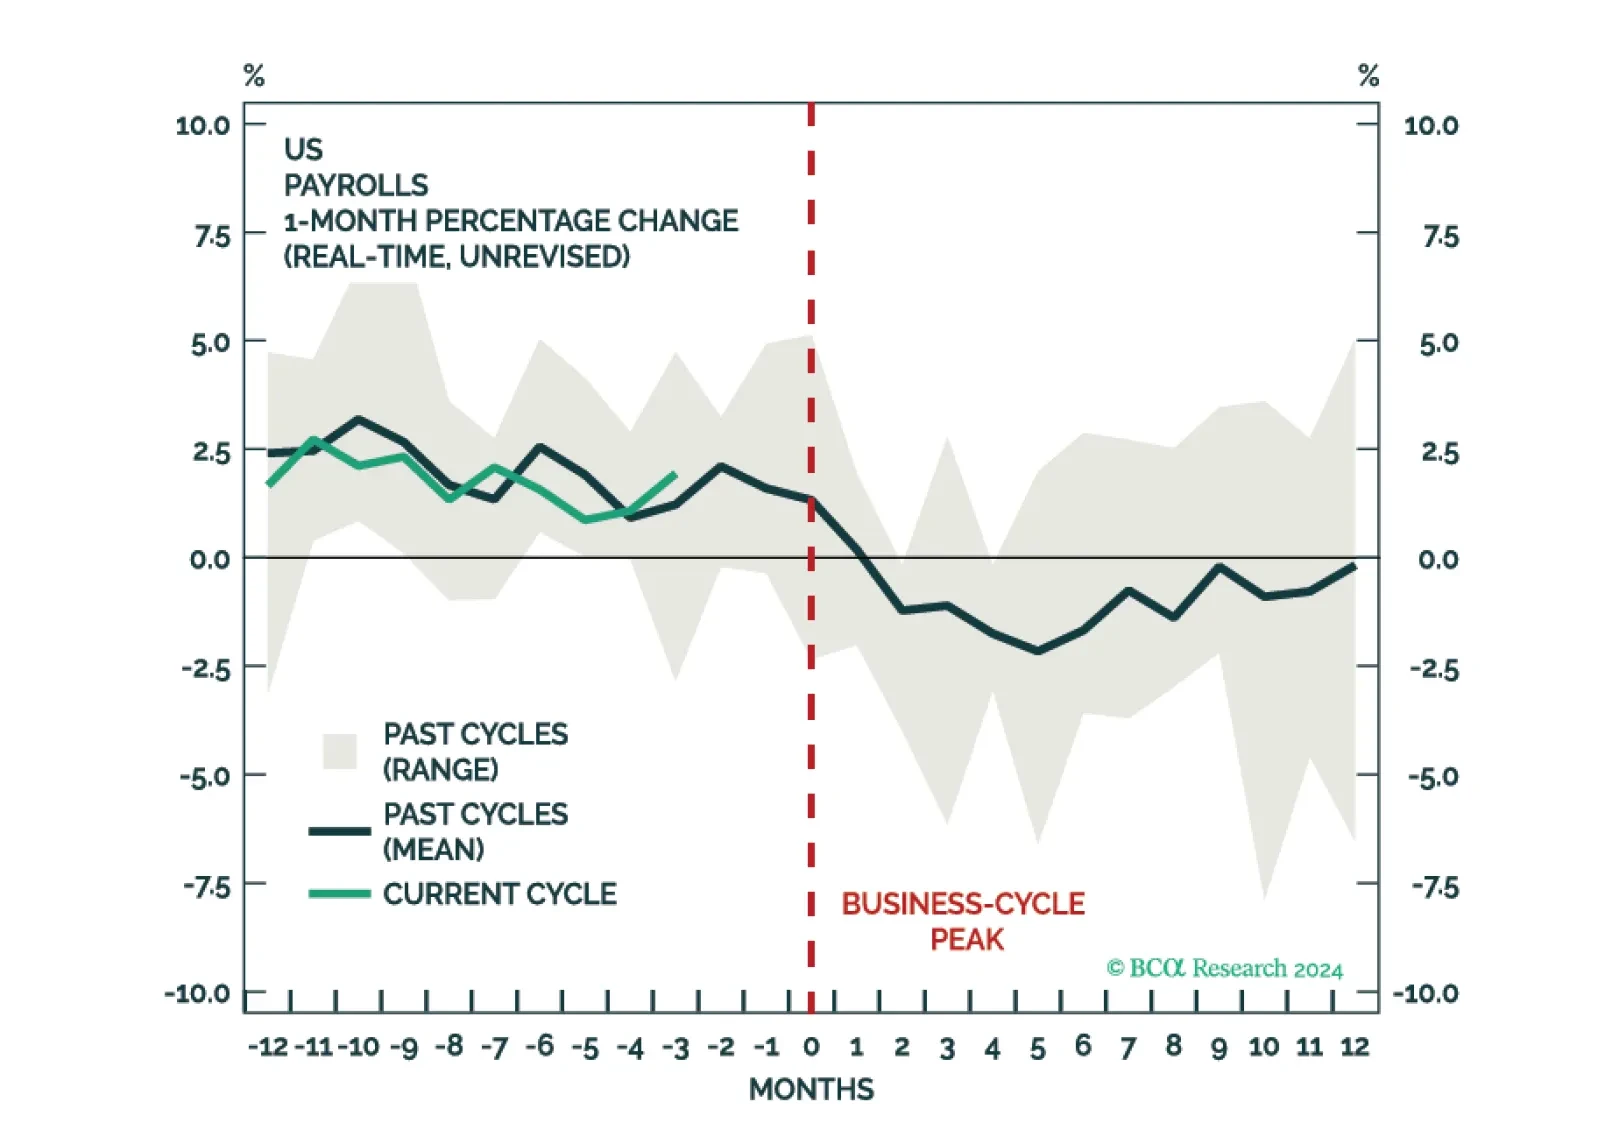
It is too early to say that the US labor market has turned the corner. We assign a 60% chance that the US will enter a recession over the next 12 months, with the downturn likely to begin in the first half of 2025. Accordingly, investors should underweight equities.
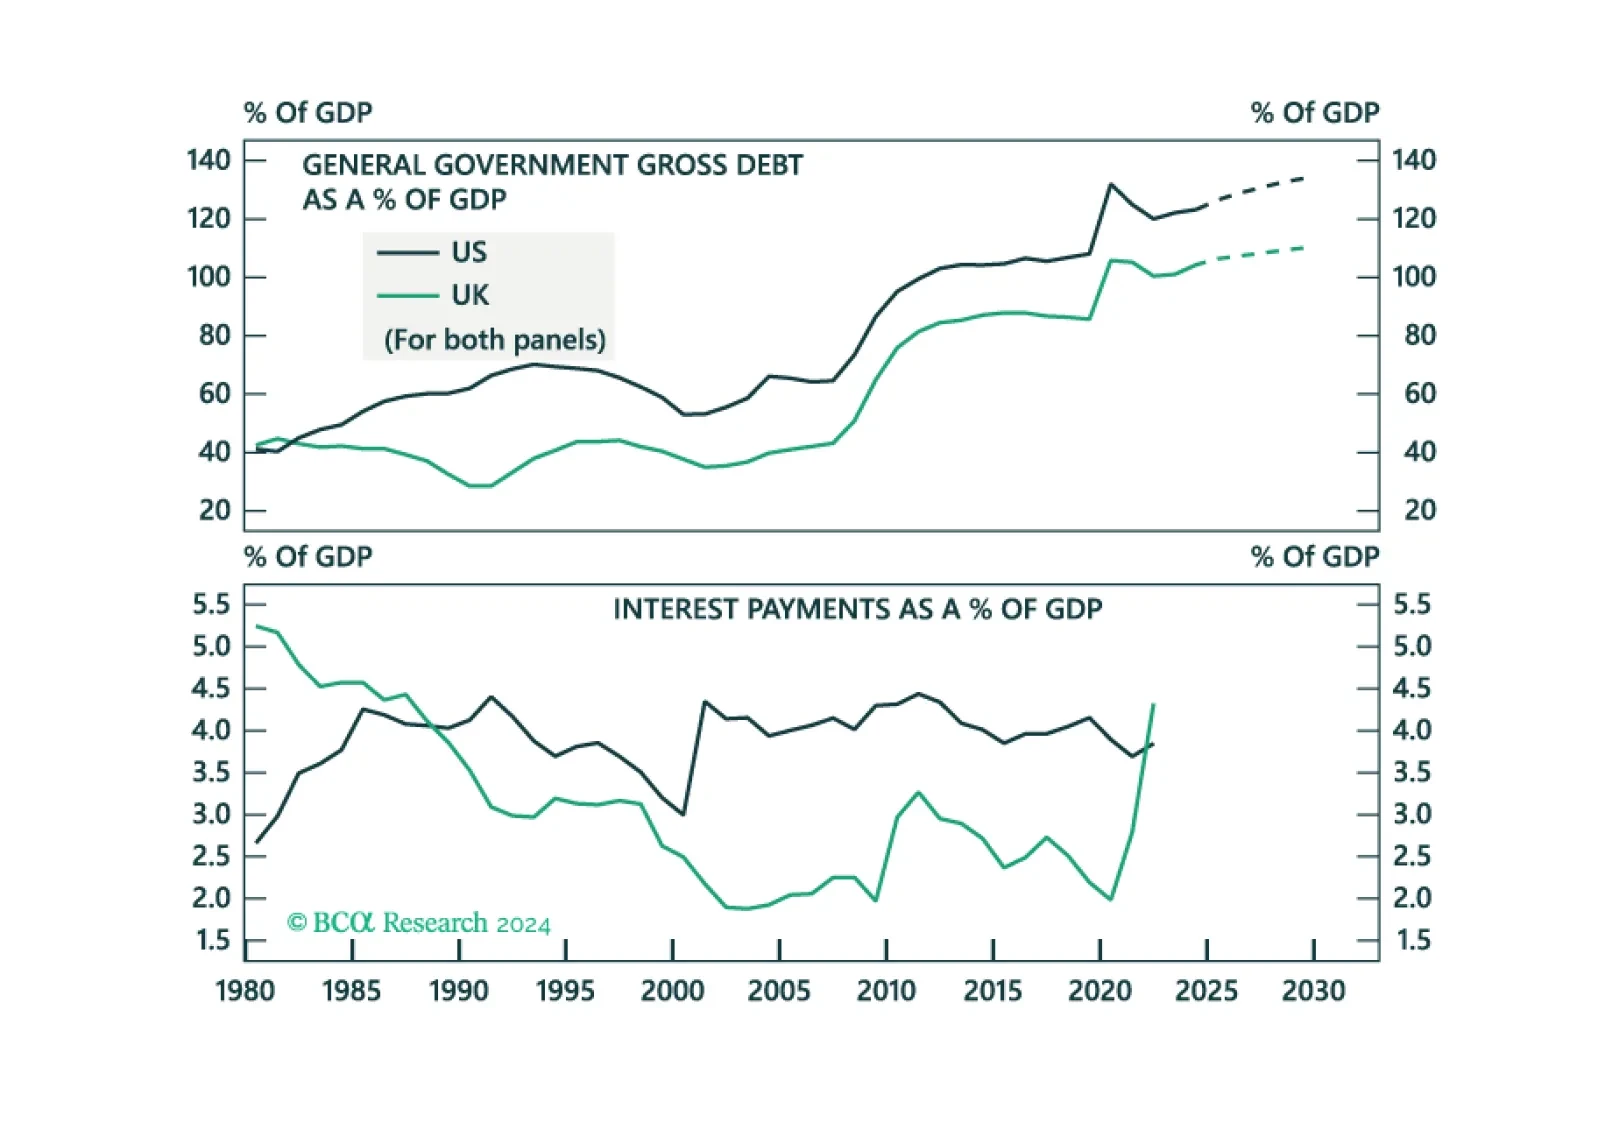
In this Insight, we assess whether investors should expect fiscal turbulence in the UK, that will drive UK yields higher and the pound lower.