Latest from BCA Research
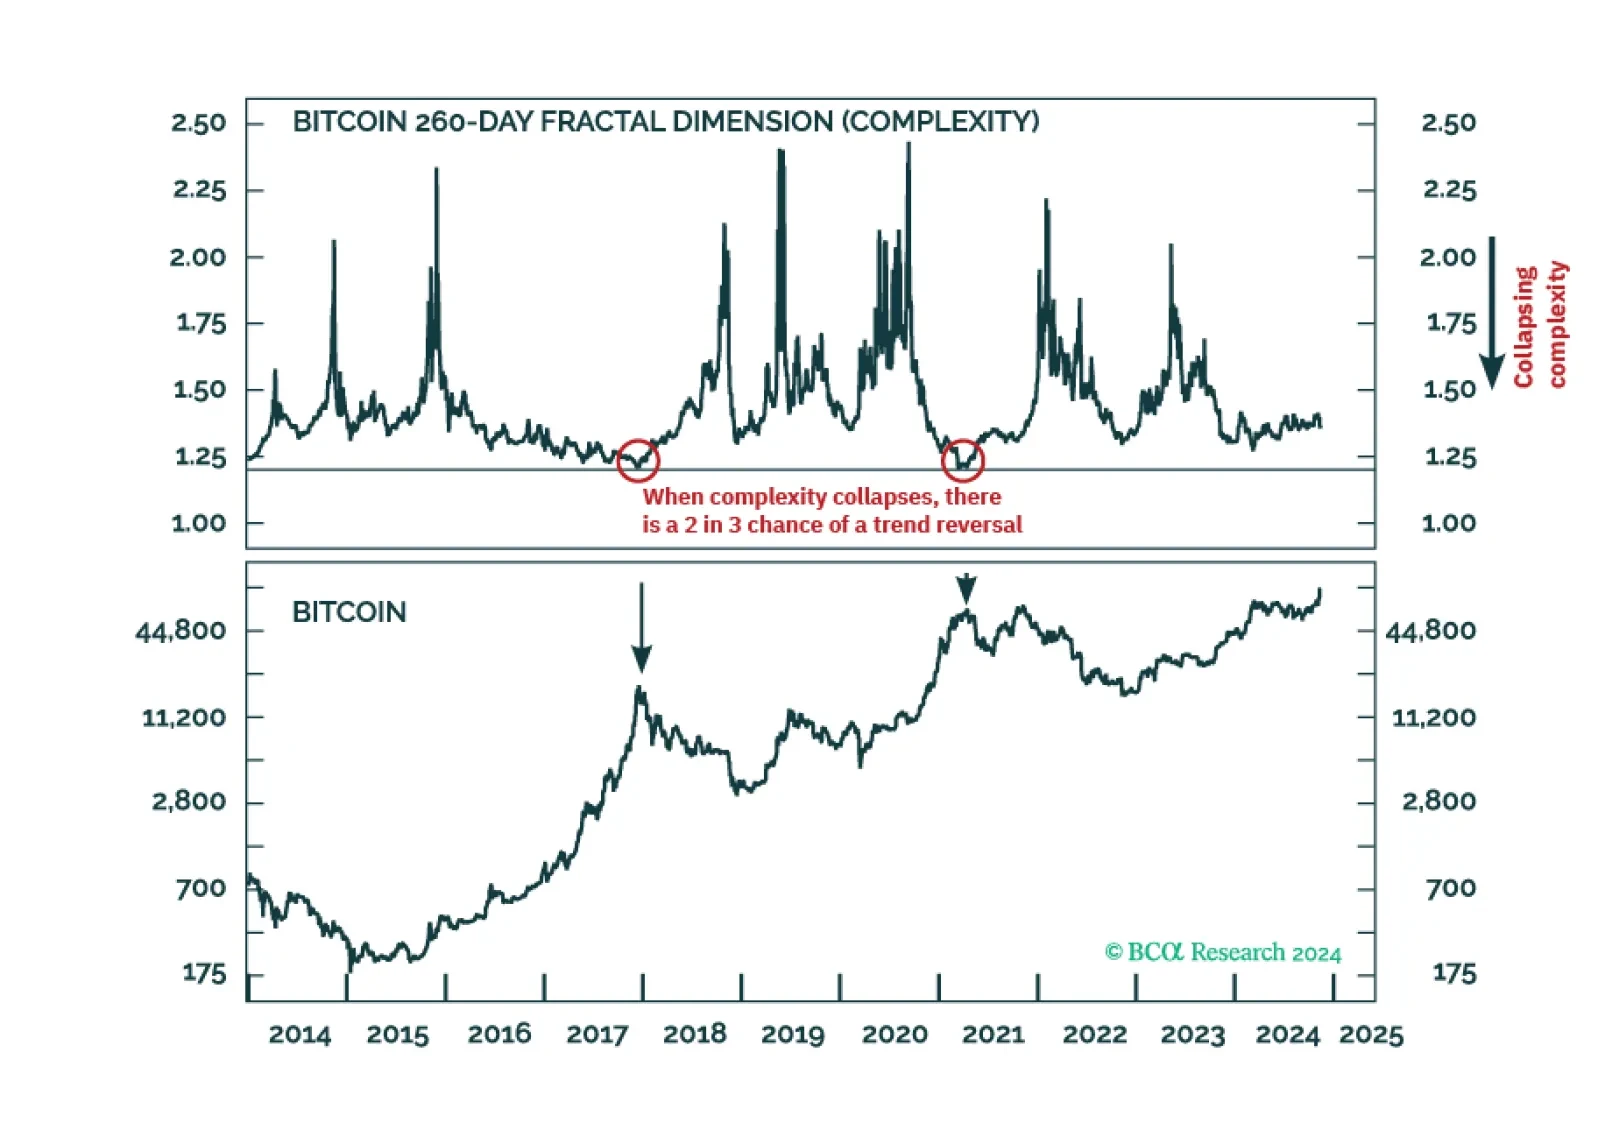
The value of both gold and bitcoin comes from the collective belief that they are the non-confiscatable assets to own in a fiat monetary system, as an insurance against hyperinflation, banking system failure, or state expropriation. As global wealth rises, the value of both gold and bitcoin will also rise. But as bitcoin takes market share from gold, bitcoin has considerably more upside than gold, with an ultimate destination of $200,000+. Plus: 10-year T-bonds and Portuguese stocks are tactically oversold.
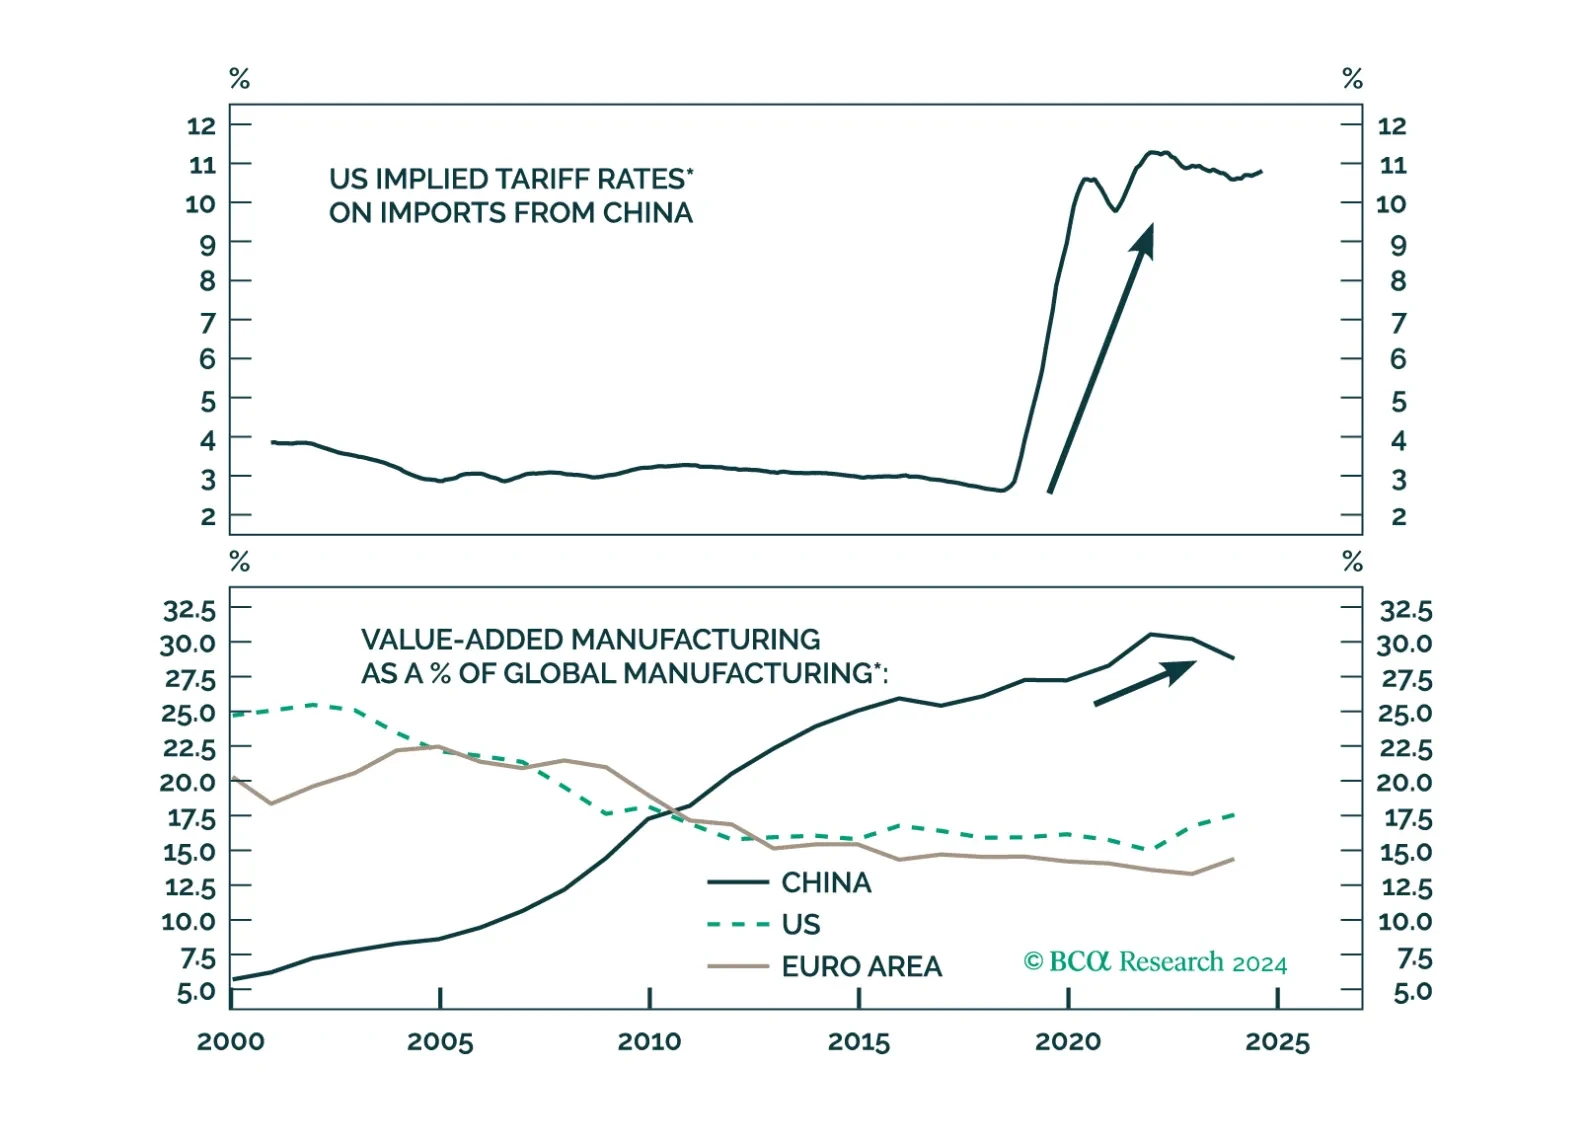
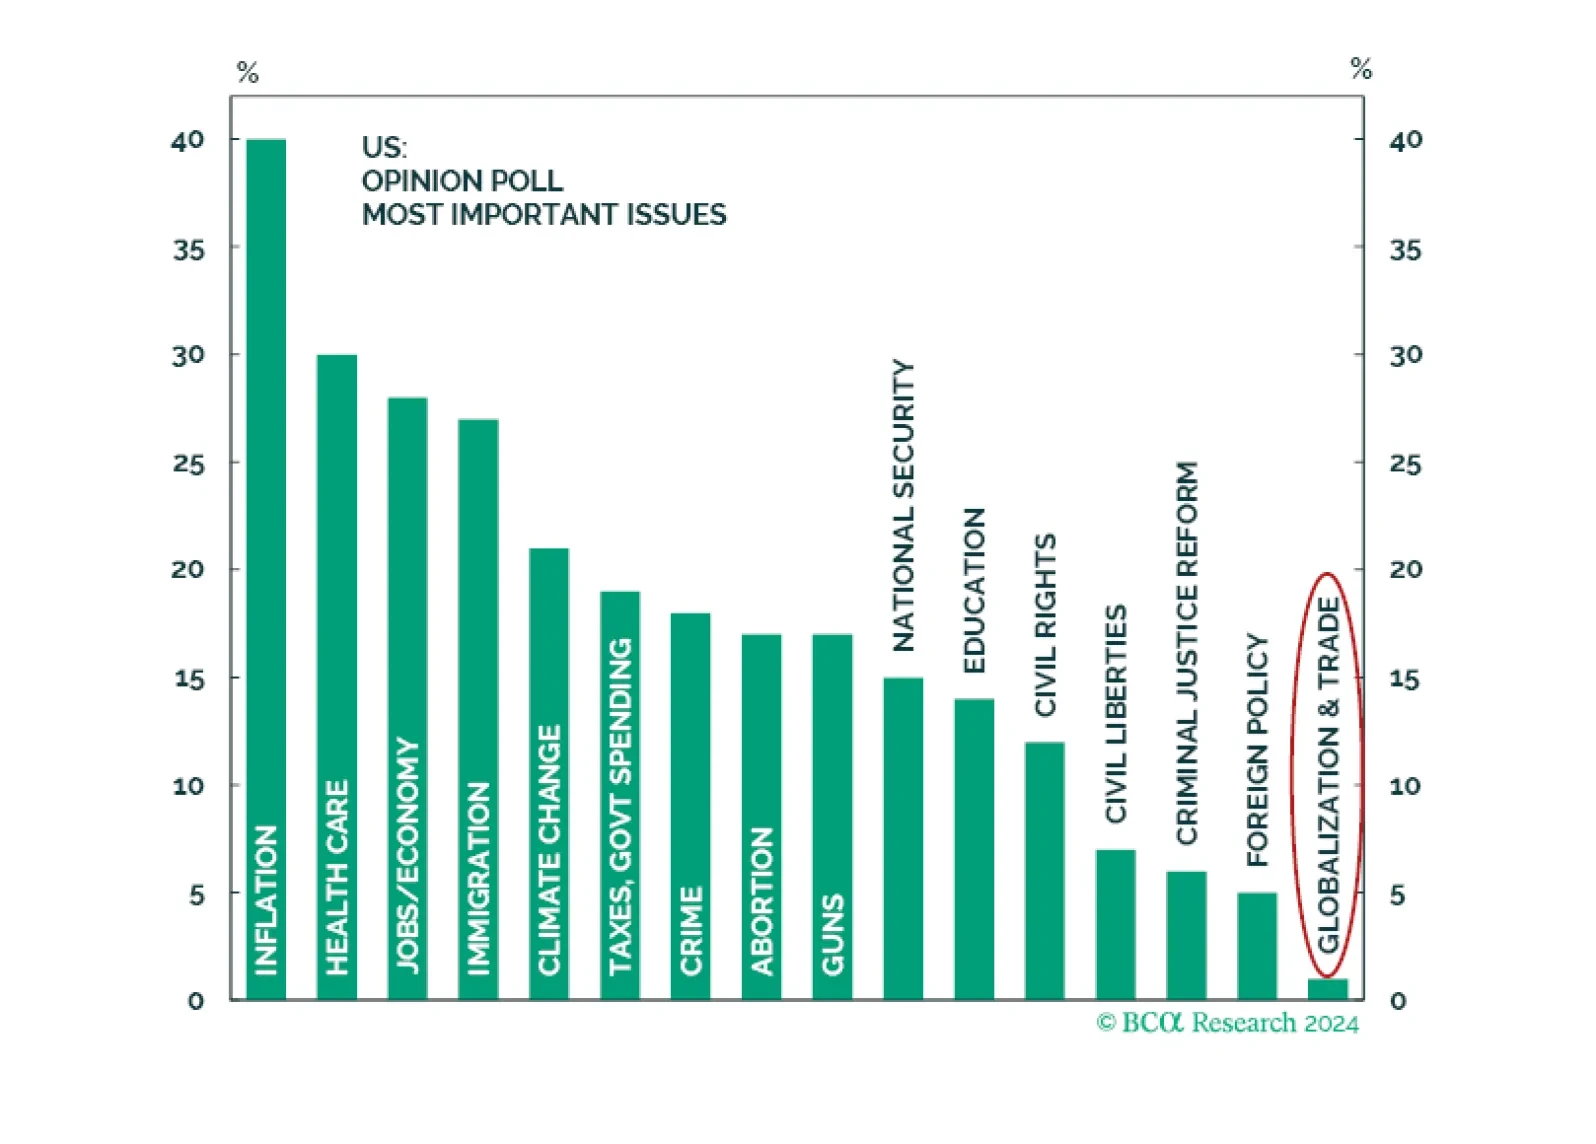
Trump's presidential re-election makes US tariff rate hikes on Chinese exports an imminent threat. Beijing has made extensive efforts to derisk the domestic economy and diversify trade away from the US. However, China is no better positioned today than it was in 2018 to withstand the impact of a renewed trade war.

We update our inflation forecast following this morning’s CPI release, concluding that TIPS breakeven inflation rates have room to fall.
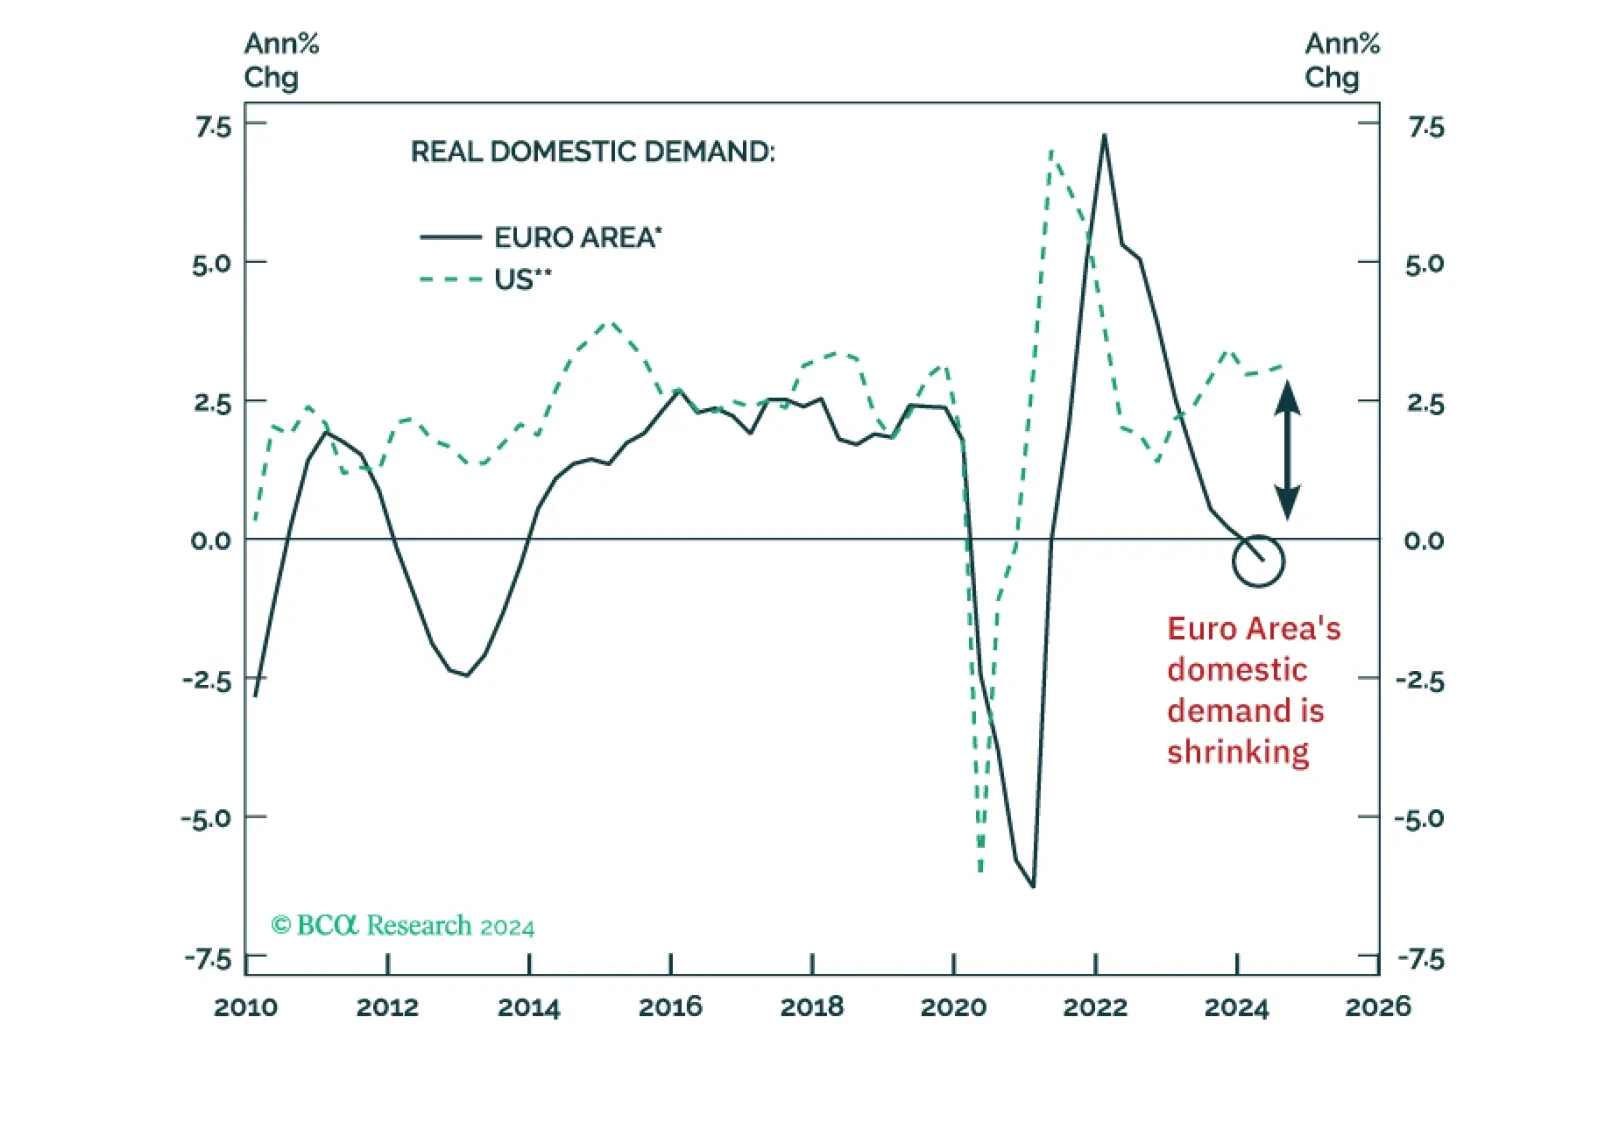
The threat of import tariffs and US growth outperformance versus the rest of the world will continue supporting the US dollar rally over the near term. Nevertheless, the Trump administration’s medium- to long-term goal will be a US dollar devaluation to boost the country’s manufacturing competitiveness. We will recommend upgrading EM stocks and bonds when we downgrade our US dollar view.
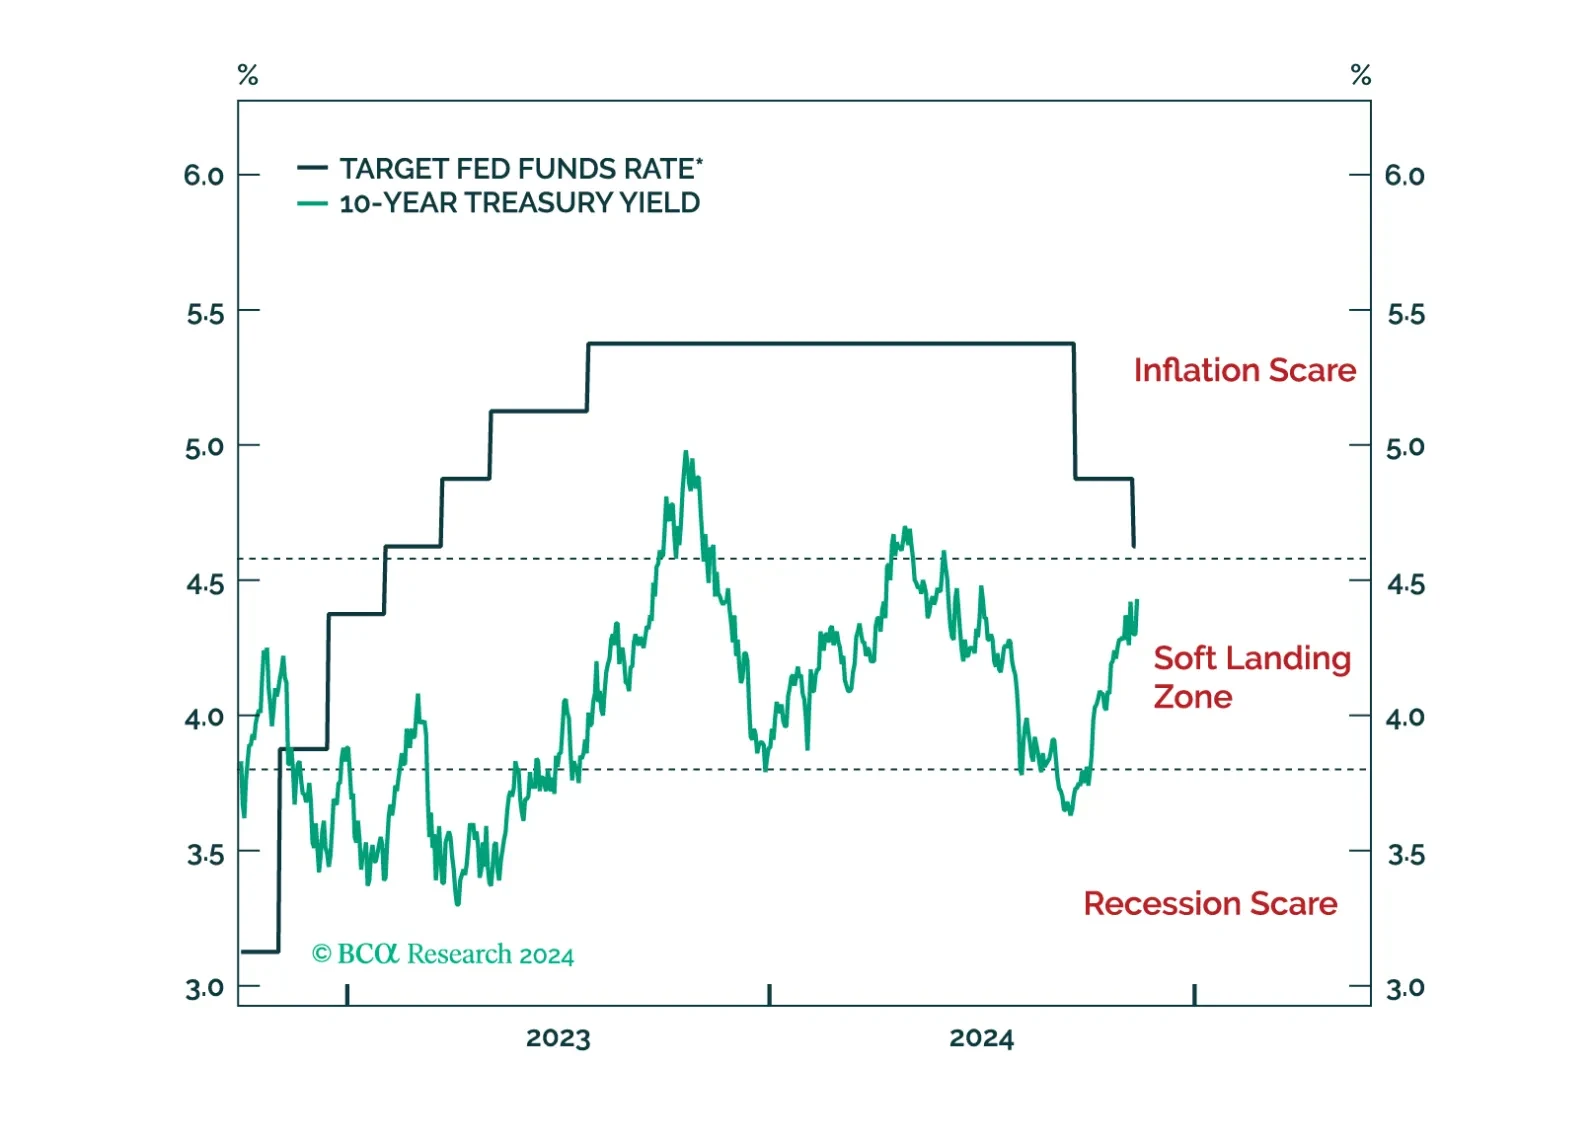
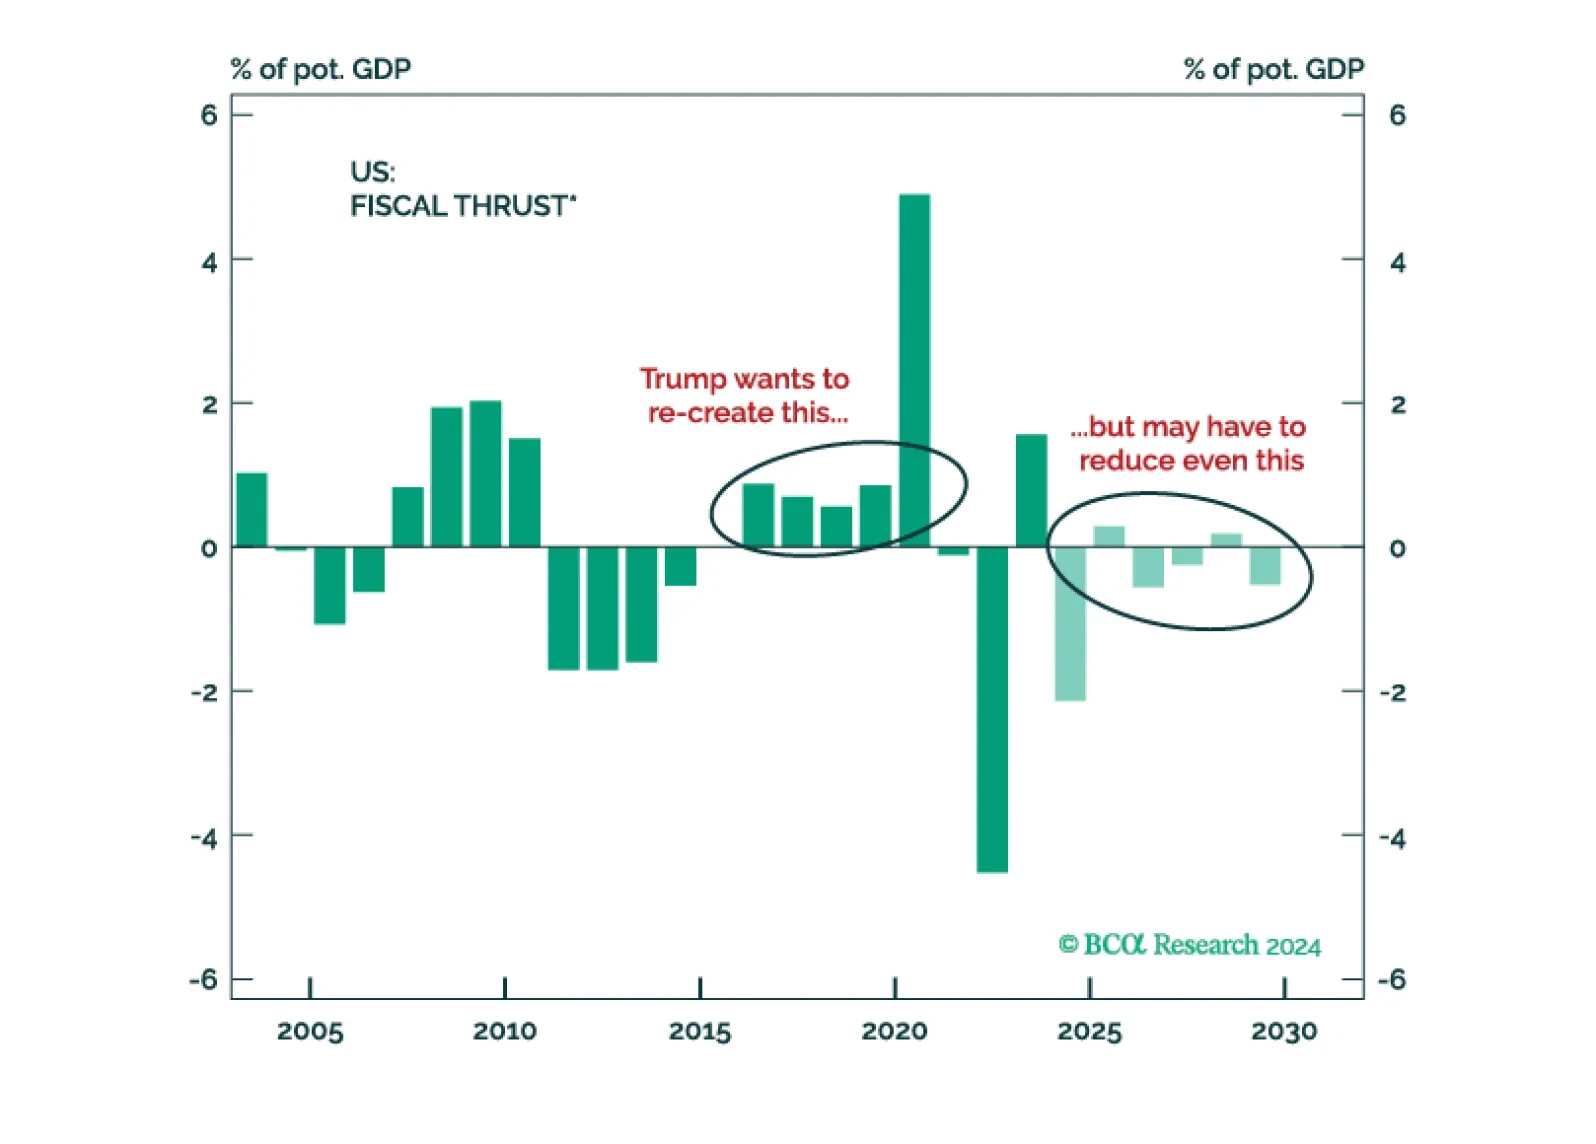
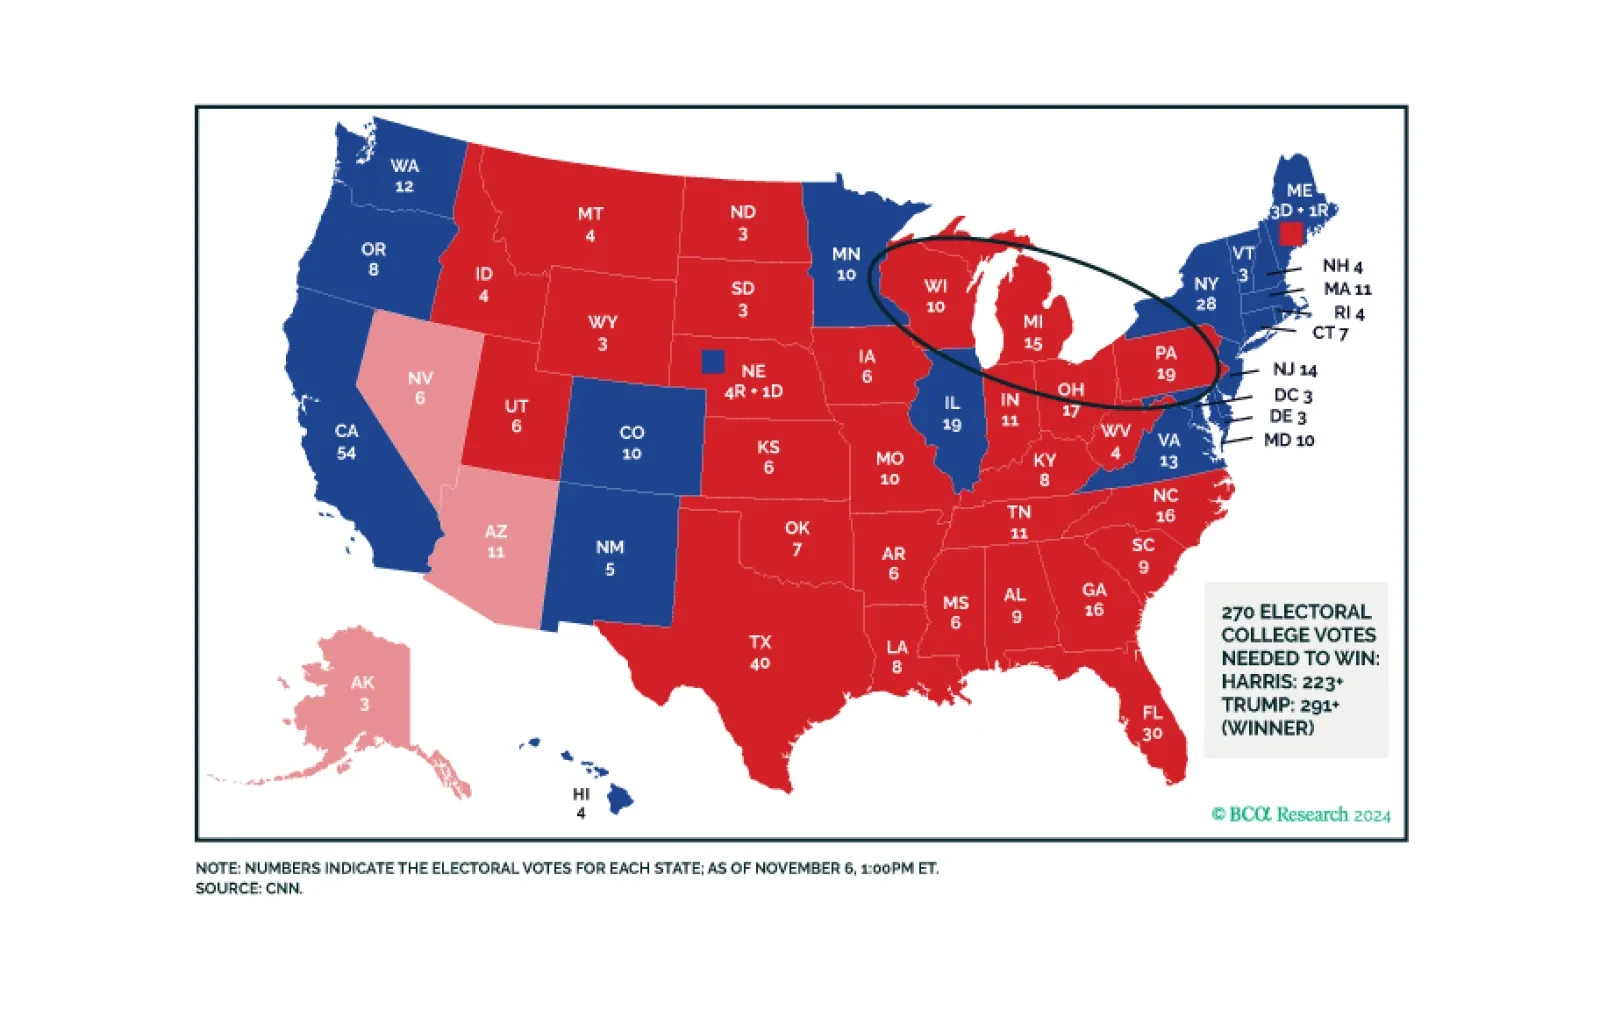
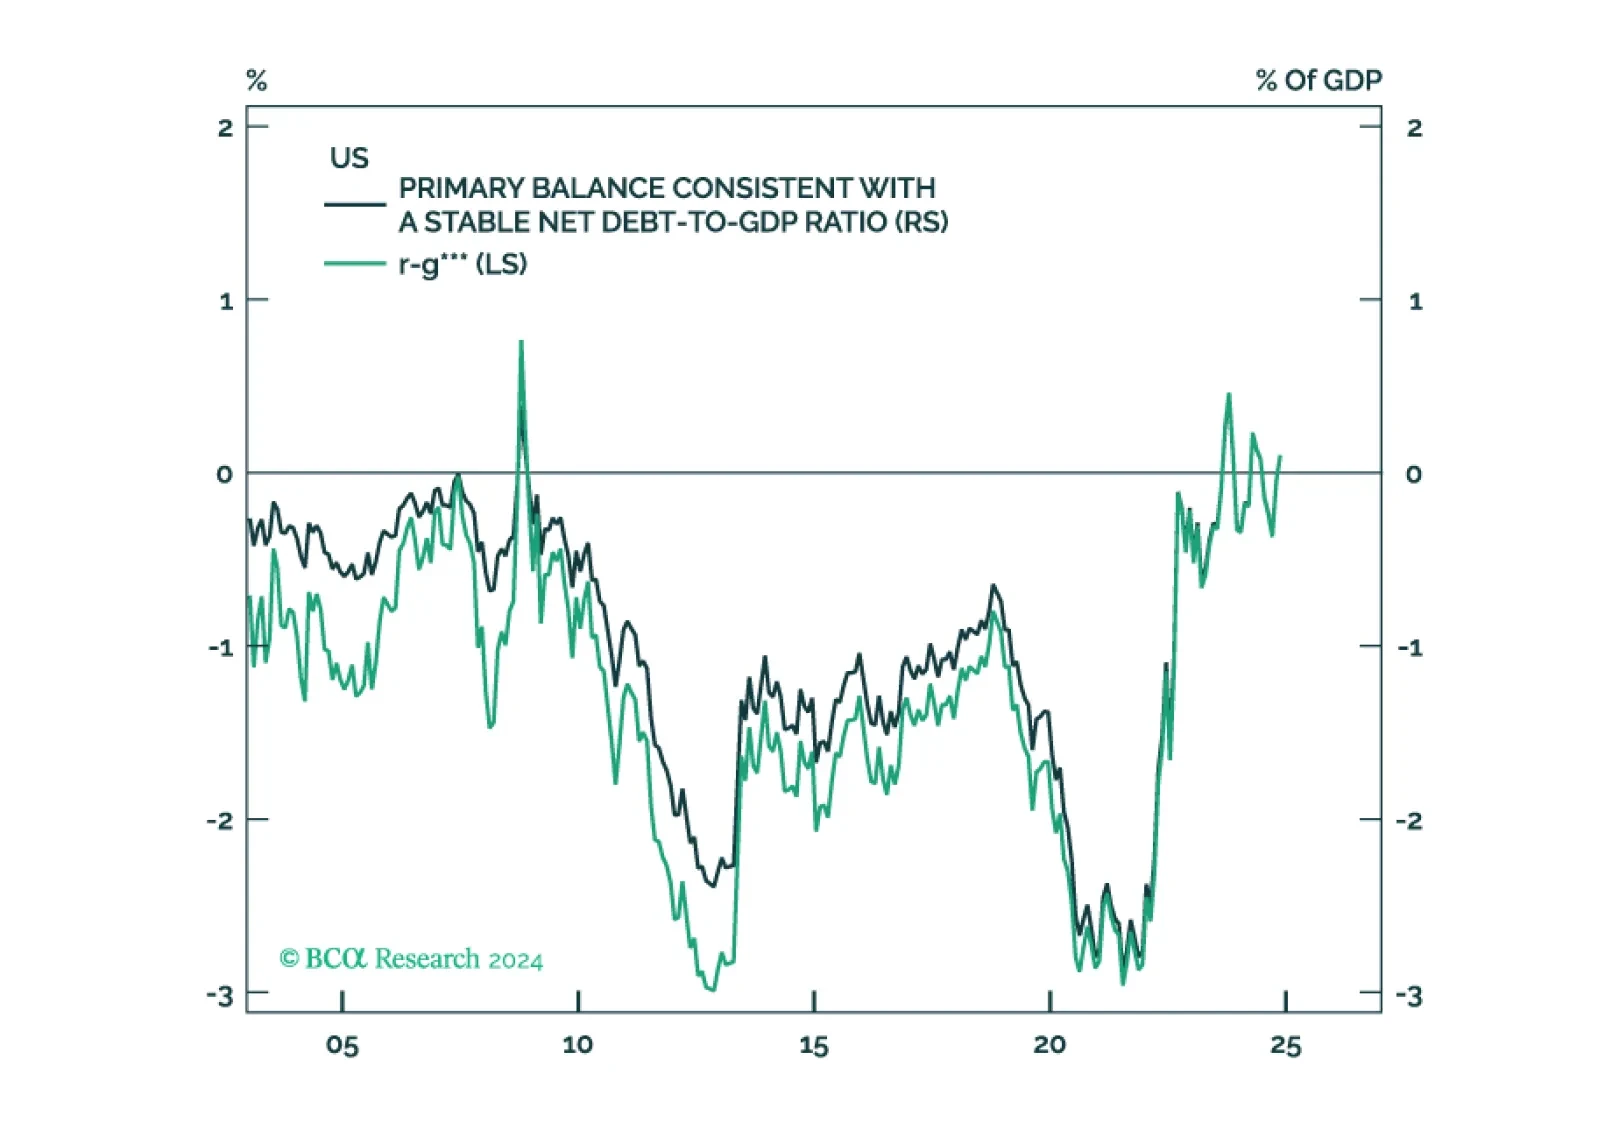
The month of November has brought us S&P 6,000! President Trump has won a “Red Sweep” (as we expected all year) and has ushered in a regime change in America. For now, we are open to chasing momentum. However, the biggest risk to the market are bond yields, which should rise as investors start to price President Trump’s policies and their impact on deficits.

This week, we update our Central Bank Monitors (CBMs), that help us calibrate how monetary policy should be adjusted in developed-market economies. Our conclusion is that while overall, easier monetary settings are required, there a few trade ideas that arise from the divergences in signals amongst G10 countries.