Skip to main content

Latest from BCA Research
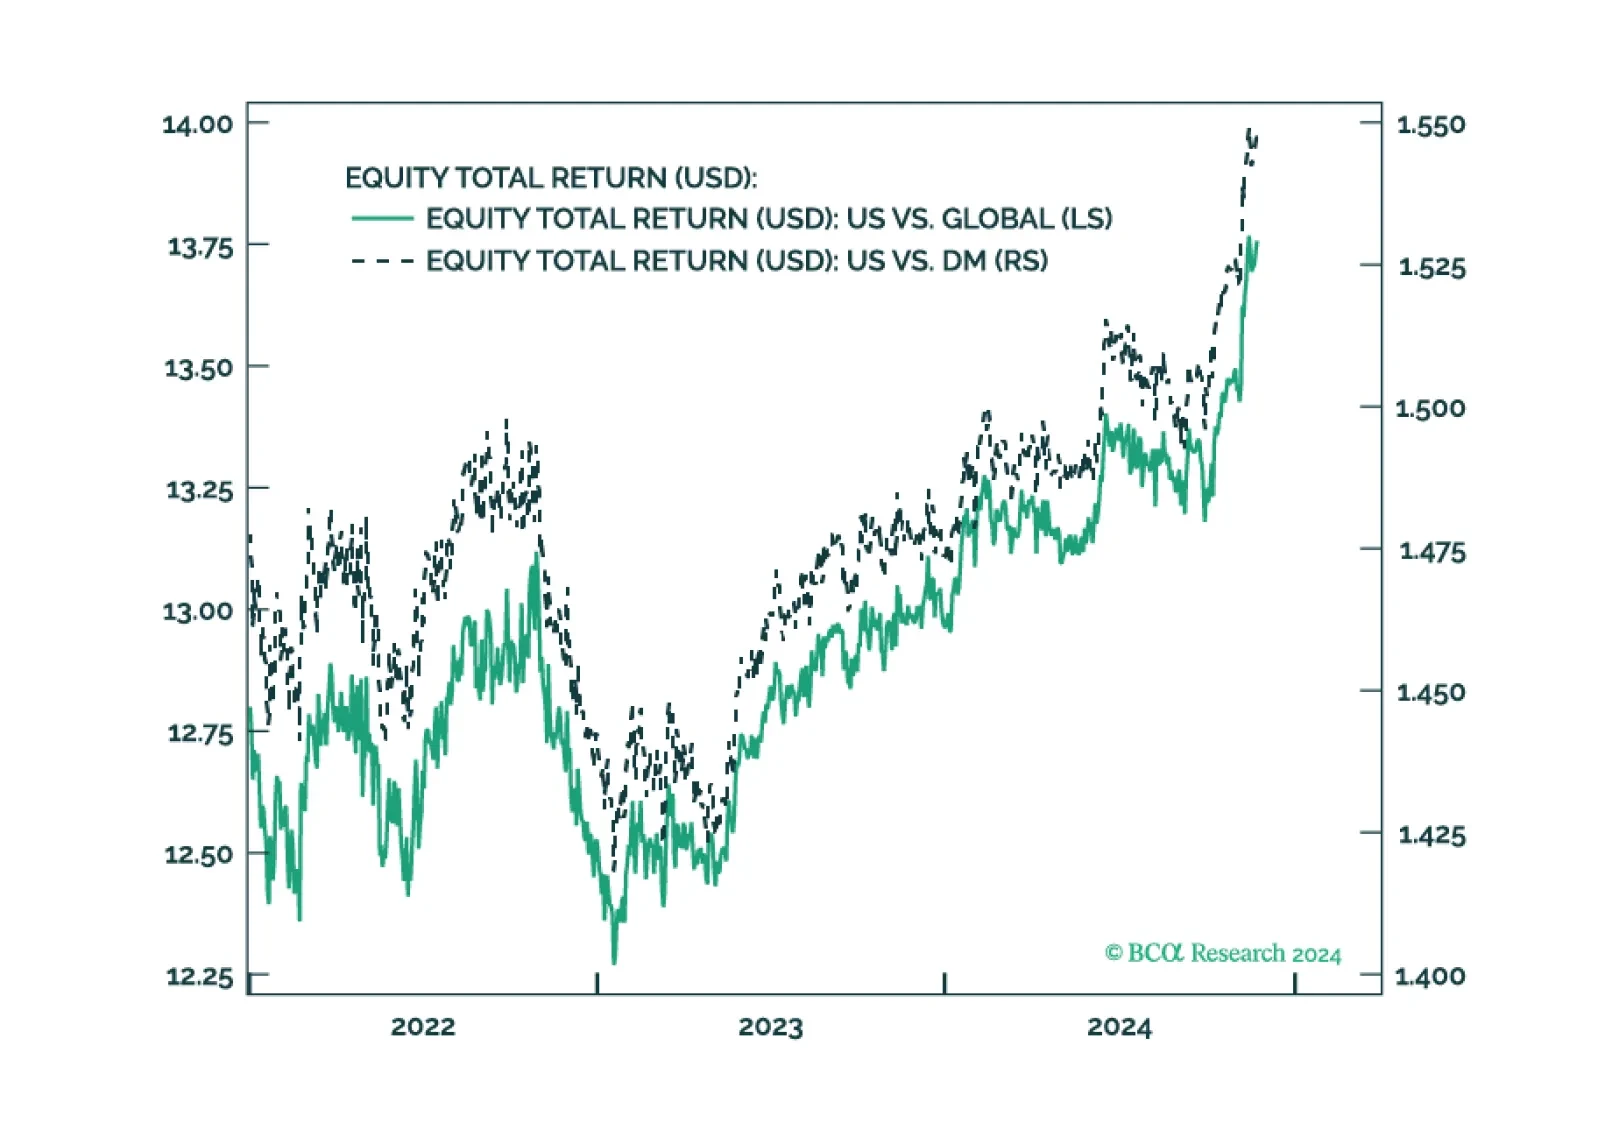
We were far too bearish on the US economy in 2024 – but the global economy remained sluggish and we got the critical geopolitical calls right. We predicted the Republican sweep in the US and the outbreak of direct military hostilities between Israel and Iran. We anticipated the escalation in Ukraine and Russia-NATO tensions that is taking place as we go to press. We stayed overweight US assets relative to global. We did not get blindsided by any of the elections in this “year of elections” – we traded several of them successfully. However, we disfavored cyclical sectors. We fought momentum stocks and lost. Many other trades turned sour. Equity volatility picked up substantially in 2024 as expected, but our attempts to take advantage of this shift fell flat.
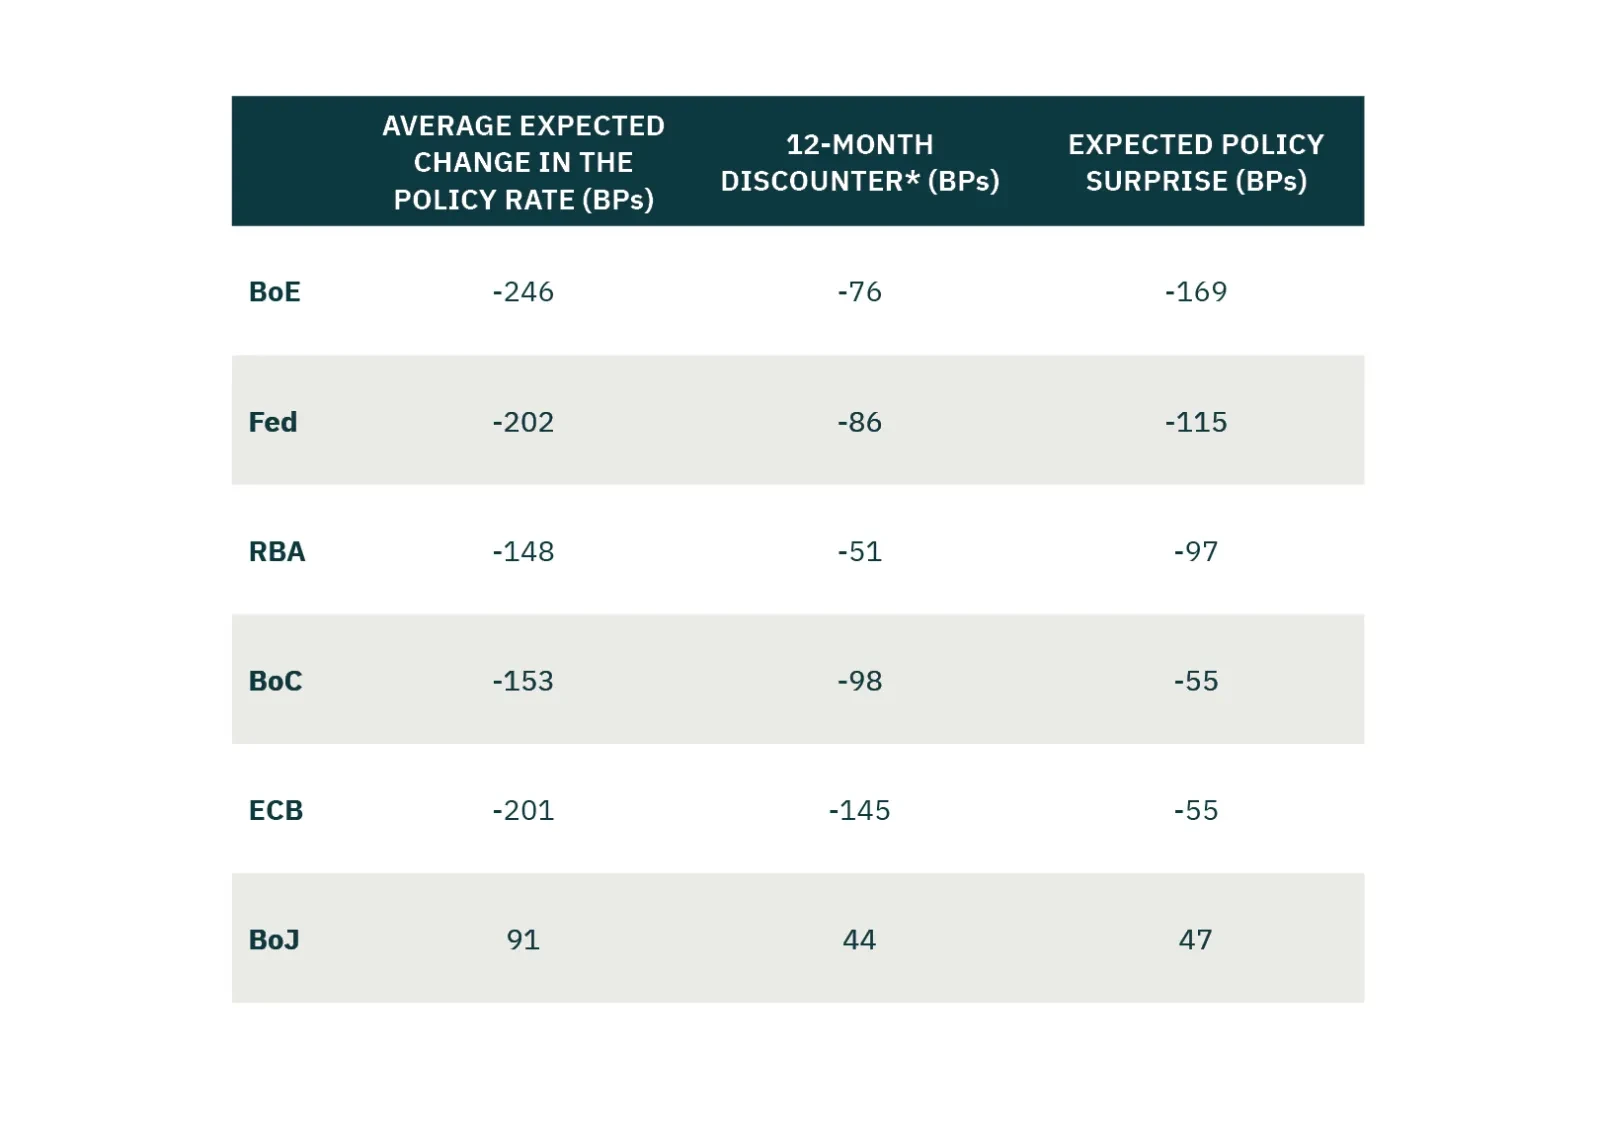
Special Report Today’s Special Report introduces a framework for country allocations in a fixed income portfolio based on relative monetary policy surprises. We present two approaches on how to identify opportunities in the current environment and update our country recommendations based on those.
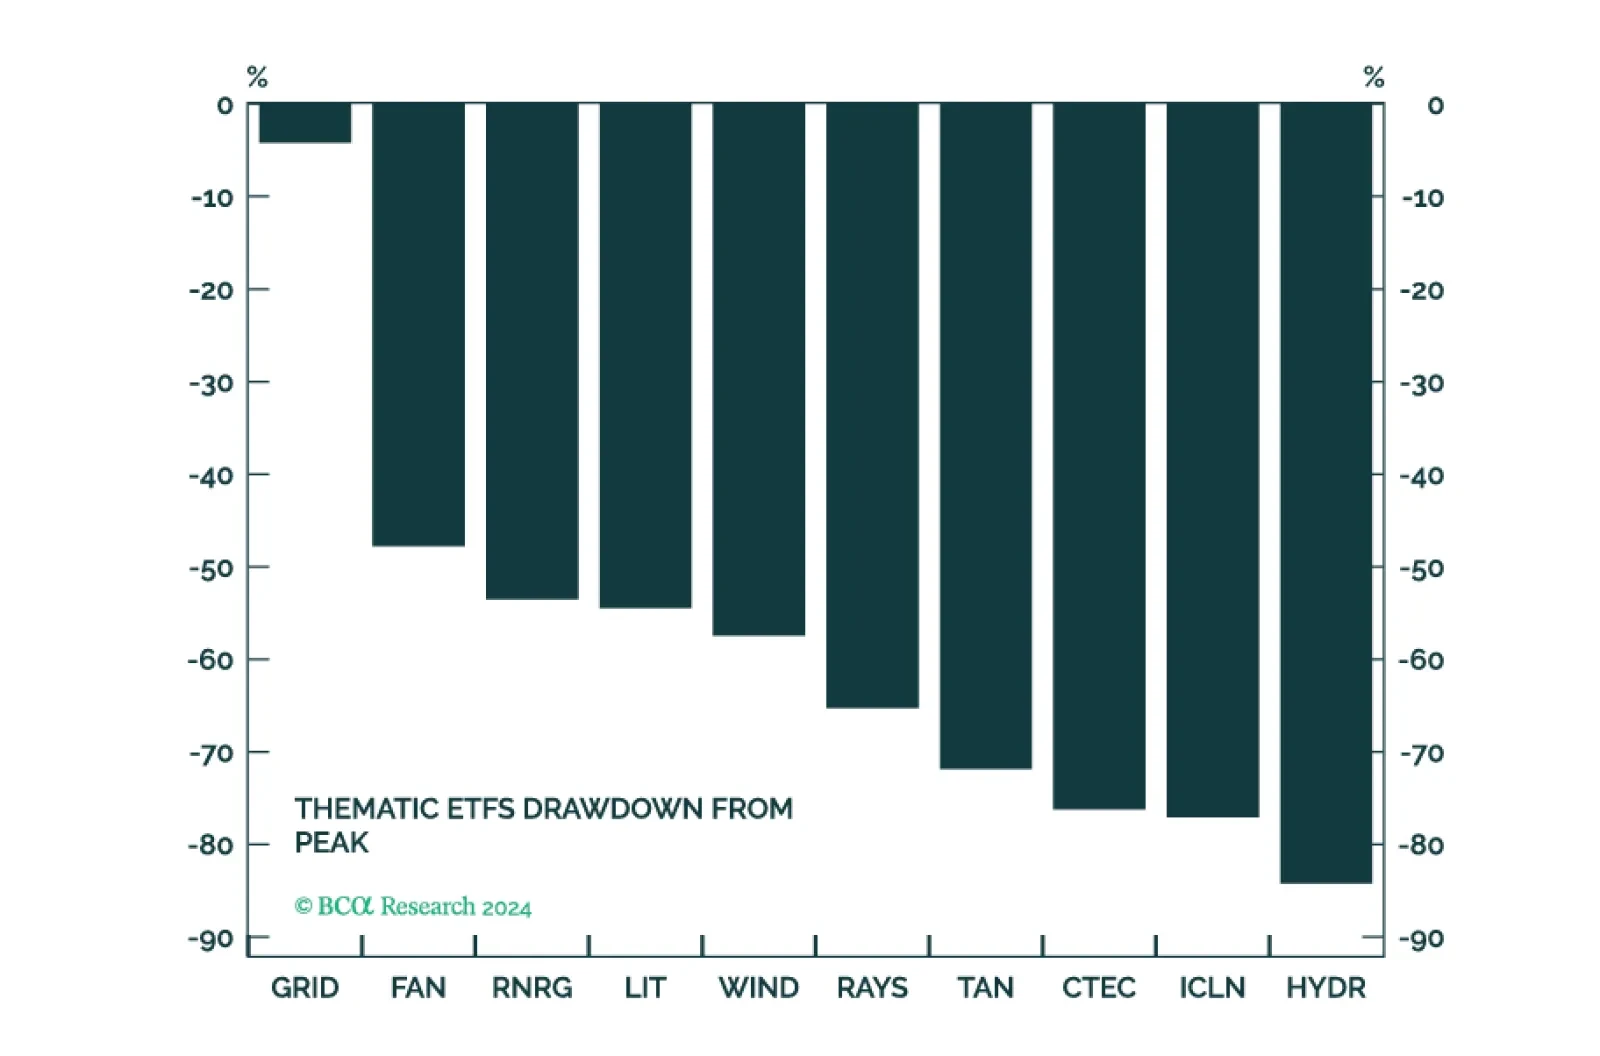
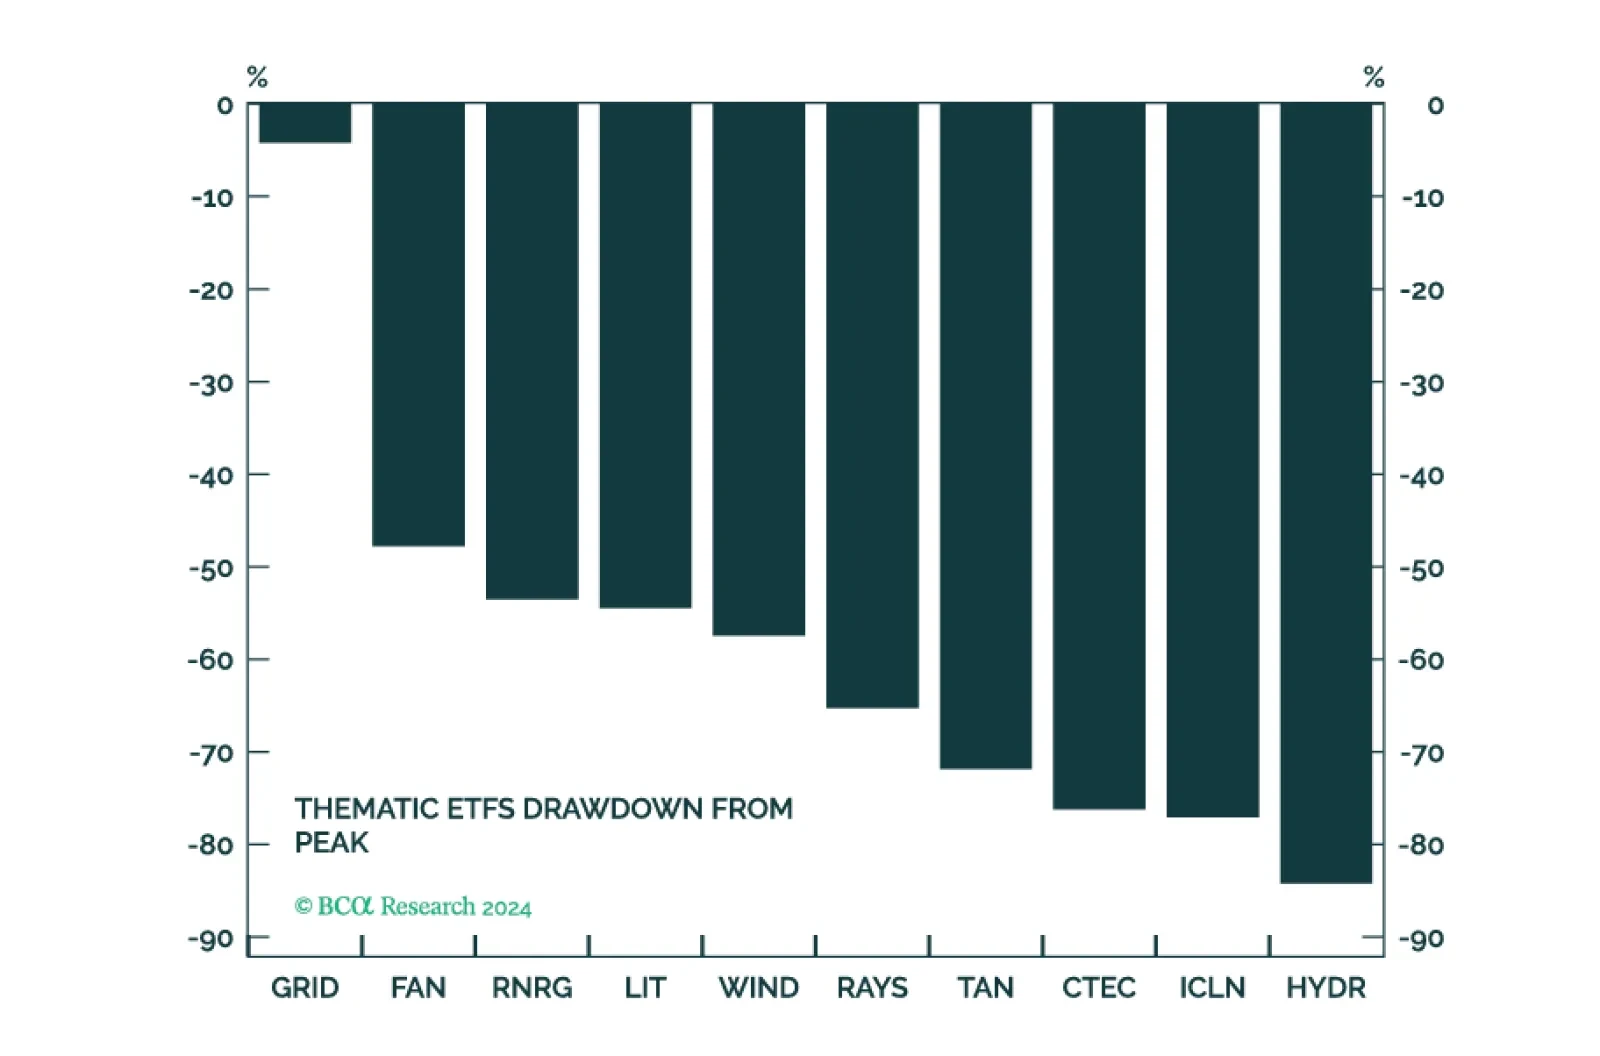
Special Report While some of these headwinds facing G&C are abating or at least are now priced in, it is hard to see the industry rebounding over the short investment horizon unless monetary conditions ease. However, long-term trends supporting a transition to renewable energy are intact – strong demand for energy from Big Tech, falling prices of renewable energy generation, and overall infrastructure buildout. Green energy is here to stay, and we overweight G&C on the strategic investment horizon.
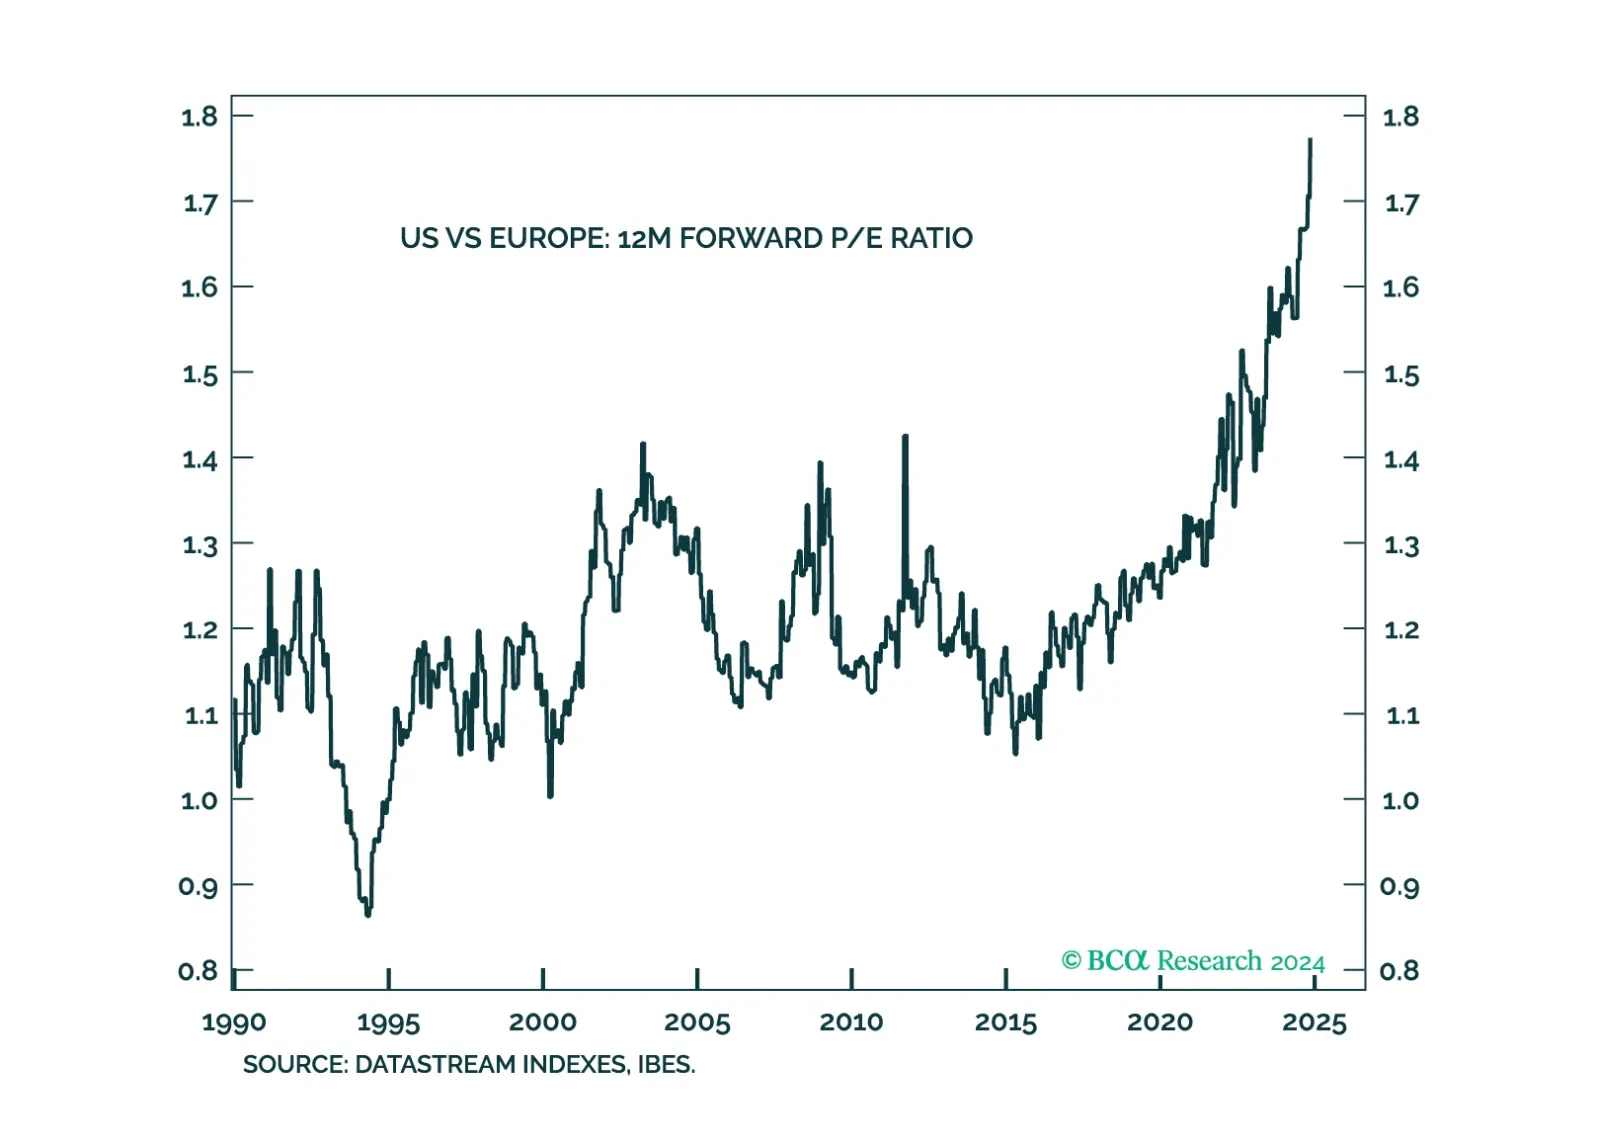
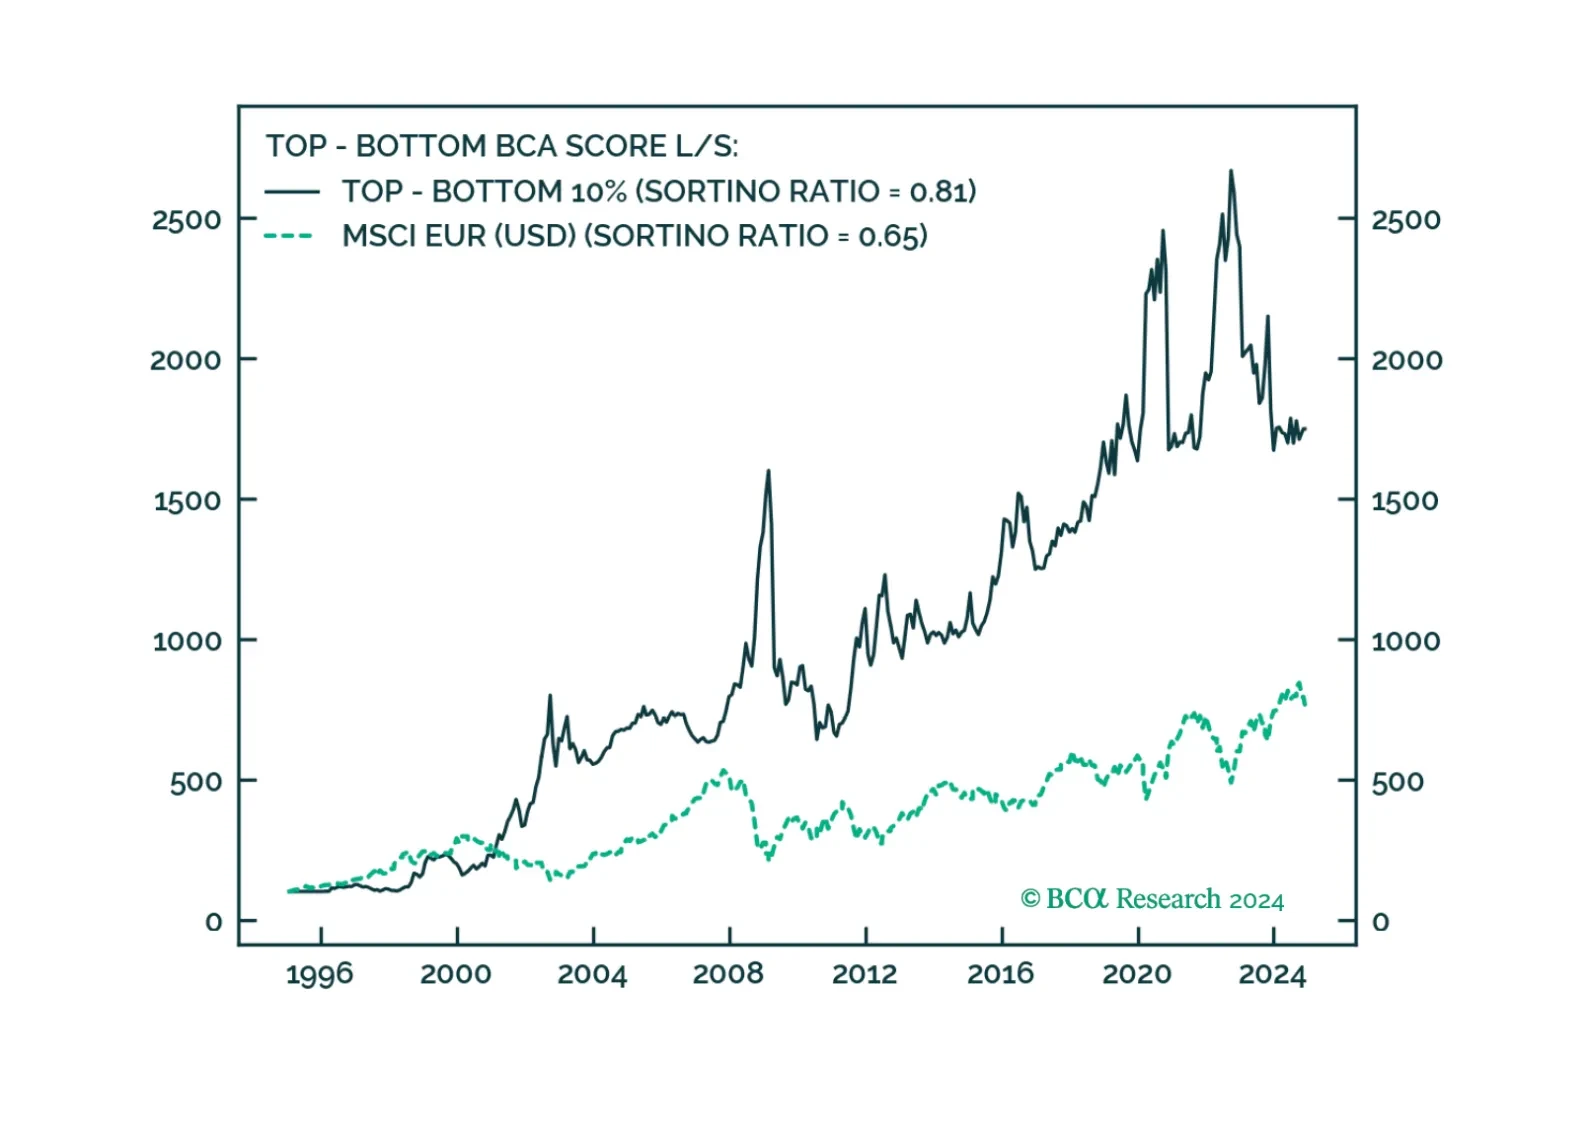
Special Report Introducing BCA Equity Analyzer and how you can enhance equity performance by pairing our top-down macro coverage of Europe with EA’s bottom-up and stock-level analysis.
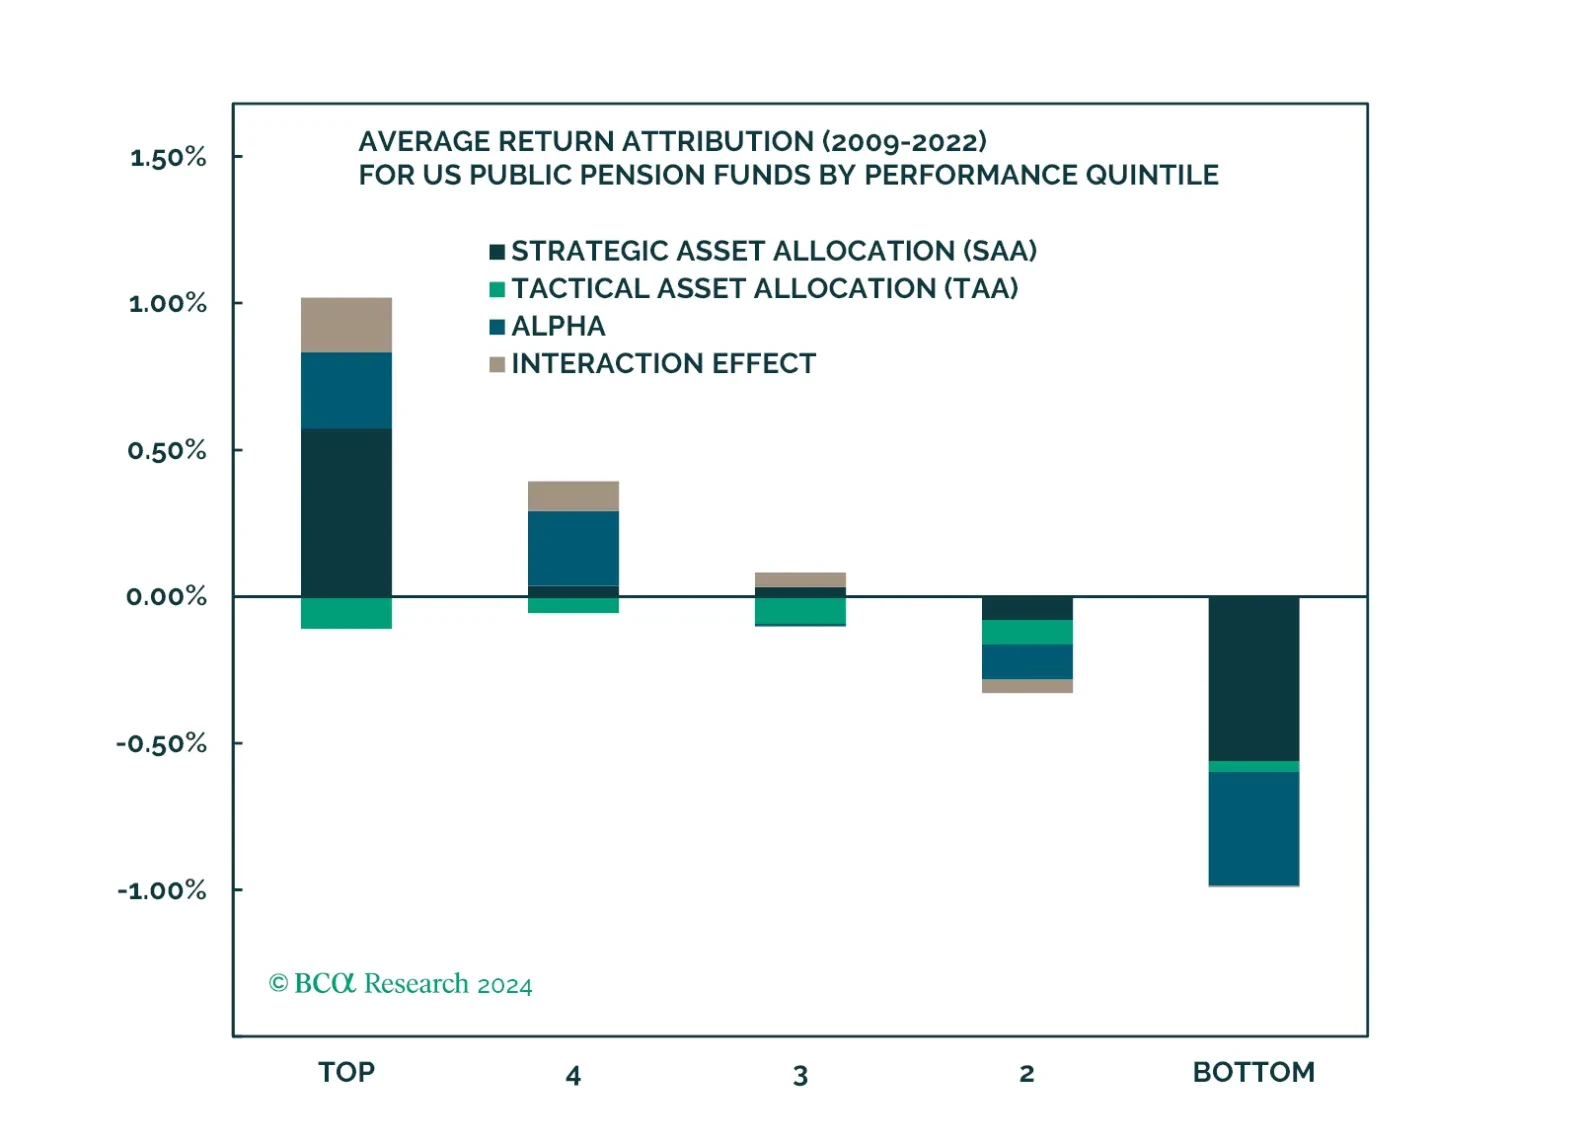
Special Report We analyse the performance and allocation of 79 US public pension funds from 2008 to 2022 with the goal of finding insights into what drives pension fund returns and drawing lessons for institutional investors. We find that most of the performance of top funds come from Strategic Asset Allocation decisions (SAA). We also find that while hedge funds can be an attractive diversifier for large allocators, they are not as attractive for smaller ones. Finally, we suggest that using futures can be an effective way to maintain required liquidity while improving capital efficiency.
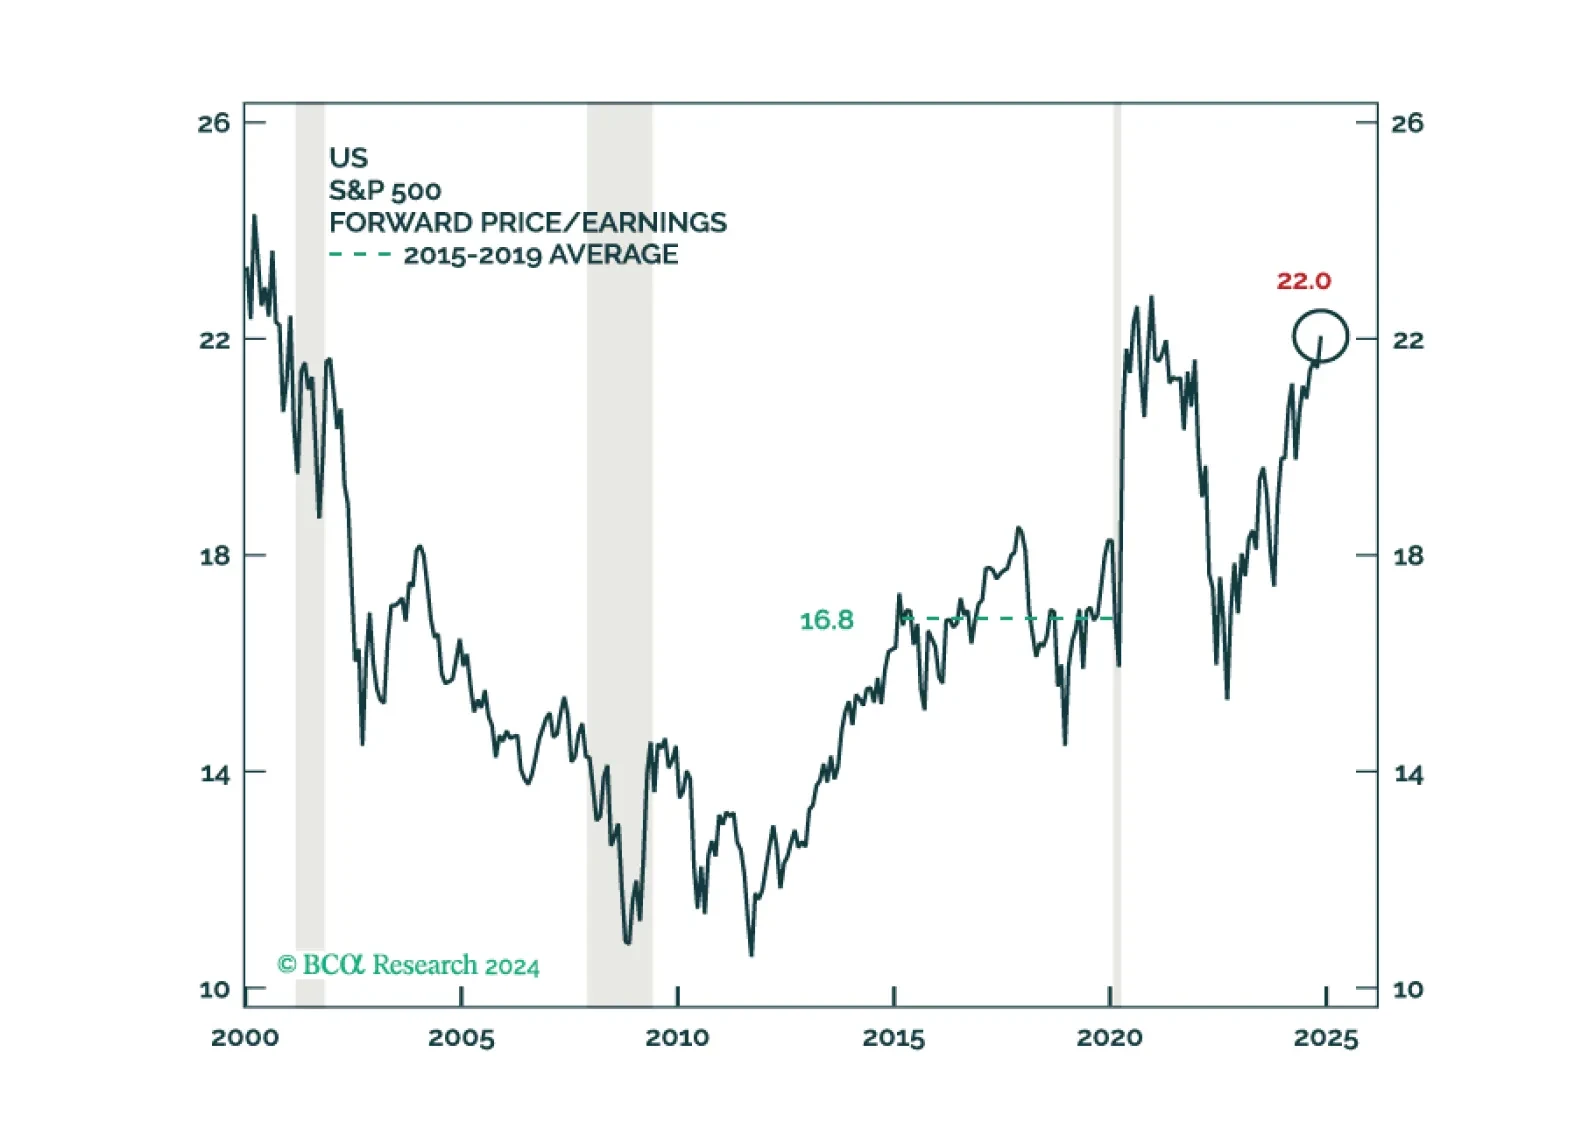
After the election, investors have begun to price in a repeat of the first Trump presidency. The market is expecting Trump to enact a flurry of policies that will unleash a year of growth like 2017. But we believe the consensus is wrong. Investors are playing the man and not the macro. The economic outlook and the political situation today are the polar opposite to late 2016. We are fading the small cap rally and recommending above-benchmark duration. We also recommend a defensive stance.