Gov Sovereigns/Treasurys
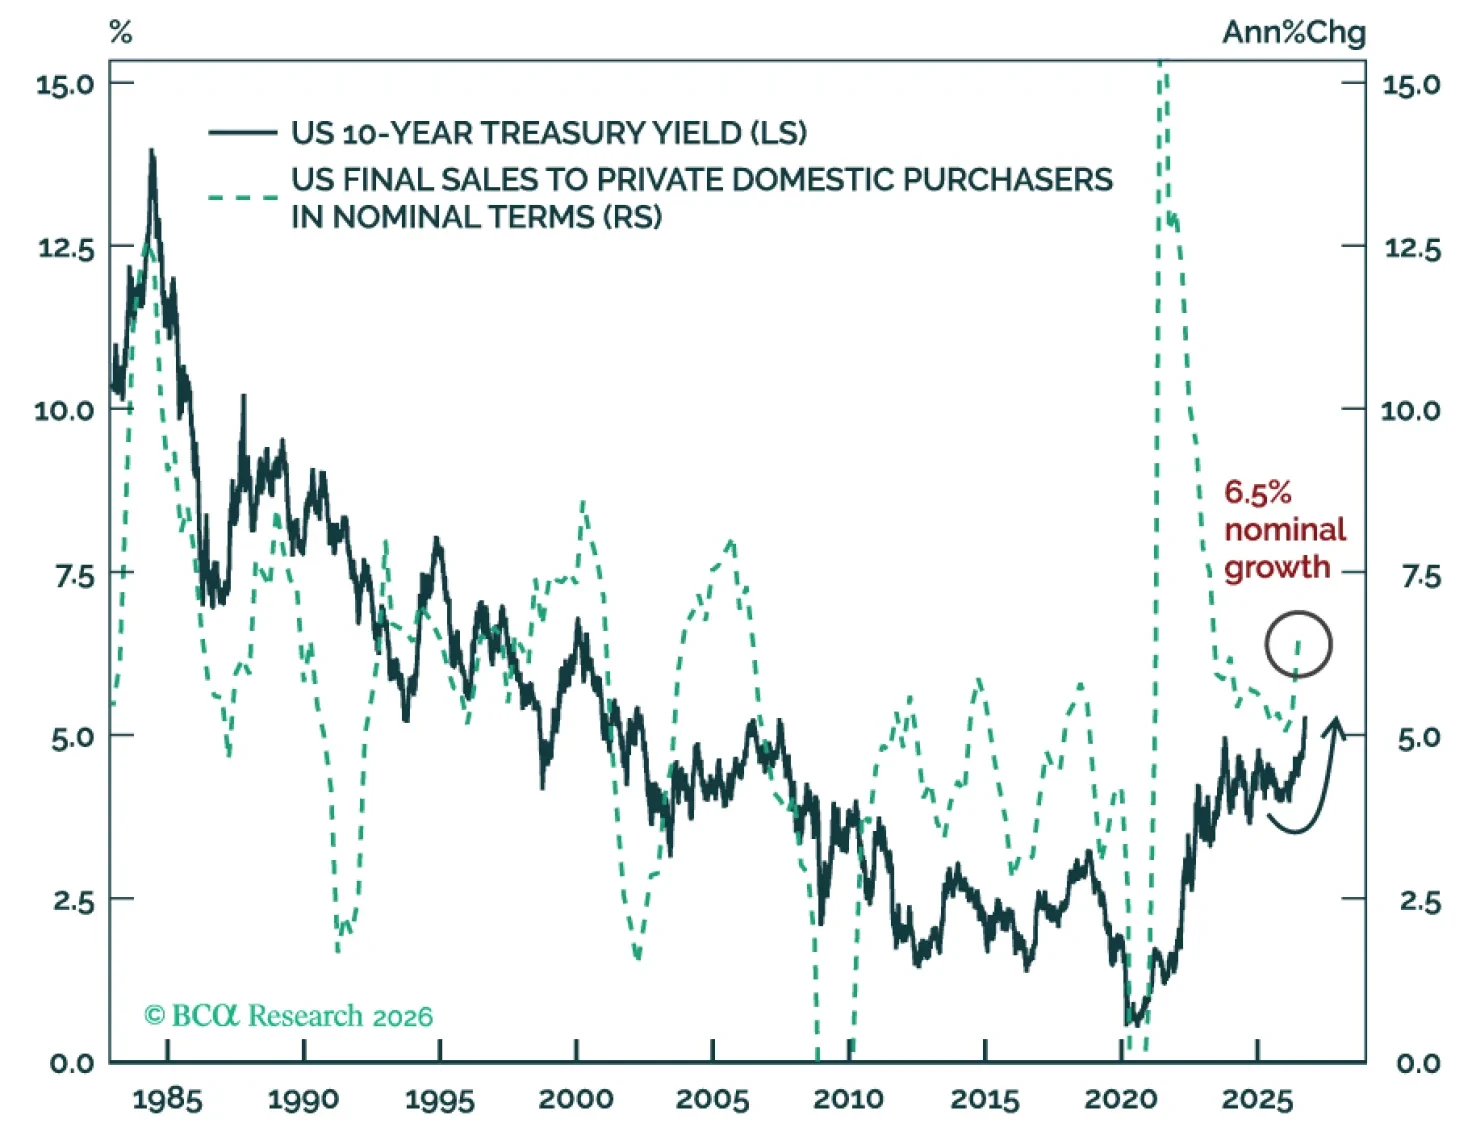
US bonds will likely continue selling off until tighter financial conditions – most plausibly a double-digit decline in the S&P 500 – cool nominal growth. Higher discount rates will threaten US equity valuations before earnings weaken. AI stocks will peak well ahead of AI capex. Remain downbeat on EM stocks.
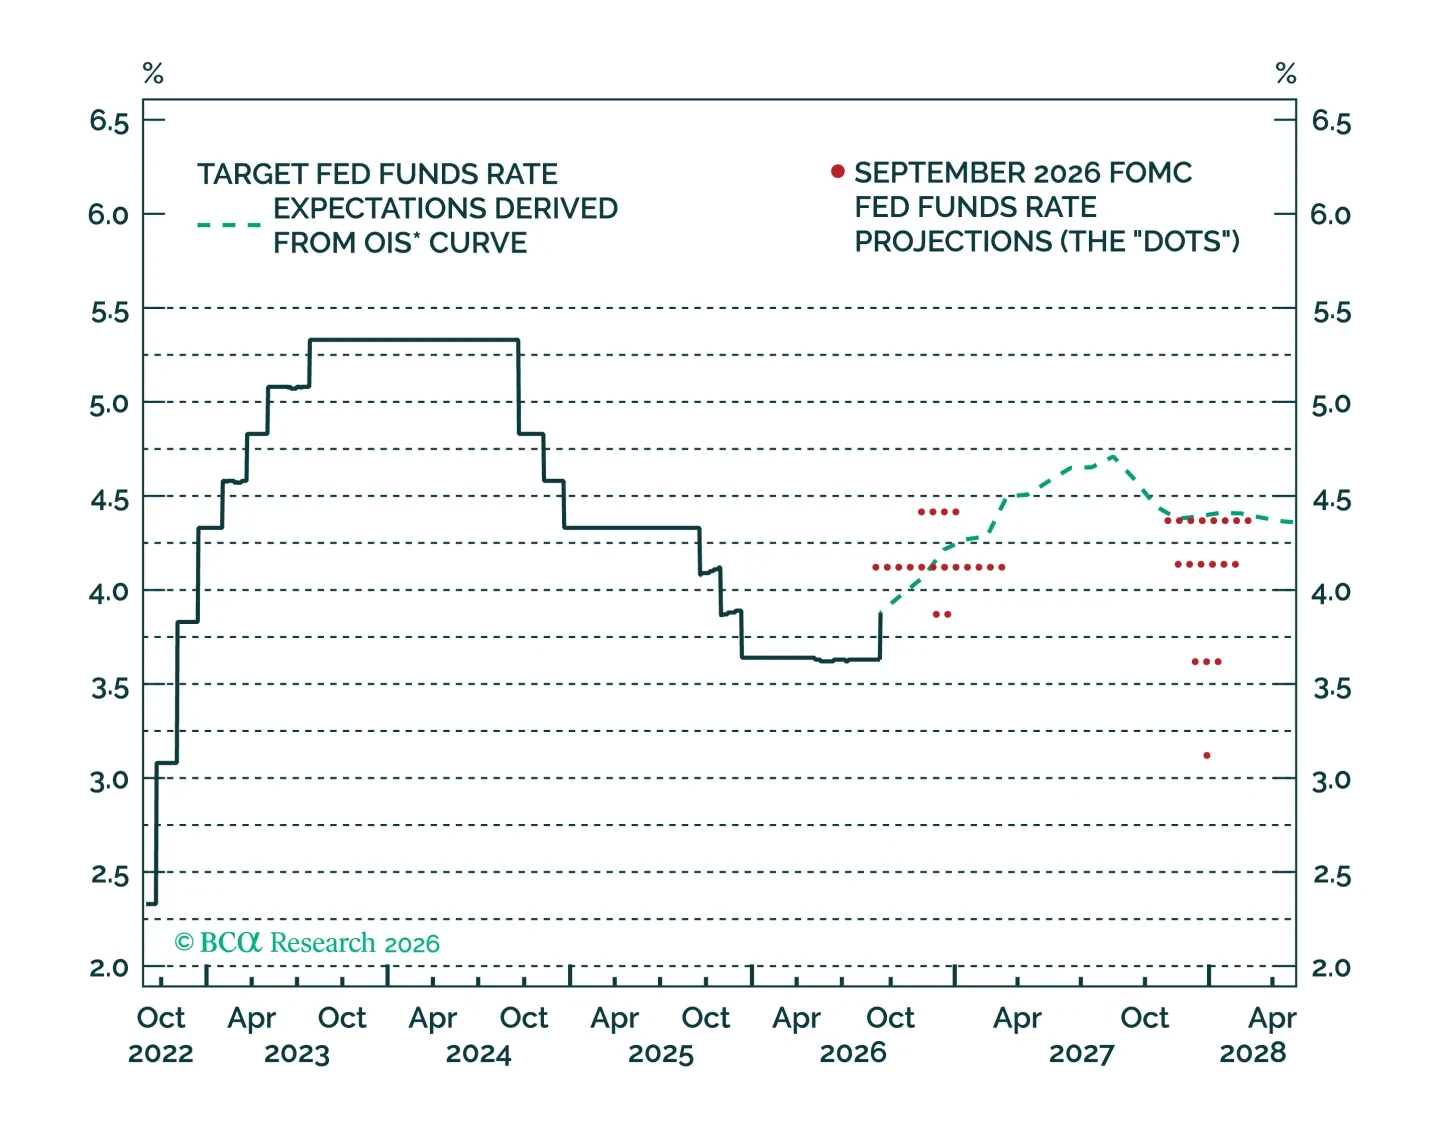
The Fed is unanimous in expecting a mild tightening cycle of no more than 75 bps, but that outcome is contingent on a rapid drop in core inflation in 2027.
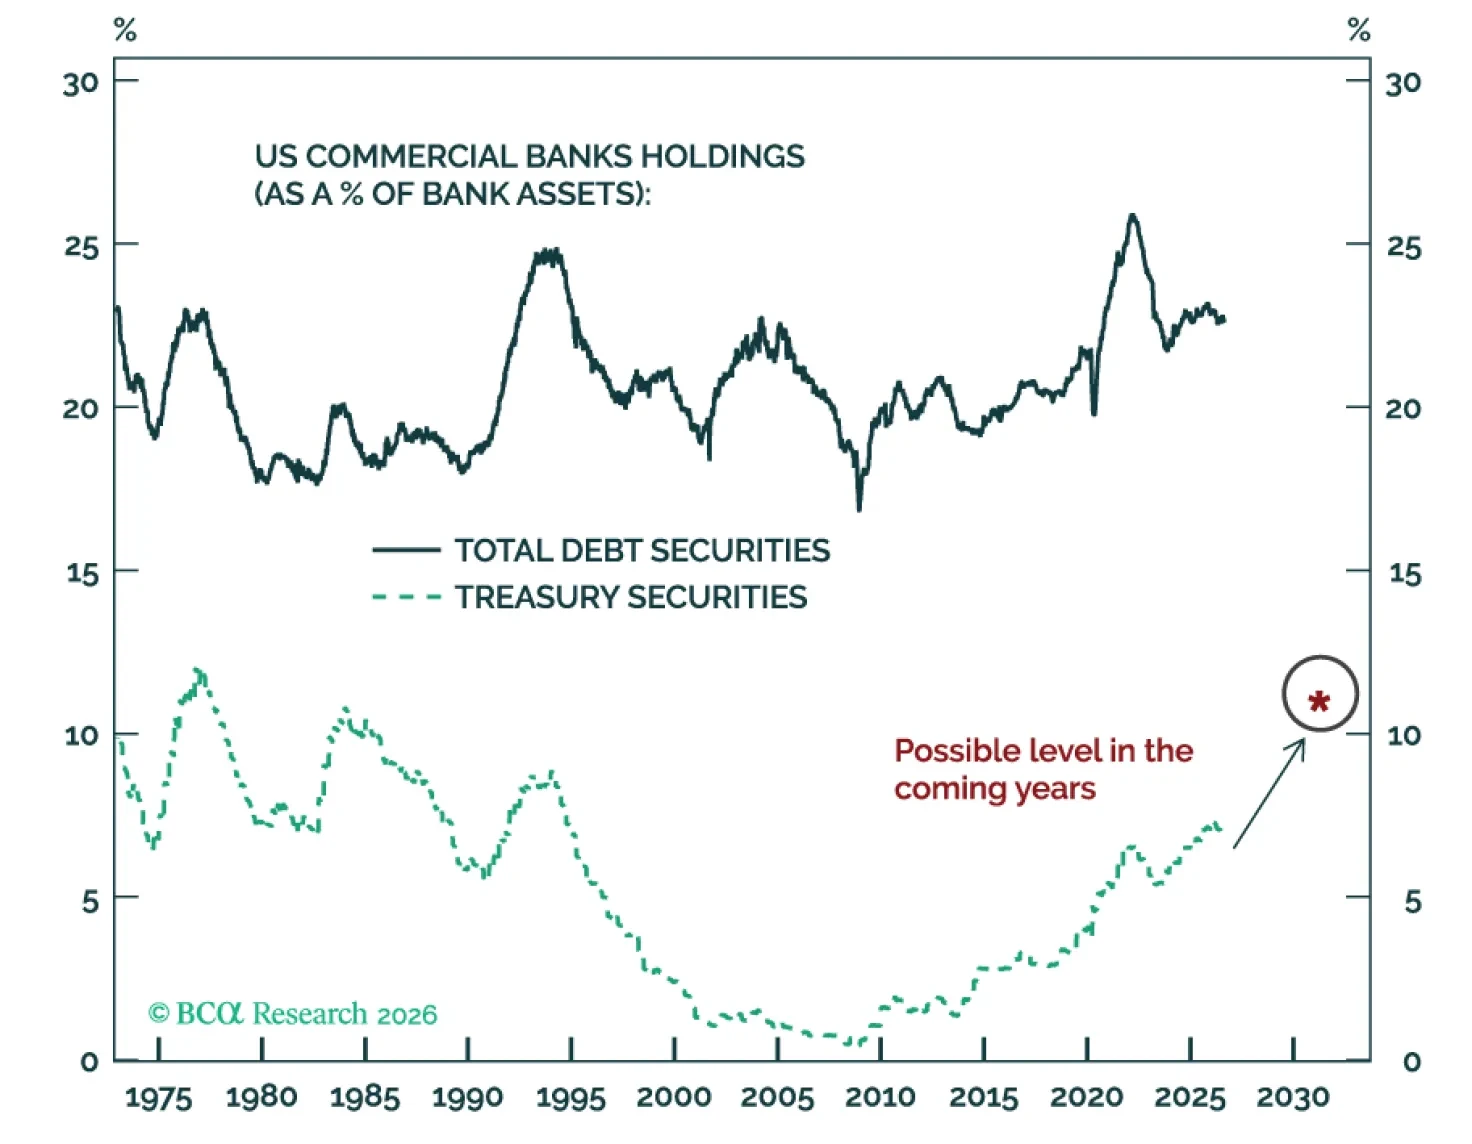
Scott Bessent’s attempts to suppress yields while financing large twin deficits risk crashing foreign inflows, the dollar, US bonds, and equities. Without a major equity selloff or large-scale commercial bank purchases of Treasurys, the bond selloff will persist – producing a major equity drawdown and a lower dollar.
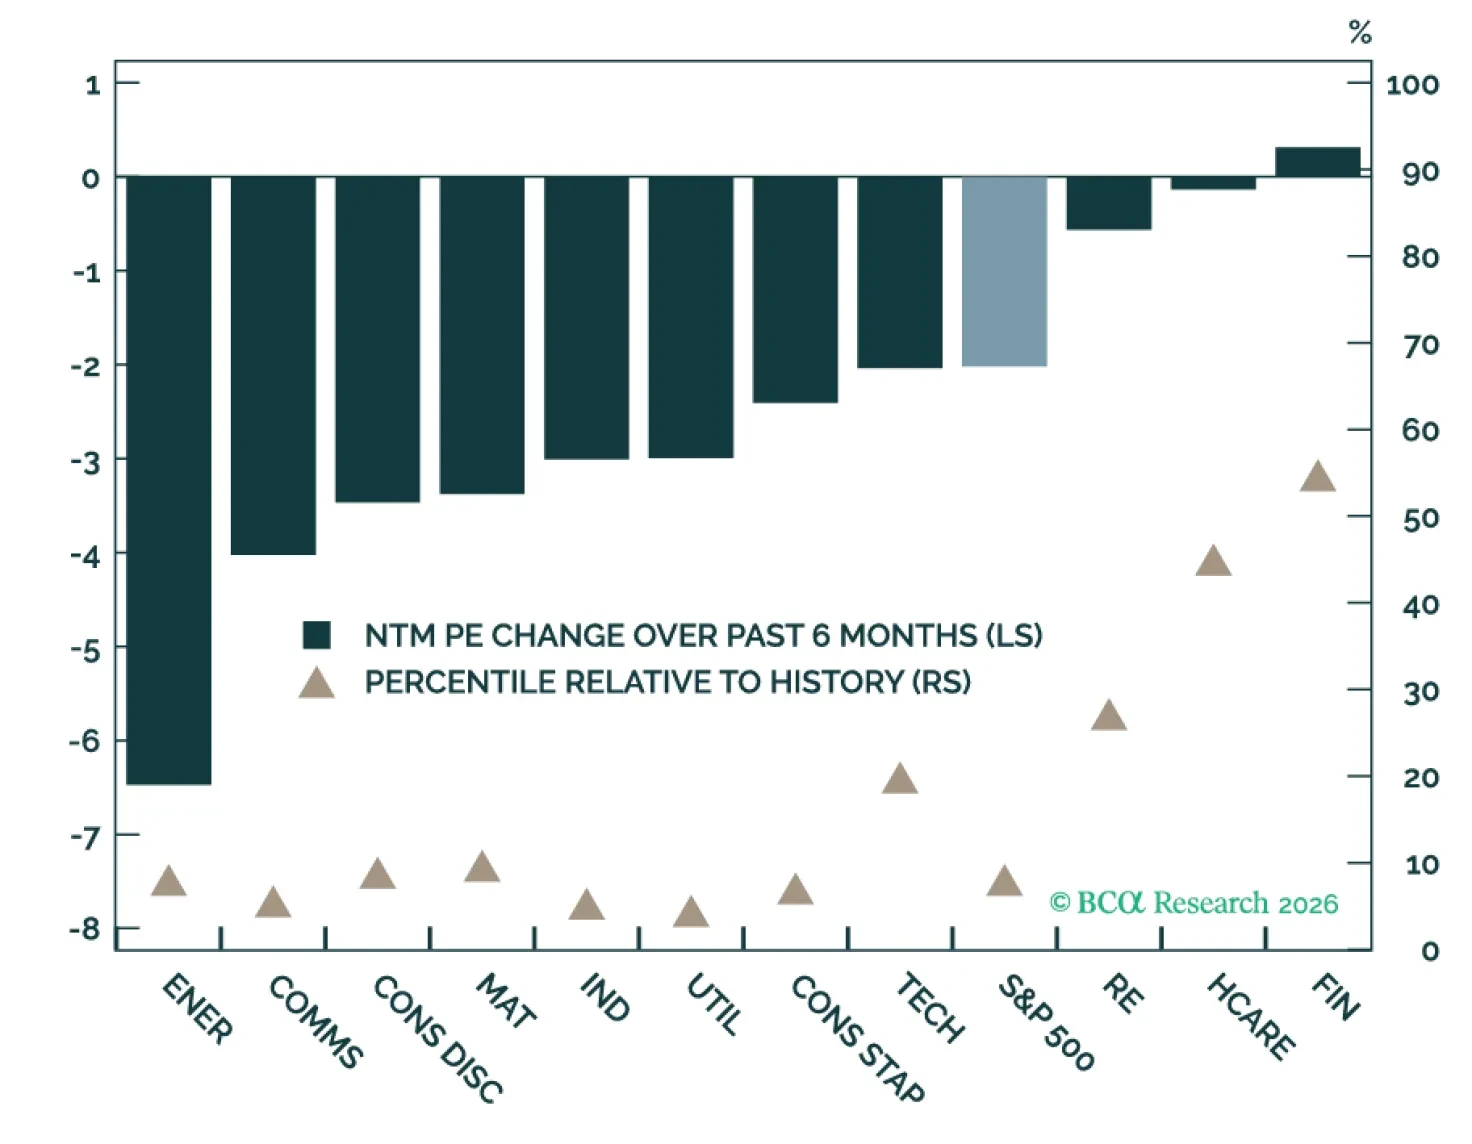
We remain constructive on US equities, but higher yields, slower EPS growth and heavy IPO issuance remain significant risks to valuations, leaving the path to our year-end target increasingly dependent on earnings. Tactically, there has already been a significant, but benign, compression in multiples, as earnings have outpaced prices. A well-communicated Fed hike could ease rather than intensify bond-market uncertainty.

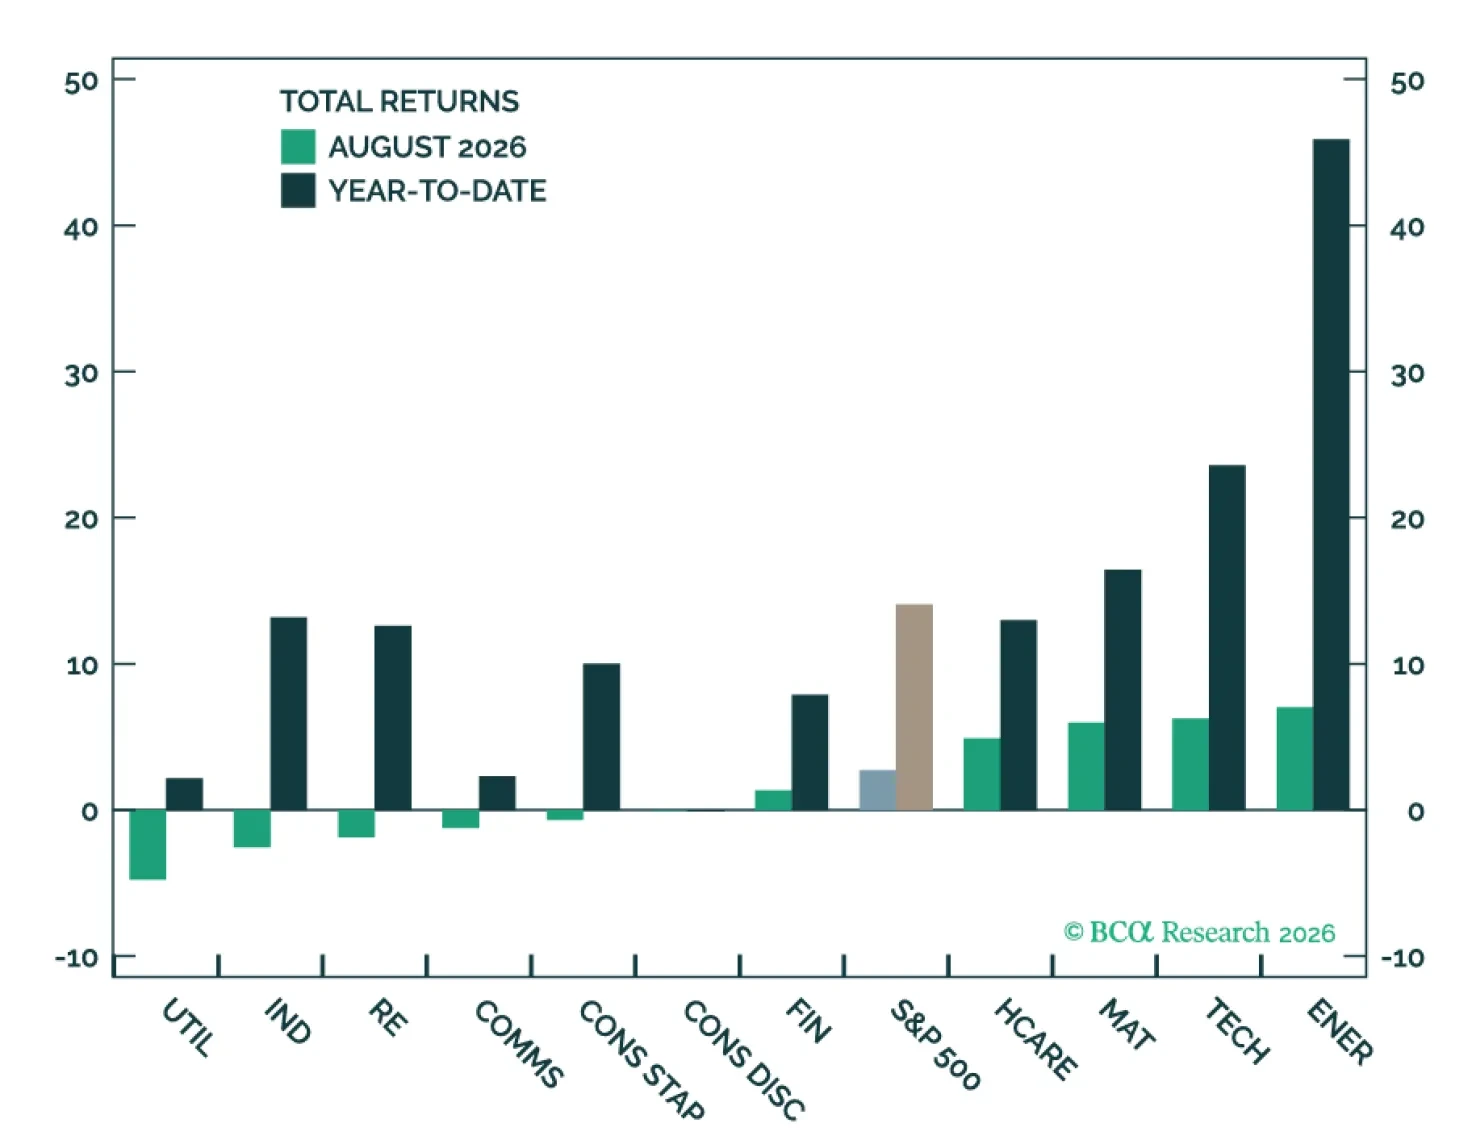
Strong second quarter earnings suggest that the AI story is intact. Buoyed in part by this strength, tech stocks have recoupled with healthy fundamentals after a late-July swoon, posting solid August gains. We continue to see upside for the S&P 500, favoring the cyclical and AI exposure of tech, materials, and industrials. But rising bond yields remain the dominant headwind.

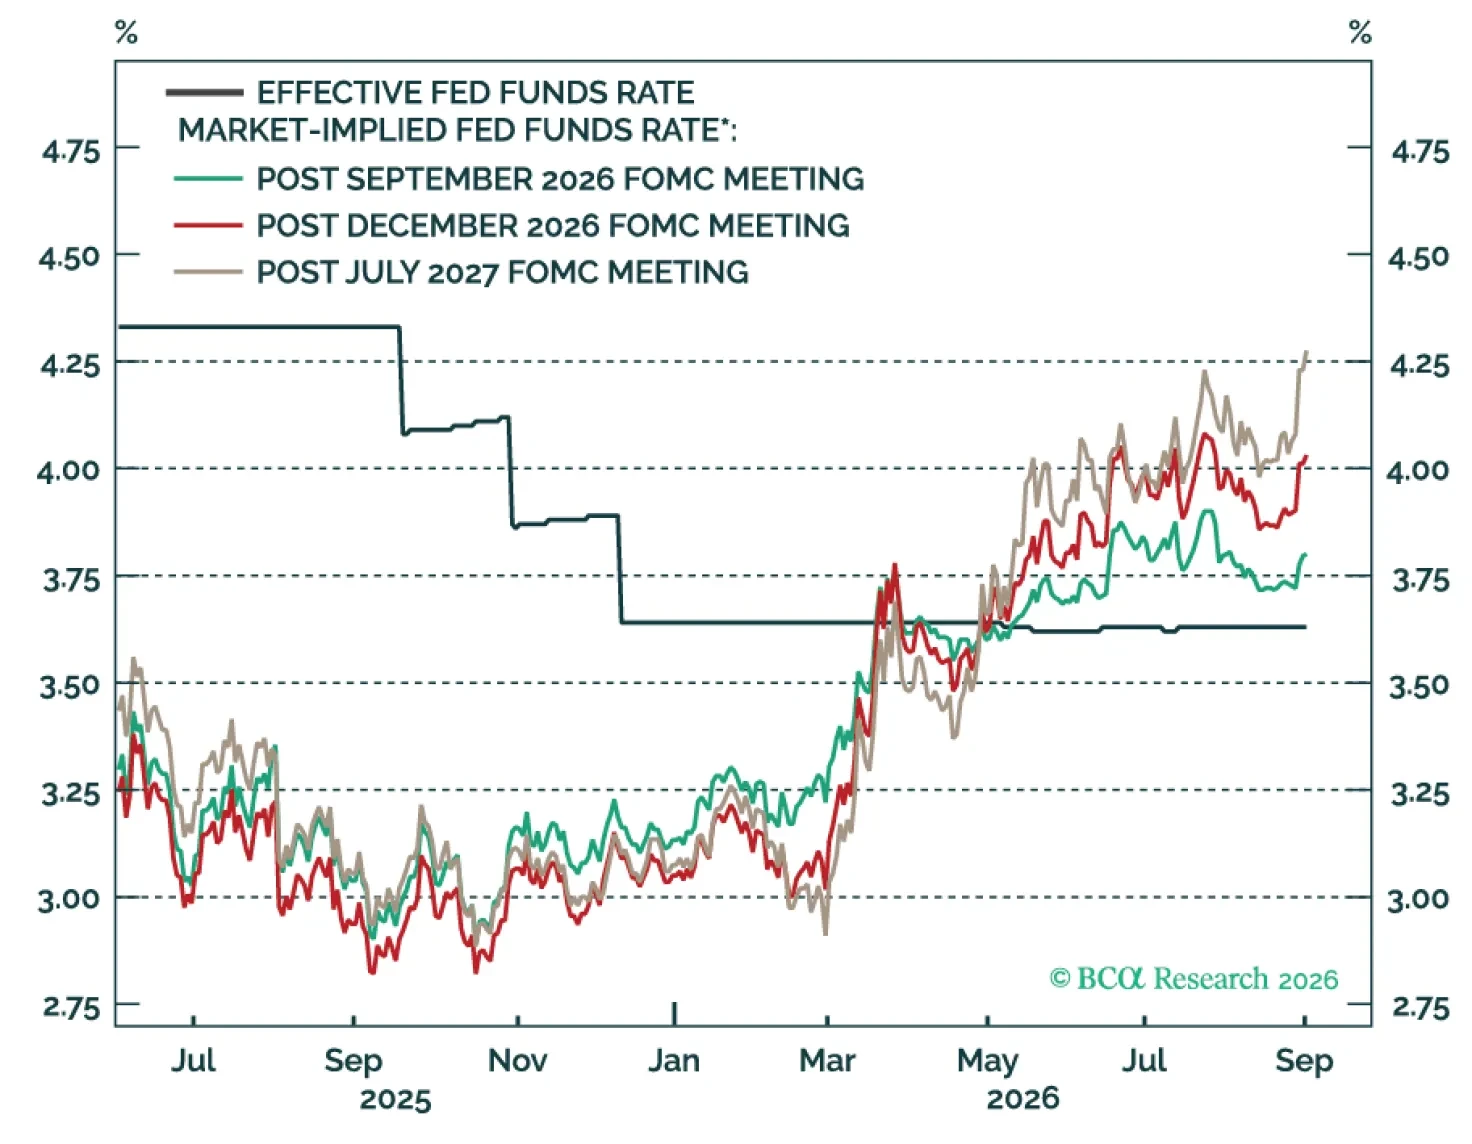
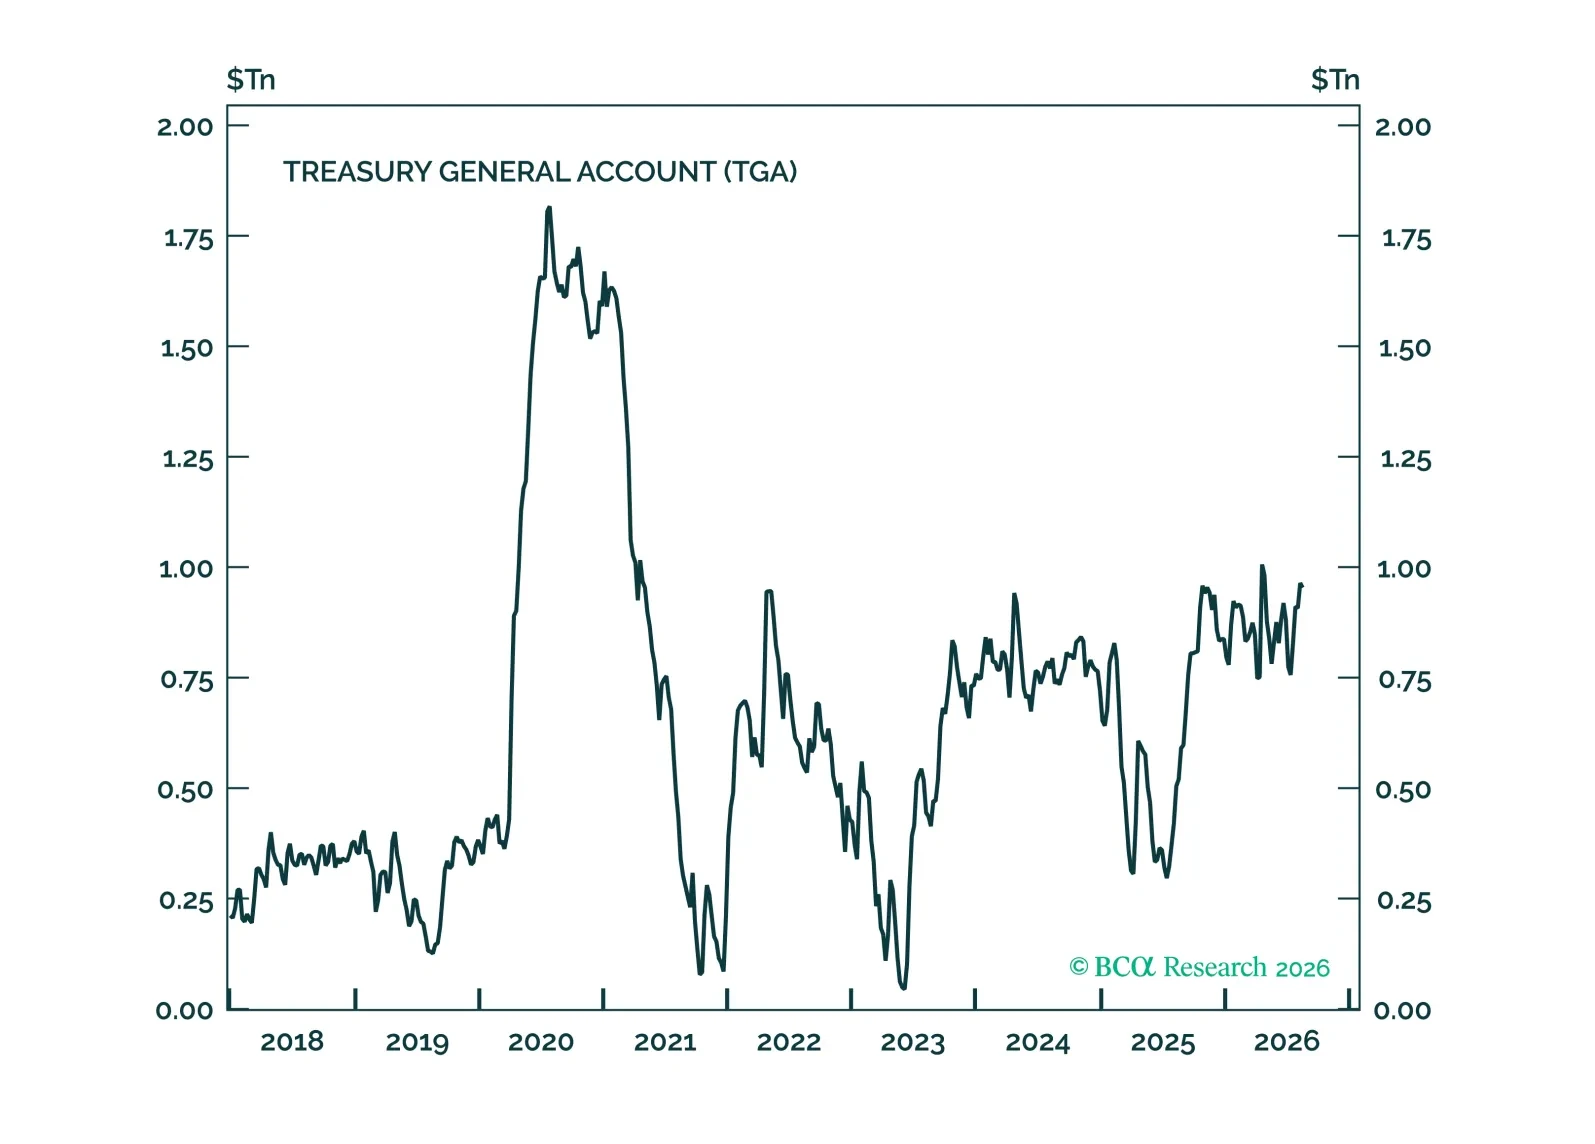
The US Treasury department’s attempts at yield suppression are doomed to fail unless the Federal Reserve gets involved.
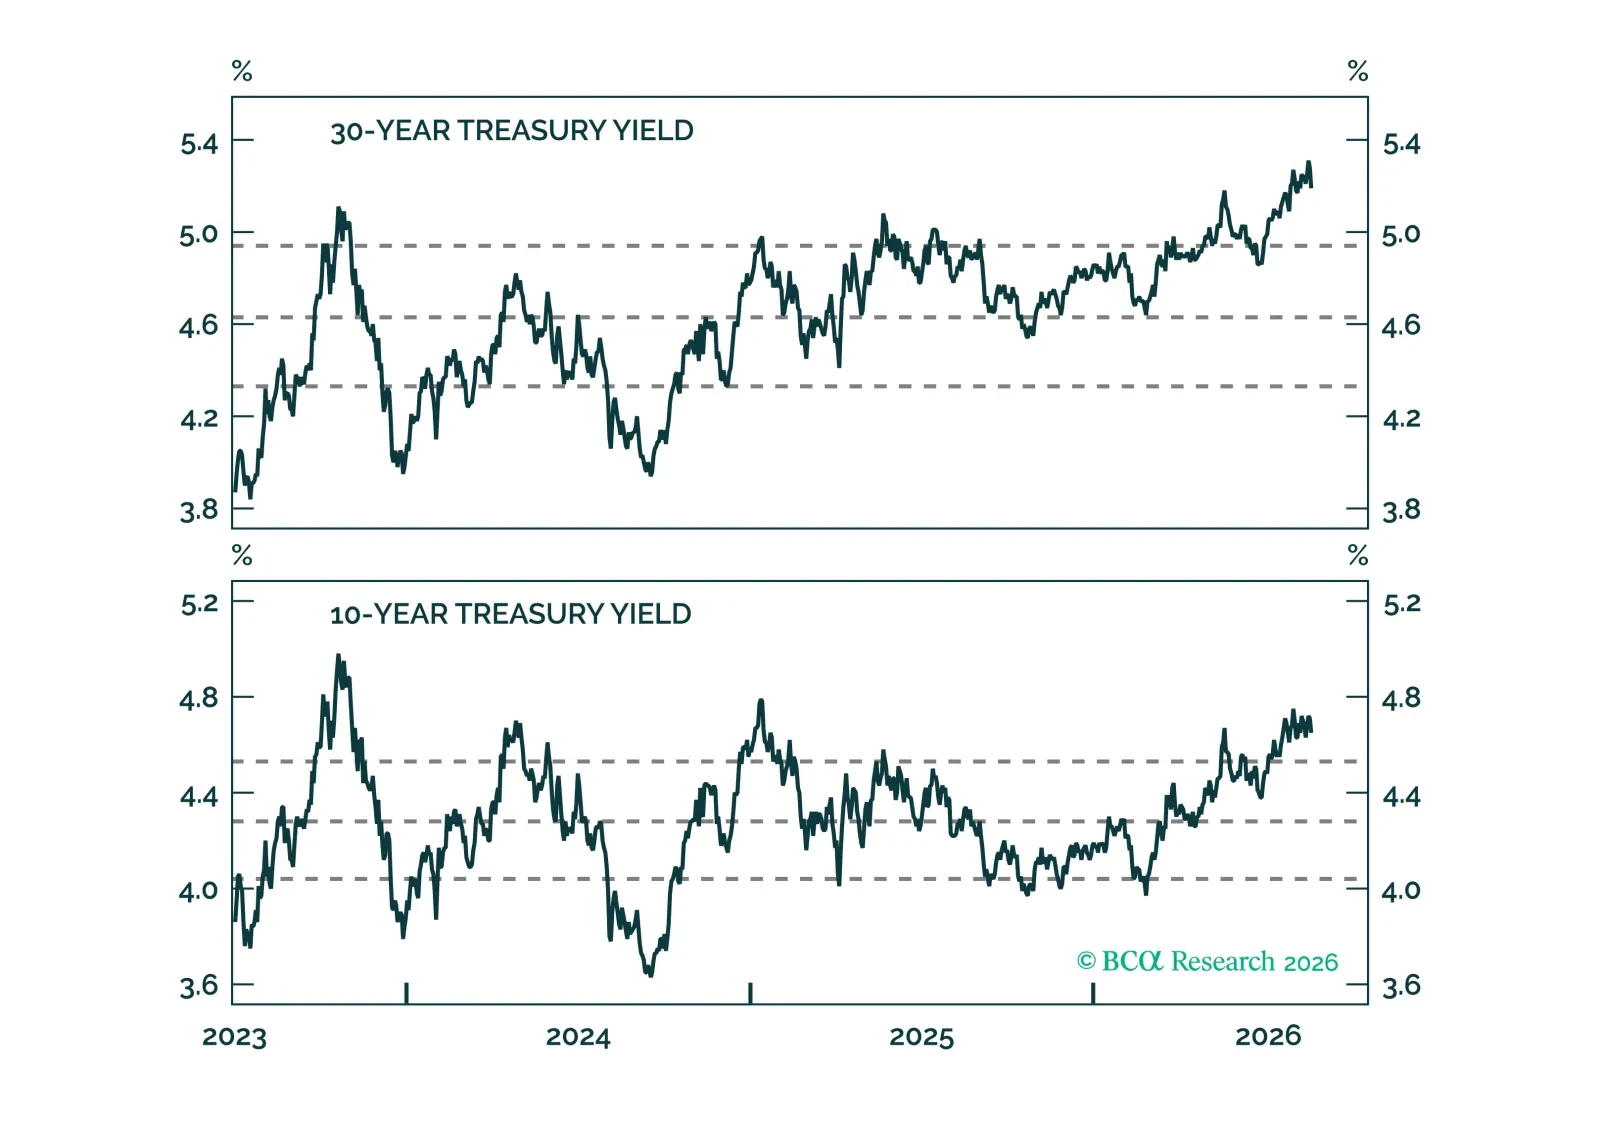
Despite recent increases, long-maturity Treasury yields are roughly consistent with fundamental fair value. We see limited value in long duration plays.