Sectors
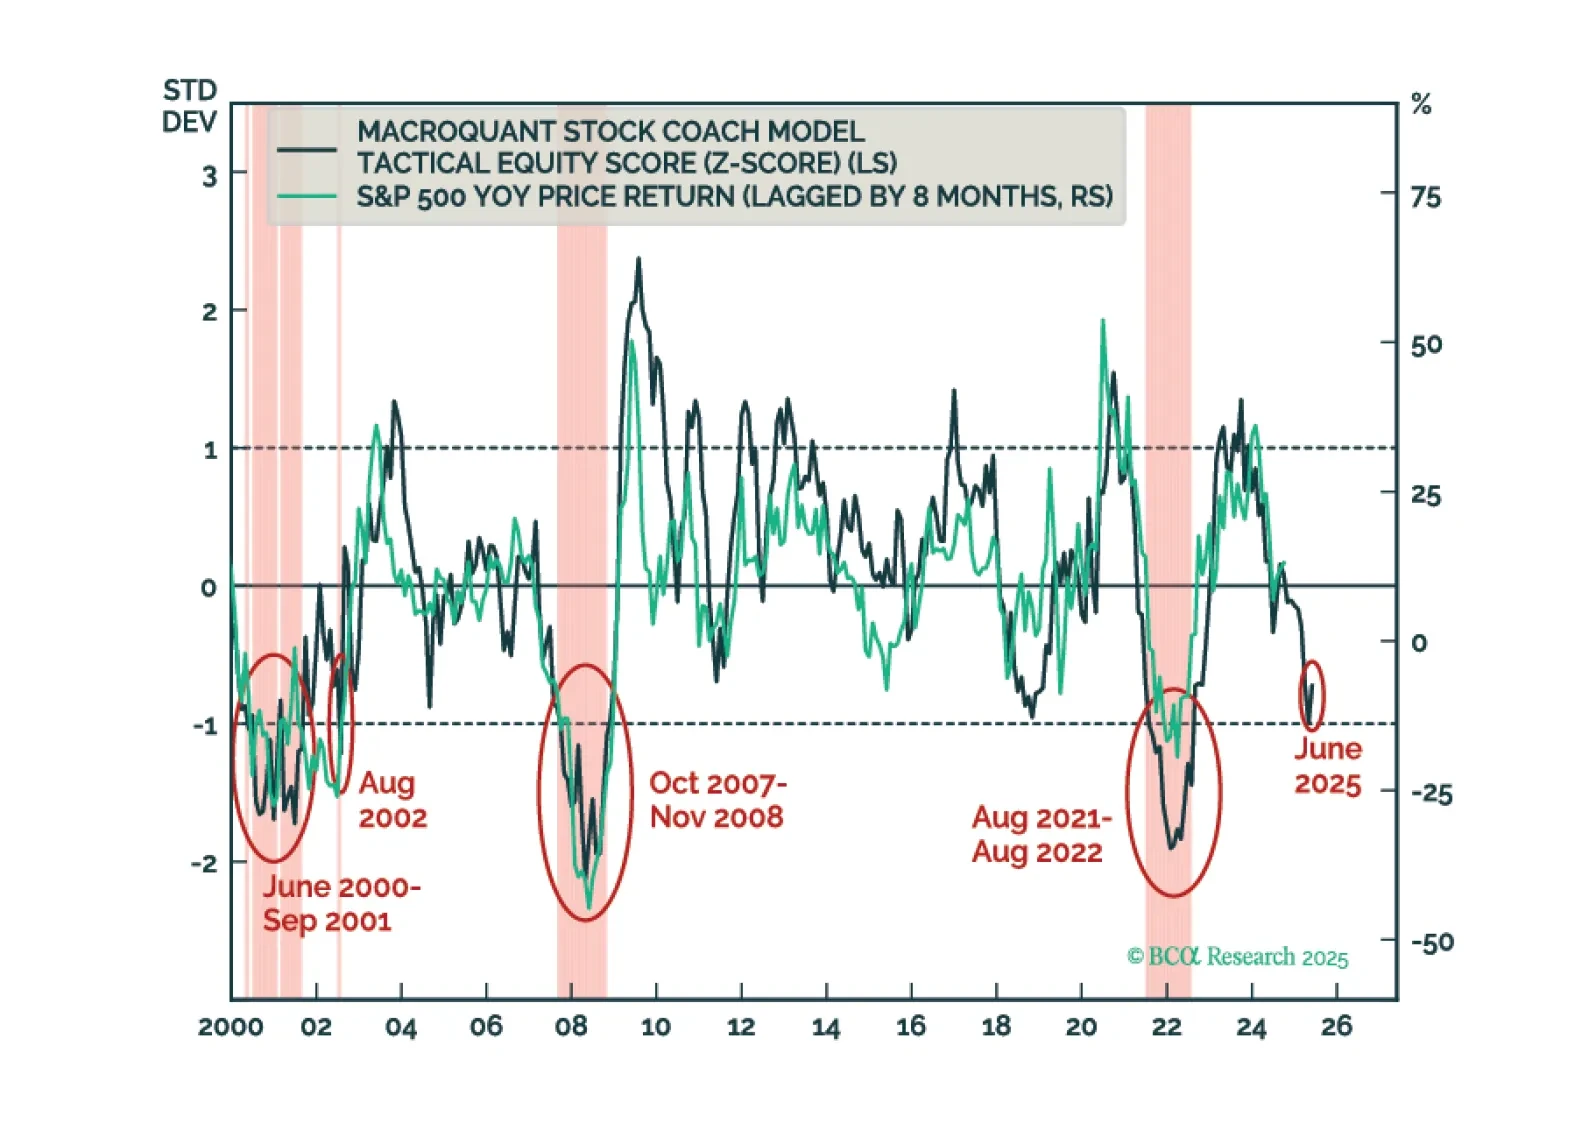
MacroQuantの米国株式zスコアは危険なほど-1の閾値に近づいています。この閾値を下回る動きは、過去に株式の弱気市場と確実に一致してきました。そのため、MacroQuantは株式をアンダーウェイトにし、債券と現金をオーバーウェイトにすることを推奨します。
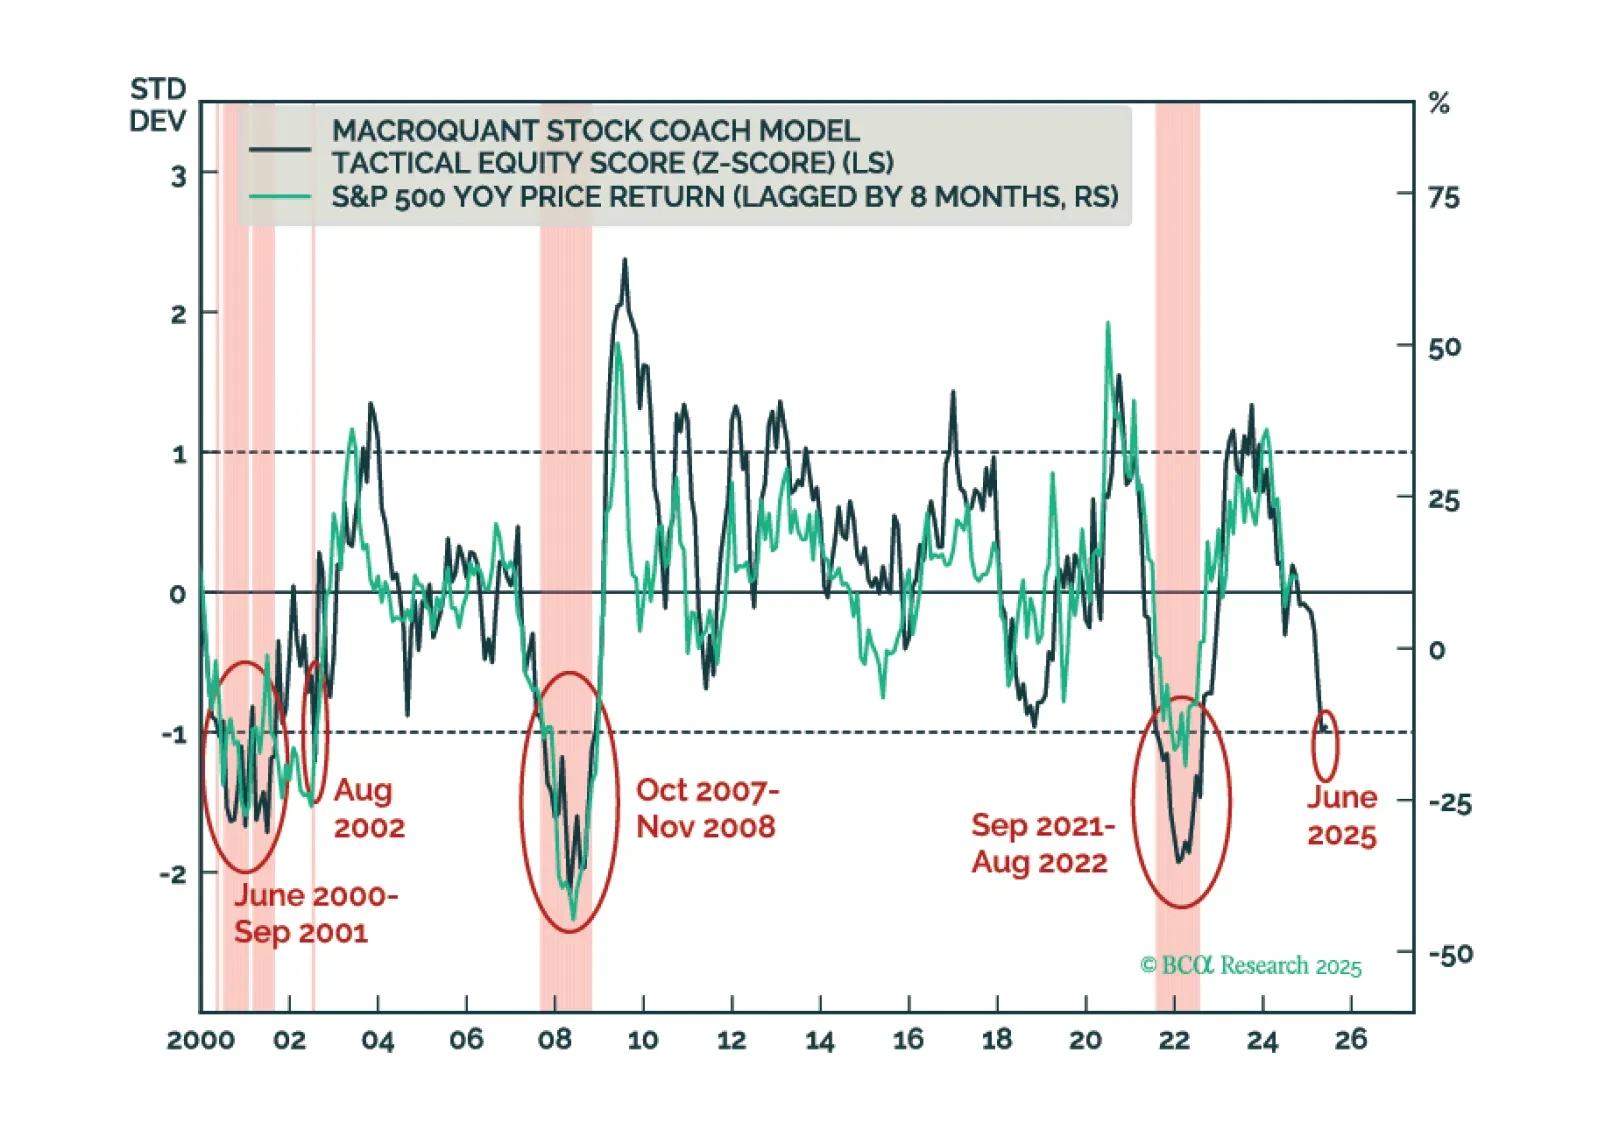
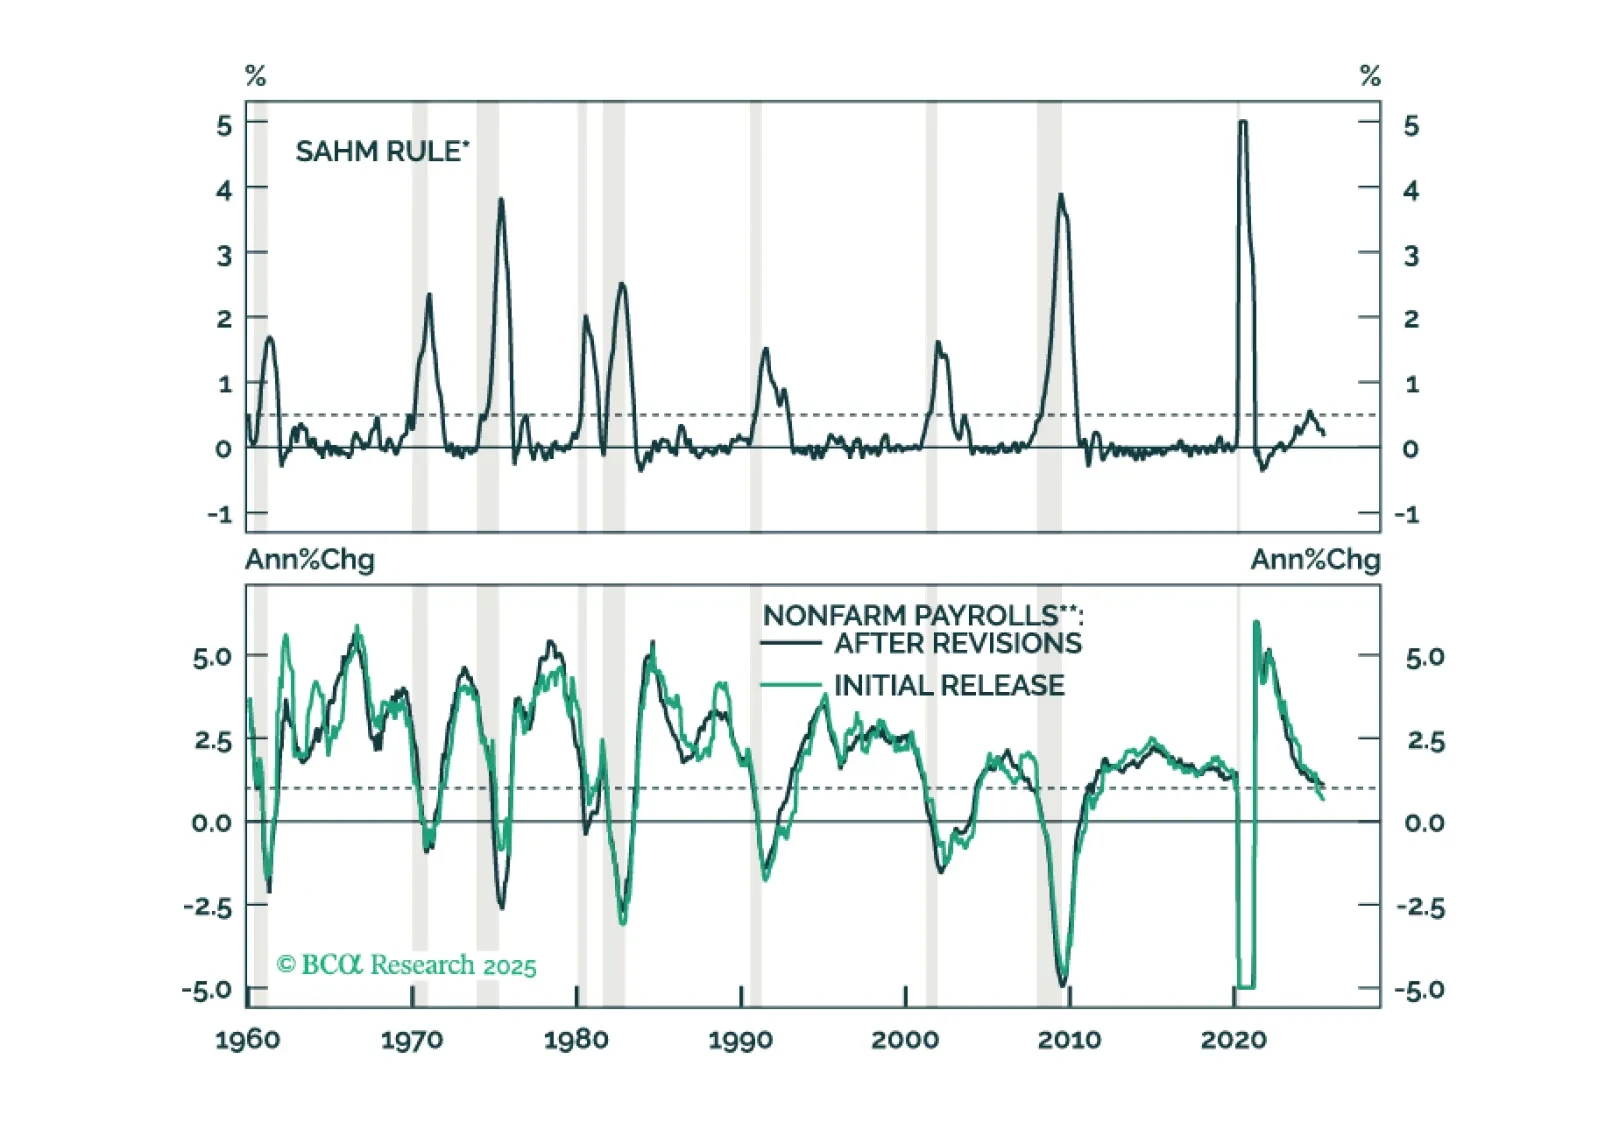
投資家はポートフォリオにおいて株式を控えめにアンダーウェイトにし、不況の具体的な兆しが見え次第、より積極的にディフェンシブな姿勢に転じるべきです。私たちはこれが数ヶ月以内に起こると考えています。
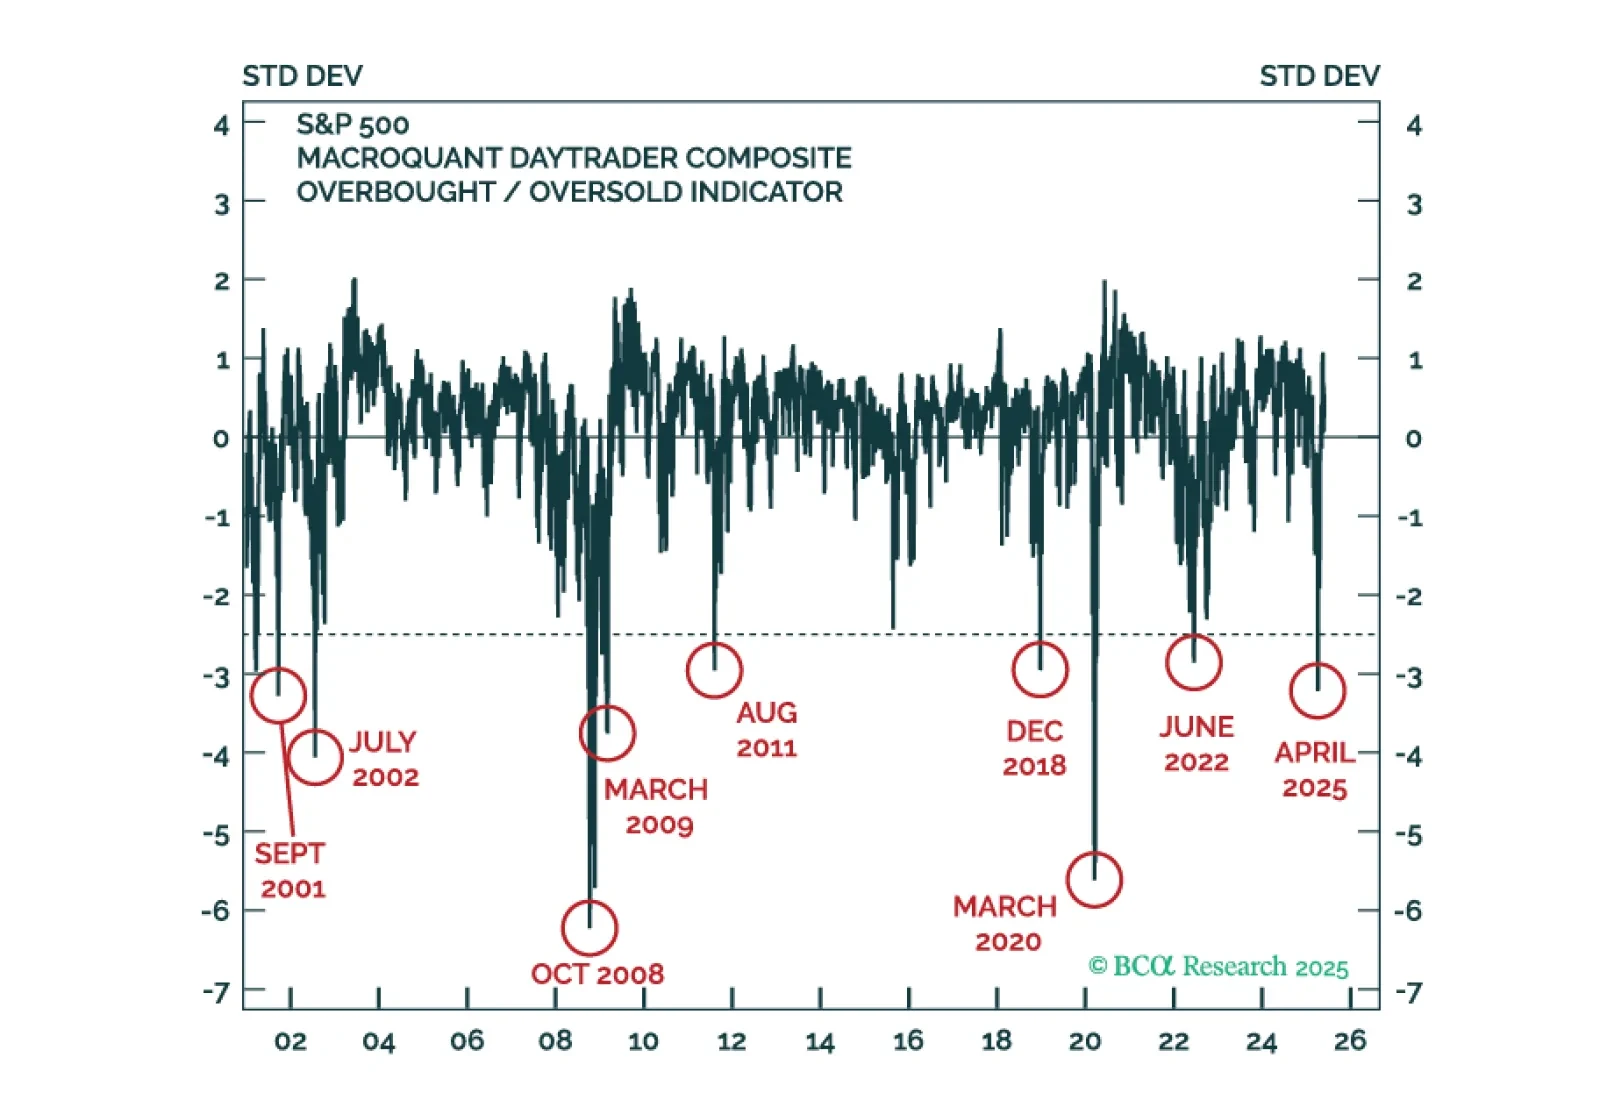
MacroQuant warns that US equities are pricing in very little economic risk. The model is shunning equities and recommends a large overweight to cash.

Right now, the major stock and bond markets are more ‘anti-fragile’ than fragile, and the Joshi rule recession indicators signal that a US recession is not imminent. This justifies a neutral, or default, tactical weighting to both stocks and bonds until a major market does become fragile, or until recession risk elevates. The one major price trend that is fragile is the 65-day selloff in the US dollar, which justifies a tactical overweighting to the dollar.
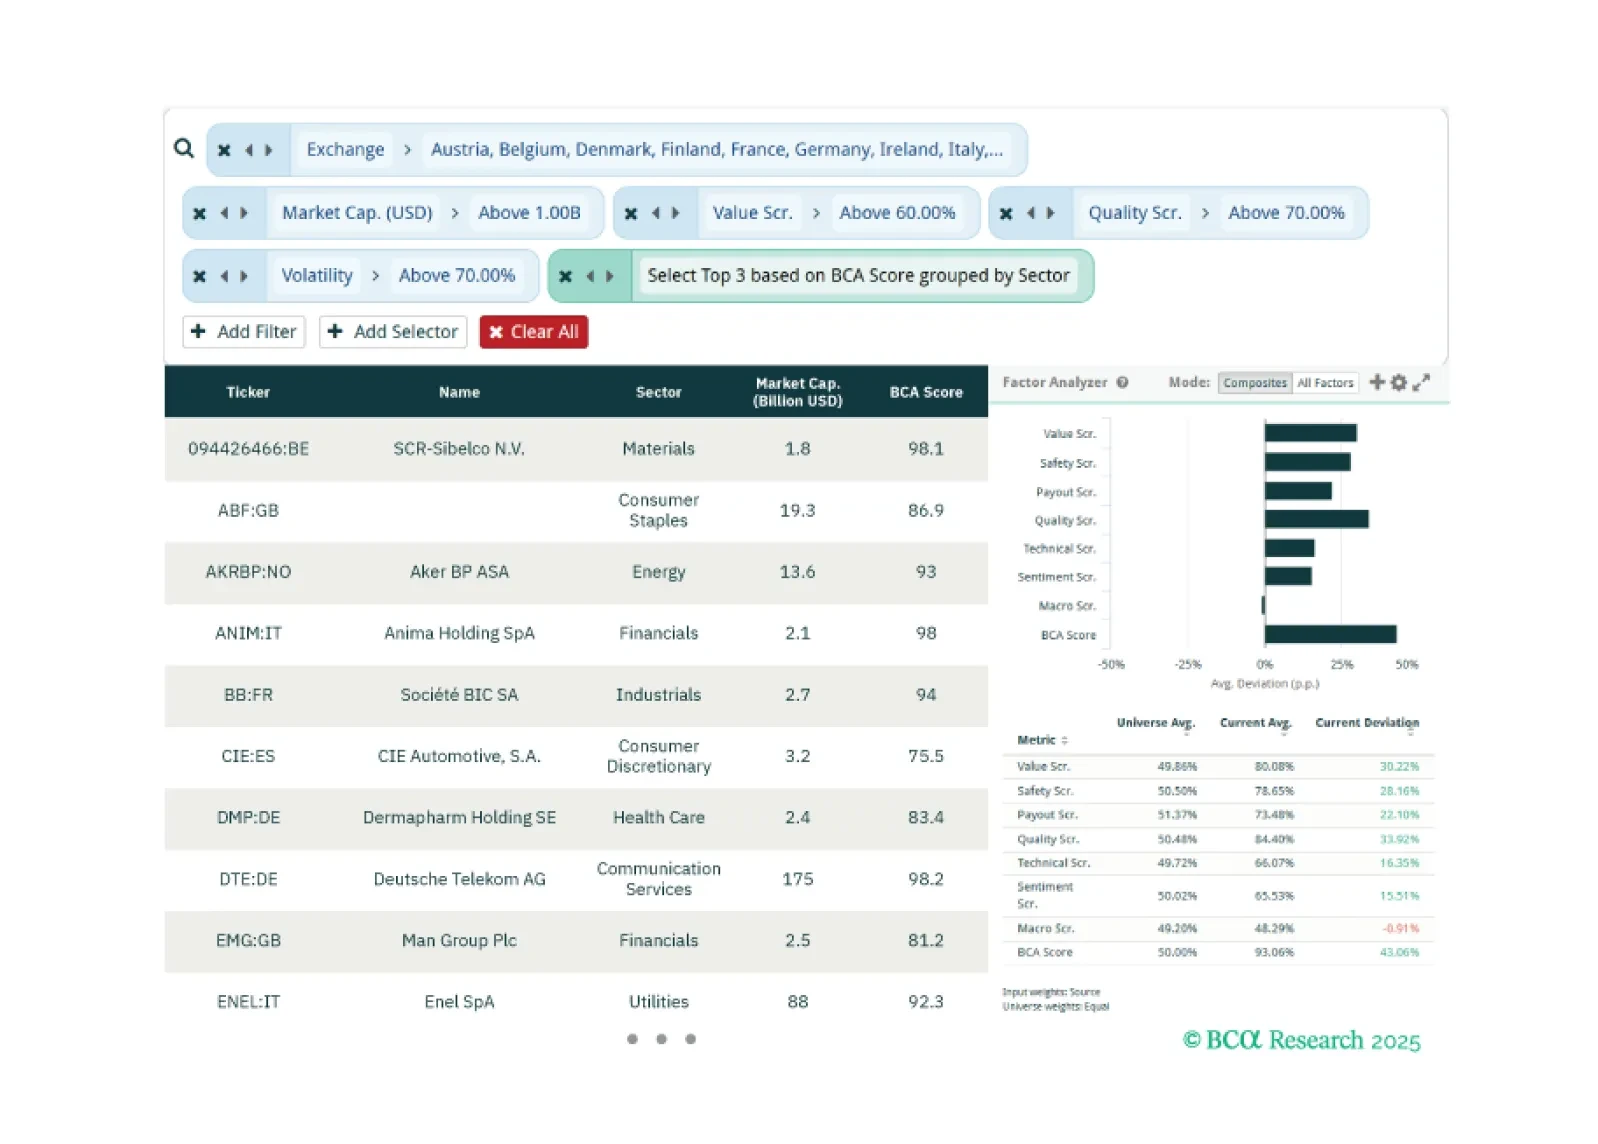
This week, our three screeners cover: Favoring European equities over US equities, cybersecurity stocks, and large caps with large moves in their BCA Score.
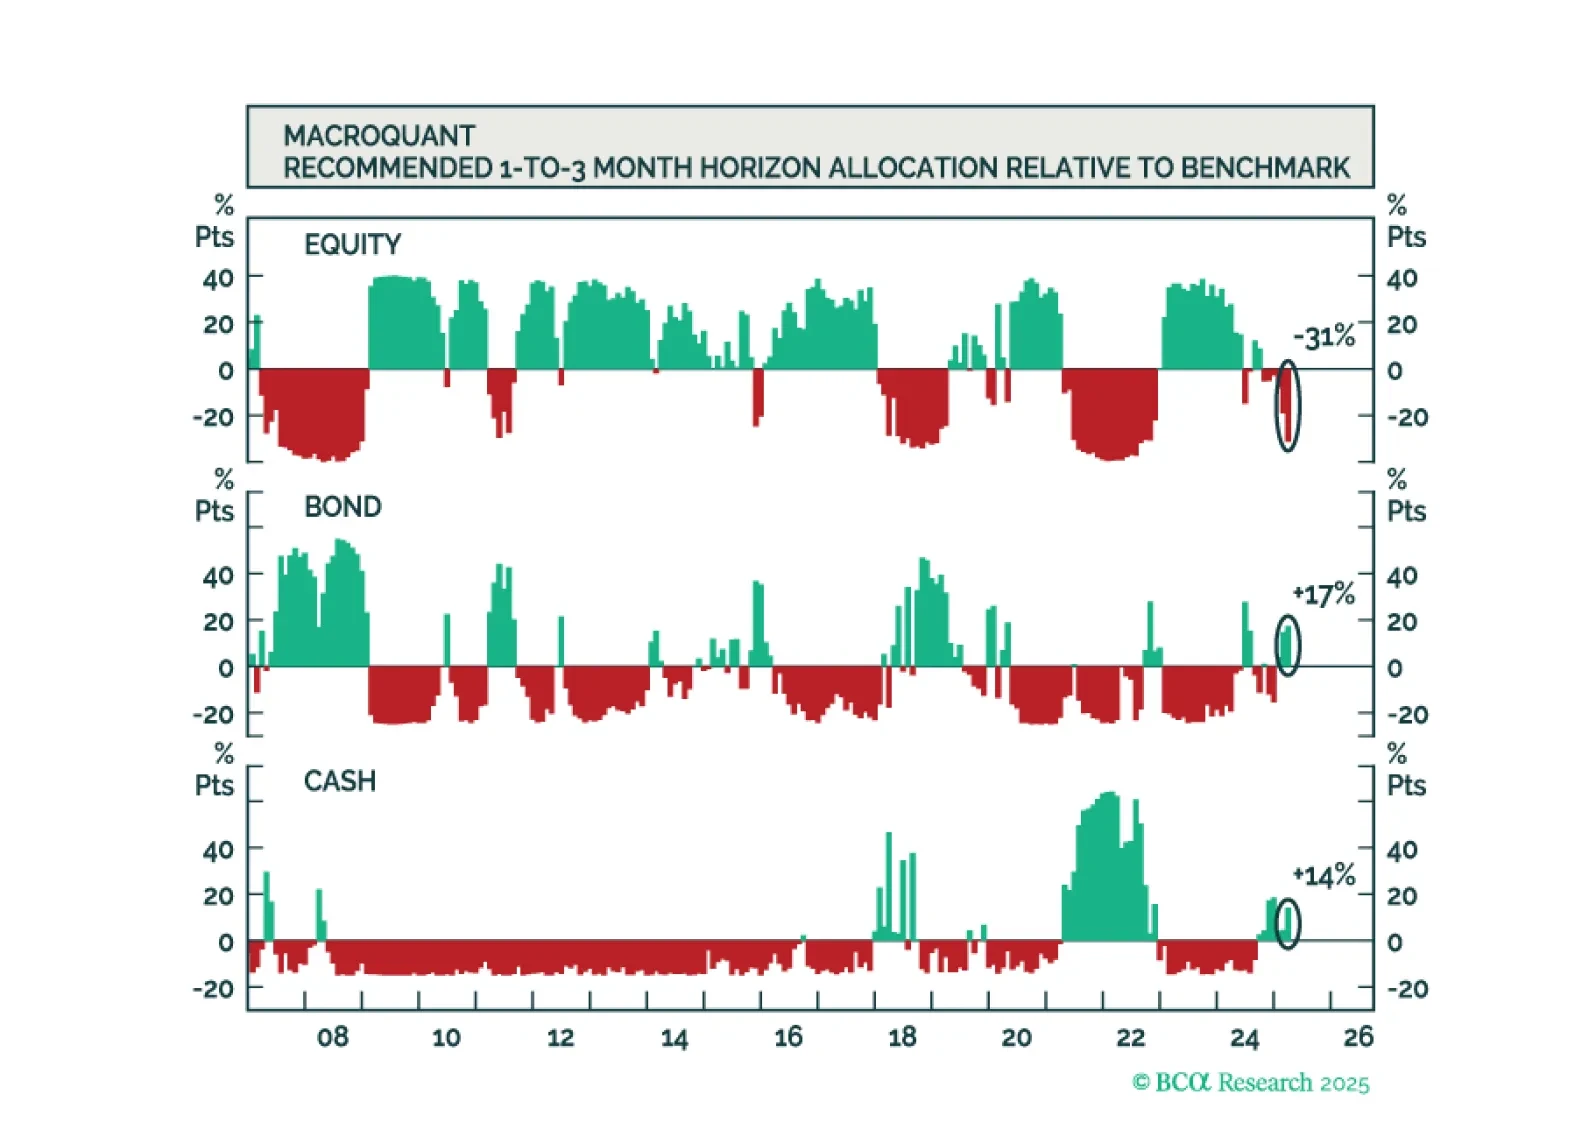
MacroQuant sees the risks to US growth as being to the downside and the risks to inflation as being to the upside. Such a stagflationary brew justifies an underweight on stocks.
MacroQuant sees the risks to US growth as being to the downside and the risks to inflation as being to the upside. Such a stagflationary brew justifies an underweight on stocks.