金融
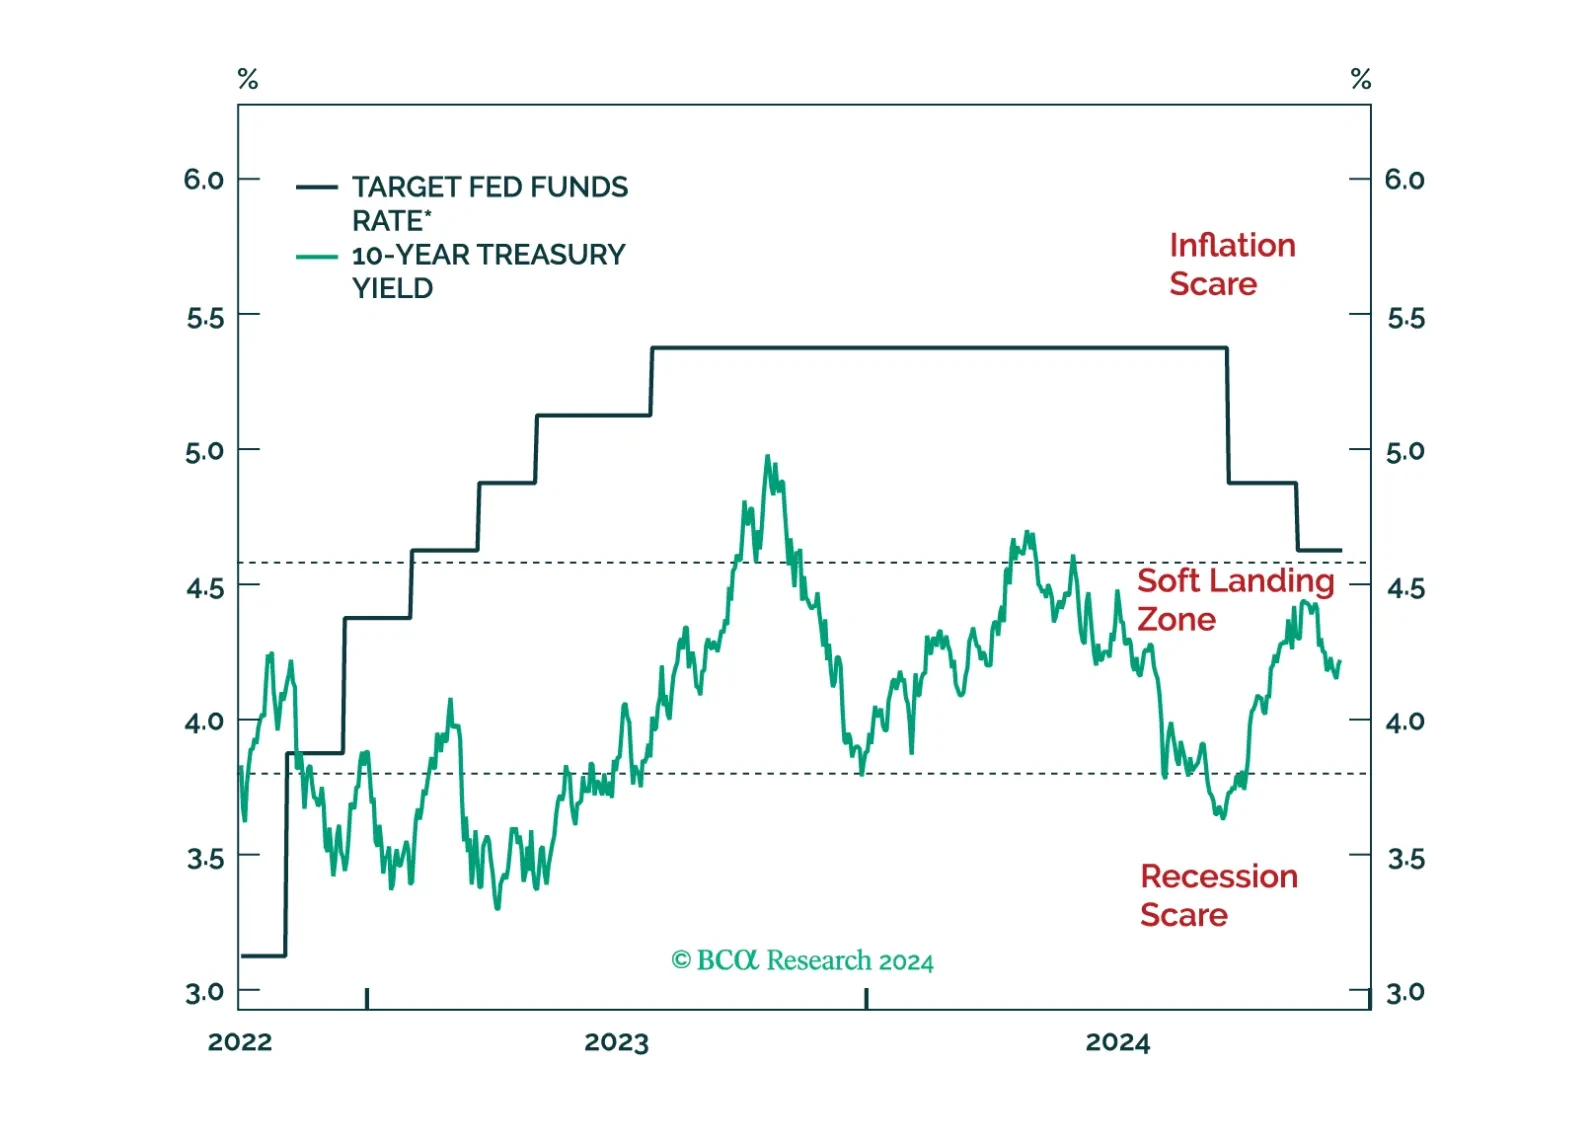
We offer 5 key investment views for US fixed income markets in 2025.
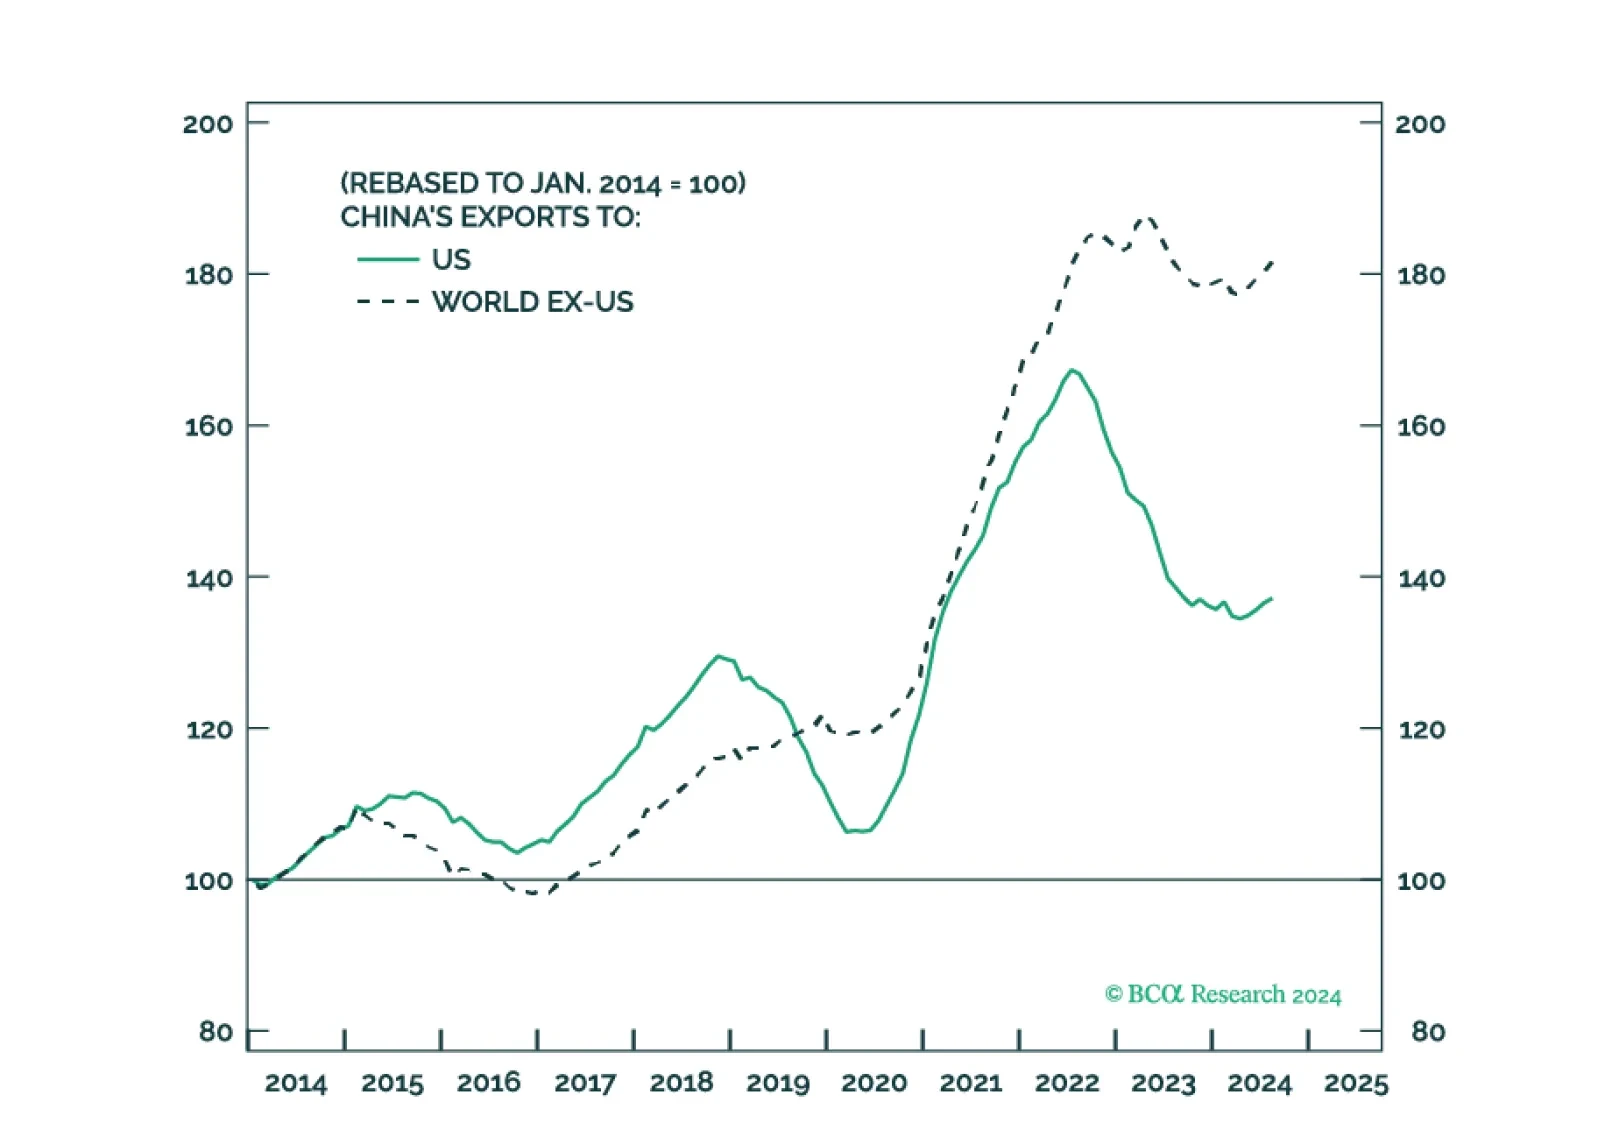
- Congress will pass tax cuts by end of 2025 producing a fiscal thrust of about 0.9% of GDP in 2026.
- Trump will count on that stimulus as a basis for slapping tariffs on leading trade partners.
- China will retaliate against Trump and stimulate its domestic economy, while pursuing stronger trade ties with other countries. Europe will also retaliate.
- Geopolitical risk will shift from Ukraine-Russia to Israel-Iran, where the conflict will continue to escalate until a crisis point is reached within 2025.
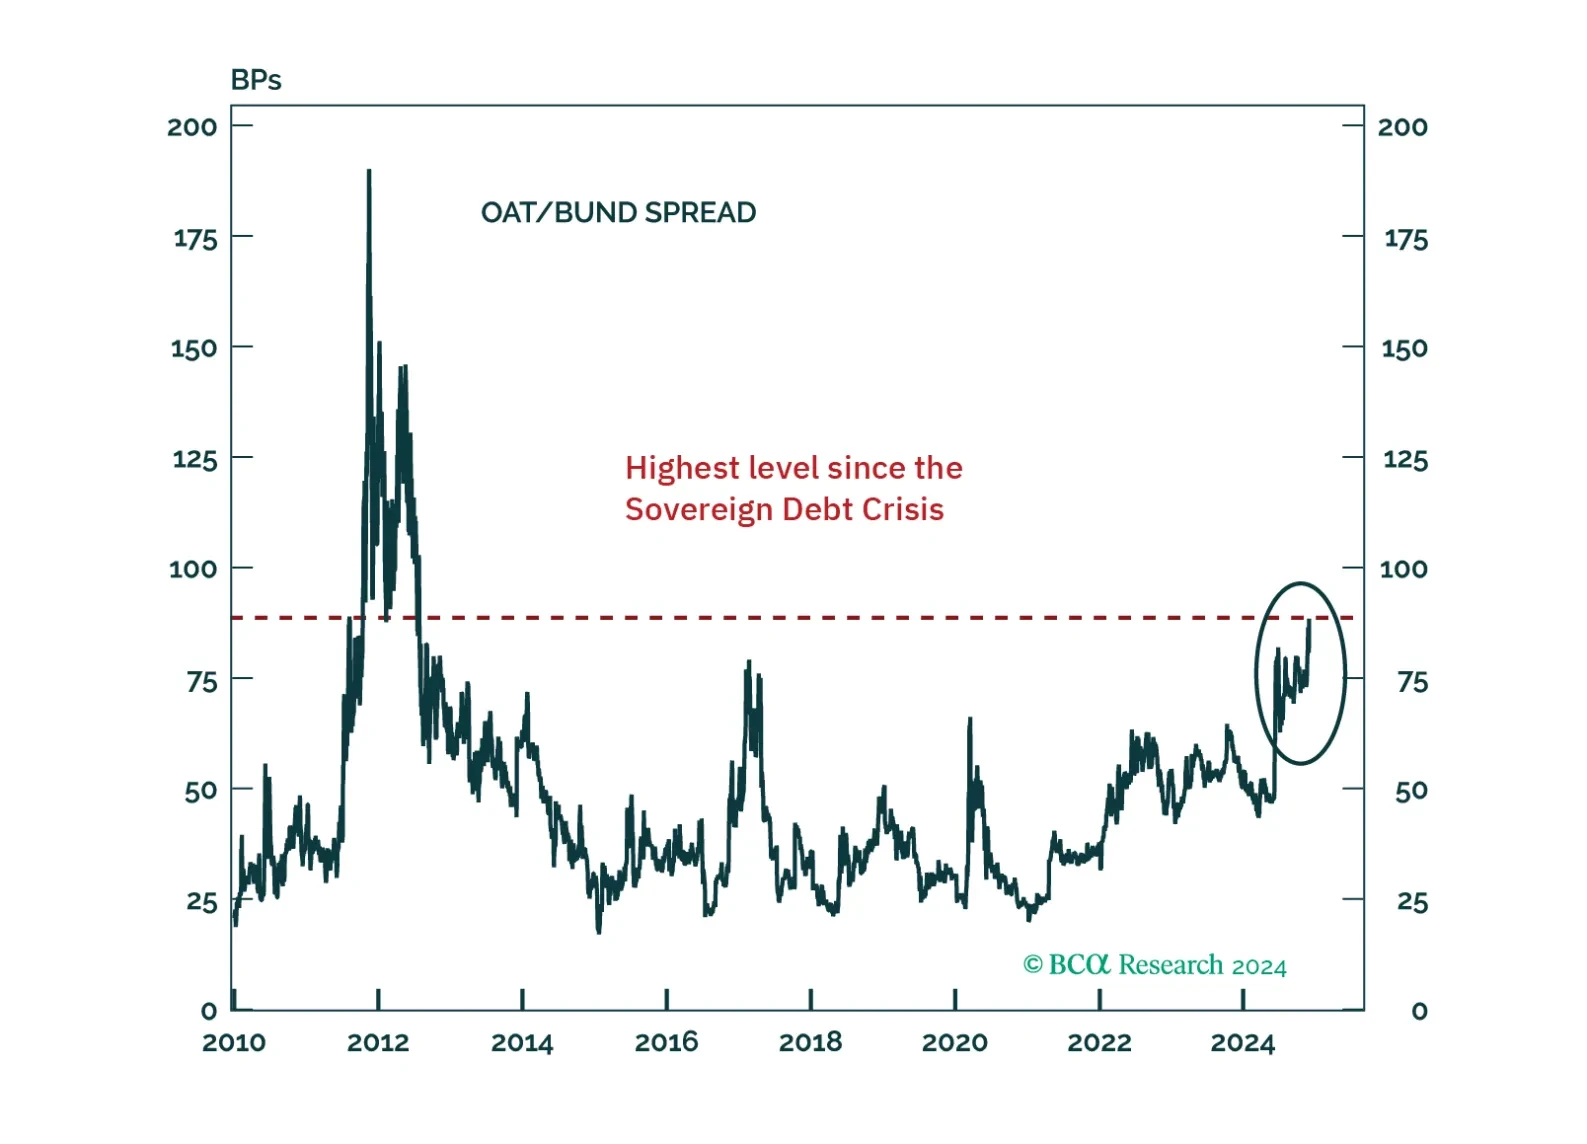
France finds itself in a unique, thorny situation. Can it heave itself out of it? And what does it mean for investors?
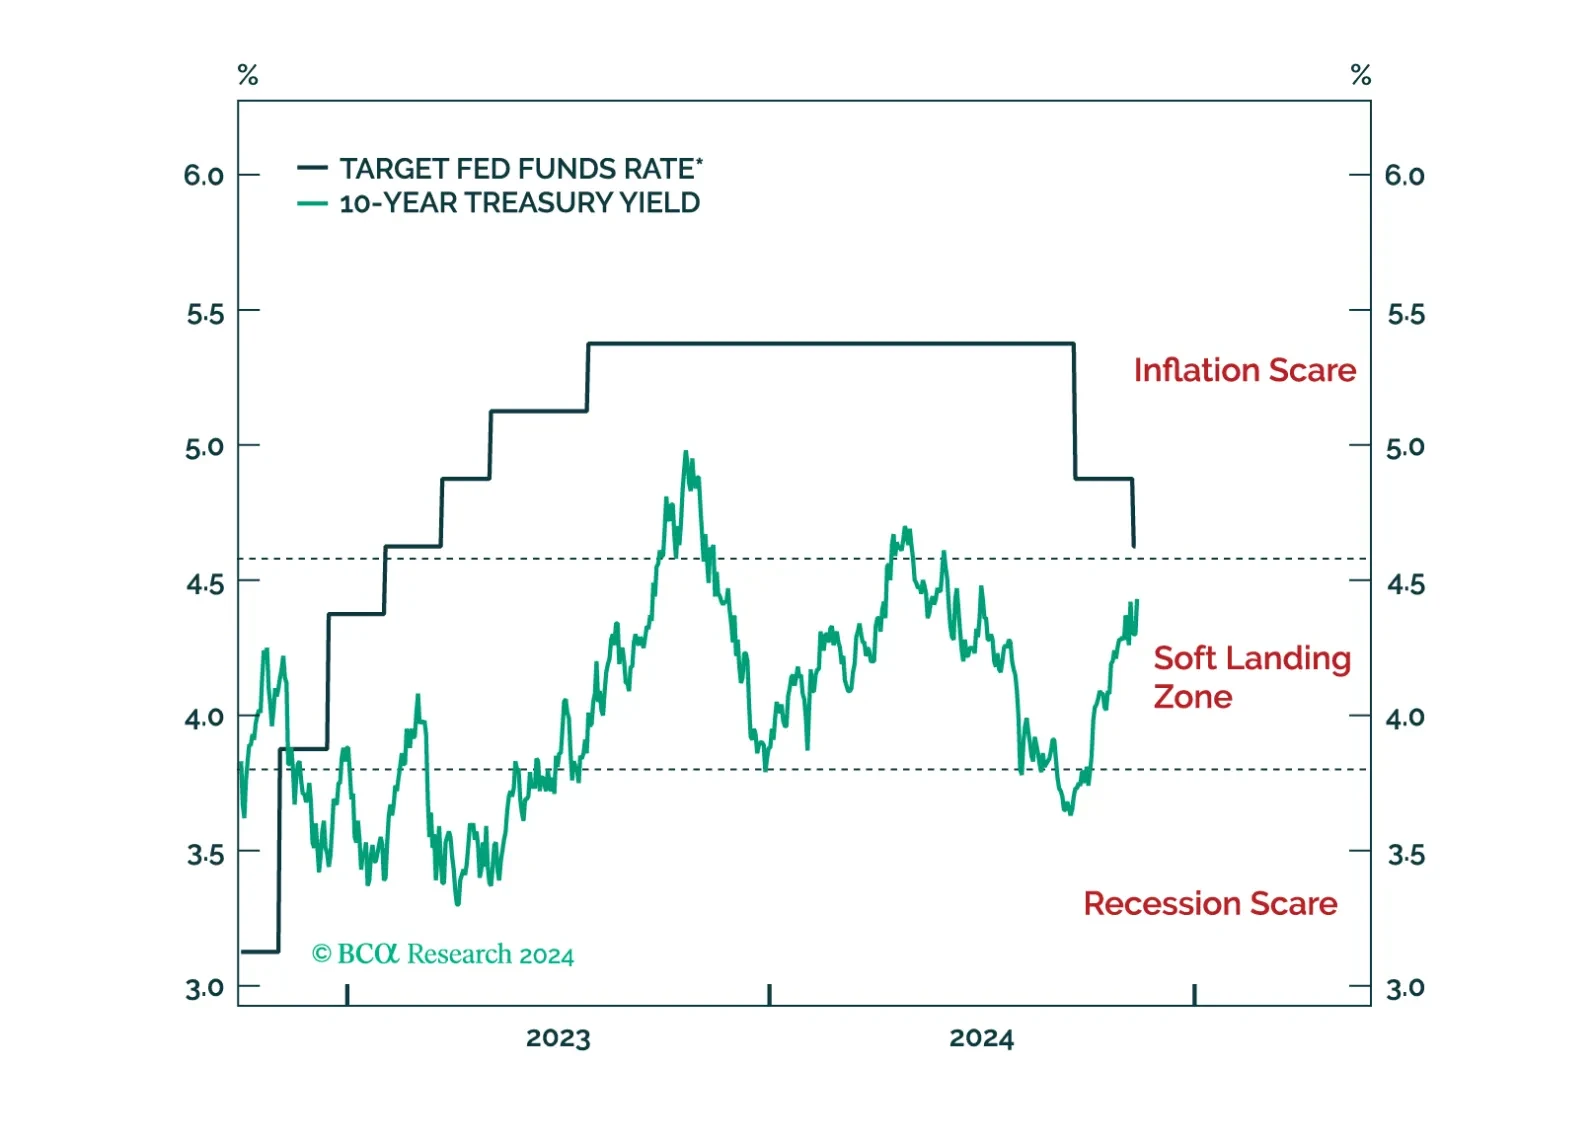

今週、当社のセントラル・バンク・モニターズ(CBMs)を更新しました。これらは先進国経済における金融政策をどのように調整すべきかを見極めるのに役立ちます。結論としては、全体としてより緩和的な金融政策が求められるものの、G10諸国間のシグナルの乖離から生じるいくつかのトレード・アイデアがあります。
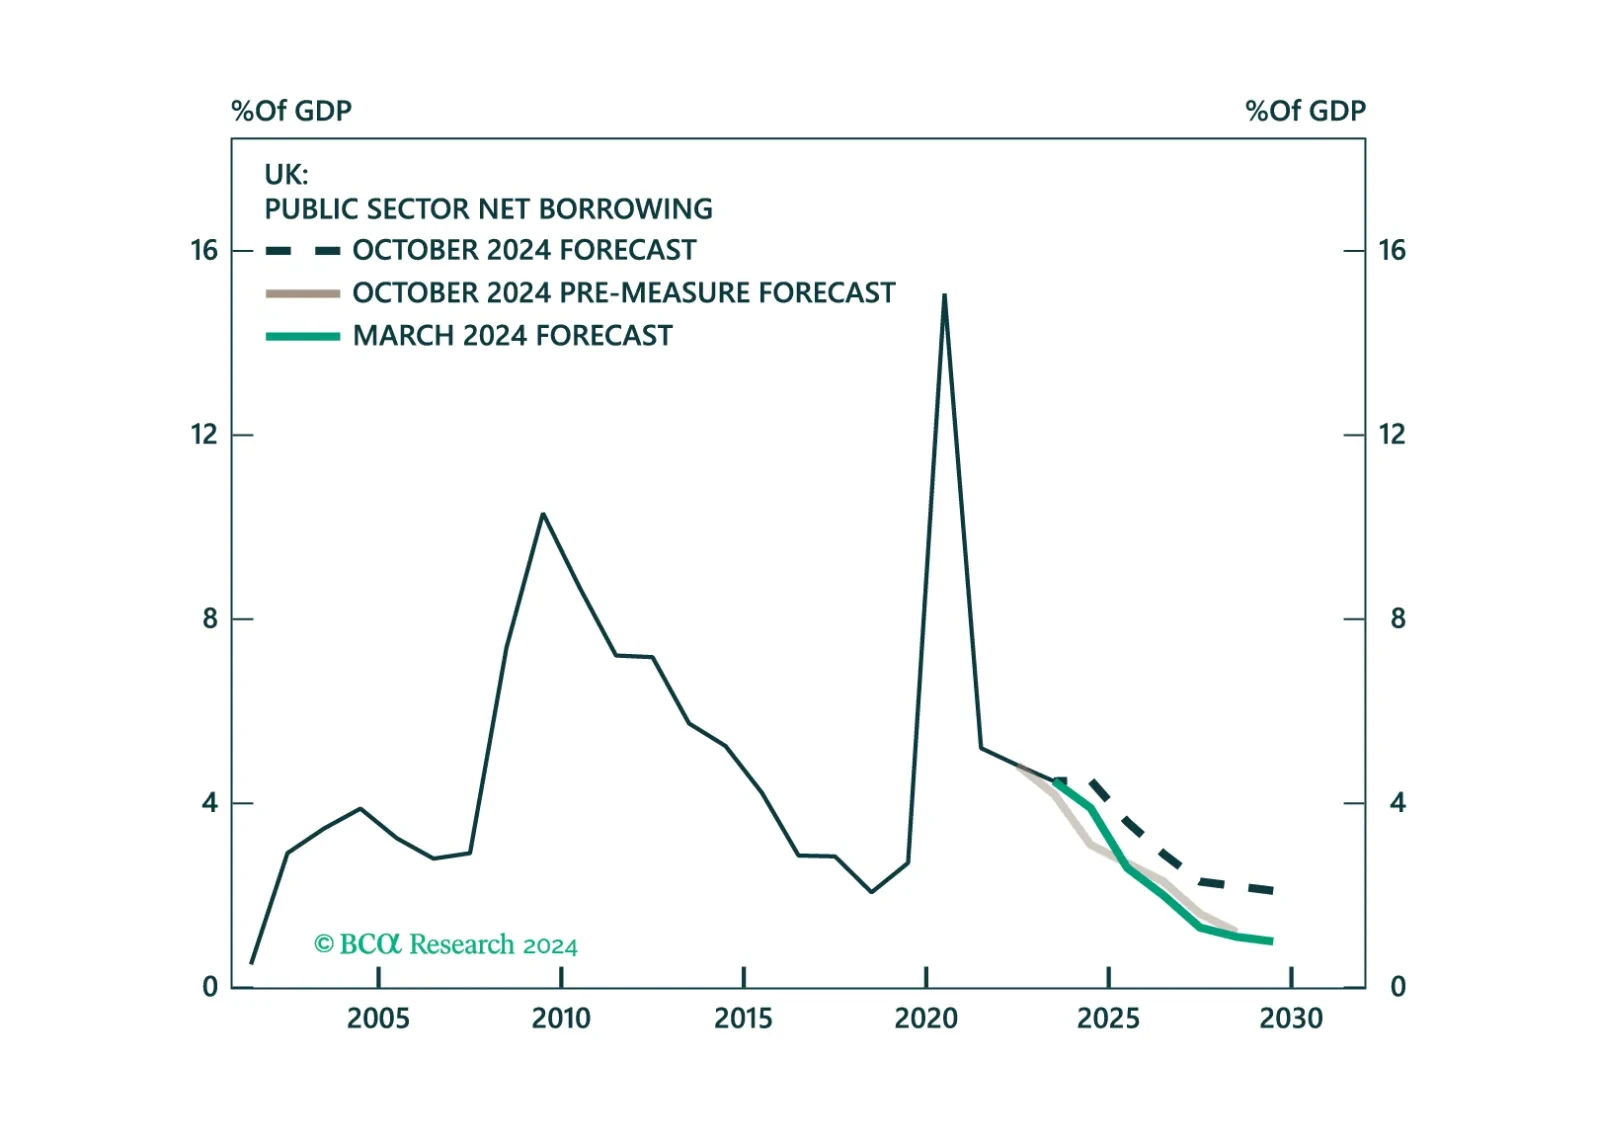
本ストラテジー・インサイトは、イングランド銀行の本日の利下げおよび先週英国政府が発表した予算案に関する当社の見解を示します。
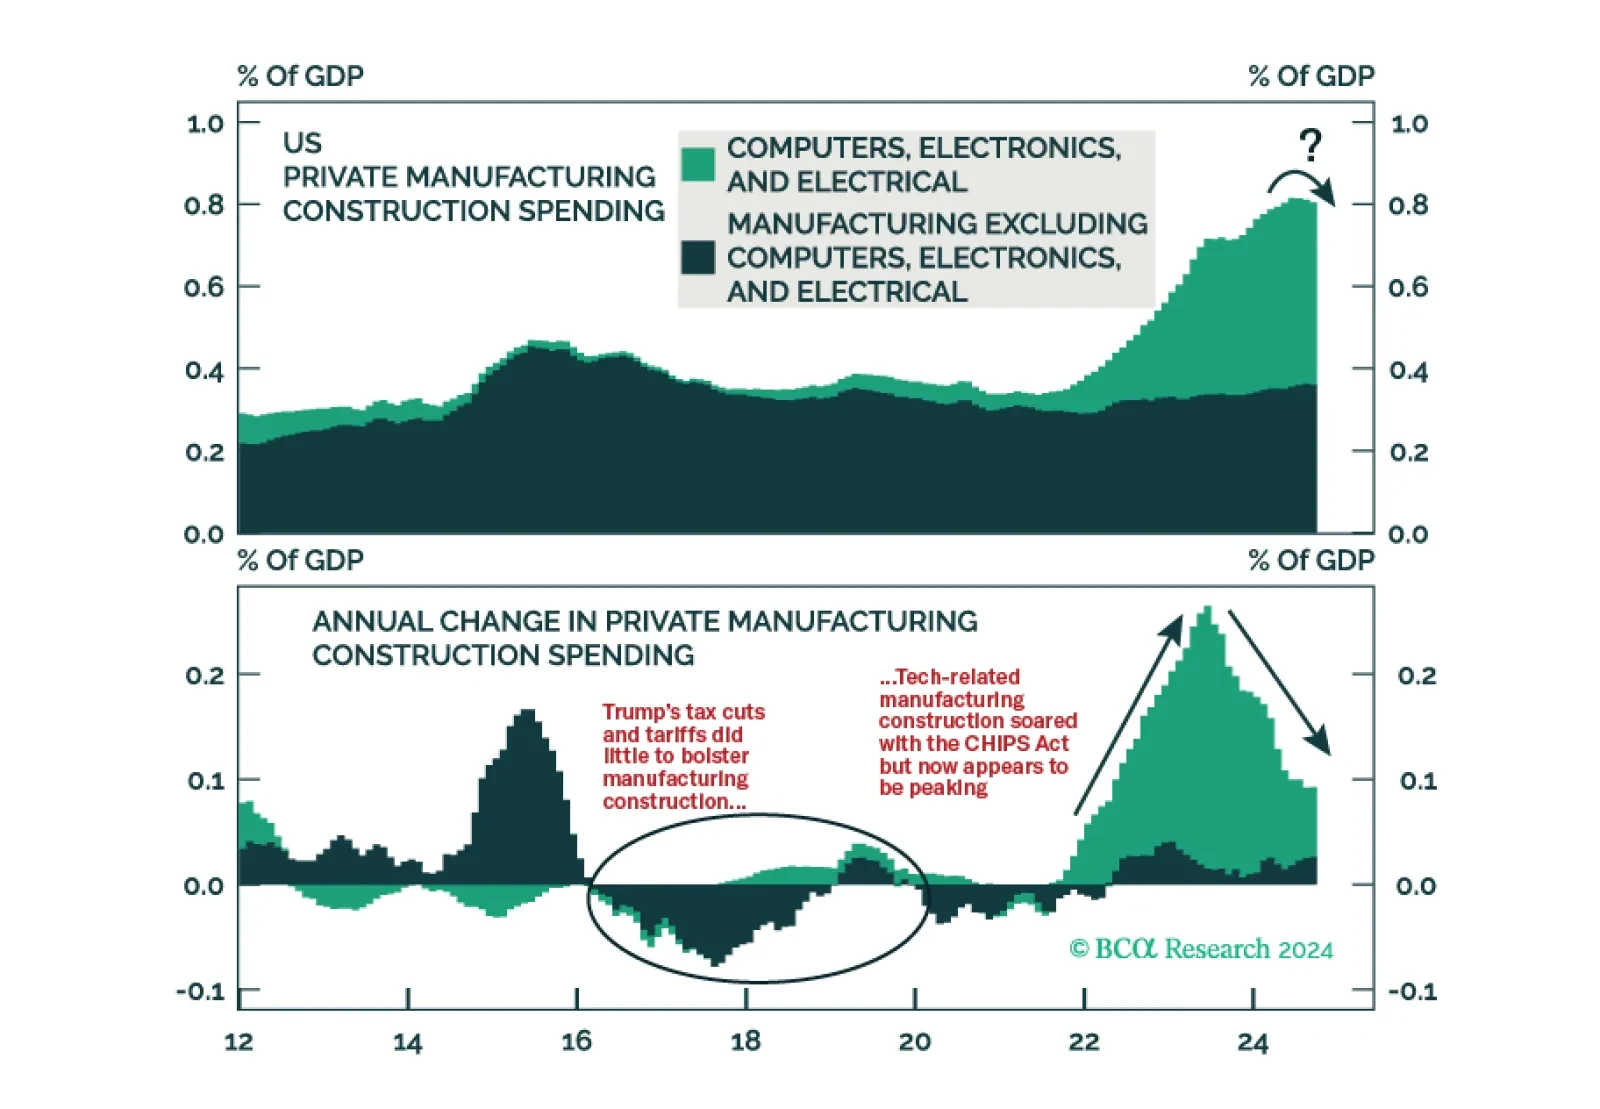
新たな貿易戦争の見通しは、トランプの政策の他の親企業的な側面の効果をそれ以上に相殺します。選挙に向けて労働市場がすでに弱まっていることから、当社は今後12か月の米国景気後退確率を65%から75%に引き上げます。

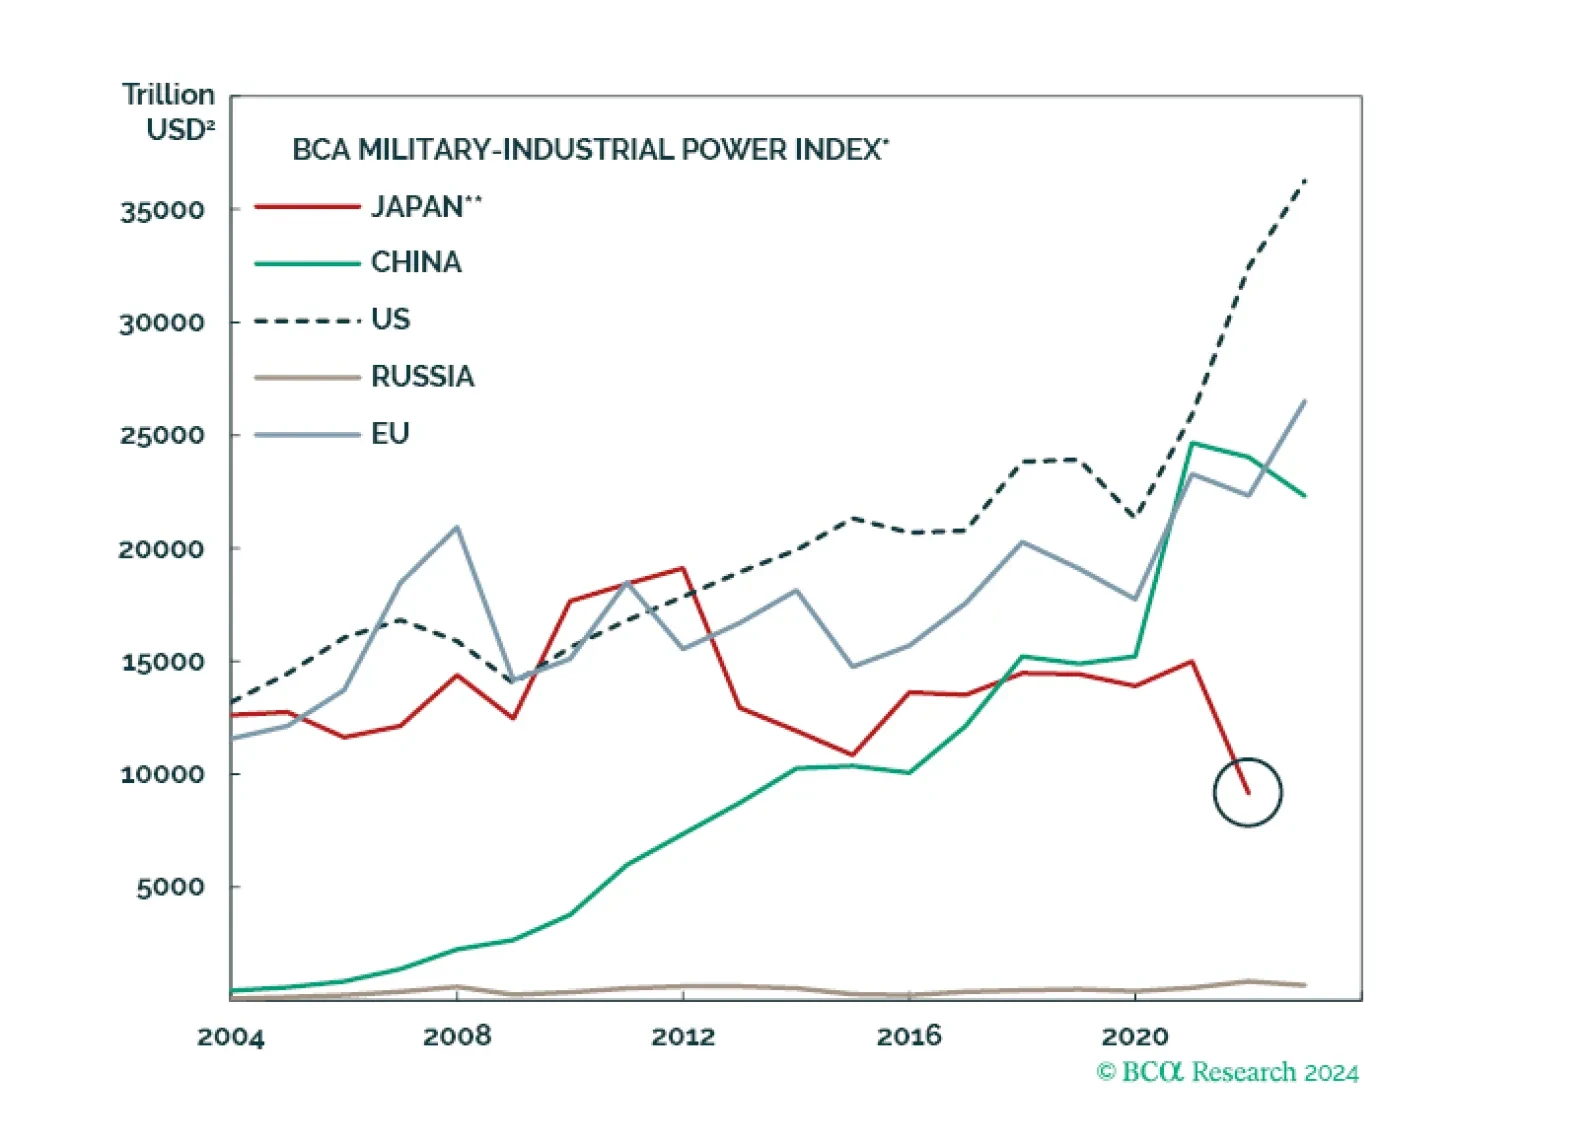
今後数か月で、日本の新政権は財政政策を緩和し、それが国内需要をわずかに押し上げるだろう。短期的には金融政策がさらに引き締まる可能性があるが、長期的にはそれほど強くはならない。地政学的環境が日本を緩和的な経済政策へと向かわせる。

The October US jobs report had mixed signals and was skewed by hurricanes and industrial strikes. Unemployment met expectations by staying unchanged at 4.1%, although it rose nearly 0.1 percentage point on an unrounded basis. Nonfarm payrolls were flat with…