メインコンテンツにスキップ
メインコンテンツにスキップ

市場収益

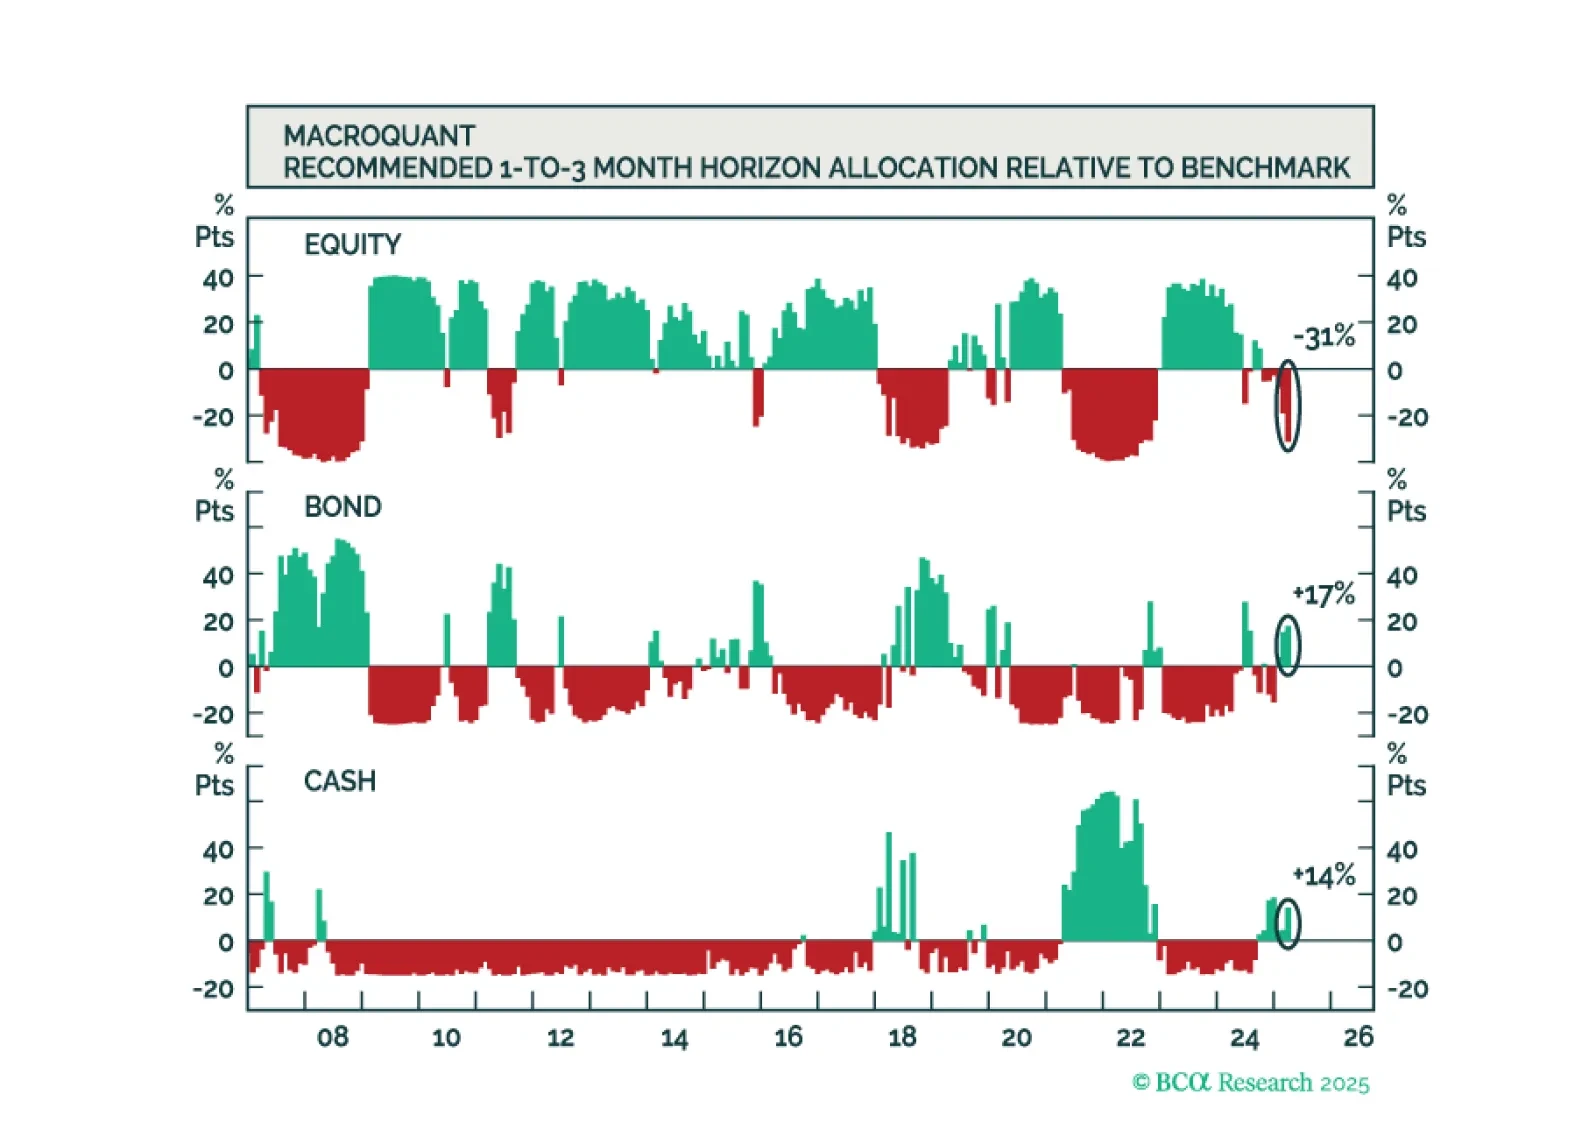
MacroQuant sees the risks to US growth as being to the downside and the risks to inflation as being to the upside. Such a stagflationary brew justifies an underweight on stocks.
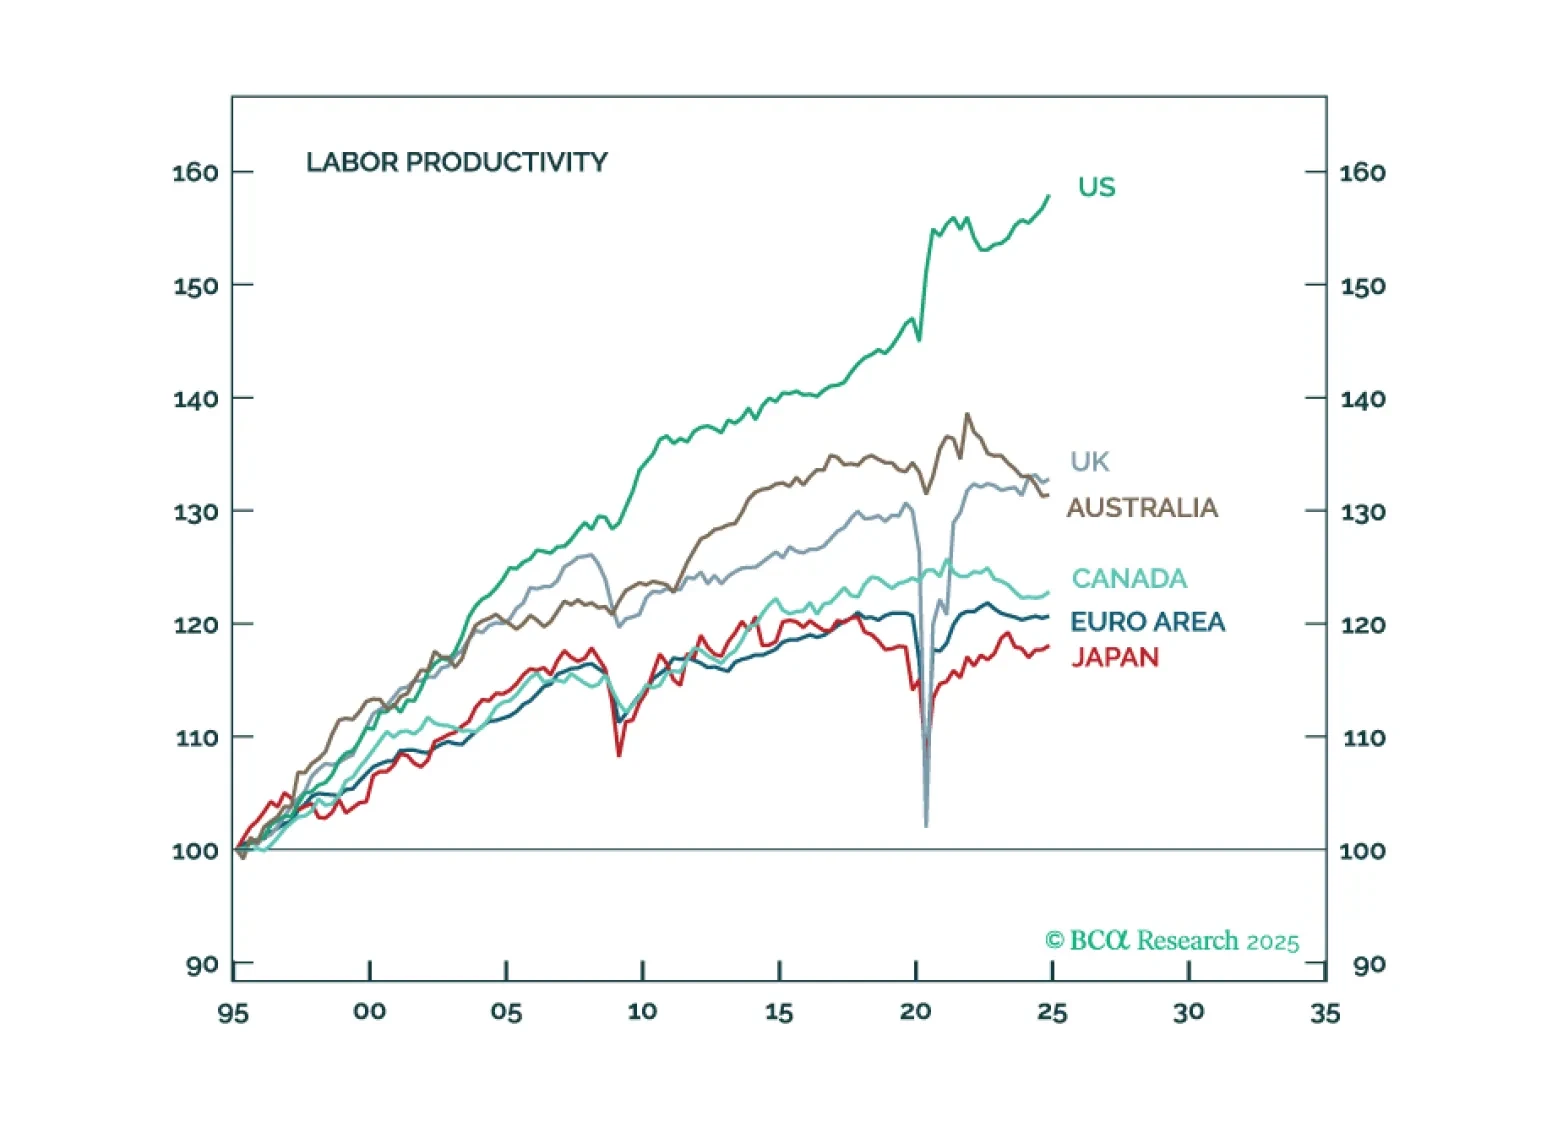
Although the sell-off in the US dollar and relative outperformance of non-US stocks will pause over the coming months as a global recession begins, the fading of US exceptionalism will still cause the dollar to weaken and US stocks to underperform over a multi-year horizon.
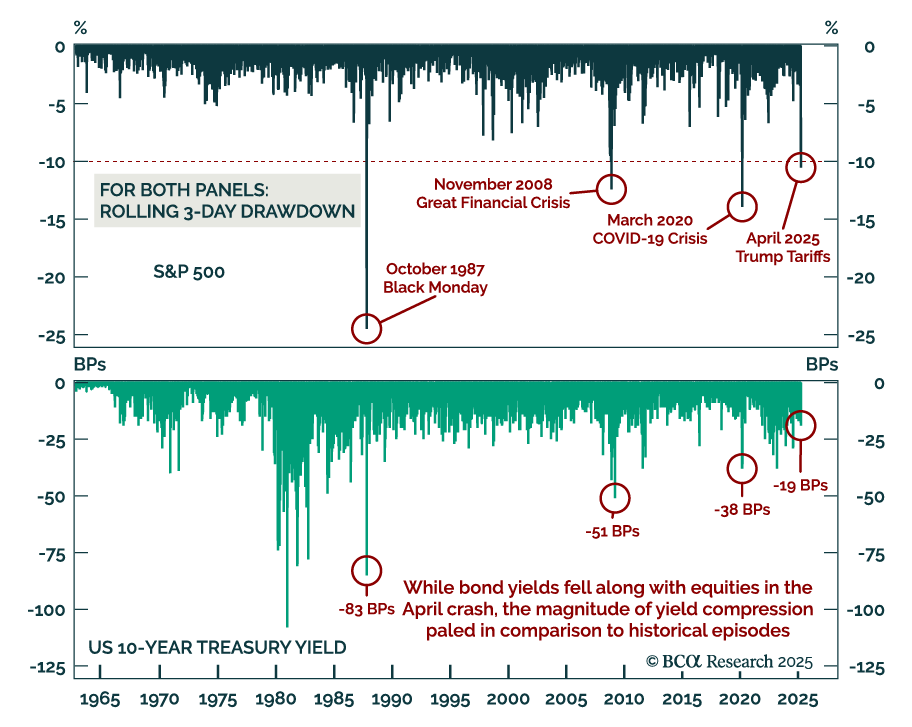
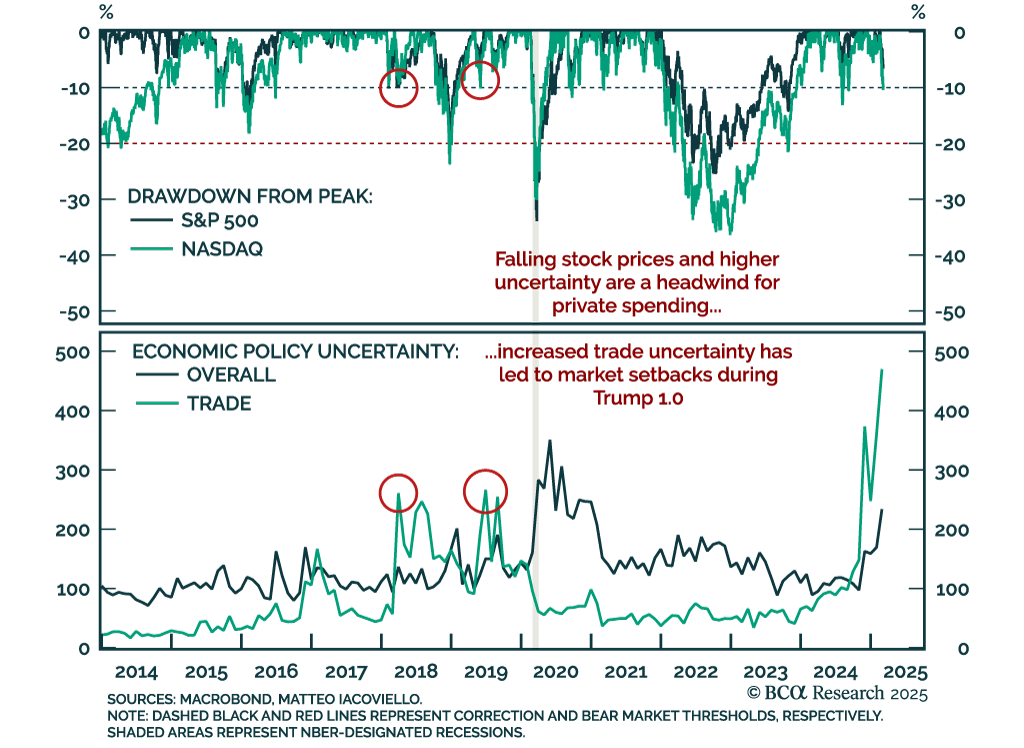
Equities’ post-Liberation Day selloff was historic, but cross-asset signals make it an anomaly. The post-Liberation Day S&P 500’s three-day, 10%+ drawdown joined a list of major episodes that includes the March 2020 COVID-19 crash, the 2008 financial crisis,…

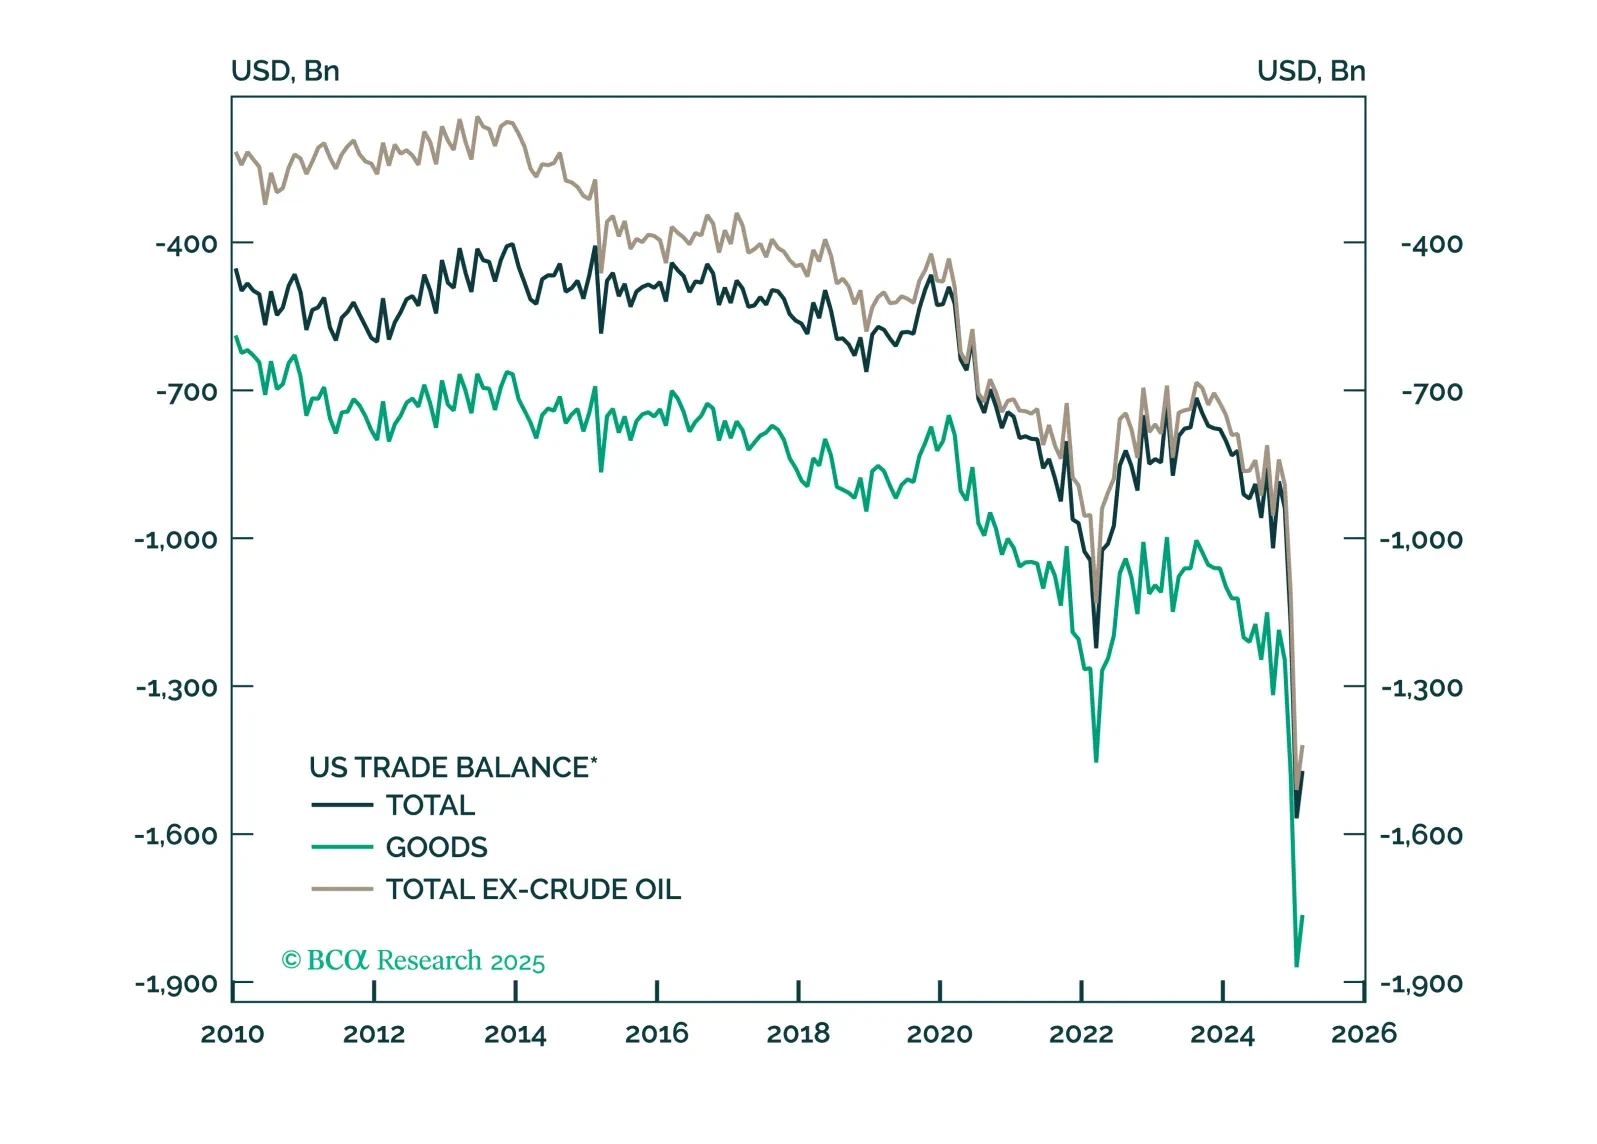
This report looks at the FX implications of the Trump tariffs, and the review of our Q1 trades.
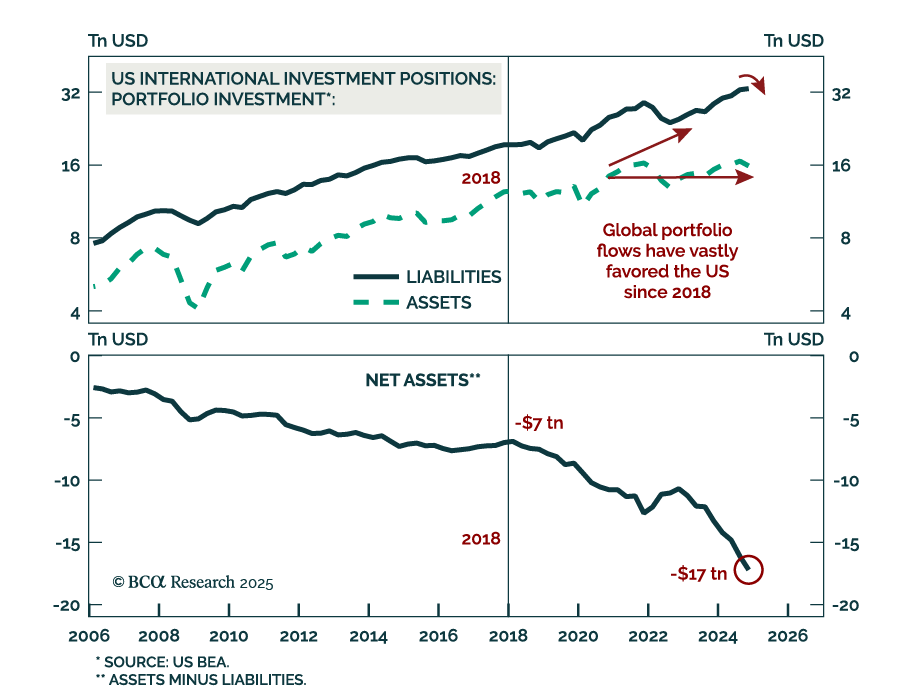
Our Emerging Markets strategists recommend staying defensive and adding exposure to EM local currency bonds, which will benefit from US dollar depreciation over the medium and long term. While tariffs are deflationary for US trading partners and will drive…

Going into April, MacroQuant recommends a modest underweight on stocks, offset by an overweight on bonds and cash. While MacroQuant is modestly bearish on stocks, we suspect that the downside risks to equities may be greater than what the model assumes.
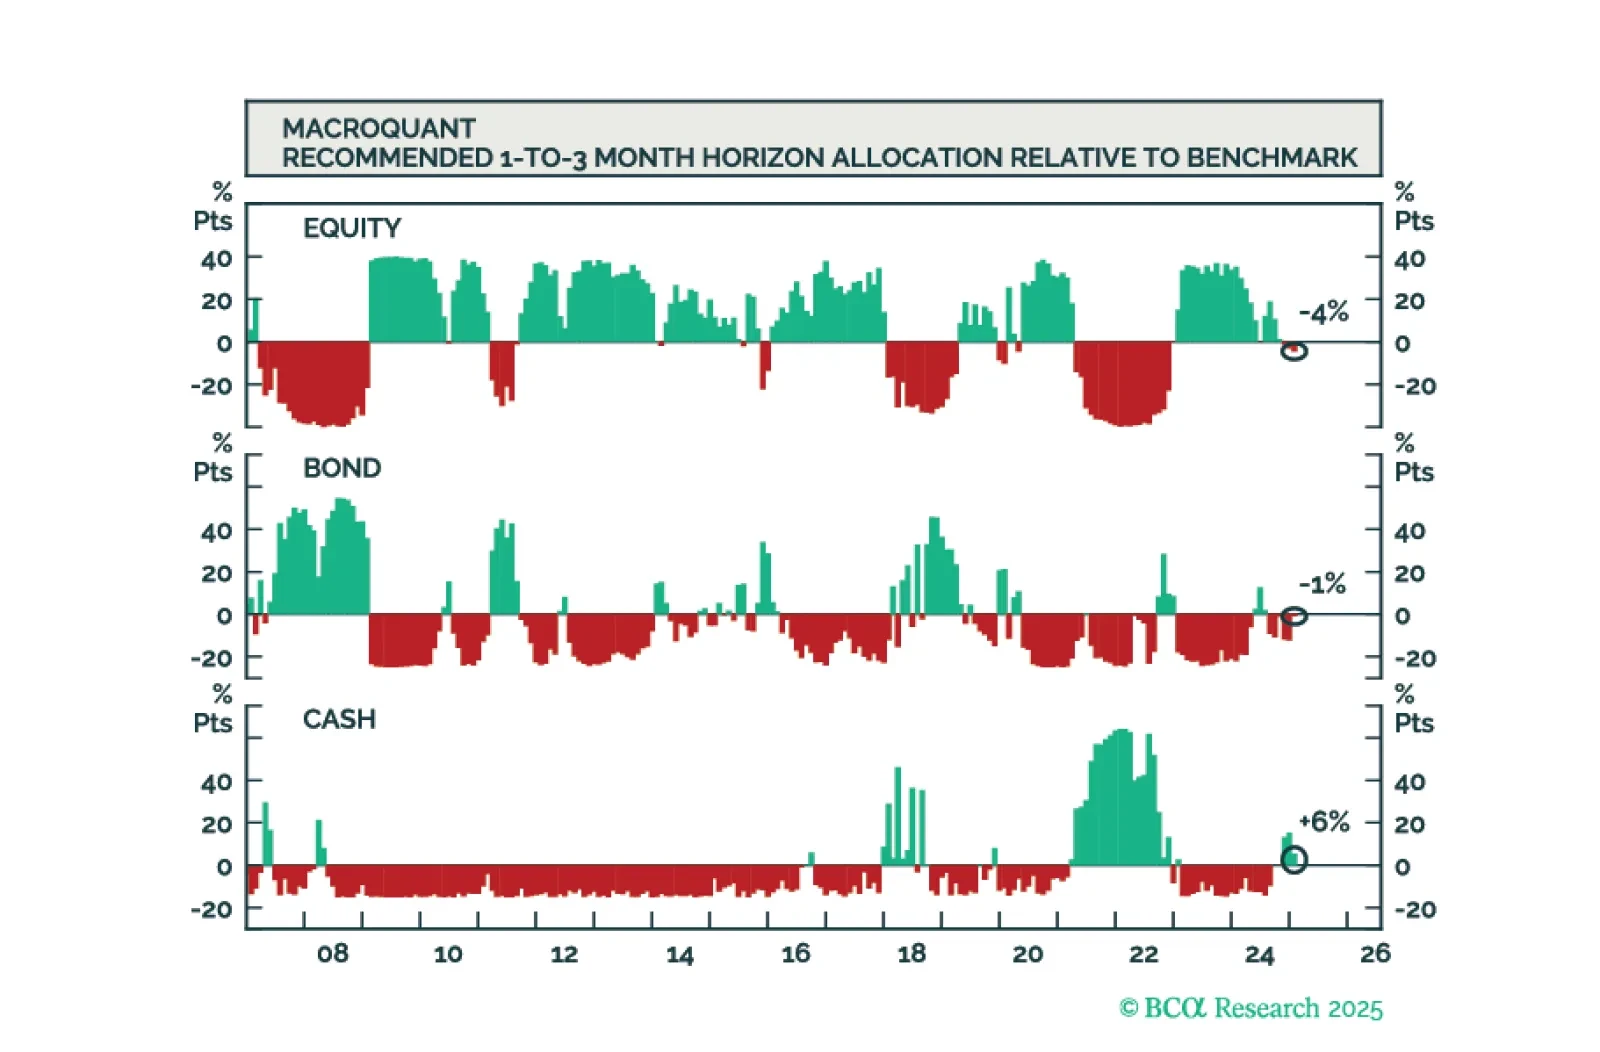
4月に向けて、マクロクオンツはエクイティを小幅にアンダーウェイトし、その分を債券とキャッシュのオーバーウェイトで相殺することを推奨しています。マクロクオンツはエクイティに対してやや弱気ですが、我々はモデルが想定するよりもエクイティの下方リスクが大きい可能性があると考えています。
After affirming he does not look at the stock market, President Trump said he cannot exclude the possibility of a recession as he rushes to implement his agenda before the 2026 midterms. Could a President willingly start a recession? A President’s economic…
マクロクォント・モデルはもはやエクイティに対して強気ではないが、まだアンダーウェイトに転じる準備はできていない。主観的には、グローバル・インベストメント・ストラテジー・チームはモデルよりもエクイティに対して弱気だ。

 
マクロクォント・モデルはもはやエクイティに対して強気ではないが、まだアンダーウェイトに転じる準備はできていない。主観的には、グローバル・インベストメント・ストラテジー・チームはモデルよりもエクイティに対して弱気である。