メインコンテンツにスキップ
メインコンテンツにスキップ

固定収入

特別レポート

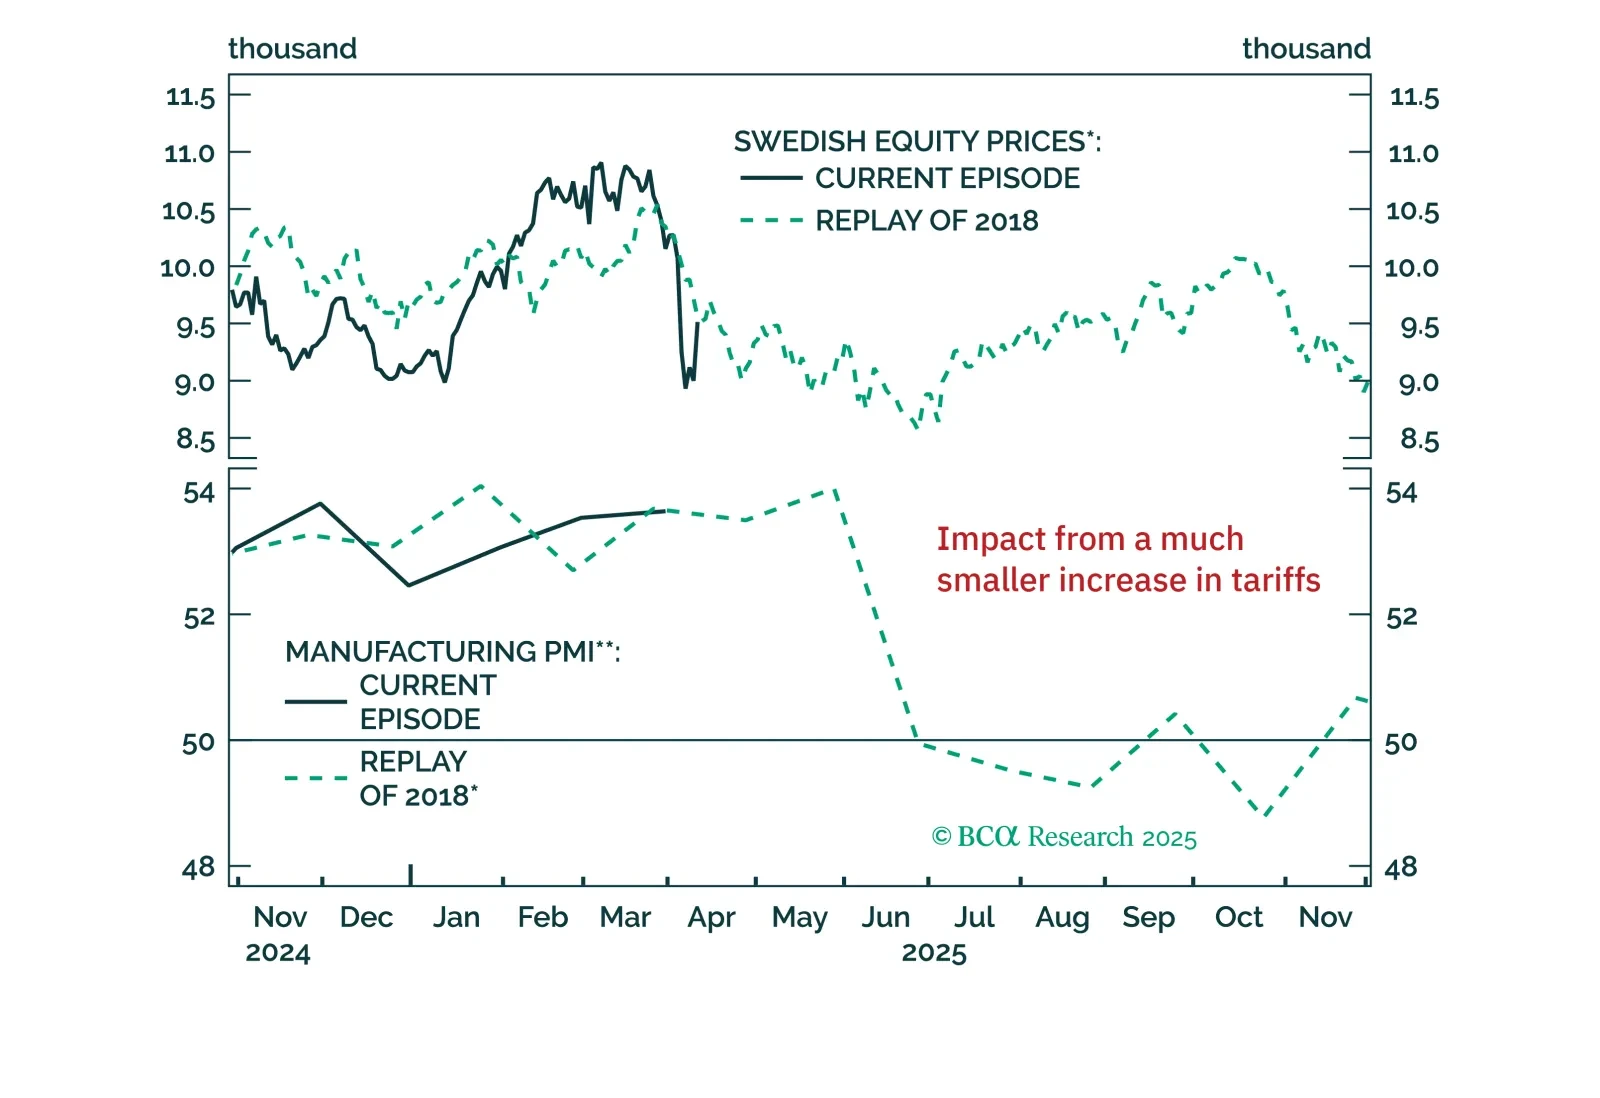
Europe’s near-term outlook remains clouded by uncertainty, even after the tariff reprieve. Our latest update breaks down why the risks to growth, profits, and financial conditions are still skewed to the downside — with Sweden standing out as a key bellwether.
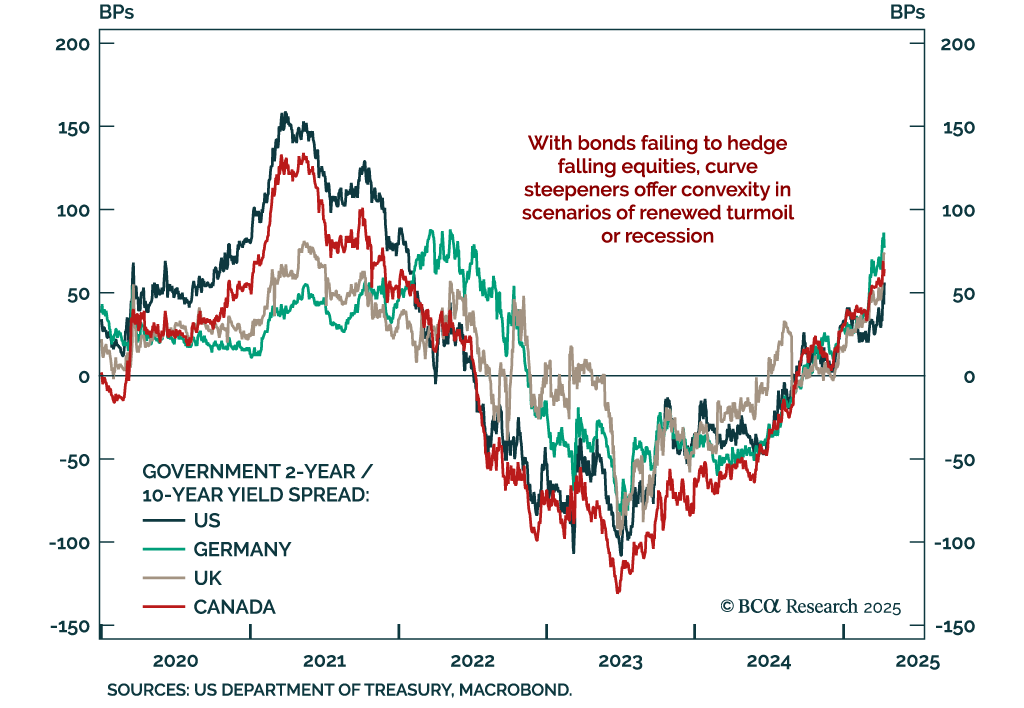
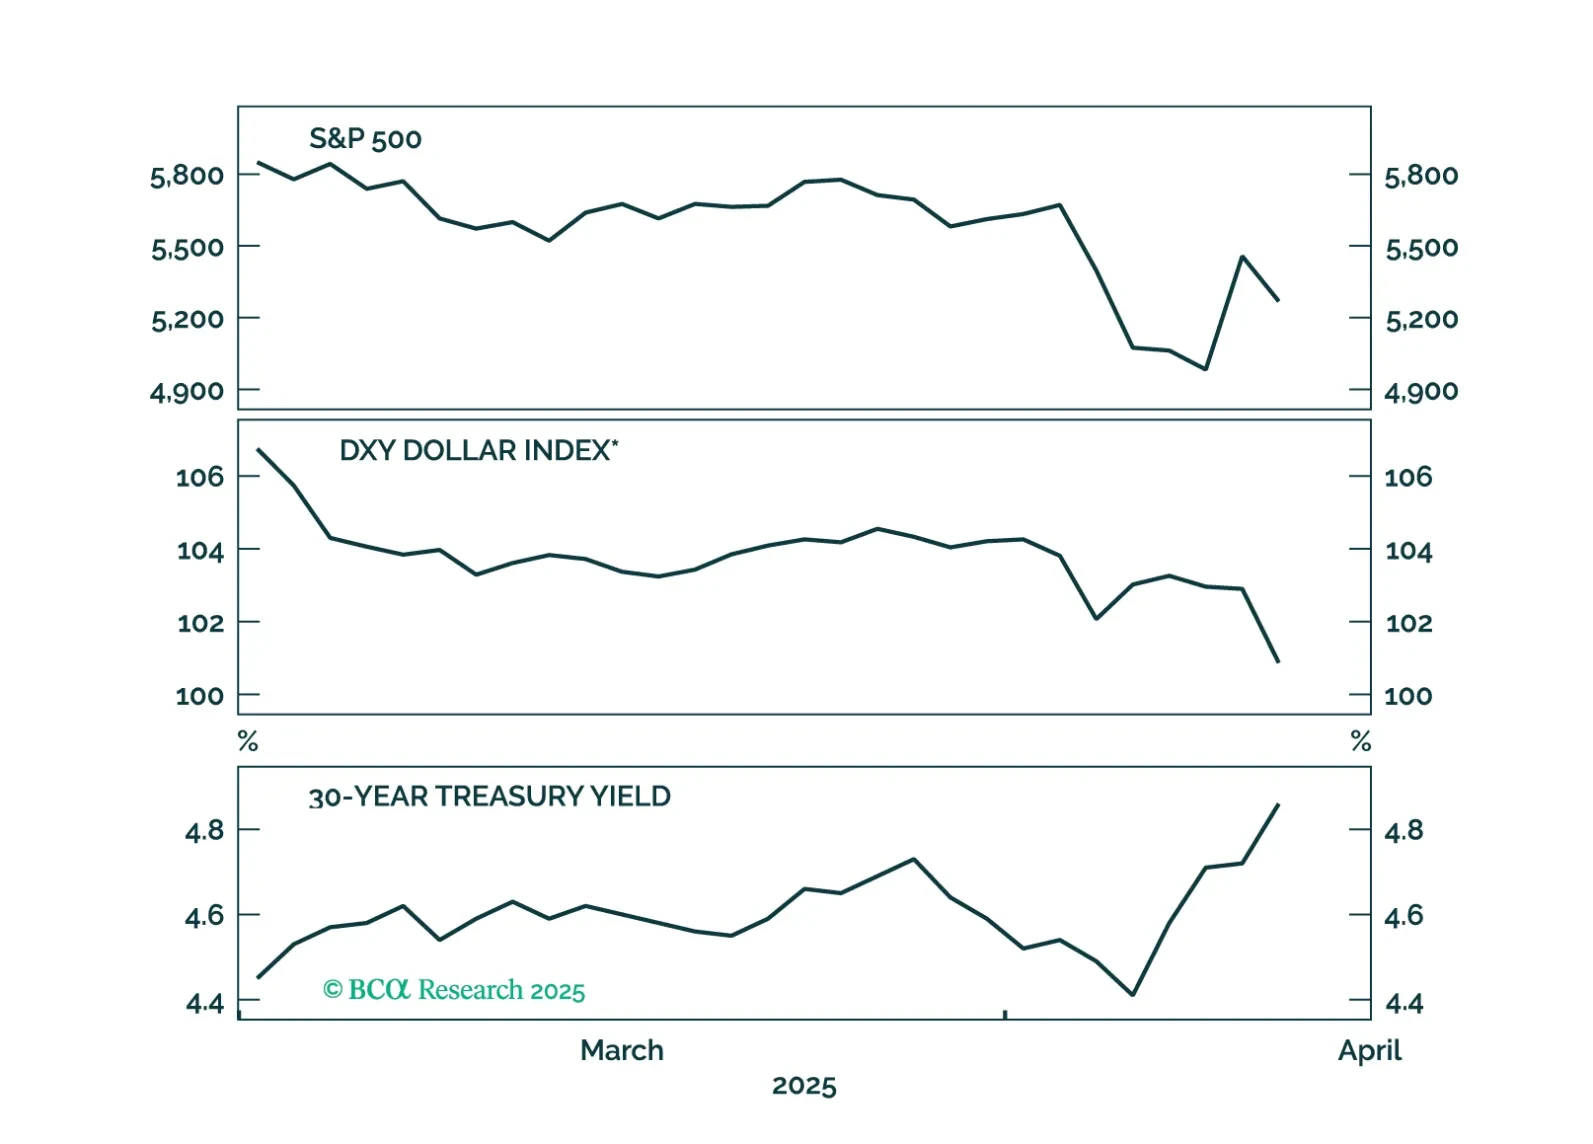
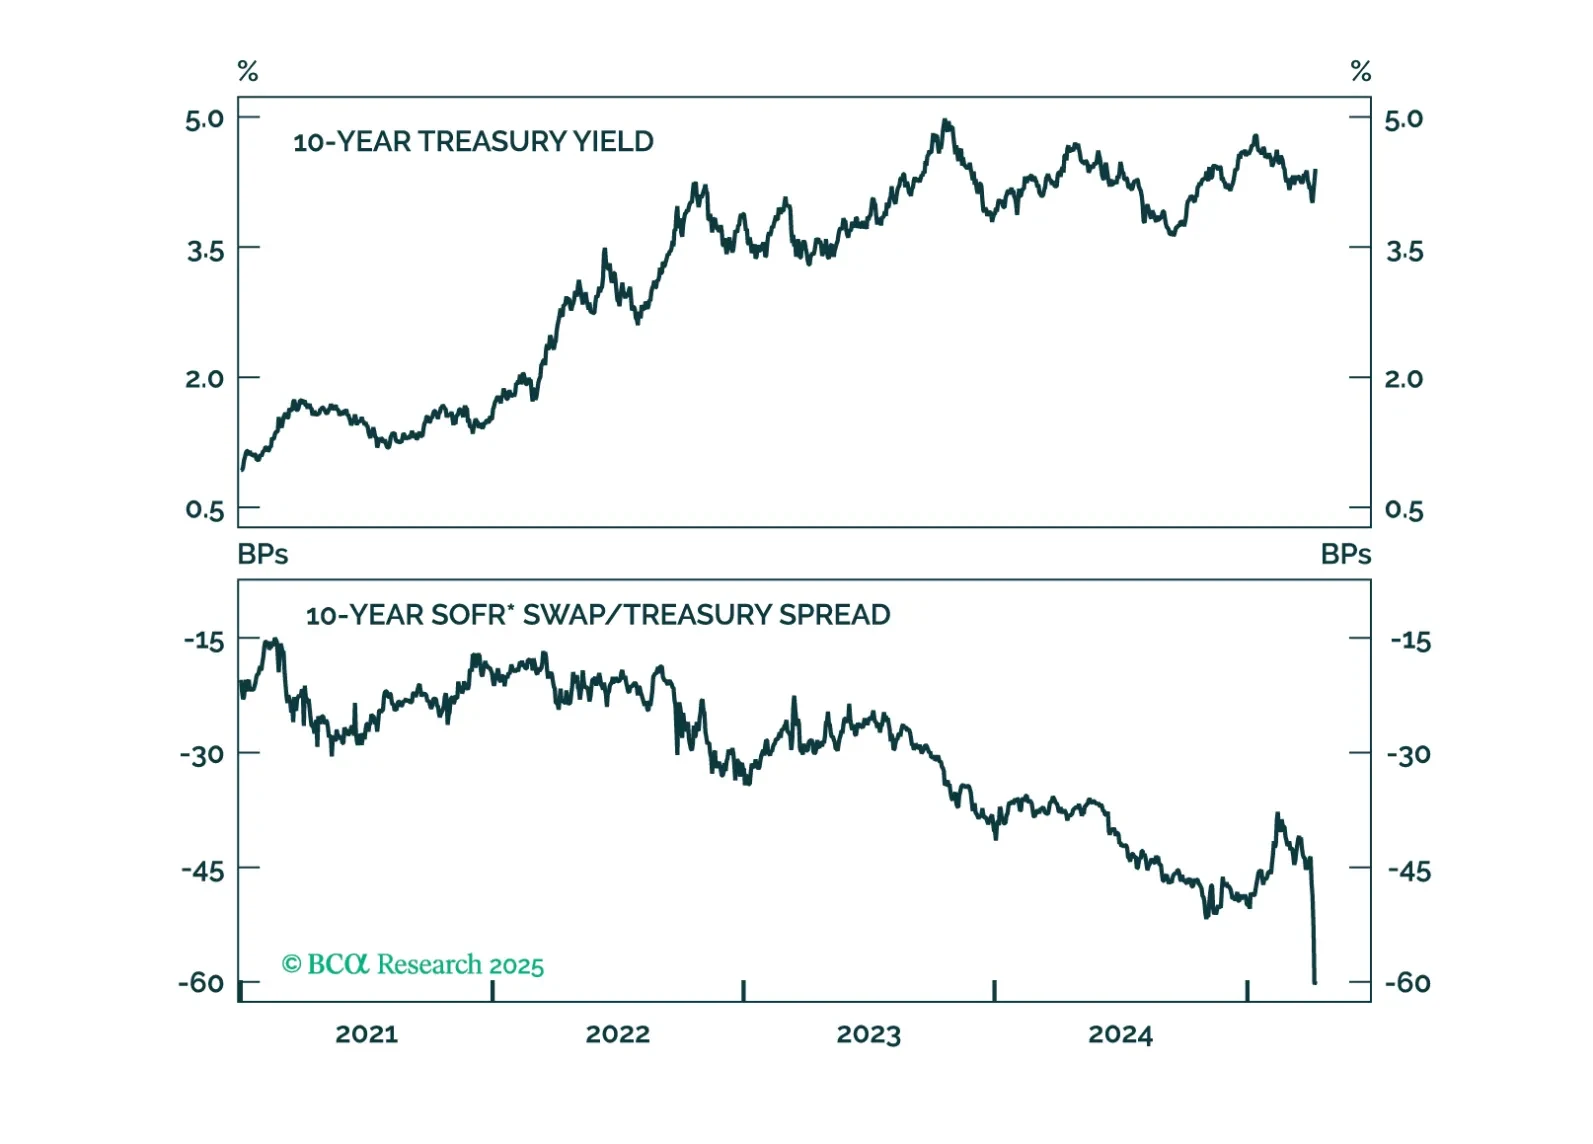
Bonds are failing to deliver defensive convexity; asset allocators should look to tactical curve steepeners for protection. Despite rising growth fears, Treasury yields have risen sharply at the long end. This is a clear break from the typical recession…

The combination of dollar weakness and rising US yields suggests global investors are questioning the safe-haven status of US Treasuries.
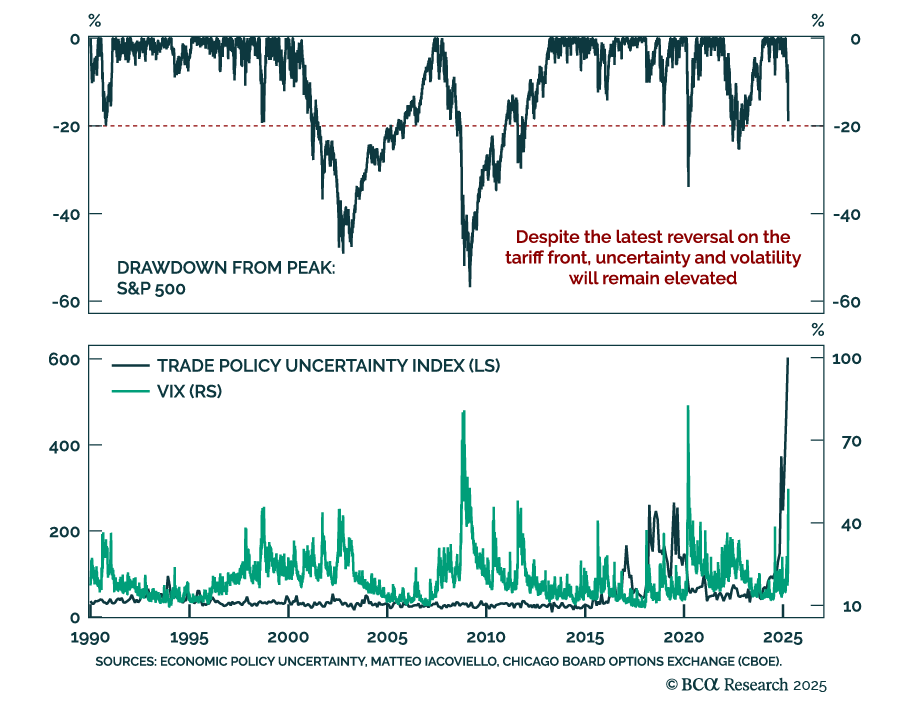
We maintain a defensive asset allocation, as the hit to confidence will linger even if tariff tensions ease. The past few days have seen sharp volatility, with trade headlines swinging markets between despair and euphoria. At the time of writing, President…
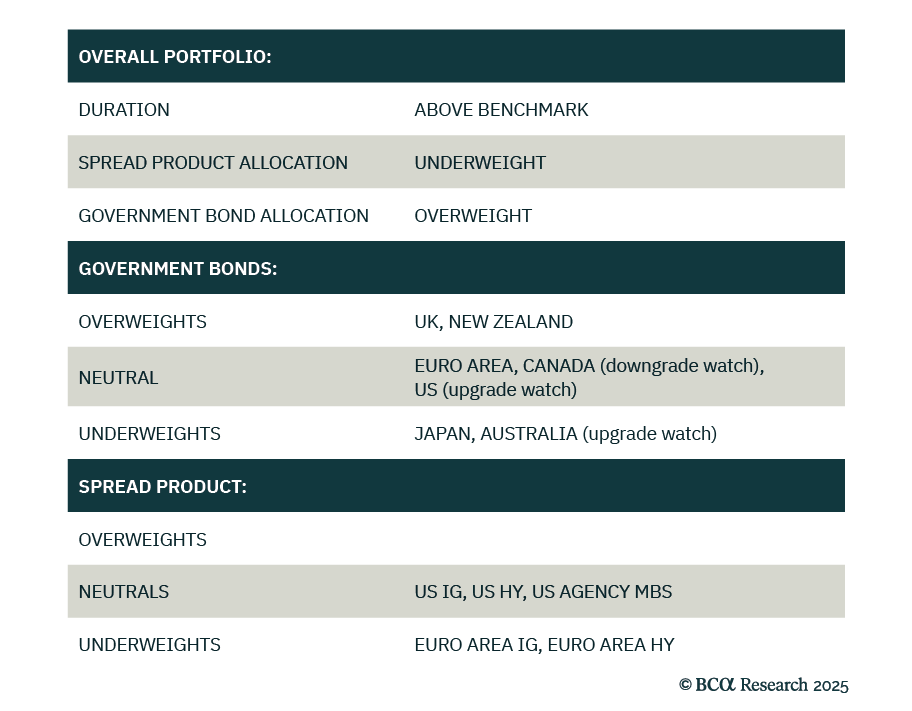
Our Global Fixed Income strategists continue to recommend long duration exposure, curve steepeners, and an underweight in corporate bonds relative to government bonds, as global recession risks rise. The trade war has increased the odds of a downturn, but the…

Our Portfolio Allocation Summary for April 2025.

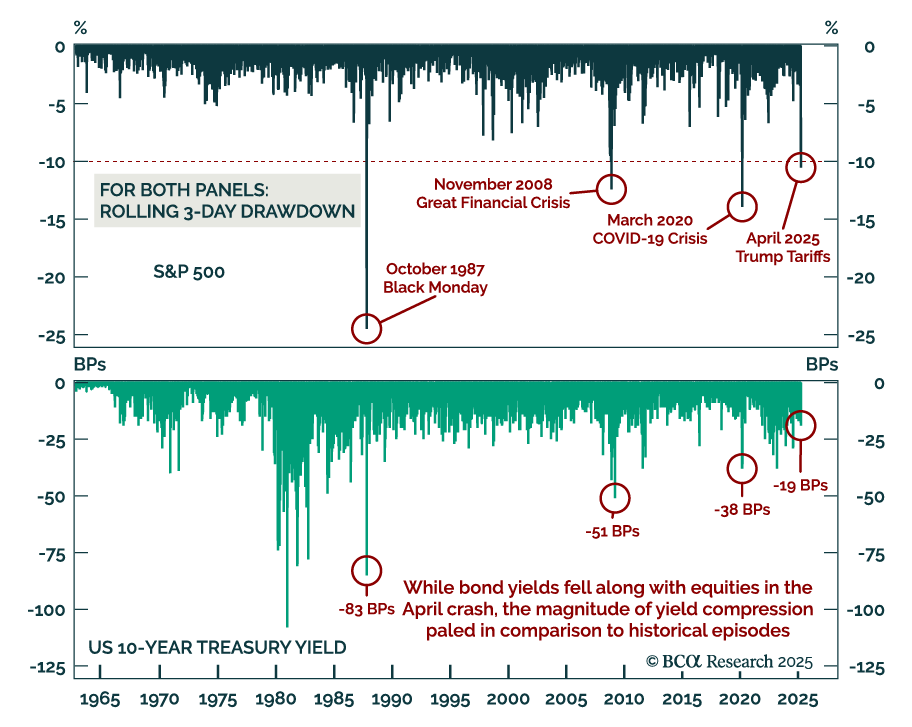
Equities’ post-Liberation Day selloff was historic, but cross-asset signals make it an anomaly. The post-Liberation Day S&P 500’s three-day, 10%+ drawdown joined a list of major episodes that includes the March 2020 COVID-19 crash, the 2008 financial crisis,…

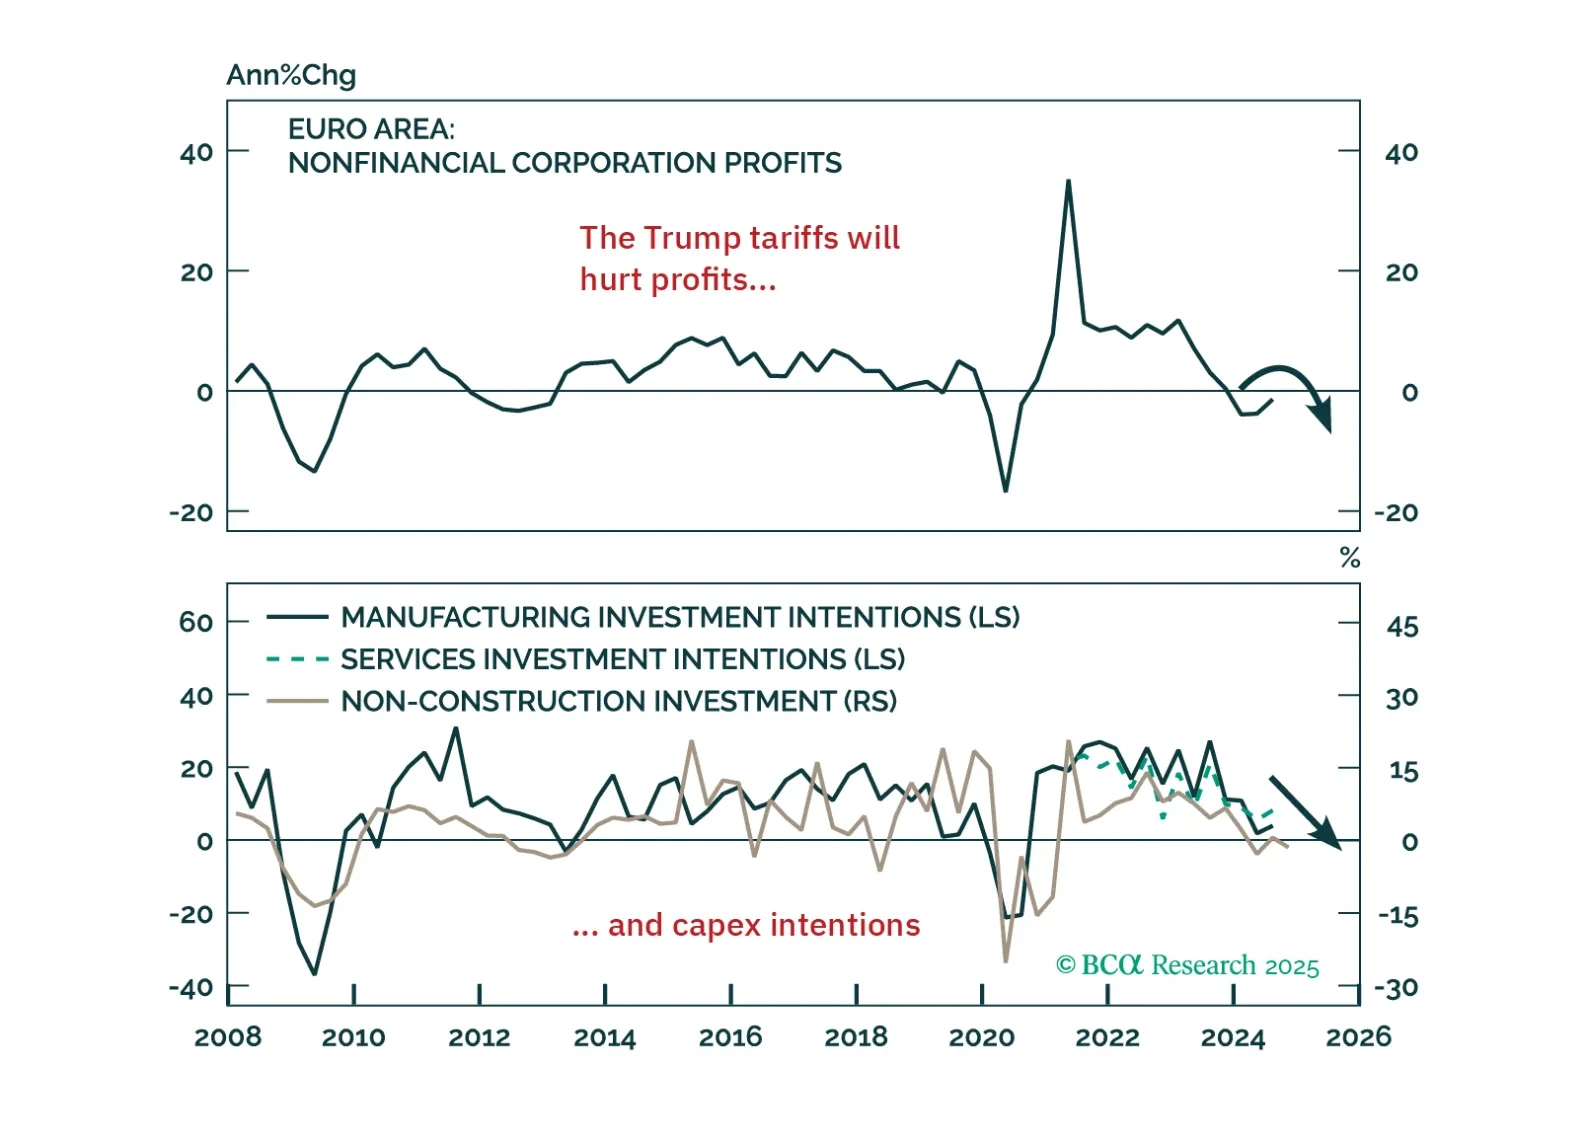
Trump’s tariff shock will push Europe into recession — but it’s also triggering a powerful integration response. In this report, we lay out the tactical case for staying defensive and the structural case for going long European assets when the dust settles.
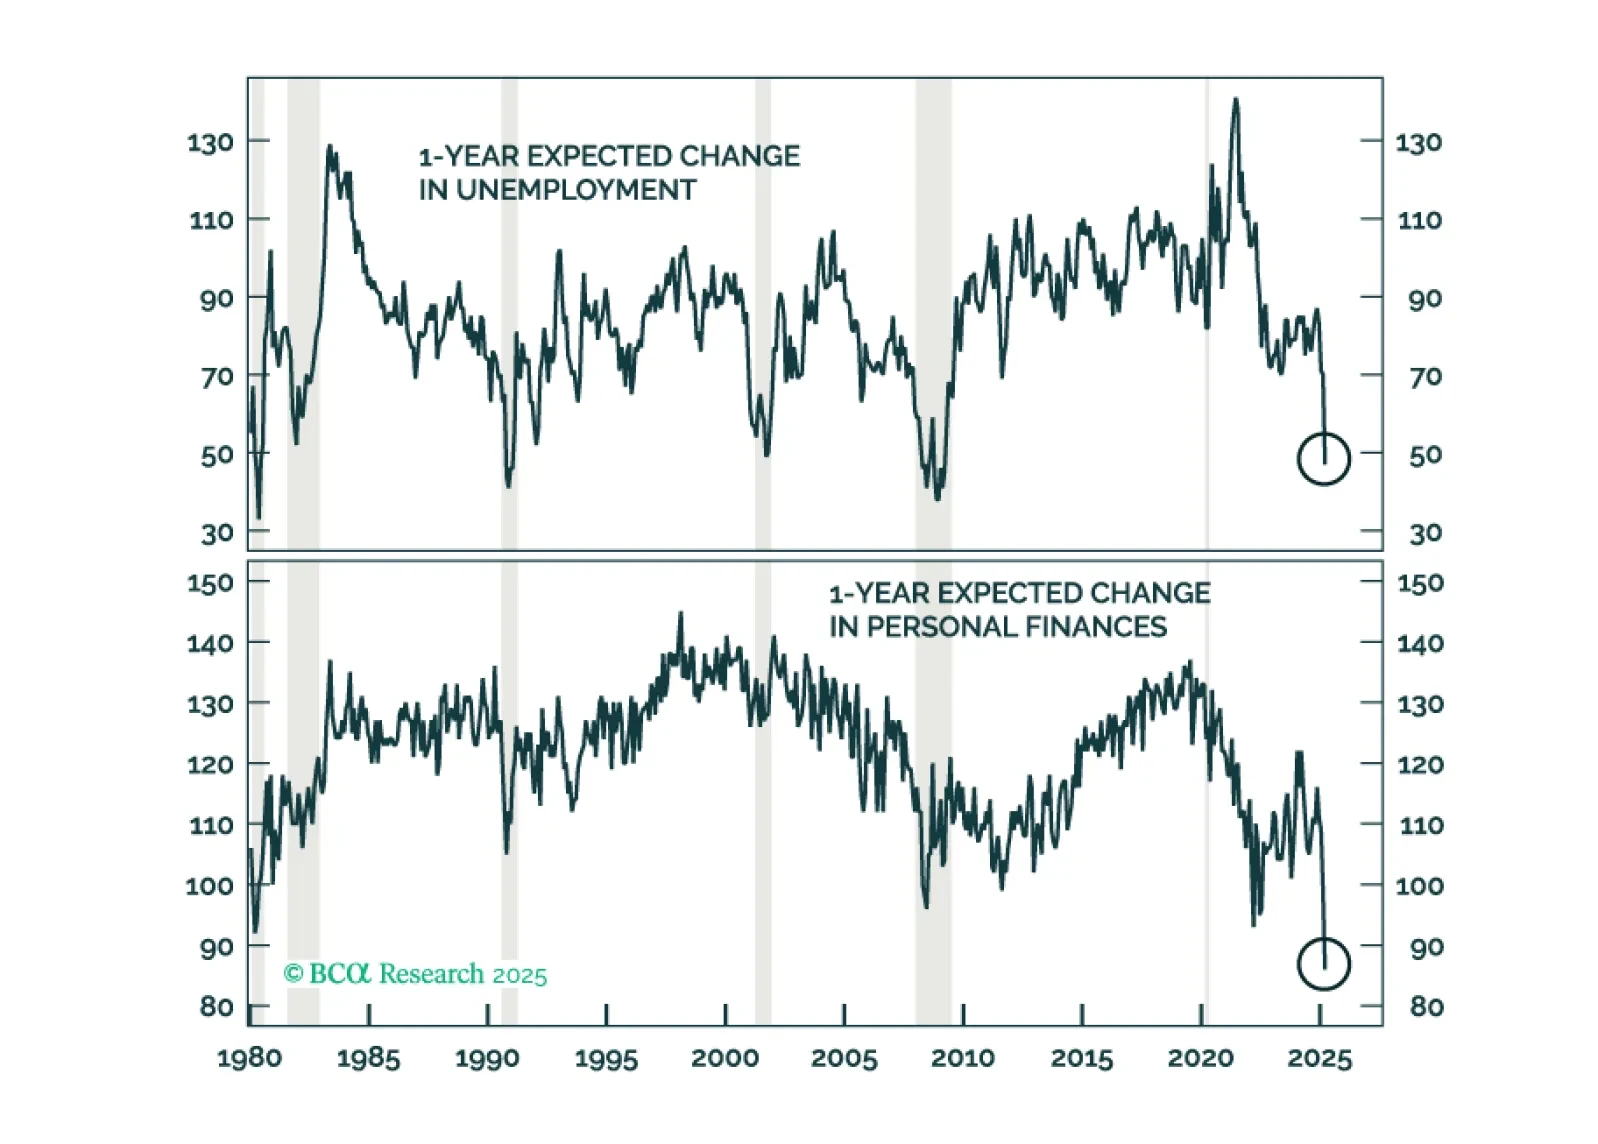
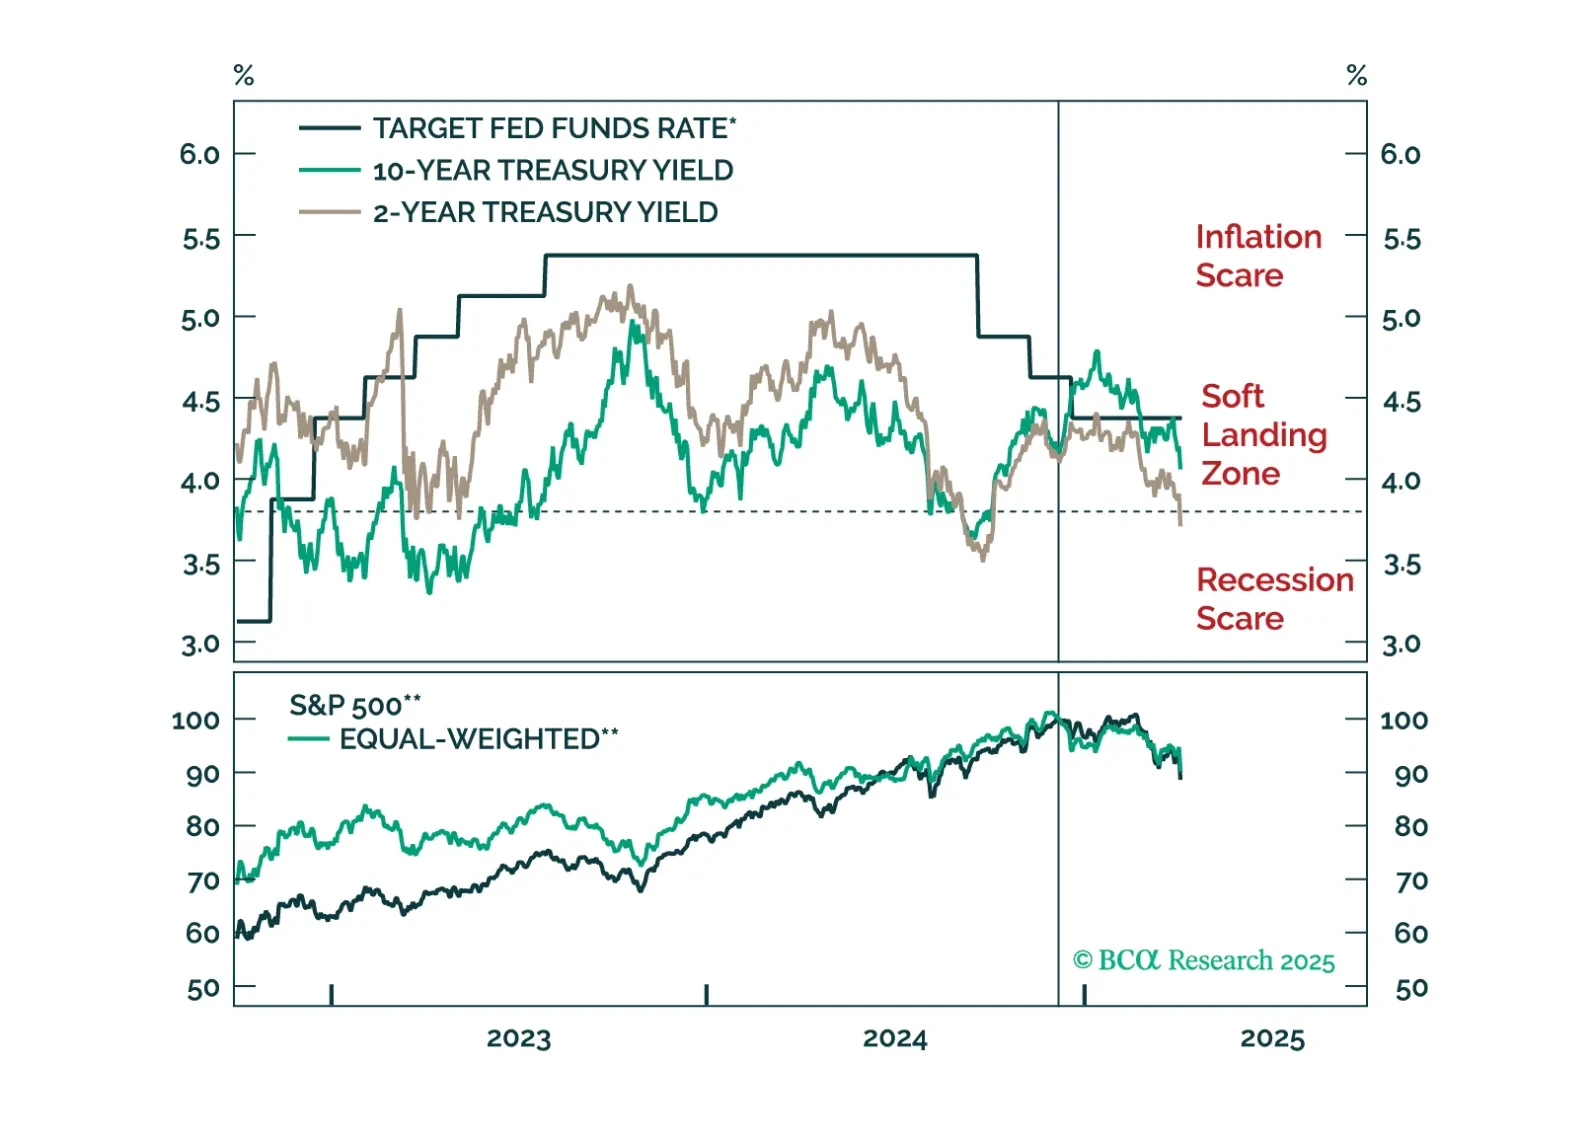
ポストCOVIDの景気拡大を支えた景気刺激策は5年を経て勢いを失い始め、経済は自然に発生する景気後退の方向に向かっていました。DOGEと多方面にわたる貿易戦争がそのタイムテーブルを前倒しした今、我々は改めてリスクオフの推奨を表明します。

The March employment report showed strong job growth, but the labor market remains in a fragile state and the demand shock from tariffs could be the catalyst that tips it over the edge into recession.