ブラジル
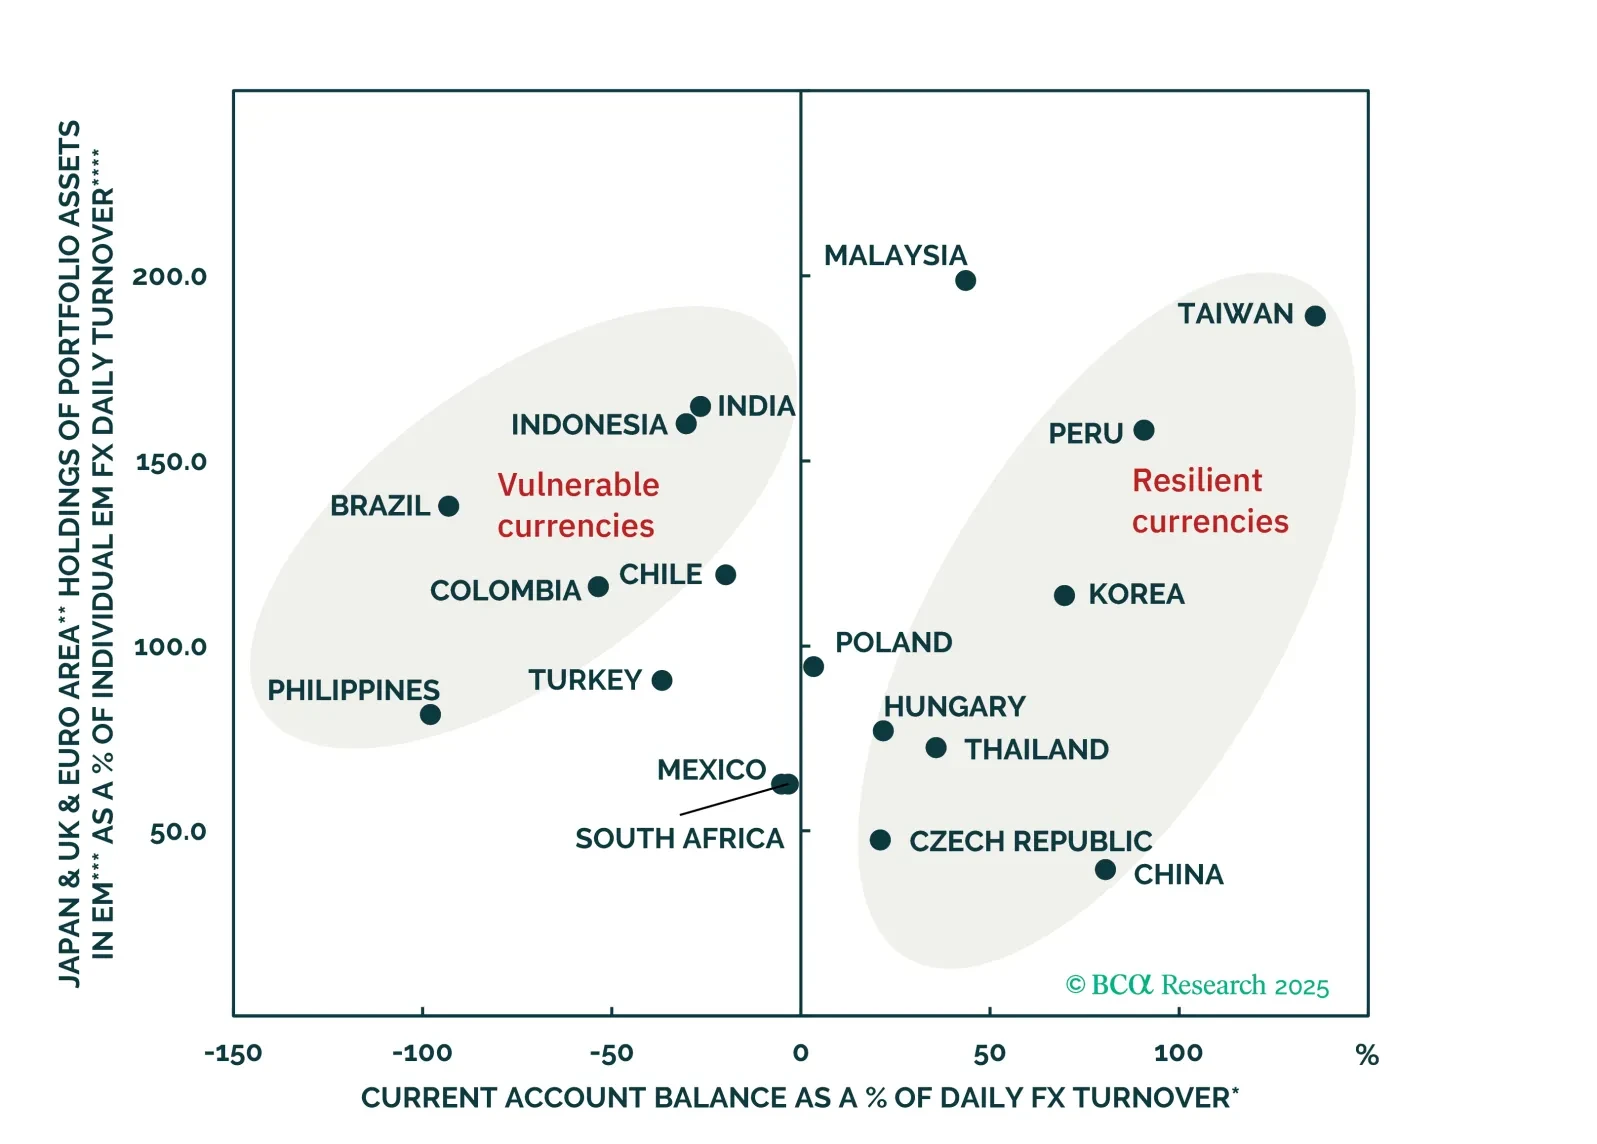
広範な投資家の楽観論にもかかわらず、ブラジルの通貨見通しは、外部要因、財政、マクロ経済の基盤が脆弱な有害な組み合わせによって困難に直面しています。BRLはほとんどの新興市場の通貨に対してパフォーマンスが劣ると予想されます。
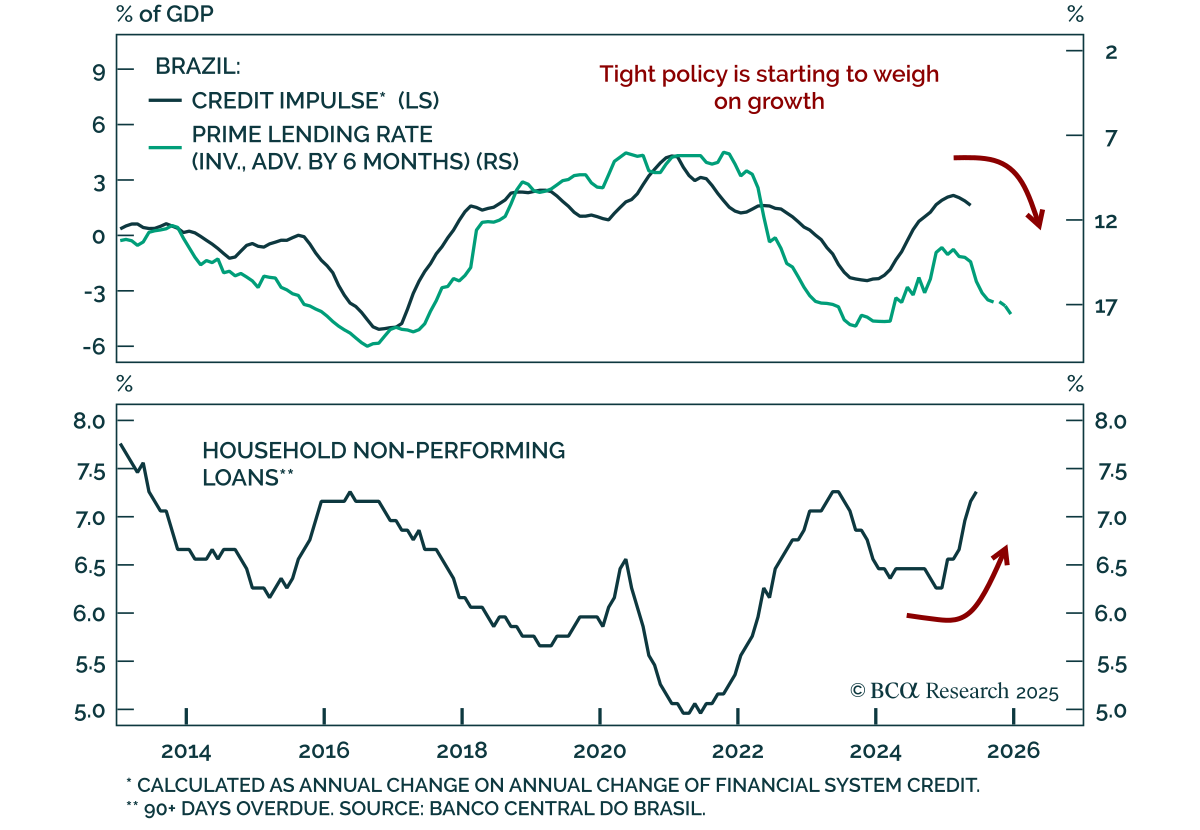
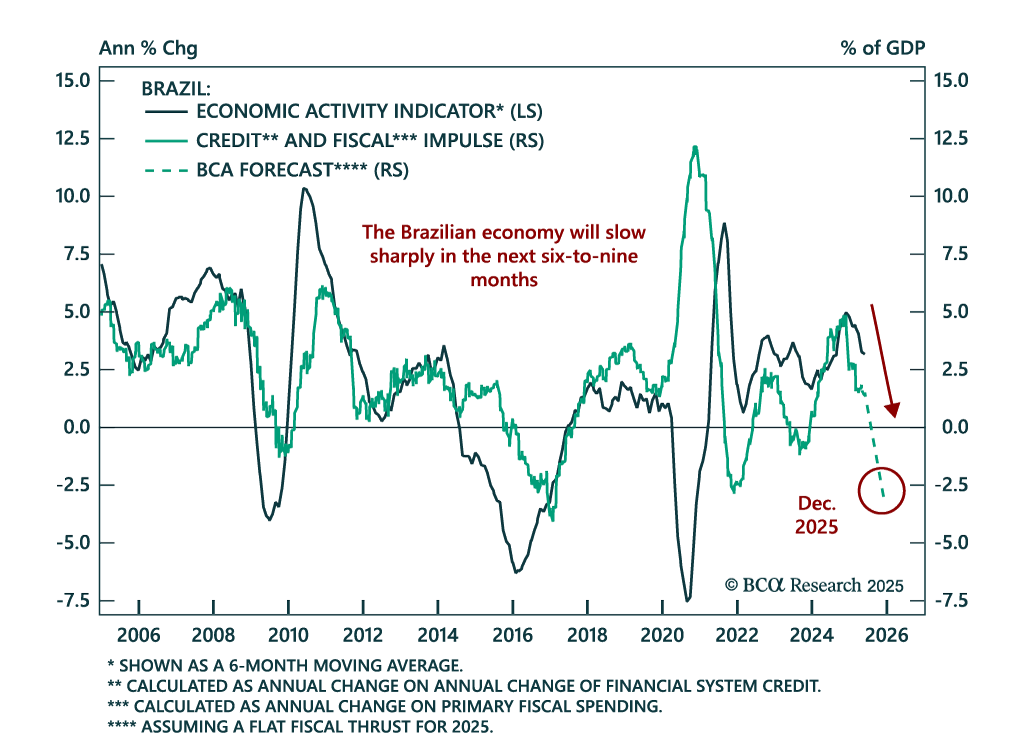
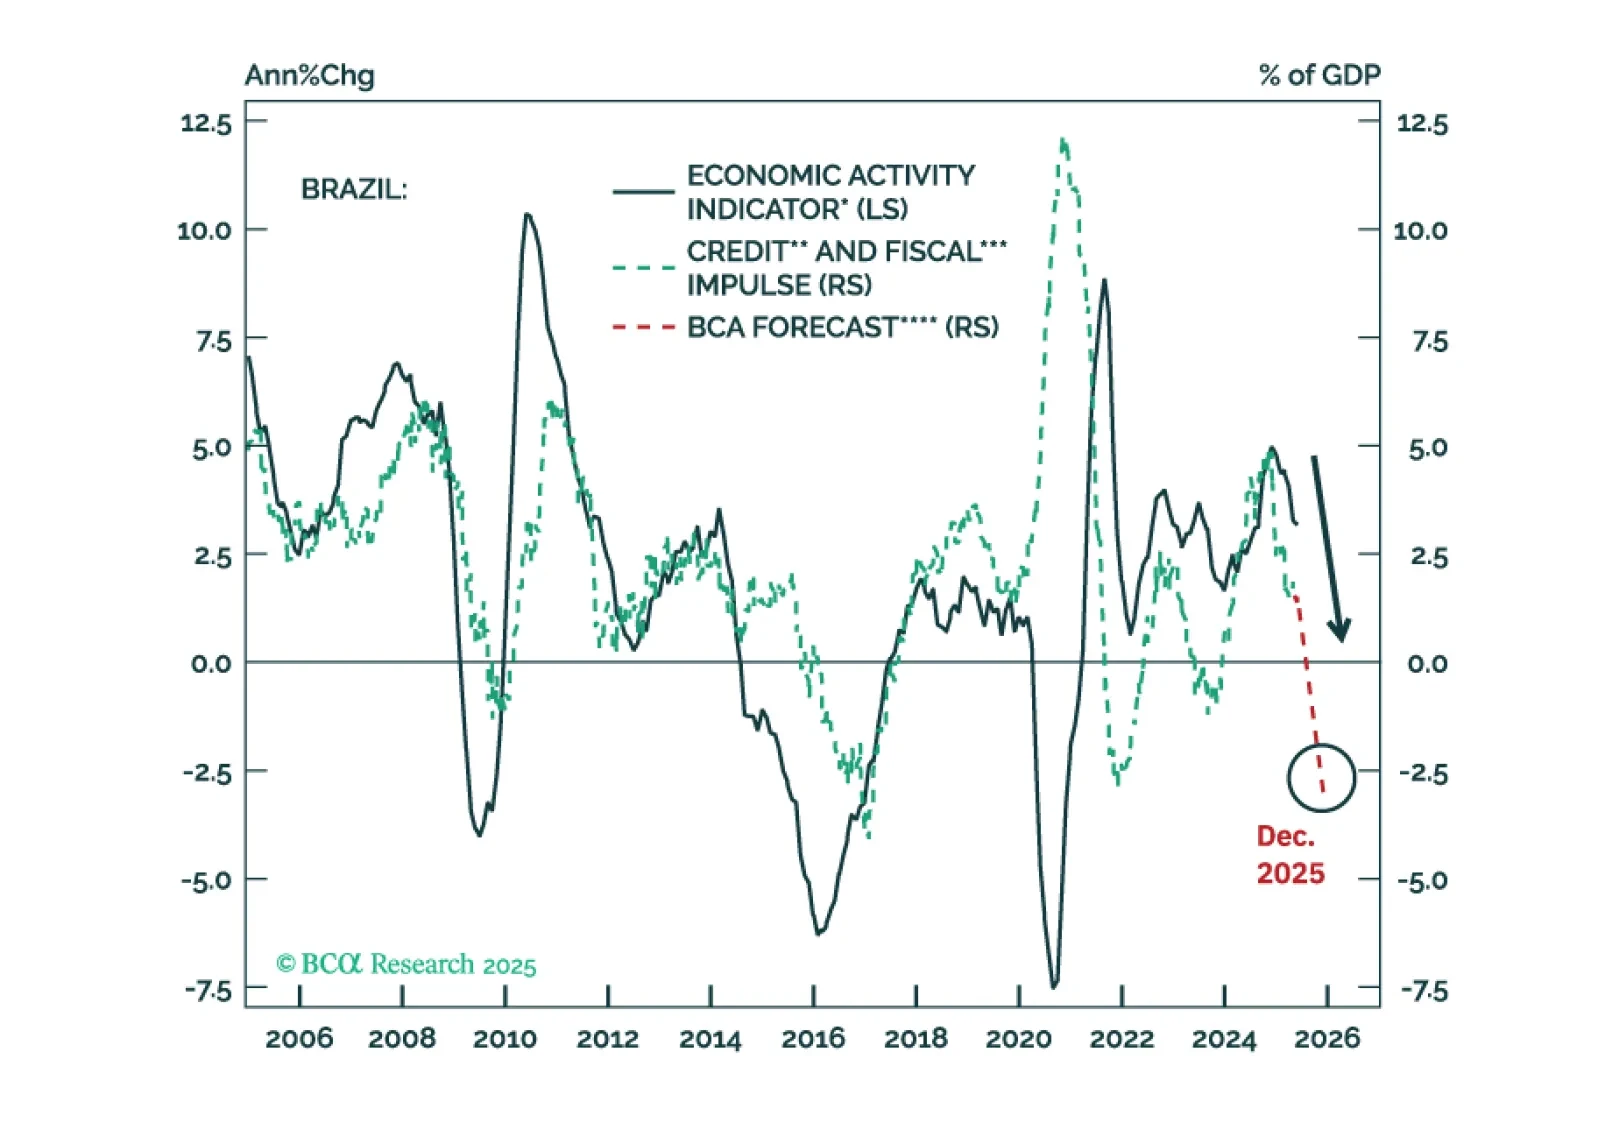
2027年における潜在的な右派政権では、政府債務対GDP比の軌道を安定させることはできません。持続不可能な政府債務、大幅な経常収支赤字、そして急激な成長鈍化により、ブラジル市場は新興市場(EM)をアンダーパフォームするでしょう。しかし、急速に減速する経済から利益を得るために、2年物スワップレートを受け取ることを推奨します。
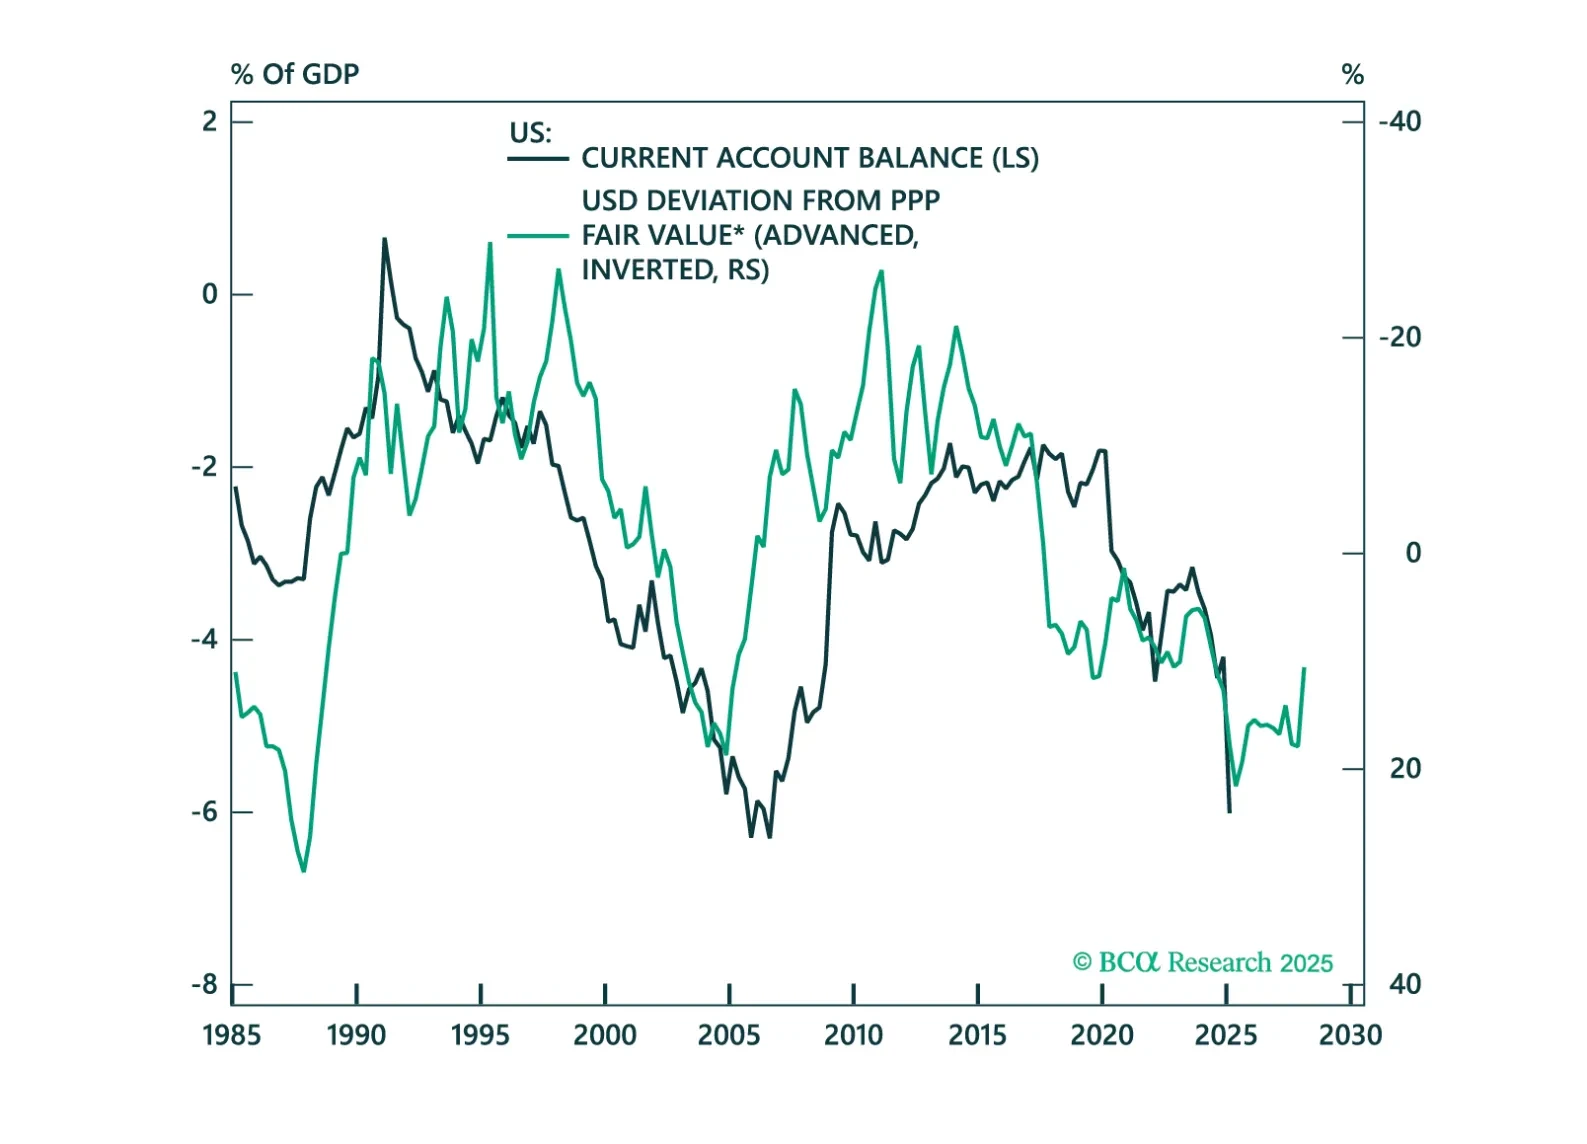
このチャートブックでは、先進国(DM)および新興国(EM)の各国の国際収支を検討します。米国の状況は良くありませんが、他のいくつかの国も同様です。
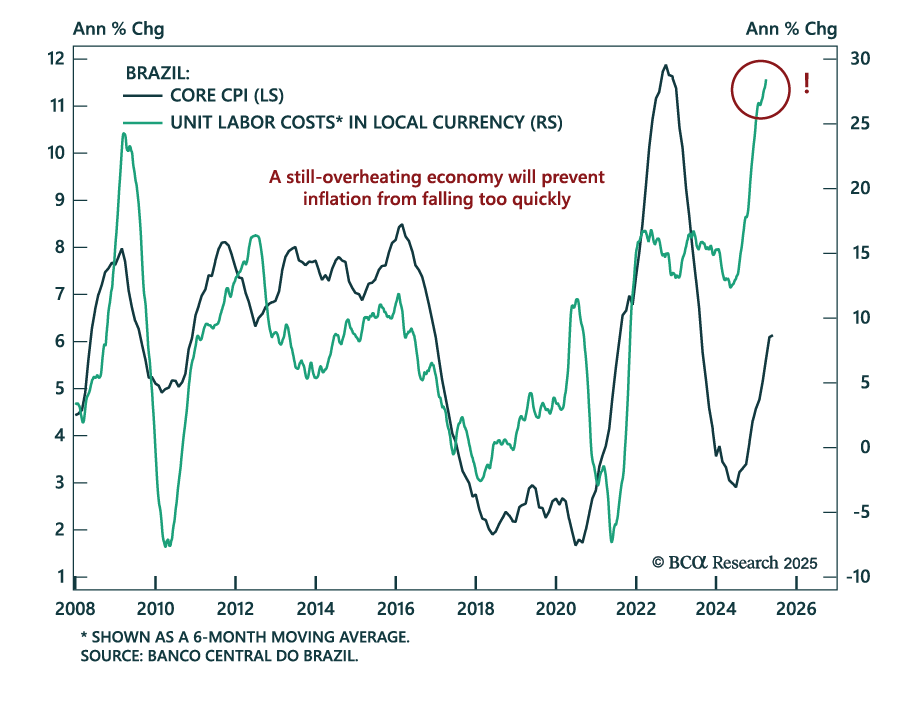
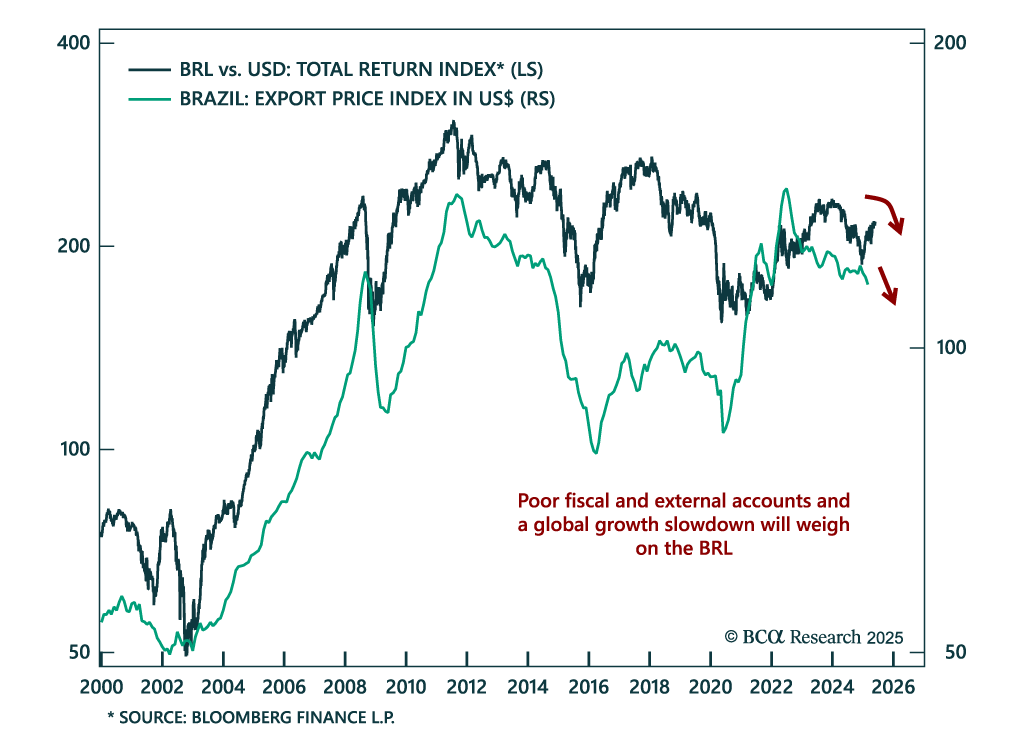
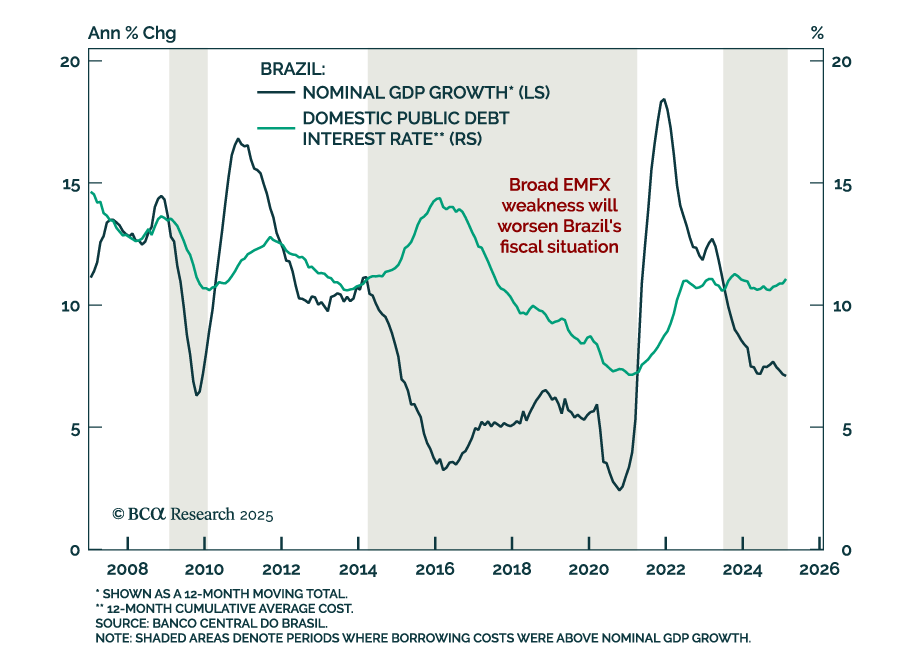
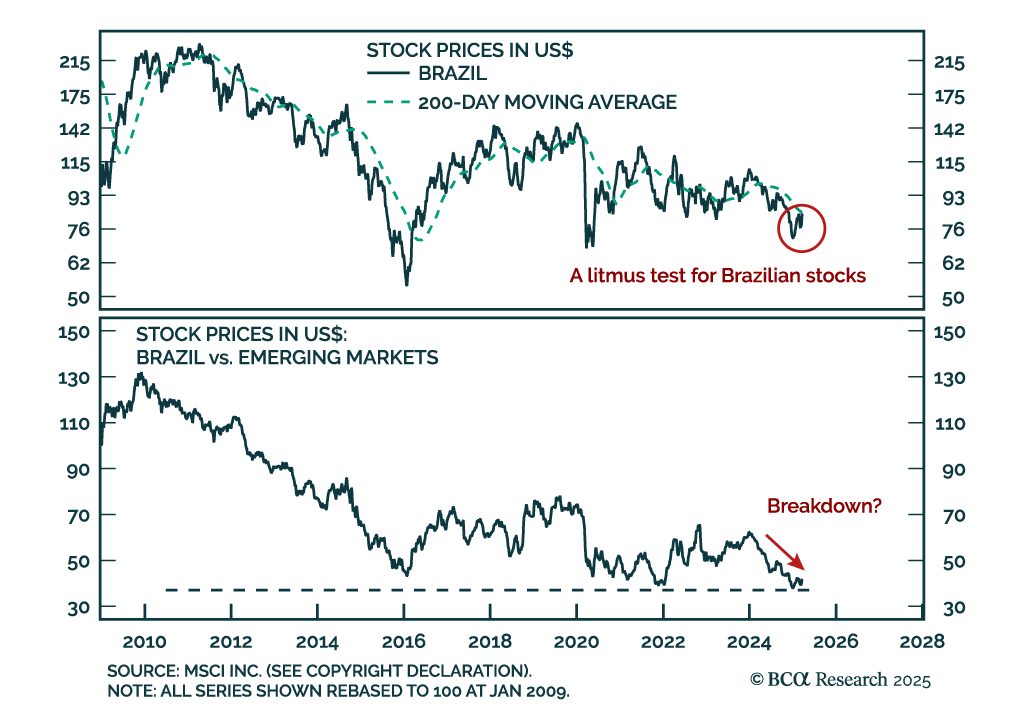

Brazilian policymakers are stuck between a rock and a hard place. There is no combination of fiscal and monetary policies that can assure decent growth, on-target inflation, a stable exchange rate, and public debt sustainability. We recommend investors maintain an underweight allocation to Brazilian fixed-income markets versus their EM peers and continue shorting BRL versus MXN. We have been bearish on the Bovespa in absolute terms and are now downgrading Brazilian stocks from neutral to underweight within an EM equity portfolio.